Small Cap Value Report (Thu 22 Dec 2022) - YGEN, WAND, SIXH, GRIO, TGP, NWF

Good morning from Paul & Graham! Almost Christmas :-)
Just FYI, if the markets are open on any particular day over the Christmas/New Year break, then there should be an SCVR, but it won't necessarily be on time, depending on how much Malbec and Baileys has been swilling around in the Scott household the night before.
Agenda
Paul's Section:
Yourgene Health (LON:YGEN) - we've only covered this speculative, cash-burning company a couple of times here before. Yesterday afternoon it announced a horrific fundraise, at an 83% discount, along with poor interim results. So I'm flagging this up as another example of how cash-hungry speculative companies are in the last chance saloon right now, with discounts of 80%+ seemingly becoming the norm. So once again, I urge readers to check every position in your portfolios, and chuck out the ones that need to raise fresh equity from a position of weakness. (more detail below)
WANdisco (LON:WAND) - I covered this one yesterday, with a big contract win. There's another one announced to day! Although I'm confused as to why the revenue guidance for FY 12/2022 still seems so small. This share does look very interesting, but it's absolutely impossible for me to value at this stage, as it remains heavily loss-making. It's tempting to have a small punt on it though. (more detail below)
Tekmar (LON:TGP) [quick comment] - up 52% to 10.25p, which caught my eye. I’ve not looked at TGP since June, when it issued a pretty awful update, and put itself up for sale. Getting up to speed today, I see there have been several updates since June, and it seems to have an interested party that might make a strategic investment, to sort out the finances - but at what price, if it happens at all? Meanwhile the bank has been supportive, and liquidity looks OK. Today there is news of a big-sounding (no details provided) contract win for the North Sea Dogger Bank offshore windfarm (set to be the largest in the world, amazingly). My view - this looks an interesting, albeit risky special situation. (no section below)
Graham's Section:
600 (LON:SIXH) (£11m) - I’ve done my best to approach this one with an open mind. It fixed its balance sheet this year with the help of a disposal, but I’m not sure that its remaining businesses are big or profitable enough, on their own, to justify a stock market listing. The financial results for H1 certainly suggest that they would be much better off without all the expenses that go with being a publicly traded company. As things stand, I’m afraid I can’t find any good reasons for investors to want to get involved with this one. (more detail below)
Ground Rents Income Fund (LON:GRIO) (£46m) (unch.) [no section below] - this investment trust, currently managed by Schroders, has never been mentioned here before. I just can’t help noticing that its market cap is only £46m, versus an independent valuation of its assets at £109m as of September 2022 (prior to the payment of a small dividend). After accounting for leverage, balance sheet net assets were £90m as of the most recent half-year report (March 2022).
There are usually reasons for such a discount and in this case we have legal uncertainty due to new regulations around building standards and the funding of building defects. GRIO is a landlord, not a developer, but the new Building Safety Act has nevertheless “increased the challenges associated with resolving complex building safety issues”. There are many legacy issues involved with this one, and it needs to survive a continuation vote (which would, if shareholders allowed it, force the liquidation of the trust’s portfolio at depressed prices). To add insult to injury, the uncertainties around valuation could cause the publication of full-year results to be delayed. Not for the faint-hearted, this! But could its problems be priced in at this savage discount to book value given that it offers a diversified portfolio of ground rents, traditionally considered to be safe and steady investments? [no section below]
NWF (LON:NWF) (£132m) - a solid update from the fuel and food distributor NWF. Volumes haven’t improved but price increases and margins are strong, resulting in H1 performance ahead of expectations. Full-year estimates are left unchanged as we head into the important winter months. NWF has been a solid performer and it also offers an acquisition growth story. The company has made a new £10m purchase of a fuel distributor that will increase its market share and improve its geographic coverage. For me, the shares are priced correctly at current levels but its excellent track record might still attract new investors, even after the share price gains achieved in 2022. (more detail below)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Yourgene Health (LON:YGEN)
0.38p (down 80% yesterday)
Market cap £2.7m
I’ve only reported here on this share twice in the 10 years the SCVRs have existed. That’s because it’s always been unclear if the company had a viable business model, with repeated losses and cash burn. Also we don’t normally cover speculative medical sector shares, as it requires specialist sector knowledge I think. YGEN hit a nice patch during the pandemic, with covid testing, but even then couldn’t turn a profit, and that’s fizzled out now.
Interim Results - issued yesterday afternoon look poor to me. Revenues have dropped a lot, and losses and cashflow are both poor, with the cash pile largely disappearing, from £8.4m at the start of the 6 months, and only £2.4m left by the end, at end Sept 2022.
There was also £4.1m of borrowings (excluding lease liabilities) - a loan from SVB (Silicon Valley Bank). In brief, it’s run out of cash, so has been forced into doing a disastrous…
Fundraising - a placing, Director subscription, and a retail offer through BookBuild (I can’t find any details on this platform, do any readers know it?) to raise “a minimum of £5m” in total. (see update further down here)
Here’s the killer - the price is just 0.3p per share, a disastrous discount of c.84% to the previous share price. So existing equity is almost wiped out.
My opinion - as we’ve discussed here several times recently, we are currently in a savage market for companies which need to raise fresh equity. Institutions are generally unwilling to provide more funding for companies that are disappointing with their performance & outlook. We can exit those shares, but institutions can’t, due to lack of market liquidity. So they just have to sit and watch their investments go down the pan. If those companies need more cash, the institutions just name their price. Discounts of 80%+ are now becoming the norm.
For this reason, I urge all readers to once again review everything in our portfolios, and chuck out anything that looks under-funded - especially the smallest stuff, with repeated losses, and cash burn. We’re already seeing a mass exodus of such shares from the market, with some de-listing, and others going bust. Even the ones that survive are now seeing existing shareholders almost wiped out by deeply discounted fundraises. Why take the risk? As much as anything, this is a memo to self, as I have a couple of things that are probably under-funded.
Update this morning - successful completion of the placing & subscription. It seems to have raised more than originally indicated, £6.4m raised, plus possibly £1.0m more from the retail offer (details to be announced tomorrow). It doesn't seem to be an open offer, for existing shareholders, but I may be wrong about that, as we don't yet have details. So existing shareholders have to decide whether to throw good money after bad, or just walk away.
A deal like this is effectively transferring ownership of the business to the (mainly institutions) who are prepared to put fresh money in now, and will end up owning the bulk of the company. Existing shareholders are watered right down. The next step after that? Either commercial success (how likely is that, given the track record?!) or a de-listing in 2023 after the share price has dropped even further. Maybe a final fundraise in some punitive form, like convertible loans, then a de-listing?
I sometimes wonder if institutions want failed shares delisted, so they can sweep their embarrassing mistakes under the carpet, and deal with the wreckage away from the glare of public market scrutiny? Everyone makes mistakes, even fund managers.
Director dealings - Interestingly, the Directors don't seem to have sold any shares all the way down, so they must have believed in the company, and are stumping up £1m in the current fundraising. They were repeat buyers of shares in the market, although looking at the list, all quite small deals - nothing over £100k individually (which are the deals that make me sit up and take notice).
WANdisco (LON:WAND)
890p (up 2% at 08:14)
Market cap £614m
$12.7m Contract and Trading Update
The newsflow at this software company is getting more remarkable by the day. We’ve already covered it 7 times this year here in the SCVRs. The first 3 times were bearish, due to terrible figures and cash burn. But we started to see the newsflow becoming more positive from late June onwards. So when the facts change, we also change our view.
I covered it yesterday here, with announcement of a $31m deal, half being paid up-front by the customer - very positive to be getting a significant part of the deal up-front in my opinion, and that could also defer or negate completely the need for another fundraise, if deals like this keep flowing.
Today’s deal announcement is different, as it’s a one-off, with c.$10m revenues being recognised this year, FY 12/2022 - unusual, as it’s a lot additional revenue to secure in the dying days of a financial year.
This sounds highly impressive -
WANdisco was chosen due to its proven ability to migrate petabyte scale data.
The customer is an automotive manufacturer, and this sector is seen as a “core and growing” market for WAND.
Revised guidance -
Following this new Agreement, the Board expects that FY22 revenues will be significantly ahead of market expectations and no less than $19m. In addition, bookings for FY22 are expected to be in excess of $116m.
Given all the contract wins, FY 12/2022 revenues of only $19m seems very small. Particularly as c.$10m of that seems to be coming from this one contract announced today. That seems to imply that revenues would only have been about $9m without it, well below $13.9m consensus forecast revenues. So maybe this contract has saved the day? WAND is too keen on announcing bookings, when it's really revenue and profit that matters most.
Also with bookings, we need to be told the timeframe over which they will turn into revenues. E.g. if it's a 10-year contract, then the annual revenues even on $116m wouldn't move the dial much on revenues, and would still leave the company heavily loss-making.
Confident outlook -
As we exit 2022, we look forward to 2023 with confidence; not only do we expect to convert the significant opportunities we have in our pipeline but we hope to see increased consumption from all of the agreements signed in 2022, providing increased revenue visibility as we progress through the year."
My opinion - the large scale of recent contract wins suggests to me that WAND has reached a key, positive tipping point, after years of trying. Therefore, the emphasis for me is less about the dismal historic financial performance, and more on the upside potential.
That said, even on upwardly revised forecasts, it’s still set to be heavily loss-making both in 2022 and 2023. So bulls need to be very sure that the big contract announcements about bookings are actually going to turn into revenues, and ultimately profits.
Conceptually though, if a customer is prepared to pay $12.7m just to move some data as a one-off, then it does suggest WAND could have some really special (and hence valuable) technology. Providing of course that it doesn't get overtaken by a competitor that can do the same thing, or better? Nothing stands still after all, especially in IT.
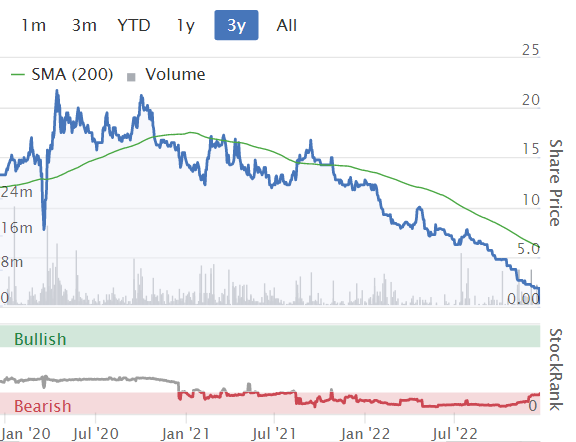
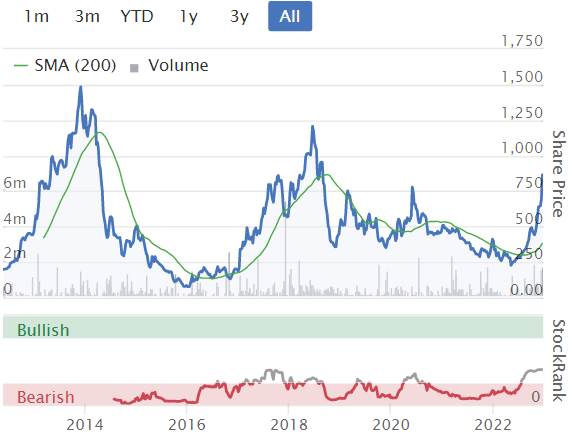
This share looks a very interesting idea to me, but I don’t have the expertise to assess the software. There were big spikes up in the share price in 2013 and 2018, both of which completely fizzled out. Although from memory, the bookings announced were nothing like on the scale we’re currently seeing.
I’m tempted to have a small punt on this, but with my eyes open, in that the share price could be very volatile.
Note that the share count has roughly doubled since 2016.
Graham’s Section:
600 (LON:SIXH)
Share price: 9.55p (-19%)
Market cap: £11m
It’s been a while since we’ve covered this small engineering group that specialises in laser systems.
The last time I wrote about this one, I described its balance sheet as “a mess”, with net debt in the region of $17m-18m (too high relative to its profitability, in my opinion).
It found a solution to this problem: it sold an entire operating division for $21m, and flipped over to a net cash position.
Here are the results for the six months to September 2022:
- Revenues +12% to $17m
- Net underlying operating loss $0.7m (H1 last year: profit $0.7m)
- Back into a net debt position of $2.5m.
It’s unfortunate to see it back in net debt, but at least this is a manageable number, unlike what it was carrying before!
Order book - this has been “maintained”, if you exclude a large one-off order from last year. So it is actually down on last year.
I’m afraid I consider this to be dubious order book reporting. If you go to last year’s interim results, they did not adjust their order book for a large one-off order. Quite the contrary! They said things like:
…our orderbook not only reflects increased demand for our products, but also an improvement in the quality of future earnings.
If you study enough companies, you’ll notice this from time to time: adjustments being made when “one-off” orders in the prior year don’t repeat, but no mention of any orders being “one-off” in nature during the prior year!
Chairman comment - profitability, according to the Chairman, has been impacted by “supply issues and cost inflation resulting from the aftermath of the Covid pandemic and conflict in Ukraine”.
Balance sheet - inventories have increased by $2m to $10m, as the company has sought to secure supply and hedge against inflation. It also holds more “work in progress” as manufacturing times are longer.
Receivables are also up $2.4m, to $9m. The explanation below doesn’t sound great from a shareholder perspective, but hopefully new orders can be agreed on better terms:
a number of orders were taken during the pandemic… with reduced margins and extended terms to cover overheads and keep our skilled workforce together which, due to the long lead times on manufacturing, are only just working through the system.
Outlook
The outlook puts a positive spin on fairly poor results:
Whilst there will continue to be concerns over a recession, COVID variants and supply chain disruption, given the continuing good orderbook activity and backlog and the move to higher specification and custom products, the Board believes the Group is more resilient to market changes and this strategy will lead to improved shareholder value in the future.
My view
The market is deeply unimpressed and has marked these shares down by about 20% this morning.
While the company did sidestep insolvency by offloading a large division, it’s not clear to me that the remaining operations are worthy of a stock market listing.
To see what I mean, here’s the “segmental” analysis of the company’s H1 results:
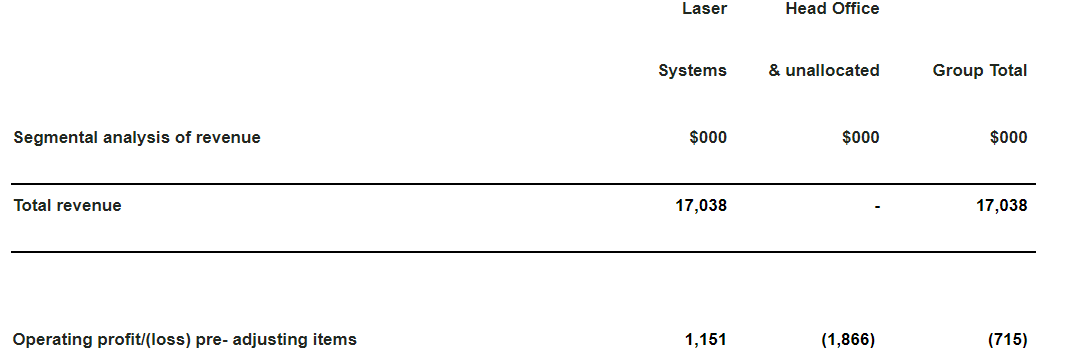
What this says is that if you exclude 600 Plc and focus only on the operating subsidiaries, the company did make a profit in H1.
However, all the hangers-on in Head Office, and overhead costs, added up to nearly £2m, resulting in a net loss for the period.
With the company now so small, perhaps the next step is for it to find a graceful way to delist and save on the costs associated with a public listing and other corporate overheads? Perhaps a buyer can be found? Unless it’s going to raise money and go for growth (probably impossible in this environment), then I think it needs to shut down Head Office as a priority.
But I’m not running this company. Instead of becoming a lean private business, it looks like it’s going to remain a marginally-profitable or unprofitable PLC, for the time being.
I’m afraid I can’t find any attractions with this share.
NWF (LON:NWF)
Share price: 266.9p (+5%)
Market cap: £132m
This is a distributor of fuel, food and animal feed (feeding one in six cows!).
Trading update - all divisions ahead of expectations in H1
Volumes actually fell in both the fuel and the animal feed divisions, but NWF has benefited from inflationary price increases and from strong margins. As I keep saying - these commodities are a safe haven in times of high inflation.
Outlook - unchanged for the full year. Despite the strong start, the company isn’t willing to raise expectations at this point. The share price is up 5% anyway, so investors are happy, but it seems prudent for management to wait and see how the winter goes. No need to assume that trading will remain this strong for the rest of the year.
Acquisition - NWF announces the £10m purchase of a fuel distributor based in Oxfordshire, paid out of its existing cash resources and bank facilities.
The Acquisition further expands and infills NWF's geographic coverage of its Fuels business within the UK and is aligned to the Group's development strategy of consolidating the highly fragmented fuels market whilst expanding its existing geographical footprint.
Sweetfields made PBT of £1.2m in FY 2021. If that’s a reliable indicator of profitability, I don’t think anyone can complain too loudly about the price paid (and duplicate costs will be eliminated, boosting profitability further).
CEO comment
The industry remains highly fragmented, with many small operators, which provides us with further opportunities to consolidate the market and increase our market share. Our pipeline of acquisition prospects remains healthy and this remains a focus for our development activity.
My view
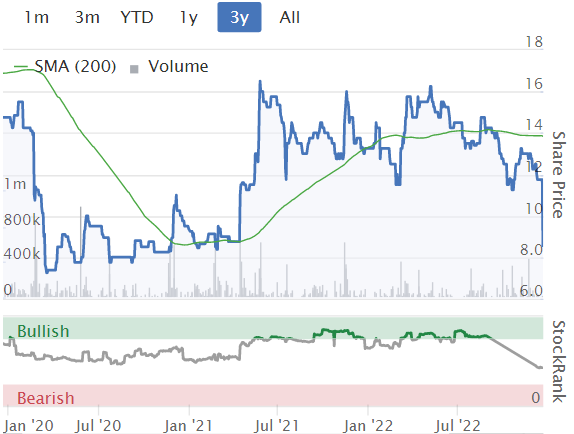
This has been a steady performer: really low margins, but it has continued grinding out profits through the years:
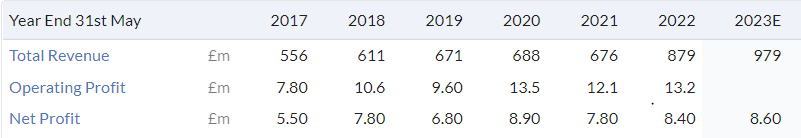
Do I trust the acquisition strategy - it seems like they can afford it, so why not? Increasing market share by adding on complementary businesses can’t be a bad thing, if it’s done without taking on too much financial risk or complexity.
And it has offered wonderful inflation protection, with the stock price increasing in a year which has seen so many other businesses suffer (Momentum Rank: 91).
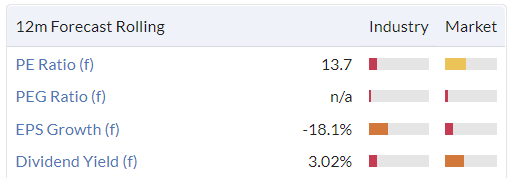
For me, the earnings multiple looks about right at the current level, given that it’s a distribution business, but it might still be low enough to attract new investors who want to hold it long-term. The StockRank is a magnificent 98.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
A quick reminder that when replying to a specific post, if you want your post to be understood in the right context, use the "reply" link below the post in question. Don't use the "Add comment" box at the beginning of the comments or you will start a new thread and readers won't have a 'kin clue what's going on. PLEASE!
Readers can select to read replies in time order or threaded at the beginning of the comments field but this only works properly if replies are attached to the correct thread.
I've followed this share for many years now and made money along the way. It's all about moving data from premise to the cloud. It's the only company in the world I believe that can move data at petabyte scale while still receiving new data that will also go to the cloud and can still be accessed while it's happening. There are millions of companies throughout the world with their own computer set ups but many will want to start using the cloud. For a start it's cheaper I believe. You don't have to buy and maintain expensive equipment and when you want to expand you simply buy more space. What seems to have given it more momentum is that the EV manufactures have discovered that it's good for IOT and transferring data as I understand it from their cars to the cloud.
Thanks for sharing with us what company you're actually promoting?
This share ... what share do you mean?
WANdisco (LON:WAND) I believe as commented below. Need to understand it and apply common sense before investing. Currently don't have a clue.
I'm thinking of satellites and autonomous cars, soldiers in the field etc. GPS is inaccurate to 10m and can be compromised. Maybe the ability to pump up shed loads of data quickly and securely and returned in seconds would be some 'moat' ability. Will wait for their first profit but likely taken over by then.
I see paul scrubbed destiny pharma from his early list, don’t blame you paul!
But it’s announcement, today is in sharp contrast to the excellent points made about YGEN. Destiny will get a fully funded agreement with a larger US based pharmaceutical company to take their product into that market, assuming it does get signed in Q1.
Almost impossible to value, but everything so far suggests that their lead asset for the prevention of clostridiodes difficile infection should get approved in the US. Having had a brother who nearly died from it, let’s hope so.
I hold.
"If you study enough companies, you’ll notice this from time to time: adjustments being made when “one-off” orders in the prior year don’t repeat, but no mention of any orders being “one-off” in nature during the prior year!"
I agree. This sort of thing, belatedly discovering that past orders were one-offs, really, really, annoys me. It may just mean that they failed to win the next order (ie failure to win led to non-recurrence) or it may be genuinely one-off, in which case they should have said so in the previous year.
Superdry (LON:SDRY) (I hold) Financing has been agreed, new auditor appointed. Plus ..
Pre close - Trading update covering the 26-week period (‘H1 23’) to 29 October 2022
From CEO "I am also encouraged with how we have started the second half, which has seen our biggest ever week for Ecommerce orders driven by a return to record levels of jacket sales over the Black Friday period and good momentum through the recent spell of colder weather."
Very annoying that they only give % changes and not actual figures
Financing Facility
Superdry is pleased to announce that it has agreed a loan facility of up to GBP80m, including a GBP30m term loan, for three years with an option to extend for one further year, with specialist lender Bantry Bay Capital Limited1. This will replace the existing up to GBP70m Asset Based Lending Facility which was due to expire at the end of January 2023. Given market conditions, the interest rate will be higher than our previous agreement at SONIA2 + 7.5% on the drawn element. The revised facility is operationally less complex to manage and covenant light, giving us the necessary flexibility to navigate the current challenging macro-economic environment and continue to focus on driving our brand strategy forward.
Notes 1. Bantry Bay Capital Limited is a specialist lender which provides supportive debt capital solutions tocorporates in periods of growth and other change. Bantry Bay focuses on asset-based financings for private andpublicly listed companies across a wide array of industries, working with clients to provide the foundations forstability and growth. 2. The Sterling Overnight Interbank Average Rate (SONIA) is the effective overnight interest rate paid bybanks for unsecured transactions in the British sterling market.
https://www.investegate.co.uk/...
Albm7, as an Superdry (LON:SDRY) holder you either have rose tinted glasses and did not read this sentence immediately after, or maybe as a a holder you're trying a bit of light promotion? :)
"That said we are under no illusions that consumer confidence is fragile
and that the picture is unlikely to change quickly."
No I read it alright, I was not trying to be misleading in anyway just highlighting for anyone interested in Superdry (LON:SDRY) that there was news out as it has been discussed here recently. I didn't want to copy whole press release.
Thank you for your quick comment on Tekmar Paul. We bought too many shares for the right reasons years ago and held for the wrong reasons ever since the cable rectification problems surfaced. Loyalty can equal stupidity, we're still holding.
Smarttech247 (LON:S247) A friend of mine has flagged this recent IPO to me as a potential opportunity. I’m struggling to find out much information and wondered if anyone else knows them or has an opinion?
Hi Grudge,
It doesn't sound too dissimilar to £CRWD over in the US and if their recent performance is anything to go by shareholders very high expectations are not being met and the SP is in freefall. This combined with the the poor performance of the vast majority of recent IPOs would make me very cautious of £S247. Apologies I can't offer any detailed input regarding the company, just be wary the risk reward may be skewed to the downside!
Cheers,
Ben
Gudge58 re Smarttech247 (LON:S247) ...
I tweeted out the below on looking at it. I don't have much of view. Its unusual in cybersecurity floats in that it seems to have real revenues and relationships. However very new to market and I think some of the aspects to the biz are opaque (inc the Visibility Blockchain arrangement) and so could be the source of surprise (positive as well as negative). Instinctively I feel there will be some rough/surprise to navigate from this before we see what it is. Also note that founder owns 67% and employees 8%...
Graham, are you sure that the low value at Ground Rents Income Fund isn't caused by a very long running review of ground rent terms suffered by leaseholders. I've been watching the "review" and waiting patiently for some years now, and as is the norm, the government seems unable to get to a conclusion, in the face, no doubt, of vociferous vested interests. Basically, I think one of the important points under review is the fairness of the price which leaseholders can charge to sell the freehold to the householder.
My lease costs £5pa and has another almost 800 years to go, but the organisation who bought it from the local authority has done their worst over the years to cajole, persuade and bully people holding these old leaseholds into buying their freeholds - mine is offered at a price of £700.
Just a thought.
Ground Rents Income Fund (LON:GRIO) The RNS concerning the discount to NAV caught my attention this morning. I was put off further research when I read that the two or three directors who own shares have holdings of less than £7000 each. There may be options, of course, but if those who know the business best are not investing it is unlikely to be substantially undervalued.
Journeo (LON:JNEO)
I see the placing is being done through some obscure platform BookBuild-has anyone ever used them?
You can only deal through a registered intermediary but it looks like there is only AJ Bell and II neither of whom are confirmed.
Plus you have to be an existing shareholder.
Clearly all designed to improve retail ownership...
Interesting update from LON:DEMG the global leader in oesophageal Doppler
monitoring, A jam tomorrow share if there ever was one! But maybe there will be some jam?
Extracts below:
Extension of standby loan facility by £0.25 million - funded by Chairman - so either foolish or a sign of confidence that the ship is about to turn. Its on "arms length" commercial terms.
Year-to-date revenues are ahead of the Group's full year 2021 revenue figures (not saying much IMO) and the Group has a large advanced opportunity in the pipeline which if successful, could provide a further boost to revenue in the short term. Given news below quite encouraging.
New Monitor to be launched will take several more weeks to be completed, including
further testing. This delay has been caused by headwinds associated with
strains in global supply chains that delayed the start of the approval
process, including the completion of the testing for regulatory compliance. A story we've heard elsewhere but I note they are talking weeks not months.
Interest has been strong, and the Group has already won a tender in
respect of the New Monitor at a price point significantly higher than price
levels typically achieved for the current monitor. Also mentioned upgrade opportunities as well.
The business has been tightly managed and therefore operating costs are lower
than originally anticipated.
Maybe they will finally turn in a profit. Disclosure I hold at a considerable loss!
Late morning update - here's what we've done so far, and hope to get done by 1-2pm (I'll probably scrub Destiny Pharma off the list, thinking about it) -
Journeo (LON:JNEO) Interesting announcement this morning of a purchase of a complimentary business - highly accretive and what looks to be great value to me.
Placing at 105p to fund it. But initial outlay is £6.2m and that buys £3m of free cash (no debt) and broker research note reckons it is £4.5m of cash. Plus £12m of revenues and PBT of £2m along with a signed order book of £25m revenue visibility.
When I put these numbers together broker has a very conservative EPS of 18p for next year. I think that looks deliberately light and expect it to be north of 20p. There should be circa £4-5m of net cash too. So including placing appears to be a market cap of £18m at 130p with say £4m of cash and EPS at 20p and growing.
What I like about this deal is that it finally gives Journeo (LON:JNEO) scale with opportunities to cross sell and I think that puts a greater level of security into the overall business.
On the whole feels like there could be strong upside to north of 200p maybe?
I read the announcement this morning and my first thought was that was going to go down to 105 as normally happens when there's a fundraise.
As an holder though I am very pleased with the response from the market and look forward to continue holding.
WANdisco (LON:WAND) - Thanks Paul and just like you - completely confused with the trading update.
WANdisco (LON:WAND) is very volatile. A near £600m market cap now for a company with such small revenues still feels way too rich a valuation. As it happens I have made money buying this stock before a few years ago when it did the same sort of rise from similar levels. As you say share count has doubled and revenues are taking a long time to come through. I like the tech and I do believe the business is now firmly on its way to profitability in years to come. Problem is when!
I'm kicking myself as I saw the start of this trend and run of announcements and was going to buy some around 400p but at 850p I would be a seller.
Seraphine (Bump)
Change of advisor RNS thanking outgoing broker Numis .
Wonder how much Numis creamed off the top in the past 2 years and now the can is seemingly empty nothing to hang around for .
Numis is of course short for
Not
Until
Money
Is
Spent
No more fat fees so off they go to milk the next cash cow .
Hi planetx,
When I've spoken to Seraphine (LON:BUMP) (I hold) mgt, I've moaned about them using Numis - a broker that has zero interest in communicating with private investors - despite us being the people who create the liquidity & set the share price for micro caps. So they're totally unsuitable (as are Peel Hunt, and all the bigger brokers) to be involved with micro caps or small caps.
Mgt took on board these points, and also the lack of research coverage, so I see them moving to Finncap as a positive move, because they'll get some research out, and explain the company to a new pool of private investors.
BUMP mgt seemed receptive to these points, and said they were planning to do something about getting research out to PIs, hence why I'm encouraged to see the announcement today, moving from Numis to Finncap.
I remain of the view that BUMP looks finely balanced. It could join the 80% club, if it gets forced into a discounted fundraise. So this is definitely high risk.
However, it got a clean going concern statement recently (which auditors have to sign off, I believe), and its bank (HSBC) is highly supportive. This was confirmed by recent relaxation of covenants. Also having a private equity backer still holding 43% probably reassures the bank, as there's implied support there.
It's now a straightforward process of unwinding the large overhang of inventories. 70%+ of product is "continuity" - i.e. not seasonal or fashion-based, and the gross margin is very high. Therefore cashflow should be decently positive in the seasonally stronger H2.
I also told mgt I'd like to see BUMP move from a main listing, to an AIM listing, as I reckon it's carrying about £0.5m pa in excess costs right now, due to the main listing. That would be greatly preferable to a delisting, which also must be a heightened risk with this share.
This one is definitely high risk: potential high reward, so very much NOT for widows & orphans. It's an outlier in my portfolio, as I wouldn't normally touch anything this risky, but the £4m market cap is just too exciting in terms of upside, but the market might hand my *** to me on a plate. Still, it's not life-changing amounts of money.
Regards, Paul.
Paul
100% agree on bump and Numis totally unsuitable and not credible .
Good move by bump management but it should never have been a main market listing and Shoukd never have given Numis the fee fest .
Management and advisors very clearly got swept away with their ability to milk the market and forgot the basics of running a lean trading business .
Rule 1. - control the costs control the business
A lot here for me rides on the CFO, He’s the fresh blood that isn’t tarred like the previous management and a strong FD can relatively easily fix this .
Move to AIM is a definite
Turn the stock
Dave
Thank you Paul and Graham for your thoughtful, amusing, and unashamed postings. May you ever remain undaunted by criticism from the ill informed.
One day you should find the time to explain to me why STB is so cheap, possibly the cheapest stock on the market. I am an undaunted substantial holder, wondering whether to increase my holding. If it's good enough for Steven Cohen (he of enormous wealth and a bumpy reputation), it's good enough for me....
I endorse your request for Paul or Graham to take a look at £STB one day. I bought this year and held until the chart persuaded me that the sp could go either way despite what appears to be a greatly undervalued business. It's been around a long time, some past problems have gone, and it seems capable of making the adjustment from low to slightly higher interest rates (I remember 15% mortgages so current rates still seem low to me). I watched the recent piece by the CEO (PiWorld?) who seemed to know exactly where he wanted the business to go and how to get there. And the yield is stonkingly high. I'm actually tempted to go back in but perhaps there is something in the accounts that I am missing - and deciphering the accounts of a bank is a bit beyond me I think. Meanwhile there is every possibility that a year from now we will look at the chart and ask, 'Why didn't everyone realise that it had formed a base and could only rise from it?'
Edit: Secure Trust Bank (LON:STB) = Secure Trust Bank - the automatic identifier hasn't worked in this post
I think you meant Secure Trust Bank (LON:STB)
Looking at the StockReport, it is a bank that does not make money (FCF is negative half the time) and pays dividends (why) and is a retail bank (at the outset of a recession where there will be an increased number of loan failures) and the F-score is 3 (big fan, click to drill down for details) - so I am not surprised it is cheap (disclaimer I am at best averagely badly informed and so my judgement is not to be trusted)
It looks like there is a PI World interview (I have not heard it) recently.
Many here (who are not Paul or Graham) have greater powers of insight, and may be able to add value.
Hi GreyInvestor,
Thanks for your kind remarks! I've just had a quick look at Secure Trust Bank (LON:STB) - it certainly looks strikingly cheap on forward PER, and divi yields. Also a big discount to NTAV.
I suppose the market must think that, going into a recession, it could see heavy impairments against loans? It calls itself a "specialist lender", and over the years I've seen quite a few of these get into trouble, because they take on borrowers that nobody else wants - fine in the good times, but then big defaults emerge in recessions.
The website says it's been around since 1952, which if accurate could be seen as reassuring. Although as we saw in the 2008 GFC, even major banks can be blown up by bad management, regardless of the history (e.g. Fred the shred).
I'll see what Graham thinks, as I rarely look at accounts from banks, as I find them too complicated, and too dependent on estimates for highly material items like impairments.
Interim (to 6/2022) profit was well down on prior year. It will have to pay more to savers on their cash, and I wonder if there's a time lag before it can raise interest charges to borrowers maybe?
Balance sheet equity of £314m. Total lending to customers is £2.75bn, so that looks a reasonable level of gearing, given that risk should be spread over many customers. £2.3bn of deposits from savers, about half of which are term deposits, which would reduce the risk of a run on the bank, I assume.
Outside of my area of expertise, but I can see why you think it looks cheap, on a mkt cap of £121m.
Banks are capitalised & regulated much more strongly now than back in 2008, so hopefully we won't see a repeat of that systemic meltdown.
Regards, Paul.
Thanks Paul.
I agree that in the short term rising interest rates are a problem. Mainly because car loans and sometimes property loans can be at fixed rates. STB admits this. So margins get squeezed over 3 years. On the other hand, interest rates are projected to fall within a year or two by some parties.
Also provisions were raised substantially. I regard this as a good thing.
If I remember correctly, divis are set at 25% of EPS, so they may shrink a bit.
But....STB have been a very shrewdly run Brummie bank. They have shape shifted a few times, and spun off serious subsidiaries. If you don't believe me, look at the NTAV per share. The shape shifting has created serious shareholder value.
This is a bank which borrows short and lends short; on cars, serious property, and on consumer goods. I dislike the latter, newer business, but the compnay should get a quick read on default rates. If you buy a sofa on 'free tick', it could be STB behind it.
My view is that earnings will fall as margins get squeezed and provisions rise. But the compnay is determined to run on a 5% margin in the future. So in a couple of years hopefully a growth business with good margins will emerge.
This is just my view; I'm an amateur investor. And I have a decent sized, long term, holding.
I would recommend doing a check of their products,
I tried to open a savings account with them but found the process to be 20 years out of date. I bailed and went to Atom where I was up and running in a few minutes.
Night and Day from a customer perspective.
Unless they invest heavily on the back end processes and front end website, I can't see them retaining market share personally, any IT savvy person would just walk away.
I had an account with them and had quite a few issues, don't forget your password, otherwise lots of problems getting it reset, read the reviews on Trustpilot, I'm not alone. Fortunately I had 1 months free phone calls, otherwise it would have cost me a lot of money. Takes ages to get through by phone, emails very slow response time. Yes antiquated is how I would describe them. Much better places to invest at the moment.
Hi
WANdisco (LON:WAND) has another contract win.
https://www.investegate.co.uk/...
I am not sure if this repeats the contract win of the 13th Dec or is an additionally one. I suspect they are one and the same as this RNS is both the contract win and a trading update as well and they are using it to reiterate their record bookings FY22 statement.
Happy to be corrected if it a new one.
Regards
Howard
The thing I find very difficult with WANdisco (LON:WAND) is the technology and understanding whether it offers sustainable advantage.
I'm in IT but not big data. A bit on IoT though, so not ideally placed - but knowledgeable enough to be curious.
I watched a couple of videos but still can't think more than "so what? What makes you different?". I suspect their salespeople are more important than the technologists. Which of course is a well trodden path, so maybe that is it.
Anyone out there used their services?
Checking their website is interesting.
They seem to rely heavily on Gartner's comment "WANdisco's ability to move petabytes of data without interrupting production and without risk of losing the data midflight is something no other vendor does".
This is an opinion that the company doesn't need to prove is true! It can stay there even after the facts change, even if they once existed. It is like the customer quotes "XYZ always give great service". You know it is not true for everyone, even if it was true for that one person. That is why companies love using them!
I have to ask myself can't Microsoft, Google, Amazon, Oracle transfer petabytes of data without going offline or irreversibly losing data? I find that amazing!
Also they show the "Magic Quadrant", but WAND aren't on it ... So why show it? Or is this a corporate website template, but the intern didn't understand what they are doing?
(sorry this is a bit of a stream of consciousness post)
The thing I find very difficult with WANdisco (LON:WAND) is the technology and understanding whether it offers sustainable advantage.
I have to ask myself can't Microsoft, Google, Amazon, Oracle transfer petabytes of data without going offline or irreversibly losing data? I find that amazing!
I'm in the same boat - IT industry for decades with good broad knowledge though no data specialist. What is their secret sauce? From what I can tell reading into the CEO's recent output, they are gaining traction within the likes of Jaguar, and using that and similar relationships as a bridgehead into the broader industry. As it happens Jaguar used to be a big client of mine but not for data services. My experience is that car manufacturers are very much NOT the leading edge when it comes to software development - and very cost sensitive. So perhaps the likes of Jaguar are happy dealing with a cheap local supplier rather than going with - and being locked into - the more demanding hyperscalers. But they have to put the data somewhere in the cloud and that means engaging AWS, Azure et al, so maybe the product really does something new and unique - until a well capitalised US competitor turns up with better tech and, more to the point, a much bigger marketing budget!
I thought most people used rsync / lsyncd (linux / unix free tools), though in more business-critical environments, perhaps some sort of process to assure the copy is complete and accurate for audit may be something you could sell.
(it is a shaky memory but I think something like that was in use at a coventry based car manufacturer about 13 years ago - i was not directly incolved)
Having worked in IT starting in 1970, I was curious and I did a lot of digging into WANdisco (LON:WAND) years ago. I decided all the good news was already baked in. The company name derives from Wide area network distributed computing and they have changed their target audience a couple of times but now concentrate on migrating customers to cloud computing. Not just storing data in the cloud but also using the compute power and communications. Web based data providers and users communicate directly to AWS et al and the on premise part shrinks to being the equivalent of a remote user once migration is complete. The intervening part is where Wand come in. There must be built into the software that runs on the cloud system and the on premise system some means of recording which data has been copied across to the cloud and whether it has changed since copying in the same way that Backup programs save time by not copying data that hasn't changed. Eventually (and depending on internet bandwith that could be some time) all the data is on the cloud server and all applications using that data are on the cloud server. Answer to how it's done is probably slowly, and probably frequently changing data done first (with a database I would guess there would be additions but not changes)
My question is are there presently enough big data customers to migrate to keep wand busy enough to repay an investment. Future big data imho will go straight to the cloud anyway, their ebullient CEO has sold about £10M worth as shown on Stocko so doesn't inspire me. I don't think in its present form it has a long future.
Palace Capital (LON:PCA) give an update on their disposal programme today selling a small number of. For those unaware, Palace Capital (LON:PCA) is effectively winding down having announced an abrupt change of strategy in July, following rebellion by shareholders, when it said: "The Board will therefore now focus on maximising cash returns to shareholders, whilst continuing to remain mindful of consolidation in the Real Estate sector as part of its considerations."
Of course this was bad timing because of interest rate rises and the hit to commercial property, so the strategy is expected to be executed over a longer period now. The NAV per share at the last review was 336p so there is some decent upside from here (215p) if they can sell properties close to NAV. If the economy recovers I would expect book value of their properties to rise further so there may be more upside than first appears as the NAV per share in March was 390p.
Journeo (LON:JNEO) acquisition of IGL seems to have gone down well with the market even with a placing @105p, I was surprised at the 10% uplift in S.P in early trading.
£12 million revenues and £2 million pre tax profits is significant, and paying off debt with the spare cash from the raise is all very positive.
I guess the question is how well will the management handle this fairly significant step up in revenues, and absorbing the newly acquired business....
I liked the idea of buying in around 105p...so will see where it goes from here.
(I don't currently Hold)
Agreed . Looks transformational from a scale perspective both in general and in rail in particular and for Journeo’s balance sheet given the free cash acquired . combined order book of over GBP 50mn .does mean it’s all about execution now but the recent track record has been good and I think the 2 businesses are well known to each other given geography. Censos note has 17.8p for next year giving no value for the cash acquired . Very cheap acquisition bearing this in mind
The business that Journeo (LON:JNEO) are acquiring has £3 million in net cash as well so an EV/EBIT multiple of less than 3, so a fantastic deal even without the suggested synergies and cross selling opportunities. Journeo (LON:JNEO) is not the highest quality business but this is a sector receiving a massive government cash injection to modernise public transport(Transforming Cities, Bus Back Better , Williams-Schapps) so it has strong tailwinds behind it and post acquisition trades on an ex-cash PE of 5
"... Malbec and Baileys has been swilling around ..." - just the thought of mixing those makes my stomach turn!
Thank you Mr Contrarian, for years of brilliant early morning information, sardonic wit and insight.....
Character (LON:CCT) feeling optimistic for 2023 and positive read across for other exporters - about time we had some optimism!
"This being said, as we look ahead on the back of a strong 2023 offering, international sales are forecast to grow significantly in the second half of the current financial year with margin improvement from that time. Although we expect domestic sales to be flat in the second half, the substantial reductions in freight rates, together with reduced costs of production from factories in China and strengthening of Sterling against the US Dollar from its recent low point has given the Board considerable optimism for a second half rebound."
Just wanted to say thanks to you and Graham for the insights that you post every day (including weekends) that have helped a middle aged novice investor like me no end. It's been a steep learning curve since I joined Stocko in February, and I've made a few daft decisions. I'm pleased however, that my position has now improved significantly and I'm only slightly down on the year.
Thanks again, and Nadolig Llawen a Blwyddyn Newydd Dda o Gymru. (Merry Christmas and Happy New Year from Wales).
Best wishes to all
Oh, and a shout out to MrContrarian for his work too.
Hi TheRaven,
How kind, thank you, much appreciated :-)
I agree wholeheartedly about MrC, his early snapshots are just superlative, and incredibly helpful to many of us! What a great guy :-)
Best wishes, Paul.
Crestchic (LON:LOAD)
Mr Robert Persey and family appear to have bought over 919,000 shares which surely cannot be because he expects to make a few pence per share when the takeover concludes. Mr. P is a significant investor in a number of companies so I wonder if he expects to see a higher offer. I Hold.
https://www.londonstockexchang...
RE: Crestchic (LON:LOAD)
Mr Robert Persey and family appear to have bought over 919,000 shares which surely cannot be because he expects to make a few pence per share when the takeover concludes. Mr. P is a significant investor in a number of companies so I wonder if he expects to see a higher offer. I Hold.
This is a standard announcement required of all holders of more than 1% of the stock following a takeover announcement. It's merely stating their current holding, there's no indication that they've bought any. Loads of these Form 8.3's have been issued by holders in the last few days.
timarr
thx timarr. I find these holdings RNS to be not exactly obvious on many occasions. Good to know someone understands them.
thx timarr. I find these holdings RNS to be not exactly obvious on many occasions. Good to know someone understands them.
Absolutely agree. Why the FCA can't redesign these so they're written in plain English is beyond me. It's almost like they want to make it difficult for people to understand what's going on ...
timarr
I think if you scroll down to section 3 there is sales or purchases, if not blank
But it is their interest, does not mean it is a recent buy, can't see when they bought these shares, could have been when company floated.
I agree these forms are bad.
I never understood these , I had thought these holders of significant % were all taking out short positions in case the bid falls apart .
So they effectively insure that risk ? Maybe Paul can explain
I never understood these , I had thought these holders of significant % were all taking out short positions in case the bid falls apart .
Err, I don't think so. It's a regulatory requirement, nothing to do with trading of any kind, short or long:
Under Rule 8.3(a) of the Code, any person who is interested in 1% or more of any class of relevant securities of an offeree company or of any securities exchange offeror (being any offeror other than an offeror in respect of which it has been announced that its offer is, or is likely to be, solely in cash) must make an Opening Position Disclosure following the commencement of the offer period and, if later, following the announcement in which any securities exchange offeror is first identified.
Etc, etc. Detail is here if anyone is interested (but frankly, if you are it's time to go and stuff the turkey instead, assuming you can afford one after the nightmare before Christmas that the markets have been this whole year):
https://www.thetakeoverpanel.o...
timarr
Think you have misread the RNS, which is not surprising on here, can't something be done about the format of these, very difficult to read.
They have to declare their interests, holdings and any short interest.
Cheers!