Small Cap Value Report (Thu 22 Feb 2024) - MEGP, TRCS, ANG, HL., MRL

Good morning from Paul & Graham.
CEO interview - Beeks Financial Cloud (LON:BKS) [I hold] - I interviewed founder/CEO Gordon McArthur again today, hopefully you might find this interesting. It's gone out on my podcast channel, or the web version is here.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
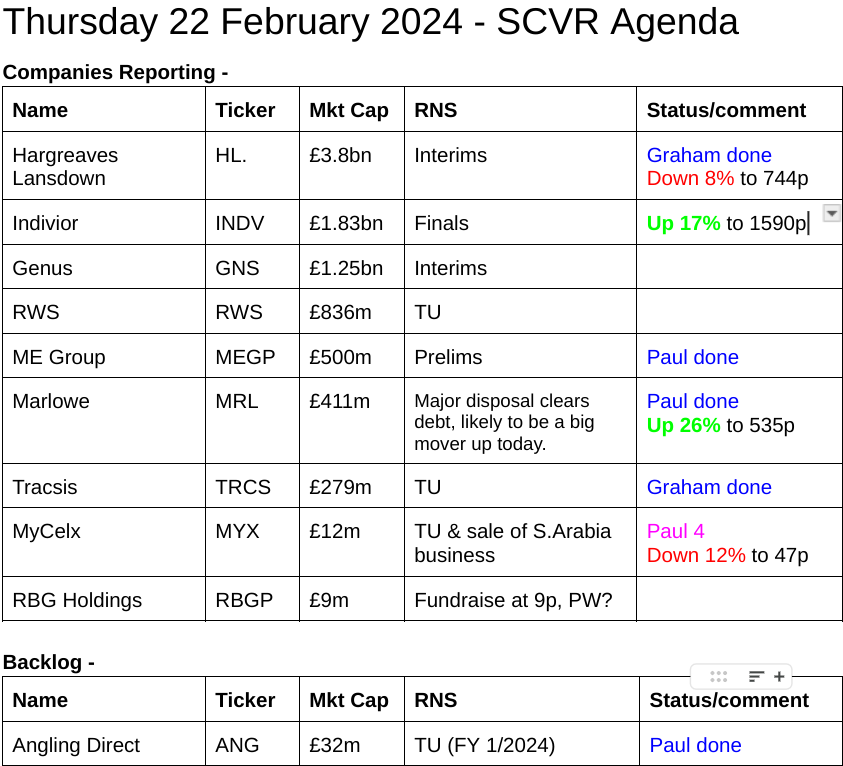
Quiet for small caps, so I've included a few mid-caps too, which we might get round to looking at. As always, this is a list of which companies are reporting, and we can't necessarily cover everything -
Other mid-morning movers (with news) -
Beazley (LON:BEZ) - up 9% to 634p (£4.3bn) - another mid-cap, insurance company saying it’s trading well. Looks cheap on StockReport metrics, and well-capitalised (similar to Cre (TYO:3458) that reported earlier this week). Announces a substantial $300m additional shareholder return, above usual divis. Not my sector, but looks interesting.
Rolls-Royce Holdings (LON:RR.) - up 9% to 358p (£30bn) - market responds positively to strong turnaround FY 12/2023 results. “Strong momentum” for 2024. Surprisingly weak balance sheet though, but the market doesn’t seem to mind! Shares have been a stunning performer in last 7 months, up from 150p to 358p!
Summaries
ME International (LON:MEGP) - 133p (pre-market) £500m - Prelims FY 10/2023 - Paul - GREEN
I review FY 10/2023, which are in line with expectations. This looks a superb business, at a remarkably attractive valuation. Thumbs up from me.
Tracsis (LON:TRCS) - down 4% to 890p (£268m) - Trading Update - Graham - AMBER
An in-line update has been met with softness in the share price, perhaps reflecting the high expectations baked into valuation. H1 numbers are uninspiring but as previously flagged, the company is expecting a big improvement in H2. I’d expect more M&A before too long.
Angling Direct (LON:ANG) - up 2% to 41.5p (£32m) - Trading Update FY 1/2024 [in line] - Paul - AMBER
An in line TU for FY 1/2024, despite disruption to anglers from recent storms. Net cash pile is now about half the market cap (it was almost all of it at start 2023, when I was bullish on the valuation). Trouble is, it's just not a very good business, making wafer thin margins in a very competitive sector. So is this a good use of capital? I'd say not, and shareholders should push for a return of cash. Probably priced about right now.
Hargreaves Lansdown (LON:HL.) - down 7% to 748p (£3.55bn) - Half Year Report - Graham - GREEN
There’s a negative reaction to these results which include evidence of excessive strategic spending and impairments of prior projects, passed off as exceptional items. On a long-term view I do continue to view these shares as too cheap for the market-leading wealth platform.
Marlowe (LON:MRL) - up 22% to 520p (£503) - Disposal & Board Changes - Paul - AMBER
A giant disposal looks set to repay all the (too high) debt, and give scope for about 30% of the market cap to be returned to shareholders in some kind of distribution. Shares are now a special situation, to work out if the remaining business is good value or not. I don't know, so will just mark it AMBER now, up from my last amber/red when debt was worryingly high.
Paul’s Section:
ME International (LON:MEGP)
133p (pre-market) £500m - Prelims FY 10/2023 [in line] - Paul - GREEN
This operator of photobooths, self-service (often outdoor) launderettes, and other self-service kiosks, is one of my favourite value/GARP shares, and made it onto my top 20 share ideas for 2024 list here. So I’ll review it first today.
We last looked at MEGP on 30/11/2024, when Graham reviewed its FY 10/2023 trading update, indicating revenues would be slightly below expectations at c.£298m, but that a focus on profitability means PBT would be at least £67m (top end of guidance).
Here’s the highlights table, and the key PBT number is as expected, so this is in line with expectations as provided in the 30/11/2024 company update -
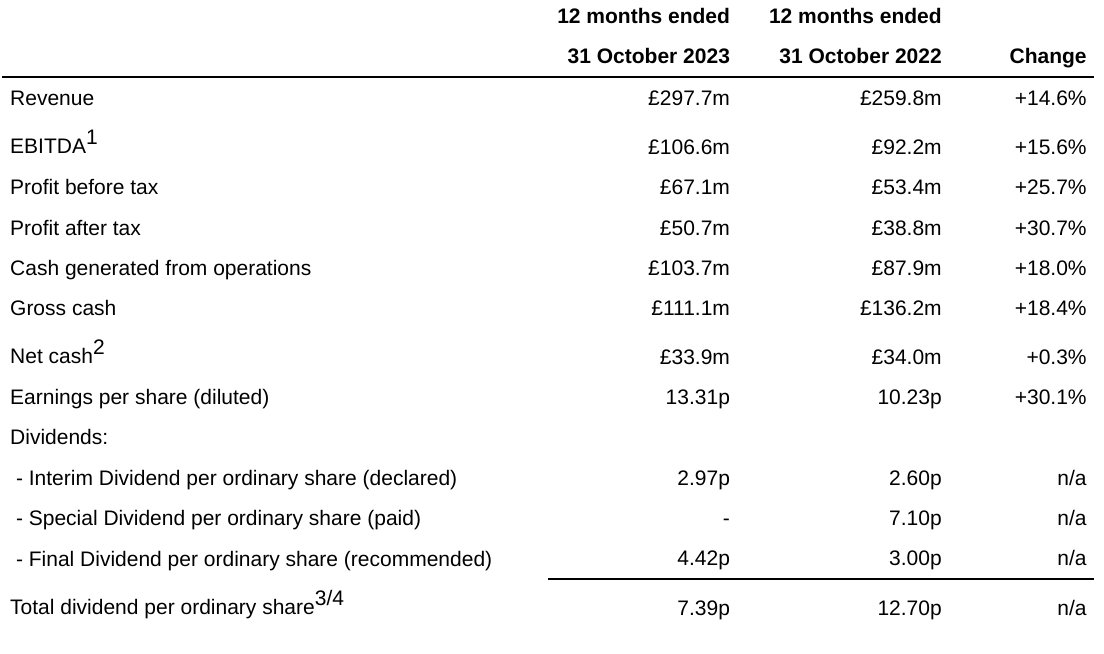
That’s impressive profit growth.
The PER is 10.0x, using the 13.31p diluted EPS figure above and 132p share price (pre market).
Yield is another key attraction with MEGP shares, and 7.39p divis above yields 5.6%, plus it pays special divis on top sometimes, and is doing buybacks actively too.
MEGP has net cash too, unchanged at £33.9m, despite heavy capex to modernise & expand its booths, and the generous shareholder distributions.
You can see why a lot of us here like this share (it’s the most viewed on Stockopedia so far today).
Broker research is thin on the ground for us. Cavendish has put out a flash note saying today’s results are fine, and that they’ll do a full update at a later date.
The StockReport shows 13.0p broker consensus, so the 13.3p above actual looks a bit ahead, although broker forecasts often contain adjustments, so I need to wait for Cavendish’s update to be certain.
This all (below) sounds positive too - MEGP is clearly a company on the front foot, expanding, and trading at record profitability, which makes its modest valuation even more perplexing! Is this a bargain share? It certainly looks like it to me.
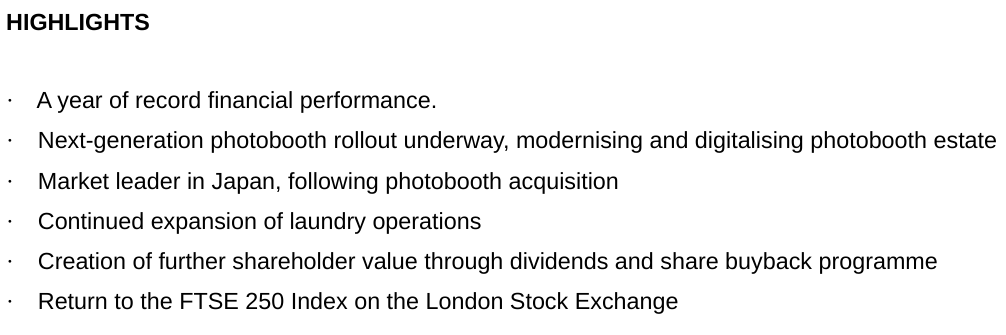
Laundry division - I think the market has missed how important, profitable, fast growing this division is -
Our laundry operations, a key growth driver for the Group, performed particularly strongly and our expansion continued at pace…
I mystery shopped laundry here, after my own washing machine broke and I had to wait a fortnight for a new one, coming away impressed. It’s a niche service, particularly useful for people who are travelling away from home, or need a large machine for washing duvets, curtains, etc. They’re often sited with other self-service machines, in carparks, outside areas of petrol stations, etc, hence low overheads. It’s a clever service that is doing well, so MEGP shares are now much more than just photobooths (the original core business).
Photo booths - maybe MEGP shares are lowly rated because of fears that tech might eventually remove the need for photo booths? People have been saying that for the last 20 years, but there’s no sign of any demise occurring so far, and tech improvements could reinforce the need for these machines, and create a bigger moat maybe? -
Demand for photobooth services remains robust and we continue to develop our relationships with governments and regulatory bodies for our digital and secure photo ID services.
"The modernisation and digitalisation of our business will drive operational efficiencies and improve the services and experience we offer. Our next-generation photobooth is being rolled out at pace, bringing a multi-service offering and seamless user experience, backed by proprietary software. This is just one of many initiatives we are driving forward, underpinned by our strategic focus on digital innovation. We are also working on a range of additional service features and functionalities that could attract more consumers to use our instant vending equipment.
Food division - not going well, with some problems, but it’s very small, so I’m not bothered about this. I still haven’t managed to mystery shop the pizza machines!
Geographies - nearly all the profit comes from continental Europe -
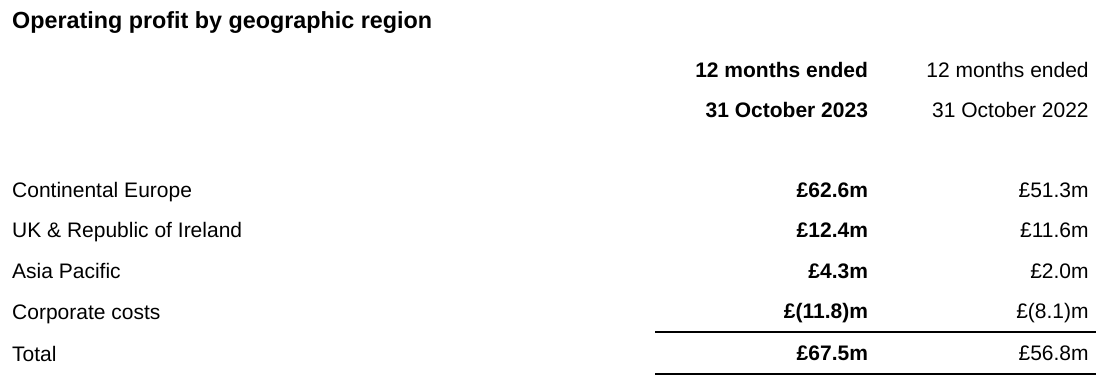
Finance income - was nothing last year, but rose to £1.4m in FY 10/2023, usefully mitigating the £2.5m finance costs. I still don’t understand why MEGP has both a large cash pile, and simultaneously has bank borrowings, does anyone know?
Outlook - none of the “profitable growth” PR fudge here! MEGP directly says that it’s expecting higher profit in FY 10/2024, which I like -
"The Board looks ahead to the future with confidence and, notwithstanding changes in the macro environment, expects the Group to build on the success of FY 2023 and achieve continued revenue and earnings growth in FY 2024."
Stockopedia is showing a modest increase from 13.0p (FY 10/2023) to 13.5p (FY 10/2024). So I think this looks nicely set up to surprise on the upside as this new year unfolds.
Unless something goes wrong, then I think we can probably attribute an >50% probability that MEGP may announce ahead of expectations updates later this year, because it is expanding quite fast with new laundry sites, and talks about improving margins in the commentary too.
Balance sheet - looks healthy to me. NTAV is about £127m, mostly fixed assets of £118m, as I would expect.
Cash is £111m, partially offset by “financial liabilities” (see note 8) of £58m and £32m, £90m total.That comes to net cash of £21m. Note 8 below shows net cash of £34m. The difference is £13m lease liabilities, which I ignore because they are not debt, but are actually future years operating costs. So the real world net cash position is as shown below, £33.9m - very healthy.
Note there is a small £4m pension deficit.
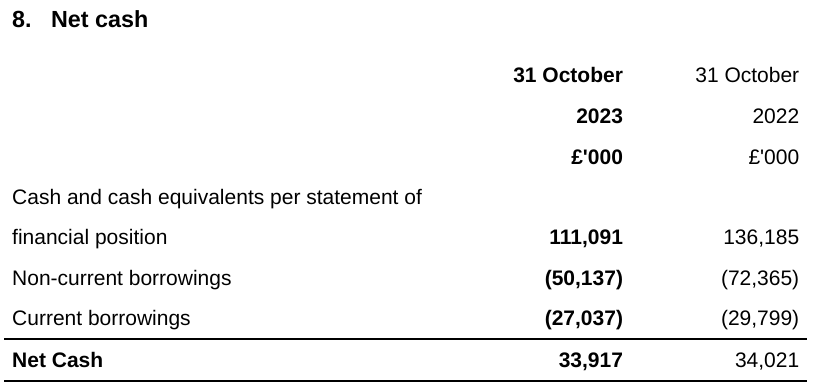
(table above excludes £13m lease liabilities)
Cashflow statement - is absolutely lovely, it gives me pleasure to review such strong figures.
MEGP generated £104m operating cashflow (LY: £88m), which was used mainly as follows:
Tax paid £20m
Acquisitions £5m
Capitalised intangibles £3m
Capex £46m - very considerable, for new machines of course, but entirely self-funded.
Dividends £23m
Overall then, MEGP is a highly cash generative business, which is self-funding its own expansion, whilst paying generous shareholder returns. It also used some of the cash pile to reduce gross debt, which I'm pleased to see.
Paul’s opinion - why is this share so cheap?! I just think it’s the wrong price. I would value this share at 200-250p. Providing nothing unforeseen goes wrong, I think patient investors could do very well here - looking in an attractive income stream, and at some point in the future this share should re-rate, once the UK market recovers from its current malaise.
The owner/managed owns 37%, I wonder if he might sell the business to retire at some stage? So a premium takeover here is an interesting upside possibility.
My view is that the current dislocated UK market is offering us wonderful buying opportunities, so instead of fretting over why things are cheap, and will they ever recover, I am just excited about being offered such marvellous value for an excellent company here.
Angling Direct (LON:ANG)
Up 2% to 41.5p (£32m) - Trading Update FY 1/2024 [in line] - Paul - AMBER
Angling Direct plc (AIM: ANG), the leading omni-channel specialist fishing tackle and equipment retailer, provides the following unaudited trading update in relation to the financial year ended 31 January 2024 ("FY24"), ahead of announcing its Final Results on 14 May 2024.
The Board expects to report overall trading for FY24 in line with market expectations1.
1 Angling Direct believes that current market expectations for the year ended 31 January 2024 are revenues of £83.0 million and pre-IFRS 16 EBITDA of £2.7 million.
Nice and clear reporting there, with a footnote. My only suggestion for improvement would be to disclose adj PBT as well as/instead of adj EBITDA.
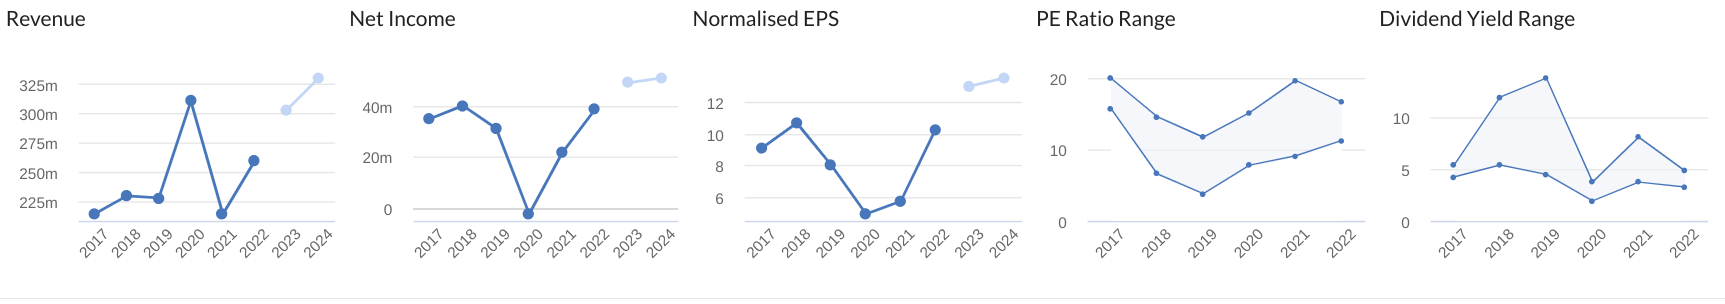
Singers helps us out, with an update today, translating £2.7m adj EBITDA into £1.1m adj PBT, and 1.1p EPS.
Revenue is £81.7m (a slight miss blamed on recent storms).
Profit margin is wafer thin, with only £1.1m adj PBT on £81.7m revenue, so it’s a low quality business of little interest to me.
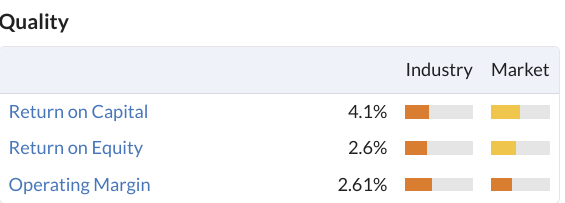
That said, a key feature of ANG’s accounts is that it’s carrying loads of surplus cash, which I like, but it does suppress some quality measures. Maybe we should manually recalculate quality measures at companies with obviously surplus cash, to remove the cash in order to see the true underlying quality of the business?
Like-for-like store sales only grew 3.2% for the year, well below inflation and wage rises.
Online growth was better, at +13.5%
Net cash is £15.8m, up from £14.2m a year earlier.
This supports about half the market cap, but it rather depends what the company intends doing with this cash pile? So far mgt have hoarded cash impressively, it would have been easy to squander it. With such low returns on capital invested, is it worth opening more fishing shops, and tying up loads of capital with fit-out costs, and large inventories?
Shareholders should be pushing for a return of capital I think.
Paul’s opinion - ANG shares were a star performer up 68% on my 2023 top 20 share ideas here. Actually, my 2023 top 20 have continued to out-perform (the spreadsheet is still updating prices live every day), with this (unamended) top 20 now 31% ahead of AIM, with only 5 fallers, and 15 gainers. Not bad going eh!
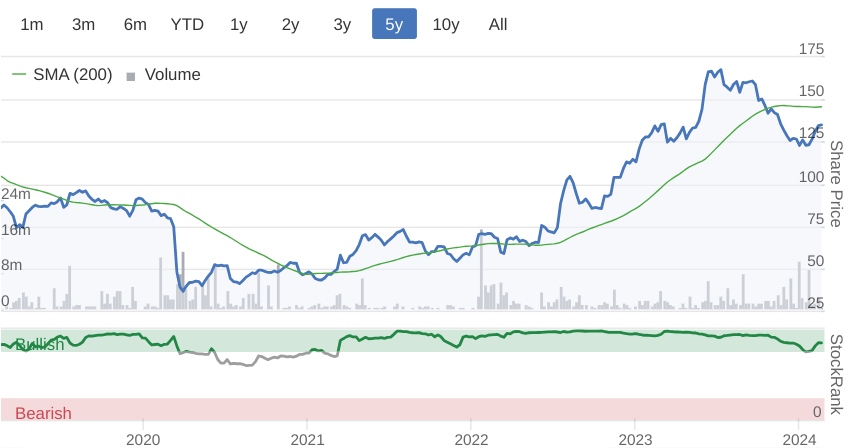
I put ANG on my 2023 list at 25p because the business was valued at almost nothing, with cash supporting almost the entire mkt cap. Since then it’s risen a lot, so I no longer see such strong support from cash, now about half the market cap.
The business itself is low margin, quite capital-intensive, and unexciting, operating in a very competitive area. So I don’t see much upside on the share price from this level, hence I’ll remain at AMBER, same as the last 2 times we looked at ANG on 17/5/2023 and 23/8/2023.
Shares have good momentum now though, so it might keep rising, who knows?!
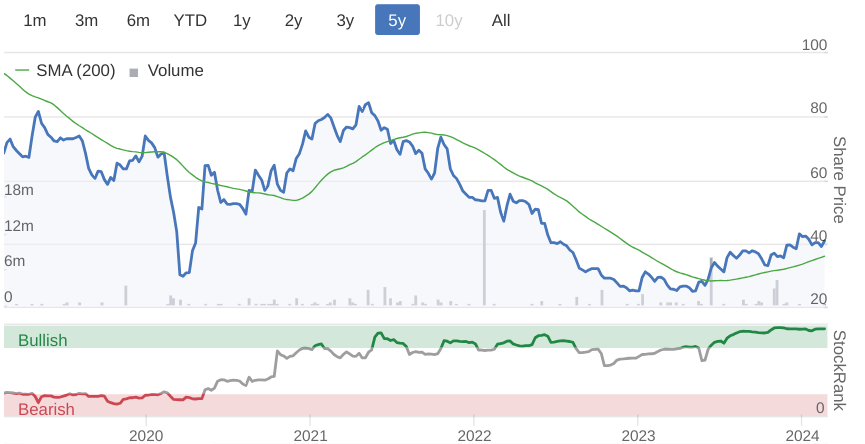
Marlowe (LON:MRL)
Up 22% to 520p (£503) - Disposal & Board Changes - Paul - AMBER
This announcement has added almost £100m to the market cap of this overly indebted, highly acquisitive (36 deals in 3 years!) software group.
Today it announces a huge deal - slightly greater than the whole group’s market cap last night -
Marlowe plc ("Marlowe", the "Group" or the "Company"), the UK leader in business-critical services and software which assure regulatory compliance, announces that it has entered into a binding agreement for the sale of certain Governance, Risk & Compliance ("GRC") software and services assets (the "Divestment") to Inflexion Private Equity ("Inflexion") ( the "Purchaser"), for an enterprise value of £430 million on a debt free, cash free basis (the "Transaction")...
representing a multiple of 16.2x proforma adjusted cash EBITDA1 in the year ended 31 March 2023 ("FY23").
Stockopedia shows the existing EV/EBITDA multiple for the whole group at 13.6x, so the disposal looks to be at a premium to the existing valuation.
This sounds like a good deal -
The enterprise value of the Divestment, which accounts for approximately 20% of Group revenues and 40% of Group adjusted EBITDA, represents 121% of Marlowe's market capitalisation as at 20 February 2024 and 121% of Marlowe's market capitalisation based on a 3-month volume weighted average share price as at 21 February 2024.
Use of the cash -
The Group intends to use the proceeds of the Divestment (the "Net Cash Proceeds") to retire in full its current debt facility and return in excess of £150 million of surplus cash to shareholders.
That shareholder return is about 30% of the latest market cap.
The current CEO moves out with the disposal, so a new CEO is being sought.
Paul’s opinion - this completely changes the business, and deals with my main worry at MRL of excessive debt.
Without seeing pro forma accounts/forecasts for the new group, I can’t give an opinion on the new fundamentals. Although now that risk from debt has gone, I’m happy to shift up from amber/red to AMBER.
Despite this looking a decent deal, overall MRL has been a disappointment over the last 5 years. Although I wonder if there might be more hidden value in the group, given that private equity seem happy to pay higher valuations than the UK public market?
Anyone buying or owning now at c.£500m market cap, looks set to receive about 30% of that back in a shareholder return, so the question is whether the remaining, debt-free business is worth £350m? I don’t know, but maybe there could be a special situation here worth researching, for experts who know how to crunch the numbers in this type of situation?
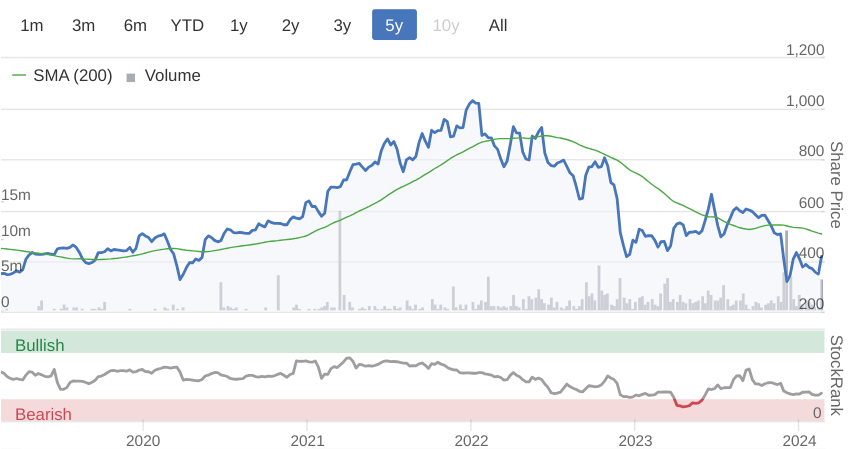
Graham’s Section:
Tracsis (LON:TRCS)
Share price: 890p (-4%)
Market cap: £268m
This is “a leading transport technology provider”.
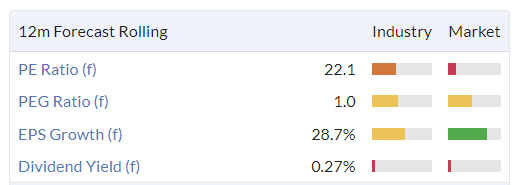
Writers in the SCVR have often remarked on how expensive it is, and it remains expensive today:
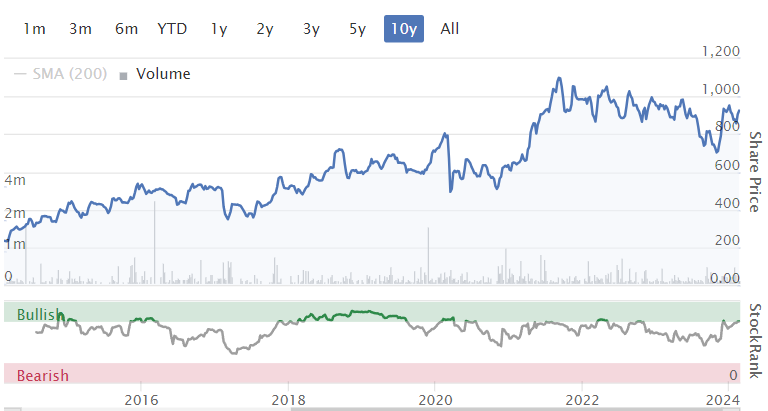
But its acquisition growth strategy has succeeded over the years, leading to a good outcome for shareholders:
Today we have an H1 update for the period to January 2024.
Performance has been “consistent with expectations”:
Key points:
Growth will be weighted to H2 (they’ve flagged this before).
H1 revenue in excess of £36.5m (H1 last year: £39.2m).
Adjusted EBITDA margin 16% (H1 last year: 19%).
The reason for the decline in profitability is higher spend on managers and the sales force, or in the words of Tracsis: “the investments made in the prior year to enhance the Group's senior leadership capabilities and to accelerate the growth of our pipeline of large multi-year opportunities”.
The adj. EBITDA margin is expected to recover over the course of H2.
Cash is virtually unchanged year-on-year at £16.8m, leaving Tracsis “well positioned to continue to invest in its technology base and further acquisitions”.
Exceptional costs: There are £2m of exceptional costs for the full year (mostly incurred in H1) to “transform its operating model and to accelerate its future growth trajectory.”
This sounded vague to me, so I’ve gone back to the full-year results for a reminder of what this transformation plan includes.
The answer is:
“...headcount reductions where roles are duplicated or are no longer required; streamlining our legacy entity and operating footprint; implementing a single groupwide IT support service; and upgrading systems to deliver improved management information.”
When a company has a large and unusual reduction in headcount, I don’t have any major objection to treating the associated cost as an exceptional item. However I’m always a little sceptical when IT and system upgrades are treated as exceptional, because it seems to me that companies always need to do this every few years. At the end of the day, it’s a judgement call for investors.
Outlook
After all the spending on the sales force, the company reckons that its addressable pipeline has doubled in the UK/North America:
We continue to see significant software growth opportunities in the UK and North American rail technology markets, as the industry looks to modernise and adopt digital solutions. The actions taken to transform our operating model and to accelerate pipeline growth leave the Group well positioned to deliver further growth.
Graham’s view
We have baulked at the valuation in this report and I think we can perhaps find some justification for that stance in recent performance.
Unless I’m mistaken, the last acquisition by Tracsis was in March 2022. Without the support of an acquisition to boost things, the company’s revenues and profit margins have begun to decline, although it’s also true that the company has signalled for a stronger performance in H2.
Estimates from Cavendish suggest that Tracsis will post some revenue and profit growth this year, on an adjusted basis:
Revenues to grow from £82m to £85.2m
Adj. EBITDA to grow from £16m to £17.7m
Adj. PBT to grow from £13.7m to £15.6m
Overall, however, I’m struggling to understand why this is valued at its current level. ROCE has been fairly average:
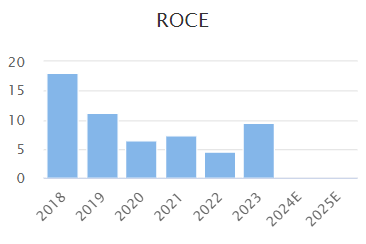
Maybe I just don’t appreciate the underlying quality and the long-term growth opportunity, particularly in the Rail Technology and Services Division.
If you’re interested in learning more about the products in that division, here’s its homepage.
Some of the products do sound monopolistic in nature, e.g. “we have the only Rail Delivery Group (RDG) accredited PAYG ticketing solution” and “we provide 90% of the UK’s delay repay services”.
I’m very comfortable with a neutral stance here.
Hargreaves Lansdown (LON:HL.)
Share price: 748p (-7%)
Market cap: £3.55 billion
(Graham has a long position in HL.)
I turned positive on this one when the shares were trading around 800p; the market doesn’t agree with me yet:
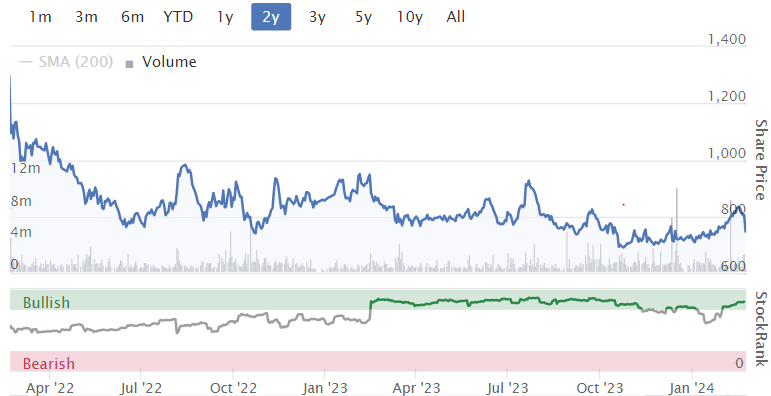
Today we have interim results for December 2023.
Headline numbers:
Assets under administration up 6% over six months (£142 billion)
Net new business £1 billion
Revenue up 5% to £368m
Unfortunately the higher revenues haven’t translated into higher profits; PBT falls 8% to £182m.
Let’s skip down to the financial review and quickly find out the reason for this.
The company argues that “underlying” PBT is up 5%, if you’re willing to look past £39m of adjustments:
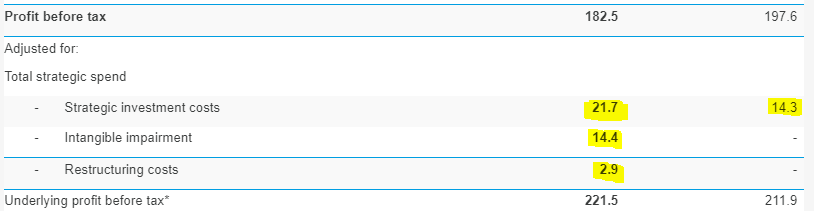
The big number here is “strategic investment costs”, which reminds me of the “transformation” spending I’ve just been covering at Tracsis.
There was also £14m of strategic spending in H1 last year. So how exceptional is it really?
I also note that the £21.7m figure that was expensed is not even the full amount; another £3m was capitalised and put on the balance sheet.
Here is the company’s description of what the spend is achieving:
The level of spend has increased as expected during FY24 as we continue to build momentum, commencing new material programmes of work including on Service Transformation, driving improvements to our Helpdesk client experience and efficiency in relation to our Workplace product offering and in relation to the scalability and efficiency of our core payment and reconciliation processes.
I don’t think I can get behind the idea that this spend should be treated as exceptional.
The £14m impairment expense from the table above also doesn’t strike me as exceptional, as it relates to work previously done - and put on the balance sheet - that is now being abandoned:
…£7.2m in relation to software that was developed to support a client financial health check tool and £7.2m on development of a tool to improve efficiency for Financial Advisors for which there is now no intended future use.
It’s worth bearing in mind that HL has a new CEO (joined six months ago).
It also has a new Chief Strategy Officer, with consulting experience, who has been “driving our strategic agenda and digital transformation initiatives forward”.
Personally, I’m in the camp which says that CEOs should be running strategy, not delegating strategy to someone else. It’s just a matter of opinion, and others may disagree. But I strongly believe that a CEO should be driving the agenda of a business and taking responsibility for its strategic success or failure. Otherwise what is the CEO really doing?
In any case, the new CEO and the new CSO at HL clearly feel comfortable ramping up spending and discarding some of the previous projects at HL. Whether or not this is the right course of action, I would not ignore the financial costs associated with these actions.
Other aspects of performance worth highlighting:
Strong market returns: market movements pushed up assets under administration by over £7 billion, so that total AUA has been able to grow strongly even with limited net new business.
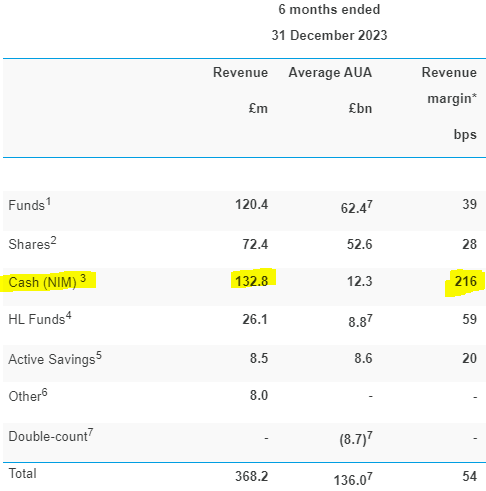
Interest on cash: this is of great importance considering the FCA’s involvement in the subject (and the situation at Jarvis Securities (LON:JIM)). HL has retained 41% of the interest it received during the period, passing on the rest to customers. The portion of interest it retains seems to be going down, with c. 36% retained in Q4.
I must say that I agree with HL that these rates are very competitive, being the rates that are passed onto customers:
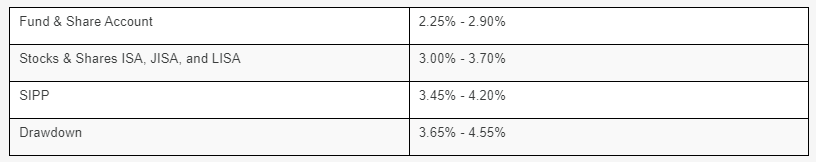
HL’s revenue on cash has ballooned in recent years as rates have risen. Earning interest on cash is now one of its most profitable activities:
Graham’s view
Despite a few points of worry, I remain bullish on the outlook here.
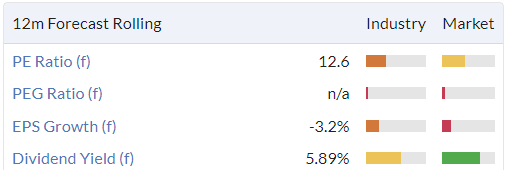
It’s not terribly expensive:
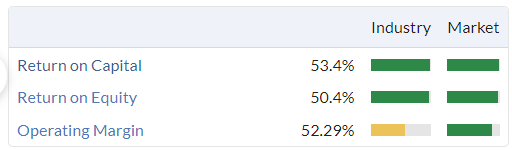
Returns are enormous:
Besides the heavy strategic spending, bears might also point at the high margin earned on cash and argue that it's unsustainable (as interest rates will eventually fall), is vulnerable to increased regulation by the FCA, or both.
I’m open to that argument but I’m also inclined to think that this risk is priced in already. I’d also point out that revenue from share trading is likely to improve during those times when investors are more inclined to trade regularly.
Even the outlook for platform fees on funds might be quite good, if you share my optimism that net new business will improve. I wouldn’t mind owning a few more shares in this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

117 comments
I see that today the most moderated person is also the person I read (from them) is most bullied on this site! Which is deeply ironic as I read they are the most right.
Will the injustice never end?
LNSK
Hargreaves Lansdown (LON:HL.)
Hi Graham
Thanks for your thoughts here.
There's an interesting slide in the results presentation today showing that c£100m of the total £225m Strategic Investment budget has been spent so far, with the remaining £125m expected to be spent over the next few years until FY26.
Spend per annum looks to be c£45m.
Hargreaves Lansdown (LON:HL.) looks like an amazing company and a part of me wants to pick up a few given the relatively cheap price (I calculate an FCF yield of c10%!).
However, these ongoing Strategic Investment costs are putting me off and will, I think, result in profits being flat for a few years.
Definitely one to keep an eye on though and it certainly looks like the dividend is safe, so perhaps a safe holding whilst waiting for any future increase in share price.
A
The segmental commentary within the ME International (LON:MEGP) results does try to touch on the topic of how much of the capex is for maintenance vs expansion, but I wish they’d be more precise. On a post tax and capex cash flow basis, without knowing for sure how much spend I can strip out as an investment in future expansion, have to say I struggle to understand the excitement driving today’s share price run. Odd one.
RE Hargreaves Lansdown (LON:HL.) HL
Interesting article on Citywire which adds some thoughts. I hadn’t realised that Peter Hargreaves was so vocal in his opposition to the Hybrid advice model which now appears to being dumped by the new management
One point in the Citywire article regarding outflows looked rather a bit strange..
"Clients transferring money to banks and building societies’ cash products"
This seems difficult to understand. HL has an excellent Active Savings product which allows cash to be moved fairly seamlessly between high interest rate 3rd party providers. HL take a cut from the provider, which even so still allows rates of circa 5% to be offered.
When you have such a useful product it seems strange that a relentless marketing machine such as HL couldn’t do a better job at retaining cash within its own product range.
As regards the post of Chief Strategy Officer, I also fall into the camp that thinks it is an unnecessary position. I suspect it is useful for the CEO however. Should the strategy fail, the CSO gets the boot -not the CEO.
Dont hold.
I was with them 30 years and am just finishing off leaving them after a bad experience with Active Cash movements. I have also helped move the rest of my family's accounts too. I have gone from being a big advocate to passionately despising them.
Are you able to expand a little?
Was it a situation where the transfer went to an incorrect destination or was it a case of correct destination - but a time transfer issue?
No connection to HL - just interested at such a strong eraction.
Hi Paul,
Just wanted to say a big thanks for the Beeks Financial Cloud (LON:BKS) CEO interview.
Really insightful, and the fact you aren't getting paid to promote the content makes it more valuable IMHO. I hold and am looking forward to BKS future announcements re big name exchanges/companies. As you have said and the CEO explains, patience is required but there is a point when the slow progress due to customer and regulator becomes a moat for BKS once they are in.
Definitely worth a listen folks.
Thanks again
Andy.
Thanks Andy! I'm pleased you found my interview today with Beeks Financial Cloud (LON:BKS) of interest. I've made such a mess of this one in my personal portfolio - I got bored, and worried about the drift down in share price, so ended up top-slicing several times, then when the big contract news came out, I didn't make much money as my position size was too small! It's definitely one I want to load up with properly, when funds are available, hence why I thought it would be a good idea to catch up with the CEO, and pose a few questions. I liked his no-nonsense replies to my more critical comments (about missing forecasts, and negative cashflow) - he openly said those were fair criticisms, before explaining why those issues had now changed.
The sound quality on my recorded line isn't perfect, but I found it was fine listening back on headphones. At some point I'll switch over to using Zoom recorded audio, but haven't had time to learn how to do it yet lol!
Thanks again for your positive feedback, much appreciated!
Best wishes, Paul.
P.S. I only feel comfortable doing interviews if I've chosen the company, and I don't charge them anything. So it's basically exactly the same as a private conversation I would typically have with company management - trying to understand the business model better, generally polite and supportive, but with 1 or 2 more difficult questions thrown in!
ME International (LON:MEGP)
I was concentrating on something else this afternoon and hadn’t realised that ME Group had ended the day up a huge 20% . Whether or not this rise holds over the next few days, weeks even, it should give solace to holders of other stocks that have drifted down on no news or those that have had reasonable trading updates and have not progressed, if they are quality they will have their moment in the sun.
Tortilla Mexican Grill (LON:MEX)
The CEO has resigned today. As this was missed I thought to mention it.
Tracsis (LON:TRCS)
A neutral review by Graham is fair enough. He is right to point to the dynamic of acquisitions boosting results.
The general low liquidity in their shares tends to underpin the share price, or will on bad news cause bigger downward movements.
I have been a shareholder for a number of years, and weighing up whether I should look elsewhere for better returns.
The bigger boost will come from wins in the US rail market, but this is a bit of a slow burn, with some evidence of traction, but not shooting the doors off, which was the early hope in this share when it started off.
ME International (LON:MEGP) Further thoughts: They appeared to say in the Investor Meet Company presentation that they see a market for 1 site per 10,000 people. They mentioned the names of 5 countries
Total population: 166,897,921
Based on these figures, the company could potentially support 16,689 sites, compared to the current 6,870. They also used the figure of 12 countries, so it is reasonable to say that their business should easily triple in the future (assuming those countries don't include the like of Vatican City and Tuvalu!). This part of the business appears to have the best margins I believe, and there is a network effect which means increased density leads to better margins because it is cheaper to service.
Hi Funnymoney, ME International (LON:MEGP) - adding to your 'cheaper to service' bit - they said that their engineers can service all of their different areas - so only one engineer needs to go to a site that has photo booths, laundry, rides, pizza and juice, printing... That was a positive surprise to me.
Focusrite (LON:TUNE) - in the process of forming a quadruple bottom and nearing very strong technical support. It's a high quality company and I'm involved in running a medium sized gig venue of some repute and we like the company's products. The problem as an investment is that, although eps has stabilised impressively at advanced levels, forecast growth in revenues and eps has slowed to below 5% since the pandemic. Consequently, the company does not enjoy the benefit of a growth stock multiple any more, its earnings yield having doubled. Is anyone else monitoring and can make a case for growth to pick up? Without that, it seems doomed to stay on a low teens PER at best, while paying a miserly dividend.
Focusrite (LON:TUNE) As a lot of their previous growth has come from acquisitions, then perhaps they need that trend to continue? For instance, one obvious gap they have in their product portfolio is mixing desks, perhaps they might add something there?
Focusrite (LON:TUNE) As a lot of their previous growth has come from acquisitions, then perhaps they need that trend to continue?
Yes I agree. The problem being that, as they have doubled in size, so must the scale or number of acquisitions to have the same impact. It's a headscratcher.
There's still plenty of scope for Focusrite (LON:TUNE) to expand the software side. Most studios are very heavily software based, and they have only just dipped their toes in with the Sonnox acquisition.
So I can see plenty of potential, a lot depends on their ambitions I suppose.
Quite surprised, if delighted, at the price action in ME International (LON:MEGP) this afternoon. The update today pretty much matched the numbers given at the end of November, which provoked a "meh" response back then even at the most energetic phase of the market's recent surge. Feels like an overhang has been lifted. Perhaps investors just needed to see the numbers confirmed, albeit unaudited.
The yanks are seriously crazy. NVIDIA (NSQ:NVDA) mkt cap is up $241 Billion so far today!!
The yanks are seriously crazy. NVIDIA (NSQ:NVDA) mkt cap is up $241 Billion so far today!!
This is the world's third largest company that raised it's revenue by 265% yoy. What's crazy is not the surge in market cap - it's the fact this vast corporation is mimicking the growth rate of a second year of revenue biotech that just invented a cancer cure - and not burning, but generating oodles of cash. Completely spectacular. I've never seen anything like it on this scale.
The comments today are all absolutely superb. Exactly what I come here for, intelligent discussion of interesting stocks. Well done everyone. It has all sometimes got a bit fractious lately and tbh, it was starting to get a bit wearing.
Of course, the main SCVR writing is always excellent, that should go without saying, but I'll say it anyway.
No the most insightful input I am afraid, but hopefully a positive one.
(Hi MattH, because your icon is Snoopy, I put in a picture of Snoopy etc being borne aloft by the Peanuts crowd. It's been removed, presumably and correctly because I didn't follow the Graphics guidelines, which I have now read.)
Hargreaves Lansdown (LON:HL.) I have no interest in HL as an investment ATM however I am a customer of theirs. I dont know if this is standard industry practice but HL only transfer your 'income' cash to your capital account once a month so you can have money sitting in their account earning interest for them and NOT you. Some of you will know this some will not. To take advantage of the reasonable interest rates that Graham has highlighted you can manually transfer this cash yourself. Log into your account, click cash tab, click income and loyalty bonus tab and somewhere on the right hand side you will see a ' transfer your loyalty bonus or cash to your capital account now' tab, click this and follow the instructions and you get interest on your money straight away without waiting for HL's monthly transfer. I do mine on the day the income is received.
My thoughts are that I didn’t realise that this was the process and am grateful for the insight. HL made a real mess of my wife’s SIPP drawdown . Several quite awful errors in the process. Such a disappointment as they have largely provided accurate and immediate answers to any queries I have had over the years.
ME International (LON:MEGP) I recently applied for a passport with selfies and the system rejected all attempts, so I went to Happy Snaps, where a person with a camera does it and checks it's OK online whilst you are there. I didn't have a photo booth nearby.
I have just applied for a Veterans ID card and I had to download an app to do the verification. I uploaded a photo of me, a photo of my passport, then a selfie. I then had to place my phone onto the passport biometric chip, which the phone read and compared to the photo's I provided.
That seem to be more checks to get the ID card than the passport.
Interesting recent experience with HL. Took 3 weeks and 7 long phone calls to extract funds from an ordinary company fund and share account which had the money "available" to withdraw. Over a certain limit you have to send a written request by email !. Despite email confirmation of receiving the request they claimed not to have it 4 times. Sleep, repeat, sleep repeat. More long calls, Supervisors always in meetings. 4 promises of a call back, not one until week 3 and eventually got someone who grudgingly put things right. Apparently they are not opening any new business funds and share accounts. Can only conclude that their systems are severely shot and staff demotivated. Good luck holders, there is more to that comments about needing to invest in their systems and processes than meets the eye!
Do you know what the £ limit is above which an email needs to be sent? Easier to withdraw in multiple transactions below the limit to avoid the hassle. Hargreaves Lansdown (LON:HL.)
ME International (LON:MEGP) charts sometimes get it spot on. A few weeks ago I posted that ME International (LON:MEGP) looked like it had formed a double bottom with price target of 145p. I bought through this period making ME International (LON:MEGP) my largest holding as I also think it’s a great company.
The point of this note is not to be smug but rather to highlight that sometimes the charts/markets seem to have all the info required to make a good profit. Especially when combined with the analysis of SCVR and the stock rankings.
PS. I’m not selling as I believe the longer term target is 200p.
I agree technicals can be useful and I should pay more attention to them. I saw the MEGP support at around 120 and happy to have averaged in around there. I’m monitoring Avingtrans (LON:AVG) at the moment and can see oversold (RSI <30) conditions with momentum (MACD) bottoming on both long and medium term scales. The trend is not the buyer’s friend right now so I’ve bought a third and we’ll see where it goes after the TU Wednesday. The chart is set up for a rebound on a reassuring report but who knows what we’ll hear?
ME International (LON:MEGP) I do struggle with investing in “yesterday’s technology” in general.
The numbers may be good, and you can certainly time a nice profit if you get it right (De La Rue (LON:DLAR), Reach (LON:RCH), Card Factory (LON:CARD) -don’t all shout at me -, ME International (LON:MEGP), Smiths News (LON:SNWS) but I do feel a bit silly when I invest and then the stock limps sideways and down and I have to ask myself “what was I thinking??!”
See my post at the start of the day. The new photobooths are not “old tech” and the laundry rollout is new. ME International (LON:MEGP) has found a new growth niche with some moat so not comparable to the others you mention imo.
DD, I totally get it, so much noise around all the exciting things going on in the world and here we are in UK small caps investing in what looks like dinosaur businesses BUT give or take, the best performers are quite often such stocks. I believe 4imprint is the best performing UK stock of the last 20 years and in the US I think it's Monster drinks.
My best performers over the last two years have been Ashtead Technology Holdings (LON:AT.) Shoe Zone (LON:SHOE) ME International (LON:MEGP) all up well over 100% and Ashtead more than 200% and look at the industries they are in...
For fear of sounding like an investing thesis book it really does help once you 'make a deal' with yourself as to the sort of person you are and what you like to look for in an investment and that will stop you turning your head everytime the next big thing is being mooted.
I personally like decent free cash flow yields, returns on capital, moats, big runways and good management, founder businesses etc if they have most of the above I'm not bothered if they are in boring businesses...
A good friend of mine only invests in Big US Tech and has no trouble buying things at 40x earnings but I just can't bring myself to do it (much to my chagrin).
But look, each to their own, there are many ways to win in this game, best of luck to you.
Thanks BO, I don't disagree about boring businesses, it is ones that seem to be in a slow death spiral (e.g printing banknotes, or dare I say taking photos in booths) that I struggle with, however good the numbers are. Of course if the spiral is slow enough (like the earth spinning gradually slower) then you can still catch a wave, and indeed I've held Smiths News (LON:SNWS) for the last couple of years of sideways shuffle.
I used to be Deep Value Dave, but now I am having an identity crisis. That's my current issue. All therapy gladly received.
Lol
To paraphrase the Stocko presentation in January, Boring Stock doing things you understand (not blue sky) = potential 10 bagger
My best performers over the last two years have been Ashtead Technology Holdings (LON:AT.) Shoe Zone (LON:SHOE) ME International (LON:MEGP) all up well over 100% and Ashtead more than 200% and look at the industries they are in...
But that success is possibly more a factor of good stock selection and sticking to what you know or can get your head around. In my case, with a tech sector background (though I'm not a techie), my top 10 multi-baggers comprise 3 from semiconductors, 3 from software, 1 medtech, and 3 tech-industrials. You can pick from a huge basket of semi and networking stocks that are up 100% or more in the last 12 months.
Yes BnB you're absolutely correct, and kudos to you for your selection of multi-baggers, that's very impressive.
Just to further qualify my process, I run a pretty concentrated portfolio of 12 stocks with 60% in the top 5. I don't really spread it around but prefer to find stocks with very limited downside and hopefully some good upside and then go in pretty hard.
At 90p odd I believed Shoe Zone (LON:SHOE) was an absolute banker and consequently stuck nearly all the proceeds of a buy to let flat into it. I know it can't multi bag like a semiconductor but I would never have the conviction to go all in like that in a sector where I can miss as easily as hit, I'm just not clever enough! But that's just my style and that's what works for me.
My old mentor's starting point was always, 'now how much can you lose at this price?' and then go from there....I always liked that.
Just to further qualify my process, I run a pretty concentrated portfolio of 12 stocks with 60% in the top 5.
I'm always really impressed at those who can run so concentrated a portfolio. Hats off to you. I have nearly 200 positions - the complete opposite. Just shows how you can approach this challenge with wildly varying strategies.
Here's something that will be of interest to most on here (hopefully).
I mentioned earlier I work in wealth management, I went down to London last year to meet a well known fund manager who operates mainly in UK mid cap space. He knows our beloved Paul Scott and like Paul is the kind of chap you could listen to for ten hours plus and not get minutely bored if your interested in UK stocks.
The names he had in his mobile on speed dial was like a who's who of the business world but what did stun me was when he mentioned one of the first places he goes when researching a new stock or reviewing one he already holds is this bulletin board.
ME International (LON:MEGP) was one of his favoured stocks all be it he see's the son eventually running the business rather than the take over scenario.
I also hold MEGP i want to say some of the comments on here today are outstanding.
I like to think after twenty plus years in this game i am pretty clued up but when I see some of the figures/arguments from people on this board it makes me feel like a rookie, so this is a big thanks to all the subscribers who along with Paul, Graham and Roland make this site such a great resource.
Two people who seem to have gone missing recently are RD Howarth and Timarr both are absolute top table on the macro so hopefully they are still lurking here and haven't jumped ship to sharepad.
Thanks again all just wish this site was going in the late 90's when I first got interested in stocks and due to the internet boom at the time thought I was an investing genius you can guess how that ended.
Regards Andy
Great post.
I'm no chartist but great to see ME International (LON:MEGP) hitting its 200 moving day average today on what I thought were superb results. Thank you Paul as well for your excellent commentary. Long and strong.
Thank you Paul for Angling Direct (LON:ANG) (I hold)
A few bull points:
- For FY23 the European division made a £1.3m loss (to be expected as it's in the start-up/growth phase). You can arguably add this back onto the profits - if it works out then it should be a big driver of earnings growth going forward, if not, they just discontinue this operation. So, when you strip out the cash and add this loss back on, the valuation looks cheap.
- Trading has been resilient, when compared to other companies that benefitted from the Covid leisure boom. See Gear4music (HOLDINGS) (LON:G4M) or Tandem (LON:TND) for example. You mention in your podcasts how you think inflation from state benefits and pensions will boost retail spending from April, I think Angling Direct (LON:ANG) will be a beneficiary of this.
- As the business becomes larger and takes more market share, they should have greater bargaining power with suppliers to drive gross margin higher.
To me, it looks like Angling Direct (LON:ANG) could be a long term multi-bagger. They're growing the top line, consolidating a niche with no big competitors and now replicating that overseas. Admittedly, it's happening slowly.
Edward,
Angling Direct (LON:ANG) will take more market share as incumbent independent retailers of a 'certain' age pack up trading in what is an industry which is in structural decline. Apart from the Covid boom to which you refer Rod Licence sales have been falling for years and there is hardly any recruitment, especially of youngsters. There are a few very good independent retailers left in the UK taking £1.5-£8 million p.a. but IMHO Angling Direct in the UK could be at peak revenue pretty soon.
Dip in rod licence sales major concern for industry - Angling International (angling-international.com)
EDIT as an extra I remember AD having cause to reference the 'weather' for unexpected drops in sales in a couple of recent reports. Unfortunately extremes in weather are no good for fishing itself or for encouraging people to go fishing, so I see more headwinds if these conditions persist in what is a very seasonal business.
Angling Direct (LON:ANG) only have a 13% market share in the UK, so far from peak revenue.
If they get to say 35%+ UK market share, either through their continued growth or retailers of a 'certain' age packing in, then their bargaining power, both with suppliers and buyers should strengthen. The structural decline you mention should deter any new competitors from entering.
Agree though that weather is a pretty weak excuse.
Re Angling Direct (LON:ANG) and its 13.5% market share - I think this figure is of the UK's specialist fishing market ie it excludes the big general retailers like Amazon and Decathlon. On the one hand that is good news as the overall potential fishing equipment market is bigger and their share lower but it also highlights the limits of their niche: these general retailers will always be a threat and a limit on prices. For instance, to get margins up they try to drive own label but a flotation jacket is prety standard. I do think they should be able to build margins from here since systems/stores are now in place but only so much as they are really geared for the big hobbyists. Europe is much more interesting to deliver new revenue growth but they need to get a shift on! In the very long term, it is unclear to me if fishing will shrink as youngsters are not growing up with it and fewer people pends less time in the countryside/outside. It probably will decline but slowly so they could make decent money for a while if they can corner a niche at an adequate scale
I think some investors would have expected them to use the cash pile to drive quicker growth in Europe but I'm happy with them doing it slowly and carefully. My only gripe with the cash pile is that they should be paying a divi to shareholders.
Anecdotally, I know many people (many on this board I expect) retiring in their 50's. These people might now go fishing in their spare time and they have plenty of money to spend on high quality fishing tackle. I don't know many in their teens and twenties though, but maybe it is more of a retirement hobby. Maybe it will become popular again at some point.
Marlowe (LON:MRL) has decided to stick to its knitting, and has agreed to sell GRC (governance, risk and compliance) and retain the other two divisions, TIC (Testing, inspection and certification) and OH (occupational health).
As a former holder (sold on last year's recovery, before the later dip) it is good to see that they have brought some focus to the business and the divestment will clear the high level of debt leaving £150m for shareholders.
It appears that the GRC division may have been too specialised, but that also provided a moat as the release notes:
"Completion of the SPA is in all respects conditional (the "Conditions") upon both (1) the Financial Conduct Authority approving the change of control of certain companies that are members of the Divestment Group which are FCA Regulated Entities, (2) the Solicitors Regulation Authority approving the change of control of certain companies that are members of the Divestment Group which are Authorised Bodies and (3) the Secretary of State for the Department of Business, Energy and Industrial Strategy approving the direct and indirect acquisition of certain companies that are members of the Divestment Group, the activities of which may make them subject to the mandatory notification requirements of the National Security and Investment Act 2021."
The sale certainly addresses Paul's previous comment
28/11/2023. "The market doesn't seem to like these numbers - operating profit looks resilient, and is up, but higher finance charges from the excessive debt pile, and higher corporation tax, cause EPS to fall. The horrible balance sheet is a deal-breaker for me. It's now doing a strategic review, after making 36 acquisitions in under 3 years! All a bit extreme if you ask me."
Another Mid-Cap reporting today is Morgan Sindall (LON:MGNS)
Quick Summary of the results:
Revenue up 14% to £4.1bn
Adjusted profit before tax up 6% to £144.6m vs a forecast of £140.9m per IBES
Net cash of £461m (FY 2022: £355m) and Average daily net cash of £282m (FY 2022: £256m).
Very high stock rank of 97
Graham last commented on it on 04/05/23
Morgan Sindall (LON:MGNS) (I hold)
In addition to year-end net cash and average daily net cash, they also disclosed their lowest net cash: "Across 2023, the lowest net cash balance on any one day in the year was £195m", which I regard as really good disclosure that all companies should follow.
I'm puzzled by the reaction to Mycelx Technologies (LON:MYX) update today - down 14%. - very much hope Paul gets to it. Yes, they've missed on both revenue and profit, but they have solved their much more pressing cash problem (though I'm unclear quite what they've sold - presumably they've kept IP on their products sold in Saudi, and are free to continue selling in other parts of the Middle East), and it does begin to look as though they may, at last, be making some progress in the US. Dreadful gamble of course, but I hold.
Good morning Paul,
ME International (LON:MEGP)
On the IMC meeting the CFO Stephane Gibon answered the question regarding having cash and debt balances, he says that in 2021/22 there was an opportunity to borrow at "extremely low" rates which they took in case there was an acquisition possibility that presented itself. He then said something that I didn't catch but I thought it meant that they were getting more in interest income than they were paying in interest .
Fantastic, thanks Helvellyn! Mystery solved re ME International (LON:MEGP) having big cash pile, and big borrowings. Many thanks :-)
I've invited MEGP to do a CEO/CFO interview on my podcast channel, they seemed receptive, but am having trouble pinning them down to a date.
ME International (LON:MEGP)
Paul, I completely agree with your analysis and thank you for that I would just like to add my views as to why the shares are so lowly rated.
I originally like many others, thought smart phones would kill off the photo booth business but actually the advancement in technology has had the opposite effect in that it has enabled the doctoring of photos such that they cannot be trusted and therefore used by regulatory bodies.
So we need something that can authenticate photos for official use and that is exactly what MEGP provide. They will eventually (I believe) be positioned to provide bio metric authentication as well (think finger prints).
Old Economy finally lands a punch on Big Tech ;-)
Old Economy finally lands a punch on Big Tech ;-)
I know you've said that tongue in cheek, but I would think of it more as evidence of the sweeping infiltration into every aspect of our lives of the process of digitalisation. It's not so much that the photobooth has defeated the computer in our pockets. Rather it's that the photobooth has become a computer.
This is the biggest theme in my portfolio. You can play it many ways, and indeed, with it reaching into everyone's lives you can't avoid it. Software, semiconductors, electrification, and now many tech-industrials as I describe them. As ever, the UK market is thin on candidates, but MEGP is one of the latter group. They can be software-led, innovation-driven, internet-hosted, electronically-transacted, data-focused or simply picks and shovels. Here are a few more I like and own:
Diploma (LON:DPLM)
Volex (LON:VLX)
Auction Technology (LON:ATG)
Auto Trader (LON:AUTO)
Cerillion (LON:CER)
Experian (LON:EXPN)
Halma (LON:HLMA)
London Stock Exchange (LON:LSEG)
Oxford Instruments (LON:OXIG)
PayPoint (LON:PAY)
Relx (LON:REL)
Rightmove (LON:RMV)
RS (LON:RS1)
Spirent Communications (LON:SPT)
TT electronics (LON:TTG)
Volex (LON:VLX)
Wilmington (LON:WIL)
YouGov (LON:YOU)
Quality portfolio BnB (a figurative knock of the table)....
ME International (LON:MEGP) .....except that I did my new passport photo with my i-phone, no problem
Great when you can... The UK allows photos taken by mobile phone, but not all countries do. And it's not always possible to find a place in a home where you have all of: plain background; large enough; well lit.
ME International (LON:MEGP)
... mind you, having said that not all countries allow passport photos taken by phone, I thought I'd find some examples and it's bloomin' difficult as the search just throws up countries that do allow it!
It did throw up suggestions of hanging up a sheet for the plain background.
I know it was easier for my brother to take my mother down to a nearby Photo.me booth when her passport needed renewing.
And if we need biometrics in the future, there may be a gap before phones can do this.
It's a kind of convenience/technology arms race.
The presentation this morning was interesting. It's on the Investor Meet website under Recent Meetings if you scroll down the home page.
Wash.me is their fastest growing and biggest margin section.
Forgot to say earlier: I hold.
ME International (LON:MEGP) From what I understood from the call, in the EU they believe that there is a security risk with phone photos as they can be manipulated (and I thought they implied that they weren't allowed?). MEGP are using this as an argument to the the UK authorities.
Also, in relation to Paul's comment about a buyout, the 27yr? old son was on the call (Vlad Crasneanski) so I don't think that is a runner.
Recently did my permanent residence visa for Canada, they only allow photos taken in a studio (e.g. jessops) with a stamp certifying the date and address of the company taking the photo.
Hi Paul
Thanks for the write up on ME International (LON:MEGP) which is a top 5 holding of mine. Regarding the query of why they are carrying bank debt, I refer you to the RNS of 2 October 2023 confirming the completion of the Japanese photo booth deal which was funded with around £5m of debt at 1,2% interest (sourced locally in Japan) https://www.stockopedia.com/sh...
ME International (LON:MEGP) - Regarding the query of why they are carrying bank debt, I refer you to the RNS of 2 October 2023 confirming the completion of the Japanese photo booth deal which was funded with around £5m of debt at 1,2% interest (sourced locally in Japan)
A classic carry trade. A good way of keeping existing cash available for more M&A in jurisdictions where debt carries a coupon above 5%, while earning interest on the cash at higher rates.
£MEGP
All the signs look good here but I am struggling to understand the working capital profile here - all the payables are non-current, while receivables and inventories are at 15% of sales, a little higher than I would expect. The notes nor the narrative provide any information around this.
I expect inventories are ink/food/detergent - all seems consistent year on year but based on my understanding of what they do, a little on the high side.
Also the DA seems to be falling, year on year, which is odd in the context of the asset base increasing.
Would be great if anyone here has thoughts on these matters?
Hi Vsihv,
Good points. I also furrowed my brow when I saw the £32.5m inventories, as I cannot see how consumables for its booths would amount to anywhere near that figure. So I've guessed that it must mostly be machines that they are building, or holding in stock for resale? So presumably these machines would then be booked into fixed assets once they are installed and operating?
Would be a good question to ask, if I manage to get a podcast fixed up with ME International (LON:MEGP) which I've been trying to do.
Thanks, Paul.
Thanks for the reply Paul.
If they're building/holding machines for resale, then I seem to misunderstand what they do - operating the machines. If under construction for future operation, then they should be in the tangible assets vs inventory.
I asked about this & cash/debt on working capital question was ignored, even though they answered the question re cash/debt. I wasn't too impressed with the call - if management are going to cherry pick questions, the least they could do is not make it obvious.
Look forward to the podcast if they come on - much harder to avoid questions vs IMC
Either way, market seems pretty enamoured with the update - I thought I would be adding here but I won't be until at least the full annual report is published with details around depreciation policy, impairments and inventory/receivables.
Such questions combined with it being "too cheap" in the context of profitability/growth concern me!
I wonder if any chance of an update on Jupiter Fund Management (LON:JUP) from Graham £100 mil plus profit on a market cap tad over £400 mil still looks good to me, loads of net cash, and divi upped also, all be it the share price trajectory like all fund managers last two years has ground ever downwards.
The flip side is loads of mergers and take overs in this sector and I got the impression last time Graham saw this as one of the cheapest in its sector due to share price to assets under management.
Negatives operating margin has declined over last few years but its still the kind of figure the likes of supermarkets would kill for , okay passives are eating into the sector but I don't think active management will die out over the next 5-10 years either.
Interestingly I work in the wealth management industry and met a fund manager who could go short as well as long he was neutral on Jupiter but equally said he wouldn't be in a hurry to short it in case an overseas bid came in.
I do hold so obviously biased but this whole sector looks cheap as chips all be it i have been wrong last eighteen months.
FCA Motor finanace investigation
For shareholders in Close Brothers (LON:CBG) CYB Secure Trust Bank (LON:STB) Lloyds included this in their 2023 results statement today:
Remediation costs of £675 million in the year (2022: £255 million), in relation to pre-existing programmes and a 450 (LON:450) million provision for the potential impact of the recently announced FCA review into historical motor finance commission arrangements
Hopefully, tnhis can be used to gauge the imapct if any on these two banks
regards
PD
ME International (LON:MEGP) If anyone has missed it there is an Investor Meet Company with MEGP at 9.00am this morning. Worth a watch for holders and those thinking of getting involved IMHO.
Jupiter Fund Management (LON:JUP). Rather muted response so far to Jupiter results - profits £100M compared to £77M last year.
Share price is up 6% - I hold
....was 2.4% at the start, hence my comment. Still less upward shift than I expected though....first good news for Jupiter Fund Management (LON:JUP) for ages, its been on its arse.
£ 76 mio goodwill impairment charge potentially holding sp back ? I hold ...
Morning Graham,
Good to see Hargreaves Lansdown (LON:HL.) listed in the Agenda above for today. I believe that you have held this in the past, and perhaps still do? Would you give us some thoughts on this please?
I thought that today's interim results look OK for HL, new CEO clearly under pressure to review the business by Peter Hargreaves, and he looks like doing a good job. Mention of business wide review being nearly complete. Nice to see 4% increase in dividend too,
Trifast
CFO gets the boot after just over a year .
I’d pencil that in as a red flag .
Though you might argue if your a glass half full person .
“good to find issues then we can fix them “
Drops another point towards the relegation zone .
Trifast (LON:TRI) The outgoing CFO had a negligible holding of shares, far below the required holding (which had to be met over a defined period) and when I asked in the Interims IMC meeting about the Director compliance with this policy, the CEO said that once out of the existing closed period, "we will both be making a commitment and getting back to be compliant with this policy".
The CEO duly kept his word, but the CFO did nothing. I saw this as a red flag on the CFO.
My assumption (and its only that) is that recovery of the company required a different skill-set and person in the CFO role and this was increasingly recognised internally and perhaps the CFO had an inkling this was not a role that would last too much longer, hence no share purchases. Maybe.
If my assumptions are correct, I see it as positive that the company are grasping this and making changes to bring the right skill-sets in to assist in the turnaround.
Which company?
ME International (LON:MEGP) As a holder I’m happy with these results
£33.9m net cash reassures
Good to see them trialling Photobooths in Australia as that would be a new market for them. Laundry business showing decent growth
The elephant in the room (and not something that can be in the Interims I know) is the continued sale by Fidelity of their holding. The daily 25k share buyback by the company is making a dent in it over time but it has ground the price down over the last 6 months by -17%
My morning smallcap tweet: Praise and malaise
Spirax-Sarco Engineering (LON:SPX) Mycelx Technologies (LON:MYX) RBG Holdings (LON:RBGP) 1Spatial (LON:SPA) IQ-AI (LON:IQAI) Marlowe (LON:MRL) Narf Industries (LON:NARF) BSF Enterprise (LON:BSFA) East Imperial (LON:EISB) Amicorp FS (UK) (LON:AMIF) Powerhouse Energy (LON:PHE) Plant Health Care (LON:PHC) Galliford Try Holdings (LON:GFRD) PayPoint (LON:PAY), Tracsis (LON:TRCS)
◄Spirax-Sarco Engineering (SPX)► the announcement nobody's been waiting for as co rebrands as Spirax Group "help everyone better understand who we are". [SP=10370 Cap=7651m]
◄MyCelx Technologies (MYX)► sells Saudi Arabia business operations for $3.125m plus $4m earn out. It contributed 64% of consolidated group gross profit in FY22. Will use cash to boost "marketing and sales plan for its unique technologies in the Perfluoroalkyl and Polyfluoroalkyl Substances remediation and Enhanced Oil Recovery market". [SP=54.49 Cap=12m]
◄RBG Holdings (RBGP)► troubled legal tinpot makes £2.7m fundraise at 9p, a 3% discount, to keep the lights on in a 'downside scenario'. Convex rev only £2.2m, down 58%. MBO talks on Convex. So yet another bright idea of the ex-CEO Nicola Foulston for the chop. "Nicky Foulston has a proven track record of leading high stake business transformations across various industry sectors together with a reputation for closing complex and high value mergers and acquisitions." - LinkedIn. [SP=9.29 Cap=9m]
◄1Spatial (SPA)► wins £0.34m 1 year SaaS contract for Traffic Management Plan Automation. [SP=57.81 Cap=64m]
◄IQ-AI (IQAI)► £300k placing at 1.5p, a 32% discount, to further the development of oral gallium maltolate, the oral anti-tumour agent. [SP=2.2 Cap=4m]
◄Marlowe (MRL)► sells certain GRC software and services for £430m (EV-adjusted). That's 16.2x adjusted cash EBITDA. Will clear debt and return over £150m to holders. CEO will leave with the sold biz. [SP=415 Cap=402m]
◄Narf Industries (NARF)► get $1.6m of orders under its exclusive US Government Omnibus contract vehicle. [SP=0.71 Cap=12m]
◄BSF Enterprise (BSFA)► update on technical and commercial development of Kerato which is developing lab-grown human corneal products. [SP=9.13 Cap=9m]
◄East Imperial (EISB)► guides FY-Dec rev only £2.35m, down 26% due to the operating constraints experienced in Q2 and Q3. Sales recovery in Q4 2023 with momentum maintained in Q1 2024. Expects cashflow breakeven in Q4 2024. I see it now only makes super-premium beverages, down from ultra-premium. Co remains sub-premium. [SP=0.46 Cap=2m]
◄Amicorp FS (AMIF)► guides FY-Dec rev $12.8m, up 8%. Adj EBITDA only $2.6m ($4.2m) due to expanding its sales force by c.50% and undertaking automation projects. In line? [SP=1.5 Cap=180m]
◄Powerhouse Energy (PHE)► signs initial 5-year framework agreement with Australian based National Hydrogen for for its intended roll out of multiple hydrogen-based projects across Australia, Italy, Switzerland, and Hong Kong. "Powerhouse will not be required to contribute any capital for these projects. Instead, the collaboration will be based on a license fee and royalties model." [SP=0.32 Cap=14m]
◄Plant Health Care (PHC)► Mexico approves SAORI fungicide. [SP=3.65 Cap=12m]
◄Galliford Try (GFRD)► wins three new infrastructure contracts totalling £98m. [SP=238 Cap=244m]. I hold.
◄PayPoint (PAY)► partnership with Royal Mail across PAY's Collect+ network so that parcels can be dropped off at 5,000 Collect+ stores. [SP=494.5 Cap=359m]
In line: TRCS
Thanks for the comments below on ME International (LON:MEGP) - just to let you know I'm looking at this first, as it's one of my favourite value/GARP shares, and is on my top 20 share ideas for 2024 list here - which incidentally has made a good start to the year, although it's very early days of course. I'm 6% ahead of AIM, and Graham is 8% ahead of AIM!
Georgia Georgia Georgia on my mind .
Georgia Capital and Bank of Georgia
Georgia capital market cap 510 million
Owns 20% bank of Georgia which is punching to yet more highs .now valued at 2 billion
20% of bank of Georgia is worth 400 million .
NAV 24.23 (maybe up another 15-20% due to further rerating bank of Georgia (quick estimate )
Georgian economy one of strongest possibly aided by Russian outflow into Georgia .
I treat this as “special situation” because you cannot really apply a big discount to the bank of Georgia stock in its portfolio .due to its main market listing, high liquidity, and relative blue chip status .
Geo political risks of course but maybe that’s also geo political opportunity .also to the upside .
Just like you buy a quid for 50p .
Anyway I’m totally 100% biased I hold a lot and bought more yesterday and last week .
And even more important to the biull case is the fact it’s in my daughters ISA and that is a 100% guarantee it will continue to go up .
Agreed Planet, Georgia Capital (LON:CGEO) barnstorming increase in NAV for 2023 is most impressive. Much of this is down to its 20% holding in Bank of Georgia (LON:BGEO) which is a multi- bagger on a forward PE of less than 5! As you say, BGEO has gone up nearly 10% since the CGEO year end valuation.
However, this is not just a play on BGEO. CGEO has been doing the hard yards in building, and adapting, its Hospital, Pharmacy and Insurance privately held businesses to the evolving regulation in Georgia. They are building large and even dominant businesses in these sectors. Whilst I’m not a fan of regulation generally, companies that successfully navigate regulatory challenges tend to find that their competition is limited…and hence strong and resilient profits.
Meanwhile, the high economic growth, low national debt, and generally reasonable governance (last time I looked Georgia had a similar governance score to Italy), leave me happy to continue investing in this country. I appreciate that Russia (on its northern border…and some lands still held from its 2008 invasion) is seen as a risk, but Georgia has prospered during the Ukraine invasion, and presumably would prosper more if Russia ever normalised (agreed a distant prospect at present). The influx of 1000s of bright young Russians wanting to avoid the war/conscription is giving Georgia a strong demographic boost.
I am long term holder of both companies.
Georgia Capital (LON:CGEO) As you know I also hold both. You can basically buy a bunch of infrastructure type assets (hospitals / pharmacies etc) for free. The NAV will be north of £25 so more than a 50% discount which feels nuts to me.
If only they paid a decent dividend yield so you were paid whilst you wait but can’t have everything I suppose. It has slowly ground up this year but not really narrowed the discount to NAV.
A more normal discount might be 20-25% so I continue to hold.
Buybacks are theoretically better when at a big discount to NAV so hopefully we will have more of them!
Just done a bag of fag packet calculation for current NAV of Georgia Capital (LON:CGEO) and given the change in FX rate since 31 Dec plus the uplift in Bank of Georgia (LON:BGEO) share price since 31 Dec and I get a current NAV of £25.75 per share (excluding any effect of buybacks/income etc since that time)
Sounds about right Nadav. I’d got to about £26. But less than half price assets on sale. There will always be a liquidity discount but given that almost all of the £12 share price is made up of the Bank of Georgia (LON:BGEO) stake you’re basically getting a bunch of hospitals, pharmacies, medical insurance etc for nothing at all which is a somewhat bizarre situation to find. These are real assets with real values - it’s not like some start up tech fund that is basing NAVon the last spurious fundraising price. In fact it looks like they are very conservatively priced given a sale of a regional hospital realised 46% above book. So rather than NAV being overstated I’d say it appears to be the opposite.
Not really sure what drives the discount narrowing - as you say buy backs help so hopefully they will continue to do that but I’d have thought given the UK focus that a decent dividend would also help as investors would then be paid to hold - that might attract an additional investor base perhaps but who knows.
Morning All,
Regarding Volex (LON:VLX) , there was a post on LSE chat yesterday saying the UK has banned the copper SB car charger., due to security issues.
There was a reply stating Volex (LON:VLX) was not the manufacturer, is indeed a company called Wallbox.
Regards.
Sylvania Platinum (LON:SLP) With the basket price down 44%, net profit is down 90%, however they still made a profit.
Production forecast is maintained. Its a well run company with a few projects and a joint venture underway. 1p dividend is as expected and for an interim is about 2% of the current price, hopefully around 5/6% for the year.
Holders could be in for a bumpy ride today, but at these prices, I will attempt to catch the falling knife. One to "pound cost average" over the next year.
Not one for Paul or Graham but what do other holders think?
Sylvania Platinum (LON:SLP)
What % of the market cap here is covered by cash ? I know it used to be pretty high.
Judging by the update $107m (£84m) 60% of the market cap of £140m
Sylvania Platinum (LON:SLP)
top banana stuff Topbanana
I was a holder in Sylvania Platinum (LON:SLP) for a couple of years and sold a few months ago because it isn't clear to me that they have a strategy to pass back the cash to their shareholders. I have some sympathy because the SA govt takes a chunk when they do pay it out. They don't need this level of cash to get through the downturn, so my guess is that they may be considering an acquisition. My criticism is that they haven't addressed this question head-on with a clear statement, so shareholders know where they stand.
The 1p dividend is basically the interest on the cash pile.
A geared play on the price of the basket going up. What is the outlook for these metals, i guess less demand if electric cars mean fewer cat converters? Also political risk being in South Africa. Looks like the low price is about right.
Although ICE cars are out of favour long term and consequently the use of PGMs for catalytic converters, there is a strong probability of an increase in their use in hydrogen electrolysers and fuel cells in transport. Could benefit Sylvania Platinum (LON:SLP)
SLP Well, it's been up hill, down dale for me. I did sell half in Jul 2021 at 98p, which turned out to be a good idea. Here's the chart for rhodium:
As you can see prices really ramped up during the Covid era. They have since stabilised to around current figures. So, the question is whether you think we're at a "new normal" or prices will revert to pre-2019 levels.
I held for a couple of years, selling just a month ago, the loss was around 6% taking dividends into account, so not a disaster!
Now I wonder if there's a buying opportunity at these prices? There are many more uses for platinum than catalytic converters, and even in the case that EV sales do start surging, there are plenty of ICE cars still being produced and sold. In countries bigger than the UK (and with little infrastructure to charge on route), the demand for EV's is surely limited.
A little old, but useful nonetheless, I thought:
https://www.bullionvault.com/g...
Regards, Jon (finger hovering over the buy...)
ME International (LON:MEGP) I make this a small miss on revenue and eps* with, frustratingly, no detail on forecasts, albeit a positive tone. I guess we have to wait for brokers to release theirs. I would expect a little pullback at open.
* EDIT ignore - I was looking at FY 24 eps estimates, d’oh
EPS higher than Stocko broker estimate.
You’re quite right. I was looking in the wrong column/year!! As a holder, happy to be in error!
Didn't they advise revenue would drop a bit in their last update? Info probably not updated on stocko? Markets look forward right....
ME International (LON:MEGP) (I hold and one of my coffee can stocks)
I have it as a beat against Finncap note (last one available to me) on every metric bar top line which they said would be slightly under in their last trading update. The dividend uplift and commentary is superb.
And with this sort of growth and trading at just 10 x, plus cash on the balance sheet, plus a very bullish outlook I think the share price goes up from here.
50,000 machines around the world collecting cash 24/7, I love this business.
Previously stated:
For the 12 months to 31 October 2023, the Group expects revenue to be marginally below the lower end of the previous guidance range1 but to be no less than £298 million [today 297.7] Nevertheless, given the Group's focus on profitability, EBITDA remains in line with the previously stated guidance range1 and the Group expects it to be significantly above £100 million. Profit Before Tax is expected to be towards the top end of the previous guided range1 and no less than £67 million [today 67.1mil].
So it is a revenue miss, but only 300k, profit 100k up. Admittedly against quoted "no less than" targets. So it's bottom end of expectations you'd think.
So it is a revenue miss, but only 300k, profit 100k up. Admittedly against quoted "no less than" targets. So it's bottom end of expectations you'd think.
And, coupled with a refusal to put out actual forecast numbers, a little underwhelming I felt. Perhaps I’m channelling Nvidia ;-)
Rolls Royce - FY23 underlying operating profit £1.6bn, margin 10.3%, up from £652m and 5.1% FY22. Free cash flow hits £1.3bn. Net debt reduced to £2bn.
And the guidance for the current FY is pretty punchy. I hold.
ME International (LON:MEGP) prelim results look good. I hope it’s covered today.
A note on these next gen photo booths. They connect directly to passport office so you don’t have to go through the hassle of getting your photo verified etc. For £10 it makes passport renewal so easy. I think their demise has been overstated. Plus the Washing machine business seems to be growing well. I hold.
ME International (LON:MEGP)
Revenue up 14%
pre tax profit up 25%
post tax profit up 30%
with 33.9m in net cash
But alas no special divis despite such great numbers..
ME International (LON:MEGP) (I hold)
Don't be too disheartened TGP20 they have allocated 55% of profits to dividends going forward, the rest of their cash flow dedicated to investing in the expansion of the business.
Special dividends are nice but progressive dividends in a growing business are IMHO even more valuable.
He's running a very balanced ship, like a founder owner would.
Hi Revs8
I have just renewed my passport using one of these booths and you are spot on. You still get your photos printed out so everyone can have a giggle, but you also get a unique reference number. When applying for your passport on line you simply upload the unique number and the photos appear on your screen, as if by magic and of course they are in the right format. (Anyone who has applied for certain overseas visas maybe aware of the nightmare it is to get photos taken in any other way, approved).
The process is quick and simple and costs £10 which is paid contactless so no expensive cash collection required. A fantastic business model I believe.
ME International (LON:MEGP) When you apply online for your passport you can now just take a photo with your phone during the application process and upload it and it doesn't need to be seperately verified. I can't see why photo booths will exist in the future.
"I can't see why photo booths will exist in the future"
They probably wont for offical photos - which has alreadty been stated can be done far more easily at home with a phone
My experience is that students use these on impulse to take wacky style photos (fancy dress etc). Interesting, but probably not enough to build a robust investment case.
Hydrus,
This morning's ME International (LON:MEGP) Investor Meet Company video, which I would imagine is now available to watch on the IMC website, covers this in some detail, Vlad Crasneanski (head of commercial operations) suggests that the passport picture situation rather than make photobooths obsolete will in fact make them a necessity . Obviously "he would say that wouldn't he" but it makes sense to me.