Small Cap Value Report (Thu 22 June 2023) - WTB, ESKN, VLX, XPS, FADL, OCDO, SDG

Good morning, it's Paul & Graham here, raring to go!
** BREAKING NEWS - interest rates in UK rising 0.5% to 5.0% ** Source document is here on BoE website.
Do have a refresh read of the explanatory notes below, as I tweak them every now and then, and hopefully these points below help avoid misunderstandings. Especially important for new subscribers, who sometimes have unrealistic preconceptions.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
I might have to spend tomorrow morning doing backlog items for the micro caps, we'll see how we get on today. As always, we usually cover 5-6 companies, prioritising ones that over/under perform, or are in some other way more interesting to investors.
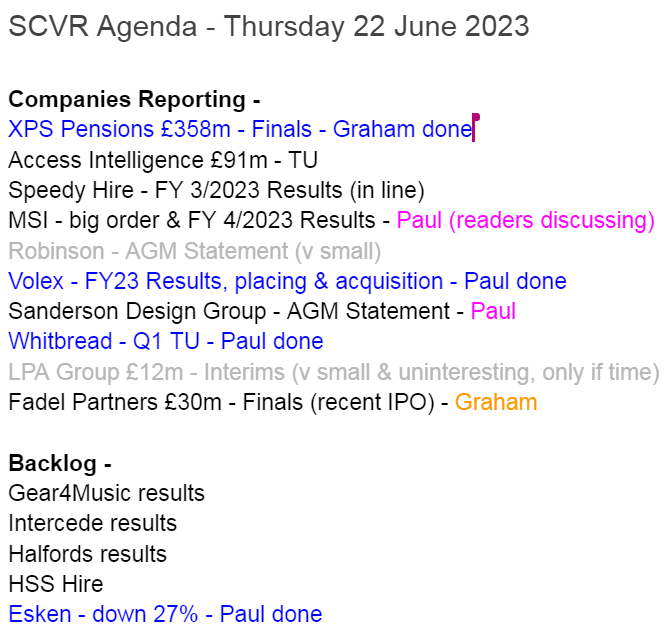
Summaries of main sections
XPS Pensions (LON:XPS) - down 3% to 170p (344m) - Finals (ahead of expectations) - Graham - GREEN
These shares are slightly down today despite beating Canaccord’s estimates. What might initially strike investors as a boring investment consultant could instead be an impressive generator of inflation-proof, recurring revenues. I cautiously give it the thumbs up.
Fadel Partners (LON:FADL) - unch. at 147p (£30m) - Finals (in line) - Graham - AMBER
This is a newly-listed stock (IPO in April 2023) that provides enterprise software in the field of IP management. It did post a loss in 2022, even at the adjusted EBITDA level, and it’s far from clear that the $8m raised will see it to profitability. But I keep an open mind for now.
Quick Comments
Ocado (LON:OCDO)
Currently up 41% to 607p, adding almost £1.5bn to its market cap, now c.£5bn - on rumours of bid talks (The Times).
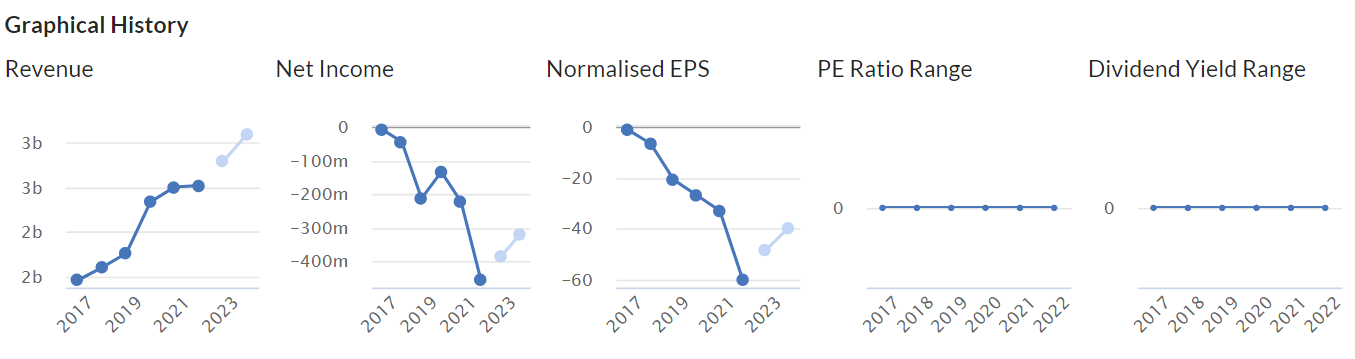
I've never understood the valuation of this share, which has seemed detached from reality for years. Terrible performance, yet it's still valued in the billions -
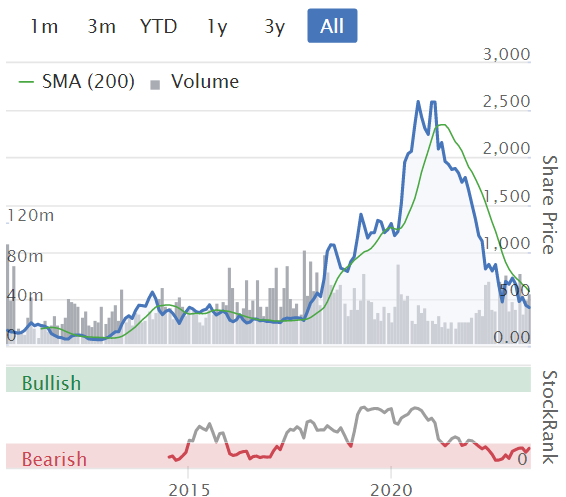
Bonkers volatility in its share price too, the market clearly can't decide what it's worth -
Whitbread (LON:WTB)
£6.8bn - Q1 TU - Paul - AMBER
For read-across to small caps? WTB these days is not a brewery any more, but instead owns Premier Inn hotels (840 hotels in total), Costa coffee, and several branded pub chains, eg Beefeater, and Brewers Fayre. That's from google, so I hope it is accurate & up-to-date. EDIT: no it wasn't, shame on you Google! Thanks to readers who corrected this in the comments, as Costa was sold in 2019. I'll go directly to company's own websites in future, here are WTB's current brands -
Strong trading, and positive outlook, for 13 weeks to 1 June 2023.
Premier Inns “outstanding performance”. Building market share as independent hotels “permanently decline”, and “lack of branded supply”. Doing £300m buyback, £103m done so far. Extended undrawn £775m RCF to May 2028. Food & beverage division also trading well, with total sales up 10% - so keeping up with inflation & wage rises.
Paul’s opinion - shares have had an excellent run recently, and look fully valued now at fwd PER of 19.7x. No sign of consumer caution hurting it, seems to be trading fine, for now. Is it a case of quality businesses hoovering up market share in a downturn? It looks that way to me. Something to bear in mind for other shares & sectors I think - the strong get stronger when conditions are tough, and gain market share as financially & operationally weaker companies go under. Also, as consumers, maybe we should be focused on supporting smaller, independent businesses wherever possible, as some people already do.
Paul's Main Sections:
Esken (LON:ESKN)
Down 27% to 2.7p y’day (£28m) - FY 2/2023 Results - Paul - RED
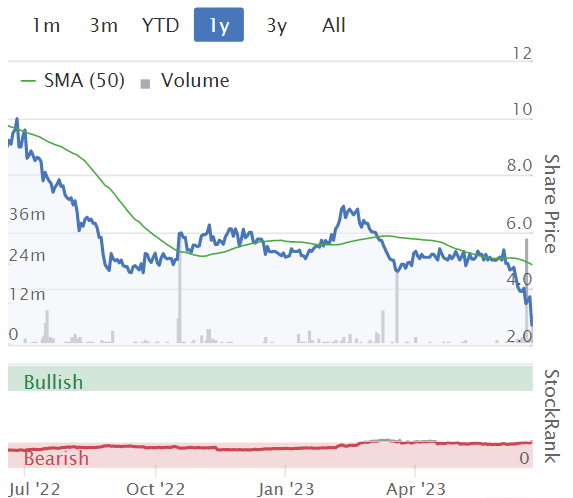
This is a special situation, where the group owns Southend Airport, and a sizeable renewables business. It is trying to sell both. It has recently relied on an expensive £50m debt facility, on top of other large borrowings, which it says should be repaid from the renewables disposal, which has to happen before Dec 2023 according to the going concern statement - essential reading!
Total net debt is massive, at £290m. It seems to be saying that once the disposals occur, “the remaining value will be returned to shareholders” - suggesting a surplus after disposals.
NTAV is negative £(15)m, so assets will need to be sold for above book value in order to clear the debt, let alone pay shareholders anything.
So it all hinges on what prices will be achieved from the disposals. Note this key bit in the going concern note -
Overall, the Directors are satisfied that the Group will have sufficient funds to continue to meet its liabilities as they fall due until at least 30 June 2024 and therefore have prepared the financial statements on a going concern basis. However, as previously noted this is highly dependent on the successful completion of the Group's disposal plans, which indicate the existence of a material uncertainty related to events or conditions that may cast significant doubt on the ability of the Group to continue as a going concern and, therefore, to continue realising its assets and discharging its liabilities in the normal course of business.
Paul’s opinion - this looks very high risk, therefore I have to mark it as RED.
Shareholders could get lucky, if good disposal proceeds are obtained, and are enough to pay off all the considerable debt, and if funds are received in time. Lots of ifs.
The danger is that potential asset buyers might do their due diligence now, but then hang back and wait for it to go into administration in 2024, then buy the assets for a song from the administrator.
Therefore I think it safest to assume the equity could end up being worth nothing.
This is a complicated special situation, not suitable for ordinary investors, unless you really know what you’re doing, and have done deep research. Occasionally though, special situations like this can be lucrative, and I have no idea how this might pan out. But my job is to flag the risks to you, then you can make up your own mind whether risk:reward appeals to you or not. For me, there has to be much clearer upside before I would want to risk any money on this, so I’m not going to spend any more time digging any deeper.
If any readers have done research on this, then do please share your views. The key question is: how much money will be raised from the disposals? It sounds like the end result will be a cash shell, so how much cash (if any) will remain after all the disposal & shutdown costs? If it’s nothing, then the shares are likely to be a zero. Why get involved?
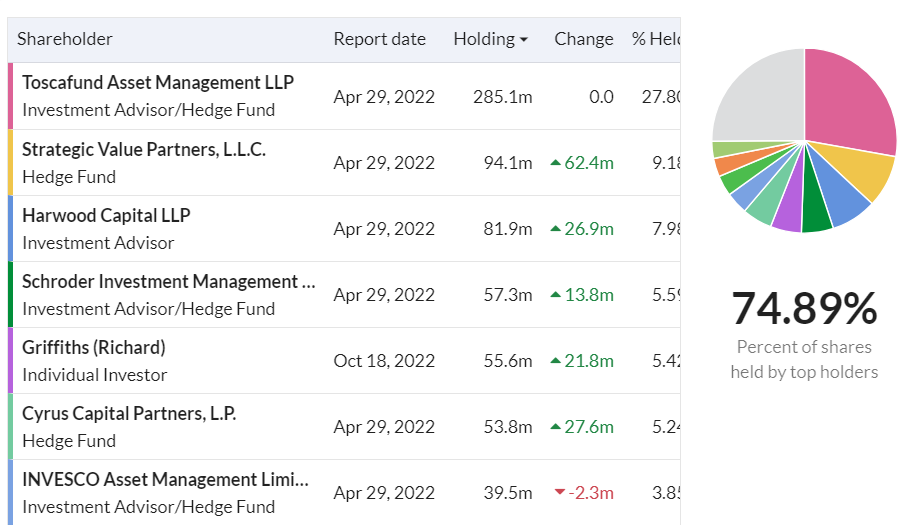
The shareholder register at ESKN is like a who's who of special situations investors! (who don't always get everything right, but are certainly very clever). With this lot in control, I'd say de-listing and/or heavy dilution on a refinancing are both huge risks. Small shareholders could easily end up being hung out to dry by these sometimes aggressive shareholders -
Volex (LON:VLX)
Volex (AIM: VLX), the specialist integrated manufacturer of critical power and data transmission products...
Fundraising & Acquisition
Key points -
- Placing & retail offer to raise c.£60m, remainder funded by existing debt facilities.
- Fundraising at 275p, which is roughly where the share price has been averaging for May & June, so that looks fine to me.
- Part-funding another (big) acquisition in Turkey, called Murat Ticaret, which makes complex wiring harnesses.
- Total consideration up to 178m Euros (E136.5m initial cash, then E41.6m deferred, subject to performance over 2 years).
- Valuation looks attractively modest, at 5.3x EBITDA (an EBITDA multiple seems to be the method used in many takeovers).
- Volex’s pro forma net debt will be 1.5x EBITDA, with a “clear pathway” to reduce that to 1.0x “in the medium term”. These are generally not seen as problem levels of debt. Although we do have to remember that debt is now a lot more expensive than it has been for the last 15 years.
Paul’s opinion - this looks an attractive deal, and the fundraising is on good terms, which don’t disadvantage small shareholders.
The StockReport shows Volex itself is on a EV:EBITDA of 10.8, so buying something at about half that rating is clearly good business! That’s the textbook way to build value in an acquisitive group - buy cheaper than your own shares are rated, and part-fund deals with debt, which is then repaid by the acquired company over several years. Rinse & repeat! It seems to me that Volex is priced as a value share, but is actually an effective acquisition growth company. That means scope for a re-rating once markets become more bullish again maybe?
It’s one of my top picks for 2023, and so far the story is panning out well I think, despite tough macro.
Volex plc (AIM: VLX), the specialist integrated manufacturer of critical power and data transmission products, announces its preliminary results for the 52 weeks ended 2 April 2023 ("FY2023").
Key numbers -
- Revenue up 18% to $723m
- Underlying PBT up 15.4% to $59.3m
- Underlying basic EPS 30.2 US cents, up 12.3% (this looks to be slightly ahead of expectations of 29.2c shown on the StockReport)
Adjustments from statutory profit to adjusted profit are quite sizeable, at $13.5m, here’s the breakdown in the table below. I’m fine with goodwill amortisation being removed (the biggest item, highlighted). But share options are really remuneration for mgt, so I would add that back in, for valuing the company -

Outlook sounds positive to me -
We entered the new financial year with good momentum, with high levels of customer demand. Our supply chains are now much improved and are therefore enabling us to step up production, particularly for high value-add complex products.
With a diverse offering, proven success in attracting and retaining customers, and extensive experience operating in our highly attractive markets, we believe that Volex has the potential to grow significantly.
We are confident that with a strong strategy, clear demand for our products and solutions, and ambitious team members, we will continue to make excellent progress towards our five-year plan financial targets.
Balance sheet - the obvious danger for acquisitive groups, is that the balance sheet gets hollowed out and ends up being a massive pile of worthless goodwill.
As at 2 April 2023, VLX had $124m of intangible assets. NAV was $233m, so NTAV is $109m, which looks OK to me.
Working capital is healthy, with a current ratio of 1.62, no concerns there, that's quite good.
Finally, long term bank debt is $89.6m, which is fine for the size & profitability of the business, I think. This will obviously go up with the latest large acquisition, but not by an excessive amount, plus the balance sheet will be bolstered by the fresh equity being raised.
Overall then, I think this balance sheet looks fine, before and after the acquisition.
Paul’s opinion - very positive, I really rate this company, under owner-manager Nat Rothschild. Without wishing to be vulgar, with a name like that, I don’t suppose bank facilities are ever likely to become a problem! Since he took over, progress has been excellent, with a string of apparently value-adding acquisitions, and a comprehensive turnaround in the original business too.
Yet shares remain on a lowish multiple (fwd PER) of only 12.1
Bear in mind profit forecasts will now rise significantly, as the new acquisition kicks in, but there will also be dilution which looks to be about 13%.
With a solid outlook statement too, talking about strong customer demand, and increasing production now supply chain problems are easing, this all looks rather good to me.
So it’s another thumbs up, I’ll remain GREEN. This was a podcast mystery share on 18 April at 247p, and is one of my top 20 picks for 2023, and after today’s good news, I’m happy those were good decisions.
Historically VLX shares have been volatile, but I should point out the previous problems were due to low margins, and over-reliance on one lucrative customer (believed to be Apple). The business is now much bigger, and more diversified, with I think much stricter financial controls & strategy, so it's making good, and apparently sustainable margins now. That's what we're told anyway, and the numbers seem to support that story. But as with every company, outside shareholders don't really know what's going on under the surface, we have to trust management to a large extent.
UPDATE: Results of Fundraising RNS has just come out. It confirms, as expected, 21.82m new shares are to be issued, at 275p, a 3.8% discount to last night, raising £60m before costs. One point I forgot to mention before, is that Directors have contributed £15m, a quarter of the total, very impressive - substantially all of that is from Nat Rothschild. It's a 13.7% expansion of the existing share count. Total share count will now be 180.9m shares.
Sanderson Design (LON:SDG)
Up 2% to 130p (£93m) - AGM Statement - Paul - GREEN
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group…
Headline -
"The Company continues to trade in line with the Board's expectations for the full year"
Here are my notes from 27 April, where I reviewed the FY 1/2023 results, quite helpful in quickly getting up to speed on the background.
Broker forecasts were cut sharply in Oct 2022, but have since barely moved, save a slight reduction dated today (it looks like this has been updated in real time, which I didn’t realise they did, so that’s very timely, which is good).
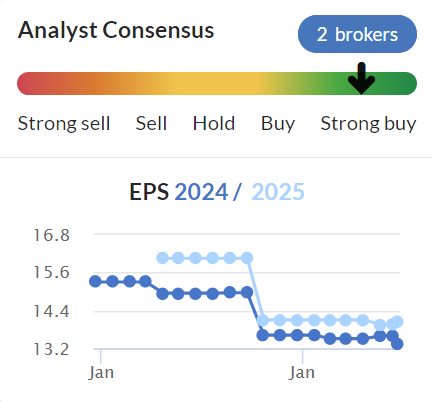
Today’s update is also confirming trading in line. It’s irritating that they refer to the Board’s expectations, when they should be saying market expectations, since it’s a reference to the full year results (not a part-year, where Board expectations is acceptable). Why introduce doubt, when you don’t need to?
"The Company continues to trade in line with Board expectations for the full year, and has a robust net cash position. We have a strong portfolio of brands, an exciting pipeline of product and licensing opportunities and we continue to benefit from our business mix, which is currently being led by the strength of our licensing activities. We look forward to providing a further update on trading in the half year to 31 July 2023 on 8 August 2023."
Valuation - many thanks to Singers for an update note, which leaves forecasts unchanged - adj EPS of 12.9p, so a PER of 10x - attractive in normal market conditions, but maybe sensibly cautious in the current volatile macro situation?
Paul’s opinion - still one of my favourite top 20 shares for 2023 (and beyond). As mentioned before, there’s got to be a chance that difficult macro might trigger a profit warning here, which is probably why the PER of 10x looks modest for a decent quality company, sitting on a lovely balance sheet, with added value of the immense design archive (that generates lovely, high quality licensing revenues). I also see SDG as a potential bid target, as this is a unique company really. So if we sit on the sidelines, we could miss a takeover bid, However, holding the shares also involves taking on some short-term risk from a possible profit warning. Strong licensing revenues have so far saved the day, offsetting reduced demand elsewhere in the business, so all good so far. I think the CEO is excellent too, very backable, having done a lot of really sensible stuff so far.
Overall then, I’ll remain GREEN and keen on SDG, on fundamentals, as a long-term hold I'd say, not a trade. Although there is that risk it might warn on profits if the economy gets a lot worse, so as with so many shares right now, it depends on your risk tolerance, and your holding period. That’s why the valuation is cheap, as it’s building in some slack for possible future disappointments. I would be inclined to treat any future profit warning as a buying opportunity, because the fundamentals are so sound.
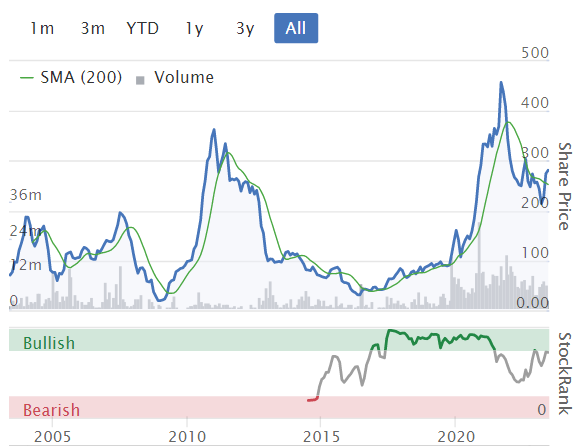
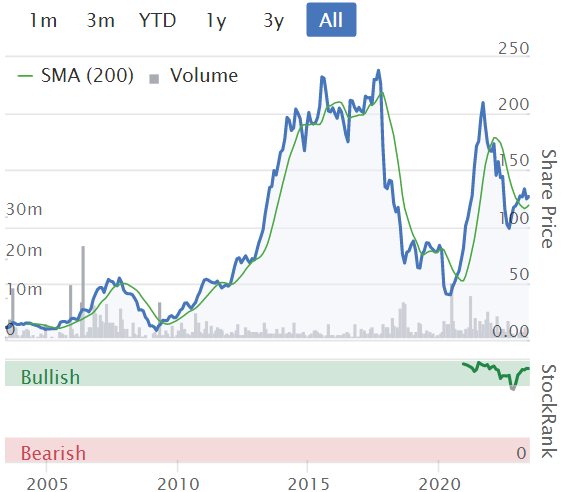
Looking at the long-term chart below, I think a lot of the problems that began in 2017 were self-inflicted by previous management, since sorted out under Lisa Montague. It got through covid well too. There's been no dilution, since the balance sheet is so robust. Hence I reckon it's probably only a matter of being patient, before the previous highs are regained. Could be a long wait though, depending on how macro pans out. There's a 2.8% dividend yield to keep things ticking along whilst you wait.
Graham’s Section:
XPS Pensions (LON:XPS)
Share price: 170.5p
Market cap: £344m
XPS Pensions Group plc ("XPS" or the "Group"), the Pensions Advisory and Administration business, is pleased to announce its full year results for the year ended 31 March 2023 ("FY 2023").
Some might consider this stock to be unexciting, but the growth figures it announces in today’s full-year results are a lot more exciting than you’ll find at many other stocks we cover.
We have 20% revenue growth and 24% growth in adjusted EPS, with numbers that are ahead of expectations:
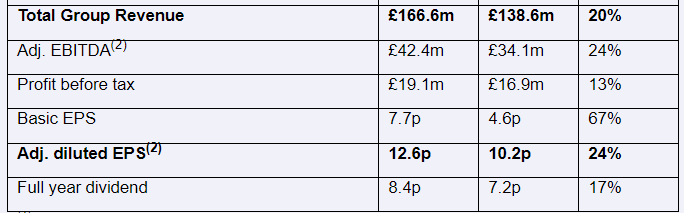
The revenue growth was driven by “strong client demand, inflationary fee increases and bolt on M&A”.
Organic revenue growth was impressive at 17%.
As we have previously mentioned in this report, XPS benefits from inflation-linked price increases, so there’s a lovely hedge for investors in inflationary times.
I note 24% growth in Pensions Consulting revenues, and 31% growth in Investment Consulting revenues. This was partly driven by inflation but also by “strong client demand due to regulatory changes and market volatility”.
The changed interest rate environment, while bad news for many investors, is in my view good news for those who provide advice to investors, i.e. it’s good news for pension and investment consultants such as XPS.
XPS also achieved stunning 54% growth in revenues from its Self Invested Pensions platform, although this was boosted inorganically by an acquisition.
The company isn’t lacking in confidence and explains its success as follows:
Sixth consecutive year of growth since listing - performance underscores the non-cyclical and resilient nature of the business
Strong growth in higher margin value-add services including Risk Transfer, DC Consulting, Scheme Secretarial and Corporate Consulting - areas where we have significantly bolstered our capabilities in the last two years
Good new business performance - winning new clients across all our business units
Outlook
We expect the demand for our services to remain high as we help our clients navigate the complex and evolving regulatory backdrop as well as economic and financial market developments. We have continued to grow market share, but with this still under 10% there are continued opportunities to grow, supported by both market and regulatory tailwinds. We expect the operational gearing that has come through this year to be a continued feature of our results in the future.
The Group has made a strong start to the new financial year with continued high levels of demand for our services particularly within Advisory and further success in winning new business. We remain confident in delivering against our expectations for the current year.
Adjusting items - the main negative feature of the accounts that I’ve found so far is £14m of adjusting items. So adjusted EBIT of £37m turns into just £23m of “actual” EBIT.
Adjusting items include (and they don’t add up to £14m due to rounding errors):
£3m of corporate transaction costs
£5m of share-based payments
£7m amortisation of acquired intangibles.
I think many (most?) investors would agree that the cost of share-based payments should not be adjusted out, as they are a real cost borne by shareholders.
As for the other items, I am happy to adjust out the corporate transaction costs but I have mixed feelings about amortisation. My instincts would be to permit about half of the £14m of adjusting items to be excluded from earnings.
Dividend - the full-year dividend is 8.4p, implying a high payout ratio on 12.6p of adjusted EPS.
Net debt is significant at £55m although the leverage multiple (over adjusted EBITDA) is ok at 1.38x. The debt is an RCF expiring in 2026.
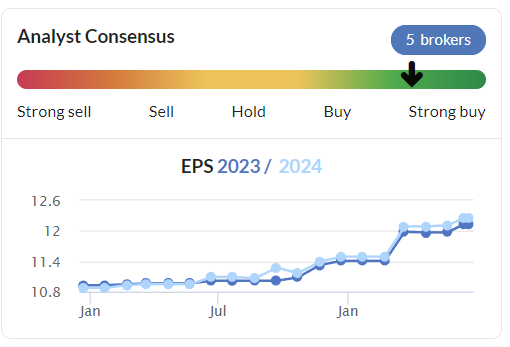
Estimates: today’s results are ahead of Canaccord’s estimates (adj. PBT higher by 5% than forecast), and they raise their adj. PBT estimate for the current financial year by 6% to £35.5m.
Graham’s view
I am close to giving the share the thumbs up. It has several positive features:
Recurring, inflation-linked revenues
Very good organic growth
Tailwinds from the economic/regulatory environment.
Strong earnings momentum; estimates for the current year were already raised twice and were still beaten in today’s results.
On the other hand:
£37m of adjusted EBIT isn’t entirely real; some of the adjusting items should not be excluded.
The market cap needs to be adjusted higher by £55m of net debt (which is floating rate).
Enterprise value is around £400m.
On balance, I think I’ll give this share the green light because my main gripe is only that it’s a little expensive. But if it hits its 2024 estimates and if adjusting items can calm down, then I don’t think the rating is all that high.
Fadel Partners (LON:FADL)
Share price: 147p (unch.)
Market cap: £30m
Firstly, let me say that I’m not sure there is any liquidity in these shares. So I’m inclined to keep this piece very brief.
According to Stockopedia, 90% of shares are held by top holders, which obviously doesn’t leave much for anyone else:
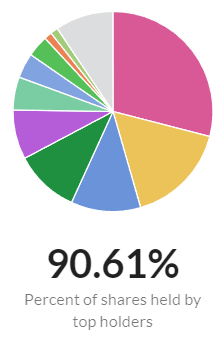
The stock listed in April 2023, and it seems like nothing has happened with the shares since then - the chart is just a horizontal line.
The New York-based company provides “brand compliance and rights and royalty management software”.
Here are the full-year highlights for FY December 2022.:
Revenue up 10% to $13m
Recurring revenue up 34% to $9m thanks to the acquisition of UK-based IDS.
Loss-making at the adjusted EBITDA level.
The company finished the period with net cash of $0.1m and gross cash of only $1.2m, but it then raised $8m (gross) from its AIM IPO.
CEO comment (he is also a 16.5% shareholders):
Following our successful IPO in April 2023, we have started deploying the funds raised in line with our strategic objectives to accelerate our growth. These include key strategic hires such as our recent addition of a global Chief Revenue Officer in June 2023, the rollout of a number of Brand Vision products at key clients and the strengthening of R&D to widen our competitive moat and expand our market share."
I am pleased to report that trading in FY23 has been in line with expectations…
Later, in a section headed “market opportunity”, he adds:
The demand for solutions to effectively manage digital content and intellectual property (IP) licensing is increasing across industries, geographies, and channels. In the area of rights and royalties, where IPM Suite operates, a notable portion of companies still rely on traditional custom-built legacy applications and spreadsheet-based methods for licensing and royalty management. These methods often involve large teams and outdated royalty monitoring and collection systems that are no longer suitable for current needs.
What FADEL apparently provides is a modern, enterprise solution to IP management.
FADEL itself is switching from a “professional services” model to a licence/subscription:

Graham’s view
Like everyone else who has only come across this stock for the first time, I’m new to it so I’ll keep an open mind.
Losses in 2022 don’t concern me, given the size of the business and the stage it’s at, although it’s important that cash burn is managed. If I find that cash is burning to such an extent that a raise will be needed in the foreseeable future, it’s inevitable that I’ll be taking a negative view on shareholder prospects.
For now, however, with $8m raised and with only around $2m of cash outflows last year (according to the cash flow statement), I’ll take a neutral stance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
I use the hub by premier inn quite often and can recommend. The cheapest rooms are very tiny - you can fit a couple - but only by climbing over each other to get into bed…
But they are very nice, modern and very affordable. Much nicer than most of the main premier inn hotels!
I have stayed in Premier Inns, the cheapest rooms were not small at all but they do vary. The last one was like a new Hotel although it was not. Excellent value for around £50 per night. The soundproofing from outside was excellent, could not hear any noise, good when staying next an airport.
One of the best blogs on Investment Trusts is provided by the renowned expert Jonathan Davis, who does a weekly podcast and a extremely reasonable paid service. I’ve tried commenting on ITs here on Stockopedia too but the site is poorly set up to make sense of them. It’s my main problem with this site
I no longer get the email alert for the SCVR. Is it something I've said/done or has that service been discontinued?
You're not alone... same here.
I never saw the point of the email, it arrived around lunchtime, just another one to delete.
On XPS Pensions (LON:XPS) (I hold)
3 of my friends work there now. When the first one joined, on his first day he got a laptop that worked, met his line manager and client Manager and accounts person so it was all clear what he was supposed to do and how and that he could (he wfh).
This was managed through a checklist.
this may seem a bit trivial but has not happened before to me or people I know in other comparable places.
And the stock was cheap and other people said good things. So I bought.
and have not regretted that decision.
I should add that as well as benefitting from rpi indexed contracts this sector has a number of tailwinds behind it in the short to medium term - 2 to 5y imo. Beyond that not sure.
Not a coffee can, more a nice coffee jar.
Looks an interesting company with good tailwinds behind it - big changes going on in the DB pension market and given the complexity I'm sure clients will need lots of help from the likes of XPS. Thanks to Graham for highlighting. Not especially cheap after a good run, but I've put on my watchlist and might buy some if it falls a bit.
Well the last 12 interest rate rises didn't work, but I've got a good feeling about this one.
Shouldnt have printed all that money. We are paying the price for it.
The thing that gets me, is this, everybody knew rates were going up, yet the market behaves like no one knew this!!
I think that will be a coincidence if it does work, they needed to wait until the last hikes filtered through. It was always a supply issue that is now reducing. Deflation in 2024 coming our way.
Recession more likely, prices will remain where they are and people will stop buying things or pay later.
Well said Lefty - you've hit the nail on the head!!
Hi
Amazon declines to comment on report of bid interest in UK's Ocado
News11 minutes agoLONDON, June 22 - A spokesperson for Amazon
AMZN.O declined to comment on Thursday on a Times newspaper
report that highlighted talk of potential bid interest in
British online supermarket group Ocado OCDO.L .
Ocado shares were up 43% by 0923 GMT on the London Stock
Exchange following the report.
Following up on some presentations we've just published from this week:
SThree (LON:STEM) trading update on Tuesday, here's the presentation to analysts. Seem to be holding up well in spite of dark clouds around. Life sciences have been impacted, the first time Timo can remember that. Otherwise, Engineering and renewables is very strong as one would expect. Always worth a listen as an economic barometer video & podcast.
IG Design (LON:IGR) Graham covered on Tuesday's SCVR. Improved FY results with continued recovery ahead of initial expectations. Rev $890m, loss before tax of $18,9m after a noncash $29.1m impairment. Margins should return to pre CV19 by FY25. Here's the management presentation & Q&A. Video & podcast.
Mind Gym (LON:MIND) FY23 presentation given to analysts. Double-digit revenue growth and an encouraging return to profitability. They have a new AI tool that they are beta testing. Interesting to see the adoption in AI across different businesses. Video & Podcast.
Paul, a few months ago you said you weren't yet buying back in to Volex (LON:VLX), you sound pretty positive today so..............
I'd like to buy dozens of different shares, but haven't got any spare cash unfortunately!
Also, I tend to like concentrating into a small number of positions.
But based on today's good results/outlook, and what seems like another good acquisition, then VLX is certainly higher up on my watchlist.
Also, as a couple of people commented at Mello recently, what I do with my own money doesn't always necessarily follow a value/GARP theme. I tend to have some money in value/GARP, and some in other stuff, including some more speculative positions.
Also we all like a good story, and most of us break our own rules sometimes, so these things aren't set in stone!
Volex (LON:VLX) - also interesting to note that Directors are putting in an extra £15m as part of the fundraising (99% of this £15m is coming from Nat Rothschild to maintain his 24.7% stake). He has deeper pockets than most of us but nevertheless it gives some comfort that he is certainly committed. I hold and have put in for a more modest amount of the retail offer!
I sold out of one of my favourite shares today Smiths News (LON:SNWS) after the SP continued to fall from 55p on 5 June to 45.3p today an 18% fall in 12 trading days.
I wonder if cost increases is affecting Newspaper sales nationwide given that so much news is on the Internet.
I did the same.. I banked a nice profit though...hopefully you did too.
Yeah I also made close to 6 figures last year on this (making up for others!!!...) and been selling since the high 50s down to 53 last week. Still got 50000 odd but down from 4x that. Worried inflation on newspaper prices, and consumers cutting their spending. Don't know details of their recent contracts if there is any committed minium or all volume based?? That would be key to know. Also worried generative AI seems very good at summarising articles so could easily replace newspapers as one of it's primary benefits. But if we see the 30s again on this I'll be back in big. Yield at that point wound be well into double digits
I do not like to over simplify, but a lot of people who buy newpapers are of a certain age and are rather attached to their daily news (like my parents) so yes, the market is shrinking, but I do not think any faster than it was 4 years ago.
Maybe the fall is just because a number of all had the same idea and sold out, me included. It's one to trade now, I think. I will be setting an alert for 40p, when I too, will buy back in...
Paul, please don't overlook AGM TU from Sanderson Design (LON:SDG), where I believe you have been interested in the past. Non-licensing seems a bit dull!
Yes, SDG is on the list, I always cover that one!
On initial reading the prelims from Volex (LON:VLX) look impressive. Haven't yet got to grips with the details of the proposed Turkish acquisition and not all platforms are participating in the retail offer, but good news that the placing it is at a commendably small discount to the current share price.
Also an interesting and positive announcement from Sigmaroc (LON:SRC) regarding the initial installation of carbon capture technology at one of its Nordalk lime kilns, which is to be rolled out over time to other kilns. The plan ultimately is to sell the captured carbon dioxide. Got to hand it to the innovative and entrepreneurial management team.
I have sizeable holdings in both of the above. Hopefully the market will share my enthusiasm, but I am not holding my breath.
Also prelims from Rockwood Strategic (LON:RKW) . Richard Staveley and the team at Harwood are canny operators. So I shall read the announcement with interest. "Follow the money" to borrow a phrase from the great 1970s movie All the President's Men for those old enough to remember it.
MS International (LON:MSI) delayed payment of counter drone system has hit profits, but they expect to be resolved shortly.
Order book doubled to to £115
Received new drone order circa £54m. Sound cautiously optimistic regarding US navy
Will likely be profit taking today but this looks very interesting. A shame they update the market so infrequently.
And they have almost doubled the dividend ! so they have put their money where their mouth is.
Really interesting one. When I read the headline I groaned a bit but then looked at the outlook and that changed my thinking.
£54m of new orders is very material. Good progress in the US too. The fact that the existing order has slipped across into new year means EPS should be very considerable for this new financial year. Looks like the non defence businesses are capable of generating 30p EPS in their own right so if we assume 25p eps from the delayed order and then on the £54m assume net margins of 20% that would be another 50-80p of eps so MS International (LON:MSI) looks like a business capable of generating somewhere between 80 and 120p earnings with 100p of net cash for £6.
There are a few on here who know this business better than me. Is that a fair assessment in margins / eps?
Looks like in FY 23 the defence segment made operating profit of £2m off revenues of £32m (so margin was circa 6%). In FY22 they had margins of 13% (i.e. op profit of £4m off revenues of £30m). Obviously FY 23 they haven’t booked the revenue from the £22m contract that was announced in December 22 and so one would assume that has affected the margins, as they have already ramped up production costs without booking the subsequent revenue. Looking at today’s results they hired an additional 11 people in their production area in Fy23 (assume related to aforementioned contract) to 263 people and the salary costs in total for group have increased by £4.4m this year, up 21%, from last year as well. Which I guess further backs this point up?
Historically the margins for the defence sector have been at around 11% (based on 2019 and 2018 results). Its ofcourse a little bit of guesswork on how much operational gearing they will get from the new £54m contract although perhaps net margins of 20% maybe at the high end (based on historic numbers), although they should definitely have a good tail wind on operational gearing for FY24.
Hello Simon,
re: MS International (LON:MSI) margins. Thank you - interesting comments. Given the lumpy nature of contract award and delivery in the defence division they often fall across arbitrary FY boundaries making it hard to assess operational performance.
In H1 the division revenue was £14m and they made a small operating loss of 200k. The anti-drone system contract was not awarded until December so this doesn't include any of those costs. But according to management there were additional costs in refurbishing of the production facility in anticipation of future orders.
In H2 revenue was £18.5m and they made an operating profit of £2.2m which looks like an operating margin of 16%. The margin on the additional £4.5m of revenue is almost 50% versus the H1 figures. Except that on closer reading it seems that the profit stemmed from the termination of 1 contract in April 23. Without any figures its hard to assess what really happened but its all we have to go on?
For additional contracts I think a 20% margin is a reasonable estimate to start from. There will be some contingencies in the budgeting as well, But things don't always go according to plan so it seems a useful 'finger-in-the-air'.
Staff - I think you've taken the group figures for production staff? For comparison the MSI Defence UK ltd figures from companies house for FY22 were £7m salary and 145 staff of which 86 were production. Unfortunately they don't consolidate the MSI Defence US llc figures - except at group level so again its hard to assess what might have happened? My estimate is that the US subsidiary has around 25-30 employess and according to the website they are hiring. Not surprisingly?
The increase in group wages that you refer to of £4.4m needs to be adjusted for the £1.636m of Covid retention scheme payments received in 2022? Which appear to have been primarily from the Netherlands which is the branding division? After adjustment the rise in staff costs appears to be similar if slightly less than the rise in staff numbers at group level? Or have I misunderstood?
You are quite right - it's hard to know what the operational gearing will be. I think there are number of reasons why MSI operational margins will be at the high end for these 2 contracts.
The MSI systems are very competitive in comparison with their peers and offer at least as high performance with higher reliability, operational performance and lower life cycle costs. MSI is the only vendor to offer this particular system which integrates the Northropp Grumman Mk44 30mm cannon with the MSI mount, MSI EOS package, RADA MHR radar and ??C2 system?? There is no reason for MSI to underbid proposals? These are large production quantities for the MSI systems which are typically delivered in low single numbers? Tends to improve gross margins slightly as well? The 2 large contracts appear to be particularly urgent. Full utilisation of staff and facilities maximises the operating margin. Production using overtime raises efficiency and customers tend to be less picky when its urgent? The quicker they are ready to ship the more profitable in general?
These are just my opinions - as always there is too little information to know what is happening. Of course all of this is assuming that they don't make any mistakes in their bids or suffer problems duriing production. The speed at which the first contract was ready to ship makes that seem unlikely, and their will be contingency budgets within the bids?
Apologies for writing another long post. As you can tell I am something of an MSI nerd - but its my largest holding by quite some way - caused by the poor performance of the rest of portfolio as much as by running my winner here. Other views are welcome,
cheers
Mark
Mark,
Thanks a lot for your excellent comments and further insight – seems like you are well up with events here.
Maybe I was being a bit cautious on the margin front after contract wins (in the back of my mind probably thinking how investors got their fingers burned with WANdisco‘s contract win ‘inflation’). I just wondered as well if the Directors may take small bite out of any additional revenue from the new contract as bonuses as I think they may not be shy of ‘going to the well’ when times are good!
You are right I was referring to production staff only, in terms of headcount, as I didn’t have the figures for defence staff but assume your estimate is correct and I completely forgot about the COVID retention schemes being a factor in 2022 (it seems a long time ago now – so well spotted).
Think they could definitely benefit short term from the focus on urgency and less focus on price as you say.
All the best
MS International (LON:MSI) FY results (unaudited) to end April 23 (I hold)
MSI is certainly raising more interest here than I am used to over the years. It's my largest holding by quite some way so I want to get my head around the detail of the results as soon as I have time - and given the lack of information (quite normal) I may have to wait for the audited accounts and the AGM in August.
Before I start the usual disclaimers regarding MSI apply. This is a family controlled firm. Very old-school in its approach - more the lack of it - to its investors. The board are not shy in rewarding themselves and there is nothing that small investors can do about it. Has to be taken into account. Luckily the company has a much better approach to its customers than its investors. Perhaps that the right way around?
On the face of it 25p eps is well below my expectations. After the good H1 results I'd expected a minimum of 37p and more like mid to high 40's. Outcome from defence was always going to be hard to forecast. But in the end its a thumping loss from the branding division in H2 which has delivered the damage a -2.6m loss for the year. Ouch! Effectively around 15p pre-tax earnings which explains the divergance? There is always one division at MSI that delivers a surprise! Either up ordown. Thats the down one.
Forging and superstructures delivered £5.9m of operating profits - around 35p of pre-tax profits on their own. Though the fall in revenues and profits from the high water mark of H1 leaves some questions over the trend for the current year.
Seems defence did ok. A 2m profit on 32m revenue. But because of the lumpy nature of the deliveries and the arbitrary date of the accounts its not a helpful guide to the future only the past? On closer inspection it appears that 2.2m is down to profit recognised on a contract terminated in April 23. That's quite a profit on a terminated contract. Very curious. And without it - the company would be short of another 14p or so of pre-tax profits. But alls well that ends well? Just like that! Thats the upside surprise then.
More good news. The delay to the delivery of the anti-drone systems appears to have been resolved and they will shortly be delivered. To be honest. I'm amazed that they were ready to go. It normally takes upwards of a year for MSI to deliver systems from contract and these were ready to go in little more than 4 months. Outstanding. That's a lot of overtime. Gives some idea of the urgency of the contract as well I guess? All the more frustrating that they are still waiting to be delivered? Its work on top of the 'baseload' if such a thing can be envsioned - though its worth noting that the work load on spares, maintence, training, refurbishment and repair is building all the time. A 20% profit margin seems a reasonably finger in the air guesstimate on that basis - so something like £4m, 25p eps on top of the recent low level of profits?
Even more good news. A second order for £54m (bear in mind that Defence turned over £32m in the year excluding the anti-drone contract) has been received from an undisclosed customer. Not stated whether the same urgency applies. Though the size of the contract and the speed with which its arrived implies some urgency. There is some implication that the land-based anti-drone market it developing much faster than MSI's traditional Naval market. To anyone addicted to youtube/twitter videos of fpv drone loitering munitions from Ukraine this will not be a surprise? It does seem that MSI are in the right place at the right time with very good connections. Huge potential to play for.
And more. The order book now stands at £115m. Which is normally primarily in defence.
Yet more good news. The company continues to make progress with its US Navy contract - a framework contract which was previously held by BAe Systems but won this time around by MSI. It's sole source and will role their systems out across large parts of the US navy and coastguard. Technical assessments seem to be complete and the framework contract exists, commerical negotiations for the first order are soon to take place. This contract is enormous over several years - but probably its biggest effect will be providing a steadier work load and also in acting as sales/marketing for global customers.
I find it very difficult to express the long term prospects for the defence division and to attach a valuation to it. There is a transformation underway which looks to be quite extraordinary, though frustratingly lumpy and unpredictable. As yet the order book leads the profitability especially since the company has been investing in facilities in the UK and the US to support its rapid growth.
Despite the disappointment of these results - the current year looks set to be record breaking - given the roll over of the delayed deliveries in H1 and the new contract. So oodles more jam tomorrow? Possibly. But management is not given to optimistic statements - and the positive tone of the commentary is very unusual. Not a single comment about the usual caveats? And the massive increase in the dividend from 7.5p to 13p - seems to be a very clear signal of jam today as well as management expectations in the current year.
All very promising, but I'm going to have to wait until December for the next exciting installment. I am optimistic for another nice xmas pressy though?
cheers
Mark
Thank you Mark. Thats a great overview of MS International (LON:MSI)
Id have normally banked profits this morning but with the delayed payment rolling into this half then December report should be very good. Certainly something special seems to be happening in defence, the recent 'Atlantic Declaration' wont hurt either.
Having looked over a few outlook comments this is, as you say, very bullish for them "We perceive that we are achieving a significant, upward step change in the further development of the Company that will again bring additional rewards and success for the business. I look to the future with confidence.
MS International (LON:MSI)
Some great work today on the above by Simon Cannell , lliswilgig an davidjhill .
Thanks to all 3 (and any that I may have missed) not an easy company to get under the bonnet so thanks for sharing your work.
Thanks for your excellent analysis on £MSI!
Am I right in saying that if the drone contract had been booked last full year, PBT would have come in around 9M?
So what would that have translated in to extra EPS? Was your 40p expectation based on this contract?
Apologies for late message, just catching up with todays SCVR!
Regards and thanks.
MS International (LON:MSI) MSI always appeared a strange mix of businesses to me. Defence I believe was mainly naval guns but has diversified into anti drone and truck based weapons... I believe they have now been approved by the US to be on their official trial list? and waiting for hopefully full approval for purchases (again correct me if I'm wrong)
On top of this we have a Forging business that makes the spokes on very large fork lift trucks.
and 2 very related businesses that deal with the construction and branding of Petrol stations.
They showed up on one of my quality screens a while ago..
I like that Revenue was growing, profits increasing and no debt
Would it be worthwhile to start reporting on some of the investment trusts?
This is an area where I currently have most of my money allocated. I know a lot of others in the same position. Some of these companies are not as difficult to analyse as you might think, for example, NextEnergy Solar Fund (LON:NESF), which owns solar assets and which offers an attractive, covered 8% dividend and which has an SRI Risk Indicator of 3 (low risk).
I see that Roland recently had a quick look at NextEnergy Solar Fund (LON:NESF) in his blog.
Think they are suffering much as Primary Health Properties (LON:PHP) as I mentioned yesterday - rising interest rates will affect them when their debts come up for renewal. On the face of it - you would think the big banks would be riding high - but they seem to be affected by fears of defaults on their loan book - you just can't win
Agree there's interesting opportunity in this space, but not convinced about the not as difficult to analyse bit. Think a degree of specialism is probably needed before anyone commented confidently.
The AIC has good data on Investment Trusts- available for free. https://www.theaic.co.uk/.
Across the range a number of options from General to specialist like Vietnam- one I hold is VNH . Valuing the private equity funds can be more of an issue. Most Trusts announce a daily NAV and since some biggish discounts now could be opportunities if sentiment improves and corporate activity- a few have decided to wind up recently. A sector I used to work in as a stockbroker-admittedly a long time ago.
I’d be keen to discuss IT’s - find myself moving more of my PF to them as fed up with seeing all my single stock holdings tank on a daily basis ! EG BOTB yesterday….
Yes I would like to see reports on Investment Trusts some like HIPL and INPP have fallen more than justified
BattleOfBrit
I hold a lot of Investment Trusts and there are some at exceptional bargain prices and on big discounts and paying big and well covered dividends too. So it’s a great time to be checking them out, including NextEnergy Solar Fund (LON:NESF) which I bought recently. Charles Mitchell mentioned VinaCapital Vietnam Opportunity Fund (LON:VOF) which I also hold and Vietnam is described as the new China. There are 2 other Vietnam Trusts VietNam Holding (LON:VNH) and Vietnam Enterprise Investments (LON:VEIL) also worth considering. I’ve had great success with Vietnam Trusts over the last 10 years, but recently their market fell by 40% to provide another exceptional buy opportunity. There has been modest recovery in recent weeks.
I’ve posted here on a range of Investment Trusts but there has been insufficient follow up to make it worth the effort. But I’m all in favour and will post on it, as hopefully others would too, IF there is genuine interest in Investment Trusts and someone starts an Investment Trust thread. Not sure it’s appropriate for this Small Company bb.
Morning All,
MS International (LON:MSI) results this morning. Delayed order impacted full year numbers, looking past that though, order book doubled, 16M net cash, divi for year up around 60%. Plus a new defence contract worth 54M.
Alpha Financial Markets Consulting (LON:AFM) had a very good update which i hold. what do people think of the update and prospects.
Any negative narrative such as this in the Outlook Comments will get hammered in this market, especially today.
"· In recent months, the global consulting market has experienced increased levels of competition as a result of overcapacity, which we expect to be the market backdrop in the short term
· As the global consulting market balances supply with overall demand, the Group will continue to manage appropriately its discretionary spend and hire selectively to invest for the future, in line with our 2028 strategic ambition to double the business
· While we currently see higher levels of competition and a lengthening sales cycle, we are confident that Alpha's strong client proposition and business strategy will continue to drive market share growth
· The Group enters FY 24 with resilient trading and a good pipeline of new business opportunities, "
yeah the market didnt react well to the update. but could just be profit taking perhaps
Alpha Financial Markets Consulting (LON:AFM) The results were very good. But I just sold my shares due to negative outlook comments. I expect that the next trading update will be disappointing.
Whitbread (LON:WTB)
Sorry Paul, your google was not up to date. Costa was sold, completing in Jan. 19. Also the pub restaurant chains were reduced, I can't remember when, to those that are co-located with Premier Inn so come under the same site management and I believe provide breakfasts for the hotels.
They still have Brewers Fayre and Beefeater pubs, not all are within Premier Inn's. I stayed at a Premier Inn, recently, very impressed, excellent value for money. It is currently trying to sell around 250 out of 440 pubs.
Morning sharw,
Drat, I cut corners to save time, so thank you for correcting me re Costa. It didn't look right when I wrote it actually!
I'll fix that now.
Many thanks! Paul.
There is talk they are currently looking to reduce pubs further, which I think is a mistake. Often the pubs are located next to the Inns and can offer breakfast etc. This aside Whitbread is a pure hotel room provider with a growing presence in Germany. In my view they have it right. I used to travel in Germany a lot and Premier Inn fits their view of hotels. They have a strong position in UK already from which to finance the development.
Whitbread (LON:WTB)
Yes, I agree selling off restaurants would be a mistake but this is outside rumour/pressure. A table issued at the last results presentation showed that of around 800 restaurants only 15 were not on a Premier Inn site and here is part of a slide from that stressing their importance:
(F&B = Food and beverage)
Whitbread shareholders get 10% off food and soft drinks at restaurants and those staying at Premier Inn get a free breakfast! https://www.whitbread.co.uk/in...
Whitbread (LON:WTB) V minor point re Premier Inns & food. Breakfast isn't free - albeit pretty decent value at £10 p/p for self service hot breakfast with decent choice. And the evening meals can be good too. Holiday Inn Express do free/included breakfast.
It is to shareholders (64 shares or over) "
Free Breakfast for shareholders"
For anyone with mobility problems, Premier score highly. The advantage of a brand with all being built to a common spec. Visit and check out your nearest one and book one miles away with confidence maybe if you want a wet room phone them to confirm availability.
My morning smallcap tweet: Keying executive vehicles
Eenergy (LON:EAAS) Westminster (LON:WSG) Good Energy (LON:GOOD) Robinson (LON:RBN) DG Innovate (LON:DGI) Access Intelligence (LON:ACC) Biome Technologies (LON:BIOM) Litigation Capital Management (LON:LIT) Volex (LON:VLX) MS International (LON:MSI), NCC (LON:NCC), Sanderson Design (LON:SDG), Futura Medical (LON:FUM), Speedy Hire (LON:SDY)
◄eEnergy (EAAS)► changes FY end from June to Dec because "revenues are weighted towards the middle of the calendar year". A week before the FY end! Nothing to see here. [SP=4.53 Cap=16m]
◄Westminster (WSG)► plans cost cutting. [SP=1.75 Cap=6m]
◄Good Energy (GOOD)► AGM stmt - "the business has performed more strongly than planned in the first five months". Leaves FY expectations unchanged. [SP=174.8 Cap=29m]
◄Robinson (RBN)► AGM stmt - first 5 months rev down 2%, volume 11% down. 4% is due to a major UK customer experiencing a supply chain issue. Profits are substantially down. Cost cutting. Nevertheless expects adjusted operating profit in line. [SP=106.3 Cap=18m]
◄DG Innovate (DGI)► £517k placing at 0.05p, a 23% discount, to fund the Company's ongoing commercialisation strategy for its Enhanced Drive Technology and Enhanced Battery Technology. [SP=0.07 Cap=6m]
◄Access Intelligence (ACC)► guides H1 rev down 0.3%. Adjusted EBITDA £2m+. Guides H2 adjusted EBITDA and cash generation in line. [SP=70 Cap=89m]
◄Biome Technologies (BIOM)► £542k contract win for Stanelco RF Technologies. [SP=125.05 Cap=5m]
◄Litigation Capital Management (LIT)► full resolution of direct balance sheet investment. A$8.6m profit. A partial award was announced in Feb. [SP=85 Cap=101m]
◄Volex (VLX)► £60m placing and retail offer at 275p, a 4% discount, to fund €178m (max) acquisition of Murat Ticaret, a leading manufacturer of complex wire harnesses. Expected to be mid-teens earnings enhancing in the first full year of ownership. Also FY-Apr small beat. Outlook confident. [SP=286 Cap=455m]. I hold.
◄MSI (MSI)► FY-Apr. VSHORAD delivery delayed into this FY but "recently received encouraging confirmation that matters have been resolved...We expect to receive payment shortly and then the equipment can be delivered." Final div 13p (7.5p). [SP=624 Cap=103m]
In line: NCC, SDG, FUM, SDY
Whitbread (LON:WTB) Didn't it sell Costa to Coca Cola?
The company was founded in 1971 by Sergio Costa in London. In 1995, the company was acquired by Whitbread, who later sold it to the Coca-Cola company in 2019. Since then, Costa Coffee has grown to more than 3400 stores in 31 countries. The company was founded by Sergio Costa in 1971 in London Fenchurch Street.
Thanks for flagging my error re £WTB , I'm afraid Google let me down badly on this, when I was trying to save time. I'll get that fixed now...
It's more likely the AI engine in google that let you down. Traditional Google search would order by the latest after sponsors, where as AI aggregates the data and where popularity is the prevailing influence. Interesting times. So we now get an aggregated view of popular opinion heading up our google searches which may or may not be correct and then we get traditional google search results below. As people far wiser than me say, do your own research.
Yes, lesson learned. I'll just go direct to company's own websites from now on.
Thanks, Paul.
Good morning to you both, coukd you take a look at Volex results please? They look impressive and a fundraise for an acquisition at just a small discount.
Atb DH2
Anyone had an invite for the REX retail offer yet? I see people on Hargreaves Lansdown have received an invite. Nothing from Interactive Investor for me so far. Volex (LON:VLX)
Edit: It's available under corporate actions on Interactive Investor until 10.30am
Nothing on the Volex (LON:VLX) offer from A J Bell either, have just been to check. Impressive results I thought and I will take part in the placing via REX given the chance. I'm not familiar with this service, I've only used PrimaryBid previously.
On the results, the standout figure for me was the 33% growth in sales in the EV segment. That momentum looks set to continue for years to come and Volex is well-placed to capitalise on it. I'm a happy holder this morning.
The market doesn't appear to be giving Volex (LON:VLX) any credit for its excellent results and acquisition, if the price drops anymore it will be cheaper to buy in the market rather than the placing, which could mess both placing up.
Has just become available on AJB. Go to Buy/Sell page and enter this code: NEWABK3
Not received an invite for Volex placing on HL yet. Web site says they cannot provide an offer price!
Not received an invite for Volex placing on HL yet. Web site says they cannot provide an offer price!
I must admit I find that strange given previous experience with HL. You’re now too late and have missed the boat. If you were eligible and they failed to contact you I’d make a complaint. My Volex (LON:VLX) holding is with AJ Bell. I took part in the retail and got all the shares I requested i.e. without scaling back.
Volex (LON:VLX) I just subscribed to the offer for new shares on Interactive Investor.
Could be a pretty miserable day if the BOE go for 0.5% rise and a really hawkish outlook...
I'm hoping it's already priced in! (Fingers and toes crossed)