Small Cap Value Report (Thu 22 Oct 2020) - QTX, SDI, G4M, CALL, CWD

Good morning, it's Paul here with the SCVR for Thursday.
Timings - mostly done now (14:00), I need a couple more hours to cover everything, so 4pm estimated finish. Today's report is now finished.
Agenda - here's what has caught my eye this morning. There are quite a lot of trading updates, from interesting companies;
Quartix Holdings (LON:QTX) - Trading statement
Sdi (LON:SDI) - Trading update
Gear4music Holdings (LON:G4M) - Trading update
Cloudcall (LON:CALL) - (I hold) - CMD Trading update (and investor presentation on IMC today at 3pm - open to all)
Countrywide (LON:CWD) - Interims & recapitalisation
Trifast (LON:TRI) - Trading update - see tomorrow's SCVR
Frp Advisory (LON:FRP) - AGM Statement - see tomorrow's SCVR
Possibles if there's time: Alumasc trading update, and 1PM AGM Statement
.
I'll probably take a look at the reader comments later today, once I've finished the main report, so please don't get offended if I don't reply.
Quartix Holdings (LON:QTX)
Share price: 335p (up 5%)
No. shares: 47.96m
Market cap: £160.7m
Quartix Holdings plc, one of Europe's leading suppliers of subscription-based vehicle tracking systems, software and services, is pleased to provide an update on trading for the 9 months ended 30 September 2020.
This is the key part of today's update -
The Board is pleased to report that it expects revenue and free cash flow for the year to 31 December 2020 to be in line with current consensus market forecasts, which are shown at the foot of this announcement1.
Adjusted EBITDA is expected to be approximately 15% ahead of current consensus market forecasts.
[1] The Board believes that consensus market expectations for 2020, prior to this announcement, were as follows: revenue: £25.8m; adjusted EBITDA £6.9m; free cash flow: £5.2m.
I’m a bit confused as to why EBITDA is up 15% on forecasts, when revenue is just in line. This is not explained in the announcement, but possibly broker notes might add more colour (see Finncap's update note today, on Research Tree).
My thanks to the company & its advisers for including a footnote, stating what market expectations actually are. This is incredibly helpful, and saves us all a lot of time & avoids confusion. I wish all companies would follow this approach, and thereby be helpful to investors.
Recurring revenues make up the bulk of revenues, and are now running at an annualised rate of £21.9m (up £1.1m this year)
Taxation - will be paid up to date by end of 2020 (re covid Govt support schemes)
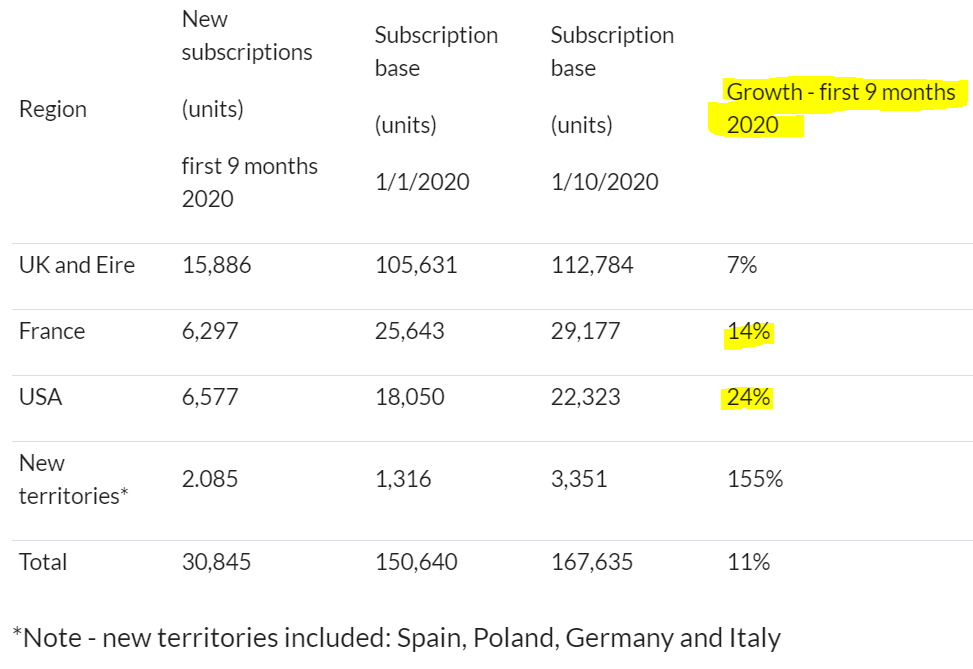
Revenue growth of 7% achieved, despite covid disruption - so this company goes on the list of shares which have proven themselves to be safe havens - important if you’re worried about the impact of a second wave.
Growth - this table shows growth per country. Note strong growth in France & USA. If it can gain traction in USA, a massive market, then I could see that driving a re-rating of the shares.
.
Non-core insurance telematics business (low margin) installations fell 49%, with this trend expected to continue. The company’s strategy has been to gradually exit from this market because it’s not very profitable. Generally it’s only young drivers who will tolerate a spy in the cab, because insurance companies force them to. They’re gleefully ditched at the first opportunity, understandably.
Recovery from covid has been better than expected, in terms of new business. The company is reinvesting the benefit of this in extra sales/marketing, and product development. That makes sense to me.
Presentation slides are on the company’s website here.
Valuation - this is the tricky bit. There’s no doubt Quartix is a high quality business, which reliably throws off strong cashflows, which are used mostly to pay divis. So far so good. The only trouble is that it’s looking almost ex-growth from the figures below;
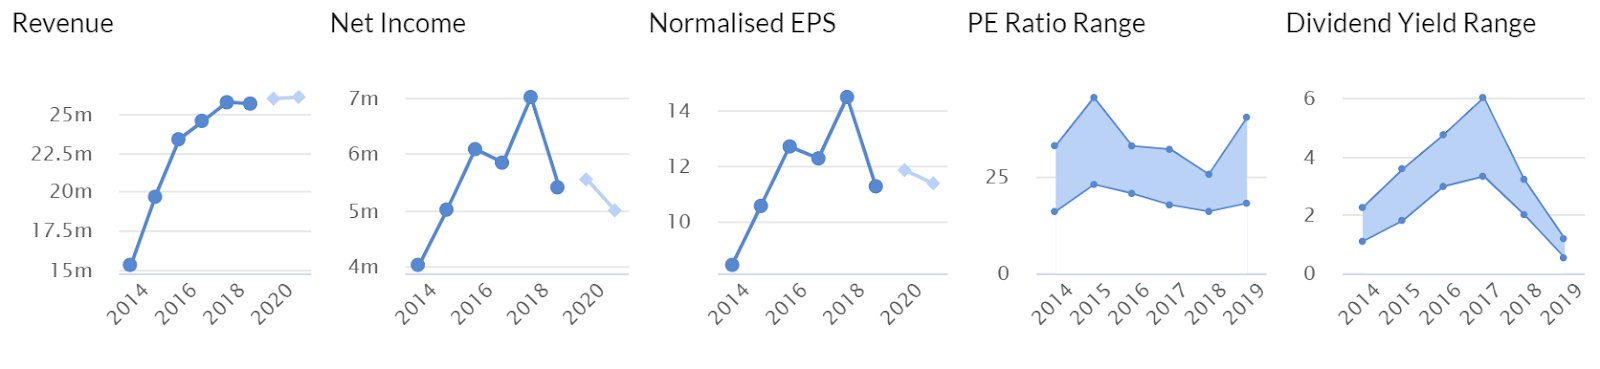
Growth in subscriber numbers is good, but remember that this is a competitive sector, so there’s always downwards pressure on pricing too, which blunts the profit growth.
My opinion - a very nice company, with clean accounts, genuine cashflows, and it even pays a decent divi yield of nearly 4% - very unusual for a small technology company.
The price looks full, but I’m more comfortable with this, given a better than expected update today, and importantly the international growth (esp. USA) which could provide better upside than if the company had remained a UK-centric business.
Finncap has increased FY 12/2020 EPS forecast from 11.6p to 13.1p today (see update note on Research Tree). Its forecast for FY 12/2021 of a fall to 10.1p doesn’t make sense now, so I imagine that’s likely to be raised to maybe 13-15p in due course.
I’m happy to value the share on 20 times my estimate of 15p earnings for 2021, so I get to 300p. The current share price is 335p, so I’d say it’s up with events. However, we’re in a big bull market for growth companies, so it wouldn’t surprise me to see the share price chased higher. 400p looks possible in an exuberant market.
.
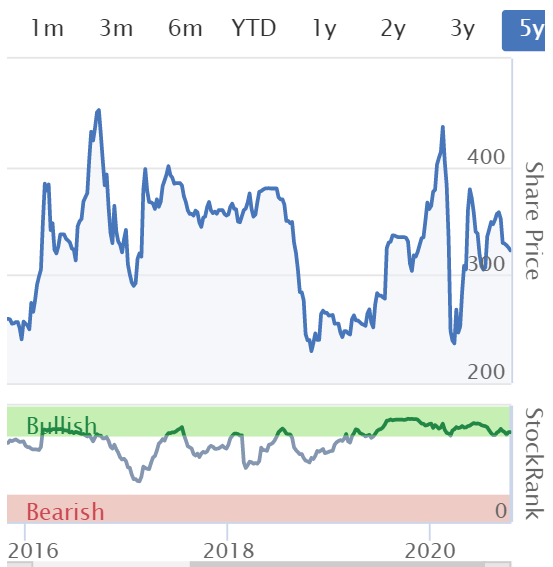
It’s surprising that the share price has traded sideways, in a wide range, for the last 5 years. This reflects the point I made above that there hasn’t been any profit growth over that period.
.
.
Sdi (LON:SDI)
Share price: 68.7p (up 6% today, at 10:32)
No. shares: 97.8m
Market cap: £67.2m
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing control applications, is pleased to announce an update on trading for the current financial year ending 30 April 2021.
One-off orders related to covid have given a boost to two of the group’s subsidiaries;
Given the very positive level of sales at Atik and MPB and the cost savings effected in the other businesses, the Board now believes that the Group is likely to achieve sales and profit before tax broadly at the levels budgeted for this financial year before the onset of the pandemic, and therefore above current market expectations.
The Board stresses that the incremental sales at Atik and MPB are the result of one-time contracts related to the COVID-19 pandemic and expects them to be completed well within the current financial year.
Consequently, the Board's view on the Group's 2022 financial year is unchanged….
Our other businesses, which have all remained operational throughout the COVID-19 pandemic, have seen customer order patterns showing a return towards normality.
That’s well explained, and I applaud the company’s openness for explaining the one-off nature of those contracts, thus keeping investor expectations grounded.
Outlook - add this share to the list of things that have proven resilient to covid/lockdown;
"Our business model has proved resilient, and we expect to exit the pandemic even stronger than when we entered it."
My opinion - clearly this is a good update. Finncap has today raised FY 04/2021 EPS forecast by 15%, to 4.2p. However, this is due to one-off contracts, so shouldn’t really alter the valuation of the shares much, if at all.
Current forecast is for a slight fall in EPS the following year, to 4.1p.
Given this group’s good track record, and high profit margins, I would be inclined to value it on a PER of 20. That implies a share price of just above 80p. The current price is 68.7p, therefore I think it still looks reasonably priced, despite a strong share price performance.
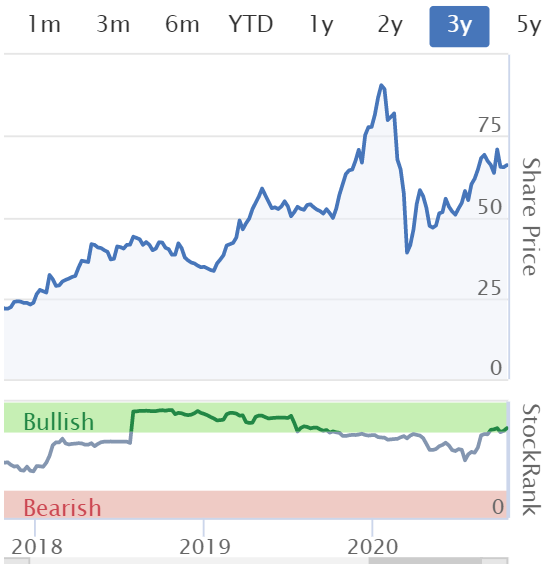
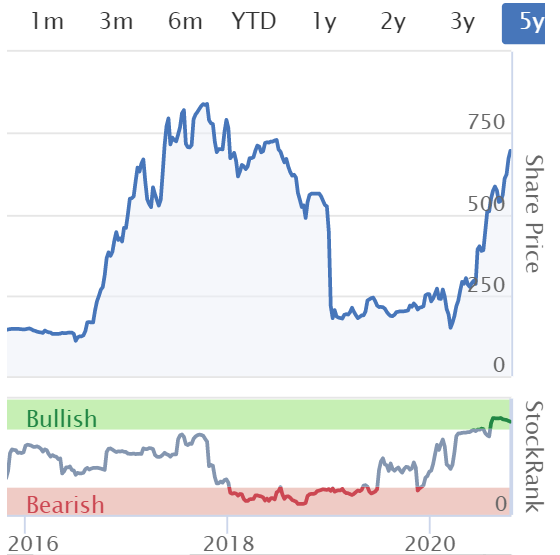
Shareholders have tripled their money in the last 3 years - very nice indeed! There are no divis, but who cares when you've seen that level of share price growth? Note that the Stockopedia computers really like it too, with a StockRank almost constantly in, or near, the green zone.
.
.
Gear4music Holdings (LON:G4M)
Share price: 705p (up 2%, at 12:42)
No. shares: 20.95m
Market cap: £147.7m
Gear4music (Holdings) plc ("Gear4music" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, today announces a trading update for the six months to 30 September 2020.
We have yet another strong trading update today, this company is really on a roll. Expectations are upgraded again;
… the Board is confident that results for the full financial year will be ahead of previous consensus market expectations
We’re not given a footnote to tell us what market expectations are, which wastes time for everyone who reads the announcement, as we then have to look up expectations, and not everyone has access to that information, or the data is often different on different financial websites.
Stockopedia is showing just above 21p EPS, which looks too low to me, it could be that an out-of-date forecast might be pulling down the average possibly? When I last looked at G4M here on 1 Sept 2020, I estimated that EPS for this year looked to be heading for 25-30p. Today’s update reinforces that my range of estimates looks realistic.
Outlook - still trading strongly at the start of H2;
Strong growth in sales and gross profits has continued during October, and preparations for what we expect to be a busy peak trading period are well advanced.
My opinion - this is a lovely situation, where sales are growing very strongly, up 42% in H1, and gross margin is usefully up 330bps to 28.5%. That is a potent mixture, for a geared benefit to the bottom line. Especially as costs have been tightly controlled, and marketing spend is substantial but falling as a percentage of revenues.
Clearly the business must be benefiting from people spending more time at home due to covid but even so, the rise in profitability from the revised strategy to focus on margin ahead of revenue growth, is delivering superb results.
The share is quite pricey now, but performance fully justifies that, in my opinion. I remain positive on this share, and think it’s likely to be a very much larger business (nearly half sales are already international, remember, so not just a UK business) in 5 years’ time, and the share price would probably be a lot higher by then too. An excellent company. I don’t currently hold, having sold too early. However, I’ve had 2 large profits from this share over the years, so am very grateful to management and their team, for having delivered superb results for investors.
.
.
Cloudcall (LON:CALL)
94.5p (up 2%) - mkt cap £36.5m
(I hold)
Company presentation, with Q&A, is on InvestorMeetCompany at 3pm today.
... robust recovery from the initial COVID-19 impact earlier this year, with the Company's growth indicators expected to normalise back to pre-COVID-19 levels by early next year….
"We have seen the Company's growth metrics continue to improve during Q3 and into the start of Q4 2020. An accelerating lead flow driven by our ongoing commitment to investment in partnerships and marketing has been feeding a strong sales process and excellent demonstration to sales conversion rates which has in turn been driving new customer wins. In Q3, we saw a record demonstration to sales conversation ratio of approximately 56%, up by approximately 50% from pre COVID-19 levels
That demonstration to sales ratio of 56% strikes me as remarkably good. As management explained on the last, very interesting webcast, if they can get in front of the customer to demonstrate the product, then they usually buy it. Hence the strategy is to do more product demos!
… Furthermore, I am delighted to see that our existing customer base are beginning to buy more, which further demonstrates that CloudCall's offering remains highly compelling in both an office or working-from-home environment. Both of these factors combined means we remain confident in our ability to return to historic levels of growth next year."
We’re hearing this sort of thing from so many companies at the moment, that I think it’s a time to be bullish about small cap shares which are saying this sort of thing. The TV news tells us that world is ending, on a daily basis, but that’s not reflective of what’s happening at many listed companies.
Revenue guidance - this is helpful;
Whilst the broader global economic backdrop remains challenging as a result of COVID-19, given these improving metrics, the Company confirms that it now expects full year revenue for the 12 months to 31 December 2020 to be ahead of expectations and will be in the range £11.5m to £12.0m.
Stockopedia is showing consensus already at £11.6m, so the update doesn’t seem to be indicating much more than that. The company is still heavily loss-making at this stage.
A new market is being entered, for property. Until now, CALL has focused mainly on the recruitment sector. That’s good news. Management is ambitious about growth, but of course that comes at a price, with heavy cash burn to date.
Before the COVID-19 pandemic, we held an ambition to reach a £50 million revenue run-rate within 5 years (2025) and now that we've returned to growth following the initial impact from COVID-19, we've set ourselves the same target to achieve this by 2026.
My opinion - it’s taking longer, and costing much more, than originally planned, but I reckon CALL is getting there gradually. This update today is reassuring.
Something urgent has cropped up, so I have to park things for now, and head back to Bournemouth. I'll aim to do some more updates later, but it won't be until this evening I'm afraid. Apologies for any inconvenience.
All sorted now, so I can carry on writing more sections.
Countrywide (LON:CWD)
165p (down 10%) - mkt cap £54m
I’ve not looked at this estate agency business for a while, but have been reading Graham’s notes here from its trading update on 26 June 2020.
Half Year Report today, here are my notes;
Big beneficiary of Govt support schemes (furlough, business rates relief, deferred £44.6m taxes), and leniency from most landlords.
As a result, the Group traded positively at the adjusted EBITDA level and had strong liquidity through COVID-19….
Group income from continuing operations was £173.8 million (2019: £241.6 million); the Group continued to trade profitably with adjusted EBITDA(1) of £14.9 million (2019: £19.2 million(2)) in spite of loss of tenant fees of £8 million and COVID-19
That’s quite impressive, given what a calamitous period this has been with covid & lockdown.
Given that we know the property market seems to be recovering, stimulated by the Stamp Duty reduction, then it’s reasonable to assume business here should be recovering too.
Net debt - it’s good that the company fully discloses the short term benefit of tax deferrals, this is essential information that all companies need to disclose, even if it’s small to nothing;
As at 30 June 2020, the Group's net debt(3) was £47.3 million (FY 2019: £82.9 million) against available liquidity of £135 million. The underlying net debt, after adjusting for HMRC deferrals, was £91.9 million. Net debt/adjusted EBITDA(3) was 2.1x (FY 2019: 3.4x)
Exceptional items - once again are huge, as in recent previous years. This time it’s a £51.8m charge. This is mostly goodwill write-offs, but note the £3.2m wasted on fees re merger discussions with LSL.
Outlook - this is a cop out, they should be able to give guidance at this late stage in the year.
Current trading remains buoyant, with positive performance indicators across the Group. The Government's stamp duty holiday for properties up to £500,000 provides further stimulus to our principal markets. However, it is still too early to assess the long-term impact of COVID-19 on the economy, and specifically housing transactions and, as a result the Group is unable to provide guidance for the full year ending 31 December 2020.
Cashflow statement - gross cash has risen from £18.2m to £76.8m in the period, but this has been driven by drawing down £25m on its RCF bank facility, and the £44.6m taxes deferred. The taxes will have to be repaid by end March 2021, I think is the deadline, so this cash liquidity should be seen as temporary.
Borrowing facilities - an interesting topic, given that CWD has a weak balance sheet. However, the news today on a recapitalisation means that I don’t need to cover the now historic position. This is interesting below - maybe the debt fund put the company under pressure to recapitalise (and thereby ensure they get paid 100p in the pound, rather than a discounted figure in the event of insolvency?). I wonder what haircut (if any) the previous debt holders took, to exit their risk?
Since 30 June 2020, the composition of the Group's lending syndicate has changed and is majority owned by a specialist debt fund who have been part of the facility since September 2018, now controlling 79.5% of the Group's facilities.
Going concern note - I’ll skip this, because a recapitalisation is being done.
Balance sheet - NAV is £53.7m. I usually write off intangibles, which total £181.8m. That gives a very weak, negative NTAV figure of £(128.1)m. That’s clearly a bad position to be in, completely dependent on continued bank support. Hence it comes as no surprise that the business is being recapitalised.
Recapitalisation - in a separate RNS, titled Strategic Investment by Alchemy. Key points
Fully underwritten equity fundraise of c.£90m
If the Proposed Transaction is approved and implemented, Alchemy will hold between approximately 50.1 per cent. and 67.7 per cent. of the Enlarged Share Capital, depending on the results of the Open Offer and Tender Offer.
66,684,215 New Ordinary Shares at an issue price of 135 pence
There are 32.76m shares currently in issue, so this deal more than triples the share count, to c.99.4m shares, considerable dilution for existing holders.
... in urgent need of recapitalisation to reduce its net debt and lessen its exposure to its lenders.
I’ve been pointing this out for years!
There’s also a tender offer at 180p;
... an opportunity for Qualifying Shareholders who do not wish to invest further to tender their shares by participating in the Tender Offer
Revised bank facilities have been agreed, “covenant-lite”.
My opinion - this deal at long last makes Countrywide investable for me, although it doesn’t completely fix the balance sheet, which will still have negative NTAV. Insolvency risk is now largely removed, since once Alchemy has refinanced it, its shareholding would be too large for it to walk away.
There’s a chance that Alchemy might take it private at some point perhaps?
With the share price currently at 165p, it’s possible that the tender offer at 180p might be supporting that price in the short term. I’m happy to leave any clever arbitrage trades to traders. Personally I’d like to wait for the dust to settle, and look at it again once the fundraising deal has been done & dusted.
This deal greatly improves Countrywide’s prospects from precarious, to a more stable footing.
Note that of the £90m being raised, a staggering £8m is going in fees, despite Alchemy underwriting the deal.
.
All done for today. See you tomorrow, which will be up early, with few catchup sections.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
I just don't get why Countrywide (LON:CWD) is becoming investable Paul? With advance apologies to any estate agent....but they're estate agents!
There's no USP that sets them above any other agent. Yes they have some brands that some people will recognise, but if the local Bairstow Eves or Austin Wyatt shuts on your High St, do people cancel selling or buying their house, No , they move along and use the next estate agent along.
Therefore to make them interesting surely they have to stand out from the rest of the rest.
All I meant by saying "investable", is that it is no longer uninvestable, due to the balance sheet risk being mostly fixed, due to refinancing. I don't want to buy any shares in it either.
Can anyone help ... Sylvania P is shown as having a dividend yield on Stokopedia of 14%, yet it is paying 1.6pence PA per share with a share price of 65pence. Surely this is nearer 2.5% yield. Am I missing something? Thanks
I think you are looking at the 12 month forcast dividend yield which is 14%, In the Financial Summary it says for 2020 the yeild is 2.32%
I'm not currently invested in Sylvania Platinum (LON:SLP) so not fully up to speed on what they are doing, but I do know that they have been considering windfall dividends based on the "super profits" they have achieved from the market prices of Rhodium & Palladium. So I presume these have been factored into the forecast dividends for FY 2021 (& 2022 - which would seem a bit more speculative).
If they do go for such a dividend it will be in the quarter after the new year - probably announced in the Half Year results around the end of January,
You’re not missing anything. Unfortunately the biggest dividend payers list is inaccurate, There ate a lot of shares shown as paying very big dividends that don’t pay any dividend at all. I questioned this with them ages ago, but those top dividend payers lists have never been corrected.
Countrywide (LON:CWD) the placing to Alchemy includes up to 17.9m shares (6 for 11) at 135p, 27% discount to last night close of 184p. Gives TERP of 167p, not far off todays close 165p. Or disgruntled holders can tender 10.3m shares (1 for 3) at 180p.
A better deal for Alchemy perhaps(who underwrite the placing for £8m!) but all in not bad for existing holders either given major derisking of balance sheet.
CALL -Given that H1 was 5.2m this is a good recovery adding 6.3 to 7m in H2 which should follow through next year as recurring revenues increase. Seems to gaining traction.
Quartix Holdings (LON:QTX) Paul says "...Its(finnCap's) forecast for FY 12/2021 of a fall to 10.1p doesn’t make sense now, so I imagine that’s likely to be raised to maybe 13-15p in due course".
Well, maybe not as they have picked up this from today's statement: "Quartix intends investing further during the remainder of 2020 and 2021 in sales, marketing and technological development..." and so explain why they have left the next year's forecast as is:
"Although further investment in sales and development (fully expensed by QTX) is flagged for FY 2021,our forecast was already conservative so we leave it unchanged".
Novacyt Sa (LON:NCYT)
just had a bit of research. Two coverage and explosive interview yesterday with two City fund managers regarding £NCYT.
NOVACYT
Today at 1pm Fund Managers including Richard Leonard from Trium will be discussing #NCYT Novacyt Sa (LON:NCYT) and answering questions we have sent to them on your behalf.
Tune in at 1pm, don't miss it!
search on Twitter I couldn't copy the link for whatever reason.
tamzin who is a reader here is apparently sorting it. Tamzin could you help re the link?
I would tune in, but that damned GoToWebinar that Tamzin's uses produces unintelligble audio on my PC - every time. Judging by the SP action the Chuckle Bros are saying nice things!
email me, and we'll try to resolve for you. Have you tried doing a sound check?
What's your email please?
Email through the piworld contact page here.
problem is trying to buy it,especially if people listened to the webinar with another one promised just on Novacyt
Sorry, was preparing for the webinar. We're now editing, and it will be published on piworld tomorrow, with a link here.
Thanks a lot Tamzin. Amazing work.
Opg Power Ventures (LON:OPG) at 10p had good results this morning and now the chart potential looks very interesting. Stock Rank = 75 (SR Value = 99)
This share is defo not for most - there are risks and they operate a coal powered station in India so it is not ESG friendly. However the growing power needs of India are so large that their carbon policy plans to keep all current coal power and invest in solar/renewable for future energy needs. So for the next 20-30 years - the coal power is needed.
Onto OPG... they had big profits to Mar 20 EBITDA of 31m, PBT of 14m, GROSS debt reduced by 24m to 56m. At the end of Sept GROSS debt reduced further to 44m i.e it has reduced by 36m in 18 mths vs MV of 40m! In addition , they have CASH of 3m, restricted CASH of 7m, and Solar assets for sale of 15m. Solar has performed well this year.
Operation at the 4 plants went from c.75% to 46% for the 6 months to Sept 20 but now is at 63% and rising. They have remained profitable during India's heavy lockdown, helped by the fast falling price of coal.
Let me state again there are risks but IMHO the upside provides compensation for these. The CASH over the last 3 years has been incredible - c.15p per share.
so in 2 years they will likely have no net debt and capable of post tax CASH flow of c.25m (6p a share).
the interesting bit for me is actually not the fundamentals but the chart. If there is a bounce and volume from the current price of 10p then it appears a very significant chart double bottom. i additionally like that the overseas earnings gives me a crude GBP FX hedge.
disc: i hold.
investing style: cautious - normally! but couldn't resist the CASH flows
The divs are showing total 1.5p over past few year?
Cloudcall (LON:CALL)
They have announced they expect 2020 sales to be ahead of expectations today- this would be a plus point but the range given is probably exactly would i would have expected based on their previous statement dated 23/9/2020 when they said
"the Group is now confident that it can expect to deliver modest revenue growth for 2020,"
Last years sales were £11.4 mill and the range they give today is £11.5-£12.0 mill - i would say if we take the midpoint then thats an increase of £0.35 mill - modest growth in my book - in their defence they may have expected £0.1-£0.2 previously and are now expecting £0.35 which is better.
However to say you are having growth then say you are exceeding that previously announced growth and still only hitting 3% increase its kinda pimping up reality a bit.
It probably says it all that the only other numbers mentioned other than the useful sales figures are the following record breaking stats - if you have to quote irrelevant stats to look good you are probably better saying nowt IMHO.
In Q3, we saw a record demonstration to sales conversation ratio of approximately 56%, up by approximately 50% from pre COVID-19 levels.
Ref long term targets these have been pushed back 1 year (50 mill sales by 2026) - not ideal but as they have been hit for six this year by covid - only 1 year delay is probably exactly what we should be expecting - if they can do 27% growth compounded each year for the next 6 years they will have done a good job - are these targets to far in the future to be worth the paper they are written on though ?
Overall i think its as you were here - hoping for better times ahead.
Gear4music Holdings (LON:G4M) (no position)
Q2 YOY revenue growth was + 21%, down from+ 68% achieved in Q1.
That's quite a drop. With many people still at home I would have expected Q2 numbers to be more elevated.
I appreciate that today's commentary indicates momentum has continued into October, but I'm wondering whether this relates to the aforementioned 21%, or perhaps more tepid growth that is likely to have happened in September?
Fingers crossed for all holders.
A
Gear4music Holdings (LON:G4M) you need to look at operational gearing. What I worked out today is that pretty much every £ of revenue is 30p less tax, so 24p to the bottom line. Thus a small revenue increase is a large EPS increase, something like 6p for every £5m extra revenue. Thus if they "only" grow revenues +21% next year then this will equate to an extra £30m revenue or +36p in EPS ! ie more than double current and would put them on 75p+
What I don't know is whether admin costs have to jump to support that £30m. They have remained stable last couple of years so that would suggest not, but most businesses have a capacity constraint, we just don't know what it is.
Anyway the main point is not to focus on revenue growth - watch the bottom line with Gear4music Holdings (LON:G4M) as this could re-rate much faster than we assume.
Gear4music Holdings (LON:G4M)
Hi David
I couldn't agree with you more.
In fact, from first glance, the current valuation doesn't look too demanding and if I had funds I'd be more inclined to investigate further.
I merely wanted to highlight that revenue growth has dropped a lot in the last 6 months (68%-->21%) and it could be lower now than. At what point does it become "not worth it?"
For reference, I compare the growth of this company with something like West Wing or Hellofresh (both German and I own), both online-only players, where YOY revenue dropped from 97%-->81% and 123%-->120% respectively in the same period reported by Gear4music Holdings (LON:G4M) this morning(April-September 2020).
It's also worth pointing out that the company might be gaining from reduced level of returns (ie reduced shipping costs , processing, etc....) as per other online retailers, so margins might be temporarily inflated.
There are certainly opportunities out there, and Gear4music Holdings (LON:G4M) may well be one of them. I'm sure results day will provide more detailed insights
A
Gb (LON:GBG)
Very positive half year trading update from GBG this morning.
Revenue and profit ahead of expectations. Restoring the dividend.
I was most impressed by the reduction in debt for GB (LON:GBG) this really is a cash generating machine.
If he is reading this then many thanks to Robbie Burns for mentioning this share back in 2014. It piqued my interest so I researched and dived in. Multi-bagged since then and am happy to hold on, in spite of a high rating since this seems to be great technology, a fabulous client base and hopefully a big take over target for the future.
4d Pharma (LON:DDDD) shot up this morning. I hold from the low 90s. any thoughts?
4d Pharma (LON:DDDD) merger with Longevity Acquisition Corporation (NASDAQ: LOAC. On the stock report click on news for full info.
this merger seems to give 4d Pharma (LON:DDDD) access to about £14M in cash which it can use to continue research and clinical testing. Values 4d Pharma (LON:DDDD) at the level it has risen too today
As Lgarvey says, this will give them access to being traded on the NASDAQ and hopefully some crazy multiples to follow!
any news from Novacyt Sa (LON:NCYT) this morning ?
i can see the chart was a clear 'breakout' yesterday but am wondering if there are any news I couldn't find?
thanks all.
not seen any news today - yesterdays news caused an uplift but then a "pause" close to £10 (probably sells being triggered) - seems to have broken above £10 today.......
what were the news yesterday?
Hi Mort1980
I think this is just a continuation of the speculative chase the "Covid" share pushing the price up especially with all the continued "doom and gloom" from our media.
I agree with the £10 barrier, there will be a psychological for some on that, with automatic sell orders going through and some top skimming, I think the question is whether it holds above this at the end of today or not.
Noting that Open Orphan (LON:ORPH) has dropped the last two days so is now down >15% from the peak a couple of days back.
Tommy (I Hold)
i think the material stuff due is whether the contract with UK government DHSC phase 2 gets underway or not. If it Novacyt Sa (LON:NCYT) manage to get the phase 2 of their contract approved too, it'll be boom. It's going to be a massive cash.
Novacyt Sa (LON:NCYT) hesitated at £10 but once it got through it has now shot up to £11. All the other covid plays seem to be falling away (for instance, GDR) and I think the message is that the first company to get there takes the spoils (not just in Covid).
The FTSE100 fell sharply again this morning to 5716 before a recovery and Bp (LON:BP.) fell below 195p (I could not resist and bought a few). How can this have fallen so much this year? I mention this because some of the larger stocks are now getting so cheap compared to the small caps or so it seems to me. I wonder if private investors will start to switch?
Bitcoin is continuing its rally this morning after the news that Paypal will allow its customers to buy and sell some crypto currency. I cannot say I understand this market but I do hold Argo Blockchain (LON:ARB) which I think is the only listed UK company that "makes" bitcoins. This company has always been very lowly rated (unlike similar companies in the US) because it seems UK investors are highly dubious about this industry. I am but maybe all the banks will soon follow Paypal?
Hi Tommy,
I am happy to see that that Novacyt Sa (LON:NCYT) held above £11 mark. What's your opinion now if any?
Cheers.
Hi Mort
I am happy that I bought some, they have almost got me back to breakeven for this year :)
Though obviously wish I had bought a lot more!
My holding is ~8% of portfolio so still at a level I can sleep at night, so I think I will continue to hold, though the debate is whether to roll the dice and top up slightly, even if the gains are potentially reduced.
Tommy
Foreign currency brokers
Much as the SCVR is my usual breakfast staple, Tuesday's ended up bedtime reading and, rather than post back into that thread now, I thought to chip in on the question of foreign currency brokers, because Charles Schwab didn't come up in that thread.
I worked for a US firm for years and had the benefit of an employee trading account, so didn't particularly have to worry about fx, at least not until I ever wanted to convert to GBP, but since leaving, I realised I stood to be robbed by HL on any foreign currency trades.
I looked across the market and went for an International Account with Charles Schwab, which I've been very happy with. Minimum of $25k to open the account, but there are no trading fees, as is now typical in the US, and it's easy to fund using an online currency broker (I've used Currencies Direct) which save you a staggering amount vs your high street bank. I see also that some of the challenger banks are now getting in on fx transfers and may be worth a look too.
It's a pain that ISA holdings have to be GBP denominated, so you can't hold in that wrapper, but as a trading account for US stocks I'm very happy with it.
I'm also very happy with Schwab, although there is one limitation I find very irritating - the list of ETF's one can trade in as a British national is very limited. I have yet to find a way of playing the VIX for example. (They had a very useful webinar on the US election this week).
For overseas holdings within an ISA I use IG Index, which has very competitive FX rates and an excellent user interface. It also allows a chocie of DMA or marketmaker quotes for UK stocks.
They have access to US, Australia and a handful of European exchanges, unfortunately not including Switzerland or Scandi.
Excuse the naive question but how does a broker make money and pay their bills if trades are free?
I would guess they make their money on the spreads (although spreads are usually quite tight in the U.S.), plus there are likely cross-selling opportunities to managed and/or recommended funds and the like. I'm surprised it hasn't been attempted over here yet, but it seems that things are moving that way (Degiro etc). I would think (and hope) in a few years Hargreaves and Co. will have a difficult time charging £10+ a trade.
One UK broker has no fees Trading 212, no foreign exchange fees either. But does not cover some shares, most AIM ones for example.
"Excuse the naive question but how does a broker make money and pay their bills if trades are free?"
This Bloomberg article gives some thoughts on the US.
https://www.bloomberg.com/news/articles/2018-10-15/robinhood-gets-almost-half-its-revenue-in-controversial-bargain-with-high-speed-traders
Gear4music Holdings (LON:G4M) numbers look good with gross margins and revenues strong. One gripe is that it would be helpful if they didn't just report gross profits as the headline measure as it forces me to look back at last years finals to check how consistent admin costs are and that's a bit annoying. Even there they barely mention EPS as a measure of profitability, which I find bizarre! It's buried deep in the report.
However, with that grumpy early morning rant over I checked back and find admin costs and depreciation appear to be pretty stable YoY so I am now comfortable with 30p+ eps for the full year. Growth will likely stabilise after that I presume but I can see operational leverage kicking in further such that EPS growth of 20%+ p/a for next couple of years doesn't feel like much of a stretch target and that would bring us up to 45p odd, so I am targeting 900-1200p share price or a 20% compound annual return over 2 years.
Note: I calc that £5m of revenue growth now equates to around 6p of EPS assuming 20% tax rate and that admin costs and depreciation stay flat. So a 7% revenue growth next year should equate to £10m+ of revenue and a 12p eps change (40% eps growth). Thus I think there is a reasonable margin of error in my numbers. If anyone thinks I have this wrong please let me know as it impacts my investment case.
LON:G4m update from progressive reseach, https://www.progressive-resear...
Gear4music Holdings (LON:G4M)
not many businesses can grow revenues 7%+ with opex flatGear4music Holdings (LON:G4M) remember that they are growing at 50% with opex flat!
They do a poor job of illustrating this, you have to go back to y/e financials for past 2 years. What you can see is that they report gross revenues and margins as their key metrics. What I am interested in is what happens to the admin costs as these are £27m but obviously not included in gross margin. What we can see is that they have remained stable now for some time with very marginal increases.
Thus the point is that growing at 50% revenues is clearly not sustainable long term but the EPS will grow significantly. Even if they went from +50% growth to +20% revenue growth next year the EPS will jump to something like 75p by my calculations.
Another positive announcement from Water Intelligence (LON:WATR) this morning, having signed up a further national insurer for their services. The first of these national insurer contracts was signed in 2017 H1; this is now the fifth such arrangement and the second of 2020 H2, indicating that their investment in Salesforce workflow management technology is paying rapid dividends. Interestingly in that regard, the RNS also tells us: "in addition to the formal nationwide account structure, the Company is continuing to grow its base of insurance customers across the US at local levels". These local (usually state-level) insurers have significant market share in the USA, so this is an important market to capture, too.
The insurance business is lower margin than direct business but is, in my view, key to maintaining rapid growth and further strengthening their national stranglehold on leak detection.
(I hold).
Morning Paul, any thoughts on STB? Trading statement out today, I understand banks aren’t everyone’s favourite cup of tea but they seem to have come through Covid relatively well and business appears to be picking up. Share price has been walloped and looks like a nice way to play the recovery over the next few years.
My morning smallcap tweet: FUM firms up FDA approval path.
Toople (LON:TOOP) 4D Pharma (LON:DDDD) Water Intelligence (LON:WATR) Cloudcall (LON:CALL) £G4M Trifast (LON:TRI) SDI (LON:SDI) Futura Medical (LON:FUM) Genedrive (LON:GDR) IXICO (LON:IXI) Pendragon (LON:PDG) Quartix Holdings (LON:QTX) Countrywide (LON:CWD), Shearwater (LON:SWG), 1pm (LON:OPM)
Toople (TOOP) 3 year contract extension with its bakery client: more locations and more services, 'significantly increasing the value of the contract'. No £££ though. [SP=0.14 Cap=5m]
4D Pharma (DDDD) merger with US Longevity Acquisition Corp valuing 4D at 110p, an 18% premium. Will list as Nasdaq ADRs. 4D holders will own 87% of group. How can it value 4D at an 18% premium when it will comprise 87% of group? [SP=91.93 Cap=121m]
Water Intelligence (WATR) wins contract with another leading US insurance company for minimally-invasive water leak detection. No £££. [SP=475 Cap=70m]
Cloudcall (CALL) Capital Markets Day trading update: guides FY(Dec) rev £11.5-12m, ahead of expectations. [SP=92.5 Cap=36m]
Gear4music (G4M) guides FY(Mar) market expectations after H1 rev up 42% to £70.2m, gross profit up 60%. [SP=692 Cap=145m]
Trifast (TRI) H1 trading has continued to be slightly ahead of mgmt base case assumptions. [SP=120 Cap=163m]
SDI (SDI) guides FY(Apr) rev and pretax broadly at pre-covid budget and so above market expectations."Board stresses that the incremental sales at Atik and MPB are the result of one-time contracts related to the COVID-19 pandemic and expects them to be completed well within the current financial year. Consequently, the Board's view on the Group's 2022 financial year is unchanged." [SP=66 Cap=65m]
Futura Medical (FUM) further trial with 100 patients agreed with FDA for erectile dysfunction gel. Q1 2021 enrolment. Also continues to target a 2021 European approval. [SP=13.5 Cap=33m]
Genedrive (GDR) has completed assay design for 20 minute covid test and "is now generating very promising analytical data aligned to market requirements." Target of final Q1 2021 for CE Marked system, allowing for thorough clinical testing requirements. Volume production would need a new version with a freeze-dried PCR bead format . [SP=113.2 Cap=64m]
IXICO (IXI) wins new contracts in Huntington's disease clinical trials. Much smaller than the £10.5m contract announced in April. [SP=97 Cap=46m]
Pendragon (PDG) Q3 LFL rev down 1%, U/L pretax up 810% to £27.3m. Remains cautious on Q4 so no FY guidance. [SP=10.6 Cap=148m]
Quartix (QTX) guides FY rev and FCF in line but adj EBITDA 15% ahead of consensus. Gives consensus as rev: £25.8m; adj EBITDA £6.9m; FCF: £5.2m. [SP=322.44 Cap=155m]
Countrywide (CWD) £90m rescue placing and OO at 135p, a 27% discount. Also Alchemy to invest up to £90m at 180p via a placing and funding a Tender Offer. A bit odd. Alchemy will end up with 50-68%. LSE listing will downgrade to standard from premium. [SP=183.9 Cap=60m]
In line: Shearwater (LON:SWG) 1pm (LON:OPM)
Great results in the half year trading update from £G4M Gear 4 Music this morning with gross profit up 60% compared to last year and full year results expected to be ahead of previous consensus market expectations.
So, as a share holder am I happy? Yes and no.
Yes, because clearly this is all going very well in the near term and that should be reflected in the share price.
No, because only last week they massively reduced the hurdle rates for their senior management LTIP to make the targets to be achieved 40 - 50% lower in order for it to pay out.
Clearly Covid has given online businesses that supply hobby products to people stuck at home a tremendous uplift and G4M just happen to be in the right place to benefit from that. So, no management brilliance involved there. The low share price prior to that was because of management failings when profits collapsed. A situation they have been turning around but of their own making.
From time to time any incentive plan is going to need adjusting. However, I feel in this situation it would have been far more honest, more deserving and less greedy to have decided the changes to the LTIP after the trading update when the new targets could be revised to reflect the increase in share price that these results will likely bring. The new targets are probably too low. I wouldn’t be surprised if the share price is already at the target for 2021 by the end of today.
Yes, I certainly agree Graham that they've put out a great update this morning. Soaring revenues coupled with equally impressive margin increases is a nice combination.
I do think you're being a bit harsh over the adjustment of targets for the share payments. Yes, they've been marked down significantly, but to be honest the previous share price targets were crazy. The management have always been very positive about the future scale of the business but to pitch the targets so high was very surprising. If they're genuinely going to provide an incentive to key staff then they need a degree of realism and I think they're about right now. I certainly wouldn't call the management team greedy, but I'd definitely say they are very deserving of sharing in the success of the company.
Maybe I am being too harsh about G4M. But I certainly didn’t say that they didn’t deserve a share in the success of the company. What I am arguing for is that (a) they should have waited until the uplift in share price from the trading update could be factored in and that (b) if this really is to be an incentive then the targets have to be a significant increase on that new share price.
So far, I am surprised the share price hasn’t reacted more strongly.
Surely the targets should relate to the share price when the incentive scheme was introduced, unless the plan is to push any potential share awards further out. I'm not sure that would go down well with the management team.
Yes, I was expecting a more positive reaction from the market this morning.
Maybe a buying opportunity? - I've certainly added this morning as was expecting a stronger reaction, and I'm sure it'll come. Especially when everyone realises we going into Christmas period, management have already said its the busiest time of the year, I can see plenty of upside, especially at the increased margins.
As a holder have you found liquidity/spreads an issue? I was looking at quotes on HL and was surprised with the spread.
It's worth looking at Gear4music Holdings (LON:G4M) broker update this morning which is free to access. They have upped their FY21 EPS target to 30.3p. However, their predictions suggest only a 5% YoY revenue growth in H2 which to me sounds far too low given the likelihood that a lot of European populations are going to be stuck in their homes for a large length of time once again and so may turn to hobbies. Plus Q2 (Jul-Sep when the most severe restrictions were lifted) was still 21% revenue growth. So I would still expect a further upgrade from 30.3p.
The big question of course is what happens next year and the year after - plus H1 comparatives in the next financial year are not going to look great. But I think the share price has a bit more room to grow yet.
Multibaggers with 10 Bagger Potential - Gear4Music Holdings
https://www.stockopedia.com/co...
Valuation looks good for 1100p FY2021
BSV
Just like to say BSV, that whilst you get a lot of downvotes round here, your multibagger blog turned me on to Creightons, which have added to the protfolio (albeit a starter stake).
Cheers.
It's good to see the blog is appreciated.
DYOR and good luck with your investments/trades.
BSV.
Today's piworld webinar is with Andy Brough, Head of the UK & European Small & Mid Cap team at Schroders, and Richard Leonard, who runs a family office. They'll be discussing markets and opportunities. With so much we want to get through, I'm concerned we're going to run out of time! In any event, it will be insightful, amusing and it may even give you some ideas. We're broadcasting live from Schroders at 1pm today, 22.10.20. To join us, register here.
Hi Tamzin, Sorry to miss the webinar today but thoroughly enjoy many of the other videos on PIWorld, will todays webinar be uploaded there also?
Yes, the video and podcast of today's webinar with Andy Brough and Richard Leonard will be published on piworld tomorrow. I'll post a link here. It's a goodie.
Hi Tazmin, it was a very enjoyable interview on PIWorld today. Andy & Richard bounce off each other with ease. I thoroughly enjoyed watching it. The interview could easily have gone on for an other hour. Maybe you could arrange another joint interview sometime in the future. I am looking forward to Richard Leonard's interview regarding £NYCT (I hold) next week if all goes to plan.
Great, thanks
Morning Paul,
Would like your view on the very brief Sdi (LON:SDI) trading update if you have time.
I find it quite frustrating that here "The Board stresses that the incremental sales at Atik and MPB are the result of one-time contracts related to the COVID-19 pandemic and expects them to be completed well within the current financial year. Consequently, the Board's view on the Group's 2022 financial year is unchanged.".... They fail to mention what the board's view of 2022 FY is!
Thanks
Although the market doesn't seem to mind!
Previously when asked about this they've pointed to the broker forecasts.
Morning Paul, be interested in our thoughts on Xps Pensions (LON:XPS) - seems to me to be a reasonably bullet proof business as it deals in pension s consulting.
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.
Thanks for these early morning summaries - they are very useful. However, your script missed the best part for Alumasc (LON:ALU) (I hold):
"Alumasc has begun the new financial year to 30 June 2021 strongly with record profits in the first quarter.
Each of our three divisions - Building Envelope, Water Management and Housebuilding Products - has contributed to this record performance. The restructuring over the previous year, which provided £2.4m in annual cost saving, undoubtedly benefitted margins, which were well ahead in the period, helping in particular Levolux and Gatic.
This profit performance has been accompanied by equally strong cash generation, reducing net bank borrowing of £4.3 million at 30 June 2020 to below £1 million at today's date, against total facilities of £24 million."