Small Cap Value Report (Thu 22 Sept 2022) - BEG, SNWS, AQX, MORE, JDG, PBEE, VLG

Good morning from Paul & Graham! Today's report is now finished.
An energy support package for business was announced yesterday, which I've yet to go through in detail. The crux of it seems to be substantial reductions in gas & electricity prices for businesses, coming directly off their bills, for 6 months from 1 Oct 2022. That's clearly going to help. There's also talk of Stamp Duty, and other tax reductions in the pipeline. No doubt we'll get more detail in due course, and I'll keep my eyes peeled for what companies start saying about these changes in their forthcoming outlook comments.
Agenda -
We're looking at today's newsfeed, but also want to cover (today or tomorrow) 2 backlog items in particular:
Warpaint London (LON:W7L) - we've run out of time today, so this will have to be tomorrow.
Hostmore (LON:MORE) - oh dear, things are starting to look grim, I'm afraid. FY 12/2022 is now expected to be a (small) loss. Forecasts for a bounce in 2023 just don't look realistic to me, so I'm worried trading could deteriorate further, and the current -14% vs pre-pandemic revenue trend is worryingly weak. I'm now concerned about the high bank debt. Risk now looks high. Profuse apologies for how badly this has turned out, but the fundamentals have dramatically deteriorated this year.
Today's news -
Paul's Section:
Begbies Traynor (LON:BEG) - puts out an in line with expectations update for Q1 of FY 4/2023. Some interesting additional detail is provided. With earnings likely to be buoyant due to increasing insolvencies/restructurings, and a PER of 14, this share continues to look a sensible place to hide.
Smiths News (LON:SNWS) - a surprisingly good update for FY 8/2022 - ahead of market expectations. Stunningly low valuation now, with the PER below 3, and the dividend yield of about 15%. It won't last forever probably, but the valuation currently looks compelling for value investors. I'm tempted to buy.
Aquis Exchange (LON:AQX) - interim figures from this junior stock exchange fail to impress. Although it does have a nice balance sheet, with plenty of cash. There could perhaps be strategic value in the business? Based on these numbers, I can't get anywhere close to the current market cap though. So I'm afraid it has to be a thumbs down from me, on valuation concerns.
Graham's Section:
Judges Scientific (LON:JDG) (£496m) - good interim results and the full year is set to be “significantly” ahead of expectations. The broker raises its EPS forecast for the year by 15%, but only raises next year’s forecast by 5%. This is due to the lumpy nature of revenues at Geotek, the company purchased by Judges earlier this year which focuses on the analysis of geological cores. Geotek’s services are provided through a relatively small number of large contracts, making it difficult to predict revenues from year to year. Overall, Judges appears to be trading well in these conditions albeit with limited growth in order intake.
Pensionbee (LON:PBEE) (£168m) - this online pension provider reports its latest interim results. There is a cash burn of £14m, leaving its cash balance at £29m. While the top-line growth figures are growing at a solid rate, I’m not sure they are enough to justify this market cap given the lack of profitability and the likelihood that meaningful profits are likely to be several years away. The valuation is around ten times annualised revenues. I give some comparisons with Nutmeg, which is also still unprofitable despite having both more assets and a higher amount of assets per customer. If Nutmeg can’t make money despite those advantages, then how is Pension Bee going to make money?
Venture Life (LON:VLG) (£27m) (-2%) (no section below) - this provider of consumer self-care products, owning brands such as Dentyl and Ultra Dex, also publishes its interim results. Trading is in line with expectations and total revenues are up strongly (+36%) to £18.9m, helped by acquisitions. The company is profitable (adjusted EBITDA £3.3m) although statutory operating profit is very modest at just £0.4m. The company highlights strong organic growth at the acquired business, but the underlying revenue growth is actually very modest at just 1.7%. This looks disappointing when you consider the inflationary environment which has seen the prices of so many consumer goods soar. The company says it has been “passing on price increases where possible”. The balance sheet is ok with net debt of £3.1 million and plenty of headroom available on a £30m RCF, which might be used for further acquisitions in the near future. I maintain my view that while VLG shares are superficially cheap against the profitability that its brand portfolio should be able to achieve, the lack of organic growth is a good reason for the shares to remain cheap. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Begbies Traynor (LON:BEG)
141p (last night’s close)
Market cap £217m
Shares in this insolvency practitioner (and associated services) have been strong this year, along with sector peer Frp Advisory (LON:FRP) - fairly obviously, they are benefiting from increasing corporate distress. Administrations and liquidations are highly complex, and high margin work, so when the economy deteriorates, they tend to do well.
My summary of today’s update -
FY 4/2022 was good, and ahead of original expectations (good trading, and acquisitions).
Strong track record - since 2018 business has more than doubled in size & profits. EPS up from 4.0p to 9.1p, and moved from net debt to net cash.
Good start made to FY 4/2023 in line with expectations.
Increasing number of larger (mid market) insolvency/restructuring cases emerging.
Guidance - is good, and a helpful footnote is provided. This is equivalent to approximately 10p EPS -
At this early stage of the financial year, we therefore remain confident of delivering market expectations* for the full year.
* current range of analyst forecasts for adjusted PBT of £19.7m-£20.6m (as compiled by the group)
My opinion - I’ve followed BEG for years, and think it’s a decent business, which seems to have successfully expanded through acquisitions, which have added value. Profits have gone up faster than new share issuance, which is what we want to see from acquisitive groups.
Current year forecasts are for about 10p, so the PER is about 14, which looks sensible to me. Given the horrible macro picture, it’s stating the obvious that insolvency practitioners are likely to be busy for several years (as cases can drag on for a long time, the more complex they are).
Hence this share continues to look a safe place to weather the storm.
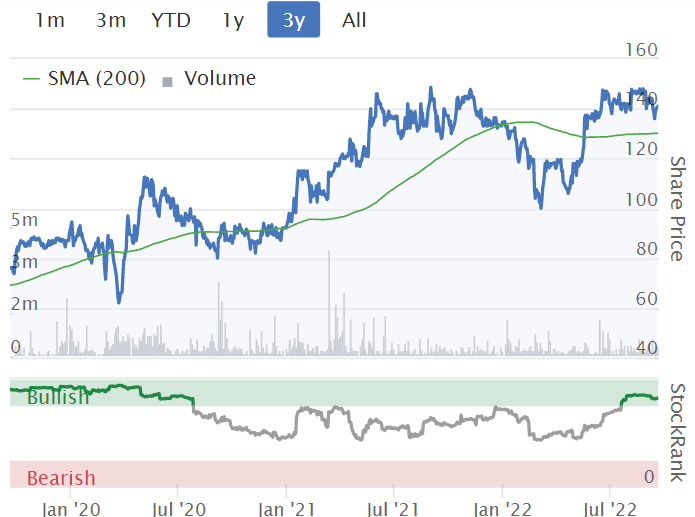
Note below a strong share price, and high StockRank -
.
Smiths News (LON:SNWS)
27.7p (last nights close)
Market cap £66m
We’ve extensively reported on the turnaround at this newspaper/magazine distributor over the last few years. It’s now financially stable, with debt reduced, and paying big divis.
The extremely low PER reflects the reality that it’s in long-term, structural decline, although this is being impressively managed.
It’s a perhaps surprisingly positive update today, for FY 8/2022 -
Smiths News is pleased to report a good trading performance in the second half of FY2022 (H2), supported by a positive sales mix and focused operational control. The Board expects Adjusted EBITDA (ex. IFRS-16 leases) for the 52 week period ended 27 August 2022 to be not less than £40m, ahead of market expectations.
I reckon that translates into EPS of something between 10-12p, depending on which basis you use. So at 28p per share, the PER looks astonishingly low, below 3! Surely that’s too extreme?
Cost pressures have been well managed, and are as expected, demonstrating impressive management & budgeting.
Bad debt from McColls sounds like it might be a bit less than the £4.4m provision.
Dividends - this is what it’s all about. At least 2.7p final divi expected, with a 1.4p interim divi already paid in July 2022. That’s 4.1p (maybe more), so a yield of an amazing 14.8%!
Divis are restricted by an agreement with the bank to gradually de-gear.
Note the pension issues were wrapped up a while ago, so no issues there any more.
Outlook - nothing much said, but this bit does reassure -
We remain focused on providing excellent service to our retailers and publishers and expect to continue to deliver consistent financial performance and shareholder returns.
My opinion - for now anyway, SNWS is a consistent cash cow. It probably won’t last forever, as the business slowly declines, which is why the stock market isn’t interested.
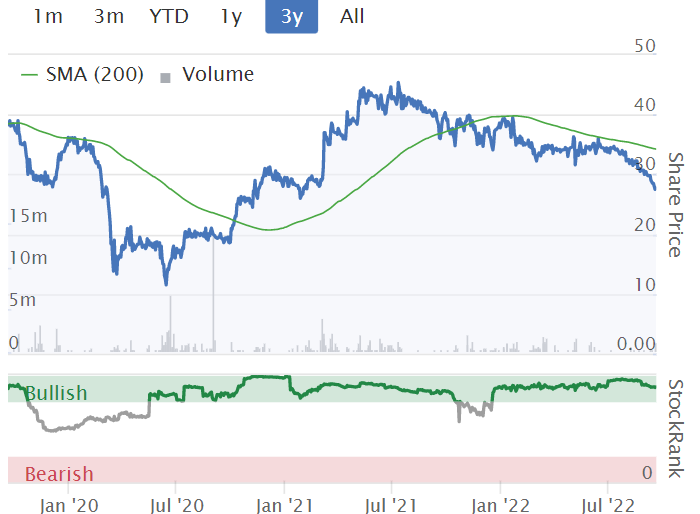
At the current bombed out level of about 28p, this share does look compelling value to me. It’s very tempting.
.
Aquis Exchange (LON:AQX)
385p (down c.4% at 08:45)
Market cap £105m
Aquis is a junior stock exchange, below AIM. Its own shares are quoted on AIM.
Readers flagged up this share a while back. I did look at the previous accounts, but couldn’t really make much sense of them. In particular, it wasn’t clear where previous profits had come from, and there were also some unusual balance sheet items.
So I was keen to look at it afresh this morning.
Here are my notes on its H1 results -
Revenues for H1 of £8.3m, up 21%
Profit before tax (PBT) £0.7m, but that’s mainly come from releasing a £425k provision, so excluding that one-off, it’s only made £275k profit - negligible.
Claims market share of 5.2% of European share trading - seems a lot, and it’s not generating much revenue from that seemingly large market share.
42 “members” - I’m not sure if that is companies listed on Aquis, or whether it’s brokers that use the platform?
Balance sheet - is pretty good, with NTAV of about £19m, and a healthy cash pile of £13.3m. One odd item is £4.7m receivables in non-current assets, which is an unusual place to find receivables, so I would need to know what this is (not explained in the notes). Also previous impairments of receivables worries me - suggesting that some revenues may not be good quality maybe?
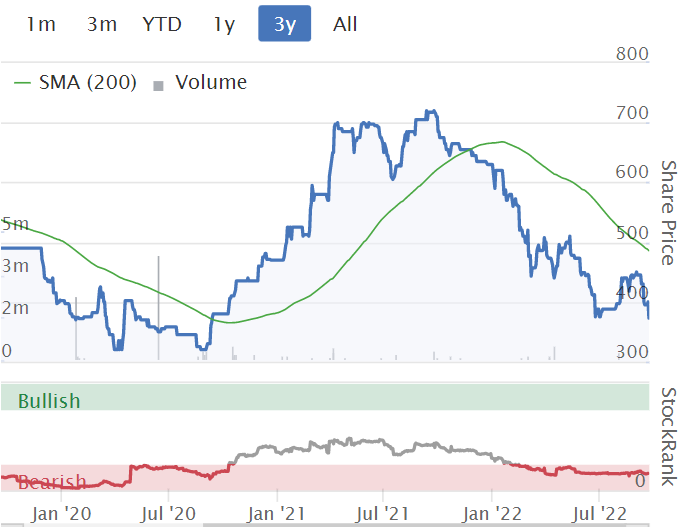
My opinion - judging from the figures, I would struggle to value this at much more than its own cash pile. Maybe £20-30m market cap might seem reasonable? Hence the £105m actual market cap looks to be including a lot of hope about future growth, or some potential strategic value in the business?
My problem with that, is that in previous incarnations, e.g Plus Markets, OFEX, etc, junior exchanges have never worked commercially, and ended up having little to no value.
Aquis looks somewhat better, and I’ve watched the enthusiastic webinars from the current boss, explaining his different charging model based on subscriptions, rather than transactional charges.
It’s looks a more viable business than in the past, but is not something I would pay anywhere near £105m market cap for, based on today’s numbers.
.
Hostmore (LON:MORE)
18p (down 6% today, at 09:22)
Market cap £23m
Hostmore plc ("Hostmore" or the "Company" and, together with its subsidiaries, the "Group"), the hospitality business with brands including 'Fridays', '63rd+1st' and 'Fridays and Go', is pleased to announce its interim results for the 26 weeks ended 3 July 2022 ("HY22").
H1 revenues £98.5m
Like-for-like (LFL) revenues down 7% vs pre-pandemic - not good.
EBITDA £7.1m (pre-IFRS 16) - the post-IFRS 16 EBITDA figure of £17.8m is best ignored, as it’s a fantasy number.
Loss before tax in H1 of £(17.0), due to £17.8m impairment charge. So it’s effectively a whisker above breakeven in H1, on an underlying basis.
Outlook - H2 so far, LFLs have deteriorated to -14% vs 2019 - clearly not good at all, so the consumer retrenchment is hitting MORE hard. They are hoping this will improve to -11% for H2 as a whole.
Some cost savings have been made.
Inflation - energy is hedged for this year, but hedges reduce next year. Expecting to take £5.8m additional energy costs in FY 12/2023, although this might reduce due to recent Govt price caps - unclear if this has been taken into account? Limited increases in food & drink costs.
Forecasts - thanks to Finncap for updating its model. FY 12/2022 is now expected to be a £(2.3)m loss at the adj PBT level. This is expected to improve in FY 12/2023 to £(0.4)m. I’ve got to say though, the 2023 forecast looks way too optimistic to me. If we assume flat revenues for 2023 vs 2022, then the company would be substantially loss-making, maybe as much as £(10)m, because of the operational gearing (high gross margin, and largely fixed costs).
So the downside scenario would probably trigger breach of bank covenants, and hence an equity fundraising or sale of the business would probably become inevitable. If that went badly, it could leave existing shareholders with little to nothing.
For this reason, unfortunately, I think this share has now become high risk.
Net bank debt was £26.2m at end June 2022, since reduced to £23.7m in last weeks, but the quarterly peaks are higher, with the next one expected to peak at £32.5m on 2 October, after rents and VAT are paid.
There are ample facilities available, but the bank is likely to want to reduce its exposure, as conditions deteriorate.
Going concern - this sounds surprisingly upbeat, but doesn't disclose what assumptions were made in the modelling. Nevertheless, the company reckons it can remain in compliance with the banking covenants. If that's correct, then the risk might not be as high as I fear -
Both scenarios, being the Group business plan and the severe but plausible downside, show that there will be no breach of the Group's covenant tests and that the Group has headroom above the minimum covenant levels.
Balance sheet - NAV is £111m, but we can deduct £146m of goodwill, resulting in NTAV negative at £(35)m. Although the main cause of this negative position is a yawning deficit of £46m on the lease entries: RoU Assets of £104m, less liabilities of £150m. If we eliminate lease entries, then the balance sheet NTAV would turn positive to £11m.
Overall, it’s not a disastrous balance sheet, but it’s very clear that bank debt is now too high, for what is probably now a loss-making business. Banks don’t like lending to loss-making companies.
The lease entries are also telling us that there are now some problem sites, generating losses. Hence why the £17.8m impairment charge was also necessary.
My opinion - I’m trying to keep the emotions out of this, and just look at the figures.
Trading has significantly deteriorated, and we now have a loss-making business, with too much bank debt.
So the dilution risk now looks high, and if trading gets worse, we could even have to consider insolvency risk.
Obviously this share has been a disaster, and I’m so sorry for anyone who followed me into this & has also experienced heavy losses. Things looked completely different a year ago, with it performing well, and having seemingly good expansion prospects, and consumers spending freely. I think expansion now looks completely off the table, and it needs to focus on survival, as consumers clearly don’t find its menu to be value for money, whatever management seem to think.
I’m not tempted to buy, despite the bombed out share price, because the risk now looks too high for me. Although if it manages to scrape through this downturn without dilution, and performance improves, then of course it could be a multibagger. We’ll just have to see what happens.
.
Graham’s Section:
Judges Scientific (LON:JDG)
Share price: £78 (+2%)
Market cap: £496m
Interim results are out from this buy-and-build operator in the scientific instruments sector.
The current year is shaping up to be significantly ahead of market expectations (so the mere 2% rise in the share price is puzzling).
Key points:
- Revenue +8% to £46.4m. Organic revenues +7%.
- Adjusted PBT +13.4% to £9.6m
- Actual PBT (without adjustments) minus 42.3% to £3.9m
We already had a clue about some of these results from the H1 trading update.
Adjusting items: the major adjusting items are amortisation of acquired intangible assets and acquisition costs. I would cautiously allow the acquisition costs to be adjusted out, but as usual I would be cautious about the amortisation adjustment.
If I only add back the acquisition costs, I get an adjusted PBT of about £7m.
Balance sheet & cash flow: net debt rises to £54.9m, following the £80m acquisition made earlier this year.
However, Judges appears to be happy with the progress at Geotek, a company specialising in geological analysis, and expresses this with an increase of the interim dividend (from 19p to 22p).
Cash generated from operations during H1 was stable, at £8.2m. Note that this isn’t too far off the adjusted PBT figure of £7m that I came up with.
Outlook: as we already knew, the different geographies in which Judges operates are offering different challenges. The prior trading update disclosed that order intake was down in both China/Hong Kong and the UK.
However, it appears that Geotek is driving the positivity. “The Board now expects that the full earn-out will be payable”, i.e. Geotek has performed at the upper end of the parameters that were agreed between Judges and Geotek’s sellers.
This means that Geotek is expected to earn an adjusted EBIT of at least £11.4m in the 2022 calendar year (perhaps more). The result is that an additional £35m will be payable to Geotek’s sellers, half in cash and half in shares.
For Judges, “the Board now expects that the Group will be significantly ahead of market expectations for the current year”.
Forecasts: Liberum have today raised their 2022 EPS forecast from 292.5p to 335.6p (up by 15%).
However, they have only raised their 2023 EPS forecast from 348.4p to 365p, on the grounds that “while Geotek’s revenues are not particularly cyclical, they can be lumpy”. They have therefore assumed a modest reduction in Geotek’s profitability next year, admitting that this “may well prove too cautious”.
I observed previously that Geotek, according to Judges, had a “reliance on a small number of large contracts”. This implies a lower quality of earnings, but the uncertainty around these contracts can result in positive or negative surprises. I’m glad to see a broker taking a cautious approach - this is all too rare.
As the 2023 EPS forecast is only raised by 5%, that might help to explain why the JDG share price hasn’t moved far today. But if Geotek’s momentum does carry through to next year, I imagine there should be significant upside for JDG shareholders from the current level!
Business performance
Let’s remind ourselves of some of the key points around JDG’s performance within the scientific instruments sector.
- Supply chain issues continue to dog the company, “probably aggravated by the Chinese lockdowns and the war in Ukraine”.
- The return of international travel has helped, but organic order intake was still “only” up by 4%. In other words of Judges, “this cannot be considered a full recovery to the pre-Covid growth trajectory”.
- China/Hong Kong/UK/Europe all lower or flat. Growth in North America and the Rest of the World.
Return on capital is strong, but unfortunately will be reduced by Geotek:
Organic Return on Total Invested Capital ("ROTIC") recovered to 29.6% for the trailing 12 months ended 30 June 2022 (30 June 2021: 25.0%). However, once Geotek is included, a sharp reduction of ROTIC must be expected.
My view
I will link you again back to my analysis of the H1 trading update, as I explained my views on JDG in some detail there.
The only difference now is that we can have more confidence in the success of Geotek and (hopefully) in the ability of JDG to carry out bigger acquisitions. This comes with the proviso that Geotek’s senior management - the sellers of the company - were very heavily incentivised to ensure that 2022 had a favourable outturn. As noted by Liberum, we can’t assume that 2023 is going to continue in the same positive direction.
Overall, however, there is no doubt that JDG is performing well in difficult circumstances. As I said in July, my view is that JDG shares are a nice long-term hold but if I was timing a purchase, I don’t see the current valuation as particularly attractive.
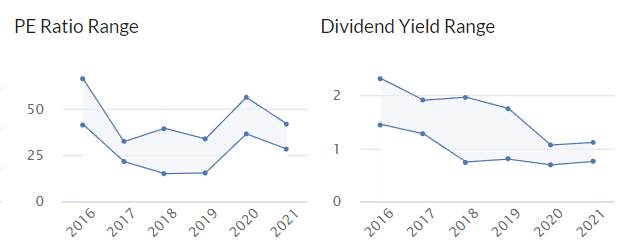
As the Stockopedia graphics demonstrate, it has been possible to buy JDG at lower PE ratios and at higher dividend yields. Maybe we will get buying opportunities like that again, some day?
Pensionbee (LON:PBEE)
Share price: 75.5p (-1%)
Market cap: £168m
This pension fintech releases interim results.
We’ve only checked it one time before: at July’s trading update.
It joined the market in a 2021 IPO, priced at 160p.
My main concern has been valuation: I can understand the rationale to pay a multiple of several times annualised recurring revenues for a growing, subscription-based business that has yet to reach bottom-line profitability.
But I struggle when faced with a price to sales multiple of 10x (or even 20x, as often occurred during the bull market).
When the price to sales multiple is so large that it starts to resemble a price to earnings ratio, for a company that isn’t profitable, I get very worried.
PensionBee announces that H1 revenues are up 53% to £8.3m, and that annualised run rate revenue is up 37% to £16.8m. Assets under administration are now some £2.7 billion.
Unfortunately, the market cap is still at a multiple of 10x ARR, even after the share price has collapsed since IPO and the company’s ARR has made decent gains.
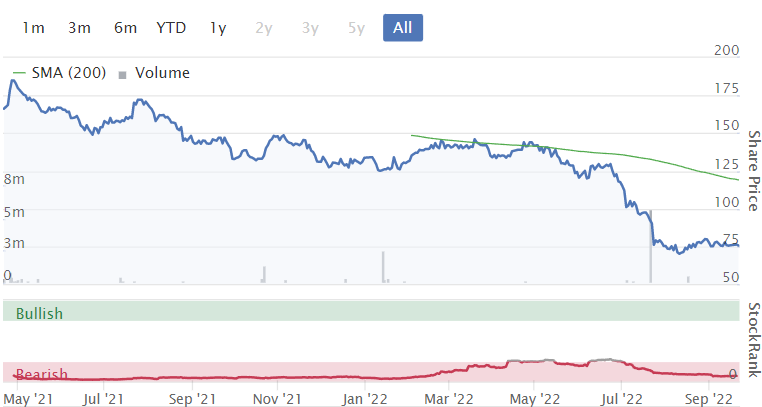
Call it what you want, but I refuse to believe that an unprofitable company trading at 10x ARR can be a “value” share (although judging by my experience on Seeking Alpha recently, many Americans would disagree!).
PensionBee’s H1 pre-tax loss was £16.9m, worse than last year. It was unprofitable even at the adjusted EBITDA level, and worse than last year.
More positively, the company reports a score of 4.6 on Trustpilot (see for yourself here) and a customer retention rate of over 95%. Customer satisfaction is of course critical for any startup.
CEO comment:
Our approach has remained focused and consistent with our plan and ambitions to scale our business while achieving our near term profitability objectives. Our robust cash position means we are well-positioned to continue growing our market share, expecting to achieve high double-digit Revenue growth in the short-term and monthly Adjusted EBITDA profitability by the end of 2023.
PensionBee already has a quarter of a million active customers. I wonder what are the limits it might run into, as it expands market share?
We could compare it to Nutmeg, now owned by JP Morgan. According to Citywire, Nutmeg posted a £19m loss in 2021. Nutmeg has never made a profit despite the number of clients reaching some 170,000 and its asset base hitting £4.6 billion (£27,000 per client).
PensionBee has 246,000 “active customers” and 159,000 “invested customers” (shouldn’t those numbers be the same?). Yet it has just £2.7 billion in assets. That means assets per invested customer for PensionBee is just £17,000, much lower than Nutmeg.
The margin earned on assets is 0.69%, i.e. PensionBee earns £117 per customer per year, on average.
That’s less than half of the amount it spends to recruit a customer in advertising and marketing costs, so there is a considerable payback period just to get those costs covered.
My view
Like many financial companies, this needs serious scale to work properly for shareholders, in my opinion. In mountaineering terms, it is still at Base Camp and I fear that it has a long road ahead, to reach the scale that is needed.
It is working towards “monthly profitability breakeven by the end of 2023”, which would be a great achievement, even if profitability is being measured by adjusted EBITDA. Positive net income could be further away and if the experience of Nutmeg is relevant, it could be several years away.
There’s no doubt in my mind that this share is highly speculative - if I had to invest in it, I would want to do so in a bombed-out placing when the company needs to raise money. With the cash balance having reduced to £29m after a £14m cash burn in six months, I think it’s a distinct possibility that fresh funds will be needed here at some point.
What I wouldn’t want to do is pay full price, e.g. 10x ARR, which is the valuation given by the current market cap (admittedly, you could reduce this a bit if you deduct the cash balance from the market cap, but I’m not sure how much longer the cash is going to be there).
In summary, I think the algorithm is correct to identify this as a Sucker Stock: it might offer a fantastic customer experience, and it might turn out to be a highly successful business in the fullness of time, but these shares today offer poor statistical odds.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
Time Finance (LON:TIME)
I would be interested in hearing thoughts on Time Finance's announcements today.
My own opinion is that the company looks far too cheap and I can't really understand why.
This should hold off competition from the current rapid rise of automated, algorythm-driven lenders.
I would not be surprised if FY profits are at least £3m vs a market cap of c£16m.
I don't have a position though I'd probably be more tempted to take one if there was a dividend to justify the opportunity cost of putting my money here.
Is this just one of those shares that remains unjustifiably low?
Thoughts would be appreciated.
A
I think my general comment would be in the current macro environment I am just not interested in fishing in £15m mkt cap companies which are pretty illiquid. There are enough uncertainties in this world without taking on that level of risk. Although I do agree on a here and now it looks interesting. Let's see in 3 years time.
Unless I missed it, no-one covered the results from Strix (LON:KETL) yesterday. I don't hold at present but their patent moat seems a valuable asset and they are passing on some cost increases. The good dividend is maintained and well covered.
Any views?
There were a couple of reader comments on Strix (LON:KETL) yesterday which may be worth checking. Personally struggle to see how much of a moat they really have and never been a huge fan - there are plenty of other producers of kettle safety devices.
Paul Quiz (LON:QUIZ) director buys small amounts in £s but ex JD sports and Mulberry CFO do experience retailers. Ex JD man does have £6million coming his way got to spend it on something. Cash end July was 8.7million sales to 3 months July were up 62% to 27million so 108£ for year possible.
Hargreaces Services (HSP) .
I hold and this is a real value play based on having three divisions, there are three divisions -
- Industrial services which works on HSE and does ok
- German trading , very profitable but I think hard to value and bamboozles the market
- Renewables one their land bank - which I have never looking into more detail than knowing they had a lot of land .
Just done some research into this and ran the numbers past a windfarm developer I am working with on some land I own.
Hargreaves have I quote "options over land with wind farm development needed to produce 580MW of power on various long term agreements with are expected to begin delivering value in the next 24 months . This represents more than 2% of the UK total installed wind power capacity in 2021. This is a particularly exciting area of Hargreaves land and represents an opportunity to increase substantial value to the group.
Hargreaves land acts solely as landlord and does not undertake any construction work or ownership of the energy generating assets " .
So the question is what value do we place on the projects due to start delivering in the next 24 months in terms of yearly rental income to the group ?
Well fag packet based on 93 turbines at circa 6.2MW turbines each producing 18,000 MWH per year at an average power price of £50 per MWH gives a yearly income of £84 million !!
The market seems completely and totally unaware of this calculation and this is for projects already a long way down the development path, and remember Hargreaves also keep the land and can grow forestry under / around the turbines.
Total no brainer at these numbers with market cap at circa 135 million .
Im buying on weakness, and going to move this up to a full position and follow where the wind blows in the market.
DYOR of course but those are the numbers we get for the wind farm "various long term projects"
I agree with your assessment
I think there may be an error in your assumptions. If Hargreaves owns the land, but not the turbines, then the income of £84m would not be received by Hargreaves, but would be received by the owner of the turbines. Hargreaves would only receive a small fraction of this £84m for allowing the turbines to be on its land. Do we know what the actual rental income is to Hargreaves?
Hargreaves Services (LON:HSP) results presentation (27th July) used an illustrative 1% for their share of income on wind farms. The conservative example given was 50MW installed capacity producing a rental of £59kpa for 28 years, i.e. 93 x 6.2MW converts to c. £680kpa.
Quite a difference between the 2 calculations, but I think your £680k looks more reasonable! I would imagine most of the £84m figure noted in the original post would be to cover the operating costs of running the turbines, and most of any profit would go to the operators rather than Hargreaves.
Let me check .
For sure the landowner received circa 7% of yearly income that is a fact , with absolutely no cost and the Developper pays everything .(I’ve seen 5% and 10%) and of course if energy levels are higher it’s much more .
7% of 84 million is circa 6 million
I’ll check the yearly income numbers for sure .
To give sone context I own sone forestry in Scotland (200 hectares ) and have 3 wind farm developers offering 7% , with zero costs my side . 8 turbines was estimated to give 600k a year clear income . There’s an adjoining property with de elopement just getting approved .
5 years to get turbines through planning so land value with s yearly income of 600k , we’ll do the numbers .
The numbers are quite frankly scary , 1 million for national grid connection (Developper) , 35 million per turbine to build , (Developper) , 500k per year to local community (Developper) , 1 million pound per year to national grid (developer ) , 7^ to landowners (Developper) .
Landowner does nothing and pays nothing with zero risk .
This is why Gresham forestry fund , Hargreaves are two big opportunities .
In my case unfortunately the wind isn’t quite hitting the required wind speed so it’s not looking economical to build so I have to content myself with knowing that “money grows on trees” albeit very slowly .
So trust me the numbers are well into the millions and the income is very significant .
Anyway let me let more facts otherwise I look a right muppet as 7% of 84 million is not 84 million
Kermit
Ps - one thing that did concern me was when speaking my contact he did comment that “Hargreaves are a nightmare and do all their wind farms through a connected company “
Given the market rate for landowner is 5-7% and Hargreaves according to above poster quoted 1% that is quite alarming .
I will ask them directjy as they need to represent shareholders and achieve best market rate for their wind farm potential - that goes without saying .
Right
Made a bit of a fool of myself (nothing changes”
The yearly income to the landowner (with zero other costs ) is
“Will be no more than 7%”
And
“Not less than 5%”
So that is day 6% of 84 million call it 6 million per year on EXISTING developments expected to complete in next 24 months .
If it’s much less than this and anywhere near the 1% mentioned something not right .
Given the size of the land bank and location it’s still ticking all my boxes despite my first post being total nonsense .
Two points spring to mind on this, but I haven't seen the source of your original information and haven't seriously looked at HSP for a while as I'm generally negative on the company.
Didn't HSP float off a few years ago their renewable energy company? Perhaps that effects the rental income by a sharing mechanism.
If these prospective wind farms are on the old desolate and often quite remote opencast sites HSP own, which I would think are the areas most likely to obtain planning permission, there would be a further huge benefit to the landowner. In order to build and maintain these major structures you need a good network of well constructed roads, which would, imo, substantially increase the value of the land even as agricultural land.
I am intrigued by the capital reconstruction currently being voted on by Coral Products (LON:CRU) shareholders.
The company proposes to cancel its share premium account (£5,621k at 30 April 2022) and its capital redemption reserve (£1,061k at 30 April 2022). By so doing, it will increase its distributable surplus by £6,682k (the sum of the two).
So far, so sensible. However, as at 30 April 2022, the Coral Products HoldCo already held distributable reserves of £4,906k. Cenkos forecasts operating cashflow of £1,416k for 2023 and £2,560k for 2024, compared to dividend plus interest costs of £1,270k for 2023 and £1,445k for 2024. Thus, it is clear that on current forecasts, the existing distributable surplus is perfectly sufficient to pay projected dividends and will, indeed, grow whilst doing so.
Why then look to more than double distributable surplus if what is there already is more than ample? I can only surmise that the Board intends to increase dividend payments materially above current forecast levels. To put this in context, the prospective yield is already around the 9% level on forecast dividends.
In this regard, it is perhaps notable that Joe Grimmond, the Executive Chairman, has a 7.72% shareholding and is 73 years old.
One hitch is that the Court may impose a requirement that a ‘special reserve’ is set up under the reconstruction to protect creditors. These would be the vendors of acquired businesses who are still due deferred payments. Special reserves would not be distributable until the relevant creditors had been satisfied.
Anyway, it all serves to a bit of intrigue to what I believe are already excellent prospects for the business, and I have added to my holding yesterday and today, taking me over 2%.
Any contrary views on this?
It smells like the managers of the company are expending considerable time and effort rearranging Coral's finances.
This is not being done so the underlying business makes more money, it is so they can pay money to shareholders.
If I was a 73 yo chairman and had my tax affairs nicely arranged, I might propose a share buyback.
Not being contrary, just wish the managers (who are no doubt well paid) concentrated on managing a bit more.
Hi andrewdb,
Thanks for replying. I'm actually very happy with how the Coral Products (LON:CRU) managers are behaving:
Biome Technologies (LON:BIOM) looks like one of today's car crashes. Seems to be an odd combination of 2 different businesses, neither of which appears to be working very well. Is there ayone out there who can shed any light on whether there is anything viable or valuable here? Deep value or even deeper value trap, it's certainly in microcap land now. Thankfully I don't hold.
I think it's a case of an innovative tech company relying on a small number of large customers.
In the past I have listened to interviews with the Biome CEO and gained the impression that they are not actively seeking bioplastic customers, but are waiting for customers to find them. When they do connect Biome don’t seem to be able to establish realistic sales offtakes. Time to replace the CEO and Sales Director I am afraid, or more Jam Tomorrow.
High Mark,
I had a quick look at Biome Technologies (LON:BIOM) but it's too small for the main report now. Shares down about 60% this morning, on a nasty profit warning - supply problems & order delays mean it's now expecting to be substantially below market expectations for revenue & profit.
Both its divisions are, to me, very stale stories, that have been around for donkey's years. Some older readers might remember the Stanelco business, which was separately listed, and was always jam tomorrow, and as these things usually are, was a flop.
Is BIOM bust? Management says today that they believe there is enough working capital, but cash is running out, and it looks tight to me. If they can turn some of the inventories into cash, then it might survive. So it doesn't look bust to me yet, but is likely to need a cash injection at some point, I think, if it wants to be on a firmer footing. Who would want to pump more cash in though?
Regards, Paul.
Good morning,
Brave Bison (LON:BBSN) (I hold), EV £18m, have released what appear to be stunning interims this morning, acquisitive, yet still debt free (net cash) and a "meet or exceed" outlook. They were one of the more impressive teams & presentations (IMO) at Mello earlier this year, which prompted the initial purchase. I wondered if I could request a look by Paul or Graham? It almost seems too good for comfort, so the bear or more cautious views in the community would be appreciated.
No doubt todays market reaction will probably be "not good enough - minus 20% off the SP"! If that's the case, perhaps this could be a buying opportunity?
Any comments on Macfarlane Paul & Graham? It looks undervalued but profitable with increasing profits. But the share price has been falling since I bought in last year.
There was a SCVR covering Macfarlane (LON:MACF) in August.
https://www.stockopedia.com/co...
There's no news from Macfarlane (LON:MACF) today - we're driven by the day's trading updates & results, rather than giving a running commentary/speculating on what share prices are doing! I usually cover MACF results, and think it's a decent company - see the archive here.
Thanks Paul. I'll continue to hold.
Macfarlane (LON:MACF) (J hold) - Hello BouncingBack - I don't think there has been any news on MACF? I expect that Paul and Graham will be tied up with the companies that have released news, as well as those left over from excess newsflow earlier in the week.
FWIW my view on MACF is that the shareprice is being derated alongside its peer group. Companies like DS Smith (LON:SMDS) James Cropper (LON:CRPR) and Robinson (LON:RBN) all of which are in the paper/packaging sector are on similar ratings. My guess is that the market sees demand for packaging falling off in a slowdown and as fears for recession grow together with inflation rising then low margin and low growth sectors like packaging - where companies generally have high costs and low pricing power - will not be attractive. DS Smith (LON:SMDS) looks to have derated further than Macfarlane (LON:MACF) despite its forecast profits growing faster than Macfarlane (LON:MACF) - I think there are valid reasons for that - but I've only taken a very quick look.
Despite its similar ratings Macfarlane (LON:MACF) does stand out on the stock report from its peers in one respect - its Quality rating at 90 is much higher than its peers - and in particular its ROCE has been consistently double the sector long term average right through the pandemic.
Bottom line - That's the kind of company I'm looking for at the moment - where it's being marked down in price alongside its peers despite being a more profitable, growing and higher quality company. This reinforces my view that Macfarlane (LON:MACF) is likely to be one of the winners when the tide turns. Despite being one of my largest holdings I will pick up some more shares below 100p if the market and my limited cash availability allow. You must do your own research and act accordingly - it's never easy looking at a large paper loss for no apparent reason,
cheers
Mark
Thanks Mark, (and Paul earlier) for your views. That helps me understand what's going on. The company passed all my checks before buying last year. I'm looking long term so hopefully things will look a lot more positive before too long.
On Macfarlane (LON:MACF) - BouncingBack you are welcome.
Another consideration I have is that management expectations have been cautious in previous years, as is the accounting, particularly at H1. The Interim results exceeded my expectations but forecasts for the FY remain unchanged. Which is sensible under the circumstances. Anything can happen in the next few months. But if MACF follow their usual seasonality then based upon the H1 figures they will significantly exceed current expectations. They usually do - but nothing is guaranteed - especially not now.
Conversely the market is seeing much higher risk of not meeting expectations across the board for many sectors - hence is de-rating multiples.
As a result there is something of a double-whammy on the share price right now. Management expectations are under-stated in case of poorer trading - whilst the market is also de-rating the understated expectations in case of poor trading. All of which does make the waiting quite painful, but improves the chances of a 'bounceback' in my view,
cheers
Mark
If the Feds have just hiked 0.75%, the logical step for the BoE, in my mind, is a higher hike, in my mind.
Inflation is running hotter in the UK, and now more so that the pound is getting weaker by the day and imports are more expensive. More stimulus is being heaped onto the economy from Truss.
Unfortunately I'm not very skilled at reading tea leaves so this is probably way off the mark!
And yup... the BoE has majority gone for only a 0.5% this time round.
Looks like they don't think inflation is accelerating in terms of growth rate, leaving them with the luxury of slowly and steadily doing meek 0.5% increases...
You're not far off no good answers for the West at the moment rumours all the bill bail outs could cost £200 billion Government doesn't have that money, bank of E can't QE it this time around so we need someone else to buy all the gilts.
With sterling falling yields will need to go up to attract buyers meaning anyone hold UK Gilts will be seeing a decrease in value at some point and most likely interest rates will have to track gilt yields higher leading to pain for anyone coming up to remortgage time.
Excellent update from Smiths News (LON:SNWS) this morning. Year end trading update contains my favourite phrase ‘ahead of market expectations’. Forecast final divi of 2.7p provides a yield of 10% on its own. Year end Borrowing down to 0.5 x EBITDA. Can’t find anything not to like. The share price has been flattened recently, so will the market respond to good news?
I really like the way management have conducted themselves at Smiths News (LON:SNWS) and I bought in with a cautionary initial stake just sub 40p early 2021, and added more in November when it was clear they were achieving what they were setting out to do. I regrettably felt I had to sell out a few weeks back after watching the SP tick down without what I felt was any real justification as I had held beyond my stop loss, but couldn't hold any longer.
For me, the fundamentals appear really attractive, and if I was looking at getting in for the first time at the current SP, I would probably take a punt and do so, but I feel it is little more than a punt at the moment. Jim Slater warns of shares performing badly in the market despite of otherwise very attractive fundamentals. I usually adopt his quick check of current share price being within 15% of their 2 year high, and for Smiths News (LON:SNWS) it is just over 30% so not encouraging. Combine this with there being nothing new and exciting in the pipeline I can't justify holding any longer. There has been some director buys this year mid 30p's but not a significant enough volume to put me any more at ease. For me there needs to be a spark to reignite this share, some sensible acquisition for example, but until that potential spark arrives, I'm happier sitting this one out and watching closely as I feel it more likely this will continue to slowly tick downward. Of course holders could get lucky with a buyout? As Jack said in a previous SCVR report, "not a share I’d want to be holding when the cost-cutting can no longer be done to maintain the divis".
The dividend is appealing, but I think that there are better options out there offering good dividends which offer better safety for your capital, such as Sylvania Platinum (LON:SLP) (I hold) and potentially Foresight Solar Fund (LON:FSFL) (Not currently holding). Good luck to all continuing to hold Smiths News (LON:SNWS), it deserves to do well from here, whether it will is yet to be seen!
Added a few Smiths News (LON:SNWS) this morning. What is the final destination for the company. Its only competitor is Menzies News, which is privately owned. Given the prodigious cash generation, my best guess is that it will be acquired by private equity. For the time being it will no doubt continue to be ignored by Mr Market despite in my opinion the compelling value currently on offer.
It should also be a beneficiary of the World Cup as youngsters try to complete their sticker collection of football 'stars'.
The sell of in America overnight was a little surprising for me as 0.75 percent increase in interest rates were expected and 'priced in' by all accounts.
I think the Wall Street continued sell off I can only be a good sign to get this bear market over with, as they still seem pretty pumped up compared to pre Covid levels, with an amazing growth rate over the last few years. The FTSE 100 could maybe give another 100 points or so, but to be fair on a five year basis it is fairly flat.
Small and medium caps continue to just about hold on previous low resistance levels with a good day yesterday to ease pressure. Could there be another panic sell off in small caps? Well I am hoping not but continue to have tight stop losses just below resistance in the case we take a further leg down, with Facilities by ADF (LON:ADF) being my first victim of that yesterday for a while now.
If we take a leg down I will be stopped back into cash for another go lower down, with this week being pretty critical in my opinion with the BOE giving rate rises today. Again 0.75 percent 'priced in', with a 1 percent rise being taken very badly I would say,
I remain pretty positive re small caps, having trimmed my portfolio a little, and sit here watching in my PJ's and a tin hat.
Good luck to you all out there.
Hostmore (LON:MORE) I would particularly appreciate your views on their balance sheet Paul/Graham. It doesn't look great to me and I don't know how they are planning to fund potential acquisitions (they've talked about adding another brand) - probably via a fundraising?
A L4L revenue fall of -14% compared to pre-pandemic period is also awful - especially as once you add in inflation the fall in sales volume will probably be nearer -20%. I appreciate they are probably at the sharp end of consumer cut backs though.
I don't hold and don't see the opportunity currently.
ps the IPO costs for floating look extortionate!
Patrick L - re Hostmore (LON:MORE) - I can only echo your call for Paul's take on the balance sheet.
However, having watched the webcast yesterday I can re-assure you that they have trimmed plans for expansion short term - specifically they are ruling out buying another brand soon, pausing Friday's expansion (after 2 completions in '22) until 'market conditions get better and talking only about Friday's to Go trials in a service station and a retail park .
I also asked a Q re the impairments - 20 sites affected with 50% of problem in 3 sites (including stadium) but CFO claimed he expected these to recover in time.
Finally, the presentation was prepared before the latest round of Govt energy subsidies were announced for both consumer and businesses plus the other tax giveaways like the reversal of the NI increase etc. These govt giveaways will be biggest for the higher income consumers already paying premium prices for Fridays.
(My current overall 'Marie Antoinette' buying strategy is to focus on beaten-down consumer-facing UK stocks whose user base is the rich and the old who I think will keep spending - so Saga, Unbound, Sanderson, Hostmore... although I know how it ended for her!)
Whilst opinions may differ on the sense of massive Govt borrowing to fund short term consumption, it is likely to put a floor on demand reduction but not be enough to stop even more financially weaker chains, branches and independents closing down. Fridays look like it will be OK to me so maybe good value on a 2-3 year basis? I hold a small position to find out.
Hostmore (LON:MORE)
It seems to me that the woes of Hostmore (LON:MORE) are very similar to the woes of revolution bars group sometime back before dilution and removal of debt - one can take a rosy viewpoint if one wants but with £25 mill of debt and bottom line losses is lets hope they can keep the lights on is best case scenario at present. Anyone who isnt worried about losing their shirt here really should be.
The Private Equity guys did it again! They must be delighted with their sale. Unbound have been an unmitigated disaster with an incompetent management team and Hostmore, in fairness have been more affected by macro issues as far as I can see. But overall they probably see the "extortionate" fees as a fair price for getting them both away. Poor old private client stuffed again. Ho ho, Christmas will be here soon.
Hostmore (LON:MORE) has further to fall I suspect.
Thankfully I got out on 8 Dec 21 @ £1.08 a share after the worst restaurant experience I'd ever had at their Cribbs Causeway site, I do appreciate their fall is not entirely down to customer service but that will play a big part in customers repeating their visit.
I am watching them but my buy price is definitely more (no pun intended) towards 10p than 18p. Might dip my toe in again if there is tangible evidence that the customer service has improved.
Hostmore (LON:MORE) has been a disaster for me but thankfully I took a good hard look at my portfolio a month ago and made some very difficult and financially painful but realistic decisions to exit shares including Hostmore (LON:MORE) and so in that respect I am pleased I am out of this and avoided an even bigger loss. I may have racked up losses from this and others but do you know what..thanks fully even though my losses have been high it's not money that I need and can live without and my slimmed down portfolio is so much better and I am much more confident in....also ..I have learnt so much over the last 2.5 years of holding stocks support rates by Paul and the team at Stocko and others. You could say that I am far more cautious, sceptical and worldly wise about holding stocks compared with 2.5 years ago,. You've got to take the positives however you can. Onwards and upwards, I am looking for long term value opportunities and building up new positions as I'm confident of an improvement however long it may take....
Agree with your comments re learning a great deal from Paul and others on Stocko. Are you a Bristolian? Bristolian :) If so we will be in fairly close proximity.
Dicky Mint, I am indeed a Bristolian, living just south of the river
Southern edge of Bristol myself - near Keynsham.