Small Cap Value Report (Thu 23 Feb 2023) - MACF, TTG, TRCS, SYS1

Good morning from Paul & Graham!
Here's the link for my latest discussion (recorded on Tuesday this week) with Paul Hill of Vox Markets - a highly accomplished small caps investor (far better performance than me!) who I always enjoy chatting to, about my latest small cap ideas, and wider investing themes too.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Macfarlane (LON:MACF)
106p (pre market open)
Market cap £168m
Macfarlane Group PLC has been listed on the Premium segment of the Main Market of the London Stock Exchange (LSE: MACF) since 1973 with over 70 years' experience in the UK packaging industry. Through its two divisions Macfarlane Group services a broad range of business customers, supplying them high quality protective packaging which help customers reduce supply chain costs, improve their operational efficiencies and enhance their brand presentation.
Results for FY 12/2022 are published promptly today, key numbers (continuing operations only, which excludes a disposal in 2021 (see note 6) -
Revenue up 10% to £290m
Profit before tax (PBT) up 7% to £19.9m
Diluted EPS 9.84p (2021: 8.62p) - up 14% (helped by a lower tax % charge in 2022)
Two acquisitions helped the 2022 numbers.
Inflationary pressures largely passed on to customers - only a slight drop in gross margin from 32.4% in 2021, to 32.1% in 2022 - I’m impressed by this, as it shows a resilient business in tough conditions.
The smaller manufacturing division is the star performer, with operating profit rising from £3.7m in 2021, to £5.2m in 2022.
The larger distribution division saw operating profit almost flat at £19.9m (2021: £19.7m).
Net bank debt is insignificant at £3.4m, and plenty of headroom within a £30m facility limit.
Pension scheme is showing a £10.2m accounting surplus, so this needs careful scrutiny. Deficit repair payments are set at £1.3m pa until May 2024. So in the real world, it’s still a deficit, although it’s only consuming a small % of profits. See note 11 for more details on pensions.
Dividends - total 3.42p, a yield of 3.2%
Amortisation - this is an important point, in that MACF does not present adjusted profit numbers, instead it absorbs a £3.6m amortisation charge (see note 2), which looks as if it relates to acquisitions (goodwill and similar). It is customary to adjust this out, which would boost reported PBT from £19.9m to £23.5m, a substantial increase of 18%. If I apply a similar % increase to EPS, then the adj EPS figure would go from 9.84p to 11.6p, and it’s the higher figure which I would use to value the shares. Apply a PER of say 12-15 (not demanding), and I get a valuation range for this share of 139p-174p. Hence it looks very cheap at the current price of c.108p. I don’t understand why the market puts this share on such a low rating, when it’s a good quality business, performing well.
Shore Capital has issued an update note today (many thanks) and it arrives at adj EPS of 12.1p, and says this is a 4% beat against forecast, so ahead of expectations.
It looks as if Shore’s figures include leases as debt, which is unusual, as most people strip those out. I regard the company as roughly cash/debt neutral.
Outlook -
We anticipate that 2023 will be another challenging year with uncertainty over the impact of the increase in the cost of living on customer demand, rising operating costs, particularly related to labour and energy, and increasing interest costs. Despite these challenges, with the effectiveness of our strategy, the resilience of our business model and the experience and commitment of our people, we expect Macfarlane Group to continue to deliver further growth in 2023.
Balance sheet - looks fine to me. NAV is £106.0m. Take off intangible assets of £75.7m, results in NTAV of £30.3m. Lease entries roughly net off to zero, so we can ignore those. Working capital is adequate, but not strong - the current ratio being 1.22, although that goes up to 1.34 if I remove the current lease liabilities figure of £6.6m. There’s no non-current interest-bearing debt.
So overall, it’s an OK balance sheet, but I wouldn’t describe it as particularly strong.
My opinion - is there something I’ve missed here? I cannot understand why this share is so cheap. It’s a good company, performing well, with negligible net bank debt, and only a small pension scheme actuarial deficit, that’s just beaten market expectations, and yet it’s valued on a PER of only 9 - that doesn’t make sense to me at all.
Therefore I remain strongly positive on this share, and repeat my previous conclusion that this share appears inexplicably cheap. I could be wrong, but it seems to me there’s a significant undervaluation here, which gives investors an opportunity to make a perhaps 20-50% profit, sitting on a plate, if/when the share re-rates to a more appropriate valuation. You might have to be patient though. Sometimes cheap shares remain cheap.
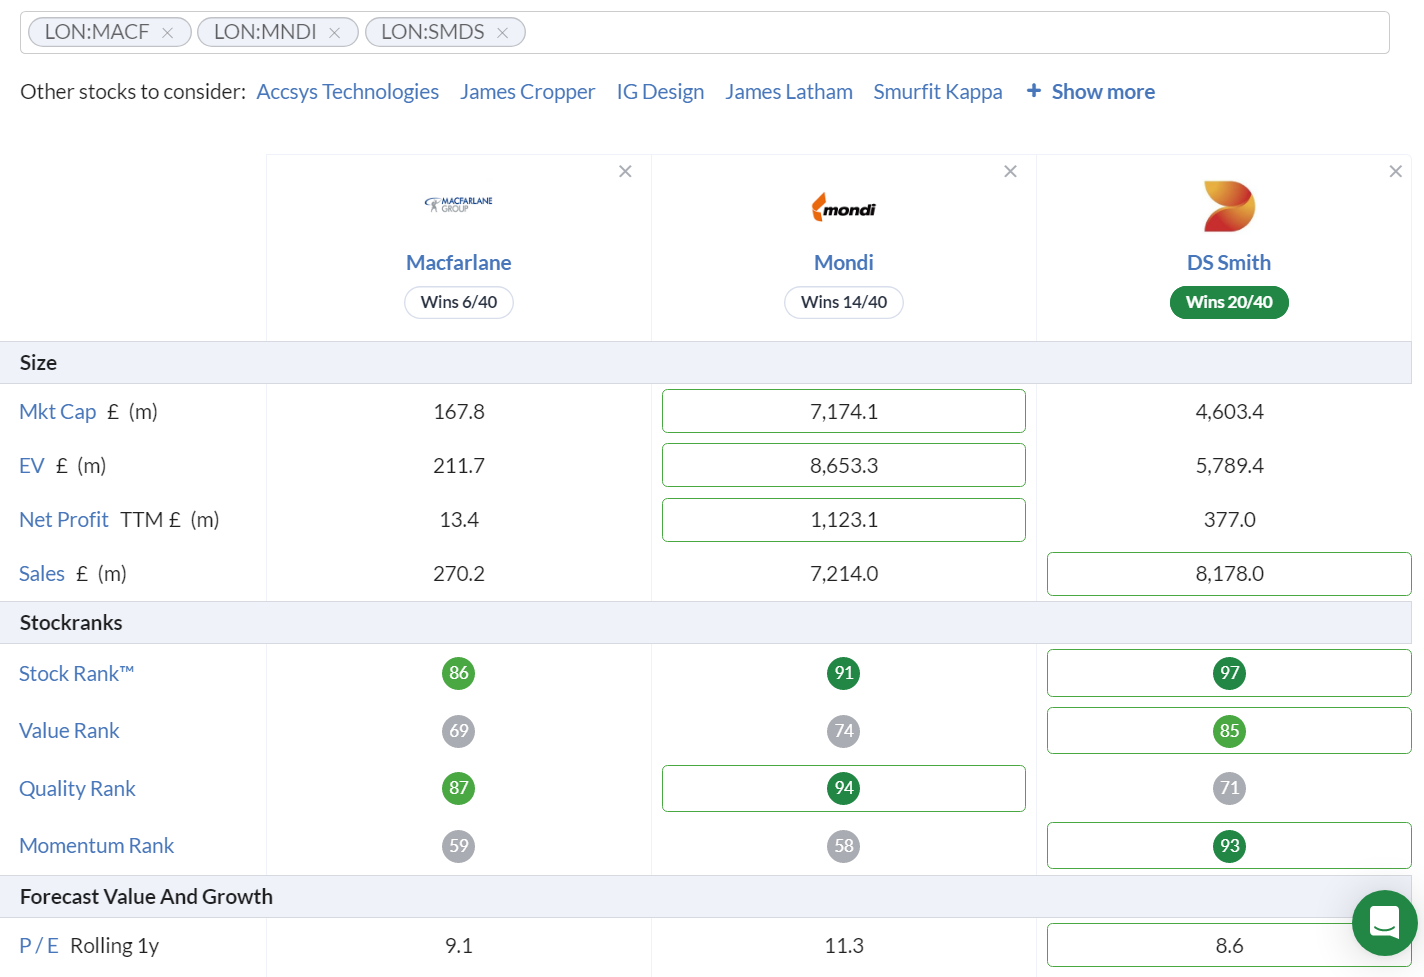
At this price, I’d say MACF looks a sitting duck for a takeover bid from a larger competitor. There again, Mondi (LON:MNDI) is only rated on a fwd PER of 11.3, and DS Smith (LON:SMDS) a fwd PER of only 8.6, so it looks as if this is just a cheap sector. Maybe MACF isn’t out of line with those valuations after all?
Stockopedia likes all 3 of these, with sector StockRanks currently:
Macfarlane: 86
Mondi: 91
DS Smith: 97
I like the sector comparison tool on Stockopedia, to give a quick & rough idea about where to prioritise sector research, and it likes DS Smith best, screenshot (with clickable link) here -
.
Tracsis (LON:TRCS)
950p (unchanged at 09:18)
Market cap £284m
Tracsis, a leading provider of software, hardware, data analytics/GIS and services for the rail, traffic data and wider transport industries, is pleased to provide the following trading update for the six months ended 31 January 2023.
H1 has traded in line with expectations.
Expectations for FY 7/2023 remain unchanged (but not stated what these are!)
Strong revenue growth in H1 (£39m+, up c.34%)
H1 EBITDA expected to be up >20% on last year’s £6.2m, so c.£7.4m
Finncap’s forecasts suggest FY 7/2023 adj EBITDA £16.0m, and adj PBT £14.2m, adj EPS of 37.3p (giving a PER of 25.5x)
Commentary today refers to - “Growing pipeline of opportunities”, restructuring done, accelerating technology investment.
Cash is c.£17m - considering further acquisitions.
Balance sheet - I always like to check, and TRCS last reported NAV of £60.4m at 7/2022. Take off £65.9m intangibles, and the (probably related) £10.7m deferred tax liability, and I get to adj NTAV of only £5.2m. So it’s a fairly thin balance sheet. The cash comes from customers paying up-front, rather than being surplus cash. That's usually the case with software businesses, so nothing untoward.
Note that there’s £8.6m of contingent consideration payable in the current financial year - worth noting that this is about half the cash pile spoken for (assuming this is payable in cash, and not shares). Although there should be fresh cash generation to rebuild cash this year, so it’s not a problem, but should be taken into account.
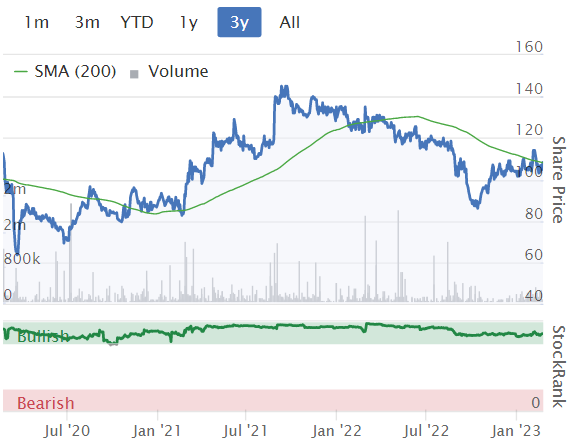
My opinion - Tracsis has an excellent long-term growth track record, and that’s reflected in a punchy rating of 25.5x this year’s forecast EPS. Note also that forecasts were lowered a few months ago, which is not something I would expect to see at a high PER share -

For me personally, I’d be more comfortable with a valuation nearer 500-600p per share, so the current price of 950p seems much too racy. That said, the company’s long-term track record is fantastic, and shares have 20-bagged over the last 12 years, so quibbling over valuation can sometimes be short-sighted!

Graham’s Section:
TT electronics (LON:TTG)
Share price: 181p (pre-market)
Market cap: £319m
This electronics supplier treats its shareholders to another positive update today.
I still think it became noticeably undervalued during the depths of the small-cap bear market (see my comments in the archives). There has been a nice recovery since November:

Today’s update for FY December 2022 is ahead of expectations:
Group revenue growth in the final two months of the year continued to be strong, with organic growth for the year of 20% reflecting our successful positioning in structural growth markets and new project and customer wins.
Adjusted profit before tax for the year is expected to be at or around the top end of the range of analyst consensus expectations with the outperformance driven by our Global Manufacturing Solutions (GMS) business.
Analyst consensus expectations are for adjusted PBT of £36.5m to £39.4m.
Net debt - one of the reasonable concerns about this stock has been its debt load.
Last June, due to higher inventories and other factors which strained cash flow, net debt had increased to £142m (including IFRS 16 rents of £23m).
This resulted in a leverage multiple (net debt / EBITDA) of 2.4x.
Today’s update informs us that the leverage multiple has fallen back within the target range of 1x - 2x, as planned. So investors can breathe slightly easier.
Remember also that TTG offloaded its defined benefit pension scheme recently, which will have a £6m annual cash flow benefit.
We’ll have to wait longer to get a full outlook statement from the company. This is what the company says about 2023 for now:
We enter 2023 with good momentum, underpinned by a strong order book and will provide a full update with our Annual Results presentation on 8 March.
My view
In hindsight, I do think the “easy money” was made on the bounce from November levels until now. But I still like this company; it has a solid long-term record, is well-diversified internationally, and has managers who try to generate an acceptable ROIC for their investors (although it’s questionable whether or not they actually do this - see the quality metrics on the StockReport).
Given a valuation that is still, I think, on the cheap end of the spectrum, and the strong trading momentum, I’ll maintain my positive view on this one.

System1 (LON:SYS1)
Share price: 179p (+8%)
Market cap: £23m
It’s a Q3 update from this marketing company, covering October-December 2022.
Key points:
Data revenue +18% to £3.4m (quarter-on-quarter)
Consultancy revenue minus 21%, falling less quickly than before.
Total Q3 revenue minus 4% to £6.2m
As a reminder, this company has been shifting away from labour-intensive consultancy work to more automated data-driven products. Data revenue now makes up the majority of the total.
The year-to-date gross margin is 82.7%, but this doesn’t necessarily mean that we get a positive bottom line. There were no profits in this year’s interim results.
Cash continues to fall and is now just £5.1m. This is “partly” due to a working capital increase, but I wonder if financial losses may also play a role.
Capital Markets Day - next Tuesday on Investor Meet Company.
Estimates: Canaccord Genuity leave their estimates unchanged. They expect an adjusted PBT of £0.1m for the current financial year, and £0.8m for FY March 2024.
My view
In my previous comments on this company, I wrote that there was too much uncertainty hanging over its shares, while management carried out a strategic review.
That review is now complete, and I’m enthused by the results. The review “validated our existing successful focus” on testing/improving services for ads.
Looking forward, the company will “target the world’s largest advertisers”, will seek to grow US revenues, and be a “Rule of 40” company, i.e. revenue growth and adj. EBITDA margin should add up to more than 40%.
There’s lots more to digest in the review, but I think it’s good news that the company has settled on a continuation of its existing strategy, along with some new goals and points of emphasis.
The founder, who is also the largest shareholder, has moved from CEO to President, and the COO has been promoted to CEO. A logical succession plan.
So I can be more positive about this company than I was last time. But can I take an outright positive stance? I’m not sure.
It has been half a decade since the company earned profits of more than £2m:

Since this is a “value” report, I think I’ll have to stick to a neutral stance, since I don’t think outsiders can say with any degree of confidence that System1’s new strategy is going to succeed.
If I wanted to make a value argument for these shares, I could point to the price/sales multiple of less than 1x, and the cash balance of £5m. It’s possible that the shares are underpriced when you take those two facts into consideration, but I’ll stay neutral.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
On System1 (LON:SYS1) I wanted to flag something alarming that I found when digging into the numbers...
Test Your Ad is trumpted as the growth engine. Subscription based product, high margins. Big growth in new clients onboarded. However....
In the FY Mar22 results, they said they had 465 customers (in FY22), of which 209 were new.
In the HY Sep22 results, they said they had a total of 240 customers, of which 85 were new, 155 were repeating.
So it looks like there has been high churn? As I think the TYA service is an ongoing subscription?
A possible explanation is that some of the customers might be on free “trials” and they sneakily included it in the 465 number for FY22? But then that's a really bad trial-to-paying conversion rate.
Could anyone share their thoughts on why the strngth after Spectris (LON:SXS) earnings on 23 Feb 23? Even with an earning suprise of -45%?
I'm getting the backlog cleared on my SCVR summary spreadsheet this evening, nearly finished it now. I've definitely created a monster here, with it taking a lot of time to update, but I think it's worth it.
The main summary page is here.
Don't think I'll be able to keep updating the other tabs, it's too much additional work.
EDIT: good that's up-to-date now. It's a neat summary of lots of SCVRs all on one page, so I'll keep it going.
It's a great reference tool. We appreciate you :D
You need a PA Paul, perhaps one who's not colourblind.
perhaps a few trusted volunteers here could do that work for you Paul, and delegate permisisons out?
iEnergizer (LON:IBPO) 50% drop since excellent interims in November, can't really fathom why? I have committed a cardinal sin of allowing a decent gain to turn in to a loss. Forward PE of just 9 times.
I don't understand that either, I have a small holding in iEnergizer (LON:IBPO), there has been some strange share price movements on no news.
My guess is someone is selling down looking at the trades. Blocks of 1,3 and 5k being sold
I remember looking at iEnergizer (LON:IBPO) last year, and the stand-out feature is the major shareholder owning 83% of the company.
Positive and negative. May want to delist? Wouldn't make sense to me, there were formal sale process talks last year where 550-600p may have been possible? So why not sell then.
Just noticed Jarvis Securities (LON:JIM) are down 14% today, on news apart from it is ex dividend (3p) today, any ideas?
Wentworth Resources (LON:WEN) The vote just past the 75% mark by 0.26%, so takeover will go ahead.
Hi
Zoo Digital (LON:ZOO) announced a large contract win 21/2, SP up about +17% since then.
This short 6min vid (released a few minutes ago) of the CEO explaining a bit about Zoo Digital (LON:ZOO) and their offering supplies a bit of context to the business model.
(I do not hold).
Regards
Howard
Like Camtab Paul I also enjoyed your chat with Paul Hill, you made me laugh near the beginning talking about the voice in your ear saying "You know you should sell" while a stubborn finger on the button refuses to do it, that's my biggest problem as losses mount, I cheer myself up with all those capital losses still to take, then hopefully use. I look forward to your next chat on Vox Markets.
&ab_channel=ProactiveInvestors
Not that long ago (I think ) Paul Scott commented on @CNIC saying that he didnt quite understand what it did.
This short vid answers a few of those questions.
Really enjoyed your chat with Paul Hill. I think you make a very good double act.
Small Cap Value Report (Thu 23 Feb 2023) - MACF, TTG, TRCS, SYS1
7:05 am by Paul Scott33 comments•2,671 Reads
Good morning from Paul & Graham!
Here's the link for my latest discussion (recorded on Tuesday this week) with Paul Hill of Vox Markets - a highly accomplished small caps investor (far better performance than me!
Why do you think that Is?
Not a small cap but delighted to see stronger results from Rolls Royce today. A great British company. I sold out a few weeks back which isn't looking too clever today. Free cashflow has improved significantly which is key given the level of debt in the business.
I thought they were terrible figures ! Still saddled with huge amounts of debt wiping out all profits. They will have to maintain similar levels of FCF over the next few years to stand any chance of paying back the debt...else there will be another equity raise I think...
Rolls-Royce Holdings (LON:RR.)
Unusual volatility. Have they cracked small nuclear reactors perchance. Ok more flying and engine maintenance plausible. Or maybe a takeover target for their IP (engines tech? govt?).
Can't be luxury cars GB UK destroyed that yonks ago. So sad.
Maybe a merlin engined drone called er 'Spitdrone'.
Made Tech (LON:MTEC) I suppose the big question today with the H1 results is whether or not expenses have got out of control, given the rapid growth. The shares have dropped, so investors are disappointed, but possibly by the huge share based charge. The £1.3m of capitalised costs is also a concern.
Can I make this request for the collective wisdom using Stockopedia on a portfolio decision I need or ought to make? We parked a decent sum of money into ABF foods when markets seemed very nervous last year. It went to a sizeable loss quite quickly but I bought more. To cut the story short we hold at an average price of 1720 and the holding is over 20% of our modest portfolio at today's 1986p. The shares have rallied well and there's a pre-close trading statement on the 27th. They have a good story to tell on Primark and are buying back shares, forecasts for 2023 and 2024 have also been raised slightly.
As shares often fall back after a strong rally on facts, I'm tempted to take the profit and re-invest in small caps which I understand slightly better. Forgive me asking but there are better investors and good analysts on this website. What would you do? All comments appreciated, even critical ones.
It is highly dangerous to have 20% in one stock. If you are high conviction 5% is ok. So you do need to sell a chunk of ABF.
The stock ranks will guide you on others you should buy. Hopefully these will be in different industries so you can diversify properly.
I now hold a tighter range of stocks with all key holdings above 5%.
I just found with 20 and more holdings all below 5% you tend to just follow the market so may as well be on a tracker .
More risk / reward with higher % and fewer stocks .
Reading your comments on primary you seem pretty happy / confident and also you seem to understand the business .
Maybe sell half then you win both ways , if they go up you’ve still 10% of your portfolio in them (full position ) and if they go sideways / down you have sone comfort as well .
I also think 20% is too high even for an excellent company (imo) like ABF. You are just too vulnerable if something goes amiss. It shouldn’t be terribly volatile but who knows. But I also would not be tempted to sell the lot and invest all in small caps though they have generally done badly during this difficult period of higher rates. Unless you think the ABF business model is wrong or the prospects poor why ditch the lot?
Everyone who is telling JAZFS that 20% of his portfolio in one company is far too much and far too risky might consider the fact that he describes that portfolio as "modest". If you are investing your life savings at retirement then maybe I can agree, but if you have only a small portfolio, a long time frame and can afford to lose it, be as speculative as you want.
I am new to Stockopaedia (first post) and have no financial qualifications (warning) but really find the stock analyses and discussions very informative. JASVFS, I was in an almost similar position with Liontrust Asset Management (LON:LIO) this week. Decided to safeguard some profits by applying a 5% trailing stop loss to 90% of my holding as I was uncomfortable with the level of risk. Regrettably I got shaken out as the stock went down before going up. At least I made a 15% profit overall. Review of that decision raised an interesting question.. Please can anyone advise on how best to select an appropriate % stop loss taking into account gaps between chart bases. This seems pertinent as a larger stop loss would seem to be required for more volatile stocks.
5% trailing stop loss, you will get taken out all the time, better IMO, to sell at a peak. Ed Croft did cover setting stop losses, think he said on speculative stocks such as Liontrust Asset Management (LON:LIO) need to set around 20%, but that is not trailing. You should look the normal share price trading range and then set it below that, however in low trading times shares can dip down, then your stop loss will get triggered and some market maker will bet your shares cheap. I gave up on auto stop losses on the London markets. I do use alerts on Stockopedia. My platforms don't have trailing stop losses either. You can read Stan Weinstein on stop losses, he uses the 30 week moving average.
Thanks Rusty 2 much sound advice except for the bit of sell at the peak as I can only ever identify that with hindsight. I will look up the Stan Weinstein guidance on stop losses but do not use them as routine. Used it on this occasion as I was over exposed on one stock and added the % trailing to guarantee a certain level of profit and the possibility of more if the stock moved in my favour which it didn't. Your implied warning against routine use of stop losses is appreciated.
Welcome to Stockopedia. You might like to read 'Excellent Investing' by Mark Simpson, it contains much practical advice on stop losses, portfolio weighting and more.
Do you have a link to the article?
Hi Caduceus
'Excellent Investing' by Mark Simpson is a book - I read it recently and thought it was good.
David
Gotcha, cheers for getting back to me. Have a great week!
Macfarlane (LON:MACF) is mainly a distributor of packaging, while the bigger players such as Mondi (LON:MNDI) are heavily involved in the manufacturing process - they have huge plants across Europe producing all the materials (and I believe they even have their own forests supplying the wood). Therefore quite different businesses. Interestingly Mondi (LON:MNDI) down sharply this morning although I thought the results looked OK. I currently hold DS Smith (LON:SMDS) but thinking of adding another name as the sector looks cheap and has very good long term drivers (sustainability, e commerce, etc)
Hi Bouden - yes, I agree they are not exactly the same vertical business structure but are certainly same sector. Probably more so than a lot of tech "peers" that get lumped in together. I think all 3 are actually really good businesses. Just finding it odd that Mondi (LON:MNDI) is down 7% trading on a PER of 8 given its cashflow generation, dividend and long term prospects. The entire sector only trades at 10-12* but 8 feels just too low for a quality business with longevity.
Interesting discussion on Macfarlane (LON:MACF) (I hold) thank you. And thank you Paul for the writeup - I don't have a lot to add (to the numbers) being a bit late to the party today.
I'm not an expect on the packaging industry. It's not a sector I'd normally consider as I'd expect it to be highly competitive, low margin and high volume. In other words not much of a moat? But looking at the 3 businesses, Macfarlane (LON:MACF) , Mondi (LON:MNDI) and DS Smith (LON:SMDS) they all seem to have higher margins and be more profitable at the moment than I'd expect. Intriguing?
The thing that stands out for me about Macfarlane (LON:MACF) is the remarkable consistency in its figures? Profit has grown in each of the last few years with CAGR 5yr profit growth of 15.8% and an ROCE that is consisently around 15% (CAGR 5yr average 14.3%). You could be forgiven for thinking that not much has been happening in the last few years?
So is Macfarlane (LON:MACF) just lucky? Or do they, as Gary Player supposedly said, find that they harder they practice the luckier they get? I think they do and the consistency of results is not by accident.
I'm hesitant to compare the 3 businesses because I know so little about the other two. Being paper mill operators they have a lot of moving parts? Whereas Macfarlane (LON:MACF) is essentially a capital-light, rent a few sheds and a few vans model? I agree the numbers for both DS Smith (LON:SMDS) and Mondi (LON:MNDI) look very good and they seem very cheap - but I can see from the stock reports that they have been less consistent than Macfarlane (LON:MACF) over the last few years and that forecasts are for falling profits?
Obviously I am over-simplifying enormously and there is a lot more detail that needs to be considered. But it seems to me that Macfarlane (LON:MACF) has a habit of under-promising and over-delivering over several years and their cautious accounting and conservative management expectations play to this. The modest improvements currently expected in 2023 can be expected to be raised. Eventually. Don't hold your breath though. I'm not relying on a re-rating in the short term and I expect the shares to be valued on results. I rate the management team very highly, so unless something changes I'm backing the tortoise on this one I think?cheers
Mark
PS - Full disclosure - I've held Macfarlane (LON:MACF) for almost 20 years since initial purchase. Turns out I was a bit previous, but bought again in 2009 (around 17p from memory) then steadily until now and although I've occasionally sold I am still a buyer rather than a seller - now about 10% of my 15 stock entirely UK small cap folio. After James Fisher And Sons (LON:FSJ) imploded it's been my largest holding until recently overtaken by the explosive progress (pun entirely intended) at MS International (LON:MSI).
Mondi (LON:MNDI) also had results out in same space as Macfarlane (LON:MACF)
scratching my head as to market reaction. They are doing 160p EPS and generating £1bn+ of cashflow and are trading at just 1380p so suggest a PE of 8! Bizarre - they put a cautious outlook in the mix but still one that is expected to grow. Makes Macfarlane (LON:MACF) look expensive (though obviously it isn't either)
Mondi was slightly ahead of consensus, so must have been the subdued outlook that has caused the fall - definitely getting tempting at these levels.
You are not the only one! Mondi (LON:MNDI) results look pretty good to me. The market reaction, down nearly 7%, to results that are ahead of consensus is very strange. Is there something other than cautious outlook though that is hardly surprising in current economic climate. Perhaps it’s the South African connection and the various issues in that economy (power outages, strikes, violence, etc.).
Don't MNDI also have some Russian forests they will have difficulty unloading?
They have a highly profitable plant in Russia that they have agreed to sell subject to regulator approval. However, this has already been discounted out of the numbers so largely irrelevant. The ongoing numbers assume zero for the Russian assets so there is upside but not downside as I understand.
Arbuthnot Banking (LON:ARBB)
Another ahead of expectations announcement this morning and price hasn't even moved!
Have a NAV of 1300p + so trade at a big discount to book at 900p, whereas I would expect banks to be trading at book or above.
Ahead of expectations of £17.3m PBT so usually thats at least 10% so say circa £19m. Price just looks wrong doesn't it?
I hold @Arbuthnot Banking (LON:ARBB) disppointed at market reaction they should advise of forecasts for 2023 as these will need to be upgraded. I am expecting a special dividend note staff had col payment
Interesting broker notes out on Research Tree
EPS going forward is expected around 200p with upside from existing base case. DY is 5% and TNAV is currently 1300p but moving towards 1600p in the next 18 months. Trading on a fwd TNAV of 0.55 just looks completely wrong to me. Banks trade at 0.9 upwards usually. Heavy sticky retail deposit base too. PER of around 4 to 5. Compared to other banks appears materially undervalued to me.
It's illiquid though so maybe as these results filter through and people take stock they will re-rate. Tempted to free up some cash from elsewhere to add though I have to admit.
Thank you for the early comments on Macfarlane Paul, I confess to missing the pension surplus is actually a deficit, it's why I'm on here. Topped up current holdings at 1.08. We held DS Smith and sold for a decent profit several years ago, I'm happy to be in Macfarlane now.
Graham
You commented on Pollen Street (LON:POLN) last November, saying it looked interesting following the merger. What's your view on today's TU?
Pollen Street (LON:POLN) Would be interested to hear Graham's view but personally am wary - I believe shareholders got shafted when the original investment trust merged with the asset manager (essentially they gave up half the company in exchange for an asset management businesses that probably has very little value). This is reflected is the sharp fall in tangible NAV per share. The company is actually trading at a premium at present so can't get too excited about this.
Positive update from TT electronics (LON:TTG) with the added bonus that gearing has improved and is now less of a concern.
I bought after the update on the company's UK defined benefit pension scheme in late November that improved annual cash flow by £6m and have recently added.
In fairness it was Graham's presentation at Mello in November on the company's operational performance that was not reflected in the share price at the time that alerted me to the potential. Thank you Graham.
I anticipate a positive market reaction this morning, but one never knows.
Wood Group receiving offers from Apollo https://uk.advfn.com/stock-mar...
The debt didn't seem to scare suitors.
And that got me thinking. Petrofac or Hunting PLC
How similar is Petrofac / Hunting PLC business compared to Wood Group? Could they be worth a punt?
I hold Hunting (LON:HTG) , outlook looks very solid, high visibility on order book, well set to beat expectations over this year and next, broker upgrades have been coming through. More of a picks and shovels play than WG imo.
WG. Don't have much debt anymore.
Made Tech (LON:MTEC) - Don't see this often - CEO & COO waiving their LTIP rights for nil consideration!
https://www.investegate.co.uk/...
Made Tech (LON:MTEC) - Don't see this often - CEO & COO waiving their LTIP rights for nil consideration!
Certainly unusual and I can't offer a definitive explanation,. But I did ask the CEO about the c£2m share-based compensation announced last September and he explained that its purpose was to reward employees as opposed to management. Today's announcement, which goes on to recognise awards made to several employees, is certainly in the spirit of that stated objective.
Today's trading update is simply in line with figures announced recently. The accompanying drop in SP looks like profit taking by traders after shares doubled in not much more than a month.
Sigmaroc (LON:SRC) Capital raise to fund planned acquisitions. Nice of them to let major shareholders know in advance.
"The Company consulted with and received strong support from many of its largest shareholders prior to the Fundraising"
Creating a false market surely?!
And the previous Sigmaroc (LON:SRC) placing, in Jul-21, was at 85p. So not sure this is a great message to be sending to shareholders.
Surely with a big capital raise you'd have to sound out support from the IIs? Likely they were told a range.
I agree but whilst they are doing this the shares should be suspended, as is the case in Australia. Otherwise you have a false market caused by price sensitive information not being in the public domain but known to a few large investors.
Phil
An optimistic view of UK economy by Andy Brough :
https://www.cnbc.com/2023/02/2...
I watched this. interesting he has recently bought M&S.
I note the Stocko also like it with quite high ranking.
Maybe I should like it too!
Driver (LON:DRV) - update note here: https://www.equitydevelopment....
The new financial year has started strongly with a strong pipeline of opportunities and a lower cost base following an expanded rationalisation programme that resulted in most regions delivering a profit YTD in FY23. The results for FY22 were broadly in line with revised expectations, although the lack of forward visibility results in a continued suspension of estimates. That said, we expect FY23 to prove to be a turning point in the Group’s fortunes as utilisation levels improve now that projects are serviced globally.
We are still suspending estimates reflecting a lack of visibility and ongoing uncertainty. While this makes the construction of forward-looking valuation models difficult, we highlight the NAV and within this the level of net cash at the FY22 year end. A historic FY22 price/book ratio amounts to 1.0x, on a book value of £16.4m, which equates to 29.8p/share. Furthermore, £4.9m or 9.1p/share of this is in cash, representing 30.7% of the Group’s NAV.
Comparing DRV to a wider consultancy peer group that trades on an average historic P/B ratio of 4.7x, suggests that DRV (on 1x NAV) remains significantly undervalued. We retain our fair value/share of 49p.
In my relief at reading Macfarlane's results I'd missed the statement from Driver, a rather different story. You'd thought it might be interesting in your last comment on it Paul as they tackled their Middle and Far East problems. They have and are paying a .75p interim with an expectation to be profitable again but not yet! Cash down and your guess of some cash being returned to shareholders is happening slowly. Your other comment on it's size and why is it quoted seems right with the shares having rallied back to where they were at the time of your comment. We are long term holders/sufferers still,being very patient.
My morning smallcap tweet: Till Debt Us Do Part
SIMEC Atlantis Energy (LON:SAE) Amigo Holdings (LON:AMGO) Litigation Capital Management (LON:LIT) Arbuthnot Banking (LON:ARBB) TT electronics (LON:TTG) DG Innovate (LON:DGI) System1 (LON:SYS1), Tracsis (LON:TRCS)
◄SIMEC Atlantis Energy (SAE)► asks bondholders for a deferral of the repayment date of end Mar. Promises them some money is coming in. [SP=1.55 Cap=11m]
◄Amigo (AMGO)► still passing the hat round potential investors. Pilot lending scheme: grown significantly through January and February after a poor start. Hikes compensation provision again by £15.9m. [SP=2.5 Cap=12m]
◄Litigation Capital Management (LIT)► $2m case investment: "partial award on liability and quantum was granted in favour of the funded party. This means that the funded party has succeeded in the claim". [SP=69.31 Cap=81m]
◄Arbuthnot Banking Group (ARBB)► guides FY-Dec pretax beat. F/C is £17.3m. [SP=890 Cap=133m]
◄TT Electronics (TTG)► guides FY-Dec rev up 20%, ahead of expectations. Adj pretax at or around the top end of the range of expectations of £36.5m to £39.4m. [SP=181 Cap=319m]
◄DG Innovate (DGI)► Collaboration Framework Agreement with two tier 1 commercial vehicle and off-highway axle suppliers. It "reflects the desire of all three parties to collaborate, in order to establish a significant position in the growing heavy vehicle electric drivetrain market". [SP=0.12 Cap=11m]
◄System1 (SYS1)► Q3 rev down 4%. Gross margin up on H1. [SP=167 Cap=21m]
In line: TRCS
Good morning Paul and Graham, I'll get in early on this on to see if you'll have time to add it to your lists. Macfarlane results today, we hold and it's good/rare to read one of ours beating expectations at this time. Profits up, dividend up and even an increased surplus on the pension fund. Tougher time in their German aquisition and some extra inflationary costs at the new North East distribution centre, cash down too but the Outlook still expecting growth. Finger poised on the buy button or lay down till the feeling passes?
Morning JASVFS,
Yes, I always cover Macfarlane (LON:MACF) and it's one of my top watchlist picks for this year. Am working on it now - section should be up by about 08:30
Regards, Paul.