Small Cap Value Report (Thu 23 June 2022) - VLX, WINE, LIO, IBPO

Good morning, it's Paul & Graham here.
Agenda -
Paul's section:
Volex (LON:VLX) (£379m) (I hold) results for FY 3/2022 look strong, and the valuation modest. Outlook comments are also surprisingly perky, with a strong start to FY 3/2023 indicated, with high demand & orders. Inflation is being passed through to customers. There's lots to like here, it's one of my favourite value/GARP shares at the moment. Patient, long-term investors should do very well on this, I reckon - with both earnings growth, and a higher PER possible once markets are through this current bear phase.
Naked Wines (LON:WINE) (£146m) - FY 3/2022 results don't look good - it's not making any profits, and growth has stalled, including forecast growth for this new year. Balance sheet is OK, but there is a cautious going concern statement. I'm worried that some customers might cancel wine subscription services, so WINE could be running to stand still. Not an attractive share at all, in my view.
iEnergizer (LON:IBPO) - readers flagged up sparkling results from this IT/outsourcing group. It looks highly profitable, and reasonably priced. But the CEO owns 83%. It's also up for sale at the moment, in bid talks. An intriguing situation for sure.
Graham's section:
Liontrust Asset Management (LON:LIO) (£610m) - Final Results yesterday showed an excellent performance in FY March 2022. However, the share price has been sliding lower for months as general investor sentiment has soured and Liontrust funds, with significant exposure to richly-valued US shares, have underperformed. The LIO share price decline has brought it arguably into value territory.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Volex (LON:VLX) (I hold)
240p (yesterday’s close)
Market cap £379m
Volex is a long-term holding for me. It was initially a strong turnaround, but is now acquisitive, bolting on reasonably priced businesses in the same sector (electrical power products & cable assemblies). So far, Exec Chairman, Nat Rothschild (24.5% shareholder) seems to have done a cracking job.
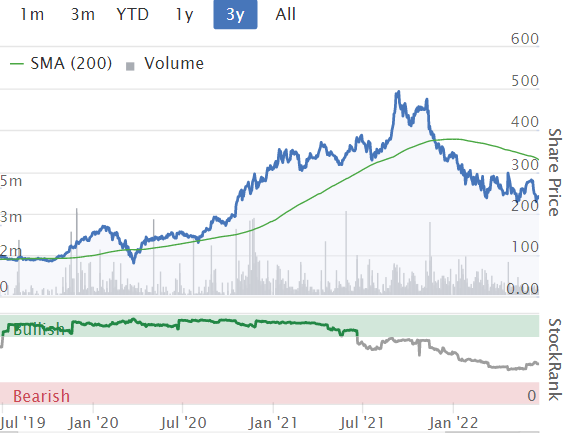
Despite putting out impressive trading updates, and constantly reminding the market that it is able to pass on cost increases through flexible contracts, the share price has sold off in this current bear market. Is this fall justified, with tougher times ahead, or is Mr Market irrationally depressed, and offering us a buying opportunity?
.
As I made clear here on 20 April 2022, with a positive year end (FY 3/2022) update from Volex, I’m firmly in the bullish camp, and wish I had some spare money to buy more now.
Here’s my quick view on an initial skim of the key numbers & outlook comments (I’ve printed off the full announcement to read at a more leisurely pace later) -
(reporting in US dollars)
Revenues up 39% to $615m (so a sizeable business now)
19% of revenue growth was organic - very impressive. Note that Volex has positive exposure to growth areas, particularly cables for electric vehicles, where revenues almost doubled to >$100m. Also pent-up demand from the medical machines sector. Industrial, and data centres are also positive sectors, so Volex seems to be in a good place, with favourable sector tailwinds, a positive antidote to darkening macro clouds in my view.
EPS fell, but that’s because of last year’s negative tax charge, which we already knew about, so no surprises there. Underlying EPS rose 6.3% once this tax effect is stripped out.
Underlying diluted (for share options) EPS was 25.2 US cents, or 20.6p in sterling.
Stockopedia shows 25.9 US cents broker consensus, so a slight miss, but a note from Liberum this morning says the results are ahead of its expectations. So I’ll probably just view it as in line.
PER is 11.7, based on FY 3/2022 actual EPS of 20.6p - that’s great value for a resilient, growing group.
Of course, earnings are likely to continue growing (organic & acquisitions), and a new 5-year plan is announced, with a target to double revenues to $1.2bn by FY 3/2027, at a operating margin of 9-10% (similar to what is currently being achieved). Hence there’s scope for this share to double earnings, and I suggest, re-rate onto a higher PER than 11.7 also, giving the possibility that this share could double or triple in the next few years. Also bear in mind, it over-achieved against the last plan, and has established a track record for making good acquisitions, which is not reflected in the current valuation.
Cost inflation (copper, plastic & wages mainly) is passed through to customers, with a lag, since contracts already factor in price rises either quarterly or annually. Copper rose a lot in 2020 & 2021, but has more recently been falling. Volex took all that in its stride, so this share looks a lot safer than many investors imagined, with chat on bulletin boards often focused on the price of copper, and some people selling the shares because they wrongly imagined it would hit profits at Volex.
Outlook - looks good -
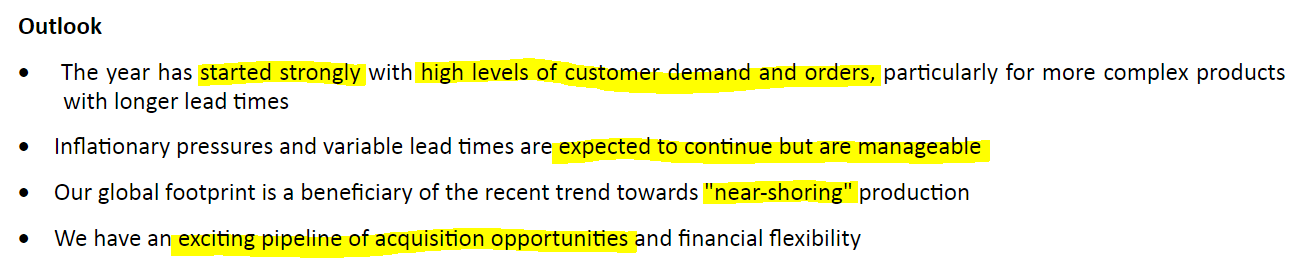
Broker forecasts - have been set quite low, with only a modest increase in EPS for FY 3/2023. Today’s update that the new year has started strongly, and the benefit from 4 acquisitions made in FY 3/2022, suggests to me that the risk of a profit warning from Volex looks relatively low.
Balance sheet - net debt has shot up to $74.4m, to fund acquisitions, but is not alarmingly high. NTAV is fine, at $78m.
My opinion - there’s a lot to like here. Macro worries, and investor fear, seem to be throwing up bargains right now - we’re finding new ones almost every day here at the SCVR.
Volex is performing well, has tailwinds from growth in its key markets (especially EVs), is passing on cost increases to customers, and clearly has excellent management with big skin in the game, delivering well on its expansion plans. Yet we can buy this for a PER barely into double digits - that’s a clear opportunity in my view.
Once markets are more settled, then I imagine this share could be 50% higher than it is now, and longer term, considerably more than that, due to the organic & acquisitive growth. Unless something goes wrong (which is always possible), then this looks a very attractive GARP (growth at reasonable price) share right now.
As with everything, I’ve no idea what the short term share price is likely to do, as that’s sentiment-driven.
.
Naked Wines (LON:WINE)
198p (down 31% at 09:36)
Market cap £146m
A painful day, indeed year, for suffering shareholders in this subscription wine business.
Results for FY 3/2022 are out today.
As with most eCommerce businesses, it had a huge surge in demand in the pandemic, but is now struggling to demonstrate further growth (+5% this year, +78% prior year). That could provide an opportunity maybe, if growth returns this new year, on a longer-term structural level, rather than boom & bust growth in the pandemic. So the outlook comments are all-important.
Revenue £350m (up 3% reported, up 5% in constant currency, against tough comparatives during the pandemic)
I’ve never accepted the “Contribution profit” number, which is fantasy in my opinion. FWIW, this is £79m, and is meant to show profit from established customers.
That all disappears, due to heavy marketing spending, to win new customers (or replace churn, more like), so adj profit before tax is negligible at £3.0m (LY: £(0.5)m) - the business is effectively running at breakeven, and marketing spend is flexible, so can be dialled up and down as required.
Note the 5-year forecast payback for new customers has fallen to only 1.5x, which concerns me greatly. It looks as if the £41.3m “investment in new customers” is not good value for money. Guidance is for a reduction of £5m in this spend in FY 3/2023.
I’m also sceptical of the “Standstill EBIT” figure of £21.2m, which has fallen by almost half of last year’s £39.3m - so questions about the business model are growing.
UK sales are expected to be “relatively flat” in FY 3/2023.
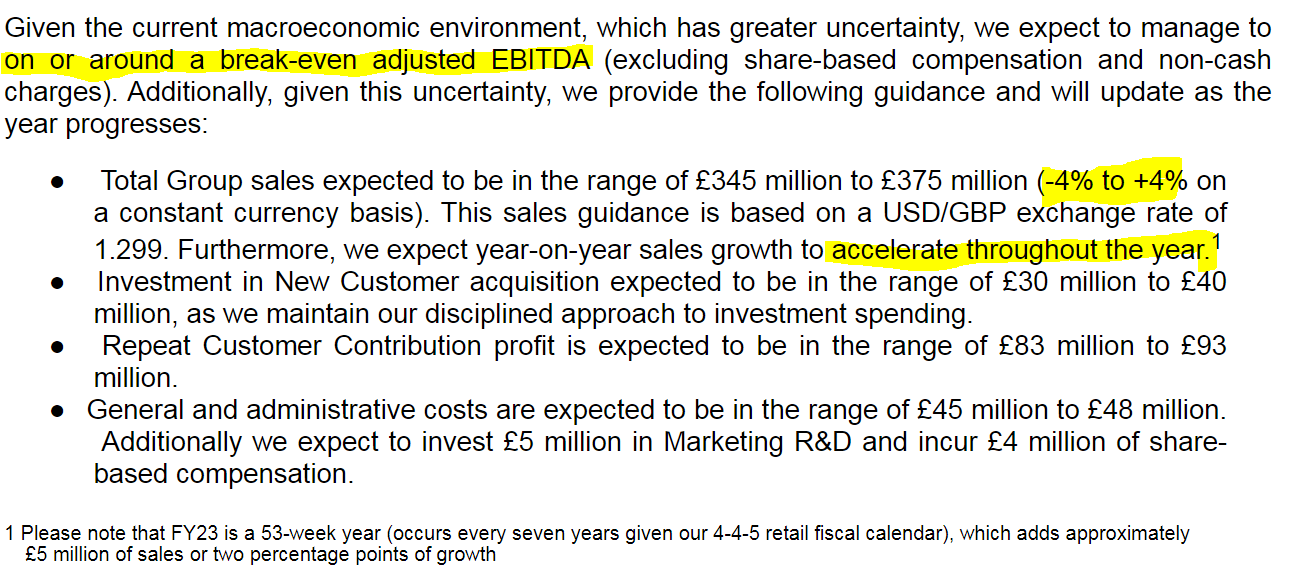
Guidance - detailed, but shows the business is now effectively ex-growth - which I could accept last year (due to very tough pandemic comparatives), but not for this year, when structural growth should be returning. WINE doesn’t expect that to happen, despite the huge marketing spending (although to be fair, the consumer macro position is bound to be less favourable for discretionary spending like a wine subscription) -
.
.
Going concern note - flags a “material uncertainty”, in downside forecasts, although the company does point out it has options to reduce things like marketing spending, and reducing inventories. I’m not overly concerned about this, because the balance sheet looks fine for now. But if future performance drops heavily (possible as consumers often cancel subscriptions when incomes are squeezed), then I would start to get worried.
Balance sheet - looks OK for now, with NTAV of £76.5m.
Remember that if business does decline, then the benefit of receiving cash up-front from customers (reflected in cash, and deferred income creditor) would shrink, which could put pressure on the cash position.
My opinion - online, subscription businesses for discretionary purchases strike me as possibly one of the worst places to invest right now, as consumers retrench.
I’ve tried out Naked Wines, twice, and it’s clever the way they hook you into a regular monthly payment, but I’ve recently cancelled it. The wine was OK, but nothing special. Connoisseurs might like all the stuff about choosing vineyards, etc, but I can’t see the point for most people. Just looking at the reviews on Waitrose seems to me a quicker and easier way to find nice wines, for the vast majority of people. Or just buy lovely wines from Aldi/Lidl, which are cheap, and generally very good.
I suppose the key question is whether WINE is now cheap, and hence worth a punt? Is it cheap though? £146m market cap, for a business that isn’t making any profit, and isn’t growing now either, doesn’t look cheap to me at all.
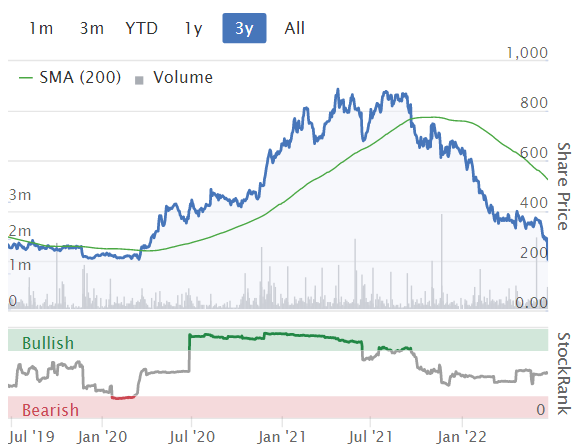
So definitely not for me, despite the 75%+ share price fall from last year. It wasn’t worth the previous lofty valuation, in my view.
If growth does resume later this year, then WINE shares could be worth revisiting. For now though, I don’t see any appeal.
.
.
iEnergizer (LON:IBPO)
508p (up 13%, at 10:48)
Market cap £967m
Many thanks to ridavies and DAZZA64 for flagging sparkling results today from this share, which for some reason we missed here at the SCVR, despite it now having been a 40-bagger since 2016! What a pity, and apologies I somehow overlooked this company, no idea why.
Researching it from scratch, the company’s own description of its activities is of almost zero use, what on earth does this mean? -
iEnergizer, the technology services and media solutions leader for the digital age… a unique, end-to-end digital solution enabler.
It then gives a more detailed description, which I’m still finding very hard to understand or visualise. Maybe you can understand this? -
iEnergizer is an AIM quoted, independent, integrated software and service pioneer. The Company is a publishing and technology leader, which is set to benefit from the dual disruptive waves of big data and the cloud in the digital age. With its expertise and cutting-edge technology, iEnergizer is uniquely positioned to facilitate the transformation to a digital world and support clients in this transition.
iEnergizer provides services across the entire customer lifecycle and offers a comprehensive suite of Content & Publishing Process Outsourcing Solutions (Content Services) and Customer Management Services (Business Process Outsource) that include Transaction Processing, customer acquisition, customer care, technical support, billing & collections, dispute handling, off the shelf courseware, and market research & analytics using various platforms including voice - inbound and outbound, back-office support, online chat, mail room and other business support services.
Our award-winning content and publishing services provide complete, end-to-end solutions for information providers and all businesses involved in content production. Our differentiation is in focusing on solutions and services that enable customers to find new ways to monetize their content assets, measurably improve performance, and increase revenues across their entire operation. From digital product conception, content creation and multichannel distribution, to post-delivery customer and IT support, we align ourselves with our customers as they streamline their operations to maximize cost-efficiencies and improve their ROI while connecting them with new, digitally savvy audiences.
On the basis that I have very little idea what the company actually does, I’ll let the numbers do the talking instead.
Anil Aggarwal (aged 61) is the CEO, and owns 82.6% of the shares! So everyone else is along for the ride, and what a ride it’s been!
On 9 June 2022 the company announced it is reviewing strategic options, and has entered preliminary discussions with BPEA Advisors Private Ltd about a possible sale.
There was an ahead of expectations trading update on 21 Feb 2022.
Annual Results - FY 3/2022
Revenues up 32% to $265m
Profit before tax up 56% to $83.2m - that’s a staggeringly high profit margin of 31%, so whatever IBPO does, it clearly has immense pricing power.
EPS of $0.39, converts to 31.8 pence, so the PER is 16.0 times - which looks great value, if you think profits can keep rising strongly.
Balance sheet - is weak, with NAV of $58.6m, less intangible assets of $115.3m, gives NTAV of negative $(56.7)m.
There’s a fair bit of borrowings $9.8m current, and $129.9m non-current, offset partially by cash of $56.3m, giving net debt of $83.4m. The company says net debt is $100m, the difference being lease liabilities of $16.7m.
Given the huge profits, then this level of debt, and the weak balance sheet, are really not a problem. They would only become issues if profitability collapsed, which seems very unlikely, given the track record.
Cashflow statement - looks fine to me. It seems a genuinely cash generative business, which since 2019 has been paying generous, and growing dividends. The forecast yield is good, at c.5%.
Outlook - sounds upbeat -
"Importantly, we have secured several new customers across each of our divisions, as well as maintaining and deepening relationships with our existing key customers. The business has maintained a successful focus on recurring revenue streams, by capitalizing on iEnergizer's advantageous position to service existing and new customers' needs in the evolving digital technology landscape.
"The first three months of fiscal 2023 have started well, continuing the recent positive trend, with extensions of existing contracts.
"With iEnergizer's solid foundation, its proven strength in operational execution, new sales initiatives, differentiated offerings, healthy balance sheet, and with substantial opportunities for further growth identified, the Board is confident in the Company's continued growth path as a unique, end-to-end digital solution enabler."
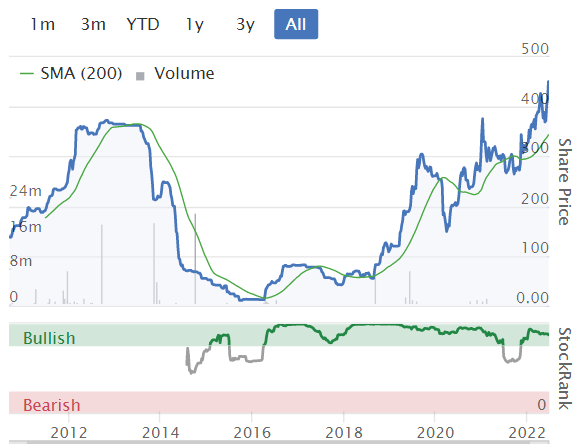
My opinion - what an interesting company! I’d like to learn more about the history, in particular what caused the share price to collapse from 2013 to 2016, then recover in spectacular fashion, as a major multibagger since then? Looking back at the 2015 results, they were poor, and the group was swamped by excessive net debt. Hence probably why the equity was so bombed out. There's since been a geared turnaround, with all the benefit flowing to equity, in a major multibagger. Just shows, every now and then, a really risky, highly indebted company can deliver a stunning result for shareholders who are prepared to risk a wipe out.
The ownership structure obviously means that the CEO can do anything he wants, with over 75% of the shares, which is a risk.
If current bid talks fall through, then there could be a risk the share price might give up some of the recent gains.
Or a bid might come at a nice premium, who knows? IT companies do seem to attract high prices when bids occur.
Overall, very interesting. It’s too soon for me to form an opinion on it, but the numbers look fantastic, and valuation quite modest.
.
.
Graham’s Section:
Liontrust Asset Management (LON:LIO)
£610m (+1% yesterday)
Good morning, everyone.
I’ve been looking at Liontrust today, as many readers are interested in it, and it was in the 2022 New Year NAPS. It released its final results yesterday.
One of the wonderful things about investing in fund managers is that it’s often quite easy to put yourselves in the shoes of the company’s customers: all you have to do is find the fund literature, and read it.
So I’ve been looking through the company’s funds. What really stands out, first of all, is the size of Liontrust’s “sustainable” funds.
Here’s a breakdown of the company’s AUM by category. You can see how big the Sustainable category is:
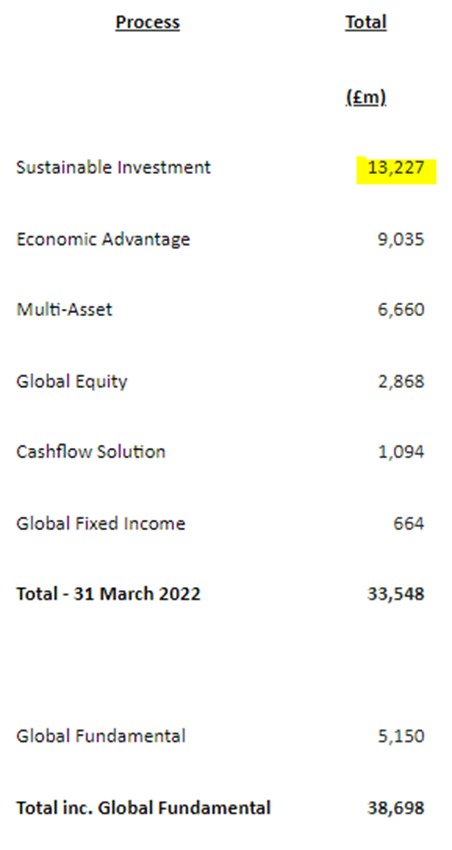
“Sustainable” is a word with many meanings, and Liontrust uses it in a variety of ways.
For example, its funds have invested in a childcare company because “better work-life balance” and “reducing stress for parents” is “part of a more sustainable future” (link).
There is a sustainable theme to go with every investment. The theme for investing in a bank, for example, is “saving for the future”.
The Sustainable Future Managed Fund is one of the most interesting funds at Liontrust – currently £2.9 billion in assets (according to the May factsheet).
This fund has two managers, one of whom is the head of the Sustainable Investment Team with over a dozen people reporting to him. The fund has in the region of 140 equity holdings, or around 160 holdings in total.
Personally, I find it difficult to keep track of my nine-stock portfolio. Keeping track of 160 holdings, while managing a team of fund managers? I don’t see how it can be done, except if the due diligence and research applied to each individual holding and potential holding is shallow.
I’ve looked up the StockRanks for many of the shares mentioned in Liontrust’s sustainable fund updates, or coming up in the lists of top ten holdings at these funds.
What I’ve noticed is that very many of the companies held by Liontrust’s sustainable funds are quantitatively poor value, and have a long way to go in order to prove themselves financially.
These ones came up on an initial survey:
· ADSK – ValueRank 13 .
· AMT – ValueRank 15.
· CDNS – ValueRank 10.
· DOCU – ValueRank 12.
· EQIX – ValueRank 10.
· ISRG – ValueRank 12.
· TMO – ValueRank 19.
· SPLK – ValueRank 7.
· SPOT – ValueRank 14.
· PAWN – ValueRank 8.
· Trainline (LON:TRN) – ValueRank 26
· Oxford BioMedica (LON:OXB) – ValueRank 30.
Many of these valuations are, in my view, hard to justify. Importantly, the ValueRanks shown above are calculated after the huge sell-off that has already occurred.
So if the value offered by these shares is going to improve, then many of them will have to sell off quite a lot more than they already have. Or else their financial performance is going to have to improve considerably.
Liontrust’s willingness to hold these richly valued shares has contributed to the weak performance of their funds in Q1 and what will likely be another weak performance in Q2.
Liontrust’s Sustainable Future Managed Fund is down 23.9% year-to-date (and note that this is not a pure equity fund – it’s a mix of equities and bonds). The pure-equity Sustainable Future Global Growth Fund is down 27% year-to-date (this is a £1.6 billion fund).
We’re writing a Value Report, and valuation is important to me. So personally, because of the poor value offered by so many holdings, these are not funds that I would want to own, and I wouldn’t mention them to my family and friends.
I’ve also looked at the long-term performance of the Sustainable Future Global Growth Fund, because it’s one of the most prominent pure-equity sustainable funds at Liontrust.
Against the MSCI World, a global benchmark index, this fund has underperformed on a 1-year view, on a 3-year view, on a 10-year view, and since its inception in 2001.
Why it matters
There is a long-term trend towards passive investing, as active funds fail to beat passive indexes. UK fund managers often focus on their performance against other funds, rather than against the index. It’s much, much easier to beat other funds than it is to beat a passive index!
In order to maintain relevance in a world where the default choice for investors is to own a passive fund, active managers need to have at least one of the following:
1. The ability to beat passive indexes (very rare).
2. The ability to access investments or structure portfolios that the customer can’t.
It looks like Liontrust’s main success, and strategy, is in marketing itself as a “sustainable” specialist, helping customers to own funds that they can feel positively about. It’s no surprise that ESG and “Net Zero” are mentioned so often.
These themes are incredibly popular right now, but will their popularity survive a period of high interest rates and a protracted bear market, when hungry investors give a higher priority to returns? I’m not so sure!
FY March 2022 Results
I’ve not said anything about yesterday’s results yet, so here’s a quick summary:
· Revenues +41% to £231m
· Pre-tax profit +127% to £79m
· AUMA (assets under management and advice) +8.5% to £33.5bn (before acquiring Majedie, with an extra £5.2bn).
Markets are forward-looking, of course, last year’s results aren’t considered particularly important. Liontrust shares are down nearly 60% year-to-date, despite the imminent announcement of these excellent growth figures.
Net inflows were positive for the year but there were net outflows in Q4 (Jan-March 2022), as investor sentiment soured. I assume that there will be more pressure on flows in the current financial year, given the overall trends in investor sentiment.
My view
It’s amazing how quickly the Liontrust share price turned from optimism to pessimism. I’ve remarked before that when you buy shares in a fund manager, you are buying a turbo-charged stock market investment: you will get inflows and rising profits in a bull market, and outflows and falling profits in a bear market.
The operational leverage at a fund manager plays a big role in this. Additional revenues tend to drop through to the bottom line very easily, without bringing many additional operating costs. Operating expenses were up 17% at Liontrust, which is significant, but revenues grew at more than double the pace, making it a much more profitable company.
But if revenues fall, this works in reverse, and profitability can collapse very quickly.

Ironically, after their steep decline, Liontrust shares are now offering decent value (ValueRank 65). There is now, according to the forecasts, a single-digit PE multiple. And if the share price falls much further, it’s possible that the PE multiple could fall below the dividend yield – another classic sign of a value stock.
Your view on the stock may depend on your belief in the longevity of the “Sustainability” theme. Would Liontrust be able to pivot to a new marketing strategy, if Sustainability was no longer considered important by investors?
In the short-term, I would be wary of continued poor fund performance. I find many holdings in Liontrust funds whose valuations, in my opinion, remain extremely vulnerable to further depreciation. Higher rates will wash out the remaining excesses in the US markets, and this may impact Liontrust’s funds more than their competitors.
I also have questions as to the extent of the due diligence and research that their fund managers can carry out, given the number of holdings in some funds.
Perhaps this has all been priced in, at Liontrust’s current share price? If I were a Liontrust shareholder, I’d be braced for at least a year of poor fund performance, with a big risk of outflows. But whenever the markets bottom and valuations have found a floor, investor sentiment will turn around again, as it always does.
I do think that the prospective risk/reward for long-term LIO shareholders is much better at 900p than it was at £20, and that the company can easily afford the dividends it has paid. So perhaps the best thing to do now is to think of it as an income play, and forget about the share price!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
Volex (LON:VLX) (no position)
There are a lot of positive points in the comments, so I hope people don't mind me throwing in a few negative ones:
Whilst this seems okay, the gross margin % is actually declining (FY21 (23.4%) ---> FY (20.5%))
I was trying to get my head around the numbers so I may as well share the below.
Here a 10 increase in Cost of Sale (80-->90) is passed through to the customer (so revenues go from 100 --> 110).
The gross profit is still 20, but the gross margin % has dropped from 20% to 18.18%.
And here's the company's own words:
Does this classify as passing on raw material cost increases? I guess it does, but I'd still prefer the GM% to not decline. The company make it seem like raw material price increases are having no impact on the business.
Note that my operating profit figure includes
a) adjusting items, which do not look like one-offs as they seem to repeat every year and,
b) finance costs
The FX rate movements are possibly working out in De-Ka's favour right now, but any retraction to the rates seen just 3 months ago - alongside the 20-30% increase in Turkey minimum wage this year, which is also scary - and this division could start going into reverse.
It's a sizeable part of the entire business.
I continue to be in 2 minds on this one.
Cheers
A
£IBPO I consider the Golden Rule of understanding a company , certainly applies here, Gobbledegook like that just puts me off. Why take the risk?
Great new photo Paul and Graham! But they (Stocko) need to change the one of the email that notify’s readers that the SCVR is published. :-)
Regards
Michael
Thanks Michael, I've flagged that up to HQ, re outdated picture on SCVR daily email.
Regards, Paul.
Thanks Michael, I've flagged that up to HQ, re outdated picture on SCVR daily email.
Paul,
Whilst they are at it, can they improve Graham’s body language on the new one! :-)
All the best, Si
Oxford Metrics (LON:OMG) interim results today, here's an overview video & podcast. In line with the plan, the 5 year strategy to achieve 2.5 times revenue growth and an adjusted PBT margin of 15%, as outlined at last year's Capital Markets Day is still in site. The brilliant sale of Yotta for £52m gives firepower for both organic and inorganic investments. The first half was supply constrained but still achieved 12% revenue growth although higher planned investment means the adjusted EPS and PTP were lower than the previous year. The outlook for the full year is in line with expectations, Vicon has unprecendented orders for H2.
Webinars coming up:
Next Tuesday 28th June, 11am IG Design (LON:IGR) will present full year 2022 results. A totally new team, Stewart Gilliland, Exec Chairman, Lance Burn, Interim COO and Paul Bal, CFO. Register here.
On 5th and 7th July, 2pm we have presentations by 6 Private Equity funds. Register for either/both LPeC events here.
Tuesday 5th July, 2pm with:
BMO Global Asset Management
Gimv
NB Private Equity Partners
Thursday 7th July, 2pm with:
Oakley Capital
CapMan
CVC Credit Partners
It will be interesting to hear how PE views the current macro backdrop.
Incidentally, Oakley Capital Investments (LON:OCI) announced today that they sold their stake in Facile.it a price comparison platform for £53m, at a 23% premium to carry value. Going forward OCI has £200m for deployment. I always think they look interesting but don't hold.
Thanks for this, Tamzin. I will certainly watch, as I did last year, which led to me investing in £BMO, NB Private Equity Partners (LON:NBPE) and £OCI. While I am saddened at recent price action, their NAVs have continued to perform, and I am even more convinced by their business models and am likely to drip feed more as time goes by. This three make an interesting balance of their overall sector, and I wonder if I'm mad to bother with small, individual PLCs with their stomach-churning volatility. Maybe these should make the core of everyone's portfolio. Given the consistency with which they are making realisations above book value, it's bonkers that they trade at 30-40% discounts.
Like the new SCVR Brand Photo!
If you both had sunglasses you'd look like the blues brothers - Highly appropriate for the current market :)
Thanks for the udpate on Liontrust Asset Management (LON:LIO) I am of the view that it was very overvalued before, but now looks too cheap. I personally wouldn't invest in their sustainable funds either, but long term performance remains strong despite a wobble this year. I have no doubt that ESG funds will remain in demand (not so much from retail investors, but institutional investors who are under a lot of pressure to demonstrate their green credentials). I think LIO are considered leaders in this area so should do well.
Worth noting that while the sustainable funds make up around a third of AUM they are not a one trick pony. The Majedie team are very much value investors, for instance. I think LIO are pretty well diversified overall.
On the point about monitoring 150 odd stocks - it does seem a lot but they will have a team of analysts, who will each cover a particular sector, so not too concerned about that. There are plenty of very successful funds that have very long lists of stocks, so it is possible to generate strong returns even with a long tail of stocks.
Just a reminder that this show starts in about 90 minutes....
Mello is hosting a FREE Investment Trusts and Funds virtual show on Thursday 23rd June at 12:30pm. https://melloevents.com/mello-investment-trusts-and-funds-tuesday-23rd-june-2022/
There will be a number of educational sessions in between each trust/ fund presentation and time for questions after each one.
The programme is as follows:
Programme
12.30 pm Mello welcome from Karin Schulte and presentation from Ocean Dial
1.05 pm Presentation from Invesco Bond Income Plus Limited
1.40 pm Moira O’Neill from Interactive Investor analyses how retail investors are asset allocating in 2022
2.00 pm Presentation from HarbourVest Global Private Equity
2.35 pm Nigel Hawkins presents on REIFs (Renewable Energy/Infrastructure Funds)
3.05 pm Presentation from TB Amati Strategic Innovation Fund
3.40 pm Mark Bentley presents his best performing income trusts for 2022
To register for free, please click here:
https://www.tickettailor.com/events/melloeventslimited/717089
We hope you can join us.
David
Thanks David,
The presentation about bonds was very interesting, I learned a lot.
Risk:reward looked so bad with bond prices high, and yields ridiculously low, that the risk of bonds crashing in price was glaringly obvious really, as interest rates & inflation rose.
In a way it also makes it a bit easier stomaching losses on equities, knowing that everyone else (bonds, bitcoin, etc) are also seeing heavy losses.
Just shows how complacent we got last year :-(
Regards, Paul.
I think the story of Naked Wines (LON:WINE) reflects what is happening in a lot of the retail landscape and wider
A lot of things seem to be increasingly 'bar-belled' (I got the term from N Taleb) compared to 10 years ago.
In the case of NW, there was Lidl/Aldi (cheap), mid-market (Majestic = NW), upmarket (Specialists like BR and The Wine Soc (big fan))
I have seen the mid-market shrinking
Aldi/Lidl have upped the quality so you can get nice wine at a good price
Majestic folded into NW and are not doing too well (and I bet the others are not doing well either)
The specialists cater for those who really care or have lots of money. Certainly TWS is doing ok.
The same appears to be true of clothing, v. cheap seems to be thriving and so does the high end.
And housing - houses in London (and other city centres) compared with the rest of the country
I would not be surprised if the distribution of share price performance over a year has become less bell-shaped than it was (more big winners and big losers).
It would be good to hear your views on Oxford Metrics (LON:OMG)
Hi Gerard88,
I've had a quick skim of interims from Oxford Metrics (LON:OMG) but don't have anything much to add to when we last looked at it. Trading in line with expectations.
The big development was the sale of Yotta, which we reported on here in May.
The most recent cash pile (after disposal proceeds received) is about half the market cap. So what happens to the shares depends on what mgt decide to acquire with that cash. Plus there's a decently profitable, growing business called Vicon. The commentary today sounds upbeat.
I quite like this, although uncertainty exists about what they do with the cash, so it partly unknown. Management seem shrewd, so if they buy something really good, it could get more interesting. Valuations are much lower now too, for tech companies, hence having a cash pile now is a good position to be in.
What's your (and others) view?
Regards, Paul.
Oxford Metrics (LON:OMG) (I hold - small position)
I was initially quite disappointed with today's results.
Cash generation was non-existent, gross margins look slightly lower than PY (calculating it gives different figures to their own published number - I don't know why) and EBITDA (which I calculated) is £1.7m, slightly below what I was expecting.
But then things got a little more interesting as management said that the company was in line to meet Market Expectations.
From the Progressive Report a couple of months ago (April 2022), Vicon revenues for FY22, which ends September 2022, are expected to = £32.4m.
That would be a remarkable H2 and given that there's only 3 months left of the year, I can't imagine the company will miss this.
My own rough workings are below, in which I've included a material ramp-up in OPEX in H2 for prudence.
So a company with an EV of c£67m should generate an Operating Profit of at least c£4m.
That's a tad expensive for this market, but perhaps not enough to make me want to ditch my small holding. Especially if more growth is coming via acquisitions, which should bring with it increased operating leverage (note that Head Office costs previously allocated to the now disposed Yotta are now included wholly within Vicon.)
It seems like a fascinating little company with high gross margins and plenty of cash to help it get through whatever is happening now/might happen in the next 12-18 months.
I would be interested in hearing from others as this is a relatively new holding for me.
Cheers
A
Hi abtan
Thanks for your note regarding Oxford Metrics (LON:OMG) in which I reached a similar conclusion. These interims and outlook are about as second half weighted as I can recall seeing. However, my own investment thesis (I bought in just after the sale of Yotta was announced) is based around the optionality provided by the cash pile upon which they now sit. Therefore, I shall reserve judgment until I see how this cash pile is deployed, hopefully supported by an outstanding second half.
Cheers
Simon
I was holding a few Volex (LON:VLX) but decided to sell today.
Muted response to the update, and the chart looks like it wants to break for another leg down.
The 76.4% Fib retracement may be where it finds a bottom, but thats a 25% drop from where it is now... too much for me.
I may be wrong, but this chart just doesn't look good :(
Tend to agree. Did not look a bad update from Volex (LON:VLX) but just think there are better opportunities out there following the recent marketwide sell offs. See more upside in the likes of Luceco (LON:LUCE) and MPAC (LON:MPAC) to give just two examples.
Thanks for posting that Breakout trader most appeciated - in some respects i can be an anti chartist at times as teh chart is only good till it changes and change in fincial update is always as good a time as any for the "trend" to be beaten. Having said that unless its a really high conviction play (i remember entering 888 when chart was terrrible) entering when there is a clear flow in one direction ref chart is clearly "going against the grain" - without knowing owt about charts it does seem that Fibs retracements do seem to be popular and pan out frequently - that would make sense if all then sheep are trading based on those known levels.
One question if i may - you have posted the 61.8% line on the graph - that level seems to have kinda held up until now - is that line an "actual support level using fib metrics" or simply a line drawn under the curent price or recent low showing how much it has retraced to date ?
Hi rmillaree,
The 61.8% level is drawn by the fib retracement tool, calculated automatically. I draw in the bottom and the top of the significant upwards move, and the retracement levels are plotted.
Price has been consolidating in that zone between the 50%-61.8% retracement levels.
The black line is drawn by me as a guide. If we break it, we may well head down to the next fib level at 76.4%. This is a common level for a significant correction to end... If it ends. Some stocks head down and stay down, but I don't think that will be the case with volex.
What chart does look good at the moment and how long does it last
See my 2 recent posts in the discussions section for possible answers to those very questions...
Alternatively, the 61% Fib level for Volex (LON:VLX) (I hold) could equally become support. Should the share price hit the 50% Fib line for the fourth time it might finally start to break out and then the 50% Fib line starts to become support rather than resistance. The truth is that nobody knows at this stage what will happen. I believe there will continue to be a bit more volatility in the market for another 3 months before Mr Market starts to see light at the end of the tunnel.
David.
Interim results from Oxford Metrics (LON:OMG) are in line - however, the line "Unprecedented level of orders-in-hand going into the second half" suggests that full year earnings could be better than in line.
Morning Paul and welcome back Graham,
These are challenging times for private investors but these are also the times where our decisions are of high importance, preventing us losing more money and laying foundations for future gains.
I often read that "it is too late to sell." Retrospectively, we all have experience of wishing we had sold at higher levels, but this is part and parcel of being a PI. I do not agree with the statement "it is too late to sell." You can only decide to sell when you realise you are no longer happy with a stock or your weighting in a stock, or maybe a macro decision. This can be a good time to rebalance as there are many excellent stocks are much cheaper than they were a few months ago. I often rearrange the deck chairs in these more challenging moments.
As investors, it is important that we are realists. If any of you have ever asked a black cabbie for directions, you may know he will often answer: "Well I wouldn't go from here..."
But we are here and this is where we start from.
Michael
Thank you Paul for your quick response this morning on Smiths News (LON:SNWS) which I should have said I hold.
You ask me to "raise a green blob". I am sorry but I have no clue what you mean! I admit there is still much I have to learn about Stockopedia and "green blobs" is one feature I see daily but
I do not know what to do. Sorry to sound a bit thick on this. Must be my age.
You ask me to "raise a green blob". I am sorry but I have no clue what you mean!
I suspect Paul means the green chat button at the bottom right of the screen. Open a chat and raise the issue. I've had quick responses the couple of times I've used it.
It just means click the green circle at the bottom right of the screen & let them know what you are not happy about. I have done it loads of times and it means that they will look into & try to fix the problem.
If you’re on a phone, click your logo in the top right-hand corner and select ‘contact support’
I agree with your views Paul, I was in this share during its rise towards the 500p level but locked in profits. I bought back in last week ready for a repeat performance!
Peter 171 What views? What company please?
Paul/Graham,
If it’s a quiet day today, I would appreciate your thoughts on Deepverge (LON:DVRG) (I hold).
They are a small @ c.£25m but have just posted very positive YE results today (especially revenue growth) and are about to become profitable for the first time.
Many thanks,
Chris
Chris, I too thought the £DVRG; results look good, but they are finals and for the year ending in Dec and not adding much to the trading update on Jan 11. I was thinking of buying but the share price has gone bonkers this morning - up 10%, now down 6% - which leaves me wondering what the real position is and whether the sp is going to slide further. There is much to like about the company. My main reservation is that the two sides of their business - Skin lab and Modern water - look to me that to have no synergy.
Paul
thanks for your report as ever - I was wondering in these horrific times if you and others had a to[ 10 of beaten up shares which have been subjected to a sell off but maybe should not be as low as they now are. I guess Boo Hoo would be one although is ASOS a better bet with the governance issues still hanging around? Anyway be interesting to see everyone’s thoughts
Hi Cleeve. I'd be interested in Paul's Top Ten Battered Stocks. I am sure we don't want 100 subscriber's views on this but if I get in first, here is my list (I own several of these and have the others on my watchlist):
Hostmore (LON:MORE)
Reach (LON:RCH)
National World (LON:NWOR)
Joules (LON:JOUL)
Lords Trading (LON:LORD)
Supreme (LON:SUP)
Marlowe (LON:MRL)
Somero Enterprises (LON:SOM)
Tremor International (LON:TRMR)
Volex (LON:VLX)
As a cheeky extra, I am very tempted with Molten Ventures (LON:GROW) as a beaten down play given their recent announcement that their NAV is worth double their share price now!
One of the reasons why the SP of quite a lot of PE and especially Molten Ventures (LON:GROW) are suffering at the moment is that the NAV is THEIR OPINION of what is the NAV. Many of the investments are in non quoted companies and frankly you could come up with any figure. Id be interested if they have an independent valuer. Whatever, the market has written down their shares massively on the basis that THE MARKET doesn't believe in their NAV valuation!
Totally agree. I would want to know the basis for the NAV - everything they have floated is down significantly (Cazoo, Trustpilot, Ui Path) but fortunately the not listed, hard to value, less transparent parts of the portfolio have more than compensated to result in an increase to NAV for the last reporting period. This is despite the significant retrace in the Nasdaq and likely (but less visible) pullback in the technology PE / VC space. I think valuations take a lot longer to catch up - it's easy to avoid a downward valuation if there hasn't been a funding round for a private investment. Most of the portfolio is early / mid stage technology that is not yet cashflow positive or profitable after all costs are taken into account (i.e. net profitable). It's relatively easy to be profitable at the gross level.
Hi BritishPat
I have sizeable holdings in Somero Enterprises (LON:SOM) Volex (LON:VLX) and £SUP
All well and truly battered as are most of the other 25 small caps in my portfolio. One day it will change but until then need to be patient or should I say very patient.
All the best
Cleeve,
The best place to look for the big risers in the next bull market is those stocks that have gone up the most over the last year or 6/3 month period. The dogs of the last bull market rarely do well in the next. I was dumb founded to read "Stocks and Shares Simplified" (think that's the title) in C1992 to find that this was true. It being the pre-internet era I went up to London to the National Newspaper Archive and looked at the microfiche of the shares pages from the Times and proved it was true to myself. A basket of the top 30 (by price appreciation) shares for the prior year always outperformed the indices (he used some sort of moving average of these shares to time the entry so that you weren't investing in a downtrend). I still am prone to thinking something that has gone down by >50% may be a good bet but it is always better to wait until a stock has based over a few months and is rising above it's 50 day MA. I think we are in a market where is is best to leave "the first 10-20%" to the other guy to ensure you are not buying into a bear market rally.
I am disappointed with Stockopedia that they have not updated the data for Smiths News (LON:SNWS) which I hold with the result that the Z Score is materially wrong.
When Smiths News (LON:SNWS) published their Interim Results for the Half Year to 28th Feb 2022 the net debt dropped from £81m to £38.8m.
Paul I wonder if you can use your influence with Stockopedia who I rate highly to get the numbers updated to give a more accurate picture of this Company which potentially could be debt free by 28th August 2023. and certainly by 28th Feb 2024.
I am disappointed with Stockopedia that they have not updated the data...
I'm glad its not just me that finds this aspect of Stockopedia so irritating. Surely timely data is important to them? The Smiths News interims were released on 4th May and it is now the 23rd June and the Stockreport has not been updated.
I'm glad its not just me that finds this aspect of Stockopedia so irritating. Surely timely data is important to them? The Smiths News interims were released on 4th May and it is now the 23rd June and the Stockreport has not been updated.
I agree. I've complained on more than one occasion and been told the problem lies with the data provider, not Stockopedia. That doesn't make it right of course - it's rubbish for a service you are paying good money for and it means StockReports can be totally misleading (sometimes for up to 3 weeks for many small caps discussed here) and many screens etc. will give false results. Must admit the stale Smith News SR is a new record though!
All the best, Si
Must admit the stale Smith News SR is a new record though!
Nowhere near a record! Good Energy (LON:GOOD) released final results on 29 March, the Annual Report was published on 28 April but it wasn't until 31 May that the StockReport was updated to reflect the results.
Hi portugull,
If you spot something that looks wrong in the data, just raise a green blob. The HQ team at Stocko are highly responsive to green blobs,
Although in this case, I have a feeling that Z-scores might be calculated on annual accounts, not interims.
As with all indicators, ratios, etc, they're just an initial guide, then we have to do our own research. As you (and I, in SCVRs) have spotted, SNWS is a turnaround, where previously problematic debt has been reducing, divis reinstated, etc.
So in the real world, bankruptcy risk looks low, so the Z-score is lagging behind.
Z-scores do give weird results sometimes, so it's not something I personally use very much, because I can do my own more detailed balance sheet analysis. But for non-accountants, or people who are time poor, it's a very good starting point. Especially at the moment, with interest rates rising, and the economy slowing - which will increase insolvency (or heavy dilution) risks.
Regards, Paul.
While Stocko is a superb research tool, the data quality is often quite poor, due to being very stale. I'm not sure if it's Refinitiv or Stocko that is to 'blame', but it materially detracts from the platform.
If any improvements can be made here it would certainly help the part time investor who doesn't always have the time to undertake the thorough research or at least not straight away. Often a company will raise cash and the Stocko data is still showing the old cash balances for example. Profit and loss forecasts can also be way out and so not adding to confidence when considering purchases or sales. If we are having to undertake that kind of research ourselves all the time then it kind of defeats the purpose to some extent of a service like this. Just my thoughts.
Hello Paul would you have a look at iEnergizer (LON:IBPO) with results out this morning. According to Stocko figures, the company seems to be progressing really well and good value. I have two negatives witch are the company is very largely owned by the principal shareholder, the CEO, and the debt figures seem to have grown significantly in the last two years. Otherwise, the figures look very good and the PE is modest.
iEnergizer (LON:IBPO) is investigating the possible sale of business. The results look good.
· Total Revenue up 32.4% at $265.2m (2021: $200.3m)
· Service Revenue up 32.8% at $260.3m (2021: $196.0m)
· EBITDA up 51.3% at $97.3m (2021: $64.3m) representing an EBITDA margin of 36.8% (2021: 32.1%)
· Operating Profit up 58.5% at $91.3m (2021: $57.6m)
· Profit Before Tax (PBT) up 55.5% at $83.2m (2021: $53.5m)
· Profit After Tax (PAT) up 52.3% at $74.5m (2021: $48.9m)
· Earnings per share up 50% at $0.39 (2021: $0.26)
· Net debt of $100.0m (2021: $115.9m)
· Total dividend of 21.92p per ordinary share ($52.8m) (2021: 14.12p) including interim dividend of 8.12p, an increase of 55%
Morning ridavies,
Thanks for flagging iEnergizer (LON:IBPO) - am not sure why, but I've not covered this one before, but the results look stunning, so I'll try to check that out later this morning.
Regards, Paul.
the high increase in debt for IBPO was £100 mill which was then paid out as a special divi 50p per share if memory serves i currently hold
Paul Scott - just looking for your view with respect to Volex versus Luceco. Similar companies in some respects. ROE, ROCE, Operating margin all superior at Luceco, Earnings yield also significantly higher at Luceco - just the outlook that's a little different - would appreciate your view if you have the time. Thanks.
Hi drkelly1975,
I think both Luceco (LON:LUCE) and Volex (LON:VLX) are good businesses, well run. The big problem with LUCE is that its stellar performance in the pandemic turned out to be pulled forward demand, which has since reversed. Also, it troubles me that mgt at Luceco didn't realise this, and in particular only said afterwards that customers have been building up their own inventories of LUCE products, so that's now unwinding, causing LUCE profits to plunge. I reckon forecasts for LUCE are still too high, and it wouldn't surprise me if it issues another profit warning.
Whereas Volex has had none of those problems, and earnings forecasts have remained remarkable static at VLX, and the outlook confirmed today is positive.
Therefore, for me, it's a no-brainer - VLX just looks a better business, with more sustainable earnings than LUCE. That said, they've both fallen so much from the highs, that both look interesting as long-term investments.
Regards, Paul.
Thanks Paul. I think you could be right re another profit warning - I may wait a little before making a decision. If there is another it will likely overshoot on the downside to Luceco could offer even greater value than currently.
Many thanks Paul for your initial thoughts on £VLX. I also hold.
It will be interesting to hear of any additional observations after you listen to the webinar on
www.investormeetcompany.com
All the best
Hi jonno,
Just reporting back on the Volex (LON:VLX) (I hold) webinar. It was useful, with mgt talking through this slide deck (well worth a look).
Some of the Q&A were interesting, including a query about the share price. Nat Rothschild emphasised that he's never sold any shares, and holds about 25% still. He said that taking a long-term view, he sees Volex shares as "incredibly undervalued".
He emphasised that since 2016, new mgt has turned around the business comprehensively, from only achieving around breakeven, to now generating an operating margin of about 9-10%. He paid tribute to the "brilliant management team" throughout the business, who have achieved this.
Personally, I think anyone selling today is nuts & just not thinking straight. But, bear markets cloud peoples judgement, because of the pain of running losses, and fear of further declines. Yet longer term, these are the best times to be buying.
What I particularly like about Volex, is that it has demonstrated it can pass on cost inflation, and has demand tailwinds from pretty much all its sectors, and further tailwinds from customers wanting to bring production of parts nearer to them, due to supply chain problems. Hence I reckon this is probably the least likely share in my portfolio to issue a profit warning, indeed I reckon it could beat current forecasts. Yet we can buy it on a PER of not much above 10. That is so attractive to me, with my long-term, value/GARP hat on.
Regards, Paul.
I also thought the Volex (LON:VLX) presentation was good.
One point mentioned several times here was covered and that was tax - Underlying basic EPS before tax improved by 20% - see slide 11 or for more detail watch the recording (IMC usually get these up fairly quickly).
Two things covered that have not been mentioned here -
Collapse of Turkish currency - goods in and out nearly all paid for in $ or Euro so only concern is workers' pay, which is more to do with inflation (the last figure I saw was 73.5%).
Noted that following supply problems (particularly containers from China) those supplied preferred manufacture to be nearer home. Volex is proud to be ahead of others on this with manufacturing sites spread out globally.
Hi sharw,
Ah yes, I forgot to mention the Q&A re falling Turkish currency. You're right, Volex (I hold) reassured on this in the webinar, saying most costs & revenues for its Turkish operation are denominated in Euros. The big cost in Turkish currency was wages, and the increases in wages tend to be offset by the depreciating Turkish currency, thus having little bottom line impact.
As you also mention, people seem to have been spooked by the fall in EPS, yet this was simply due to the corporation tax normalising (last year had a tax credit that boosted PAT, due to recognising a deferred tax asset). This is just numpties, selling the shares because they weren't paying attention to an obvious factor that was flagged well in advance, and fully included in broker forecasts!
With solid results, and a very positive outlook statement, Volex shares should have risen strongly yesterday. Instead they fell! That's totally illogical, and a buying opportunity created by panic/fear, and irrational selling, in my opinion.
Regards, Paul.
Sureserve you can buy at 81.79 and sell at 82.1 .
Trying to figure that one out ??
Deleted, already covered earlier.
Thank you Paul re Volex, we hold and topped up when the market opened but had to pay the early mark-up.
I was lucky as missed the market open and just bought at 235
I'm not sure it adds any value here, when people feel the need to announce their trades, but without any supporting information or views!
(no offence intended, but it's worth bearing in mind that thousands of people are ploughing through these comments, so best to keep it concise & meaningful if possible please!)
With Volex (LON:VLX) the results look amazing and if their 5 year plan is executed this is a great long term prospect at a great price. The bit that doesn't seem to be covered off in detail is: "FY BASIC EARNINGS PER SHARE FELL 24.3 PERCENT TO 0.193 USD"
Is this down to acquisition costs and amortisation of intangibles?
Volex (LON:VLX) "Basic earnings per share were 19.3 cents (FY2021: 25.5 cents), a
decrease of 24.3%. Before tax, basic earnings per share increased, but
due to the recognition of a significant deferred tax asset in FY2021
basic earnings per share after tax decreased in FY2022."
RE: Volex (LON:VLX)
Before tax, basic earnings per share increased, but due to the recognition of a significant deferred tax asset in FY2021 basic earnings per share after tax decreased in FY2022."
True, but what does that mean?
They brought forward a big tax credit last year, which would have boosted EPS. I had a look at last year's results and they weren't making a big point about this not being real earnings back then - in fact it's hardly mentioned at all. Take your own view on that.
If we ignore the mystery of the tax system it looks OK, given the circumstances. We have revenue up a lot, cost of sales up a lot, operating expenses up, PBT up a lot, debt up a lot. On the cashflow - operating cashflow down a lot and a significant decrease in cash overall, working capital up a lot with a significant increase in inventories. The latter is explained as, unsurprisingly, being needed to handle supply chain disruption.
Decent results given a difficult situation.
timarr
Hello CamRaid, I see the footnote in Volex (LON:VLX) about one off tax benefits in last year's figures.
Volex (LON:VLX)
FY BASIC EARNINGS PER SHARE FELL 24.3 PERCENT TO 0.193 USD"
Camraid
is this down to acquisition costs and amortisation of intangibles?
The biggest elephant here is the tax charge as mentioned by slopsjohn - tax this year $5.8 mill compared to last year minus $9.5 mill - so the basic eps clearly gives a very false picture of underlying trading due to the wonky tax.
Company confirm this when they say
"Before tax, basic earnings per share increased"
You are right though ref amortisation that has knocked the figures too - being $10 mill this year compared to only $5 mill last year.
Acquisition costs also $2 mill higher so yes that affects the figures too.
Note both the above 2 amounts are excluded from the "underlying figures" - probably part of the reason why they use underlying figures as their go to numbers
Rather depressing AGM Statement from Tandem (LON:TND) today packed full of cautionary words and phrases:
"trading in the current year began slowly", "Trading in the 24 weeks to 17 June 2022 has remained challenging", "own brands were behind", "bicycle sales were disappointing", "demand has now diminished", "higher stock levels than we would like against a backdrop of overstocked customers", "disappointing results", "Home & Garden division has also seen a decline", "outlook for the remainder of 2022 remains challenging", "customers cancelling and delaying orders", "much uncertainty in the market".
Crikey, I imagine such gloom is a foretaste of what must be coming down the line from many businesses, especially consumer facing and discretionary purchase retailers.
The SP has not yet retraced to its March 2020 low but perhaps today's undoubted step down will hasten the move back there.
For the brave it might soon be an opportunity to get a discounted piece of the longer term e-mobility growth story. The note today references the forthcoming legislation to fully legalise the use of privately owned e-scooters as part of a new transport bill which led to a boom in France when the same thing happened.
I don't hold but I'm happy to keep watching to see where the SP eventually settles.
Cenkos note out this a.m. unhelpfully does not have 2023 forecasts but gives adj eps of 22.2p for 2022 (lots of 2's), putting it on 11.7 x at 260p.
I posted on Tandem a while ago along those lines .
Bicycle market brutal with MASSIVE oversupply coming into a very soft market .
It’s going to take 12-24 months to unwind and work through the stock levels .
You will see a lot of brands disappear especially the smaller newer ones that don’t have the resources to ride it out and they will simply Chuck the towel in .
I had a long conversation with one of the high profile niche brands last week , working their arses off , struggling to get components. Needing to lift prices (they were already top end ) yet no customers . These guys making making a tough living but doing something they love for less than the salary of basic pay rate .
Tandem can ride it out for sure and have cash and assets , IF they were smart, aggressive, agile and on the money they could play a very smart “rope s dope” game here and win big time .
But they are not those things and they have no ambition or entrepreneurial ability so they will plod on in their day to day comatose state taking their director salaries and failing to see the opportunity .
To be fair it takes a private business owner unrestricted by the needs of shareholders for growth and profits to adopt what I called the rope a dope tactic , a stock market listing doesn’t allow a company to do it .
- Sit back
- get your stock very lean
- keep your overhead very tight
- at best maintain sales but don’t be scared to let them slip
- hold margin on current product
- clear all non performing inventory even at low margin / loss
- build up the cash pile
- do the day job only , improve operational excellence .
Then wait for the leveraged high profile growth hungry brands to fall over and you can do sone very smart acquisitions .
As I say impossible to see a PLC getting away with this but it’s the best tactic in the perfect storm the bicycle guys are in .
They have got it worse than most industries as the excess of the covid boom has caught this massive tidal wave tsunami effect . Problem is they ordered the tsunami 18 months ago and it’s only just arriving .
Supply@Me Capital (LON:SYME) annoys me everytime I see an update. It is everything that is bad about fintech. People wasting investors money.
I held Vokex previously but am currently very unconvinced .
The issue for me is that the “5 year strategy” of growing from 600 million to 1.2 billion usd turnover at 10% profit , even if achieved would not make the share as attractive as other opportunities we have .
Margins - very hard to see margins being maintained at historic levels even if as the company claims increases are passed on. They then qualify this by saying there is a time lag in this so it’s only half true .
Doubling turnover - sounds fantastic on paper but includes acquisitions and does not say how much by organic growth at good margin and how much by acquisition. Acquisition with dilution and no improvement is margin ration is vanity not sanity .
I think volex is starting to get to a size where it has limited upside even if it achieves its goals and manages somehow against the tide to maintain margins in a sea of price increases of material cost and wage inflation .
The very simple question is -
If it got its 5 year plan and became a 1.2 billion turnover making 100 million usd profit with either dilution or debt to fund sone contributing acquisitions what share price / valuation / PE does it get .
After this 5 year plan is delivered what is the next 5 year plan .
The smart thing to do here for shareholder value is increase margins and efficiency and be lean and mean .
Having said that great company in a great sector but I think it will end up a bigger company with a lower PE and it’s actual valuation ratios by definition must trend downwards .
Just playing devils advocate as it is owned by a lot and was a bull market runaway hotshot .
For me it’s not far off the correct price for now and I do think it will get to 1 billion but the big beneficiary will be the ego of Rothschild and not the ratios and value metrics of shareholders .
Todays results from Naked Wines (LON:WINE) show a coming of age for me. Growth is a little stunted but that needs perspective. As an online retailer that benefitted enormously from lockdown they have still managed to grow after that.
They have addressed supply chain issues, have a customer acquisition strategy that is proven, have strong current assets in cash and inventory and are well placed in the US which has the largest DTC wine market.
I know Paul has his doubts on this business but I think it is a good model and great underlying cash/profit generation. Customer retention is amazing. Given this in a year after the end of lockdown I think this is a great set of results for an online business.
Me too - have absolutely backed up the truck this morning. Insane price levels. On no reading of the results or nearly any future scenario, should Naked Wines (LON:WINE) be worth a fair bit less than it was in 2019
Volex (LON:VLX)
Quick skim read through of the results and it seems to tick all the right boxes other than perhaps debt being more than I would like - they have been acquiring new business though so it is what it is in that regard . Particularly like their comments about doing more complex jobs and their global footprint helping ref near shoring being the way to go for now.Seems clear to me they are in fine fettle and the stuff they do must be adding value to what their customers get - it’s clear they have a moat. New upgraded plan ref sales and margins - I have remained on sidelines probably waiting for shares to become a bargain and with todays upgraded long term plans it seems like the time is now other than the fact I don’t have a huge pot of cash waiting to be invested.
My first instinct was that this has a good 15% bounce this morning and so was looking for a buy or trade. The concern for me is that debt increasing and the free cashflow is negative (from a skim of accounts). Some of the problem is working capital movements which I sometimes ignore as a timing issue, but the size of investment is still higher than operating cashflow if I ignore working capital. Hopefully this means the investment will provide growth, but need to be careful here.
Greyster
Volex (LON:VLX)
Very sensible comments greyster - their plan will work if the businesses they are acquiring add value to the group aftre acquyisition. They simply should not be expected to grow at this lick without piling on some debt too . To me i get the ipmression that they have critical mass and that things are trending in the right direction albeit you cant expoect new acquisitions to have the bells and whistles that should come later too quickly. Can't blame anyone for not being convinced here about the story - acquisition led companies with material debt are generally more of a risky proposition and even if they do it right acquisitions need to ad more value than the extra shares being created - so it can work ref higher profits and target and fail ref doing so providing added value for current shareholders. If Doug was still posting i am sure he wouldnt be a fan of this share.
Minor quibble if i look at stuff ignored for underlying earnings - share based payments - come on boys (and girl) your toys are a real cost to the business (would you still be there without your toys?) . Also amortisation ignored (fair enough but material sum and additions do cost cash !) . I see the rationale for ignoring these for comparing "trading alone" but in the real world particualrly the share based payments are real cost of keeping the board in place. If directors remuneration benefits bonuses are is included in "core costs" i suggest share freebies are no different and should be treated no differently
Does the 'diluted' EPS figure reflect the share based payments? I remember Jack (I think) previously pointing out that the company has four different types of share based payments. This includes acquisition retention awards which could be seen as a cost of the acquisition and justify an adjustment, but the others less so (including performance share plan, long term incentive plan, and deferred bonus plan).
Volex (LON:VLX)
Does the 'diluted' EPS figure reflect the share based payments?
I have got bored of digging back into the figues but the "diluted" figures should by definition include the warts and all so i would say yes that will most certainly include what has been "expensed ref share based payments"- Note these amounts may be highly variable so the reality may be that $9mill over 3 years may be zero year one zero year 2 and $9 mill year 3.
Volex (LON:VLX) what's not to like, except the share price. Gonna guess this may get pride of place in today's report, fingers crossed.
EPS is down significantly:
Underlying1 diluted earnings per share2
25.2c
30.0c
(16.0%)
Volex (LON:VLX) "FY2021 earnings per share includes the impact of deferred tax credits of $12.9 million (FY2022: $2.9 million). Excluding deferred tax asset recognition underlying diluted earnings per share increased by 6.3%"
The phrase “ what’s not to like “ has been used on a number of comments on earnings results recently. Maybe time for a new acronym- WNTL. We love acronyms
indeed. WLA
:)
We also love pedantry (don't we?) "WNTL" is an initialism; "BRIC" is an acronym, because it's read as a word not spelled out. Unless we're pronouncing WNTL as"Wintel" :)
Yes I am aware of the distinction but didn’t want to be pedantic.