Small Cap Value Report (Thu 23 Mar 2023) - SCS, OSI, FCAP, CNKS, SPE, PMP, EAH, SRT, WIX

Good morning, it's Paul & Graham here!
Today's report is now finished.
I reviewed SCS last night, and will shortly publish that below, once I've had a coffee (EDIT: that's now published, as always, do let us know your views too, in the comments section, especially if you disagree, we like bull-bear debates!)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
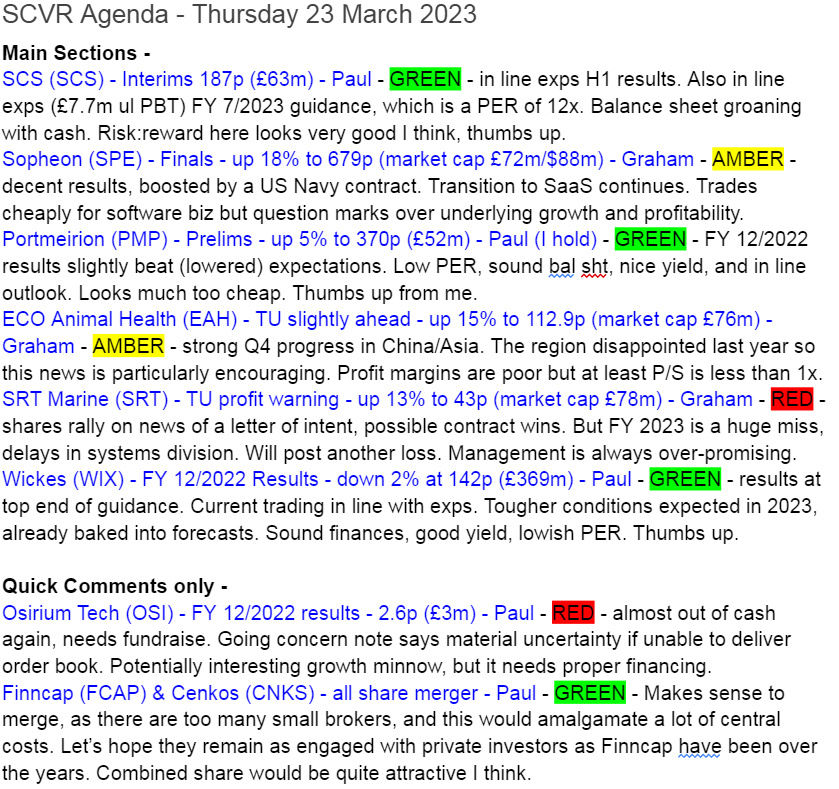
This is the stuff we didn't manage to cover today -
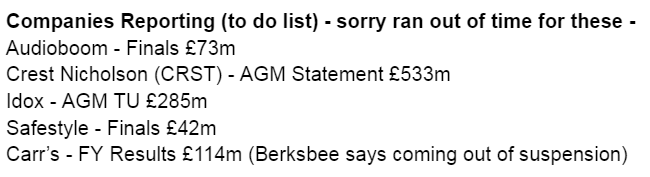
Paul’s Section:
Reach (LON:RCH)
Waiver of award
This impressed me, and is worth a mention. Perhaps more companies where the share price has seriously under-performed should also see Directors waive their share options?
Long Term Incentive Plan 2012 ("LTIP")
Waiver of Award Granted to Jim Mullen
On 27 March 2020 the independent trustee (the "Trustee") of the Company's Employees' Benefit Trust granted awards under the LTIP to acquire ordinary shares in the capital of the Company to Jim Mullen for the amount of 750,258 shares.
The LTIP award is scheduled to vest on or after 27 March 2023 in accordance with the LTIP rules subject to satisfaction of the applicable Performance Conditions relating to cumulative adjusted net cash flow and relative total shareholder return, as measured over financial years 2020, 2021 and 2022.
As noted in the Company's 2022 Annual Report, the indicative vesting outcome for the 2020 LTIP awards was 46.43% of maximum which would otherwise have resulted in the 2020 LTIP award held by Mr Mullen vesting over 363,274 shares. Despite this positive outcome, Jim Mullen asked that his 2020 LTIP award not vest and that his award be cancelled.
On 21 March 2023, the Company received, and the Board has accepted, a waiver by Jim Mullen of his 2020 LTIP award together with all related rights. No compensation shall be paid to Mr Mullen in respect of the waiver.
Bravo to Mr Mullen. Let's see more Directors waive LTIPs too, when other shareholders are suffering.
SCS (LON:SCS)
187p
Market cap £64m
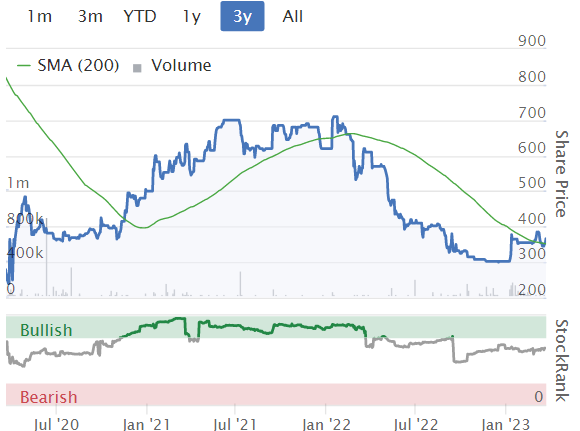
Looking back through my notes, I was green on SCS on 3 Feb 2022, when it reported an improvement in recent order intake, and a confident outlook for FY 7/2023. Plus a cash pile of £77m. I did wonder if the share price might need to consolidate or retrace at 222p, which it has done in the recent general market sell-off, down to 187p currently.
Prior to that, we looked at SCS on 10 Jan 2023 here, when it announced a very cheap acquisition from an administrator of an online competitor.
So it’s a share I view favourably, but that might change depending on what the latest numbers look like - here we go -
ScS, one of the UK's largest retailers of sofas, flooring and furniture, presents its interim results for the 26 weeks ended 28 January 2023 ("period" or "H1 FY23").
SCS PERFORMANCE IN LINE WITH EXPECTATIONS
ACQUISITION OF SNUG DIVERSIFIES GROUP AND POSITIONS IT TO FURTHER INCREASE MARKET SHARE
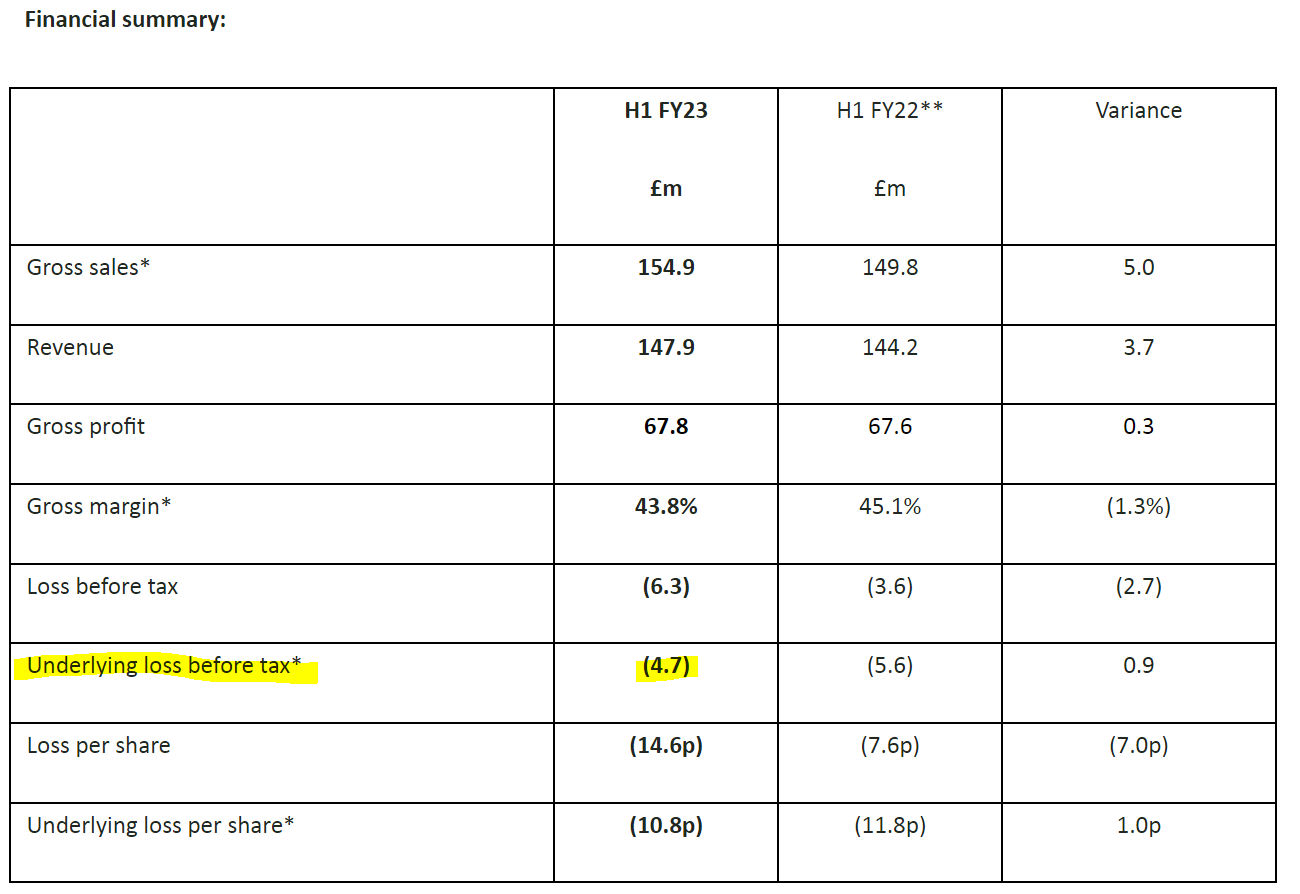
Oh, it’s a loss, that’s a bit disconcerting.
I’ve looked back pre-pandemic, on Stockopedia’s useful H1 H2 comparison tool here, and as you can see below, in both 2018 & 2019 it was a tiny bit above breakeven in H1, and all the profit was made in H2. So there’s a strong H2 seasonal weighting to profitability. Even so, a £4.7m underlying loss in H1 2023 is a deterioration from the pre-pandemic H1 performance.
(clickable link on screenshot below) -
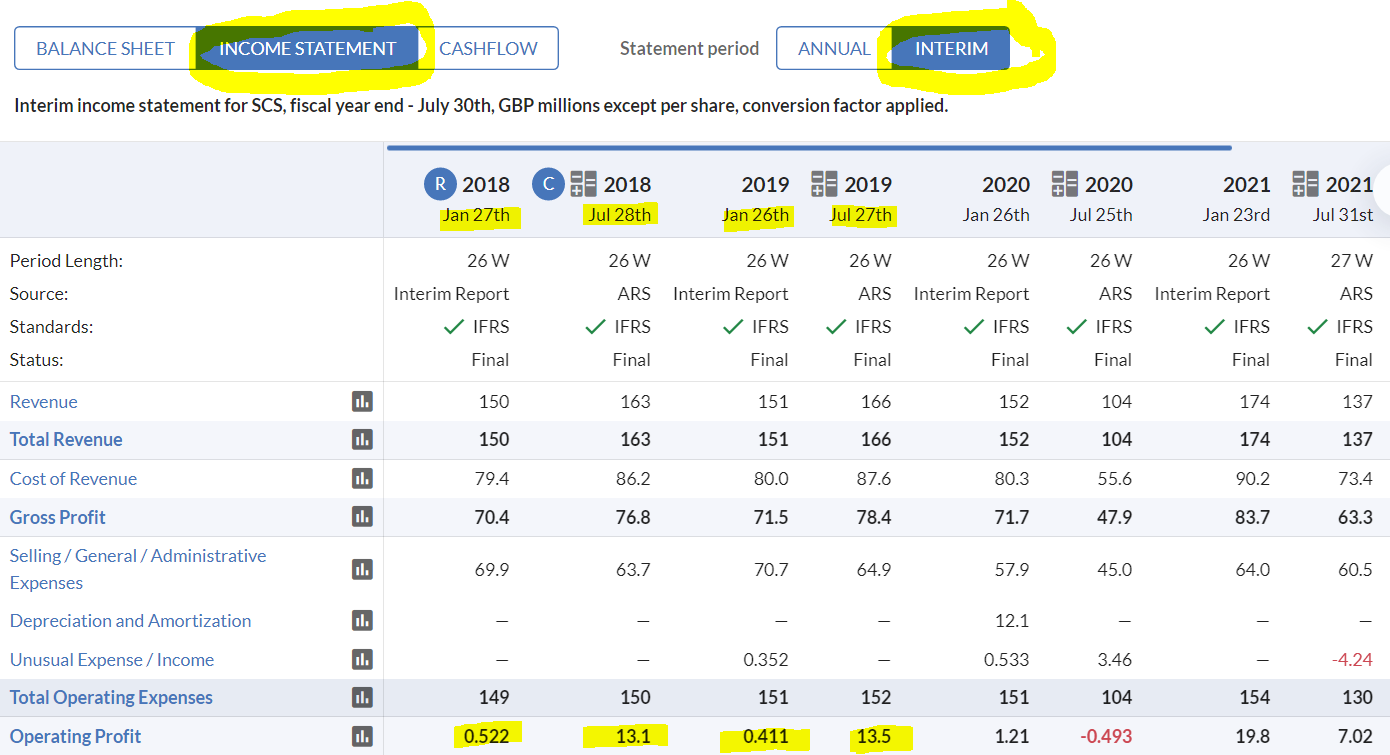
Obviously the numbers & seasonality above then went haywire during the pandemic, but should now be settling down to some kind of normality.
The company confirms seasonality, and why it happens -
...typical of H1 performance, which includes significant marketing expenditure to support the winter sale and where profitability is substantially H2 weighted
I suppose this is because the orders taken over the winter sales period don’t actually get recognised as revenue until H2, when the product is delivered (after a delivery delay that extended out to something like 3-6 months during the pandemic in this sector, where product is made to order).
Reduced gross margin it says is due to “decluttering” as display stock was sold off.
Cash pile of £76.9m is fantastic. It’s true that this is almost matched by trade creditors of £75.7m, but both numbers perpetually rotate, so there should always be a substantial cash pile on SCS’s balance sheet in good times or bad. Larger competitor DFS has taken advantage of this favourable working capital structure to spend all of its cash pile, and max out its bank borrowings too, to pay divis & buybacks. Compare the two companies, and you’ll see that SCS’s approach is super-cautious.
Although note SCS has done significant share buybacks, reducing its share count from around 41m in 2019, to just 33.8m shares in issue now. This is very important, as it enhances shareholder returns of EPS and dividend yield.
The RNS of 17 Feb 2023 says the £7m share buyback programme has completed. What a smart move that was, I wish they had done more - management is too cautious I think -
The New Programme, together with the previous programme announced by the Group on 22 March 2022, has seen a total of 4,057,981 ordinary shares repurchased and cancelled, representing 10.7% per cent of the Group's issued share capital as at 22 March 2022. In total, ScS has returned £7 million to shareholders.
The Group's issued share capital is currently 33,954,674 o rdinary shares, each with one voting right.
Balance sheet - is absolutely fine, with about £35m NTAV.
Outlook - improving, but still not great, I’d say - but given the wobbly macro picture, cost of living crisis, etc, maybe I’m expecting too much? -
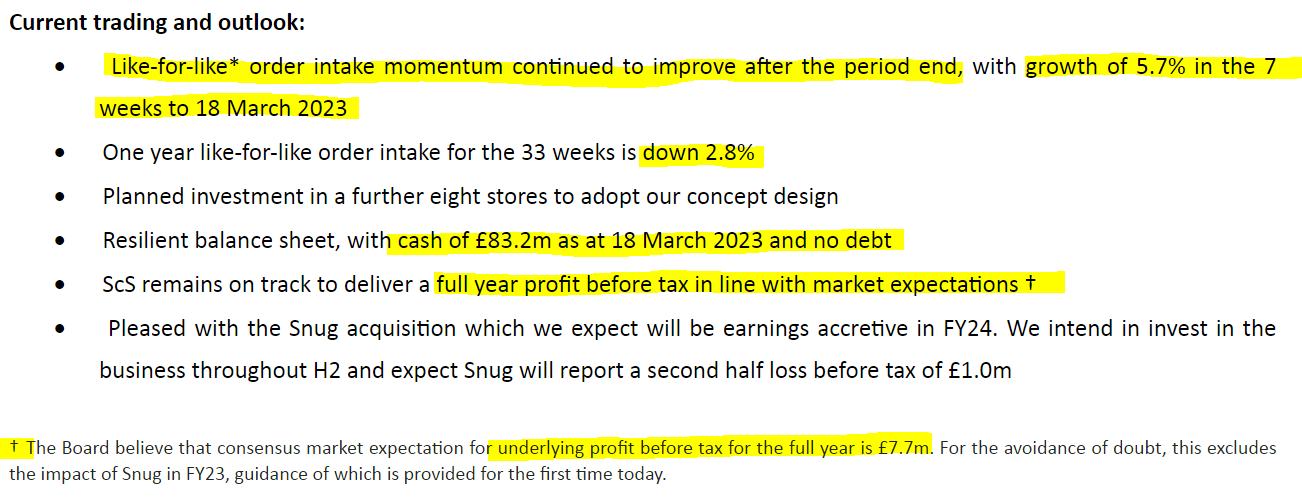
Broker consensus is about 16p EPS for both FY 7/2023, and FY 7/2024. Put that on a PER of say 10-12, and I get a theoretical share price of about 160-192p. The current price is 187p, which is within that conservative range. I’ve ignored the benefit of the balance sheet groaning with cash in that calculation too.
My opinion - this looks very solid to me. Shares possibly priced about right for now? But you’ve got the upside from a recovery in for free, and all the downside protection from a very safe balance sheet also thrown in for free.
Whereas with DFS, which I looked at recently, earnings forecasts have fallen more than SCS’s, the forward PER is about the same, but you’re getting all the financial risk of a hideously negative balance sheet laden with debt.
Hence I feel risk:reward is much better with SCS.
Thumbs up from me, although I’m not feeling any particular need to rush in and buy SCS right now, given all the current uncertainty in markets generally. Longer term though, it should recoup the 300p level in due course once earnings rise again. Plus it's paying nice divis whilst you wait. An attractive set up, maybe I should buy some?
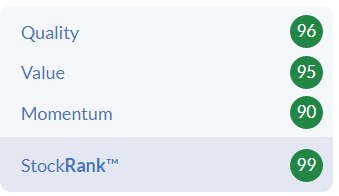
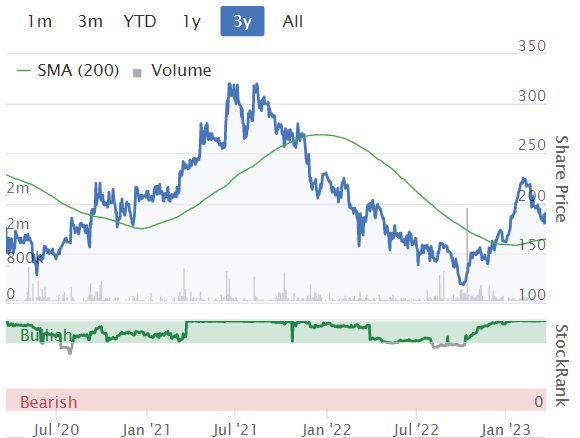
Stockopedia’s computers absolutely love it -
Portmeirion (LON:PMP) (I hold)
353p (pre market)
Market cap £49m
I last looked at PMP here on 12 Jan 2023, when it looked significantly under-priced at 323p per share, and issued an in line trading update for FY 12/2022, which put it on a PER of only 7.2x the expected c.45p EPS.
With a decent balance sheet, and energy hedged until Q1 2024.
Accordingly, I bought a standard position size for my own portfolio, when the proceeds came through from selling my Seraphine (takeover bid) in the market came through earlier this year.
Today we get the FY 12/2022 results, let’s have a look -
Portmeirion Group PLC, the owner, designer, manufacturer and omni-channel retailer of leading homeware brands in global markets, is pleased to announce its preliminary results for the year ended 31 December 2022.
Another record sales year shows continued resilience of our brands and strong global demand
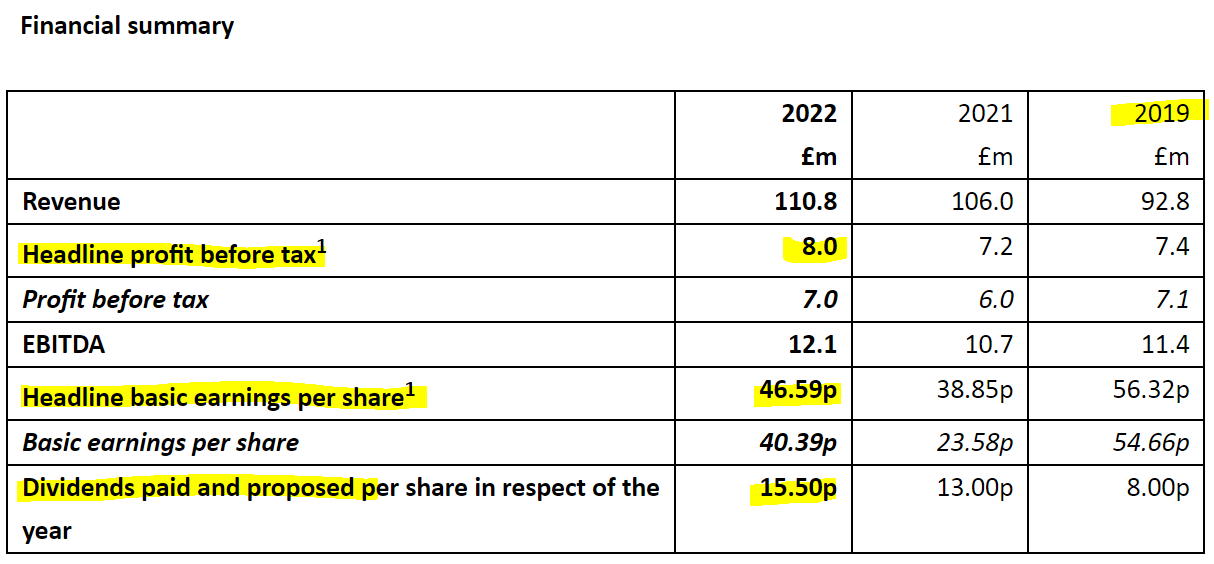
46.6p EPS is slightly ahead of the 45p I was expecting, so this is in line really (a slight beat against lowered [in Sept 2022] expectations).
Why is the share price only 353p, when the highlights table below seems to show a business that’s recovered from the pandemic, and is operating normally, and achieving solid growth vs last year? Surely this should be rated on something like 12-15x PER? (that would equate to a share price of 559-699p).
So at first sight 353p looks the wrong price to me (much too low, and a PER of only 7.6) , unless there’s something horrible in the outlook section, balance sheet, or the adjustments? I’ll check all of those. But so far, this looks like a bargain that’s been hiding in plain sight since January.
InvestorMeetCompany webinar is 11:30 this coming Monday, 27 March. I tend to watch the recordings later, as watching them live stops me doing work here, and there aren’t usually any surprises in webinars. Although I find them invaluable just for picking up the general tone of management, and sometimes throwaway remarks or answers to good questions can be quite interesting in firming up my view either way.
Profit margin - reiterates its aim to increase this -
Headline operating margin1 increased from 7.2% to 7.8% and we reiterate our long-term ambition to improve the operating margin to 12.5%.
Adjustments to profit - headline PBT is £8.0m, which reduces to £7.0m statutory PBT. The main difference is £1.0m of restructuring costs. That’s the same as the 2021 restructuring costs figure, so it could be argued that these are normal costs of making the business more efficient, which might be ongoing. So perhaps we should value the share on the more conservative statutory figure? That’s 40.35p (note hardly any dilution from share options) instead of the 46.5p diluted adjusted figure. The PER at 370p per share is still cheap at 9.2x using the statutory, diluted profit. So it stacks up well, even if we reverse out the adjustments.
Tax charge is much lower this year at £1.4m (2021: £2.7m) which obviously flatters EPS growth. We’re seeing this at quite a few companies actually - it’s explained by PMP -
The charge for taxation for the year was £1.4 million (2021: £2.7 million), an effective tax rate of 20% (2021: 46%). The reduced tax charge is mainly due to the one-off impact of the change in UK corporation tax rate from 19% to 25% in the prior year which caused an additional deferred tax charge of £1.1 million.
Inventories - planned reduction should free up cash in 2023, which I like - it made sense to raise inventories during supply chain difficulties -
Inventory levels remain elevated at year end to avoid supply chain disruption and this is expected to normalise in 2023.
Outlook - the middle point seems to contradict itself, so asking for clarity on this would be a good question for the webinar -
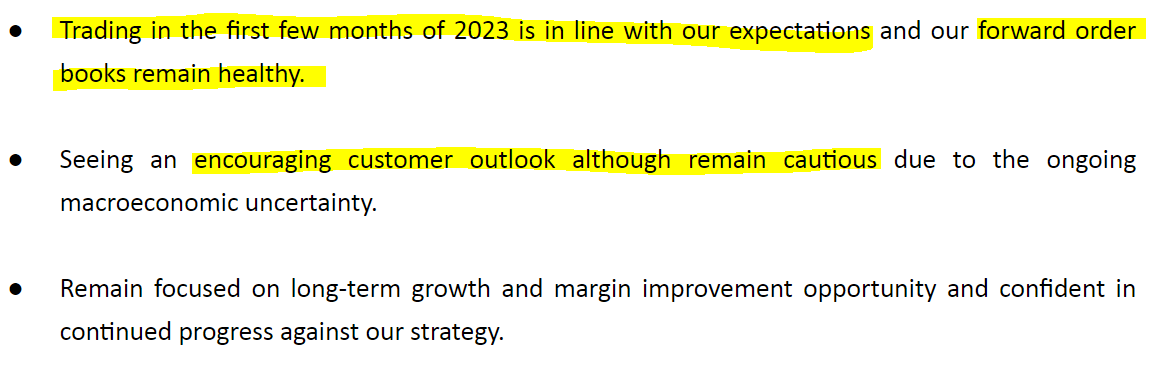
In addition there are signs that global supply chain disruption and general overstocking in retailers are subsiding. Similarly global shipping costs are trending back to historical levels.
See Research Tree for updates from 2 high quality brokers (Singers & Shore, many thanks).
Singers has a rise from 2022 actual 46.8p, to 51.7p for FY 12/2023, so at 370p (correct at 09:14) the 2023 PER is only 7.2x - very significantly undervalued, in my opinion. Particularly given that the outlook comments are pretty solid (in line so far this year, and good order book). So I’d say the risk of a profit warning looks quite low here. Although you can never rule out profit warnings at any company - as sometimes things that you couldn’t have foreseen can go wrong. Hence why we diversify our portfolios, knowing that the odd one will go wrong (especially with small caps, more than the odd one!).
Balance sheet - the commentary explains that inventories are elevated due to supply chain issues, but expected to reverse in 2023. £41.1m is indeed a bloated figure for inventories, so we do need to see that come down, as it’s tying up a lot of cash
A good question for the webinar would be to ask for more colour on the inventories, and how rigorous the audit testing was for slow-moving or obsolete stock? Will much of it have to be sold at reduced prices, to clear it? (which could hit 2023 margins)
Net debt is £10.1m, with £15.7m headroom on the bank facility.
NAV is £66.7m. I take off intangible assets, of £18m, to give NTAV of £48.7m - healthy for the size of company.
Overall, all the other numbers on the balance sheet (apart from inventories) look OK to me.
There’s a tiny pension scheme asset, but it required a £900k contribution from the company, so as usual with ridiculous pension scheme accounting rules, a surplus is actually a deficit.
Capex was £4.1m, similar to last year’s £4.5m. Note that £1.9m (up from £0.8m in 2021) was capitalised into intangibles, so I’d like to know what that is - website development costs maybe?
Cashflow statement - tying in with my balance sheet comments, the cashflow shows that almost all of the operating cashflow got sucked into increasing inventories. That should unwind, but we need to be vigilant in 2023 to ensure that does actually happen.
My opinion - very positive. There could be unconscious bias, as I bought some shares personally earlier this year, hence why we disclose if we hold anything. I am happy to hold, and looking forward to collecting my divis, and seeing the shares re-rate in due course, which looks likely to me (providing nothing goes wrong).
It’s a nice company, well-managed I think (the CEO strikes me as a safe pair of hands), well-financed, cheap PER, and decent divis whilst we wait. So pretty much a classic value share I would say. Thumbs up from me. I think there could be c.50% upside on this share, just to get it to a reasonable valuation.
Wickes (LON:WIX)
142p (down 2% at 09:40)
Market cap £369m
Wickes is a chain of home improvement retail sheds in the UK.
I last looked at WIX here on 1 Feb 2023, concluding that it looked an attractive value share, at 152p. Its FY 12/2022 guidance was £72-76m PBT, with trading in line.
On to today’s results. There’s a slide deck available here, which can be easier to digest than reading a whole results announcement in detail (but might gloss over negatives!)
Key points -
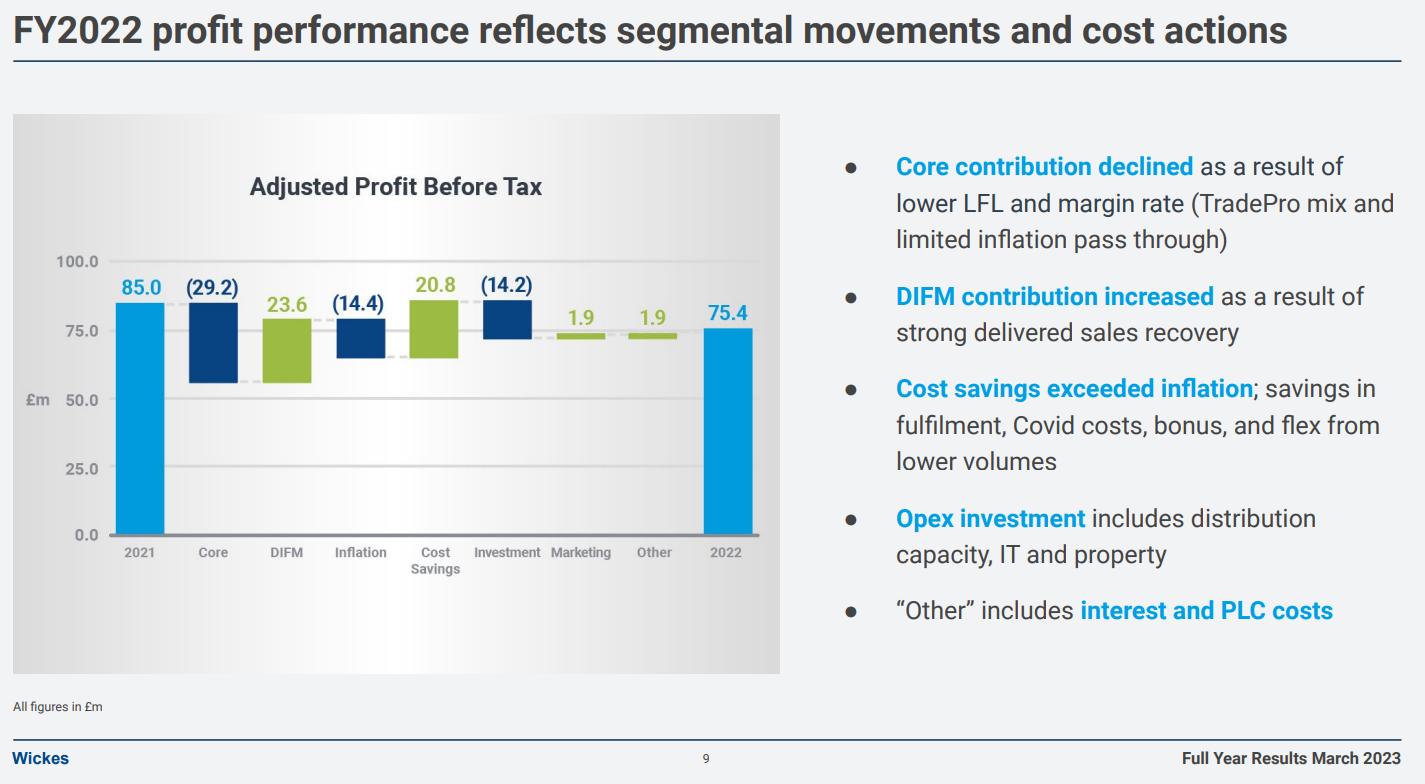
Adj PBT has come in at £75.4m (down 11% on 2021), nicely near the top of the previously indicated range of £72-76m.
Adjustments are big - adj PBT of £75.4m turns into statutory PBT of £40.3m. The 2 big adjustments are £24.4m IT separation costs (re demerger from Travis Perkins), and £15.4m leases RoUA impairment. These are adjusted out presumably as they’re seen as one-offs, and not underlying trading.
Revenues £1,559m - a sizeable business.
This profit bridge is useful (slide 9 in the deck linked to above) - it tells me most importantly that profit held up quite well, with inflation more than offset by cost savings.
I wish abbreviations would be accompanied by a footnote. I think DIFM is goods delivered to customers (as opposed to the “core” retail sheds sales)
Do have a look at the rest of the slides, as there’s useful information in there.
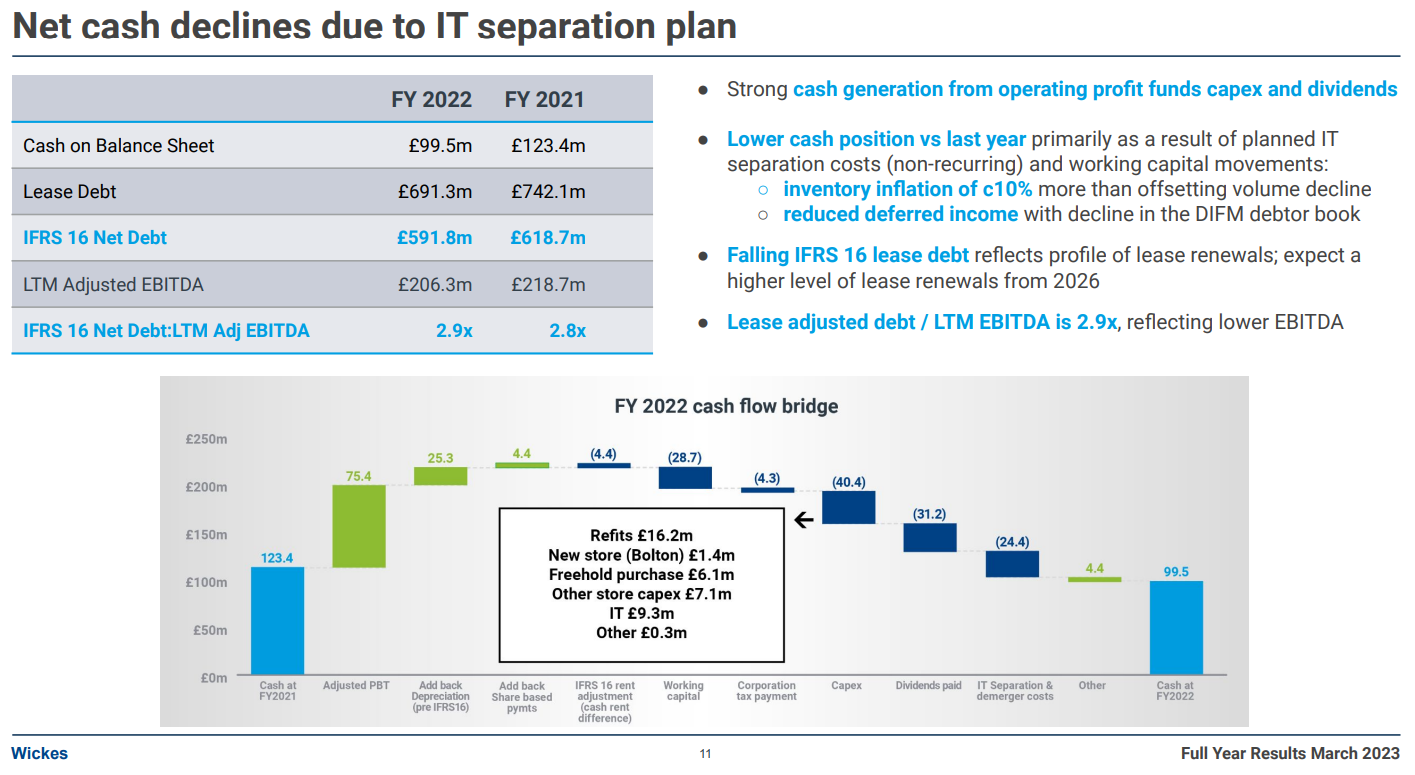
This cash bridge is fantastic, we like bridges here at the SCVR - a really easy to digest visual version of the cashflow statement -
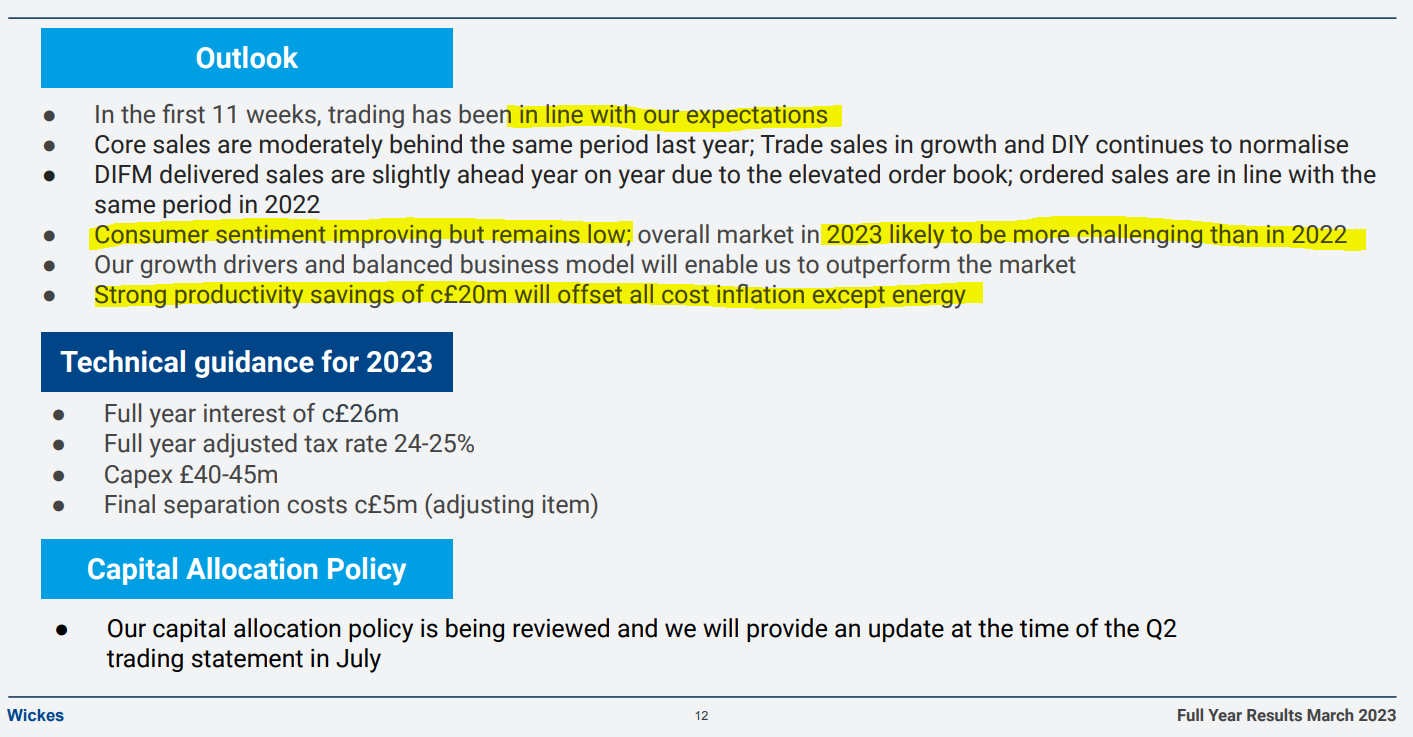
Outlook - in line with expectations so far for FY 12/2023. Again, the slide deck explains this clearly (my highlighting added) -
Balance sheet - NAV is £164m.
My adjustments to this are - remove goodwill & intangible assets = £25m.
NTAV is therefore £139m.
Remove IFRS 16 lease entries, a deficit of £(148.9)m, which boosts NTAV to £288m - which well supports most of the market cap of £369m.
Now you could argue that by ignoring lease entries, I’ve not included an allowance for loss-making sites, which is a fair point. But those are losses that will be absorbed by future trading from the profitable sites, so I don’t see those as liabilities, instead future losses.
The main reason I look at balance sheets, is to ascertain what the risks of insolvency, and dilution from an emergency fundraising would be.
In this case, my assessment is that WIX is financially secure, and the risks are low.
Retailers generally don’t tend to need massive balance sheets, because they’re selling for cash, and buying on credit.
My opinion - I like this share, it’s a good business, reasonably priced, with a modest PER of 8.6x for 2023, and a 5.7% divi yield. Finances are secure. So it’s a thumbs up from me. Over time, as the economy recovers, I think WIX shares should recover. I don't see a permanently damaged or deteriorating business here, which is what the share price seems to be telling us.
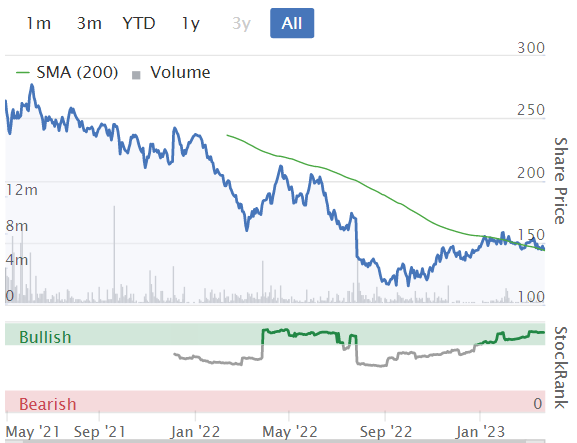
The StockRank is now very high too, which reassures me that I'm probably leaning in the right direction here.
Graham’s Section:
Sopheon (LON:SPE)
Share price: 679p (+18%)
Market cap: £72m / $88m
This morning we have full-year results for 2022 from Sopheon, the enterprise software company:
Revenue $36.8m (2021: $34.4m). There were acquisitions in Dec 2021 and May 2022, so this is not a true like-for-like comparison.
Annualised recurring revenue $24.3m (2021: $20.7m)
PBT $1.3m (2021: $1.2m) that includes the amortisation and impairment of intangible assets.
Net cash $21.1m (2021: $24.2m)
As we have noted before, Sopheon is switching customers over to SaaS contracts, and this process continues..
CEO comment:
Sopheon delivered solid growth with record ARR last year, and acquisitions and new products tripled our multi-billion-dollar addressable market. Our ambition is for Sopheon to double run-rate revenue every three to four years, with world class margin and retention metrics. This will require a contribution from acquisitions, on top of accelerated organic growth. We start 2023 with a strong foundation of ARR, a stable of new products, and a growing sales pipeline.
The company now describes its software as “InnovationOps”, as it is designed to help customers to innovate faster, more successfully and more efficiently.
After the acquisitions that took place, it has a family of four products instead of just the one flagship product.
It continues to promise that 2024 will see higher growth and profitability, as the SaaS contracts will generate better long-term revenues than the short-term revenues created under the old model.
My view
I won’t dwell on this stock much longer, because I already know that I’m giving it an “amber” view.
Firstly, on valuation. After this morning’s share price gains (to 679p currently), the price/ARR multiple is c. 3.6x.
Deduct cash from the market cap and EV/ARR is only 2.8x.
This is definitely on the cheap end of the spectrum for software companies.
However, I think there may be some good reasons for it to trade cheaply:
Organic growth appears to be somewhat limited and the company acknowledges that it will need more acquisitions to hit its growth targets.
Current profitability is also subdued. In 2022, the company capitalised $5.2m of development costs, which was nearly all of its net cash from operating activities.
2022 results were boosted by one major contract signed with the US Navy. So customer concentration could still be improved.
In summary - I do think this is cheap for a software business, but I’m not sure that it deserves to trade at a vastly higher multiple.
ECO Animal Health (LON:EAH)
Share price: 112.9p (+15%)
Market cap: £76m
It has been a while since we checked in on this company; it’s “a leader in the development, registration and marketing of pharmaceutical products for global animal health markets”.
Last August, it revealed that demand in China had dropped off. With a poor revenue outlook, EPS estimates continued to slide:
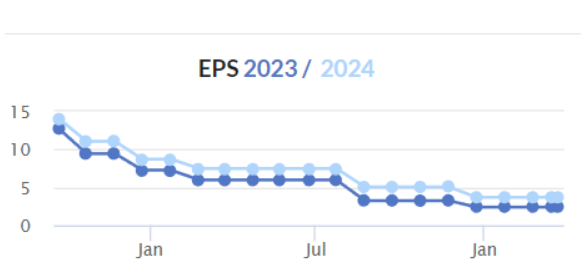
Today brings better news for FY March 2023:
The ECO Group has experienced strong trading in its final quarter and it is clear that the demand for Aivlosin has been a little stronger than expected in China and Asia. As a result, the Board now expects that Revenue and Earnings before Interest, Tax, Depreciation and Amortisation will be slightly ahead of market expectations for the current financial year.
While this is indeed good news, market expectations were already very muted. So “slightly” beating them is perhaps not saying all that much:
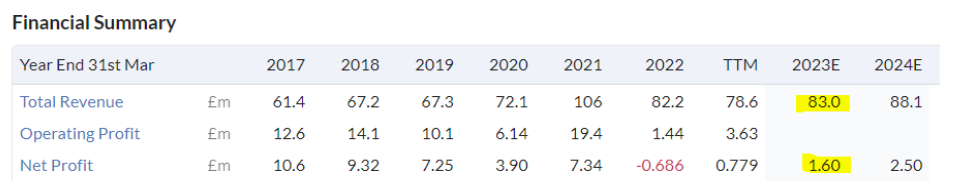
This stock remains expensive on a P/E multiple basis. But trading appears to have stabilised after a turbulent period, and the P/S multiple is less than 1x. So I can get behind a neutral stance on this one.
SRT Marine Systems (LON:SRT)
Share price: 43p (+13%)
Market cap: £78m
Over the past six months, this company has finally delivered the huge growth in revenues that it promised for so long.
However, this update is very strange. Prior to today, brokers were forecasting revenues of £56.6m in FY March 2023 and adjusted PBT of £6.8m.
Instead we get this:
The Company expects revenues for the year ending 31st March 2023 to be approximately £30.0m, a 265% increase on the previous year, generating an EBITDA profit of £2.5m and an expected loss before tax of £1.0m.
The explanation:
These results are lower than market expectations for the current year primarily due to material systems business project milestones that had been expected to be completed by the end of the current year being delayed to the early part of the new financial year.
In other news, SRT announces a new coast guard systems project worth £145m where a Letter of Intent has been signed.
Customer funding for the project still needs to be finalised but SRT expects that once it is underway, the project will be mostly delivered within two years, and thus “generate significant revenues in the coming financial year alongside our existing system projects”.
Validated sales pipeline - the company has “specific projects where we have ongoing discussions with an estimated aggregate value of £1.4 billion. However, many of these are in their early stages and usually take several years to develop into defined projects and contracts…”
The potential £145m coast guard project is included in this £1.4 billion pipeline.
Additionally:
…there have also been some recent material events which have significantly improved timing confidence of two other potential projects. Firstly, a series of meetings at the highest level for another prospective new coast guard customer who wishes to build up a very significant national scale system over the next ten years in a series of incremental annual projects with an indicated annual project budget in the region of £50.0m commencing from 2024. Secondly an existing customer who has secured funding of up to £150.0m to undertake a significant expansion of their existing SRT supplied system starting from 2024.
My view
My view might be controversial, given that the company’s revenues have risen dramatically over the past year (despite the delays in the systems division) and given that the share price is up again today on the back of all the positive contract-related news.
However, I am going to give this company the thumbs down.
The reason is that I simply do not trust what it says about its revenue prospects. It spent 17 years over-promising and under-delivering, before the big contract news last year.
And then when it was finally supposed to land with material profits in FY March 2023, it has failed to do so and is posting another loss.
Perhaps FY March 2024 will be the year of financial success, but then I’m afraid I would have no confidence in FY 2025 and FY 2026.
SRT’s work is inherently extremely lumpy. Even if I give management the benefit of the doubt, the best I can say is that they are simply unable to forecast their own results.
One final point: when companies talk about their “validated sales pipeline”, I think it should be treated with the same level of scepticism as talk about a “total addressable market”.
SRT has a very long history of over-promising. Perhaps this time is different, but I personally don’t trust what they say and so I believe these shares should be avoided.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
WIX - have you actually been in a Wickes recently? This may not be typical but I walked in to Wickes Guildford when looking for wallpaper two months ago. Few people in the store, almost no staff except one poor lady at checkout with a queue of about five customers waiting to pay. No-one to help customers. Awful place, disgusting car park, unpleasant all around, will never get my custom nor my investment.
The out-of-town Wickes in Tunbridge Wells was reasonably busy when we went in 2 weeks ago, and the staff were helpful. A local builder has said that Howden's provide better service to him.
Just one data point. {No positions)
Lowestoft is always quiet, the stores have not changed in years. Staff not very helpful. Their tile selection is very poor. Obtaining certain items is very difficult.
Click and Collect was not even manned, have to collect within 24 hours, Screwfix you have 2 weeks to collect.
Screwfix I think are much better.
Does anyone here know why there was a sharp downgrade in the 2023 broker forecasts for Cambridge Cognition Holdings (LON:COG) on Jan 31st, a couple of days after their positive trading update?
:-) SRT Marine Systems (LON:SRT) vs Blackbird (LON:BIRD) - both decades long over-promisers (BIRD's prior existence included). Until recently BIRD (rev £2.7m) was a bigger MCAP than SRT (rev £22m).
SRT deals with very large contracts using new tech in parts of the world where things don't move with pace. Think HS2 and double the drag!
BIRD deals with TV news and sport organisations who make decisions quickly and getting an edge via tech is basic operating procedure.
Which one sounds more credible when contracts are delayed?
I am living with the fact that SRT sales cycles are years or maybe decades long capex sales. But BIRD is a SaaS model. Not sure if you can "pay for a month", but it is minimal opex investment - and they still can't sell enough to pay the bills.
Paul, I can see why you think SRT isn't to be trusted, it is a frustrating and risky investment, but I have no idea how you concluded differently for BIRD.
BIRD have no excuses other than the tech isn't what the market desires, The tech isn't delivering the benefits, they would have many more customers after 20 years.
BIRD's £10m of balance sheet cash will end up in bonus' and pension payments and they will have to send round the hat again.
Hi wolfspirit,
Paul, I can see why you think SRT isn't to be trusted, it is a frustrating and risky investment, but I have no idea how you concluded differently for BIRD.
Graham actually wrote the section on SRT, whereas I wrote the section on BIRD.
The layout of the reports is always the same, every day - my section at the start, labelled "Paul's Section", then Graham's section below, labelled "Graham's Section".
Maybe we need to put the name of the writer in every section, as we seem to quite often get this problem where readers don't notice who has written each section?
Personally I wouldn't invest in either company, they both look awful, jam tomorrow things! I can't believe how long SRT has got away with dangling massive contracts in front of investors, with little actual delivery. Its validated pipeline seems to grow exponentially, soon it will be equivalent to the GDP of a small country, and it'll still be loss-making!
OR you'll suddenly make money from it, like people have been hoping since SRT floated in 2005. That's 18 years ago!
Regards, Paul.
:-) I stand corrected on author! It probably would be useful to have author in front of each.
I think there is a solid argument to not invest in either. They are both a bit like "investing" in a horse at Aintree!
BIRD started in 2003 - but it's heritage goes back further than that. Before Eidos got big in video games.
I've been wondering about inverted bond yields, and it's something I've heard a lot about (as a predictor of recessions), but have never properly researched. So I decided to ask CHATgpt! This is the answer it provided -

Is an inverted bond yield a reliable predictor of recessions?CHATGPT reply - 2 / 2
An inverted bond yield curve has been a fairly reliable predictor of economic recessions in the past. This occurs when the yields on long-term bonds fall below the yields on short-term bonds.
The reason why an inverted yield curve is considered a predictor of recessions is that it indicates a situation where investors are willing to accept lower yields on long-term bonds, which suggests that they expect interest rates to fall in the future. This typically happens when the market is uncertain about the economic outlook and expects a slowdown or recession.
Historically, an inverted yield curve has often preceded economic recessions by around 6 to 18 months. However, it's important to note that an inverted yield curve is not a perfect predictor and there have been instances where a recession did not follow an inversion, or where there was a recession without an inversion.
Therefore, while an inverted yield curve can be a useful indicator of economic health, it should not be relied upon in isolation and should be considered along with other economic indicators to form a complete picture of the economic outlook.
This sounds like a reasonable summary from ChatGPT My understanding is that the signal of an imminent recession is actually when bond yield curves un-invert. In other words, central banks are responding to current conditions (that things have broken etc) by now rapidly cutting interest rates. By this stage though its probably rather late to be very useful as a predictor!
An excellent Presentation today by Gulf Keystone Petroleum (LON:GKP) on the Investor Meet Company Site given by the CEO and CFO.
I learnt a lot in a short time so time well spent.
Wickes (LON:WIX) Paul the DIFM I believe is Do It For Me which I guess is their equivalent of the Howdens or Magnet approach - clients ordering but Wickes contracting the trades. I would have thought a lot of bathrooms and kitchens are covered in this category. Possibly more.
Thanks sevenccc!
It's infuriating when companies use abbreviations which they are familiar with, but other people may not be. You would think that they would have someone in-house, or an adviser, that prompts them to add explanations for these abbreviations, when publishing material for people outside the business who may not know all their company/sector abbreviations.
ECO Animal Health (LON:EAH) I was slightly apprehensive to see that todays TU was going to be covered in the SCVR as it’s a fairly recent new holding for me (I started buying early February this year). I see the positives that China and Asian markets are recovering but would have liked more detail. Guess I’ll be waiting for the results.
Cue a sigh of relief that Graham has given it a neutral status, a feeling I compare to winning a ‘taking part medal’ in a running race, still much to do but worth keeping going ;-)
The biggest concern was their China market (c24% of the rev, I believe). Now that this has been dissipated, given the low pork prices in China, they are very likely to be looking forward to improved pork prices in China with lockdown finished.
RoW is growing fast. Pipeline of drugs are growing fast. Bottom has been c85p. Schroders began buying a few months back as well.
It's a company that has historically traded on a high-ish PE ratio.
Overall, IMO, it's been the concerns over the low China pork prices that have impeded SP rise on this stock. (as well as having lead to their previous profit warning). Should be on the road to recovery. Re-bought in today.
Is there an easy way to find out whether a company is being covered (free) by a research company (eg Equity Development. Edison, Progressive Research, Hardman & Co etc)?
I noticed that Sopheon have a note out today by Progressive Research but I just happened to stumble across it. No reference to the coverage in the results RNS today.
Seems a bit hit and miss. Any help would be appreciated.
are you using research-tree? that page collects all research companies reports, videos... you can create your watchlist and never miss it.
Thanks donQ - would you recommend the free version?
I'd recommend it Snazzytime. Add shares to a watchlist and you'll get alerts for broker notes,news if you want it, short interest changes.
Think a free account gets a small snapshot of broker notes, but you'll know which ones are free to read so you can then look on individual broker websites.
So for those research notes that are locked you can only access them by paying a £25pm subscription?
Locked research notes do not appear to be accessible on the broker site (eg Liberum for Vertu Motors).
I pay £25 per month for Research Tree, and it's worth every penny - a vital service for serious investors I think. It amazes me that people are so tight, wanting everything free, but throwing large amounts of money around in their portfolios - penny wise, pound stupid! (not you, I'm just talking generally).
Services like Stockopedia, and Research Tree, cost money to run, and I think people should be happy to pay up for quality information, otherwise such websites wouldn't exist, hence why we should support them, I feel.
The subscriptions pay for themselves many times over I find, just on one good decision prompted by information provided by them.
Just my view! (which I would say even if I didn't have a vested interest in writing for Stockopedia)
I'm not connected to Research Tree, other than pre-pandemic having had lunch & drinks with the founder, Rob, who's a top chap!
Regards, Paul.
£20 a month on this link https://www.research-tree.com/code/nakedtrader
Please note I get a small bung on that link but you'll get a fiver off a month.
Agree with Paul, well worth it. After all we are running a business and the costs
are very small.
Has Luceco (LON:LUCE) been left off the agenda for any reason or have I just missed it. It would be interested in others’ take on the FY22 figures released on Monday. It is and remains a long term hold for me: a well run company with committed and competent management in an area which should see meaningful fundamental growth over the long term, but the erratic share price suggest the market cannot make up its mind about them.
LUCE is on my list! Lots still to do today, but I should have time tomorrow, as it's something I do want to cover. We're just getting a deluge of stuff to look at each day, getting really busy again, and remember full accounts take a lot more time to go through than just trading updates.
Hi Paul
This Investor Meeting vid for Luceco (LON:LUCE) should assist
I hold
An excellent detailed explanation of their numbers and adjustments for the Covid trading variances.
https://www.investormeetcompan...
Regards
Howard
Thanks, Paul and Howard.
I've reviewed Luceco (LON:LUCE) (and 10 other companies!) ready for tomorrow's SCVR, following a rare burst of energy this afternoon. So I'll put those up tomorrow morning.
Right, off to get some beers & settle down to watch The Apprentice, then shout at the tele when Question Time comes on :-)
See you in the morning!
Good morning Paul, I'd like to ask you if Inland Homes (LON:INL) is too small a company for you to look at. It might be interesting for a bystander to watch but I hold. There is talk of a fund-raise at ten-pence a share, the publication of accounts deadline of March 31st will be missed and its share dealing suspended on April 3rd. Strange goings-on have been going on, it's so highly speculative but heigh-ho, I'm a risk-taker so added more at sixpence today.
Silver
Edit: I missed your earlier reply to JASVFS, if I had I may not have doubled-down!
If you click on the link in your post and then Discussions, you will see Paul looked at Inland Homes (LON:INL) on the 1st of March.
Thank you slopsjon, how remiss of me, I did read Paul's assessment at the time so now it's fingers crossed.
I don't hold EKF Diagnostics Holdings (LON:EKF) and I won't pretend to understand all of the details of this acquisition and disposal but I can't find a way to view this as a positive reflection of EKF management's competence:
Unless I've misunderstood the deal, he gives back 1.2m of the initial consideration shares and gets to keep around £2m worth of EKF at the current share price.
The balance of some intercompany amounts results in Stanley holding a 36 month loan of $0.65m at 2% interest, only repayable if ADL generates excess operational cashflow over its needs. Unsurprisingly, there is no guarantee that the payments will be received.
EKF also get back some capital equipment and inventory with a net book value of around £0.44m but the resale value is expected to be below this amount - I wonder if they'll find anybody with a testing and diagnostics business to buy this stuff at below net book value?
So in summary, lucky Stan perhaps opportunistically creates a testing business at the height of the pandemic and flogs it to a gullible EKF just as the pandemic is waning. Stan's creation unsurprisingly doesn't live up to its touted expectations and is given back to him 18 months later.
Wondering if anyone can allay my cynicism here?
Excellent Synopsis. Seems like someone else profiteering from a useless product developed during the chaos and lack of scrutiny during the pandemic. Shades of Theranos, perhaps.
I have been buying EKF Diagnostics Holdings (LON:EKF) on the way down and it has not been one of my better decisions. I held it a few years ago, when it was on its way up the Covid testing curve. Maybe it is always a bad idea to revisit a former stock that you have done well on. ( it gives a false sense of “I understand this stock”).
John, I think your summary sums things up pretty well and EKF management have made a number of mistakes. Mike Salter has since been demoted from his CEO role - although the ADL acquisition was completed under the the previous regime (which is now back).
To be fair to EKF it was always clear at the time that the value of the Covid testing industry was very difficult to put a firm number on and so the deal to buy ADL included many contingent payments (which have not been made).
I am very happy ADL has been sold (even if for almost zero and at a loss) as it simplifies the business and allows management to focus on more important issues - in particular getting the enzyme investments up and operational.
I do think the share is cheap but management has to show it can deliver. In addition, with Christopher Mills as a key shareholder, there is the shadow of Sourcebio over the stock (Mills supported the delisting of Sourcebio around the turn of the year, when he felt the share price was too low.)
EKF Diagnostics Holdings (LON:EKF)
My thanks also to johnsmith68 for his detailed comment earlier. That made me angry with the wording of the RNS which said "...the return of 1,200,000 EKF shares ... which were originally issued as consideration..." Surely that should have been part of those issued... There was no mention of the rest of the 8,937,337 Consideration Shares. I had not realised that on a quick read.
That said, given that "there was no alternate transaction available and that the outcome to EKF is more beneficial than the cost of closure of the disposed business" I think getting rid of it was right.
I agree that hopefully attention will now turn to the (delayed) expansion of the enzyme business which is key to an uplift of the SP as is the appointment of a new CEO, preferably from outside current management this time!
Reminder - next Tuesday prelims with webinar on IMC at 16 30
Sureserve (SUR)
Strong move up on Sureserve not sure why and looks solid .
Still one of my biggest 5 holdings but did trim last week when I somewhat bottled it abd got sucked into the bear trap doom and gloom .
Actually with the illiquidity in a lot of small caps and with me being fully invested found myself permanently out of cash the past 6 weeks so bit the bullet and trimmed a good few across the board .
There is a lot of distress in the bike business that no one has ever seen before so good chance to pick up some businesses / brands so cash is king and the ability to act very quickly with funds is probably a smart move though like s muppet sold on a down day
As Warren Buffet says “the best investment is yourself”
planetx. Bike business?
Bicycle industry .
Where I cut my cloth . (Planet x bikes)
Is that connected to Sureserve (LON:SUR) ?
Not connected to Sureserve just got sidetracked sorry
Good website planetx , tough times, good luck. Not the place for socialising but think you might know a man who runs the cycle shop in our village, Kev Dawson.
Yes I know Kev very well he rode in my team in the 90s for a long time , great rider won a fair few national championships for me .
Rode 100 miles in 3 hours 22minute which is very quick
FYI
Planetx is a long standing bike business and the poster of that name is its founder.
I dont think he will mind me posting this.
What is the reason for the distress?
I dont know as much as others here about it, but it may be the 35k bikes to be auctioned after Moore Large has gone into administration
Moore large tip of iceberg, they did an MBO At a very high price at the peak of covid and loaded with debt .
Bicycle industry distress easy to explain
- huge sales during covid so no one had stock
- everyone went Billy big balls and placed huge orders
- factory leadtimes went up to 18 months
- so huge orders placed all start arriving 18 months after the boom
- boom ends and sales rates back to normal
- there is a tsunami of backed up stock in Taiwan / China and demand is down so all manufacturers are bunged up with stock they can’t sell and more orders backed up
Moore large big wholesaler 50 million turnover 100 staff just gone pop .
Specialised cutting 8% of staff
It is Armageddon for a good couple years anyone with debt is going to be under duress if banks aren’t supportive.
-
Sounds like it might be a good time to buy a bike!
planetX I clearly got hold of the wrong end of the stick today regarding the topic of bikes; apologies for withering on about Halfords (LON:HFD) and Tandem (LON:TND)
All the best.
Unfortunately, the illiquidity in small caps is causing some strange moves. An AIM Inheritance Tax service, dealing through platforms, made a complete mess of Sureserve yesterday. As they were looking to deal for their clients, through multiple platforms, it made it look like there were multiple buyers all at once. In turn, the platform dealers, they were using, made no effort to look properly for sellers, in size, of the stock and instead bid for stock in the open market; rather than picking up the phone to holders/potential sellers!
Portmeirion (LON:PMP) is the largest holding across the family portfolios that my wife and children allow me to operate. This morning's prelims read well and are very encouraging. In my view and to paraphrase Howard Marks, one of the great investment minds, it is trading below intrinsic value, which also in my opinion applies to Ten Entertainment (LON:TEG) another portfolio holding.
Let's hope that the market reaction to Portmeirion (LON:PMP) is more favourable than that which Ten Entertainment (LON:TEG) received yesterday. If Mr Market fails to value either company fairly I suspect in time someone else will.
Portmeirion has been top of my buy list on several occasions but never pulled the trigger .
Looks a great company and easy to understand, not unlike a ceramic version of Sanderson Design group .
Looks like management have a good long term vision and like the fact they did an opportune acquisition out of administration last year on the candle business .
There a few things I don’t like so much as just points to slightly slovenly attitude towards some basics but if your a believer in the very long term business you should get over these .
There seems to be a decrease in cash to circa negative 10 million (despite 7-8 million profit ) plus a significant stock build .
I just find it a bit lazy to justify a significant stock build as to service the market ,.
The company is not “spitting out cash”
If they were to become leaner with super sharp production and processes and more of a JIT operational setup then they would surely be making profits and generating cash .
Also not convinced about candles and certainly not “wax lyrical” as a brand name that is a pretty competitive sector .
Having said that looks good and as I don’t know the business well enough might be not valid points but the two combined together do seem to be somewhat unaddressed eg
- cash is down
- stock is up
Morning planetX
Thanks for your thoughts on Portmeirion (LON:PMP) . I was fortunate to buy much lower down around 330p. Like you I try to stick to companies that are relatively easy to understand and Portmeirion (LON:PMP) as you say fits that mould, as does Sanderson Design (LON:SDG) which you also reference and I would suggest the likes of Ten Entertainment (LON:TEG) Avingtrans (LON:AVG) AND Pressure Technologies (LON:PRES) . Although there are never any guarantees.
It reminds me of Warren Buffet's saying "I try to invest in wonderful businesses that an idiot can run. Because sooner or later one will."
A little outlandish perhaps, but carries more than a grain of truth. Not that of the above are wonderful businesses but in my view are or have the potential to become good businesses.
Back to Portmeirion (LON:PMP) , I take your point on on the cash position versus inventory increase, but I very much like the clear strategy mapped out by the newish CEO Mike Raybould to improve margins back towards 12/13% and like Sanderson Design (LON:SDG) I can see both being bid targets as their heritage brands have inherent value.
Regarding bicycles and opportunities I can only think of two listed players, Halfords (LON:HFD) and Tandem (LON:TND) . Of the two I prefer Halfords (LON:HFD) who I believe own the TREK brand, I also like the diversification in auto centres and commercial vehicle tyres. Any further thoughts would be appreciated.
All the best
Trek Cycle Corporation is a large company with a turnover greater than a billion dollars which owns a number of other well-regarded brands. Halfords do, however, own Boardman Bikes.
Apologies got my 'T' s confused. Halfords acquired Tredz.
Halfords snaps up Tredz… but won’t be stocking their bikes - BikeRadar
King Charles Coronation Gifts | Portmeirion
I am guessing these will give a lift to Portmeirion (LON:PMP) sales in FY23.
Have to admit the potential relevance of the Coronation to Portmeirion (LON:PMP) had passed me by, but yes I suspect that you are right.
It would be interesting to know what estimates Portmeirion (LON:PMP) themselves have made for it.
Re Portmeirion (LON:PMP): (I hold)
sorry late to the party today.
In todays results UK sales accounted for only 25% of revenue and likely even less by operating profit. The UK has been very weak -14% YoY sales and likely even lower in volumes. I don't expect coronation gift sales to make an appreciable difference to group revenue or profit - but every little helps as they used to say - and I'll be quite happy to be found wrong on this.
cheers
Mark
A couple of other things to pull out of the Portmeirion (LON:PMP) results:
Berksbee has already mentioned Carrs, I feared it might follow some of the grief Anpario described yesterday but it seems to have escaped (so far?). Wickes seems ok too in very tough markets but oh dear I can hear the bugles playing the last post for INL. I know I was warned strongly and quite rightly on here to get out but I could n't help hoping somewhere in that mess was a proper business, now I get it, it will move to the uncomfortably large capital loss column today, no doubt in messy increments.
Hi JASVFS,
Thanks for flagging that there's an update from INL. I've had a quick skim. Doesn't sound as if the company is completely dead yet, but does need a raise to keep the lights on (and pay the fees for PriceWaterhouse no doubt!) saying -
Separately the Company announces that it is contemplating a fund raising of up to £5 million, to be implemented at 10 pence per share, being the nominal value of the Company's shares. It has received indicative support for around half of this amount and is progressing discussions in this regard. Completion of any such fund raising would be subject to customary formalities and launch.
It's probably best to mentally write INL shares down to zero (which is what I've done with WAND) then you get the disappointment out of your system quickly, and if there is any value left in the shares, it's a bonus!
We all make mistakes, and sometimes things happen that you couldn't possibly have foreseen. All part of the joys of small cap investing! Then occasionally we get a multibagger that mops up all the losses.
Best wishes, Paul.
Just over a week to go for Q1.... so far FTSE 100 +1.5%, 250 -0.5%, S&P 500 +2.5% and Nasdaq +11.5%.... all to play for.
I was hoping for a pause last night....but as it happens the increase of 25bps looked more like a pause... Bonds up strong, $ down, Gold up etc...equities sold off after Yellen said ALL deposits were not insured but reacted well beforehand. The bond market seems confident.
Yet in the UK...the inflation print was strong - grabbing headlines at 10.4%. ....services a more palatable 6.6% and core 6.1%. My best guess is most of us on here are getting on a bit and not in our 20s. We can do our bit actually for the environment, the cost of living crisis and our wallet by simply consuming less. Subtle adjustments can take the sting out of the inflation tail..... One way or another the bond market and the inflation data are going to have to meet up at some point....
Anyway I like $ down...good for all sorts of things... esp UK and retail and retail prices.....market seems to think Fed is done here.... let's hope the numbers support this without getting out of control.
If the rest of the year pans out like this we probably all make a little money so let's not get too stressed and minimise the aging process.
Agree RD. Whats interesting is for all the panic and fear over bank runs, bank contagion, credit tightening etc etc the S&P is still trading in the middle of a 10 month sideways move. VIX is dropping back to more normal levels and the dollars dropping.
I'm looking at- 'definitely not QE' injection by the FED/ rates peaking vs US recession later in the year/something else going pop in the financial system.
No idea which way it'll go, and no point in guessing really. Luckily we can follow price action/ individual company trading and go with whichever way the market takes us.
Thanks for a great review on SCS Paul...
Morning ! The only stock on my radar today is Portmeirion (LON:PMP) who are still looking incredibly cheap with a forward p/e of 7x ! Great results today and nice div too of just under 5%.
I hold SCS (LON:SCS) and wish I'd added more last autumn (buy the dip. always).
But you only know it's a dip after it's gone back up.
Got to know your shares, shipoffrogs ;-)
I sold out of SCS (LON:SCS) about 6 weeks ago, may buy back if the price drops some more.
CARRS (LON:CARR) has exited suspension and the results look pretty decent. The cash from the sales of the Unit that caused the suspension gives a net cash position on the balance sheet. I hope to see a small bounce in the share price on opening.
Morning Berksbee, thanks for flagging that Carr's (LON:CARR) has exited suspension, I wasn't aware, so will move that up the list of priorities to cover today, if there's time.
Best wishes, Paul.
Hi Paul, apologies for my naivete but I assumed the lifting of the suspension would be automatic on publication of the results. Checking further they still have to apply to the FCA to achieve his. I would assume this to be fairly trivial and imminent but I've already been wrong once today. Still worth a glance IMO as good results.