Small Cap Value Report (Thu 23 Nov 2023) - VLX, MOTR, PAY, XPS, JET2

Good morning from Paul & Graham!
Today's report is now finished, I think we've covered the most interesting companies today, in a fairly thorough fashion.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
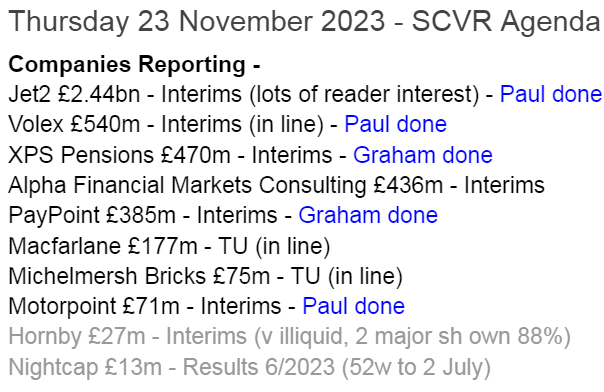
Summaries
Volex (LON:VLX) (Paul holds) - 298p (pre-market) £540m - Interims - Paul - GREEN
Decent interim results, with profit up 16% vs H1 LY. Outlook reassures with in line FY expectations. Balance sheet is still positive NTAV, but goodwill and debt are both increasing, at top end of what I'm comfortable with. Overall, I remain upbeat about this share - a resilient, good quality group, on a cheap rating, I think.
Motorpoint (LON:MOTR) - down 7% to 72.3p (£65m) - Interim Results - Paul - AMBER
Poor H1 results, with a big drop in revenues. Costs cut, but not enough to rescue profitability, which has moved into an H1 loss. Recently, post period end, used cars have plunged 6% in value, in 6 weeks. I'm worried this could trigger another profit warning. So for now, I'm steering clear. Sector read-across also worries me. Could be good longer term though maybe?
PayPoint (LON:PAY) - up 0.5% to 527.4p (£383m) - Results for half ended September 2023 (in line) - Graham - GREEN
These results don’t look very good at first glance, but they are impacted by the normal seasonality of the acquired Appreciate/Love2shop business. I continue to view this as an under-appreciated and under-rated “fintech” stock with many attractive features.
XPS Pensions (LON:XPS) - up 0.4% to 227p (£471m) - Half-Year Report (ahead) - Graham - GREEN
These shares haven’t budged much today despite an ahead-of-expectations outlook and EPS upgrades of 4% for this year and 8% next year. That may reflect the already racy valuation that’s baked in here. I’m cautious on the price but have to keep my positive stance.
Jet2 (LON:JET2) - down 4% to 1084p (£2.33bn) - Interim Results - Paul - GREEN
Straying into mid-caps, as there's so much interest in JET2 from subscribers here. This looks a terrific share, if you can tolerate the sector risk. Low PER, excellent balance sheet, and a brilliant long-term track record. I'm very keen on this too!
Paul’s Section:
Volex (LON:VLX) (Paul holds)
298p (pre-market) £540m - Interims - Paul - GREEN
Volex plc ("Volex", the "Company", or the "Group"), the global supplier of integrated manufacturing services and power products, today announces its half year results for the 26 weeks ended 1 October 2023 ("H1 FY2024").
It reassures right from the start -
Strong revenue growth and margin expansion underpins confidence
in the full year and progress towards five-year plan
Impressive summary (my comments below) -
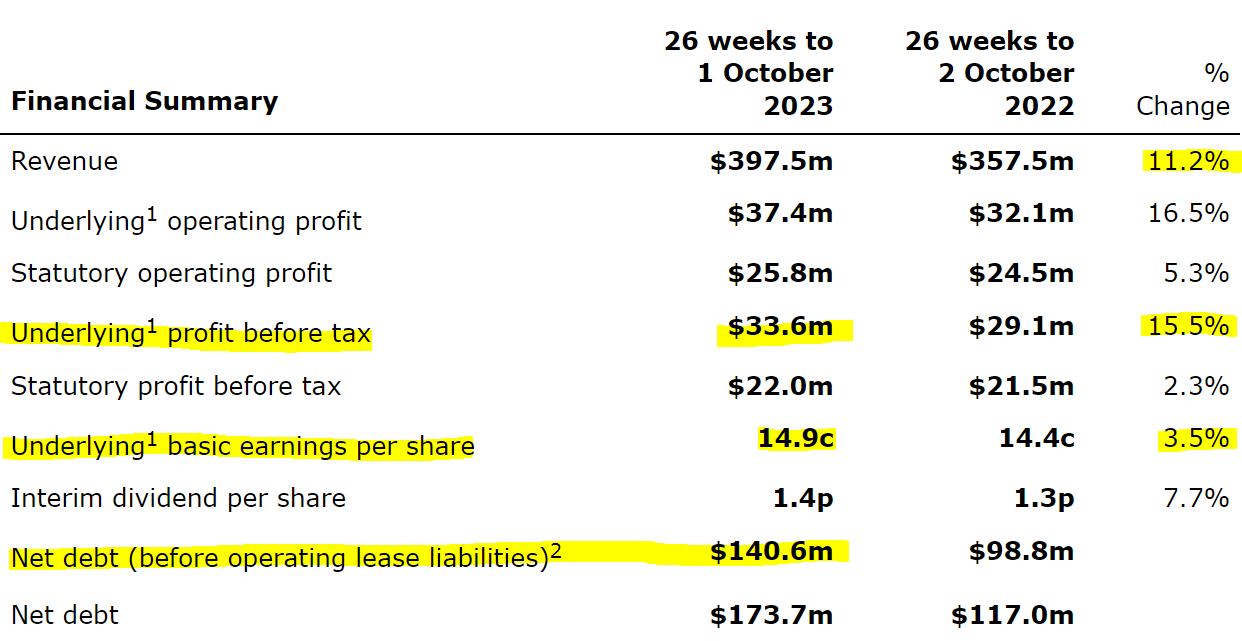
Revenue growth - good at 11.2%, and of this, 4.2% is organic, the rest from acquisitions. That’s pretty good in my view.
Operating margin has risen to 9.4%, vs 9.0% last year in H1 - impressive.
Remember to convert these figures from dollars into sterling! (divide by 1.25)
Acquisitions strategy is causing debt to rise, and the commentary sounds as if management is relaxed about debt.
Adjustments to profit are mainly ($8.6m) acquisition-related (costs of deals, and goodwill amortisation), which is fine. However, note the share options charge is also adjusted out, and is quite hefty at $3.0m in H1.
Outlook - sounds very confident about achieving the 5-year growth plan. Diverse markets provides resilience. Conclusion -
As a result, the Board remains confident in our ability to achieve long-term objectives and meet full-year market expectations.
Valuation -
The StockReport shows consensus of 31.5c for FY 3/2024, rising to 35.8c in FY 3/2025. That no doubt factors in an uplift for recent acquisitions, so there should be a solid basis for this anticipated rise in earnings.
Convert into sterling, that’s 25.2p (PER 11.8x) and 28.6p (PER 10.4x) - good value, but don’t forget the $141m (£113m) net bank debt, which needs to be adjusted for, which is 21% of the £540m market cap.
Given the consistently resilient trading reported this year, and allowing for net debt, I think this share remains good value. Also management don’t seem to be given any credit for the successful acquisition strategy. Once the next bull market starts, I think there’s scope for Volex to re-rate upwards from a PER of 10.8x, to something more like 15-20x. That in itself provides nice upside, even without any earnings growth. The same can be said for lots of decent quality small-mid caps, and I think people sitting in cash could end up kicking themselves for ignoring these buying opportunities, once markets have recovered. Although taking a bolder approach does expose us to profit warning risk, which I see as offset by upside from takeovers.
Balance sheet - intangibles are growing, due to the acquisitions strategy, now totaling $254m. However, NAV is higher, at $312m. So NTAV of $58m is tolerable. As long as NTAV stays positive, I’m relaxed about this.
A resilient, cash generative business can handle a reasonable amount of debt, although it’s now at the top end of what I’m comfortable with.
Cashflow statement - quite good cash generation in H1 vs H1 LY at $25.6m post tax & interest costs (LY H1 $8.2m). These numbers are dwarfed by acquisitions activity, with $131m paid out, funded by $106m of increased loans, and $72m fresh equity raised.
So investors here need to be comfortable with the acquisitions, as that’s key to the growth strategy. It seems well thought out, and VLX has established a good track record for buying reasonably priced, decent quality companies to bolt on. They seem a logical fit, and VLX knows what it’s buying, given that it has a quite narrow sector focus on electrical connection equipment. Hence hopefully acquisition risk would be fairly low. The Exec Chairman explained the process for acquisitions in previous webinars, which can involve quite a long-term getting to know each other process before a deal is sealed, especially where it's a retirement sale, where cultural fit is important to the vendor.
My opinion - remains very positive. I see this as a successful acquisition-driven group, that doesn’t seem to have put a foot wrong, despite the pandemic, energy crisis, and tough macro.
Buyers are getting a lot for their money I think - a decent quality business, that’s performing well, with a good growth strategy, at a reasonable price. Thumbs up from me, I’m very happy to stick at GREEN. It's only a small position for me at the moment, but I want to increase (hopefully before it re-rates!)
I’ve not read all the commentary yet, just the key bits, as I wanted to get this section out by 8am.
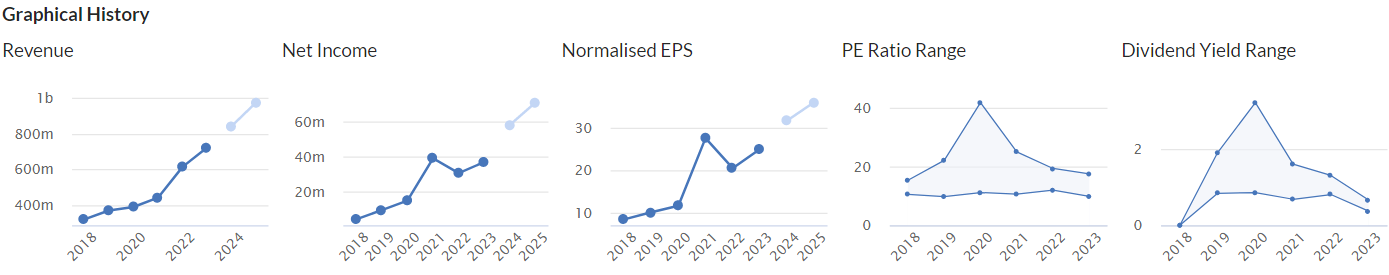
Given the chaos of recent years, this is an impressive track record -
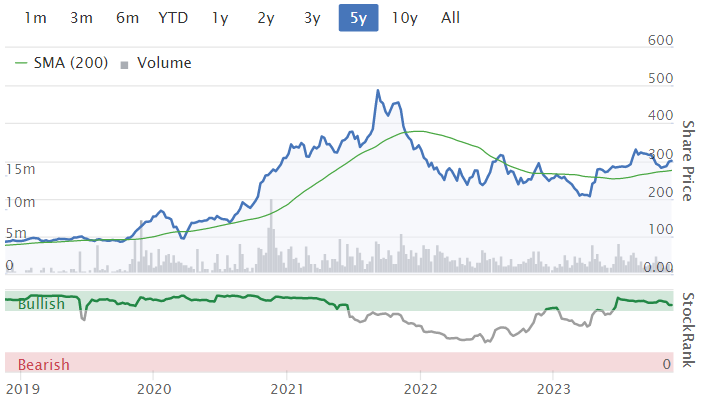
Looks like it's formed a base too, and a good StockRank -
Motorpoint (LON:MOTR)
Down 7% to 72.3p (£65m) - Interim Results - Paul - AMBER
Motorpoint Group PLC, the UK's leading independent omnichannel vehicle retailer, today announces its unaudited interim results for the six months ended 30 September 2023 ("H1 FY24").
The waffly, PR headline suggests to me that these numbers are going to be bad! -
Positioned to navigate continued market challenges, whilst building strategic capabilities to lead in market recovery
They are bad - this is a big drop in revenue -22.8%, and the H1 profit LY has turned into a loss this time -
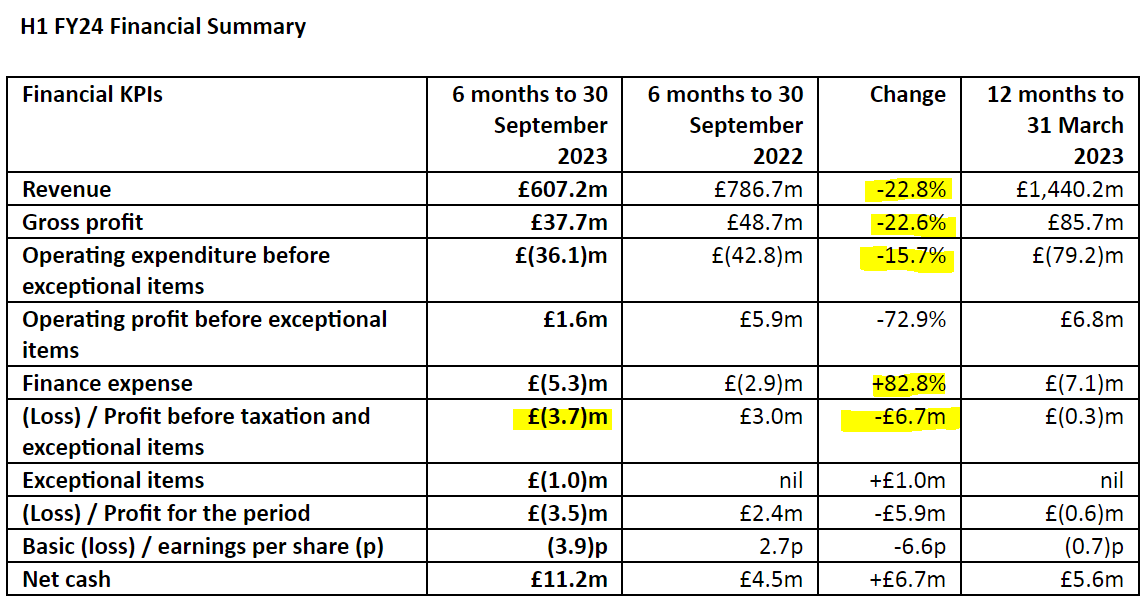
Also note the big increase in finance costs.
Thankfully it has reduced operating costs by £6.7m by reducing staff numbers (by 12%) and marketing costs.
At least cash is OK, with net cash having risen to £11.2m, and an undrawn bank facility. Although I think this excludes vehicle stocking loans (yes it does, see below).
Other points -
Reduced customer demand due to cost of living, and higher interest rates.
Prioritising unit profit ahead of sales growth.
Paused new site expansion now (after Ipswich opened) - a good idea when a format isn’t working. It currently has 20 sites - these are car supermarkets, so typically large, out-of-town plots with shed-type buildings are large open air parking areas.
Outlook -
The impact of high inflation, interest rates, and consumer uncertainty continues to affect demand for used cars.
This is impacting the value of used cars, which has fallen since the end of the period, with a reduction in wholesale values of c.6% in just the last six weeks.
Whilst we have taken proactive measures to limit the impact on our stock, the current environment is likely to be volatile as new car supply into the used car market begins to increase. Our lean cost base means that we are well placed to weather this period and the correction in values bodes well for next year and beyond as the used car market begins to normalise.
Key elements of a normalised market are already underway, including an easing interest rate environment, continued corrections in used car values, and an increase in market size as demand grows and supply is bolstered by new car registrations feeding into the used segment. Motorpoint is a leaner and more agile business, and is ready to seize the significant growth opportunity as market conditions improve.
The rapid fall in used car values since the period end is unquestionably a near term challenge, however it also provides reassuring signs of supply finally beginning to improve in the nearly new market that we have dominated in the past. I believe next year will be a key turning point for the market and I look to the future with confidence.
The most striking point above is that used car values are now falling fast (-6% in the recent 6 weeks!) from the elevated levels in recent years that was caused by lack of supply. With new car supply starting to normalise, that’s clearly feeding through to improved used supply, hence lower prices.
Does this mean the bonanza for the franchised dealers is now over too, I wonder?
Is it time to bank profits on Vertu Motors (LON:VTU) (I hold - small position) I wonder? Although someone would probably bid for it immediately after we sell, after waiting years for a bid! There aren’t many listed car dealers left, after a flurry of takeover activity. The listed conventional dealers have several profitable activities, especially aftersales, whereas Motorpoint just does used car sales and finance commission. So it’s much more focused, which is obviously hurting its profitability in the short term. Is it a viable business model longer term though? I’d say probably yes, because it has made profits in the past - although that was before all the new, online only entrants moved into this space. So maybe MOTR’s business model is now damaged or broken? Only time will tell.
Balance sheet - is quite small, with £32m NTAV (although mkt cap is now only £65m). It looks well-structured to me, with £144m inventories (all the cars), mostly financed with stocking loans of £102m. So the £11.2m reported net cash is misleading, as the real net debt is £91m once stocking loans (which is debt!) are included. That goes up to £153m net debt once leases are included, but I don’t include them personally.
It would be interesting to find out who provides stocking loans to car dealers, and what the terms are - e.g. any covenants? Risk of withdrawal of those stocking loans is important, as that would kill the business instantly, although that sounds very unlikely.
Paul’s opinion - I’m in a quandary on this. MOTR shares are now very cheap compared with historic levels. I don’t see any signs of financial distress here, and a £(3.7)m H1 loss before tax is weak, but not a disaster. What happens in H2 though? With a sudden, recent 6% drop in wholesale prices, that implies its £144m inventories might have just fallen in value by up to £8.6m, which due to fast stock turn, could possibly be a hit to profit in H2.
Shore Capital (house broker) updates today, and reiterates its FY 3/2024 guidance, expecting an improvement in H2 profitability. It’s expecting breakeven in H2. That doesn’t seem at all consistent with the profit hit from plunging used car values in the last 6 weeks, so I don’t understand that stance.
Zeus has very similar forecasts. Thanks to both for publishing their research, although we should always bear in mind that forecasts are frequently wrong, as nobody can predict the future with certainty.
I like investing in shares where the forecasts look far too modest, and then enjoy the profits from the subsequent out-perform update. MOTR looks the opposite to that. I struggle to see how H2 is likely to be better than H1. Although yesterday’s Autumn Statement will be pumping additional cash into consumers pockets (giving back some of the PAYE plundered from us through fiscal drag!) from Jan 2024, and the considerable increases in Living Wage, pensions and benefits from April 2024 could trigger increased consumer demand, as inflation falls to an expected 2.8% by end 2023. So macro could actually turn positive in the coming months. Will that be enough to rescue FY 3/2024 results for MOTR though?
I suspect this share could have another profit warning in it, maybe in early 2024. Although I also think there are credible reasons to start to anticipate something of a recovery in calendar 2024. Possibly.
As to whether MOTR’s business model is damaged, or broken, from much more online competition, I just don’t know at this stage. Although performance in recent years suggests to me that it’s been considerably damaged by increased competition. Will that competition survive though? They don’t make any money either, and spend huge amounts on advertising, so their deep-pocketed backers could pull the plug, giving back some market share to MOTR.
I just can’t decide, so will sit on the fence with AMBER.
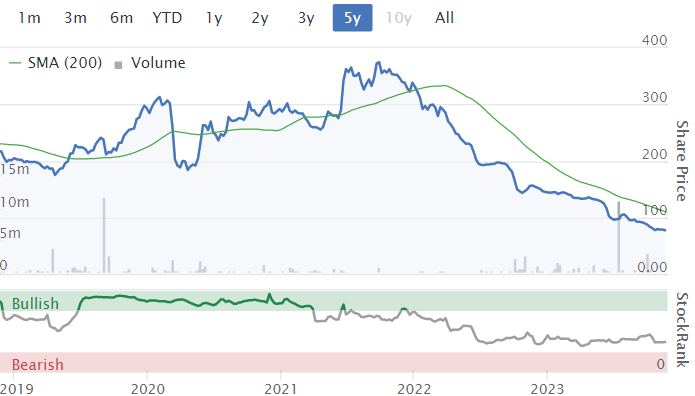
In permanent decline, or poised for a powerful rebound? -
Jet2 (LON:JET2)
Down 4% to 1084p (£2.33bn) - Interim Results - Paul - GREEN
I’ll have a look at this holiday/airline business, as it’s the readers’ top share of interest today, and I’ve followed it for many years, when it used to be an obscure little freight airline and distributor called Dart Group. It roughly 100-bagged from the lows, but there wasn’t really any indication at all that this was going to be the outcome, as is often the case with major multibaggers. As Ed pointed out in his brilliant recent multibaggers webinar, the major winners can often come from unlikely, and apparently quite ordinary businesses. Also Ed pointed out that they’re often cheap, value shares at the start of their multibagging journey. Dart Group definitely was. I remember looking at it with David Stredder, and we couldn’t understand why it remained stuck at about 75p, despite being on a really low PER. I gave up in disgust in the end, as it refused to budge. Whoops! Patience is a virtue in shares, definitely, and I don’t have enough. Many investors see long-term as after lunch, so at least I’m not that bad!
Conventional wisdom is to avoid airlines, so again, an unlikely winner. It must all be down to good execution from strong management, something that’s not always easy to pick up on, when management are publicity-shy, and just get on with the job rather than promoting the shares.
Philip Meeson is still the largest shareholder, at 18.3%, is stepping down soon I believe, having taken JET2 from a minnow to a giant. What a remarkable career, hats off to him.
[This table appears on the Stockopedia home page every day]
Interim Results - for the half-year ended 30 Sept 2023.
No fancy PR BS headline here, JET2 lets the numbers do the talking -
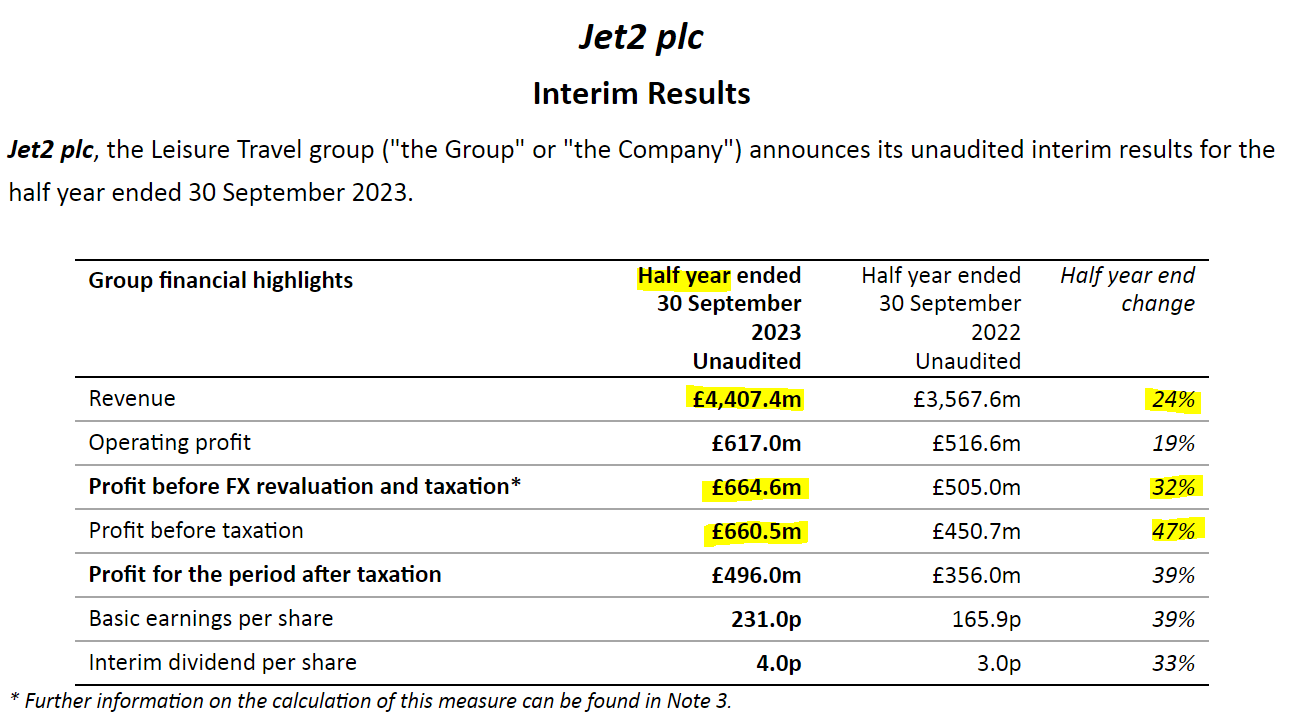
Full year forecast consensus revenue is £6.2bn, so there’s clearly a big seasonal bias towards H1, being the summer season for holidays. Hence we cannot just double the above figures to annualise them.
Load factor (seats filled) flat at 90.7%
Package holidays (higher margin) now make up 70.8% of passengers (LY: 65.9%)
I'll skip over the rest of the detail.
Outlook -
Some short term caution - it will be interesting to see if the recently announced NI cuts might stimulate demand? -
Although bookings have been a little slower in recent weeks with average load factors currently 1.3ppts down on Winter 2022/23 at the same point, average pricing to date remains robust.
We are currently on track to deliver Group profit before FX revaluation and taxation for the year ending 31 March 2024 of between £480m and £520m, in line with our previous guidance.
Canaccord has kindly done the number-crunching, and shared it on Research Tree (many thanks to both). It forecasts £500m adj PBT, bang in the middle of the company’s guided range. This is 160.3p adj EPS - for a PER of 6.8x - gosh that’s cheap! In old money that’s an earnings yield of 14.8% (the inverse of the PER, and much more useful I think).
Very modest divis of 14.5p are forecast, yielding only 1.3%, but covered 11x by earnings, so JET2 has scope to become a bigger dividend payer longer term, should management decide to adopt that policy.
Balance sheet is large, and quite complex, with various ways of looking at cash, and net cash, as the reader comments today show!
I tend to fall back on NTAV as a good overall view, and this is £1.57bn. That is 67% of the market cap, so JET2 has very healthy real asset support for its share price.
Cash + money market deposits total a huge £3,215bn, but “Borrowings” total £761m, so I would say net cash is £2,454m. So plenty of interest should be earned on that. Indeed finance income in H1 was £80m ,exceeding finance expenses of £(33)m.
Note that deferred revenue creditors total £1,121m - this is the credit entry to reflect the amount within the cash pile that has been received from customers up-front. So to be prudent, we should take this off the £2,454m net cash pile, giving £1,333m of net cash which JET2 can call its own.
The commentary claims “own cash” of £2,121m, which is gross cash, not net cash. Deducting the £761m debt above, comes to £1,360m net own cash, which is near enough to my figure of £1,333m. So this is the most prudent measure of net cash, and it’s 57% of the market cap - so a tremendously healthy cash position, in my view.
Also remember that JET2 owns a load of aircraft too. The last Annual Report shows £877m NBV of “aircraft, engines, and other components”. Only £20m in land & buildings, so JET2 doesn’t seem to like (or need?) much in property.
It also leases aircraft, with £530m NBV of leased aircraft, engines, etc. So I make that about 62% of the aircraft & similar by value, are owned rather than leased. Sounds nice and prudent.
Paul’s opinion - it’s been a long time since I last reviewed JET2, and I have to say, these numbers have delighted me. What I see is a remarkable business, that has been built up by an obviously brilliant entrepreneur, and clearly serves an excellent niche, providing affordable holidays to households mainly in the Midlands & North of UK.
The valuation statistics look terrific - a lovely low PER, excellent asset backing from a prudent, strong balance sheet. The only missing piece is divis, but those should naturally flow as the business matures.
The only downside risk I see is sector risk - are investors so keen to own travel companies now that we know the go-to response of politicians is to shut them down when a nasty bug appears? That could mean the whole travel sector deserves to be on a permanently lower rating than pre-pandemic.
Overall though, I very much like what I’ve seen on a quick review of this share. It looks excellent. Definitely a GREEN from me!
Graham’s Section:
PayPoint (LON:PAY)
Share price: 527.4p (0.5%)
Market cap: £383m
The headline for these interim results inspires confidence:
Strong revenue growth across the Group and significant progress with ongoing business transformation
We already had a trading update in early September that was in line with expectations. These interim results take us to the end of September:
Today’s results confirm that net revenue is up, but profits are lower (both “underlying” PBT and actual PBT).
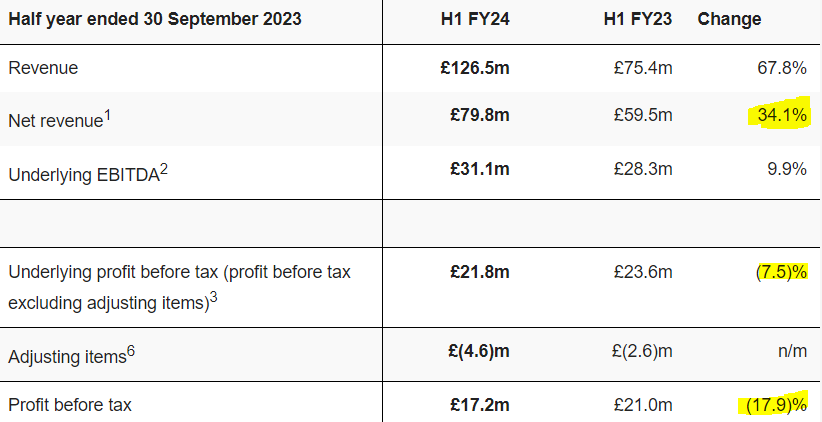
The £4.6m of exceptional/non-underlying items comprise £4m of amortisation and £0.6m of one-off items.
The gift voucher and Christmas savings group Appreciate was acquired in February 2023, so this latest H1 period (March to September) is the first period which includes Appreciate’s revenues and H1 losses.
“Love2Shop” (the new name for Appreciate) generated a £1.8m loss in H1, which is the same as the amount by which PayPoint’s overall underlying PBT declined in H1. So I think it’s fair to say that the original set of Paypoint businesses has had a flat performance.
The good news is that Love2Shop is a seasonal business, and PayPoint investors can look forward to a positive contribution from it in H2.
CEO’s comments refers to a difficult economic backdrop and reduced revenues from energy payments:
This has been a positive half year for the PayPoint Group with a period of significant activity supporting a number of key initiatives across the business…
It is testimony to the transformation of the business that we continue to deliver overall Group net revenue growth in a period where energy sector net revenue has decreased by almost 20% and against the background of uncertain consumer behaviour and weakening confidence due to the Cost of Living challenges.
He also notes that “trading momentum has remained strong into the second half of the year” (more on that in the outlook).
The company has a total of four divisions, so there’s quite a lot of detail, but the main points are:
Shopping (i.e. the convenience store business) - net revenue up 4% to £32m.
Payments & Banking- net revenue down 2% to £25m. Cash payments are falling and energy payments greatly reduced, in part due to “unseasonably warm weather”.
E-Commerce (parcel pickup/delivery at Collect+ in partnership with Yodel, Amazon etc) - net revenue up 72% to £5m.
Love2shop - £17.5m of revenues. Lots of restructuring and change seems to be happening here. Park Christmas Savings has started growing again.
Outlook
This is in line with expectations.
The word “momentum” is mentioned 13 times in today’s RNS.
The energy business is showing “a more resilient performance early in H2”; hopefully its poor performance in H1 is not representative of a long-term trend.
Interim dividend - 19p, vs. 18.6p last year. It seems reasonable to give shareholders a small increase, as it is well covered by earnings (there is no “final” dividend in addition to the interim dividend).
Note that the interim dividend is paid in two equal instalments of 9.5p each, in December and March. I’m not sure why they do it this way but I have no objection!
Earnings per share - 17.4p in H1, or 22.4p on an underlying basis. The share count is up and the tax rate is up. So these numbers are quite a bit off H1 EPS last year (24.7p / 28.1p underlying).
Estimates - Liberum has a full-year EPS forecast of 66.4p for the current financial year (FY March 2024), presumably based on adjusted earnings. Strong seasonality is expected in H2 with gift vouchers and Christmas savings activity, etc.
Net debt was £83m at the end of September. With £69m of EBIT due this year, again according to Liberum, Paypoint’s leverage continues to seem reasonable.
Graham’s view
I’ve been a fan of PayPoint for a long time, so I’m at risk of becoming a broken record.
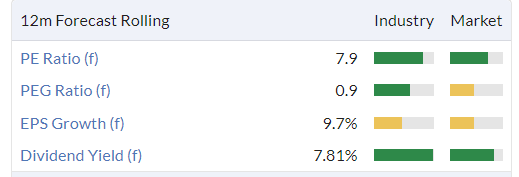
It tends to trade cheaply:
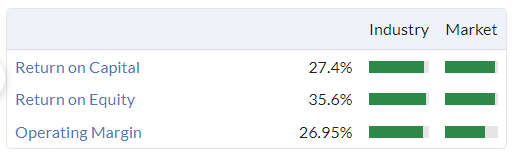
This is despite being a high-margin, high ROCE business:
My favourite aspect of this stock is the importance of the “PayPoint One” terminal to so many convenience stores. However, the other parts of the business are interesting too and while they may not have the same market share, I still think they are important parts of the retailing/shopping infrastructure (I was a fan of Appreciate for many years and formerly held shares in that one, too).
It’s unthinkable to me that I wouldn’t give this stock the thumbs up at a PER of 8x and with current trading looking so robust. But of course I may have missed something - if cash payments declined very rapidly, for example, that could take a bite out of profits. And I acknowledge that it will be a challenge to hit H2 numbers, with quite a lot of seasonality being priced into the forecasts.
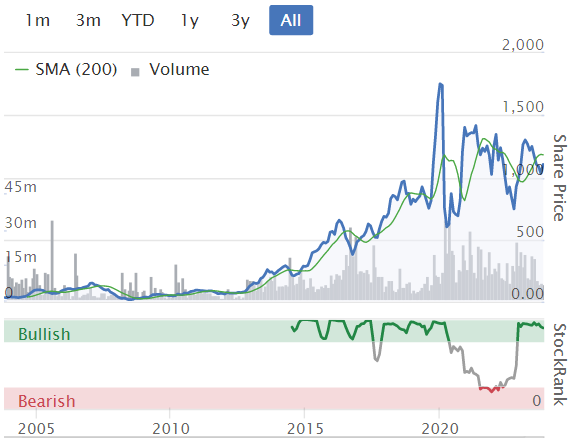
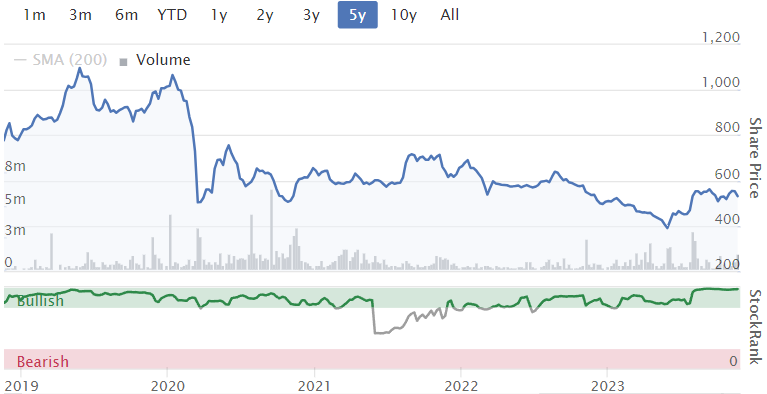
It has been a while since the market has shown much interest in PayPoint:
XPS Pensions (LON:XPS)
Share price: 227p (+0.4%)
Market cap: £471m
This is a consultancy on workplace pensions. The shares have performed remarkably well in recent years:
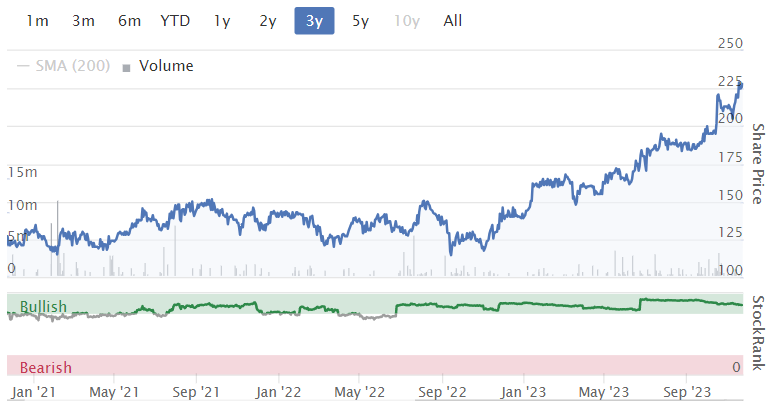
I’m encouraged to see that I give it the thumbs up in June (at 170p), despite it being “a little expensive”. Strong organic growth with recurring, inflation-linked fees were impressive enough to push me into taking a positive stance.
That theme continues today with more signs of strong growth. The momentum in the advisory revenue streams (actuarial/investment consulting) is particularly striking:
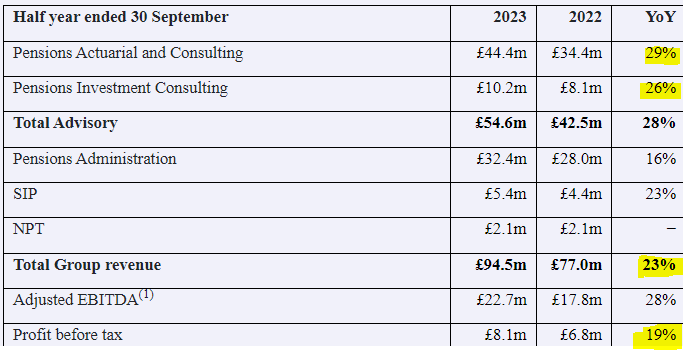
It has two advisory revenue streams: Pensions Actuarial and Consulting (the larger division) and Pensions Investment Consulting.
The company tells us that this is “the eighth consecutive half year of YoY growth in revenues” at its advisory and administration divisions.
Recent news and outlook: the company has been appointed to the John Lewis pension scheme, and sold a division (National Pension Trust) in July for up to £42.5m (including defcon), which will enable a deleveraging of the balance sheet. XPS will continue to generate revenues from work on the NPT even after the sale.
Outlook is ahead of expectations:
The strong first half financial performances underscores the resilience and predictability of the XPS business model. We expect the demand for our services to remain high underpinned by both market and regulatory tailwinds as well as the strength of our brand. The business continues to trade well in H2 and combined with the completion earlier this week of the EPS accretive sale of NPT, the Board are confident of achieving overall full year results ahead of its previous expectations.
Estimates: Canaccord Genuity have upgraded the EPS forecast for the current year (FY March 2024) by 4%, thanks to better-than-expected trading and a reduced finance cost from deleveraging. FY March 2025 sees an even bigger 8% upgrade to EPS expectations.
Market commentary: there are some comments on the state of pensions in general which should be of general interest.
In general, most defined benefit schemes are in a healthier financial position than they were. Schemes continue to need to re-look at their long-term objectives and strategies to reflect the 'new world' of higher long term interest rates and funding levels. This has driven significant demand for advisory services, and we expect this to continue. XPS is well placed to meet this demand with the depth of capability we have.
This is a theme we’ve been following at the SCVR: higher rates boosting the health of pension schemes, sometimes making formerly uninvestable pension sinkholes becoming investable businesses again.
I suppose that any general change in conditions - positive or negative - can drive demand for advice from consultants. In this case, a positive change is driving demand.
Then there is the question of whether there will be changes to overarching pension rules:
Pension funds have also been the subject of Government scrutiny and newspaper headlines, with focus on asset allocation and whether changes could be made so that the very large sums of money in the pension system make an increased contribution to long term growth in the UK economy. This is a live, ongoing debate with cross party support for change and we have been pleased to be an active participant including attending meetings with Treasury and the Bank of England. The timing and extent of future developments is still unclear, however any changes to the system are expected to drive demand for advice from our clients.
Again, any change drives demand for advice.
Graham’s view
I’m certainly going to keep my positive stance on this share - the analyst’s equivalent of “letting my winners run”.
It remains more expensive than I would normally wish to pay for a consultancy:
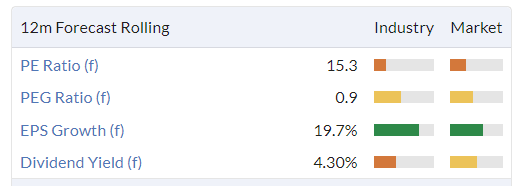
However, XPS seems to be a much better-than-average consultancy. I keep going back to those recurring, inflation-linked fees: not many consultants benefit from that!
One important point to be aware of is that the stock does look horribly overvalued if you use the unadjusted numbers (e.g. profit after tax in H1 was only £5.5m). So if you’re interested in this one, I’d strongly recommend taking a look at the adjustments and satisfying yourself that they are reasonable:
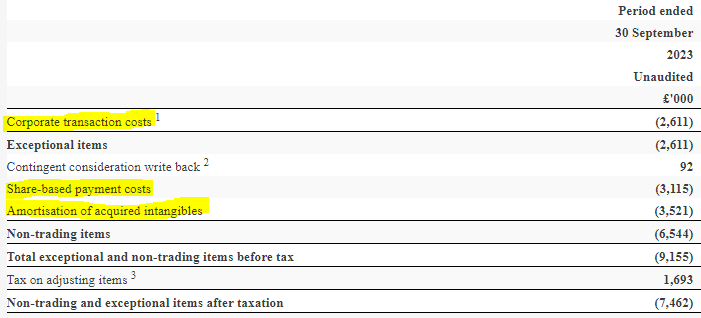
Once again, I would have to insist that the share-based payments (£3.1m) are a real cost. The others (adding up to £6m) can arguably be adjusted out.
It remains very expensive, but my sense is that XPS has done enough to justify the premium valuation. So my thumbs are staying up for now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

94 comments
.....and I trimmed my Vertu Motors (LON:VTU) holding by 100% on seeing the same news.
I see Card Factory (LON:CARD) has taken a sizeable hit today, down 7%. Have I missed something here? I know a trading update was expected and hasn't arrived, plus some budget announcements yesterday could have has an impact, but I would not have thought to this degree. Motorpoint (LON:MOTR) is down by less on a disappointed trading update!
Is this just a case of Teleios taking their foot off the gas for a few weeks to let the SP climb so they can sell into the market rise? Topped up a little after trimming Vertu, but fear it could go lower. Longer term, they can't sell forever, they only have a limited number of shares and once it's cleared there is surely a runway to push higher and higher.
Card Factory (LON:CARD) has been doing this for awhile now, getting upto around 113p and then falling back to the high 80s. I nearly sold hakf yesterday as I thought it may fall back. Can't see any news.
Card Factory (LON:CARD) That's right, there've been quite a few irrational 5-10% drops over past 6 months or so, often on the back of good results. The general view is that one of the big shareholders are steadily reducing their position.
Cockney Rebel posted on X a link to an article in the Retail Gazette today regarding forecasts for Xmas 23 and there are comments from Card Factory CEO in there - "Darcy W-R also expects value for money to be a key driver his Xmas, with the retailer upping its value messaging ahead of the holidays.......says its pet greeting cards (!!!!), which have been some of its fastest growing lines this year, will be a big seller this Xmas. The retailer has also launched a pet gifting range across 300 of its stores".
Probably also worth mentioning that the minimum wage increase will potentially impact "lower end" retailers more. Personally I dont buy into that argument.
Minimum wage increase was announced yesterday so surely any impact from that would have been felt on the day, not 24 hours later. Also doesn't appear to have affected other discount retailers, such as Shoe Zone (LON:SHOE) which was slightly up today.
I joined Dart Group (formerly Channel Express Group) in 1989 as Group FC and left in 2005 when it was Jet2.com. and the HO/operation moved from Bournemouth to Leeds/Bradford airport. From humble beginnings as a freight airline and transport company it now has a mkt cap of £2.33bn. Its success was down to the strength of the management team during this period with strong financial controls in place supporting the balance sheet which generated positive cashflows. It was an exciting time but hard work and as a Bournemouth boy I am very proud of the success of Jet2. I have nothing but admiration for PM and what he has achieved.
Thank you for the analysis on Volex (LON:VLX) which I hold.
The debt makes me uncomfortable and I have always followed Robbie Burns’ maxim of not investing in companies where debt is greater than three times profit and indeed I think most of my holding are debt free (though Reach (LON:RCH) has that hideous pension deficit).
So I need to decide whether I need revisit my position. But I like Volex, I believe a proper company producing proper profits, in a good sector and I like management and that Rothschild has a lot of skin in the game.
Regards
Michael.
Not wishing to sway you either way but they are inside 3 x operating cash flow: $173.7 v annualised operating cash flow of (2x $38).
Thank you. Duly swayed
Hi Michael,
It might sound obvious, but I think we might be able to stretch the EBITDA covenant a little when the boss and major shareholder has the surname Rothschild, and floats around near Corfu on a mega yacht when he's not busy.
So a reduced worry maybe, given that he owns 25% of VLX?
Debt situations are NOT all the same. Surprised other people havent picked up on this obvious point.
Regards, Paul.
Volex (LON:VLX)
The slides from the presentation are now available here.
Slide 13 Cash Flow shows: "Covenant net debt : EBITDA ratio at 1.3x"
Slide 21 Capital allocation to deliver sustainable growth shows: "Target net debt to EBITDA of 1.0 - 2.0x (based on covenant net debt which excludes IFRS 16 leases)"
That's alright then, except that I couldn't work out the quoted ratio - looked much bigger. I then found this in the RNS report:
Covenant leverage represents the ratio of net debt, excluding operating lease liabilities, to underlying EBITDA excluding the impact of right of use amortisation arising on operating lease arrangements, adjusted to include the EBITDA from the last twelve months of acquisitions on a proforma basis. This measure is aligned with the covenant calculations used for external debt facilities.
(for us PIs presentation is on IMC Monday morning).
Thank you so much for this. Will look in detail tomorrow.
Regards
Michael
Thanks Paul and yes that has been my thinking when I have my optimists hat on but with my cynic’s hat on I sometimes find myself thinking he is so loaded that if it all goes tits up, he might so rich that the loss would be pocket change. To quote:
“His estimated net worth is around $1 billion, but Nathaniel Rothschild is reported to be in line for a $40 billion inheritance set up in Swiss trusts - and this may be a very modest estimate.” - TheRichest.com.
That said I like him when I meet him at drinks parties (joking) when he does shareholder presentations so for now will stick with it.
Regards
Michael.
Norcros (LON:NXR) for those who missed the Webinar here is the full video recording: CEO and CFO giving a snappy review of results / ambitions, then 30 mins of engaging Q&A with the PI audience:
Norcros (LON:NXR)
Cheers - would be nice it catchup article was done on this one if time ever permits - seems to have been crazy busy with updates the last 10 days or so i guess they cant all be covered here always.
Paul. I hope you picked up some discounted Volex (LON:VLX) (I hold) this morning. Amazing daily price move on Volex (LON:VLX) . Forming a big hammer. Good volume too.
Hi Revs8,
Paul. I hope you picked up some discounted Volex (LON:VLX) (I hold) this morning. Amazing daily price move on Volex (LON:VLX) . Forming a big hammer. Good volume too.
I don't have any spare cash at the moment, and there's nothing I want to sell to raise any cash. Also, I don't really worry about the initial share price reaction to announcements from small caps, because it can often just be kneejerk reactions from small traders, or people who need liquidity (e.g. funds facing redemptions, or stop losses triggered). Hence that initial price move on a small, handful of trades, doesn't necessarily mean our analysis here is wrong. The sellers might need the cash, or just latched onto something negative-sounding, who knows? And who cares?
Although if it had been a big position of mine, I would have dropped everything and re-read every word of the RNS, to make sure I hadn't missed something important!
As always, it's a careful balance between being confident in your own analysis, but not over-confident!!!
Thankfully I'm looking sensible, and it's not me who's the muppet - today, at least LOL! ;-)
Regards, Paul.
I hold VLX having picked some up at 250p in the spring. I added more this morning (even a stopped clock etc…). Personally my initial observation to interims was how little EPS accretion there was given the dilution. I think possibly this is what disappointed traders first thing. Like others I think it looks like a ‘solid’ business with moderate but improving margins, a clear acquisition strategy, momentum and resilience (or so the board keep telling us - and I know nothing to the contrary). My one hang up is whether there is much runway beyond the five year plan. I see this as a doubler, but once that goal is reached, without evidence of a far larger market opportunity the ‘fair’ PER may be 10-12 after all? Of course IF there is a much larger prize out there (without undue dilution), we could even see multiple expansion…but I know little of the immediate and adjacent market opportunity. Can anyone comment?
It was very hard this morning to not get fooled into making the knee jerk reaction! Fortunately I didn’t.
Just noticed that new directors at Argentex (LON:AGFX) have been buying reasonable chunks at current prices - over £100k in total. So looks like they are bullish on the business prospects at least.
Does seem to be quite a lot of director buying in decent size in general at the moment. A clear sign we are close to the bottom when collectively but independently boards are buying shares at same time.
Vertu read across and Pressure tech / restore
Not liking the motorpoint comments on falling prices so trimmed Vertu holding by 10%.
Listened to Richard Staveley few days ago and after reading the Rockwood report there’s has been a surge of interest in a Pressure tech / restore .
Not sure if the price jumps of both are due to his comments but seems more than a coincidence and doesn’t take much buying pressure to spike these up.
Both look good turnaround stories .
Pressure tech I like because very easy to keep an eye on as they are opposite us .
Restore has returning CEO, . Director buying and looks a relatively straightforward thing to execute .
Bought both quite heavily yesterday morning and both up 10-15% in 24 hours which doesn’t happen very often.
Motorpoint (LON:MOTR) & Vertu Motors (LON:VTU) falling prices are a positive for the industry, it's a sign that new car production / volumes and price inflation are on the road to normailty.
Reduced prices will improve affordability, which will drive demand, which will drive more production and volume. It's the start of the turn in the cycle for the positive.
a couple of very(!) chunky trades on Motorpoint (LON:MOTR) today
3.5m~ shares a piece - wonder who is buying or selling!
(incidentally, the top shareholder data for Motorpoint (LON:MOTR) is wrong; i have already mentioned this to the stocko-team)
Most of the shareholder data are wrong and it’s something that needs to be improved immediately. But if you suggest or ask anything the answer is : the provider hasn’t updated it!
Well done! I agree Restore looks straightforward and Pres hinges on the sale of the PMC business, hopefully in the next 6-12 months, after which the turnaround should really gain traction
Pressure Technologies (LON:PRES)
I also added recently before the Richard Staveley's interview with Paul Hill, which it would appear gave some impetus to the shares. Early days but it may also be that there has been some interest in the PMC division that has recently been put up for sale. Should that complete at a half decent price that will in my view certainly energise the share price.
Hi planetx,
Nothing wrong with taking your profit but Motorpoint and Vertu cannot be classed as the same. As for Pressure Technologies I agree with you.
Yiannos
Yes agree not the same at all .
Just the softening in 2nd hand car prices will certainly mean a stock provision / revaluation for vertu (it should do anyway) .
Fortunately for once I timed vertu well and bought most of my holding when it dropped sub 50p .
It was my 4th biggest holding and a full position, as I run a very very concentrated portfolio just felt a slight shave of 10% was a decent shout as it’s a “sign” .
I have to have strong convictions in these top 5 holdings and vertu just moved from a 9/10 to an 8/10.
Also wanted a little liquidity to replace part of the cash I deployed yesterday into pressure tech / restore / pennant and a 10% slice on vertu sorted that out .
Motorpoint (LON:MOTR) Victoria (LON:VCP) Speaking of waffly pr.Victoria (LON:VCP) 's waffle yestedat was some of the best.I will accept some of it from Tim J D Wetherspoon (LON:JDW if i believe the CEO and numbers stack up. From yesterday's RNS :
'whilst consumer spending on flooring may be subdued during difficult macro-economic conditions, unless people wish to return to walking on mud floors , demand always recovers.'
Brings a bit of colour to a bad RNS for shareholders nonetheless.
The market seems to be buying it though and not letting go of Victoria (LON:VCP) 's past market successes.So if debt becomes too much, they could end up just fine.
Markets definitely give some companies a hall pass and some not........ noticed this over the other side of the pond as well.
With Jet2 (LON:JET2) and other airlines an important figure to track is the deferred revenue because this shows the amount of money the airline has received for tickets on flights which they have not yet flown (£1.1mm for Jet2 at Sept30). In a responsibly run airline, like Jet2, this cash is held to meet the future expenses of the flights. But it is one of the seductive elements which has in the past attracted doubtful operators, since once you start an airline the cash comes in immediately, long before your expenses are due.
Thanks for your very useful evaluation of both Volex and Paypoint. We must do our own research but your views are so beneficial.
I just came across this article from about a week ago. Apparently Amazon are going to be selling new cars through their platform. It appears they have an agreement with Hyundai (or rather some US Hyundai dealers) and I would assume that if things go well they would look to expand the offering with other brands. From my understanding, much of the profits in the 'new car' market are made through upselling, i.e. insurance, maintenance etc. Presumably Amazon will also be offering these types of add-ons.
Amazon have huge visibility and tremendous buying power (with the ability to undercut competitors), along with their very undemanding razor thin operating margins. This type of retailing, along with the likes of tesla and their direct to consumer model, does have the feel of a disruptive period for traditional car dealers.
So over the coming years, it may be that traditional car dealers find that new cars become harder and harder to source and sell at current margins. Perhaps they will have to focus more and more on the used market. Anyway I am sure all of this would take a long time to play out, but worth bearing in mind as it does seem to be an old world model that is currently being targeted for potential disruption.
Amazon says it will soon sell cars on its website (msn.com)
I don't think the partnership with Amazon is a threat to traditional dealers, the partnership is just using amazon's platform as an additional shop front (similar to an AO world company page on Amazon). Amazon won't purchase or hold the inventory, they will just act as a search tool to help shoppers identify available cars for sale in their local geography. So shoppers will be able to search what Hyundai cars are available for purchase straight away in their local area and finalise the sale through Amazon. Amazon i imagine would take some sort of cut / commission on the total value of the transaction, but it will be fulfilled by Hyundai and the local dealership.
So i think its a market place model as opposed to a new dealer model. It would be a potential threat to market places such as autotrader or carwow for example. But not to a traditional new or used car dealer.
But surely if Amazon is best price (which it tries to be on most product lines) then the consumer no longer needs to bother shopping around. Market place or not this will disrupt the traditional dealer imo. Also Amazon has very good customer service and the best product visibility in the entire western world - if they carry this out successfully and are able to scale it up - then surely it has to have a big impact on the future of this industry. Time will tell, but I think this sector could look very different in 10 years time.
XPS Pensions (LON:XPS) has announced its Half Year results. Every area of the business is up. 28% growth in EBITDA. Revenue up. Profit up.
Eighth consecutive half year of YoY growth in revenues across Advisory and Administration:
I'm looking forward to Graham's writeup and I'll leave him to mention the excellent figures.
I Hold.
David.
Interesting acquisition by Wilmington (LON:WIL). WIL had a rather bloated £42.2m net bank cash as at 30.6.23 but has been patient in looking for acquisitions. Today’s it’s spent £16.8m plus a potential £4.8m contingent consideration on Astutis, which provides training for a range of globally recognised and regulated health, safety and environmental qualifications. The RNS refers to Astutis’s turnover in FY to 30.6.23 as £7.5m and PBT of £2.0m. The short form Companies House filings suggest PAT of £1.479m (plausible at 25% tax rate). This gives a post-tax multiple for the initial consideration of c. 11, below WIL’s rating, and before synergies (there should be some savings from Astutis using WIL’s central facilities and buying jointly, even though the areas of training are complementary). With 89m shares, adding trailing PAT of £1.479m notionally increases FY23 EPS by 1.66p. Going back to Companies House, Astutis’s trading was stronger in FY23 than FY22, raising the question whether WIL has caught the bottom of an upward trend or the vendors have picked their moment. The large deferred element derisks this for WIL and shows the vendors are confident.
£pay
Interested in Graham's update on the £Pay Interims which as usual are extremely detailed (perhaps too detailed!)
EBITDA has increased, but net profit reduced for the period. I note that the EBITDA adjustment includes adding back Net Interest expense (up £2.6m on the period). I am not an accountant, but I thought EBITDA was in purer form a way of seeing underlying cash generation, taking out non cash items like depreciation etc.
I don't see Net interest as non cash myself!? Obviously with Christmas bringing a greater H2 weighting to some of their new acquisitions, perhaps this will be more in balance in H2, but arguably it shouldn't be there. More expert opinions gratefully received.
I need to look a little harder at what the plans are to reduce net debt, as they have a highish % dividend yield
I hold
Hi Trident.
EBITDA stands for Earnings Before Interest Tax Depreciation and Amortisation so PayPoint (LON:PAY) are correct to add back net interest for this measure.
The purpose of adding back D and A is indeed, as you say, to remove non-cash items, so getting a measure which is closer to cashflow. The reason for adding back Tax is that taxes on profits can vary for reasons which have nothing to do with business performance (eg a Chancellor changing corporation tax rates). The purpose of adding back Interest is to aid comparisons between companies using different funding structures (debt vs equity) which, like taxes, only indirectly affect business performance.
Personally, I'm not a fan of adding back D. Most businesses with material Depreciation also need to spend a material amount on maintenance capital expenditure to avoid the fixed assets deteriorating. Adding back Amortisation is more defensible if it is writing down goodwill arising on consolidation of acquired companies (as it mostly is) because it is not relevant to the performance of the business - but it can tell you something useful about the effect of past management decisions in acquiring companies. Most companies adjust Amortisation out of their normalised earnings. You do have to watch for companies which are amortising intangible assets which are not goodwill arising on consolidation because arguably that is a genuine business cost (albeit non-cash), particularly if the company is also capitalising development spending as an intangible asset.
As with most other accounting measures, EBITDA can't be looked at in isolation. One has to look at EBITDA, EBITA, EBIT, PBT, PAT, eps etc. to get a meaningful picture (sorry about all the acronyms!). Not to mention, of course, balance sheet and cashflow items. Fundamental analysis is tough!
As for PayPoint (LON:PAY) itself and its valuation, I suspect Graham is a tad generous to call it a fintech. It's always diffcult to plough through their verbose announcements to understand what is really going on. However, I think there may be an old core business, very profitable and cash generative but dying, in facilitating pre-payment cards for utilities (energy and mobile phones), a classic cash cow; and PayPoint (LON:PAY) is forever running fast to stand still, using the cashflow to fund other lines of business with mixed success whilst keeping shareholders happy with juicy dividends. Will the development of the other lines of business ever produce enough growth to offset the decline of the dying business lines? The Appreciate acquisition buys a bit more time because its business model has similarities to the prepayment card business. Also note they have a couple of outstanding cases against them at the Competition Tribunal which could cost them and that's not the first time they have attracted regulatory scrutiny for the way they operate.
I hold, having bought on the back of a high StockRank, been underwhelmed by performance but not quite able to walk away from a low P/E, high yield share which may come good one day (probably shortly after I sell out!).
Hi SheriffJEB
Ah, silly me. I forgot about the 'I' element in EBITDA!
I suppose the danger is when debt & interest payments are high on its own this adjustment can look over flattering when it shouldn't. So we have to look around the other elements of analysis, or reverse out the Interest adjustment ourselves.
Agree with the view that PayPoint (LON:PAY) is using the cash generation characteristics to remodel their trading profile due to the status of the old business.
Hopefully H2 will bring home the goodies for PayPoint (LON:PAY) shareholders.
Excellent post.
Anyone looking at Jet2 (LON:JET2) - seems market didn’t love the update but at first glance looked pretty good to me. Haven’t read in detail yet tho.
I don’t hold but is on my watchlist as a high quality travel business. Cost of living doesn’t appear to be hitting holidays too much.
Although the historical numbers looked fairly strong - I didn't like the comments in regard to Winter bookings which are 1.3ppts down on last year as well as the comment that the bookings had been a little slower in recent weeks. In the longer term I think there is good value in the stock but it has run up almost 15% in recent weeks so a pull back on slight weakness in bookings is understandable (to me at least).
So MTI Wireless Edge (LON:MWE), having yesterday told us that they had sold all the shares in Treasury for a loss, at 31.5p, to majority shareholders, have now started buying their shares again at 34.5p.
Is this legal?
MTI Wireless Edge (LON:MWE) Is this legal?
I bet it is in Israel! I do have two Israel-based holdings. But I try to avoid as a general rule.
It is Israeli, lots of folk avoid the like. I held MTI Wireless Edge (LON:MWE) long ago, could have made money on its ups and downs but once was enough.
The RNS is the announcement relating to director purchase on 21 November when it says the price was 31.5p.
The buyback was a couple of days later when the price had moved. What's the problem?
The problem pj8 is that the purchase were not in the market but bought from the company - the shares had been purchased by the company at higher prices and were not being sold for a loss.it is reasonable to assume that if they had tried to buy that many shares from the market the price would have been higher (volume today is only 28,000)
From the company's point of view - they have bought, for example, some shares for 45p 28th Sept - sold those share on 20 Nov for 31.5p to connected parties and then bought more shares 22 Nov, at a price of 34.5 p. What benefit has there been to the company? If the company thinks it is worth buying shares this week for 34.5p why were they selling them for 31.5p? I might be missing something here but that looks like theft of shareholder value.
Announcements from three of my portfolio holdings this morning.
Volex (LON:VLX)
Difficult to fathom the market reaction to this morning's interims as on initial reading they look good, although as Paul alluded to I would like to see debt reduce.
Jet2 (LON:JET2) overall impressive results, but again no interest from Mr Market. My preferred play on the holiday market. A derisory rating for a well managed company. Fail to see why easyJet (LON:EZJ) , which in my view is a poorer quality investment has a higher rating.
PayPoint (LON:PAY) A smaller position than the above and lots of moving parts to digest, but is expanding its product portfolio and has established a dominant position in its chosen market. Look forward to Graham's view and help in unravelling some of the financials.
Hey Ho!
Jet2 (LON:JET2) - stand-out numbers: Mkt cap of £2.43bn; own cash £2.12bn. Bonkers! Very high quality management and stand-out balance sheet & fleet for the industry.
You do forget though to mention borrowings, lease liabilities and deferred revenue!
Even including borrowings, lease liabilities & deferred revenue Jet2 (LON:JET2) still has Net Assets of £1.6 billion.
So for £2.43bn market cap you get £1.6bn net assets that generate c£400m PAT. This seems bonkers cheap? What am I missing?
I do not know if you are missing anything; it’s something you will have to decide.
I just clarified to grumpy5 that their cash position is not a NET cash position.
I think Jet2 (LON:JET2) planned to invest in new planes a few months ago so I would expect the cah pile to reduce before too long. I hold.
Jet2 (LON:JET2) has a large number of aircraft on order, hence they need the cash
18/10/22 - "Jet2 plc is pleased to announce that to meet the future anticipated growth of its Leisure Travel business and to refresh its existing aircraft fleet, the Company has entered into an agreement with Airbus to purchase 35 new firm ordered Airbus A320 neo aircraft with the ability for this to extend to up to 71 aircraft.
The firm ordered aircraft deliveries stretch over three years until 2031 and at base price represent a total value of approximately $3.9 billion, with a total transaction value for up to 71 aircraft of approximately $8.0 billion, though the Company has negotiated significant discounts from the base price.
This order, which is in addition to the A321 neo aircraft orders announced in 2021, means Jet2 now has a total of 98 firm ordered aircraft, which could eventually extend to up to 146 aircraft.
The Company will retain flexibility in determining the most favourable method of financing the aircraft, which will be through a combination of internal resources and debt."
Jet2 (LON:JET2) - stand-out numbers: Mkt cap of £2.43bn; own cash £2.12bn. Bonkers!
its very unhelpful to quote half a balance sheet - for transparency purposes they have trade payables and borrowings of nearly £1.6 billion - (i have ignored lease liabilities of over £600 mill). I would say this on an initial glance looks a sound as a pound balance sheet - i would presume its almost certain that they CANNOT simply dish that £2 billion out as they choose- they will need decent cash resources to convince peeps to give them credit or even ensure that card processing companies are happy to allow them to use their services. Note looks like operating losses in 2021 and 2022 were £550 million plus - so when it does go wrong for airlines the negative numbers can get very scary and a sound as punds plus soem balance sheet is mandatory if one doesnt want to be diluted.
Note at september 2019 Jet2 had £1.6 billion of cash and they still needed to raise money when covid came along in 2022. This kinda suggests holding what appear nice high cash balances is kinda mandatory rather than being spare cash that can simpoly be handed out to shareholders.
You are all quite right, I shld have focussed on net debt. But the fact remains that their B/S is better than that of most rivals, and I think they manage it quite conservatively.
Thank you for this. I do not hold Jet2 (LON:JET2) (though have in the past) and was wondering why they felt the need to hold so much cash.
I would certainly have to dig deeper on this before I took any position.
Regards
Michael
Jet2 (LON:JET2)
Thank you for this. I do not hold Jet2 (LON:JET2) (though have in the past) and was wondering why they felt the need to hold so much cash.
I would certainly have to dig deeper on this before I took any position.
Note i didnt do any sort of deep dive here and was making presumptions en masse - so my thoughts might have been wide of the mark - i cant remember for life of the name of the airline that did go fom something under a penny a share (gievn away for nowtish ) peeps were confused at the time as it might have had some decent cash on hand (the goijng concern note in teh acounts should have been the clue there) - so my post was simply to warn that there could be various different kinds of things that affect the cash they hold - and quoting cashj without matching net debt/bills owed out is slightly useless. Overall my thoughts tally with Pauls today i do like the look of what i see - i used to be an easyjet fanboy back in the day when turnover was going up decent lick every year without thjem having to to anything new - it does seem like Easyjet did lose their way and my mates who use Jet2 are fairly complimentary for a bunch that are norally pretty hard to please on a thursday night in the pub after 6 beers (if you arenty easily pleased after 6 beers summit aint right imho). Overall despite my prior post saying what it did they seem sound as a pound - if i invest in an airline i actually want to have £500 mill extra sat there doing now bizzarely as thats the best protection against dilution
PayPoint (LON:PAY) is one of those companies where one's head hurts after reading their results but in one respect that's a good thing. PayPoint is a multi-headed business doing largely unfashionable things, is deeply embedded, and increasingly able to cross-sell. As such it's very hard to encroach upon PayPoint's territory because it's all too complex, (and admittedly perhaps because no one else would want to!), so it's got a moat, but maybe one without a drawbridge meaning potential competitors can't easily get on and PayPoint can't get off.
Aside of the risks associated with the decline in cash use there's risk in Love2Shop/ Park because that element of the business is basically a turnaround, but PayPoint management make a pretty good fist of other revenue streams, Collect+ being a good example, and they need some diversification long term.
For anyone interested also in Card Factory (LON:CARD) I spotted this line in the PayPoint RNS:
"Furthermore, there are several new sector opportunities that are in development, combining capabilities across the Group, including a new partnership with Card Factory to combine Love2shop gift cards with their greetings card offer through PayPoint’s extensive network."
PayPoint have this habit in my view of spotting opportunities where there were none.
[I hold PAY and CARD]
Me too, good spot!
Hi Tein
PayPoint (LON:PAY) Nice summary; would certainly agree with you on brain ache trying to digest the numbers.
Also an excellent spot regarding Card Factory (LON:CARD) . I have a reasonable holding in both.
Thank you NewInvestor1972 and jonno, I'm wondering if the Love2Shop/ Card Factory idea will work both ways, (cards into PayPoint network and Vouchers into Card Factory)?
Volex (LON:VLX) Some 5 hours after the RNS was released the market now likes Volex!
Volex (LON:VLX) Some 5 hours after the RNS was released the market now likes Volex!
I think some investors must’ve been shaken out by one or both of a) the absence of an upgrade to expectations, to which investors may have become accustomed, and b) the suggestion of a slowdown in the e-mobility segment of the business. I would not worry about a) because I think it is accounted for by b) in any case. But I think it is reasonable to expect some choppy trading for the e-vehicle/charging part of the business over the course of the next year or so, judging by reports from the industry.
Fundamentals however, are attractive and that accounts for the recovery.
I agree on Volex (LON:VLX). I also dont think the market likes H2 weightings in the 'uncertain' environment. Hopefully the institutions have been re-assured during this morning's analyst presentation perhaps leading to the SP turnaround.
Nightcap (LON:NGHT) doing a good job of showing us all how difficult it is to make profits in hospitality, even if you buy cheaply / out of administration (although cheap didn't apply to the original acquisition, that started the business, that of Ms Willingham's London Cocktail Club).
How about this:
"On the back of record breaking like-for-like growth in 2022 of 23.6% we saw like-for-like revenue growth normalise in 2023 through a 12.5% decline".
Strikes and weather of course are blamed. Strikes is a fair point (although at my 5 outlets LFL's are all up this year, despite strikes). Not sure unhelpful weather can be wheeled out.
I'd continue to avoid the sector generally. The continuation of support on rates (capped at £110k) helps the smaller operators (like us), but energy costs are still a huge worry and continuing steep rises in wages eats significantly into margins. It's true valuations are probably at rock bottom so maybe this will attract bids from bottom fishers, but I can't help feeling that private equity hasn't covered itself in glory in this sector lately and may be in retreat.
It's almost as if the only game in town is competitive socialising, where I wonder if there isn't a big bubble forming...
Thanks Mark!
Great to have your sector experience input, as someone actually doing it, not just talking about it! I recall our interesting chat at Mello Chiswick last year!
Best wishes, Paul.
Mixed results for me from Volex (LON:VLX) this morning for me. Decent growth when adjusted for acquisition costs etc. though organic growth isn't that strong. Maybe why the market is punishing the share price this morning? Lot's of good points, but also a few bad. Plenty of scope for growth if the acquisition delivers, but it needs to with increased debt & dilution. A familiar story of customers reducing inventory levels in a couple of their operating segments.
Bear in mind I use un-adjusted figures at the top, mainly because I use one template for all my stocks, including many US stocks and I find it gives a clearer picture of what's going on. Especially for US stocks.
(I hold)
Just some of my own thoughts on Macfarlane (LON:MACF) . It dipped 4.2% today on its Trading Update. It was down a little yesterday, too. It says it expects profits to be in line with expectations, and ahead of last year. It looks like what upset the market is:"Revenue year to date is 2% below the same period last year, with weaker volumes and lower pricing impacting most sectors."
I bought this share back in Nov 2021 at 139p. So I'm down 24% on the share. Its ROE is around 15% and its FCF has been growing at around 22%pa over 6 years. Its interest cover is 11, so its balance sheet is fine. It trades on a PFCF of 5.9 and a PE of 9.
According to Yahoo insider ownership is 18%. I'm not sure how accurate that is, because these stats can be a little wonky. If anyone knows of a reliable site for insider ownership then I'd be happy to hear it. I'm continuing to read through the book 100-baggers by Chris Mayer, which was recommended in Ed Croft's first webinar. (Many thanks to Ed for the webinar, as is has definitely influenced my way of thinking.) The book says that 10-20% insider ownership is a positive sign.
It's a share I'm looking to top up on come ISA season, although I'm spoilt for choice at the moment.
Hi Mark
Macfarlane (LON:MACF) is another company we share, which I have owned for many years and which has been a good performer owning to the current CEO and his team. They seem conservative, eg include goodwill w/o in eps, very few if any "adjustments to profit". In my view, like Next (LON:NXT), they tend to under-promise and over-deliver, so my own guess is is that the market was building in some over-performance to current estimates and has been disappointed with an in line forecast particularly on reduced revenues.
Could you explain what you mean by insider ownership? Is this something other than directors' ownership, which we can see on Stocko.
By insiders I mean directors. I also class family with large stakes as insiders. This is usually positive, as it suggests directors use a more business-oriented approach than play a numbers game.
If it helps at all Mark, Yahoo's figure of 18% insider ownership may be well off the mark:
Institutions hold practically 83% so the vote of an IP is worthless. As you can see in the Stock Report 2 members of the Board sold a quarter of a million shares last September the 5th at around 110 pence/share. I don't hold Macfarlane (LON:MACF) but should the price drop below the pound I might consider it using the rule of thumb, Buy Low, Sell High.
Silver
Thanks for that. Yeah, a lot of places like Yahoo and Google have some very dubious stats on them.
Macfarlane (LON:MACF) Forgot to mention the director holdings - according the last Annual Report the directors hold just over 1% of the shares, which together with options in existence takes them closer to 2% in their eventual ownership.
Director shareholding is low, but this is balanced - for me - by impressive long term conservative management by executive team which seems well aligned with shareholder and all stakeholder interests. Succession planning is a long term risk on my horizon.
cheers
Mark
Those Director sales were to cover the tax implications of options that both directors received the day before.
Hello Mark, thank you for your usful thoughts on Macfarlane (LON:MACF). I am a long term holder. Currently my second largest holding.
On the face of it the reversal of revenue from 2% up at the interims to 2% down by end October is disappointing. But not surprising? The economic situation in the UK is something of a grind at the moment. It would be odd for packaging to be exempt from that?
Which makes the ability of the company to increase margins and maintain profits in line with expectations all the more impressive? I am relieved that they are not 'investing in prices' as many do and chasing the lower margin business. Instead moving the business towards higher margin sectors with future growth prospects. Which will be all the better for the long term.
This is led by the recent acquisitions - this year including Sutton's (packaging manufacturing to the medical and industrial sectors), Gottlieb (local customer relationships) and B&D group (supplier/manufacturer to defence and aerospace)
The acquisition ability of the long term management team is exceptional - in my view the most valuable attribute of the company over the last decade and the latest example - Packmann (Germany) acquired in 2022 is performing above expectations - is particularly good to hear as there is a long runway for future growth in Northern Europe, where the economic environment is also difficult but likely less volatile longterm than the UK?
Although today's Trading Update is short on figures - Shore capital the house broker release a new note at each trading update/significant RNS which is very useful to see how the numbers change. Today's note is available free via Research Tree (free registration needed).
Cash generation looks to be impressive. And there is a hint from the research note that this will feed the acquisition pipeline. Under current circumstances I can see acquisitions stepping up - but without reducing the quality of acquisitions - as owner/managers look for access to the larger scale and finance and an exit route that Macfarlance offers. I think the revenue figures in the reseach note are conservative (likely reflecting management expectations) and don't reflect any improvement in UK economy or more importantly continued high quality acquisitions in growth sectors.
While disappointed with the revenue reduction in today's update I am reassured that the business is improving in terms of margins, customer relationships and growth sectors. The company will prosper even under current circumstances but the tailwinds on any economic improvement are likely to be significant.
The shares look very good value to me at current price - sadly I don't have spare capital to invest (I live on the proceeds of my investing ) or I'd be buying more. I note that prices of my small caps are starting to rise across the board - but there are still a lot of bargains yet to be reached by a rising tide?
cheers
Mark
Thanks for your insights.
Two things that stuck in my mind about MACF is that I think they will have economies of scale as they grow. They also have design teams and seem able to differentiate their products.
Some notes I took of their investor presentation in August ...
92% of their business in UK, with 8% in Europe. So maybe they have plenty growth prospects if they want to expand abroad? They grow 50% by acquisition and 50% organically. Their pretax ROCE is 18%, which is definitely the kind of thing I like to see. They also have a pension surplus.
They're consolidating some of their locations, so there's likely to be cost efficiencies there. E-commerce is ~25% of their business. No sector of their business is above 5%, so they don't go overweight in any one sector.
It's also worth me pointing out the Stocko rank of 97, with Quality 96, Value 72, Momentum 83.
Avation (LON:AVAP) I hold, from the AGM statement this morning, they say
“The Company's broker was approached over the summer in relation to a potential takeover offer, however, while the board diligently contemplated the proposal, the broker was ultimately unable to verify the funding package of the potential bidder and discussions were therefore brought to a close.”
As has been mentioned numerous times by Paul and others on here other investors/buyers are seeing UK stocks undervalued. My hunch is the buy interest came from the fund who has been building the stake Rangley Capital who now own 25.78%
I will repeat my post from Nov 10th's SCVR (there is some subsequent discussion with Mr. Hill as well if you look back):
I'm a long-term holder of Avation (LON:AVAP) alongside some other aicraft leasing cos...of the patient rather than trading variety.
I've had a bit of a look at Rangeley Capital...not entirely sure I am any the wiser for it.
The key individual publishes articles regularly here:
https://chrisdemuthjr.medium.com/
as well as this......
https://valetudo.substack.com/p/disproportionate-response
Then he is acting in concert with this gentleman, who runs a subscription based website:
https://rapercapital.com/about
You will see he has written investment notes in the past on some of the major aircraft lessors - AerCap and Avolon.
Are these guys equipped to bid for a company?
Sorry Monty Carlo, my post crossed over yours!
rapercapital?
Avation (LON:AVAP) Here is what I found, which may make sense on what might be going on.
Mr. J Townsend was a Managing Partner at Rangeley Capital (Chris de Muth is married to Richard Townsend daughter) Richard Townsend was recently CFO of a US Listed SPAC called Monocle which merged with Aersale (NAQ:ASLE)
Richard Townsend Bio
About AerSale Corp.
A global aviation leader celebrating its 10-year anniversary, AerSale specializes in the sale, lease, and exchange of used aircraft, engines, and components, in addition to providing a broad range of maintenance, repair, and overhaul and engineering services for commercial aircraft and components. AerSale also offers asset management services to owners of end-of-life aircraft and engine portfolios.
Good digging Albm7, on Avation (LON:AVAP)
I usually sigh & move on at the mention of a SPAC, but the Townsend CV is interesting - background at GE, IBM, ITT, Loral adds a lot of credibility.
Brings to mind Melrose Industries (LON:MRO)
I've seen him on a value based youtube channel, if interested, as i was interested in a guest they had on who has been in court following the Spirit Airlines (NYQ:SAVE) JetBlue Airways (NSQ:JBLU) takeover, DoJ antitrust case currently going on as a potential arb.I think he was talking about Serica Energy (LON:SQZ) with the host though in one video.
From having a scan of the youtube videos on there, the other chap Chris DeMuth, seems to have been interviewed too.The name of the channel is Yet Another Value Channel.
https://www.youtube.com/@yetanothervaluechannel6876 .
I think shareholders should be told if an offer is on the table but it's good to see some sense and due diligence taken here.
Look at UPL's recent "offer". Either the board are all muppets or they were complicit. Not great either way!
The good news for Avation (LON:AVAP) shareholders is that Jeff and other board members hold sufficient stock that they are unlikely to sell way below market value particularly as they have spent a lot of time over covid putting the company back on a growth track. It would be foolish to give that all away now and in my conversations with Jeff he doesn’t strike me as a fool. Would he take a 10-20% haircut? Probably - so I think he would want to see a bid at 225p or above to have credibility.
Anyway with my estimated NAV closing in on 300p no real surprise to see bid activity. Even at a 200p bid you’re buying a company assets of a £1 for 70p which given the booming aircraft market is a nonsense really.
Per the AGM and reading between the lines NAV is clearly going up with aircraft prices up 10-15% over a 12-18month window.
Cash generation is strong so net debt still going down and it seems a window has now reopened to refinance the portion of non asset backed debt. Once that’s done I fully expect to see them north of 200p.
Upland Resources (LON:UPL) wow is all I have to say! I agree shareholders should be told if an offer is made so everyone has all available information to make an informed decision. With regards with Avation (LON:AVAP) I personally would have liked to have seen a bit more commentary around the offer price made. (probably will be given to the analysts)
Volex (LON:VLX) A rather brutal open on a decent update I added as the fundamentals must surly come good with time.
Yes, misleading share prices on Stocko, shares are now down 5.88%.
Buried at the bottom of the Avation (LON:AVAP) AGM statement:
The Company's broker was approached over the summer in
relation to a potential takeover offer, however, while the board
diligently contemplated the proposal, the broker was ultimately unable
to verify the funding package of the potential bidder and discussions
were therefore brought to a close.
Good report from Volex (LON:VLX), so of course the share price drops!
Happy 'Thanks Giving' everyone
Indeed so far this month, its been a "November to Remember" for smallcap investors.
My morning smallcap tweet: Pre-owned news
Motorpoint (LON:MOTR) Macfarlane (LON:MACF) Windward (LON:WNWD) Intelligent Ultrasound (LON:IUG) Hornby (LON:HRN), Michelmersh Brick Holdings (LON:MBH), DX (Group) (LON:DX.), Cambridge Nutritional Sciences (LON:CNSL), Volex (LON:VLX)
◄Motorpoint (MOTR)► H1-Sept rev down 23%. Pretax -£3.7m (+£3m). Market: "the value of used cars, which has fallen since the end of the period, with a reduction in wholesale values of c.6% in just the last six weeks. Whilst we have taken proactive measures to limit the impact on our stock, the current environment is likely to be volatile as new car supply into the used car market begins to increase". [SP=77.7 Cap=70m]
◄Macfarlane (MACF)► guides FY23 adj pretax in line. Jan-Oct rev down 2% with weaker volumes and lower pricing impacting most sectors. Co "does not expect trading conditions to substantially improve in the near term". [SP=110.47 Cap=176m]
◄Windward (WNWD)► €3,2m five-year contract with a European national coastguard. Paid up front. Co trading comfortably in line with market expectation. [SP=66.8 Cap=57m]
◄Intelligent Ultrasound (IUG)► launch of new gestational age estimation AI software, Also sells four ScanNav FetalCheck systems in Africa. [SP=9.3 Cap=30m]
◄Horby (HRN)► H1-Sept rev up 6%. "Order book is strong and although, like everyone, we are seeing the ramp up into Christmas trade coming later than in previous years, we are starting to see some encouraging increases in performance." [SP=15 Cap=25m]
In line: MBH, DX., CNSL, VLX