Small Cap Value Report (Thu 25 April 2024) - MEX, G4M, TRCS, SUP, SDG, TUNE, MRIT, CRDL, KMK, INCH, LSL, DAL

Good morning, it's Paul & Graham here.
Mello - Results Special - It's free! There's a mammoth Mello show starting at 13:00 today, with interesting companies eg. Journeo (LON:JNEO), Equals (LON:EQLS), accesso Technology (LON:ACSO), Property Franchise (LON:TPFG) presenting, and yours truly doing a roundup of recent results. I don't think anyone is expected to watch the whole thing! I tend to put on my headphones, and drift in & out of online shows.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
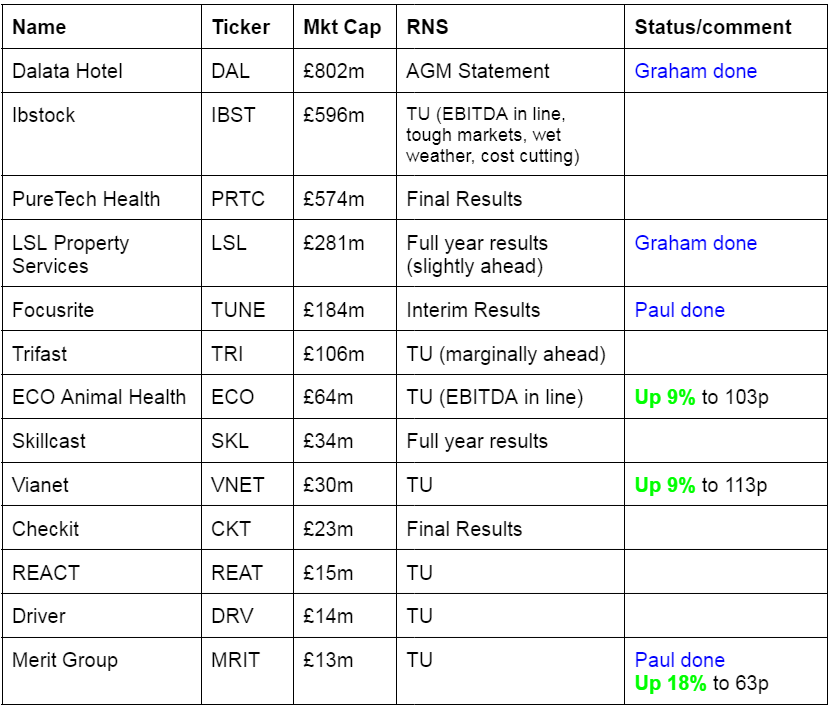
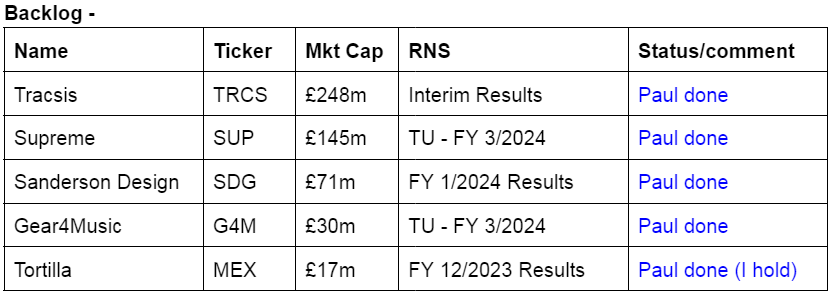
Other mid-morning movers (with news) -
Kromek (LON:KMK) - up 9% to 7.65p (£49m) - Contract Win - Paul - RED
Kromek Group plc (AIM: KMK), a leading developer of radiation and bio-detection technology solutions for the advanced imaging and CBRN detection segments, is pleased to announce that it has been awarded a contract, worth up to $2.9m, from a US federal entity for the provision of nuclear security products.
The contract, which is from an existing customer, covers the provision of the Group's D5 RIID, D3M and D3S-ID wearable high-performance radiation detectors. The Group has received a $358k order under this contract for immediate delivery, with up to $2.5m to be awarded over the next 24 months.
Paul’s opinion - It’s not clear from the above if this is a proper contract, or just a small initial order with the hope that more will follow? KMK has such a bad history, 10 years of missing forecasts, and multiple fundraisings, that people who give it the benefit of the doubt tend to regret it. Even the latest forecasts show it nowhere near profitability, even if it reaches the target revenue growth. Despite a fundraising, its last balance sheet showed net debt. I wish it well, but there’s no evidence this is a viable business as yet. Hence it has to be RED.
Merit (LON:MRIT) - up 18% to 63p (£15m) - Trading Update FY 3/2024 - Paul - AMBER/GREEN (speculative)
This has been listed many years, and used to be called Dods Group.
Merit Group Plc (AIM: MRIT), the AIM-listed data and intelligence business, today issues an update on trading for the financial year ended 31 March 2024 (FY24).
Trading has been good - with a long-awaited return to profitability.
The Group expects to report revenues in FY24 of approximately £19.9m (FY23 £18.6m) and Adjusted EBITDA1 of around £4.0 million (FY23 £2.7m), approximately 10% ahead of market expectations2.
Based on the unaudited management accounts, Profit before Taxation and non-recurring items for the year ended 31 March 2024 is expected to amount to £1.2m (FY23: Loss of £0.2m), the first Profit before tax for the year reported since FY18. The Group had net debt of £1.9m as at 31 March 2024 (31 March 2023: £2.6m).
Our current activities are focussed on further revenue and earnings growth in the new financial year."
Paul’s view - I’ve not looked at this since 2019, so am out of date. I see the bounce back into profit was achieved in H1, announced in Nov 2023. It was talking about using AI long before it became fashionable, on checking my notes from 2019.
My main question is how scaleable the business is? In particular its political intelligence division looks very niche. Weak balance sheet at 9/2023, could need a placing to bolster things?
I’d say this looks worthy of a closer look, on the basis that it seems to genuinely use AI and data analytics, makes a small profit, and could re-rate as a sexy AI share in future, perhaps?
Cordel (LON:CRDL) - up 13% to 4.3p (£9m) - Contract win - Paul - AMBER/GREEN (speculative)
It’s won a “12-week paid trial” from a “major national railway” in Asia. Doing a little digging, I like the sound of the product here - it’s camera-based computer systems that are fitted to trains, and they automate various activities such as checking for obstructions on the line, and other analytics, reporting back to customers with actionable reports. It has customers in several countries. Sounds clever, and scaleable. Revenue doubled to £2m in H1, so the product obviously works. Note it also received grant income of £409k in FY 6/2023, another sign that it has something credible, in my view. Cash looks tight, so a placing is possible, and as with all nanocaps there’s de-listing risk.
Paul’s opinion - for people like me who like the odd nanocap punt, this one might be worth a closer look perhaps.
Inchcape (LON:INCH) - up 8% to 779p (£3.20bn) - Q1 Results - Paul - AMBER
This international vehicle distributor recently sold off its UK retail operations for £346m.
The market clearly likes its Q1 update today. It says Q1 has been positive. Outlook is reiterated, doesn’t sound very good to me - “moderated growth in FY 2024”, but higher growth expected medium to longer term.
Paul’s view - valuation metrics on the StockReport look attractive, PER 8.2x, and 5.1% dividend yield. So it might be worth a closer look maybe? Shares have oscillated in a sideways trend for the last 10 years. Doesn’t excite me, so I probably won’t do any more research on this.
It’s surprising to see large caps on the top movers list, but here we are, very briefly -
Anglo American (LON:AAL) - up 13% to 2,491p (£33bn) - possible bid approach from BHP, and AAL considers selling De Beers diamond unit.
AstraZeneca (LON:AZN) - up 6% to 12,024p (£186bn) on Q1 Results.
Unilever (LON:ULVR) - up 5% to 4,066p (£102bn) on Q1 Trading Update.
That must have helped the FTSE 100, up 55 today to 8,090 - I haven’t got used to it starting with an 8 yet!
Summaries of main sections
Tortilla Mexican Grill (LON:MEX) - 44p (£17m) - FY 12/2023 Results - Paul - AMBER/GREEN
Made a £1.1m loss before tax in FY 12/2023, but this masks good cashflow (pre expansion capex). Balance sheet looks OK, with plenty of headroom on 2026 Santander facility. Should be scope for profit to improve as cost of living crisis recedes, and energy/food inflation ends. Looks too cheap to me, for a national chain with a good brand, and decent products. My target is c.100p exit, maybe through takeover?
Gear4music (HOLDINGS) (LON:G4M) - up c.5% to 145p (£30m) - FY 3/2024 Trading Update - Paul - AMBER
Traded in line, but net debt has come in much lower than anticipated. I would need to see the full numbers to see how much is due to de-stocking, and how much is just seasonal. Modest profits, but cost-cutting in H2 may be setting up an improvement for FY 3/2025. Maybe priced about right, or could be more upside, I'm not sure!
Tracsis (LON:TRCS) - down 3% y’day to 820p (£248m) - H1 Results - Paul - AMBER
H1 profit fell, but it's been saying for a while that profit would be H2 weighted. As before, I like the business, but find the valuation too high.
Supreme (LON:SUP) - up 3% y’day to 125p (£145m) - Year End Trading Update - Paul - GREEN
In line results, show profit doubled on last year. Shares look very cheap, but uncertainty/aversion to its main profit generator being vaping products. Has paid off all its debt, and looks set to make more acquisitions of new products or companies. Has to be green as it's so cheap.
Sanderson Design (LON:SDG) - down 4% to 99p (£71m) - FY 1/2024 Results - Paul - GREEN
I see these results as being resilient, considering a consumer downturn. Strong licensing performance saved the day. Bulletproof balance sheet. Sensible strategy from management. Shares look too cheap to me, although some risk of possible profit warning?
Focusrite (LON:TUNE) - down 9% to 335p (£198m) - H1 Results - Paul - AMBER
Weak H1 numbers, but it reckons an H2 weighting means it should hit (reduced) FY 8/2024 forecast - as we know, H2 weightings can be a deferred profit warning sometimes. I flag some balance sheet & cashflow issues below too. I'm shifting down a gear to AMBER for now, and we'll see how things pan out.
LSL Property Services (LON:LSL) - up 4% to 280p (£291m) - Full year results - Graham - AMBER/GREEN
Exciting times at LSL after a wide range of changes to its makeup and structure, with the overall goal of becoming a focused, capital-light B2B group. After a couple of “ahead” trading updates, it now treats investors to a £7m share buyback. I certainly view this one as being worth researching in greater detail.
Dalata Hotel (LON:DAL) down 0.5% to 372p (EUR €934m) - AGM Statement - Graham - GREEN
A very confident and positive AGM statement from this hotel owner and operator, noted for its Clayton and Maldron brands. It does acknowledge that there has been some weakness in the first few months of the year in the Irish market. With many key months ahead, there is plenty of time for this to turn around.
Paul’s Section:
Tortilla Mexican Grill (LON:MEX)
44p (£17m) - FY 12/2023 Results - Paul - AMBER/GREEN
Tortilla Mexican Grill ("Tortilla"), the largest and most successful fast-casual Mexican restaurant group in the UK, is pleased to announce its Annual Results for the 52 weeks ended 31 December 2023 (the "Period").
I had a quick look at these results early yesterday morning, and jotted down the key points -
Revenue up 14% to £66m
Loss before tax of £1.1m (slightly worse than 2022 of £0.9m loss)
Current trading: in line with expectations. Letting some unprofitable delivery business go.
Net debt looks fine at £1.3m, with gross debt £3m of a £10m Santandar facility (to Sept 2026)
Clean going concern statement.
NAV: £2.9m, including £2.6m intangibles, so NTAV £0.3m (error corrected, my apologies) - adequate I’d say, but not strong.
Paul’s opinion - what’s the attraction here then? Tortilla (which also owns Chilango) is the UK’s largest Mexican-style tortilla fast food chain. The product is very tasty, and reasonably priced. I reckon this could be the low point for earnings, hit by: consumer downturn (now reversing as real incomes move positive), spike up in energy & food costs. Big rise in living wage is another headwind. It also has a successful franchising arrangement, and international franchise expansion planned, which is telling us that the format works (or the franchisees wouldn’t want to open more stores). So a cyclical recovery, and for me I’d be happy with an exit (possibly from a takeover bid) at c.100p. Is it the best business in the world, no of course not! But it’s too cheap at 44p I reckon. Recently we saw an institutional overhang placed with some shrewd investors, causing a burst of excitement. Cash generation is good, even when you adjust out all the IFRS 16 nonsense. By my calculations it generated £3.8m in positive cashflow, before spending £4.5m on (mostly expansion) capex. Debt isn’t a problem. Overall, these numbers are better than I expected.
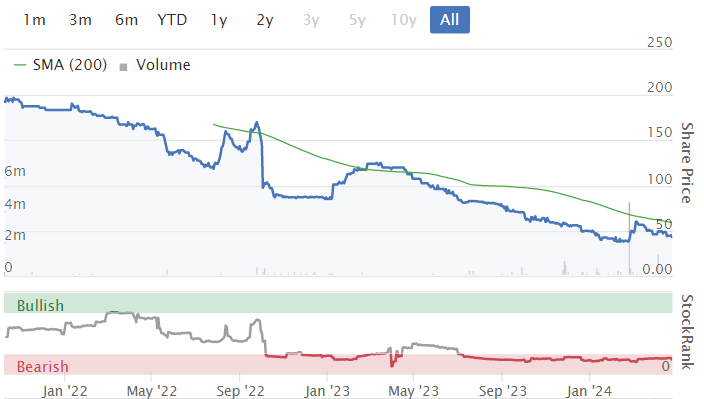
Another over-priced 2021 IPO -
Gear4music (HOLDINGS) (LON:G4M)
Up c.5% to 145p (£30m) - FY 3/2024 Trading Update - Paul - AMBER
Gear4music (Holdings) plc ("Gear4music", "the Company" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, is pleased to announce its Board succession plan.
Board succession - Non-Exec Chair, Ken Ford, is retiring after 9 years. Founder/CEO Andy Wass is becoming the new Chair. Existing Chief Commercial Officer Gareth Bevan is becoming the new CEO. Neil Catto (former BOO CFO, and now with Revolution Beauty) joins as a new NED.
Year-end Trading Update - for FY 3/2024.
Sales down 5% to £144m - as expected, due to strategy to prioritise profit, not revenue growth.
“Net debt reduced significantly to £7.3m at 31 March 2024 (31 March 2023: £14.5m; 31 March 2022: £24.2m), ahead of market expectations*”
EBITDA expected to be in line with market expectations*.
* Gear4music believes that current consensus market expectations for the year ended 31 March 2024 are revenue of £144.1 million, adjusted EBITDA of £9.8 million, adjusted profit before tax of £1.3 million, and pre-IFRS16 net debt of £11.6 million.
“Planned cost reductions delivered during FY24 H2 will support further net debt reduction and profitability improvements”
I’ve moaned before that EBITDA is particularly meaningless here, so it’s good that fairly recently the company also started disclosing the much more modest level of adj PBT, as above.
As readers commented yesterday, it’s the debt reduction that’s the most important aspect of this update.
Net debt was £18.1m at 30/9/2023, and is now down to £7.3m, although I think there’s probably some seasonality in that movement. I’d need to see the full balance sheet and cashflow, to properly analyse this, but it’s moving strongly in the right direction.
Paul’s opinion - not bad. The days of smaller eCommerce companies being given massive valuations are long gone, unlikely to ever return. I think now investors see these as low margin companies, up against a lot of competition. It’s only made £1.3m adj PBT in FY 3/2024, and still has some debt, so a £30m market cap doesn’t look especially cheap to me.
Singers is forecasting a big uplift in PBT to £2.7m in this new year, FY 3/2025. If that is achieved, then I could see upside on the current share price. I’d like to better understand why Singers thinks PBT is likely to more than double in the next year? Sounds like it’s due to cost cutting. The trouble with that, is it tends to only give a one-off boost to profit.
On balance, I was AMBER last time (on 17/11/2023), and with the share up about 20% since then, G4M shares look priced about right to me, so I’m happy to stick with AMBER. Risk has reduced nicely with reduced debt, but some of that reduction might be seasonality. So I’m happy with the risk side of things, which is now acceptable. I’m just not convinced that the reward side of the equation, the upside on this share, is big enough to get me excited about it again. It wouldn’t surprise me to see G4M shares continue an uptrend, maybe getting to 200p later this year, but what happens after that? Maybe I’m being too cautious here, and amber/green could be justified, given that G4M has done all the right things in the last year or so - cutting costs, focusing on margin not just revenue growth, and debt reduction from lowering inventories.
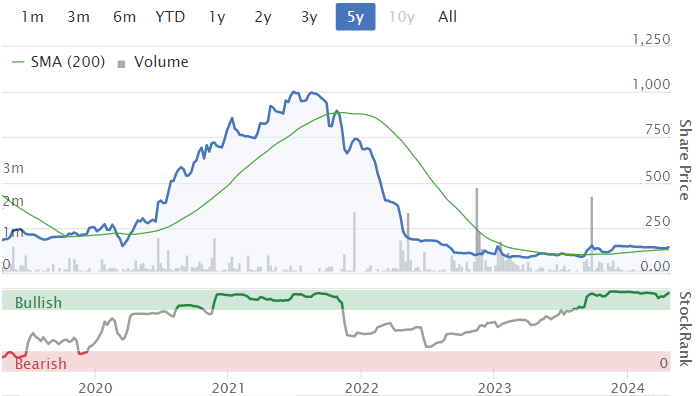
Note the pandemic boom & bust. Looks like it's put in a floor over the last 2 years. Also note there's been no dilution since it listed in 2015 -
Tracsis (LON:TRCS)
Down 3% y’day to 820p (£248m) - H1 Results - Paul - AMBER
Tracsis plc (LSE: TRCS), a leading transport technology provider, is pleased to announce its unaudited interim results for the six months ended 31 January 2024.
Rather uninspiring, was my reaction to the numbers, and a rather flat management presentation online.
H1 revenue down c.7% to £36.6m, with only about a third being recurring revenue.
Adj EPS down 36% to 10.3p.
Statutory EPS was a small loss.
H2 weighting to profit, it says.
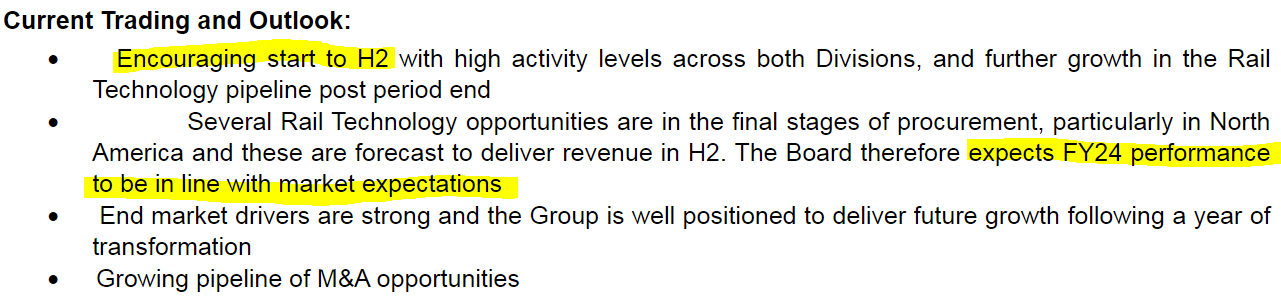
Broker update - thanks to Cavendish, showing forecast of 39.8p for FY 7/2024. Therefore that means it’s expecting H2 to be 3x the actual H1 EPS result of 10.3p, which seems a challenge, increasing the risk of a profit warning if it doesn’t convert the pipeline into deals as expected.
Also this forecast is only a whisker above actual adj EPS of 38.5p achieved in FY 7/2023.
Yet we’re being asked to pay 20.6x forecast earnings. That seems too expensive to me.
Balance sheet - looks sound, and management said all the deferred consideration creditors have now been paid. So expect more acquisitions they say.
NTAV is fairly modest at £13m. Net cash is healthy at £16.8m.
Paul’s opinion - I can’t get excited about this. As we always say, Tracsis looks a decent collection of rail/transport related IT businesses. Although there seems little organic growth, and H1 actually went backwards. So why would I pay 20.6x earnings for this? The valuation seems too high to me. Clearly bulls are betting on the future growth improving. I don’t know whether that will happen or not, so there’s too much guesswork involved for me, and I’m generally not a fan of H2 weightings, better avoided I think due to the heightened risk of missing forecast. Although it has been consistently stating for a while that this year would be H2 weighted.
So it’s not for me, but good luck to holders. It’s quite a nice company, just not priced attractively at this stage, the way I see it. So let’s stick with AMBER, as we viewed it the last three times, in Aug 2023, Nov 2023, and Feb 2024. Nothing much has changed over that time.
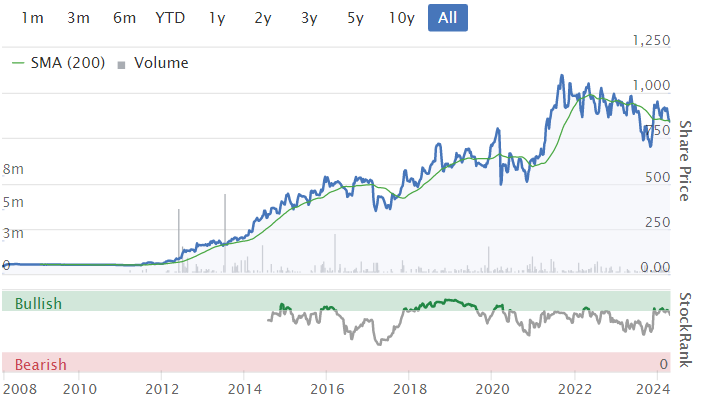
Long-term chart below shows a 10-bagger from 2011 to 2016, but gains have been more pedestrian since -
Supreme (LON:SUP)
Up 3% y’day to 125p (£145m) - Year End Trading Update - Paul - GREEN
Supreme PLC (AIM: SUP), a leading manufacturer, supplier, and brand owner of fast-moving consumer goods, is pleased to provide a trading update for the twelve months ended 31 March 2024 ("FY24" or the "Period"). Audited financial results for the Period will be announced on Tuesday, 2 July 2024 ("Final Results Announcement").
The main money-spinner is vaping products, which some of us don’t want to invest in. I won’t go over that ground again, as we’ve discussed it a lot in the past here, and everyone has had their say.
Impressive headline -
Record financial performance, almost doubling Adjusted EBITDA1 to at least £38 million
Note the superb track record of big forecast increases -
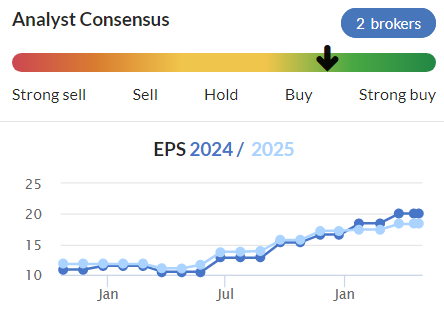
Broker note - thanks to both Shore and Zeus. Zeus says £38m adj EBITDA is in line with expectations, and turns into real profits (adj PBT) of £32.9m, which is 19.9p adj EPS. Therefore the FY 3/2024 PER is only 6.3x. Clearly this is due to investor uncertainty about the future for vaping products. Zeus says forecasting is tricky, and currently it is forecasting a fall to 18.2p adj EPS for FY 3/2025.
Cash - no figures provided, but it says net bank debt has been paid off this year.
Acquisitions - it’s considering complementary products & companies to acquire.
Paul’s opinion - it’s very cheap, if current level of earnings can be maintained longer term, which is the bit we don’t really know for sure. The numbers are so good, I have to view it GREEN, but it’s not a stock I would personally want to own, due to the vaping issue.
Sanderson Design (LON:SDG)
Down 4% to 99p (£71m) - FY 1/2024 Results - Paul - GREEN
Sanderson Design Group PLC (AIM: SDG), the luxury interior furnishings group, announces its audited financial results for the year ended 31 January 2024.
SDG has some impressive historical brands, and a huge design archive, eg William Morris. It manufactures wallpaper and fabrics, and also licences its designs to fashion and interior furnishing companies, which is increasingly important to profits.
Demand has been struggling a bit in recent years, but CEO Lisa Montague has rationalised product lines, stripped out costs, and protected profitability pretty well considering, in my view.
Strong licensing income saved the day in these results.
I enjoyed the reader comments here yesterday, with a variety of interesting bull & bear views on SDG from you, all food for thought!
Considering tough macro, I find these figures quite decent -
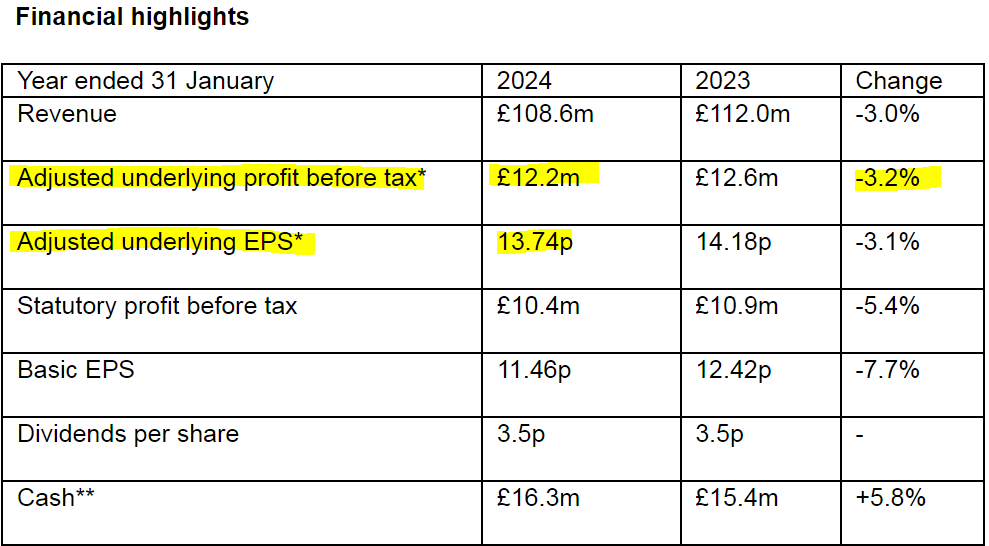
The share price of only 99p means we’re only looking at a PER of 7.2x - that strikes me as very cheap.
Outlook - no sign of a cyclical recovery as yet -
"Trading conditions overall are expected to remain challenging in the year. The Board remains focused on its strategic growth drivers, including North America and licensing, and remains confident in the business's agility to navigate further market uncertainties, supported by the Company's strong cash position. The Board's expectations for the current year's performance are unchanged."
Webcast of results recording is available on SDG’s website here. I’m listening to it now in the background. It feels a little flat compared with previous more energetic presentations, does that matter though?
Balance sheet - is very strong. NAV of c.£87m becomes NTAV of £60m, which includes £16.3m of net cash. The current ratio is very strong at 3.33 - this is a very conservatively financed business with no gearing, so I would say solvency & dilution risk are close to zero. This is a sleep soundly share for value investors.
Note that the pension scheme is still cash hungry, with the cashflow statement showing £2.3m pa contribution to pension schemes.
Paul’s opinion - I find the current market cap an extremely gloomy valuation for a decent business, that is weathering the consumer downturn very well I think (thanks to surging licensing revenues).
I was amber/green last time, but with shares now just below 100p, I think it’s too cheap, so will go up to GREEN.
There are risks of course. Some of the licensing revenues are lumpy, so we can’t guarantee every year will produce resilient profits. A profit warning at some stage is entirely possible.
I think the value of the brands & archive, could be worth more than the current market cap. So for patient investors, I think this could be a fairly decent investment in the long-term. It seems well-managed too.
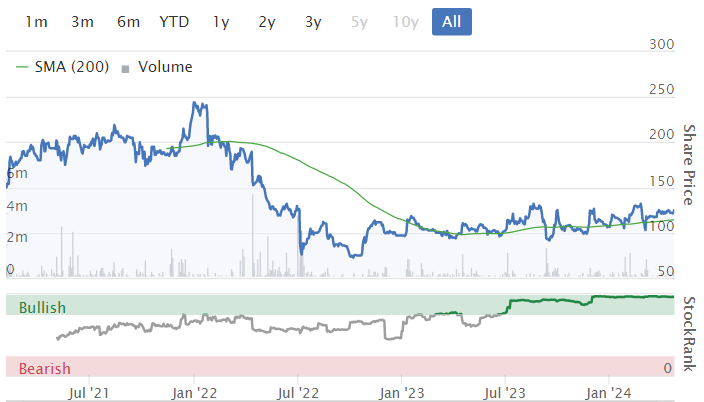
A volatile share that does big movements -
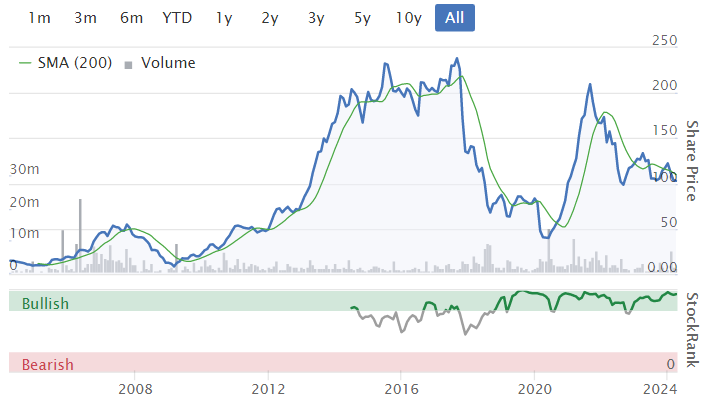
Focusrite (LON:TUNE)
Down 9% to 335p (£198m) - H1 Results - Paul - AMBER
Focusrite plc, the global music and audio products company supplying hardware and software used by professional and amateur musicians and the entertainment industry, today announces its half year results for the six months ended 29 February 2024 ('HY24').
The highlights table below reveals an unhappy H1 performance with adj EPS (my preferred measure) down 57% on H1 LY.
Also note that net debt has risen a fair bit, which it blames on seasonal stocking-up - although it has since come down a bit in April -
…net debt has now reduced from a net debt position of £27.3 million reported at the end of H1 to approximately net debt of £25.1 million at 22 April 2024.
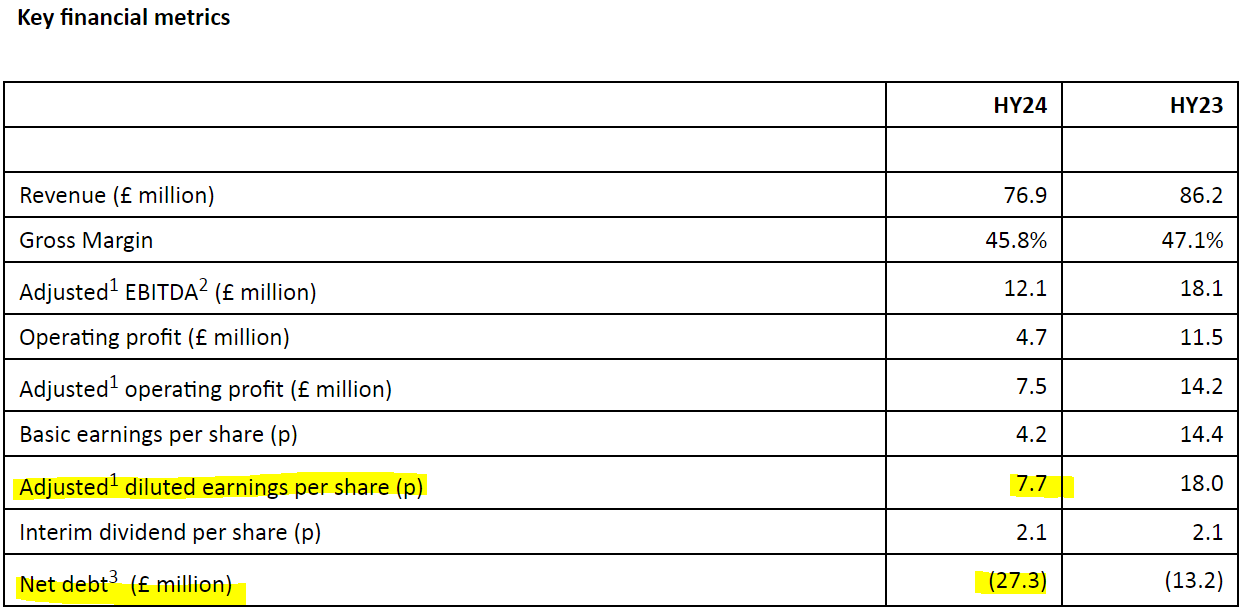
Adjustments are reasonable in my view - being almost all related to amortisation of goodwill. It is customary to adjust out that non-cash item, and I’m fine with that, as I always eliminate all intangible assets anyway, hence the related amortisation charge would also be eliminated.
Outlook for the full year sounds OK (in line), although we don’t tend to like H2 weightings as they can sometimes be wishful thinking, and develop into a profit warning -
Though the industry outlook, particularly for Content Creation, remains tough, we remain encouraged by our product registration data which is comfortably outperforming the market.
The sustained robust performance of our expanding Audio Reproduction division offers a positive counterbalance to the ongoing headwinds in Content Creation.
With a series of planned product launches in the coming months and a continued emphasis on our strategic growth initiatives, which will lead to a greater weighting of sales in the second half, we remain confident of meeting our full-year expectations."
Note below that broker forecasts have come down a lot, with the biggest lurch down being the most recent after its March 2024 profit warning -
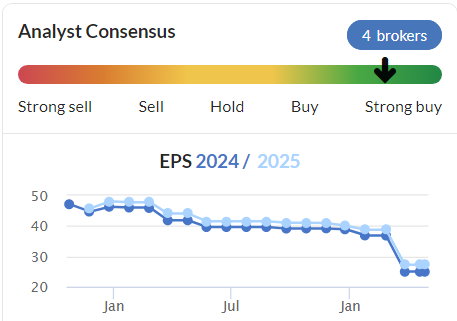
FY 8/2024 forecast is now 25p, and it did 7.7p in H1. Therefore 17.3p is needed in H2 to hit target. That’s quite a big jump up from H1, but might be achievable, as it mentions new product launches in H2. Subjectively, I feel that the chances of another profit warning here look medium, so I’d want a lowish forward PER to compensate for that risk - say 10-12x, which on 25p EPS gives me a target share price of 250-300p (versus 335p at time of writing - so a little bit above what I would be comfortable with).
My previous notes show that TUNE was trading in line on 19/1/2024, but issued a profit warning on 18/3/2024 - I commented at the time that the plunge to 272p looked overdone, and that a bounce was possible. It did rebound, but so far today’s H1 results seem to have left investors cold, with some of that previous bounce being given back.
Broker notes - we don’t get any - a glaring gap in TUNE’s investor relations. So all we’ve got to rely on is the broker consensus numbers, which usually update quite quickly. Hence I don’t know what the premium brokers are telling their favoured clients today. Often when a share price drops sharply, despite an in line update, it can be because brokers have slipped out downgrades without telling us plebs. It’s not a level playing field, is it? This area needs urgent reform.
Going concern - some interesting explanations of how they’ve reviewed the finances, and stress tests, etc. These sections are very useful, well worth reading, and I’m trying to remember to always read the going concern note at all companies with debt.
It gives itself a clean bill of health, with supporting (credible I think) explanations.
Balance sheet - intangible assets are £87m, so deducting those from NAV of £118m, gives NTAV of £31m. We could deduct the £10m deferred tax too, which would adjust NTAV up to £41m, which is about right for the size & type of business, I feel.
My concern is that inventories of £55m seem much too high. Note that H1 cost of sales in the P&L was £42m, so it’s holding well over 6 months’ sales within inventories. Normally I would expect inventories to be maybe 1-2 months’ sales. This is costly, because there’s £36m of bank loans in current liabilities, effectively funding this considerable over-stocking.
The danger with excessive inventories is not just that it’s costly to finance now interest rates are higher, but also that there could be slow-moving, or impaired items within inventories, that get a provision made against them at the year end audit, or have to be cleared at low (or negative) margins to shift them.
This is a worry. TUNE needs to explain what it’s doing to reduce excessive inventories.
It does reassure on this issue in the commentary though, so hopefully this is just a timing issue, and not something more serious -
Net debt3 of £27.3 million (HY23: net debt £13.2 million) has increased due to higher working capital levels, with higher stock in Audio Reproduction to support growth and higher debtors in Content Creation both of which are expected to largely reverse in the second half of the year.
Cashflow statement - more than all the cash generated is absorbed into working capital, with a big reduction in trade creditors in particular. This looks like normalising trade creditors from a spike up at the last year end six months earlier, so nothing to be concerned about, but combined with the excessive inventories, this is why net debt has risen.
A key point, mentioned before, is that TUNE capitalises a ton of development spending on product innovation, patents, etc - £5.1m in H1 alone (up on prior year). See note 8. Hence why EBITDA is meaningless here. It has to run to stand still, with continuous product development.
Paul’s opinion - tricky one this. I moderated from green to amber/green after the March 2024 profit warning, but am thinking whether I should moderate further to amber, given the poor H1 results, unconvincing outlook (with H2 weighting), and balance sheet & cashflow issues (which hopefully are only temporary).
It’s now looking obvious that the big surge in pandemic sales was a one-off, that has reversed. Hence the share price should be much lower than the highs reached at the bull market peak in mid-2021.
Another risk is that I go cool on what is fundamentally a decent owner/managed group, just near the low point, then end up kicking myself as it strongly recovers in future - I’m sure we all know that feeling well!
Bottom line, I cannot predict the future, and can only go by the facts & figures as of today. That means logically I have to go with AMBER for now, and will happily revise that up once trading starts to improve.
Or an alternative view would be to just ride out the softness in trading this year, taking a longer term view.
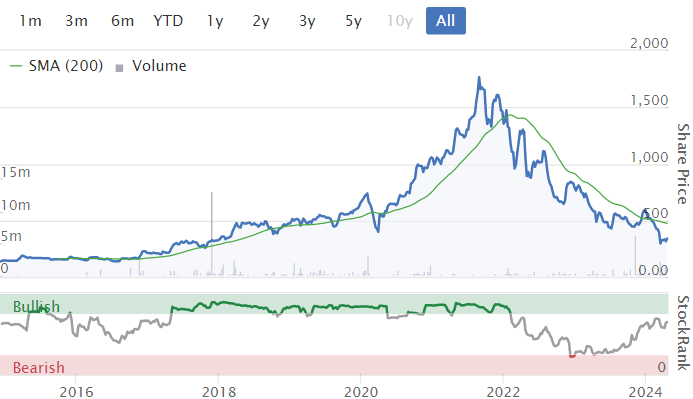
Almost a round-trip in share price since since Dec 2014 AIM listing -
Graham’s Section:
LSL Property Services (LON:LSL)
Up 4% to 280p (£291m) - Full year results - Graham - AMBER/GREEN
This is “a leading provider of financial services, surveying and valuation and estate agency services”.
It had a positive trading update in March, covered by Paul.
After a difficult 2023, improvements in the health of the housing market are flowing through to better performance for LSL:
The mortgage and housing markets were significantly disrupted in 2023, impacting the financial performance of the Group. However, following a positive final quarter of 2023, the preliminary results are slightly ahead of expectations. Momentum has continued to build further in 2024, particularly in our Surveying & Valuation Division. Over the first quarter, Underlying Operating Profit was materially above the same period in 2023, reflecting the benefits of the Group's transformation programme completed in 2023 as well as improving market conditions.
Net cash was £35m at year end - a very healthy level for a company of this size, and LSL today announces a share buyback for an initial amount of £7m. That’s only a little more than 2% of the market cap, but it’s a good start.
CEO comment snippets:
"2023 marked a period of significant progress in our transformation to a higher margin, less capital-intensive business that will perform more consistently through market cycles…
"Following this significant restructuring, LSL is now a more streamlined, agile Group comprising three market leading businesses with high return and organic growth opportunities that are well positioned to capitalise from the recent recovery in the housing and mortgage markets….
Some key bullet points regarding the company’s actions:
Converted an owned estate agency to franchisees. - excellent! The franchise business model is a huge success elsewhere, e.g. Property Franchise (LON:TPFG).
Separated off its B2C businesses into Pivotal Growth, a joint venture. LSL’s core activities are now focused on B2B.
Sold a London estate agency brand “which did not fit into our overall franchising strategy”.
Bought a mortgage network (Feb 2024).
Result of the above: annualised cost basis reduced by a remarkable £140m.
Of course revenues will also reduce, e.g. converting an estate agency to a franchise business model will mean sharing profits with the franchisees.
The company states that it believes its weighted average cost of capital is 12% - I find that few companies will publicly state this. Good transparency! It means that if the company can’t earn a return of more than 12% on investments, it should instead return the surplus cash to shareholders.
Dividend is unchanged at 11.4p for the year.
When you have a long verbal commentary at the beginning of a results RNS, it’s often the prelude to very bad numbers. This is the results table for 2023:
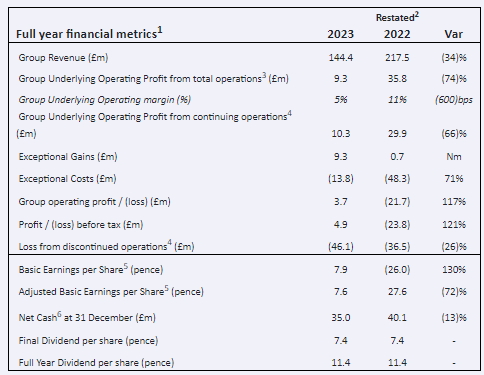
The company emphasises that the like-for-like revenue decline was only 10%, not the 34% shown above. Given the mortgage market troubles, this is understandable.
Current trading and outlook
As noted at the top, mortgage market conditions have improved in 2024. The company continues:
It was against this background of improving activity and Group trading that we issued a trading update on 6 March, since which time trading has remained ahead of expectations. At the end of Q1 2024, Group Underlying Operating Profit was materially ahead of the same period in 2023. This improved trading reflects better market conditions as well as the benefits of the new Estate Agency franchise model, improved lender contracts, and our decision to retain surplus capacity throughout the second half of 2023 in our Surveying & Valuation business.
Although we retain a degree of caution, inflation data still suggests that interest rates will reduce in 2024, which would help support our markets. This, together with the strong performance since our recent trading update on 6 March, reinforces the Board's confidence, and our expectations for full year Underlying Operating Profit have increased further.
Estimates for FY Dec 2024 have increased again at Zeus. They have increased their revenue estimate by 2.5% to £164m and their adj. EPS forecast by 14% to 18.6p. The current share price 280p divided by 18.6p implies an adjusted PER of 15x.
Graham’s view
This company hasn’t interested me too much before, but I’m sitting up and taking notice of today’s results.
We have:
A rational capital allocation policy, including an explicit WACC and a commitment to returning excess cash to shareholders, starting with a £7m buyback.
A business model I really like - the franchise estate agency model.
Possible comparisons (with thanks to Zeus for mentioning it) with another business model I like at Mortgage Advice Bureau (Holdings) (LON:MAB1).
Developments here suggest that LSL is now a much higher-quality business than it was before, implying that a PER of c. 15x makes good sense.
I’m therefore maintaining Paul’s AMBER/GREEN stance.
Dalata Hotel (LON:DAL)
Down 0.5% to 372p (EUR €934m) - AGM Statement - Graham - GREEN
Dalata is “the largest hotel operator in Ireland, with a growing presence in the United Kingdom and Continental Europe”.
After Jet2’s statement yesterday suggested a little softness in pricing for their package holidays and flights, let’s look at the travel industry from a different angle with this share.
Dalata has 53 hotels with a total estimated value of €1.7 billion and 2023 revenues of over €600m.
2023 saw new properties added to the portfolio in Amsterdam, London and Edinburgh.
2024 will see new hotels in Liverpool, Brighton, Manchester and London.
So how is 2024 going so far? Here is an excerpt from the AGM statement.
(RevPAR = revenue per available room.)
2024 has commenced with good performance for our UK portfolio which is expected to achieve modest RevPAR growth on January to April 2023. We also continue to see healthy levels of corporate demand across all regions.
As reported during our full year results in February, there has been lower levels of trade in Ireland…
RevPAR for the Group is expected to be 4% behind 2023 for the period of January to April on a ‘like for like’ basis.
As we look ahead, we remain optimistic in our outlook for the remainder of the year where trade typically is driven by stronger seasonal factors…
The Group has considerable firepower available for further growth in line with our ambitious and disciplined growth strategy. We remain focussed on growing in 11 key cities in the UK and establishing a presence in targeted large European cities with a strong mix of corporate and leisure demand.
Graham’s view
It’s not a great start to the year, but with eight months left there is plenty of time for things to pick up.
When it comes to the bigger picture, I appreciate Dalata’s ambition to expand and I’m a fan of their Clayton and Maldron brands.
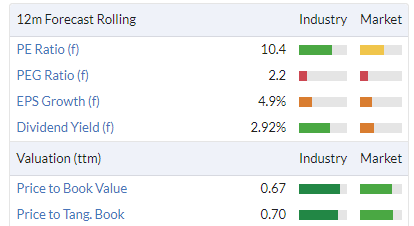
The value metrics here strike me as potentially tempting for new investors:
When I last looked at this share, back in August 2023, I gave it the thumbs up.
With the share price unchanged, I’m inclined not to change my view. The company’s expansion plans will bring financial risk but after generating net income of €90.2m in 2023 (which does not include revaluation gains on property of €92m), and free cash flow of €133m, I would say the company is entitled to expand.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Hello Paul, I believe the £5.5m and £2.9m figures for NAV & NTAV are back to front on the MEX commentary. Thanks for your brilliant reports and podcast.
Thank you Plutarch!
Re Tortilla Mexican Grill (LON:MEX)
Very well spotted, I was wondering if anyone would notice that ! ;-)
The correct figures for MEX's balance sheet are: NAV is £2.9m, then I deducted £2.6m intangible assets, so NTAV is actually £0.3m.
Very sorry about that, I'll correct the article now.
Thanks!
Best wishes, Paul.
US 10-yr rates moving towards 5% again. Up to 4.71% as of now on the back of higher than expected Q1 US inflation numbers today and lower GDP growth than forecast. https://tradingeconomics.com/u...
At least the UK markets are holding up better for a change. US rates peaked at 5% in mid October 2023. This all looks a tad stagflationary to me! Not great conditions for global equities.
UK indexes up 10-15% since the October 23 lows. Painful sitting on the sidelines. Remember, no-one rings a bell at the bottom!
Just for clarity, I'm not on the sidelines Kouremenous, but am 34% cash and short-dated gilts, 66% equities of which over half is in the UK. I will reinvest the cash only after the yield curve inversion plays out and not before. Still plenty of things to buy in the UK but caution is the name of the game (in my view) unless this time really is different and we are off to the races again. Time will tell, but at least you can get 5% tax free in UK gilts whilst you wait...getting boring though after c2 years!
Yes indeed, only time will tell as you say topvest. I've been bullish since October 23 but I was also bullish in Oct 22! Hopefully this one is for real :-)
Tortilla Mexican Grill (LON:MEX) . There is an Investor meet company webcast tomorrow at 9 am with the new chief exec (ex FD) about the results. www.investormeetcompany.com
LSL Property Services (LON:LSL)
Coincidentally I've just watched the IMC presentation of Property Franchise (LON:TPFG) 2023 results HERE. As well as good performance last year in a very slow market much is devoted to an update on the Belvoir merger and I was impressed by the plans for the future. Worth a watch if this sector interests you, I can see more consolidation in the future.
Mello physical meeting 22-23 May, But Who is Who?
I am looking forward to attend and in particular meeting some of the Stocko community there. My problem is that many of the community here use their nicknames in Stocko but are under their real names in the meeting. I have difficulty identifying who is who.
I can recognise Paul, Graham and Ed. Thank you for being yourself.
I appreciate any help in this regard!
Keyboard warriors don't like to give away their true identities...
You will easily recognise me from my user name.
But I might be bluffing.
Hi yadi
I will be at Mello on Thursday 23rd. I can't make the 22nd as unfortunately I have another engagement. Look out for John Dunne on the name tag, hence my Stockopedia nickname Jonno.
Look forward to meeting you if you are there on the Thursday.
Corero Network Security (LON:CNS) - "Excellent momentum in new orders"
Corero has secured $8m of orders from both existing and new customers in the first four months of FY24E. The group reported a 17% YoY growth rate in annualised recurring revenue (ARR) last year. This level of momentum in orders not only supports our double-digit % growth forecasts, but also validates the Group’s go-to-market strategy.
We are forecasting +13% growth in revenues in FY24E to $25.3m (unchanged), With gross margins high at 90%, the drop through rate of incremental revenues to earnings means that EBITDA margins should reach double digits this year. The stock is free cash flow positive with a forecast FCF margin of 6.7% in FY24E. Net cash balances will continue to grow as a function of this free cash flow growth (+33% to $6.9m in FY24E).
The share price is only just beginning to wake up to the progress made in bringing the business model to maturity, in our view. Trading at the top of its 12 months price range, the stock’s forward rating of only 2.7x EV/Sales in FY24E continues to support our fair value assessment of 14p price/share.
New research note: https://www.equitydevelopment....
Thanks for looking at the update from Focusrite (LON:TUNE).
It's clear they made a complete bodge of the rollout of their 4th gen Scarlett interface range. 8 months after launch and there is still plenty of stock of the 3rd Gen models in the shops - clearly something was terribly wrong in their forecasts of how quickly they would shift the older models, not to mention the delay in releasing the rest of the (higher priced) range due to engineering resource issues.
However they do have a very good brand range overall, with the Focusrite & ADAM brands maintaining very good market share. The Thomann web store publish sales ranks, and the Focusrite interfaces had 5 out of the top 6 sellers when I looked earlier in the week.
If you do a read across from the Gear4music (HOLDINGS) (LON:G4M) results it seems like the overall market drop in sales has reached a plateau.
So depending on what their new products are, they could well see an upturn in sales in H2, coupled with a hoped for consumer recovery, if they maintain their market share. From personal experience, everyone loves a new bit of gear for their home studio!
Re Focusrite (LON:TUNE) I would also add that there is direct read across from the recent Videndum (LON:VID) update where content creation has also been very tough.
Additionally as this may be a post pandemic miscalculation regarding the stock overhang it is similar to what planetx has been posting often about the bicycle market just getting demand forecasting hideously wrong -to the point of bankruptcy in some cases. The problem for TUNE is that technology probably goes out of date more quickly than a bicycle frame! Though I do acknowledge other factors could be involved too such as fads and fashions ;)
Inchcape----Paul, you may be missing the point. The market has at last woken up to the fact that by selling its volume intensive, but low margin, UK retailing operation, the company will now be a distribution business demanding to be valued on a higher p/e multiple
Thanks david kleeman, that sounds credible, good point re a possible re-rating for Inchcape (LON:INCH)
Could it be attractive to a foreign takeover too, I wonder?
Given its popularity here, I'm surprised nobody has commented here, as far as I know, on Beeks Financial Cloud (LON:BKS) tie up with SST announced on 5th April. Is there an overlap? Will there be profit sharing? Who is in the lead? Is this a sign of weakness or strength?
Beeks Financial Cloud (LON:BKS) went up on the news, then down again almost straight away. Sounds as though the mkt doesn't value it either way.
Not sure there was much to value Sheeza
I am a big fan of Beeks Financial Cloud (LON:BKS) longer term for all the reasons I’ve highlighted before. However, this feels like product development but I have zero idea what it means to revenues, margins and/or when so I discount it for now.
Trading statement by PPHE Hotel (LON:PPH) https://www.stockopedia.com/sh...
All about future growth with new opening, London was yesterday, Football euro benefit in june, july, nice and boring
Thanks for flagging PPHE Hotel (LON:PPH) - interesting to see how much better it was than Dalata Hotel (LON:DAL) .
Bioventix (LON:BVXP) is not the most communicative company - interims were on 25/3 and if last year is a guide the next trading RNS will be the prelims at the end of October. So it is helpful that Cavendish have today put out a detailed (16 page) note on the main hope for replacing Troponin revenue when that ends in June 2032. "Laying out the longer-term opportunity in Alzheimer’s Disease" can be found here: https://www.cavendish.com/rese... (registration may be needed).
Norcros (LON:NXR)
Norcros handing the keys to Johnson tiles over to management.
I can't work out whether this is good news or bad news , i was kinda undecided until i looked at the 2018 Annual report comments below - it seems clear to me that this unit has had prior struggles even pre covid , so i have semi satisfied myself that they are not hopefully giving away a decent unit dirt cheap at the bottom of the cycle. There are clearly some parts of the business making "good profits" so effort spent on stuff not making decent ROI is probably semi wasted (there is obvious cross selling opportunities) - so overall its probably the right choice - even if its possibly got down sides ref cross selling top customer etc - thats the beauty of norcros they should be able to cross sell their complimentary products to different customers/customer bases - so slightly less opportunity there , i would say perhaps selling to management may be the lesser of evils rather than selling to competitor who may use that as in in to their customer base - who knows what management may do though they may sell for quick buck to topps tiles !- hopefully very friendly divorce
Whilst the actions to restructure the Johnson Tiles business in 2017 were completed successfully, market conditions in the second half of the year proved more challenging than expected. As a result, a further restructuring programme has commenced which will involve the loss of up to 50 jobs. This has resulted in an exceptional charge of £2.1m. Annualised savings are expected to be at least £2.0m and we remain confident that this decisive action will return the tilebusiness back into profitability in the current year.
Norcros (LON:NXR)
I am a bit slow on the uptake here - the last major acquisition for Norcos was Grant Westfield, they are specialists in panelling. With the move away from tiles to panels generally (are there any old skool peeps left who still like to use tiles where panels would do the job?) it does make much more sense them ditching the Tiles side of things if Panels is the way to go. Obviously nowt wrong in theory with offering both but better to be in expanding rather than contracting segment. The price they paid for GW didnt seem particualrly cheap at the time but it does seem to have probably be a necessary pivot at the right time here - a quick look at the Topps tiles site confirms they have plenty of Panels for sale - so even the tile retailers can see the writing on the Panels here.
I looked at panels but they were very expensive, so I'm still looking at using tiles. Don't know anyone who has panels. But I will check again, maybe prices have come down as they become more popular? Choice of colours was rather limited as well. Range in Wickes is very uninspiring.
Seems like Norcros (LON:NXR) are almost giving away Johnson Tiles for free? £1m consideration, some earnout (they already caveat as "modest" and only in 2028).
Costs of the transaction will be less than £1m, but still in the 6 figures I am guessing?
£35m rev, £0.5m operating profit in FY Mar23... looks like it was not bleeding money massively... although they did say it was "sucking up cash" in the last three years (losses? working capital?)
I get the (weak) strategic rationale, but this is a brand name in the market, has some decent sales volume and manufacturing capabilities, and wasn't losing huge amounts of money, plus at a cyclical low of tile demand...
Not really seeing much of this being good news.
Norcros (LON:NXR)
Obviously the fact they are losing revenue and "potential" profit is a poor starting point , as you say at the low point of the cycle management may be driving round in the same type of car as richard pryor in superman 3 soon. However it looks to me like this unit has been struggling for years as per earlier post 2018 was woeful - a line needs to be drawn somewhere and and the ulta poor margin preumably aint worth the effort compared to the rest of what they do. It makes sense to ditch all the low margin stuff and concentrate on stuff where you know extra sales will bring home the bacon. I am probably glossing over the other negatives here but seems reasonably clear it simply didnt pay its way enough (if at all) - i trust management here to know whats best for us shareholders or on the balance of probability be more likley to get it right than wrong.
per zeus - taken from stuff posted freely on the net by others
contributing a margin of c. 1.4% compared to the overall UK EBIT margin of c. 12.6% in FY23. Today’s announcement confirmed Johnson Tiles UK has been consuming cash for the last three years with the sales proceeds to be used for working capital purposes. Zeus view this sale as a positive step towards streamlining the UK operations and highlights the strong operating margin the UK business achieved (excluding Johnson Tiles UK) in FY23 (c. 14.1%).
Change to forecasts: Zeus adjust forecasts for FY25 and FY26 following today’s announcements. We assume Johnson Tiles UK would be capable of generating c. £35.5m in both FY25 and FY26 but contribute no operating profit for the group. This results in EBIT remaining unchanged for both years, with FY25 revenue of £366.7m (previous: £402.2m) and EBIT at £41.5m. We repeat this for FY26. Based on these changes, the Group’s EBIT margin improves 100bps in both FY25 and FY26 to 11.3% and 11.6%, respectively, with the UK generating an operating margin of 14.7% (previous: 12.9%) in FY25 and FY26. Net debt (excl. leases) for the Group remains unchanged at £31.9m in FY25 and £17.8m in FY26. This may turn out to be a conservative assumption as Johnson Tiles UK consumed low single digit millions in cash over the last three years.
Norcros (LON:NXR) like you I was surprised by the disposal. However on reflection it’s sounds as though this will free up management time from a headache and at 8% of group sales will give quality of earnings a really nice upward kick which might bring in excited new shareholders in the next few years and do wonders for the valuation. Fingers crossed!
Norcros (LON:NXR)
I think we are all agreed here perhaps - its not that this is a particulalry positive move at face value , the fact it makes sense doesnt mean that any of use want them to be giving up in areas they should excel at - it is a realistc solution though - i think perhaps we have all slightly missed how poorly this unit has been performing - their route taken has obviously not been taken lightly. Ref updward kick - the brokers have made clear they expect this to be neutral so i dont really see any specific positive benefit - its just that they are making the best of a semi bad job.
Norcros (LON:NXR) Puzzling that the brokers think it will be neutral. We’ll have to see what they say online at the presentation on the 7th May.
Norcros (LON:NXR)
its not clear to me whether you think profits should go up or down without this unit ? basically they are saying it wasnt really making any meaningful profit - if there was a profit contribution then removing that may streamline central costs perhaps to compensate. This being the case its business as usual.
Re Norcros (LON:NXR) in theory the disposal should surely improve earnings by the amount of rent the MBO pays for the valuable site it occupies…in reality I suspect matters are more complicated by the need for Norcros (LON:NXR) to give the newco the best chance of being ultimately able to reach self sustaining status….I'm also curious as to how this “disposal” impacts the pension scheme as this division historically had a far larger headcount …lots of questions remain for the investor call.
Norcros (LON:NXR)
the ability to accrue pension contributions ended in 2013 i am pretty sure. I would expect any entitlement that is based on years of service would probably be as what it was previouly with staff being tupped over. So i wouldnt really expect anything to change - Norcros will be on the hook for what they were previously with no change to that position. Perhaps there could be some benefit if the business later closes and that reduces years worked - but i wouldnt preume that is the case. Not sure if the yearsd of service calcs might have been frozen at the same time future contributions were scrapped in 2013?
Norcros (LON:NXR) I was thinking that profits would be down and defrayed a little but better quality ratios as they would be a larger percentage of a reduced group turnover denominator if that makes sense…
However, I could see that maybe it might be less impactful if there is a lower contribution to group overheads and other costs such as the pension.
ECO Animal Health (LON:EAH) - FY24 ahead of expectations
In a trading update for the twelve months to end 31 March 2024, ECO Animal Health reports that revenue should be close to £90m; this compares to the March trading update outlook of £88.7m. The Group expects that FY24 (adj.) EBITDA should be in line with the current market consensus expectation of £7.8m (ED estimate was £7.6m). The year-end cash position was approximately £22.0m; we estimated £20.1m.
The Group also noted EBITDA delivery against the background of maintained investment in R&D, the wellspring of future product and revenue streams. Our FY24 estimates include provision for £4.2m of R&D spend for the year.
Our Fair Value range is 137p-146p, reflecting the potential in the pipeline of products under development, which is backed by the rigour of EAH’s development-to-distribution process.
Link to research: https://www.equitydevelopment....
ECO Animal Health (LON:EAH)
unfortunately Eco are very poor on the updating the market , i hold a few shares here. They say its an update on profits and there is no mention of what the profits are - that is utterly ridiculous and management should be hauled in front of hot coals in that regard . There is reference to EBITDA but no reference to profits - EBITDA begins with an E and has no P as it doesnt reference the bottom line profit total. If this company wants to be taken seriously they should at minimum cross reference underlying earnings and ideally pre-tax profit. If you aint referencing profits dont pretend you are either !!
Being ultra sketchy can mask good updates unfortunately
Ok some clues ref the important profits that the company chooses not top tell us today.
looking at last year EBITDA was £7.2 mill and post tax profit was £3.1 mill. ooh i was expecting worse. Note out of that profit 2/3 was non controlling interests profit make of that what you will.
Equity Development feel free to send my fedback back to the board - hopefully if Paul/Graham agree they can similarly chip in as they may pay more attention to what Paul says than me
Driver (LON:DRV) - Trading update - activity remains on budget
The pre-close trading update from Driver Group delivered encouraging progress overall, with the smaller regions returning to profitability and a positive performance in the UK and Europe. The cost rationalisation was completed during the period following the move to a smaller London office. Cash continues to remain high, representing 32% of the market capitalisation.
The strategy put in place in H2 of FY23 is expected to deliver higher revenues and profitability ahead of 2027, not least reflecting the focus on added-value expert services.
We see little reason to adjust our 40p fair value/share, with no change to estimates. The share price remains below the NAV currently and is underpinned by cash.
Link to research note: https://www.equitydevelopment....
MEX is on my swing trade watchlist too. Has given quite a bit back after the late February excitement though so would want an uptrend confirmed first if the stock broke out of the 60p high.
Tortilla Mexican Grill (LON:MEX) A very healthy 77% gross margin on £65m top line but where is it all disappearing to? The majority of their staff are on minimum wage but I note Head Office count is up to 52 and they have some NEDs on over £80k pa! That's excessive for such a small company and I can't believe new shareholders Luke Johnson & Hanover International won't be pushing the new CEO to have a long hard look at costs.
Still it's valued at something like £250k per restaurant, which is peanuts, less than fit out costs, debt is minimal, cash flow positive, share count has remained stable, I agree with Paul it is far far too cheap but as a holder I would say that....
Avation (LON:AVAP) looks interesting. Last aircraft leased so fewer storage costs etc and generating income. NAV over double share price, has $150m cash on hand.
Even ignoring assets from p&l looks like they can generate c£10m pa from the leasing business so the £72m mcap is justified by this with all the net assets on top. Can't see any downside except a major pandemic. And up to 100%+ upside, so maybe being realistic around the £1.75 level assuming some haircut
Any other views?
AVAP are still paying down debt - once that is reduced they may start paying dividends . I Hold. 100% upside certainly looks realistic over the next 24 months, bar as you say any international pandemic- which looking at historically should not happen for a number of years.
Hi
Not small caps but interesting M&A in the UK market.
BUZZ-Anglo American soars after BHP Group's $38.8 bln offer
 Anglo American
News24 minutes ago** London-listed miner Anglo American's AAL.L shares jumpmore than 12% to 2,470p, their highest level since July 27, 2023
** BHP Group BHP.AX made an offer to buy Anglo American,
valuing its share capital at 31.1 billion pounds ($38.84
billion)
** BHP will offer AAL shareholders 25.08 pounds per share,
including 4.86 pounds apiece in Anglo Platinum AMSJ.J shares
and 3.40 apiece in Kumba KIOJ.J shares
** AAL says it is reviewing BHP's proposal with advisors
** BHP closed at A$45.23 on Wednesday
** As of last close, AAL stock up 12% YTD
($1 = 0.8008 pounds)
Regards
Howard
Anglo American (LON:AAL)
From Morningstars London Early Market Call :-
"The buyout offer from BHP, the world’s largest publicly listed miner, for Anglo American, won’t just shake up the mining industry, but will send a fresh chill through the City of London. There are concerns that if the deal goes through it could be the tip of the iceberg and more giants could leave the exchange," said Hargreaves Lansdown analyst Susannah Streeter.
Quite a while ago I came to the conclusion that I couldn't understand any company listing on the UK stock market - it needs major surgery or it will whither on the vine.
"......will send a fresh chill through the City of London". Well its the City of London that's causing the problem.
A.
I think the regulator may stop this merger from happening. I doubt SA will be pleased with BHP taking over AAL. Plus why would AAL shareholders want BHP paper ... history shows they are not the best run mining company.
This bid for Anglo American (LON:AAL) looks too low to me. I hold. I can buy BHP (LON:BHP) shares today but I choose to buy Anglo American (LON:AAL. ). Think they need to raise the bid to nearer £30.
It’s a derisory offer for Anglo American (LON:AAL) and it’s paper, so worth even less if the BHP (LON:BHP) share price falls. BHP was down 70p just now.
Anglo American (LON:AAL) share price was over £40 two years ago. £25 paper bid when the share looked oversold, looks opportunistic. So Anglo American (LON:AAL) could well go way higher than £25.
A big and long running Mining sector bull market could well be imminent, and already the main shares in the sector like Rio Tinto (LON:RIO) Glencore (LON:GLEN) BHP (LON:BHP) are well above recent lows. Anglo American (LON:AAL) bottomed at about £17 and 55% below the 2022 peak.
A few reasons why a big Mining bull market could already have started:-
1. Mining sector debt is at historic lows and at lows compared with other sectors.
2. There has been a decade of underinvestment in to new metal supply. So supply shortages and rising commodity prices ahead.
3. Inventories for copper are now at relatively low levels. So recent oversupply because of that temporary lower demand will likely reverse.
4. Metals are ESSENTIAL for renewable energy.
5. Global demand for copper, nickel, cobalt and lithium likely to rise dramatically along with masses of iron ore going to be needed just for wind turbines for starters. The copper price has already soared this year while iron ore hasn’t…YET.
That underinvestment in new mining projects could well see demand far outstripping supply with much higher core commodity prices ahead as a result.
6. Mining sector trading at around 6 times cash flow. That’s the lowest for many years apparently.
Another UK listed company taken out on the cheap. This is getting ridiculous!
According to Citywire, The Times has an article this morning (behind paywall) that some of London's largest listed companies could see their valuations as much as double by moving to New York
Pinewood Technologies (LON:PINE) issued their first set of financial results this am. Hoping Paul or Graham gets a chance to comment on these. Paul wasn't too keen earlier in April after a quick review of the info available at that time.
Morning Paul,
This message thread looks like it doesnt appear on the front page of stocko, just in the all discussions section. Might be worth a tweak to settings, I think you mentioned previously.
Just letting you know, as I kno, I for one usually look for your daily thread on the front page.
Keep up the great work.
Andy .
Morning Paul, thanks for all the work you and Graham put in. Also it is not appearing under Small Cap value report in the blog section either
Sorry Andy, I've fixed the settings now. Thanks for flagging.
Just a reminder that there is a marathon Mello Results Review show this afternoon from 1pm and scheduled to finish around 6.45pm.
It is completely free and an amazing programme lined up with about 17 companies presenting or featured and so long as you have registered then you can receive the recording and watch at leisure or simply tune in at the start and listen in during the day….
https://melloevents.com/mrs-25...
It will be a post pandemic record attendance and if you have questions during the show I try to fit them all in but apologies if I don’t as I suspect there will be lots today.
See you all later
David
Wow....thank you to everyone for registering...it has been one of you every minute since 7.30am and we now have 340 registered so this will be a post pandemic record attendance
I appreciate it is easy access and no need to travel anywhere to see and hear about all these companies this afternoon but do please consider coming to Chiswick next month and meeting and networking with fellow investors and actually meeting the management teams of 45 companies under one roof.
Mello2024 – Mello Events