Small Cap Value Report (Thu 25 Aug 2022) - LIFE, AQX, MACF, ARB, HTG, SCHO

Good morning from Paul & Graham. Today's report is now finished.
Agenda -
Paul's Section:
Love Hemp (OFEX:LIFE) shares are suspended on the Aquis junior stock market. It has been fined £70k by Aquis, after an investigation into important information not being reported to the market. So it looks as if Aquis has a reasonable regulatory system.
Macfarlane (LON:MACF) - solid interim numbers are out today. Full year expectations for FY 12/2022 are confirmed. Balance sheet & cashflow look OK. I particularly like that MACF is passing on higher costs to its customers. That should mean solid profits, even in a tough economy, and long-term inflation protection for investors too. Divi of 3.1%, and a PER of 9.9 make this a sound vale share. Thumbs up from me.
Hunting (LON:HTG) - interim results show a recovery from heavy losses in 2021, to breakeven in H1. Outlook for H2, and 2023 is more upbeat, with a strong order book, and obvious macro tailwinds. Superb balance sheet, and a reasonable dividend yield add to the attractions. Worth a closer look, for people who understand the sector.
Graham's Section:
Argo Blockchain (LON:ARB) (£196m) - Interim results from this bitcoin miner with operations in Canada and Texas. The reduced price of bitcoin has resulted in red ink all over this report as the company reports a very large pre-tax loss. It has also resulted in the company slowing down its growth aspirations for this year. I’ve always found this company quite interesting but never had any desire to invest in it, and the latest balance sheet confirms my view that management are pursuing an extremely high-risk financial strategy with the assumption that bitcoin prices will rise in perpetuity and that it will always be possible to refinance their borrowings.
Scholium (LON:SCHO) (£6m) (+7%) [no section below] - this is an oddity: a Mayfair bookshop specialising in rare books, plus related operations dealing in rare works. It has never been entirely clear why it is listed, given its size and lack of growth. The shareholders must have a keen interest in trading with each other, to put up with the costs of being listed every year! Well-known investor Peter Gyllenhammar owns a 13% stake.
Today’s full-year results show revenues up strongly to £8.1m (post-Covid bounce) with an improved gross margin of 38% and a pre-tax profit of £177k. Net asset value per share is fully tangible and stands at 69p (versus the latest share price 45p). The company has a new CEO who reports that trading in the first four months of the new financial year (beginning in April) is in line with expectations. Profits in FY 2022 were impacted by £240k of exceptional costs so perhaps pre-tax profits can move in the direction of £500k in the current financial year? If I could put up with the delisting risk and illiquidity, I’d find this an entertaining deep value play, with the hope that it could eventually trade at or above its balance sheet value.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Love Hemp (OFEX:LIFE)
Share suspended
Love Hemp (OFEX:LIFE) shares are listed on the Aquis Exchange, the sub-AIM independent stock market, which has been through several previous incarnations, including OFEX, and Plus Markets. Aquis shares are themselves listed on AIM under the ticker Aquis Exchange (LON:AQX) . I did check out its accounts a while back, and didn’t really understand where the profit was coming from (especially given that previous versions of this junior exchange had always been heavily loss-making), so went away not keen.
This is an interesting situation which caught my eye this morning -
Love Hemp (LIFE) is listed on Aquis, and this announcement today explains how the company failed to inform the market that an investor failed to produce the £1.2m agreed investment in the company.
LIFE withheld this information for almost 2 months. When it informed its corporate adviser (Peterhouse), they resigned, and its shares were suspended.
Finally LIFE then announced the failure of the investor to deliver the funds due.
So a rather sorry tale.
Today this is all announced by Aquis, along with the imposition of a £70k fine on LIFE.
The disciplinary notice also sets out the various rules that have been broken. So it looks as if Aquis has a fairly decent structure of rules, with consequences when wrongdoing is discovered. That seems reassuring as a potential investor, seeing that there do seem to be sensible rules in place, and action taken when they are broken.
LIFE itself announces that it has reached a settlement with Aquis, and hopes to resume trading of its shares, once a new adviser has been appointed (which sounds like the equivalent of a NOMAD on AIM).
My opinion - there are a couple of shares on Aquis which I’ve always quite liked, and information is available on Stockopedia too - Daniel Thwaites (OFEX:THW) and Chapel Down (OFEX:CDGP) . Also I looked at Samarkand (OFEX:SMK) a while ago, and thought it looked quite interesting.
My broker told me that liquidity is very poor on Aquis though, so I didn’t end up buying any of those.
It’s encouraging to see Aquis take proper action against LIFE, after investigating wrongdoing. So I’ll keep an eye on things, and report back when Aquis publishes its next accounts. It would take a lot to convince me that another stock market, junior to AIM, is viable though.
Macfarlane (LON:MACF)
114p (pre market open)
Market cap £181m
This group, headquartered in Glasgow, makes & distributes packaging products.
Company’s summary crams in a lot of information into one sentence! -
Expectations for the full year unchanged; managing inflationary environment; slowdown in e-commerce; progress in Europe
A few numbers -
H1 revenue up 14.0% to £139.2m
Gross profit £47.1m (33.8% margin, slightly down from 34.2% margin H1 LY)
Distribution costs up 32% to £5.17m
Profit before tax of £8.9m, up 3.2% - I’d say that’s a reasonable performance, given that we know there must be considerable cost pressures, due to macro factors.
Labels division has been sold (Dec 2021), so is stripped out of the above figures. It seems to have been generating small losses.
2 acquisitions have boosted the numbers.
Softer demand from eCommerce customers.
Key point - successfully passed on cost increases to customers.
Net bank debt £9.7m (“well within” £30m facility, to Dec 2025)
Pension scheme - showing an accounting surplus, but the cashflow statement shows a £1.3m cash outflow in H1, so caution needed here. See note 12 for more info.
Balance sheet - NAV £97.8m, less intangible assets of £79.4m, gives NTAV of £18.4m.
Other adjustments I would make, is to remove the £8.8m pension surplus, which looks an anomaly (as we often find with unrealistic pension scheme accounting, showing deficits as surpluses). It should probably be replaced with the more realistic actuarial deficit number, but I can’t find that figure, so just eliminating the £8.8m bogus surplus is enough. That takes NTAV down to £9.6m - which looks OK, at least it’s positive.
Receivables seem quite high at £60.8m, indicating that the company may not be collecting in payment for its invoices tightly enough. I make that payment terms of 66 days, although it could be a bit less than that, as usually there are other sundry items (e.g. prepayments) within receivables. So it might be more like 60 days average payment terms by customers, which is at the top end of what’s acceptable. It’s important not to let customers use you as a bank, so I think some tightening up of credit control might a be a good idea. After all, MACF is having to pay interest on its bank borrowings, which could be eliminated if it accelerated customer payments to say 45 days instead of 60 days. That’s worth mentioning if anyone talks to management. Customers paying slowly also increases the risk of bad debts.
Overall, the balance sheet looks OK, although I would prefer them to raise some fresh equity, if they do any more acquisitions.
Cashflow statement - looks clean, i.e. this is a genuinely cash generative business, which is being used to pay modest divis, but mainly for acquisitions (£9.3m outflow for acquisitions in H1, and £12.2m last full year).
Outlook -
We expect to experience a continuing challenging environment with inflationary pressure on our operating costs and slower demand from our e-commerce customers. Overall, the Group is confident that the effectiveness of our strategy, the diversity of the customers and sectors we serve, the quality of our people, and the resilience of our business model will ensure 2022 will be another year of growth for Macfarlane.
Our expectations for the full year 2022 are unchanged.
My opinion - this looks a good, solid business.
We know that macro conditions are deteriorating, but so far MACF has demonstrated it can cope with higher inflation, by passing on the costs to its customers. Therefore, I imagine this share would probably be a fairly safe haven in a tougher economy.
That you can buy a decent quality business like this for a forward PER of only 9.9, looks a good long-term buying opportunity to me.
There’s a 3.1% dividend yield to keep you amused too.
Another key point to consider, is that businesses like this, which can prove they are able to pass on inflationary cost increases, could turn out to be very good ways to protect yourself from inflation. Sure, profits might dip in the short term, but inflation means that the business is getting bigger. Hence, over time, logically the share price should also rise.
Whereas bonds & cash are terrible places to invest, in a high inflation environment, for any extended period of time anyway (cash has done nicely in avoiding plunging equity prices in the short term, but that effect is inevitably going to reverse at some point, no idea when though).
EDIT: Thanks to Effortless Cool who reminds us in the comments section below that MACF expenses its amortisation charges relating to acquisitions. Whereas practically all other companies adjust out this charge, thus boosting their EPS. So comparatively, MACF understates its profits by not presenting adjusted numbers. That's a positive from an investment point of view, as it hides some of the value in the share. I remember now covering this in a previous SCVR, but had forgotten about it, so a useful reminder, many thanks! End of edit.
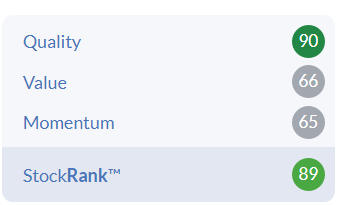
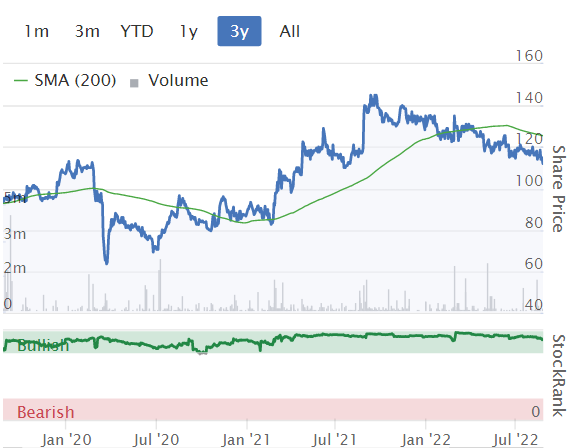
Overall then, a thumbs up for MACF from me, and the StockRank system -
.
.
Hunting (LON:HTG)
256p (up 13% at 09:03)
Market cap £421m
Nearly £50m added to the market cap this morning, so these numbers must be good.
I last looked at this energy services group here in June 2022, with a very confusing update which sounded positive, but was actually a profit warning, triggering an 18% share price fall. The problem was that existing forecasts were too high, so were brought down.
Strange that they’ve issued 2 separate announcements, normally companies include a current trading section within interim results. Also you have to click through to 2 further pdfs for the detail, so HTG has managed to scatter its interims into 4 different sections!
I’ll look at the interim results first.
Hunting PLC (LSE:HTG), the international energy services group, today announces its results for the six months to 30 June 2022.
H1 revenue $336.1m (up 38% vs H1 LY)
Heavy losses in 2021 (including big write offs of fixed assets & inventories) have improved to a near-breakeven result for H1 2022 of $(0.5)m loss before tax (2021 full year: $(85.5m) loss.
Balance sheet is large, and very strong. NAV $853m, NTAV $657m.
Working capital is strikingly good, with current assets of $496m, and current liabilities of only $121m. There are very few long-term liabilities (only $34.8m), hence this balance sheet really is bulletproof.
It has net cash of $81.7m.
Hence absolutely rock solid overall, although it does raise the question of whether this company is making efficient use of that capital? Generating only a breakeven result for H1.
If it can’t improve the return on capital, then it might make more sense to shut the company down, and distribute the capital to shareholders, but that’s probably not feasible. At the very least, the group might need a strategic review, and possible restructuring, to generate better shareholder returns?
Although with the price of oil now so much higher, and an energy crisis in full swing, the outlook could be much improved for Hunting? So perhaps low quality ratios might sort itself out if business improves?
Dividends - interim of 4.5 US cents (up 12.5% on H1 LY).The StockReport suggests a forecast yield of 3.36%, not bad, and that’s growing remember. It’s affordable too, given the balance sheet strength, and improving profitability.
Outlook - comments within the interim results statement sound upbeat - e.g.
The second half of the year is expected to see further improvement in earnings, which is supported by our forward sales order book, which now exceeds the position seen in 2019, providing a positive outlook for the remainder of the year and into 2023.
… strong progress continues to be made in building its forward sales order book, which provides further visibility on revenue and earnings for the balance of 2022 and into 2023…
The Board notes that Hunting's sales order book now exceeds c.$400 million which represents a near doubling since 31 December 2021, demonstrating that the global energy industry continues to strengthen following the COVID-19 pandemic.
Broker update - many thanks to Arden for providing an update note today, very helpful.
It has forecast $10.7m adj PBT for FY 12/2022, rising strongly to $30.3m in 2023.
Not madly exciting numbers for a £421m market cap company.
In EPS terms, that’s 5.0 US cents for 2022, and 14.2 for 2023.
Converting that at £1 = $1.18 gives us 4.2p and 12.0p (PERs of 61 and 21 times).
So to be reasonably valued, this share needs to at least achieve 2023 forecasts.
My opinion - neutral, as I don’t know enough about the sector.
Although it seems obvious that with a high oil price, and new concerns over energy security that have been ignored for years, with the dash for renewables and the foolish European reliance on Russian gas supplies, that there must be a strong macro tailwind for Hunting, and others in the sector.
I like its super strong balance sheet, dividend paying capacity, and upbeat outlook comments/order book strength. So plenty to like here, but how do we value it? That’s the tricky bit.
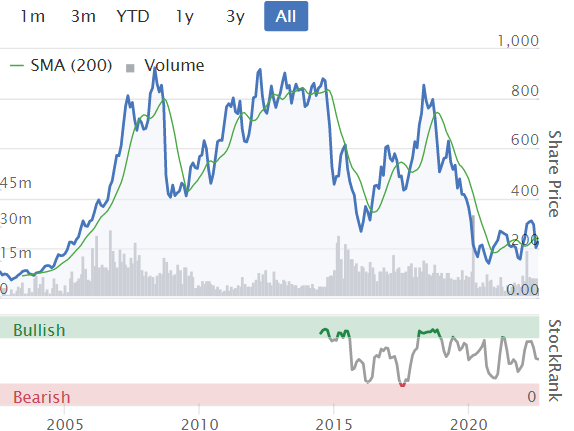
Looking at Hunting's long-term chart below, it's been volatile, but peaked at well over 3 times the current share price several times over the last 20 years. So that might indicate interesting possible upside from now? I checked back to a random RNS in 2007 to see how many shares were in issue, and it was 130m. The number now is 165m, 27% higher - not too bad at all, in 15 years. Hence theoretically, it might be possible to reach similar share prices to in the past. It looks a bit of a feast or famine, cyclical business, like so many resources sector companies. If you catch the up cycle early on, then that could be lucrative (and sell at the top of course, like everyone on Twitter claims to have done, some time later!)
.
Graham’s Section:
Argo Blockchain (LON:ARB)
Share price: 41p (pre-market)
Market cap: £196m
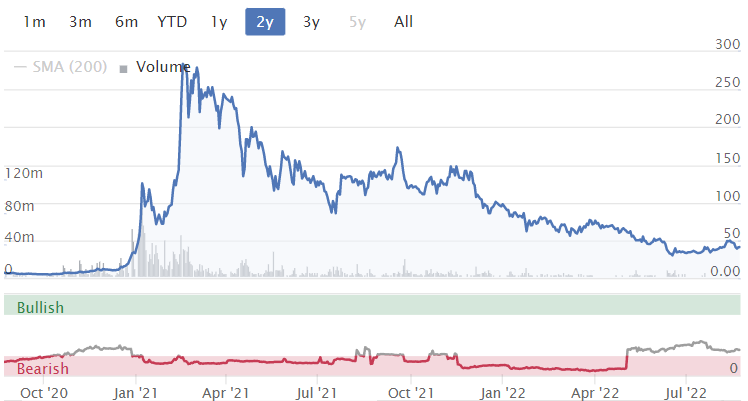
Let’s get up to speed with this bitcoin miner, whose shares have plummeted over the past 18 months:
Interim results highlights:
- 939 bitcoins mined, an increase of 6% compared to last year
- Revenues down 14% to £26.7m
- Adjusted EBITDA is down 28% but it’s a nonsense number for a mining company.
- Mining margin 71%, down from 81%
It’s built into the bitcoin system that the coins get progressively more difficult to mine (more difficult calculations are required of the computers mining them). So for the same amount of work, fewer bitcoins are produced.
When the bitcoin price was rising, it could outpace this feature of the system, so that the profitability of miners kept growing, too.
But if the bitcoin price stalls, then miners are destined to become less profitable as the mining margin reduces. If the bitcoin price actually falls, as it did in H1 2022, then it’s a double-whammy of negativity for miners.
Profitability - there is a pre-tax loss of £36.9m.
This is how the gross loss was calculated:
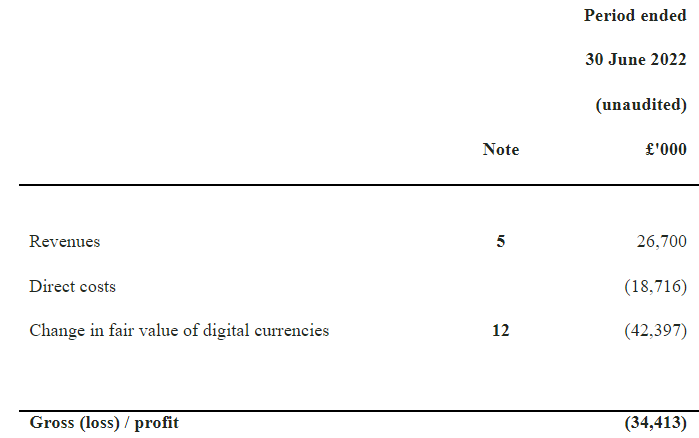
Without the £42.4m loss on digital currencies, these results would have been very different and indeed the company might have been profitable.
But Argo hoards a lot of bitcoins: it finished H1 with 1,953 of them. At today’s £18,300 price, they would be worth £35.7m. The bitcoin price has approximately halved relative to pound sterling since the end of 2021.
Operational highlights - the company continues to grow its capacity and has borrowed against its equipment and machines in order to do so.
A far safer (but slower) strategy would be to self-fund, i.e. to sell the bitcoins it mines and to buy whatever new equipment it can afford with the proceeds. Instead, it borrows to fund its growth plans.
Argo’s hashrate (computational power) is up by 38% from the end of 2021 to the end of July 2022. It plans to double computational power this year.
You would think that doubling its capacity would be an aggressive target but the company as recently as May said that it wanted to more than treble its capacity this year.
Here’s the explanation from Canada-based CEO Peter Wall on the reduced guidance for 2022. I’ve added the bold, as I think it’s a diplomatic way of saying that the company wants to slow down until the price of bitcoin recovers:
The revision to our hashrate guidance reflects our current expectations for delivery and deployment of the custom machines we are developing with ePIC Blockchain Technologies ("ePIC") that utilize the Intel® Blockscale™ ASIC chips. We have worked closely with ePIC and Intel to modify the machine design to increase total mining efficiency, which has delayed our expected deployment schedule. Further, we are preserving our optionality by reducing our overall capital spending on these machines as market conditions remain volatile.
Argo’s new facility in Texas is operational. Crypto mining has indeed migrated over the years from China to the US and specifically to Texas and other states with abundant power. So it makes sense that Argo would open its new facility there.
At the same time, I am aware of the allegations made last year by an anonymous short-seller, who said that Argo may have overpaid for the Texas land. I’ve not seen a direct refutation by the company of these allegations. (Argo issued shares worth $17.5m for land that was allegedly worth only a tiny fraction of that amount.)
Outlook
The company is trying to fix its electricity prices, which seems entirely sensible and obvious.
It has also been selling some bitcoin to help fund capex and opex, and is confident it can survive this “crypto winter”:
Argo is well positioned to weather the current downturn with its large and highly efficient mining infrastructure, runway for growth, and experienced management team, which has successfully navigated the Group through previous crypto winters.
Balance sheet
Argo’s balance sheet worries me.
The company has total assets of around £300m. Within this, £185m are data centres and mining equipment.
There are also over £80m of “mining equipment prepayments”.
So in total, almost 90% of the company’s assets are related to mining activities, with a relatively small pot of liquid assets.
That wouldn’t worry me if it was funded by equity, but there are £118m of loans and borrowings outstanding. The loans and borrowings include:
- An 8.75% bond maturing in 2026 with a face value of $25. The bond currently trades at $18.50.
- Loans secured against mining equipment with terms of 2 years to 4 years and interest rates of 8.25% to 12%. £44m of the loans are classified as “short-term loans”, i.e. potentially repayable within a year.
My view
While this share has already collapsed by around 85% from its high, I would still have doubts around the risk/reward at today’s valuation of nearly £200m.
My reasons for concern:
- The almost £200m market cap still represents a premium to balance sheet equity (when investing in miners, I’d always look for a discount to book value).
- The company’s bonds trade at a big discount to par value, and they were 8.75% bonds to begin with.
- Even secured against mining equipment, other loans are paying interest of up to 12% (I would expect that the real-life value of this equipment depreciates rapidly.)
- I’ve not seen a good explanation for the price the company paid to buy the site in Texas. Can anyone point me to such an explanation?
- The entire strategy is predicated on the price of bitcoin going up in perpetuity. As a lender or a bondholder I would expect the company to raise equity or sell its fixed assets to repay me, if necessary. But this would not work out so well for the equity holders.
To balance this, I need to try to come up with some positives.
- The company operates 100% of the mining machines it owns and has likely developed some in-house expertise.
- It launched “Argo Labs” this year, an in-house crypto investment division. This might be able to find original ways to make money by deploying the company’s crypto assets.
- Mining margin was still strongly positive in H1. If the bitcoin price stabilises, then Argo should return to profitability.
At the right price (i.e. much lower), I could consider investing in this, after its balance sheet was fixed. With the current financial strategy, at the current market cap, and with some questions unanswered, I would have to give it the bargepole treatment.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Interesting bit on price of Bitcoin on cnbc
Love it or hate Bitcoin/Ether will be around for a longtime to come to many millennials and Generation Zs believe in it and if enough of them believe they are worth X that’s what it sells for the same as anything else
Made quite a bit out of Argo Blockchain (LON:ARB) last time it spiked last year have only watched it since
Is very high risk but probably no more than Boohoo (LON:BOO) which I have never owned
https://www.cnbc.com/2022/08/2...
Re: Steve Holdsworth
I don't know if anyone here knew Steve Holdsworth (who was a longstanding PI, Mello attendee, Motley Fooler, Twitterer etc ) but if you did, you might like to know that he sadly died in the last few days. He'd only just retired and, having made big trading losses, had cleared his debts and was now a full time investor. He was also well known for posting pictures on Twitter having a 10am pint whilst commenting on stocks. Anyway, I thought some of you would like to know. Puts things in perspective...
Cheers
Francis
Very sad news.
I think he posted on here as goStevie .
Yes, sad news. He was on a lot of platforms, but always pleasant and had a good way of putting things across. Saw him on here a few days/week past. RIP. Sorely missed.
Hi fwyburd,
That's terrible news, but thanks for letting us know.
I had lunch with GoStevie in March, when he insisted on treating me to a lovely lunch at the Carlton Club, his favourite haunt. He told me he wasn't well, but didn't want to dwell on it, so I did wonder if that was his way of saying goodbye in style, which he certainly did.
Steve was so lovely, an absolute gent, never a negative word to say about anyone, he was always positive and kind, and smashing company.
We've lost someone really special. I'll be toasting him with his favourite (a pint of Carlsberg) this weekend. RIP Steve.
Regards, Paul.
Paul,
He would have appreciated those words.
R
The world will be poorer without him. I never knew him or met him but became aware of him on TMF's DWD board where he was advised by all and sundry, including the experts, to declare himself bankrupt. He point blank refused, took responsibility for them and set about repaying them.
A gentleman of honour, we need more like him.
RIP
I don't pay much attention to the numerous emails I get from ShareProphets but I do remember reading something about a Forest of Red Flags around Argo Blockchain (LON:ARB) many months ago. Personally wouldn't touch anything to do with Crypto anyway.
Agreed. Fool and his money....
And I wonder how significantly the likes of Argo are contributing to (regional) energy shortages?
There comes a time in life where responsibility kicks in and ethics come into investing.
Anglo Pacific (LON:APF) Half year results out today. Not too shabby.
Record portfolio contribution in H1 2022 of $92.8m, 303% higher than
H1 2021 ($23.0m) and 8.4% higher than the whole of FY 2021 ($85.6m)
Worryingly a name change is due soon. I remember contacting Investor's Chronicle maybe a decade ago asking why Anglo Pacific results weren't covered. Despite having a MCap of £404M it seems to fall under a lot of radars, so I hope the new name is something like, "Oy! Look at me!". It's a mining royalties company transitioning away from coal yielding 4.2%. Very good Investor Relations too.
Anglo-Eastern Plantations (LON:AEP) great H1 results today. £58m profit after tax, £208m cash, no debt. Lower H2 Palm Oil prices will make FY a story of two halves. I expect H2 profit after tax of between £15m and £20m. No additional dividend announced. DYOR.
On Chapel Down (OFEX:CDGP) (I have held for a long time)
As noted above, the market is iliquid.
I understand (from others here) that an investment manager decided / was forced to dispose of a large holding (£millions). Thus the fall in sp from may~40p -jul ~19p due to the massive overhang.
A blogger / twitterer (cockney rebel) noticed and I think he publicised this in a private newsletter. His followers got in there and so ~19p - ~30p in July
It looks like they are now trying to unload and so a fall from 30p - 25p in Aug.
Is the SP cheap or expensive? - no idea - If I was a believer in charts, I would counsel patience.
What I can say is you get 33% off if you have 2000+ shares. If you like their wine and drink about a bottle a week, you get to breakeven at 25p per share after about 3-4 years.
On Scholium (LON:SCHO)
I had to go and look at the book value :) - 9.36m, market cap 5.7m
More seriously, It reminded me of Stanley Gibbons who had a book value of > 100m (as valued by themselves), until they tried to liquidate some of it and then it wasn't.
Before this is seen as a red flag, it could be they are cautiously undervaluing that stock. You just do not know until it is too late.
It's rare books - probably properly valued by accounting standards, but the reliance on book value comes into play in a liquidation scenario when they'd probably go in a fire sale.
I was making the same point yesterday about the properties bolstering J D Wetherspoon (LON:JDW) and Lookers (LON:LOOK) balance sheets. Even with something as tangible as real estate you can never be sure the value will be there if you need it. What about Marks and Spencer (LON:MKS)? All those lovely freehold town centre properties.... when I were a nipper M&S was the focal point of every important High Street and their properties were immensely valuable (sp down another 4% today).
A general comment on relations between companies and private investors following my remark on Monday's SCVR re Smoove (LON:SMV) that "Another thing putting me off is that they do not appear to want to engage with PIs. The presentation this morning was for analysts - no IMC or PIWorld or similar".
Yesterday I watched two presentations:
Costain (LON:COST) reported interims yesterday and announced an "Analyst & Investor" Presentation. When it came to Q&A the first two questions were from a PI (including a good one on margins - Paul's concern the last time he wrote on this https://www.stockopedia.com/co... ) so Numis had to wait in the queue behind him.
Recording available https://stream.brrmedia.co.uk/...
Aferian (LON:AFRN) presented on IMC following results the previous day when Paul wrote "...Balance sheet is quite weak, but mgt think it's strong...". So when it came to Question 2 There has been criticism that you consider yourselves well capitalised when in fact a large portion of your assets are intangibles. How would you respond? I had a 'know where that came from' smile on my face.
So thumbs up to those companies that bother to include PIs in their presentations.
I was being asked by my bank to review my cash holdings and have a discussion with one of their in house fund managers. The rationale was that inflation was wiping out x% of the value of my cash per year.
I held off engaging in that discussion, because whilst I did probably have too much cash standing relatively idle, I had my pension contributions, my ISA, and my share dealing account all in equities, and it didn't seem right to tilt more cash in there as well.
A couple of months after that discussion the market promptly noes dived, and had I invested more in equities, I would have suffered significantly more than the inflation hit.
I think at this stage its hard to see what's right to do in this cycle. Searching for dividend bearing shares as an end in itself, is a case of having been there before and paid the price.
Interested in how other people are balancing their portfolio's.
I’m sitting around 60% cash and have been most of the year (down around 13% still) , facing the same dilemma as you. Someone on here pointed out that whilst inflation is high, if the thing you will be spending any cash on is equities and they are dropping consumer inflation is somewhat irrelevant. But who knows if things will keep dropping?
I don’t think there are any easy answers but I’m also interested to hear other people’s approach.
I have considered moving at least part of my portfolio into dividend shares (or funds) but that growth/accumulation habit is hard to kick.
Work out your own current rate of inflation.
The headline rate may be high but your own personal one maybe higher or lower . Do you drink, drive lots of miles, holiday in USA ( more FX) eat out regularly, have any big ticket spend looming, planning an extension ??
Its no good buying a dividend stock yielding 5% just for somewhere to park your money if it loses 10% capital is it .
Only you can answer your question , its a play off between 2%ish saving rate , your perception of inflation and where you think equities will be in 6-12 months.
R
Cash 15%, BH Macro 22%, O&G 22.7%, Commodities including (mostly) Uranium 9.1%, Gold Bullion & Royalty companies 18%, small cap (mostly) equities 13.2%. I also have some oil calls, some Uranium straddles and puts on Ark Innovation and Scottish Mortgage held in a different account.....the theory being to transfer any profits + a tax credit to my SIPP to help offset any declines in SIPP assets.
Cash gives us optionality and something like BH Macro (or Ruffer/CGI) enables you to re-balance (at least on the basis of their track record) should the proverbial hit the fan .... we must surely be coming to the end of this bear market rally? Trend following funds like BH Macro, who largely operate in the currency and derivative and interest rate swaps markets, have little correlation with equity markets. Also, these types of strategies are impossible to craft yourself within the wrapper of a SIPP or ISA.
Gold? Well you are either a believer in the Austrian school or you are not.
I find it frustrating to hold so little in vanilla equities but I don't like losing money.
There is an interview coming out on Citywire which will hopefully explain my undoubtedly eccentric portfolio.
A naive question. Why isn'r a medium duration, treasury gilt such as T30I a good inflation hedge, when it's indexed to RPI and there's talk of CPI inflation >15%?
It should be .... Personal Assets and Ruffer both think md IL gilts area good inflation hedge. The track record of these so called inflation-linked gilts and treasuries is a little more erratic though (I use gilts to mean UK and Treasuries to mean US). I also think inflation is running a good deal hotter than the CPI indicates.
There is a lot of evidence to support the view that O&G equities are the best inflation hedge .... Google Schroder's inflation hedges and you will hopefully find an excellent report. Gold is not always a good inflation hedge and not the reason I hold it.
Still fairly heavily invested in equity but I do have 20% of free assets in cash . Also a fairly significant investment in fine wine :) Will continue as is for the foreseeable future. Not too worried about the inflation hit .
I’m 60% cash, 20% long term holds in an ISA, and 20% in my spreadbetting account which I use for trading.
When inflation is high and interest rates are (relatively) low, there’s no easy option.
My approach has been to try and outpace inflation with trading returns, and my spreadbetting account is on +20% so far this year. However, that’s definitely not an approach for everyone (although for clarification I’m swing trading on the weekly timeframe with strict risk management, not day trading).
Thank you for the Macfarlane comments Paul, I'd re-read Roland's SIF buy comments (under Discussions) after seeing their results today, and decided to add to our holding. Your observations were very helpful. I am puzzled that the single analyst shown on the Stock Report has the target at 87p, surely this is out of date or incorrect?
Re Morses Club (LON:MCL) - Now a complete punt: potential liability north of £110Mn from an "estimated" take up rate of 40% of customers able to claim redress. In other words, assumption driven - a Mr Excel largely made-up figure!!.
Analysts-only briefing this morning plus huge ongoing inside info based on contact with FCA on scheme of arrangement and insight into how the ombudsman 'feels' about compliance to compliance to FCA guidelines.
In the real world, controlled, regulated F2F lending is suspended despite rising need and passed back to "unofficial" lenders who will include organised crime, unlikely to practice 'forebearance' and re-scheduling of loans. Will the "new" lenders get consistent 97% customer satisfaction scores? I doubt.
(Anyone who thinks the credit-deprived can/will stop borrowing to meet emergency needs and/or can go to a bank should talk to people in tough places more. The grubby end of finance has just got much worse. )
At the same time, largely unregulated Klarna style fin tech style online borrowing puts more and more people in trouble without any meaningful credit checks. They, the claims companies and lawyers are the winners here.
Disaster all round. (As you can tell, bitter and disillusioned £MCL shareholder)
The other comment in the update was investigating moving from self employed agents to customer reps directly employed. That worked out brilliantly for Provident! Regulator appears to have limited understanding of the customer need and type of lending required. Game on loan sharks!!!
Macfarlane (LON:MACF) - inline update (comprehensive and clearly written!)
Today’s update has several positives including passing on inflation increases in input costs. I believe this is a well run company as highlighted by others.
However, e-commerce is already starting to show signs of slowing (albeit against strong figures from last year). I wonder if their operations in Norther Europe (Germany) might be affected by the manufacturing slowdown?
The SP has been sliding for several months and now sits at the bottom of a long term rising channel. Will todays update be enough to stop it dropping out of the channel?
I like the company but wonder if now is the wrong time to invest? I hope Macfarlane (LON:MACF) gets covered today.
I haven't had time to consider myself yet but it looks like some of the increased costs at Macfarlane (LON:MACF) are non recurring and should be adjusted out. Anyone done the homework?
Patrick L,
There is a big amortisation charge within the MACF numbers that should be adjusted out (albeit is only about £0.2m above the comparatives) and there are £0.2m of pre-acquisition expenses that you may or may not adjust out, remembering they have a buy and build strategy. I didn't notice anything else.
Hi Effortles
You seem to have a very good handle on £MACF
I am struggling to reconcile the 6m interims with 12m forecast EPS. If 6m EPS = 4.3pps that leaves a lot to catch up in second half, namely 7.1pps - unless I'm being Mr Thicky!
Hi Norfolk'n'Good,
I had a good handle on Macfarlane (LON:MACF), but the change in the economic environment and the sizeable recent acquisitions and disposal is making forecasting particularly tricky at present.
However, as you can see from the table below, Macfarlane has historically had a strong bias towards H2 earnings.
This broke down in 2021, but that was due to an exceptionally strong H1 that year (due to COVID restrictions, per today's interims).
On a simplistic basis, if we assume the resumption of a more normal relationship between the two halves, then (conservatively?) if H2 was 200% of H1, we would be looking at 13.1p earnings for the 2022 FY, and thus a sizeable beat against the 11.4p forecast.
Adjust for amortisation costs, and the current valuation is, in my opinion, absurdly low.
Of course, this is very simplistic and there must be more uncertainty than normal about the H2 outcome this year. I'm working through my own projections at present and will post on this site when I have some results.
Thanks for that EC and for taking the time to reply - I appreciate it!
Macfarlane (LON:MACF) (I hold)
my thanks as well EC - particularly for the table. I knew there was H2 bias but somehow my excel sheet doesn't put it as well as your table.
I'm happy with H1. Exceeded my revenue forecast and slightly exceeded my profit forecast - which was all a little finger in the air given the number of moving parts in the period.
Accounting is always conservative. H1 particularly so, and under current conditions that's no bad thing in my view. That does mean that investors might miss whats happening under the covers. This mornings bizarre reaction being a good example. Mr Market brought me a lower price - and I couldn't resist adding a few more, just to make the point - in-line results, slightly exceeding my expectations and gross margins maintained. Seems the kind of company I ought to be buying at the moment, though shame on me that I rarely do!
cheers
Mark
Macfarlane (LON:MACF) Met with indifference so far by Mr Market. I thought it was a decent set of results, backed up with a good set of broker notes, and an increased dividend, but this recession narrative is clearly becoming imbedded, and I think many investors now just can't see past it. Too much bad news flow, and MACF would suffer from one.
Again lots of shares looking like good buys ATM, but volumes are very low.
Am back into more than 50% cash via my least favourite method of share exit 'the stop loss', but its a comfortable place, and Volex (LON:VLX) Clarkson (LON:CKN) Coats (LON:COA) Morgan Advanced Materials (LON:MGAM) although look very cheap are as yet not tempting me in.
Get this banks meeting out the way, see what they are saying, and then have a look, perhaps America may have seen peak inflation, but am not sure we in the UK are anywhere near peak as yet, and a winter of discontent weighs heavy on my mind. To that end I have hedged with a smallish FTSE 100 short, it won't cover my losses but its a stake in the ground.
MACF (I Hold)
I've found myself wondering about Pavlov's dog, and whether I'm any more intelligent, as I'm now incapable of reading any Morses Club announcement without shouting (usually in my head) "It's not a club!".
Thanks. For. That.
Chris.
Thanks MrC.
I initially read "providing credit to underserved customers" as being undeserved customers!
P.
We've all had a few of them! :-)
I don't know who Morses Club (LON:MCL) is, but when it said "providing credit to underserved customers" I thought to myself aye aye, sounds like trouble. Given that they're pursuing a Scheme of Arrangement, it's pretty clear that they are "underserved" for a reason. MCL sounds like a real bottom-feeder. It sounds like it's just as well they're going under.
Also, what really grinds my gears is that they say they have a "Continued deep commitment". It makes them sound like a bunch of social justice warriors. Companies are supposed to exist to make money, not virtue signal how compassionate they are.
I'm going to guess that the company charges usury rates in any event.