Small Cap Value Report (Thu 25 July 2024) - AVON, JDG, CVSG, CMCX Movers: INDV, NYCT, CYAN

Good morning from Paul & Graham! Many thanks to Roland for covering a couple of days off for me, with excellent service maintained I'm sure you'll agree!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
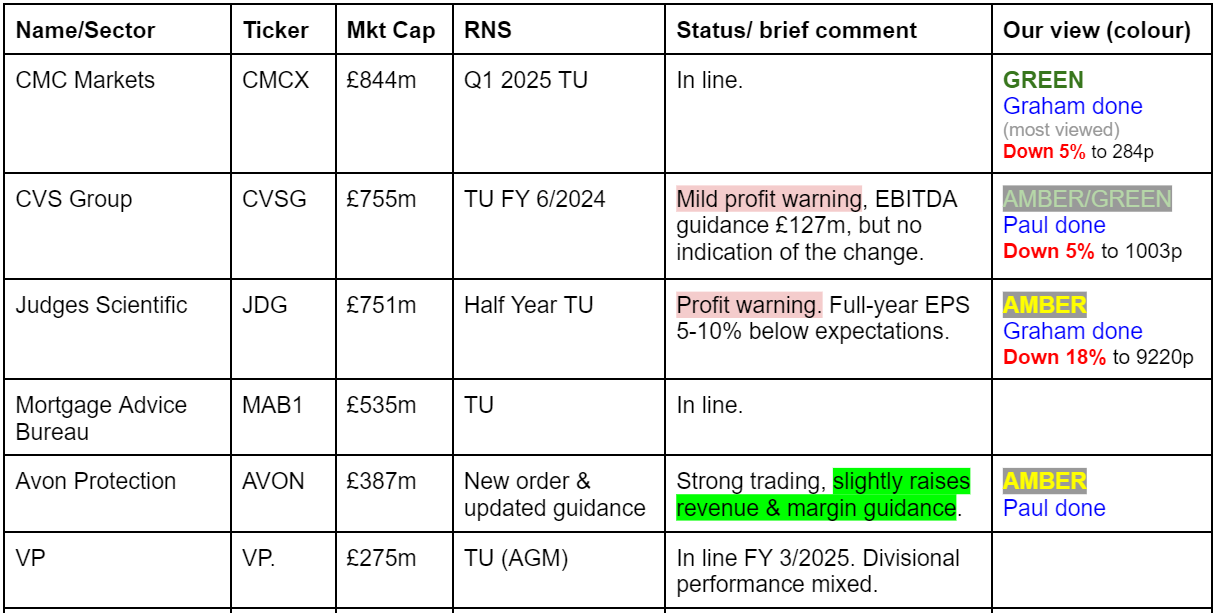
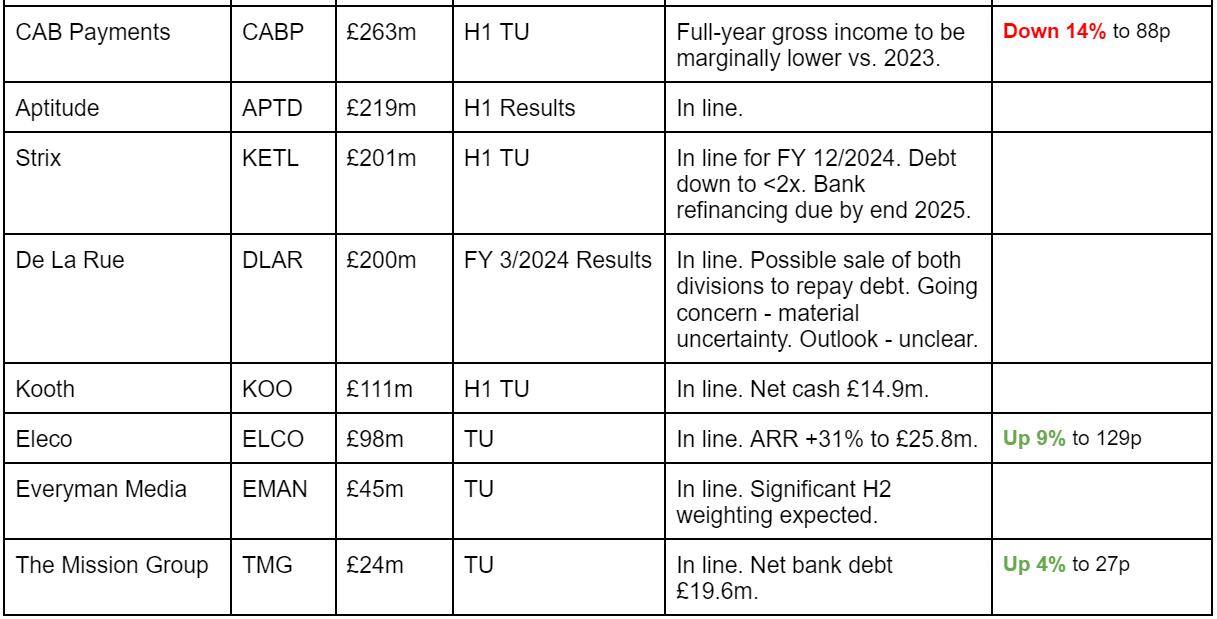
Other mid-morning movers (with news)
Novacyt SA (LON:NCYT) - up 20% to 55p (£38m) - H1 Trading Update - Paul - No View
Quite complicated, with various moving parts, so this is a special situation. Some interesting elements to today’s update, including a large cash pile remaining after settling its dispute with the UK Govt (health dept). Reckons it should get a big VAT refund on invoices which will now not be paid (makes sense to me). Lots of cost cutting since acquiring Yourgene.
Could be worth a fresh look perhaps?
Indivior (LON:INDV) - up 17% to 966p (£1.29bn) - H1 Results & $100m Share Buyback - Paul - No view
I flagged this as potentially interesting to research, after a sharp fall on 9/7/2024.
Today the market responds very positively to H1 results and a big share buyback.
It says Q2 was in line with reduced guidance. Expects settlement of litigation.
Today’s update strikes a much more positive tone, eg -
“While 2024 has proved to be a more challenging year than we had anticipated, we remain highly confident in the underlying fundamentals of our business and strategy, and that we are on a clear path to create substantial shareholder value. Reflecting our confidence, we are today announcing a new $100m share repurchase program which we intend to execute over an accelerated time frame."
I remain of the (uninformed!) view that this share looks potentially interesting. It remains highly profitable.
Cyanconnode Holdings (LON:CYAN) - down 8% to 7.6p (£22m) - FY 3/2024 Results - Paul - RED
CyanConnode Holdings plc (AIM: CYAN), a global leader in Narrowband Radio Frequency (RF) Smart Mesh Networks, announces its audited results for the year ended 31 March 2024.
This is a jam tomorrow that always seems on the cusp of great things, but never quite gets there.
Revenue growth is quite impressive, up to £18.7m in FY 3/2024.
Gross margin seems to fall almost every year, and was only 30%
It’s another thumping loss, of £(4.2)m at operating level.
Almost out of cash again.
Reckons it can raise bank loans in India. A Director has lent it £400k as an advance on a tax credit.
“Material uncertainty” in going concern note.
Receivables on balance sheet are far too high - red flag.
Paul’s opinion - very high risk, its finances are obviously on a knife-edge. Why get involved, when it could go bust, or do a highly dilutive equity raise? Bulls have to just hope that the supposed big orders come in, and even then it would probably need more equity for working capital. Too risky, why get involved when it’s a complete gamble? Occasionally one of this type of share multi-bags, but far more often they grind down to nil.
Summaries
Avon Protection (LON:AVON) - unch 1,278p (£387m) - New order & updated guidance - Paul - AMBER
Today's update is a modest increase in profit guidance of c.3-4% if I've done my sums right. That's not enough to get me interested. Shares have already more than doubled in 18 months, despite no increase in forecasts, so it's now on a rich valuation which I'm struggling to understand. Bulls must be confident there are further improvements in trading in the pipeline.
Judges Scientific (LON:JDG) - down 19% to £91.81 (£510m) - Half Year Trading Update - Graham - AMBER
Full-year EPS will miss forecasts by 5-10%. The decline in the share price today reflects that miss and also takes some of the air out of the earnings multiple. But with huge clouds hanging over the business in China/Hong Kong and declining quality metrics, I would be wary about investing at this valuation.
CVS (LON:CVSG) - down 1% to 1,040p (£766m) - FY Trading Update - Paul - AMBER/GREEN
A familiar problem here trying to interpret an unclear trading update, without access to any broker updates. I've managed to piece it together, as looking like a mild profit warning. The share price has barely budged, so it looks as if maybe the downside risks are priced-in? Various issues, including the ongoing CMA investigation into vets over-charging and lack of price transparency & competition. Who knows how that will end? I'm taking a risk here, but think there could be more upside than downside, hence AMBER/GREEN.
CMC Markets (LON:CMCX) - down 0.7% to 297.5p (£833m) - Q1 2025 Trading Update - Graham - GREEN
The range of possible outcomes for FY March 2025 remains very wide, as it’s too early to predict customer trading activity at this point in the financial year. But signs are looking positive for reduced costs and with a successful launch of the tie-up with Revolut. Still plenty to excite investors here in my view.
Paul’s Section:
Avon Protection (LON:AVON)
Unch 1,278p (£387m) - New order & updated guidance - Paul - AMBER
This has been an interesting situation. Shares have more than doubled since the Oct 2023 low c.600p, and I think it’s become quite a crowded trade, with lots of PIs getting involved, backing a turnaround. However, the impetus for the share price doubling has been a PER re-rating of the shares, not an increase in earnings forecasts - as you can see below -
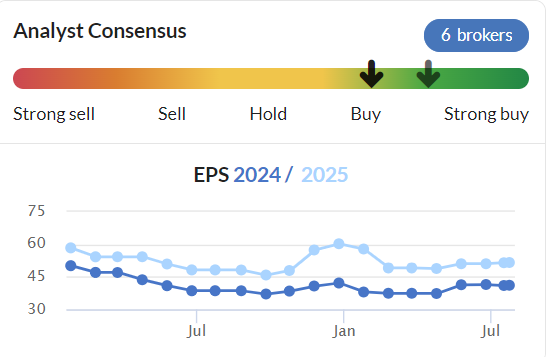
In this type of situation, investors are clearly betting on the company beating forecasts.
I can’t find anything more recent, but a note from Zeus dated 23/5/2024 is titled, “Good momentum but valuation full” at 1378p. The market price is now at 1278p. Zeus had a forecast of US$0.501 adj EPS back in May, for FY 9/2024. That was actually a reduction on the previous year’s US$0.58 EPS actual.
Note the currency! I just had to re-write this section, as I originally misread the EPS figures as being in pence, and got nonsense results out.
Today’s news is positive -
Follow-on order for $19.5m - compares with forecast revenues of $269m for FY 9/2024. Was it in the forecasts? That’s not clear.
Good visibility (I assume this means for the combat helmets part of the business) -
“This gives good order cover well into FY2026.”
“Overall trading has continued to be strong…”
Guidance is raised - thankfully giving the previous guidance too, which is crucial, yet often omitted by some companies -
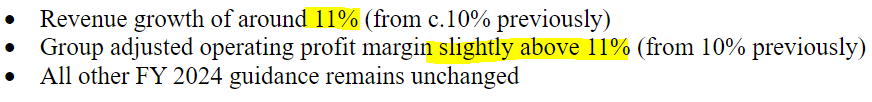
If I work out the effect, it doesn’t look that great, because Zeus’s May 2024 note already had in adj operating profit margin of 10.7%. So raising that to say 11.1% would only add $1.0m to Zeus’s existing forecast, from $30.5m to $31.5m adj operating profit. Nothing to get excited about, and barely worth RNS-ing. Maybe some other brokers had lower estimates though?
Just realised I forgot to add on the extra 1% revenue growth, but that’s only a couple of hundred £k in operating profit, so not material.
Overall then it looks like a c.3-4% increase in forecast earnings. That still leaves the PER very high.
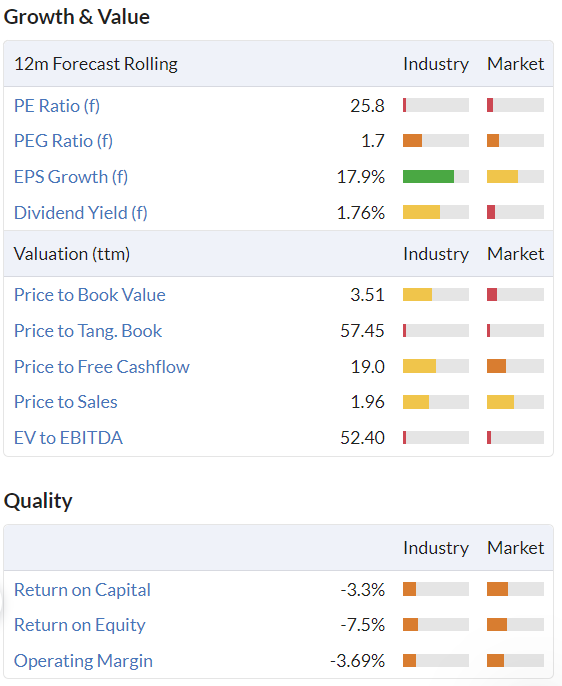
Here were last night’s valuation metrics -
Management sound upbeat -
“Jos Sclater, CEO of Avon Protection plc, said:
"Our market leading protection technologies and contract frameworks position us well in the current geopolitical environment.
We have successfully rebased the business to create a fitter, stronger organisation and it is encouraging to see the benefits of our transformation plan and continuous improvement culture drive improved financial performance.
We still have a lot of work to do but are increasingly confident that our strategic initiatives will enable us to meet our medium term targets."
Paul’s opinion - I don’t know the company in any detail, so I can only go by the forecasts, which don’t really impress me. Certainly not enough to justify paying anything like a PER of 25.8x forward earnings. Or slightly less once today’s modest upgrades go through.
Bulls must have done more research, and become comfortable with the idea that prospects are better than brokers are currently forecasting. That’s the only reason I can see for paying this much for a company with a lacklustre track record, and not madly exciting current forecasts -
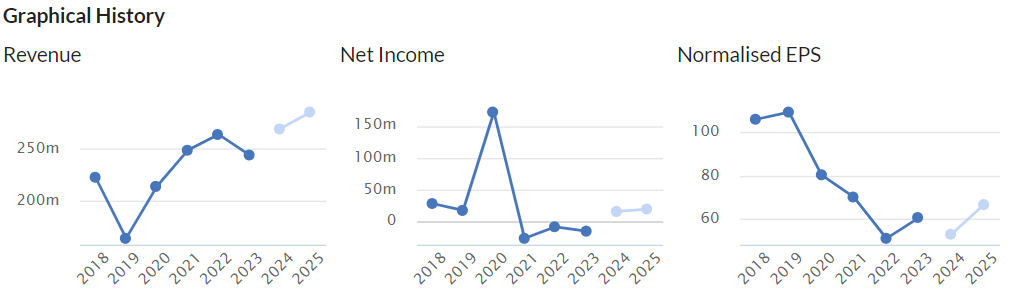
Hopefully for the bulls, performance will beat expectations - it needs to, to justify the current price, let alone provide further upside. Good luck with it! Please remember all we do here in the SCVRs is assess the facts, figures, and forecasts on any given day. We’re not trying to foretell the future, that’s your job! So if you think AVON will thrash forecasts, then that’s your bull case, let’s hope it works out for you. I don’t see attractive risk:reward here, so will sit on the fence with AMBER again.
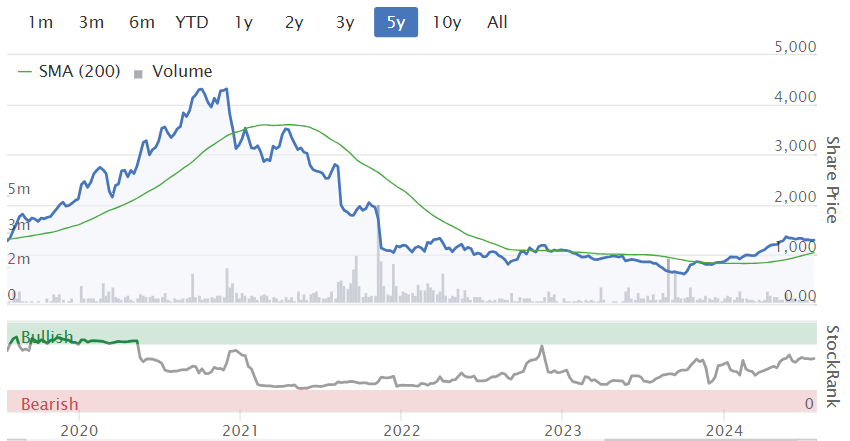
Can AVON shares get back to former glories? It's possible, since there's not been any dilution over this period -
CVS (LON:CVSG)
Down 1% to 1,040p (£766m) - FY Trading Update - Paul - AMBER/GREEN
CVS, the UK listed veterinary group and a leading provider of veterinary services is pleased to issue the following update on trading for the financial year ended 30 June 2024 ("FY24")1, other business developments and Board changes. The Group expects to announce its FY24 preliminary results on 26 September 2024.
The big story here was shares crashing on news of the Competition & Markets Authority (CMA) launching an investigation into the UK vets sector being taken over by price-gouging corporations. Anyone who’s got a pet will know how much more expensive vets have become over the years, as they’ve turned from local practices, into corporate branches.
Key points today -
LfL sales growth has slowed from 7.3% last year (LY) to 2.9% this year.
Problems? Cyber incident in April 2024, softer demand, adverse publicity (re CMA), cost of living.
These caused an estimated reduction in LfL sales from 4.1% to 2.9%, so not a disaster.
Adj EBITDA margin at “lower end” of stated 19-23% range.
Overall - this sounds like a profit warning, but since it doesn’t provide any detail of what the previous guidance was, we’re in the dark. This is a recurring problem with lots of companies. What we need is a simple before/after guidance section. Isn’t that obvious? Instead CVSG has made it really difficult for me to find out the financial impact (if any) of today’s update. That cannot be seen as good reporting.
“As such the Group expects to report FY24 Adjusted EBITDA4 of c.£127m (unaudited)”
Looking back at its H1 numbers (to 31/12/2023), adj EBITDA was £63.0m, and 19.1% of revenues.
So the latest FY 6/2024 guidance of £127m implies a very similar H2 result of £64m adj EBITDA.
Last year (FY 12/2023) showed equivalent adj EBITDA of £57.8m in H1, and £63.6m in H2.
Therefore it seems that the H2 weighting of last year hasn’t happened so much this year, implying a profit shortfall of about £5m in H2 this year, would be my guess.
That’s as far as I can go with incomplete information, so it looks as if today’s profit warning is only mild. The barely-moved share price confirms the above.
Other points -
International expansion (esp Australia) is on a big scale with £82m spent on 28 sites this year.
Leverage has increased, and was 1.5x EBITDA at 30/6/2024. Its target is under 2.0x. Plenty of liquidity, through undrawn facilities of c.£165m.
Capital allocation policy is reiterated (see RNS for the details).
Net bank debt is growing and quite hefty, although not a cause for alarm at this stage (assuming the CMS investigation doesn’t deliver a hammer blow) -
“Net bank borrowings as at 30 June 2024 were £168.0m (31 December 2023: £129.2m, 30 June 2023: £74.0m).”
CMA - will grind on for a while -
“Competition and Markets Authority
The Group, continues to support the CMA with their market investigation and has responded to a number of detailed information requests. The Group also held a "teach-in" session with the CMA on 24 June 2024 and has arranged site visits for 31 July 2024. The market investigation is expected to conclude by November 2025 with an interim update expected from the CMA in April or May 2025.”
Outlook - headwinds, but it’s powering on with its (partly) debt-fuelled expansion -
“CVS has strong long-term prospects and great people. The Group is facing short-term headwinds with the recent cyber incident and modernisation, softening demand and the ongoing process with the CMA. The fundamentals of the sector remain very strong with an increased population of pets, pet life expectancy increasing and continued advancements in the provision of clinical care.”
Balance sheet - is weak, but that probably doesn’t matter, since it’s a cash generative business.
It’s using more than all its cashflows for capex and acquisitions, with the gap being funded through increased debt.
This leaves a balance sheet increasingly laden with intangible assets. Leaving a NTAV deficit of £(55)m at 31/12/2023.
This is not necessarily a problem though, unless something really bad transpires from the CMA investigation. Just bear in mind that an adverse outcome from that regulatory review would leave a fairly highly indebted group with nothing in NTAV support.
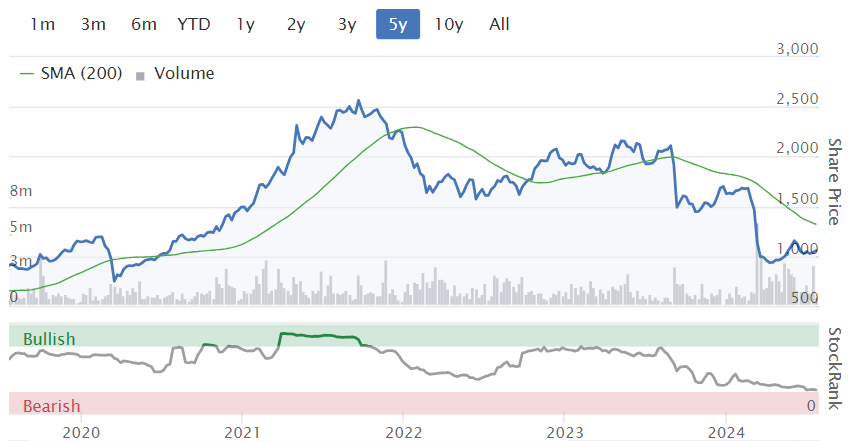
Valuation - simplifying it to EPS, the StockReport shows the latest consensus at 92.9p for FY 6/2024, which has been in a gentle downtrend. So it looks as if all the acquisitions of overseas sites are not managing to offset a decline in UK earnings. That worries me a bit, because the increased levels of debt are incurring higher finance costs.
The PER is c.11.2x which looks cheap, although adjusting for the increased debt would probably move it up to about c.13x. Possibly still cheap, but there needs to be a discount for the regulatory uncertainty from the CMA.
Note that divis are negligible, because it’s using all the cashflows to reinvest in capex, and buy up new sites. I wonder what the regulatory framework is like in Australia?
Paul’s opinion - overall, I can see that this share might have appeal in the hope of the CMA investigation delivering (as expected) a requirement for increased transparency over fees, and some other small measures. Hopefully that might not impact profits or cashflow very much, which would then open the door for CVSG shares to re-rate onto a higher multiple maybe in 2025?
A bad outcome from the CMA might require CVSG to dispose of some of its UK sites, or face onerous measures of some kind. I’d like to know the market share figures for CVSG and MediVet in the UK, which seem the dominant corporate vets groups.
On balance I’ve decided to go AMBER/GREEN here, as regulatory hurdles can usually be accommodated without disastrous consequences, and I think a forward PER of 10.6x probably gives an attractive enough discount to make this worth a slightly above average risk punt, for a 1-2 year potential recovery.
Let me know what you think! Have I taken leave of my senses, do you see more risk or reward here?
Before signing off, I should emphasise that most of us are fully aware that vets are highly trained, and do a great job, nobody is quarrelling about that. It's the corporate structures, and associated greed, that are the issue.
Graham’s Section:
Judges Scientific (LON:JDG)
Down 19% to £91.81 (£510m) - Half Year Trading Update - Graham - AMBER
I’m afraid we have a profit warning from this old favourite of ours.
If you check the archives, you’ll find that I’ve been anxious about this share in recent times. Most recently, I gave it an AMBER in March 2024. Indeed, I’ve been nervous about this valuation, and neutral on JDG stock, since it first approached £600m back in March 2023.
The latest news is that H1 trading has been “subdued against a backdrop of difficult market conditions and versus record prior year comparatives. The challenging environment has caused mixed trading across our Group.”
Key bullet points:
Order intake down 4% vs H1 2023.
Orders: China/Hong Kong down 65% (!), North America down 9%, Europe +2%, Rest of World +34%.
Revenue down 3% vs H1 2023 (only down 9% in China/Hong Kong. There is a lag between order intake and revenues).
Earnings per share is down by a fifth vs H1 2023, with cash conversion “below the levels traditional for Judges”.
Outlook includes a reminder that Geotek’s latest contract will not produce any recognisable revenue in the current year.
Geotek was acquired for £80m in 2022, being the largest ever acquisition by Judges. It is prone to generate lumpy revenues, implying that Judges’ future results could be noticeably more volatile than they were in the past..
The outlook concludes as follows:
Despite the expectation of an improved second half, the Board no longer expects the Group's performance to recover sufficiently to enable us to deliver a year-end performance in line with current market expectations*. As a result, the Board now anticipates earnings per share to be between 5 and 10% below the consensus.
The Group still maintains a healthy order book, and a solid financial position, which gives the Board confidence that the subdued performance of the first half doesn't hamper the Group's continuing strategy.
While I don’t doubt that the company has good control over its finances, I should point out that net debt as of Dec 2023 was £45m. As Judges has grown, it has grown more comfortable with using larger bank facilities.
A recent RNS from the company announced that its bank facilities were now £140m (£90m RCF + £50m accordion).
Consensus expectations were for Adj. EPS of 384.6p. The new range of possibilities is therefore 346p - 365.4p.
Graham’s view
My concerns here have been two-fold. A) A highly demanding valuation. B) Deteriorating quality, making the valuation particularly difficult to justify.
Today’s near-20% fall in the share price has taken some of the air out of the valuation, but EPS is missing forecasts by up to 10% anyway. So it’s still commanding a hefty multiple at this level, on revised earnings:
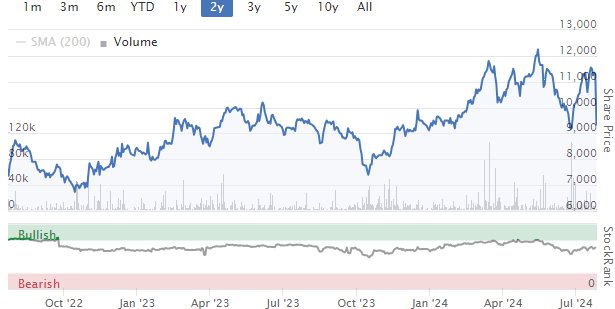
Indeed, I calculate that the PER on current-year earnings is now 25x - 26.5x. That could be a price worth paying if you are happy to look past 2024 and see Geotek’s next contracts providing a boost to revenues and profits from 2025.
But the overall Judges group is bigger than Geotek, and overall order intake is remarkably weak, particularly in China/Hong Kong.
The broker note from Zeus suggests that tough local competition is the reason for the fall-off in orders in that geography. This is a theme we’ve seen before, as China has its own unique approach to intellectual property rights. We’ve seen before that Westen companies sometimes find that their competitive advantage doesn’t last in that market. And this is not something that can typically be reversed: when the competitive advantage is gone and replaced by local Chinese businesses, it doesn’t come back.
Putting China to one side, some short-term weakness in global orders wouldn’t matter too much if Judges could still make acquisitions at attractive valuations that moved the needle. But I think the jury is still out on that (excuse the pun).
The acquisitions completed in H1 2024 were Luciol Instruments (priced at CHF 2.5m / £2.2m) and Rockwash Geodata (priced at up to £6m). These were attractive deals at single-digit earnings multiples, but surely deals of this size will struggle to make a big difference to the fortunes of a group valued at over £500m.
Therefore, I have to retain my cautious approach here and stick with a neutral stance. What Judges has achieved over the years is fabulously impressive. But with weak order intake, small acquisitions that probably can’t move the needle, and declining quality metrics, I would still have my doubts about whether the current valuation can provide an attractive entry point for investors.
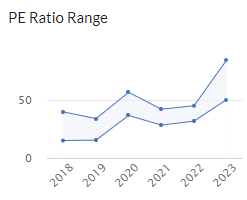
Stockopedia’s graphics illustrate how a stock that used to sometimes trade at “value” entry points, no longer does so:
CMC Markets (LON:CMCX)
Down 0.7% to 297.5p (£833m) - Q1 2025 Trading Update - Graham - GREEN
This is a simple trading update: Q1 performance (April to June) has been in line with expectations.
The new partnership with Revolut is highlighted:
The initial onboarding of Revolut clients has commenced and some clients are now live and trading. Further details will be provided at our half year results in November as the partnership picks up momentum and develops over the coming months. This exciting and important partnership reinforces CMC's position as a market leader and innovator in the B2B fintech space through technology and our API ecosystem.
Unchanged Guidance is for net operating income of £320-360m (last year: £332.8m).
Costs excluding bonuses and non-recurring charges will be c. £225m.
The corresponding costs figure last year was higher at £237.2m: one of the reasons for CMC’s enormous share price gains in 2024 has been its ability to cut costs. On that point, it says today that it “remains focused on opportunities to drive additional cost efficiencies”.
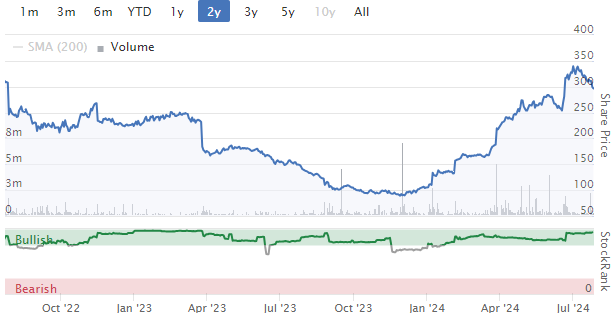
Bonuses and non-recurring charges also need to be considered, on top of the base costs figure.
Last year, bonuses (“variable remuneration”) were £18m. They were £17m the year before.
Non-recurring charges last year consisted of a £12m impairment.
CMC’s presentation of its profits is usually quite clean and I’m hoping for another reasonably clean set of numbers this year, without any excessive or unreasonable non-recurring charges. Redundancy costs are likely to appear prominently.
Graham’s view
Based on the numbers above, there remains a very wide range of possible outcomes for FY March 2025.
At the low end, perhaps we should see an operating profit this year (excluding non-recurring charges) of at least £75m. At the high end, it could be £115m+.
After taxes, the consensus figure on Stockopedia suggests that net income could be £49.3m. Clearly there should be scope to beat that if net operating income is at the higher end, but it’s too soon to tell.
It’s worth noting that interest rates are a factor as CMC earns income on client deposits and on its own cash (£35m earned in FY March 2024). That might not be a big factor in terms of FY March 2025 but for future years, the path of interest rates certainly needs to be taken into account.
Finally the tie-up with Revolut, announced in June, strikes me as something with the potential to be huge for CMC. The initial product set includes FX, Index, Commodities, Treasuries and Equity CFDs.
I am a heavy user of Revolut, although I’ve commented publicly before that I do have some risk-related concerns that, until they are resolved, would prevent me from trusting it with larger deposits. But those concerns are probably irrelevant when it comes to the partnership with CMC - from the point of view of CMC, I would say this is a very exciting opportunity to expand the usage of CMC’s trading infrastructure. Hopefully we can learn more about this partnership very soon.
On balance, I’m happy to maintain my positive stance here.
It’s true that the PER is now arguably demanding:
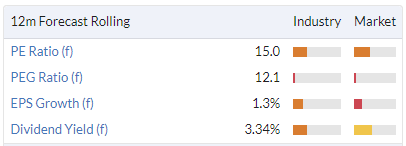
However, the company reported net assets of over £400m as of March 2024, mostly tangible. Within this figure “own funds” were £325m and straight cash was £160m. So I think there are plenty of liquid assets to help support CMC’s valuation, even over £800m.
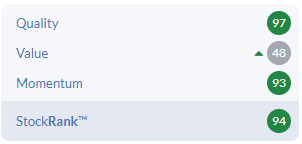
Even the algorithms don’t think that the value on offer here is all that bad. And they give a nearly perfect Quality score!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
Big thanks to Paul Hill and Paul Scott for a thoroughly enjoyable session on the Exchange today! Always well worth a watch. Thanks guys!
Thanks Gimmers! I can't believe we talked shares for 2 hours, it went by in the blink of an eye!!
Lol - one to watch at the weekend then if its a marathon :-)
Paul - you genuinely do a great job - it is the quality of the analysis that attracts a certain type of investor to the forum, which in turn produces some great quality opinions and analysis on a wide range of shares and topics that then helps us avoid traps and get a deeper insight into the retail pool that is driving liquidity (or otherwise).
Its a great symbiotic relationship and one that usually only attracts sensible investors.
But it only plays out that way because of the diligence that goes into the analysis. Without it things would disperse....... so keep it up ; great job both you and Graham
Well said David. Thanks also for your comments on Avation (LON:AVAP) today, they have encouraged me to take a look at it this weekend.
Aew UK Reit (LON:AEWU) and Hollywood Bowl (LON:BOWL)
Further to my reply to Ken Mitchell earlier today on Aew UK Reit (LON:AEWU) I bought a few more this afternoon for my own ISA, having earlier bought for my daughter's ISA. The 9% yield with the likelihood of share price appreciation should interest rates come down was too hard to resist, combined with the current wide discount to NAV
For what it is worth Simon Thompson at the IC, perhaps not everyone's cup of tea, but gets more right than wrong continues to be a fan.
The following narrative (see bold text) taken from this morning's announcement by Aew UK Reit (LON:AEWU) also piqued my interest, as I have a reasonable holding in Hollywood Bowl (LON:BOWL) . Admittedly anecdotal but nonetheless interesting.
"Having acquired Central Six Retail Park, Coventry, with circa 24% vacancy in November 2021, the property is now fully let, with the final letting to Salvation Army completed this quarter. Since acquisition, the asset's annual contracted rent has been grown by circa £478,000 per annum. This is the product of an extended period of active asset management, which has also resulted in a further 9.58% valuation increase this quarter. Other asset management initiatives in the Company's retail warehousing holdings continue to advance well, with the reletting of the former Sports Direct unit at Barnstaple progressing and exchanging on a new 25-year agreement for lease to Tenpin Limited at The Railway Centre, Dewsbury. The billing of Hollywood Bowl's turnover rent at London East leisure park is testament to the current popularity of bowling and the corresponding attractiveness of bowling operators as tenants, with bowling being the market leader for experiential leisure spend in the post-Covid era. This activity continues to highlight the significance of ongoing asset management in bolstering the Company's earnings performance."
Tracsis (LON:TRCS) has fallen suddenly today, any thoughts, please?
Avation (LON:AVAP) announce a new customer and clear strong partnership with ATR and the shares go down…….go figure…….. I reckon TNAV is close to 300p now and they trade at 127p
Avation (LON:AVAP) yes this looks one of the most obvious bargains in the UK market, although has been strangely weak for last couple of months. As you say, trading at more than 50% discount to NAV and airline leasing market now really picking up. Seems very under the radar, but wouldn't be surprised to see someone bid for this.
Hi Bouden
I seem to think they did indeed have people sniffing around but the price was too low.
Historically aircraft leasing tend to go for 1.1* TNAV though the pandemic may have changed that, but Avation (LON:AVAP) really haven’t recovered anywhere near their peers.
And AVAP will consider to start paying dividends once debt reduced-I asked the question a few months ago
Centaur (i hold now)
Got hammered yesterday and lots of big buys and sells since then in a normally illiquid share .
Results didnt look too bad and in particular their prized asset “the lawyer” seemed to be up 7%.
Still plenty of cash .
Chairman has packed in (not pushed I checked )
Rockwood on 30% are very motivated to get this unbundled and will certainly be helping get the right chairman.
My thesis is its simply a matter of time before this gets sold or carved up and thats going to be in 55p:60p region
So its sit and hold, get a 5% dividend and double your money at some point in the next 24 months .
Thats the theory though admittedly thats the same theory as past couple years .
Its also looks a decent well run company .
Hmm.....are you sure about 'results not too bad' with Centaur Media (LON:CAU) . I double-backed and looked at Edison forecasts from back in March and low and behold they have cut adjusted EBITDA by some 28% now that they have 'reinstated' post the end of the takeover talks. I don't like the way that Centaur Media always puts plenty of positive spin into results announcements and then forecasts edge back (or in this case more than edge back) as the shares drift lower. Long wait till we double our money, I fear.
Centaur
As its effectively an unbundling of assets that a buyer sees value in then to a certain extent relatively short term trading lumps arent particularly relevant .
Its not loss making , It has lots of cash , and if its a case of selling off assets these arrent going to be valued by a buyer on a short term timescale of the last 6 months figures .
You just dont buy businesses based on 6-12 months fluctuations,
Unlike the market which in my opinion puts a ridiculously onerous spotlight on “trading ahead / behind” short term updates .
Is “the lawyer” worth any less today than a week ago ?
To “mr market” its now worth. 20% less
Centaur Media (LON:CAU)
Seen worst companies double in 24 months!
But just asking since :
1. Revenues from 2019 to 2026 estimates will be lower (about £16m less) so the company in eight years has not only managed not to grow but has lost revenues.
2. FCF from 2021 (£8m) to 2026 estimates (£4m) will basically be 50% lower.
How do you come to the assumption that this makes sense to double since they will not be growing at 25% pa?
It will only double as the assets / unbundling occurs
Sum of the parts valuation as either the business or the assets are sold
Rockwood for 100% sure will drive this and are a very motivated 30% holder .
This means this is not a typical Aim share where management ate happy to tske hige salaries and no nothing .
I liked the growth in the lawyer, if the prized asset is performing well thats a big plus .
What’s the. Book value of Centaur Media (LON:CAU) ?
The problem is that they announced a potential takeover approach and the buyer walked away. That suggests that either their assets aren't as valuable as we hope or that management has put too high a price tag on the company. It certainly shouldn't be the latter because as Yiannos suggests they haven't exactly driven shareholder returns higher since 2019. I say all this as a grumpy holder myself, so I hope you are proved right in the end, planetx!
Centaur Media (LON:CAU)
There is no cash as planetx suggests as well and the whole balance sheet is full of goodwill. The cash in the balance sheet is JUST an upfront payment as there is clearly a bigger amount as deferred income liability - The NTAV for me is only close to £2m!
Illiquid and definitely not for me.
What planetx is missing here is that most of these companies he is referring to are not Harwood Capital ORIGINAL picks but just companies inherited after the acquisition of Rockwood.
BUT 70% of the shares are held so obviously not difficult to go up from here.
All the best
Wow. Thank you to Paul Hill & Paul Scott for a marathon Vox Markets interview. Many ideas and I’ve just sold Anexo (LON:ANX) as I hadn’t realised the receivables issue! Thanks for the warning.
Interesting to see that De La Rue (LON:DLAR) is potentially getting close to selling off either their Authentication or Currency division.
The fact that there were interested parties in May, and there continues to be interested parties in discussion now in Jul, solidifies in my mind that there are some credible/serious buyer.
Wondering if Spectra Systems (LON:SPSY) is one of those circling; would definitely have some strategic sense to either either. Albeit I don't think they have the firepower to do so. Nabil, the CEO of Spectra, in a recent interview did say something like "more good news to come soon" after the blockbuster contract they've announced.
There would be huge acquisition/merger efficiencies. Most of of the products/solutions are super high gross margin, and you can strip out the duplicate fixed costs.
(I hold SPSY in the Boon Fund)
With regards @CMCX and the comments on trust around revolut, this may have some relevance which was coincidently released today.
Revolut has secured a UK banking licence – with “restrictions” – more than three years after Britain’s most valuable fintech firm lodged its application with regulators.
It is a milestone for the company, though it may still be some time before it can hold its customers’ deposits.
Tentative approval from the Bank of England means Revolut is in the mobilisation stage, where it will build its banking operations before a formal launch.
Don’t post often but i’m sure it would be echoed by the silent majority by adding my thanks for the incredible effort from all three contributors , the wider stockopedia team and the informed subscribers which makes this worth every single penny of the subscription,.
From a personal experience with Revolut :
I was trying to open an account for a company and at the end I just gave up as I found the number of documents required enormous and not necessary.
For the same company I have opened an account with a reputable UK high street bank in minutes.
All the best
Wynnstay (LON:WYN) making a move today. MACD and TSI crossing over. Possibly a sign that the sellers are out for now. They did say that May June were better than the spring months. I hold.
Wynnstay
One of the “real” companies on Aim .
Not one of jam tomorrow pie in the sky home run frothy hype and hope nonsense comoanies .
Good compaby, well run, boring , but keeps doing the day job so a good anchor stock for a portfolio with good dividend and IHT cover if thats important to you .
Not going to 10 bag .
Sleep at night share.
Time will tell whether this is a buyable dip on Judges Scientific (LON:JDG) but concerns that the company is getting too large (at USD 0.8bn) to run should be put in the context of some of its competitors, who typically compound at a rate of about 10% pa:
Waters 17bn
Agilent 39bn
Thermo Fisher 220bn!!!
If nothing else, Judges would be a tasty little morsel.
Hi Paul, re CVS (LON:CVSG)
"Overall - this sounds like a profit warning, but since it doesn’t provide any detail of what the previous guidance was, we’re in the dark. This is a recurring problem with lots of companies. What we need is a simple before/after guidance section. Isn’t that obvious? Instead CVSG has made it really difficult for me to find out the financial impact (if any) of today’s update. That cannot be seen as good reporting."
IMHO, there are enough companies about that are open and honest in their financial reporting to, as a matter of policy, just totally avoid investing in companies that deliberately try to conceal their situation from investors.
As with preferring companies with genuinely strong balance sheets, I find avoiding duplicitous (maybe a slight exaggeration here) management teams helps me sleep better
Paul, I think your being brave !. I worked in the Vet sector for a few years as a consultant -on the IT side. But what I saw with suppliers also providing the software to run the practise (which meant orders went directly through the software to that supplier cutting out competition), drug mark ups that were extraordinary and consultancy fees which seemed ridiculous I would think an enquiry will find some nasty truths. I would think the pet insurance providers will be concerned as well. The small animal sector will be the main area, large animals means dealing with farmers/horse owners so profits far less !
I’m slightly baffled by all the hate directed at the pet sector. According to google the average vet makes a salary of between £40k-80k I.e. far less than many Gps, despite what I understand are 5 to 6 years of difficult training (can’t be easy getting familiar with all those animal types). Then I look at the CVS (LON:CVSG) EBIT margin (so pre any dividends or interest costs related to scale up) and it seems to have historically been in single figures, albeit slowly trending up towards 10%. I would humbly argue that’s pretty low compared to many other industries. Where is the insane corporate avarice that I see constantly being mentioned?
I have another theory, particularly as regards the UK, which is that the dominance of the NHS means that most people are very insulated from the huge costs of medicine in general. My neighbour had an endoscopy the other day, albeit having waited some months. Direct cost to him nil whereas in, say, the US it would be at least $5k+. That same individual is then surprised when the cost of treating their pet can run into the hundreds. Is that partly not because medical technology is advancing with the concomitant cost of treatment. Ditto on the drugs front. In tandem you have the increased anthropomorphism of pets owing to increased wealth, fewer children, etc, etc, and hence a willingness to spend on those treatments. Bottom line - Yes you have an element of information asymmetry (as indeed I have with my dentist, etc. yes, there is an element of local monopoly (unlikely I will drive my dog half way across the country to save a few pounds). but then again most places have several practices owned by different groups - similar to many other industries where this is sufficient to keep the participants relatively honest. All in all I would be astonished if the CMA report comes up with any serious remedies or magic bullet that will wave a wand and lower those fees. And on the bright side at least your pet isn’t waiting 6 months in a queue. I wonder how much people or their pets would prefer a ‘NPS’ funded out of general taxation…
Hi Paul
Good summary on Avon Protection (LON:AVON) and I am equally puzzled by the rich valuation. I was looking to buy in around 700-800p mark where I thought it had good long term value but kept missing the boat and was reluctant to chase.
I look at Cohort (LON:CHRT) and MS International (LON:MSI) in comparison and don’t really understand the valuation gap. MS International (LON:MSI) has something like £40m of net cash and trades on 11* PER for this year whereas Avon Protection (LON:AVON) is on 26* PER and has a load of net debt. Just feels like investors are pricing in a lot of upside and I much prefer the relative muted value of MS International (LON:MSI) - though noted it is not a pure defence play.
Avon Protection (LON:AVON) they have won quite a few new contracts this year. Orders were up around 60%. The HY results:
Adjusted2 basic earnings per share
22.3c
15.3c
59.3%
I agree with Rusty2. I hold Avon Protection (LON:AVON) and am in no rush to sell. The data on Stocko has not yet caught up with events. Although, on the face of it, Avon Protection (LON:AVON) looks expensive, they are cheap based on confirmed forward contracts. A lot of turnarounds have crappy looking balance sheets and look expensive at the bottom.
Avon Protection (LON:AVON) have a unique product favoured by armed forces, special forces, the police and response services the world-over. It is not easy to replicate, and they are the favoured supplier to the US, UK, and rest of NATO. There are substantial tailwinds for obvious reasons and new threats have emerged because of Russian belligerence including chemical warfare and underwater sabotage of gas pipelines and internet cabling. The demand forAvon Protection (LON:AVON) will only grow as the European end of NATO reconfigures its posture.
But Avon Protection (LON:AVON) have said they are basically in-line. That's for the full year - they are not "ahead" despite the orders.....well maybe 3% ahead but the EPS forecast is 50p so there is no big jump expected anytime soon based on these orders.......ie the orders are all in the forecasts already.
so they are considerably more expensive than Cohort (LON:CHRT) and MS International (LON:MSI) but with a much patchier record. Why would you own them over either of the other two that are cheaper, have a better balance sheet and are growing faster?
Don't get me wrong i like Avon Protection (LON:AVON) as a business but it is now richly rated and doesn't appear to be shooting the lights out. On a relative value basis it appears a poor choice compared to peers
Cohort (LON:CHRT) l can't see that much growth and the shares have gone up considerably as well.
You must be looking at the wrong charts then Rusty
Cohort (LON:CHRT) - (I don’t hold) alas are growing EPS consistently at 20%+ per annum, trade on a 1 year fwd PER of 19 and are net cash.
MS International (LON:MSI). (I do hold) are growing considerably greater in the short term, have a big net cash pile of £45m and trade on 11* PER
Avon Protection (LON:AVON) have a PER of 25 and net debt of some £70m
So Avon Protection (LON:AVON) falls short on growth and balance sheet and has a patchy record but trades on more than double the rating of MS International (LON:MSI) and is 20% more expensive than Cohort (LON:CHRT) that has a great track record of consistent 20%+ EPS growth
So investors have already factored in some significant future growth and yet the current update is lukewarm.
Here we must disagree Rusty2. I also hold Cohort (LON:CHRT) and the growth has been pretty consistent over the past 5 years. They have a solid balance sheet with net cash and are, on the face of it cheaper. Within my portfolio, I hold Avon Protection (LON:AVON) in my turnaround pool ... they sit alongside Marks and Spencer (LON:MKS) and Rolls-Royce Holdings (LON:RR., whereas Cohort (LON:CHRT) is in my GARP pool, alongside Warpaint London (LON:W7L, Bloomsbury Publishing (LON:BMY) Goodwin (LON:GDWN. Different strokes for different games, although both are obviously in the same sector.
PS. I know lots of folks will argue whether or not Goodwin (LON:GDWN) is a GARP share. It is: (2) Goodwin plc – breaking good - by Alex Sweet - Sweet Stocks (substack.com)
Excellent update from Aew UK Reit (LON:AEWU) today , providing more evidence that the bombed out Commercial Property sector is at last on the up.
Here’s the full update:-
https://www.stockopedia.com/sh...
NAV total return from March 31st to end of June is up 5%.
Share at 91p so about a 14% discount to that upped NAV.
Quarterly dividend maintained at 2p. It has now been at that level for 35 quarters. So yield is a useful 9%.
Note disposals at a good price too. e.g Oak Park, Droitwich:-
“Disposal of Oak Park, Droitwich, for £6.30 million, reflecting a 33% premium to the 31 March 2024 valuation.”
I’ve held Aew UK Reit (LON:AEWU) since buying at 63p in 2020. It’s arguably the best quality Trust in the UK Commercial Property REIT sector.
I hold several REITS including Supermarket Income REIT (LON:SUPR) on an 18% discount and paying 8.3% dividend, and Schroder European Real Estate Investment Trust (LON:SERE) in the Commercial Property Europe sector on a huge 40% NAV discount and 8% dividend.
Aew UK Reit (LON:AEWU)
Bought some this morning for my daughters ISA. Close to 8.5% yield, large discount, LTV 25%, borrowing fixed sub 3% until 2027. An awful lot to like, especially with interest rate reduction likely.
Aew UK Reit (LON:AEWU) really good managers in my opinion. Consistently delivered asset mgmt outperformance and paid 8%+ yields. I’ve held for a while - probably should have sold when the interest rate cycle turned and then bought back but the real fall from the 120p mark was on Truss’s work experience which was too rapid. But I like them and relatively happy with an 8%+ yield that I can recycle each year.
Aew UK Reit (LON:AEWU) agree looks a good update - I follow the REITs quite closely and for my money AEWU is the best quality name in the sector. They sold a property at a big premium and reported a large increase in EPS. Suspect it could trade at a premium again once sentiment improves, and in the meantime you're getting a c9% yield.
Hercules Site Services (LON:HERC) - Q3 update highlights continuing momentum - link to new report here: https://www.equitydevelopment....
Hercules’ Q3 update follows upbeat interim results in June and gives us further confidence in our forecasts for the current year (we make no changes to estimates). Further contract successes have been achieved across the Group and Hercules looks to be well positioned to benefit from the new government’s infrastructure and housebuilding commitments over the coming years.
Labour supply, the Group’s largest division, delivered strong growth in H1 (revenue +25%), and has reported continued success during Q3. The Civils Projects division continues to win work for its major water clients, notably Thames Water and Anglian Water, with £7.9m of contracts awarded to the business across the Q2 and Q3 periods - this is an attractive sector, given the urgent need for investment in this area, where Hercules has a strong market position. The Hercules Construction Academy in Nuneaton (launched in January ’24) has made a positive impact with the local community since launch and has also been appointed as an approved training provider.
Today’s update references the new government’s housing and infrastructure plans, which should benefit Hercules as a leading supplier of labour for the UK infrastructure and construction sectors. We also note a recent uptick in construction sector sentiment (PMI reading over 50 for past four months), which may suggest an improving outlook for this important market.
We reiterate our 55p Fair Value / share estimate and note the attraction of a 4.7% dividend yield, unusually high for a smaller company with Hercules’ growth profile.
Re Yu (LON:YU.)
I've followed this share over the last month since seeing Gervais Williams talk out it but the SP of Yu (LON:YU.) Has fallen off a cliff this week. Apart from the reasonable trading does anybody know what's going on
Paul Scott reviewed the RNS in his usual dispassionate way. GW is a salesman?
Yu (LON:YU.) Only now down 1% today. Good Energy (LON:GOOD) has also fallen back this week. Only thing l can find is fears about Labour's GB Energy.
Yu (LON:YU.)
There is a large ROC liability that will take out half of the cash!
Also the revenues are declining now (prices stabilised) as they have taken advantage in the past of the big fluctuations of energy prices.
All the best
i think it more a read across from Centrica (LON:CNA) results today which are lacklustre given the easing in energy prices.
I'm reading Siegel's book "The Future for Investors." I think Buffett didn't like the book, but I am finding it quite interesting so far. Actually, I'm finding the history of the stock market and tech to be pretty interesting. There's not so much brainwork involved, and there are some pretty interesting turns of events. Here is an extract from Chapter 1:
"The more than 900 new firms that have added to the [S&P500] index since it was formulate in 1957 have, on average, underperformed the original 500 firms in the index. Contintually replenishing the index with new, fast-growing firms wile removing the older, slower growing firms has actually lowered the returns to investor who like their returns to the S&P 500 Index".
He also ran a comparison between IBM and Standard Oil of NJ from 1950-2003. Revenues per share grew by 12.9% for IBM, divs per share by 9.19%, and EPS by 10.94%. The comparable figures from Standard were 8.04%, 7.11% and 7.47% respectively.
Which one do you think did better? Well, it turns out that Standard did marginally better in terms of total return annualised : 14.42% as opposed to 13.83% for IBM. How so? IBM had an average PE of 26.76, compared with Standard's 12.97, so quite a valuation gap. The dividend yield of IBM was 2.18%, whilst for Standard is was 5.19%. That dividend yield difference turned out to be important, as it affected the total return, and tipped the balance in Standard's favour.
Pretty interesting stuff.
Pretty interesting stuff.
indeedy
If you are saying old skool stocks have outperfoamed new stocks that have turned up thats very interesting. Not sure exactly how you do a fair comparison not to get biased results here albeit i will presume its not some satistical fluke - ap;olgies if i am mising the point here - i may be.
Perhaps its common sense that stocks that have been around for decades have proved themselves to perhaps be resiliant - whereas new up and coming stuff - maybe they have just been lucky enough to be in the right place at right time to get onto teh list - if they dont have experienced old hands and good insight with regard to dealing with leaner times and the like perhaps we should expect them to be more flash in the pans than those that have come and gone.
Perosanlly if asked I would have expected the extreme outperfomance of the googles and microsoft would result in better results for the newbies - being honest i dont know how the "index" is exactlyu calculated so its a little bit outside my ability to analyse - deffo intersting though IF old skol has ben news skool despite the new biggies dominating so much.
Would be intesrting for similat uk comaparison with ftse - i have possiblyt soemwhat stupidly preumed ftse 100 may have big element of companies that have had their day - so tfse 100 has never really interested me as an index - perhaps it may be more resilient tan i give it credit for ?
Siegel's book was published in 2005.
The Voya Corporate Leaders Trust is an interesting one to watch. It was launched in 1935, so all results are actual, not subject to backtest errors. It is completely passive and only makes trades where forced by corporate actions.
Its largest holdings are here: https://money.usnews.com/funds... The portfolio looks rather unbalanced, although I guess 90 years of existence with (near) zero trading will do that. It's also interesting to note that Berkshire Hathaway is in there. It wasn't in the original portfolio in 1935, but was given in exchange for its holding in Burlington North Santa Fe railroad, if memory serves.
Pundits have noted that the fund has outperformed the indices throughout its existence, although that undoubtedly excludes the last decade. Performance over the last decade has lagged the indices: https://money.usnews.com/funds...
You never know, it could actually make up lost ground. The S&P could fall substantially due to the Mag 7 coming down to more reasonable valuations, and Berkshire could continue motoring on like it always does. The last 10 years has been exceptional for growth stocks, so is likely to be unrepresentative, I think, especially given valuations now as opposed to valuations then.
Most people would probably think that the Voya fund would be kaput by now, ravaged by bankruptcies. But nope, it still keeps on keeping on.
I can confirm that Jeremy Siegel's book "The Future for Investors" is an excellent read. It has a good section on strategies and more importantly has lessons for new investors. IPOs are risky and are often overvalued.
His first book "Stocks for the Long Run" published in 2002 is also a stock market classic. Advocates the importance of diversification.
I rated each book 5 out of 5.
In the investment world its ‘better to be lucky than smart’.
Fortunately in this case – since highlighting premature baby medical device firm Inspiration Healthcare (LON:IHC) as a possible turnaround idea at Mello on Monday – I’ve been the former.
Indeed today IHC announced that it had signed a much delayed $4.3m Middle Eastern contract for SLE6000 neonatal ventilators, First Breath Humidification and associated accessories.
So what does this mean?
Well together with the £3m top-up placing at 14p/share – this deal for me is a major step forward.
In turn taking the business out of intensive care and back onto the hospital wards in order to further progress its turnaround plan under industry veteran & Exec chairman Roy Davis (ex Medica & Optos).
Next steps are to obtain a Bank guaranteed ‘letter of credit’ for this export order, ship the products sometime over next 6 months and hopefully agree a longer term relationship with the customer.
Sure IHC is not totally out the woods. Albeit the $4.3m of cash (once received) should bolster the balance sheet (ie reduce inventory) and allow the Board breathing space in terms of reducing gearing levels (Est proforma net debt of £7m).
Wrt the numbers house broker Panmure Liberum have a 40p/share Price Target – based on Jan FY’25 turnover, adjusted EBITDA and EPS of £40.9m, £2.0m and -0.9p/share. Climbing to £50m, £6.8m and 3.5p respectively by Jan FY’27 - which putting the stock on a modest 12x EV/EBITDA, would equate a theoretical intrinsic worth of 90p/share, assuming the turnaround is successful of course.
That said, IHC remains high risk & certainly not for the feint hearted.
Disclosure: I own shares in Inspiration Healthcare (LON:IHC)
Yes you were lucky this week Paul, but not so last year when you flagged Inspiration Healthcare (LON:IHC) on Mello June 2023 when the share price was c56p.
Certainly agree its not for the feint hearted, but with the share price at these levels and this contract it does look promising.
Who is the customer for this $4.3m order in the Middle East for Inspiration Healthcare (LON:IHC) ?
They really messed IHC around last year with delays to contract signing. This must be the case as IHC started producing all the order I think (hence why they had cash crunch issue?).
Will IHC actually get any of the $4.3m?
Pennant International (LON:PEN) (I hold)
Trading statement today shows it is well positioned to benefit from increased defence spending:
Software development completed by the end of H2
Looking to land several 'material contracts' in H2
Board strengthened
Rockwood have recently bought over 10%
£10m mkt cap with minimal debt
On Pennant International (LON:PEN) the TU cites a £300k reduction in net debt without mentioning the much larger raise that occurred in the period.
And they continue to focus on EBITDA and EBITA without acknowledging that the development costs need to be accounted for somewhere (either expensing the cash cost or charging the amortisation) as they can’t function as a software company without it.
CARD Factory (LON:CARD) have issued 750,000 new shares & I have sold at previous highs.
The new shares are for a Save As You Earn employee scheme, nothing to be seen here?
i sold all mine yesterday as was trading the sideways range
Announcing your trades here just doesn't add value. Can we please try to avoid this type of clutter, it seems to be creeping back in lately. Thanks.
...and also incessantly asking why this or that share price has moved on a day, gets on our collective wicks! DYOR and then if you sense a reason for the move, post it, rather than chasing noise.
Yes tricky one this GTrader... Wise (LON:WISE) absolutely fell out of bed at lunchtime, but I couldn't find the reason ... potentially a fat finger ?
£ 7.40 down to £ 5.58, now back to £7.00, for a £ 7 billion market cap !
I know that we all have price alerts set, but when you get such a rapid move down ( and recovery), sometimes it's useful to be alerted ... it may not be a share that you had an alert on and having it brought to our attention can provide opportunities ...
CMC Markets (LON:CMCX) news of tie up with Revolut being a competitive threat potentially?
Tech stock of which I do follow, hold and was alerted to, potentailly caught in the US AI/Tech pullback. Mid day movers (pre US open, open at UK 2:30pm ) are ofter US linked. No News.
Telios out and a new Australian Billionaire buying in cheap as chips on stocko. If interims good 1.12 will look very cheap. Card looking to go global this may be the open door FY 27 revenue forecast £650 m
IG group (LON:IGG) thoughts?
I'm struggling to work out what product velocity and client centricity are..
PV is an indicator of product development and how quickly ideas are converted to products in the market. CC is all about how closely alligned the products/services are to meeting the end client need. Concepts are usually close but then the accountants/lawyers/IT/others cause CC drift. Clients wanted apples, but we couldn't afford apples, we couldn't contract apples (to mitigate bad apple risk), we couldn't render a red apple on the screen, so we sold bananas, still a fruit.
Many thanks GTrader ! Not just marketing bsspeak. I will reread with fresh interest.
Headlines themselves don't read that great but you have a new CEO that investors like esp as he did a great job a Betfair.... IG group (LON:IGG) is a cheap stock rating wise and the outlook is in line with Co. compiled guidance. This is 24 86 ... 25 102 and 2026... 110. So you have a 10% grower below 10x... even if this is supported by today's small buyback. Adjusted EPS is slightly ahead and reported slightly behind today...mainly Tasty acquisition intangibles. Either way... given the shares have done pretty well, running with financials, today's numbers look fine but no better than that .... I half expected the shares to be down but encouraging that they haven't fallen.
Has the shine finally come off Judges Scientific (LON:JDG). They did warn on softening trade in the last update, but the share price recovered pretty quickly. I don't think it will happen this time, until they update to say growth has returned
Has the shine finally come off Judges Scientific (LON:JDG).
There’s a major slump in demand for instruments, particularly in China, affecting all global suppliers. It’s not idiosyncratic. I would buy this dip if I hadn’t already added at this level previously.
Thanks, any reason why? Will it recover?
Will it recover?
No one knows what share prices will do next. I just think like a business owner and look at the quality of management, the company’s earned advantages and the niches in which it operates. If those make me feel all warm inside and the price is acceptable - relative to its trading history and valuation of competitors - then I buy (subject to the availability of funds, as I’m almost always fully invested).
Like Judges Scientific (LON:JDG), SDI (LON:SDI) has seen volatility in its end markets over the last few years, though with different timing. But a lot of commentators had their claws out when SDI reported low single digit organic growth, comparing it unfavourably with JDG. The reality is that end market demand is not smooth for either of them.
Revolut has secured a UK banking licence. 45m customers globally with 9m in the UK.
CMC Markets (LON:CMCX) are partnering with Revolut for clients to access trading services via their pipes.
I don't mean to be a party pooper, but could this not mean that millions of folks simply make micro investments. Someone in our office just bought £1.00 worth of a company called Chess - this seems to be what a lot of young people seem to do these day. I hold CMC BTW.
Jim
Interested to see how CVS (LON:CVSG) opens. I picked up clear signs of stress in the TU. it seems Paul felt the same. At some point, this could be a great buy, if/when the CMA finds that, actually, operating on animals is every bit as complicated as performing surgery on humans. The lower this goes, if at all, the bigger the opportunity, though I would not be buying today, no matter the open.
I acknowledge that animal owners see this one through a different lens. But I know several vets and veterinary corporate executives and all think the inquiry will achieve little once the CMA better understands the high cost of providing care. Of course, they could be biased in their view.
The 'reaffirms strategy' of "Investment in overseas acquisition of >£50m per annum" seems at odds with "Strategics disposals : Netherlands and Republic of Ireland".
The Australian expansion seems to be going apace, but I ask myself - what are the particular challenges in the Netherlands and Republic of Ireland ? (sub-scale just means that they haven't acquired enough practices). I dont see Dutch or Irish pet owners being less caring .. is it regulatory ?
It could well be that CVS (LON:CVSG) is shying away from the regulation-happy EU geography
It could well be that CVS (LON:CVSG) is shying away from the regulation-happy EU geography
There was an announcement earlier this explaining the disposal of the Irish and Dutch subsidiaries. Primarily they were subscale and Australia is the focus due to similarities with UK market.
https://www.stockopedia.com/sh...
CVS is likely to be an interesting opportunity at some point but we're over a year from any CMA report so it's hard to see the share price doing much for the next year.
timarr
What a great summary, this really helps with which announcements to look at with a busy morning!
"What a great summary, this really helps with which announcements to look at with a busy morning!"
Thanks Nanotrader09! It's excellent isn't it, even if I say so myself!
I found the early summaries so useful this week, as a reader not a writer, that we're definitely going to focus on doing this every day - with snapshots on almost everything by (ideally) before 8am. In a way we're duplicating what MrC already does, but in a different format. Then we can focus on doing longer sections on the most interesting, and most viewed (by subscribers) items.
I think we're getting there, gradually experimenting & tweaking the format here!
Thanks for the feedback,
Paul.
I really also love the SCVR summary of announcements. Well done on the innovation . I am also find very, very useful Mr C’s morning comment (on the days he produces it.). I think there is more than a formatting difference between the two summaries. Mr C’s comments on stocks which have lower market caps (and lower quality) than SCVR would usually cover - and for me personally that is very useful. [and that is not mentioning MrC’s bone-dry humour].
VP (LON:VP.) - Trading in-line and delivering strategic progress - link to new research note: https://www.equitydevelopment....
Today’s AGM update confirms that Vp continues to perform well, reiterating full year expectations despite challenges in certain markets (notably construction). Meanwhile, the new management team is progressing the refreshed strategic priorities set out in June.
Broad market trends are consistent with those reported in recent periods. Infrastructure remains supportive, with good momentum and strong demand in transmission, water and civil engineering, although rail has seen a slower start to the year at the beginning of Control Period 7 (UK’s regulated five-year rail programme). The energy market is positive in the UK and internationally, whilst construction remains mixed (non-residential challenging, housebuilding subdued).
The new management team remains focused on the strategic priorities set out at June’s full year results: cross divisional collaboration, simplifying the Group’s operating model, and developing the digital roadmap.
Vp has an excellent track record of earnings and dividend growth over the long term, underpinned by the specialist focus of its activities and the diversity of its services and end markets. In our view, this track record warrants a premium rating.
We therefore consider the current valuation (a P/E of 9x and a 25% discount to peers) an anomaly and an attractive entry point for this high-quality business. We make no changes to our forecasts and maintain our 1,110p Fair Value estimate.
Strix (LON:KETL) - Early operational recovery and net debt cut - link to new research note: https://www.equitydevelopment....
We are encouraged by the H1 trading update. The highlight was the news that the decline in indebtedness/key covenant ratio has triggered a lower interest rate on outstanding debt. The update stated that the net debt/EBITDA ratio had fallen comfortably below the 2x level. We envisage this falling to modestly below 1.7x by the year end and achieving the Group’s target of 1.5x during FY25.
Good progress was seen within Kettle Controls and Billi during the period. Shipments of kettle controls are ahead yoy, led by improvements in the regulated and less-regulated markets. The launch of a new range of low cost controls into the less regulated and Chinese markets during H2 should help Strix to further improve its market share. We note that UK housing transactions improved yoy from April, a key determinant in the replacement of small domestic appliances.
Billi should build on the positive progress witnessed during H1 as new products are launched and its expansion into Europe via sales and service partners. As such, we anticipate an acceleration in growth levels, commensurate with the double-digit uplift witnessed in previous years within Premier Filtration Systems.
With no change to financial estimates, as per guidance, we retain our fair value/share of 167p, suggesting that the shares remain materially undervalued.
Morning everyone
Just as a reminder, I'm chuffed to bits again to be interviewing expert smallcaps investor, analyst and commentator Paul Scott today at 2pm - live here on Youtube.
If you'd like to ask him any questions live via the chatbox, then I'll be delighted to read them out.
Should be great fun & fascinating as always.
Is he back due to "popular demand" again :)
Centamin (LON:CEY) update looks good. Doubling of free cash flow. New site looking promising. I hold.
Centamin (LON:CEY) Small increase in divi too. Yet the share price has fallen 7%. Probably due to fall in price of gold over the last few days.
In line from CMC Markets (LON:CMCX) . I don't see how stocko have a forecast of 19p with the guidance they give. I think it should be around 25p so clearly forecasts are very conservative or wrong or I'm wrong! Has anyone seen the any broker notes to explain why eps is flat on last year?
Catalyst Media (LON:CMX)
companies like this (and specifically this copmpany too) can have wild fluctuations in their fortunes - often without much real advance notice that fortunes will change. IMHO its very clear they are in sweetspot right now - i.e. expectations are for eps to be twice as high as perhaps 7-8 month ago (where there was continual downgrades over prior 6 months) . They wont always be in the sweetspot and to presume the sweetspot will continue if you are projecting better results than them is kinda saying you know better than them.
Note i am not saying the sweetspot wont continue and it may be that things can get even better - good news if for example they now earn from revolut customers where they didnt previously thats got to be a great client base if thats come along recently. Note the curent sweetspot ref uptredn in numbers still leaves them well short of prior years boom times - unless company is predicting return to the golden days though i would ignore somewhat prior glories.
Hopefully this company are perhaps being over cautious - i have always though IGG have been very cautious ref forecasts with plus perhaps being more "thats what we expect" - not sure what went wrong 12 monthns ago for 6-9 months in that regard.
So if the company are projecting what looks like abnormally low profits at this stage in year personally i would probably not preume they are wrong even if i may privately hope they are - after all they know more than us. Hopefully its caution but we all know profits can vanish in short shrift so if they are not expecting better stuff i would go with their wisdom.
Personally i sold out a few months back after the shareprice had had a great run - they still seem to be delivering so perhaps my caution selling here wasott the current news deffo seems to justify the current price unless we get collapse in profits again - perhaps though the expectation from some (you?) of continual outperformance was perhaps a little too much to expect without any pause for breath.
Note sure if there were any brokers left with perhaps more conservative expectations than other perhaps there room for an upgrade or two from brokers who may have lower expectations (not sure how many brokers they have?)
15 days in, and I'm already getting sick of the term 'rotation' ..