Small Cap Value Report (Thu 25 May 2023) - HEAD, SUS, LSL, CHRT, BOOT

Good morning from Paul and Graham!
Charity challenge - Our friend Damian Cannon, who many investors will know as the presenter of the StockSlam evenings, and all round lovely chap, is doing a truly remarkable challenge for a very worthwhile charity. He's going to run up to the top of a city skyscraper, then cross to the gherkin on a zip wire! I feel bilious even thinking about it. Anyway, if you can bung his charity, Tommy's, which helps research and support re miscarriages, a few quid, I know he'd be very grateful. Link here to his donating page.
I thoroughly enjoyed Mello Chiswick, and was one of the last to leave when they closed the bar at nearly midnight. It was terrific to meet up with lots of investor friends, and meet new ones, many/most being Stockopedia subscribers. What struck me is how everyone has their own distinctive approach, and many of the people I spoke to are obviously very shrewd indeed. So overall I had some fascinating chats with some lovely people! I do hope physical investor events continue, as it would be such a shame to lose everything to online.
Talking of which, Mello has an online only third day today, starting at 1pm, with some very interesting speakers that I'm looking forward to hearing from. I find there's always at least one key point from almost every investor talk that gives me an insight, so I lap up these type of things, and podcasts.
I did my quarterly catch-up on Monday with Paul Hill, which you might find of interest. I think 1 (Watkin Jones), maybe 2 (Portmeirion?) of the companies mentioned issued profit warnings the next day, which must be a new record! Very difficult markets at the moment, for sure.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections
Headlam (LON:HEAD) - down 10% to 236p (£181m) - AGM TU (profit warning?) - Paul - AMBER
A frustratingly vague update, that sounds like it might be a profit warning. Shares look cheap now, taking a medium-term view, but weak consumer demand sounds like it's hurting margins in the short term. I'm also worried about possible damage from growing competitor Likewise (LON:LIKE)
S&U (LON:SUS) - £25.23 (-1%) (£306m) - AGM TU - Graham - GREEN
There’s no explicit reference to expectations in today’s update and nothing new on Research Tree yet. However, collections in car finance are ahead of budget and management promises steady lending growth over next two years. I remain a fan of this company.
Quick comments
LSL Property Services (LON:LSL)
Down 3% to 270p (£281m) - AGM TU - Paul - AMBER
Significant progress made in restructuring. “Very challenging market conditions”. Recently announced to convert its estate agents offices into franchises, with 143 out of 183 branches done, remainder to follow soon. Franchising - simpler to manage, and higher margins.
Outlook - “some early signs of improved trading”, and expecting an H2 weighting in 2023. Overall, confirms in line with (considerably reduced) expectations for 2023 still.
Paul’s opinion - a quick skim of the StockReport doesn’t show anything of appeal to me, in terms of value or growth, so why get involved?
Cohort (LON:CHRT)
Unch at 503p (£209m) - FY 4/2023 TU - Paul - AMBER
Describes itself vaguely as “the independent technology group”. It is actually a group of 6 companies focused mainly on the military sector.
Long-term performance was excellent, being a multibagger between 2011-2020, although shares have been drifting gently down since.
Today’s update says trading for FY 4/2023 has been “slightly ahead of expectations…”
Net funds of £15m. Order intake up. Big closing order book of £325m, is well over 2 years’ revenue, giving good visibility: 84% of FY 4/2024 revenues already secured.
Outlook - it mentions that war in Ukraine, and Taiwan tensions, is driving higher defence spending, and higher demand for CHRT. Confirms in line with expectations for FY 4/2024.
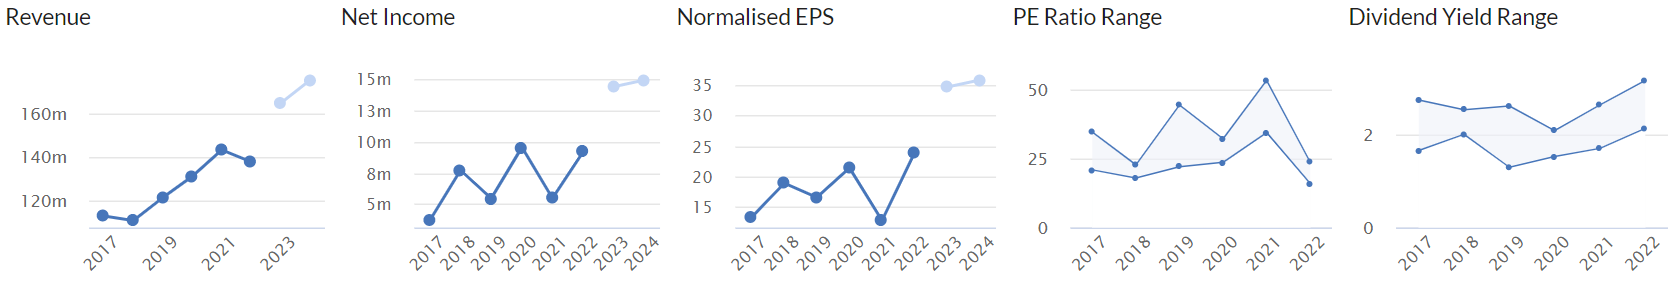
Paul’s opinion - Cohort looks quite interesting.Over the last 6 years, this share has typically commanded a PER in the high teens or above. It’s now only priced at 14x FY 4/2024 forecasts (confirmed today), which looks attractive value compared with previously. The financial track record below looks attractive, particularly as the lighter (forecast) blobs have been confirmed today. Overall, this looks a nice quality business, at a reasonable price, albeit with some contract lumpiness risk.
.
Henry Boot (LON:BOOT)
Up 2% to 239p (£320m) - AGM TU - Paul - GREEN
An interesting land development, and construction group. Its detailed AGM update today is worth a look, and surprisingly upbeat. A few snippets -
- Good start to 2023, trading in line with exps (although these have been lowered).
- Housebuilders are buying land again, selectively.
- House buyers returning to the market.
- Planning permission delays ongoing - frustrating but also supports value of sites with PP.
- BuildToRent sector is seeing strong demand, and investors looking to fund schemes again.
Paul’s opinion - I don’t know this company very well, but it looks interesting, with a nice mix of activities. Stockopedia shows it’s trading at a significant discount to NTAV. Other housebuilders have bounced a lot, whereas this hasn’t. So there might be an opportunity here for subscribers to research in more detail yourselves? Although the latest news this week on inflation & interest rates might dampen the sector perhaps? On my initial review, I see this favourably, so it's a thumbs up from me, GREEN.
Paul’s Section:
Headlam (LON:HEAD)
Down 10% to 236p (at 08:28)
Market cap £181m
Headlam (LSE: HEAD), the UK's leading floorcoverings distributor, is releasing the following trading update for the first four months of the year ahead of its Annual General Meeting being held later today.
Company’s headline -
Revenue growth despite suppressed residential volumes
This is a frustrating, and I think badly constructed trading update. Mainly because it’s too vague, and doesn’t say if the company is trading in line (or below, or above) market expectations. It really needs to be compulsory for companies to clearly state this. So much confusion is caused when companies don’t make it clear how they are trading vs market expectations, which is the whole point of trading updates!
By missing out that key information, investors tend to just assume the worst, and that a profit warning is being slipped out on the quiet, often via broker updates. As you can see, brokers have already cut forecasts considerably -
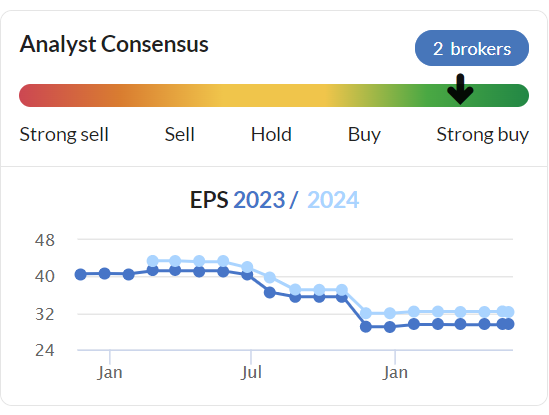
Remember that the graph above is as of close of play last night, so it won’t yet reflect the likely downgrades that today’s vague update is likely to trigger.
Headlam doesn’t get any broker notes out to private investors through Research Tree, because it uses brokers who restrict their output to paying clients (Peel Hunt & Panmure Gordon). Panmures used to put out some notes on RT, but seem to have stopped unfortunately.
So unfortunately we’ll only have the share price today to indicate to us how much the brokers (who have privileged access to the company) have privately downgraded their estimates by. What an unsatisfactory situation. The regulators need to look at this I think, as it’s obviously unfair to have brokers privately reducing forecasts, but only informing a select few investors no doubt after having been given a steer by the company privately. As a CEO once told me, "Broker forecasts are the company's forecasts!" Everyone just pretends that they're independently set.
Summarising the detail of the trading update (profit warning?) today -
(this is for 4 months to end April 2023)
Revenue up 3.4% vs 2022.
Claims market share gains (based on independent research).
Gross margin reduced (no figures provided).
Residential market weak, offset by stronger commercial, trade counters, & larger clients.
Mitigating actions taken, eg price rises, cost cutting, and pushing own label products - benefits to come in H2 mostly.
Overall performance - nothing stated, which is ridiculous. Just a vague comment that -
...overall profit performance remains dependent on consumer sentiment in the residential market.
Paul’s opinion - this is a highly unsatisfactory and vague update. I’ve got no choice than to interpret it as a veiled profit warning. Gross margins being down suggests to me that HEAD is facing competitive pressure, probably from the rapidly growing Likewise (LON:LIKE) which is run by the former boss of HEAD. LIKE did £122m revenues in 2022, which has got to be coming from somewhere, so it seems likely to me that LIKE must be chipping away at HEAD’s sales, which they’re protecting by accepting a lower margin. I could be wrong, but that seems an obvious interpretation. The trouble is, that's not a temporary thing, it's a structural problem - an ambitious competitor growing fast.
Which makes me wonder if HEAD will be able to return to its pre-covid normality of making c.40p EPS each year, and paying out generous divis from that? HEAD should be able to continue paying good divis though, as it has such a lovely strong balance sheet. Note that the StockReport shows a very good price to tangible book of 1.03 - so the market cap is almost fully supported by tangible assets, a lot of which is freehold property. Hence why HEAD is a safe share to hold, even in a downturn.
Consumer demand is linked to the housing market, as people often replace carpets when they move into a new home. Although people also replace carpets in their existing homes when they wear out, especially if they can’t afford to move. So it can work both ways.
As with many small caps, I think HEAD shares look cheap, if you look beyond current subdued trading conditions. At some point the downtrend is likely to turn, and become an up-trend. I’ve no idea when of course. It might be a time to be looking at charts to help get some guidance on that, although we’re also seeing plenty of false dawns, where charts bottom out & start to break out upwards, only to fizzle out and fall back down again after a while. There’s no clear trend I can determine at the moment.
I’ve just looked at the share price at 08:28, and see it’s down 10% to 236p, not too bad considering. I’d like to own some HEAD shares, but don’t feel in a rush to get involved, after today’s disappointingly vague update. So I’ll give a neutral opinion at this stage, AMBER.
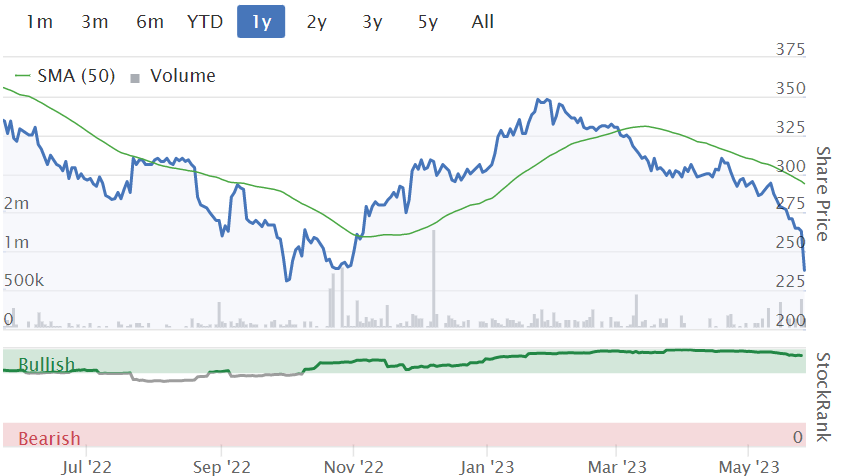
As you can see below, the share price (1-yar chart) had already been anticipating softer trading. It's probably at a level where value investors will be sniffing around. Sooner or later there's likely to be a nice recovery, so I think this is worth adding to our watch lists. High StockRank too from Stockopedia.
Graham’s Section
A big thanks to David for a thoroughly enjoyable Mello conference, with some very interesting companies presenting, and it continues today in online format!
S&U (LON:SUS)
Share price: £25.40
Market cap:£309m
Today brings an AGM statement from this family-run car finance and property lender.
At first it sounds like they are reporting more of the usual high growth that they always seem to report, albeit with a bigger drag than usual from interest costs:
Profit before tax for the period is £0.3m ahead of the same period last year, despite a rise in Group borrowing costs of nearly £3m for the period versus the same period last year. This is the result of interest rates which have significantly risen since early 2022 and a net receivables book which has now reached £418m (25 May 2022: £340m).
But actually this is a departure from the norm, as the receivables book has finally taken a break from its fast pace of growth seen in recent years. Group net receivables had already reached £421m at year-end (January 2023), so we have at last seen a decline in this important measure of the company’s size.
In the company’s words, “commercial prudence and preparations for the new Consumer Duty framework due in July, have seen a hiatus in the rapid growth of the Group's motor net receivables. Hence, in the latest quarter these grew by £1.5m against £14.5m in the last quarter of 2022/23.”
The most important thing from my perspective is that S&U maintains a high rate of collections. So long as this continues to be the case, I wouldn’t quibble with management about their rate of growth.
In any case, the growth in lending has been remarkable here in recent years, so a short-term pause is hardly a huge cause for concern? With both difficult economic winds to face, and the imminent implementation of the FCA’s new Consumer Duty, a more cautious approach may be perfectly reasonable in the short-term!
Financing: S&U has been hitting against the upper limits of its borrowing facilities as it grows the business, but we do get more positive news on this front today. Given the strength of both of their divisions, the company says it is “justified” to open new medium-term funding facilities. This gives them extra headroom of £70m and brings total funding facilities to £280m. This will enable them to fund the “steady and sustainable” growth they are looking for over the next two years. Current gearing is 79%.
Car finance: collections in the first c. four months of the new financial year are “above budget” at 94%. S&U is looking for this division to return to growth over the rest of the financial year, helped by “an increase in transaction sizes to higher scoring customers”.
Property bridging: this new division is finally starting to experience defaults, with 10 of its 140 loans currently in default. However, all of these are expected to be recovered by the end of June.
My view
Shareholders have plenty to ponder here but I think most of it is positive. It feels like the moment of truth for the bridging loans - now that a chunk of them are late, we find out how prepared the company was for this to happen!
Car finance continues to motor on (pun intended) with a fine collection rate.
The outlook for the next two years, with £100m of total headroom in lending facilities, suggests to me a moderate rate of growth in the receivables book of something in the region of 10% p.a. annualised. “Steady and sustainable growth”, in the words of the company.
The valuation has ticked higher in recent months but to me this is still within the range where sensible investors may find it interesting as a possible candidate:
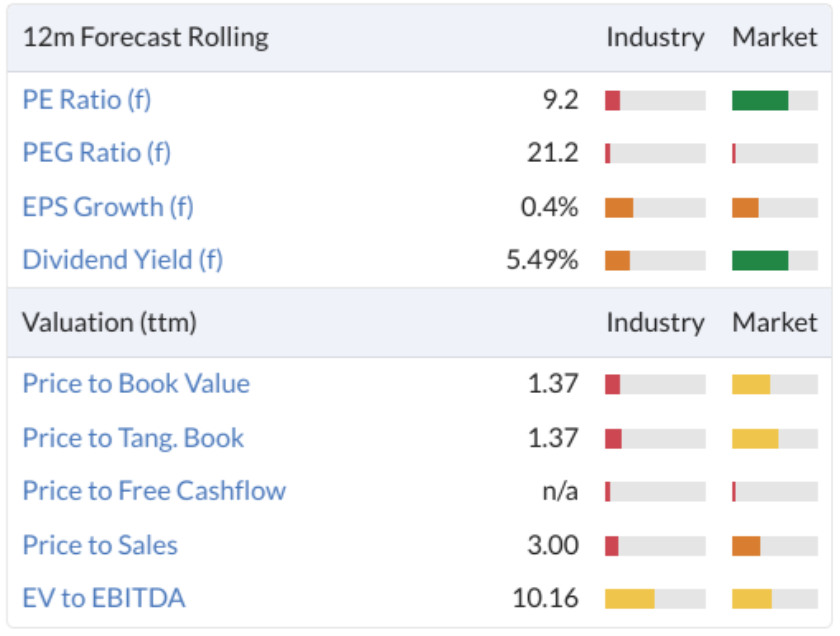
The researchers at Edison (paid by the company) forecast return on equity of 14%+, while Stockopedia calculates ROE of 15.6%. With this level of return and to my eyes a moderate level of risk given continued high rates of collections in car finance, the valuation metrics on offer here are still quite attractive to me.
The company is taking a more aggressive stance than it did before re: gearing, so I think we do have to accept that risk levels are elevated compared to where they were previously. But I remain positive on this.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
NVIDIA (NSQ:NVDA) up 25% in a day. I assume it is a small cap? That is the sort of excitement I like! I hold (very small position but getting bigger).
Regards
Michael
Hi
With regard to NVIDIA (NSQ:NVDA) (I hold). Not one for the SCVR I accept. But the rapid evolution of AI, LLM's and Chatbots or co-pilots is. These technologies will effect all of us and certainly all size of companies.
As some in the thread have questioned the stock price rise of NVIDIA (NSQ:NVDA) and its resultant valuation I thought I would prompt ChatGPT to provide a possible explanation as to what might be occurring. This is the prompt I posed to ChatGPT
What aspects of Nvidia's business model help to make Nvidia stand out from any likely competitors such as AMD, Intel, TSMC or ASML
ChatGPT response is quite lengthy (I could have requested a shorter version, but thought some might be interested to read some of the detail about this fast evolving technology).
Nvidia stands out from its competitors in several ways:
While competitors like AMD, Intel, TSMC, and ASML have their strengths and compete in various aspects of the semiconductor industry, Nvidia's combination of GPU expertise, AI focus, datacenter dominance, ecosystem partnerships, and forward-looking vision helps them maintain a distinctive position in the market
**** end of ChatGPT response *****
I repeated this response and others through Google's Bard. It's responses were quite good but not nearly as 'rich' as this one.
So, as an aside, this is also an example of how I as a investor is making use of these two (free) AI tools to broaden my own research. The time saving is very beneficial. Plus, I am evolving my skills as a 'Prompt Engineer'. I skill we will all develop as these AI/LLM's permeate our lives.
Regards
Howard
The publicly accessible version of ChatGPT stopped "learning" in 2021, so it is not up to speed on anything that has happened since then - such as Nvidia terminating its agreement to buy ARM in 2022. As well as not having up-to-date knowledge it is also prone to make up "facts". So I wouldn't recommend using ChatGPT to analyse company strategies, ask about competitors, give investment advice, etc.
ChatGPT freely admits to this shortcomings:
"My training encompasses a wide range of internet text up until September 2021. It's important to note that while I can provide information and generate responses based on that training, I don't have the ability to learn or update myself in real-time."
Hi andatza
Your point is completely true, and I concur with it completely.
That is partly why I always push my prompts through both ChatGPT (I am fully aware of its cut off date) and Bard. Because Bard is real time, thus it does incorporate events such as the one you point out.
The main point about my post is how we as investors can utilise these tools to get a vast amount of insights in seconds.
Clearly we all need to be cautious about the output (the technology is in its infancy) but if a prompt is thoughtful, then in most cases the output is pretty good and offers a far more extensive analysis (in seconds) in contrast to anything that I could have uncovered in several hours of research.
The example I presented is, but a single illustration of how these tools are penetrating into any part of our lives whereby we have a curiosity about any subject whatsoever.
Thus, the most salient point is that I believe every investor needs to pay attention to events as every investment we make will become effected by these technologies. Some are terming this roll out the fourth industrial revolution, which it might be. But one major differentiation, from the past, is the speed by which this assimilation is occurring. It is in days and weeks, not even months and years.
Regards
Howard
Hello Stockopedia peeps, one and all. May I make a suggestion (cos I'm lazy!). 'Securities mentioned' to RHS this page. How's about ALL securities mentioned put there such that one can quicly leaf through.
I may hav4 posted this in the wrong place. In which case - apologies!
Did anyone at Mello chat with Xeros? If so, what did you think? TIA.
Paul, can I ask you to comment about NVDA (NVIDIA), up 27% in pre-market. I know it's neither UK nor small-cap, but I wonder if you could give you thoughts on what you think it means for the state of the US and UK markets.
Haha Mark, NVDA is way beyond my pay grade I'm afraid! But I know we have at least one subscriber (Mary, who I was speaking to at Mello) who has done very well on NVDA shares, so you never know, there might be some subscribers who can comment knowledgably on it.
Regards, Paul.
Yes I must confess to be very happy today with NVIDIA (NSQ:NVDA)'s news. I was quite impressed with the ChatGPT response to Howard Adams question below until I got to point 4 where it stated it had taken over ARM. This acquisition did NOT happen, it was terminated in February 2022, which can be confirmed by checking on the NVIDIA website (sorry I couldn't get the link to work).
For anyone interested in NVIDIA I would suggest they visit their website which has a lot of comprehensive information of the sectors they are involved in.
I've held since 2016 and my most expensive purchase was at $59, so have no intention of selling despite the fact I expect the share price will pull back from where it is today.
Should have added there was a 4 for 1 share split in 2021 so the book cost was actually $14.75 rather than $59
Don't know much about Nvidia, but there has been a lot of comment about the sharp rally in a narrow band of US tech giants - all linked to AI which seems to be the latest craze/bubble.
Indirectly, that was the kind of question I was asking. A market lacking breadth and concentrating on a handful of winners in tech. It feels rather like 1999 all over again with the possible exception that the markets are perhaps a little more risk-averse now than they were then.
I found an interesting site that folks might like to check out: https://www.multpl.com/s-p-500...
It shows the S&P500 PE ratio. The graph shows it to be around 24, which is pretty high. Confusingly, the table below it shows lower mean and median. I assume that means an historic average.
The US markets seem to have moved into a "new paradigm" sometime in the 1990's where a PE of 15 was a floor rather than the average.
Mark
Surely there is one major difference here compared to 1999 and that is that the companies showing extraordinary gains this year are profit making in spades and not been valued on eyeballs, clicks or sales?
Alphabet (NSQ:GOOG) 39%
Amazon.com (NSQ:AMZN) 37.2%
Apple (NSQ:AAPL) 32.5%
Meta Platforms (NSQ:META) 109%
Microsoft (NSQ:MSFT) 34%
Netflix (NSQ:NFLX) 23.3%
NVIDIA (NSQ:NVDA) 161%
Tesla (NSQ:TSLA) 49%
I hold all but in small size except Apple (NSQ:AAPL) which I hold through my holding in Berkshire Hathaway (NYQ:BRK.B) and while they may have got away from themselves a bit maybe they were oversold. I am not going to analyse them individually here but most are well below ATH's.
My thinking (oh they are over priced, wait until they pull back) has cost me a fortune in the past. Drip feeding some money in to these over a couple of years to give a 10% to 15% weighting in a portfolio will work out very well over the next 20 years or so. Just my opinion and DOYR etc etc.
Regards
Michael
NVIDIA seem to be extremely lucky. They did very well from the crypto boom and just when that seemed to be collapsing and prices of high end graphics card were coming down the AI boom appeared.
You need a lot of GPUs (graphics cards) to train and run these very large models. So they should continue to do well if the AI trend continues.
By coincidence, I bought a graphics card off ebay the other day, and still waiting for it to be delivered. I wanted something extremely cheap - as cheap as possible - because it was for an old computer that lacked HDMI and it was type I was looking for. I opted for a second-hand unit. The cheapest new graphics card seem to be about £50 on Amazon. Nvidia's site is showcasing graphics cards for £1200 and even more. These are crazy high prices.
Are you sure it is luck? I'm not.
Regards
Michael
Hi Mark, with NVIDIA (NSQ:NVDA) its important to remember what they do. In the main, they produce, a physical product, in this case chips. Whilst they implement some other technology systems and products, chip making is their primary source of income. As with any physical product it can, to an extent, be replicated by other companies. I recognise Nvidia is the market leader, much like Tesla with EV, but I cannot comprehend how it is worth $400 per share. The PE must be well over 200 times after last nights rise. Is there really scope for that level of growth where there are competitors like Taiwan Semiconductor Manufacturing Co (NYQ:TSM) setting up factories in the US? I personally think Nvidia is in a purple patch where its stars have aligned with the AI trend and a fantastic set of earnings. If I held, I would most certainly be selling up when the US market opened today and taking my profits.
To answer your question on what it means for US and UK markets, I actually think very little. There are a few companies right now, predominantly Nvidia, Microsoft (NSQ:MSFT), Alphabet (NSQ:GOOGL) that are almost immune to geopolitical concerns. I think they are being invested in as safe havens by many investors. I would not be surprised to see the likes of Palo Alto Networks (NSQ:PANW) and Crowdstrike Holdings (NSQ:CRWD) move into this category over the next year or so as cybersecurity becomes the next big thing.
Ben
I hold Alphabet (NSQ:GOOGL) and Crowdstrike Holdings (NSQ:CRWD)
TSMC actually manufactures most of NVIDIA's chips.
TSMC is very much a contract manufacturer - they own the silicon foundries and specialise in doing that job very well. They also make Apple's M1 and M2 chips and a whole bunch of chips for other companies - it's probably not in their interest to compete directly with their customers and they don't really have the knowledge to do it.
NVIDIA's real value is in its IP and knowledge of how to design GPUs.
Forward PE is about 50 now. Expensive but not outrageous.
NVIDIA (NSQ:NVDA) is Mr Market enjoying himself and having a throughly good time - 29% up post/pre market is just bonkers; it's the equivalent of over £150B added to their market cap!
For context: that's 2/3s of a Coca Cola, or an entire Wells Fargo, or 1 and a half American Expresses!
As an aside it is decimating everyone who tries to short it, which is enjoyable to watch
No comments on here yet about the Tata battery factory that MIGHT be signed next week. Jeremy Hunt seems to think it will happen, but I want to see the ink on the line that is dotted. This is not an industrial policy. This smacks of scraping around for good industrial projects due to a lack of vision. We now need it to happen. And more of the same. Did anyone watch the recent government session about battery experts telling the gov energy experts that the uk is miles behind the pelaton? It was as fascinating as it was worrying.
I nipped down to Mello yesterday and echo Paul's comments. Really lovely day and I do hope they survive in their current format. I went for 3 reasons 1) to support Mello, 2) to meet Sam Bazini of Warpaint and 3) to have a drink with Paul and Graham. Scored on the first 2, but did the get the honour of meeting Graham and also Damien who I just couldn't place which was extremely silly of me, hey ho I will back his charity to make up for it! The Great Scott never turned up clearly until later and as I had to get back to Cambridge I couldn't wait. Anyway I had the pleasure of a charming chaps company as I waited and I thank him for that.
The reason I am writing this really is to say how impressed I was by Sam Bazini who was a really belt and braces sort of manager. Very straight forward, very successful but with no airs and graces, just a good bloke. I really trust that. So great company in a resilient niche, growing with founder managers with skin in the game (they own over 50%). The key to the business is keep costs down so they can offer a better price for what is essentially the same product. I love this company the only thing is I don't want to pay over 20 times in the new interest rate world so I will wait but I want it in my portfolio.
Ha ha don't worry about it and thanks for the support.
I agree regarding Warpaint London (LON:W7L) and Sam Bazini. He spent ages talking to me at his stand on Tuesday and everything that he spoke about in his presentation was in-line with the picture that I've formed of the company. I suspect that the P/E will fall as analyst forecasts continue to rise and perhaps we'll get an update on growth at next month's AGM.
'a charming chaps company'
Superb!
It was a pleasure to meet you and share a chat and a beer.
Hi Paul
I completely agree with you re Mello. Two really great days at Chiswick with lots of joshing and views exchanged between investors. I caught one of Graham’s sessions which was excellent and I must read my notes again today; just so much good stuff to take in.
Three cheers to David and his team. Only sorry that I couldn’t stay for the evenings but probably good for the state of my liver…
A few quid will be winging their way towards Damian’s appeal later.
Cheers, Mark
Totally agree with the Physical Mello sentiments, however I plan every year to attend but the week is just no good for me (still working full time and last week of the month is just too busy at work especially before the bank Hol w/e). Another date next time?
Thanks Mark - much appreciated. I have to say that I probably couldn't take three straight days in the Mello bar but two was just about survivable!
Destiny Pharma (LON:DEST) CEO steps down to pursue new challenges ahead of AGM. I was going to dip in yesterday. Glad I did not.
Paul, What is your view on the results from XP Factory (LON:XPF) yesterday? Do you plan to cover them today?
Hi FREng, re XP Factory (LON:XPF) (I hold, my 2nd largest position), I did a 10-minute briefing on it at the StockSlam at Mello on Tuesday, but perhaps because I was ill-prepared, having had little time to read the results on that day, I dismally failed at convincing the Mello attendees that it was a good share idea. I think only 3 people voted for it, whereas the runaway winner was Kevin's presentation of Secure Trust Bank (LON:STB)
To be fair, it was a tough audience, of mainly I think value investors, who focused on the historic numbers, which of course are now irrelevant because XPF opened about 20 new Boom Battle Bar sites near the end of 2022.
My point was that the unit economics have now been proven to be good, for both Escape Hunt, and BBB, therefore it's now a simple, and quite rapid, roll-out of new sites, which are being funded almost entirely through landlord cash & rent-free periods.
All of this fell on closed ears I'm afraid, but it was nevertheless interesting (and rather encouraging in a way!) that investors don't even want to listen to a roll-out of a successful format. That probably means more buyers for the shares at a later date, and at a higher price, once market sentiment has improved. In the meantime investors probably have ample time to research it, without having to worry about the share price rising, probably!
I'm planning on going through the numbers again either today or tomorrow, so will write up something for here once I've done some more digging through the numbers.
Hence please bear with me, but yes I'll definitely be writing up XPF in the next few days.
Regards, Paul.
I liked your pitch Paul but perhaps XPF is a bit racy for the Mello crowd? I suspect that more mystery shopping is required to truly grok the concept!
Thanks, Paul. I look forward to reading how the numbers back up your enthusiasm and the success of the existing locations.
Think some may have been put off by the Stocko quality rating !! Zero
Thanks very much for the hat tip Paul. It was great to see you and Graham in Chiswick. It's just so much better to get together in person so I hope that the Mello events continue and that smaller companies realise that they need to get in front of investors.
And, yes, if anyone would like to sponsor me to jump off a tall building in these dark days then here is your chance: https://www.justgiving.com/fun...
Not sure if anyone follows 4Basebio (LON:4BB) but news of contract out today on sales of the synthetic DNA. Would have thought it would have had more of an effect on the share price. Granted this is a niche company and very illiquid but nonetheless. Recent M&A in this space is multiples of current share price but obviously in the pharma services space you need to know what you’re doing.
Good morning Graham. Would you be in a position to comment on Volvere (LON:VLE) final results published this morning? I believe this is a long term hold for you, and have previously appreciated your comments on this stock.
It would be good to understand how you would value Shire Foods, it has continued to grow strongly under their ownership and must now be reaching a point where they look to dispose of it.
The recent recovery in share price has reduced some of the underlying discount to net assets, but I continue to believe Shire is undervalued when the large cash balance is removed.
I have been disappointed with the Landers' lack of any action in recent years, and am starting to find the standard, repeated outlook comment as pretty tedious. In the meantime they continue to pick up a healthy management fee. I do continue to hold however, at around 3.5% of my portfolio.
Cohort (LON:CHRT) - "ahead and unified" (new research link below) *** In a Trading Update for the year to 30 April 2023, Cohort plc expects performance to be slightly ahead of market expectations based on higher revenue. We note FY23 net funds reported at c.£15.0m - well ahead of ED estimated, at £4.6m - strong order intake of c.£218m (FY22: £186.7m), and a closing order book of £325m - at the Interim £304.2m. This underpins £145m, i.e. 83%, of our FY 24 estimated revenue, compared with 69% in FY23 (E). Overall, the update confirms the strength of momentum into the medium term with delivery projected to 2032. At the Interim we raised our FY23 revenue outlook by 3% to £165m (+20%YoY) and maintained our (adj.) EBITDA outlook of £22.0m (+13.1%YoY). At this stage, our outlook remains unchanged, with the opportunity to review with full FY 23 results, and which indicates a FY23 EV/EBITDA of 8.9x; and for FY24 (E) 8.2x. Our Fair Value remains at 650p/share. Link to note: https://www.equitydevelopment.co.uk/research/fy-23-trading-update-ahead-and-unified
A bit of a macro point, but 10-year gilt yields have gone above 4.2% again. Approaching the Truss high of 4.5%. UK 10-yr rates going up faster than US and Euro countries. Poor inflation data probably the cause. Not good for equity markets!
EMIS (LON:EMIS) FY22 results in line. Management overview: video & podcast.
On the acquisition: The CMA has referred the Acquisition to a Phase 2 investigation, Bidco & EMIS have agreed to extend the Long Stop Date for completion of the Acquisition to 30.6.24. EMIS expects the Scheme to become effective in Q4 23 or Q1 24.
Also, a webinar on 20th June, 2pm, with IG Design (LON:IGR), we have Chair, Stewart Gilliland and CEO, Paul Bal, who will present Full Year results for the year ended 31 March 2023, followed by Q&A. Register here.
Morning ! I don't think Portmeirion (LON:PMP) was a profit warning Paul, sounded inline to me...
There was a note of caution (about demand in the US) in the Portmeirion (LON:PMP) update but both Shore (NOMAD) and Singer published notes after the update and neither changed any of their forecasts. What is clear is that the stock price has fallen 14% in the two days since the update - so "the market" did not like what it was told.
I don't disagree ! But the point is it wasn't a profit warning...
IMHO, many people expected Portmeirion (LON:PMP) to announce an ahead TS highlighting bouyant Coronation sales. Perhaps that wasn't a realistic expectation, but it certainly did not happen. So a profit warning for those people.
I would describe it as a warning there may be a profit warning.
This made me chuckle