Small Cap Value Report (Thu 25 Nov 2021) - ALT, IQE, MUL, CBOX, LTHM, MACF, AOM

Good morning! It's Paul & Jack here with the SCVR for Thursday.
Agenda -
Paul's Section (I've gone a bit nocturnal, so apologies for the erratic timings, this was mainly prepared overnight) -
Altitude (LON:ALT) - in line update. Altitude has over-promised and under-delivered in the past. £20m market cap could be a speculative idea?
Iqe (LON:IQE) - profit warning - shares down 24%. It sounds tech impressive, but doesn't make any cashflow. Not for me.
Mulberry (LON:MUL) - interims looks good, but more than half profit came from a Paris lease disposal. Weird ownership - 95% owned by 2 shareholders. But if this brand takes off again, could be a multibagger. Worth a look, for fashionistas, not bean counters who mistakenly think they know about fashion! like me! :-)
Cake Box Holdings (LON:CBOX) - when is it right for founders to sell? We love CBOX here at the SCVR - exactly the type of hard-working founder entrepreneurs, with big shareholdings. But they're selling a quarter. How do we feel about that?
Jack's section:
James Latham (LON:LTHM) (I hold) - strong H1 results, as previously flagged. The group faces a number of cost pressures now, while volumes and margins are normalising. The current period has benefitted from stock bought at historically normal prices and then sold at a mark up amid unprecedented demand conditions. Receivables have increased and customers are 'a bit quieter' as they hold off in order to source parts. It's a good company but I wouldn't be surprised to see the share price ease back over the next year or so, depending on how the wider market plays out.
Macfarlane (LON:MACF) - a short update confirming that the group now expects to exceed full year expectations. There's a good track record of long term revenue growth and operating margin expansion here that warrants further investigation.
Activeops (LON:AOM) - relatively new software float with recurring revenue, although it remains loss-making. The company has cash to invest and I'm interested to see how it might grow in time but, for now, the valuation looks quite full.
Paul’s Section:
Altitude (LON:ALT)
28.5p (up 6% yesterday) - mkt cap £20m
There’s a change of Chairman too, which doesn’t really matter in my opinion.
The new Chairman has a background in the insurance sector, so I’m not sure how relevant that is to promotional products?
In terms of trading, this is the latest -
The Group is pleased to report that it has made good progress in the six months to 30 September 2021 ("HY1 2021") with US recovery across the promotional product industry having accelerated recovery for the Group. The Company is trading positively and in line with management's expectations.
The Group will announce its HY1 21 interim results on 30 November 2021.
My opinion - neutral. Altitude has over-promised & under-delivered in the past, so it’s difficult to muster much enthusiasm for the outlook.
However, at £20m market cap, for a company that’s trying to build an online marketplace type business in the USA, the upside could be considerable if it takes off.
I see this as a complete punt. It’s tempting to have a dabble with fun money.
Iqe (LON:IQE)
38p (down 24% yesterday) - mkt cap £306m
IQE plc (AIM: IQE, "IQE" or the "Group"), the leading supplier of compound semiconductor wafer products and advanced material solutions to the global semiconductor industry, announces a trading update for the year ending 31 December 2021.
Here are my notes reviewing the FY 12/2020 results, back in March 2021, where I was left unconvinced by the business model - heavy capex, and uncertain/volatile profits.
The other difficulty, is that it’s difficult for generalists like me, to appraise companies in sectors that we don’t understand. Hence why sometimes I think it’s best to stick to your knitting - i.e. a few sectors that are simple, and where you have an edge, in terms of understanding.
There again, the numbers don’t lie (usually!), and it’s been clear for a long time that IQE has to run to stand still, in terms of capex. Is it doing anything unique? The numbers suggest not.
Trading Update (profit warning)
There’s useful detail in this update, but the outcome is that FY 12/2021 guidance is reduced, due to reduced demand & forex headwinds (weak dollar).
The new guidance is £18m EBITDA, and £14-17m capex (reduced, as some has been deferred into 2022).
The simplistic way I look at things, that is telling me that IQE is running at around cashflow breakeven, after deferring some capex into next financial year.
Net debt - sounds modest -
Net debt is expected to be less than £10m.
My opinion - I’ve had a look at the last (interims) balance sheet, and it’s robust, so there’s no solvency or dilution risk here, in my opinion.
It’s a capital-intensive business that owns the assets with equity, so there are no worries about borrowings.
IQE is a business that I’ve followed for years, and the pattern seems to be that it needs to constantly update/replace its machinery, with very heavy capex, just to stand still.
Looking at the last 5-6 years, revenues have risen, but profitability has collapsed. What does that tell us? Probably that competition might have caught up, or even overtaken IQE? I don’t know, because this sector is a mystery to me, but the numbers tell me it’s probably best to avoid this share, unless there are good reasons to expect a dramatic improvement in profitability in future - a story I’ve heard before from IQE, which didn’t work out.
Overall then, it’s not for me, but sector experts can probably give a better analysis.
.
Mulberry (LON:MUL)
370p (up 23% yesterday) - mkt cap £222m
There’s been a striking rise in share price for this vendor of fancy handbags. As we’ve discussed here before, the big problem is that 2 shareholders own about 94% of the company -
.

.
Unfortunately, the explanatory note on this Stockopedia page takes up so much width, that it compresses the columns to the left so that I cannot see the most important one! (% shareholdings). Hopefully the IT team can do a quick fix on this simple problem, by making the columns wider, or just getting rid of the explanatory note which obliterates the actual data? I’ve been moaning about this for a long time, so it would be good to get it fixed.
The problem is that I don’t have great eyesight, being over 40, probably like most Stockopedia subscribers, so I have to increase the font size to see things. That changes the layout, and sometimes it doesn’t work as a result. Although, to be fair, it usually works fine, this particular page about shareholders is the problem for me when I enlarge the font, everything else is fine. Don't’ shoot the messenger, it’s constructive feedback!
Mulberry Group plc (the "Group" or "Mulberry"), the British sustainable luxury brand, announces unaudited results for the twenty-six weeks ended 25 September 2021 (the "period").
Further strategic progress amid strong consumer demand
Haha, the PR headline about “strategic progress” probably means the figures are no good. But, the share price is up 24%, which suggests the figures might be good (in a very thin market), let’s see which is right.
Balance sheet looks OK, but watch out for loss-making sites - lease liabilities are about double the right of use assets figure. This could improve in future though.
Very important - a profit of £5.7m on the disposal of a property lease in Paris. That provides just over half of £10.2m H1 profits.
My opinion - this is a very quick skim of the figures, so more work is needed (as always) by subscribers to do your own research. We’ve got to look at loads of companies here at the SCVR, so can only ever publish a quick view.
Mulberry is a very well-known brand, and it’s shot back into impressive profits, even when you strip out the one-off £5.7m disposal of a Paris property.
Clearly the 2 big shareholders control the company, so that makes me wary.
This share could be quite interesting. Why? Because of the fashion side of things. Bean counters like me, who’ve worked in the fashion sector, like to think that we know about fashion, but we don’t. We’re clueless about fashion! However, we have observed that when the design & buying team get the fashions right, then profits explode upwards, and often do that for several years. We’ve seen this with Mulberry before. So it could happen again. The brand could be very valuable again, who knows?
Women pay staggering amounts for fashionable handbags - it’s a status symbol apparently. Maybe a bit sad, that self-esteem has to come from a bag, but that’s a discussion for another day.
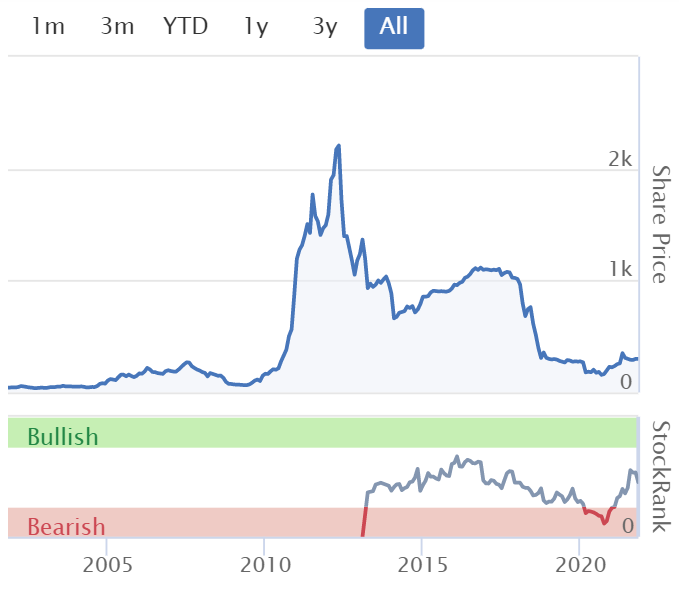
I’ve got to say though, Mulberry shares look quite an interesting punt to me. There doesn't seem to have been any dilution, with 60m shares in issue, if these handbags hit the fashion big time again, then there’s a potential multibagger. Look at the long-term chart below.
I think it’s time to consult our fashion guru figures, and see what they think about the brand?
Overall - I like it, there could be a speculative opportunity here. What do you think? When I have some spare cash, I’m tempted to just tuck away a small position here and forget about it for 10 years.
.
.
.
Cake Box Holdings (LON:CBOX)
405p - market cap £164m
The founders of CakeBox are selling some of their shares.
My view is that deals like this need close scrutiny, because if the people who know the business best want to sell, then that’s telling me the price is favourable to them, not to me.
The main issue with secondary placings in the past, is that the City brokers overtly lie about this - by trotting out the misleading phrase that, founders are selling due to institutional demand. Everyone knows that is untrue, so it needs to be stamped out. Hence why I add my voice to the widespread criticism of brokers publishing such lies - it’s not acceptable, stop it right now.
The truth is that there are many reasons why founders want to reduce their shareholdings in secondary placings. The main reason is that they want cash, instead of an over-sized position in the company they founded. That is perfectly reasonable, but please tell the truth! You’re not selling due to institutional demand. You’re selling because you want to sell at a good price, and there are buyers happy to pay up.
If the buyers offered a lousy price, you wouldn’t sell. We all know that, so don’t let the broker lie about it, which doesn’t fool anyone.
Scrutinising CBOX announcement, it says -
The Sellers announce that in response to investor demand and a desire for financial diversification, and in line the ambition expressed at the time of the Company's IPO to increase the Company's freefloat over time, they intend to sell in aggregate 3 million ordinary shares in Cake Box (the "Placing Shares").
Sukh Chamdal and Santosh Chamdal currently own together c.12.79 million ordinary shares and will, assuming 3 million Placing Shares are sold in the Placing (as defined below), retain a significant holding in the Company of c.9.79 million ordinary shares representing approximately c.24.47 per cent. of the Company's current issued share capital.
My view - that sounds fine. The explanation given sounds reasonable - founders want to partially sell, to diversify so that all their eggs are not in one basket.
Founders are selling about a quarter of their holdings, and retain a major shareholding. That seems fine to me.
Does it cap the upside if the founders want to sell a quarter? Yes, to be blunt, at least in the short term.
Overall, I think CBOX is a smashing business, management come across extremely well in presentations, as just the type of entrepreneurs I would want to back. Sorry I missed this opportunity early on, but you need to see track record build.
Given the secondary placing, I’d say it’s probably fully priced for now, with limited upside, after a great run? Long term, it's probably good, CBOX looks a smashing business, based on an excellent track record so far.
If founders are happy to sell a quarter, it shows how shrewd they are! Also big positions remaining, and performance of CBOX has been really excellent, it looks a very nice business. On the watchlist, so something I would buy on dips to maybe 300p-ish?
.
Jack’s section
James Latham (LON:LTHM)
Share price: 1,294p (+3.11%)
Shares in issue: 19,900,800
Market cap: £257.5m
(I hold)
James Latham is a supplier of wood-based panel products, natural acrylic stone, hardwoods, high grade softwoods, cladding, decking and plastics to manufacturers, shopfitters and other market sectors.
It’s a 9th generation family business, publicly listed since 1965, which has grown to service customers from 11 locations across the UK. In 2019 it acquired Abbey Wood in Ireland and this year it has expanded its presence here with a further acquisition.
Highlights:
- Revenue +81.2% to £193.9m,
- Gross profit +183.2% to £51.1m; gross margin up from 16.9% to 26.4%,
- Operating profit +421.6% to £34m; operating margin up from 6.1% to 17.5%,
- Diluted earnings per share +419.5% to 133p.
Revenue for the six months ended 30 September 2021 was £193.9m, up 81.2% on £107.0m for the same period last year (with the previous period significantly impacted by the first lockdown).
Cost prices on both timber and panels have risen significantly, with average cost prices up over 25%. The strong volume growth evidenced in the first quarter is returning to more normal volumes, finishing the half 4.9% higher than in the six months to 31 March 2021.
Gross profit percentage, which includes warehouse costs, for the six month period ended 30 September 2021 was 26.4% compared with 16.9% in the comparative six months. This six month period has been very turbulent with significant increases in the market prices for our products and well documented problems in the global supply chain leading to difficulties in obtaining regular supplies of inventory. We anticipated this issue and made sure that sufficient contracts were placed to ensure that our customers were not left short of stock. These significant increases in market prices did lead to a short-term improvement in margins as we worked through inventory purchased at competitive prices.
Overheads have been well controlled during the six months, although they are starting to increase with pressure on transport costs in particular.
Increasing cost pressures explain a notable difference between reported net profits (£26.6m) and net cash generated from operations (£1.7m), with the company investing £20.9m in inventory, while a similar £20.6m increase in receivables is something to monitor. The group says:
As at 30 September 2021 net assets are £146.4m (2020: £109.1m). Inventory has increased significantly, up to £69.1m from £41.3m. Apart from the increases due to the higher cost of our products, the supply chain has become extended leading to increased stocks on water from £7m to nearly £20m, as vessels are delayed both at the port of origin and the destination port. Trade and other receivables have increased by £23.65m to £68.4m due directly to the increases in revenues, but continue to show good debtor day figures, with bad debts remaining at a low figure. Cash and cash equivalents of £24.5m (2020: £26.1m) have been important to allow us to increase our investment in working capital especially the inventory levels. We continue to take advantage of additional early settlement discount opportunities with our suppliers.
The pension deficit is calculated as decreasing from £2.5m to just £12,000, largely due to a recovery in the plan asset valuations although the discount rate has slightly reduced. I would have expected the discount rate to rise in the current conditions, which would have been an added positive here.
Current trading and outlook - The second half of 2021/22 has started with slightly weaker volumes compared with the ‘exceptional’ six months to 30 September 2021, and margins are returning to more normal levels. There has been a reduction in prices of some commodity products but most products are seeing prices remaining firm.
The challenges persist in our supply chain, with shipment delays, congestion at the ports and container prices at all time high levels. Latham says issues could persist throughout 2022. Inventory levels have remained high in order to meet customer expectations. There will be continued inflationary pressure on the group’s overheads for the foreseeable future.
Some customers ‘are a bit quieter’, which is in part due to projects being delayed due to supply issues with non-timber products ‘but overall we remain confident that we will have a good end to our financial year despite the challenges ahead of us’.
The balance sheet looks fine - £24.5m of cash set against £50.4m of current liabilities, a current ratio of 3.21x, nearly £70m of inventories in hand (up from £41.4m), and a net tangible asset value of £143.96m.
Conclusion
These are exceptional first half results, well flagged to the market, but you can’t accuse the management of that classic strain of C-suite over-optimism. A number of pressures and challenges are noted in the update, with more time spent on these than on the stellar results. That strikes me as a prudent move.
It’s a fairly unforgiving market at present. Anecdotally, almost every private investor I’ve spoken to has had a difficult 3-6 months. So I wouldn’t be surprised to see Latham’s shares marked down on the cautious outlook. It doesn’t really matter to me, as I’ve bought in here for a long term hold. Any weakness could be a topping up opportunity.
The group’s recent acquisition in Ireland is integrating well and should complement Latham’s existing Abbey Woods business.
LTHM continues to be a relatively low risk investment given the strong cash position, no debt and stable yield. Can it repeat this performance in H2? It’s sounding unlikely, but what’s also far from clear is just where performance will settle given the variables. Based on the comments above, forecasting in the short term would be a complete stab in the dark.
With 133p of diluted earnings per share already in the bag (nearly double that generated in the entirety of FY21, and more than double that of any other year for that matter), the shares trade on less than 10x FY22 earnings assuming the group does not incur substantial losses in the second half. We’ll just have to wait as the conditions evolve to see what level of earnings per share H2 brings, and what more normalised trading conditions will really look like in the medium term.
It’s entirely possible that the shares might derate at some point in the future as volumes and margins normalise while managing the cost environment. Whatever the conditions may bring over the next 12 months or so, I view this as a sensibly managed business that can generate steady long term underlying growth.


Macfarlane (LON:MACF)
Share price: 136.44p (+3.75%)
Shares in issue: 157,812,000
Market cap: £215.3m
Macfarlane has been listed since 1973 and has over 70 years' experience in the UK packaging industry. It supplies a broad range of business customers with protective packaging and labels, which help its customers to reduce supply chain costs.
You might think that sounds boring, but that’s sometimes not a bad thing. It has worked well so far here.


There are two divisions:
Packaging Distribution - the leading UK distributor of a comprehensive range of protective packaging products; and
Manufacturing Operations - high quality self-adhesive and resealable labels for FMCG companies, and protective packaging for high value and fragile products.
These products are distributed to a range of sectors including e-commerce, consumer goods, logistics, and mail order.
- Robust performance since the first half and the group now expects to exceed its previous full year expectations,
- Revenue has grown by 25% in the year to date and PBT is well ahead year-on-year,
- Both acquisitions made in 2021 are performing well,
- Net bank debt has reduced from £8.7m to £2m.
The remainder of 2021 will remain challenging due to input price inflation, supply constraints on various raw materials, and increased labour costs. Demand for packaging is also beginning to be impacted by customers’ own supply chain issues.
The group says:
The Macfarlane Group performance has been robust in demanding market conditions and is testament to the strength of our business model and the diligence of our people. At the interim results we indicated that we expected headwinds in the second half of 2021, so it is particularly pleasing to be once again raising our expectations for the full year.
Conclusion
This is a very short update to communicate that the group is trading ahead. Pressures are flagged for the rest of the year, but these were also raised at the interim stage and the company has since gone on to exceed expectations.
I have a positive initial impression of this company and it’s high up on the watchlist to research further. Today’s update does nothing to change that, in fact it probably makes it more of a priority given the relatively muted reaction to positive news this morning. Admittedly, it’s not all good given the challenges this company, and many others, presently face.
Even after a period of fairly strong share price performance, the company qualifies for the Neglected Firms Screen, which suggests it's far from too late to begin investigating.

Activeops (LON:AOM)
Share price: 187p (-0.27%)
Shares in issue: 71,320,680
Market cap: £133.4m
This software company is a recent listing. It allows complex businesses to outsource their back office functions with its Management Process Automation (MPA) software. It could be quite a big market, and if the company’s software is good and its market position is strong, then it could grow to become quite large in time.
That might be reflected in the valuation already though, with a fair bit of growth priced in. The group remains loss-making, is forecast to continue to be so for at least the next two years, and currently generates annual revenue of just over £20m on a market cap of about £134m. On the other hand it is growing its recurring revenue and should benefit from operational gearing if the company continues to win new business.
The thing to figure out is where will the company be in five years’ time? There are some notable institutions on the share register, including Canaccord, BlackRock, and Schroders, all of whom presumably feel this company can do quite well.
Highlights:
- Total revenue +22% to £11.5m, made up of a 12% increase in software and subscription revenue to £9.6m and a 137% increase in training & implementation revenue to £1.9m,
- Gross profit +21% to £9.2m; gross margin of 80% is up from 78.4%,
- Loss before tax of £1m compared to a H1 20 LBT of £0.6m,
- Earnings per share of -1.4p compared to H1 20 EPS of -1.19p.
Annual recurring revenue at the end of the period was up 16% to £19.8m and the group notes ‘significant expansion sales in all key regions and targeted industries’, with five new customer logos added in the period.
Renewals have been in line with historical standards and retention is good, with three long term Australian banking customers extending their renewal cycle from one to three years (two of these came after the period’s end).
There has been a 60% increase in software development capacity and a data science function has been set up ‘to more rapidly address the many opportunities to exploit Artificial Intelligence within the product set’.
Increased investment in sales, marketing, and technology result in the increased loss before tax of £1.0m (H1 FY21: Loss £0.7m).
Outlook -
- Continued positive trading in the second half of the year, with a further new customer win, customer expansions and investment in product development
- Strong recovery of T&I revenue continues, supporting software sales
- Increased confidence in delivering a positive full year performance, slightly ahead of Board expectations
Trading in the second half of the financial year has seen a continuation of the momentum seen in the first half. We continue to focus on our established strategy, maintain our position as thought leaders and expand the scope of our Workware+ platform to support our customers in simplifying the running of their operations.
With strong market drivers, alongside a proven and expanding proposition, we remain confident that we are well placed to deliver on our growth ambitions and we are excited about our future prospects.
Conclusion
The group is investing in its product suite and capability but the valuation remains a little high in my view.
Activeops does have a few trends working in its favour. The shift towards WFH and more hybrid methods of working increases complexity, which should benefit the group, as should the constant competitive search for efficiency gains, while the Covid pandemic has accelerated a more general digital transformation.
The StockRank has steadily improved (from a very low level) and the company has cash to invest, so it could be worth keeping tabs on in case growth trends accelerate or the valuation becomes more favourable.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
''Unfortunately, the explanatory note on this Stockopedia page takes up so much width, that it compresses the columns to the left so that I cannot see the most important one! (% shareholdings). Hopefully the IT team can do a quick fix on this simple problem, by making the columns wider, or just getting rid of the explanatory note which obliterates the actual data? I’ve been moaning about this for a long time, so it would be good to get it fixed.''
I so agree! The RH column seems such a pointless waste of space. Eg in a typical SCVR daily report all it has is a mugshot, summary detail on just one of perhaps 5+ stocks being discussed and links to the other 4 or 5 stocks. This really adds nothing of value but means the meat of the report is on my good quality Huawei laptop compressed into just 7'' width. Not too painful on typical SCVR but really annoying on some other threads where people post intricate charts/tables that I often have to open in a separate tab to read the detail of the axes, labels etc (OK I know I can easily magnify with a touchscreen, but not everyone enjoys this facility).
I agree with you. To me it makes no sense to display two panes side by side when the main pane is many pges long, and the other one very short. You soon scroll past the end of the text in the RHS pane and then have to put up with reading the main article restricted in width while the RHS pane - now just grey, occupies the rest of the available screen width. It would be fine if the smaller pane were put above the main article so you could quickly scroll past it and then be able to read both at full screen width. I raised a green blob about this a few weeks ago and was told it would be passed to the technical team.
I agree it takes up too much width. Maybe there should be an option to turn off this feature?
Also it does not always have the correct stock, as the Boohoo (LON:BOO) general discussion post has Anglo Asian Mining (LON:AAZ) as the default stock.
Paul, when you are on % shareholding Stocko page left click and drag to right and % holding appears on right
Paul, when you are on % shareholding Stocko page left click and drag to right and % holding appears on right
Dx (group) (LON:DX.) RNS 15.51
Director Share Purchases
On 25 November 2021 Lloyd Dunn, Chief Executive Officer, purchased a total of 529,801 ordinary shares of 1 penny each ("Ordinary Shares") at an average price of 18.18 p
Paul Ibbetson, Managing Director DX Freight, purchased a total of 109,970 Ordinary Shares at an average price of 18.18 p
disclosure: no position
I just don't understand how they were allowed to purchase stock where they have information that they haven't disclosed to the market (i.e. they know what the issue under investigation is - and its severity - and we shareholders do not). Of course, I'm sure the NOMAD cleared it before the purchase, but this seems crazy to me. Confused holder. £DX.
Today’s Dx (group) (LON:DX.) Director purchases remind me of student ruse at Uni. Walk into the college bar and shout that there’s a fight going on outside. Wait till everyone rushes outside to watch and then calmly minesweep all of the unfinished drinks on the tables. That wasn’t especially good “corporate governance” either but it worked a treat (apparently - not one I tried, honest).
These director purchases show an appalling lack of judgement on their part, even if it wasn’t insider dealing/illegal. Not hard to see why the Independent Directors on the Audit & Risk Committee might be having a few issues with the Executive Management if this is typical of their behaviour.
Gus.
It's not right that Dx (group) (LON:DX.) directors can trade when they almost certainly have more insight into the accounts problem than we do.
Outrageous for DX directors to trash the price with such a vague RNS and then buy in the resultant market, when they know the detail of the issue behind the RNS.
A good clue that things are overdone, however - I picked up 300k just before the close!
Dx (group) (LON:DX.) yeah - not sure how I feel about that !! On the one hand great that they are trying to back up their confidence in current trading with share purchases so as to assuage investors it's not going to zero............ BUT..............
the issued statement this morning didn't clarify anything for shareholders around the issue hence the big reaction. If management have more information on the issue than investors and it proves to be innocuous (I have no idea either way) and the share price recovers quickly, they gain a lot whereas shareholders selling on uncertainty have lost out.........hmmmmm.
I contacted the Company Secretary and they confirmed to me that the directors purchasing the stock know no more than the information released to the market this morning.
If you believe that you'll believe anything - at the very least they'll know what its about - which no one else does!
Yeah. Company speaking bs here. Plus you don’t just buy on a 40% down day as CEO without having an eye on what’s happened. I think we find out how much AIM is regulated for investors here…
re Cake Box Holdings (LON:CBOX)
My view - that sounds fine. The explanation given sounds reasonable - founders want to partially sell, to diversify so that all their eggs are not in one basket.
They don't have any eggs to put in their basket - it's an Eggfree Cake Box :)
Snazzy
Thanks for the review of Macfarlane (LON:MACF) , Jack. I am a long-term holder of these and have added a little more detail below, based on my own analysis.
Headline revenue growth is quite heavily impacted by the two sizeable acquisitions made this year, one in March and one in April.
Doing some rough calculations, I reckon that LFL growth over the year has progressed as follows:
Extending the analysis to the full year, I reckon that my current revenue forecast of £279.6m implies a meagre 0.2% LFL growth in Nov-Dec. I'm comfortable with that, given the current impact of supply chain challenges and the tough comparatives.
The end-October net debt position of £2.8m is a lot better than my year-end forecast of £5.7m. Last year, net debt improved by £0.3m from October to December so, assuming this year is similar, it looks like my current forecast is too pessimistic. However, the variance of £2.9m is small compared against current assets/liabilities that will be around the £90m mark at year-end, and could easily just reflect "noise" in working capital movements.
Overall, I'm comfortable that my current forecast is broadly consistent with this update, albeit with a slightly prudent bias. Hence, I am not updating my model. Due to an increase in the market median forecast PE ratio since August, however, my valuation of Macfarlane (LON:MACF) has improved to 231.5p.
Thus, Stockopedia's "neglected firms screen" appears to be working well. I would endorse your suggestion that it may not be too late to get in here; I'm certainly anticipating further excellent returns.
More information here, for those that are interested.
https://www.stockopedia.com/co...
£LTHM. Thanks Jack for your analysis (I hold). Agree the pension deficit does seem odd, but well done. To your comments that the MP may slide over the next year - am thinking that as long as the building boom continues there will be a strong market for timber - not only new homes but renovations also. Another factor which may be driving the price up - the IHT relief ? Finally - there is very little Institutional holding - just two totalling 7.5% - and wonder whether the £250m barrier (almost there) might encourage them to invest...?
One of my top 5 rules in investment is the moment owners start selling their shares get out. Not because there is necessarily anything wrong, I understand people want to profit from their work, no problems there. The issue is no one who understands their business is going to sell if they believe there is a lot of growth to come. So you are buying the initial business on its valuation, again fine but if I was the owner I would take advice on that, so shouldn't be too much there for thee and me. So the only reason I would stay is if the remaining business churns out cash and pays it to the investor. Otherwise, bye bye..........always happy to return when I have seen the company for a while thereafter and a new story emerges.
Headlam (LON:HEAD) slipped out a lovely, low key trading update today.
It is "On track to deliver profit marginally ahead of expectations" which it helpfully explains as "*Company compiled consensus market expectations for 2021 revenue and underlying profit before tax are £684.8 million and £35.0 million respectively (on a mean and post IFRS 16 adoption basis).
Two thoughts: First, how clear and simple is that! Second, business is trading well.
So very worthy but a bit dull initiatives are steadily making the business better and offsetting short term headwinds on costs etc. (I had been a bit worried that some Mgt changes eg CEO leaving might indicate start of trouble but no sign of it).
So every chance its on track for target of post Covid, end of 2023 7.5% margin - roughly 50% than pre-Covid on same/slightly larger turnover.
Nice divis on the way as well. (I hold)
Newriver Reit (LON:NRR) pleasing update with signs that valuations have finally stabilised. Announcement of 4.1p interim dividend also very encouraging. Still on large discount to NAV even after this morning's rise.
Yes, I bought as a future income play around 75p a while back so it has required patience but looks like it is now a 10% p/a income on an 80% payout of earnings.
I think ERPA NAV is probably now on the low side and should start rising back towards 150-160p quite quickly. At least from the asset trading prices they have been doing recently it appears that way to me. Nonetheless looks in decent shape and I am happy to hold long term at 12% p/a yield on investment. Would probably trade out if it comes back towards 6%.
Please, could you have a look at MJH
After Best Of The Best (LON:BOTB) , I'm staying well away from anything where there's significant founder/director sales.
Agree, this is a huge sale Cake Box Holdings (LON:CBOX) - no interest from me now - the shares won't go higher unless there is another significant catalyst
Paul,
Re major shareholders. On my screen (phone and laptop) there is a horizontal scroll bar just below the major shareholders information.
re £CBOX "all their eggs are not in one basket". Paul, I think you'll find their business model is built on having no eggs at all ;-). Sorry, couldn't resist.
eggs-basket?
youngsters call it x-box! :)
£DX. Delayed results, now annual report delay due to corporate governance enquiry. AGM postponed. Possible suspension of shares in January. Quite the shitshow from DX
Liberum recommendation and target price under review.
Not sure how they can put that RNS out ... and not suspend shares today.
I am half tempted to have a bit of a punt if it falls towards 15/16p. Agree we are a bit blind but the sector is a good place to be and the CEO has reiterated trading and guidance.
"Corporate governance" enquiry doesn't exactly give much away but doesn't appear business threatening either. Investors hate uncertainty as we know and there's nothing like a suspension to create uncertainty!! might be an opportunity but not one for the feint of heart or meaningful amounts.
Dx (group) (LON:DX.) - cigar butts and cardboard don't mix - but Shares mag were bullish long last week.
£DX were on my research list, thankfully I did no purchase any, about the only thing I got right i the last few months.
Yes I've been tempted to take a punt with a small amount. The way I see it if it's a complete fraud and it goes bust I'll lose the lot, but if it's a storm in a tea cup it could double. Based on the RNS and recent TU reckon the odds of a total wipeout are a lot less that 50:50 so makes sense :-)
Re Dx (group) (LON:DX.) -> might be a good punt...but I'd note that the mgt team have been very promotional and have very much talked up how they are going to make money and really push the share price. Obvs that's the name of the game...but I'm always suspicious of management that are that brazenly trying to bait PIs. I'd also note that they are extremely opaque around what the corporate governance problem is and that it can't be adequately quantified (ie not resolved but quantified!) by early Jan reporting deadline is quite concerning particularly as they started looking before the end of the financial year.
This hints to me that NED(s) in conflict with management. Its hints that there's a lack of trust and/or communication between them given last minute pulling of AGM and report...and it may hint to something quite serious that is lawbreaking (why else the strange delay and timing around AGM?). Its noteworthy that preliminary results make no mention of an issue (based on my quick scan)...this is odd and again hints at significant internal disagreement.
A more positive take that supports idea of orderly functioning of DX (but still negative) is there's been some internal whistleblowing and that's made progress slow and opaque....and maybe outside operational management's ken.
I highlight the above to caution against the reflexive comments higher up that say large share price fall equals good return opp. It might...I'm going to guess that the price continues down if no further comment. The best risk-reward trade-off is likely to be when they conclude investigation and start trading again....though that wont be the highest return potential.
This is completely blind situation so step in and buy if you can accept further (potentially total) loss
yes - I think if you take a punt you have to accept there is a non zero chance of it not coming back from suspension. It's an odd situation - potentially innocuous but potentially not.
I'm trying to work out what I think the risk/reward is. Just because it has fallen a lot doesn't necessarily make it good value though of course it might work out a decent trade. I'm half tempted if it goes to 15 or 16p but I must admit I'm a bit tetchy on pulling the trigger and it's nowhere near that level anyway atm. As you say it may be better to wait - lower return but maybe a better risk/reward.......possibly less risky things out there with close to similar reward structure too.
Looking at the previous £DX. annual report (page 36), the Audit and Risk Committee is composed of two NEDs (Paul Goodson and Ian Gray) who both joined the company in 2017 and, by invitation, the CFO. Reasonably independent but should have a good working knowledge of the business. Seems to have a relatively finite scope of responsibility although noted that KPMG are due to be replaced/stand for re-election as auditors this year and that the previous A&R report gives a clean bill of health. The unspecified “Corporate Governance” issue identified in July referred to in today’s RNS could be insignificant but the fact it’s taken 5 months or so to review and is not yet resolved (and the company must have anticipated what impact delaying the Annual Report and suggesting a suspension of the shares would have) suggests there is something of substance. Whether it’s a 40%+ of the market cap issue is moot. Interested to see if the directors fill their boots buying more shares at these levels (although probably not allowed to - after all, that might be construed as bad Corporate Governance!). Over the years, the company does seem to have had a track record of shooting itself in the foot and then recovering the situation so agree it’s possibly worth a punt at these levels for the brave/foolhardy.
Gus.
Watched an interview regarding this share, £DX , getting a heavy promotion from some fund manager, of sorts, last Christmas. It shot up after that - thinking I had missed out on the value I stopped monitoring it. Lucky escape me thinks.
It was, in fact, none other than Stephen English who chose Dx (group) (LON:DX.) as his share for 2021 (but note the prediction of embarrassment!) :
As you say Paul, the 'responding to institutional demand' story has worn more than thin! In some cases, when the selling price is very close to the current SP, then the story is perhaps a little more believable. In this case, Cake Box Holdings (LON:CBOX) the discount is well over 10%! The demand cannot have been that pressing if the institutions needed that size of sweetener. Although the sale represents 25% of the family holding, 9m shares is peanuts spread over a range of buying institutions. One would have hoped that, after the recent bullish investor presentations, the upside would be still there, but this will have taken some of the wind out of the shares for a little while.....and they may sell more in 6 months time!
There was some discussion of the Hochschild Mining (LON:HOC) situation here earlier this week. In essence, an RNS reporting the Peruvian government would require the closure of several mines, including the two owned by Hochschild Mining (LON:HOC) , its primary assets, over “ESG concerns” resulting in an initial 50% crash in the company share price followed by a partial price recovery during the day. Further RNS this morning suggesting the government has rowed back from this position and “will respect the rule of law” etc..
https://www.investegate.co.uk/...
Company suggests all is well and it’s business as usual but interested to see whether the market is quite so relaxed. Trust but verify and all that. No position.
Gus.
James Latham (LON:LTHM) interims as good as signalled. Revenue up 81% on 2020 although the truer comparison is against 2019 - which still means a 54% rise.
Lots of pandemic / supply chain issues - which in this case have flattered the figures, although that's largely to do with the management's skill in ensuring they had supply when no one else did. Normalisation of profit margins seems quite likely but they don't expect supply chains to sort themselves out until 2023. Not sure if that's a general statement or lumber specific.
In the bones of this you can see how the current problems are going to hurt less well run companies that rely on imports - supply chain issues, transport cost issues, additional inventory and working capital costs, inflationary pressures on overheads and some customers delaying projects because of difficulties obtaining other supplies. Latham's is one of the few businesses I own that is exposed to supply chain issues and I can't really see how the share price will make much progress from here.
Fantastic company, superbly managed, but probably fully if not slightly overvalued. No doubt the share price will fall sharply today :-)
timarr
£LTHM interims as good as signaled.........
Didn't the company update profit before tax to £18m for the first 4 months? How does that signal a 6 month PBT of £34m? These results seem extraordinary to me. Clearly they are 'extra-ordinary' but that's nearly 14% of the market cap. Who knows how the market reacts at the moment but I'll be surprised if the share price falls.
These results seem extraordinary to me. Clearly they are 'extra-ordinary' but that's nearly 14% of the market cap. Who knows how the market reacts at the moment but I'll be surprised if the share price falls.
They are extraordinary. They had revenue of £127m after four months, £193m after six. But markets seem to be focusing on the future rather than the past: "slightly weaker volumes compared with H1, and margins are returning to more normal levels."
Personally I'm more of a time in the market than a timing the market kind of investor and I had no idea which way the share price will go, hence the :-)
timarr
Paul, you need to get with the times. I’m sure Mulberry could outfit you with a lovely man bag.
CANACCORD GENUITY GROUP INC have increased their stake in Eenergy (LON:EAAS) to 11%
paul can you look at studio Studio Retail (LON:STU) profit downgrade was looking cheap
Would echo looking at Studio Retail (LON:STU) (I hold). From a quick skim so far it's trading at a p/e of 10 based on half year results alone! HOWEVER, the second half is predict to give adjusted PBT of £11.3m-£16.3m compared to £27.4m last year reflecting cost pressures which is a pretty significant shortfall. When I have more time after work I need to look at what those cost pressures might mean for next year results (or find a broker note!).
Hi
Here is a vid presentation of Studio Retail (LON:STU) results. I do not hold.
https://www.studioretail.group...
REgards
Howard
Studio Retail STU Hit my stop loss today and I sold all my holding in this stock
Does the profit warning from Studio Retail (LON:STU) suggest trouble ahead for N Brown (LON:BWNG)?
Mulberry (LON:MUL) was covered by TMI in their October issue. Excerpts:
Mulberry currently trades from 110 outlets around the world including 45 in the UK (17 own stores, 28 concessions in John Lewis, Harrods and House of Fraser); five own stores each in Europe and North America and 34 outlets (15 free standing, 19 concessions) in Asia.
Focus on sustainability
Anderson says Mulberry aims to manufacture 50% of its bags in the UK with the rest outsourced to suppliers in Turkey, China and Vietnam. Even in the early days Mulberry was keen to build an environmentally sustainable brand, long before such views became fashionable and management have built on that; 82% of its collection uses leather sourced from environmentally accredited tanneries, which will increase to 100% by Autumn / Winter 2022. It even has a thriving repair centre in Somerset, restoring 10,000 bags a year, plus a Mulberry Exchange buyback and re-sell program.
Gross margin: 63.6%
Net cash over £20m
However, what particularly excites me is its re-launch of the Alexa bag as part of the brand’s 50th anniversary celebrations. Staying true to much of its original design, it’s available in three sizes (mini, regular and oversized) and includes signature detailing such as the postman’s lock fastening and braided top handle.
One other reason the shares are attractive is that unlike some of its indebted rivals, it was not compelled to issue new shares during the pandemic and net cash was £11.8m as at March ’21. Since then it has sold a Paris leasehold, netting £10.8m, while it also has access to £15m revolving credit and £4m overdraft facilities and so is well funded to pursue expansion opportunities.
Mulberry is a sleeping giant in the quoted brand heritage space but amazingly no analysts cover the shares. However, its deep value hasn’t gone un-noticed by Frasers, 667p (formerly Sports Direct), which took a 36.8% stake last November. My gut feel is that when tourism recovers, sales, earnings and the share price could really going through the roof. I am a buyer ahead of that.
https://www.momentuminvestor.co.uk/index.php