Small Cap Value Report (Thu26 Jan 2023) - BOTB, SPEC, ROL, FNTL, AGFX, ANCR, AXS, EMR, FOXT, ECEL

Good morning from Paul & Graham!
Today's report is now finished.
Agenda/summaries
A huge list again today, so we're only going to be able to cherry pick a few items (Graham's unwell, so might not be able to do his sections, but says he really wants to cover them at some point, as marked below). Therefore, no reader requests today please, unless you've spotted something exceptionally good, in which case do shout!
I'll keep going until about 15:00 today, as there's so much left to look at. Update at 15:19 - all done for today!
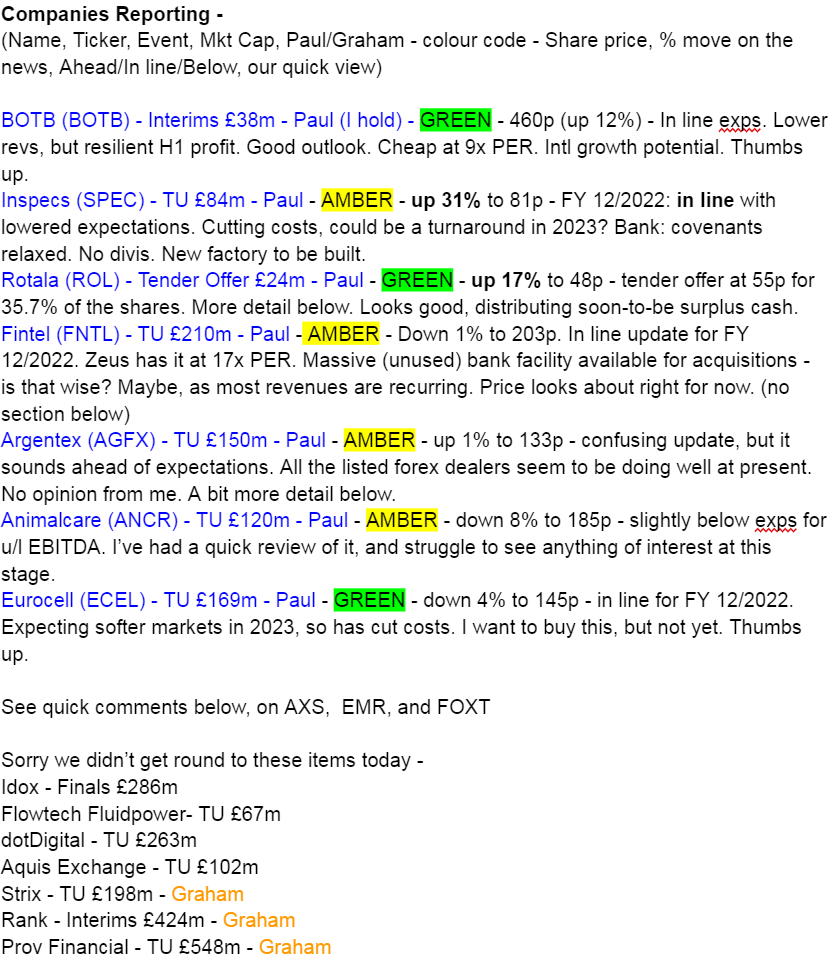
Quick comments (no sections below) -
Accsys Technologies (LON:AXS) - TU £182m - too complicated & lousy track record. But upbeat signs in today’s update - strong revenue growth, and “We remain on track for sales volumes in H2 to increase by 50% compared to H1 and, as a result, we continue to target our previously stated ambition of nearly doubling underlying EBITDA for the full year.''
So it might be worth readers taking a fresh look, possibly?
Empresaria (LON:EMR) - £29m - up 10% to 65p - FY 12/2022 results in line with exps. Net debt £7.9m, signif better than exps. Growth eased in Q4. “Some caution” for 2023, but also seeing “strong demand” in many markets, due to skills shortages. Medium term plan to double operating profit is reiterated. My view - a strange group of international staffing businesses, but it performs OK, and could be cheap maybe?
Foxtons (LON:FOXT) - £110m - down 4% to 36.6p - FY 12/2022 ahead of exps. 2023 more challenging. Net cash £12m. 65% revenues are “non-cyclical” - lettings and financial services (I would have thought fin servs is at least partly cyclical?). New CEO’s operational review says investment in people, etc, will be mostly self-funded from cost savings. Expecting a softer H1 2023 for sales, but lettings should be resilient. My view - probably priced about right for now, on 11.8x PER, but I suspect 2023 forecasts might need to come down, given macro conditions.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Eurocell (LON:ECEL)
145p (down 4%) - mkt cap £163m
Year end trading update
Main point - underlying PBT (cont.ops) in line with expectations (no footnote)
Revenue up 12% to £384m, driven by price (not volume)
Market now returning to pre-pandemic norms, after very strong demand.
Continuing to offset input cost inflation, although with a time lag in H2 (so margin pressure).
Key raw materials now stabilising, or even falling in price.
Insurance claim re cyber incident partially resolved at >£1m
Disposal - gets a £1m loss off the underlying figures into discontinued operations - smart move that means they manage to hit forecasts for continuing ops!
Outlook - industry expected to contract by 9% in 2023 (repair/maintenance, and new build), then recover in 2024. Confident they will out-perform market.
Restructured in Q4 2022, anticipating a slower 2023, stripped out £5m of costs.
Paused branch openings until outlook clearer.
Low debt, strong balance sheet (I’m pleased to confirm this is true!)
My opinion - a very nice company, but obviously 2023 is likely to see earnings dip. I’m not sure the forecasts have yet adequately allowed for this. I want to add this to my personal portfolio, for an economic recovery, but for now am holding fire with buildings supplies sector generally. This one, and Wickes (LON:WIX) are my two favourite sector picks, for purchase at a later date, hopefully cheaper!
Argentex (LON:AGFX)
TU £150m - Paul - AMBER - up 1% to 133p -
A confusing update, as it’s changing year-end. Singers note re-works the numbers helpfully, and puts through a big EPS upgrade, which seems to be reversing a previous downgrade, so I’m not sure what to make of this! Singers reckons 8.0p adj EPS for FY 12/2022, rising to 9.0p in 2023. PER looks reasonable, and if you think it will beat forecasts, then shares might be good value?
The forex dealers all seem to be doing well at the moment - will it last? Today’s update sounds thoroughly positive throughout. The business is expanding, taking on more overheads, including international expansion. The sector looks interesting, but I don’t know how to assess the prospects.
Rotala (LON:ROL)
Tender Offer £24m - Paul - GREEN - up 17% to 48p
Proposed tender offer at 55p for 18.18m shares (£10m). 34% premium price. 35.7% of total shares in issue will be bought back. Directors hold 31.8% of the company, and will tender their shares. Strangely, it’s borrowing £10m from HSBC existing facility, effectively as a bridging loan, to be repaid from the major property disposal underway. Why not just wait until the sale completes? My view - gives a nice opportunity to partially exit, at a premium price, if shareholders wish. Good that it confirms the value flagged here in the SCVR on 28 Dec 2022, at 34.5p per share, that the company would have ample cash for divis/buybacks. The tender offer gives a 59% profit on a third of the shares, not a bad trade!
Inspecs (LON:SPEC)
TU £84m - up 31% to 81p -
FY 12/2022 trading in line with lowered expectations (after bombshell profit warning in Oct 2022 smashed the share price down to c.45p).
Revenue flat vs 2021, at $246m. Revs up nearly 10% on constant currency though.
Slowdown in demand from Europe hit Q4. Other markets OK.
Cost cuts implemented.
Order book flat at $42m - doesn’t seem much, only 2 months revenues.
2022 hurt by Euro weakness, cost inflation & high freight costs.
Net bank debt up slightly to $34.1m. Bank has agreed covenant waivers to Sept 2023, indicating some financial distress, so possible dilution risk if trading get worse?
No divis for now.
Outlook - looking for more cost savings. Building a new factory in H2 2023 - is this wise?
New CEO from Dec 2022.
My opinion - none, as there’s not enough information to value this share. It’s still profitable though, with EPS of 6 US cents forecast for FY 12/2022. Could be a good turnaround in 2023 maybe? Personally, I prefer turnarounds where you don’t have to worry about bank debt, so it’s not for me, but good luck to holders.
Best Of The Best (LON:BOTB) (I hold)
430p (up 5% at 09:09) - mkt cap £36m
This is starting to look interesting again, after the pandemic boom has dissipated.
What’s interesting is that costs have been managed down, so profitability in H1 is only about 10% down on the much stronger revenues in H1 LY - revenues are down 29% on H1 LY. This is one of the advantages of an online-only services business - the overheads are completely flexible, especially marketing, which can be dialled up or down at will, with generally no forward spending commitments.
Moreover, investor sentiment generally has radically changed, from wanting growth at any price, to wanting profitability, and an unwillingness to back new funding rounds. Even the phrase “funding rounds” has always jarred with me, as it implies a complacent belief that constantly generating losses & cash burn is routine and acceptable.
BOTB has never been in that position, it’s always been a prudently managed, cash generative little business.
Key numbers for H1 (6 months to 31 Oct 2022) -
Revenues £13.7m (down 29%)
Profit before tax (PBT) £2.7m (down 11%)
Profit after tax (PAT) £2.44m (LY H1: £2.57m) - down 5% - this year flattered by a lower tax charge (see note 3, with a £185k benefit from “overprovision in prior period”). Hence we should probably normalise tax, which would reduce H1 EPS to about 23p by my calculations (based on 25% future rate of corporation tax)
EPS 27.65p (diluted) - UP 2% - note there are hardly any share options (good - mgt are rich enough already!), as undiluted (27.95p) EPS is almost the same as diluted.
Note that EPS has actually risen 2% vs H1 LY, see note 4, because the share count has dropped from 9.5m (weighted average) to 8.8m, a 6.8% reduction in share count - showing the benefit of the tender offer (a form of share buyback) last summer - I reported on the tender offer here in June 2022.
Balance sheet - NTAV has fallen to £3.7m from £8.1m 6 months earlier, due to excess cash (which had hit £10.8m) being used to fund the tender offer mentioned above. It’s a capital-light business, with negligible fixed assets, no inventories, and minimal receivables (probably just cash-in-transit through card merchant processors, I imagine). Therefore it could happily run on NAV of nil. Anything above that is a bonus, and a safety buffer in case of poor future trading. So everything is fine here.
Cashflow statement - always worth a look (many investors ignore this key financial statement). It clearly shows how the surplus cash has been returned to shareholders, with a £6.3m share repurchase, and £0.5m in divis paid. That is the essence of this business - it’s a cash generation machine, which rewards shareholders with a variety of divis, special divis, and buybacks - a long-standing and excellent track record (albeit volatile during the pandemic).
Outlook comments - which I find reassuring -
Following the normal attrition profile of the very large cohort of customers acquired during the pandemic, player numbers have now stabilised and the business is well placed for a return to steady growth…
Trading since the period end has continued in line with our expectations. BOTB is underpinned by solid financials, a large and loyal customer base, and a proven business model. We are excited by the business development opportunities resulting from the Globe Invest relationship and look forward to the future with confidence."
Globe Invest (GIL) - this is Tedi Sagi’s investment vehicle, which bought just under 30% of BOTB, and is planning on partnering to expand BOTB overseas. It all went rather quiet, so I was wondering if that growth idea had run aground?
GIL has a number of affiliated entities which have an extensive international presence covering content, digital marketing and software development sectors in particular, as well as a proven track record of growing global B2C and B2B businesses.
Today’s update says a deal has still not been finalised, but the mood music sounds positive - e.g. “current period of information sharing and close collaboration”, “great opportunity…”
Therefore we have to wait and see, but I could imagine a successful partnership deal being a lovely catalyst for a re-rating of this share. And even if this partnership falls through, the valuation is still cheap for the existing business.
There’s also the potential for a takeover bid from Tedi Sagi, if he likes the potential.
App - is now 25% of revenues. I’ve not tried this, so will give it a whirl.
Marketing costs - this is what has clobbered so many online businesses, and hurt BOTB badly in 2021 and 2022 - soaring cost of player acquisition through online marketing. Good news here, which could have read-across for all online businesses maybe? -
Customer acquisition during the Period focused on the best-performing digital channels, complemented by traditional TV media and the PR coverage generated by our winner surprises. We continue to see the benefits of our ongoing SEO marketing, with improving organic results allowing us to reduce spend on paid search to drive traffic to the website.
More recently, CPMs on Meta channels have started to return towards pre-Covid levels, allowing for more efficient player acquisition, particularly for the Midweek Lifestyle Competition where the wide-ranging prize offering is attracting a broader pool of players.
Looking ahead, a new TV commercial is launching in February 2023, a bespoke tracking and optimisation platform developed by GIL is being road-tested and we continue to explore new channels to market - TikTok in particular is a focus.
(there are too many abbreviations in today’s update, something that many companies are guilty of - they forget that investors may not know all the industry jargon. Memo to all companies - either don’t use abbreviations, or if you do, provide a prominent explanation please!)
It's interesting how Tik Tok seems to be breaking the stranglehold Facebook/Instagram had on online ads. That could benefit lots of eCommerce businesses maybe, with lower online marketing costs?
Broker update - thanks to Finncap for updating its spreadsheet - EPS is unchanged at 53.9p for FY 4/2023. It’s already done about 28p in H1, so that looks fine, the risk of a profit warning seems low to me. Although we don’t know if, and how much, cost of living pressures might impact sales of the ultimate discretionary spending?
These interims do show that even on reduced revenues, margins and profit are fine - because the cost of marketing is coming down. So I’m not worried about the consumer downturn impacting profit here.
At 53.9p adj EPS, the PER is 8.0x - that’s a bargain in my view.
My opinion - this has taken a while for me to review in detail, but I’ve been looking forward to a proper rummage through BOTB’s update. The reason is that I thought this share could be set up nicely for a decent recovery. Investor sentiment was shattered by the boom & bust pandemic performance, not helped by management banking multiple millions at £24 per share secondary placing with institutions. But that’s the past, it’s the future that should interest us.
What we currently have, is a value share, producing good profits, on a low PER of only 8.0x
The international expansion through GIL partnership (30% shareholder) is in for free, so doesn’t really matter if it falls through, there’s just upside, the way I see it.
As you can probably tell, I’m seeing the glass half full here, whilst acknowledging for others, the history might put you off.
If things work out well with GIL, this could be a nice ground floor opportunity to get a second multibagger out of BOTB shares, which worked great the first time around (if you sold during the boom). Hence I’m increasingly bullish on this share, and included it in my top 20 watchlist ideas for 2023. So far, I’m comfortable that was probably a good decision, with less guesswork & hope needed after today, as it’s confirmed that trading is OK.
Can be tricky to buy & sell though, as it’s tightly held. And as with everything, there are no guarantees the upside case will definitely happen. Something unknown could always go wrong, as with all shares.
We foolishly thought that the pandemic boom was structural growth. When it became clear it wasn't, this is what happened -
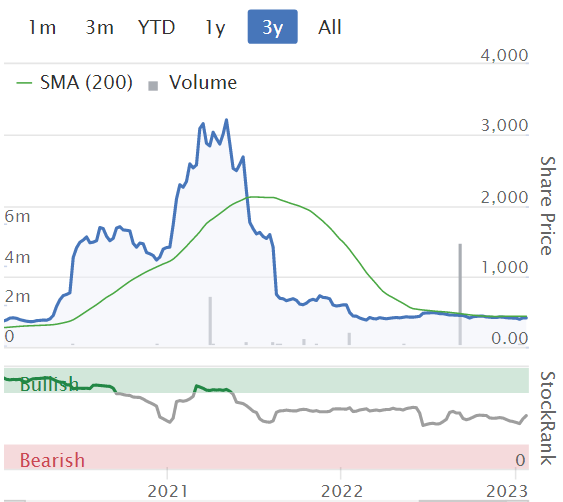
.
Note that Finncap raised forecasts significantly quite a while ago, but the market didn't seem to care -
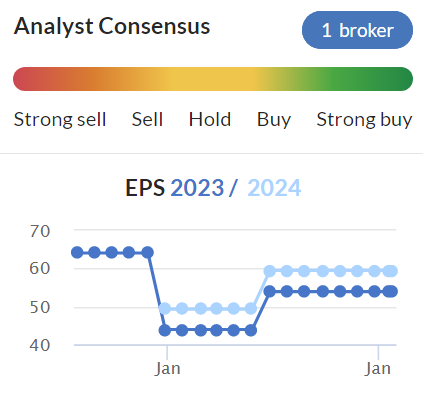
.
Note that the longer term growth trend is now becoming clear, as the pandemic boom stands out as a blip -
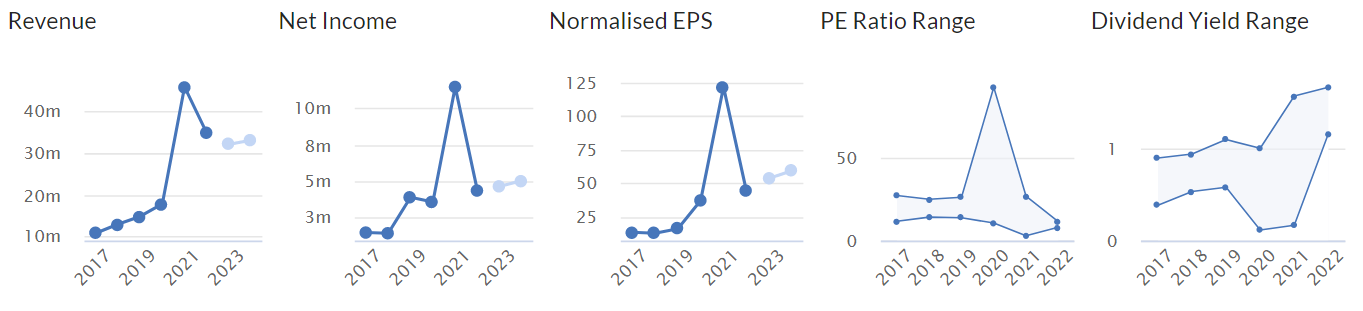
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Recently have tended to fast scroll through the SCVR, but listened to the podcast and actually peaked interest in Best Of The Best (LON:BOTB) which missed form the fast read.
So thanks for the podcast and also the "its only money" - made me feel a bit better. I suggest you sort out some stop loss rules or get a family member to manage in trust.
Got a small bet and holding in Manchester United (NYQ:MANU) - bidding closed on Friday with Saudi, Quataris and Ineos tendering so should lift the price above EV a little - a gamble no insider knowledge other than a boy who seems to listen to their podcast all day.
Great effort Paul!
Inspecs (LON:SPEC) I'm a bit confused about intended dividends from Inspecs. They approved the board to pay dividends at the last AGM and suggested that dividends were to be paid but radio silence ever since....
Paul, thanks for a brilliant effort today. Impressive.
My pleasure! Thanks for the pat on the back :-)
Seeing Machines (LON:SEE) anyone follow this one? I see the CFO has been buying regularly last few weeks - now 4,000,000 shares so he's spent £250k at around this price. I presume he has good visibility over prospects given his position. Interesting anyway.
They never SEEm to make a profit. But, yeah,, lots of director buys. Hmm…
Hi Paul, with regards to your comments on Argentex (LON:AGFX) the brokers reduced their estimates following an upbeat trading update in December which was strange but I put that down to the adjustment for the year end change, so wasn't, in reality, a change to their previous estimate. The upgrade today, I feel, catches up with what the company and CEO have been saying for a while and continue to be very bullish. (I hold)
Regards
Argentex (LON:AGFX) Trading statement today confirming that trading remained strong through end of year - some 54% increase in revenues is pretty impressive and I like their European hub expansion : being regulated in a market with gold standard guidelines certainly acts as a decent moat. Surprised they haven't really moved - in fact they are down since the trading update in December.
Net cash of £45m = 45p of the share price alone. FCF yield of 8% is good and an EV/EBITDA of sub 5 seems very low. Sitting on a fwd PE of 10. Dividends of 2.3% are helpful if not mind-blowing. Strikes me as very good value - have a small starter position.
The financials suggest there's incredible value at Argentex (LON:AGFX) but the profit margins seem excessive through the whole sector . Surely all these new FX brokers are offering a pretty undifferentiated service which should eventually lead to fierce competition and miniscule margins? Clearly the barriers to entry are not very high as both Argentex and Alpha FX have grown very rapidly from a standing start with modest capital requirements . It seems like the end state for these businesses should be 7% profit margins not 30%.
not really jesse - the market for these types of services remain 90% with the main banks and their margins are way in excess of the likes of Argentex (LON:AGFX) and have been for many years. The corporate FX market is enormous - there is room for a good number of players here. They are not competing with each other - they are competing with the banks. Barriers to entry are now quite high as to trade in Europe you need a european entity and to be regulated. This is onerous (believe me I've done it).
Margins aren't going to come under any pressure in the medium term - none of these guys are out there undercutting each other hunting for business. They are taking a small market %age away from banks who charge way higher and have little incentive to change that.
Their profit margins do look high compared to Wise (LON:WISE) which is a much larger player in this sector, Argentex (LON:AGFX) is very small, Alpha International (LON:ALPH) is around £700m mcap, Wise (LON:WISE) is over £7bn.
I use Wise (LON:WISE). Alpha International (LON:ALPH) is often one of the best dealers to buy foreign currency. Wise is good for transferring money abroad, a lot of expats use Wise, a lot cheaper using your bank.
not really in the same space but irrespective Wise (LON:WISE) trades on a PER of 43* versus Argentex (LON:AGFX) on a PER of 10 and the latter is growing more quickly and with better margins............ seems a lot more value in the latter
They don't actually compete with banks. The banks allow them to exist as the cost of running big client lists at banks is now excessive. So the banks are happy to effectively outsource the reg risk, compliance and RWA usage that comes with servicing the smaller end of the FX mkt. They still get the flow but let these little shops earn good money for the pleasure of it. Plus banks wouldn't pay the sales staff as well. Its effectively a regulatory arb business.
But a lot of retail must be going to these companies instead of their banks?
Much is done online now, so staff are not sitting in shops.
Argentex (LON:AGFX) aren't retail. Their core market are SMEs - ie businesses that need to hedge or make/receive payments in different currencies but aren't big enough to have their own treasury function. They offer a service helping these businesses manage their currency requirements at good spreads that are better than their banks will give them. Once example the CEO gives is that a customer can call up and within 3 rings will be on the phone to a person who can track their transaction. (Try doing that with your bank!). They have invested heavily in their tech so now as clients onboard they also have the ability to transact online - good spreads for the client and good margins for Argentex (LON:AGFX. There is no reason they can't offer this same online service to retail further down the line but that isn't their business.
Banks prefer large size so hawkipa's point around banks not being concerned about these guys eating a chunk of their market share is valid. Even a tiny increase in market share is very significant in revenue terms so there is no margin cutting frenzy going on to gain business.
Argentex (LON:AGFX) have global capability now (ie dealers / support across the 5.5 day * 24 hour trading period) and are actively growing their corporate clients in these locations (Holland and Australia) aside from the UK. They will start to use the regulatory passport they have from Holland to expand across Europe over time.
Thus -business opportunity remains very strong and growth can continue for a good period to come and margins are under no real pressure (there may be a bit of a race to the bottom in retail but thats not their market and the whole travel fx type business is small in comparison anyway).
The investment case for me about Argentex (LON:AGFX) specifically is the fwd PER of 10 and EV/EBITDA of sub 5. Compare that across the peer group range and they are on less than half the valuation of the others but appear to have a high quality business, regulatory approval moat and a good strategy where a lot of the investment has been done and we can see the proof of results (ie not blue sky). The valuation just looks anomalous.
Thanks, David for that information.
RE: Argentex (LON:AGFX)
As I recall (and it was a while ago) the issue I had with Argentex was that it was quite hard to scale - i.e. attracting new customers and then onboarding them was a manpower intensive task. Because of that it looked like the business would be slow to scale up and revenues might be a bit lumpy.
Is that right? Has anything changed?
Otherwise it looked like a nice business.
I hold Record (LON:REC) and Wise (LON:WISE) in the FX area but all of these businesses are very different under the covers, to the point they're not really comparable. FX and cross border payments is so inefficient and so massive (something like $15 trillion in payments in transit and therefore unusable at anyone time) that there's plenty of opportunity for everyone.
timarr
hi timarr - nope, not difficult to scale. customers increased 12% in the period : you can see the potential to scale in the 54% revenue growth. I think Argentex (LON:AGFX) has now reached a size of client base and strength of brand that scalability is not an issue at all. I suspect in the early days it was probably harder as they were having to sell the benefits, concept was newer to FDs and they lacked size. Now they've way passed that inflection point which you can see in the numbers of clients that joined in the last trading period alone.
hi timarr - nope, not difficult to scale. customers increased 12% in the period : you can see the potential to scale in the 54% revenue growth.
Thanks, will take a closer look.
timarr
I see Sosandar (LON:SOS) continues its slow and steady ride. I hold. I think the management saw a gap in the market and build s productocracy to fill it. Very interesting to watch it.
Eurocell (LON:ECEL) rather lacklustre udpate, which is probably to be expected under the circumstances. Obviously cheap on long term view, but can't see any catalyst that's going to drive any meaningful recovery in the next few months.
Paul, can you please please please have a look at Polymetal International (LON:POLY) last results and what will happen to the shares listed on LSE when the company relocate to Kazakhstan market? thank you, you are a superstar
DrMeShaker, sorry no chance today - I'm snowed under, as Graham's unwell. Also Polymetal International (LON:POLY) is above our market cap size limit at £1.3bn. But by all means post your thoughts on it here, I see it's a big faller today. Super low PER shown on the StockReport, which could be flagging problems!
Problems are most of its assets are in Russia and they're having to try to keep both Putin and the West happy. Plans are under consideration which may result in them de-listing from the LSE.
Agreed - Big de-listing potential! Why take the risk
Agreed, it's a big risk, but de-listing is far from being guaranteed to happen. The potential rewards are that they are a very profitable company which would justify a higher shareprice based upon their Kazakhstan mines alone and they have the potential to re-rate substantially if there's an improvement in the Russian/Ukranian situation. I have a small, very speculative, holding.
My main concern with POLY, and the reason I don’t currently hold, is that future growth is largely dependent on the POX2 plant which is based in Russia. Indeed, all future development sites are Russian. There are so many excellent Canadian, Australian and African gold stocks to choose from that I just don’t see the need to take the risk with POLY.
I can't argue against that. I've had quite a bit of my portfolio in Gold since 2020/21 because I doubted the story around transitory inflation, but it's taken until the last few weeks for me to get any significant benefit. I have tried to disperse the geo-political risk. There are very few countries where miners operate that are without risk, even in places that might not seem that unstable - take for example the recent social unrest around mining in the likes of Chile and Peru. For example, I agree with your assessment of Shanta Gold (LON:SHG) and they're one of my largest holdings in gold miners, but Tanzania has its own poor history in this area too so I wouldn't want all my eggs in that one basket. So I wouldn't necessarily advise anyone else to go for Polymetal International (LON:POLY) I've just chosen to have a wee dabble myself.
Agree entirely, I hold 3 gold miners just now to try and balance risk across the board, Newmont, Minera Alamos & Shanta.
Newmont is the biggest one in the game, the other two have re-rating potential as they move from explorer / juniors into mid tier miners.
Barrick Gold (NYQ:GOLD) (balanced superstock) tracks Newmont (NYQ:NEM) and hold as opposed to an ETF.
Shanta Gold (LON:SHG) as stocko says speculative so for you braver souls. Agree 12p technical resistance.
Hi DrMeShaker, I posted a quick thought on this yesterday elsewhere…
Disappointingly high AISC was stated imo. I don’t currently hold but watching with interest. Newmont is still a preferred option in this space imo owing to lower AISC and reduced jurisdictional risk.
As an add on to that, Shanta Gold (LON:SHG) is worth a look if you like gold miners, excellent fundamentals, lower AISC than POLY and currently threatening a breakout from the 12p pivot point. (I hold)
thanks for your thought Forbsy.
I was planning to sell my Anglo Asian this morning but not sure where to put the money . Gold is on the bull run. Frenillo and Centamin were on my mind.
I hold Shanta Gold. Tamesis has a 30p price target (2.5x current price). If management plans play out then the share does not look expensive.
The key bull story at the moment is that the Singida mine (32k oz pa) is due to come on stream in March 2023. This will move Singida from being a considerable cash drain to the company to a cash contributor. It will also diversify risk from what is currently a single (c70k oz) New Luika mine. Therefore, 2023 FCF and profits should be completely different than 2022 and recent years.
Shanta’s 3rd project (West Kenya) is coming out with encouraging data but it is difficult to put a value on it (although the brokers do) until a feasibility study is produced. And if West Kenya is developed it will require hefty financing.
The main negatives are, as I see them:
* The New Luika mine’s life only goes out to 2028, currently. Mine life has been regularly extended over recent years with new drilling adding back reserves. So management saya that the short official mine life should not be a concern.
* But grades have fallen sharply over the last couple of years and new reserves added are generally lower grades - leading to upward pressure on AISC at New Luika
* Production out of New Luika has been below original guidance in the last couple of years (largely because of lower grades).
* There was 3 possible bidders for the company a few months ago - two of which as Chinese miners (Shandong and Yintai) were cash bidders. But the bidders quickly walked away, with management saying that they would not accept low-ball bids. Why neither would bid at a level Shanta would see as acceptable, remains a question mark.
Always good to hear from other holders. Agree with all your points, there is always risk with gold miners…. weighing up the risk / reward is for individuals to gauge where they’re comfortable.
The note below from Hardman is from a year or two ago but it’s still relevant to current outlook, worth reviewing for anyone looking into Shanta Gold (LON:SHG) as a potential investment. My current holding is from 7-9p area so I’m happy to stand pat for now. I previously traded the rise from 7-20p a few years back so looking for something similar or better this time too.
http://hardmanandco.com/wp-con...
I'd actually missed the RNS from SHG this morning, this looks excellent and appears to be the start of a positive news flow period.
Yes. Good posts. I hold and added more this week. Not breaking pasts 12p at the third attempt in recent months. Waiting to see what news comes in March. Yeah, the bids situation was weird.
Rotala (LON:ROL) Fabulous announcement for those who own these. Tender offer for 35% of your holding at 55p, financed by a £10m loan.
Why are they doing this?
That's what I'm scratching my head over. I hold and will probably take the offer from Rotala (LON:ROL) to the extent I can. But I don't see why they are doing it.
They are expecting quite a significant cash flow from the enforced sale of most of their assets (depot & buses) supporting their service in Greater Manchester and say they have no large scale capital investment requirements this year, but still they're not debt free.
Looks like most large shareholders aren't taking it, so will increase their percentage shareholding.
Looks like one large shareholder want to reduce his holding whilst the largest shareholders are happy to increase their holding, at the same time handing back some cash. On balance all looks reasonable to me, shareholders are being offered a good bid in an otherwise illiquid share , but those wishing to hold have the assurance that the largest holders are increasing their % of the company.
Looks fair and a win/win to me.
Or is it a takeover in disguise ?
Diaceutics (LON:DXRX)
Morning Paul and Graham - would be interested if you might have a look.
Opened a position a couple of months ago. Like the picks and shovels of Life Science / software as not so reliant on drug approval and structural growth. Liked the high growth and GM of 80% or more and large director holdings and net cash of £19m. Also moving to a platform and subscription based model. Impressive clients. SP had halved from peak.
Today's FY update: "Strong trading performance in 2022, with revenue materially ahead of market expectations."
Revenues increased 44% to approximately £20.0 million (2021: £13.9 million), 29% at constant currency, materially ahead of market expectations² - RNS details market expectations in RNS :)
EBITDA in line as investing for growth. Cash £19.8m (£19.7m) No debt.
Improved visibility of future revenue with growth in order book value at 31 December 2022 to approximately £15.6 million (31 December 2021: £1.75 million), with approximately £9.9 million of the order book expected to be realised in 2023.
There was also a 2nd RNS this morning reporting 2 seemingly additional contracts worth $7m over 2 years with 2 top 10 global pharma - subscription platform contracts.
A strategic update is also announced to accelerate investment to fully capitalise on momentum.
I have an opening position.
Investegate |Diaceutics PLC Announcements | Diaceutics PLC: USD 7m enterprise engagements for data services
Investegate |Diaceutics PLC Announcements | Diaceutics PLC: Trading Statement and Strategy Update
Record (LON:REC). Q3 update today. Price has been firm lately but has market fully appreciated the impact of the new interest rate environment on this business?
Last year it generated just £0.5m in performance fees. In the first 9 months of the current year that's moved up to £5.8m (total revenue last year: £35m) - attributable to "increases in interest rate differentials".
These performance fees were previously very sporadic but now they report they've generated them 4 quarters in a row, and this seems sustainable so long as interest rates don't revert back to near zero.
Performance fees will be higher margin.
RE: Record (LON:REC)
Price has been firm lately but has market fully appreciated the impact of the new interest rate environment on this business?
To put this in perspective, IG group (LON:IGG) update today states:
Net interest income of £24.2 million (H1 FY22: £(0.4) million) rose significantly across all businesses, reflecting higher interest rates and continued high levels of client money.
Obviously not all businesses will see their interest income rise by a factor of 60, but for the investment platforms holding client monies this may make a significant difference in their revenues.
timarr
If we are talking about interest earned on client money, platforms pass this interest back to clients so their net retention will be minimal. It’s not really revenue in the proper sense of the word?
The performance fees at Record aren't about the company earning interest on cash as such. It's about the "carry trade" whereby clients buy a currency with high rates funded by selling a currency with low rates. Years ago it generated fantastic returns at Record, but the dramatic fall in rates killed the trade - it now seems to be back on.
Pleased with the update from Time Finance (LON:TIME) today. Now up +10% so far, and IMO further to run. There's a profit upgrade for the FY ending May23, quite substantial, at least a +14% vs broker forecasts.
They're successfully executing their strategy of increasing their own-book lending (+27%) instead of syndicating the loans off to third parties. Their visibility of future earnings ("unearned income") is up +32%, which provides the momentum for future half years from today's HY results to Sep22.
Furthermore, my key worry that their SME customer base would start to feel the economic stress, and start seeing higher bad debt, has been nullified. % of debt is arrears have actually gone down YoY. No warning that this has started to creep up in the last few months since Sep22, so presume it has held steady or further decreased even.
PBT for the HY was £2.0m. They guide a FY PBT upgrade from £2.8m to £3.2m, but even this seems low? I need to go through the numbers in detail to see what's included in the £2m HY PBT. The market cap is currently only £20.8m, which is a bargain as FY24 will see continued increased revenues, already baked in due to the rise of "unearned income" from their loan book.
NTAV at £32.1m, 34.7p per share, is the icing on the cake. Provides downside protection. I get that financial companies often trade below P/B value, even the large banks. But even if we take 70% as an acceptable P/B ratio for a growing company (really, it should be at a premium to P/B), I get a very conservative valuation of 24.3p, which is still higher than the current share price.
Not many negatives to take from today's update. Except, of course, that the great economic squeeze is happening at the moment, and for sure SMEs are being squeezed. I don't expect the bad debt rate to continue to be low; but then I expect Net Interest Margin to increase, and should cancel out the rise in bad debt. Also, their lending is in the secured space; mainly against asset financing and invoice financing, I believe.
The only other negative is whether they have compromised credit quality to rapidly increase their loan book. I think not, because they're just changing their business model; rather than syndicate the majority of loans like they did before, they're now holding them onto their own lending book. I need to dig into total origination volumes over the last few years to make a call on this.
(I hold in the Boon Fund)
Does anyone know why Beeks Financial Cloud (LON:BKS) has suddenly shot up this morning? No RNS and all quiet until 9am and since then up almost 10%. I hold.
I was about to post the same on Beeks Financial Cloud (LON:BKS) and a little annoyed as I have taken profits on some ridiculously fast small cap gains these last few weeks (saga, Smiths news, jds Inspecs today to name but a few all some 50-100% up) and BKS was on the list to look more into. Very hard to buy , haven't been able to get a quote all morning until now at 142p so just added. The fund raise last April was higher at something like 165p and it looked last year that there was a consistent trading range from 140p-200p or so maybe it is finding this again! Hopefully some contract news on the pipeline and positive update coming soon. Will continue to scour around.
Fun
Yes there was a TU on 02/02/22 last year for Beeks Financial Cloud (LON:BKS) so looks like we might get positive news next week.
Looks like it was tipped by Regency Capital, could have kickstarted the jump.
Would really welcome your take on Best Of The Best (LON:BOTB) this morning Paul. I only had time for a quick read before work but it looked like profitability had significantly improved even if revenue is again lower on H2 22. I've decided to start a position this morning.
The one thing I am cautious about is the relationship with GIL if they charge some kind of fee which undermines margins. I am surprised there's still insufficient detail about that.
Morning Patrick!
You don't have to ever request BOTB (I hold), I always look at it!!!
It's one of my top 20 watchlist picks for 2023. So nice to see a reassuring update today.
Full section is now up, above.
Regards, Paul.
My morning smallcap tweet: Sure bets and night-time sweats. A record 29 companies.
Fintel (LON:FNTL) Animalcare (LON:ANCR) Renalytix (LON:RENX) Time Out (LON:TMO) Hemogenyx Pharmaceuticals (LON:HEMO) LSL Property Services (LON:LSL) Ilika (LON:IKA) Proton Motor Power Systems (LON:PPS) Parity (LON:PTY) Learning Technologies (LON:LTG) Eurocell (LON:ECEL) Empresaria (LON:EMR) Foxtons (LON:FOXT) Diaceutics (LON:DXRX) Rotala (LON:ROL) Hansard Global (LON:HSD) Argentex (LON:AGFX) Time Finance (LON:TIME), Velocys (LON:VLS), Novacyt SA (LON:NCYT), Skillcast (LON:SKL), dotDigital (LON:DOTD), Flowtech Fluidpower (LON:FLO), Just (LON:JUST), Tclarke (LON:CTO), Strix (LON:KETL), Inspecs (LON:SPEC), Aquis Exchange (LON:AQX), Best Of The Best (LON:BOTB)
◄Fintel (FNTL)► guides FY-Dec core rev up c.8%. Adj EBITDA up 6%, in line with mgmt exp. Outlook in line. [SP=206.75 Cap=214m]
◄Animalcare (ANCR)► guides FY-Dec rev down 3%. U/L EBITDA approximately in line with market expectations. Blames macro. [SP=200 Cap=120m]
◄Renalytix (RENX)► co and its partners get $10m Horizon Europe grant to validate and implement in clinical practice, novel biomarker-based tests that predict response to existing drugs used by patients with chronic kidney disease. 10% of the budget targeted for commercial translation activities to be undertaken by Renalytix. [SP=117.5 Cap=103m]
◄Time Out (TMO)► to open Time Out Market in Barcelona in H2 2024. [SP=34 Cap=114m]
◄Hemogenyx Pharmaceuticals (HEMO)► £4m placing at 2.5p, a 17% discount (not mentioned natch'), for clinical trials and continue development of product candidates for the treatment of viral infections based on its Chimeric Bait Receptor, ie to continue its business. [SP=3.08 Cap=30m]
◄LSL Property Services (LSL)► sells London Estate Agent Marsh & Parsons for £29m as it simplifies the group. Well, you could sell everything and make it very simple. Considering investment and shareholder distribution options. [SP=267 Cap=278m]
◄Ilika (IKA)► the grant addicted cash pit to get £2.8m in grant over 2 yrs to lead Faraday Battery Challenge and to integrate high silicon content electrodes into its Goliath solid-state batteries. [SP=49 Cap=77m]
◄Proton Motor Power Systems (PPS)► order from UMSTRO for 18 "HyModule S8" hydrogen fuel cell systems for delivery throughout 2023 and into 2024. No £££. [SP=12.49 Cap=194m]
◄Parity (PTY)► guides FY-Dec Net Fee Income down 15% ad adj EBITDA £0.4m (£0.1m). Significant improvement in operating performance with anticipated break even adj op profit. In line? [SP=7 Cap=7m]
◄Learning Technologies (LTG)► guides FY-Dec rev £595m+ and adj EBIT £100m+, both ahead of consensus expectations. Confident. [SP=121.72 Cap=961m]. I hold.
◄Eurocell (ECEL)► guides FY-Dec rev up 12%. U/L pretax in line. Partially resolved its cyber insurance claim and expect to recognise compensation over £1m. Outlook "In anticipation of weaker markets in 2023, we completed a restructuring programme in Q4 2022, which along with other cost saving measures, will reduce operating costs by approximately £5m PA from the start of 2023. A charge of c.£2m will be included as a non-underlying item in 2022". [SP=150 Cap=168m]
◄Empresaria (EMR)► guides FY-Dec pretax in line, debt significantly better than market expectations. [SP=60 Cap=30m]
◄Foxtons (FOXT)► guides FY-Dec rev c.£140m up 11%, ahead of market expectations. Adj op profit also ahead of market expectations. Outlook "H1 2023 to be more challenging". [SP=38 Cap=115m]
◄Diaceutics (DXRX)► guides FY-Dec rev up 44%, materially ahead of market expectations. EBITDA in line. Exp are rev £16.3-16.8m and EBITDA £3.4-3.6m. [SP=78.05 Cap=66m]
◄Rotala (ROL)► 55p tender offer, a 34% premium for up to 18m shares. [SP=41.75 Cap=21m]
◄Hansard Global (HSD)► warns H1-Dec new biz down 33%. "Environment has remained challenging for investment and long-term savings plans. However, we continue to make good progress developing new product and distribution opportunities." [SP=41 Cap=56m]
◄Argentex (AGFX)► strong, in line? [SP=132.14 Cap=150m]
◄Time Finance (TIME)► H1. Guides FY significantly ahead of market expectations. [SP=20.5 Cap=19m]
In line: VLS, NCYT, SKL, DOTD, FLO, JUST, CTO, KETL, SPEC, AQX, BOTB
Wow Mr C! How do you do it?! Is speed reading a natural ability you have or have you ‘trained’ or done a course? Asking for a friend ;)
It didn't come naturally. I was a pretty pedestrian reader so I learnt. I can do RNSs even faster because I read so many.
Paul and Graham, if you get a chance can you comment on dotDigital (LON:DOTD) and Argentex (LON:AGFX) both of which have provided trading updates. The former is in-line and seems a stable well run business, but sometimes an in-line gets treated like a warning in todays markets. AGFX seem to reiterate previously notified exceed expectations and is in a hot (fashionable) sector. I hold both and see no reason to sell but interested in other opinions. If there is more exciting stuff today not a problem if you don't get to them.
Best wishes.
Greyster
Sorry Greyster, I won't have time to get to the "in line" updates today, as short-staffed, so just focusing on price-moving announcements today.
No problem Paul, I understand the need to focus on movers when short staffed.
G
£KETL / Strix (LON:KETL) - The pre-close trading update for FY22 is evidence of a business determined to deliver. The focus is now on revenue generation and shorter investment payback periods. Two factors proved disruptive to activity levels in FY22; the war in Ukraine and lockdowns across China to prevent the spread of Covid-19. Although the former looks set to continue indefinitely, the re-opening of the Chinese economy represents a positive factor for FY23 onwards.
Cash levels will be boosted as the supply chain relaxes post-lockdowns, enabling the Group to reduce inventory levels, and marketing expenditure is likely to decline. Billi is integrating well into the Group following its acquisition in December, with new products launched and distributors appointed in Asia. We have left estimates unchanged for FY23 and FY24.
We reduced our dividend estimates in early December, reflecting the level of indebtedness but this still suggests a highly attractive yield of 7% for FY22, rising to 7.6% in FY23. We have left those estimates unchanged, as the c.£23m guidance for PAT and consider it too early in the year to revisit FY23 and FY24 estimates. Our net debt estimates are higher than the recent £89m guidance, although c.80% of the difference reflects the payment of deferred consideration to LAICA switching to February ’23.
Although the share price is off the lows recorded in late 2022, there remains a significant gap between the current share price and our fair value - the combination of our DCF & peer group comparison models suggest a fair value / per share of 234p, materially above yesterday's closing price.
Link to note & audio summary here: https://www.equitydevelopment....
I wonder if this morning's RNS from Strix (LON:KETL) means the final dividend will be lowered or cut? Aside from that, this morning's announcement suggests the company is responding to concerns about excessive acquisitions and capex leading to uncomfortable debt.
For now I see Strix (LON:KETL) as a hold.
I'd say the dividend is almost certainly going to be cut.
I bought some post the last profits warning and sold out ahead of the trading update for a bit of a profit as I was suspicious that forecasts could be lowered again, particularly as China went from zero to infinity on Covid and I had no clue what the impact on demand would be, which made me nervous.
The other thing that made me trigger happy was the debt. It's way too much and it seems that management have come round to the same conclusion and are now focused on paying it down as rapidly as possible. For me that should entail eliminating the dividend (but I doubt they will) and let all FCF repay debt. Combinations of high debt, new material acquisitions to integrate and investment in capacity have a propensity to blow up and cause problems.
I suspect though that if Strix (LON:KETL) drifts back a little it may be a good time to take a starter position for me as normality resuming in China should give them some tailwinds, but that is all caveated on wanting to see debt re-paid rapidly
Results out from IG group (LON:IGG) today, I hold. A bit lacklustre but on track to meet forecast. Priced about right, I think.
Maybe Graham likes to comment on IG as it is his 3rd largest holding!
I am a holder for many years.
Hi Graham, if you do get a chance to review IG group (LON:IGG) later in the week that would be good. One thing that puzzles me is that they seem to have up'd goodwill by £20m+ due to exchange rate differences, which does seem to be a bit of sleight of hand and about 5% of the PBT for the half year.
PS I hold.
Good morning Paul,
Although I have many times criticised your investment ideas I have to say a big thank you to you now on introducing to us Rotala plc and its potential value.
Keep up the good work.
Morning yiannos1,
What a nice message, thank you!
Yes, Graham & I have been finding all sorts of bargains in recent months, rich pickings at the moment!
Although avoiding the banana skins is tricky now that a lot of outlook statements are sounding more cautious.
Glad you did well on Rotala. I was thinking about buying some myself, but didn't unfortunately! Never mind.
Best wishes, Paul.