Small Cap Value Report (Thu 26 Oct 2023) - SCS, VLX, IPF, BMY, AGFX

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
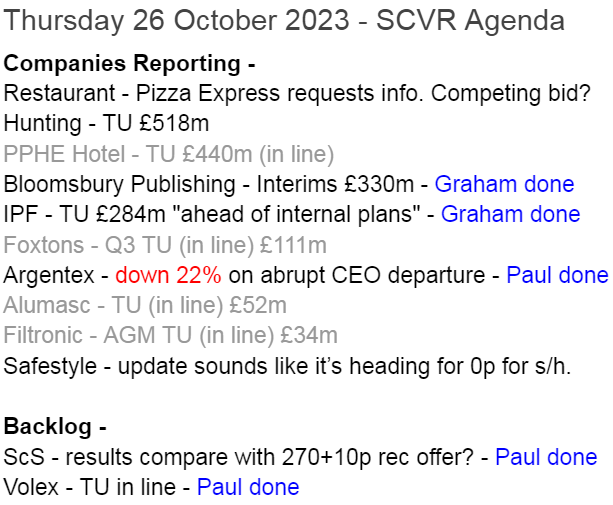
Summaries
SCS (LON:SCS) - 270p (£92m) - Preliminary Results FY 7/2023 - Paul holds - GREEN
I suspect the undisturbed share price (ie. if no takeover bid at 270p +10p divi) would have probably dipped from about 160p to maybe 150p on this update? That's because profit is down about 33%, and the outlook comments indicate a softening order intake recently. Hence shareholders are currently being offered a fairly attractive price relative to what it might have been without a bid. On balance I think the 270p+10p offer looks reasonably fair, given tough macro. Holders (including institutions) may hold out for more, but then run the risk of the deal falling through. Your money, your choice as to what to do if you hold.
Volex (LON:VLX) - up 1% to 285p y’day (£517m) - H1 Trading Update - Paul holds - GREEN
Another in line update, with customer destocking offset by good growth in other parts of the business. So much to like here - a successful business, growing strongly through a seemingly well-executed acquisition strategy, all for a PER of only about 10. I remain a firm fan of this share.
International Personal Finance (LON:IPF) - down 0.2% to 127.7p (£286m) - Trading update (ahead) - Graham - GREEN
This international group offering home credit, credit cards and online loans continues to perform “ahead of internal plans”. I remain impressed by its improving profitability and intrigued by the cheap valuation on offer, despite good share price performance in 2023.
Bloomsbury Publishing (LON:BMY) - unchanged at 404p (£330m) - Interim Results (in line) - Graham - GREEN
Solid interim results from this publisher which sells into both the consumer and the academic/professional markets. It has big ambitions to grow its “Digital Resources” business and is now less geared towards H2/Christmas seasonality. Appears to be a quality outfit.
Argentex (LON:AGFX) - down 22% to 75p (at 12:39) £85m - Board Change - Paul - AMBER
A sharp downward move today, on news of the abrupt departure and replacement of the CEO (and 12% shareholder). It's not clear what has happened. I quickly review the last interim numbers, which weren't bad, but sounded a bit wobbly on outlook. I'm guessing it might be limbering up for another profit warning perhaps? Too opaque at present, so I'll sit on the fence with AMBER. It's also not a sector I'm interested in owning either.
Paul’s Section:
SCS (LON:SCS) (Paul holds)
270p (£92m) - Preliminary Results FY 7/2023 - Paul - GREEN
Obviously we had the huge news this week, of an agreed (by mgt, but not shareholders) 270p takeover bid (plus 10p divi) from an Italian trade buyer, for this furniture retailer.
Allow me a moment to wallow in the glory here, as we’ve been saying here for as long as I can remember that SCS was a sitting duck for a buyer. That's because the favourable working capital dynamics of furniture retailing means that they sit on a whacking great cash pile, which continuously rotates (with some fluctuations), which could easily be stripped out and used for other purposes, and replaced with a seasonal overdraft. Which is exactly what larger competitor DFS has done for years. Amazingly, I even made a video about this, comparing the balance sheets of DFS and SCS, showing the obvious value sitting on a plate, ready for extraction, at SCS, but it’s buried somewhere in youtube and I cannot find it. Post a link if you can resuscitate it, as I want to look smug for a brief moment, to offset all the things I get wrong! (which is how small caps work).
At this stage, all that matters is - how much is the company worth based on the fundamentals and outlook, and how does that compare to the quick exit price of 270p + 10p divi? (takeover bid, or market sale). It’s a simple choice, and of course small investors have the luxury of being able to sell some or all in the open market immediately. I like selling half sometimes, to keep my options open, in bid situations, and to claim victory irrespective of the final outcome!
Others have pointed out that the bid announcement didn’t seem to have any declared support from institutions, and mgt shareholdings are shockingly trivial, especially galling given their greed with excessive remuneration (for lacklustre performance I’d say).
One investor pointed out to me that any bidder would have a c.10% instant boost to profit by clearing out overpaid management - a point that is backed up by the figures, so difficult to argue with. Do they think they’re running Marks & Spencer or something?!
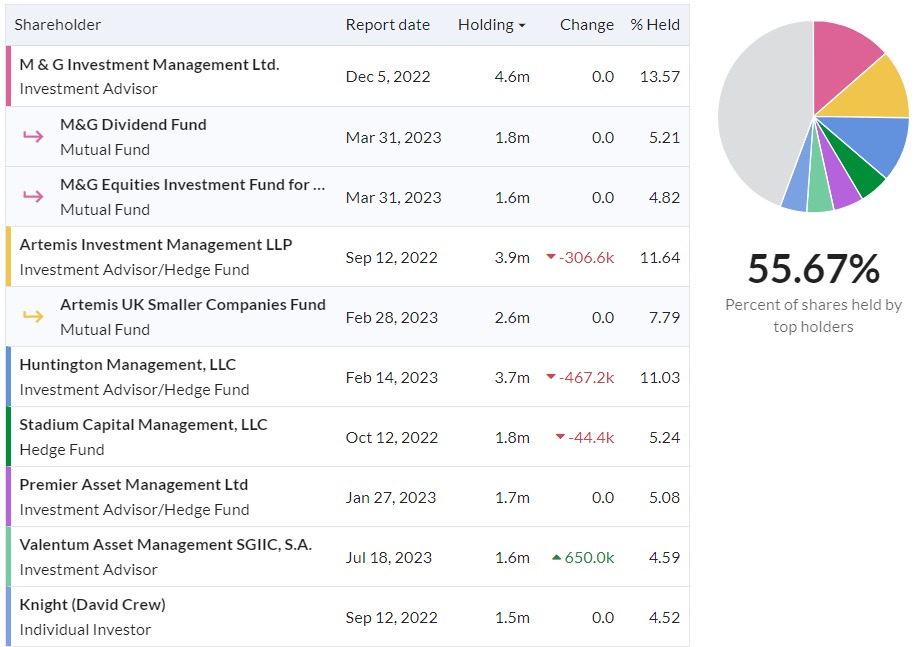
Shareholding structure matters most in takeovers. Here (below) we can see there are 3 significant institutions, who don’t seem to have backed the deal publicly anyway. Although I doubt mgt would have recommended the deal without at least tacit agreement from major shareholders.
Is this a case where the 270p deal (+10p divi that people would have got anyway, so it’s not really part of the takeover price) is out there in the open now, and institutions might be hoping for a higher competing bid? Quite possibly I’d say, although SCS might be too small to attract much interest from private equity, other than niche players? Who knows? It’s all exciting guesswork at this stage.
The danger of course is that if shareholders reject the takeover deal, then the share price could crash, and never recover - as happened with the rejected Stonegate offer for Revolution Bars of course at over 200p, which is seared on my memory, and has now lost over 98% of that price, years later. So sometimes it can be a big mistake to reject a takeover deal.
The other question is whether the Italian trade buyer can be persuaded to sweeten the offer, given that everyone knows it’s paying for a lot of the deal using SCS’s own cash pile, something I’ve been shouting about for years! (you do start to doubt your own sanity sometimes with things like this, when nothing happens for years).
OK, that’s the background. Now it’s time to erase our memories, like they did on Blakes 7 when dealing with alien species rather than UK small cap takeover bids, and look at the numbers afresh, pretending that there hasn’t been a bid. How would the market have reacted to these numbers, if the share price had been at an undisturbed pre-takeover bid 160p?
ScS, one of the UK's largest retailers of upholstered furniture and floorings, is pleased to announce its audited preliminary results for the 52 weeks ended 29 July 2023.
Good that the numbers are audited (as expected).
It splits out the losses from a small acquisition (called Snug), so underlying numbers are most relevant, with £9.2m underlying PBT for FY 7/2023, down 33% on LY (FY 7/2022).
That’s not bad, given how tough macro, and consumer sentiment is, and SCS’s mkt cap is only £92m.
Share buyback of £7m completed, so the share count has now fallen a lot since 2019.
Balance sheet - a key point, as we’ve discussed here many, many times!
NAV is £46m. Take off £4m intangible assets, and NTAV is £42m - good, but under half the £92m market cap now.
Lease entries suggest it has an issue with some loss-making sites: RoU asset £89m, liabilities of £101m. Actually that’s not too bad, so not a big worry.
Cash pile of £69.5m, with no interest-bearing debt. At 76% of the market cap, this is enormous! As I've always, correctly, said, a bidder could remove this cash and use it to repay bridging finance, and that would pay for most of the purchase cost of buying SCS, using SCS’s own cash! If the buyer is soundly financed, it would have no trouble then arranging some debt on top of that, similar to what DFS has done with its own balance sheet, and hey presto, anyone with a decent credit history could buy SCS for nothing! It’s bonkers really.
All of this only unravels if credit dries up - which is exactly what happened in 2008, when SCS went bust. I looked back at the numbers, and was shocked to discover that SCS looked healthy in 2007. But when the banks withdrew credit, its favourable working capital cycle literally froze, and it went bust. Something to remember, if you invest in any company that relies on customers paying before creditors have to be paid. We saw an inkling of this this week with Mission (LON:TMG) actually, when its net debt shot up because customers have stopped being generous with up-front cash payments - no doubt because customers CFOs are saying, hang on I can earn 4% on that cash, stop throwing it around like confetti to our suppliers.
This is why you need to really look hard at all parts of balance sheets, not just the year end probably window-dressed numbers.
Bottom line though with SCS, is that I reckon its cash pile is likely to be pretty safe, and it’s c.£70m. That could, and maybe will, pay for most of the £92m acquisition price, and the Italians could then slap on a £30m overdraft, and they’re laughing all the way to the Trevi Fountain! They’ve bought SCS for nothing!!
This is no revelation, hence why I suppose SCS’s institutions don’t want to back this deal. They probably want something better to come along, and it might. Or it might not.
Outlook - cash fell from £70m to £57m at end Oct 2023.
Also note apparently slowing demand recently.
Although this can be fine-tuned with marketing spend, which reaches a crescendo around Boxing Day of course, as we oscillate between egg nog, James Bond, Mary Poppins, and dreaming of how much better social housing might look internally with a new SCS sofa at unbelievable never to be repeated, half price offers that they do most of the time.
I’m only pulling your leg! Some of these designs actually look quite nice, and prices low enough to see a new sofa as a regular, not big-ticket purchase maybe?
Paul’s opinion - tricky one isn’t it! We all knew the prevailing 160p share price was absurdly cheap, but it pertained for a long period of time. This is due to a structural mis-pricing of UK small caps currently - it’s more about supply and demand for the shares, than the value of the companies.
Meanwhile, private equity and trade buyers, are picking off the ones they want, at premium prices. This is a fabulous opportunity for stock pickers. I cannot remember ever seeing anything like it actually, in my 25+ years in the small caps market.
Stockopedia subscribers can discuss in the reader comments what you want to do, and how to make your own buy/sell decisions - sell now for a bankable profit, or hold for an improved offer? (but risking that it falls through).
I reckon that SCS shares probably would have fallen a little, to about 150p, on today’s wobbly outlook comments, if there had not been a takeover bid.
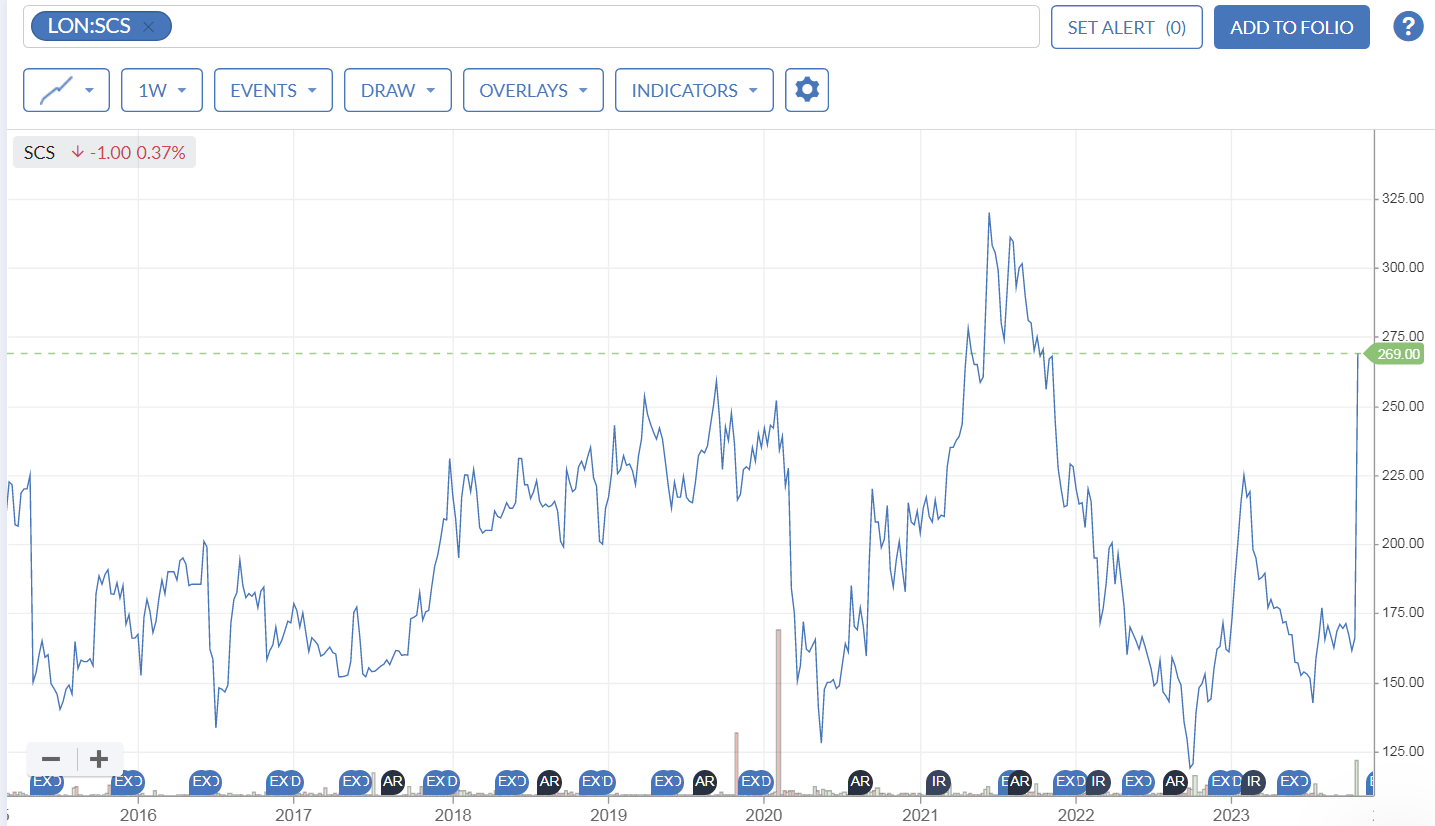
So the 270p takeover bid is offering you the chance to bank a fat profit compared with a depressed market valuation. Of course we can all see that longer term SCS is worth more than 270p, but maybe not that much more I'd say. It only peaked just over 300p in a roaring bull market in 2021.
On balance then, I’m inclined to sell my own very small SCS shareholding, and recycle the money into any number of other ludicrously cheap shares. Then we get a double benefit.
Or, we could sit and wait for an improved offer on SCS, which may happen.
Selling half also sounds a sensible option to me.
Let me know what you think!
Volex (LON:VLX) (Paul holds)
Up 1% to 285p y’day (£517m) - H1 Trading Update - Paul - GREEN
Volex (AIM: VLX), the specialist integrated manufacturer of critical power and data transmission products, today issues an update on trading for the 26 weeks ending 1 October 2023 (the "Period" or "H1") and the cyber security incident announced on 9 October 2023.
This is one of many small-mid caps that tends to drift down between announcements, as people worry about macro impact on its trading. Then we get in line updates each time. It’s the same this week, we’re reassured -
The Group continues to maintain strong financial momentum and is well positioned to achieve full-year results in line with market expectations1,2…
2. The Company has compiled forecasts from four analysts with current market forecasts for the 52 weeks ending 31 March 2024 for revenue to be in the range of $849.8 million to $891.0 million, with a consensus of $864.6 million, and for underlying operating profit to be in the range of $82.3 million to $87.0 million, with a consensus of $84.3 million.
Excellent, very clear reporting there. Hats off to owner/manager Nat Rothschild for building a significant sized, and decently profitable group here.
Remember that Volex was quite a mess years ago. I can remember being initially sceptical about its turnaround, but then turning positive on it possibly around 2019 from memory, when the figures really began to strongly improve.
Since then, Volex has been absolutely transformed through a turnaround, and it seems an effective, value-building, disciplined (not over-paying) bolt-on acquisitions strategy.
Revenue growth in H1 of 4% is quite modest, but that’s organic, and against a strong comparative.
Customer de-stocking is mentioned, an important point of general read-across that I’ve spotted other companies mention too - higher interest rates mean that companies generally want to reduce cash tied up in receivables and inventories. Improving supply chains also mean that companies feel safer to run down inventories back to more normal levels.
I’m impressed that Volex seems to have been able to ride out and offset this destocking -
This has been more than offset by strong demand in Medical and Complex Industrial Technology supported by better availability of key components. There is evidence of de-stocking slowing in some channels, as order patterns are starting to normalise, particularly in Electric Vehicles.
Major recent acquisition $195m - of Murat Ticaret - positive-sounding comments on this. It will contribute 7 months to the P&L for FY 3/2024.
Debt - “covenant leverage” of 1.3x looks fine to me, and would only become an issue if trading fell off a cliff. Also I cannot imagine that the owner/manager called Rothschild would have a lot of trouble arranging bank facilities!
Cyber incident - we have to trust management on these things, but I don’t see (or even hear) any alarm bells ringing here -
… there is not expected to be any material adverse impact to revenue or underlying operating profit as a result of the incident. Costs for the recovery and remediation of systems are anticipated to be approximately $2 million, which will be reported as an exceptional item in the second half of the year.
Hopefully they’ll now have bulletproof IT protection going forwards, as far as it can be done.
Outlook - most companies are sensibly sounding cautious in their outlook statements, given all the macro trouble, and risk.
Volex sound pretty upbeat to me, and I trust what management say here, as their track record is good. Also, well-chosen acquisitions can be a nice way to mop up any shortfalls in performance elsewhere - so rising debt needs to be considered against rising earnings.
I like that Volex has a good spread of sector exposure too, which seems to smooth out peaks and troughs. It’s all sounding encouraging to me -
Volex delivered a robust performance during the first half of the year, despite the challenging backdrop, whilst executing its most significant acquisition to date.
The Board remains optimistic of a number of potential near-term sales opportunities to make further progress in the second half of the year, and remains on track to deliver full-year results in line with market expectations.
That’s very good actually, given tough macro.
Paul’s opinion - I hold a small position currently. I really must buy some more. It’s GREEN again.
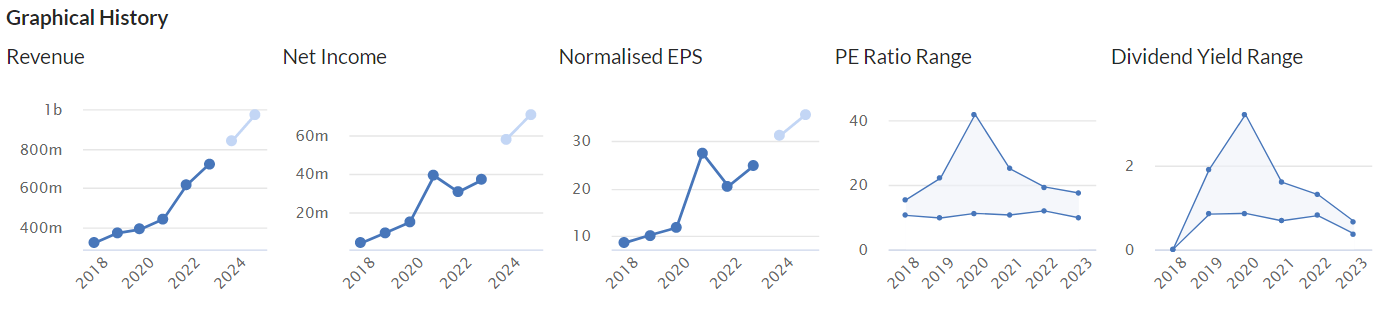
The forward PER of 10.3x seems modest, considering the excellent track record here, and no signs of any impact from macro problems. Could it warn on profit in future? Possibly, I don’t know. Hopefully the nice exposure to growing sectors could continue to mop up softness in other areas, who knows?
This is hard to argue with, and a forward PER of 10x seems distinctly undemanding -
Argentex (LON:AGFX)
Down 22% to 75p (at 12:39) £85m - Board Change - Paul - AMBER
A severe negative reaction this morning, to the abrupt departure of its CEO - although I’ve just had to edit the bit above to change it from -29% earlier this morning, to -22% now, so it’s found some buyers since the initial plunge.
Argentex Group PLC (AIM: AGFX), the service-led, tech-enabled provider of currency management and payment services to international institutions and corporates, announces that Harry Adams, Chief Executive Officer, has left the Company with immediate effect.
An interim CEO, Jim Ormonde, who seems to have relevant sector experience, and has acted previously as a consultant to AGFX, is appointed interim CEO.
This seems rather odd, and suggests to me some kind of board room bust up, especially with a replacement (interim) CEO already on hand.
Looking for more clues as to what’s going on, the Chairman is quoted today in the RNS as saying -
"We have recently conducted a review of Argentex's strategy and have identified a number of areas of focus to ensure the continued growth of the business. Jim is an experienced operator with a strong track record in successfully scaling technology businesses and I am pleased that he has agreed to step up and lead the team to start the important process of implementation."
This all suggests to me that things can’t be going well.
Interim Results were published on 13 Sept 2023, for the 6-months to 30 June 2023.
We didn’t cover them at the time, so I’ve had a quick look now.
H1 numbers look fairly good, with revenue up 28% to £25.0m, and PBT up 12% to £4.8m. Remember that’s just for a half year.
Balance sheet - looks decent with c.£40m NTAV at 30 June 2023.
Outlook - indicated “more challenging trading conditions” post period end, but still positive at +20% revenue growth. Indicated “a greater season reduction in market activity”, whatever that means - typo possibly with “season”, did it mean seasonal perhaps? Trading in line with full year expectations.
Paul’s opinion - I can’t see anything wrong with the interim numbers, other than saying that growth seemed to be slowing, with no particular reasons provided - must be competitive pressure I suppose.
I can see why the market has taken fright at the sudden CEO (Harry Adams) departure, and others have commented that he is a major shareholder at 12.2%, which creates uncertainty over his intentions with that shareholding - could it create an overhang perhaps?
I baulk at valuing this share on the existing 9.06p broker consensus, as this has a whiff of impending profit warning about it, which is what the share price is saying too.
It’s too uncertain for the time being, so I’ll stick with AMBER which we viewed it as when last looking, in Jan 2023.
I’m not keen on the forex & payments provider space, as there are so many companies active in this area, and I don’t have the knowledge or sector experience to sort the wheat from the chaff.
Indeed we saw yesterday with Cab Payments Holdings (LON:CABP) (I’m ashamed to admit I caught the falling knife there yesterday at 60p, with my punting segment of money, which is not looking at all clever now it’s struggling to hold 50p) - how quickly the wheels can come off when something unexpected changes. Which raises the no.1 investing question for all companies - are profits sustainable?
All these companies claim to have great technology, and seem to be exploiting a gap in the market for forex that the big banks seem happy to let them enjoy. There seems to be lots of competition, and new entrants, things constantly changing, etc, so I just don’t know where to start with this sector. Hence why I’m happy to completely ignore it.
I imagine we might see a weak trading update, possible profit warning from AGFX once the new CEO has got his feet under the desk. Then a revised strategy, maybe slowing the rapid expansion & headcount growth, and cost-cutting, at a guess?
At this stage it’s impossible for me to value, so I’ll just file this under “don’t know” - AMBER.
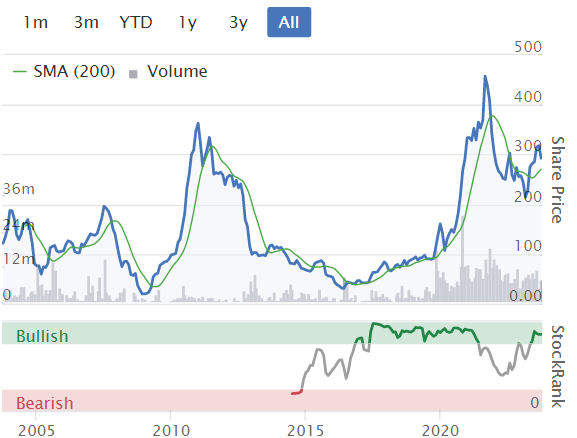
Shares have almost halved from the highs in the spring of this year -
Graham’s Section:
International Personal Finance (LON:IPF)
Share price: 127.7p (-0.2%)
Market cap: £286m
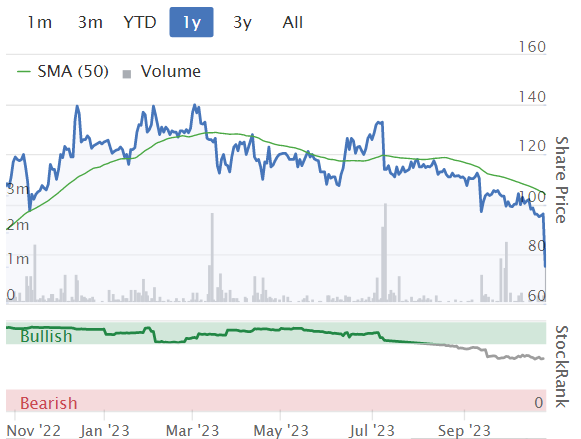
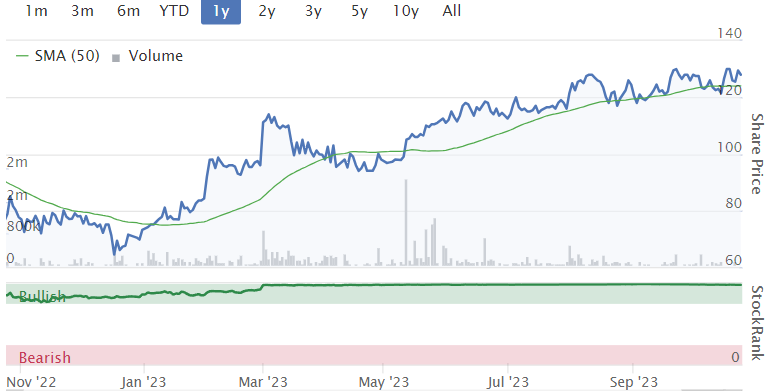
This is an unsecured lender to customers primarily in Eastern Europe and Mexico. Its shares remain “cheap” despite decent share price performance over the past year:
I’ve viewed it as a high-risk, high-reward financial stock and liked what it offered shareholders at a cheap valuation: e.g. see the SCVR comments in August and in April.
Today we have a Q3 trading update with good news: “the group has continued to perform ahead of internal plans”.
Growth figures:
Customer lending fell 1% year-to-date as the home credit business in Poland has declined due to new regulations. Excluding Poland, lending is up 11% year-to-date. Lending in Poland was down 23%.
Despite lower lending, overall customer receivables at constant exchange rates rose 4% year-on-year to £875m. (A loan book can grow even if the volume of new loans is falling!).
Poland: IPF has issued 100,000 credit cards as it changes the business model to deal with the new regulations. Half of these cards were issued in Q3 alone!
CEO comment excerpt:
Credit quality is very good throughout the Group, and our balance sheet and funding position remains robust. We continue to make good progress in raising new funding and refinancing our existing facilities which will support our future growth plans.
A key performance indicator is the revenue yield: this is revenue divided by average receivables and we can think of it as the annual interest rate that IPF charges on its entire loan book. This KPI is now 54.8%, up 4 percentage points compared to last year.
Repayments: the annualised impairment rate is 12%, versus 8.5% a year ago. This is “fully in line with our expectations as impairment rates normalise and we continue to grow our business
Once again, IPF says it has not seen “any discernible impact from the cost-of-living crisis on customer repayment performance”.
Profitability: IPF’s profit margin continues to improve as the cost-income ratio falls from 63.9% all the way down to 56.7% year-on-year. The medium-term target for this ratio is 52%-54%.
Definition:
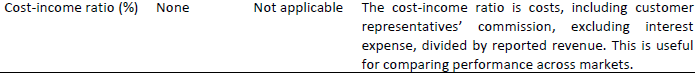
The lower this goes, the better!
Balance sheet: IPF has borrowings of £519m with available liquidity of £100m.
Today it announces that it wants to issue a new bond that will be available for retail investors on the ORB. It has an old 7.75% retail bond expiring in December 2023 - half of the holders of that bond already swapped it for a new 12% bond expiring in 2027. It seems that it wants to make a fresh offer to holders of the December 2023 bond (about £40m is left outstanding).
More importantly, IPF is already looking at ways to refinance its €340 million 9.75% Eurobond, maturing in November 2025.
Outlook
We will continue to maintain a cautious approach to lending given the uncertain macroeconomic landscape and maintain tight cost control across the Group to drive cost efficiencies.
Our strong performance through the first three quarters of the year, together with our robust balance sheet and funding position, gives us confidence in delivering a good performance for the year as a whole and provides the foundation for delivering further strong growth in 2024.
Graham’s view
I remain a fan of this business, although I acknowledge that it’s high-risk. The company’s debt is rated junk by the agencies and some investors will feel much safer owning IPF debt rather than equity. Maybe the risk:reward is even better with the debt: earning 12% interest as a lender to this company doesn’t strike me as a bad deal at all. I’ll be curious to see what price the new proposed retail bond achieves.
The company is still operating at a much safer level than it feels it is able to: it is actually hoping to take more risk as it continues to grow, in a manner that boosts profit margins and returns on equity.
The most recent balance sheet (June 2023) showed equity of £463m, or tangible equity of £410m. That compares with a market cap today of only £286m.
The share price hasn’t grown today despite another positive update, but the market may have already priced in the good news in recent months:
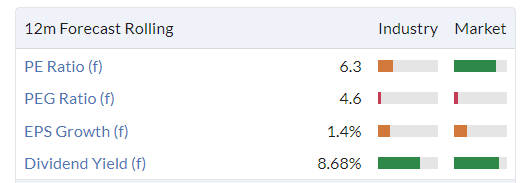
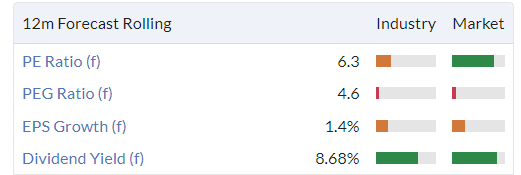
I remain very interested in this share and I’m not the only one: the StockReport gives it an extraordinary StockRank of 98:
Bloomsbury Publishing (LON:BMY)
Share price: 404p (unch.)
Market cap: £330m
Bloomsbury Publishing Plc (LSE: BMY), the leading independent publisher, today announces unaudited results for the six months ended 31 August 2023.
This publisher of Harry Potter has given solid interim results.
Highlights:
Revenue +11% to £137m
Adjusted PBT +11% to £17.7m
Actual PBT +8% to £14m
Only modest adjustments being made to the profit figures - I like to see it. The “highlighted items” add up to £3.7m and are the normal collection of amortisation, restructuring and acquisition costs.
Consumer division: revenue +17%, adjusted PBT +26% to £11.2m.
Demand for Harry Potter “remains strong” (I presume this means not growing)
Non-consumer division: revenue +2%, adjusted PBT falls 17% to £5.9m.
Dividend plans are unchanged except that reduced seasonality enables more of the full-year dividend to be paid now, rather than at the end of the financial year.
The company helpfully lays out its strategic goals for each division, plus a range of other goals related to growth, employees and sustainability.
Some of these goals look rather undemanding (e.g.”to ensure that new children discover and read” Harry Potter every year) but it’s a helpful layout all the same.
One of the more interesting goals is to see Bloomsbury Digital Resources (BDR) achieve 40% organic revenue growth over five years to 2028, reaching approx £37m turnover.
Expectations: revenue £273m, adjusted PBT of £32.5m. As pointed out by jonno in the comment thread below, this implies no growth in H2 over H1, so it may be conservative. The company does emphasise that it is now less weighted to Christmas (which occurs in H2) but I tend to agree that H2 should be better than H1.
Net cash: £39m, versus £41.4m a year ago. Lots of cash is tied up in receivables of one form or another, which have grown from £115m a year ago to £121.7m.
Outlook: confident of achieving market expectations.
Excerpt:
Our digital strategy anticipated the structural change in the academic market from print to digital learning; a trend which has accelerated and which gives us further confidence in our BDR strategy. Our strategy and acquisitions mean that we have been well placed to capitalise on the market growth to date as academic institutions pivoted at pace to digital learning.
Graham’s view
I see that Paul gave this one a brief comment in July, also covering it in June.
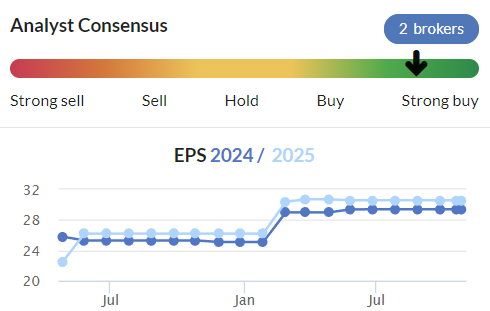
Earnings momentum has been positive:
This is not a company I’ve covered regularly myself but I’m happy to maintain the positive stance suggested by Paul - it appears to be a properly profitable company, of decent quality, and not overly expensive.
Cash flow looks lumpy to me but perhaps that is to be expected as investments and inflows don’t all happen in lockstep.
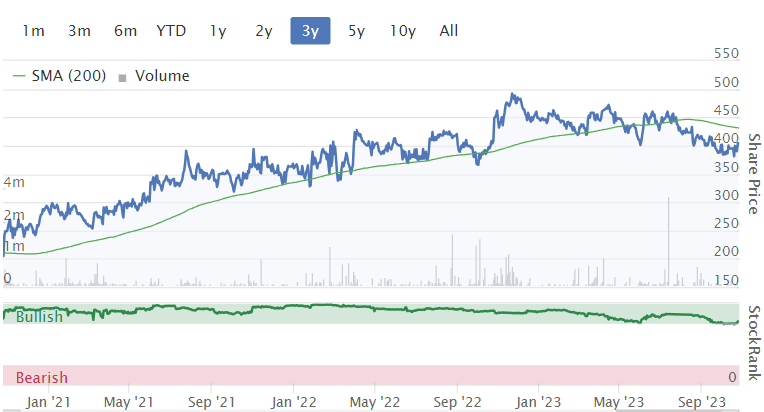
Here’s a three-year chart:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

97 comments
Argentex / Harry Adams
I have commented previously on several occasions on Argentex and how many years ago a young Harry Adams was my currency broker at Moneycorp (maybe traveled)
Typical wide boy wheeler dealer currency broker was my memory and certainly not CEO quality .
Everyone got carried away with Argentex in the bull run and share price went on a great run.
Management were very well looked after from memory but I saw nothing from Argentex of real value.
Equals is a different proposition with a very credible CEO and CFO.
I even had my FC set up an account with Equals to benchmark them against moneycorp it all works seamlessly however we still use moneycorp as they tend to give us a slightly better spot rate.
Was pretty frustrating a year ago to see equals stagnate whilst Argentex ran ahead but looks like this is now reversed .
Harry Adams will have left with a nice send off and 12% of the company as well as having had a very well rewarded previous 24 months with incentives and bonuses so he will not be visiting the local food bank .
Renewi (LON:RWI) bid has fallen through. Macquarie upped their original offer yesterday but board held out for still more, and today the bidder has walked away. This is why I ALWAYS sell at least half on initial bid.
Arbitrageurs are still buying at the only somewhat reduced price so perhaps all is not lost.
Paul’s video on SCS (LON:SCS) vs DFS Furniture (LON:DFS)
https://vimeo.com/653451564
Huge thanks to Paul and Graham for these daily deep dives. As a relatively new investor, these are phenomenally educational. Congratulations on your stellar work .
Snap.Having only really recently joined up apart from a previous trial period a few years ago, it really helps especially in this harsh market and having never invested through a period of persistent inflation before.Some great informative discussion and polite too.And support in the comments section too.
St James’s Place blocks clients from pulling money out of major property fund
Britain’s biggest wealth manager has blocked withdrawals from its major UK property fund as the working from home era continues to hit office rents.
St James’s Place suspended dealing in its £924m property fund – blaming the rise in vacant office space and falling demand for UK commercial property in the wake of the pandemic.
It is the latest major property fund to suspend or cease trading following the dramatic slump in demand for office space. Commercial property has also been hit hard by soaring borrowing costs.
https://www.telegraph.co.uk/mo...
Crikey. Even BMY can't hold its head above water in this market. Fwd PW is 13.4, which is undemanding. Operating margins have improved over the last couple of years, too. It's been raising its dividends by about 10%pa over the last 5 years.
Its shares are down 10% YTD. That's more than the SMXX (FTSE Smallcap Ex Its Index), which is down 7%.
It's a good business, with a Quality score of 91. I hold.
Hi everyone, just wanted to share my thoughts in the hope it might help me, and to see how others are coping. I am finding this rather difficult now, I check my portfolio every day (perhaps I shouldn't?? ) to find the same old story. I am fighting with myself if to sell or not, but I know it is the wrong thing to do. I have even found myself Googling about the lengths of bear markets in the hope we can't be far from the end. I am frustrated with myself that I have rightly held my nerve but now beginning to despair. I also feel a little thoughtless when you look at what some people are dealing with in other parts of the world. I must say I am feeling a little better just writing and sharing these words. It is good to talk as they say. Take care all, I hope you are coping better.
Hi Lefty99, firstly it is good to talk so please feel free to post here and/or reach out to fellow investors, you'll be surprised at how many are in a similar situation.
Secondly, with regards to your concerns, (caveat this is not advice, everyone knows their circumstances better than others etc) there is no doubt that we've had a brutal 2 years (especially if you are exposed to the UK markets) and we cannot see it any other way. Even if you are a really good investor you will have had some drawdown during this period. I'll stick my neck out and say that is NOT the norm though. In other words, most UK investors are in a similar predicament to you - very frustrated, death by a thousand cuts and salt still needs to be added.
BUT I believe, strongly, that we are closer to the bottom than many think. If you are holding good quality companies AND you not leveraged, don't need the income/cash then you can ride this through. There is no benefit in checking your portfolio daily unless it is to add to positions or sell fundamentally poor businesses. Otherwise you're better off finding ways to get more cash into your accounts and get serious about investing. Failing that then get out more. Enjoy life, that is better for your health and ultimately I'd argue will be better for your wealth too.
This too shall pass.
on X if you wana reach out - MGinvestor
Thanks MGinvestor, you are of course right in what you say. I do feel as though I hold good quality companies, I am not leveraged (couldn't cope with that), not in debt, and have a reasonable income. In the past I always invested in funds rather than individual companies, maybe that is something to think about again. As for getting out, I have actually started running as a hobby, which although early days appears to help. Thank you for your kind words.
Hi Lefty,
Two things I've found help the most, maybe things others won't mention:
1. Having a close contact who also invests, someone you can message daily as a reminder that it's not only you who's being impacted, my friend and I just exchange memes and GIFs in an attempt to laugh at the situation. Especially when takeovers are the take of the SCVR it's easy to think you're missing out more than most.
2. Being honest with my family. I tell my wife it's going bloody awful at the moment. She trusts my judgement and then I don't feel I've got to hide losses or feel guilty I've made poor choices.
Head up, were all having a tough time out there. I check my portfolio multiple times a day, always have, probably always will.
Ben
Thanks Ben, yes good to laugh in these times, things could always be worse I guess. Yes I have told my wife to put retirement off for now.
Lefty, its just part of the investment cycle. Near the bottom its demoralising and scary and no ones interested. It should feel like a waste of time and money to even bother.
We're way past denial, more at capitulation and despondency, although I think it can still get worse as theres so many potential banana skins around, but thats why I like charts they take all the emotion out if it at major turning points.
Something will happen at some point to change sentiment. US growth today was good, inflation in UK should drop, German business sentiment was better, China looking like starting QE.
Obviously World War 3 is a potential downside:)
The continuing rise in yields is the potential downside and they will only fall the day the market crashes +10%.
Thanks Wolf, I hope you are right.
Hi Lefty99 - It's been a real emotional struggle for me over the past couple of years and it is not nice seeing the portfolio reducing in size on a daily basis. I am definitely in the depression stage of the bull/bear chart (not sure about the market!), however I try to remain stoic and looking for the best opportunities as we come out of this long bear market. I find that I have switched my strategy slightly and been investing in Investment Trusts, which are on wide discounts and providing decent income but as we see some green shoots - inflation falling, interest rates decreasing and perhaps announcement of a short technical recession - I will be buying more cyclical value stocks, such as the housebuilders, investment companies such as Jupiter Fund Management (LON:JUP) etc.
Just remember that you are not alone and there are plenty of investors feeing the pain at the moment - not to mention the seemingly non-stop depressing headlines in the news. I am being made redundant as well, so not ideal!
Best of Luck,
Ben
P.S I have found that since I started investing in 1998 that the times where it feels the most difficult/scary buying will become the best performing investments over the mid term, once a recovery kicks in. I have often looked back at these tough times and thought - why didn't I back up the truck and buy more, with the benefit of hindsight!
Wise words bsharman, sounds like our investment period is similar, and yes in hindsight should have been a little braver. Sorry about your redundancy, I hope something comes up soon for you.
Hi Lefty
You have already received lots of wise words from other Stocko members, so excuse me if some of what I say is duplication. I would also add that I don't know your financial circumstances. So leaving the preamble to one side I would make the following observations/points that I have learnt through personal experience and from some of the great investors over 40 years or thereabouts.
None of this is new, but it works for me.
In no particular order:
The market goes in cycles from boom to bust. A pattern that has been repeated for longer than I can recall. To quote Howard Marks shares/stocks go from flawless to hopeless. In terms of UK shares and in particular UK small caps, where I invest we are clearly towards the hopeless end of that process. Whether we are yet at the bottom is another matter, but most of the small cap shares I hold are trading in line, on single or low double digit PEs with cash on the balance sheet and often at a discount to their net asset value. Examples being Hargreaves Services (LON:HSP) Sanderson Design (LON:SDG).
Understand the company, focus on how it is performing, not on the share price. If the company is performing to plan but the share price is depressed I will generally add to my position. The less I have to pay for the shares the better. I want to buy shares in good companies when nobody wants them. Now strikes me as a good time to do so. This is very much out of the Peter Lynch playbook.
Before making a purchase I ask myself 3 questions
Howard Marks maintains that the secret to success in the stock market is 'buying well'. To quote Peter Lynch "In the stock market, the most important organ is the stomach. It's not the brain." This I would suggest is what most retail investors, myself included are struggling with at the moment given the continuing drift downwards in UK mid and small caps.
The market will turn and when it does so it is likely to happen quickly and without fanfare. As some one much wiser than me once said no one blows a whistle when the bottom is reached. Going back to Howard Marks the bottom is reached when the last seller has sold, as to when that is I don't know, but it will happen.
To conclude my ramble, if one is invested in good companies that are not overly indebted and performing to plan (in-line) and the money is not needed for more pressing issues I will remain invested and use dividend income to add to positions
Like all investors I don't always get it right and have made many mistakes that I try to learn from, but this is the approach I follow and it works for me. It is not intended to be personal advice or a recommendation for you or anyone else, it is just my view.
Good luck in whatever you decide.
Thanks Jonno much appreciated, and wise words again. Hargreaves Services (LON:HSP) is in my portfolio so fingers crossed for both of us. I’m not sure on the catalyst that will make this turn round, but like you say it always does. Thanks once again and good luck.
Hi Lefty, you have had some good advice, so will add a little thing that I do that makes the losses seem no so bad.
I have a spreadsheet that charts the first 20 years of my retirement, after 20 years I suspect I am not going to worry to much or at least need that much to keep me going.
It includes:
I then work out how much I can pay myself every month when I do retire. In this way, I can see how much it goes up every month, but more importantly, I can see that the huge loss I have just suffered over the last two days, thanks Argentex (LON:AGFX) and Sylvania Platinum (LON:SLP) actually over the 20 year retirement period isn't that much per month and depending how far away you are away from retirement, plenty of time to make it up, I only have one year to go and still investing every spare penny into the stock market.
You joined in 2018, so must have some experience of the bull run, it will return and you will be so much wiser when it does.
Take Care, GB.
I’m very similar GB, I should have a good pension when the time comes in say 5 years ish, so ISA and SIPP will hopefully be money to enjoy life with. Good luck with your future, and thanks for your help it means a lot.
At least Sylvania Platinum (LON:SLP) went ex dividend today, which probably accounts for most of the fall.
Everyday I'm getting hit with a big fall. Even some US stocks are going down now.
Hi Lefty
You’ve had some excellent responses… I’d like to add one simple point that is hugely underestimated…I’ve found it much easier* to invest by absolutely concentrating on the underlying business I’ve a share of…not the price it’s on sale at.…obviously that only works if you’re fishing in the right waters of quality businesses with good balance sheets & attractive end markets…but why fish elsewhere unless you’re blessed with the trading instincts required to do so successfully?
Best wishes
*easier to sleep at night too
Awful time for small cap companies. Some catalyst will occur for rerate and as long as in companies with good management, the right growth sectors and that are not over leveraged, in time should be ok, looking at number of bids in this sector is under valued. Never gamble to make up for losses that only ends one way. With Uk markets down to around 4% of worldwide total, any profits taken are being invested more in growth and income international investment trusts for diversity.
Lefty. None of us know what comes. History is not a guide IMO…it provides simultaneously false comfort and concern. Operate in your comfort level. If you are losing too much money relative to near term needs then you are over exposed.
I believe the only thing that drives returns is dissonance. This is not an easy investment formula. Only if you are a trader should you pay attention to momentum and short term factors driving ‘dissonance’…short term dissonance is a volatile quantum that requires you to be a better poker player than others. Possible but remember you are in this game of bluff, guess and double bluff.
I prefer longer term perspective and finding companies that are viewed dissonantly over that time frame. I believe the U.K. is rich with these opportunities…although obviously the last couple of years has seen opportunities get richer (ie stocks go down!). A bear market is never easy over shorter term…history says rich over longer term…when it arrives! But sometimes countries and markets fail structurally…I don’t forecast this for the U.K. but some of the vibe in recent times is this is where we are (…perhaps why foreign interest has been very low…capital flows are often footloose and emotional)
I would say just try to have faith in your good quality companies and not place too much importance on what the share price happens to be on any one day. As we've just seen with SCS today the market doesn't necessarily have a clue what the correct price should be, but value will eventually come out one way or another.
I've been investing for around 25 years and this is the worst market I've experienced so you're not alone - of course 2008 was worse for more speculative small cap investors, but for a more balanced investor such as me (with a decent allocation to bonds and some alternatives) this has been much worse, as bonds have fallen in tandem with equities (in 2008 they acted as a hedge) .
The good news is that if you look through history it is very rare for bear markets to last more than 2-3 years so feel we must be getting towards the end. That said, I do get a feeling we are due a nasty final lurch downwards (possibly a 1987 style drop in US equities) before we'll be back on the road to recovery.
UNILEVER. OK, so not a small cap. But you guys don't seem to mind be rambling on occasion, so here goes anyway ...
ULVR published its Q3 report today, sening the shares down 3% to 3890p. I bought in July 2020 at 4351p. So I'm nursing a 10.6% loss on this. Weak sauce.
Billionaire investor Nelson Peltz joined the board of ULVR in May 2022. It appears he was not happy with the way things were run (who wouldn't), aiming to shake things up. Hein Shumacher was appointed new CEO in July 2023, replacing Alan Jope. He spent about five years at the helm.
I've heard more than one view that ULVR was a good company run by bad management. Yahoo UK Finance reported "Jope also emphasised the social purpose of Unilever's brands."
https://uk.finance.yahoo.com/n...
The article mentions such nonsense as "brands like Domestos disinfectants [were] trying to improve access to toilets in developing countries, drew ridicule from investors."
In January 2023, Terry Smith accused ULVR of "virtue signalling," which sounds about right. Fundsmith wrote a postmortem in January 2022, which you can find here:
https://www.fundsmith.co.uk/me...
Terry has a good rant. "Apart from observing that one swallow doesn't make a summer and few quarters of growth do not amount to a satisfactory track record, we would also suggest that Unilever shouldn't see long term shareholders if doesn't want them to judge its long term performance."
On the subject of aquisitions, Smith says "Bloomberg Intelligence noted that: since Kraft bought Heinz in July 2015, its shares are down 48%; since ABI bought SAB Miller in October 2016 its shares are down 49%; since Reckitts bought Mead Johnson in June 2017 its shares are down 21% ; and since Danone bought WhiteWave in April 2017, its shares are down 10%"
ULVR is a top holding of LTI (Lindsell Train Investment Trust) at 7th position (4.75%) (https://www.hl.co.uk/shares/sh...). As at 31 August, 68% of its holdings are in the UK (https://markets.ft.com/data/in...). That's quite a show of confidence. EXPN doesn't appear on the list of top 10 holdings, which surprised me a little. Nick Train started a position in Oct 2020 (https://portfolio-adviser.com/...). I'm guessing that the price must have been around 3000p (now 2409p). He added in April of this year. So it's in the portfolio somewhere.
Fund manager Michael Ulrich of JO Hambro Capital Mgt is positive on the shares. He talks about it in this video:
https://www.youtube.com/watch?...
around the 32 min mark. He shares the view that it has been badly run. There's a lot of changes at the top (new CEO, Chair, CFO), and thinks that there will an emphasis on growth spending. ULVR tried to deliver higher margins, but Ulrich points out that there's only so far you can take this. He is confident that the new management understand this. ULVR's valuation is as attractive as it has been for awhile (Stocko has a 12m fwd rolling PE of 16.7, which may sound a lot, but ULVR frequently trades on a PE of 18). ULVR has a joint venture in India, so it should be good if it gets some innovation going. ULVR is the second-larget holding of J O Hambro Capital Management UK Opportunities Fund at 4.8%).
I had considered booting ULVR out of my portfolio come the new ISA season, but I have since changed my mind. I think it worth giving the new guys a chance.
It’s good to see someone introducing more discussion of large caps, Mark. Good on you. I’m very much not a fan of Unilever (LON:ULVR) because its track record of growth has been so dismal for so long. The whole products with a purpose bollocks was a case of trying to shoehorn old brands into hipster shopping baskets and missed by a mile. I guess the dividend is safe and the shares will do better if/when interest rates are cut. But the real total return is negative right now, especially after tax on the dividends. I hope shareholders enjoy the next 5 years better than the last.
In my own frustration at overall portfolio performance I question why I didn’t just put the lot in Microsoft 5 years ago and find a different hobby. That still looks like a viable strategy today!
The same kind of culture change is happening at BP (LON:BP.) and Shell (LON:SHEL) . The woke brigade are moving on leaving the grown ups in charge. It does not seems to be a problem afflicting small caps.....they are all too busy running a business.
Housebuilders
"How to spot a housebuilder's recovery " was the title of an article by Robin Hardy in IC yesterday (25 October).
a very comprehensive and nicely written about many aspects of housebuilders in the current market.
Conclusion: Do not be tempted to buy now. They do look cheap but they are not! It is a cyclical and will do well when the market turns but we are nowhere near there. More pain to come, sales are dropping, margin are collapsing and dividend will be cut but still you may get 4-5%.
If you are a holder you may well hang on there for the eventual recovery.
I’ve not read to article but it is my thoughts too, though I do believe it is not that far off the bottom, maybe 20% but who really knows.
Also, I think some are closer to the bottom than others. Here’s screen shot I have of some of the house builders. Take note that the 1 year forecast PE for some is way higher than the 5 year average while a few are actually already below the 5 year average.
It is ofc not always that simple. Generally the market for house builders runs about 18months ahead. So we need to think about where the economy for houses will be in 18 months. Has the uk felt the pain fully in higher interest rates but also inflation? We also know there is a shortage of houses, so more do need to be built.
Finally, there will be an election in the next 14 months which I’m sure will affect the house builders depending on the rhetoric of the different parties.
A lot has been said recently about small cap liquidity, or should I say the lack of it. Example from Renold (LON:RNO) below this morning:
Over 6% genuine spread (not just what's quoted), and just the two trades in the first two hours of the day. The sells taking place at these spreads are surely out of pure desperation rather than based on any fundamentals.
I get that it's a painful situation for many at the moment, myself certainly included, however we have to batten down the hatches and not be tempted into illogical sales - especially where companies continue to report in line with expectations or better, yet are 10-20% down on where they were earlier in the year. Bloomsbury Publishing (LON:BMY) being a perfect example this morning.
Hold the line - How 2021!
I wonder what happened at Argentex (LON:AGFX) for them to sack their CEO Harry Adams - nothing is said in the commentary and the share price is currently down over 20%.
Paul mentoned on SCS:
'Others have pointed out that the bid announcement didn’t seem to have any declared support from institutions, and mgt shareholdings are shockingly trivial, especially galling given their greed with excessive remuneration (for lacklustre performance I’d say).
One investor pointed out to me that any bidder would have a c.10% instant boost to profit by clearing out overpaid management - a point that is backed up by the figures, so difficult to argue with. Do they think they’re running Marks & Spencer or something?!'
What are their salaries? One starts to wonder if its even worth taking all the risks with those UK stocks when directors pay themselves so generously first before leaving anything for shareholders. And then you have the government who has ramped up corporate taxes to 25%? Aren't these taxes higher than in the USA? Is the UK heading to a wall?
Please take this SCS (LON:SCS) comment with big pinch of salt. I was a holder from lows and liked the company some years back after it fell following IPO but sold out after couple of years as in my opinion they were showing signs of poor capital allocation decisions and lack of shareholder value focus (sort of looking to build empire rather than value). So I've not closely followed since inc this bid. That said, here's a view:
1) yesterday, without a preceding bid, the share price would have fallen more than 10p (ie c.6%) in current environment. Any bad news is getting hit...I suspect if you are very short term sort the 'alpha' is in these news events at moment. The way SCS reported their Oct sales cliff would have spooked the market a little imo.
2) The bidder is an industry player. IMO and based on my old view of SCS before I fell out with their capital allocation I'd say that the bid undervalues them. However, in the current market context its reasonably 'rich'...perhaps as this is an industry player rather than a financial bid.
3) I do not believe a financial bidder goes higher in the current environment. It would take an enthusiastic industry player. I'm not expert on the industry...but this seems unlikely.
4) The Italian would need to be off their heads to increase their bid now (given profit warning and market environment)...
So, you ain't getting a new offer. I think there's a reasonable risk the deal falls through too. My hunch is that prelim was delayed as they wanted to get the Italians over the edge...but was the subsequent pw a surprise to the Italians? Dunno but possible. If so do they feel a little sore/played? Could this drag and Italians seek to lower bid?
My view is that deal isn't certain and the price to bid will widen
The bidder would have been told of weak trading when it did due diligence. Nevertheless I don't see a better bid coming.
Maybe. I don't claim any insight on legal requirements here. But its very current trading that is disappointing and therefore possible that its not been shared. I point to the segue of late prelim and bid coming in before...were management being a little cute? I have been in such situations in a non-listed environment and its quite smoke and mirrors
SCS (LON:SCS)
Great summary mojomogoz - i dont know what will happen but i would agree 100% with your logic. Couldnt believe that anyone could call a 68% premium offer a law ball bid - clearly anyone who thinks 68% premium if low ball offer is not living in the real world - the reality is they may think the bid is under valuing the company on their metrics - but before yesterday the market as a whole disagreed with that logic by 68% plus - and today the market is still saying the bid price seems fair value. Peeps may want more but imho this is anything but low ball bid simply due to fact its 68% premium alone to current price. This is particualrly the case if you look at prfit expectations being well down opn what was expexted a year or two back.
Ref uncertainty of bid - cant see any specific reason for it not to go ahead (other than softer trading)- but if shareholders/company officers take the viewpoint they "deserve more" and try and get more or delay process then i would bet on there being more chance of whole bid collapsing than higher price being acheived. If potential acquirer is/was not aware that trading has worsened again when collating bid then that would also be a worry that they might slightly downgrade their offer.
Spot on.
SCS (LON:SCS) . Thanks mojo, I feel the same and accordingly sold this morning in the market. In the current climate I feel a profit banked for a stock I had long grown weary of can only be a good thing and as Paul commented yesterday it's not difficult to replace or improve the current yield. That is if you feel like buying at the moment.
SCS (LON:SCS) does seem like a perfect strategic fit with Polttronesofa. Cerezzola, who have made the offer for SCS, is a hwolly owned subsidiary of Poltronesofa. Poltronesofa have retail operations in Italy, France, Belgium, Italy, Malta and Cyprus, but nothing in the UK so SCS is a very logical fit. The Poltronesofa has a decent reputation in Italy. It will be interesting to see how this pans out, but I think the deal will go through.
Indeed, it does seem an excellent fit….
“Poltronesofà is well known in Italy for its advertisements in which it promotes seemingly perennial discounts on its products.”
https://www.ft.com/content/6b2...
Kromek (LON:KMK) announces a $5.9m biosecurity contract with none other then the US Dept of Homeland Security. Now at least soundly financed and looking like it is achieving profitability albeit at ebitda level (H1 loss, H2 ebitda profitability). Evel Paul said "Looks worth putting on the watch list" back in July. I hold starter position. DYOR!
Kromek (LON:KMK) have spent too long being a jam tomorrow stock. The technology is world class and if they wanted to sell it privately it would command multiples of the current share price.
The problem is also that they are the only public company left with tech that goes into CT scanners. That can be a good thing as it means they are now the go to supplier but also means that their monopoly significantly reduces their natural buyers.
In reality Kromek (LON:KMK) have to demonstrate that they are finally capable of generating their own cash. Becoming ebitda positive is a step in the right direction but more is needed. I expect to see many contracts signed in next few months but for me the jury is out until we see that cash generation. They remind me a bit of Niox (LON:NIOX) so perhaps a more commercially focused management team is required to unlock what is undoubtedly world leading tech. Hmm
comments much appreciated David. Jam tomorrow was very much in my mind too. It won't take much to shake me out but then again, if there is evidence of meaningful progress, I would start to give the mamagement the benefit of the doubt. One contract is not yet sufficient, although I'm impressed with the customer.
I think there is a lot of value in Kromek (LON:KMK) tech. It has a blue chip client base. The question is unlocking it….. management say they are now profitable which is a start but imo to get taken seriously they need to start showing this in cash flow and as a PER. IF they can demonstrate that they will likely re-rate rapidly in my view…..the question is whether mgmt are capable of showing that.
Hi Paul
Thank you for the update on Volex (LON:VLX) . it is my largest holding, first bought 3 or 4 years ago, at just under £1, when operating margins were beginning to rise. although in fairness I have sold and bought a few along the way.
Nat Rothschild owns 25% of the company and has never sold a share, so despite the enormous family wealth I cannot conceive of him not telling it as it is. To date I have always found the company to be straight and fair with its retail investor base and I have no reason to change my opinion.
Best wishes
Wynnstay
Thinking of deploying a bit of recently freed up cash into Wynnstay
Was a major holding of mine but slices 1/3 of it 6 months ago.
Looks to have received strong support at the 350p level which seemed a silly price .
130 million assets
700 million revenue
At least 10 million profit
EPS circa 40p
For a company trading below NAV making 10 million a year 90 million looks very solid .
There could be a one off provision for Glasson their fertiliser division which is a counterbalance to the one off gains last year, so that doesn’t really affect the long term case . A one off gain one year followed by a one off provision is irrelevant .
Nice share for my ISA as IHT covered and decent dividend .
Would I buy this business if I had 90 million quid probably .
Any counter points
or maybe best tactic is sit on hands
Wynnstay - £10m profit on £700m revenue is quite low margin - about 1.3%.
Could that be easily tipped negative by weather or unforeseen wholesale price changes?
Planetx I have been looking at Wynnstay (LON:WYN) recently. My only concern is that forecasts show decent profits but the cash position is also forecasted to go into debt. I have asked about this, got a general response on company accounting due to regulations re Private Investors.
"The reasons for cash balances being negative can reflect an amalgam of things from working capital movements, tax and dividend payments, and capital investment."
Since they are on a capital investment programme with new Feed Mill in Carmarthenshire and more I assume this is the reason. We have a store near us that I visit from time to time. Seems as busy as ever.
Wynnstay (LON:WYN) - a really good company that I hold. Quite cyclical, but the long-term trend is up and its always very profitable. Great dividend record and management are very sensible. I will await the change in share price trend (either the share price or 50 dma crossing the 200 dma) before considering adding a few more, but undoubtedly good value long-term.
I personally wouldn't worry about the balance sheet here. It's cautiously run. There can be large swings on working capital and capex.
Margins are low but their feed business is effectively on a cost-plus pricing formula I believe. It remains profitable in good times and bad. Gleeson is more exposed to stock gains and losses, but it made massive profits last year and losses this year - its quite a small part of the business.
This is a boring, but dependable dividend growth company.
Bloomsbury Publishing (LON:BMY) Positive interims. One my largest holdings.
A couple of observations:
I have long subscribed to the theory that Harry Potter has the characteristics of an annuity. I am not surprised to see it continue to be among the most popular children's titles simply because the books have become a classic. So as one generation grows, the passion to read the exploits of young Harry and his friends will pass to the next. A point that was well made by Richard Leonard two years ago on PI World when he compared the Harry Potter books to those of Thomas the Tank Engine, which were first published in 1945. My son who is now 35 was an avid fan of the latter when he was very young. I understand that a television series based on the Harry Potter books is to be produced, but we wait to see.
Bloomsbury Publishing (LON:BMY) announced revenue of £136.7m at this morning's interims, albeit unaudited. They cited consensus market expectations for the full year of £273.1m. On this basis revenue for the second half will be the same as the first. Given that the former contains the all important festive period, my view is that the company is being somewhat conservative with its forecasts and there is a good chance that these will be beaten. Last years split was £123M (H1) and £141m (H2). However this is speculation and as one of my great mentors, Peter Lynch has said one should focus on the facts, which for the time being means that Bloomsbury Publishing (LON:BMY) is trading in line.
All the best
Likewise, Harry Potter, although I have no personal interest in that genre, is one of the reasons I bought and still hold Bloomsbury Publishing (LON:BMY) . Even though they were first published in the 1930's Arthur Ransome's 'Swallows and Amazons' series were my favourite as a youngster in the late 1960's and I still re-read one or two of them every year even now.
I heard that a TV series has been commissioned for Harry Potter (US telly??), so there still seems to be plenty of life in it.
SCS (LON:SCS) I sold all mine yesterday been 10% of my portfolio . I feel they are too many other opportunities to wait to see what happens . I think the price is fair in this market and retailers don't often trade on a high p/e regardless of the balance sheet .
my two best performers this year have been Numis and SCS (LON:SCS) - both takeovers.
Morning,
Another day, another day AIM falls. Surely the end is nigh of this bear mkt? Wishful thinking perhaps!
In my experience market situations like this need a huge event to turn sentiment, maybe peace in one or either main conflicts in the world or more likely the drip drip market falls need a puke out to clear the system. The first scenario seems much les likely than the latter which means more pain for us investors!
When studying past bear markets, especially those occurring in periods of high inflation, the markets tend to pivot when inflation is falling and central banks begin (or are rumoured to) loosen monetary policy.
Inflation is still far too high at 6.7% in the UK. It would be crazy for the BoE to loosen monetary policy at this stage, until we see sufficient evidence of inflation going back down to the 2% target. It's anyone's guess as to how long this takes, but for me, I'm thinking at least another 3 - 6 months of stock market pain. 2023 will most likely be a write-off for many investors, but if we go by the BoE's projections, then 2024 could be a year of two halves. The first half being a similar sluggish bear or bottoming phase, the second being a bull market recovery.
just a note on the inflation rate - something like 2% is scheduled to drop off October's rate from 12 months ago so as long as nothing else has ballooned this month we should be around 5% or just under.
Hi Paul, just one consideration regarding the @SCS dilemma... If I understand correctly, the dividend will be paid to anybody holding on November 17th?
So for anybody deciding to sell, it may be worth holding at least for a few more weeks, unless you really don't want any risk if the deal falling through.
SCS (LON:SCS) Is there an opportunity over the 10p dividend ?
If the deal is still in place when it goes ex on 16/11, (payable 15/12) will the sp drop by the 10p, giving an opportunity to buy at 260ish ?
Just thinking out loud !!
Can't see the logic in this although Wentworth Resources (LON:WEN) is further into its being taken-over and the current share price is the opportunity you speak of, Helvellyn. But who said the AIM was logical anyway.
I think the SP has already effectively dropped, as the deal is for 280p (270p SP + 10p divi)
SCS (LON:SCS) Sold my holding- bought a few years ago-at pretty much the offer price - so happy to escape without a loss. Not sure another buyer will appear- but who knows.
Sherborne Investors (Guernsey) C (LON:SIGC) disappointing lack of announcement re the strategic review at Navient yesterday, in the Q3 results. Next scheduled news is Q4 finals at the end of January. On the call they referred to a comprehensive review and dropped a few clues re capital and costs. The market focussed more on low lending volumes and a provision that took the shine off nos. Shares reacted badly but with $360m of buyback incomplete this was limited to a fall of 6%... and Id expect shares to continue to bounce. The CEO said as soon as the review is complete an announcement will follow so I am "hopeful" that these results clear the way for better news next.....although admittedly not much to hang my hat on. Best case would be a follow on announcement in the next month or so setting up a rally into year end and worst will be sitting it out til January.....either way better news should follow but as always nothing is guaranteed. In Sherborne Investors (Guernsey) C (LON:SIGC) you have the protection of the discount should they decide to give up and just return capital which I think is unlikely.
Hi RDHOWARTH,
.." In Sherborne Investors (Guernsey) C (LON:SIGC) you have the protection of the discount should they decide to give up and just return capital which I think is unlikely..."
Maybe I'm misunderstanding something - but isn't that exactly what they've said they intend to do ?
AIUI, from the 18th May RNS, the appointment of the new CEO (certainly an activist - and possibly Bramson's man) 3 days earlier was the specific trigger , and has to do with the division of the spoils post monetisation :
If you go to p 52 of the last A/R 'Related Party Transactions', there's this bit
.."The Special Limited Partner is entitled to receive an incentive allocation once aggregate distributions to partners of the Investment Partnership, of which one is the Company, exceed a certain level of capital contributions to the Investment Partnership, excluding amounts contributed attributable to management fees.
For Turnaround investments, the incentive allocation is computed at 10% of the distributions to all partners in excess of 110%, increasing to 20% of the distributions to all partners in excess of 150% and increasing to 25% of the distributions to all partners in excess of 200% of capital contributions, excluding amounts contributed attributable to management fees. An investment is considered a Turnaround investment when a member of the General Partner is appointed chairman of, or accepts an executive role at, the STC."
The RNS goes on to say ."The board of Sherborne Investors (Guernsey) C Limited (the “Company”) announces that, it has been advised by the Investment Manager, Sherborne Investors Management (Guernsey) LLC, that, following the distribution to the Company of any proceeds from the Company’s indirect investment in Navient Corp., the Investment Manager does not intend to seek to recall any funds for further investment."
I read the italicised bit as SIGC may be expecting some kind of corporate activity or rerating that warrants exiting the investment; and the bold bit that, in either case, SIGC will in due course be wound up and proceeds returned to shareholders ie the discount will pull to par.
Upsum :
(1) they've changed the eventual distribution of spoils- as pre-agreed, having achieved a KPI and got 'their man' in place; and
(2) they don't intend to roll over into a new investment, when (ever) this one is monetised.
Activist Bramson didn't get his way at BARC, but maybe he has at NAVI ?
Are you reading the situation differently?
ATB
PS
Although Bramson made a loss on his BARC tilt, he appears to have been successful elsewhere :
https://www.theguardian.com/business/2021/may/07/activist-edward-bramson-ends-barclays-battle-by-selling-stake
.."In a letter to investors on Friday, Sherborne said it was taking advantage of the rise in Barclays’ share price to exit its position, having seen the stock rise to more than 180p from 73p a year earlier. However, the share price is currently 15% lower than when the fund’s position became public.
Sherborne Investors told investors it had joined the boards of five other companies since taking a stake in Barclays, and launched “successful turnarounds at all of them”. It said: “Each of these investments returned 100% or more , so it is a pity that the opportunity did not arise to join the board of Barclays to assist in a turnaround with a similar result."
Let's see what happens with NAVI......
Hi extrader, sorry for confusion .... the plan is to execute the turnaround at Navi and return all money to shareholders of Sherborne Investors (Guernsey) C (LON:SIGC. My comment referred to the fact that if he has lost faith in the Navient (NSQ:NAVI) turnaround then selling the stock would still yield a positive return from here because of the discount. I don't think that will happen though. I think it will all take about a year from now but you are likely to get a pop out of Navient (NSQ:NAVI) when plans are announced....which I hope is 2023 not 2024.
Thanks for clarifying ! I think there's a bit of headwind on the litigation front - latest results show Navient (NSQ:NAVI) making bigger provisions for the (alleged)mis-selling/maladministration of its student loan portfolio, proceedings initiated way back in 2017 by the Consumer Financial Protection Board (CPFB)....
Making bigger provisions isn't usually good for investor sentiment - or the share-price. So, maybe the decision to exit will be brought forward?
Interesting short statement from Braemar this morning, we hold and look forward to receiving the increased dividend (delayed FY23 dividend up 33%) when they re-list! If you have chance for a quick comment Paul or Graham I'd appreciate your thoughts on the company. FY23 underlying profit expected not less than £20 million v FY 22 £10.1 million. H1 24 not less than £7 million board confident on H2 24. Results for FY 23 mid November. Investigation at last completed. It hasn't been a smooth cruise so far aboard the good ship Braemar.
FYI - Some good news/ silver lining?
I see that Bill Ackman has closed his short position is US treasuries.
https://www.reuters.com/busine...
Bill Grossman is bearish as well, so maybe we are at the peak in the US, but inflation seems a lot more sticky here in the UK.
Alumasc (LON:ALU) Confident update, share p/e below yield again. Debt is nearly eliminated. I hold and looks good once sentiment to the sector improves.
SCS (LON:SCS) : Morning Paul, Thanks for the comments on SCS and quite a dilemma do you stick or twist !? Feel the offer is far too low for the reasons you've outlined but at the same time if the offer isn't sweetened or another bidder doesn't enter the fray and the offer falls through due to lack of institutional support the share price will undoubtedly drop back towards 150p-160p. I'm erring on the side of holding onto my shares in the hope that the offer is increased / another party makes an offer. Which probably means the offer will fall through !
Argentex (LON:AGFX) - bit of a shock announcement that Harry Adams has immediately left the business. A sign of trouble to come?....probably significantly increases the risk that the next RNS will be that revenues are below expectations! Forecasts were looking very difficult based on YTD trading anyway, particularly with the higher cost base.
The fact that both founders have now exited (as well as the Chairman) says it all really. Business model isn't really working - costs increasing much faster than revenues. Fortunately I exited, at a c10% loss, after losing confidence in management back in July.
It may be worth another look next year if Pacific Investments (Henry Beckwith), who are a major shareholder, are behind the strategy reset as they are quite good. That's what initially gave me the confidence to invest in AGFX.
Argentex (LON:AGFX) Down 25% this morning wow what a reaction to a stock that looked quite cheap before is there something else amiss?
My read on Argentex (LON:AGFX) is that the market strategy review highlighted a number of growth areas Harry wasn’t focused on. The guy doing it and now the new CEO has a strong track record at building and selling businesses and major shareholders, fed up with the persistent share price declines, decided to back him. A coup? Maybe but ironically I think I’d back the new guy more. Perhaps that was also the boards thinking.
Interestingly the broker hasn’t changed forecasts and you would imagine the company has spoke to them given a new note appeared this morning. The company also didn’t mention trading, which they are obligated to do if they are aware of anything more than a few % variance to forecast, so one has to assume (tho am not blind to companies not always doing what they are supposed to!!!) that trading remains broadly in line.
After todays drop a lot of the market cap is net cash (about 40%) so a cash adjusted sub 5 PER looks very unjustified (unless of course there is something hiding that we aren’t being told - in which case they would be in breach of MAR but it’s not impossible of course). In reality it’s liquidity driving the SP - £400k worth of shares on a now £80m cap company - so investor uncertainty more than anything.
Argentex (LON:AGFX)
I know little about Argentex, but wonder if there is any read across to EQLS which I hold.
My reading of the Argentex (LON:AGFX) RNS this morning is not positive.
It was a very blunt and clear message saying that Harry Adams departs immediately, no thanks, nothing. This is unnecessary and very negative. They could easily have thanked him but chose not to - would have looked better to the market and a poor move in my opinion. There has been a fallout. The board are unhappy with Harry Adams.
It is likely there is trouble ahead even if it has not been mentioned yet. If everything was ok, they would have said trading inline but nothing mentioned. I suspect a warning is coming. A change of strategy and sudden sacking of CEO for an interim CEO is not good. A change of strategy implies the previous one was not good and a change of strategy usually requires Capex.
I do not hold Argentex (LON:AGFX) . I do hold Equals (LON:EQLS) . I do not think it is a sector thing just very poor management at Argentex (LON:AGFX) . I think it actually shines a positive light on Equals (LON:EQLS) and how well their management have looked after their business. It is worth mentioning Richard Cooper the highly impressive CFO at Equals has been exercising his options at the earliest opportunity which has cost him approx £700k of his own money.
Problem is Michael that you’re just making guesses. It’s like trying read tea leaves.
It could be a falling out, it could be impropriety, it could be a coup that was not well received by Harry. Ie it could be many things.
It could be trading but if it is they are in breach of MAR (the obligation is to report changes immediately - not even wait till 7am rns…..it’s immediate). So a breach of that would be bad! However, broker note came out this morning and said in-line with trading update due in Jan. As the company will have spoken to the broker that suggests to me no real change in trading and to be fair given market volatility in FX markets recently I would expect them to be doing ok in voice broking business. Doesn’t rule anything out of course, as not all companies behave scrupulously but they are also a regulated business so I’d be surprised.
Uncertainty is not a shared friend though so in the absence of a full explanation of the change the selling is unsurprising particularly in current market conditions.
What you would say though is that new CEO is top drawer- so for all those chomping for a change of mgmt to lead the business…..we’ll you now have it and he’s certainly credible!
hi davidjhill
Argentex (LON:AGFX)
What you would say though is that new CEO is top drawer
I don't know much about the new Interim CEO Jim Ormonde other than what is stated in the RNS so I respect your view of him.
What surprised me (in addition to the suddenness of Harry Adams exit without thanks) was that they have sourced an outsider at such short notice. This perhaps signposts a coup as being more than possible.
Jim Ormonde wasn't a non-exec nor was he in the employ of Argentex. However, the RNS does state that he has previously acted as a consultant for Argentex.
He may well have been part of the team who conducted the review of Argentex's strategy (but we don't know for certain). If indeed he was part of the strategy review team then he is likely to have had a major role in triggering the exit of Harry Adams.
There is clearly much that we have not been told and which we may never learn.
All rather unsatisfactory in my view.
I don't hold.
Snazzy
Hi Snazzy
Yes and I suspect the “we won’t know” bit is most of the reason for the fall. A surprise and a possible overhang if Harry sells his holding. Markets hate uncertainty.
Everything else is conjecture. Paul’s point About Cab Payments Holdings (LON:CABP) is irrelevant as they are floundering due to a specific African ccy problem. EM FX can be fraught with challenges but this isn’t Argentex (LON:AGFX) game at all.
In fact since the interims there has been more ccy pair volatility which should play fine to the voice broking part of the business you’d expect.
It's important to note that Argentex (LON:AGFX) has a different business model to Equals (LON:EQLS) . Argentex (LON:AGFX) is focussed on selling structured products to the finance sector. This requires higher investment in sales people and more complex and therefore expensive back office operations.
Equals (LON:EQLS) is focussed on less complex payment related FX products across multiple sectors. It leverages technology investment in two ways - 1. 'ease of use' technology for clients with automated straight through processing and 2. effective client on boarding and transaction risk management ie sanction/embargo monitoring and reporting, fraud prevention detection etc
Impropriety came into my head perhaps due to the high profile CEO resignations such as Looney's at BP recently, as why would it be so sudden.Surely if it was something pertinent to the fundamentals of the business the CFO would have left too?The market is clearly spooked though........Perhaps a buying opportunity for the extremely brave in these market conditions..!Someone is buying the 'dip' though so far..
Oh I miss Orac. When robots had proper voices - like Alexa but with less notifications.
Not a small cap but nice solid half year figures from Bloomsbury Publishing (LON:BMY) this morning. Steady growth across the board (even with a cost of living crisis). They are significantly diversified now, but would you believe Harry Potter and the Philosopher's Stone is the 4th best selling kids book this year in the UK!
Bloomsbury
As usual lovely simple presentation with rock solid set of results
39 million cash
32.5 million profit forecast
33&0 market cap
This is my favourite share, a sleep at night great company in a nice sector with superb management .
Note also the complete lack of mention of EBITDA in its presentation.
It’s never going to be a 10 bagger but is a real good anchor holding to any portfolio .
I think its a quality business who year in year out perform with a strong net cash position being c. 12% of the market cap. Potential upside for me in two places - acquisitions, which they do well and have done 19 since 2008, and the move from print to digital in its academic space which you'd expect significant margin improvement here.
As with most shares at the moment its incorrectly priced and for me should be on at least a 15 times P/EV multiple.
Bloomsbury Publishing (LON:BMY) is a small cap, around £320m.
Fair play - I think of it as mid but that's my mistake.
When you read the RNS for Bloomsbury Publishing (LON:BMY) it makes you appreciate how detailed and clear an RNS should be. A number of deceptive and misleading companies could learn a lot! Very happy to have bought a mid-large holding a few weeks ago following discussion with readers and some further research. BMY seems about as solid of a company as you are going to find in the current climate.
My morning smallcap tweet: Extra topping for RTN offer?
Argentex (LON:AGFX) Safestyle UK (LON:SFE) Kromek (LON:KMK) Restaurant (LON:RTN) Hellenic Dynamics (LON:HELD) Sutton Harbour (LON:SUH) International Personal Finance (LON:IPF) Next 15 (LON:NFG) Haydale Graphene Industries (LON:HAYD), Mattioli Woods (LON:MTW), Filtronic (LON:FTC), Foxtons (LON:FOXT), Braemar (LON:BMS), Alumasc (LON:ALU)
◄Argentex (AGFX)► CEO scarpers. He is not thanked. [SP=94.2 Cap=107m]
◄Safestyle (SFE)► lenders slam the UPVC door in company's face. Talks continue on sale of some or all of the Group's business and assets. [SP=1.69 Cap=2m]
◄Kromek (KMK)► $5.9m 4 yr contract from the US Department of Homeland Security. [SP=4.1 Cap=25m]
◄Restaurant Group (RTN)► PizzaExpress requests due dil but no indication of possible offer price. [SP=66.5 Cap=512m]
◄Hellenic Dynamics (HELD)► $3m unsecured convertible Loan facility with RiverFort. 15% PA with warrants. Strike 9.884p, a 40% premium. [SP=0.07 Cap=9m]
◄Sutton Harbour (SUH)► extends full repayment of £1.6m loan to 13 Dec but will pay £900k of it on time. [SP=15 Cap=21m]
◄International Personal Finance (IPF)► Q3 has continued to perform ahead of internal plans. [SP=128.5 Cap=288m]
◄Next 15 (NFG)► £30m max buyback. [SP=625 Cap=633m]
◄Haydale Graphene Industries (HAYD)► FY-June. Outlook: "remains confident that the Company will be able to take advantage of the traction it is now seeing." If it can't get additional debt it is very likely that it would need additional equity funding. [SP=0.44 Cap=8m]
In line: MTW, FTC, FOXT, BMS, ALU
Good morning Paul. Regarding SCS (LON:SCS) which I hold, don't you think Bidco is falling over itself to snare SCS? Here is what I have just read:
"The boards of Poltronesofà S.p.A. (Poltronesofà) and ScS Group plc (ScS) announced that they have reached agreement on the terms of a recommended cash offer by Cerezzola Limited ("BidCo"), a wholly-owned subsidiary of Poltronesofà, for the entire issued and to be issued share capital of ScS (the "Acquisition"). It is intended that the Acquisition be implemented by way of a Court-sanctioned scheme of arrangement under Part 26 of the Companies Act. Prior to the Scheme becoming Effective, a request will be made by ScS to the London Stock Exchange to cancel the admission to trading in ScS Shares on its Main Market for listed securities to take effect on, or shortly after, the Effective Date and the FCA will be requested to cancel the listing of the ScS Shares from the Official List on, or shortly after, the Effective Date.
On the Effective Date, share certificates in respect of ScS Shares will cease to be valid (and should be destroyed) and entitlements to ScS Shares held within the CREST system will be cancelled. As soon as practicable after the Effective Date and after the cancellation of the admission to trading in ScS Shares on the London Stock Exchange's Main Market for listed securities and the cancellation of the listing of the ScS Shares on the Official List, it is intended that ScS will be re-registered as a private limited company under the relevant provisions of the Companies Act."
Personaly I would like to see a competing Offer.
Silver Moon
Hey Silver
Good luck whatever you decide to do here with SCS (LON:SCS) . I got caught out earlier this year with the Apollo bid for Wood Group being withdrawn. At an sp of 220p the bid was 240p and pre bid price was around 140-150p. Fortunately sold holding in ISA but got too greedy with the larger holding in SIPP. Where are we now? All the way back down the ladder!
Now plan to work off a 3 or 4 to one rule and use that to inform my judgement. For Wood it would have said downside 4x the upside, so take the money. Not sure how much upside you are hoping for on ScS. And also easier said than done.
Always have Paul's suggestion to sell half immediately and then think about the rest in the back of my mind in these situations. Your holding, your call. Just wish I'd pulled the trigger and had the same riddle to solve. Best.