Small Cap Value Report (Thu 27 July 2023) - LOOK, HEAD, JUP, VLX, CMCX, GMR

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Rather a lot of gaps today, so Graham has offered to help me do some catch-up items tomorrow.
Do add your own views on announcements in the reader comments, we like it when subscribers do that! :-) Especially when you spot something interesting (e.g. a big contract win, or trading ahead of expectations) -
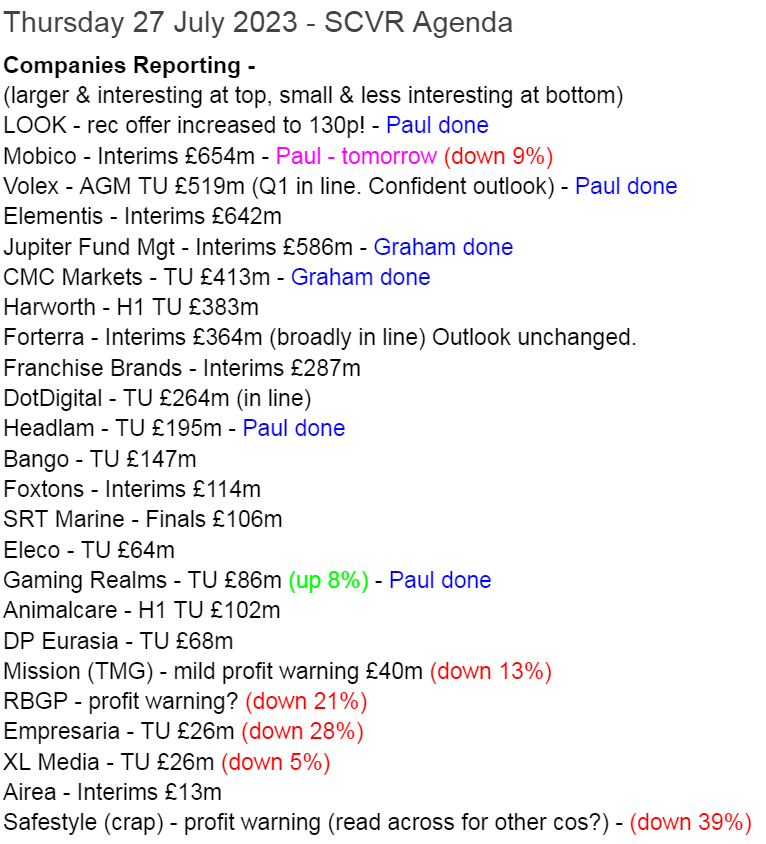
Summaries of main sections below
Jupiter Fund Management (LON:JUP) - up 16% to 125.6p - Interim Report - Graham - GREEN
The market is pleased by these numbers: profits are up as bonuses and other costs are down. The fund range has been rationalised. Everything seems to be going according to plan for the new CEO and I continue to believe that the shares have been unduly depressed.
CMC Markets (LON:CMCX) - down 1% to 146.6p - Trading Statement - Graham - GREEN
Trading activity by CMC’s customers remains weak, and that’s no big surprise. The company’s plans are unchanged and it continues to target 30% growth in net operating income by 2025 (vs. 2022). I believe this sector offers great value (disclosure: long IGG).
Lookers (LON:LOOK) - recommended bid increased to 130p
Headlam (LON:HEAD) - 239p (pre-market) £193m - Trading Update (profit warning) - Paul - AMBER
Profit warning initially slammed the share price, but recovered to -10% - rather encouraging I think, as it seems some investors had already anticipated a slowdown due to tough macro. Bulletproof balance sheet. Could be a nice recovery share medium term I think.
Volex (LON:VLX) (Paul holds) - Up 2% to 293p (£529m) - Trading Update (AGM) - Paul - GREEN
A reassuring update from this wiring products group. Trading in line, and confident outlook. Looks excellent value to me, hence why I hold some personally.
Gaming Realms (LON:GMR) Up 7% to 31.7p (£93m) - Trading Update - Paul - GREEN
My previous scepticism is removed now, by strong performance, and a valuation that can be justified. Worth you having a closer look at this one - I've only done a quick review due to time constraints, as always here.
Paul’s Section:
Lookers (LON:LOOK)
Good news here for holders - Global Auto Holdings has just announced an increased cash offer of 130p (and recommended by Lookers Board, it says). Previously it had offered 120p, but the deal looked to be falling through, as institutions were selling in the market, and major shareholder Cinch pulled its support for the 120p deal. Shares had dropped down to 98p by yesterday, and it was starting to look interesting as a possible buy back in situation, which has now been scuppered by the higher bid - it's likely to gap up to something like 128p on the opening bell (writing this at 07:35).
For technical nerds, it’s also been switched to a “Takeover Offer” instead of the previous scheme or arrangement.
It only has 11.2% support for the deal so far, so it will be interesting to see if 130p is enough to tempt existing holders to back it.
I banked the profits at about 119p on my imaginary holding in my 2023 top watchlist, as a bird in the hand and all that, especially in uncertain times. It’s not a binary decision anyway, we can sell none, some, or all of our shares in a company when a takeover bid is announced. A nice dilemma to have (providing there’s a good premium on offer).
Headlam (LON:HEAD)
239p (pre-market) £193m - Trading Update (profit warning) - Paul - AMBER
Headlam Group plc (LSE: HEAD), the UK's leading floorcoverings distributor, is providing a Pre-Close Trading Update in respect of the first six months of the year to 30 June 2023 (the 'Period') ahead of announcing interim results on 5 September 2023.
H1 revenue £332m (up 2.5% on H1 LY)
Recent trading soft, especially residential (volumes down 20%, partially offset by price rises).
Inflation hitting profits, especially wages & energy, £5m headwind.
Profit warning -
…taking a prudent view, it is now anticipated that the Company's underlying profit before tax for the year will be significantly below current market expectations**
**Company-compiled consensus market expectations for revenue and underlying profit before tax, on a mean basis, are available on the Company's website at www.headlam.com
Revised guidance -
Underlying profit before tax in H1 2023 was therefore lower at £6 million (H1 2022: £17 million), which also reflects strategic related investment to support future growth. Strategic investment is expected to total £6 million for the year, of which over half is in relation to the trade counter roll-out to support its growth to a £200 million business unit.
Outlook/Dividends - rather convoluted wording here. I think they’re trying to say that divis will be maintained, hence cover is reduced?
While current trading is challenging, the Company's strategy and investment in the business gives the Board confidence for the future, with increasing contributions from both strategic and efficiency actions. As a result, and supported by its strong balance sheet, the Company intends to temporarily lower its dividend cover in respect of the ordinary dividend payment for FY23 to that of pre COVID levels.
It’s not at all clear what that means. Badly worded.
The Company is well positioned despite the market backdrop, with ongoing expansion of its market leading position, broadening of its market presence, increased revenue streams, and ongoing efficiencies. All of which will support future financial performance, particularly as volumes return.
Paul’s opinion - a key problem with HEAD is that they don’t get any broker research out for private investors to see. So at this stage, I don’t know what the revised EPS forecast would be. With H1 uPBT now down almost two-thirds on last year, simply extrapolating that out suggests to me that last year’s FY EPS of 41.1p might turn into something like 13p this year possibly? That compares with current consensus of 28.4p, so this looks a big profit warning unfortunately.
Expect a harsh drop in share price, maybe 20-30% today, at a guess? (written just before the opening bell). But remember HEAD has very solid asset backing, with loads of freehold, so you have plenty of downside protection here, hence no reason to panic in my view.
EDIT: good to see buyers come in, after the initial plunge. only down about 10% now at 214p (at 09:58) - that seems quite encouraging to me, although only 210k shares printed as traded so far. We have no idea what's going on in the background (larger buy/sell orders being worked, which don't get printed until later). So we can't draw conclusions from short term price movements, but I think it does at least show that very few small shareholders are panic selling on this profit warning. That seems quite encouraging. It's only slightly above the pandemic lows now, which seems a bit overly pessimistic. The share count has dropped too, due to buybacks. Price is also below NTAV. So lots to like here, for patient investors only, looking beyond the current downturn. I do worry somewhat about the emerging competitive threat from Likewise (LON:LIKE) though, which is probably the main factor (alongside macro worries) which makes me hesitate in buying any HEAD for now.
Volex (LON:VLX) (Paul holds)
Up 2% to 293p (£529m) - Trading Update (AGM) - Paul - GREEN
Volex plc (AIM: VLX), the specialist integrated manufacturer of critical power and data transmission products, is pleased to report a trading update for the three months ended 30 June 2023, ahead of the Company's annual general meeting, being held at 4:00pm BST today.
Interestingly, the AGM is being broadcast live I think, on InvestorMeetCompany at 4pm today. I’m not sure if they’re going to do a presentation too, or just the formal AGM business?
Volex has been pleasing shareholders with positive trading updates this year. Also a recent placing to part-fund another chunky acquisition was well supported, at no significant discount, for what looks another excellent deal. I’m very positive about the performance, prospects, and modest valuation for Volex shares, and it’s been my podcast mystery share twice this year. I also picked up a few personally a while back, and am happy to continue holding.
Today it reassures again (good, in such tough macro conditions in my view) -
Trading continues to perform in line with management expectations and the Company is pleased to report a continuation of the positive trading momentum experienced in the prior year, with year-on-year constant currency organic growth of 6.5% recorded in the first quarter of the 2024 financial year. ..
Overall, trading for the first quarter is in line with the Board's expectations, and coupled with the encouraging trends in the first quarter, gives the Board confidence that the business will continue to make further progress in the year.
Other points -
- Margins holding up
- “Healthy” customer demand
- Supply chain improving, and some customers normalising inventories
- New customer project wins, incl next generation data centres hi-speed cables - AI driving growth, and electric vehicles.
- Latest acquisition (Murat Ticaret) expected to complete in 2-3 months.
Paul’s opinion - good in tough circumstances. Volex has established a very good track record under the latest management team. It seems to be adept at bolting on cheap, but good businesses that complement its existing business, getting some synergies, and broadening markets & products. Often these seem to be retirement sales, where cultural fit, and sensitivity towards the vendor & staff, can be just as important as price, which is what Nat Rothschild was saying in the last (very bullish for him) webinar.
Once the next bull market in UK small caps starts, and I think we may be arguably at or near that point, then I could see a double benefit for Volex shareholders - a re-rating from its current PER of 11.6x, to something more like 15-20x, combined with growing earnings both organic and acquisitive growth.
This looks a perfect type of situation I want to be invested in actually, taking a multi-year view.
What’s the downside risk? As with anything, just something unforeseen going wrong. In the absence of that, I imagine Volex shares shouldn’t have too much trouble pushing up from c.300p to 400p+ in the not-too-distant future, as the fundamentals justify that already, I reckon.
Stockopedia agrees, with a StockRank of 87.
If any readers disagree, then I’d love to hear from you, to see if there’s anything I’ve missed that concerns other investors. We want courteous bull-bear debate here, it’s not an echo chamber, so post away freely, whatever your views :-)
A nice looking chart too -
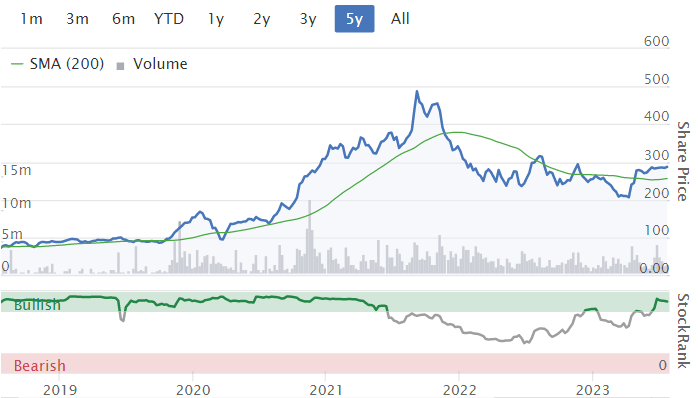
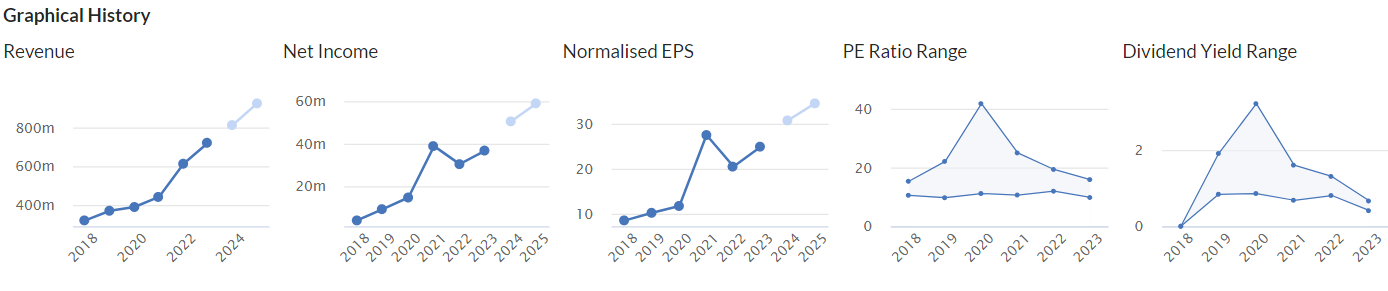
Note that the share count has roughly doubled over this period, to part-fund acquisitions. However, as the graphs below show, EPS has risen strongly, therefore the acquisitions have added shareholder value. Some dilution can be good, if it's to fund great acquisitions or investment that adds more value than it dilutes -
Gaming Realms (LON:GMR)
Up 7% to 31.7p (£93m) - Trading Update - Paul - GREEN
Gaming Realms plc (AIM: GMR), the developer and licensor of mobile-focused gaming content, announces a pre-close trading update for the half year to 30 June 2023 ("H1'23" or "the Period").
The market has reacted positively to this update, shares up 7%.
This sounds good, although as with so many companies, it’s a pity they only report the sometimes unreliable EBITDA as a profit measure -
The Company is pleased to confirm that it expects to report H1'23 revenue of c.£11.4 million and adjusted EBITDA* of c.£4.6 million, up 34% and 32% respectively, year-on-year. This strong performance was driven by the continued growth of the Group's licensing business, which consolidated its market share by going live with 25 new partners and launching 5 new Slingo games.
Good year-on-year growth there in both revenues & EBITDA.
Forecasts - many thanks to Canaccord, whose analyst Mark Photiades has crunched the numbers - making no changes to existing forecasts, but pointing out the positive update today leaves forecasts “well underpinned”, which I interpret as meaning that the risk of a profit warning is probably low.
FY 12/2023 forecast is for £10.1m EBITDA, so with £4.6m in the bag for H1, that leaves £5.5m for H2 - seems reasonable considering the good growth momentum, and new product deals mentioned today (as an aside, I like the sound of Tetris licensing, as that’s the only computer game I’ve really enjoyed playing in my adult life).
Indeed the company confirms full year expectations -
This strong momentum in the Period gives the Board confidence that the Company is on track to meet its full-year targets.
What about proper profitability? Canaccord’s £10.1m EBITDA forecast for FY 12/2023 turns into £5.9m adj PBT, and 1.6p adj EPS - a PER of 19.8x - not particularly demanding, given the strong organic growth (assuming that continues).
The PER drops to 13.8x on FY 12/2024 forecasts.
Paul’s opinion - this is preliminary view, just on a quick look today, I need to do more research. It looks like 2022 was a breakthrough year, in which meaningful and genuine profitability was reached. That trend is clearly continuing in 2023. I’ve only properly spotted that today, as previously I’ve been quite sceptical about GMR, so haven’t prioritised it as one to look at, although we did flag good growth and a confident outlook here on 1 Feb 2023.
Belatedly, I’ve today had a look at the FY 12/2022 results, which look fine to me. Balance sheet is OK, so I don’t see a need for any fundraise. Also the profit looks real, being stated after amortising a similar amount to what it capitalised in development spend.
Is it worth £92m though? I think that reflects strong performance, but could end up looking cheap in a couple of years, if the growth continues.
The key Slingo product seems to have been widely licensed by online casinos, internationally, so it’s obviously popular with gamblers. I’d like to better understand how much of licensing revenue is recurring, and how much one-offs? Management seemed very unclear about that on a webinar a couple of years ago.
I’ll go GREEN on this, with the caveat that more research is needed, but on an initial review of the numbers & outlook, I like what I see.
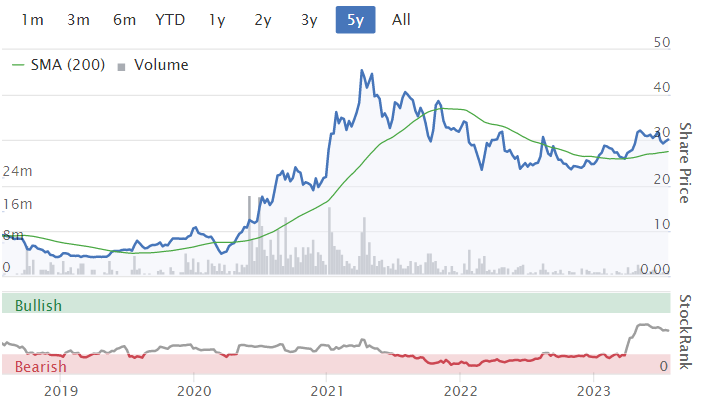
Graham’s Section:
Jupiter Fund Management (LON:JUP)
Share price: 125.6p (+16%)
Market cap: £688m
I’ve been positive on this fund manager since October last year. The share price has been volatile since then, rising by nearly 70% before giving back most of those gains:
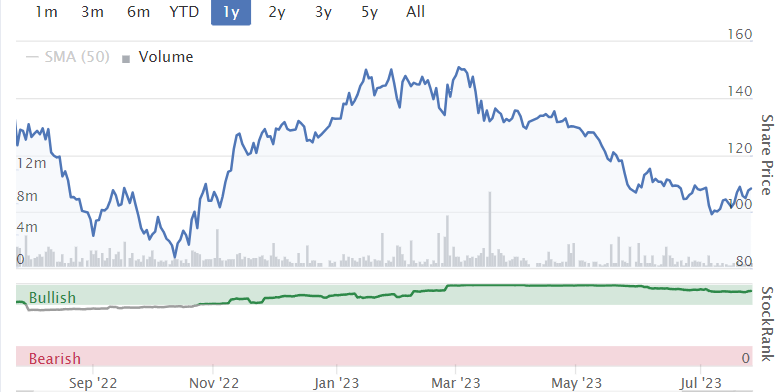
Today we have interim results. For starters, the key points are:
AUM finished the period up 2% at £51.4 billion, although average AUM declined.
Net revenue fell by 11% to £181m.
Staff compensation (excluding performance fees) increased to 41% of net revenues - “to ensure we attract and retain key talent and build scale across the business”.
Nothing too exciting in any of those bullet points, but now let’s look at the performance fees earned (from customers) and paid (to fund managers) by the company.
Last year, in H1 2022, the company earned only £0.7m of performance fees from customers, but it paid out nearly £25m in performance fee-related bonuses to fund managers. This is because performance fees are paid out on a delay. Those bonuses will have been earned in prior years, but would typically be contingent on the fund manager remaining at the company and various other conditions.
In the latest period, H1 2023, performance fees earned from customers have again been very low: only £0.4m. However, the good news for shareholders is that the entitlement of fund managers to get paid performance fee-related bonuses also collapsed during this period. These bonuses only amounted to £3.5m during H1!
In other words, Jupiter saved over £20m by having to pay much smaller bonuses this year compared to last year.
Additionally, the new CEO - who promised to rationalise the range of funds and costs - says that they have “identified higher than expected cost savings” from that programme.
We have also continued to remove undue complexity from within our business, following the restructuring of our operating model last year. The fund rationalisation programme is now mostly complete and, because of the focus on the tail of sub-scale funds, the resulting attrition rate remains low at 0.7% of Group AUM. We remain focused on cost control with further savings identified and implemented.
Lower average AUM also means slightly lower overheads, and the end result is that total administrative expenses fell by nearly £30m in H1, falling at a much faster rate than the fall in net revenues.
Thanks to that fall in expenses, pre-tax profits have risen by an impressive 85% to £34.8m.
Flows - there were small positive net flows in H1, as institutional customers put in slightly more money than retail investors took out.
Flows have been poor at Jupiter at a long time, but the company points out that it also had positive net flows in H2 2022. This means it has just experienced the first 12-month period of net inflows since 2017!
Outlook from the CEO highlights the success of the past 6-12 months:
In what has been an uncertain and volatile backdrop, it has been a good start to the year. Our financial performance has been robust and we have made pleasing progress against each of our strategic objectives.
We have generated net positive flows over both six and 12 month periods and are cautiously optimistic that a well-diversified pipeline will continue to deliver further AUM gains in future periods.
Our capital base is strong and we will look for opportunities to further develop our business, both organically and inorganically. The short-term outlook remains uncertain, but we are well-positioned for growth over the medium term and confident that our strategy is the right one.
Graham’s view
I am already fully invested, having bought into Hargreaves Lansdown (LON:HL.) in recent months, but I need to look under the couch cushions to see if I have any spare change with which I might buy a few Jupiter shares. It doesn’t have the quality that I typically look for, and I wouldn’t make it a core holding, but it does have enough profitability and cheapness to keep me interested.

The stock has never been more unfashionable than it is today. But I don’t believe that active funds are destined for extinction at the hands of passives, and I don’t believe that sentiment around UK funds can get any lower than it is right now. The new CEO at Jupiter is doing what he said he would do, and I’m a believer.
CMC Markets (LON:CMCX)
Share price: 146.6p (-1%)
Market cap: £410m
It’s a Q1 update (April-June) from this spread betting/forex trading provider.
Consistent with the Group's expectations announced on 13 June, quiet market conditions in the first quarter have resulted in a decline in client trading and investing activity of 15-20% year on year. These conditions have continued into the start of Q2, however weaker client activity has been offset by stronger interest income, resulting in overall net operating income tracking at a similar run rate to the same period last year.
It’s easy to forget how many financial companies benefit from higher interest rates. We really need to watch out for them. So many years of ZIRP made it easy to forget how their business models used to work!
Back to CMC, it says that its “underlying KPIs”, such as the number of active clients, remain “robust”. That bodes well for trading revenues to improve when activity picks up.
Excluding staff bonuses, the company’s spending plans for the current year (FY March 2024) “are in line with prior guidance”. More new products will soon be launched: cash equities for institutional clients, more options and futures, and the share dealing platform will be enabled for SIPPs and mutual funds.
Graham’s view
This share is down by 40% since January, when I was positive on it. So my stance then is not looking very clever right now! It had a P/E ratio of 11x at the time.
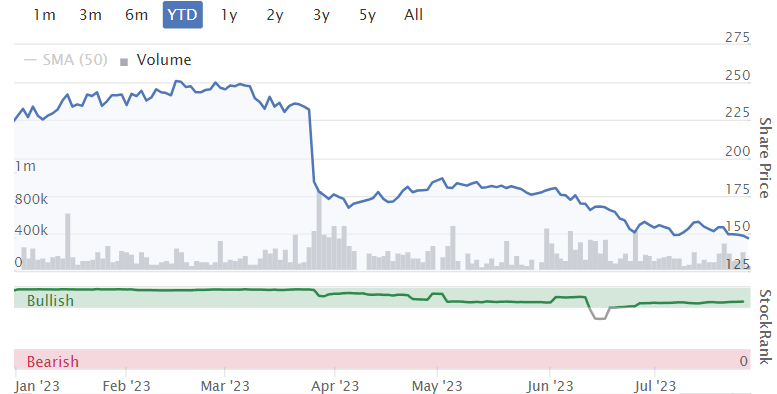
Most of the damage was done in March, when the company said that net operating income for FY March 2023 would be £280-£290m (it had already earned £153m in H1, so it was acknowledging that H2 would be weaker than H1). EPS estimates have been on a downslope:
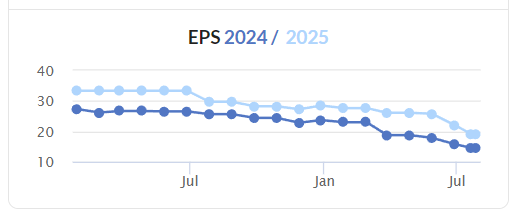
Full-year results were published in June, and covered by Roland here. The company remained bullish on prospects out to 2025, saying “Expectations of the underlying 30% net operating income growth from 2022 to 2025 remain unchanged”.
In the short-term, however, profitability is going to be squeezed. Net operating income might be c. £290m again this year (including interest income), but then costs will remain high at around £240m, excluding staff bonuses.
It is very much looking as if FY 2024 will be a slow year for the company, as client trading activity is simply too depressed right now.
Personally, I still like the odds offered by this stock over the long-term. Although perhaps my bias is too strong when it comes to this sector: IG group (LON:IGG) is my third largest personal holding and I also think that one is far too cheap! So maybe I’m overly fond of this sector.
While profits at CMC may be a bit thin this year, the company will be set up with more institutional products and a richer retail offering both in the UK and for its Singaporean customers, and will be well-placed when trading sentiment improves.
The 2025 target does look very challenging at this stage but even if it misses that target, I still think a long-term holding in CMC shares could work out well. Lord Cruddas continues to steer the ship with his 59% shareholding and I wouldn’t mind owning a few shares in this one to see where he can take it from here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
ARM get themselves back on the market later today - def worth a look for trading long/short
Headlam (LON:HEAD) revised estimates have come in as
Headlam Group PLC (9:34:07 AM)
Profit forecast decreased from £30.5m to £16m (Forecast year ending 12/23)
Thanks tic_tac_toe, that's very helpful posting the updated broker consensus for Headlam (LON:HEAD)
A forecast drop from 28.4p to 14.7p is quite nasty. My early guesstimate of c.13p in the main article was in the right ballpark I'm pleased to see!
The question now is how do we value HEAD shares? On a simple PER basis, at 222p per share current price, the PER is now 15.1x FY 12/2023 latest forecast. But does it make sense to value any share on a multiple of a bad year's depressed profits? That depends on whether you think it can recover to previously normal earnings of about 40p. Also note that the share count seems to have fallen, so it must have done buybacks.
In that recovery scenario, the PER would be only 5.6x, so I would say the bull case could see the share price double.
Or if we take a middling forecast of say 30p EPS, then the PER now would be 7.4x, still attractive I'd say, for a group with a bulletproof balance sheet, and a cash generative business that likes paying out generous divis historically.
The only question mark to me is how much growing competitor (run by HEAD's old CEO) Likewise (LON:LIKE) is impacting HEAD? It's targeting £200m revenues, although this year is forecast to do £137m. So it must be eating some of HEAD's lunch? Although since LIKE is partly growing by acquisition, then maybe it's not necessarily eating into HEAD's market share, as those revenues were already being generated by existing competitors. Lumping then together into a group under the guise of LIKE would therefore not necessarily indicate HEAD is losing market share. Although it might put additional pressure on margins, as LIKE is only operating a little over breakeven, so might be buying market share through discounting perhaps? Who knows, I'm just guessing really.
The big rebound on Thursday's profit warning, suggests to me that HEAD shares might be close to a low. Although they're not terribly liquid, so it would only take one big holder trying to sell in the market, to continue the downtrend.
Interesting though, I'm tempted to dip my toe in, but will wait a few weeks to see where the dust settles. Buying after a profit warning is usually a mistake in the short term I've found.
Regards, Paul.
Thanks Wol and rmillaree - yes, why wouldn't they just buy a few investment trusts and cut-out the expensive middle-man? I suspect the truth is somewhere between not understanding investments, being caught by a pushy financial adviser and being able to tell your friends that St. James's Place look after their wealth, which sounds very impressive!
Every couple of days I see adverts to sue St. James's Place and their complaints provision seems to be increasing. This sort of investment advice might have worked 20 years ago, but surely its not in the best interests of consumers anymore, who shouldn't be paying much more than 1% if they want to do well. I will definitely take it off my watch list despite the impressive returns.
St James's Place (LON:STJ), the blue-chip wealth manager... this is above the mid-cap size limit, but this comment caught my attention:
Clients are charged an initial advice fee of 4.5 % cent of their investment value and pay an additional 0.5% annually to cover the cost of their adviser. They are also charged an initial product fee of 1.5 % and an additional 1 % on an annual basis as a product management charge.
The 1% is going to 0.85% causing todays share price decline.
I hadn't realised that they charge initial fees so high. Sounds like 6% initial and 1.5% ongoing. No wonder they have a lot of litigation and complaints. How do investors get a return? That's £1 turning to 94p and then 92.5p by the end of the first year before investment returns. Hmm I think I will take STJ off my watch list!
How do investors get a return?
They probably don't unless the times are good
A few years ago a friend spoke to me about her husband's investments, managed by St James's Place (LON:STJ) . In order to help I asked her the obvious questions - what return has he had on his investments, which benchmarks do they use as comparatives... The answer she gave me (of course this is just third hand) was that he had no performance data on how his portfolio was doing but that the nice man at St James's Place had assured him that his portfolio was going just fine.
This may of course be an exception or my friend's husband may not have wanted to tell his wife. But we are English which means unwilling to complain or ask any questions which might cause embarrassment to someone. And of course it is easier to stay quiet than to admit our original decision (to invest through STJ) may have been a mistake. Especially after such a hefty entry fee
I also had another look more recently when another friend asked my advice while considering an investment with STJ. For this friend the charges were clearly laid out with a prospectus of possible funds that they would use. Some are unavailable to buy directly, others are also available to the retail investor or at least very similar to those available on the market. Past performance of these funds was acceptable but hardly spectacular (not close to e.g. Fundsmith) even before the STJ charges
Why bother when there are good unit trusts or investments trusts available?
SJP is style over substance - very slick and glossy - but you have to pay for it. I cannot believe people still believe the hype .
STJ
Incredibly the client retention rate is around 90-95 %
most clients pay for other services like inheritance tax planning.
Generally speaking, it is serving the rich which has been a very good business to be in, at least for the management and the army of advisors.
Had been planning to ditch CVS (LON:CVSG) but today's update makes it my best performer of the day. Must be something special that their new Aussie vets dispense (up 9%). Just so long as their consolidation of independent operators doesn't result in a similar fate to that of Dignity.
Mobico (LON:MCG) Not sure what has caused the fall in these shares. The figures seemed to be ok to me ?
Mobico is on the agenda for Paul to review this pm. I am eagerly waiting for that!
Sorry, I don't think we're going to get round to Mobico (LON:MCG) today. Productivity here peaked on Mon-Weds I think!
I seem to be incapable of picking a winner ATM. Thought it looks a good recovery play and the update looked ok to me. Still wtfdik
Right now you know 1 thing more than I did about 8 years ago
wtfdik
And over 2022, it seems a lesson I needed to be reminded of.
Very few people "pick winners" successfully.
Most successful investors pick a portfolio using a set of rules, which can change over time. Over the last few years PS has (i may be misunderstanding) become rather less "aggressive" in use of leverage and growth assumptions and recently places more weight on net cash, profits, stable income.
The market currently likes only Ahead results, anything else is punished badly. Mobico and St James Place are examples!
The market currently likes only Ahead results, anything else is punished badly. Mobico and St James Place are examples!
Both Forterra (LON:FORT) and CMC Markets (LON:CMCX) reported what could be described at best as lacklustre results today and they've hardly moved. There are a lot of companies out there that have been so badly hammered already in expectation of poor results that actual poor results don't make any difference. It's classic value territory, but many of these stocks are of decent quality, albeit cyclical.
In many ways the market is a coiled spring - if any of these beat expectations, however low, they'll bounce. Problem is, of course, we'll never see it coming ...
timarr
Hi Tim
Are you a holder of Future (LON:FUTR) ? Are you able to add any thoughts to my comment below? Would be very interesting to hear your views. A new company to me but looks very cheap?
Hi NnG
Are you a holder of Future (LON:FUTR) ? Are you able to add any thoughts to my comment below? Would be very interesting to hear your views. A new company to me but looks very
cheap?
I did hold for a while but sold at the £12 mark.
It's a tough one - it is obviously cheap but the profit warning in May spooked the market. The problem is advertising revenue, which I suppose is unsurprising. But debt is down (still too high in my view, but I'm risk adverse) and FCF looks OK (I haven't checked that the Stocko numbers are correct and there aren't any funnies in the accounts but if the numbers are correct it's very cheap on a FCF basis).
Overall I reckon it'll be OK but advertising is an easy save for companies looking to cut costs and Future is right in the firing line. Also they have to deal with the secular decline in physical magazines (although they're holding up quite well, it's the digital side that's suffering).
It's cheap but I struggle to see how this was ever valued at £40 a share. The buyback program is a step in the right direction, buying back around 5% of the company. So ... yes, probably it's a weak buy. It'd have been a better one at around £6.
Along with most of the market it'll probably recover quite sharply when confidence returns. Advertising driven stocks tend to be chained to the economic cycle but I'd be amazed if it ever returns to the nose bleed valuations of the past.
timarr
Thanks Tim, I appreciate your input
Re Future (LON:FUTR)
I thought I remembered you holding these in the dim and distant. Obvious problem here is the potential for fall off in advertising revenue, as you suggest.
However the large CEO purchase together with the buy backs seems to put a floor under the share price at this level?
Agreed that previous valuations appear to have a very US stock market look about them!
Mobico (LON:MCG) looked pretty good to me and not sure why down 9%. Obviously a lot of debt and no asset backing, but that was all known - in fact debt has come down quite a bit.
I think a number of traders jumped into this one Mobico (LON:MCG) in the hope of a big bounce. Only yesterday there was a 4% rise in the SP before the bell, wind back to July 7th and the SP was 5p lower than it is currently after the 9% drop. Most of these will have jumped ship today disappointed. You only need to check the bulletin boards to read peoples displeasure at the lack of movement in the SP. Personally, I'm more than happy to hold as provided the forecasted 200+ million profit is to believed and comes to fruition, the cash generation is so high that even a premium bid could see the company pay for itself in around 5 years. An attractive bid proposition target and a respectable Divi to collect whilst a gentle recovery takes place. For what it's worth, in the short term I do think it will drift back up a little tomorrow and next week.
Very interested to hear Paul's take tomorrow.
Ben
Thank you Paul re RBG Holdings (LON:RBGP) I quite understand.
I do agree it really is a dilemma I cannot decide if it is too cheap or too expensive either!
Thanks for your segment on Jup. As a real novice it really helped with figuring out some of the more detailed bits on the figures side of things. As my very basic rationale for investing in it was slight instituional increase and the natural big outflow of retail in UK, depressed funds, of which my very basic thesis is when the UK starts rebounding (hopefully sooner rather than later!) more of them will return as everyone loves to back a winner (buy high, sell low kinda thing) and hates watching 'their money disappear'.It's nice to see they have a new and perhaps better CEO too!
You're welcome, SD! I've been really impressed with the new CEO's strategy. Hopefully they will buy back some more shares in the next few years, too. Graham.
Jupiter Fund Management (LON:JUP)
No fuss update from Sylvania Platinum (LON:SLP) this morning. Improvements in PGM recovery, "plants exceeding production throughput targets"....."exceeding our increased guidance for the year". Cost movements but nothing major "operating cost focus remains a priority" and so it should at any business. Developments being managed. Cash gen, Div paying, Buying back. Weak technicals since Feb23. Risks remain SA economy and Zim type business takovers/closure.
Thanks for coverage of Volex (LON:VLX) Paul, I might be biased as this is now one of my largest holdings, but looks undervalued to me!
Seplat Energy (LON:SEPL) announces earnings tomorrow. It has seen a nice ride upwards over the past month or so but there has been some unusually bullish activity on its alternative listing, the Nigerian Stock Exchange (NSE) over the past few days.
After conversions the NSE listing is normally priced a few pence higher than the UK listing. However, over the past week this gap has widened significantly. At the time of writing, the UK listing is currently trading at 138p where as the NSE price is at 1862ngn, which converts to 188p. This is a huge gap of 50p! Considering Nigeria's reputation is not one typically described as honest and law abiding, it rings the alarm bells that maybe some local investors know something others do not...
If Seplat Energy (LON:SEPL) was not already my largest holding I would add before tomorrows results. I recognise that an energy stock based in a high risk country is certainly not to everyone's taste but thought some might find this interesting.
As always DYOR!
Ben
Stocko algorithms like Seplat Energy (LON:SEPL) and the chart set up is very interesting. A potential H&S bottom with significant upside target (if it breaks out). I now hold.
Good luck for tomorrow Revs!
Volex (LON:VLX)
my one concern is here is the +6.5% organic growth y/y for Q1. Surely that’s not considered “good”, even with tough macro (only ~40% of their end markets are now consumer electricals) Why does that deserve a 15x-20x PE? Does anyone know what brokers were forecasting for FY24 organic growth ?
I hold, and agree that management have done a fantastic job at transforming the company and have acquired brilliantly too.
Anyone with any broker notes for next 2 years?
my one concern is here is the +6.5% organic growth y/y for Q1. Surely that’s not considered “good”, even with tough macro
I invest in a lot of quality industrial manufacturers. Anything over 5% in organic growth, usually supplemented by M&A to reach mid-high single digits, I consider pretty decent. Provided always that operational efficiencies bring earnings + distributions into double figures. In a tough year for macro, even better.
Interesting piece in shares magazine on active fund managers. Ive always thought 95% of them are a waste of time and the numbers tend to prove it
One big advantage private investors have in small caps is being able to get out of things quickly letting funds take the pain instead, which is always nice. Fund managers will of course always say its better to be in the market etc etc but they would say that wouldnt they.
I mentioned it earlier in relation to Headlam, and I know lots of stocko subscribers are buy and hold investors so wont be interested in timing the market, but one thing I always do is a quick 'am I being an idiot' sanity check (as well as looking at the stockrank graph) when considering buying a downtrending share.
Its very basic, but take Hostmore in 2022 (or majority of 2021 floats for that matter). Could count on one hand the number of times it closed above the 10 d moving average for the entire year. Even if youd bought in July shouldnt have lost anymore than 10-15% stop loss, compared to 85% yearly drop. Basically do not buy until it closes above the 10day trend line!
You can set it up anyway you like but heres what I use. This has saved me more money than anything else over the years.
Very interesting. Thank you
Thank you that's a great insight.
Great stuff keep the pearls coming Wolfie.
Another example here Mind Gym (LON:MIND) . No rally for 2 years!
Director buys £290k and its up 35% in last 4 days. No idea if it holds but pays to stay patient on such an obvious downtrend.
No ADVFN posts for a month. They'd likely thrown in the towel also
Thanks for another great post. I now use the price being above the 30 week MA as per Stan Weinstein's method in his book Profiting in Bull and Bear markets. This has helped me a lot to get into some good trades and stay out of others! I now have the 30week MA as my default indicator on the charts in stockopedia and other software I use.
re: Jupiter Fund Management (LON:JUP)
Hi Ben, you're very welcome!
In case anyone is wondering, here is the link for the SCVR on 25 April where I explain the AUM multiplier. For me it's a simple way of valuing fund managers, The industry standard is to use EV/AUM.
Cheers
Graham
Link
Hi Graham
Thanks for the link. I have recalculated the AUM/EV multiple today using AUM of £51.4bn (from your piece above) and EV £241m (from the Stockreport) giving £213. This appears outlandish compared to the average you quote of £20. Where am I going wrong?
Hi Steve, I used market cap, not EV. Good Q! G
SRT Marine Systems (LON:SRT) I hold
Final results today - I see it's on Paul's list. Big increase in revenue, split £18m from Systems side, £12m from Transceivers business. Tiny profit after tax. Operationally progressing well with 3 live systems. £40m contract in ME (known to be Saudi) where phase 1 is complete. 2 more phases to complete by end 2024. Philippines where phase 1 is operational and further phases are intended, plus Bahrain, a longstanding completed system.
Recently announced £140m contract in Asia (known to be Indonesia) is being prepared for work to start probably by end 2023. Finance from UKEF is being finalised.
Systems pipeline (VSP) is growing and stands at £1.4 bn. SRT are keen to emphasis that all prospects in the VSA are only included when it is clear they have the finance and the political will to embark on a project. Some are in late stage prior to contract signing with possible contracts before long.
Transceivers grew strongly, supplying own brand EmTrak and OEM labelled products. New DAS product gaining traction and expected to become a valuable market. NEXUS product testing period extended to ensure it is as perfect as can be - sees big opportunity from entry into voice market.
Finances improved following recent placing and raised loan note program. Live webcast this morning, recording will be available on SRT web site later.
Commenting on today's results, Simon Tucker, CEO of SRT said:
"Our many years of technology, product and market investments are now starting to show in our financial results. Our transceivers division grew by 60% and our systems division is back on track following a pause in government business during Covid. We go into the new year with an expanded product range and distribution network, a forward contract order book of £160m and a new prospects pipeline of system contracts worth approximately £1.4bn. This position reflects the early strategic decisions made to position SRT at the centre of these substantial global markets."
Jam is getting closer.
At least the toast has popped up.
SRT Marine Systems (LON:SRT)
webcast recording here
https://srt-marine.com/news-2/
Thanks for the link.
At min 10:26 in the presentation, discussing the validated sales pipeline, it sounds to me as though SRT is expecting something to be signed 'in the coming month or so'.
Did I mishear or did Simon mis-speak ?
ATB
Future (LON:FUTR)
Has anyone got any knowledge on what is happening here - this company is starting to look very cheap/oversold? Yes, there is a high level of debt. Very little broker info available to PI's hence my question.
New experienced CEO has made a large purchase of shares (c£800,00 May 23), P/E now only 5.4 but Stockopedia's forecasts show a significant up tick in Net Profit and EPS this year and next. With the P/E this low is the market suggesting a possible profits warning?
Company is now doing buy backs (c£45M) as well, so presumably they think SP is cheap too? I am guessing that concerns around AI may be weighing heavily and of course macro outlook, but surely this has been overdone?
What am I missing here?
(Just squeezes in to our territory with the recently reduced market cap).
For any holders ofPersimmon (LON:PSN) , a mid morning RNS concerning a director change also includes the following statement hidden away at the bottom:
"There is no change to our guidance from that reported in the recent trading update published on 26 April and Persimmon will announce its Half Year Results for the period ended 30 June 2023 on 10 August."
Foxtons this morning reported resilience in its lettings business - offsetting weakness in sales as expected - possibly a good read across to Belvoir (LON:BLV) which is mainly lettings and been weak recently.
Paul I know you have a very long list but RBG Holdings (LON:RBGP) has issued a "kitchen sink" RNS today. I hold a small position. I would welcome your thoughts especially on the comments by our wonderful Mr Contrarian in his post this morning on yesterdays High Court Ruling.
The problem with RBG Holdings (LON:RBGP) are a long list for me.
The Lionfish business feels very much like it was set up on a “we should be doing this” rather than “we have a core competence” basis and as such it doesnt strike me as having a good business model or diversity of caseload behind it. Contrast to Litigation Capital Management (LON:LIT) which has had the case at Supreme Court on its radar for a long time and understood where it had implications for its business model. So the write offs are not much of a surprise to me.
Then you have debt - too much of it
Plus the court case with the sacked ex CEO
And delayed projects
The business needs a complete reset and it strikes me that this is what the new CEO is trying to do. Until the case with Nicola is resolved I doubt they will be able to shake off the negativity surrounding the business though, particularly as she has a relatively large shareholding (so perceived overhang).
I’ve looked at this a few times as a recovery play and I’m just not a buyer. I will watch though as in a couple of years it could look quite different.
RBG Holdings (LON:RBGP) Plus you have spiralling lawyer costs, which will further eat into margins.
FYI RNS issued yesterday that Nicola Foulston has sold her stake
RBG Holdings (LON:RBGP) I can't help but think its a better time to be buying now rather than when everything looked hunky dory at 170p
The RNS this morning reads like a clear up job of the ex CEOs mis steps- lots of non cash /accounting profit implications re the lit fin aspect but not anything too detrimental to the core, profitable, cash generative businesses that now remain.
I wonder if there is a decent improvement to come in debt in the next half due to the dividend saving, a reduction in salaries from lion fish exit, NF remuneration being gone, an uptick on interest income from client monies and completion of some of the Convex pipeline? (EDIT: also will there be any tax payable this year?)
Its worth a read of the Singer note issued today which suggests year end net debt at £20m in the context of £10-12m EBITDA in todays RNS. Also, they say that RBG will need a covenant waiver if it falls at the lower end of the range but not if around the top end.
Personally i'd wait for the price action to form some kind of base but a turnaround doesn't seem out of the question? I've seen much worse!
I don’t disagree Wolfy and thanks for drawing my attention to the share sale as I missed that yesterday.
I’d want to see progress on the debt before taking a position though. I’d rather miss out on a 20% rise and know that debt was reducing, PBT and cash flow going in right direction and this risk of a dilutive placing significantly reduced rather than buying on hope of a turnaround here. If there is a covenant breach I think there’s a high likelihood of an equity raise and I suspect it would be at a significant discount so I will sit on the sidelines until a change of business momentum occurs as I think that’s a better risk/reward profile personally.
As a professional services company a turnaround should be perfectly feasible though - it’s not like they are trying to sell something novel.
Yes that's a sensible approach of course
The only thing I thought re a dilutive placing was that it might be a more simple alternative to sell down one of the group companies as the valuation level for a significantly discounted placing here (after the fall today) would potentially be bettered selling in the market (caveat being its not a fire sale!)
My other takeaway from the current episode at RBG Holdings (LON:RBGP) is what on earth were Progressive Equity doing publishing research on the 17th July (post Lionfish sale) talking about a "forecast 18% dividend yield"?
I don't think many assumed this would be paid or a divi even held but some might have taken them at their word- as paid for research who presumably would be in contact with the company, I think this is unforgivable
You also have to seriously question the quality of the analyst behind the report
Morjning portugull,
I think I'll leave RBG Holdings (LON:RBGP) to others to comment on, as it's a complicated special situation, where I don't think I can really add any value at this stage. Obviously the bank debt is my main worry. Plus all the chaos that the former CEO left in her wake. It's either too cheap, or too expensive.
Regards, Paul ;-)
Airea (LON:AIEA) Interims (I hold) – at £13.5m Mcap this tiny Osset (Wakefield) based carpet (tile) basher is too small to float most investors boat.
Today’s interims are best described as solid? Which in the current environment is as good as its likely to get? Good top line performance:
Revenue £9.8m +15%
Operating Profit £0.836m +10%
but not so good bottom line
pbt £0.62m -5.4%
apparently due to the increase in pension interest cost of £100k. Following the recent triennial review (July 23) there is no deficit contribution to the fund – but apparently an interest charge is payable? Is this another IFRS result of the recent rise in interest rates and arcane DB fund accounting?
Whatever. Other than the pension interest - the accounts are delightfully straightforward to read?
Operating cashflow was £1.2m (up 0.5m) before increase in inventory in advance of new product launches, paying down debt and £0.8m spent on the installation and commissioning of solar power (does the sun shine in Wakefield?) for an increase in net cash yoy of £0.2m.
Net assets have risen to £17.2m (including net cash of £2.7m and a £4m investment property) putting it on a 22% discount to the Mcap – a reasonable margin of safety for the business given the current level of growth in sales and operating profits?
The company notes that they have not been able to pass on steep increases in the cost of raw materials, labour and energy in a price sensitive market. Which is concerning on the face of it – especially given the recent performance of its much larger peers, James Halstead (LON:JHD) and Headlam (LON:HEAD) – but Airea still posted a 10% increasing in operating profits which is quite promising under current conditions and its not unusual for price increases to lag increasing costs in these sectors?
The company has invested heavily in efficient higher productivity machines (looms) for new product launches which should result in considerable operating leverage as volumes rise. The new solar power facility should pay back rapidly with reduced energy costs and the new product launches are design led (and feature 'sustainable' produces) marketed directly to architects and contractors which should enable gross margin to recover whilst not impacting continued growth in sales volumes. Airea is not in the residential market which boomed during lockdowns. It’s in the commercial market which was depressed. Though I don’t see that being particularly significant as Airea’s small size, niche market and new products allow for plenty of expansion, including exports, without overall growth in the commercial market.
No interim dividend – but I’d prefer that they keep paying down the debt for a while yet, and let the rising sales, operating profit and cash take care of things.
I added/bought as a value play during the pandemic, and there still is some value to come out – but the business performance is also looking promising. I particularly like cash-rich well invested niche businesses with unacknowledged growth prospects, the ability to buy the business at a discount to tangible assets limits the downside and lack of recognition of the growth prospects enables future multiple rises. It’s never going to be a rapid multi-bagger more of a steady compounder?
Cheers
Mark
Great comment. Thanks Mark.
Jupiter Fund Management (LON:JUP) - Want to give a thanks to Graham on this one. He explained his method of valuing fund managers (EV/AUM) and I bought Jupiter a few weeks ago after running the numbers for most of the asset managers. Jupiter Fund Management (LON:JUP) was by far the cheapest based on AUM per £1 invested (around £95 at the time). Bucking the trend they actually posted a 2% increase in AUM this morning and gifted shareholders with a special dividend. Overall I was pleased with this result as a new holder. Other holdings RBG Holdings (LON:RBGP) Mobico (LON:MCG) not so good today... Lots to digest this morning!
Look forward to the healthy chat and debate on here today.
Ben
Ben, could you possibly point me in the direction of Graham's explanation of valuing fund managers, I missed it and cannot find it! Many thanks
It was from the report on Tuesday the 25th of April. He might explain more today perhaps in his report? Cheers.
Fantastic, thank you very much
Not sure where Graham outlined this, but you basically look at the Enterprise Value (market cap plus or minus any cash or debt) as a percentage of AUM. I believe 3% is a typical level, although this can vary tremendously.
However, you need to beware of using this metric on its own - if the AUM is low fee (eg passive or money market funds) then the AUM is clearly less valuable. You also need to consider margins - eg some fund managers have high costs, so higher AUM doesn't always translate to higher earnings. For these reasons I prefer to look at the good old PE ratio, where all of this is effectively factored in.
Many thanks Bouden
re : Sherborne Investors (Guernsey) C (LON:SIGC, Navient (NSQ:NAVI) Q2 yesterday, not much to report in the nos. A slight miss after absorbing exceptional CEO exit fees...so would have been a beat. For me, the new CEO made some interesting comments.
A review is taking place, with a sense of urgency. They want to simplify and improve efficiency. This sounds like reduce cost...central costs...to demonstrate the FCF of the historic loans business. Their focus will be to increase the proportion of variable cots supporting business processing, which is growing. Nothing is off the table. Best case is an announcement with Q3 in October. The shares traded ok until the Fed and then came off 3%... On the call the review got the attention of analysts... with increased FCF and capital returns mentioned several times. It's not just about capital though, they need to show the value of the growing business disguised by a legacy business in decline. Maybe they need to separate them out...
Quite a discount on Sherborne Investors (Guernsey) C (LON:SIGC) which is pretty stubborn.... 25% ... but a return to book value means a 36% rise in the price. Success with the target could build on this and almost certainly get you to 100% from here. Navient (NSQ:NAVI) are quite volatile and I would hope this settles down as confidence in the strategy builds. Obviously $ risk is something else to be aware of. I quite like turnaround stories since their investment case is often resilient to an economic downturn....but not immune.
As I understand it, @NAVI had a standstill agreement with Bramson, he/@SIGC being its largest shareholder, that prevented a Bramson concert party from going over 20%.
hxxps://delawarebusinesstimes.com/news/navient-sherborne-seat/
Per the article, that expired at the recent AGM (Q? either May 25 or June 1st, stockopedia isn't clear).
Separately, David Yowan (believed to be Bramson's man-or, at least- 'a man Bramson can do business with') was appointed Pres and CEO on 15th May 2023. He's been a NED on NAVI for abt 5 years.
Yowan appointment was based, inter alia - per the press release - on his "proven track record in transformational change.."
His predecessor, Remondi, "according to a U.S. SEC filing, was terminated without cause, meaning that he was laid off but not because of any misconduct."
See hxxps://delawarebusinesstimes.com/news/navient-yowan-ceo/
Meanwhile, over at SIGC, they issued an atypical RNS on 18th May 2023 that says :
.."The board of Sherborne Investors (Guernsey) C Limited (the “Company”) announces that, it has been advised by the Investment Manager, Sherborne Investors Management (Guernsey) LLC, that, following the distribution to the Company of any proceeds from the Company’s indirect investment in Navient Corp., the Investment Manager does not intend to seek to recall any funds for further investment."
I read the italicised bit as SIGC may be expecting some kind of corporate activity or rerating that warrants exiting the investment; and the bold bit that, in either case, SIGC will in due course be wound up and proceeds returned to shareholders ie the discount will pull to par.
Activist Bramson didn't get his way at BARC, but maybe he has at NAVI ?
If you go to p 52 of the last A/R 'Related Party Transactions', there's this bit
.."The Special Limited Partner is entitled to receive an incentive allocation once aggregate distributions to partners of the Investment Partnership, of which one is the Company, exceed a certain level of capital contributions to the Investment Partnership, excluding amounts contributed attributable to management fees.
For Turnaround investments, the incentive allocation is computed at 10% of the distributions to all partners in excess of 110%, increasing to 20% of the distributions to all partners in excess of 150% and increasing to 25% of
the distributions to all partners in excess of 200% of capital contributions, excluding amounts contributed attributable to management fees. An investment is considered a Turnaround investment when a member of the General Partner is appointed chairman of, or accepts an executive role at, the STC."
My guess is that Yowan is a member of the GP. I have no idea how to confirm that, but it seems pretty likely.
Lookers (LON:LOOK) revised bid of 130p this morning was a nice start to the day (I recently bought back in at 99p-104p)
From my understanding they need 50.1% for it to go through. All eyes now on acceptance levels, particularly from Cinch who withdrew their letter of intent when the bid was 120p
My morning smallcap tweet: Well, here's another fine mess I've gotten myself into!
RBG Holdings (LON:RBGP) Mission (LON:TMG) Eenergy (LON:EAAS) Lookers (LON:LOOK) Safestyle UK (LON:SFE) Litigation Capital Management (LON:LIT) dotDigital (LON:DOTD) Harworth (LON:HWG) Empresaria (LON:EMR) DP Eurasia NV (LON:DPEU) Headlam (LON:HEAD) Novacyt SA (LON:NCYT) Hansard Global (LON:HSD), Yourgene Health (LON:YGEN), XLMedia (LON:XLM), Bango (LON:BGO), Animalcare (LON:ANCR), Eleco (LON:ELCO), Fintel (LON:FNTL), Gaming Realms (LON:GMR), Volex (LON:VLX)
◄RBG Holdings (RBGP)► warns FY-Dec EBITDA only £10-12m. Legal Services broadly in line but Convex Capital transactions taking longer to complete as a consequence of the current economic environment. Writes down all funded litigations to nil from £13.3m. 13 were done by Legal Services, not LionFish. Div suspended. Kitchen sink and toilet chucked out by new CEO. Astonishing work by sacked CEO Nicola Foulston and team. [SP=25.4 Cap=24m]. I hold.
[edit] RBGP does not mention yesterday's Supreme Court ruling (see https://www.clydeco.com/en/ins...) but cites that its £9.3m Project Shango case will not be successful so it's writing them all down. But the cases are Conditional Fee Arrangements and Damages Based Agreements which are ruled unenforceable. Why didn't RBGP cite the Supreme Court?
◄Mission (TMG)► warns FY-Dec ikely to be at the lower end of mgmt expectations, with pretax still above FY22. Blames "challenges in the US technology sector and the reduced level of activity in this market in 2023 has impacted margin mix, particularly in comparison to 2022". [SP=43.25 Cap=39m]
◄eEnergy (EAAS)► guides 12 months to June rev up 50% and adj pretax up 34%. Outlook "confident in the trading outlook for the remainder of FY23 [18 mth FY]". [SP=5.5 Cap=19m]
◄Lookers (LOOK)► inc rec offer of 130p, from 120p. [SP=95 Cap=363m]
◄Safestyle (SFE)► warns FY-Jan24 materially below market expectations due to weak demand. H1 rev down 5%, in line. Industry data for last 3 month shows installations down c.12%. Conditions have worsened over the last 5 weeks into July. [SP=18.96 Cap=26m]. I hold.
◄Litigation Capital Management (LIT)► update following yesterday's UK Supreme Court Ruling on litigation funding. "The decision will have very limited or no impact on LCM's portfolios of dispute investments in terms of future value...[in fact] will have a potential positive impact on our future market share, given the lack of diversity in a number of our key competitors." [SP=72.6 Cap=87m]
◄Dotdigital (DOTD)► guides FY-June rev up 10%, lightly ahead of market expectations. Pretax in line.Outlook confident. [SP=88 Cap=263m]
◄Harworth (HWG)► EPRA NDV at 30 June broadly in line with 31 Dec. [SP=119.5 Cap=382m]
◄Empresaria (EMR)► warns FY adj pretax materially lower than market expectations. Blames "difficult market conditions have been experienced across the Group, particularly in the US. The greatest net fee income impact has been on permanent recruitment which was down 24% year-on-year with temporary and contract down 8%." [SP=51 Cap=26m]
◄DP Eurasia (DPEU)► guides FY-Dec LFL sales (inflation adjusted) growth in the low teens, better than previously expected high single digits. [SP=46.91 Cap=69m]
◄Headlam (HEAD)► warns FY-Dec adj pretax significantly below market expectations. H1 rev up 2.5% despite residential own nearly 7%. U/L pretax £6m (£17m) partly due to "strategic related investmen". "Recent residential trading volumes are weaker than expectations, with recovery now expected to take place over a more prolonged period." [SP=243 Cap=196m]. I hold.
◄Novacyt (NCYT)► guides H1-June rev down 80% to £3.3m. Even non-covid rev down. "Well positioned for diversified organic and non-organic growth." Yes, from FA. [SP=63.2 Cap=54m]
◄Hansard Global (HSD)► guides FY-June ew business down 29%. Blames "general hesitancy by clients to commit to long-term savings products". In line? "We are confident that our new product pipeline will lead to increased sales and long term growth in the business." [SP=46.6 Cap=64m]
In line: YGEN, XLM, BGO, ANCR, ELCO, FNTL, GMR, VLX
OMG Mr Contrarian! What a cr4p day for you!
Pour yourself a stiff drink later!!!
A bad day MrC, but can I thank you for this gem which made me genuinely LoL ?
""Well positioned for diversified organic and non-organic growth." Yes, from FA."
:D
A busy morning for a number of my holdings;
Profit warning from Headlam (LON:HEAD) - was only debating with myself last night if I should cut the losses on my remaining remnants of that holding which I had done well on in the past - I guess that now makes that decision.
From a quick look at the ITV (LON:ITV) HY results seems to be a bit of a mixed bag - they had flagged up a drop in advertising revenue so potentially this was already known about, but on the positive studios and ITV-X seem to be growing well.
The best news was Foxtons (LON:FOXT) whose interims to 30th June showed a continuing improvement since their new CEO joined and shook things up, so I am more positive on this one, but could be challenging times ahead, but they have now built their lettings division to be more than 50% of their portfolio, so I am hopeful that whatever happens in the sales dept the lettings will provide some great growth/stability.
Plus the pre-AGM statement for Volex (LON:VLX) - which I think sounds positive and should hopefully prove to be a winner.
Headlam (LON:HEAD) Id rather wait until positive trading shows up, or at the very least less crap trading.
Everyone sees things different but personally not bothered about catching the bottom, just be in for the good bit where EPS starts a growth phase. There'll be plenty of upside from the first positive trading update .
One thing Id want at a minimum is a close above the 10 day ema. Apart from a brief rally in June its been an avoid since February.
Morning all,
Steady as she goes for Volex (LON:VLX) this morning. Hopefully laying the platform for an "ahead of" later in the year?!
Compare to profit warning at Headlam (LON:HEAD), and a rather uninspiring update from £CMCX.
Thanks for flagging profit warning at Headlam (LON:HEAD) I'll take a look as soon as I can.
No problem. PBT "significantly below ". I think most have been anticipating a profit warning, but they were seemingly proving resilient up to now!
Maybe mention your views about Likewise-Group at the same time please
Headlam (LON:HEAD) it's a good company, whether it can stay in business without a fundraise to ride through what is a cyclical issue, I'm unsure. But given that they are lowering their dividend cover, rather than cutting the dividend does make me wonder what strategy they are deploying (apart from slowing down investors exiting swiftly), I'm not sure. Perhaps a lack of any buying by directors is a sign they don't have much confidence in the short term?
Morning Viz,
Headlam (LON:HEAD) is extremely well funded, and has a huge freehold property pile too. So there is no concern over funding/solvency whatsoever at HEAD in my opinion. We can relax on that front. It's also still profitable remember. Also being a distributor, it's not particularly operationally geared - so falling volumes (on low margins) don't do too much damage to profit, since many costs are variable (esp. staff). Hence lower volumes means they don't need as many people in the warehouses, and same for reduced vehicles/drivers, etc.
HEAD is very much a sleep at night stock, at least in terms of solvency and balance sheet.
The other thing to consider is that it's when we have downturns like this, that companies are forced to cut costs and improve efficiency. Thereby (under!)laying the groundwork for better profit margins in future, when demand returns.
Another point is that HEAD says it's absorbing startup costs for expanding its trade counters, which seem to perform well once they're established. That's a short-term drag on performance, but again should help it gain market share and boost future profitability.
It's a good business I think, and some softness in demand in current macro really shouldn't be a big surprise to anyone. That's why the share price had been falling in anticipation. Management should have better managed broker forecasts though, and just quietly lowered forecasts over several months, rather than issuing a profit warning. So it could have been handled better I think.
Regards, Paul.
I agree with Paul about the threat to Headlam (LON:HEAD) from Likewise (LON:LIKE). I don't get much right but sold Headlam when I saw the Likewise board, who have been responsible for most of Headlam's previous success. Management Team (likewiseplc.com)
Just a little scuttlebutt on Headlam (LON:HEAD) . I'd be surprised if everyone was disappointed to see Tony Brewer leave. Several of his supporters were poached to help start up Likewise (LON:LIKE) and the rest of the management team then started to sort out the issues that had been left behind from the numerous takeovers/acquisitions and outdated working practices, hence the AR focus on efficiencies for the last few years. Headlam still 5x Likewise on revenue and 3x their ambitions for growth to £200m turnover. Probably a worthy competitor and not one that should be underestimated.
Agree the wording on future div policy is woolly. My interpretation: Board are happy to maintain divi this year at a lower level of cover as they expect trading to improve next year and investment in retail counters to generate greater returns /less capital outflow once established. Bold move to keep investing in them now when Eurocell (LON:ECEL) for example have put their retail counter roll out on hold.
This is also another example of the stupidity of share buybacks when you still have debt/market uncertainty. Money well spent for shareholders? I don't think so. Only completed last £15m buyback on 3 March....
hi Paul
Headlam (LON:HEAD)
But remember HEAD has very solid asset backing, with loads of freehold,
so you have plenty of downside protection here, hence no reason to panic
in my view
Fair comment although my main concern here is regarding management ability. Present management team are relatively unproven with CEO appointed 4/22 (was previously
CFO for 5 years) and new CFO only joined 3/23 (previously had an
interim appointee for 12 months from 4/22).
This may take a while to unravel so the risk of further profit warnings looks high.
Given the lack of clarity regarding strategy and dividend policy going forward and lack of Management skin in the game I am an uncomfortable holder. It may make sense to take the hit and move on.
Hello, there are 2 active short positions on Volex (LON:VLX) . should we be concerned about that? it's making me reluctant to add more. (obviously i'm a new investor :) )
Well the shorters may have some inside information unbeknown to the rest of us, but I suspect the chairman who has just invested another 15 million of his own, has better knowledge of where the company is going.
Drip feed your money in and ride out the bumps.