Small Cap Value Report (Thu 28 Dec 2023) - TRYB, CHLL

Good morning from Paul!
Quiet for news again today, but I'll be taking a look at a couple of £20m market cap minnows. Today's report is now finished.
I was pleased to see there's clearly subscriber demand for SCVRs in this quiet period, with 4,713 reads, and 154 thumbs up for yesterday's report. If the market is open, then there will be an SCVR, as subscribers need somewhere to discuss topical issues every trading day.
I'm keeping my eyes peeled for unusual share price movements - in the usually modest liquidity of the Christmas break, price spikes can occur, presenting the occasional opportunity for people paying attention.
Same as every year, I'm planning on writing my year end review, and my top 20 value/GARP shares for 2024, over the New Year break. I also really enjoy reading subscriber posts about your investing year, and how you see 2024 panning out, so I encourage everyone to share your thoughts either by creating a separate post, or in the comments here.
While I'm preparing today's report, take a look at Keelan's review of the mining sector in 2023.
Two more 2023 reviews have been published today -
Graham's 10 share picks for 2023 have delivered a remarkable +25% (including divis)! Article is here.
Megan posted some more macro-focused themes today in this article.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Tribe Technology (LON:TRYB)
Down 8% to 8.5p (£19m) - Trading Update - Paul - RED
As it’s a quiet day, this is an ideal time to look at a recent float, so we can get some details into our archive here for future reference.
TRYB was created in 2019 in W.Australia,now having its HQ & factory in Belfast, UK (20,000 sq.ft, 30 people). It develops autonomous mining equipment (eg self-propelled land-based drilling rigs, said to be cheaper & safer to operate). It floated on AIM recently in Sept 2023, raising a modest £4.6m before expenses (only £3.2m after expenses!).
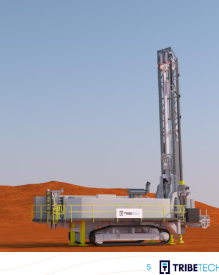
There’s a useful slide deck here from the IPO. The story seems to be that it has two initial orders of £6.4m and £4.1m from mining companies, and a pipeline of sector interest. There’s no financial information in the slide deck though. So I’ve had to download the AIM Admission Document from this page. These can be daunting, as they’re large documents, but I only dip into it for key information, when doing an initial review to see if the share looks interesting or not.
Key IPO facts -
Shares in issue expanded from 150m pre-IPO to 221m post IPO (230m fully diluted after options & warrants).
10p placing price.
Allenby organised it.
c.10% of enlarged share capital is EIS/VCT money (less discerning, due to attractive tax breaks).
IPO raised £4.5m gross, but fees were £1.3m, so only £3.2m after fees! That’s bonkers.
Risk factors - cash constraints mentioned, and contract risks (can be terminated any time by customers), early stage nature of the company.
Zero revenues, and £(1.7)m loss after tax credit for FY 6/2022. NAV negative £(1.2)m at 6/2022, but will have gone positive after IPO.
Overall - this is clearly an under-capitalised, jam tomorrow company, which cannot afford any project delays. Unfortunately, that’s exactly what has happened -
Today’s news - project delays mean there’s a risk that first revenues may slip from FY 6/2024 into FY 6/2025.
Cash position £3.34m at 23 Dec 2023. Is that gross or net of debt? (note that a new £3m loan was arranged in Oct 2023, at 13% pa interest). What is the monthly cash burn? It doesn’t sound very good, for a pre-revenue company with 30 staff. Hence I suspect high risk of dilution from another equity raise.
Paul’s opinion - after spending about 20 mins skimming through the admission document, I’ve seen enough to realise this share is not of any interest to me. Why?
TRYB is pre-revenue, and loss-making/cash-burning. It’s got 2 big contracts, and there are now contract delays. Cash looks tight. Yet again, a jam tomorrow project has been floated on AIM with inadequate funding, far too early (pre-revenue), and has already run into problems just 3 months after listing.
I cannot see why this is valued at £21m at this stage. Why get involved, when it might need another placing in 2024?
Upside? That the company claims to have spotted a gap in the market, contract values are large, and if the product is well received by the first 2 customers, then it might see a surge in repeat orders perhaps?
There’s no broker research available that I can see.
Overall then, I have to introduce a note of uncertainty, and flag it as high risk at this stage, so it’s RED for me. We can keep an eye on it, and see how the newsflow and figures develop, but risk:reward seems unattractive to me at this stage. Early stage companies like this hardly ever succeed on the IPO plans, with share prices usually performing badly, and delays plus more funding needed being the usual outcome. Why get involved at this stage? Liquidity is also likely to be very poor, due to the concentrated shareholder register and small size.
Chill Brands (LON:CHLL)
Down 3% to 4.65p (£20m) - Interim Results - Paul - RED
Chill Brands Group, the international consumer packaged goods company, announces its interim results for the six months ending 30 September 2023 (the "Period"), which can be viewed below and also on the Company's website at www.chillbrandsgroup.com.
About Chill Brands Group
Chill Brands Group plc (LSE: CHLL, OTCQB: CHBRF) is concerned with the development, marketing and distribution of wellness and recreational products containing natural, functional ingredients. The Company's proprietary product range is distributed by some of the most recognisable convenience retail outlets in the US and includes nicotine-free disposable vapour products that cater to the rapidly growing market for tobacco alternatives. Chill Brands also operates the chill.com e-commerce website, on which it is building a marketplace of products from third-party brands.
I’ve not looked at CHLL this year so far, because my impression is that it’s rubbish.
Looking at today’s interim results has very much reinforced this view. The numbers are terrible -
H1 revenue only £83k!
Loss after tax in H1 £(1.56)m
Balance sheet is weak, with NTAV negative £(1.9)m.
Cash is £1.95m, which looks about enough for another c.6 months after Sept 2023, so it will almost certainly need to do another fundraise in early 2024. Hence very high risk of a possibly deeply discounted fundraise.
Note there is already debt on the balance sheet, of £4.6m, including £3.2m in current liabilities, so how is this going to be repaid or extended?
Outlook - deals have been done with retailers, to list CHLL’s products, which it says will lead to a big increase in H2 revenues. Although it also mentions some up-front costs associated with getting products listed at retailers. Given that it’s fast burning through the remaining cash, this looks a precarious situation.
Paul’s opinion - I’ve seen enough to want to completely avoid this jam tomorrow cash burner. It hasn’t yet delivered any meaningful sales, let alone profits. Cash will need replenishing in the short term (on unknown terms). So why on earth is this share valued at £20m? There must be some punters who believe in the story - good luck to them, but personally I won’t be going near this share until it’s properly refinanced again (I think it needs £5m+ in fresh equity), and has proved that it is generating decent revenues and positive cashflow. At this stage, I doubt it will ever achieve that. So it’s a bargepole job for me - RED.
We keep an open mind here at the SCVR, so if the facts & figures improve, then we’ll take a fresh look at it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Chill Brands (LON:CHLL) - isn't the idea of nicotine free vapes a stupid idea?
If it get people off nicotine vapes then it's a cracking idea, but without the "addiction" factor, it's going to be a tough sell.
I remember in the 1980s, when I was trying to quit smoking, and I found some nicotine-free "cigarettes". There was absolutely no point in smoking them, because there was no nicotine hit, which is the sole reason for smoking.
Also I got banned from a local cafe, as the owner confronted me and told me my nicotine-free cigarettes smelt like a bonfire, and to take my coffee and cake requirements elsewhere. He didn't have any objection to people smoking conventional cigarettes.
For this reason, I very much doubt that nicotine-free vaping will take off. Other than as a vaping-cessation product.
Global non-alcoholic beer sales apparently $20 billion in 2023 and projected to rise to $40 billion in 2033
But a lot of that is because people are driving? Beer sales, worldwide, are around $320bn.
Thanks to my son's "research" I've been introduced to an alcohol free (well very very low) beer that amazingly tastes like beer. It's Brooklyn Breweries Special Effects. £4.50 for 4 330 ml bottles.
Erdinger alcohol free is also superb.
Good Morning. I spent most of 2023 in arrears with the last month enabling me to claim a small premium for the year. I suspect this might be quite a common outcome. But really what a boring year. 2020 for me a was a great year with 2021 up 5% and 2022 marginally down. The key being I managed to protect my capital when small caps collapsed, largely by shorting 10 year gilts and treasury and switching across into index linked gilts. But definately not an exciting couple of years and when you take inflation into account loss making. I remain cautious that macro influences could throw in a googly this year. The balance of power seems to be shifting and this does make things more unpredictable. That said for me it also highlights an opportunity in anything defence. I have spent the last few months initiating holdings in MS int, Avon Protection, Concurrent Tech, Global Data and James Cropper (yes defence! But incredibly hard to get any size and wouldn't want to pay much more than £7.50 at current time anyway). I continue to hold Avacta and Verici DX. Avacta could have funding difficulties but I personally think this will end up a £10 share, (contentious I appreciate but its my money). I was interested to hear Christopher Mills say this sector is finding it more difficult raising funds. Verici were clever and have shown leadership which i like. Otherwise I hold a handful of shares on valuation arguments. IPO are still valued less than 50% of their NAV. I think Record Holdings will turn out to be cheap. I prefer a handful of shares in size having spent time over the years building diversified portfolios only to end up relying on beta for return. I am interested in capturing the alpha i.e. backing my judgement. Well I wish you all success in 2024, there are many uncertainties out there but were I to back one theme I think defence has got to be a growing sector over the next 5 years. If not Poootin is going to be as happy as a pig in a poke!
Thankyou one and all for your contributions over the last few years. I prefer working in a team.
I prefer to think of Pootin as a pig in s**t, but concur with your views that one should have a v solid weighting in defence. One should not overlook European stocks - Rheinmetall is a core holding for me, and I also have Cohort (LON:CHRT) and MS International (LON:MSI) .
Really looking forward to your year end review Paul, and your top 20 value/GARP shares for 2024. Maybe I will try and post about my year given your invitation!
One of the sectors I think might rebound strongly in 2024 as higher interest rates subside are REITs and property companies as a lot of these are well down and trading at large discounts to NAV. I was wondering if any readers had any favourites they are keen on to aid my research?
I only hold Tritax EuroBox (LON:EBOX) which I like a lot because:
I also used to hold Palace Capital (LON:PCA) but I don't think the potential upside is significant enough in the current market.
Also see a lot of value in REITs, which should continue to do well as interest rates fall. I follow the sector quite closely and agree the Tritax EuroBox (LON:EBOX) probably looks the best opportunity right now for the reasons you've outlined.
If anyone is like me and doesn't want to pay more tax than necessary..
Hello from New Zealand the day is all but over here. Great to see Burford Capital (LON:BUR) up 21% yesterday but where is the RNS ?
Hi mikebianchi,
There was extensive debate about this in yesterday's comments section - essential the likely financial impact of a Court ruling on one of their very large litigation exposures.
There was no RNS. The rise was because of a few words spoken in Argentina. Their new president made some comments about how he would intend to pay an award made against the Argentinian government which currently stands to benefit Burford Capital (LON:BUR) to the tune of $6bn (at least in theory $6bn - a substantial discount is assumed). There's no large exposure on that case; Burford Capital (LON:BUR) have already sold off sufficient parts to have made a small profit. There is a hugh amount of expectation though.
What did Bruce Forsyth say when the Christmas pheasant repeated on him?
Good Game, Good Game!
It's the best of a bad lot :). On today's news, I'd have expected Derek Trotter to have sold more out the back of his van than Chill Brands (LON:CHLL) managed in 6 months.
Chill Brands (LON:CHLL)
Had a quick look through the update today couldn’t find any positives here to take away. Do they have any expected numbers for next year? Seems like a complete basket case without any firm numbers showing quick path to proper level of income / profit
Presumably should be easy enough to keep an eye out at whs and Amazon to see if these sales do actually take off or not. I note they mention fees they need to pay peeps for taking their products so I would place zero faith in the fact they have their stuff being sold with large names - I would want to see stuff is prominent and flying of the shelves,
Is it me or does the fact they still seem to have a less than 50k bounce back not seem like poor admin - I know it doesn’t need paying off early but it’s so small beer but that one would have thought they wouldn't want to advertise they are still making do with covid related financing with material inflow of funds from other investors.
Interest is fixed at 2.5% and you can get payment holidays and even extend the loan term. Given it's paltry revenue it doesn't make economic sense to pay this off imo!
Chill Brands (LON:CHLL)
I see the logic for not paying back - but I also see the logic for saying that we no longer need the support of the emergency prior funding that was handed out. Many of the listed companies rightly imho went above and beyond with regard to repaying these loans early and not seeking any government grants freebies that are were not wholly necessary for the business so thrive. Presumably the rationale of why they needed the funds then no longer applies too so would have been nice small positive sign if they had repaid the 30k they owed from recent funds raised and advised that was the right thing to do. No biggie that they haven’t paid back I would agree.
Placing imminent I'd imagine. Burns more cash than a bus load of tourists at Bicester Village before Christmas.
I'm in awe of the 46% return you got last year, but note that new nicotine free vape was on sale for 2 months of that 6 months, has ramped up significantly since. I guess you'll be waiting for full year results before investing
Chill Brands (LON:CHLL)
Bri72
What we really need from companies like this is firm future forecasts and regular updates ref those forecasts - in the absence of that this company doesn’t make any sense to me as an investment case from my perspective. It’s early days as yet but do they have any expectation ref numbers next year and year after ? Any proper company should have targets in that regard with updates ref those known expectations each time they update the market. Talk of deals done whilst ignoring the big picture of the totals imho is pretty useless.
I don't disagree - it's early days. They're expecting £2m of revenue in next quarter, but by own admission this has happened much faster than expected. I haven't seen research on them - closest is the Sunday Roast, but that's more PR than research. Personally, I believe its more than a hope, hype stock - there's something tangible building here - it just looks like it needs some more time to become apparent. Up 15% on the results - so some people agree with me. Many thanks to Paul for reviewing today, I'm hoping for a more positive review soon...
Many thanks Paul for posting this during the festive break. Also thank you and the team for the continued excellent coverage every trading day. It has helped me find some gems over the years and also avoid some car crashes. My portfolio has had a much-needed recovery this year mostly from SCS (LON:SCS) buyout and the Santa Rally. But I have been bullish since your starting pistol fired back in the summer! And have been "all in" since then, which looking back was the start of the bull for my stockpicks. Please keep up the good work and I find the Podcast at the weekend very helpful. ( the longer the better by the way)
Happy New Year to you and the team. I hope it is a prosperous one for all.
Thanks marcusb! :-)
As promised, I have collated the suggestions of possible takeovers I have noticed in the SCVR in the last couple of months. Planetx was the first to suggest we pool our ideas. I probably haven't found every suggestion so if you think I've missed anything please note it here.
This is the list, a Google Sheet, here.
Thanks Michael. Google sheets is saying I have to request access. Maybe you could change the permissions so that "anyone with link" can view it?
Is it working now?
Yes
Seems so now. Many thanks.
Thanks for creating and sharing Michael
Yes that link works now, thank you Michael C.
What a briliant idea, collating this list, many thanks for the effort you put into creating this, and for sharing it with us, much appreciated!
Best wishes, Paul.
There are a lot of "no reason given" but is it the case that if Harwood/Rockwood/Odyssean and maybe DBay own a piece of them it makes them an automatic candidate in some peoples minds? (including mine to be honest)
With regards to Equals (LON:EQLS) They issued confirmation yesterday that the strategic review deadline has been extended again until 24/01/24. I suppose there is nothing to conclude from this either way, that it is just standard practice and the deadline could be extended again on the 24th (am I right in saying they can only be extend the deadline in these four week chunks?) but would be interested in the thoughts of other more knowledgeable investors here if you have a different view (I hold and intend to stick it out)
Also, thanks to Paul Hill who first alerted me to Equals (and Northbridge/Crestchic for that matter)
Thanks for posting the spreadsheet Michael C. Another one from the Harwood stable for the list maybe is Real Estate Investors (LON:RLE) Chris Mills talked about it with Paul Hill at the following link (from about 78mins in) flagging it up as such albeit, dependent on the correct market appetite returning (pays a decent dividend while you wait). I hold. https://www.voxmarkets.co.uk/a...
This list of possible takeover candidates from Shore Capital may also be of interest, it was published in a Shares magazine article dated 16/11/2023:
Small caps:
Larger caps:
Halford and SPI are on my list for disappearance!