Small Cap Value Report (Thu 28 Mar 2024) - DPP, SPT, CML, C4XD, PMP, XAR, ZOO, AO., DUKE, JD, LTHM, RBGP, SND, FA., SDRY

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
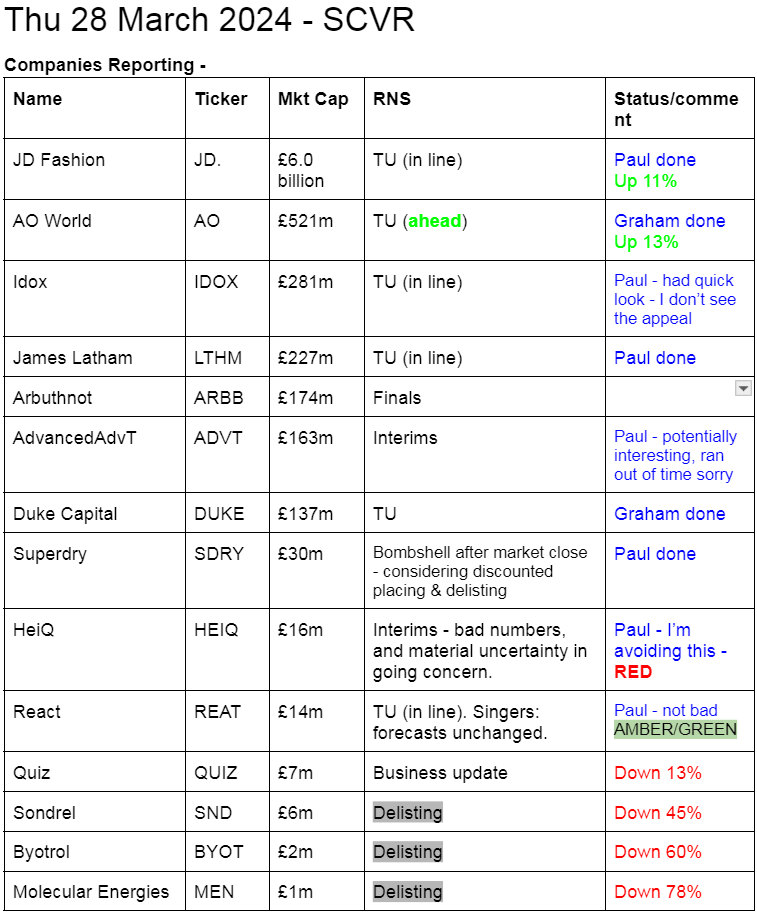
Other mid-morning movers (with news) -
Northamber (LON:NAR) - down 23% to 35.5p (£10m) - H1 Results - Paul - AMBER/RED
The only attraction to this share is that its NTAV is £22m, more than double the market cap. This is all tied up in inventories and receivables, and the business trades at a small loss.
A totally pointless company, tying up inefficient assets. The 63% major shareholder doesn’t seem to have any idea how to unlock shareholder value, and is impervious to outside pressure with a controlling stake. No point in it having a listing, so why get involved?
Molecular Energies (LON:MEN) - down 78% to 5.4p (£1m) on announcement shares are to de-list - Paul - GREY (delisting)
This explains it well -
Peter Levine, Chairman, comments: "I take no joy in recommending the cancellation of trading in Molecular's shares on AIM and know that this proposal will impact many shareholders. However the primary benefits of being listed are to avail oneself of access to capital, the ability to utilise one's shares as currency and enjoying the reputational boost of being on the London Stock Exchange. Molecular no longer receives any of those benefits and so can no longer justify the disproportionately high costs of remaining listed. As a Group its interests are best served by turning to the private arena where Molecular can regenerate away from the microscope and constraints of the public markets yet avail itself of funding and exit opportunities in some ways more flexible and abundant than remaining as a small public company on the London market.
MEN only recently did a deeply discounted fundraise which I mentioned briefly here on 24/1/2024. Terrible news for shareholders, as this share entered 2024 at 78p, so it's now lost over 90% in just 3 months.
Sondrel (Holdings) (LON:SND) - down 43% to 6.25p - Delisting & Refinancing - Paul - RED
Private Equity firm ROX is tightening its grip on this insolvent chip designer. It’s managed to renegotiate onerous supplier payments, and ROX has been drip feeding in smallish amounts of cash (as convertible [at 10p] loans). It’s put another £2m in today, to meet payroll for March & April (what a situation!). However, the bombshell buried in today’s announcement is that it intends delisting from AIM because -
The Company and ROX are of the opinion that the costs and complexities of being quoted on AIM do not benefit the Company and its shareholders during a period where the business is undergoing transformation.
There’s a bolded warning at the end of today’s announcement, which makes it clear that ROX is in control now -
There can be no certainty that the conditions to the Potential Investment will be satisfied or that ROX will proceed with the Potential Investment or that ROX will provide any further funding to the Company. Under the terms of the Exclusivity Agreement, the Company has undertaken (subject to ROX not withdrawing from negotiations with the Company) not to solicit other forms of investment from third parties prior to 30 September 2024 save for engaging with the Company's existing shareholders in connection with their participation in the Fundraise. Should ROX not proceed with the Potential Investment, the Company will not have sufficient working capital resources to meet its immediate requirements and may have to cease trading.
Many investors become forced sellers once a delisting is on the cards, so I think this latest move removes any upside for small investors, and draws a line under this total debacle, one of the worst IPOs ever.
Fireangel Safety Technology (LON:FA.) - down 47% to 2.65p (£5m) - Legal claim of £7.26m - Paul - RED
It may be Good Friday tomorrow, but it’s Terrible Thursday today.
FA. has just announced that a legal claim has been filed against a subsidiary, alleging supply of faulty units between 2011-19. The claim is £7.26m + costs, or for the repair/replacement of the faulty units - that's now more than FA's market cap, so you could say FA chance of the claimant getting paid, even if it does win the case!
FireAngel says the claim is without merit, and it will robustly defend itself.
I thought FA had been taken over, as we last covered it here on 27/10/2023 on announcement of a recommended bid at 7.4p. Checking the RNS, it appears the bid was delayed by regulatory clearance re national security. This was delayed again on 1/3/2024, until 31/7/2024. This bombshell legal claim today doesn’t exactly increase the odds of a takeover going through, but who knows? With the share price now barely a third of the supposed takeover price, the market doesn’t seem to have much confidence in the deal happening. FA has been a terrible share, repeatedly disappointing, and it wouldn’t surprise me if they end up a zero. So it’s a continuing RED from me.
Summaries
Another fundraise, £20.5m at 9.92p. The difference this time is UK Dominos Pizza is cornerstoning just over half the raise, which is a big vote of confidence. Could this serial disappointer finally be turning into a viable business? It's looking interesting, but the valuation is far too high for me at this stage.
Spirent Communications (LON:SPT) - 179p (£1.04bn) - Recommended acquisition by Keysight Tech - Paul - PINK (takeover bid)
Another US suitor gatecrashes a 175p takeover bid, with a 201.5p counter-offer. Management switch sides to support the higher offer.
CML Microsystems (LON:CML) - 310p (£50m) - Trading Update [26/3/2024] - Paul - BLACK (profit warning) - on fundamentals GREEN
Profit warning mainly due to customer de-stocking. I see this as a good business, with very good property & cash backing, so this could be presenting a buying opportunity possibly?
C4X Discovery Holdings (LON:C4XD) - Down 24% y’day to 10.0p (£25m) - Interims & Voluntary Delisting - Paul - GREY (delisting)
Unusual situation where the company announces delisting, combined with exceptionally good results (a one-off). It sees the listing as a hindrance, with private valuations much higher.
Portmeirion (LON:PMP) - 244p (£34m) - FY 12/2023 Results - Paul - AMBER/RED
Still profitable, but well down on 2022. My main concern is the "material uncertainty" in going concern note. I think it needs to urgently reduce inventories, to remove reliance on the bank, which may not renew facilities. Outlook doesn't inspire. Looking increasingly risky.
Xaar (LON:XAR) - 103p (£81m) - FY 12/2023 Results - Paul - AMBER
Adj PBT up 4% to £2.9m. Still has cash in the bank. Outlook uninspiring, with only breakeven expected in 2024. The bull case is that new product development could produce upside, not something I can guess at.
Zoo Digital (LON:ZOO) - 36.4p (up c.67% this week) £36m - Trading Update - Paul - AMBER/RED
Some promising signs of improvement after the Hollywood strike disruption has ended. But the numbers are stark - it's close to running out of cash, and has to increase revenues 50% just to get close to breakeven. Not a very good business in my view.
JD Sports Fashion (LON:JD.) up 11% to 129p (£6.7bn) - Trading Update FY 1/2024 - Paul - GREEN
In line trading update for both FY 1/2024 and the new year to date. Still looks cheap, we like this one.
James Latham (LON:LTHM) - Unch at 1,120p (£227m) - Trading Update FY 3/2024 - Paul - GREEN
In line trading update for FY 3/2024. Astonishing balance sheet with tons of surplus working capital. Put those two things together, and I think it's an attractive share, even though there might still be some excess profits being made from the pandemic boom maybe?
RBG Holdings (LON:RBGP) - up 10% to 9.5p (£12m) - Disposal of Convex - Paul - AMBER/GREEN
It announces selling the last problem area, Convex, which is sold to management. A small recent placing, extended bank facilities, and simplification of the business, means I see a risky, but potential turnaround punt here.
AO World (LON:AO.) - up 7% to 96.5p (£558m) - Trading Statement - Graham - AMBER
An excellent update as FY 2023 adj. profits will be “at least” at the top end of the previously guided range. The company now has a healthy net cash balance (ex. leases) and its core business is starting to grow again. I don’t view it as cheap but am genuinely impressed.
Duke Capital (LON:DUKE) - up 3% to 33.55p (£143m) - Trading and Operational Update - Graham - GREEN
A solid update confirming that Q3 (to Dec) recurring revenues hit a new all-time high. Q4 (to March) recurring revenues have fallen due to disposals; Duke needs to reinvest the proceeds well and without too much of a delay. I continue to like this at a discount to NAV.
Superdry (LON:SDRY) - 28.8p (£30m) - Various announcements - Paul - RED
Bombshell announcement after the market close, indicating founder/CEO won't be bidding for the company, but might underwrite a heavily discounted equity fundraise. Brace for the share price to collapse on Tuesday morning.
Paul’s Section:
DP Poland (LON:DPP)
12.7p (£92m) - Proposed Fundraising - Paul - AMBER
Yet another equity fundraise from this serial disappointer, the Poland operator of Dominos Pizza. However, this looks different. For a start, the share price has been rising nicely, although the 9.92p placing price is at a discount. Secondly this £20.5m fundraise is cornerstoned by larger UK Domino's Pizza (LON:DOM) which is subscribing for just over half the fundraise. I think that turns it from the usual DPP fundraising mode of desperation, into a more promising setup.
The business model is changing from losing money operating stores, to a franchising model.
Paul’s opinion - heavily biased by years of reporting dismal results. There might be a turnaround here now, but personally I think paying (post dilution) over £100m for it, looks unattractive, so it’s not for me, because they’re asking me to pay too much up-front for future success that has been so elusive to date. Current trading sounds good though, but it always does with this company. Good luck to everyone involved.
Spirent Communications (LON:SPT)
179p (£1.04bn) - Recommended acquisition by Keysight Tech - Paul - PINK (takeover bid)
RNS this morning confirms Spirent management has agreed a higher cash bid from Keysight Tech at 199p + 2.5p special dividend. This beats the previous bid of 175p from Viavi Solutions.
(This section below written last night)
Never mind checking the RNS every morning at 7am, we now need to check the SNS (Sky News Service) before going to bed every night, as that’s where we repeatedly get inside information early, particularly takeover bids. The Takeover Panel rules demand that companies respond if talks are leaked to the press, which has always struck me as ludicrous. It now seems established practice that deals are leaked to Sky, in order to force an announcement, in what is often a false market where companies themselves hide price sensitive information from investors.
So actually, given we have a lousy system, then all power to Sky News, and I hope they keep pre-announcing as much price sensitive information as possible.
According to Sky, an ideal situation has arisen for Spirent shareholders, where two US bidders are now competing for it.
Checking my previous notes, SPT warned on profits in 2023, pulling it down from c.250-300p range in 2020-22, to a low of c.95p in Oct 2023. Then a good bombshell on 5/3/2024 with a recommended cash offer at 175p from US competitor NASDAQ-listed Viavi. My crystal ball was working quite well, as I did ponder on 5/3/2024 if a higher competing bid might appear, and some subscribers thought the bid from Viavi might be opportunistic due to Spirent seeing a temporary dip in performance?
This is what Sky says now -
Sky News has learnt that Keysight Technologies, which is publicly traded in New York, is preparing to launch a formal offer for Spirent worth roughly 200p-a-share.
That would value the FTSE 250 target at about £1.15bn.
Keysight's bid will trump a 175p-a-share bid unveiled last month by Viavi Solutions, a US-based technology company…
One institutional investor said they expected the higher offer to persuade Spirent's board to switch its recommendation from Viavi to Keysight…
The emerging bidding war between two American companies for a London-listed technology provider will again raise questions about whether the UK equity markets are mispricing successful businesses with substantial growth prospects.
Paul’s opinion - exciting! The bid(s) for Spirent may be a decent premium to recent bombed out share prices, but if you think Spirent can recover profits back to previous levels, then the bidders may even get a bargain.
Over & over again we’re seeing that UK public markets are under-valuing many companies. There are opportunities galore in UK shares, as these bid approaches keep confirming.

CML Microsystems (LON:CML)
310p (£50m) - Trading Update [26/3/2024] - Paul - BLACK (profit warning) - on fundamentals GREEN
CML Microsystems Plc, which develops mixed-signal, RF and microwave semiconductors for global communications markets, is today issuing a trading update for the year ended 31 March 2024 ("FY24").
I thought it would be interesting to check out CML, as the shares have dropped a lot recently. This is a hybrid share, which has built up strong surplus assets (cash and freehold property) over the years. So there could be an angle on this share whereby the recent big fall in share price might be letting us own the operating business on the cheap (since the assets might support the share price better now?)
My previous notes indicated that some of the surplus cash pile had been earmarked for a US acquisition.
Summarising the latest update -
Good H1 as previously reported.
H2 has been tougher for various reasons, customer destocking sounds the main problem.
De-stocking expected to continue for a while.
MwT acquisition has gone well.
FY 3/2024 revenues expected “close to £23m” slightly below expectations.
Profit expectations reduced mainly due to sales mix shifting to lower margin products.
Shore capital has kindly updated us, but doesn’t do a before & after, so I’ll do it -
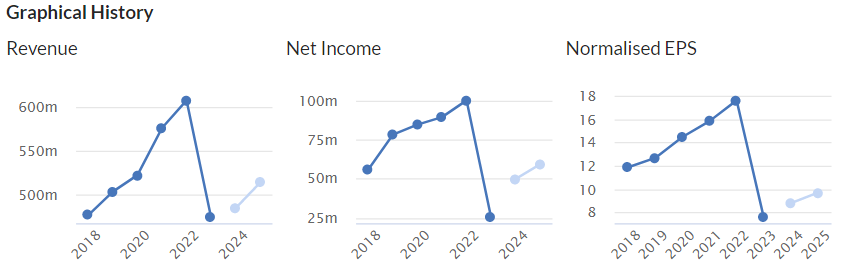
New (26/3/2024) forecast FY 3/2024: £3.7m adj PBT, 18.7p adj EPS (down 15% on LY)
Old (5/12/2023) forecast FY 3/2024: £4.4m adj PBT, 22.2p adj EPS.
Ah OK, so it’s worse than the RNS makes out, annoyingly.
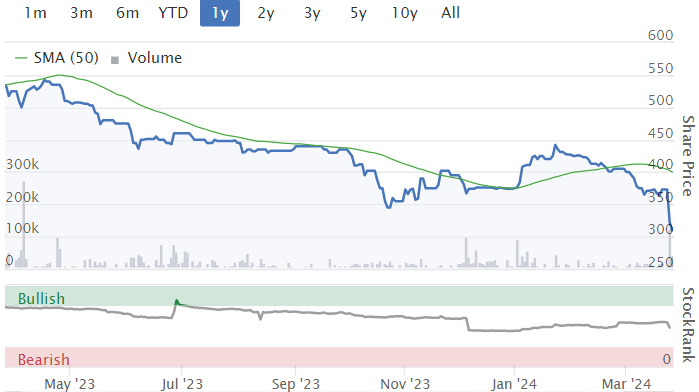
Does this (arguably temporary de-stocking issue) justify such a sharp share price reduction as this though? -
Cash - is still highly significant considering the market cap is £50m -
The Company retains a strong balance sheet, with net cash reserves of just under £18m.
Paul’s opinion - as profit warnings go, this looks pretty mild, and seems to be a “good” profit warning - ie fixable, temporary problems, not a structural downturn … hopefully!
There have been several (disastrous) recent floats of chip developers, that seem to run out of money, and have a history of never making any profit, despite which investors seem to become easily excited if they issue contract win announcements. Whereas here with CML we have an established chip business, that has reliably generated cash almost every year, doesn’t need to raise cash from equity holders (indeed it pays divis) and owns a large business park that it’s been trying to redevelop for many years.
From this quick review, I think the plunge to 310p could be providing us with a potential buying opportunity, but you need to do a lot more detailed research for yourself, that’s just my quick initial view.
C4X Discovery Holdings (LON:C4XD)
Down 24% y’day to 10.0p (£25m) - Interims & Voluntary Delisting - Paul - GREY (delisting)
I’m trying to keep track of delistings on my spreadsheet, so am just flagging this for that purpose. We’ve never covered C4XD here in the SCVRs, because it’s been a serial loss-maker, jam tomorrow and repeat equity issuer.
Today it issues strikingly good interim results, very much a one-off, with a £18m H1 PBT, thanks to 2 large milestone payments from pharmas.
In another RNS it announces it’s flouncing off (delisting) because AIM investors give it such a derisory valuation, compared with the much higher valuations available in the private market. They’ve got a point, that the AIM listing is now an impediment to shareholder value.
The announcement also re-writes history to make out that C4XD has performed well, which of course is nonsense. It’s many years of poor performance which has caused the market cap to get this low.
As I’ve always said, the stock market is completely the wrong place for speculative, loss-making, jam tomorrow companies.
Note the share register is dominated by 3 large investors, who probably don’t see any value in a stock market listing either.
It must be galling to small shareholders though, some of whom might have supported this company for years, to be presented with the first decent set of accounts, which come with news that it intends to delist. I find this disconcerting, as it’s the first situation I can remember where a company which has actually had some success, promptly announces it wants to delist. It’s usually just the complete basket cases that delist. So it’s now looking worryingly, that we might face delisting risk at both good and bad companies. Something to ponder. Checking the shareholder register for one or a few dominant shareholders, also greatly increases the delisting risk. They might want their mistakes taken out of public view, as much as anything, perhaps? I can feel a rant coming on for this weekend’s podcast!
Portmeirion (LON:PMP)
244p (£34m) - FY 12/2023 Results - Paul - AMBER/RED
Portmeirion Group PLC, the owner, designer, manufacturer and omni-channel retailer of leading homeware brands in global markets, announces its preliminary results for the year ended 31 December 2023.
This ceramics maker has disappointed once too often for me, and I don’t like the way it slipped out profit warnings through broker notes on the quiet.
Although personally I did catch that 60% bounce from 300p to 500p last year, and luckily sold at the top. Who needs US tech shares, when it’s possible to make a 60% profit in a few months from a Stoke-on-Trent teapot maker (as one of our subscribers hilariously quipped when tech stocks were soaring, we were obsessing about teapots here!)
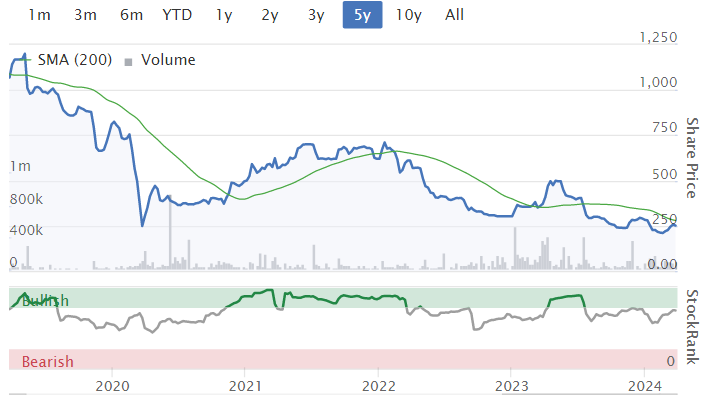
Zooming out on the chart to 5-years, the recent rally has been barely a blip in a very disappointing downtrend -
2023 results look poor, with a modest adj profit, and a hefty statutory loss -
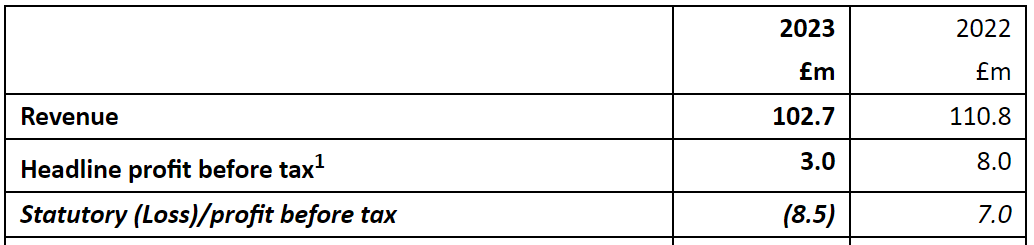
Dividends have been cut from 15.5p in 2022 to 5.5p for 2023, which I think makes sense given the poor profit performance.
Borrowing is under control I think, however there’s a bombshell in the going concern note, saying that a “material uncertainty” exists over Lloyds Bank renewing facilities in Sept 2024. Management think that’s unlikely, but I’ve personally experienced Lloyds pulling the rug out unexpectedly (back in 1996), so I wouldn’t trust them as far as I could throw them. So there’s a risk PMP could need to dilute, with an emergency placing.
The balance sheet overall looks fine, but there’s too much tied up in inventories. PMP needs to greatly reduce inventories, so it doesn’t need to rely on the (uncertain) bank, in my view.
Outlook - little reason to celebrate here -
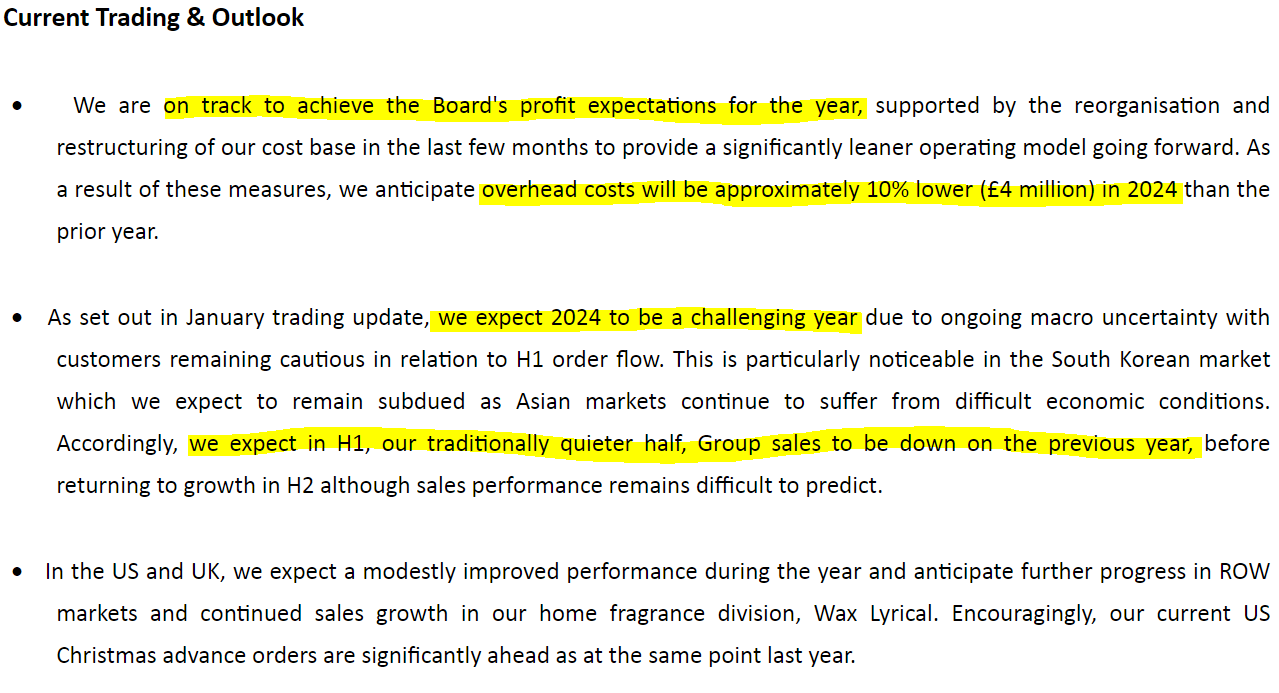
Paul’s opinion - I’m a bit wary of PMP now, and doubt I’ll be bottom fishing again here. It feels to me as if there could be scope for another profit warning, PMP seems to have developed a liking for missing targets. Although lower costs (especially energy) should be helping somewhat.
I think it’s a good example of a company that is bad at acquisitions, so money was wasted on deals which have not delivered any overall benefit, but have left it financially weaker.
The “material uncertainty” in going concern compels me to flag the higher risk, so my hands are tied, it has to be AMBER/RED.
Xaar (LON:XAR)
103p (£81m) - FY 12/2023 Results - Paul - AMBER
Xaar plc ("Xaar", the "Group" or the "Company"), the leading inkjet printing technology group, today announces its full year results for the 12 months ended 31 December 2023.
It says these results are in line with management expectations. I’m pleasantly surprised actually, as Graham had written quite bearishly about XAR in late 2023.
The highlights below shows adj PBT slightly up, but note that’s due to big adjustments, with a statutory loss before tax. Also it’s still got net cash of £7.1m -
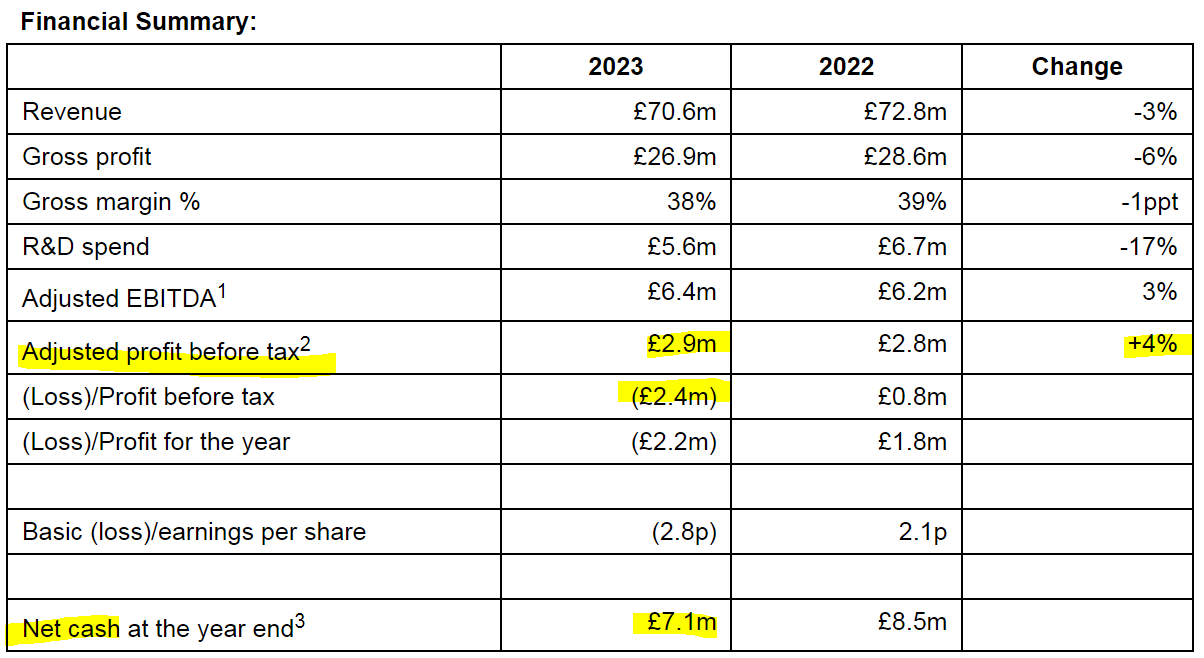
Even though the share price has come down a lot, the £81m mkt cap is not exactly a bargain against these numbers above.
So the market is still anticipating increased profits in future.
Note that profit is stated after expensing £5.6m of R&D.
Balance sheet has a couple of unusual items. Inventories of £31m looks far too high, and so there might be write-offs to come maybe? Note £2.1m of deferred consideration is payable in 2024. Also I query the £8.3m in fixed assets called “Financial asset at fair value through profit or loss”, I’m not sure what this is?
Overall, if they can get inventories down, then the balance sheet should be OK.
Outlook - makes generally positive noises, although it also sounds cautious -
Whilst the end of 2023 was challenging, and the current external trading environment remains so…
As previously announced in our November 2023 trading update, due to the current geo-political and macro-economic conditions, bringing some of our customer's products to market is taking longer than expected, meaning we are cautious on precise timing.
It gets worse - gross margins are expected to fall -
As we reduce our finished goods inventory during 2024, the lower volumes will impact our ability to recover production overhead costs. Together with the effect of increased input costs, as previously explained, our gross margin will be impacted this year.
Overall though, no change to expectations for 2024 - which according to Progressive is only for breakeven.
We believe the business is well positioned for growth through both new applications and share gains in new and existing markets and our expectations for the full year remain unchanged.
Paul’s opinion - there’s no denying XAR has been a big disappointer for a long time. However, that massive spike in 2013 was when one of its innovative printheads hit the big-time for a while, I think that was when it cornered the market in Chinese tile printing for a little while.
So the company has demonstrated what upside can happen if one of its products really takes off. Trouble is, it wasn’t able to follow up on that success.
With only breakeven forecast for FY 12/2024, and some quite negative things in the outlook section, I can’t get excited about XAR shares. We’re just being asked to have a punt on its new products hopefully taking off. I have no idea how likely that is, so can’t really work out how much this share is worth. I’ll be a bit kinder than Graham last time, I’ll go with AMBER.
Zoo Digital (LON:ZOO)
36.4p (up c.67% this week) £36m - Trading Update - Paul - AMBER/RED
ZOO Digital Group plc (AIM: ZOO), a leading provider of end-to-end cloud-based localisation and media services to the global entertainment industry, today provides an update on trading.
This share has been an unmitigated disaster in the last 12 months, losing c.90% from peak c.200p to low last week just above 20p. It’s put in an impressive 67% rise this week, although percentages from a low base look better than reality of it only being a small blip in a big downtrend -
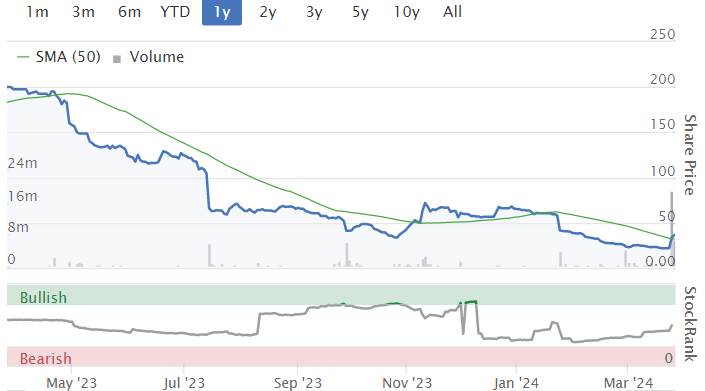
What went wrong? Hollywood strikes, and streaming services retrenching. Even so, the rapid descent into large losses took us all by surprise, even commentators like me who were not keen even before all the problems emerged.
Has it turned the corner? The current financial year is FY 3/2024. Tuesday’s update this week said -
“the Company is beginning to see an acceleration of its pipeline with work expanding in March and April 2024…”
It now expects to beat market expectations, but is coy about saying how much of a beat, and see the footnote which shows the expectations are dismally low, for a large loss -
As a result, the Company expects to beat revised market guidance for FY24* with revenues of at least $40 million. Consequently, the anticipated EBITDA loss will be reduced.
Net cash on 31 March 2024 is expected to be at least $3 million, also higher than revised market expectations, and although the Company has no debt it intends to renew its current undrawn facilities when they fall due.
* The Company understands market consensus for FY24 to be revenue of $37.6 million, EBITDA adjusted for share based payments loss of $14.0 million and net cash of $1.6 million.
My question would be whether the bank is happy to renew facilities for such a heavily loss-making company? If not, then it’s almost out of cash, and could need another equity raise.
Broker updates - many thanks to Singers for making its updated forecasts available to us.
The FY 3/2024 figures look seriously grim. Adj EBITDA has only been improved by $0.5m, to a $(13.5)m loss. That translates into a $(20.8)m adj PBT loss. Horrendous, in other words.
FY 3/2025 forecast is for a +50% recovery in revenues to $60m, and adj PBT slightly loss-making at $(0.8)m.
Outlook - the company makes positive noises here, but remember that according to Singers, it has to increase revenues by 50% just to get close to breakeven. Also I imagine such a big increase in revenues, even if it’s achieved, would suck cash into working capital. So the cash position looks precarious to me.
My opinion - I’m highly sceptical. ZOO has incurred such large losses in FY 3/2024, that I’m struggling to imagine that it could recover sufficiently quickly to avoid another likely year of losses in FY 3/2025, albeit hopefully reduced losses.
It’s burned through a cash pile in FY 3/2024, and I reckon it will need another fundraise.
This update does its best to sound positive, but with things looking finely balanced, I’m not tempted to punt on this share. I’d rather sit on the sidelines and wait to see if trading actually does rapidly rebound. Even if +50% revenue growth is achieved, it would still be a modestly loss-making business, so where’s the attraction of taking all the risk of a possible fundraise, when the upside is only that it might get to breakeven? Risk:reward looks weak to me, so I’ll go with AMBER/RED.
JD Sports Fashion (LON:JD.)
Up 11% to 129p (£6.7bn) - Trading Update FY 1/2024 - Paul - GREEN
This is a large, international fashion sportswear retailer. Shares have been looking cheap for a while, so I’m interested in reporting on this mid-cap.
Key points -
FY 1/2024 adj PBT in line with guidance of £915-935m.
Initial guidance for FY 1/2025 PBT £900-980m (before accounting policy changes, which will boost this range by c.£55m).
First 7 weeks of new year trading has been in line.
Outlook - a bit mixed I’d say -
The market remains challenging due to less product innovation and elevated promotional activity in key markets, particularly online. We anticipate trading conditions will improve as we move through the year, helped by a busy sporting summer, softer comparatives with last year from Q2 and an improving product pipeline towards the end of the year. Given this, Q1 is likely to be the softest LFL period of the year and H2 is likely to be stronger than H1. In addition, cost inflation remains elevated, particularly labour, and we will continue to invest in our infrastructure in FY25 to deliver our long-term growth plan.
Paul’s view - I remain of the view that this share seems modestly valued on a PER basis, for a group with a stunningly good long-term track record.
Even after today’s rise, the PER would only be about 10. So I’d say it’s worth readers taking a more detailed look yourselves. There was a profit warning on 4/1/2024 which I reviewed at the time - it wasn't too serious, just soft Xmas trading.
James Latham (LON:LTHM)
Unch at 1,120p (£227m) - Trading Update FY 3/2024 - Paul - GREEN
We like this company, a family-controlled timber merchants. It had a profits bonanza during the pandemic, when limited supply met with excess demand, causing profit to soar. Conditions are now normalising, and it’s good to hear that trading is in line with expectations (which already factor in a big reduction in profits from the pandemic boom) -
The Board of James Latham provides the following trading statement ahead of the Company's results for the year ended 31 March 2024.
Revenue for the year to 31 March 2024 remains in line with market expectations. Cost prices of both timber and panels are relatively stable. The ongoing issues affecting shipping in the Red Sea have caused some delays and increased costs for some of our imported products, although this is currently not causing concern. Sales volumes are very similar to the previous year.
Overheads have been well controlled but are slightly higher due to inflationary increases and our continuing investment in our depots to improve service levels. We anticipate that our profit before tax will be in line with market expectations. The Company's balance sheet and cash balances remain strong.
The Board plans to report the Company's preliminary results for the year ended 31 March 2024 on 27 June 2024.
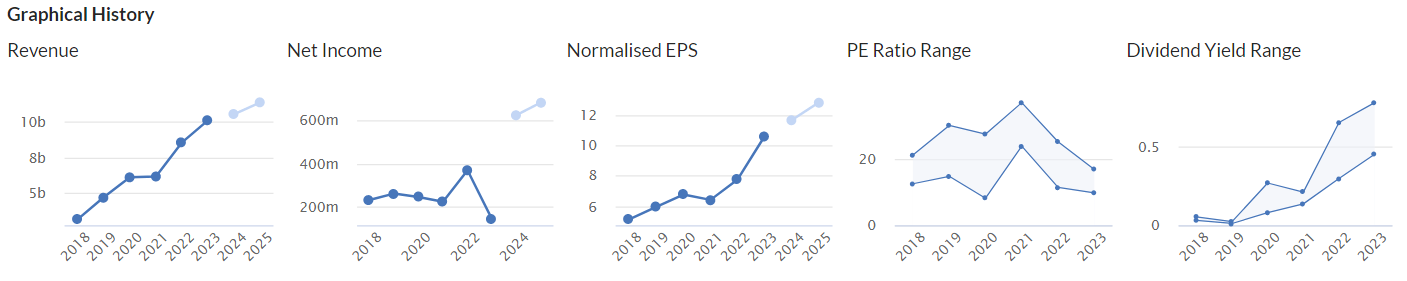
The StockReport here is showing 96p forecast for FY 3/2024, which is still about 50% higher than pre-pandemic, so I am still a little worried that normalising supply could result in selling prices falling in future maybe? The PER is 11.7x
Why would profit be permanently 50% higher than pre-pandemic in future?
For that reason, I’m a little sceptical that high profits are necessarily sustainable, but so far it’s doing OK.
The last H1 balance sheet isn’t just strong, it’s groaning with surplus liquid capital - look at the middle section (below), and bear in mind there are no significant long-term creditors -
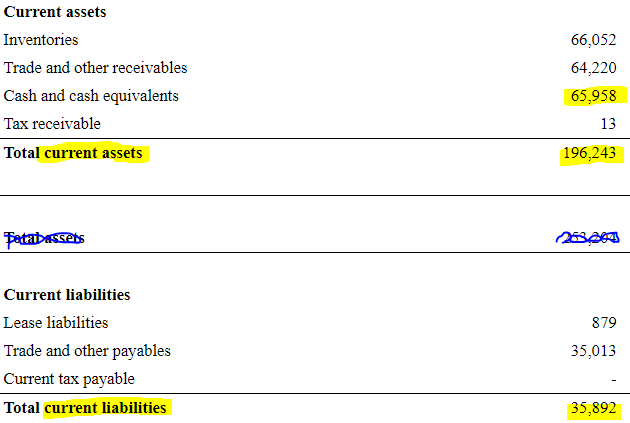
The mkt cap of £227m is only a bit higher than the last balance sheet NTAV of £202m. So at some point LTHM shareholders should receive a bonus from special divis, buybacks, etc.
It’s difficult to think of any other small cap with a balance sheet this ridiculously strong, so LTHM shares are absolutely copper-bottomed, for investors who want to sleep at night.
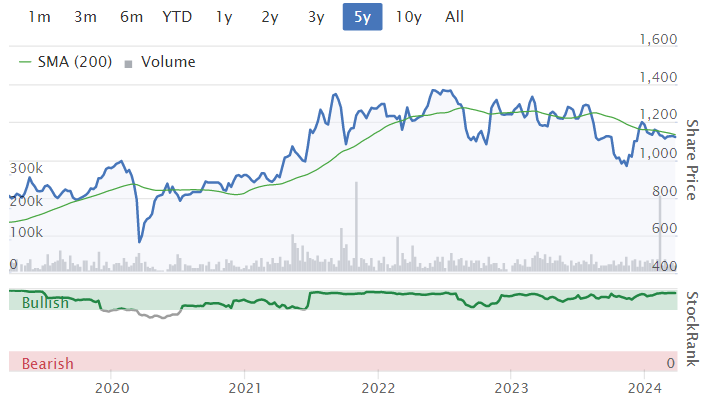
I have to stay at GREEN, due to this immense financial strength, and reasonable valuation (providing future profits don't slip) -
RBG Holdings (LON:RBGP)
Up 10% to 9.5p (£12m) - Disposal of Convex - Paul - AMBER/GREEN
This accident-prone legal services group seems to have resolved another of its problem areas - selling its M&A division Convex to a management buyout team for £2.0m initial cash, with a possible £0.6m earn-out, linked to 4 specific deals. This 2019 acquisition has been a bad one, and will incur a £13.5m non-cash write off (of goodwill I assume).
The Disposal is in line with the Group's strategy to reduce its risk profile and to refocus on and invest in RBG's established legal services businesses - Rosenblatt and Memery Crystal - where the Board believes it can best maximise profits. Similarly in 2023, the Group disposed of LionFish Litigation Finance Limited ("LionFish").
Paul’s opinion - I wonder if there’s turnaround potential here? Old management’s disastrous diversification strategy has now been unwound, leaving behind what should be 2 decent legal firms. Although I’ve never liked the conflict of interest that staff and Directors have, when legal firms become stock market listed.
With the market cap now only at £12m, and the main problem divisions apparently resolved, along with a small placing (at 9p) done and proceeds from the sale of Convex, I’m starting to wonder if this might be worth a little punt for a possible recovery in share price?
Debt is now the biggest risk. HSBC renewed facilities in Dec 2023, and there should have been some progress in paying down some of the debt. So I’m leaning towards seeing this positively as a risky, but interesting recovery punt.
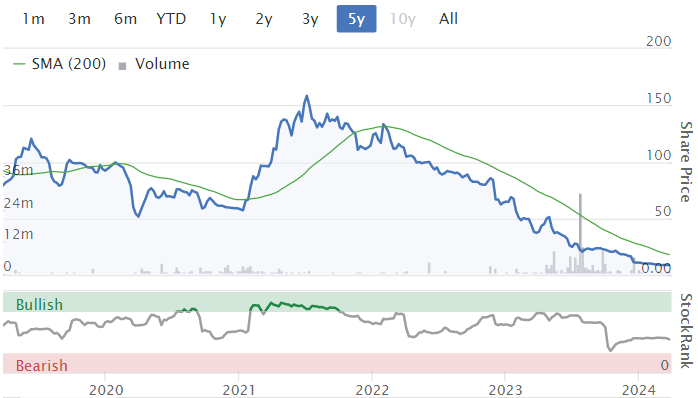
Not the best of track records -
Superdry (LON:SDRY)
28.8p (£30m) - Various announcements - Paul - RED
Bombshell announcements tonight have ruined the Easter break for punters hoping for a miracle at this struggling fashion brand.
Hilco extends borrowing facility with another £10m available immediately, plus £10m extra for the seasonal peak in Sept-Nov. Note it’s “subject to” Hilco approving cost saving measures. It’s expensive, at base rate + 11.5%, so 16.75% pa interest cost on the drawn down amounts. It’s asset-backed, and covenant-light.
There’s another specialist lending facility in place with Bantry Bay.
I can’t see any particular nasties in this, so it sounds a positive thing that (as previously indicated in press reports) Hilco is giving Superdry more financial headroom.
Julian Dunkerton announcement - says that the founder/CEO won’t be bidding for the company. However, he is discussing other financing options, with this bombshell making it sound like existing small shareholders could be about to get wiped out and many forced to sell -
...including a possible equity raise fully underwritten by Julian Dunkerton, which would provide additional liquidity headroom for the Company's turnaround plan. It is expected that any equity raise would be at a very material discount to the current share price, require shareholder approval of a Rule 9 waiver (as referred in Note 1 of the Notes on Dispensations from Rule 9 of the Code) and be conditional on a de-listing of the Company. A further announcement will be made as appropriate. There can be no certainty that a transaction with Julian Dunkerton will be agreed.
That’s a disaster for outside shareholders, prepare for the share price to collapse on Tuesday morning.
Company’s response - was announced 1 minute later, using identical wording.
Interim CFO is appointed, to the operational board, not the plc board.
Paul’s opinion - this is a disaster, with outside shareholders likely to be diluted heavily in the next rescue fundraise.
Graham’s Section:
AO World (LON:AO.)
- Share price: 96.5p (+7%)
- Market cap: £558m
AO World plc... the UK's most trusted electricals retailer, today issues the following pre-close update for the 12 months to 31 March 2024.
This stock is a good example of “when the facts change, I change my mind”. A long-term bear of this company - even going so far as to short it at one point - I switched to neutral on it when it started to focus on profitability over empty revenue growth. I covered last year’s results here.
Paul took a look at it in November, expressing concern over the exposure to production protection plans and mobile phone connections.
Today we do get some good news for AO shareholders. Key bullet points from this full-year update:
Revenues c. £1.04 billion.
The company leaves out a comparison with last year - but it’s another annual decline in revenues. FY March 2022: £1.14 billion. FY March 2021: £1.37 billion.
Given the historic lack of profitability at AO, I view its decline in revenues as a good thing. Remember the phrase - revenue is vanity!
Adjusted PBT at least at top end of previous guidance £28-33m.
Great news! It goes to show what’s possible when a company is run for profits rather than for revenues.
Net funds of over £30m.
One of the features of this stock that attracted shorters over the years was the net debt position, but the company has fixed the problem (albeit at the cost of some dilution).
CEO John Roberts comment:
"I'm pleased with the clear progress that we're making after pivoting our focus to profit and cash generation during the 2023 financial year. As we expected at our half year results, we returned to revenue growth in our core business during Q4 and, as a result, we're entering the new financial year with good momentum. With net funds on our balance sheet and a clear plan, we remain confident in our ability to deliver on our ambition for 10-20% revenue growth in the year ahead and medium-term profit guidance of 5% adjusted PBT margin."
Graham’s view
I still can’t believe that this is the real John Roberts! The old John Roberts loved buzzwords and dreamy aspirations, whereas the new John Roberts is a calculating, cold-hearted businessman.
Ever since it ran into some difficulty in 2022, and raised new equity, this company has been telling us the things that most value investors would want to hear: that it’s being run for profit and cash generation, instead of unprofitable revenues.
Revenues have collapsed all the way from a high of £1.7 billion in the Covid-influenced year of 2021, but according to today’s update, the core business is now able to start growing again - from the stable footing of profitability.
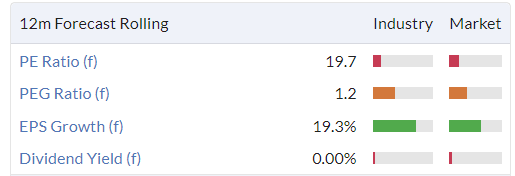
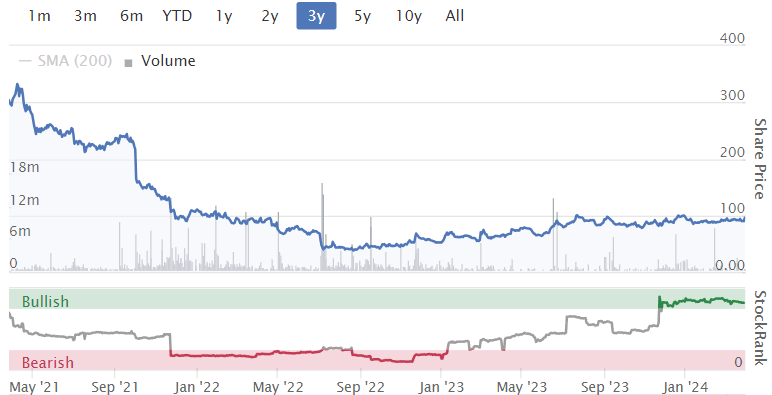
Could I even consider taking a positive stance on these shares? I may be forced to at some point, but my sense is that the shares are fairly valued at the current level (PER 20x according to Stocko). For an online retailer that doesn’t own any of the brands it sells, that does seem quite high enough.
But I am definitely more optimistic about this company than I have ever been before:
Paul is right to point out that there are risks related to the company’s reliance on warranty sales. Of course the same could be said of many retailers in this space.
Duke Capital (LON:DUKE)
- Share price: 33.55p (+3%)
- Market cap: £143m
This is “a leading provider of hybrid capital solutions for SME business owners in Europe and North America”.
I think of it as providing a corporate mortgage to small businesses. The key feature of the product is that payments to Duke are adjusted, depending on the revenue growth at the borrower. In this way, Duke gets to participate in the growth of the companies it has invested in.
Today we have a Q3 update (to December) and guidance for Q4 (to March).
Q3 update: Recurring revenue up 12% year-on-year to £6.3m
Q4 guidance: Total cash revenue £10.2m, breaking £10m in a quarter for the first time.
It’s important to note that “total cash revenue” includes non-recurring items such as:
Profits when companies buy back their mortgage (i.e. pay it off early) at a premium.
Profits from the sale of equity investments.
One-off fee income.
Therefore, while the £10.2m figure is a useful measure of profits, it’s not a measure of the stable quarterly income that is Duke’s bread and butter.
Q4 saw two profitable buyouts of their investments, resulting in total income of £19m.
Checking recent RNS announcements, one of these was a UK manufacturer in which Duke had invested £6.2m. The IRR (internal rate of return) on the investment was 36%, enjoyed over a three-year period.
The other investment was a Swiss pharmaceutical company (“Fairmed”). The IRR of this investment wasn’t given but Duke did say that the recently agreed sale was “at the upper end of the expected rate of return for Duke with no equity participation”. €11.4m was the agreed price of the disposal.
I’ve quickly checked the background to the deal; it was originally described as a €10m royalty, and it started in mid-2021. So to receive €11.4m in 2024 is not going to provide an amazing return, but perhaps not bad. Maybe c. 4.5% annualised? And that does not include the income received from Fairmed over the years, which would massively boost the IRR when you take them into account.
Overall, these two buyouts seem to be good news for Duke, providing decent returns although at the same time each buyout brings a challenge to reinvest the funds in a timely and attractive way. This is reflected in the following bullet point:
Duke expects to achieve recurring cash revenue of £5.8 million in Q4 FY24, a small decrease versus the previous quarter. While the recent buyouts have resulted in increased total cash revenue, until this capital is redeployed, there is a temporary impact of reduced recurring cash revenue.
Other highlights include:
£2.9m purchase of shares in United Glass Group to bring Duke’s equity stake from 30% to 74%.
I’ve been nervous about Duke’s equity investments, seeing them as a risky venture that could distract from the core royalty product. Duke says that the equity investment in United Glass “is in line with Duke Capital's vision to deepen its engagement with its high performing partners”.
CEO comment:
"We are delighted to show a record quarter of total cash revenue following the successful exits of two of our investments. Fabrikat particularly highlighted the value of Duke's capital, having financed an MBO by three executives in 2021, facilitating an exit three years later at a 36% IRR. We look forward to redeploying the capital from these exits into our pipeline of immediate and longer-term opportunities, driving a return in the short-term to delivering record quarterly recurring cash revenues.
Graham’s view
As a former shareholder, I remain a fan of this company, and I’ve been positive on it for some time now.
The share price has been struggling to get back to book value, and remains at a discount. Net assets were £162.5m as of the interim results, versus a market cap of £143m:
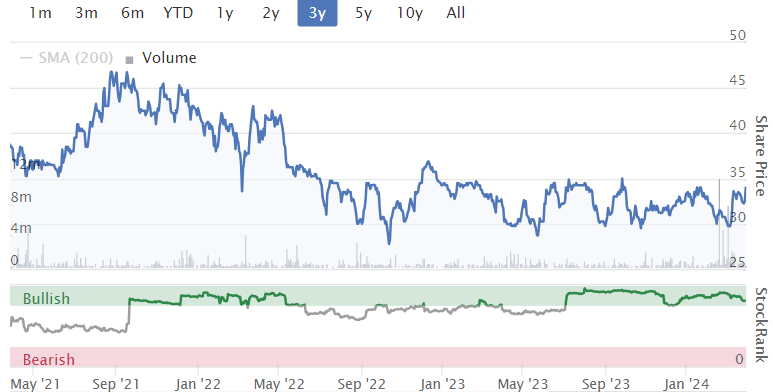
I imagine that the company would probably like to raise money, in order to continue growing and diversifying its portfolio.
However, with the share price sitting at a discount to book value, and with general investor appetite being what it is, raising new money right now is probably not very easy or very appetising.
But until it raises new money, investors might (with some justification) worry that the portfolio still isn’t diversified enough yet. And this in turn justifies a share price discount to NAV! So we have a chicken and egg-type of situation.
For me, the shares at this level do continue to represent decent value. The company has only had one unprofitable exit so far, and even that exit was very impressive (it failed to lose much money despite investing in a riverboat cruise operator prior to Covid).
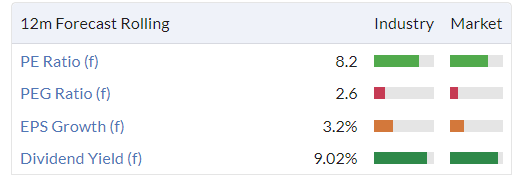
At a yield of 9% and with the company still not having put a foot wrong, it gets the thumbs up from me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Dear Paul,
You may have followed the company but you clearly do not understand the Zoo Studio licence that Zoo has with Disney and how that is compensated for doubtless the company would happily explain this to you but it would help you if you did. 36m shares trade this week in that stock you should be up to speed on that sort action and understand both sides of the debate
Note I am not taking a side merely highlighting some of the blanks in your discussion about it
I think you’re out of line. Paul’s job is to assess the health of the businesses under review with particular reference to the balance sheet and to consider the risk/reward based on the valuation multiple. Your job is to investigate further and come to a conclusion about the companies’ products and prospects. If you firmly believe he and, more to the point, the market, have got it wrong, then back up the truck.. But don’t chastise Paul for disagreeing with you. That’s what makes a market!
Definitely out of line... its not possible for Paul to understand every nuance of the hundreds and hundreds of companies that he covers per year ... you may very well be right that it multibags from here ( and with director buying this week ), but if you can't be bothered to explain the Zoo studio licence to him, then its hard for others to get onside...
You are replying to the wrong person. Should be Tombholiday not BnB.
Many apologies... you're quite correct.. I was obviously agreeing with BnB and thought that it would read clearly as a thread... but you're right if it's unthreaded... many thanks indeed for pointing out
No problem.
Tombholiday... Please enlighten us about the nuance of the Zoo Digital (LON:ZOO) and Disney relationship then...
Add something useful to this discussion forum rather than just point out that others are wrong? Share with us, just like we share with you here on SCVR...
Paul as a long term investor in Zoo your comments about being a bad business could be read as ‘ a business I have not bothered to understand’ you do not become a key supplier to Disney based in Sheffield for a decade plus without offering a valuable service please try and understand the company and the industry before passing judgement - has anyone mentioned that Hollywood was on strike for most of last year
Hi Tombholliday,
Actually I've followed and researched Zoo Digital (LON:ZOO) for many years. I owned some shares in it myself, catching the move up from about 10p to about 50p around 2010-11. Lots of my investing friends & contacts have been bullish on ZOO more recently, so I've heard the bull case in great detail from lots of people.
Why do I say I think it's a bad business? From the figures! It failed to make dependable profits until 2022 & 2023, when there was a boom in streaming services, spending big on rolling out to new territories, commissioning their own programmes, etc. That has since fallen back somewhat, and as you say, collided with the Hollywood strikes to make FY 3/2024 a financially disastrous year with a huge loss that has almost wiped out a cash pile it raised in a placing just before disaster hit, which had been intended to pay for an acquisition in Japan. Instead it proved a lifeline that kept the company afloat, with most of that cash now gone.
ZOO has always claimed that it has some unique technology, but actually its contracts are low margin, in a very competitive sector. That's why it's only ever had one year of significant profit, in FY 3/2023. All the other accounts for the previous 22 years are either loss-making, or negligible and unrepeated profits. This is why I think it's a bad business! The figures tell me that. Although it started out in computer games, and seemed to pivot into interactive DVD software, then into subtitling/dubbing services more recently.
I assume you've looked at the most recent broker note, which shows 50% revenue growth is needed in FY 3/2025, but that only gets it near breakeven, not profits.
Why did the loss in FY 3/2024 become so extreme? Partly due to the strikes, but it's also clear that ZOO has far too much in fixed costs. It should have been able to scale down during a fallow patch caused by the strikes without incurring the massive losses it has incurred. That suggests to me the costs are too fixed, when they should be flexible, scaling up or down according to demand.
Why did Disney use them for 10 years as you claim? Probably because they offered the best mix of quality and price - and in doing so didn't make any profit throughout that period. So what's the point? Clearly ZOO doesn't have the pricing power that I would look for in a quality business, which would be making a consistently high PBT margin, which ZOO has failed to do over the last c.24 years, other than a blip of big profits in FY 3/2023.
I'm happy to change my mind, if the facts change. But at the moment, it's really struggling. Lots of positives in the latest update, but the bottom line is that things are just getting less bad, and even with positive assumptions the broker can't get the forecast into positive PBT.
We've written about ZOO 36 times here over the last 12 years, so it's one we follow quite closely.
I know it hurts when somebody expresses a bearish view on a share that you are emotionally attached to. But it pays to listen to what other investors think, as they may have spotted something you haven't. All our 36 articles are based on the facts & figures at that time, and we change our minds readily all the time, when the facts change.
Dismissing people as not having researched a company, just because you don't agree with their conclusions, is not a good move I find.
Anyway, I hope ZOO does well for you, and you recoup your losses. It certainly has the wind behind it now business is picking up again - the only question is whether that will be enough to get it back into profit before the cash runs out? I'm happy watching from the sidelines, because it's just not a very good business model, as the financial results have clearly demonstrated over the years. Why would anything change to suddenly make it a profitable & cash generative business, given its failure to achieve that in c. 24 years to date? The interesting thing will be what level of business it is able to rebuild after the strikes. FY 3/2023 showed that it can make a decent profit (one year only) when revenue shot up. If that's the new normal then great, you're on to a winner. I'm just sceptical about that until we have more proof. So is the market, with shares having collapsed over the last year.
A final point is that I think AI could well prove difficult for ZOO. I know it argues that AI can't produce all the nuance of human speech, but look at how fast the technology is advancing, and the amazing results (in the early stages). At the very least that might mean ZOO has to price even more keenly to win contracts, when computers can do nearly as good a job for a fraction of the cost. Who knows how that will pan out, but it's bound to weigh on sentiment.
Good luck with your investment. Sentiment may have turned recently, so there's already been a nice rebound trade in it for people who bought at the bottom. Time will tell how it pans out. But until there's evidence it's moving into profit, I remain sceptical.
Paul.
P.S. Dilution is an issue, as ZOO is a serial fundraiser. I think it might struggle to get any more fundraises away, as there was uproar after the last one, when some investors commented here that they felt fleeced, paying a high price just before trading fell off a cliff.
Looking back through the old RNSs, in Dec 2009 ZOO seemed to be doing its current activities, having moved on from the old activities of computer games and interactive DVDs. It had 21.3m shares in issue then. The total now is almost 5x, at 97.8m. This is the trouble with jam tomorrow companies generally - they need funding for the years of losses, so that early investors end up seeing a lot of the gains diluted away. Here we are at 35p, with pretty much all the boom from 2017 having been given back. Could it have another bull run? It's possible, I don't know how things will pan out. the market cap is only £35m now, so if it can demonstrate really strong growth, and not need another placing (unlikely in my view), then there could be nice upside maybe. Personally I'm not convinced, so will sit on the sidelines and see how things pan out, as it's pure guesswork at this stage.
For those at HQ, I don't pay my subscription to Stockopedia for the figures, but for gems like Paul's well reasoned and argued response, thank you Paul.
Elementis (LON:ELM)
Bid rumour perhaps or just the usual market ups and downs? Previously rejected bids at 160p much to the irritation of institutional shareholders. It is the largest holding in the Odyssean Investment Trust (LON:OIT) managed by Stuart Widdowson and Ed Wieleckowski, part of the Harwood stable
Share price up nearly 6% today on very large volume, closing at a two year high. The shares are held in my wife's ISA.
Corero Network Security (LON:CNS) If you missed Corero Network Security y/e live presentation yesterday, a recording is available HERE. They are a disruptor to the business of mitigating denial of service attacks on businesses and are offering twice the performance at half the price. With an impressive growth record of ARR CAGR of 24% over the last 5years, 11% YOY revenue increase to $22.3m, cash generative and debt free with a YE cash balance of $5.2m yet still a very modest valuation of £46.3m.
HSS and Speedy Hire
Talked a week or so ago about these .
HSS seems to have had some sort of short squeeze on stock with a 22% rise, there is the possibility someone is making a move on it or just more buyers than sellers .
Not entirely sure what’s going on could have been just totally oversold a week ago .
Speedy has only ticked up s bit .
Anyway I’ll take a 22% rise in the week after buying as an Easter present , I did sell 15% of what I bought right at the top today just in case it’s going to resume its long downward trend and this is blip in thin trading where we are getting extreme spikes on no volume .
Paul your comments on Zoo were you not on the wrong side of the business when it ran up from sixty to two pounds turning near the top? I only mention this as there is a danger that you are about to repeat that mistake I see the CEO has put his hand in his pocket and they have order clarity from their largest customer ?
Tombholliday, you asked -
Paul your comments on Zoo were you not on the wrong side of the business when it ran up from sixty to two pounds turning near the top?
We're analysing the company fundamentals here, not trying to predict what share prices will do in the short term. The two things can & do detach completely very often.
I've been sceptical about ZOO for a long time, as I don't see a viable business. More one that enjoyed a boom in the pandemic when streaming companies binged on content creation, but are now cutting back. Plus of course the impact of the Hollywood strikes, whose ending now could provide upside - but will the upside be enough, remember that current forecasts require a 50% uplift in revenues for ZOO just to reach a bit below breakeven?
Looking at the 5-year chart below, who was right, the bulls or the bears? Arguably both, at different points in time. I think my fundamental analysis has proven correct, that's why the share price is so bombed out.
Could ZOO do another bull run? It's possible yes, but it has to grow gangbusters just to reach breakeven. Oh, and it's almost run out of cash too. It's just not a very good business I'm afraid. Hence why I remain moderately negative at AMBER/RED. If the facts change for the better, and the growth rate exceeds 50% this year, then I'd be happy to shift our view upwards.
Remember we're weighing up the facts & figures here, not making emotional judgements about what we hope will happen.
Regards, Paul.
Sanderson Design (LON:SDG) Just took a position in this company after noticing recent fall and doing a bit more research. It's part of my basket housing recovery shares that I except to do well if the UK market does pick up at some point - along with MJ GLEESON (LON:GLE) Michelmersh Brick Holdings (LON:MBH) and Property Franchise (LON:TPFG)
SDG is clearly cheap on a roughly 8x PE ratio, and with a decent chunk of cash so even cheaper on EV basis. It's also nearly fully asset backed.
The key thing here is the licencing. As we know the core UK business has been soft over the past year and basically operating around breakeven, Thankfully, the licencing (which is pure profit) has offset this and earnings have proved pretty resilient as a result.
However, I never really understood if the licencing was a one-off that would fall away, or rather the start of a new growth engine. If the latter, then SDG's prospects should be very good as you have the potential for continued growth in licencing, coupled with a recovery in the core UK business.
Licencing grew very strongly last year, but from what I can gather there could be more to come as there has been a raft of new deals announced over the past 12-18 months and many of these have not even commenced yet (although I think there is some accelerated income that they have already accounted for) - eg a major new deal with Next to sell Clarke & Clarke homeware products isn't even due to start until spring/summer 24 (although they do have other older deals with Next on the clothing side). Similarly, a deal with Habitat isn't due to start till autumn.
Perhaps more interestingly, there are now several deals in the US where the overall growth opportunity has to be much bigger - eg a deal with NY-based designer ENVOGUE was announced in January and rug company Ruggable in December. They also have an older deal with Williams Sonoma - not heard of them before but they are listed in the US and have a market cap of around $20bn with very strong share price performance - can't be a bad thing having an agreement with a company like that!
Overall, based on my initial research I'm fairly re-assured that the licencing part of the business has good growth prospects, and if we combine this with a future recovery in the core UK business, coupled with some multiple expansion, then I think we could see some pretty good returns here over the next 2-3 years.
Bouden
SDG
Good analysis fully agree with you .
Think the William Morris archive is very valuable and under appreciated by the market and probably not on the balance sheet (not sure )
I asked the CEO if there was a risk license agreements would be lumpy or ever increasing and fair to say she was very bullish .
A good friend of mine runs the IP for Conan Doyle estate and if a company can focus on developing the value in its brands and heritage it can generate a lot of “free” cash as licensees literally wrote out cheques and you don’t do much .
If SDG can generate 10 million a year on license revenue you would have to say the archive alone is worth 50 million .
Anyway your preaching to the converted but one of the best AIM companies and I think it is valued incorrectly .
Sanderson Design (LON:SDG) it would help if the directors bought some shares, nothing for nearly 3 years.
Would I buy shares in the company I work for currently Urm NO
Do I work for them, YES
Complex and very personal it is a nice to see but I do not see it as necessarily bad if they do not
I hold Sanderson Design (LON:SDG)
Tommy
Airline and Tour operator Jet2 have announced that they will be launching flights from Bournemouth Intl Airport to 16 destinations from April 2025. Its coming home as the concept for Jet2 was started by Phillip Meeson in 2002 at the same airport.
Yes, I'm very much looking forward to mystery flying with Jet2 from Bournemouth, and reporting back on the experience! The share price of Jet2 has done very well, but it still seems cheap on value metrics. We like it here, hence have covered it a few times in the SCVRs.
Someone posted a really useful link to a site displaying gilt prices/yield to maturity etc (a private one, not the HL one) a year or so ago. My searches aren't finding it - does anyone have remember/have a link.
Many thanks, Rob.
(Apologies not small cap related)
Was it this one - https://www.yieldgimp.com/gilt...
Many thanks - that was the one
Glad I could help
Might also have been this one?
https://www.dividenddata.co.uk...
Thanks - that was a new one for me. Also useful :-)
Airline and tour operator Jet2 is launching flights from Liverpool to 20 different holiday destinations.
The first flight jetted off from Liverpool John Lennon Airport to Tenerife at 08:00 GMT.
They are also putting in about 20 destinations from Bournemouth Airport. Should do very well and have monopoly on large territory.
#ZOO I would have brought into Zoo Digital earlier this at week on the day of the TU and director buy. I can see investors pushing this SP up alot over time with time and futher positive updates. A lack of cash stopped me.
That said, a possible negative that may or may not have been fully dealt with in my eyes in the proposed acquisition of the Japanese 'trusted partner'. Surely that deal got very close, was anything signed, they last said it was on hold as far as I'm aware. Clearly they want to get it done but they wont get it financed by equity (for the second time), they dont have the cash as Paul has indicated, will they end up compensating the target for not completing, if not, has that impacted their relationship.
A loose end, maybe someone has the answer from management?
Shorts reducing at ASOS (LON:ASC) - could be a nice squeeze
https://shorttracker.co.uk/com...
I know Paul was desperate for a Papa John's pizza last week, they are closing a 10th of their branches in an effort to boost profits, but not the one in Bournemouth.
Hi Paul I appreciate all your hard work, its a great guide for me. I like britsh engineering companies have ever cast your eyes over Flowtech Fluids?
Graham looked at it https://www.stockopedia.com/co... . Look on the discussions tab for Flowtech Fluidpower (LON:FLO) for the other times it was covered.
Nexteq (LON:NXQ) - (I hold).
Interesting RNS today headed 'Proposed Share Buyback and Notice of GM'.
Excerpt reads:
Proposed Share Buyback and Rule 9 Waiver
The Company proposes to seek Shareholder approval to have the authority to buy back up to 10 per cent of the Company's issued share capital, being up to 6,653,906 Ordinary Shares.
Assuming utilisation of the full buyback authority, the Concert Party (being Nicholas Jarmany, Francesca Marzilli, Alessandro Jarmany, Oliver Jarmany, Daniel Jarmany, Gary Mullins, Sophie Mullins, Susan Mullins, John Mullins, Mark Mullins, Jacob Mullins, Joseph Mullins, Louis Mullins and Best Acumen Limited), may own up to approximately 37.3 per cent of the voting rights in the Company. Therefore, the Independent Shareholders will be asked to waive an obligation on the Concert Party to make a general offer for the entire issued, and to be issued, share capital of the Company which may arise under Rule 9 of the Takeover Code as a result of the Company purchasing its Ordinary Shares.
I did ask a question at the recent results presentation regarding possible return of some of the large cash pile to shareholders so I see this as good news.
Shares up 3p to 156p.
Snazzy
Some very solid results today for high dividend stocks: Chesnara (LON:CSN) - 19 years of dividend growth at 3% with a 9% yield. Share price doesn't reflect the progress. BBGI Global Infrastructure SA (LON:BBGI) - 6.5% yield, 17% discount and 6% dividend growth. This is the lowest risk listed infrastructure company on the LSE with 56 availability type infrastructure assets. Dividend can be increased for 15 years without any new deals. International Public Partnerships (LON:INPP) also good, with 5% dividend growth and an increased dividend since 2006 but slightly higher risk owning things like Tideway Tunnel. Not sure that these are going to remain on such discounts once the pivot comes. BBGI Global Infrastructure SA (LON:BBGI) is my favourite and will watch the presentation at 1.30pm today.
Not a big fan of banks, but do hold Arbuthnot Banking (LON:ARBB) - excellent results from Sir Henry Angest's bank today. Prudently run. On a P/E of less than 5 despite a 4.3% dividend yield and a Return on Equity above 10% in the current year. In my view, it should be valued at book value of over £15.47, but its £5 off. £173m market cap versus £252m equity.
Thanks for some ideas Topvest, I do love a good divi payer.
Thanks Topvest, nice ideas, I hold BBGI & INPP in my income fund, will look at Chesnara but I already own L&G and Phoenix in that space.
Please keep the ideas coming, I am trying to perfect a 'buy and forget about' income compounder fund with a 15 year time horizon. It currently has 25 stocks in it but want to get that to 40 with a blended yield of 6.5% + but most importantly growing dividends.
I might start a fresh discussion thread on this subject so as to not disturb the SCVR theme because I think a lot of people are interested in income...
Hi Burnt Onions,
Greek Organisation of Football Prognostics SA (ATH:OPAP)
This one by far exceeds your criteria. Its largest shareholder (Allwyn) recently took over as the operator of the UK national lottery. Growing profits, dividends (current yield 11%) and SP for the last 10+ years!
All the best
Thanks Yiannos, you're right, an impressive business and amazing performance over the last 5 years, definitely worth learning more about it.
Hi Burnt Onions take a look at Ken Mitch's "how to win in a bear market, buy quality it works" thread loads of stuff on their that will most likely appeal to yourself.
Regards Andy
Good post, thanks - amongst a wide selection of investments I'm holding both Chesnara (LON:CSN) and BBGI Global Infrastructure SA (LON:BBGI) for the excellent income and potential capital rise if / when IRs fall.
hi Paul
DP Poland (LON:DPP)
Secondly this £20.5m fundraise is cornerstoned by larger UK Dom Development SA (WAR:DOM) which is subscribing for just over half the fundraise.
Sorry to have to correct you on a day of stunning output but the £11m subscriber should read Domino's Pizza (LON:DOM).
Assuming the full £20.5m is raised then Domino's Pizza (LON:DOM) would have a 12.1% interest. Also they have an option agreement to increase to 29.99% in future.
I find this investment rather perplexing given previous Domino's Pizza (LON:DOM) CEO's exited their foreign operations to become a pure UK & Ireland operation. The new CEO clearly thinks differently but then again he does have extensive experience having been a major franchisee in Australia.
I hold but do have some reservations whether this is a good move for Domino's Pizza (LON:DOM) . Initial market reaction is a little subdued. Time will tell.
Snazzy
Domino's Pizza (LON:DOM) DP Poland (LON:DPP) there was a reassuring announcement yesterday afternoon about this from DOM which caught my eye as I hold. It seems the opportunity is to grow from 111 outlets to 500. There is more detail in the announcement. In a nutshell Mr Rennie was involved in appointing the CEO of DPP and describes him as a “Dominoid” ;) -so maybe we will have experienced people here now who are intelligent fanatics about the business? I must say Dominoid reminded me a little of the kind of thing that would appear in a Games Workshop annual report.
Andrew Rennie, DPG Chief Executive Officer, said:
"I'm delighted to be partnering with DPP as we continue to execute against our new growth plan. DPP is a fantastic business with a significant growth opportunity ahead of it. Whilst the Domino's brand is strong in Poland and Croatia, both markets are significantly underpenetrated with a unique store opening and profitability opportunity."
"We have strong guardrails in place as we re-enter international markets, and our investment in DPP is structured in a capital-light manner, with an initial investment of £11 million. Stoffel Thijs, who has deep experience operating in the European markets, will be our Board appointee to help accelerate growth and drive value for our shareholders. I look forward to working with DPP's CEO, Nils Gornall, a near 30-year Dominoid, who has done an outstanding job leading DPP since his arrival almost 2 years ago."
Thanks Snazzytime, drat the publisher picked the wrong company for the ticker I input, and I didn't spot its error. Will correct that. Of course it was meant to say Dominos Pizza. Apologies & thanks for pointing out.
Loungers (LON:LGRS) Delivering self-funded growth “all day” long *** initiation report ***
Loungers is an award winning, uniquely positioned all day café-bar group that has grown revenues an impressive 22.5% CAGR FY16-FY23. Comprising of Lounges, Cosy Club and Brightside, the 257-site group still has huge scope to grow towards its conservative ambition of over 650 sites.
Loungers is profitable with improving margins and we forecast will generate over £100m free cashflow (pre-expansion capex) FY24E-FY26E. This, we estimate, will fully fund c.100 new site openings over the next three years driving 16% CAGR in Revenues, 18% CAGR in Adj. EBITDA and 20% CAGR in Adj. EPS FY23-FY26E.
This high growth is not reflected in the group’s valuation, in our view. We initiate coverage with a Fair Value of 360p, based on 8.0x cal 2025 EV/Adj. EBITDA.
Link to research note: https://www.equitydevelopment.co.uk/research/delivering-self-funded-growth-all-day-long
…AND they serve the new and much improved Hofmeister beer (unlisted - I hold!) on tap across the whole estate. Classy beer for a classy format. Loungers continue to do a great job in differentiating in a very competitive market.
Easter watching for investors: Investing in Compounders. Video & podcast.
This superb presentation was made by Bill Fawkner-Corbett, Head of SIGnet (Serious Investor Group Networks, part of ShareSoc). It gives methodology of how to value high growth companies with strong ROCE and gives confidence to pay up for them and still make a stunning return, or indeed not to sell them as they ascend.
As Charlie Munger says,
"If a business earns 18% return on capital over 20 or 30 years, even if you pay an expensive
price, you'll end up with a fine result. So the trick is getting into better businesses. How do you get into these great companies? Find them small get 'em when they're little.”
This was given to Bill's regional SIGnet group, it provides a flavour of what you might enjoy by joining a SIGnet group. At the end there are details of SIGnet, how to join and what to expect. (SIGnet is a non profit organisation for investors.)
Heiq (LON:HEIQ) results mentions "Adjusted LBITDA" - made me chuckle!
https://www.investegate.co.uk/...
Damning piece about 'univestable' UK mkt in the The Standard:
Fears over ‘uninvestable’ London stock market as more firms tipped to leave City
https://www.standard.co.uk/bus...
The question is whether this is part of a cycle or a permanent shift towards a smaller less relevant market.
At this rate a useful investment strategy might be to look at take outs of undervalued companies with limited downside.
If someone at Stockopedia is looking for a new thread idea they might want to start an official takeover thread
Not a new thread but I seem to remember Planetx started a "Top Takeover Bids Challenge" on the SCVR on 24/10/23. See link https://www.stockopedia.com/co... Hope this helps :)
Thank you
Probably an indicator that the market is going to explode upwards! It certainly feels like there is a significant amount of money flowing into small caps (and large).
I think that it is becoming fashionable to view the UK as uninvestable.
However I believe the current low performance of the FTSE is largely cyclical and you will recall that fifteen months ago one of the worst performing indexes was the Nasdaq (clearly no longer the case).
The market is beginning to recover and broaden the sectors which are improving which include those that are economically sensitive and cyclical.
The situation does make me recall Ben Graham's comment about the stock market being a voting machine in the short term but a weighing machine in the longer term. I think we are moving away from the voting scenario to the weighing scenario.
I think the good value in the FTSE makes it very investable.
Megan Boxall using Stocko data, has reviewed the medium term performance of FTSE 100 I think. The weak industrial performance is down to much more than 'cyclical'. Issues on growth, ROCE, and relatively big dividends rather than finding investment opportunities etc. Such trend analysis is what makes Stocko so valuable. However Tamzin's stear to Bill Fawkner-Corbett video on Compounders is useful too. He says he has lots of UK firms in his portfolio, but doesn't mention any! Yah Boo
Low performance of the FTSE is nothing new and has been going on for years now due to the lack of growth from most of its constituents. Banks and supermarkets that are not growing , too many insurance , building and mining companies , and meaningless telecommunications listings.
Urgent change needed regarding the entry and exit rules of its constituents.
All the best
No growth, high debt and often high dividends. Compare that with most US large caps, growth, no debt, lots of cash, low or no dividends.
The largest companies in the US has changed considerably in the last 20 years but not in the UK.
Both cyclical and long term..
Obvs but worth pointing out the size of a stockmarket and depth of capital pools it has access to is v.v. closely linked to the size of the host economy.
Ours has been in relative decline compared to the world for the last 150y or so.
We got a boost from EU membership which helped the city to grow relative to the uk but that will move back to the EU over time.
Most of the growth companies listed in the uk do a lot of business overseas in the us and eu. The deep EU capital pools are now in the EU. Inevitably more companies will move away from the uk because the money isn't here anymore.
In terms of cyclical we have a different mix of companies compared to the us and I think if you looked on a sector/sector basis you would see similar returns.
In the short term I do think we are enjoying (?) a continuing moron discount. Looking from the outside: over the last 10y we have voted to be poorer like no one ever, had 5 pms like Italians, stated we will walk away from international treaties like South Americans. And liz truss.
It is short term so I am happy buying and holding uk stocks.
I will leave what one might politely describe as financial journalists to their own often sensationalist views. Good news doesn't sell newspapers. As for me its about what you buy and more importantly what you pay.
Thanks for the comments yesterday .
Transense , Volvere ,
Volvere was the most interesting going to have a good look today .
Met the MD of Transense yesterday afternoon for a very interesting chat .
The good news is s proven entrepeneur who has built s similar sector business from nothing and exited it a few years sgo and learnt a lot of lessons on his journey - these are hard won expensive battle scars that you don’t get too often in an MD .
Transense appears to have been previously in the luxurious position of having a very nice income stream from licensing / selling sone technology to Bridgestone at which point the staff associated with the Bridgestone part of the business left leaving two parts of the business that are a work in progress sucking up this cash .
No need a cash raise because the Bridgestone cash supports it but very much leaving a science led men in white coats operation with s luxurious income stream and no commercial driver or accountability especially to long suffering shareholders .
Not quite sure why the new MD would want the job as he’ has built bigger businesses that he owned himself and exited but he seems to be fully committed and commercial and grounded .
We discussed some business strategies that we had found useful that he said he had had to explain to some incumbent staff
“We have to sell our products for more than they cost us “
“We have to charge for our time when working for a client “
Really quite interesting and I suspect very common on these outfits that have evolved out of “spin out” companies that then list on AIM with a bit of hope and lot of hype where effectively non commercial scientists and money men try to commercialise an idea but are really fish out of water commercially hence so many jam tomorrow cash burning drive the shareholders into a brick wall Armageddon wipeouts over the years .
Going to be one to watch, the tyre depth measuring system looks a total tap in but they’ve had it years and done nothing with it of note so I think that will either start to happen this year with sone new effort and a recently hired head of sales with s good track record or it’s never going to happen .
The other part of the budiness an engine monitoring thing sold to manufacturers has a very long runway and lots of potential so not going to be much moving there so I would be expecting much from that just yet but all sounds very interesting but my brain got foggy with technical details
Anyway I liked the guy and we had a lot of shared stories and the rise and fall and rise and exit of building previous businesses and thankfully he understands “sell it for more than you pay “ so that’s a good start for an MD .
Saw this this morning:
"Thames Water said its shareholders would no longer provide £500mn of fresh equity by the end of the month, noting that conditions imposed by the industry regulator made the company’s business plan “uninvestable”
Any risk to Costain (LON:COST) ? I remembered that they do alot of work for water companies. Presumably less equity/funding means less capex than be spent.
I can't imagine that any Government would allow the increasing sewage pollution of water courses and rivers. It's hardly a vote winner. On that basis whether or not Thames is nationalised I can only envisage spending on water industry infrastructure increasing in the medium term.
There are huge sums involved in having to upgrade the sewage systems because of the old style dual function of UK's sewer system of combining water run off and sewerage draining- with increased rainfall overloading the system. That's something you hear less about in our media age, because outrage is a better headline than solution finding. The Govt can't afford to upgrade all the systems, so it needs private capital to step in and do so, and that requires a semblance of a return for shareholders/lenders, but it seems, as usual, people want improvements but don't want to pay for it themselves. That's not to say of course that all Water Companies are wonderful.
Agree ... majority sentiment is that we can honestly and virtuously look to utility shareholders to gift us an unearned free lunch. Vegan, of course, so that we can all continue to feel even better about ourselves.
Capital comes with a cost. It has to be paid for ... no matter the use.
ONS revised figures show we did enter a recession at the end of last year. A 0.1% and 0.3% contraction.
Kitwave (LON:KITW)
A business that is not resting on its laurels, this morning announces a further reasonably sized acquisition of Total Foodservice for £21m in cash. It will be integrated into the higher margin foodservice division. This appears to be a sound deal with the net outlay to Kitwave (LON:KITW) being £17m due to the £4m on the balance sheet of Total Foodservice.
Kitwave (LON:KITW) is a company I hold and like. It is easy to understand, generates cash and has a substantial runway for growth. Although the founder Paul Young has recently retired he remains a significant shareholder. The former Chief Operating Officer, now CEO, Ben Maxted has been with the company for sometime and knowns the business inside out. He came across very well in the recent investor meet company webinar.
My main concern is that the company doesn't over extend itself financially.
"Established over 130 years ago, Total Foodservice delivers wholesale catering supplies of around 4,000 product lines including chilled, frozen and ambient food, non-food and cleaning products. Total Foodservice's depots are located in Clitheroe, Lancashire and Huddersfield, Yorkshire with customers including licensed trade and restaurants, coffee shops and sandwich bars, schools and universities and the care industry across the North of England.
Total Foodservice reported an audited turnover of £25.4 million, profit before tax of £2.0 million and the balance sheet had net assets of £8.5 million for the financial year ended 30 April 2023. The acquired balance sheet includes c.£4.0 million of cash and freehold property with a book value of £2.1 million. The net cash outflow from the Group as a result of the consideration payable and the cash acquired is c.£17.0 million. The Board believes that the Acquisition will be immediately earnings enhancing after adding back costs relating to the transaction."
Enjoy the Easter holiday.
hi jonno
Kitwave (LON:KITW) - (I hold)
Excellent post and agree with your comments.
Canaccord Genuity increase their f/c EPS for FY'24/25/26 by 2%/4%/6% respectively. They also increase their target price from 435p to 455p. Dividend f/c for FY'23 reduced to lower end of expected payout range (i.e. broadly flat at 11.3p).
Estimated leverage FY'24 including leases is 1.8 (company target max 3.0) and 0.8 excluding leases. That's comfortable now but I agree it's worth keeping an eye on debt with further acquisitions given the main use of funds raised at IPO in 2021 was to reduce debt from quite stretching levels.
Broker estimates the multiple paid for Total Foodservice Solutions (excluding cash and freehold) is c.5x annual run rate EBITDA of c.£3.0m which makes it look a good deal for Kitwave.
Market seems to like this deal with SP up 15p to 371p.
Snazzy
Todays acquisition with operations out of Clitheroe and Huddersfield, following on from last years acquisition in Oldham, adds to KITW already large footprint in Lancs and West Yorkshire.
Can’t help but think that there may be an opportunity at some point to consolidate some of these sites and reduce lease liabilities.
Thank you Snazzy, very kind.
Founder CEO agrees to step down as CEO at Quiz (LON:QUIZ), good news.
Bad news? His son is taking the CEO role! "fresh approach" is trumpeted as one of the benefits....
No wonder the strategic review has so far failed to materialise any new investors or bids for the company.
In recent weeks I’ve had a clean out out of some old “starter” positions like Quiz - those which haven’t worked out.
Why be stuck in something paying no dividend in the uncertain hope of recovery when you can redeploy funds into new opportunities with strong investment cases?
I track the performance of all holdings I have sold and broadly there is a pattern: where I’ve top-sliced a successful investment I generally regret it in hindsight; in contrast where I’ve reluctantly acknowledged mistakes and cut and run I generally don’t regret it.
My morning smallcap tweet: Masters of disasters
Byotrol (LON:BYOT) Cloudcoco (LON:CLCO) Northamber (LON:NAR) Team (LON:TEAM) Sareum Holdings (LON:SAR) Quiz (LON:QUIZ) Kanabo (LON:KNB) Microlise (LON:SAAS) DG Innovate (LON:DGI) AO World (LON:AO.) Journeo (LON:JNEO) SIMEC Atlantis Energy (LON:SAE) Digital 9 Infrastructure (LON:DGI9) AdvancedAdvT (LON:ADVT), Idox (LON:IDOX), James Latham (LON:LTHM)
◄Byotrol (BYOT)► guides FY-Mar rev inline. EBITDA -£1m (-£0.7m). Proposes to delist blaming cost and lack of liquidity. [SP=0.39 Cap=2m]
◄Cloudcoco (CLCO)►I always read this as CloudCuckoo. FY-Sep accounts will miss end Mar deadline by a month and shares will be suspended. Trying to refinancing the loan notes - is this the real reason? Trading in line. [SP=0.76 Cap=5m]
◄Northamber (NAR)► H1-Dec rev down 13% due to weak mkt. Pretax -£413k (-£250k). Outlook cautious. [SP=46.5 Cap=13m]
◄Team (TEAM)► £1.1m placing and subscription at 20p, a 5% discount, for acquisitions and deferred consideration pls working cap. [SP=20 Cap=6m]
◄Sareum (SAR)► £1.5m placing at 10p, a 31% discount, to complete Phase 1a clinical studies on its SDC-1801 TYK2/JAK1 inhibitor and working cap. [SP=14.04 Cap=10m]
◄Quiz (QUIZ)► Guides FY-Mar in line. Jan-Feb rev down 9%. YTD (to Feb) rev down 12%. Big-hitter chmn Peter Cowgill gets stuck in to sort out this failure. CEO & founder steps down to NED. [SP=5.89 Cap=7m]. I hold.
◄Kanabo (KNB)► expansion of its online clinic, Treat It, to include specialised mental health treatments. [SP=1.5 Cap=9m]
◄Microlise (SAAS)► wins AU$20m 5 yr contract from Woolworths Australia. [SP=133.7 Cap=155m]
◄DG Innovate (DGI)► MoU to establish a JV with an Indian electric vehicle maker and automotive technology company to make Pareta® e-drives. [SP=0.17 Cap=17m]
◄AO World (AO.)► recovery under the returned founder continues. Guides FY-Mar rev c.£1.04bn and adj pretax at least at the top of the guidance of £28-£33m. Outlook - "confident in our ability to deliver on our ambition for 10-20% revenue growth in the year ahead and medium-term profit guidance of 5% adjusted PBT margin." [SP=89.85 Cap=520m]
◄Journeo (JNEO)► wins £1.5m purchase order from Swansea Council. Amount is in mgmt expectations. [SP=276.88 Cap=46m]. I hold.
◄SIMEC Atlantis Energy (SAE)► gets first £5m milestone payment from EL (Uskmouth). Remaining £4.8m payable against three further milestones - expected over next 12 months. [SP=0.79 Cap=6m]
◄Digital9 Infrastructure (DGI9)► independent asset valuation (at end Dec) gives preliminary NAV of 84p/sh, down 16% on June. [SP=21 Cap=182m]. I hold.
◄AdvancedAdvT (ADVT)► H1-Dec adj EBITDA -cont £3.7m, ahead of management expectations. Guides FY ahaead of mgmt exp. [SP=122 Cap=163m]. I hold.
In line: IDOX, LTHM
AdvancedAdvT (LON:ADVT)
A great start to Vin Murria’s latest venture, which listed on AIM in January. One of my first large investor successes was with Advanced Computer Software where she was CEO and I have followed her career since. (I hold AdvancedAdvT (LON:ADVT) ).
Six months to 31 December 2023 - financial performance
· Revenue from continuing operations of £15.1m. Total revenue from all activities of £16.1m which includes revenue from Synaptic Software Ltd which was disposed post period end.
· Recurring revenue represented 76% of total revenues.
· Adjusted EBITDA from continuing operations of £3.7m ahead of management expectations.
· Pre-tax profit of £3.3m (2022: loss £0.1m).
· Reported EPS of 2p.
· Cash of £78.7m as at 31 December 2023 (June 2023: £104.7m).
AdvancedAdvT (LON:ADVT) A great start, in profit in the first interim and year looking to be ahead of expectations.
Share price a sum of parts:
c.60%(£98m) of market cap in cash and SAA holding which is 73p of current share price of 122p.
Leaves £65m for the underlying business, 49p per share. PE of 12 (updated thanks to Poker111).
Maths may be rusty, not had my morning cuppa yet :)
If the EPS is 2p for 6 months, PE is more like 12
I stand corrected. Knew I should have waited till I’d woken up properly :)
Fabulous start!! Great work as always
Excellent early run down Paul!
Amazing quality output - Happy Easter chaps!