Small Cap Value Report (Thu 28 Oct 2021) - FOXT, SPEC, VARE, FTC, VINO

Good morning, it's Paul & Jack here with the SCVR for Thursday. Today's report is now finished.
Agenda -
Paul's Section:
Foxtons (LON:FOXT) - the London-based estate agent reports surprisingly robust London housing market, with lettings and sales recovering strongly - including rents back up to pre-pandemic levels. That's encouraging for a wider recovery in London activity I reckon, although it remains to be seen how many office workers will continue working from home?
Various Eateries (LON:VARE) - an expanding chain of all day "clubhouse" type bar/restaurants called Coppa Club. There's a bit too much PR spin in today's update for my liking. LFL sales are good, but it glosses over the benefit from temporarily lower VAT, and fails to mention its related party debt, preferring to only mention gross cash - selective reporting that raises my hackles. Market cap of £72m looks a stretch, given that it only has 12 sites, and no track record of profitability yet. But, both customers and investors like new formats, for a while.
Filtronic (LON:FTC) - a reassuring update, in line with expectations for FY 05/2022. Trouble is, the expectations are for only £0.5m profit. No divis for years, and lumpy performance, makes me struggle to understand why anyone would want to own this share. Do explain in the comments section, if there's something great about Filtronic which I've missed.
Virgin Wines Uk (LON:VINO) - results for FY 06/2021 look good, especially when £3.5m IPO costs and pre-IPO finance costs are adjusted out. Growth has slowed from c.30% to c.13% in the new financial year though, now that tougher comps are annualising. Valuation is probably a bit higher than I personally would want to pay, given likely slower growth in future. But overall, it looks a decent company.
Jack's Section:
Inspecs (LON:SPEC) - vertically integrated eyewear and lens manufacturer. Recent IPO that has since made a large acquisition, transforming the revenue profile, but margins are low and the company is loss-making, so wider supply chain issues and cost inflation could be a concern.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Foxtons (LON:FOXT)
48p (pre market open) - mkt cap £154m
Foxtons Group plc (LSE: FOXT), London's leading estate agency, today issues its trading update for the nine months ended 30 September 2021.
“Strong performance” in all business areas
Lettings - revenue strongly up on 2020. Also up on 2019, but only because the £7.1m contribution from an acquisition kicked in for 2021. Stripping this out, lettings revenue was actually down 5.2% on 2019, which they don’t draw attention to!
Sales - a strong recovery here, although £4.8m of the increase is due to an acquisition.
Mortgage broking - has also recovered.
.

.
London lettings market - has fully recovered, which really surprised me, but seems really encouraging about life returning back to normal -
As a result of the Covid-19 lockdowns in 2020 and the early part of 2021, the lettings market in London started the third quarter with an excess supply of listings and with rents in the first half of the year down 9% on pre-pandemic levels. This trend has largely reversed during the quarter, with lettings listings now at historically low levels and rents having returned to pre-pandemic levels in August and September.
House sales - good news here too, this is also better than I would have expected at this stage. The worry was that the market would shudder to a halt when the Stamp Duty holiday was phased out, but that does not appear to have happened -
At the end of September, the sales commission pipeline, based on the value of properties 'under offer', was broadly flat with the same point in 2020 and up over 20% on September 2019. This provides confidence that the increase in sales market transactions in London is not just a function of temporary stamp duty relief. Although we don't have full visibility on future market volumes, the pipeline is encouraging and indicates that revenues in Q4 will be ahead of 2019 levels.
Cash sounds healthy at £24.5m, and it’s doing share buybacks.
Outlook - nothing is said today about performance vs market expectations, but I would imagine the scene is probably set for forecast beating 2021 results in due course.
We have good momentum going into the fourth quarter, with rents back to 2019 levels and an under offer sales pipeline that is significantly ahead of 2019 levels."
My opinion - this update strikes me as a lot more positive than I would have imagined, although the acquisition has made a big contribution. There’s clear evidence here of London’s property market returning to normal, especially with rents having risen back to pre-pandemic levels.
Annoyingly, the company declines to tell us how it’s performing against market expectations - that’s so irritating, because that’s the key information trading updates are meant to give us! So simply ignoring that requirement is not good enough.
However, reading between the lines this looks like Foxtons might report ahead of expectations once Q4 is in the bag, possibly?
Are the shares cheap? It’s only forecast to make £3.85m after tax earnings this year, but I’d say a higher number is now looking likely. Plus it has a strong balance sheet. So the £154m market cap doesn’t look extortionate, but not cheap either.
The trouble is, Foxtons was struggling pre-pandemic, and hasn’t made a decent profit since 2016. I’d need more information on how it’s reduced its lease liabilities, as all those central London showrooms must be expensive.
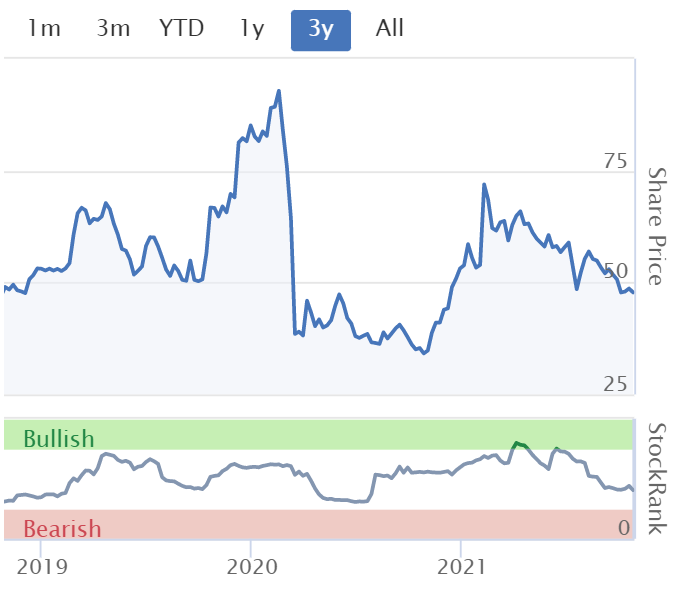
I imagine today’s update is likely to be well-received by the market today (am writing this pre market open). FOXT shares strike me as more of a short term recovery trade, rather than a good long-term holding.
.
.
Various Eateries (LON:VARE)
81.5p (up 6%, at 08:58) - mkt cap £72m
Preamble - this is a bar/restaurant group which floated in Sept 2020, with well-known sector expert management. I think it’s now an established fact that recent (2020-21) floats have generally been over-hyped & over-priced. Hence the more interesting-looking ones go on my watchlist, and I’ll wait for them to come down to more realistic valuations.
So far, so good, in this regard with VARE -

.
Another problem, is that floats are often too early stage, with stellar early growth being extrapolated out, to justify a toppy valuation. Often fuelled by one-off gains during the pandemic. Parsley Box (LON:MEAL) is the obvious example of that. I was worried that Virgin Wines Uk (LON:VINO) might be similar, but today’s results from it look quite good, and I’ll be reporting in more depth on VINO later today.
Both Various Eateries (LON:VARE) and Nightcap (LON:NGHT) seem too early stage to me. They have celebrity management, with a pot of money to go and open some new bars. The trouble is, there’s not enough track record to be able to value the business accurately yet.
The problem for investors is that any newly fitted-out bar, regardless of concept or branding, will attract customers. Why? Because people are paying about 4-5 times supermarket prices for the drinks, and hence are paying for attractive surroundings within the bar, and hopefully good service & food, and a fellow clientele that suits them - smart bars attract smart people.
That all works great from day 1, with a spangly new fit-out so new bars pretty much always trade well to start with. However, over time the fixtures & fittings begin to wear out, not many bars are properly maintained to continue looking new, and gradually the punters drift away to whichever new bar has opened nearby and looks/feels more attractive.
Therefore if we value an expanding bars group on multiples of site profits from brand new sites, we’re probably over-valuing it. It would make more sense to estimate average profitability (lower) over the 5-year life of the fittings.
This was fundamentally the problem with Revolution Bars (LON:RBG) (I hold) a few years ago, which is being fixed under new management (refurbs now resuming, and delivering a good ROI). Old management had a 7-year update cycle for the capex, which was too long - it should have been 5-years, and with better refreshes during that 5 year period too. Hence many of the bars became tatty, and lost some of their customers, with management instead focused on new site expansion. Not good, when you’re heavily operationally geared with a gross margin in the 70%’s - any downturn in sales has a painful drop-through to profitability.
This is why I’m reluctant to pay top dollar for the newness of VARE and NGHT - I’d like to see more of a track record, and see how its sites trade once they’re say 3 or 4 years old. Also, with both companies, their concepts seem nice enough, but not exactly earth-shattering, and can be easily copied by competitors.
Another one is Loungers (LON:LGRS) (I hold), which does look interesting, as they’re widely regarded as best in class operators, and seem to be doing an effective roll-out of new sites. That said, it is too expensive for me to want to expand my existing (tiny) position there.
Having said all of the above, I can understand why plenty of investors don’t like investing in the hospitality sector at all! As well as the companies mentioned above we also have a variety of large pubcos to choose from. The only one that seems properly differentiated to me, is J D Wetherspoon (LON:JDW) - I enjoyed reading its latest results with typically punchy (and sensible) commentary from Tim Martin.
Listening to Rishi Sunak’s Budget yesterday, it does sound as if Tim Martin’s views have made some inroads into the way the Govt thinks. The sector newsletter today, from Propel, commented on this, with industry insiders saying there seems to be a change of tone from the Government from anti-pub (overseeing many closures, mainly due to cost advantages enjoyed by supermarkets), towards a recognition that well-managed pubs can have a positive community role, compared with the alternatives.
This is what VARE says today.
Various Eateries plc, the owner, developer and operator of restaurant, clubhouse and hotel sites in the United Kingdom, announces an update on trading following the end of its financial year, the 53-week period to 3 October 2021.
Coppa Club delivers strong like-for-like sales
Coppa Club is its main all-day bar/restaurant/clubhouse format. It looks very attractive, with obviously expensive fit-outs - I wonder how often those posh settees will need to be re-upholstered?
Sales since re-opening -
The Group's trading performance since the recommencement of trading on 12 April 2021 has been very encouraging.
Like-for-like revenue across the Coppa Club estate was up +21% from full reopening on 17 May through to 3 October 2021 against the same period in 2019 (pre-Covid).
Several Coppa Club sites delivered record sales months.
That’s good, but we know from other operators that there’s good pent-up demand at the moment, which won't last forever.
Also when VARE last reported LFL sales, 17 May - 20 June 2021 the uplift was higher, at 28.3%. That implies that July-Sept must have been below the +21% reported above for the longer period.
Also, VARE doesn’t mention the benefit from temporarily reduced VAT at the moment. This is having a significant benefit to LFL sales. Some other operators have split out this benefit, which I think VARE should have done too, otherwise there’s a risk that the sales uplift is over-stated from commercial reality.
There’s speculation that the reversion of VAT back to normal might be deferred by the Chancellor but I don’t recall the Budget saying anything about this yesterday (although I was having a nap during the first few minutes).
I’m not really interested in VARE’s Italian themed restaurant, Tavolino, which just looks a me-too type of format. I doubt whether that’s likely to make much difference to the long-term outcome of this investment, Coppa Club seems the important bit.
Cash -
The Group's balance sheet is solid with cash at bank of £19.7m as at 3 October 2021.
I’ve checked the last interim results, and what the company fails to disclose today, is that it also has £12.5m in related party loans. So that makes the net cash figure much lower, at £7.2m
I don’t like selective reporting of numbers like this - it’s dishonest by omission - the full picture should be presented, which means disclosing cash, and debt. We like complete transparency here at the SCVR, that's what builds investor trust in management. So VARE achieves a "must try harder" score from me for transparency.
Coppa Club is now operating 12 venues, not many for a £72m market cap company. The 2 most recent openings are said to be trading ahead of budget.
2 more sites are opening fairly soon, with more in the pipeline. So this is very much a roll-out investment.
Outlook comments reflect what we’re hearing from other operators - a good time to be expanding, but with uncertainty & cost pressures. More sites are expected to be available when the rent moratorium ends. Living wage going up 6.6% to £9.50 won't help the sector either.
Valuation - this is the tricky bit! As it’s so early stage, with newly opened sites there’s no track record to value the company on. So it’s largely guesswork. That completely puts me off.
I’ve seen a note from WH Ireland this morning, but it doesn’t seem to have forecasts in it.
Also, what if broker forecasts are wrong?
The market cap of VARE is considerably more than Revolution Bars (LON:RBG) (I hold), but we don't know if VARE is profitable, and if so, how much? Therefore it’s total guesswork at this stage, which is not how I like to invest. The valuation is entirely based on expectations of future profits, as yet unknown.
Whereas with RBG, I can deduce from the last 2 updates that it generated over £8m in free cashflow in just 3 months after full re-opening, and has paid off all its debt, now holding net cash, and is also in expansion mode. It’s got a chequered past, but so what? I’m not buying the past, I’m buying the future.
Therefore, at this stage, I don’t have anywhere near enough information to judge VARE. But paying £72m for a business with only 12 bars & 1 restaurant, and c.£7m in net cash, looks a considerable stretch to me. I'll monitor progress with interest, and as the facts build, then obviously my opinions in future will reflect that.
Have any readers visited Coppa Club sites? If so, do please post your comments.
.
Filtronic (LON:FTC)
11.8p (down 7% at 10:10) - mkt cap £25m
Filtronic plc (AIM: FTC), the designer and manufacturer of products for the aerospace, defence, telecoms infrastructure and critical communications markets is pleased to provide the following update ahead of its Annual General Meeting being held later today at 11.00am.
The Group's trading performance in the opening months of FY2022 is in line with internal forecasts and shows a healthy improvement on the prior year. Therefore, we remain confident of delivering results for the full year in line with market expectations.
It needs a footnote to say what market expectations are, but there isn't one.
In its absence, I had to look up the numbers in Finncap’s update note today - for FY 05/2022 they’ve pencilled in £18.0m revenues, £0.5m adj PBT, and 0.2p adj EPS - very small profits, which leave me wondering why this company (with erratic historic performance) is valued as high as £25m? If it’s only going to deliver £0.5m adj profit, then I would struggle with a valuation of £5m, let alone £25m.
Maybe investors are hoping for out-performance, and future growth?
My opinion - there doesn’t seem to be anything of interest here that I can see.
Why is Filtronic a listed company? I’ve followed it for years, and nothing much seems to happen. Performance goes up for a while, then goes back down again. It seems to depend on the life cycle of its products, and lumpiness of orders. So how are we supposed to value its future prospects? Maybe there's a blockbuster product in the pipeline?
There don’t seem to have been any divis for the last 5 years. I’d rather invest in something that’s a reliable cash cow, making loads of profits & paying it out in divis, e.g. Somero Enterprises Inc (LON:SOM) (I hold). Why would anyone invest in Filtronic, in preference to Somero? I’m completely baffled by that idea! Maybe there’s some (well) hidden depth to Filtronic which has eluded me?
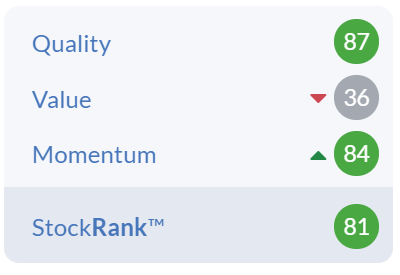
The StockRank is surprisingly high, so perhaps there might be something good here?
.
Virgin Wines Uk (LON:VINO)
194p (up 5%, at 11:32) - mkt cap £108m
This looked quite an interesting float in March 2021, so I’ve been following it with interest - wondering if the strong growth which formed the basis for the float was a pandemic one-off or not? That’s pretty much what happened with Parsley Box (LON:MEAL) so it’s something to be wary about with recent floats. There’s always a risk with every float, that the people who know the business best might be taking advantage of favourable circumstances to part-sell it at an over-valuation, on unsustainably good figures. It happens so often, that no wonder many seasoned investors are highly sceptical about IPOs, with good reason.
As always though, here at the SCVR, it’s the numbers (and outlook) that do the talking, so let’s take a fresh look.
Virgin Wines UK plc (AIM: VINO), one of the UK's largest direct-to-consumer online wine retailers, today announces its audited Annual Results for the year ended 30 June 2021 ("FY21").
Strong growth across all sales channels
Here are my notes -
Revenues £73.6m, up 30% on FY 6/2020 - remember VINO is a beneficiary from lockdowns, as it’s selling wine online, so the prior year comparative would only have had c.3 months pandemic benefit, whereas FY 06/2021 had some level of pandemic benefit throughout. So I think this will have boosted that 30% growth number somewhat.
Q1 in the new year, FY 6/2022 confirms this, with revenue growth slowing to +13.3% - so this is probably a more realistic growth rate to forecast for the future. Any growth is good though, showing that the business seems to be hanging on to the new customers it acquired during the pandemic.
Gross margins quite low, at 31.6%, due to there being a great deal of well-established competition, both physical and online. So it’s not a particularly attractive sector, in my view. Although I would imagine the returns rate on wine is probably very low, and the average transaction value is quite high, both factors which make a lower gross margin more workable. The cash profit on each case is probably quite good, similar to the business model of Gear4music Holdings (LON:G4M) (I hold) - lowish margins, but big basket size, and not many returns. Compare that with fashion, which is a much higher gross margin but a high returns rate destroys a lot of the benefit from that high margin.
Virgin Wines isn’t really doing anything new, they’re just trying to do things well, with a (third party) brand name that has some attractions.
Adj. EBITDA of £7.0m (up from £4.8m LY) looks good, at 9.5%
Reported profits (are much lower and presented badly in the highlights I think, because the £3.5m IPO costs and the pre-IPO finance charges on private equity debt (since repaid) should have been adjusted out - bit of an own goal here in how the numbers are presented.
To demonstrate the point, there’s a table further down which gives a better explanation as to why reported profits are much lower than EBITDA, and it’s unusual costs which don’t apply going forwards, so can legitimately be adjusted out -

.
The way I look at profit, I’m trying to work out what the true underlying profit is, with the new listed company structure & debt, and ignoring any one-offs like IPO costs.
So I’m happy to start with the £7.0m EBITDA then deduct £0.9m amortisation & depreciation (the amortisation relates to capitalised development spend, so should not be ignored).
That arrives at £6.1m adjusted profit before tax, which is a respectable figure.
Personally I’m now factoring in higher future corporation tax at 25%, which it will be rising to, hence I get to my workings of Profit After Tax (earnings) of c.£4.6m - that compares with a market cap of £108m, so a FY 06/2021 adjusted (by me) PER of 23.5 times - not unreasonable for a growth company.
Supply chain - the company makes reassuring noises on this big current issue, and says t brought in stock early for the Christmas trading peak. I wonder if VINO might benefit from people ordering their Xmas stashed of booze earlier, due to worries about perceived shortages?
Balance sheet - looks fine to me. Remember some of the gross cash is the “wine club” funds belonging to customers. So there will be a corresponding creditor to reflect that.
My opinion - I was half-expecting to find some holes in these numbers & outlook, but to be fair, it all looks pretty robust to me. The valuation’s a little warm for my personal tastes, given that growth has now slowed down to 13%, and there’s always going to be customer churn, thus requiring continuous marketing & special offer costs to attract new customers.
As you might expect, I’ve tried out the service myself, and it’s pretty good. The wines were OK, nothing special if I’m honest. Also, it didn’t take me long to realise that the supposed savings from the wine club “interest” are giving with one hand, and taking from the other. I think that there’s probably better overall value sniffing around the supermarket websites, looking for special offers on wines you particularly like, if you can be bothered.
Wine is heavy to buy, so there’s a lot to be said for ordering online and having it delivered. But you can do that from Waitrose, Tesco wherever. Is VINO doing enough to make them a compelling place to buy your wine from? No, I don’t think so. Probably the only truly different player in this sector is Naked Wines (LON:WINE) but I’ve never liked the numbers or valuation there.
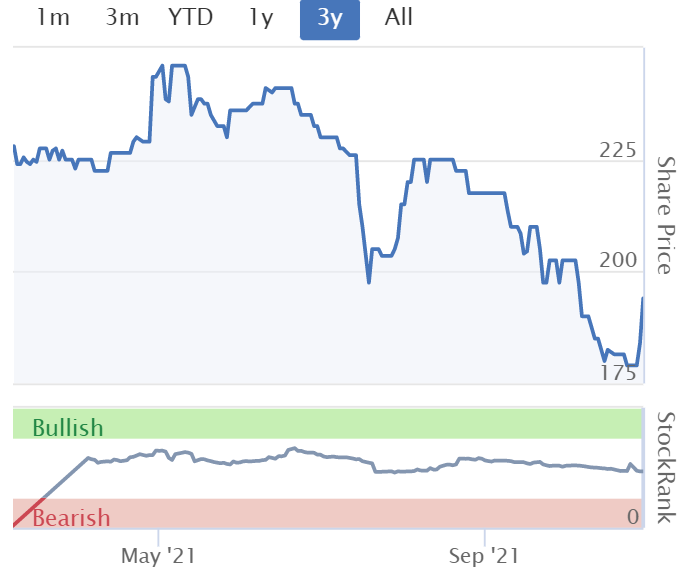
Overall, VINO looks a reasonable share to hold, I’m certainly not negative on it, and these numbers are pretty good. I just don’t see enough growth, or an attractive enough valuation, to motivate me to buy this share at the moment, when there are better bargains around from recent small cap sell-offs.
Results webinar - is today at 16:30 on InvestorMeetCompany. Should be interesting, management come across well I think, on previous presentations. They seem grounded & are hands-on entrepreneurs, which is my preference (not plummy-voiced financial engineers in fancy suits!)
.
Jack’s section
Inspecs (LON:SPEC)
Share price: 389.8p (-0.05%)
Shares in issue: 101,290,898
Market cap: £394.8m
Inspecs is a recent IPO that has done rather well, with the share price nearly doubling from 195p to 389.8p over the past 18 months.

The company has built up a vertically-integrated eyewear frame and lens platform, which manufactures products in house for supply to a global network of retailers and brands. It sounds interesting but the concern I have is over pricing power and margins.
Is the manufacture of frames and lenses really where the value is here? It would have to be with the brands, you would think. Margins have been fairly choppy despite annual revenue in the tens (and now) hundreds of millions.

So it’s possibly a more commodity-like market where economies of scale, low costs, and vertical integration are key to outlasting competition.
Essilorluxottica is worth some £63bn though, with operating margins of around 12%, so perhaps this is too harsh a view. There must be some kind of competitive advantage to be gained in this business. Perhaps through a mix of scale, low cost base, and established retail and brand partnerships.
Revenue for Inspecs has jumped recently - clearly a significant acquisition (Eschenbach) - signalling ambition. The important point is whether revenue growth can translate into sustainable value creation for shareholders.

Shares in issue have increased from 71m in 2017 to 101.3m today, while net debt has also risen from about £4m in 2016 to £35.7m. Not necessarily bad things in isolation, but it does show that growth so far is not being organically funded, which is worth bearing in mind.
The group's strong trading performance delivered in the first half has continued into the third quarter with unaudited revenues for the nine months to 30 September 2021 of $185.0m (six months to 30 June 2021: $125.7m). The Board remains cautious of headwinds in the fourth quarter as COVID-19 continues to impact the global supply chain, but the group remains confident in its full year outlook and notes the 2022 order book is in line with management's expectations.
Conclusion
I thought that was the headline comment of a longer piece, but the above is actually the entire update. I suppose many companies don’t even report a Q3 update but there’s still obviously not much to go on here.
Reverting back to the interims from the 8th of September, the group reported revenue up from $16.7m to $125.7m, a gross margin of 44.9%, underlying EBITDA of $17.7m, and a reported loss before tax of $2.6m.
It’s hard to build a vertically integrated, multinational business but Inspecs looks to be doing that. It is not yet profitable but I suspect reaching a certain scale is key here. If it can achieve that, then it could do well. I haven’t looked at it properly since May 2020, when the share price was around 190p. Since then the significant Eschenbach acquisition has fundamentally changed the proposition, resulting in a larger business with more shares in issue.
From the interim results:
We continue to work on further acquisitions with our advisors, as the enlarged Group now has many additional opportunities available to it.
The group needs to scale up and realise some margin gains. It looks more cash generative now, with net operating cash flow of $15.4m compared to -$2.5m. It could continue to scale and reach sustainable profitability, but today’s environment of rising costs and logistical issues means the short term risks have increased, so that’s enough to keep me neutral here for now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Virgin Wines Uk (LON:VINO)
I don't hold this one, but I did think about opening a position.
Some thoughts:
1 - Older Cohorts (+ve)
Pre-FY18 Cohort revenues are fantastic, with £32m-£34m of revenue each year for the last 3 years:
I imagine marketing here is minimal - perhaps the occasional discount/promo - so presumably these cohorts are quite profitable - and recurring - for the company.
I've made an assumption on fulfilment costs from the IPO Admission document (37% from FY20) , and in my opinion the pre-FY18 cohorts alone justify the current market cap:
2 - Payback Remains Very High (+ve)
3 - Recurring Revenue (-ve)
There seems to be a slowdown in Active Subscription Customers from H1 to H2, in addition to a rise in non-subscription customers.
4 - Geography (-ve)
My main reason not to buy would be the focus on the UK market only.
The company states that they already have 10% of the £750m market (wine bottles >£6), which I can't imagine is growing very fast and is likely subject to intense and/or growing competition.
This makes me question where the growth is going to come from, which leads me too...
5 - New segments (+ve)
Beer/spirit services were recently started and I must admit to being impressed by the growth here (albeit from a small base.)
Perhaps the opportunity might not be so great, but at the very least it dispelled my preconception that there were few avenues for growth.
---
I started writing this with the intention that I would not buy, but I think that I might have convinced myself otherwise.
The company has a very strong underlying recurring revenue, which alone supports the share price, alongside a market that will grow, with potential to move into other segments.
Given the decent levels of cash generation and lack of debt I also think international expansion is probably (or rather hopefully) just a matter of time.
I think that they are too far behind to catch up with Naked Wines in the States, who have a very impressive US logistical infrastructure already, but I imagine that there's still some room for smaller companies like Virgin Wines Uk (LON:VINO).
I think a purchase here might not be a bad idea.
A
Ahh, React (LON:REAT) -> yet another share I’ve been accused of being too negative on in the past ;)
The React short term letdown has been telegraphed for a while...I’m surprised there’s surprise. But today’s TU is further let down. 10% fall in sp is not a big deal...I wonder if people have dug into the announcement well? I think the price response is undercooked and we'll see more fall/drift. This could go under 1.5p imo (not a forecast) due to earnings/cash concerns. Some issues of concern:
Today's TU release infers some significant negative inflexions in trading for the core React ex Fidelis cleaning business. The issue is whether it is structural or short term. There isn't evidence to support short term blip hypothesis at the minute (given early stage turnaround and benefit of covid to reactive work) so the price pressure is likely to persist. Some significant insider or big holder signalling is probably the sign that future is more assured (note the only signal in H2 was NED selling >1/3rd of holding at 3.4p in May!).
Half on half fall in EBITDA (H1 £420k vs H2 £330k) despite both organic revenue growth and acquisition of profit/cf positive and growing Fidelis for all of H2 indicates that gross margins have been hit hard in H2 2021...TU could do with contextualising that rather than leaving it hanging. It looks like it all comes out of the React side of business and not Fidelis who are reaching for earnouts on EBITDA targets for their year to March 2022…
There’s a contingent payment to Fidelis of up to £3.05m if they hit £1m EBITDA for their year to end of March 2021 (note this is the old annual accounting period for Fidelis as independent).
Only the annual report will tell us exactly how much H2 2021 was a damp squib for React ex Fidelis. The comparison is approx £2.25m revenues for H2 2020. H1 2021 saw 20% YoY growth and the total inc Fidelis is 20% organic YoY for 2021. As Fidelis is reported as particularly strong it implies that React ex Fidelis is not holding up its side of 20%. 20% organic on 2020 is £872k extra revenue.
Note, its possible that the meaningful reduction in expected EBITDA (from £850k to £750k) despite revenue being just slightly below expectation could relate to the accounting treatment for contingent liabilities connected to earnout payments to Fidelis. If they are overshooting their target then balance sheet recorded contingency of £2.1m moves closer to the £3.05m max. Any recognition of that in period would come through profits. In addition, this might also partly explain why the cash performance is poor (Allenby now expect £567k year end cash rather than £896k, ie £329k reduction) as depending on the schedule for payment of the expected £2.1m further consideration (but up to £3.05m if very good performance) then extra cash than expected might have gone out the door to Fidelis management. The cash plus EBITDA shortfall on half is c.£430k and that is roughly half the increase that would be seen in contingent payout to Fidelis for exceptional performance. Its an analytical faux pas to conflate all these items perfectly...but I believe there is likely strong hints in this. Good or bad then?...
Well, React ex Fidelis underperforming and Fidelis compensating for its is a nice steady state balance. However, Fidelis outperforming draws on more cash from the group to pay out Fidelis. That’s not so good as a draw on cash resources (and remember Fidelis owners specifically want to paid cash to ‘realise wealth from their work over 10 years’ and don’t want equity) to pay Fidelis sucks out cash for investment to grow. React ex Fidelis needs to put in good cash generative performance to pay for Fidelis and investments to grow broad biz. There’s hints of capital raise to come in this...unless React ex Fidelis turns around sharpish.
React are also paying the price of too much hype too quick. Mgt talked up the biz a lot late last and early this year. This now looks like simply a desire to trigger full options/warrants payout at (I think) c.2.8p ...job done, free holding banked...so now PIs got to suffer the reverse disillusion effect. And…
...given just how loquaciously keen React were to talk to market before now on many matters its a shame they haven’t been able to be ‘open and honest’ on their current situation and have us holding off until January in the hope of game changing luck.
Your mojo, out
(There’s quite a lot of info to parse with React and haven’t done it yet and above done quickly...I’ll notify of any changes)
React (LON:REAT)
Correction: There’s a contingent payment to Fidelis of up to £3.05m if they hit £1m EBITDA for their year to end of March 2022 (not 2021) (note this is the old annual accounting period for Fidelis as independent).
Yes Paul, when I watched React (LON:REAT) present at Mello my opinion was that the share price was being ramped. My perception is that REAT is a low margin cleaning company.
I don't Hold.
Re £VINO
There is a phrase "if you ask a stupid question, you will sound stupid once, if you don't ask the question you will always be stupid", so here goes.
Does Virgin Wines have any connection with Richard Branson's group of companies, and if so, what? Or is it just a similar name?
Going on all the other "Virgin" branded products, typically they pay him a fee for using the name...
Interactive investor mobile 6 digit security number.
Had problems yesterday regarding above,apparently if you have Virgin mobile. Solution was to temporally remove 6 digit security when logging in.
Could it be your phone signal, I often don't get texts on my phone, even with 4 bars on signal strength. I have real concerns about using my accounts, when I go travelling with these security numbers sent to your phone.
I'm not a customer of ii although I do like to read their articles. This whole idea of using phone numbers for 2 factor authentication is something I really don't like. I begrudge giving out my private phone number, as is my right under data protection laws and trying to reduce the number of scam calls and texts I receive. If I know an organisation doesn't have my number I know any impersonated contact from them is not real. For example I don't have an account with Lloyds so if I get a spam text looking like it is from them I can ignore it.
I've had my mobile number for >23 years and up until about 4 years ago never received any spam/scam contacts. Then I was involved in a car accident and my insurer asked for my mobile number so they could discuss the situation during the day and have lawyers involved. I agreed and ever since have been targeted by frauds. Coincidence?
I'm not saying it is a breach of trust by these companies but for fraudsters the most valuable things they want is data. No matter how secure a company is they can be subject to a data breach, anyone remember the NHS a few years ago, FBI, Sony etc etc. Every organisation is vulnerable to just one mistake by an employee clicking a phishing e-mail, rogue employee and so on.
My reluctance to share my data also impacts my future custom with a company. For decades I've been a customer with Nationwide, yet a year ago they brought in a change where they wanted a mobile number to allow me to perform online activity. I haven't given it to them so they have lost transaction activity from me for the last year, unless I go into a branch or make an in person credit card transaction.
I work in financial controls and have a strong value on security. My argument is that these organisations can provide 2 factor authentication via e-mail, yet many of them flat out refuse to do so. These organisations need to wake up and realise:
- not everyone has a mobile phone
- people change their phone numbers and it is a hassle to try to remember all the organisations to tell of this change
- people have weak or no mobile signal at times (like a commentator on here)
- people don't always have their phones with them. I certainly don't. Pre pandemic I travelled a lot internationally and I was not going to be paying extortionate roaming charges for the numerous times I travel and visit many countries for work
- some people are like me and strictly desire to protect their privacy. I've never (that I know of) been a victim of fraud in my life and by controlling who has my data reduces that risk
Sorry for the rant but organisations keep changing the rules and just assuming people have a mobile phone number and are not flexible enough to cater for those who do not, or for valid reasons don't want to share the number with numerous organisations. 2 factor authentication is great but it can be done with e-mail codes etc.
I know Robbie Burns often talks of how he doesn't have a mobile phone. In this day and age I don't know how he manages.
Sorry for going off topic but this is something I (clearly) feel strongly about.
Yes I agree with most of that. The issue also is now using credit cards online, they may need a phone verification. However when I travel abroad I either don't have a mobile or I may use a local sim card. I have been locked out of accounts for not having the correct phone number, it can be a major hassle sorting it out. I understand about security but some banks are not very good at a simply reset, I spent about 3 hours recently sorting access to one account. HL have this verification as well, I had a problem because my landline was not working for a few days, then recently my mobile was off for 1 week because my phone changed companies and I had to get a new SIM and then wait until they change over. Some companies only accept mobiles not landlines. Mobile reception around here is not great.
I believe this is an EU ruling.
I believe this is an EU ruling.
It is for online electronic payments and access to bank accounts but not for anything else. It was adopted into UK law and that's not likely to change, for good reasons. It's not a requirement for other services, like brokers.
As a general statement two factor authentication using a mobile phone as the second factor is a good thing as it makes account takeover very hard. Using an email address / password as the second factor means that you'd be using two knowledge factors (password for online account and password for email account) which exposes you to a number of relatively simple attacks. It's also not allowed for payments, although many banks are breaking this rule.
The best option is to use a properly designed and tested mobile app. Done well that's more secure than an SMS, and only requires wifi, not a mobile signal.
As always this comes down to a balance between ease of access and security. Personally I wouldn't use any service backing significant amounts of value that doesn't require strong two factor authentication. The minor inconvenience of the second factor is vastly outweighed by the risk of losing a significant amount of money.
Having said all of the above many companies have terrible support for situations where phones are lost, changed or stolen or where people have limited access to mobile networks.
timarr
At home it is not usually a problem as long as the phone is working but if I'm travelling it could be a major issue, not just trading stocks and shares but also doing credit card bookings. I agree some platforms the service is not all good. Of course most don't also have free phonelines now, so it can get expensive as well as time consuming. HL you get logged out every minutes, unless you are actively using the site, I even get logged out even when I am using it. Looking at IG the App has bad reviews, many warning not to use otherwise can't access their accounts. Not everything is supported only iPhone, iPad, or Android device.
I did not have a mobile for 1 week.
At home it is not usually a problem as long as the phone is working but if I'm travelling it could be a major issue, not just trading stocks and shares but also doing credit card bookings.
Hi Ray
Most High Street banks or credit card companies should offer an alternative to SMS although you may have to chase to find this out. There's still quite a large cohort of mainly elderly people who don't have mobile phones, and they also need to cater for people who are visually impaired. Lloyds, HSBC, etc are obliged to offer non-mobile based second factors. Smaller payment institutions may not.
For brokers and other non-payment companies the decision to require 2-factor authentication is a service issue - but frankly, if they don't offer an alternative they should expect to lose customers. Personally I wouldn't use a broker that didn't offer 2FA, there's too much at risk.
On a mildly amusing note John Authers ended his newsletter today by describing how he clicked on a phishing link while distracted. Fortunately for him it was an internal test, but it's easily done and that's all it takes to expose yourself to account takeover. 2FA makes that more difficult - not impossible, but most attackers will go somewhere else.
timarr
Ray,
You can edit your timeout preferences on the HL platform. Go to Your Account > Passwords and Timeout Preference.
I looked at that, it says not possible to change from 5 minutes.
With Nationwide (which you cite), you have the option of either text message with auth code or home card reader device. So no need to use your phone if you don't want to as long as you have their (free) card reader.
Thanks for the information ISAallowance. When I had a discussion with Nationwide last week about this issue they made no mention to me about a card reader as an alternative. I was just flat out told that I needed to provide a mobile phone number. Nationwide said they would escalate my query/complaint but I've had no reply as of yet.
For info I have a credit card with them and a savings book account. I don't have a bank account as such with them. Not sure if that matters? (It was never asked for when I discussed the issue with them last week.)
For info I have a credit card with them and a savings book account. I don't have a bank account as such with them. Not sure if that matters?
It's required by law on any payment account. That definitely covers a credit card. It's arguable on the savings account.
A One Time Password generated using a card reader would be a perfectly acceptable second factor.
timarr
ISAallowance, I thought you might appreciate an update. I received a letter today from Nationwide that apologised for them incorrectly informing me on the online chat. The letter confirmed that I can set up for online banking with a card reader device. I've begun the registration process online and hopefully will be set up within a week or two.
Thanks for your informed detail, you know more than the rep I spoke to the other week.
I completely agree with everything you have said.
I agree with your comments on accessing a ii a/c - probably implemented by someone in the younger generation that have phones surgically attached. Most other organisations provide an alternative - usually either email or landline phone where you use the keypad to relay back a number displayed on your screen - alternatively you have a device like the one mentioned by ISAallowance (I have one from HSBC).
So if others can do that why can't ii? (or, come to that, the Yorkshire and Principality Building Socs.?).
"Of course most don't also have free phonelines now, so it can get expensive as well as time consuming".
Hi Ray,
Have you tried using the website:
www.SayNoTo0870.com (all one word)
I use it all the time and I've used it for donkeys years to lookup freephone 0800 numbers or 0300 numbers or 01 or 02 landline numbers. Just enter, either the company name or enter the expensive premium rate number to find an alternative free or local call rate number. As you probably know if you have a mobile contract with inclusive minutes then 03, 02 & 01 numbers are free and part of your inclusive minutes.
David.
yes I have used that site but a lot of 0800 numbers have gone recently. I only have PAYG mobile.
I too only have PAYG mobile but that could change. Being retired I don't make many daytime calls so for a long while I have had an evenings and weekend package on my landline. A few years ago there was a tipping point when daytime calls became cheaper on the mobile than the landline so such calls (in my case usually emergency calls to the dentist!) are now made by mobile. I now have received an offer of anytime unlimited calls and texts on my mobile that is approaching the evenings and weekends landline package cost so another tipping point is coming.
Regarding Inspecs (LON:SPEC) - I’ve owned global eyewear behemoth EssilorLuxotica (Big Spec!) for some time now and this is a business with powerful demographic drivers and truly formidable vertical integration (lens, frames, brands, retail). The two seem to be valued fairly closely with some similarities in their operating numbers and growth forecasts. Consequently the valuation of Inspecs is neither in value territory nor egregious.
Before anyone takes a risk on the plucky newcomer, I’d encourage them to investigate the phenomenal market power exerted by the almost monopolistic EL. It’s the closest thing to an Apple of consumer healthcare wearables. EL could alternatively crush Inspecs or buy it - so you’d have to be convinced that Inspecs can compete hard enough to survive the first option and grow fast enough to encourage the latter. Otherwise, just buy EL and stick it in the coffee can next to Microsoft.
Always a difficult one when you currently hold - as I do. So appreciate all these factors. - but suggest there is room for a tiny bit of competition - shareholder list does offer comfort - good holding from Directors and from Fund managers. If they get bought out - so be it!
Don’t worry, I wasn’t suggesting there’s no room for competition. Simply that if the big’un and the littl’un have similar growth prospects and valuation, then I’d feel more secure owning the proven quantity. Risk vs reward and all that. But EL possibly performs a different role in my portfolio (defensive growth) than Inspecs (LON:SPEC) (small cap growth?) plays in yours. Noting the execution risk with the inevitable M&A-driven expansion, Inspecs looks interesting - there are terrific drivers for multi-decade sector growth.
Anybody else having trouble receiving the security number text this morning, to allow login to interactive investor? Or is it just Me?
I have had no problem
Just tried again and still no problem
II security texts can sometimes be slow. And I once discovered I had no mobile signal (was working happily on wifi) and the message didn't arrive.
me too
Ouch! The market is hammering React (LON:REAT) this morning [I hold], having missed forecasts.
Investegate |React Group PLC Announcements | React Group PLC: Trading update
I view the trading update as disappointing but not disastrous. The business is still materially growing revenue, profits and cash, albeit by less than previously indicated. Continued growth in all of these areas is still a reasonable expectation.
Allenby Capital research is freely available on-line. They have 2021 EPS of .12, putting React (LON:REAT) on a PE ratio of x16.5. This historical ratio includes just a half-year contribution from the acquisition of Fidelis, so will reduce materially with a full-year contribution in 2021/22, never mind any additional underlying growth achieved.
LON:REAT (I Hold) I'm sitting on a paper loss of 22% as of this morning. I plan to keep on holding as I really like the ambition; the approach to grow the company to a size that can win larger contracts from FTSE 100 / 250 firms. FTSE firms tend to prefer to contract out cleaning, but find they end up having to manage a large amount of suppliers, due to not having any bigger players in the market. Reacts aim to to fill this gap, provide a quality service and also tackle the harder jobs that require specialist qualification.
Until recently I held two micro caps in React (LON:REAT) and Kinovo (LON:KINO) but I've sold both of them at about break even. Both seem well run businesses. But both have a significant proportion of their work tied up in what must be competitively priced contracts, and both seem susceptible to recruitment/retention and wage inflation issues in the current environment. They've gone back on the watch list, but I just decided that in a tricky market, shares like these don't hit the right risk/reward balance at the moment.
Hi Paul,
I read recently regards Foxtons (LON:FOXT) that the new chairman bought approx £150k worth of shares on appointment which is a positive sign.
As you say though they have a hugely expensive estate to service, but I would hope that the new Chairman who has experience of property sales/lettings business will start to refocus their strategy and begin to make a difference. I don't hold.
Somewhat embarrassing announcement from Ince (LON:INCE) that they’ve had to suspend their shares from trading this morning as their nominated advisor, Arden Partners, has felt impelled to resign as NA following yesterday’s announcement of a proposed all share takeover/merger of the two businesses. You might think with all those lawyers and brokers on the case someone might have figured out the potential for this ahead of time and arranged a replacement?
https://www.investegate.co.uk/....
Gus.
It is mornings like these when you realise you’ve been spoilt in the past with rambling.