Small Cap Value Report (Thu 28 Sept 2023) - SUP, CHRT, OPTI, ZOO, ABDP, XPF, 888, RWI, INL

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.

Summaries
Supreme (LON:SUP) - 107p (£127m) - AGM Trading Statement - Paul - AMBER
Excellent news here recently, with trading "significantly ahead of market expectations". Upwardly revised broker forecast means that the PER is now only 7.0x - is that cheap enough to tempt you, given the well-known issues over vaping products?
Cohort (LON:CHRT) (Paul holds) - up 1% to 504p y’day (£209m) - AGM Statement & Q1 Update - Paul - GREEN
A reassuring Q1 update, trading in line with expectations. The big order book provides excellent visibility, so I think very low risk of a profit warning. Shares seem really good value to me. Sound finances too, with net cash.
OptiBiotix Health (LON:OPTI) - up 4% to 27.5p (£24m) - Interim Results - Paul - RED
Always jam tomorrow from this stale story stock. Negligible turnover, and continuing losses. Cash position looks tight, although it does own shares in Skinbiotherapeutics (LON:SBTX) which it can use to raise cash, if there is a bid in the market in size, which can't be guaranteed in markets like this. When will the company actually deliver some commercial success?
Zoo Digital (LON:ZOO) - down 34% to 34.5p (£34m) - AGM Trading Update - Paul - AMBER
Oh dear, it's another nasty profit warning. Continued impact from the Hollywood strikes, and customers retrenching, means revenues have crashed, and a hefty loss of $(13.8)m PBT is now forecast for FY 3/2024. Deep cost-cutting is being implemented in H2. I discuss the bull & bear points below.
Ab Dynamics (LON:ABDP) - up 2% to 1668p (£383m) - Pre-Close Trading Update (ahead) - Graham - AMBER
An excellent update from this vehicle testing and simulation group that now also supplies retrofit solutions to make existing vehicles driverless. Revenues to exceed £100m and operating profit to exceed prior expectations. Looks fully priced but can it prove me wrong?
XP Factory (LON:XPF) (Paul holds) up 2% to 16.5p y’day (£29m) - Interim Results - Paul - GREEN
I have a good rummage through the interim results published yesterday. Very rapid growth, due to a large number of new sites being opened in H2 2022. Adjusted profit, but statutory loss, so I go to the cashflow statement for clarity - which shows a nicely cash generative business, spending that cash on new site openings. Not the best balance sheet. Overall, I think this is a nice entry point for an ambitious, growth business in an expanding niche of experiential leisure. It's work-in-progress, so don't make the mistake of trying to analyse this like a mature business.
888 Holdings (LON:888) - down 16% to 92.8p (£416m) - Update on current trading (profit warning) - Graham (holds the stock) - AMBER
This profit warning is due to weaker Q3 revenues than expected. Compliance costs and gambling safety initiatives, combined with customer-friendly sports results, are all mentioned in the explanation. These shares are unfortunately call options on a mountain of debt.
Renewi (LON:RWI) - up 33% to 677p - possible bid at 775p (£543m) - Paul - COLOUR
Thanks to our takeover king here, BnB, who flagged this announcement in the reader comments below. Macquarie has issued a statement saying it approached RWI management with a possible cash takeover at 775p, but was rebuffed. So it's clearly now decided to go public, over the heads of RWI management, and explains why it thinks this is a full and fair offer for the company, at c.50% premium. RWI is on a low PER, but it has a lot of debt. Could be a nice trade here - with the share price 100p below the indicative proposal. Well done to holders of Renewi! Yet another example of how private markets are valuing many companies more than public markets.
Inland Homes (LON:INL) - shares suspended - Intention to appoint administrators - Paul
A sorry end to this hopelessly badly managed land/property developer. We've never rated management here, after seeing how peculiarly arrogant and defensive the CEO was at an AGM years ago that I attended. It somehow managed to completely destroy shareholder value, during a multi-year boom in the residential property sector. Also more recently, it was investigated for dodgy dealings. Anyway, good riddance to bad rubbish, I'm glad we won't have to report on this awful company again - it's announced intention to appoint administrators, so that means the equity is almost certainly a total loss now. I hope no members here got caught on this one.
Supreme (LON:SUP)
107p (£127m) - AGM Trading Statement - Paul - AMBER
Supreme (AIM:SUP), a leading manufacturer, supplier, and brand owner of fast-moving consumer products, provides an update ahead of its Annual General Meeting…
Excellent news for shareholders -
Trading for FY 2024 now expected to be significantly ahead of market expectations1
1 Company compiled analyst consensus for the year ending 31 March 2024 prior to release of this announcement was Adjusted EBITDA of £25.6 million.
2 Adjusted EBITDA means operating profit before depreciation, amortisation, share-based payments charge, fair value movements on non-hedge accounted derivatives and exceptional items.
What a pity they follow the fashion for reporting adj EBITDA as if it was real profit, which it isn’t of course. I’ve yet to meet any investor, or fund manager, that actually wants companies to report adj EBITDA as the main profit metric! So why on earth do companies keep doing this? It’s because they’re being badly advised, by brokers/analysts/PRs.
Updated forecasts - from ED, show £29.0m adj EBITDA, and £22.6m adj PBT for FY 3/2024.
This is adj EPS of 15.3p, giving a PER of 7.0x - cheap, but that’s because of investor unease/distaste for vaping.
Paul’s opinion - on a PER of 7.0x, there’s no doubt that this share is now factoring in a substantial discount, due to the controversy over its vaping products.
It’s entirely your call how you view that issue.
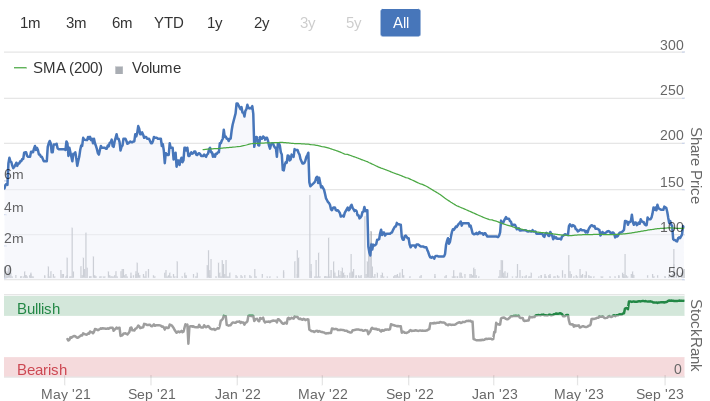
Cohort (LON:CHRT) (Paul holds)
Up 1% to 504p y’day (£209m) - AGM Statement & Q1 Update - Paul - GREEN
Cohort, the AIM listed independent technology group…
This is 6 largely independent, defence-related businesses, under common ownership and control. I’ve been impressed with the group’s long-term track record, reasonable valuation, sound finances, and great visibility from a large order book.
Nothing much to see here -
Overall, we have had an encouraging start to the 2023/24 financial year and our expectations for the full year remain unchanged.
Strong order book & hence high visibility -
Following contract wins since the start of the financial year of over £90m, the order book on 22 September 2023 stood at £370m, representing consensus revenue cover for the current financial year of 93%.
As the year is FY 4/2023, I would say that having 93% revenue visibility when we’re only about half way through the year, seems impressive.
Net cash of £15.2m is little changed from FY 4/2023 year end. The balance sheet is strong at Cohort, it’s well funded.
Some cash is to be deployed on capex -
As a result of planned capital expenditure and expansion in working capital, we anticipate our net cash balance will decrease, but that we will maintain positive net funds at the year end.
Paul’s opinion - no change, I see this as a quality business, at a reasonable price, hence why I hold personally.
Latest forecasts are for about 36p EPS this year and next, so at 502p that’s a PER of 13.9x, which doesn’t seem demanding at all, for a nice quality business.
Hence a thumbs up from me.
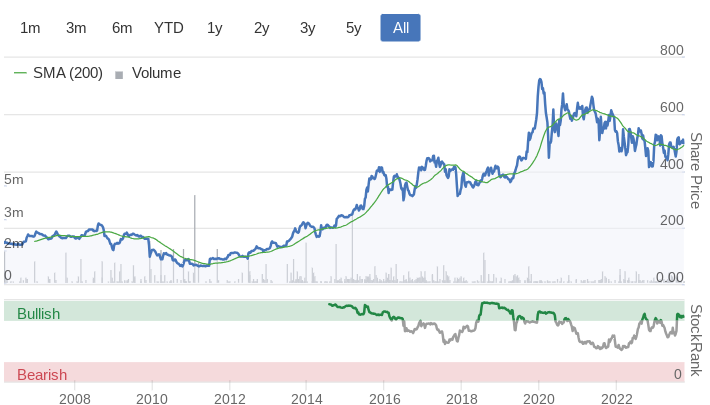
OptiBiotix Health (LON:OPTI)
Up 4% to 27.5p (£24m) - Interim Results - Paul - RED
OptiBiotix Health plc (AIM: OPTI), a life sciences business developing compounds to tackle obesity, cardiovascular disease, diabetes and skincare, announces its unaudited results for the six months ended 30 June 2023.
Shares have been on a tear since July 2023, on a series of announcements that promised jam tomorrow, but little of any substance, in my opinion.
Today’s H1 results are lamentable. It describes H1 as “strong” despite only achieving £351k in revenues!
The operating loss is £(760)k in H1, and I suspect the small cash pile of £893k may not be sufficient.
By my calculations, revenues would have to increase 6x to just reach breakeven (and that’s assuming no increase in overheads).
The receivables balance of £666k on the balance sheet is nearly double all of H1’s revenues - which suggests that customers don’t seem to be paying their invoices - so are those revenues genuine, given that the customers have not paid up?
Note that OPTI does have an investment in its spin-off, jam tomorrow loss-maker Skinbiotherapeutics (LON:SBTX) which amazingly is valued at £37m currently, goodness knows why, its figures are also hopeless. OPTI’s 15.7% holding in SBTX has a mark to market value of £5.8m. This means OPTI could possibly fund its own cash burn from disposing of some or all of its SBTX holding, but it would have to find a buyer first - which may not be possible in size.
Paul’s opinion - yet again, reported numbers from OPTI show no sign of a viable business. Yet the commentary serves up lashings of jam tomorrow.
I recall receiving an abusive email from the CEO of OPTI a few years ago, something which has never happened before, where he described my commentary here as “lies”. Since the company has produced nothing of commercial value since then, my comments were clearly the truth.
Who knows what the future holds, maybe OPTI might eventually achieve some meaningful sales for its food additives? Looking back at its history, OPTI seemed to take over a cash shell called Ducat Ventures in late 2013, which had previously been Ceres Media. Adam Reynolds seems to have been involved.
Here we are almost 10 years later, and OPTI has still not produced any meaningful revenues, let alone profits. It looks a very stale story to me.
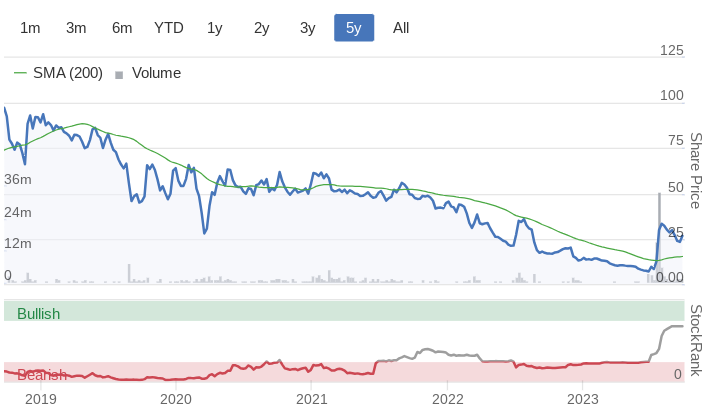
Zoo Digital (LON:ZOO)
Down 34% to 34.5p (£34m) - AGM Trading Update - Paul - AMBER
More bad news here unfortunately.
Checking the recent history, in previous SCVRs we said -
14 July 2023 - AMBER/RED - down 37% to 66p - misleading update, big profit warning slipped out via broker update. Plenty of cash.
11 August 2023 - AMBER - 64p - good results FY 3/2023, but poor outlook. Could shares bounce once Hollywood strikes over?
ZOO Digital Group plc (AIM: ZOO), a leading provider of end-to-end cloud-based localisation and media services to the global entertainment industry…
So this is things like dubbing, and subtitling of films, which has enjoyed a boom recently due to expansion of streaming services (now over?)
Today’s news is that it’s revising down guidance again for FY 3/2024, due to the ongoing strikes (hopefully nearing a resolution), and customers cutting back to focus on profitability -
"Whilst orders are being processed monthly, they have been and continue to be at historically low levels such that H1 revenues are expected to be approximately $21 million, leading to a significant EBITDA loss for the first half of the current financial year
Singers is now forecasting revenues of $44m for FY 3/2024 (down from $85m old forecast!), and a thumping great $13.8m loss for the year.
Cost-cutting is being done, aiming to reach breakeven in Q4 (Jan-Mar 2024).
Japanese acquisition - terms have been renegotiated (no details) and competition deferred.
Industry retrenchment - ZOO reckons this will work in its favour, with customers using fewer suppliers.
However, the Company is in a strong financial position with net cash at 30 September 2023 expected to be no less than $16 million.
Singers forecasts this will reduce to $8m net cash by FY 3/2024 year-end. It’s not clear if that is after completing the Japanese acquisition or not?
Paul’s opinion - this is a tricky one. Shares have already crashed in value, so at some point the market might look beyond the Hollywood strikes, and factor in improving business, maybe even a backlog for ZOO? I could see that potentially triggering a rebound in the share price.
On the downside, there seems very little visibility. Historically, over many years, ZOO failed to generate any profitability. It then produced a one-off spectacular profit for FY 3/2023, but on the balance of probabilities I reckon that’s unlikely to be repeated any time soon, maybe ever.
Investors also have to think about the potential threat from AI. The company has said that computers can’t match the subtlety & nuances of human dubbing, but AI is improving so rapidly, and I’ve heard text to speech models that are now astonishingly lifelike, that I don’t think ZOO should be complacent about AI.
Single customer risk is another worry, with the biggest customer (rumoured to be Disney, I think?) accounting for most of the revenues in its bumper FY 3/2023 results.
ZOO was lucky in that it raised cash in a placing just before a nasty profit warning, and sensibly deferred its planned acquisition in Japan. This has provided it (more through luck than judgement I’d say) with a nice cash buffer to ride out this lean patch. So it doesn’t look as if solvency is an issue for the time being anyway.
Overall, I can’t decide, there are bull and bear points, and I could be tempted to have a little punt here, given that the market cap has fallen to only £34m. Is it a good business though? Not really.
A calamitous year for shareholders so far -
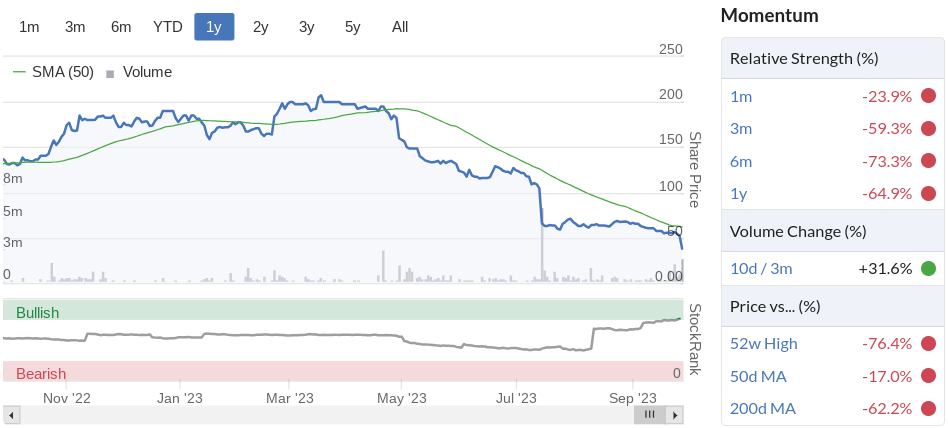
XP Factory (LON:XPF) (Paul holds)
Up 2% to 16.5p y’day (£29m) - Interim Results - Paul - GREEN
XP Factory plc (AIM: XPF), one of the UK's pre-eminent experiential leisure businesses operating the Escape Hunt® and Boom Battle Bar® brands, is pleased to announce its unaudited interim results for the six months ended 30 June 2023 ("H1 2023").
This share was originally “Escape Hunt” escape rooms, which doesn’t particularly excite me, and obviously had a rough time during the pandemic. However, the notes to the accounts today show that Escape Hunt is a nicely profitable part of the group, so shouldn’t be dismissed, making strong EBITDA margins at a site level (better than Boom).
The more interesting part of the business is the newer Boom Battle Bars, which was acquired (funded by a 30p placing, and deferred consideration shares - which have now been issued) in Nov 2021. In 2022, XPF embarked on an astonishingly rapid roll-out of new Boom sites, some company operated, some franchised out. This is what has caused the large jump in reported revenues in H1 2023, as all those new sites contribute for the first time.
I had a quick chat with management yesterday, who sounded perplexed that they’ve successfully delivered everything that was planned in 2021, yet the share price has halved!
Here are my notes from reviewing the H1 2023 numbers -
Revenue £18.7m (up 130%)
Like-for-like (LFL) revenue growth excellent, at +20% in H1 for both formats, helped I think by the 2022 H1 comparative being a little soft, due to catching the tail end of Omicron virus.
Sites trading: Escape Hunt 47, Boom Battle Bars 29. Some owned, some franchised. So it's becoming a significant business, and bear in mind the franchised sites don't contribute much to revenue, so the underlying size of the business is larger than revenue numbers suggest.
Like-for-like revenue growth accelerated in H2, to +24% for the 9 weeks to 3 Sept 2023 - established sites getting much stronger, is very pleasing.
Profitability - we’re presented with a range of options here! Adj EBITDA for H1 is £2.4m (up from £1.1m H1 LY). Whereas taking into account all costs, it’s a statutory loss before tax of £2.4m. No single measure is right or wrong in my view, we need to form a view based on all the variables.
Central costs seem too high to me. Hence XPF will need to accelerate the pace of new site openings, in my view. But the good news is that site economics are clearly very good, so getting new sites open should help dilute the arguably rather too high central costs. You can see the breakdown in note 5, which shows excellent site level EBITDA of £6.2m in H1, mostly consumed by central costs of £4.4m - nearly £9m annualised central costs, seem a helluva lot for a smallish bars group.
Tax - note that the balance sheet shows retained losses of £32.7m, so that should hopefully mean there are decent tax losses to be offset against future profits.
Outlook - confident in meeting market expectations for the full year. However, the forecasts have changed from a previous £1.1m adj PBT for FY 12/2023 (from Singers notes 23 May and 4 Aug), to a loss before tax of £(1.6)m but for the extended 15-month period to 31 March 2024. Singers says that its forecast for FY 12/2023 (not shown) is unchanged. So it seems to be the case that a loss of £(2.7)m is being forecast for the 3 month additional period from Jan-Mar 2024, which strikes me as odd, because I recall that trading was quite good in Q1 of 2023, so not sure why they would now be forecasting a loss for Q1 of calendar 2024? I’ll contact the company and try to get some clarity on this.
Year end change (previously announced) means we’ll get a second set of interims covering 12 months ended 31 Dec 2023, then the full results will be the 15 months to 31 March 2024. The reason for the change is sensible - to better balance the year, and simplify the audit (eg not having to do stock checks at peak trading around new years).
New sites - a much slower pace of expansion is planned, after the headlong rush to open new Boom sites (from about 9 to 29 sites in 2022 was an insane rate of expansion!). I think management tacitly admit that there have been some teething problems with new sites, which is understandable. I still don’t really understand why they did that mad dash for new sites expansion in 2022.
I’m told there are still excellent deals on offer from landlords for new sites, often coming with a large reverse premium to fund a lot of the new site capex. Being a listed company is a tremendous competitive advantage when sourcing & negotiating new sites.
Balance sheet - oh dear, nobody proof-read the accounts, which is sloppy.
(EDIT: replacement RNS has just been issued, correcting the balance sheet).
This is the error, and it’s a big one - receivables should be £965k, but is stated at £9656k!
I’ve contacted the company, to suggest that this large error is corrected, and a replacement RNS published -

Overall, the balance sheet is weakish I would say.
NAV is £23.6m, but £23.4m of that is intangibles. So NTAV negligible at £0.2m.
However, the lease entries contain a large deficit of £(7.9)m, which suppresses NTAV, and I am happy to strip out those lease entries, which makes the NTAV more palatable at £8.1m. However, I am concerned that a large deficit on leases suggests that XPF must have some problem, loss-making sites. Otherwise they wouldn't be showing a deficit of lease liabilities being £8.1m more than the right of use asset figure. I wonder if this might relate to under-performing franchisees? XPF signs the main lease, and then sublets to franchises, so a badly performing franchised site would I think impact XPF's lease entries. Hence buying the franchisees out, and switching to a company managed (better performing) operation, could help correct this. I'll ask for more clarity on this when I next speak to management.
Cash is £3.7m, but interest-bearing debt is the same amount of £3.7m, hence net cash/debt is zero that's fine by me, given that the company is now cash generative.
This would concern me if the company was burning cash, but it’s not any more -
Cashflow statement - shows good cash generation now, from the larger number of sites operating, which is why I’m more relaxed about the balance sheet being a little weak.
Operating cashflow in H1 was £3.4m, although I would adjust off £1.15m of finance & lease costs further down, so real-world cash generation of £2.25m in H1 (the seasonally quieter half), which I think is really pretty good going, considering this business is only really a couple of years from being little more than a startup.
The cash generated has been spent on expansion capex (new sites), of £2.7m.
A noteworthy new site opened is in Dubai, which is trading well I’m told. This is certainly an ambitious management team, that’s for sure.
Paul’s opinion - so far, so good, is my overall view. This is a fast-growing leisure business which seems to have first-mover advantage, and is expanding fast. I think management has demonstrated considerable skill at doing a fast rollout with a modest amount of cash, yet the stock market has given them no credit at all for what has been achieved.
£29m market cap seems strikingly low, and I think this could re-rate nicely in the next bull market, so I see this as a good ground floor opportunity, if you like what they’re doing.
On the downside, the balance sheet is OK rather than good. Faster expansion probably would need an equity raise - maybe they could do say £5m equity, and £5m debt raise at the same time, once the equity has recovered back to say the previous 30p fundraise level. I wouldn’t want to be diluted at a lower price than that, especially as private investors are often effectively excluded from discounted fundraises. Management seem to me averse to dilution, as they could benefit from the generous share options package already in place.
Overall, it’s not perfect, but I think for £29m mkt cap, this is a nice entry point for what is now a viable, cash generative business. Whereas in the past, we had to pay more for the shares, and take more risk - hoping that it would become cash generative in future.
Graham’s Section:
Ab Dynamics (LON:ABDP)
Share price: 1668p (+2%)
Market cap: £383m
This is an ahead of expectations update.
AB Dynamics plc.. the designer, manufacturer and supplier of advanced testing, simulation and measurement products to the global transport market, issues the following trading update for the year ended 31 August 2023 ("FY23"), in advance of the publication of its annual results.
I had a look at this company’s interim results back in April.
Today we learn that “trading momentum was sustained during the second half of the year”.
The Group saw continued good performance in the track testing sector and particularly strong growth in the laboratory testing and simulation sector, which benefitted from an earlier than expected delivery of a large, high margin contract. Further progress has also been made through FY23 in developing the ABD Solutions offering.
I must say that ABD Solutions looks seriously impressive: “a retrofit system providing everything needed to go driverless”. They say that they can make any vehicle work without a driver, so businesses can use their pre-existing fleet. It is targeted at mining (“ideal for open-pit mining and hazardous off-road environments”), agriculture, defence and materials handling.
Revenues for the financial year ending August 2023 are therefore set to exceed £100m (the StockReport shows £98.9m expected). Adjusted operating profit will be above the top end of the range of current market expectations, which the company helpfully discloses as being £14.7m - £15.9m.
Net cash is at the very reassuring level of £32m, even after making cash payments to acquire Ansible Motion.
Outlook: “Alongside sales, order intake continued to be strong through the second half of FY23, providing good momentum as the business enters FY24.”
Graham’s view
Like many others, I rate this as a high-quality international business: it operates in attractive niches that are clearly in high demand. It should enjoy long-term growth, as autonomous driving capabilities continue to develop. And it has already been profitable for many years.
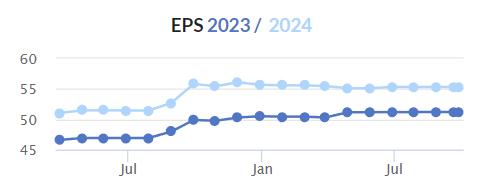
Current trading is clearly very strong, with pleasant upward momentum in EPS estimates:
You can view its various divisions here to find out more about its subsidiaries.
Against the positives, it must be said that profit margins have not been high enough to allow the company to generate strong ROCE/ROE, and the valuation is very racy:
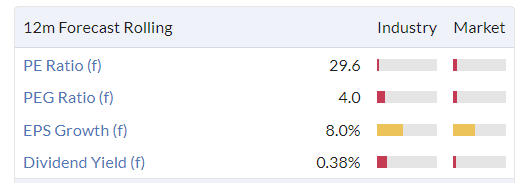
I’m going to keep my neutral stance on the shares because my base case assumption must be that it’s fully priced at this level. But hopefully it will prove me wrong and profits can grow fast enough to justify further gains for shareholders.
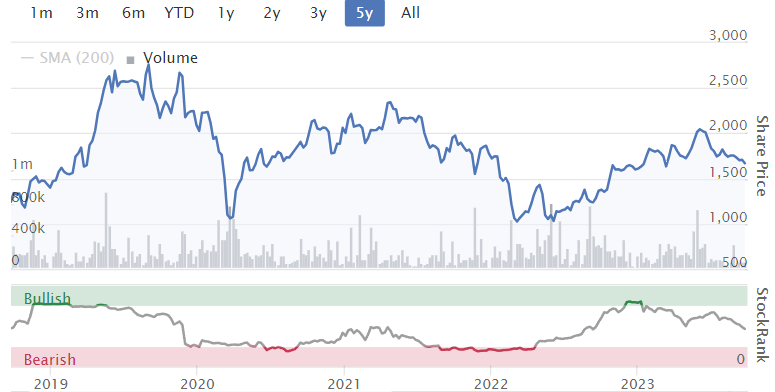
888 Holdings (LON:888)
Share price: 92.8p (-16%)
Market cap: £416m
(At the time of writing, Graham has a long position in 888.)
888 (LSE: 888), one of the world's leading betting and gaming companies with internationally renowned brands including William Hill, 888 and Mr Green, today announces an update on current trading and FY23 guidance.
This is my one very high-risk holding in my personal portfolio. Thankfully, it’s a very small holding, just 3% of the total. And I’m aware that it could end up being a zero, if it fails to manage its leverage properly.
I’ve been holding it for several years; my mistake was failing to sell out when they bought William Hill during the post-Covid era. They ruined their formerly cash-rich balance sheet and took on an arguably lower-quality business.
However, they have not yet suffered actual financial distress and there remains a (slim?) chance that everything will work out:
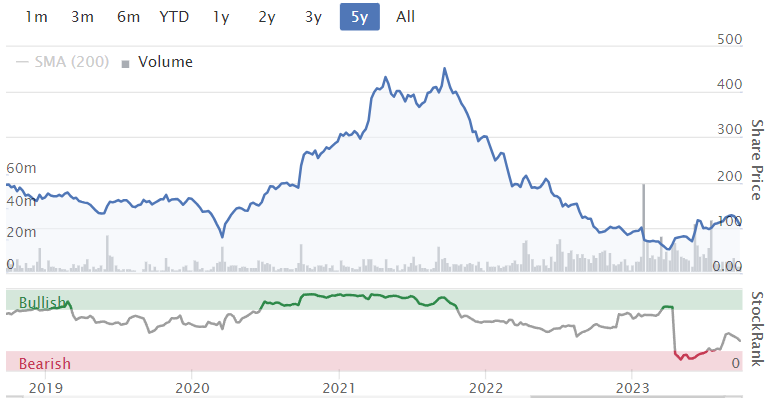
However, today brings a profit warning, due to poor trading in Q3.
Key points:
Performance has been “mixed”, Q3 revenues down c. 10% year-on-year to ~£400m.
Efforts to improve the “sustainability and quality of the mix of the business” are weighing on short-term performance.
But active customers are still growing at a “strong double digit” rate.
So we have more customers, but betting smaller amounts?
The company sets out the following reasons for the revenue decline: compliance changes in online markets, customer-friendly sports results, safer gambling changes in the UK, and a short-term impact from a changed marketing approach.
This industry is of course a regulatory minefield. On top of that, sports results do sometimes favour the punters (not all risk gets hedged away by bookies).
Liquidity is still high at more than £300m (cash of £162m plus undrawn borrowing facilities of £150m). But remember that there is a mountain of net debt: £1.7 billion as of the interim results..
Outlook: some good news here that “synergy delivery is on track and significant cost savings are being delivered”. If there is a bull thesis to be made here, it’s that the combination of brands inside 888 can keep eliminating duplicate costs and benefiting from their combined buying power.
Perhaps surprisingly, the company says that “additional savings will be reinvested in growth initiatives” - they are seemingly hoping to grow their way out of their balance sheet problems, instead of running everything on shoestring budgets.
However, for the current year, investors have to reset their expectations. Whereas the company previously expected an adjusted EBITDA margin of at least 20%, new guidance suggests that this margin will only be 18-19%. Targets for 2025 remain unchanged.
Chairman comment
The Chairman welcomes the new CEO (starting next month) and the new CFO, and says:
We are strongly focused on investing to deliver good levels of expected revenue growth in 2024 as we progress towards our clear target of more than £2 billion of revenue in 2025 and I look forward to the coming years with confidence."
So there is little sign of panic at this stage.
Graham’s view
The bulk of the company’s outstanding debts do not expire until 2027 and 2028, so there should be time for many plans to be implemented between now and then.
The July 2028 bond currently trades at 96.6 Euro cents, and the price of this bond has picked up this year, implying increased confidence:
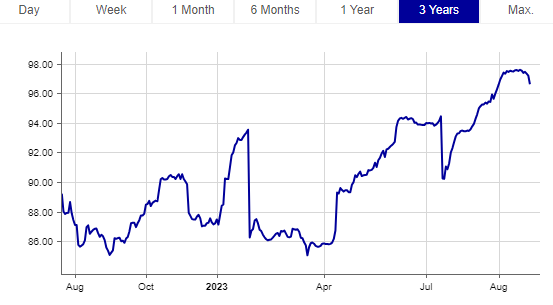
Naturally, these are junk bonds with 888 having speculative-grade credit ratings from all of the rating agencies. Here is a table in which I’ve highlighted in yellow where 888 sits:
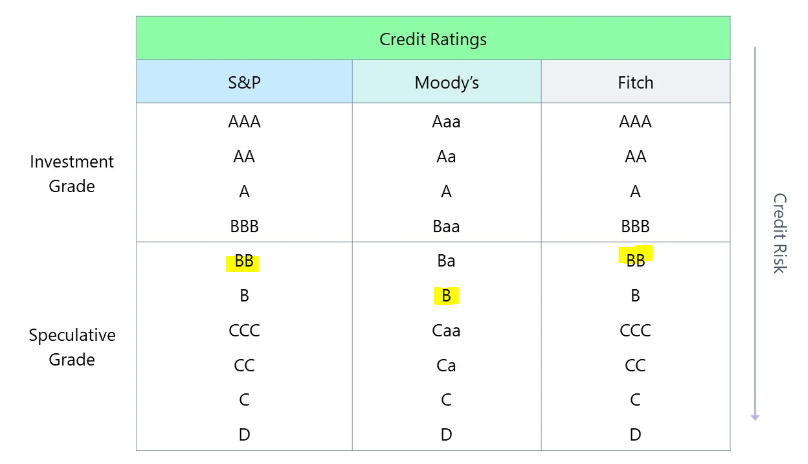
The debt pile might seem insurmountable but with bond investors remaining calm, I’m going to keep my neutral view on the stock for the time being. If I had a negative stance, I would have sold already - I still think it’s possible (perhaps a 30-50% chance?) that the equity emerges unscathed from this situation. Unfortunately, that does make the stock suitable only for those willing to take a gamble.
If the equity does somehow emerge unscathed a few years from now, I would hope and expect to see very strong returns for shareholders from the current level.
If they hit the £2 billion revenue target and achieved a 20% adj. EBITDA margin, that would be £400m of EBITDA with which to pay their interest bill and reinvest in the business. Hopefully there will still be meaningful amounts left with which to actually reduce the outstanding debt, instead of merely attempting to refinance it when the time comes.
This is clearly not a sleep-sound-at-night type of stock.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
XP Factory (LON:XPF) well done Paul it seems that your email got the correction we needed. Great spot. Need you as my accountant.
XP Factory (LON:XPF) their proof reading remains awful…
RBG Holdings (LON:RBGP) - I am glad that Jon Divers isn't wasting shareholders time any more. His presentation lasted 3:53 on Investor Meets Company. If I was still holding (which I am not), then I couldn't have been more reassured by this. Looks like he has got back from a particularly boozy lunch with Nicola Foulston.
That's the way to do it cheeky minnows. Could he look any less interested?
"Incorrectly sitting on our balance sheet" haha. On the upside at least there was no time for ESG junk.
Sounds great! I hope they publish the recording of RBG Holdings (LON:RBGP) on IMC.
I wouldn't waste your time Paul. Keep giving us your picks of the week :o). My comment was very sarcastic, as other companies have had to work hard to recover the damage that RBGP did to my portfolio. His presentation was essentially him telling us how excited he was about the future (I have never seen anyone look less excited about what he was talking about). It looks as though it was cut from a much longer interview, where someone said in editing.... 'well let's just keep the positive points, eh ?...'
Was like a cross between a hostage video and me trying to look interested in woman's football.
S&p is setting up what could be a good time to go long looking forward to a potential Oct-Dec year end rally.
Sentiment is back to fear levels and the index is at a natural level to find buyers. Next few days will be interesting
Hi Wolf any thoughts on if Liontrust Asset Management (LON:LIO) is setting up for a stage 2 base been a dog for the last eighteen months, but seems to have plenty of net cash and still profitable and should benefit when markets turn.
The downside is still seems to go down even on market up days.
Regards Andy
It's on my watchlist Phoenix but it's still making new lows so I've no interest until that changes.
Jupiter Fund Management (LON:JUP) looks better, it's at least trying to make a base and forecasts/AUM seem OK
Jupiter Fund Management (LON:JUP) is on my watch list also Wolf fund management sector does look cheap and there is a huge amount of mergers and take overs going on in the background Greham House, Brewins, Numis, Charles Stanley to name a few from last 1-3 years.
Bond yields and Oil continuing to marching higher in lockstep isn't helping matters though.
What's the utilisation/occupancy rate of existing sites at XP Factory (LON:XPF) ?
I note that in the past year there's been a boom in people seeking "experiences" and "activities" - benefiting Boom Battle bars. Indeed, the one near me in central London is usually booked out during popular times (as well as other experiential places like minigolf, darts, etc)
So if they are hitting the limits of capacity/occupancy, there is little scope for extra revenues (and operationally geared margin) from existing sites, and growth will solely depend on new sites.
And if utilisation/occupancy is at a cyclical high, when it moderates downwards, that will have a big negative operational gearing impact.
Food for thought.
Part of the investment thesis is that sales will be resilient through any downturn as XP Factory (LON:XPF) is a market leader in the relatively new, secular growing subsection of competitive leisure.
Just as importantly XP Factory (LON:XPF) can generate additional revenue from mature sites by increasing prices (they have held them flat so far) and changing the site game formats at minimum cost. Management have a track record of doing this successfully with Escape Hunt sites.
Management have also shown that margins grow as sites become more mature. This should generate cash that can be deployed into additional new sites both in the UK and overseas. Management see the opportunity to for up to 100 BOOM sites in the UK alone and are keen to develop overseas too.
As Paul mentioned it would be good to understand what has driven the broker forecast changes and the lack of profitability now forecast in FY25 especially. With so many sites up and running I dont think it makes as much sense now to focus on site as opposed to group profitability.
Still a very young business and not without risks but management now have a track record of making continuous progress over the last 3 or 4 years.
This famous management you are talking about what exactly have they achieved with Escape Hunt’s share price?
Part of the investment thesis is that sales will be resilient through any downturn as XP Factory (LON:XPF) is a market leader in the relatively new fad of competitive leisure.
Fixed that for you. It might turn into an enduring trend. We don’t know yet. But it’s not like we’re talking cloud computing, the rise of the Asian middle class or the energy transition.
Renewi (LON:RWI) - offer incoming from Macquarie. Yet another potential takeover in a secular growth market. Shares had looked cheap but then performance wasn't much to shout about. Board says no, but Macquarie are appealing directly to shareholders.
And yes, it's another of my holdings to be snaffled up.
Xlmedia looking very cheap to me, looking forward to some commentary on it...
Hi CHRI55,
I've had a quick look at XLMedia (LON:XLM) and can't say it looks particularly cheap to me. Of the $6.0m H1 operating profit, $4.0m came from an impairment reversal. It seems to be retrenching into areas where it can still make money, and dropping other stuff.
Balance sheet is weak, with negative NTAV, and note the deferred consideration creditors which will be cash or shares to be paid.
Dividends stopped a few years ago, and I'd say its dividend paying capacity now is close to zero.
Looks a low quality business to me. Like many others in this sector, they have a few lucrative years by taking advantage of favourable payouts from online advertising, and the loopholes are then closed, and profits dry up.
This type of share always looks very cheap on a PER basis, that's what sucks people in. But it fails the simplest test that we should always apply to every share - question whether profits are sustainable.
Overall, for me then it's probably AMBER/RED for XLM. Sorry about that.
Regards, Paul.
Digital 9 Infrastructure (LON:DGI9) - very sharp drop this morning on news that dividend will be scrapped (complete cock-up by the board who only recently announced the dividend was safe). Looks like a very badly managed company - and the spiralling unhedged debt costs are a concern - but the underlying assets look sound (such as data centres). Could perhaps be decent upside if they decide to wind-up the company and return cash to shareholders? That would seem the most obvious route as it can't possibly have any future as an investment company given the very wide discount.
I sold out this morning. Horrid loss, but with no dividends and the debt issues, I took the view that something was better than nothing. Very disappointing.
Digital 9 Infrastructure (LON:DGI9) share price behaving like a small cap 'story' stock which has hit the buffers. A complete disaster and can only hope that something positive happens over the next 10 years (!) as not going to sell at these levels. What with the ongoing shenanigans at Thomaslloyd Energy Impact Trust (LON:TLEI, which I also hold, this is a very clear indication to me that I should never, ever, invest in specialist Investment Trusts again. They are not supposed to behave like a small cap high risk, high growth stock that issues a major profit warning. What a disaster!
Chapel Down (OFEX:CDGP)
Investor Meeting Half Year Results - Investor Meet Company
Worth an hour for anyone in or thinking of Chapel Down, this is their IMC vid. from yesterday.
Bullish
* I found CEO and CFO Carter and Smith straight talking and focused on the company plan, and lacking the corporate gobbledygook that is far too abundant nowadays. *Climate change. Record harvest in quantity and quality for 22 and 23 and raised awareness of English Sparkling wine as an acceptable alternative to Champagne.
* 2023 marketing campaign has been a huge success for CD, raising brand awareness and giving momentum to sales in both On and Off Trades. * The price points of the sparkling wine are roughly 2/3rds of an equivalent bottle of Champagne, with no discernable difference in quality, so could benefit from consumers trading up and down. * The wine stock, land and vineyards are valued in the books at cost which is probably considerably less than net realisable value.
Bearish
*The company's focus is on English Sparkling wine that is produced in the same 3 year process as Champagne which will require capital as they expand land under planting. *Weather risk. * Execution risk as they build the new wine making facility at Highland Court, Canterbury.
£JNEO ( I hold)
I think Journeo are on IMC today at midday. They reported 2 days ago. Business is still seeing good growth both organically and through acquisition. Not only do they have a good order book (£27m) but an excellent pipeline (£55m). Historically management tend to be conservative and so anything in the pipeline tends to be high likelihood of landing. There is clearly momentum in the business and opportunities to grow in buses, airports and trains, both in the U.K. and geographically.
They have cash and have moved into profitability though operational leverage doesn’t currently seem to be huge. Regardless, a small cap that is growing and being rewarded is always good. Management continue to be very positive about prospects and are not naturally prone to over exuberance. I also notice that Barney Kent formerly of Ideagen has joined the board.
They are on about 10x next years earnings and still,have a lowly market cap. The business is a mixture of hardware, software and some services.
Eenergy (LON:EAAS) - "Driving Net Zero through innovation and technology" (initiation of coverage) *** Full report and audio summary: HERE
eEnergy is a leading B2B energy services business in the UK, supporting c.2,000 clients with their energy strategies across public and private sectors. We believe the energy crisis has combined with the Net Zero agenda to create a tipping point for action on energy security, costs, consumption and waste. After three years of significant growth and investment since listing on AIM, eEnergy looks ideally placed to play a leading role in the Net Zero transition. This is underpinned by a compelling proposition, which delivers energy efficiency upgrades that are paid for by the savings generated.
Today’s interims to 30th June (12-month period) confirm the continuing strength of demand, which we expect to drive sustained EBITDA growth and an improvement in free cashflow (estimated 10% free cash flow yield from 2025). In our view, medium term growth prospects are highly attractive and are not reflected in a very modest £20m market cap.
A modest P/E ratio (7.7x falling to 6.3x in FY24/FY25) appears to overlook the growth trajectory, with EBITDA expected to increase by 41% in 2023 and 30% in FY24 without factoring in the potential for M&A. A 7.5x EV/EBITDA rating would suggest Fair Value of 13p per share.
Thank you. I am surprised that there is not more interest on these forums in £EAAS.
The fund raising was a bit of a disaster in terms of investor PR but I think that the business is well placed.
Eenergy (LON:EAAS) I bought in Oct 2021 at about 16p and despite a doubling of turnover and achieving its first profit and a forward PEG of just 0.2 it's price is now just 6p, over 60% down. I should probably buy more now but hesitate because sentiment is so bad. That, I think, is the issue - almost all small cap stocks have been continually sold unless actual profits are being made, preferably with a dividend too (but then even I3 Energy (LON:I3E) has been smashed and they offer a 13% div!)
I suspect Eenergy (LON:EAAS) has reached a point where no future story is required and the price will be dragged kicking and screaming slowly upwards based on actual returns. I will need to have another close look at the currently available information but will likely top up. IMO the potential for a service company like this, with a market cap of just £20M, to re-rate and multi-bag is high.
Hi Monty9
I had some issues copying and pasting the above from Eenergy (LON:EAAS) update today - with £7m of debt imagine the risk of equity dilution is significant
Any thoughts on HSS Hire (LON:HSS) 6 monthly update today, sp significant decline, just who is dumping the shares ????? Surely a long opportunity or getting that way, can you take a look Paul or Graham
HSS Hire (LON:HSS). Agree with you Mike. SP fall this morning is quite a surprise. I thought there would be a jump back up today (might still happen as the price regularly goes up and down by massive percentages with little/no news). Recently the direction has been markedly down.
The 6%+ fall in price yesterday was on relative high volume - generally quite a worrying combination. However, looking at the absolute volume of shares it was around 2m... at a total value of around £200k. Perhaps not so worrying after all? Just shows how relatively small amounts of money flowing in/out can really shift the price on small caps. Also made me think that the average daily level of buying/selling on HSS Hire (LON:HSS) must actually be quite small for £200k to be a high volume day. Figures seem crazy - but I think they're right.
Perhaps there's quite a few investors like me sitting on their hands waiting for the property market to improve, which will undoubtedly raise all boats like the tide.
I note that HSS Hire (LON:HSS) is part of Ed's SNAPS Portfolio for the second half of 2023 - so its metrics must be good as the picks are based on the best in each sector. Just a matter of waiting I suspect.
Cambridge Cognition Holdings (LON:COG)
Following on from my comments a day or two ago, I logged in to the results webinar yesterday, with both CEO and FD on camera.
Key points that weren't in the RNS:
They did refer to the share price reaction briefly, but did not seek to explain it. There were multiple mentions of contracts being delayed longer than they expected.
The subjective stuff? There was some glancing away to the side of the screen - either because corporate finance were there off the side or because some answers may have been pre-scripted. They didn't look entirely comfortable, but then this is a small cap, not an acting school. No live questions, but they didn't appear evasive either.
What still wasn't entirely clear at the end was whether the need to raise working capital was because the integration of the aquisitions had proved more cash consumptive than expected, or because of contract delays had left them exposed.
Any mistakes in the above are because I was cooking two children dinner while listening in....
Thanks for this re Cambridge Cognition Holdings (LON:COG) very helpful. I did glance at the figures recently, and was aghast, noting down "What on earth have they done?!" - referring to the way they've spent almost all that lovely cash pile, on acquisitions that don't seem to be contributing any profits. The cash was money received up-front from customers, so really shouldn't have been spent in my view. Also it's moved from breakeven/small profits into losses now. The whole picture seems to have changed - for the worse. And now it looks strapped for cash. So I'm afraid I've really gone off this share, because risk:reward seems to have significantly worsened due to management's actions.
I di dhave a long one-on-one chat with the CEO at a conference earlier in the year, where we discussed the acquisitions in more detail.
Winterlight was effectively buying in something they would have needed to develop anyway - saving themselves several years of development time, and they may not have been able to build it for much less. It wasn't profitable, but they paid the same multiple of sales as Cambridge Cognition Holdings (LON:COG) was trading at.
ClinPal is much smaller & the necessity isn't as obvious to me, but at £1.7m it doesn't change the big picture.
But yes, they've certainly introduced balance sheet risk that wasn't there before, and they've communicated very poorly indeed about the cashflow situation. Making macro observations & saying things like "when interest rates fall" will not endear them to investors either - they have no better idea than shareholders.
Personally I think they modelled their expected cashflows at the time of the acqusitions and thought they would get away with it. Contract delays and finding out exactly what they've bought meant they didn't.
Does that change the big picture? If they are correct about not needing to raise further finance and they are indeed cash positive in H2 then I expect it will be seen as just another speed bump in the rear view mirror.
The downside is if they've been acquiring to diversify because the original CANTAB product has nowhere near the competitive market traction that they've led the market to expect. If that is the case (and you have to assign a substantial probability to it) then we can expect further contract delays and Claret turn the screw as they have the first right of refusal to any further fundraising....
On the other hand I do believe the "moat". A close relative works in neurology and affirms that the CANTAB tests are referred to regularly in the academic literature.
@ABDP - A B Dynamics - I hold
Very upbeat trading update today.
"Following a strong performance in H1, the Group is pleased to report that trading momentum was sustained during the second half of the year. The Group saw continued good performance in the track testing sector and particularly strong growth in the laboratory testing and simulation sector, which benefitted from an earlier than expected delivery of a large, high margin contract. Further progress has also been made through FY23 in developing the ABD Solutions offering. In addition to the significant organic growth achieved, a strong performance was delivered by Ansible Motion, the simulator business acquired during the year.
In light of the better than anticipated trading in the latter part of the year, the Board expects revenue for FY23 to exceed £100m for the first time. Enhanced by the significant productivity and capability investment made over recent years, the strong revenue growth is anticipated to translate into a full year adjusted operating profit result that is above the top end of the range of current market expectations1."
Shocker from Zoo Digital (LON:ZOO)
Update isn't good but the brokers reveal the real damage.
PBT now expected -13.8m. Both brokers drop 2025 estimates.
So they've went from needing a placing of £12m in April to buy an unnamed Japanese company, for a secret price, with no director participation ......to blowing all of it in 12 months.
Agreed. And they didn’t even mention (in their statement) the biggest worry - that the studios will start to get their subtitles and their dubbing done by AI. Maybe AI subtitles won’t be as a human translation but will the studios care? And when we are all scared of AI created fakes mimicking people we know how far away is good enough dubbing?
Interestingly Stocko rank had climbed quite a bit recently, hence I asked for views yesterday. Best avoided now imo Zoo Digital (LON:ZOO)
Yes the figures are bad, but I'm surprised to see a further 27% fall - the company isn't in immediate danger and the medium term plusses and minuses are unchanged
I suspect it's fallen because forecasts have been pulled. I suppose that's one way of avoiding a profit warning.
Market cap is low enough it could bounce but it's really a gambling chip right now in my view. Depends if you trust what the CEO is saying.Theres some very good points made by Graham here
www.youtube.com/live/j...
Positive trading update from Mitchells & Butlers (LON:MAB. Outcome to be at the top end of consensus expectations for the current year with good momentum going forward.
Also other listed 'pub' companies appear to be reporting good trading, City Pub (LON:CPC) for example, Again I don't hold but it is reasonable to extrapolate a read across to Young & Co's Brewery (LON:YNGN) that I do hold.
The non-voting shares in my opinion offer significantly greater value than the much more expensive voting shares, for reasons I have previously posted.
Morning Paul,
You are absolutely correct on OPTI and will survive only by selling its Skinbiotherapeutics shares. I also believe that on Saturday its CEO was attacked (verbally of course) in an event , where Paul Jourdan of Amati was present as well , by Lycian Miers ; a great bear specialist.
Its a bit of a strange case where the products themselves particularly the natural sweetener one would think if it is brought into loads of products as agreements signed with major manufacturers, the IP in itself would in my opinion form the most valuable part of the company and possibly other components with connected companies Probiotix (spun off) and Skinbiotix which OPTI still holds shares in. However yes as Paul has illustrated the associated turnover to date is lamentable, but I am hoping that the company and its products do thrive as potentially assisting to prevent obesity and diabetes among other ailments. That said my investments into ethical stocks, and green companies mainly jam tomorrow one must say none of which have born any fruit yet and nursing losses to date.
My morning smallcap tweet: Temptation, elation or deflation?
Shield Therapeutics (LON:STX) Kromek (LON:KMK) Frp Advisory (LON:FRP) Team (LON:TEAM) ValiRx (LON:VAL) LungLife AI (LON:LLAI) Concurrent Technologies (LON:CNC) Zoo Digital (LON:ZOO) Ab Dynamics (LON:ABDP) FIH (LON:FIH) Novacyt SA (LON:NCYT) Let's Explore (LON:LETS), Colefax (LON:CFX), NWF (LON:NWF), RBG Holdings (LON:RBGP)
◄Shield Therapeutics (STX)► $7.5m placinf, subscription and retail offer at 8p, an 18% discount. $20m loan. "to accelerate initiatives to improves gross to net discounts", working cap and repay a loan. [SP=11.5 Cap=82m]
◄Kromek (KMK)► completes refinancing of its borrowing facility with the signing of a new £5.5m convertible loan (looks like a death spiral). [SP=3.81 Cap=23m]
◄FRP Advisory (FRP)► AGM stmt- will at least deliver the current full year market expectations of rev £111.8m and adj EBITDA £28.7m. [SP=116 Cap=291m]
◄Team (TEAM)► issues £4.25m loan notes at 12%, for additional working capital. [SP=39.4 Cap=8m]
◄ValiRx (VAL)► operational review. [SP=5.45 Cap=6m]
◄LungLife AI (LLAI)► data from the clinical validation study for its LungLB test delayed from end Sept to sometime in Q4.. [SP=93 Cap=24m]
◄Concurrent Technologies (CNC)► launches ruggedised plug-in-card, Buddon, an upgrade for those customers who have deployed systems based on 3U CompactPCI. [SP=74 Cap=63m]
◄ZOO Digital (ZOO)► warns again as 'Hollywood' strikes continue. Guides H1 range from similar to H1 to an increase in revenue in Q4. Guides H1 rev c.$21m and sig EBITDA loss. "The Board will manage ZOO's cash position carefully whilst protecting production capability and capacity to enable a rapid rebound of revenues when orders return." [SP=52 Cap=51m]. I hold.
◄AB Dynamics (ABDP)► guides FY-Aug rev over £100m and adj op profit bove the top end of the range of market expectations of £14.7m to £15.9m. [SP=1633 Cap=375m]
◄FIH (FIH)► AGM stmt - "PHFC continues to perform as expected and whilst Momart and FIC have each had a slower start to the year than expected, a stronger second half performance is anticipated for both". [SP=244 Cap=30m]
◄Novacyt (NCYT)► H1-June rev £3.3m. Guides FY rev £10-13m. Co needs to do "further work on the combined businesses to determine financial/EBITDA expectations". [SP=65.8 Cap=53m]
◄Let's Explore (LETS)► to buy Huddled for £3.95m, most of its cash pile. Huddles owns Discount Dragon, "a fast-growing direct-to-consumer e-commerce". [SP=NA Cap=NA]. I hold.
In line: CFX, NWF, RBGP
Let's Explore (LON:LETS) Imagine having a few million in cash and the most exciting thing they can find to buy is a seller of dry and tinned grocery goods close to their best before date.
It’s an odd one but not so bad. The management are wheeler dealers - they have a very good track record in getting in and out of businesses as the wind changes. Possibly not for the long term this one but I’d back them to make money from here.
Discount retailing can actually be super profitable and a great business if you know what you are doing. Booker being a good example. Interesting that they’ve gone from £75k p/m to £400k p/m in just 1 year. Suggests that business has legs.
Not massively keen on the concert party element but at least the price paid is all in shares so the cash doesn’t get eaten and the sellers are aligned to shareholders. Ie unlikely the directors think it’s a pup! On the plus side they also know the business so there shouldn’t be any integration problems.
Market seems to be unimpressed but possibly just investors who held because net cash is so much more than market cap are getting out. If it drifts I will likely buy some I think as can see this getting nicely profitable with a 1 to 2 year view.
It's a pity that Let's Explore (LON:LETS) are buying Huddled from their own directors. Related party transactions always make me nervous as I'm never comfortable that the view of the NOMAD and independent directors is entirely dispassionate.
(EDIT) Related Party Transaction
Martin Higginson, Daniel Wortley, M Capital Investment Properties Limited (a
company controlled by Martin Higginson) and Lanton Investments Limited (a
company controlled by the family of David Marks) as directors of the Company,
and in the case of M Capital Investment Properties Limited and Lanton
Investments Limited an associate of a director of the Company, are considered
to be related parties pursuant to Rule 13 of the AIM Rules as they are also
shareholders and Sellers in Huddled.
The participation in this Acquisition by Martin Higginson, Lanton Investments
Limited and Daniel Wortley is considered to result in a related party
transaction under AIM Rule 13 of the AIM Rules due to these individuals being
directors or associates of directors of the Company. The Independent Directors of the Company, having consulted with Cavendish Securities PLC, the Company's Nominated Adviser, consider that the terms of the Acquisition are fair and
reasonable insofar as the Company's Shareholders are concerned.
In addition, as a result of the interests held by Martin Higginson and the MH
Connected Persons (being approximately 21.63%) in the Huddled Sale Shares, the Acquisition constitutes a substantial property transaction for the purpose of section 190 of the Act and, accordingly is also subject to shareholder approval at the General Meeting.
Yes - but as I say the directors have a history of making money for shareholders from businesses they’ve owned.
The fact they took consideration in shares rather than cash tells me they think there is much more value in the forward equity. I’m ok to back that.
But in general I don’t like related party transactions. I will make an exception for this one as I know management history. Might not be for everyone tho.
Avation (LON:AVAP) getting themselves ready for growth again post Covid. Been a lot of fixing their balance sheet the las my year and moving their fleet around. A crazy 60% discount to NAV which can only be justified if we think there’s going to be another shut down. Would love to hear the bear case on this as struggling why this should be sognifiohigher rated
I follow this one (Avation (LON:AVAP) , and some of the larger aircraft leasing firms like AerCap Holdings NV (NYQ:AER) . The price to tangible book ratios do make Avation look cheap on a relative basis, but I'm not expecting that to change quickly.
There is quite a lot going on in the industry - insurance settlements over the planes the Russians appropriated, the Pratt & Whitney Geared Turbofan problems, Boeing still struggling to deliver on time, widespread ongoing disruption to airlines even with COVID behind us...and trying to price in the fact that a similar episode to COVID will always be ahead of us.....
Avation's problem is scale - the efficiencies of scale in dealing with lots of ATRs just isn't the same as dealing in the large jets - you incur the same legal and admin costs to manage a $20m turboprop as you do a $300m widebody jet like an A350.
Before COVID they had started to take on some jets and climb up the ladder to larger ticket size, but then had their legs kicked out from under them.
I suspect much of the reluctance with AVAP is a fear over what rate they can refinance at going forward. It is a small asset-financing play in a world of steeply rising rates, with lots of (secured...) counterparty risk to emerging market airlines.
It’s not really as they tie financing to lease duration. Once the plane comes off lease it’s unencumbered.
Credit risk is the main area but they have managed this pretty well so far.
For Avation (LON:AVAP) , 40% of their debt is unsecured, and it isn't cheap (including the Avation Capital S.A. 8.25%/9.0% unsecured notes)
Their interest expense in 2023 on the secured borrowings was $21m. On the unsecured it was $31m.
Lease rates are well ahead of cost of capital. They have 4 unencumbered aircraft already. Debt pays down ahead of depreciation so NAV goes up. Within 4 or 5 years they will have a lot more unencumbered aircraft so will swap bond debt for asset backed finance.
I never understood the rationale from the prior FD to tap the bond market. That was a mistake I think. Bank lending against assets was and is perfectly open for business. Far better to fully match the asset and liability.
I suppose no one saw the pandemic coming but nonetheless.
Agreed! A 60% discount to NAV is excessive and well above other aircraft leasing businesses. But should they really be “sognifiohigher” rated?
Can’t figure why Avation (LON:AVAP) isn’t much higher. Traditionally leasing companies sell for 1.1* book so that would be 300p+
The company was one of the best at navigating the covid pandemic.
Maybe people don’t understand the debt structure. Basically the vast majority is essentially a mortgage. Ie they lease the plane for the same duration as the debt with no interest rate risk. So in essence money coming in from the lessor pays the debt on the plane plus a decent margin. The core risk is one of credit but they seem to manage this pretty well too. We can see the mortgage effect by the debt reduction that is way greater than depreciation. In fact some of previously written off values are being written back in as plane values go up.
Anecdotally I was in the BA lounge in Heathrow the other day and my word was it busy. Barely a seat (and it’s massive). If that’s anything to go by plane travel is very very well supported at the moment so Avation (LON:AVAP) should be able grow and finance new planes.
It’s a strange one - understandably people may be worried about another pandemic etc but that’s not really borne out in the travel companies so a discount of 60% against NTAV given managements record of steering the company through extraordinary circumstances seems way too wide.
You are missing the fact that with Avation (LON:AVAP) secured debt doesn't fund the entirety of each plane, only the senior part of the debt structure.
They have to fund the remainder of each plane with junior/mezz/subordinated/unsecured or whatever term you wish to use as plugging the gap with equity is uneconomic.
It is sourcing this "subordinated" debt at an affordable rate that has been a key challenge for Avation historically (even in the high yield market you need to issue a certain minimum size), and as I've already commented, the majority of their interest rate bill is derived from the 40% unsecured portion.
But as the company have already stated the unencumbered element of their fleet will be sufficiently high that they would finance the repayment of that bond through secured bank debt on fleet.
Cost of capital which includes that unsecured bond is well below lease rates of 11% for next year.
Plus $100m of cash at 5% reduces that bond interest by $5m
The company is buying back the unsecured debt not issuing more.
Hi Paul, is there a chance for you to comment on the interims released by XP factory (xpf) which were in line? Many thanks.
Morning TGP20,
Yes I looked through the interims from XP Factory (LON:XPF) (I hold) last night, so just need to type up my notes later this morning. It's on the list! The quick version is that it's a good work-in-progress growth company I think. Cash generative in the quieter H1 period, now it has scaled up the number of sites. It's using internal cashflows for expansion capex (new sites).
Balance sheet looks a little threadbare, but they don't want to dilute, and can continue self-funding a more moderate pace of new site openings, helped by landlord contributions.
Very good LFL sales growth in H1, and even quicker in July & August, augurs well for the FY performance, which they say trading in line with.
Singers research note seemed much lower than I expected, I'll have to check back, but it seems they're forecasting a loss for this year. I could have sworn that previous forecasts were for a profit.
For me, the main thing is that management pulled off an extraordinary growth burst in 2022, opening about 20 new Boom Battle Bar sites in H2 2022, employing over 1,000 extra people, etc, which must have been a nightmare to manage, but they did it. Under-performing franchises are bought back in, which I like - get the franchisees to set up the new site, then hand it over when they manage it badly.
I had a quick chat with the CEO yesterday. He mentioned that being listed on AIM is a huge competitive advantage, when it comes to negotiating with landlords especially, as they would rather have the strong "covenant" of a listed company, than a private company, as tenant, especially in sites where BBB acts as a magnet for customers, pulling in business into the shopping centre in a way that just another generic bar might not do.
He's happy with competition, saying XPF consistently beats competitors with its customer satisfaction scores. He also believes the experiential leisure sector is at the early stages of a structural growth phase, and that XPF is the market leader, and does things better than the competition. So for now anyway, he's happy to have competition, and thinks the market opportunity is large, so there's plenty of room at present.
Regards, Paul.
Thank you Paul for sharing your comments here and Im looking forward to reading your notes later! I became a holder yesterday following the interim results which I thought were tipping the scale towards more positive than negative...Followed this company since you presented it at Mello last May..
XP Factory (LON:XPF) yes I noticed Singers had cut forecasts
In August they had PBT 1.1m for Dec 2023 .
That's been cut to -1.6m (15 months March 2024). 2025 is flat, 2026 is £1.3m profit. How anyone can forecast into 2026 is beyond me but that looks a big change to me.
So it's valued at 30x 2026 numbers. Will need to beat forecasts I would suggest.
XPF also stated they "expect to report full year numbers in line with market expectations." Which doesn't add up with Singers new numbers
That is so annoying, the company announce everything in line with expectations, come out bullish as you like in interviews and then the research note, that PI's like me don't have access to, says a profit warning and all the forecasts are downgraded
Could you ask Richard WTAF is going on if you speak to him again please Paul
Revenue looks in line when adding extra 3 months on.
Net cash was supposed to be 1.7m now it's 0.2m. That's the bit I'd be concerned about.
I wouldn't bother listening to what the CEO says, he's always going to be positive. I'd wait until black Friday and get a subscription to research tree, maybe get a half price deal.
Any chance on some thoughts on Saga (LON:SAGA)
I am also interested in any thoughts on Eenergy (LON:EAAS) They have announced their results today and the appear positive. To me it looks like a great business operating in a sector with good tail winds and a great market in terms of schools and educational institutions. Revenue up 50%, adj EBITDA up 131%, adj PBT up 34%
Yes, we'll try to cover Saga (LON:SAGA) either today or tomorrow :-)
Thank you Paul. Much appreciated.
I am surprised Eenergy (LON:EAAS) doesn't have more interest on these discussions.
Re Eenergy (LON:EAAS) I find it difficult to get comfortable with their net debt position and the need to refinance by Feb 2024. The success of the latter is material to their ability to remain a going concern:
In assessing whether the going concern assumption is appropriate, the Directors have taken into account all relevant information about the current and future position of the Group and Company. These include the current level of resources, the ability to trade within the terms and covenants of its loan facility, the assumed success of the debt refinancing and the ability of the Group to raise additional equity or debt capital if required. After taking these matters into consideration, the Directors consider that the continued adoption of the going concern basis is appropriate.
HSS Hire (LON:HSS) Having read comments on another chat orientated investment website last night I had an uncomfortable nights sleep. Some seemed to think that the half year results out this morning would have dire news. But instead we have growth in revenue and profit coming down. Not a bad result (in my opinion) when considering the state of the property market. I quite like the sound of what they are doing with the business... moving more online and inside builders merchants - but I haven't used their services. Anyone out there who has?
Has anyone else got the problem with the Today button (top left) not working? Mine stopped a few days ago and I now have to rummage around the get access to the small cap report...
All OK with me - I normally use the Discuss button on the menu which then lets you see how many new comments have been added since you last looked at it.
No, but it’s a different layout on that page with the SCVR slightly more difficult to find imo
The Today button works fine on my Mac using Firefox.
I have been having issues loading Stocko app on my mobile since its last software update (Yes to i.os 17 if you must ask!) - Several others reporting similar
I have problems with the pop-out menu from the left for the folios; it has been an ongoing problem but seems to be much worse this week. The menu didn't work half-way through going down the list of folios but lately the folios won't open at all without a log-out and log-in again. Not complaining as no one else has this problem (?) but highlighting it in case it is related to the new Today page layout. :-\