Small Cap Value Report (Thu 29 Aug 2024) - PPH, HTG, SOM

Good morning from Graham & Paul!
All done for today! See you tomorrow.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 26/8/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
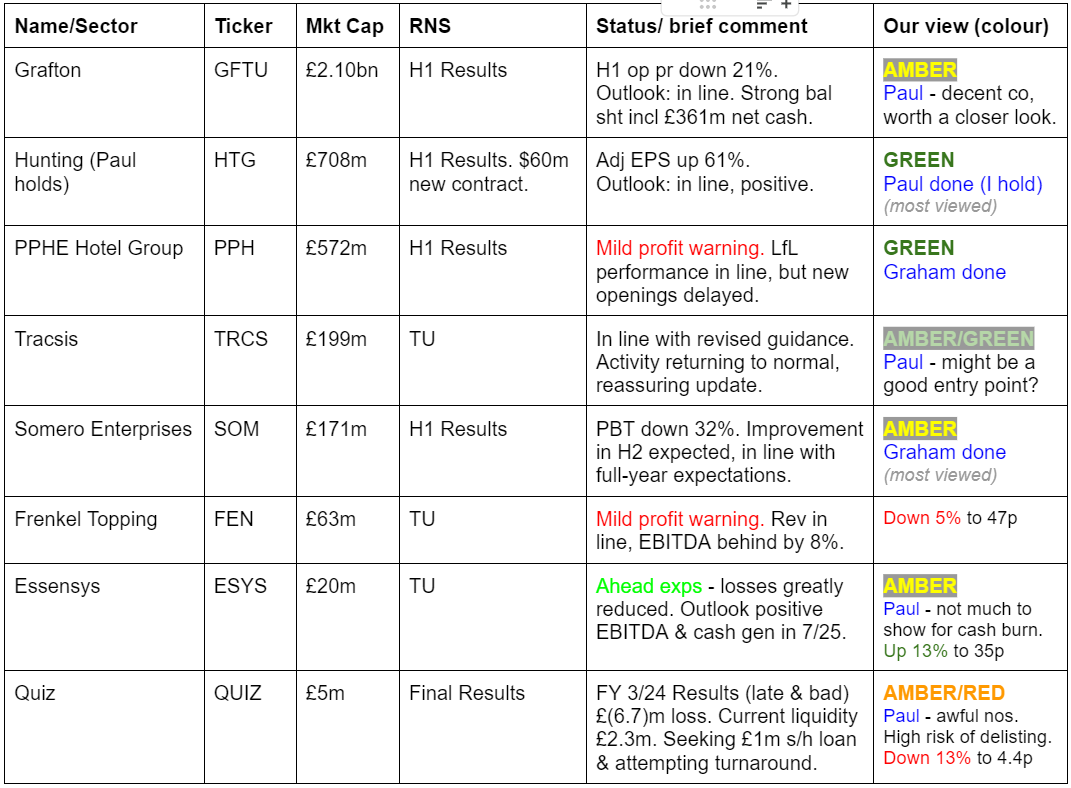
Summaries
PPHE Hotel (LON:PPH) - down 3% to £13.30 (£558m) - Interim Results - Graham - GREEN
This is a mild profit warning as a couple of PPHE’s new hotel openings have been delayed by supply chain problems. However, the existing portfolio has performed in line with expectations and the delayed hotels are expected to make a positive contribution from 2025. I remain intrigued by the valuation on offer here, although the market remains sceptical.
Hunting (LON:HTG) (Paul holds) - down 5% to 408p (£672m) - H1 Results & Contracts - Paul (I hold) - GREEN
Good H1 results, although there seems conflicting broker opinion on whether H1 was in line, or behind expectations. FY guidance (raised in July 2024) is re-confirmed. Superb ungeared balance sheet. I enjoyed the informative IMC webinar this morning. This looks a high quality business, with good IP & margins, and profits heading to c. double vs 2023 in 2024. I cannot fathom why the valuation is so modest, it looks obviously undervalued to me, and could attract a takeover bid.
Somero Enterprises (LON:SOM) - down 3% to 297p (£163m / $215m) - Interim Results - Graham - AMBER
Going back to AMBER on this one as I’m nervous about the company’s ability to hit full-year forecasts (revenue of $110m and EBITDA of $30m). International sales have plummeted in certain regions and the home market of North America is seeing sluggish sales, attributed to project start delays and interest rates. While I still think this stock has some attractive features, it hasn’t done enough to get the thumbs up from me.
Paul’s Section:
Hunting (LON:HTG) (Paul holds)
Down 5% to 408p (£672m) - H1 Results & Contracts - Paul (I hold) - GREEN
Hunting PLC (LSE:HTG), the global, precision engineering group, today announces its unaudited half year results for the six months ended 30 June 2024.
The headline numbers look good -
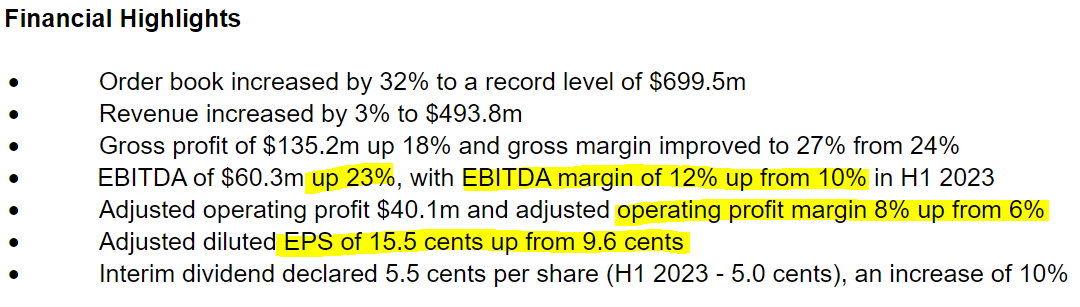
Decent H1 profit growth, combined with a reassuring in line outlook statement, so I expected (as did some brokers in pre-market indications) HTG shares to rise today, but instead they’ve fallen 5%. Why?
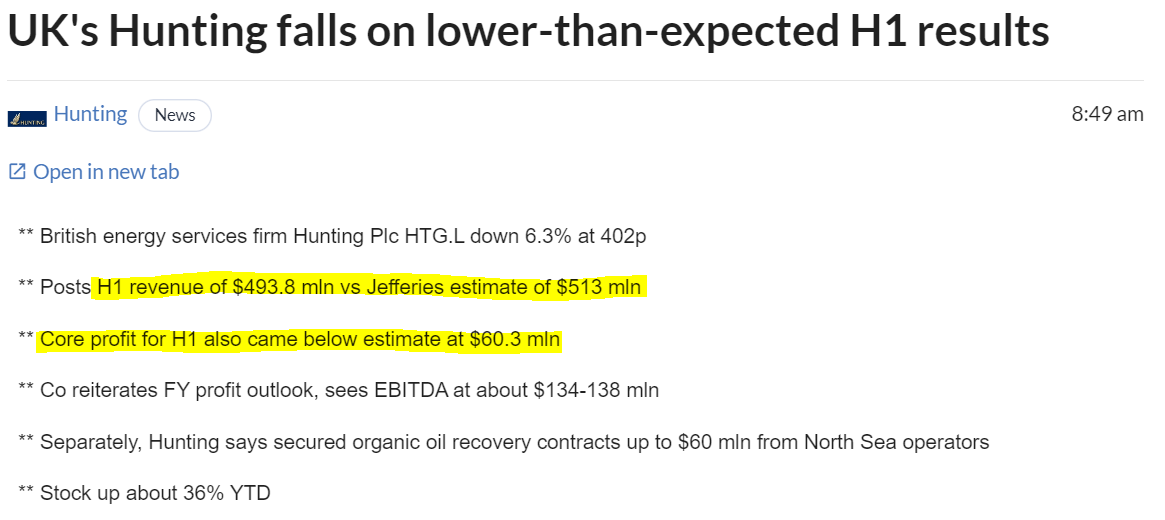
The news snippets on Stockopedia news are the first place to look, and we have this item indicating that Jeffries expected better H1 figures -
Full year outlook - is unchanged, and was raised in July 2024 -
“As noted in our July 2024 Trading Update, Hunting has raised its 2024 full-year EBITDA guidance to c.$134-138m, reflecting the impact of the Kuwait Oil Company ("KOC") orders to be delivered prior to the year-end, offsetting trading headwinds seen in the Perforating Systems product group. The KOC orders will continue to be worked through during H1 2025, which supports a positive outlook for the Group's trading well into 2025…
In summary, the Board remains comfortable with current market consensus with the overall outlook positive given the activity levels across multiple regions and product groups and the diversity of Hunting's portfolio.
H1 EBITDA of $60.3m actual, means H2 needs to deliver a higher $73.7m-$77.7m to achieve the July guidance. The way I look at it, they wouldn’t have raised guidance in July if unsure about achieving it, and it’s been reiterated today, so this supposed H1 miss doesn’t worry me. Also Canaccord says H1 was in line, so we have conflicting views from brokers today.
Watching the (excellent) IMC webinar this morning, management are clearly confident about the full year guidance, and mentioned that the order book supports their growth expectations for H2.
Perforating systems division (which makes things like explosive charges for drilling, mining) has been the problem area, with a poor H1 performance seeing profits drop sharply to not much above breakeven. This is due to soft demand in the US, so they have restructured it with fewer staff, and merging two facilities. This has masked superb performances in some of the other growth divisions. Watch the webinar recording for a run through the impressive performances in some other divisions, and the growth opportunities in higher margin areas, it certainly impressed me.
Strategic aims & targets (called Hunting 2030) are progressing as planned. Eg, EBITDA margin has already risen to 12%, with a target of 15%+
Broker note - thanks to Canaccord for its update. It says H1 results were in line, different to Jeffries who expected higher figures seemingly.
For FY 12/2024 Canaccord estimates adj & diluted EPS of 42 US cents (over double 2023 actual), so 31.8 pence = PER 12.8x
Another big rise to 61 US cents is pencilled in for FY 12/2025 (given the record order book and big Kuwait contracts that looks feasible) or 46.2 pence, giving a 2025 PER of only 8.8x - that’s clearly the wrong price for a decent quality business, in my opinion, with no debt too (it’s expected to have £30m net cash at year end).
Balance sheet - I don’t like the way Hunting reports a summary, and you have to click through a link to get the full accounts. That’s not good practice, why would any company do this? Anyway it doesn’t matter because the balance sheet is absolutely superb. NAV is $971m, including intangible assets of $194m, so NTAV is $777m, or £589m. That supports almost all the market cap of £672m. I think this makes HTG vulnerable to a private equity bid, since they could finance maybe half a £1bn takeover bid (c. 50% premium) by loading it up with debt. So I would say the chance of receiving a takeover bid here looks quite high, an added attraction for private investors/traders. But that’s pure guesswork of course.
Cashflow statement - nothing untoward. There was a build-up of working capital in H1, but management say this should improve in H2.
Paul’s opinion - I think there’s lots to like here, having spent most of the morning going through it all. The IMC webinar today was really informative, so I urge you to look at the recording once it’s up (probably tomorrow). It was only 30 minutes, but gave an excellent overview of the group, and its performance, and some Q&A too. I took notes, and always write a conclusion about my view of mgt, and what to do with my holding. In this case I’ve noted down: CEO & CFO both good, and buy more! Obviously as always just my personal view, not a recommendation, as we do our own research here, and take responsibility for our own portfolios.
I cannot see why the market is only giving this decent quality business, making improving margins, with a bulletproof almost debt-free balance sheet, a 2025 PER of only 8.8x? It just seems the wrong price. Maybe there are worries about sustainability of higher profits, or dollar strength, and the cyclical nature of the oil/gas markets which produce over 90% of Hunting’s revenues? For me that is offset by the specialist & innovative nature of HTG’s products, eg N.Sea contracts announced today are really interesting, where HTG has spent several years developing a specialist method of extending the life of oil wells, and efficiently extracting the remaining resources from older oil wells. HTG has over 500 patents protecting its tech, hence the decent & improving margins. That sounds lucrative. It’s now started winning some decent sized contracts oil recovery, eg $60m over 5 years announced separately today. That could have obvious growth potential. Similar things were said about other divisions, where HTG also has proprietary, and high margin products & services.
This looks very good I think, and cheap, so it’s a shiny bright GREEN from me. Bear in mind I hold personally, and want to buy more when funds are available, so I am clearly biased. Or to put it more accurately, I think it’s really good, so have backed my view with my own money.
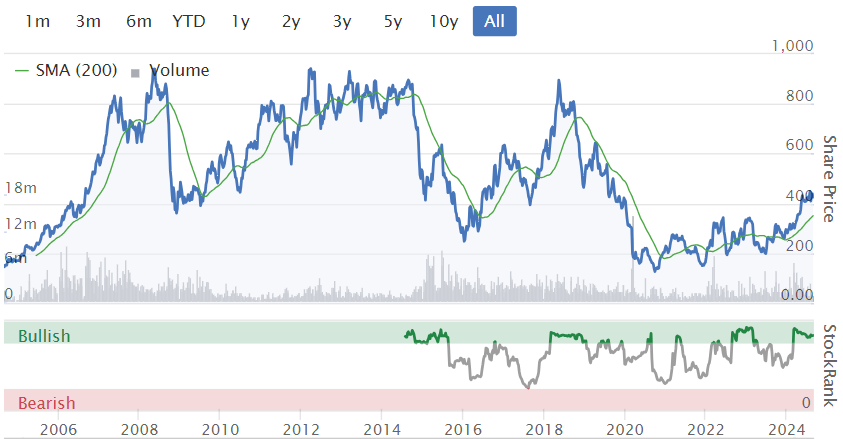
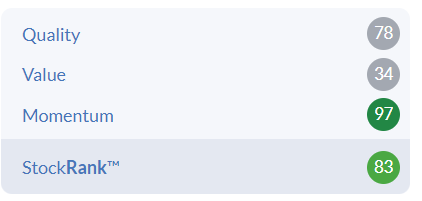
Stockopedia likes it too, so it gets approval from man & machine. Nice looking chart too.
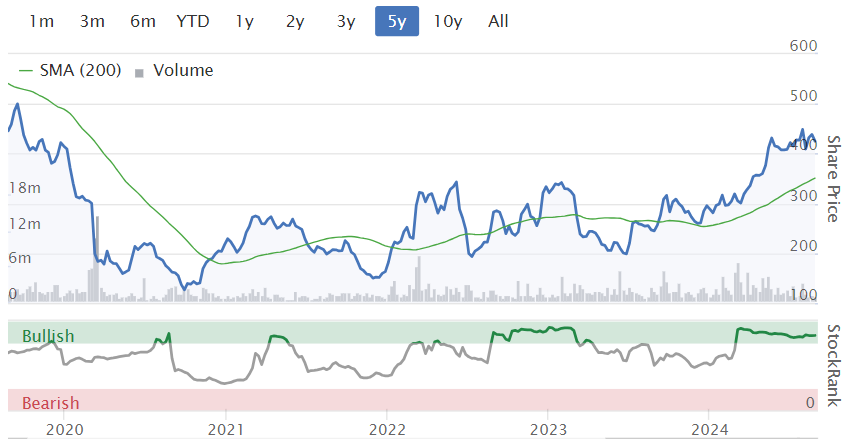
As the CEO pointed out today, last time revenue & profit was at the 2025 expected level, the share price was double the current level. There hasn't been any dilution either. All of which reinforces my view that this share maybe has medium term potential to recover further to possibly 600-800p in due course? Who knows though, anything can happen with shares, as you know!
Graham’s Section:
PPHE Hotel (LON:PPH)
Down 3% to £13.30 (£558m) - Interim Results - Graham - GREEN
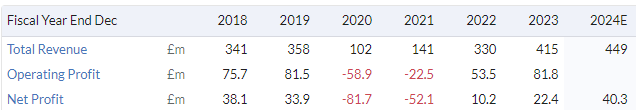
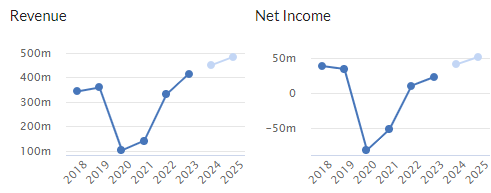
This hotel owner-operator has been enjoying a pleasant recovery in financial results in the post-Covid era and is now making record revenues:
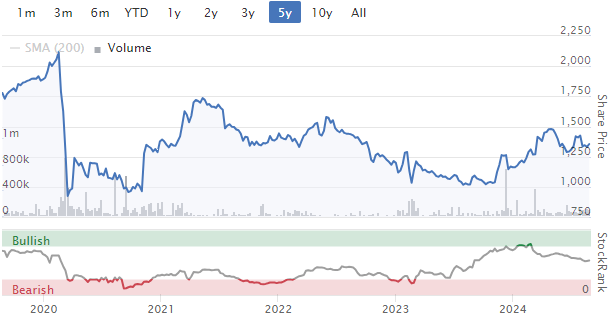
The share price still has some distance to travel, to get back to the levels of early 2020:
Here are the highlights from today’s interim results:
Like-for-like revenue up 4.3%, total revenue up 6.1%. London flat, all other territories growing.
Like-for-like EBITDA up 10.9%, total EBITDA up 7% (negatively affected by new hotel openings).
Like-for-like revenue per available room (RevPAR) was very slightly lower at £109.9 (LY: £110.3). This key metric has declined due to average room rates falling (down 4.4%), offset by higher occupancy (from 69% to 72%).
Interim Dividend: increases from 16p to 17p.
Net reinstatement value (NRV) per share (a standard measurement of balance sheet value): declines slightly due to FX movements and dividend payments, but at £26.24 is still nearly double the share price.
As we covered here in July, PPHE thinks that a good response to the share price discount vs NRV is to buy back its own shares, and has launched a £4m buyback, the second of the year.
New hotels: a £300m pipeline is being delivered - in London, Rome, Zagreb, Belgrade and Berlin. Planning approval received for another new London hotel (South Bank).
Current trading/Outlook
The key sentence here is:
Excluding new openings in the year, the Group's like-for-like1 performance remains in line with expectations.
New openings are being held back by “certain supply chain issues”, causing delays to openings in London and Rome. Positive EBITDA from these projects will therefore not commence until 2025.
Graham’s view
Readers will know that we don’t cover hotel chains very often here (the other one I like to review is Dalata Hotel (LON:DAL)). But the asset value here has caught my attention, and the 50% share price discount to NRV says to me that someone is wrong: either the stock market is wrong, or the calculations are wrong.
NRV is designed to calculate the value of the company’s balance sheet, where properties are valued based on the cost of rebuilding them, not on historic cost. As of June 2024, this figure for PPHE stands at £1,117m (NRV is stated after deducting net debt).
The market cap of £558m says to me that the stock market thinks PPHE’s properties would probably not be worth rebuilding. This seems overly pessimistic to me.
There is admittedly some financial risk included with this company, which carries gross borrowings of £900m and net debt of £765m.
The H1 income statement shows that financial expenses (£19m) did eat up a large portion of the company’s EBIT or operating profit (£25.4m). After all expenses, the company did fail to make a positive PBT (I would prefer if PBT was the headline, rather than EBITDA).
I’m going to continue giving this one the green light, based on my belief that its assets are undervalued, but it does need to follow through with real profits if I’m going to keep my positive stance. Hotel openings are very expensive, and it takes time for them to deliver profitability, so personally I do think PPH deserves a grace period from investors as it delivers its £300m pipeline.
My big-picture view is that PPHE’s post-Covid recovery is succeeding:
Somero Enterprises (LON:SOM)
Down 3% to 297p (£163m) - Interim Results - Graham - AMBER
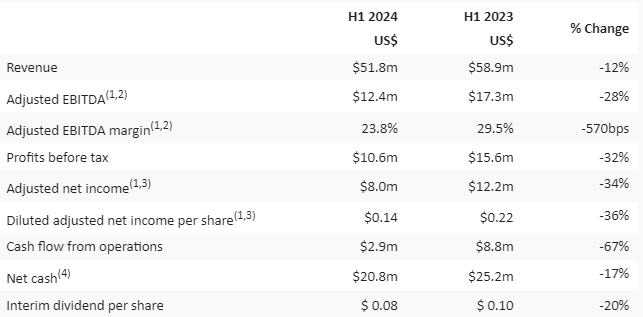
The numbers here are grim, as expected:
Paul covered Somero’s profit warning in July, when it became clear that the company was headed for a poor H1.
Let’s skip ahead to the outlook statement. Somero says that the non-residential construction market “remains healthy” and issues unchanged guidance:
The Company anticipates improvement in H2 2024 trading in compared [sic] to H1 2024, driven by a combination of new product revenue growth, including the launch of a third new machine, and an expectation of improved weather conditions. This confidence is supported by our primary means of gauging market health, which is direct feedback from customers.
As such, the Board remains confident that 2024 results will fall in line with the revised market expectations published following our 30 July 2024 Trading Update, with revenues of approximately US$ 110.0m, EBITDA of approximately US$ 30.0m, and year-end cash of approximately US$ 27.0m.
It’s a bold statement considering H1 revenues of only $51.8m and H1 adj. EBITDA of only $12.4m. To hit forecasts, the company will need H2 revenues of $58.2m and H2 adj. EBITDA of $17.6m.
Estimates: thanks to Cavendish for issuing a note today with confirmation that there is no change to 2024 guidance. For FY25, they would “conservatively assume a flat revenue year”.
CEO comment:
"I am pleased with how the Company has navigated the challenges presented by the first half of the year. While revenue decline in North America and Australia impacted performance, our focus on operational efficiency and the enduring nature of our long-term growth drivers ensure we are well placed for when conditions improve…
"Looking ahead, the resilience of the non-residential market gives us confidence that, as external challenges subside, our performance will improve…
Regional overview
North America - sales down 8%. Healthy project levels for customers, but “they are not operating at full capacity due to project start delays and pauses caused by elevated interest rates”. No mention of competition.
Europe - sales up slightly.
Australia - sales down 40% (from a low base).
Rest of World - sales down 39% (also from a low base).
Cash flow comment - operating cash flow was much lower ($2.9m vs £8.8m in H1 last year) and the company mentions an increase in inventories “as a result of lower sales unit volume and product mix”. Checking the balance sheet there was an almost $5m increase in inventories , from $19m to $24m.
Cash falls from $33m at the end of 2023 to $20.8m at the end of H1.
Graham’s view
I was happy with AMBER/GREEN last time, but my inclination currently is to be AMBER due to what I perceive as a significant risk of the company failing to hit full-year forecasts, with higher inventories being another warning in this regard.
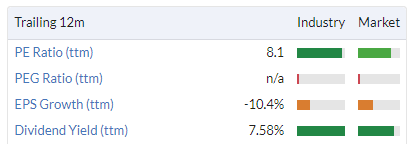
For a company with a great track record of profitability and excellent quality metrics, this may be a little harsh:
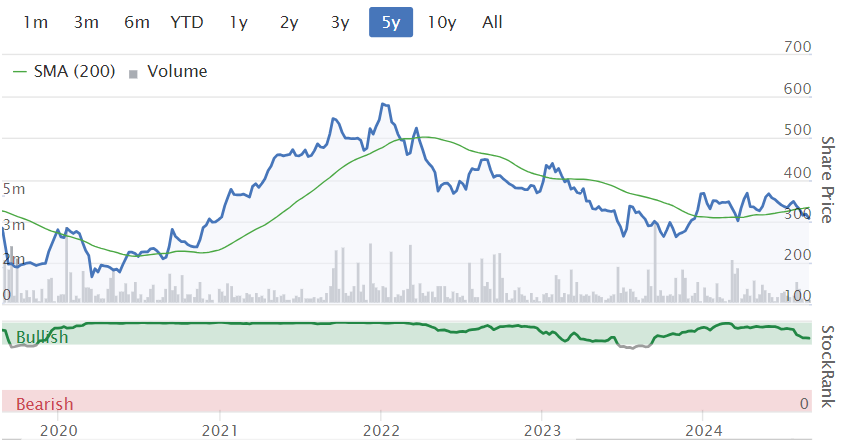
However, I’m concerned that tougher competition may also be a reason for Somero’s difficulties. The company has been around for a long time and it hasn’t grown as much as I would have hoped - and now it’s going in reverse again. So I’m just not seeing enough here to get me excited about the prospects for investors.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Hunting (LON:HTG) - Onwards and Upwards - new research report freely available here: https://www.equitydevelopment....
One year on from Hunting’s 2030 Strategy launch some good progress has been made towards these long-term targets in mixed market conditions. H124 EBITDA came in at U$60.3m (+c.23% y-o-y), in line with pre-close commentary.
Successful order execution in International and Subsea markets more than offset largely weaker North American oil and gas demand. An elevated order book position, re-affirmed EBITDA and year-end net cash guidance (both raised at the end of H1), together with a 10% interim DPS uplift, all project a confident outlook.
Strong H124 EBITDA increases from Subsea, OCTG and Advanced Manufacturing operations were partly offset by a lower Perforating Systems’ contribution, but good y-o-y and sequential progress was achieved by the Group overall, sustaining recent trends.
Hunting’s c. U$700m order book position at the end of June supports our unchanged core profit estimates, albeit on slightly lower FY24 revenues factoring in current Perforating Systems’ run rates. We now include JV/Associates in EBITDA, consistent with the revised company presentation, and have trimmed the current year contribution here largely to reflect the India JV start-up position.
Hunting’s c.40% YTD share price uplift was effectively attained in May - including a boost from OCTG orders at that time – and has largely traded in the 400p-460p range subsequently. Having significantly outperformed its peer group, valuation metrics are now more aligned with these peers on an FY25 P/E basis but remain on a c.20% EV/EBITDA discount.
Successful delivery of the KOC OCTG orders over the next nine months is an important near-term focus. Ongoing material order success and improving visibility at higher levels of profitability in the medium term and beyond will be the key drivers of future share price performance and we leave our existing fair value of 436p / share unchanged for now.
After 26 months the yield curve inversion (10 yr and 2yr) finally ended yesterday https://fred.stlouisfed.org/se.... US recession is likely coming given the contraction in money supply according to Professor Steve Hanke.
Steve Hanke is well worth listening to on YouTube if you ever get a chance. Of course, Central Bankers don't like him talking about money supply as it points the finger towards their money printing as the cause for inflation. I think Steve Hanke is probably correct, personally.
Most people don't have 26 months worth of patience, that's for sure. I'm still sceptical of the argument that "this time its different" despite the very long lag. Time will tell who is correct on all of this macro stuff!
the write-up about Hunting (LON:HTG) was interesting and informative. But as an amateur investor, I'm constantly told by the pundits to pay considerable attention to ROCE. And this seems to make sense. Many of the metrics of Hunting seem good, but it has a consistently low, or very low, ROCE. Should I worry about this?
the write-up about Hunting (LON:HTG) was interesting and informative. But as an amateur investor, I'm constantly told by the pundits to pay considerable attention to ROCE. And this seems to make sense. Many of the metrics of Hunting seem good, but it has a consistently low, or very low, ROCE. Should I worry about this?
In a word, no. ROCE on its own is not everything and as with the case of Hunting (LON:HTG) it is merely indicating a whole sector with poor profitability metrics rather than a poor company; it’s a competitive industry where companies tender for work against each other generally, so you would expect somewhat limited margins and profitability. Look at the historic gross margins of the sector… pretty awful really. Look at the amount of capex needed; which in turn makes cash conversion poor. Not my cup of tea but sometimes “where there’s muck, there’s brass” :)
I can see Paul is attracted to the forecast earnings growth here and the low rating, but the perception of the sector is that its prospects are tied to the oil price, and it’s difficult to ignore that no matter how well a company is performing operationally. It doesn’t seem like Paul’s typical type of investment to me, but wish him all the best with it.
Bank Georgia / Georgia Capital
Not moving in sync at moment
Bank of georgia worth 2.05 billion
Georgia capital worth 417 million but owns 20% of bank of georgia plus its ither assets
So about 15 million apportioned to other assets .
Anomaly getting stretched so either Bank of Georgia to pull back or G Cap to catch up
Not for everyone due to geopolitical risk
planetx- The elections look like they could be very confrontational-" Georgian Dream already saying opposition parties getting Foreign financial support. I sold BGEO today as getting nervous and was up 11% from recent purchase. Going to keep a close eye on the polls.
As the CEO pointed out today, last time revenue & profit was at the 2025 expected level, the share price was double the current level. There hasn't been any dilution either. All of which reinforces my view that this share maybe has medium term potential to recover further to possibly 600-800p in due course? Who knows though, anything can happen with shares, as you know!
Paul RE:Hunting (LON:HTG)
Not a company I’ve ever looked at before as I normally avoid companies associated with the O&G sector based on past bad experiences, although one success in the services sector was Kentz Corp, so thanks for highlighting this idea. It does look mispriced on first glance and worthy of further digging.
Personally, I don’t like management talking about share prices, but assume he had no choice other than to do so on the IMC call. I’d suggest, without looking in detail, and in common with most companies in this sector, that the share price is pretty correlated to the WTI Crude price and that the most likely reason for the higher historic share price was that it occurred during periods when Crude was $100 USD/bbl. And that’s the problem for me… you need to take a view on the future WTI price.
All the best, Si
I held Kentz back in the day. As I recall private investors were pretty miffed at the low takeout price.
I held Kentz back in the day. As I recall private investors were pretty miffed at the low takeout price.
It was 10 years ago, so I can’t remember the takeout multiples now. It looks like the premium was around 30% above the prevailing market price at the time. It was a multibagger for me in the 4 years I held it, so I wasn’t too disappointed, but yes, the premium could have been higher even bearing in mind the WTI price was > 100 USD/bbl at the time.
Good morning. I picked up several comments on Warpaint London (LON:W7L) late yesterday, and for reference before I make my comments
I put yesterday's comments up here now. Please be patient and scroll down to mine today at the end.
proffittpar Joined 2016 58 posts Yesterday 1:13 pm
Warpaint London (LON:W7L) - Some significant movement in the share price over the last week or so, its drifted down from £5.90 to £5.35 back up to £5.90 and then in last couple of days sunk down again to £5,40. Is this Market Makers playing games, forcing stop/losses through, or a general perception weakness in the market with a read across to other reports increased freight costs, warehouse employee costs, any opinions, good buying opportunity?
simoan Joined 2009 1,508 posts Yesterday 1:27 pm
Warpaint London (LON:W7L) - Some significant movement in the share price over the last week or so, its drifted down from £5.90 to £5.35 back up to £5.90 and then in last couple of days sunk down again to £5,40. Is this Market Makers playing games, forcing stop/losses through, or a general perception weakness in the market with a read across to other reports increased freight costs, warehouse employee costs, any opinions, good buying opportunity?
It sounds like you’ve spent too long reading threads on ADVFN. Market makers playing games? Really? All they want to do is balance their books based on supply and demand. I hope dealtn (I believe a former market maker IIRC) doesn’t see your post :)
I would just chill and stop trying to analyse short term share price movements. That way madness lies.
proffittpar Joined 2016 58 posts Yesterday 1:45 pm
Thanks Simoan sentiments appreciated will try and do, I am a long term holder of stocks and don't do day trading just find frustrating when one of the few stocks that I have that has appreciated in value drops!
Peter T Joined 2021 137 posts Yesterday 2:15 pm
Warpaint London (LON:W7L) proffittpar, Schroders have been selling Warpaint so maybe they are still at it. They have been buying another cosmetics company Creightons (LON:CRL) maybe thinking they can be the next Warpaint.
Pimlico on Thames Joined 2012 115 posts Yesterday 4:18 pm
Creightons (LON:CRL) is a United Kingdom-based company that is engaged in the development, marketing and manufacture of toiletries and fragrances,
which includes the development of brands. The Company offers a range of
toiletries, skincare, hair care, fragrances, and home fragrances. Its
operations are organized into three business streams: own branded
business, private label business and contract manufacturing business.
This stock peaked at 130p on the pandemic demand for cleaning and self pampering, after which it slipped back to 2017 - 2019 range following PW in July 2022 when dividend was suspended. MD sacked Nov 2023 and Chair/CEO retiring in March 2024. Latest FY announced in July saw loss due to write down of pandemic acquisition and dividend reinstated.
I hold a small position and see this pausing at 50p as it recovers.
I also hold Warpaint London (LON:W7L), which I top sliced at 580p after the recent pull back
Now for what you have been waiting for!!!
First, the Schroeder reference. Schroeder have been reducing their shareholding by the odd 1% for many months, even during the peak period of Trading statements when Warpaint London (LON:W7L) were issuing them with forecasts of even better figures than expected before. In 2023, there were the Interims 20/9; Trade Up 10/11, Trade Up 12/1; Trade Up 9/4
Next, perhaps the recent bombshell from Keir Starmer made those with large Capital Gains like Warpaint London (LON:W7L) run for cover, top slice etc. Not surprising.
However, we are approaching the company's Interim's for this year; the indications of the success (or otherwise!) of focus on the US with a new US exchange offering aimed at US investors, upcoming orders for the festive season and dare we hope for a series of similar Trade Ups for this year. None forthcoming so far, but there weren't any before the Interim's last year either.
We will see. In the meantime, I am a holder. I did top sliced in the last, and then bought back at and 'lost' several £000 in the process.
I don't see the relationship between Schroders gradually reducing their stake in Warpaint London (LON:W7L) and investing in Creightons (LON:CRL) as being particularly significant. I certainly don't plan to invest in the latter. Good money after questionably weak/bad?
Regarding market makers, you'd do well to watch this video from a few years back from PI World; https://www.piworld.co.uk/educ...
Market makers absolutely do move the share price around during quiet periods, for any number of reasons;
- They can 'tree shake' if they think a share has run too far and they want to back test support
- If they want to stimulate trading (and earn money via the spread) they can also do this
- If a broker has a large order to fill in an illiquid AIM stock and they need to generate some selling, again the answer is to drop the price and 'work' the buy
- If a broker is short of stock due to a period of high demand, dropping the price will help to resolve this and vice versa
There are likely many more reasons, however telling people that all a market maker wants to do is balance supply and demand does a disservice to them & is naive to reality.
The decline in revenue & profits continues for Somero Enterprises (LON:SOM) , though in line with expectations. A lot of the decline is blamed on poor weather & concrete shortages in the USA & Australia.
I continue to hold from my value investing days. I think when or if they return to growth there is a lot of upside potential here & the dividends are a nice bonus while waiting. I would like to see their cash stop declining though, that is getting a little concerning.
Somero Enterprises (LON:SOM)
i hold too and struggle to take todays update as being overly positive - they are obviously going through tough times so commenting at low point in cycle doesnt help i must admit.
ref comments on new products beginning to gain traction - well no they arent really - gaining traction would imho be something multiples above what they are delivering. I may be unduly harsh here and and happy to be corrected - perhaps they need to ramp up slowly to ensure that when they do "mass deliver" the product will be robust and not let them down - one would like to think their customers would be waiting with baited breath for new products that work and and their experience would mean its all good to go. seems to me they are p ssing in the wind ref getting new products to work. Perhaps i am being over critical here - from 0.8$ mill to $3 mill - is decent expeonential growth - it is still peanuts though and thats my point here.
Other than that it just seems like they have the same old tickover work without the benefit of the peak "lets build new giant warehouses quickly at any cost" that did exist for a while.
I have no plans to sell today despite my above comments - at least they still expect improvement in h2 and thats the most important thing even with my above gripes.
Hi rmillaree, fair points & I completely agree with your sentiment that the overall contribution from new products isn't much to write home about and needs to be a lot higher for long term sustainable growth.
Though in terms of traction, 288% growth in sales for those new products over the last year is pretty decent & if they can continue that, or even half that number, it wouldn't be long before it is a very meaningful contribution to total sales. I will certainly be keeping a keen eye on that number & if it falls considerably that could well persuade me to sell. I think the really telling factor will be if new product uptake improves when their trading conditions improve. I can't imagine their customers will be that keen to try new products while they are struggling with concrete shortages, inflation pressures and project delays.
They do make comment that their new electrical laser screen is struggling to gain traction in the USA & Australia, but is seeing strong interest & uptake in Europe, where they are more environmentally conscious. Perhaps they need to be a bit more focussed with where they target new products to save on sales & marketing costs.
on Somero Enterprises (LON:SOM) - i hold - thanks - and continue to hold on the belief that there will be a lot of industrial expansion in the US etc as both parties seem to be keen on cutting out china / reshoring jobs.
On your checklist - is it home grown or sourced from somewhere.
Hi Andrew. The checklist in itself is home grown, it's changed over time as my investing style has changed & I frequently tweak it to find the best results. Personally I find a checklist useful to narrow down my pool of potential investments and made my own checklist to fit my investment style.
The idea of the checklist & what goes in to it however is completely unoriginal. I've taken inspiration from many sources, but in it's current form it's mainly influenced by William O'Neil's CANSLIM strategy, as well as Mark Minervini's & Stan Weinstein's books, with some other quality metrics thrown in.
Gulf Keystone Petroleum (LON:GKP) 2024 Half Year Results Announcement:
Positives: Returned to profitability and free cash flow generation in H1 2024, with gross average production increasing by 69% to 39,252 bopd. They've maintained a strong safety record and improved operational efficiency, reducing gross operating costs per barrel by 25%. The adjusted EBITDA rose by 6% to $36.4 million, and $25 million was returned to shareholders through dividends and share buybacks. The cash balance increased to $102.3 million.
Negatives: Revenue decreased by 11% to $71.2 million due to a significant 49% decline in average realised price to $26.3/bbl, reflecting the transition from exports to discounted local sales. Kurdistan export pipeline still closed, leaving over $150 million in outstanding receivables (could be seen as a positive). Uncertainty surrounding the restart of exports and normalisation of KRG payments, as well as concerns about longer-term local market dynamics. Additionally, planned maintenance in November 2024 will temporarily impact production.
Gulf Keystone Petroleum (LON:GKP) has generated $40m of free cash flow (FCF) in the 8 months YTD and although November may be a touch weak due to maintenance and capex somewhat higher in H2, I am assuming it will generate $60m of FCF in 2024 as a whole. This puts the market cap on around 6x 2024 FCF and with $100m of gross cash with no debt the EV is only just over 4x 2024 FCF. Furthermore there is upside in that the Turkey pipeline could get reopened - in theory doubling revenues - plus the upside if/when the KRG pays the $150m of so far unpaid receivables.
The stock is only so cheap because of the obvious political risk - where it is entirely possible to imagine to waking up one morning and hearing that all production has been stopped by somebody The company also clearly feels something similar saying on today’s call saying that they want to be sitting on about a year’s costs in cash - just in case (so around the current $100m.)
The key part of the valuation where I am unclear is what happens in a few years time when the “cost oil” is exhauseted and Gulf Keystone Petroleum (LON:GKP) ’s entileme t to the Shaikan field falls from 36% Slide 17 in today’s presentation (appendix) is helpful but I still do not really understand this Can anyone help on pointing out where this mechanism is spelt out?
Diageo (LON:DGE the read across from a well-received TU by Pernod Ricard SA (EPA:RI) suggests that the name may have bottomed. It’s not a very exciting share, but the portfolio of brands is high quality and shares are cheap next to history. It’s no good comparing the PER with small cap multiples. This name trades in a higher range - and deservedly so. For those that want to get rich slowly and surely, this looks a good entry to me - although I prefer the French competitor not just on a comparison of Jameson vs Jonny Walker, but also on what I perceive to be a slightly better potential upside.
Diageo (LON:DGE)
my one worry for company like Diagio is if there is astructural shift by consumers away from "big corporate brands" to niche products - seems like there is bordering on unlimited different amount of brand names competing for the attention of bar owners and consumers. Ok their products are never going to go away - but compared to 2019 net debt has ballooned not far off 50% according to stocky (are there fake lease liabilities perhaps?) - while profits have hardly shifted - that sounds like a company to me that needs to be splashing the cash to stay still.
One would always worry that if they bury their head in the sand and use debt as way to "keep profits up with the jones" could they at some stage hit the wall with regard ovoiding the issue that they cant grow peofity withoiut debt increasing?
My comments and very uninformed here above is all wild speuclation on virtually no research - quite like the thought of buying solid brand companies now at the right price if the debt isnt the issues it loooks like it might be. Note debt doesnt have to be unafordable to be an issue.
Diageo (LON:DGE the read across from a well-received TU by Pernod Ricard SA(EPA:RI) suggests that the name may have bottomed. It’s not a very exciting share, but the portfolio of brands is high quality and shares are cheap next to history. It’s no good comparing the PER with small cap multiples. This name trades in a higher range - and deservedly so. For those that want to get rich slowly and surely, this looks a good entry to me - although I prefer the French competitor not just on a comparison of Jameson vs Jonny Walker, but also on what I perceive to be a slightly better potential upside.
I would agree, although I can’t help thinking some of Diageo’s issues are more self inflicted and operational in nature. And of course, the balance sheet is pretty ropey compared to Pernod. Slightly OT here but thought it worth noting that Diageo (LON:DGE) has gone ex-dividend today for anyone comparing relative share price movements.
Morning all, here's my snapshot for Hunting (LON:HTG) interim results.
Impressive bottom line growth, though decelerating from the huge growth they have experienced in the recent past. My checklist score, which is based on growth & momentum, has decreased from 40 to 36 with these results. Still a pass & on my watchlist though. Looking for the share price to break through 462p.
With Paul's undoubtedly more in depth review upcoming & possibly more detail to come from the Investor Meet presentation, I'll leave it there.
Yes the revenue growth numbers look impressive. My reservation with Hunting (LON:HTG) is the weak cash flow since the recovery began. This is partly explained by the need for more working capital as orders come through but the cash figures still look weak to me. It will be interesting to hear Paul's thoughts.
Quiz (LON:QUIZ) results this morning do not read well, with CEO putting a lot of the blame on 'cost of living' pressures. I have two family members involved in the mid price women's fashion trade who both tell me that after a number of years Marks and Spencer (LON:MKS) have really got their act together and are performing incredibly well in that space. I do wonder if this is having more impact than smaller competitors like Quiz or perhaps Sosandar (LON:SOS) realise or are prepared to admit.
I went to an out of town M&S the other day, and there were quite large queues for the Pay In desks. I think they've hit their stride on clothing offering all ages attractive and reasonably priced clothes. I bought two pullovers (no change there!), and my wife bought a top and some fashionable jeans, and was very happy. I can easily imagine young people looking to get smart, good value clothes as well as the older customers.
The fact that there is talk of opening M&S clothes only stores does tend to suggest they are feeling more confident as well as looking for higher margins, though I think mixing the footfall with their foodhalls is a sensible hedge strategy.
Women’s market is enormous - Marks and Spencer (LON:MKS) have most certainly hit their stride but that doesn’t mean there isn’t more than enough room for the smaller or larger fashion businesses. It is strategy and execution, not market share that are having the impact.
Trends are changing - up cycled, vinted and hand made clothing are growing markets - very small businesses offering these products but lots of them - prices considerably higher than fast fashion but considerably lower than designer.
People are also shopping less directly on-line and more experiential - to be fair Next (LON:NXT) got this trend exactly right way before everyone else - I remember when Next (LON:NXT) were on a PER of less than 10 with analysts pouring scorn on their outdated business model, bricks and mortar outdated concepts whilst loving online. Next (LON:NXT) were right and the massive rise in their share price reflects that. The fast fashion brands all missed the trick.
Quiz (LON:QUIZ) needed a reset - they may or may not get that with the new CEO. Younger, more dynamic, more in tune with market trends…..but jury is out….too early.
Sosandar (LON:SOS) at least recognised it (if a bit late) and have switched to omni-channel, but again lets see how that plays out. You need a decent number of stores really - you want your customers ordering online, trying on in a shop, finding a different size when it doesn’t fit and walking out with an extra garment or two they liked the look of whilst they were in there in order that you get the efficiencies of the model. 3 stores won’t achieve that - 30-50 might.
More management upsets, this time at PRS Reit (LON:PRSR) where Harwood want to remove Chair Stephen Smith, plus Steffan Francis.
Shares up 6% on this news. Unfortunately, I sold a few weeks back just before the recent 20% SP spurt.
The after hours moves in the US, following NVIDIA (NSQ:NVDA) quarterly results, suggest we are going to have a pretty volatile afternoon regardless of our local performance. I imagine that many here are what Starmer would characterise as the “broad shoulders” necessary to support the government’s enthusiastic spending of other people’s money. My confidence in the UK’s recovery/growth is draining away.
Well, I suppose it makes a change that they're spending other people's money, rather than printing their own :-)
my feelings too
I agree, according to Jeffries Matt Hose, if that ham sandwich man Starmer employs, builds on the UK offshore wind capacity assumptions, projected power prices could fall by over 15% between September 24 and May 2027. Terrible for pensioners and British industrial prospects!
Nvidia sold off a little as the expected growth was correctly modelled by a bunch of highly paid analysts.Perhaps it's 'peak Nvidia' for a while now...? Investors have officially now bought the dip.
On another note ..Octopus Group has discreetly invested £25m of its own funds into London's struggling AIM market, seizing the opportunity to capitalise on what it sees as "mispriced" smaller companies."
This is mispriced. We're really comfortable and confident in the outlook for [the market]," Rogerson told City AM, highlighting the firm's long-standing experience with the market. "We've been running money in that market for the last 15 to 20, years, and we are very high conviction."
Kinovo (LON:KINO) management must be licking their wounds after yesterday's AGM, where only 3 resolutions passed and 5 were voted down, including re-election of the auditors. [I hold]
The Annual General Meeting of Kinovo plc was held on 28 August 2024 at 12:00pm at the offices of Hudson Sandler, 25 Charterhouse Square, London.
All Resolutions, as set out in the Notice of Meeting dated 2 August 2024, were voted by way of a poll. Resolutions 1, 2 and 4 were duly passed at the AGM.
The Board notes that resolution 3 in respect of the re-appointment of Moore Kingston Smith LLP as auditors of the Company was not passed. The Board will make a further announcement confirming next steps as soon as practicably possible.
In addition, the Board notes that resolution 5 in respect of authorising the Long Term Incentive Plan (on an advisory basis), resolutions 6 in respect of authorising the Directors to allot shares in the Company and resolutions 7 and 8, in respect of authorising the directors to disapply pre-emption rights, were not passed and that a significant proportion had voted against these resolutions. The Board will continue to engage in discussions with shareholders to better understand their views.
Tracsis (LON:TRCS) A relatively positive update, looks like the last warning is confirmed as a more of a timing bump rather than a 'de-railment.....'
However I was hoping the comment further down about a drop in revenues of £5m in FY25 would hit the shares enough to present a buying opportunity but I guess tightly held with few sellers..
A quality stock but still rated a bit too highly for my liking, it stays on the watch and wait list.
Tracsis (LON:TRCS) I was hoping the comment further down about a drop in revenues of £5m in FY25 would hit the shares enough to present a buying opportunity but I guess tightly held with few sellers.
Patience might be rewarded here as the lack of a bounce on an otherwise reassuring update might presage a drift over subsequent days. I bought half a position down near £6 and would buy some more at those levels, if the opportunity presents itself.
Good morning Paul
Can you cast your eye over Hunting (LON:HTG) half year results out today, preferably after seeing the presentation on IMC this am?
Looks pretty good to me with all the metrics going in the right direction
Thanks
I hold
Morning Threepeat, yes I'll be looking at Hunting (LON:HTG) first, as it's on the "most viewed" list (by Stockopedia subscribers), as flagged. I also want to watch the IMC webinar which starts at 10:30.
Regards, Paul.
Aug 29 (Reuters) - British energy services firm Hunting (LON:HTG) posted a 23% jump in its first-half profit on Thursday, buoyed by a strong order book across its oil and subsea portfolios.
The firm reported a core profit of $60.3 million for the six months ended June 30, up from $49.1 million logged last year.
Shares down today presumably due to concerns about govt tax threats. Plus strong £ not helping I guess.
*RBC RAISES HUNTING PRICE TARGET TO 500 (450) PENCE - 'OUTPERFORM'
Morning all, any chance on your thoughts about the GEM diamonds results?
BBGI Global Infrastructure SA (LON:BBGI) - solid results again. For me this c£1bn company is probably the best infrastructure play on the UK market. Top quality and low risk availabilty style investments, no RCF, progressive dividend, low costs and excellent track record. Boring, but dependable!
I agree topvest, I also own in my income fund along with International Public Partnerships (LON:INPP, a sensible Board with a progressive dividend policy, like you say steady and dependable, slow growers
Anyone interested in Resolute Mining (LON:RSG) the H1 report is here:
https://announcements.asx.com....
Synectics (LON:SNX) - CEO has died suddenly. He was instrumental in the growth of the business with 35 years' relevant experience.
Looks like a substantial shareholder revolt at the Kinovo AGM yesterday. I wonder what lay behind that. Auditors sacked and management incentives binned. Ouch!
Sounds like a topic for the Eye!
My morning smallcap tweet: Bitter Topping
Frenkel Topping (LON:FEN) Totally (LON:TLY) essensys (LON:ESYS) KRM22 (LON:KRM) Roadside Real Estate (LON:ROAD) Life Settlement Assets (LON:LSAA) Synectics (LON:SNX), Tracsis (LON:TRCS), Somero Enterprises (LON:SOM), Quiz (LON:QUIZ)
◄Frenkel Topping (FEN)► warns FY-Dec EBITDA 8% below mgmt exp despite rev in line. Blames problems at Partners in Costs in recruitment and technology implementation impacting its ability to handle increased workloads [SP=49.45 Cap=63m]
◄Totally (TLY)► wins c.£4m of contracts and contract extensions. [SP=9 Cap=18m]
◄essensys (ESYS)► guides FY-July rev £24m and adj EBITDA loss £0.9m max, both ahead of market expectations. On track for positive EBITDA and cash generation in FY25. [SP=30.35 Cap=20m]
◄KRM22 (KRM)► wins £0.7m 3 year contract. Also two renewals which net to unchanged ARR. Total ARR now up £0.2m to £6.3m. [SP=34.4 Cap=12m]
◄Roadside Real Estate (ROAD)► gets shot of its 4 remaining pubs, as mooted. [SP=21 Cap=30m]
◄Life Settlement Assets (LSAA)► gets the hoped for $4m (max) overpayment of premiums from acquisition of policies held by the Mutual Benefit Keep Trust. Will accrue to NAV. [SP=1.79 Cap=85m]
◄Synectics (SNX)► CEO dies. [SP=200.61 Cap=36m]
In line: TRCS, SOM, QUIZ
Most subscribers really appreciate your kick-off the morning summaries Mr C.
How do you assemble these so quickly after the RNSs are released whilst also managing to inject humour and witticisms?
Always great to start the day with a smile . . . . .
Howdy Paul
A somewhat belated thanks, but the weekend podcasts continue to be excellent - informative and enlivened by you occasionally going off on one about nontransparent RNS announcements or base corporate stupidity (e.g. your venues are losing money, so why spend shareholders funds rolling-out more of them?).
I do however miss the frisson of excitement and intrigue around mystery share reveals.
I will give to Zane by way of thanks.
Good morning The Jayman,
Thanks for the nice feedback, appreciated! (we all like a pat on the back after all!)
Point taken re mystery shares, I've made a note to do those again (and I'll reveal the identity in a comment in the previous Friday's written SCVR). I'll now be able to borrow Paul Hill's phrase "by popular demand"!
I will give to Zane by way of thanks.
Awesome, that's what I hope some people will do (and others already kindly do), so very much appreciated :-) Especially as founder Tom & Jane (plus dog Moses) are currently doing their umpteenth sponsored walk right now for ZANE.
Tom's quirky & often controversial walking blogs are not to everyone's taste, but personally I find them brilliant (I don't necessarily agree with everything he says). Also note he very much plays to the crowd (as an exasperated pensioner!), in terms of the big donors who are mostly of a certain age - a serious problem for ZANE as sadly the big donors are dying off, so it desperately needs a new cohort of supporters (like us).
Regards, Paul.