Small Cap Value Report (Thu 29 Dec 2022) - BIDS, SOM, FNX, SLP, SAGA, TSLA, RM.

Good morning from Paul & Graham. Today's report is now finished.
Many thanks for your suggestions yesterday. Although I had to laugh at some of the suggestions! But we'll see what we can do, based on the number of your thumbs ups.
Agenda
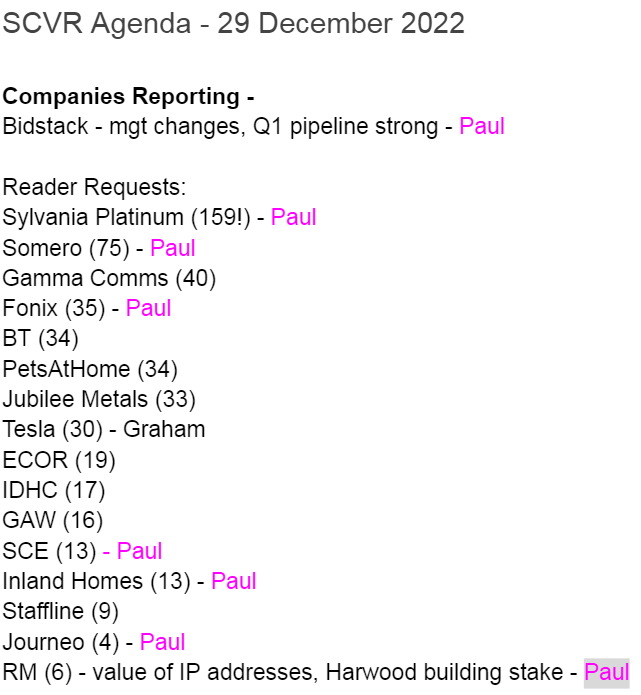
Here's an initial list (below) of yesterday's reader requests, with the number of thumbs ups in brackets. It's not realistic to ask us to look at most of the mid/large caps, as that would take too long researching things from scratch, but I've noted below the small cap ones that I can give a relatively quick view on. Graham's looking at Tesla, as he knows it well and it got a lot of thumbs ups from you (sorry if this triggers anyone, having a mega cap US stock in a UK small caps report LOL! Look at it this way, It's Christmas, and rules are made to be occasionally broken!) -
Paul’s Section:
Bidstack (LON:BIDS) (2.8p - mkt cap £37m) [quick comment] - announces that its Managing Director is resigning, but staying on as a Strategic Adviser. Also, a 13.5% shareholder Irdeto BV, which made a £5m “strategic investment” in Oct 2022 is seeing its CEO become a NED at BIDS. Does this all hint that things might not be going so well, possibly? COO Camila Franklin is joining the main board, and the comments sound as if she’s more experienced than the CEO - maybe he’ll be stepping down next?
CEO comments eulogise on the outgoing MD, and claims that the “business has never been in better shape”, and “...our pipeline of revenue for Q1 looking stronger than ever…”
BIDS raised just over £10m in a 2.85p fundraise in Oct 2022. It raised a similar amount in 2021, and burns cash prodigiously.
My opinion - I’m keeping an eye on BIDS, as it sounds an interesting concept (selling ads within computer games), and there’s been lots of bullish jam tomorrow news from the company, although nothing of commercial substance so far. H1 results in FY 12/2022 remained heavily loss-making. But at least it’s not likely to run out of cash again for now, and probably has enough cash to keep going through 2023. Could be interesting, if the product takes off, but there’s no firm evidence of that happening yet. (no section below)
Somero Enterprises (LON:SOM) (370p - mkt cap £207m) [quick comment] - 75 readers voted yesterday for us to look at this long standing SCVR favourite. Unfortunately, there’s not much more to say, as the last trading update came with interim results, which Roland reviewed positively here on 7 Sept 2022. Somero confirmed on 5 Oct 2022 that Hurricane Ian had not caused any material damage or disruption to the company or its staff.
Valuation looks really cheap, with a fwd PER of 7.4, and an 11.0% dividend yield. The balance sheet is also bulletproof, and Somero has a fantastic track record of cash generation. Why is it this cheap? Clearly the market (assuming it’s being rational, which is not necessarily the case), is pricing-in a cyclical downturn in business. Investors still seem obsessed with the near-death experience in 2008, when credit dried up. SOM is now much better financed than back then, and would such a drastic crash in demand be likely to repeat? Who can say? If profits halved, back down to 2017 levels for example, we’d still be on a PER of about 15, which is probably a fair price. So there’s a lot of downside already priced-in. Also, readers have pointed out that both Chairman and CEO are getting on a bit, and the shareholder structure is very fragmented, so SOM looks an obvious candidate for a takeover bid. Personally I wouldn’t be a seller here, if I held. Although we do have to be aware of the risk that forecasts might need to come down if a significant recession happens in the USA, its main market. (no section below)
Fonix Mobile (LON:FNX) Fonix (213p - mkt cap £213m) [quick comment] - Subscriber Helvellyn requested this share in yesterday’s reader comments, and 35 of you gave it a thumbs up, so let's have a recap on it. Fonix provides telephone voting IT for popular reality TV shows, and charities such as Children In Need. It has very sticky clients, and is very rare in actually having delivered on its promises when it floated in Oct 2020. I did a fairly detailed review of the admission document, and talked to the CEO, reporting back to you here in Feb 2021, with a positive view on the company, but I didn’t know it well enough to want to buy any shares at the time, and was a bit nervous about client concentration risk, although that has not been a problem since.
The latest news looked encouraging, and I gave this share a thumbs up here on 23 Nov 2022. Overall, this looks a really nice business, with an excellent track record, and every reason to believe it should keep churning out good profits and cashflows. You have to pay for that though, with a fwd PER of 23.3, so there’s no room for disappointment. Divis are pretty good, with a fwd yield of 3.5%. Balance sheet is fine, and in any case it's a capital-light business model - another positive. Fonix gets another thumbs up from me. (no section below)
Sylvania Platinum (LON:SLP) (104p - mkt cap £276m) [quick comment] - Jack used to report on this value share. I know very little about resources companies, so all I can really do is flag up the wonderful value attributes on the StockReport - super low fwd PER of 4.9, big dividend yield of 7.2%, and decent asset backing with a P/TBV of 1.31 (the lower the better, with this measure).
Why is it cheap? I don’t know, but obvious things might include perceived risk from operating in South Africa. Also risk from volatility of price, and demand for its metals (e.g. would the move to electric vehicles reduce demand for metals used in catalytic converters?). What is the life of the mines remaining?
Q1 results (Jul-Sep 2022) look impressive, with $139m cash held, and $18.6m “net profit”. Last balance sheet at June 2022 looks amazing! Stuffed full of cash, and no debt. Love it!
My opinion - I can only comment on the numbers, not the business model or the outlook. The numbers look fantastic. So if profitability/cashflow can be maintained at anything like the current level, then this share looks great value. The low valuation is clearly the market telling us that it doesn’t think current profit/cashflow is sustainable. Is that right or wrong? I have no idea, that’s your decision.
Saga (LON:SAGA) SAGA (132p - mkt cap £186m) (I hold) [quick comment]
This was also mentioned yesterday by reader eParo (and got 34 thumbs up), who pointed out that a new >3% shareholder had just declared, and that the share price has risen over 50% from recent lows. It seems to be rising every day at the moment, which is very welcome, but also unsettling when there’s been no trading update for a while. Is this just a speculative move, or do the buyers know something we don’t? Has everyone likely to sell already exited? Who knows.
The downward trend in broker forecasts stopped about 3 months ago. They’re now only expecting breakeven for FY 1/2023, which seems gloomy compared with the last outlook comments from SAGA (which I reported on here in late Sept 2022) indicating FY 1/2023 profit of £20-30m. I see that the 2026 bond, which plummeted to a low of 63 in early Oct, has since partially recovered to 73. Still weak, but better than it was. The 2024 bond looks fine now, with a running yield of 3.8%, and a price of 90. The company already has enough cash to pay off this 2024 bond in full.
I’ve mentioned extensively before, that I don’t see SAGA’s debt as a major problem - because most of it is just asset funding for the owned cruise ships (nearly new) which should now be beginning to earn their keep again, generating good cashflows. There’s no bank debt, just an unutilised RCF. There’s loads of gross cash on hand. So personally I don’t see liquidity as an issue at all - unless trading really falls off a cliff, and the company becomes loss-making - in which case the debt covenants could become a problem. We’ve had really good debates about this before, in the comments. I know some people see it as higher risk than me. A NED spent £200k on shares recently, at 94p.
My opinion - there’s some risk here with SAGA for sure, but if travel rebuilds as hoped (it’s recovery has been frustratingly slow so far), and the insurance business gets through regulatory issues without too much damage, then we might see a geared recovery in the equity price. Possibly. It’s not guaranteed of course, and we just have to wait and see what the next update says, and hope that it’s not more downgrades to forecast profit.
RM (LON:RM.) RM (52p - mkt cap £44m) [quick comment]
Several readers - rogerh, mojomogoz, Boon, AstonGirl, and planetx, all flagged interesting developments at RM in the reader comments to yesterday’s SCVRs. I generally find that when a number of smart investors converge on a particular share, it’s usually worth investigating.
RM has been in a dismal downward spiral, and when we last looked at it here on 17 Oct 2022, Graham rejected it as being too high risk, with both financial, and operational problems. The share price has since more than doubled, and there have been some interesting developments -
28 Nov 2022 it announced the proposed sale of 2 businesses, RM Integris (school admin management software), and RM Finance (school financial management software).They generated £2.0m in PBT for FY 11/2021. This disposal raises £12m in cash, plus a possible further £4m if competition clearance is achieved. It’s being done to reduce debt.
29 Nov 2022 RM announced the appointment of Investec, to join Peel Hunt, as joint broker. Neither of these brokers take any interest in private investors, so the only reason to employ them is to raise money from a larger pool of institutions. Hence I’d say a placing looks likely.
Does it need a placing? The last balance sheet at 5/2022 looks wobbly to me, with negative NTAV of £(29.9)m, once you write off goodwill other intangible assets, and the accounting pension surplus of £39.7m which is actually an actuarial deficit.
Bank net debt was £41.5m at 5/2022, and covenants had to be relaxed, suggesting debt is a problem. Although the £12-16m disposal noted above helps reduce that net debt.
28 Dec 2022 - this is the intriguing announcement that readers spotted, and flagged. RM has agreed to sell some IP addresses for a whopping $10.2m. It doesn’t say what these are, but clearly someone at the company was very shrewd, as they were acquired for no cost, and are hence not in the books at all as assets. It says an additional £4.1m of IP addresses were sold in FY 11/2022. This is remarkable news, and it says another 294,000 IP addresses remain owned by the company. We definitely need more information on this, as it’s something game-changing when a problematically indebted group suddenly finds, and sells £12.6m of assets which cost it nothing!
My opinion - I can’t find any broker notes unfortunately, but the disposals seem to greatly improve risk:reward for shareholders. So I think this share looks well worth re-appraising with fresh eyes.
Graham's Section:
Tesla (NSQ:TSLA) - I provide some analysis of the key points and questions surrounding Tesla stock. This inevitably requires some analysis of the character and track record of Elon Musk. Looking forward, I expect that Tesla’s margins are going to suffer as the company cuts prices in response to weakening demand. Questions about demand are central right now, as investors weigh up a weaker economic environment, higher borrowing rates, and the effects of Musk’s antics on Twitter. Regulators are taking a keener interest in Tesla’s claims to have “full self-driving” capabilities, and this may also weigh on the stock (unless Tesla can finally produce this technology). (lots more detail below!)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
None, as all my comments are in quick comments above, so I could get through lots more companies today.
Graham’s Section:
Tesla (NSQ:TSLA)
Share price: $113
Market cap: $353 billion
Disclosure: I do not currently have a position in $TSLA stock.
This is a stock I’ve shorted from time to time, but in recent days I’ve closed out my position in Tesla puts, so I’m currently flat, i.e. I currently have no position in the stock.
It’s a stock that has caused enormous pain to short-sellers over the years and I too, in aggregate, have lost some money attempting to short it. The biggest difficulty with short-selling - timing the trade - has been a major problem for people betting against Tesla.
For example, many of us noticed that the company was close to bankruptcy in 2018 (see comments by Elon Musk himself on this). Given that bankruptcy was on the cards, and yet the valuation still appeared to be very high, how could any self-respecting short-seller not bet against it?
But the company pulled through and went on to have a multi-year period of extreme share price strength (and volatility).
To help illustrate the volatility that we are dealing with, the stock has a Beta of around 2, i.e. it has double the systematic risk of the market as a whole.
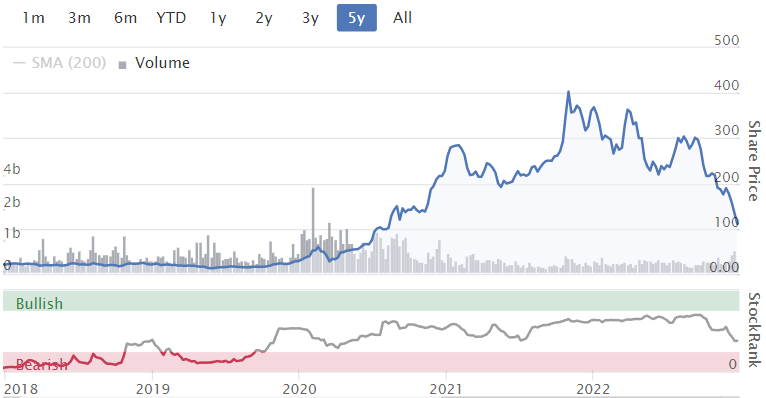
2022 has been the biggest win for the bears so far, with the stock down 72% year-to-date. However, only 2.3% of shares are currently sold short, as most bears have given up at this stage.
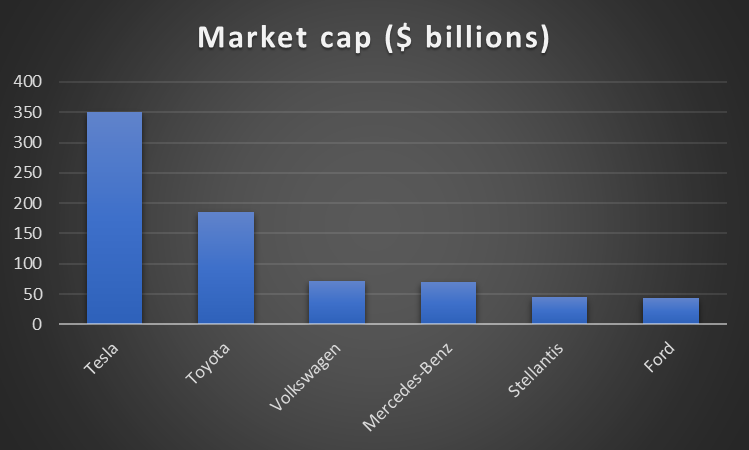
I remain keenly interested in the stock and I’m open to the possibility of trading it again. For context, here are the market caps (in USD) of some major car manufacturers:
Tesla: $350 billion
Toyota: $185 billion
Volkswagen: $71 billion
Mercedes-Benz: $70 billion
Stellantis: $45 billion
Ford: $44 billion
Now let’s see how many vehicles each of these companies have recently sold on an annual basis (source).
Tesla: 1.2 million vehicles sold since Q4 2021
Toyota: 9.6 million vehicles sold in 2021.
Volkswagen: 8.9 million in 2021.
Mercedes-Benz: 2.1 million in 2021.
Stellantis: 6.1 million in 2021.
Ford: 3.9 million in 2021.
Visually, this looks like:
And:
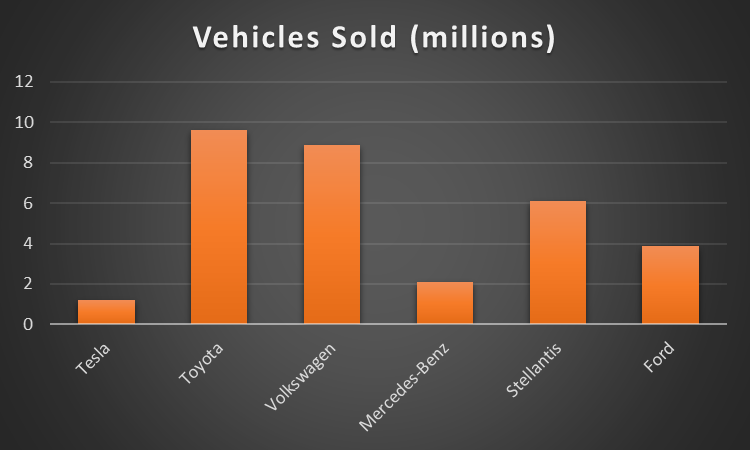
So Tesla has by far the largest market cap out of these manufacturers, but it produces the fewest cars.
We can divide market cap by vehicles sold to get valuation per vehicle sold:
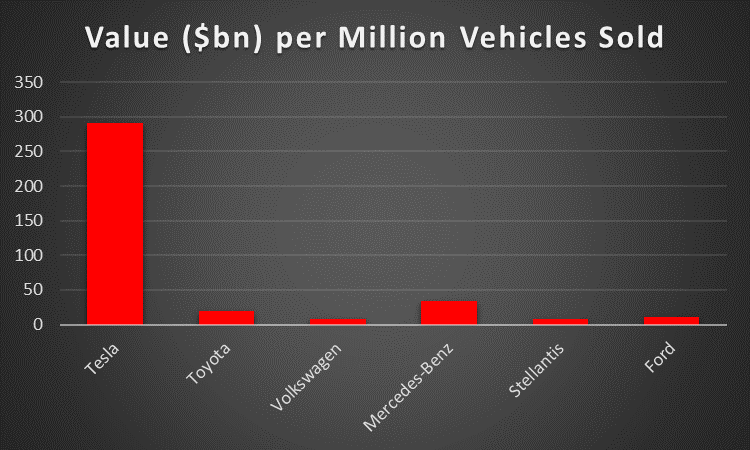
It is clear that Tesla is still being treated as “special”: its valuation is many multiples of other car manufacturers, when you account for Tesla’s smaller production.
If you categorise Tesla as a luxury vehicle manufacturer, and restrict yourself to a comparison with Mercedes-Benz only, the relative valuation of Tesla is still nine times the value of Mercedes-Benz. Against the likes of Volkswagen and Stellantis, the Tesla valuation is 35x - 40x the valuation of these other brands.
Riding the waves of popular investment themes
For Tesla to still enjoy this extraordinary valuation premium against its rival manufacturers, it must be doing something very different. In a nutshell, Tesla has the following special traits:
Pure EV production: Tesla only produces battery electric vehicles. No hybrids.
Tesla enjoyed first-mover advantage when it came to collecting EV subsidies and tax credits in the United States and many other countries, and has nothing to fear from proposed moves to ban petrol and diesel cars in the EU, UK and California.
Autonomy: for many years, Elon Musk has promised that Tesla cars will soon be autonomous. Thousands of customers have bought a package called “Full Self Driving”.
Artificial intelligence: as Tesla claims to be a leader in self-driving cars, it also claims to have special AI technology. At the company’s AI Day in 2019, Elon Musk said that Tesla “is arguably the world’s biggest robotics company because our cars are semi-sentient robots on wheels”. The company now has a prototype for a humanoid robot.
Genius leadership: Elon Musk is widely considered to be a genius and a visionary, the modern-day equivalent of Thomas Edison. “Don’t bet against Elon” is often said.
My view
To prevent this article from getting too long, I’ll try to summarise my own view under each heading.
Electric Vehicles: I’ve always viewed Tesla’s use of subsidies as a temporary competitive advantage, that would unwind as the subsidies were cancelled and as rival manufacturers increased their EV production.
Here is a recent chart from ev-volumes.com, showing that Chinese company BYD is actually the biggest EV company in the world, and the likes of VW, GM, Hyundai and Stellantis are also large players in the space. The non-Tesla companies have grown to substantial size, from a standing start:
(Key: the first bars (green) are BEV (battery electric vehicle). The second bars (blue) are PHEV (plug-in hybrid electric vehicle)
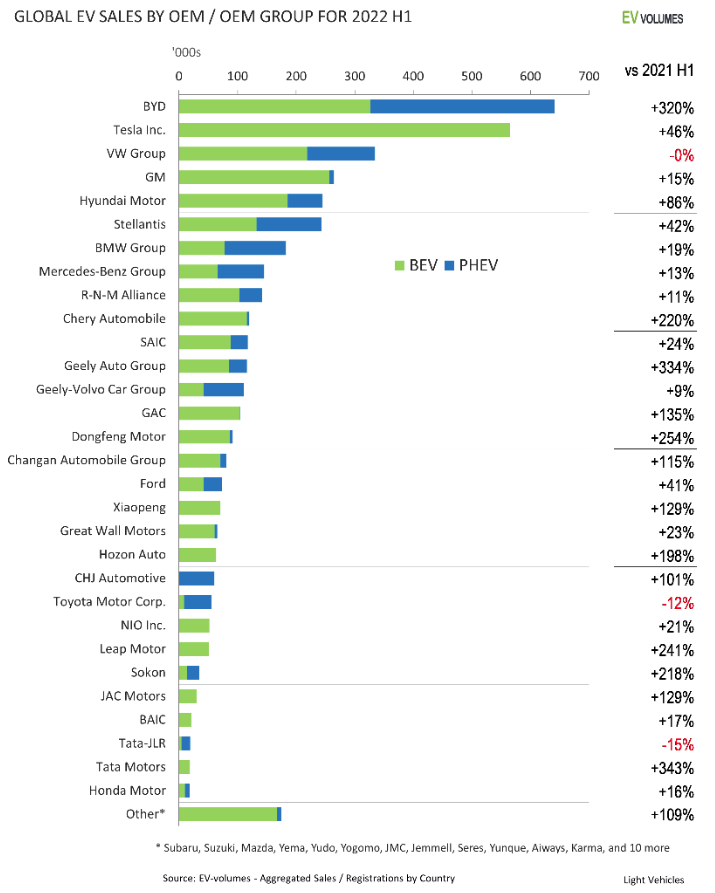
Volkswagen’s new CEO seems determined to accelerate VW’s transition to EV production, including models that are cheaper than any Tesla. It’s conceivable that VW, rather than Tesla, will be the largest Western EV manufacturer in a few years.
Autonomy
In 2016, Tesla began claiming that all of its vehicles had full self-driving hardware. It has a very long history of wild claims and promises around full self-driving. The result has been a series of lawsuits and California has now banned Tesla from calling its software full self-driving.
My own view is that Tesla has similar autonomous capabilities to many other manufacturers - many other cars are also capable of parking themselves, have motorway lane assist features, etc. I believe the difference is in the marketing: Tesla has repeatedly claimed that its software is special, and many of its customers believe that it is special. But that is about as far as it goes.
All other manufacturers use a radar system called LiDAR in addition to cameras, but Musk has repeatedly claimed that LiDAR is too expensive and is unnecessary. His strong views on the subject might come back to haunt him: there are signs that Tesla wants to start using radar again.
For an example of actual autonomous driving, see Alphabet’s Waymo project. Members of the public in San Francisco and Phoenix are able to take autonomous taxi rides from Waymo right now (disclosure: I have a long position in Alphabet).
Artificial intelligence
Tesla’s AI humanoid robot has no commercial reality and is not worth addressing here.
Tesla’s leadership
I first started studying Elon Musk in detail around the time of the SEC lawsuit in 2018, after Musk tweeted (while the stock market was open), that he intended to take Tesla private at $420 per share, and that funding was secured for this deal.
Under the terms of the settlement reached with the SEC, Musk cannot deny that he committed fraud.
My personal view is that this tweet was, when you consider the many billions of dollars worth of Tesla stock being traded at the time, the single biggest act of securities fraud and stock manipulation in the history of finance. I also believe that any normal CEO would have immediately and rightly lost their job after committing such an act.
There are very many other aspects of Elon Musk that I could go into here. Books have been written about him, and many more will be written about him. But we don’t have time to go into every detail here.
One particular red flag for Tesla that has become more apparent this year is that the company does not have the full attention of its CEO.
Again, any normal company would require that its CEO position is a full-time job and that other commitments would be limited.
At Tesla, however, Musk has also simultaneously been the CEO of two other companies for many years: spacecraft manufacturer SpaceX and a construction company called The Boring company.
As if that was not enough, Musk decided to get involved with Twitter this year, buying it and becoming the CEO.
Whatever your views on Musk’s Twitter strategy, it’s clear that his time is now even more stretched and this can’t be good news for Tesla.
Additionally, there are the political consequences of getting involved with Twitter: Musk can’t resist sharing his opinions on controversial topics, and many people have strong views when it comes to Twitter’s policies around free speech/misinformation. Therefore, it is inevitable that Musk’s actions and policies on Twitter are going to alienate and upset some percentage of the public.
This is now a major concern for Tesla investors: are potential buyers of the product being turned off by Musk’s Twitter antics? Has the association with Musk - long considered an asset - become a liability? Does the Tesla brand risk becoming tarnished beyond repair?
Summary/Conclusion
I’ve been a sceptic of this company for many years, so I do need to work hard to maintain an open mind.
There is no denying that the company’s financial performance has improved:

I’ve been surprised and impressed by the company’s improved margins, although it must be said that substantial aspects of Tesla’s accounts are a matter of opinion, e.g. revenue recognition for FSD sales.
The “Quality” metrics are currently good, too:
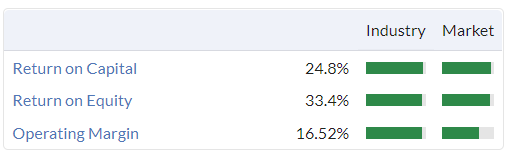
Should I be weighing these factors more heavily in my analysis? Perhaps. But given how rapidly the economics around this company and the car industry can change, I’m not sure that I’m willing to place much importance on the recent financials.
With borrowers facing higher interest rates in the US and elsewhere, I think there are serious questions around the demand for luxury cars over the next few years, which could have a disproportionate impact on the demand for Teslas. The company has already unveiled steep price cuts this month in the face of weakening demand.
The immediate outlook, therefore, does not look positive at all.
At the end of the day, I think the key questions around Tesla haven’t changed too much:
Does the company have special autonomous driving technologies?
Will the company be able to expand production to maintain high market share in EVs?
Is Elon Musk a genius and a visionary, or a fraudster and a liability?
Will competitors capture the imagination of consumers in the same way that Tesla did?
I’ve come to my own conclusions, but I love reading about the company - either from bulls or bears - and I look forward to your comments.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
The world's favourite drama queen geopolitical strategist on EVs and Tesla (NSQ:TSLA)
The economics of EVs don't make sense
1) The resource input requirement is huge relative to current known reserves. There are many problems with this but the most significant is the energy requirement as input to make this happen before you arrive at the new energy paradigm of 'green' EV
2) Recycling is much harder than portrayed once the multitude of mineral inputs are considered. So can target getting a mineral out and recover a decent proportion...but then the process needs to be repeated for other minerals you want to target. Reclamation is a serial not parallel process. Reclamation is an energy intensive process. So the problem is very high energy costs to make a fully recyclable process as in the 'circular economy' nonsense some academics peddle and policy makers swallow. This is simple to see once a truly physical view of the world is employed rather than abstract finance and policy...recycling is an intense fight against entropy the most disruptive and energy sapping force in the world
Of course, we may make great breakthroughs. This will be in new materials and chemistries rather than the existing consensus. I note that progressing battery technology has proven a very hard slog
ICE is going to last a lot longer than people think and be much greater part of fleet than assumed (majority IMO for decades to come)...super energy efficiency leaps in ICE are probably more doable and net net that likely means less environmental destruction than mega mining earth for EVs
(As I've said elsewhere, EVs make sense in big dense cities from pollution control perspective...and that makes most sense on a car share/AV sort of basis)
Saga (LON:SAGA)
"The downward trend in broker forecasts stopped about 3 months ago. They’re now only expecting breakeven for FY 1/2023"
Analysts consensus forecast for 1/2023 EPS was recorded as "1.267p".
I had reason to ask the stockopedia help line to check that the decimal point was in the right place.
It has now been corrected to "12.65p".
It would seem that the stockopedia data provider made a typo and put the decimal point in the wrong place.
Regards,
Ian.
I was surprised that Tesla has the second best selling car, in the UK, in November.
Still seen very few around here but there are 2 Hondas across the road from my house.
Tesla (NSQ:TSLA) Can't be discussed without mentioning The Elon. He's the first car industry big cheese since Agnelli to have the general public following his opinions. He should be evangelising this new technology he is spearheading (There are plenty of EV naysayers like myself who he could be trying to convert) but instead he, well I'll be diplomatic and say "He gets easily distracted". He doesn't even appear to understand the industry he is trying to disrupt, which should be a prerequisite of auto industry rule breaking. The Cyber Truck being an excellent case in point: it's panels can't be produced by the industry standard die stamping process and it's parameters have been set by someone who can't understand the fundamental concept of energy absorption, which underpins crash protection. The only nation that is going to grant it type approval (In it's 2019 unvaling state) is a country that he either buys or invades. I think IFRS needs a formula to calculate the financial value of a director who alienates people and can't keep his mouth shut and then enter The Elon on the balance sheet- as a liability! Strip him out of the equation and Tesla gets more promising. Will return to after dinner.
Tesla's strength is it's access to battery technology and associated infrastructure. Long-term this may be it's big asset, as done right it could make them systemically important to the motor industry.
I don't see them as a long term marque despite the model S being a very attractive machine; it is almost 10 years old but looks as fresh as a daisy. I think it nails what Jaguar were aiming for (And missing) with the XF.
However I also think the car industry is very good at thwarting predictions. In the 60's the consensus was that VW and their economy cars were being left behind by the "Economic miracle" and they would fall by the wayside like Hansa and Loyd. At the start of the 70's the Alfasud represented the standard to aim for for small family cars, then someone snuck up from behind and launched the Golf... Triumph was predicted to have a bright future- by Lord Stokes at least- and people talked of Peugeot as being "A French BMW". Twenty years ago no one would have predicted Honda's retrenchment from the British market yet I can't remember the last time I saw one.
Tonight I counted 4 newish Tesla's in Tesco's car park, 4 new or newish Mazda's and 0 Honda's of any vintage. It's probably daft to draw conclusions from one location but my reading is that there is equal appetite for EV standard-bearers and also the engineering-heavy marque that had very pointedly snubbed EV's until recently. I don't care if petrol car production is ending in a few years, the entry fob for our Mazda 3 (Better fuel economy from a consensus breaking old school 2 litre 16 valve engine than Fiat claimed for the TwinAir engine, let alone what drivers actually got!) will have to be eased from the dead fingers of my partner and I. We are the type of motorists who The Elon should be wooing but the benefits aren't been articulated by the one who actually has the platform to proclaim them and the product isn't compelling enough to wean us off Hiroshima's finest.
What I don't understand is most of Tesla batteries are made by Panasonic and CATL, a Chinese company, so why does Tesla have a big asset? Also the problem with most batteries is they use lithium, which is in short supply and expensive.
Honda are due to launch 3 new EVs next year.
I thought all the expensive cars were in Aldi's car parks?
What I really don’t understand about Tesla and EVs generally is they require so much raw material to make in metals for batteries, they are far heavier than a normal petrol / desiel vehicle of similar size. The amount of mining required to mine for batteries is significant. If moving to EVs is seen as saving the planet I don’t see it. Then on top of this is the infrastructure required to charge / power the EVs.
I think it was Volvo who said that compared with a conventional car, their cars break even on the CO2 front after about 80,000 miles due to the high embedded CO2 in producing the vehicle I.e. the battery.
However, after 80,000 miles, a conventional Lithium battery is about shot, so needs replacing, so up goes the CO2 emissions again.
Totally agree.
Somehow musk & Tesla have persuaded the world / governments and other car makers that batteries are the answer which for Tesla and their mega battery factories is good for them.
I think the exact figure was 68,400 miles - however - and this is a big however, that's based on the assumption that it's being charged by the current global electricity mix.
If it's charged with renewable energy then it's potentially 16,000 miles.
Volvo estimated that an electric Volvo C40 needs to be driven around 68,400 miles (110,000km) to have a lower total carbon footprint than its petrol equivalent, if the former is powered by the current global electricity mix. However, it could offset its higher production emissions in only 30,000 miles (49,000km) if charged with wind-generated electricity. EV experts dispute the claims, saying the crossover will come after 16,000 miles
Polestar (an ev maker) performed a lifecycle analysis and confirmed that electric cars have a co2 deficit at the moment they role off the production line.
The point at which they become "green" is highly dependent on different factors, especially the methods used for electricity generation where they're used. Then there is the small issue of how to manage the increasing numbers of car batteries that need to be disposed of in an environmentally friendly manner.
The point for me, is that until green charging and recycling infrastructures are in place, to handle sufficient volumes, governments and other groups should not be incentivising people to scrap perfectly good petrol and diesel cars. Those vehicles have done the bulk of their emitting, and should be used until failure. That would be greener than replacing them with new electric vehicles, despite the propaganda.
While I agree that old ICE cars don't need to be thrown away for a while, I think it's important that people begin to understand the EV life cycle that is emerging.
1. No, there won't be lots of lithium batteries in landfill. Companies are wanting to re-use them for house energy storage and other less critical applications, e.g https://www.secondlife-evbatte..., but there aren't enough for an industry to be visible yet. The problem?
2. They aren't degrading as fast as predicted. For instance, our Nissan Leaf 40KwH has done 34,000 miles after 5 years, but has >95% capacity still. "About shot" at 80,000 miles is unlikely...
3. Our power is from renewables. Hardly any ICE cars running on chip fat.
4. Some people wish to highlight that the extra weight means you use more tyre tread. Perhaps, but not significant to us. And brake pads get less wear in EVs because of how regen braking changes people's driving style.
5. There's plenty of lithium; It's just the mining cycle issue. And it's disingenuous to think that fossil fuel mining has no environmental/health/political impact.
6. Like other technology disruptions, it's really about the value curve. As soon as those cars are the same price as ICE equivalents there'll be tabloids complaining about lack of supply.
I put this not as an evangelist but as an investor. This is the start of a disruption that will strand assets, and who the winners will be is unforecastable. I was in the digital imaging disruption. I warned various companies who didn't believe me and subsequently suffered. But predicting the winners is much harder! Which western car company is a good investment? Perhaps none of them, because the Chinese are coming. But I AM invested in copper miners. It's the most straightforward commodity that must grow in demand from EVs and the broader electrification of global life, and we're probably into world supply deficit by the end of this year.
I use lithium batteries in my cameras, they are generally fine for about 5-6 years then rapidly go down, many go from green to red in less than a year. Funnily enough the expensive original batteries are not always the best, prices are ridiculous now, over £100 for one.
Looks like car batteries are better than camera ones but I would keep an eye on it. Nissan give 8 warranty on batteries.
I'm in the minority here as a Tesla (NSQ:TSLA) fan and have been buying over the last Month. IMO it is more than a car company, and has so many areas to still grow. Solar panels, solar roofs, battery storage, cyber trucks, semi, and of course the affordable car just around the corner, amongst many other things. They are always thinking ahead, they are planning to have a lithium refinery in a few years.
I do think it will be the largest company in the world in a few years, but we will see.
One think that makes it difficult is financial media and mainstream media hate Musk equally, and in turn hate Tesla, so the old adage only believe half of what you read is doubly true. He is hated by the Guardian, Daily Mail and Routers equally.
Sorry to break it to you, you’re exactly the mark the stock pumpers we’re looking for as they become dumpers, now you’ll likely be a ‘bag holder’.
Solar panels. They buy them.
Solar roofs. They buy them.
Battery storage. They buy them.
Clustertruck. Doesn’t exist. Years late.
Semi. Is a joke, only useful for delivering crisps.
Affordable car. Not even announced, let alone revealed. Keep dreaming.
“Always thinking ahead”. No, they’re always spending money announcing products that they “can do today” (semi convoys cheaper than rail) that don’t exist 5,6,7 years later.
The cult of Musk is coming to an end.
I am also a Tesla fan and own one.
I think the problem with most stockpickers evaluating technology shares is that they don't understand technology well enough to evaluate what they're assessing. My husband has been an extremely good electronic engineer for over 30 years, and I know from watching him work on some pretty complicated stuff (mobile networks) that to get something to work well technologically from an engineering perspective is hugely complex, especially when the technology is in its infancy and leading edge. I remember talking to some of his contemporaries about the complications of the new mobile phone networks in the 1990's and there were a handful of people in the world that understood the mathematics and physics behind these networks at that time (I am not one of them although I am a mathematician by background).
From what he has said to me, what's special about Tesla is the battery management software, and this is totally non-trivial in a way even he doesn't understand because it's way more complicated than we can begin to comprehend. This is not the battery itself, it's the software that manages it (although there's a huge interplay between hardware and software and I suspect that the two are inextricably linked).
To give you maybe a small example of this, although I suspect it's a trivial part of what the car does, in order to charge at a fast rate on fast chargers, Tesla cars make a decision to warm the battery up BEFORE you get to the charge station (this is particularly significant in cold weather like we've had recently). This relies on you having programmed into the mapping software in the Tesla car that you are heading to a charger. My husband read a whole article about why the software does this, and when I asked him about it he said, "I don't really understand it" - this is from someone who has 30 year's experience and read a lot about it and is insanely interested in this kind of stuff. Elon Musk is right to categorise Tesla cars as AI/Robots, and it's laughable that people would say to take him out of the equation, they may not like him, but have they not been paying attention to just how well-qualified he is to do what he has done to date?
I'm a Tesla fan because it's an amazing car. It just works extremely well, in a way that other EVs do not. And a lot of that is totally non-trivial.
I'm not some huge Elon fan, but IMO we should be thanking him for changing the nature of the game - especially in cars. I hope he keeps on doing it in lots of other areas. Petrol companies bought up patents for other car fuel/power designs for decades to make sure we all kept buying fossil fuels. Look where that has got us. Are lithium batteries the solution? Who knows. There are other technologies that aren't lithium batteries that are getting good investor interest now he's shaken things up. God knows we need him to keep on challenging the status quo.
I'm not sure where that gets me in adding to this comment, but I would be extremely cautious in trying to predict what will happen with Tesla shares. Will VW and China match the car's performance? (Tesla probably had at least a 10-year start, and in technology, that's huge). One thing's for sure, I wouldn't bet against it.
Wow, it knows that you're going to a supercharger because you tell it, and then it uses gps to work out an eta.
Sounds like magic. However would any other company achieve such wizardry?
If he can't grasp the concept that batteries perform better when they're warm, both charging and discharging, then I guess he's not as smart as you think he is.
(Tesla probably had at least a 10-year start, and in technology, that's huge).
I'd very much doubt that. Others may not have developed the tech so far, or made so much of it, but I think we can be pretty sure that all the large car cos would have had teams working on electric car tech for a long time.
And what the big car cos do have, that Tesla don't, is decades of experience in building cars, that last, that are reasonably easy to repair ... I certainly wouldn't bet on VW or Nissan not being able to produce end user EV products for the masses efficiently and effectively.
RM (LON:RM.) (no position)
For any interested, I found this (possible) list of RM IP address.
---
I also found the seller auction website run by Hilco Stream Bank, the company which just bought IP addresses from RM (LON:RM.)
https://www.hilcostreambank.co...
https://auctions.ipv4.global/p...
The average domain selling price over the last 1 year is c.$50.
We are told that there are 294,000 IP addresses still held by RM.
That works out at a possible "hidden" book value
= $14.7m
= £12.2m
It's important to note the difference between a domain name like stockopedia.com and an IP address (which is what RM (LON:RM.) are selling off as per the RNS) which is a numerical code of the form 1.2.3.4 - the maximum values for each of the 4 numbers is 255, so that's a lot of combinations... or it was until we all had phones, tablets, washing machines, etc which all want one. Whilst there are ways to work around this for private networks like your house or office, this format of address has some scarcity value to it, which is what is probably driving this.
Going forwards this addressing (IPv4 technically) is being replaced by IPv6 which allows for a much much larger number of addresses, so the possible shortage of IPv4 addresses should be less of an issue. So the future value of the remaining IPv4 address blocks held by RM could be reduced. I found this link (one of many!) which has a summary of Address ranges held by RM Education Ltd
(No position).
The company I used to work for had a few class A addresses when taken over by HP.
The 16.0.0.0 block equates to over 16M individual addresses. That works out to over $700M These were assigned to various companies etc at the start of the internet. Some interesting names on this list ie UK Dept of social security.
http://www.aturtschi.com/whois...
Careful, not all ip4 addresses are worth the same amount!
Plus, the remaining addresses they have might be needed for continued smooth running of the RM (LON:RM.) business, so might not be feasible to sell, as intimated by the rns.
RM (LON:RM.)
Hi Boon
I just went by the column header - "$/address" - and then used $50 for my own rough calculation - which seems like a good average when one looks at all the other figures in the same column.
Or perhaps I'm reading it incorrectly?
A
You are reading it right, all the recent auction results are quite similar pricing. But I remember a few years ago, when I was learning about IP addresses, that some blocks were more valuable than others. Like Google had paid a massive premium at some point to get a specific block? So it has stuck in my mind that not all ipv4 addresses are the same value. However, it isn't clear if the remaining RM ones are high or low value.
Tesla (NSQ:TSLA)
Which magazine regularly publish car reliability survey results by brand. Tesla cars are reported as having a higher fault rating than the average of all other EV's. Given that the average includes some pretty inexpensive EV's it doesn't say much for Tesla's premium cachet. In fact one of its models, the X, gets one star (out of five) for reliability. Battery range and acceleration are nice to have but I would want a car I can rely on, especialally when I'm shelling out big money
Re Tesla - I do not hold, never have and likely never will, but:
You can’t compare Tesla to traditional car manufacturers on an operational level which is why comparing the valuation multiples of Tesla vs traditional OEMs is a nonsense. On the one hand, you have a focused maker of battery electric vehicles, the biggest in the world, with its own battery supply chain and electricity/charging delivery network and the largest bank of autonomous driving data in the industry. On the other, a group of smokestack ICE car assemblers who have belatedly seen the writing on the wall and are rushing to catch up while burdened with assets designed for a previous era. A significant premium/discount is entirely justified - the difficulty is in assessing the correct level!
That said, I think Tesla will fall short of its grander objectives. Cars are not just their engines and acceleration. There’s coachwork, suspension tuning, handing characteristics, comfort, noise, vibration suppression, interior fit out etc. And in none of these areas does Tesla excel today. In truth, they’re a bit crap on any measure other than acceleration combined with a far superior charging network. I fully expect future Audi EVs to exhibit smarter interiors, BMWs to handle better, and Mercs to do for their owners what I’ve never quite worked out but I guess they like the badge. Meanwhile, the space below the luxury levels at which Tesla current competes is rapidly being filled by excellent family wagons from the likes of Hyundai and Kia and the Chinese are making rapid progress in the budget category with the likes of MG.
The change in the industry that I predict is not that Tesla takes over the world. Rather that the paradigm shift in propulsion opens the way for SE Asian brands to knock the current big guns, Ford, GM, Toyota, VW off their perch.
In a similar space to Saga (LON:SAGA) is Global Ports Holding (LON:GPH) (I hold) a cruise ship ports operator. Essentially they invest in improvements in ports to facilitate use by cruise ships. The price has improved 60% in the last month and it still shows a forward P/E of 5.3. Its market cap is still just below £100 million. I bought, hoping to benefit from operational gearing and an increase in the market size (oldies like me go cruising as well as the covid rebound). Having said that I have been surprised by its recent price performance, which has helped in transform my YTD performance from appalling to bad!
I really like the review of Tesla. Tesla (NSQ:TSLA) . I wonder if you both can review some larger well know stocks with your unique insights. This would be a nice weekly thing through 2023. Thanks and keep up the good work
Happy new year.
WANdisco (LON:WAND)
Apologies for being late in posting this, I switched my computer on after being away for Christmas and posted on last Thursday's SCVR. Having spent the time, it seemed a waste not to repost for anyone interested.
Having worked in IT starting in 1970, I was curious and I did a lot of digging into WANdisco (LON:WAND) years ago. I decided all the good news was already baked in. The company name derives from Wide area network distributed computing and they have changed their target audience a couple of times but now concentrate on migrating customers to cloud computing. Not just storing data in the cloud but also using the computing power and higher bandwidth communications. Web based data providers and users communicate directly to AWS et al and the on premise part shrinks to being the equivalent of a remote user once migration is complete. The intervening part is where Wand come in. There must be built into the software that runs on the cloud system and the on premise system some means of recording which data has been copied across to the cloud and whether it has changed since copying in the same way that Backup programs save time by not copying data that hasn't changed. Eventually (and depending on internet bandwith that could be some time) all the data is on the cloud server and all applications using that data are on the cloud server. Answer to how it's done is probably slowly, and probably frequently changing data done first (with a database I would guess there would be additions but not changes)
My question is are there presently enough big data customers to migrate to keep wand busy enough to repay an investment. Future big data imho will go straight to the cloud anyway, their ebullient CEO has sold about £10M worth as shown on Stocko so doesn't inspire me. I don't think in its present form it has a long future.
RM Group
I do really like the fact that a company already trading significantly below NAV can pull 10 million usd out of nowhere. That is the best “hidden value” .
I nearly bought a few months ago but was pretty much fully invested at the time and did not have anything to selll.
The Crestchic situation has unlocked 30% of my portfolio so have taken a starter position today albeit a month or so too late to catch the lows
Having said that it wasn’t so apparent a month ago that they were going to get cracking on reducing the debt so effectively.
The key to management change is to make all the changes and get a few wrong (or something like that) so I am liking the change of pace here.
I can’t see how they will fundraise as they seem stuffed full of plump assets that are proving easy to sell off , and if they can raise 10 million usd for assets we never knew they had on the balance sheet it’s certainly tipped me over the edge from watcher to buyer .
hi - why do you think RM (LON:RM.) is trading significantly below NAV?
Last accounts says it has £140m of tangible assets against £106m liabilities (if we exclude the capital leases of £18m) so that's circa £34m net tangible asset value. But then debt appears to have gone up since last year (which will be offset by the two asset sales) so will still be looking at circa £30m net debt by year end I think - maybe a reduction of £10-15m from current £45m.
Cash outflow at half year of £3.6m and per quote below sounds like similar for remainder of the year and at least H1 of 23. If we assume similar cash outflows then from the £41m of net debt at y/e we go up £11m in outflow to £52m and down by circa £20m from asset sales hence the £30m figure. from the accounts........
" The continuation of the warehouse automation and IT platform investment programmes contributed £11.8m of the cash outflow. Following the decision to extend the timeframe of the rollout of the IT platform we now anticipate the programmes to continue into
FY23 and we expect the associated benefits to be delayed and the costs to support the change programmes to continue. "
So feels to me like tangible NAV after the sales is around £45m which is about the same as its market cap.
But education budgets are under significant pressure and the business has moved into loss making and suspended the dividend.
I can see why the shares have moved up from 25p-55p but it strikes me that the sale of the businesses has lost a further £2m PBT from the bottom line and the residual IP addresses appear to be required for the business connectivity, so aren't likely to impact on cashflow/debt reduction. End markets are challenging so if you are buying here it seems you are now buying into a recovery with all the associated risks and an IT program expected to produce efficiencies that is well over budget and significantly delayed.
I am new to RM (LON:RM.) so appreciate I may have missed some nuggets of value, but having done some drive by analysis I am at best lukewarm on this one so far. What's the bull case?
I take a more cautious view of tnav at RM (LON:RM.) . Can't remember off the top of my head what I discounted in my calcs, but after the sales, and assuming further losses and cash outflow from the warehouse and IT projects, my tnav is coming out close to zero.
I still feel amnequity fundraising is on the cards. They've done a good job getting the SP up from the crazy low levels, and now would be a good time to get another £10-20m raised to repay debt, to get to a more sustainable debt position.
Somero Enterprises (LON:SOM)
I suspect that the 'special' dividends will be a little smaller over the next year as the management contemplates a more uncertain outlook, so perhaps the yield is nearer 7.5%, rather than the headline 11%. Still fantastic!!
Saga (LON:SAGA)
Paul
They’re now only expecting breakeven for FY 1/2023,
. I see that the 2026 bond, which plummeted to a low of 63 in early Oct, has since partially recovered to 73.
I’ve mentioned extensively before, that I don’t see SAGA’s debt as a major problem - because most of it is just asset funding for the owned cruise ships (nearly new) which should now be beginning to earn their keep again, generating good cashflows. There’s no bank debt, just an unutilised RCF.
Again i take the opposite viewpoint here ref debt - medium term to long term
I would 100% agree with you short term due - not an isssue - 2026 is not that far in the future though and they have £250 mill owed then !
Facts are they have £400 million of non ship bond debt and (£250 and £150 mill bonds) and only £180 mill of cash. so i cannot see how £220 mill of net bond debt for business at breakeven is not an issue end of. Do you not aknowledge this £220 mill of net debt ultimately due for repayment in full by 2026 may be tricky to refinance in 2026 or settle? - i simply dont see how they will have cash to pay that off the way they are going. I fear you are concentrating on the "not at issues" 2024 bond repayment" whilst not really addressing the nitty gritty of the facts as how they will sort the 2026 issue (note if they are back to £50 millpa plus profits per year soon not so much an issue perhaps - but we arent there now)
number of 63/73 ref the bonds do suggest they are not in rude health any an means !
In addition to that they still owe £600 mill debt of ship financing - note they have delayed payment of part of that debt during covid so allocated cashflow medium term to repay debt is higher with catchup payments needed.
unless trading really falls off a cliff, and the company becomes loss-making
errrr is that not excatly what has hapened here over the last 6 months - i think they were expecting to make £50 mill profits this year at startn of year and you yourself have said they are now only at breakeven - so is your fear here exactly what is close to happening right now if they are only at breakeven?
At present i place little faith in projections for future years showing rosy numbers - the company themselves have advised that 3-5 months into year they couldnt forecast how well they would do. They seem very "off the ball" ref their ability to be able to guesstimate adn updated shareholders in clear manner - being frank they come along as being clueless with regard to what the future holds.
On a slightly more positive note oil prices are of peaks - and china ending covid restrictions will hopefully be a line in the sand where the whole world is realsing now covid at present simply needs to be treated more like flu. So hopefully return to calm waters may see this one good.
Fair points, but remember that there's a large depreciation charge on the ships, so the cash generation should still be pretty hefty for SAGA. I think they said the cruise loans are now up-to-date in the last announcement, but that's just from memory, so could be wrong.
Also, the business has gone through covid, which basically shut down the cruise and travel businesses. They're now cranking up again (frustratingly slowly), hence it's realistic to expect profits to at least partially recover.
Hence with the 2024 bond paid off from existing cash, I would imagine SAGA should have built up enough cash to easily pay off all, or at least a large chunk of the 2026 bond too, by the time that falls due. Most companies with debt are in a similar or worse position if they rely on bank debt - not many companies I've seen have bank facilities agreed until 2026.
What's to stop SAGA just issuing a new bond in say 2024 or 2025, which is exactly what they did in 2021, which paid off all the bank debt & have a nice gross cash pile. It's not all or nothing. Many companies roll over existing bond payments by issuing a replacement bond. SAGA's 2021 bond issue of £250m was linked to redeeming £100m of the previous bond I think, expiring 2024, which now has £150m remaining. Why not do the same again in 2024 or 2025? I can't see any obstacle to that, providing trading is going reasonably. There could be a problem if trading remains poor though, for sure.
Finally, there's the back stop position, where Sir Roger would probably cornerstone another equity raise if needed, which he did on terms that were more than fair to existing holders last time. Or take it private. But I'd say as things currently stand there's no need for fresh equity.
I'll keep monitoring SAGA though. For me, if it moves into actually trading at a loss, and the outlook doesn't demonstrate clearly a likelihood of improvement, then that would be the point where I would sell, as risk would at that point be higher than I am prepared to tolerate - the covenants are set at a level where once it becomes loss-making, they could be triggered.
Look at the historic levels of profit. SAGA was a big cash cow for many years, and I think there's a good chance it can recover, in which case it's a multibagger potentially.
Or it might go wrong, but with travel resuming now, and an affluent customer base, why would it go wrong now? I think they're probably over the worst, but time will tell.
Regards, Paul.
I do think Saga (LON:SAGA) can multi-bag from here on a 3-5 year horizon but I actually think the debt situation is in the middle of rmillaree and Pauls positions.
The existing cash resources could pay off the 2024 bond but will be tight and the business does also require a decent liquidity buffer. So I would expect to see this addressed quite quickly else it could provoke a going concern note to the accounts which wouldn't be helpful. I think this uncertainty is actually why you are seeing the 2026 bonds in particular discounted. If the 2024 bonds are dealt with smoothly I suspect you will see a jump in the 2026 tranche. If that proves difficult the 2026 will trade distressed despite the 3+ years to maturity.
The reality is that the bond market has been gridlocked for the last few months with all the turmoil so the company need the fixed income market to return to more normality in sufficient time and then it shouldn't be an issue. My bet is that about half the 2024 bonds are actually rolled to 2029 to preserve cash liquidity.
Refinancing of the 2026 bonds is well in the future in bond terms. UK 3Y is now stable at 3.5% so as long as the business is proving cash generative (and realistically it should be unless the underlying business is badly managed) bonds shouldn't be horrible to refinance in 2025 and beyond. Particularly as we now expect rates to start falling again by then.
So debt is both and issue and not an issue in my opinion. They need a little luck that the bond market reopens in sufficient time for 2024 not to look sketchy and providing it does then 2026 will look fine and trade higher. But like any business with debt the underlying cash generation is key. You have to believe they have the execution capability to start generating the profitability the business should be capable of though, and for me the jury is still out on that. I'm not yet sold on the CEO but the Chairman is more than capable imo.
But why should an investor involved in a Saga plc , with a market cap of £180m and bond debt of £400m (plus interest). At the moment this company belongs to the bond holders.
Until there is deleverage and slowly the value is transferred from the bond holders to the equity holders , there is no investment case here. I find today’s analysis very disappointing and very risky indeed , for current and potential shareholders.
Re Bidstack (LON:BIDS) I owned this for a period as I thought the company had transitioned from speculative to operational and was being under appreciated for that move due to all the past bs and investor hurt from it. Simply they had focused on the nitty gritty of how to sell product rather than a blue sky build it and they will come mentality. Note, Bidstack was at and probably over the edge in terms of risk of things I would normally hold...but I did a lot of digging and believed there to be a large dissonance around the company.
My above view holds true still...but I sold out earlier this year. The proximate catalyst for the CEO sending a private email to select group of shareholders (some of those taking part in the placing) with material information that should have been disclosed in rns. However, I was already feeling shifty about them mainly as rather than doubling down on their in game ad product and really putting everything behind that to push into the market and make notable revenue gains (profits would take much longer!) they have been developing adjacent products. Remember they are loss making and raise capital regularly so are capital constrained....so why waste money, time and people diverting away from the main mission? Made me think there's evolving problems in being able to truly launch the main mission.
The meat of the selective disclosure issue above was that they are in legal shenanigans with their one global reseller, Azerion. Azerion wants to back out claiming some lack of compliance from Bids. Bidstack's revenue forecasts for fy22 and fy23 are pretty dependent on reseller doing the $30m promised. Let's agree this is at least unhealthy....and gives me paranoid thoughts re why the dalliance away from core product to other new product? My guess is that Bidstack are stumbling on commercialisation through ad agencies etc...its not about whether the tech is or isn't good enough but the ability to engage with, hold hands through process and step through reassuringly with advertisers and ad agencies...and this is why they have splashed out on an expensive US sales team after (!) the Azerion deal.
Additionally, after signing the Azerion agreement Bidstack have gone out and hired a whole new and expensive US based team to sell their product in US! (Note, I suspect this US team aren't impressed with some of the diddies managing them in UK fwiw) Azerion were contracted to do this. Confusing...and expensive for a company that burns cash. The contract with Azerion supposedly has a commitment that they will sell $30m over 2 years....this is unlikely to be worth anything as Bids wont have the money or staying power to legally press it.
In 2019, 20 and 21 Bids gave a year end trading update on 17 or 18 Dec (2018 was their first year listed and didn't do then). As 2022 is THE commercial year with a 'lot of exciting things happening' its a little odd not to have an on schedule TU.
Anyway, I only scratch the surface on the complex story that is Bidstack above. It has a fervent bunch of rampers on twitter and its good fun to play with them...they are truly irrepressible and teflon. There really is possibly something big about Bids...but the fog is too much again and imo I was wrong/premature to believe they had resolutely struck out on a commercialisation path. If they manage to get a sure footing on the path then this company can be a rocket....but its looking a lot like they will be coming back to tap market again sometime in 2023 imo and its possible its surprisingly early given an elevated burn rate particularly if Azerion deal not pulling through (I suspect it'll get cancelled and maybe Azerion will pay a mill or two to settle and avoid legal expense). That could be very dilutive and/or open the door for a cheap takeout or even a take private again. So its possible that Bidstack are big...but not on AIM.
Couple of things Mojo on Bidstack (LON:BIDS) - Azerion are European so this is their focus area. The splashing out on an expensive US team is because they lacked penetration in the north american market. Frankly I am surprised they didn't tackle the US market first as it is by far the biggest and most innovative.
Not sure it's quite right to say they are in legal shenanigans or that Azerion wants to back out either. I'm not sure that's clear. They asked for certain details and reserved rights pending those details, which is what happens in any legal letter around confirming compliance. This was immediately post the capital raise and was clearly related to that. Personally I suspect there was a financial covenant type clause in the agreement that spooked Azerion and prompted the letter. Drapers email though was unfortunate and clumsy. I, like you, was surprised the nomad didn't consider it an rns. I suspect though that was on receipt of the letter from Azerion rather than the disclosure of the email. Nonetheless if it is true that revenue is building with record months it would seem unlikely that Azerion would have any desire to pull out unless they have financial stability or reputational concerns around client contract fulfilment, which may have prompted the request in the first place. We will see I guess.
Outside of those two differences I pretty much share your view though. It could be very big IF they can get the commercialisation act together and so far I'd say thats been pretty sketchy. It's an enigma of a company and definitely on the risky end of the spectrum. I used to be quite positive on it but I'd say management actions have somewhat neutered that positivity, such that today I sit on the fence.
I believe the Azerion deal was global and on that basis can easy see why they are a bit miffed with US team hire...and with the product focus 'pivots' (Bidstack (LON:BIDS) are already light on resource). Yes they are based in Europe. I'm dealing off of recall though so detail should be checked. Cynically, I think having the deal and the nominal revenue was more important at the time with a raise needed (...that I had asked about at AGM and being implicitly told it was unlikely as they had other sources nudge wink etc). I'm not trashing the Azerion deal just saying that the US team was a sort of after thought...perhaps as they got a more grown up chair as well as could look beyond the immediate funding horizon. I've been in a couple of early stage businesses as funding hurdles approach and know the extreme winsorizing that occurs around them (which can damage the prospects of biz)
I'm making a leap on Azerion's wants but I think its a good educated guess in the circumstances. I'll bet you one fine £1 that the end of the deal is announced by time fy22 report published
A PS re Bidstack (LON:BIDS) and the Azerion situation...
I've just remembered that resigning managing director (and co-founder...the guy who was more the tech side to CEO Draper's 'commercial') Fran Petruzzelli was lauded as the guy who secured and onboarded the Azerion deal and would work quite exclusively on the relationship (if my memory is correct).
At the AGM (May?) Fran was quite detached from proceedings IMO and didn't hang around at the end for chat with other directors or investors in attendance (only me and Michael Taylor...you'd think there would be loads given the heat generated on twitter for the company and for last couple of years AGM is the only forum to speak to mgt).
Fran seems an interesting guy to me. Clearly driven by the coding/tech side of things. From school straight into work and dabbled in a few businesses it seems trying to create something (I think his only conventional work experience is as tennis coach if I recall correctly). Anyway, very young guy who's done something pretty interesting and hard out of the gate...and is now walking away (or pushed, we can't know). It'll be interesting to see what he does next...that is something to keep an eye on. A lot of interesting learning and scarring for such a young guy.
Interesting info on Fran. Can't help thinking he was gently pushed myself.....but could be completely wrong.
I wouldn't like to say whether the Azerion deal survives the FY22 year end report but in the spirit of liquidity I'll bet you a pint ;) instead of a £1
I do agree there is something going on under the covers that investors are not privy to. Given the shape of the advisory board I suspect there is a pivot to the US market and the company is being repositioned. Be interesting to see. I do retain a small position but I'm not entirely convinced I'm not being an idiot holding either.
It genuinely could be a big winner! There is really a big market and adjacent market to be broken.
Pint agreed
Agreed - it's just whether or not they have the execution capability and jury is def still out on that for me.
Re Tesla (NSQ:TSLA) - I don't have much view on the company as in the too noisy and complex to get involved with for me and for years I've suspected its a short (but don't short!...short sellers great imo and often the best analysts but I take enough risk long only and mental task of trading off long and short risk is a distraction too far for me). My one relevant view...
I don't believe EV is going to be anywhere near as big as is hyped. We lack the resources and infrastructure to make this shift and its highly questionable to what extent the move would be environmentally positive.
Its possible we move a lot to vehicle sharing/AV (particularly cities) but this is highly unlikely to be a boon for vehicle makers. There's an argument that Tesla is first mover in this area (one that the famed Cathie Woods would make) but I'm sceptical it would be like this. Yes there's lots of driving algo training to be done...but if we make such a shift (for environmental reasons...pretty sound logic there) then its highly likely that local/national govt have a significant role in designing/policing infrastructure, partly safety, and significantly as a route to taxation/toll payments. And this is likely to minimise the competitive advantage one driving algo has over another....
...competition more likely on brand and service grounds in variety of ways including integration into other services we use. That gives a big opp for non car companies like Apple (NSQ:AAPL) to make a splash (...not surprising to know that cars are a big research area for Apple!)
I'll be called a luddite or climate denier for such views by some....I prefer to think of myself as imaginative yet bounded by the physically possible ;)
You can fool all the people some of the time and some of the people all the time but not all the people all the time. This describes Tesla.
...but sometimes a cunning double bluff works...see Elon
Thanks graham for your Tesla (NSQ:TSLA) comments. I wouldn’t go anywhere near it even though I have several risky shares like Kromek (LON:KMK) and SRT Marine Systems (LON:SRT) . The chart value to vehicles sold says it all for me
Cheers rh
The thing about Tesla (NSQ:TSLA) historically (on its phenomenal run up) for its eulogists was that it wasn't a car company but a tech company. ie one shouldn't value it against other car manufacturers because its business model was to become the pre-eminent autonomous vehicle manufacturer. Once that was achieved the Teslas themselves would no longer be sold but effectively just drive around all day picking people up and dropping them off at very low prices per km. Thus the worlds largest taxi company :) that could generate huge profits from driverless vehicles. Original Tesla owners would not be left behind as their software would allow them to do the same whilst they weren't using the car, thus generating income and being an investment rather than drain......... etc etc.
What I could never get my head around was not the concept itself, as I am sure that sort of thing will ultimately happen, but the length of time and obstacles in getting there. For me at least, investors vastly underestimate the time it will take for any level of mass autonomous vehicle adoption, so paying forward for massive multiples on something that I expect to be well over a decade away looks crazy.
Which brings us back to valuation - if the above is currently no more than a pipe dream littered with mammoth risks and likely competition then Tesla (NSQ:TSLA) shouldn't really be valued much higher than other large car manufacturers.
I wanted to short but could see that was likely folly so just stayed clear but I still don't get the valuation.
Hello Paul
What are the chances of another shindig at that Pub near the Aldwich ( back in late Jan I think)?
Been keeping my eye out for one, either I missed it or there wasn't one.
It really was a good evening out and would be great to have another one.
All the best and good fortune to all for next year.
Good morning Paul,
I was wondering if you had any appetite for an official “Paul Scott balance sheet strength screen”? Obviously it could also work as a checklist. I don’t want to put you out of a job but it could be useful to use this stockopedia feature to help avoid some potential pitfalls.
Happy new year to you and everyone else here, may the investing gods smile on us all for 2023.
Good morning MattH,
That's a nice idea, and I have pondered creating something like that myself - i.e. a rules-based balance sheet scoring system. The only thing is, it's quite subjective (because each company is different), and varies wildly from sector to sector.
I'll give it some more thought though, as it would be good to put something together, even if it's quite simple. As always though, finding the spare time is the difficult bit.
Regards, Paul.
My morning smallcap tweet: Austerity diet
Allergy Therapeutics (LON:AGY)
◄Allergy Therapeutics (AGY)► FY-June audit not ready. Shares will be suspended on Jan 3. Co "not aware of any material change that will be required to be made" to the prelims. Co " reviewing all funding options" (as announced) so probably a going concern issue. [SP=11.34 Cap=77m]
Thanks for another year of daily updates MrC, it is much appreciated
Someone suggested this Allergy Therapeutics a couple of weeks back.
He actually said that he was buying quietly every day and building up a stake and insisted even after being challenged that this company is just a cash burner and will need a huge fundraise.
Have a happy new year everyone.
Was me …sadly. I no longer hold as sold at a loss. Looks messy now. Broke my own rules on AGY. No one gets all their calls right. It’s the nature of the game.
That's a classy response Raleigh4343, well done.
As you say, we all make mistakes, I've made heaps this year.
Hi Paul
In my opinion if one has made mistakes this year your probably not telling the truth.
Me I held Boohoo (LON:BOO) down to selling last week at 37p from buying at 400p for a high five figure loss.
Anyway onwards and upwards.
Happy New Year all.
Regards
Michael.
Hi there Paul,
Someone alerted me to your post.
So basically whoever gets it more wrong is popular here , but the person that tried to protect the community from another shambles of a plc company is not welcomed or not even thanked for his effort.
I thank you yiannos1 for your effort and please keep it up.