Small Cap Value Report (Thu 29 Feb 2024) - ADF, MACF, WIN, RENX, HWDN, DRX, AVCT, HEMO, POLX, CRN, HTG, ZOO

Good morning, it's Paul & Graham here, as usual!
I forgot it was a leap year, so happy 29th February, and good luck with any marriage proposals!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
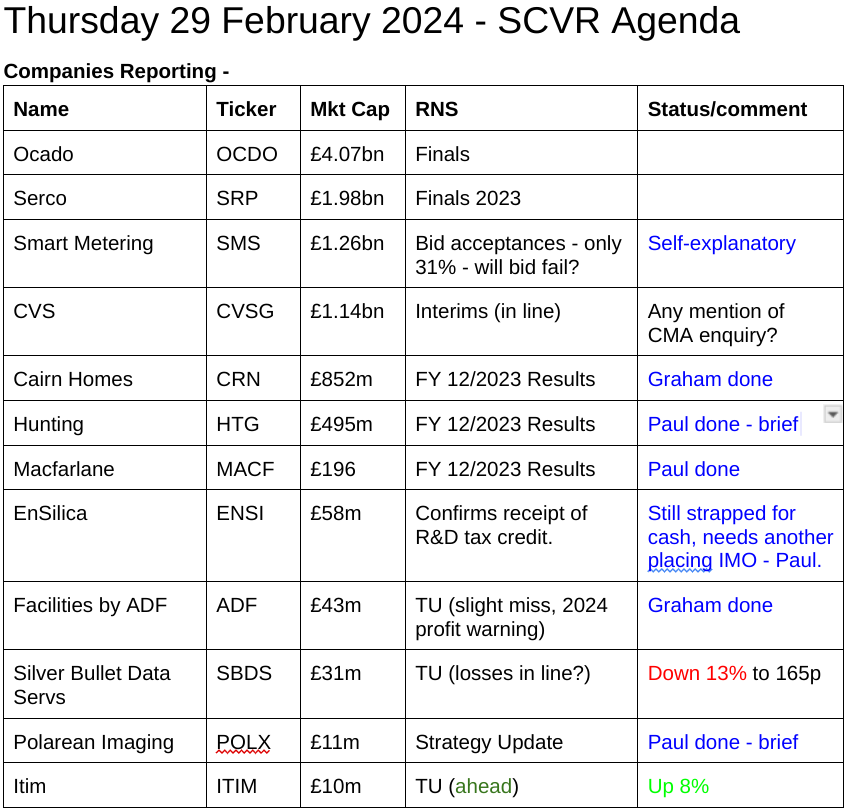
Other mid-morning movers (with news) -
Wincanton (LON:WIN) - up 18% to 600p - New cash bid at 605p!
Terrifically exciting news here - a new bidder (US logistics co GXO) has blown away the existing 490p offer from CEVA Logistics. Sky also reported that Clipper was sniffing around here too. GXO says it has 28% support already. Interesting detail in the announcement shows that the price is 11.9x IAS17 EBITDA, but £45m anticipated synergies (seems a lot!) brings this down to only 7.0x. GXO’s own StockReport shows that its shares are valued at 10.8x EBITDA, so I can see why this deal stacks up. Yet again, we’re being shown how UK small-mid caps are just too cheap! Rich pickings to be had, as this deal demonstrates.
Renalytix (LON:RENX) - up 12% to 33.5p (£33m) - FDA approval for its kidney tests. Good news, but there’s the small matter of the company being almost bust! Huge losses have burned through the cash pile, with only a scrap remaining at Dec 2023, probably down to almost nothing by now. Interims issued 15/2/2024 make grim reading, with “substantial doubt” over going concern. Urgently needs a large fundraise. Harwood own 10%, will they help refinance it? Maybe, but I wouldn’t want to be a hapless small shareholder - your risk of dilution/wipeout looks extremely high. So until it’s refinanced, it has to be bright RED, as currently super-high risk of insolvency/big dilution. Let’s hope it turns out alright, but I definitely wouldn’t want to risk my own money on something with such adverse risk:reward.
Howden Joinery (LON:HWDN) - up 8% to 837p (£4.6bn) - FY 12/2023 results are in line. PBT down 19% to £328m, down 15% if adjusted for week 53 costs. Outlook - encouraging start to 2024, with revenue rising, and “confident” overall. Strong bal sht, talks about returning surplus cash. Looks a nice business, with decent margins, although not an obvious bargain on PER of 16, compared with a lot of the small cap building supplies companies which are much cheaper (albeit lower quality).
Drax (LON:DRX) - up 9% to 456p (£1.75bn) - FY 12/2023 results show big rise in profitability. Outlook for 2024 in line. Increased divis. StockReport shows fwd PER only 3.8x and 6.1% yield. So worth a closer look, although obviously it’s a complicated business & energy market - profits may not be sustainable long-term at current elevated levels? It needs careful research I think, no opinion from me, but some attractive headline numbers do look interesting. Recent press accusations of burning the wrong type of wood also needs looking into.
Avacta (LON:AVCT) - down 31% to 51.8p (£146m pre-dilution) - drops on news of a 50p placing to raise c.£25m, 18% increase in share count. Co says this raise gives it 2 years cash runway to develop cancer treatment.
Hemogenyx Pharmaceuticals (LON:HEMO) - down 23% to 1.92p (£22m pre-dilution) - raises $4.2m in 2p placing, to fund leukemia treatment. It hasn’t even reached phase 1 trials yet, so this won’t be the last fundraise I would suggest.
Polarean Imaging (LON:POLX) - down 17% to 4.25p (£9m) - Strategy Update - as if on cue, this serial disappointer pops up. “Notoriously lengthy process” of 18-24m to sell into hospitals. Cost cuts done mid-2023, $6.1m cash left at Dec 2023. Cash runway extended a bit from Jun 2024 to Oct 2024. Refinancing - minimum needed is $10m, with $7.6m committed from 3 named investors, but on unknown terms. Will need another $20-25m additional funding to reach profitability by late 2027. Paul's view - I got excited about this project in the last bull market, and got it hideously wrong. Management under-funded it, and existing equity is now almost worthless, as everyone could see it needed more cash. Who knows what terms will be for this latest raise, no pricing is indicated. Whoever is providing the next funding round can call the shots, so existing equity could easily be diluted away to nothing unless instis stand their corner and decide to be kind to small investors. Such a pity it’s been so badly managed, as the project itself looks good long-term. AIM is the wrong place for this type of business.
Hunting (LON:HTG) - up 10% to 330p (£545m) - FY 12/2023 Results - the share price has seen an accelerating rise this morning, catching my attention. “EBITDA, ahead of previous guidance provided, and increased by 98% to $103.0m.” “$83.1m of previously unrecognised deferred tax assets recognised at year-end.” Adj PBT up from $10m to $50m - impressive. Superb balance sheet. This looks interesting! Not a detailed review, but I’ve seen enough to say this seems worth a closer look.
Zoo Digital (LON:ZOO) - down 10% to 23.25p (£23m) - no RNS today, but I see Canaccord reduced from 11.98% to 10.95% yesterday - they can be brutal sellers when they lose confidence in a share. Also possible read-across from ADF profit warning today? ZOO doesn’t interest me, but people keep hoping it might recover from the ending of the industry strikes.
Fundraises Generally
A pattern seems to be emerging, where speculative companies run out of cash, then they pump the share price with upbeat-sounding RNSs. Shortly afterwards they announce a discounted placing into any subsequent share price rise. Private investors speculating on these shares, buying the price rises, seem to be lambs to the slaughter.
It doesn't seem right to me that shares are still trading, when the company is secretly offering discounted shares to larger investors in placings. It's often obvious from the share price that news has leaked. We really do need the rules changed (and/or enforced), so that shares are suspended when any company decides to do a fundraise. Also we need quicker, cheaper mechanisms for companies to raise cash.
In the meantime, there's a simple way to avoid being clobbered by a discounted placing - don't buy or hold any share where the company doesn't have a cash runway of well over 12 months. Ideally investments should be companies which are profitable and cash generative, hence won't ever need to raise more cash just to keep the lights on.
Jam tomorrow/ blue sky shares are a graveyard for optimistic investors, avoiding these things has been the biggest boost for my personal portfolio returns. That said, the odd one multibags, which is what excites people.
If we invest in jam tomorrow companies, the risk is that we get sucked into throwing good money after bad, by averaging down to lower our average buy price after each piece of bad news. I've heard some horror stories of gullible investors throwing away large amounts of money doing this. My current view is that if the original business plan has gone badly wrong, and there's a clear need for additional funding, then I need to just admit I got it wrong, and sell up. I can always revisit it later, once the funding has been sorted out by someone else, once risk:reward might have improved to looking favourable, as stale bulls throw away their shares for next-to-nothing. I'd much rather be averaging up into a rising share price on the back of positive news. Chasing a falling share price, in the hope that there will be salvation from a sudden turnaround does occasionally work, but who can time these things? Speculative stuff often falls way further than anyone anticipated, even to zero.
Anyway, all good reasons to try to avoid pretty much all the cash burning, loss-making companies. It's so risky, and like searching for a needle in a haystack.
Summaries of main sections
Facilities by ADF (LON:ADF) - down 11% to 47p (£38m) - Trading Update (profit warning) - Graham - BLACK (profit warning) - on fundamentals: GREEN
Cavendish has written down 2024 estimates as ADF reveals that the 2023 strikes will have some knock-on effects in H1 of the current year, as schedules have had to be reorganised. I tentatively take a positive stance, looking for performance to pick up again in 2025.
Macfarlane (LON:MACF) - 123p (pre-market) £196m - Results FY 12/2023 - Paul - GREEN
One of my favourite value/GARP shares. Comes up with the goods, with decent 2023 figures, I go into a fair bit of detail below, and find everything satisfactory. Looks a nice long-term, boring, but good value share to me.
Cairn Homes (LON:CRN) - down 1% to 126p (£817m/€954m) - Results FY 12/2023 - Graham - GREEN
This housebuilder confirms 2024 guidance with a target ROE of 15% and continued strong growth in revenues and operating profits. It will soon have completed its second €75m share buyback. I’m very impressed by its performance and goals, and maintain my positive stance.
Paul’s Section:
Macfarlane (LON:MACF)
123p (pre-market) £196m - Results FY 12/2023 - Paul - GREEN
Through its two divisions, Macfarlane Group services a broad range of business customers, supplying them with high quality protective packaging products which help customers reduce supply chain costs, improve operational efficiencies and sustainability and enhance their brand presentation.
Shore Capital helpfully updates us today, saying these numbers are c.4% ahead of expectations.
I’m pleased to see MACF has for the first time added adjusted numbers to its highlights table. This was a glaring omission in the past, and didn’t make sense, showing only the unadjusted figures, which were out of step with the adjusted figures published by its own broker. So this is great to see, and saves me the trouble of having to manually adjust the figures for goodwill amortisation mainly.
The only figure missing below which I would have liked, is adj EPS (which Shore Capital calculates as 12.8p [up 6% vs 2022]- this is the key number that I use for valuation purposes) -
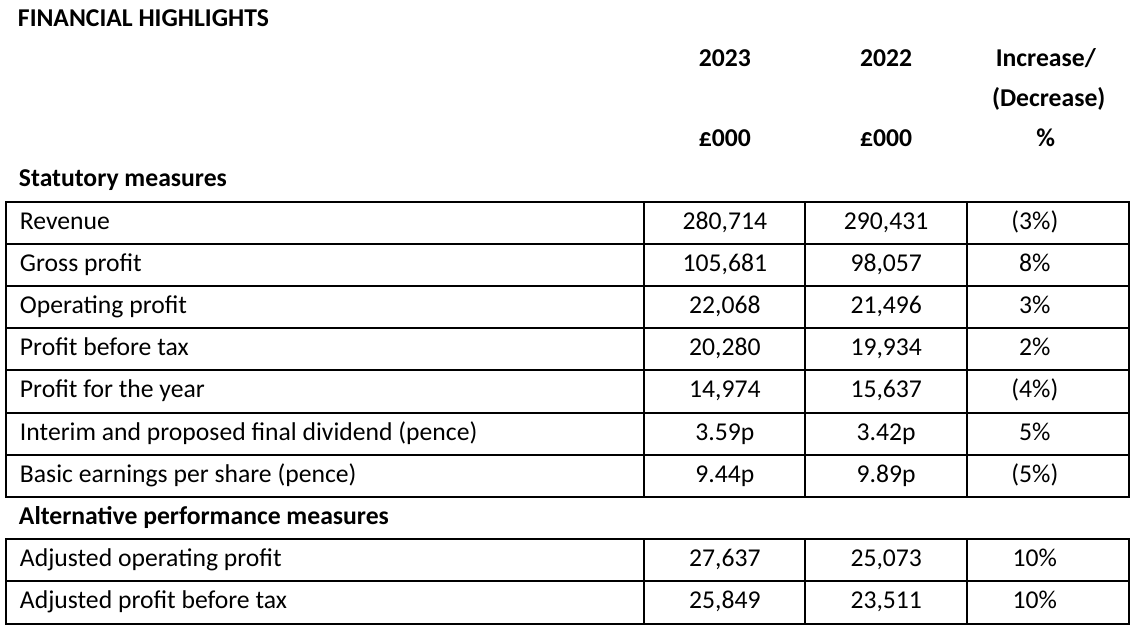
The company summarises performance neatly here -
Group profit before tax in 2023 was ahead of the previous year. This profit growth has been achieved through the completion of three high quality acquisitions, effective management of input prices, good progress in Europe and stronger new business momentum which has offset weak customer demand in the UK and Ireland, sales price deflation and inflation in operating costs.
Adjustments - as this is a new (and welcome) way of presenting the figures, I’ve checked the note (see below) and it’s simple, and perfectly reasonable. So I’m happy to value MACF shares on the adjusted figures, which also makes it consistent with how other companies are valued too, and shows us the true underlying trading performance of the business in my opinion -
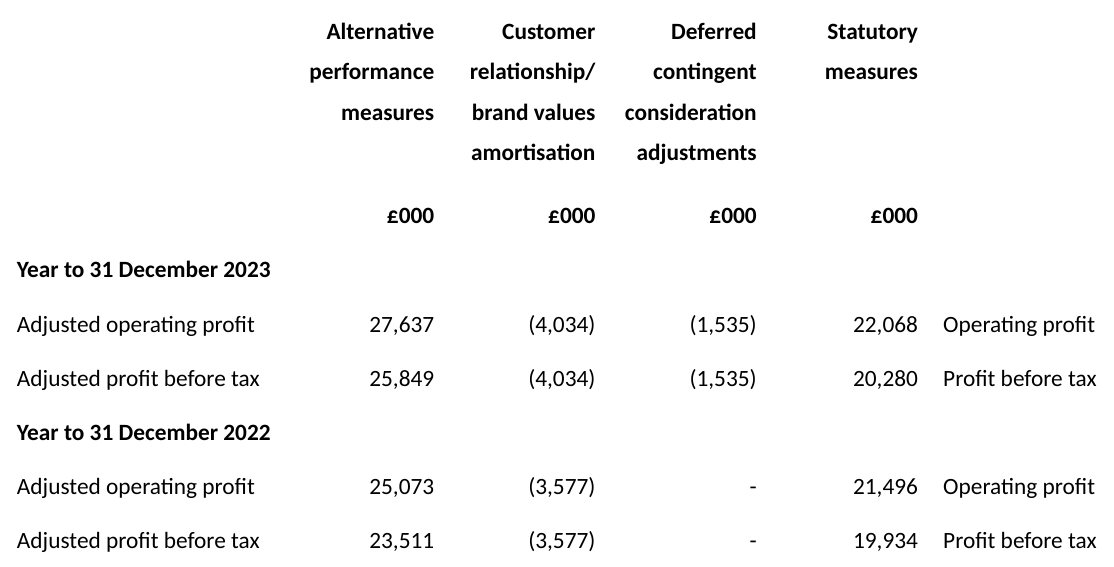
Valuation - at 123p/share, and 12.8p adj dil EPS, the PER is only 9.6x - good value, but packaging shares seem to be lowly rated generally.
Shore has a slight fall to 12.4p forecast for FY 12/2024, which is due to a full year’s higher tax charge. Note that the higher 25% corporation tax rate is now suppressing EPS growth temporarily at most companies - so it’s quite normal to see PBT up, but EPS slightly down, due to higher tax charges. We could see a similar effect next year, as the full year impact of 25% corp tax compares with only a part year of higher taxes in calendar 2023.
Basic and diluted earnings per share were 9.44p per share (2022: 9.89p per share) and 9.34p per share (2022: 9.78p per share) respectively largely due the higher tax rate of 23.5% in 2023 (2022: 19.0%).
Balance sheet - cash & liquidity all looks fine -
Net bank funds were £0.5m on 31 December 2023, following a net cash inflow of £4.0m in the year, even after £16.6m (2022: £11.9m) of investment in acquisitions and capital expenditure.
· The Group is operating well within its bank facility of £35.0m and relevant covenants which run until 31 December 2025.
· Pension Scheme surplus of £9.9m at 31 December 2023 (31 December 2022: £10.2m). Following conclusion of the 2023 triennial valuation nil contributions are required from 1 January 2024 forward.
NAV is £115m, but the biggest number is goodwill & similar of £87m, which I always remove. That gives NTAV of a modest £28m, which includes £9.9m pension surplus, which I would usually also remove, unless there’s a clear route to receiving the surplus in cash. On this it says -
The Group is working with trustees to prepare the scheme for buy-out. This process is not expected to be completed during 2024.
I’m assuming that would probably not involve MACF receiving much, if any cash, but do leave a comment if that assumption sounds wrong. I’ve searched through the RNS today, and can’t find any more detail on the pension surplus. It’s good news anyway, as no further deficit recovery payments are needed.
The rest of the balance sheet looks fine to me, with no funnies. Inventories in particular look lean (good), and receivables under control vs revenues. Which adds to my perception that the CFO is running a tight ship here. Prompt reporting of 12/2023 figures today reinforces that view.
Cashflow statement - is lovely, and benefits from some favourable working capital movements (reduced inventories & receivables).
MACF generated about £26m of post-tax cashflow (after I adjust to deduct lease financing costs). Of this, the main uses were acquisitions £14.5m, divis £5.5m, and a little capex of £2.2m. That’s it! MACF is a really simple business to understand, with nice clean numbers.
In some ways I find cashflow statements clearer than P&Ls, and we should generally focus more on cashflows (some investors don’t seem to even read them) - because it’s much harder to hide the truth on a cashflow statement, than on a P&L.
Outlook - nothing exciting, but nothing alarming either -
We expect the year ahead to remain challenging due to uncertainty over customer demand. However, we are confident that we will continue to make progress in 2024 through strong new business momentum, a well-developed pipeline of potential acquisitions, the continued effective management of input prices and operational efficiencies…
However, our strategy and business model have proved to be resilient and despite these challenges we expect 2024 to be another year of growth for the Group.
I feel that the way MACF sailed through the pandemic, and the energy/cost of living crisis more recently with barely a scratch, proves this is a resilient business model, and it appears well managed. So I’m not worried about macro downside risk.
Paul’s opinion - I wanted to dig into MACF’s numbers properly, because it’s one of my favourite value/GARP shares, and is on my 2024 top 20 shares ideas list (doing well so far, but it's early days). I’m not necessarily expecting anything barn-storming from MACF, but overall it seems an excellent value GARP share. It’s making apparently good acquisitions, which it’s mainly self-funding from own cashflow generation. There doesn’t seem to have been any dilution since 2017, yet profit & EPS have roughly doubled since then. Despite all the chaos of pandemic, energy, soft GDP, etc. To me, that is the mark of a good business, with capable management.
Shareholders also get a c.3% dividend yield too. Not overly generous, but that’s because most of the cashflow is funding bolt on acquisitions. So management always has the option to stop acquisitions, and pay out divis in high single digit %. It's that high dividend paying capacity which is more important to me than the actual yield, taking a long-term view.
I think this share is best seen as a nice long-term investment for very patient investors who are not going to get itchy fingers if it’s not multibagging overnight!
The fragmented shareholder register means it could attract takeover interest too - someone could offer a 30% premium and still end up getting a bargain.
Overall, it's an easy thumbs up from me, as a decent long-term investment idea - GREEN.
Graham’s Section:
Facilities by ADF (LON:ADF)
Share price: 47p (-11%)
Market cap: £38m
This is “the leading provider of premium serviced production facilities to the UK film and high-end television (“HETV”) industry”.
I tend to associate it with actor’s trailers but there are several other vehicle types provided by ADF.
Today’s trading update is for 2023:
Revenue £34.8m (market expectation: £35m, previous year: £31.4m)
Adj. EBITDA £7.3m (market expectation: £7.5m, previous year: £7.9m)
2023 saw a record H1 performance, but then H2 was disrupted by the writer and actor strikes (we discussed this issue quite a bit last year - overview by Paul here. Wikipedia article here).
Outlook for H1 2024 is “significantly ahead” of H2 2023, although we can’t expect another record performance as we had in H1 2023:
Notwithstanding the end of the Strikes, the impact on the film and HETV industry has carried on into H1-FY24 with film and TV producers having to reorganise the schedules of all relevant parties (studios, cast, crew, ancillary services etc), which is proving challenging at short notice. This has meant there will be a one-off reduction in utilisation in H1-FY24 before returning to a full second half, more in line with pre-strike levels. The Board will provide further guidance in this regard on publication of its audited full year FY23 results.
CEO comment:
"Our performance in FY23 demonstrates the Group's resilience with a strong first half countered by the first joint strike of Hollywood actors and writers in over 60 years. The effects of the strikes will continue to be felt through the first half of the current year, but we will carefully manage our cost base during the period. The long-term market dynamics remain very much in ADF's favour with continued high levels of investment in the UK HETV industry and the Board is confident that we will return to pre-strike order levels and beyond as conditions normalise."
Graham’s view
As Paul said last year, in reference to ADF, the obvious time to buy is when something temporarily impacts performance - this is a lesson that’s useful for any share. Essentially there are two things to figure out:
a) is the problem temporary, not recurring?
b) putting the temporary problem to one side, is the company a good long-term hold?
In the case of ADF, I feel confident in saying that the strike was a temporary problem and is unlikely to recur regularly. ADF’s CEO has pointed out that it was the first joint strike by writers and actors in over 60 years. Yes, it dragged on for a long time. But I would be shocked if strikes of this magnitude and duration became a common occurrence in the industry.
As for whether or not ADF is a good long-term hold? I haven’t got such a strong view on this. I can’t see any competitive “moat” in the provision of these vehicles and even in the absence of strikes, I expect that demand would be volatile.
I should also mention that estimates have been revised lower today, in response to the new 2024 outlook. Cavendish have reduced their revenue forecast for ADF from £58m to £47m, and their adj. net income forecast from £7.6m to £5m.
So the stock is currently trading at about 8x adjusted earnings for the current year, these forecast earnings being depressed by the knock-on effects of the strikes.
I’ll tentatively take a positive stance on ADF shares, hoping that performance will normalise in H2 of the current year and that 2025 will be entirely normal, allowing for performance to improve.
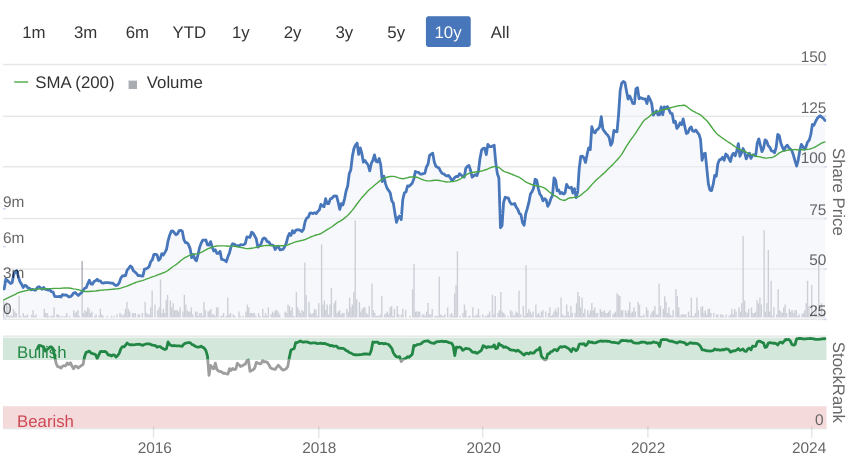
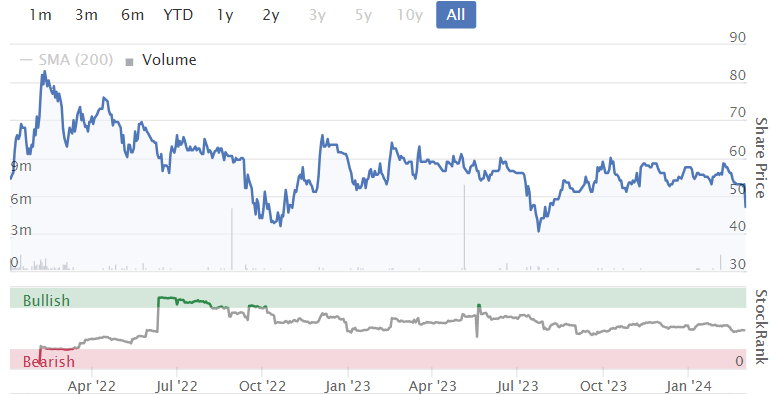
This stock IPO’d at 50p in early 2022. Today’s share price gives investors a small discount to that level:
Cairn Homes (LON:CRN)
Share price: 126p (-1%)
Market cap: £817m / €954m
We already covered the trading update from this housebuilder in January. I’ve been positive on the stock due to its very strong order book, a reasonable valuation and a declining share count as it buys back its own shares.
Today we have the actual full-year results for 2023, with the following highlights:
Revenue +8% to €667m, at a slightly improved gross margin (22.1%).
Operating profit +10% to €113m
ROE improves from 10.8% to 11.3%
I always appreciate seeing a company use its ROE or its ROCE as a key indicator - this doesn’t happen enough.
Cairn’s net debt was almost unchanged year-on-year at €148m. This was very much the company’s choice: they returned €75m to shareholders during the year in the form of a share buyback.
In 2024, they already announced and began a new €75m buyback. Most of this new buyback has been carried out already; it is expected to complete “in the coming months, at which point the company will issue a further capital allocation update”.
CEO comment excerpt:
Our sustained positive momentum has carried through into 2024 and strong sales since the beginning of the year has seen our closed and forward order book growing further to 2,473 new homes. We continue to invest heavily in work in progress as we ramp up delivery across our 20 active construction sites. Cairn will deliver another year of strong growth in volumes, revenue and profitability.”
The forward order at the end of 2023 was 2,350 homes. I’m not sure how sustainable this is, but it’s great to see that it’s continuing to grow and is now nearly 2,500 homes, with sales value c. €950m.
Economic backdrop - this is thought to be “supportive” with falling inflation, nearly full employment, strong consumer spending and a growing population. The cost of living crisis is very real but from a housebuilder perspective, there is plenty of demand for new homes and political support for new construction.
I’ve noted before that Ireland could arguably support 60,000 new homes p.a. Cairn has this to say:
There continues to be a significant structural demand for new homes and despite the delivery of 32,695 new home completions in 2023, the highest since 2008, the Housing Commission estimates that c.42,000 – 62,000 new home completions are required per annum.
There will be a general election in Ireland at some point in the next twelve months, and housing will be one of the biggest topics due to widespread concern around a shortage of accommodation of all types. This surely can’t be a bad thing for housebuilders!
Outlook
The order book already mentioned supports the FY 2024 outlook, “with the Company poised to deliver another year of exceptional growth in volumes, revenue and profitability”.
The company has an ROE target of 15% (more companies should have this!) which it expects to deliver this year.
2024 guidance is re-confirmed:
c. 2,200 units (2023: 1,741 units)
Operating profit €145m (2023: €113m)
Graham’s view
I remain seriously impressed by Cairn’s financial performance. It’s clearly very focused on ROE, with buybacks serving the dual purpose of a) exploiting a good value share price for the benefit of all shareholders, b) keeping the balance sheet efficient, so that the ROE target of 15% can more easily be achieved.
Of course this does elevate the risk levels and means that investors need to be that much more vigilant. It would be more impressive if the company could hit ROE of 15% while in a net cash position, rather than with net debt of nearly €150m.
But with operating profit guidance of €145m, the debt load should be manageable.
Let’s check the overall share of the balance sheet:
Total assets slightly over €1 billion, with the vast majority of assets being inventories classified as current assets.
Total liabilities €280 million, including €170m of gross loans and borrowings.
Total equity €757m
Cairn has a 35 site land bank with 16,300 potential units. While I would guess that €757m is quite a low estimate of the true value of Cairn’s assets, the difference will be reflected in future profits.
Putting it all together, I’m comfortable to maintain my positive stance on these shares at a market cap equivalent to c. €950m.
It’s no longer that bargain that it was, now trading at a price to book value of around 1.3x:
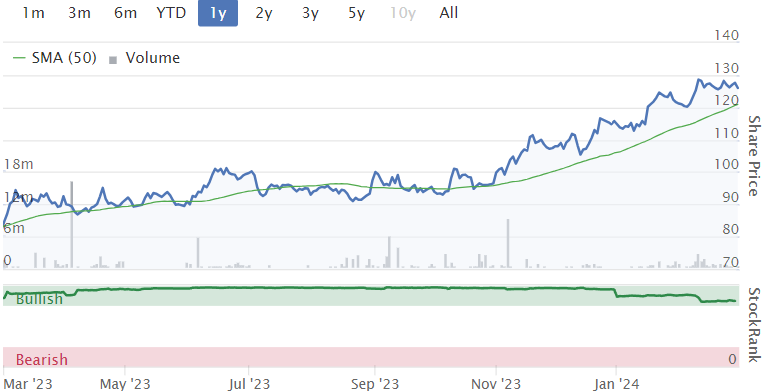
Maybe it has already reached fair value, but I’m still excited to see what might happen as the company continues to reduce its share count.
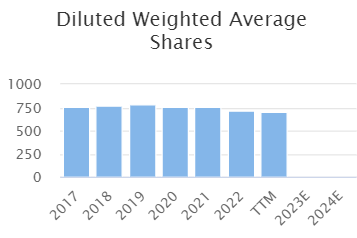
The buybacks achieved tremendous value last year. This year, they are still happening at an attractive PER or earnings yield:
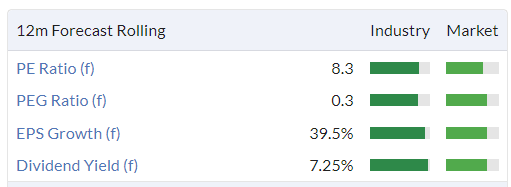
Of course all housebuilders will suffer in the wrong economic conditions. But if I was picking up a housebuilder today, it would be on the assumption that we are not about to get an economic hammering. And I would want either a very cheap housebuilder (at a discount to book), or one that is high-performing and still not overly expensive. Cairn could fall into that second category. And if the share count keeps falling while profits remain robust, then shareholders should do well, even from current levels.
So I’m still positive on this one, but there is a level where I would switch to neutral. That would probably be at a price to book value of anything above 1.6x, i.e. if it reached as high as 200p over the next six months.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Hunting (LON:HTG) - "Guidance beaten in FY23 and unchanged for FY24" (research report here: https://www.equitydevelopment....)
Hunting delivered EBITDA of US$103m, ahead of revised guidance and the inferred year-end expectation, representing a 98% y-o-y uplift (and 11.1% margin, +380bp). Significant contract awards boosted Subsea and OCTG activities in particular, but top line progress was also accompanied by good cost control to deliver the full year outturn. A record year-end order book position leaves the company well-placed to deliver further progress in FY24, where guidance is unchanged.
At the headline level, Hunting delivered group revenue growth of 28% and margin progress (ie gross +90bp to 24.5% and EBITDA +390bp to 11.1%), feeding into a fivefold increase in pre-tax profit with EPS up over four times in FY23. The full year dividend rose by 11% to 10c per share, covered twice by earnings.
Against our selected peer group average, Hunting’s P/E and EV/EBITDA multiples sit on discounts of 25-30% and 20-25% respectively. Taking a simple average of our P/E and DCF based analyses generates an unchanged fair value per share of 407p.
"Jam tomorrow/ blue sky shares are a graveyard for optimistic investors, avoiding these things has been the biggest boost for my personal portfolio returns. That said, the odd one multibags, which is what excites people."
And that's what keeps me buying the (very) occasional punt only to sell it for £100 profit instead of the 10 bags I could have got on Helium One Global (LON:HE1) recently, doh !
Need to have some fun in any game. And its a game.
Who was the guy - Livermore - won lost suicide. Dumb. Health is and family - just need to remind myself often.
Wincanton (LON:WIN) - a real bidding frenzy. I don't hold directly, but at least Aberforth Smaller Companies Trust (LON:ASL) are making a very good profit on their 10% holding.
Volume leaders so far today
Cairn Homes (LON:CRN)
Graham, thanks for taking the time to have a look at Cairn Homes, it is appreciated. I have just noticed that there has been a buyer of £2.0million worth of stock this afternoon.
I know I am wasting my breath with this request but I am going to say it anyway.
If, like I, you dip in and out of the SCVR during the day the best way to read it is in UNTHREADED mode, otherwise you have to scroll all the way thru every time to pick up new comments/replies. However if you do this you will see comments like this ;
topturkeyJoined 202079 posts12 minutes agoIn reply to NewInvestor1972
Who were Paul's friends who were well renowned people in the know per the scvr initial posting?
It was always speculative and I also followed in wrongly on this one in a meaningful way around 4% of portfolio at one point
So with apologies for picking topturkey's example please can I, and I am sure lots of others, ask that each comment is tagged with the @ followed by the ticker to give what you are saying some context.
Please
Just would like to say thanks to Paul and Graham for the stellar work load over the last few days. Good job by both of you. It is appreciated.
Been watching my most hopeful share Resolute Mining (LON:RSG) slowly drop over the last few months. A lot of small trades went through yesterday all at the same time. This looked to me as if a seller has finally cleared out. Then all of a sudden today it shoots up 8% which makes me think that the seller has really cleared out. Anyone got any insight they would like to share on this one?
A £3.6m miner with SR 89 and Value 87 and in profit - gobsmacked am I.
Thanks for the 'heads up' but have no 'insights'. Resolute Mining (LON:RSG)
Hi harry, Resolute Mining (LON:RSG) £363m.
Possible positive for gold now is recent US data.
“Gold scaled a one-month high on Thursday as the dollar slipped after inflation data came in line with expectations, with traders' attention turning to further commentary from Federal Reserve officials for cues on interest rate cuts.”
who knows if this will be the reversal of the sp but rsg is cheap and has 11.2m oz to mine so it’s in a good place atm.
Hope you bought some Resolute Mining (LON:RSG) Harry. Ended well today. Markets looking at US rate cuts begging soon. Here’s hoping or it will slide back down.
Agree with your comments on fundraisings Paul. Id be careful of any speculative company announcing something not signed and delivered......future potential collaborations, possible MOU, unsigned contract wins etc. Even a flurry of pointless news releases together is suspicious. All very well saying im a long term holder but if a placing ends up at a 30-50% discount I dont get bonus points for just holding.
" I'd much rather be averaging up into a rising share price on the back of positive news. Chasing a falling share price, in the hope that there will be salvation from a sudden turnaround does occasionally work, but who can time these things? Speculative stuff often falls way further than anyone anticipated, even to zero."
100% agree! Averaging up is where Ive made most of the big gains. If its trading ahead, news is good, price is moving up, in a good sector, earnings upgrades..... buy more. If its growing well it'll be rated higher than most, chances of a profit warning are greatly reduced so much safer than bottom fishing. Just my tuppence worth
This is a simple screen I use, these are the types of companies I prefer to be in rather than having anything to do with profit warnings or stagnating share prices/falling earnings. Want something to be happening or its dead money. Many of these you can spot from RNS or broker notes the day before they start to show up on stocko, but useful none the less.
re Pauls comments on avoiding all the cash burning, loss-making companies. It does feel that the good ones rarely make the UK/ AIM markets but instead they fine Private Equity funding and have proper business plans! There are some good exceptions (to any such broad comment) of course. It also feels that the P/E players treat the UK fund managers / markets as dunces looking back at the previous floats. Which leads me to conclude that 1. private equity with its apparent low valuations might be a good section to invest in and 2. if investing in a small cap fund the likes of Rockwood (which frequently gets mentioned on these boards and I did not really know about before) - with a street smart type manager - holds attractions.
"It also feels that the P/E players treat the UK fund managers / markets as dunces looking back at the previous floats"
Many of them are dunces, I wouldnt leave them alone with my bike for an hour let alone my money. Lots of very intelligent, well spoken, well educated people no doubt but many (not all) seem to lack any basic common sense.
Many of them are dunces...
Unlike the sagacious and well-informed individuals who frequent this forum!
There are times when I wish Stockopedia allowed smileys. ROFL
I was typing this earlier when news that DLG have given cold shoulder to Ageas came through but it might be helpful to post anyway
Direct Line Insurance (LON:DLG) Ageas are the most likely bidder. When you look at the 10 largest in the Uk https://www.insurancebusinessm... only Admiral look like a realistic fit. Whether Aviva or Allianz could get it done possibly doubtful on market share grounds. Allianz recently gobbled up LV's general business so I doubt they would try. Aviva have not done much for a while so might be tempted? RSA has gobbled up NIG (sold by DLG) and exited personal lines (Which is DLG's business) so they are out.
I was going to say - suspect some background talks between Ageas and DLG have been continuing hence the apparent press speculation. Likely Ageas are playing the long game.... But - todays update means Ageas would likely have to go hostile to make it work it seems.
Strategic reasons here - https://www.postonline.co.uk/p...
The last time I remember a take over being enthusiastically received amongst the big boys of the UK Insurance industry is way back when Commercial Union/General Accident (CGU) had made such a mess of their merger they offered to buy Norwich Union and give its boss the top job of running its UK operations ! Result was Aviva !
Just a thought - I wonder if / where SABRE insurance fits in - its small and seems to be doing well
Sabre Insurance (LON:SBRE) Small specialist outfit, specialises in the high risk end of the motor market - my knowledge on this firm is at least 10+ years out of date now but it typically did young drivers and higher powered cars and a combo of the both through the broker market - which the bigger insurers always struggled to accommodate / make money out of. Did not do home insurance. Reputation was never as good as the big boys. I have seen them on compare the market type websites.
What that means these days for Sabre - not exactly sure but if it can keep its niche in the market then it should do OK
It has a B- rating from S&P if that drops any further then that would be a red flag. For as many brokers would be prevented from dealing with it as their PI would not allow them to deal with "poorly / unrated rated" insurers (whatever poorly rated means). Not to mention the FCA compliance stuff.
There were historically many other players in the high risk/young driver market, mainly Lloyds motor syndicates or subsidiaries of the likes of RSA. These have now mostly gone. Some brokers are still surviving and running schemes for car insurance and appearing on the compare type websites.
One thing for sure is it seems harder and harder for insurers to make money out of home / car insurance these days despite the price increases.
Absolutely spot on Paul, time and time again this happens to the unwary investor and it's scandalous how easy it is to get away with it. Some of the financial press are complicit in this - on a regular basis. Perhaps they are plain lazy and don't do any research before they write a glowing article for a company promote - or perhaps they are just interested in any old story and just haven't got a conscience. Perhaps they don't have any financial experience at all and are just as unwary as some PIs. My tactic now is that if there is a sudden concerted effort by a co. to ramp its share price and its balance sheet is low on cash then if I'm holding the share I sell into the price spike - more often than not there's a fund raise coming soon.
Fundraises Generally
A pattern seems to be emerging, where speculative companies run out of cash, then they pump the share price with upbeat-sounding RNSs. Shortly afterwards they announce a discounted placing into any subsequent share price rise. Private investors speculating on these shares, buying the price rises, seem to be lambs to the slaughter.
It doesn't seem right to me that shares are still trading, when the company is secretly offering discounted shares to larger investors in placings. It's often obvious from the share price that news has leaked. We really do need the rules changed (and/or enforced), so that shares are suspended when any company decides to do a fundraise. Also we need quicker, cheaper mechanisms for companies to raise cash.
In the meantime, there's a simple way to avoid being clobbered by a discounted placing - don't buy or hold any share where the company doesn't have a cash runway of well over 12 months. Ideally investments should be companies which are profitable and cash generative, hence won't ever need to raise more cash just to keep the lights on.
Jam tomorrow/ blue sky shares are a graveyard for optimistic investors, avoiding these things has been the biggest boost for my personal portfolio returns. That said, the odd one multibags, which is what excites people.
FREng thanks for your post on Smiths News (LON:SNWS) and yes the 3 trades went through just before 11am. I hold. Very encouraging I think these shares are very cheap as results will surely show a big drop in debt and a great Divi payer.
Made Tech (LON:MTEC) analyst presentation and Q&A from last week video & podcast. Revenue is down 7% but they are focussed on cost control and productivity, which we are starting to see evidenced with the EBITDA margin up to 7% from 2% and adj EBITDA £1.4m v £0.5m. They have cash of £7.9m. The contracted order backlog is £61.3m, down from £67.9m but still healthy, sales bookings are slowing which might be due to paused decisions around the election. Over 70% of their business is from Central Government. The client list is impressive including DVLA, NHS England, Home Office, Cabinet Office, Dept for Education, Ministry of Justice, HMRC, etc. Neil Elton, ex Learning Technologies has come in as CFO, which is interesting. They've also recruited a new CPO.
Smiths News (LON:SNWS) I think Canaccord put out a broker rating today with a buy and target of 85p. (I hold)
Ocado (LON:OCDO) to make pretax profit in SIX years says its finance chief!
Take your time ; although that means never basically.
FTSE100 companies…….
Another request for Cairn Homes (LON:CRN) if you have time, please. We hold
Facilities by ADF (LON:ADF)
Somewhat surprisingly the shares have recovered to above 50p. The market is being unusually gracious. I have retained 60% of my holding following this morning's sale but remain a fair bit underwater.
It will be interesting to see if the price holds.
Yep a good bounce back. I’m not back in yet though. It’s in a downward move still so I’m hoping to see 35p where I’d pile in. Just feel it may take time to stop the downward trend and some good news to start it rising again. But who knows for sure?
I think we can safely say Polarean Imaging (LON:POLX) is going to zero this year, what a shambles of a company.
Who were Paul's friends who were well renowned people in the know per the scvr initial posting?
It was always speculative and I also followed in wrongly on this one in a meaningful way around 4% of portfolio at one point
Who were Paul's friends who were well renowned people in the know per the scvr initial posting?
Obviously I'm not going to name names, that would be completely out of order.
My point was that a lot of smart people backed Polarean Imaging (LON:POLX) and got it wrong. I suppose the lesson is that following smart/shrewd investors doesn't necessarily guarantee success. They get things wrong sometimes too, just like everyone else.
Sound like expensive, high capex machines too like Advanced Oncotherapy (LON:AVO) .Great medical technology, which is the most important point of capital markets for biotech in my opinion, but lousy long term investment (especially in a bear market).
Hopefully the technology will be picked up by someone who can carry on rolling it out.I think there are some bigger name investors. who smaller investors got encouraged by during the FDA run up excitement during the bull market.
Investor exits for biotech seem to be big Pharma takeovers or fast revenue growth eventually leading to profitability, as so much h R&D money is needed to get a biotech product/drug to market.More ‘fail’ and need to rely on investors’ continued confidence than imagined perhaps, even post FDA approval.Continual capital support and specialist scientific knowledge as well as a good bit of luck are needed for long term investors in this sector.
Increased offer for Wincanton (LON:WIN) - 605p in cash from GXO Logistics @ 8.35. I don't hold, unfortunately.....
Yup, I am the mug that sold my entire holding of Wincanton (LON:WIN) when the first bid came though #eggonface
Toad1957 - I wouldn't feel too bad. The first offer was a decent bump. I too took the money on the first offer. I'm new to the game and was my first takeover so wasn't sure how the share would behave afterwards.
Wincanton, counter bid from GXO Logistics of 605p. I was just offered 608p to sell.
Another vote for Cairn Homes (LON:CRN) if Paul or Graham have time, beautiful looking chart, nice covered dividend, and from memory not one of the names caught up in this pending government inquiry.
Graham's looking at Cairn now.
Thanks Paul hat tip to Graham
Big director buy announced at ASOS (LON:ASC) yesterday just before close.
474,000 shares @ £3.63819 worth £1,724,502
https://www.investegate.co.uk/announcement/rns/asos--asc/director-pdmr-shareholding/8061720
I've been thinking about the SHEIN UK listing. Would ASOS (LON:ASC) be a perfect takeover candidate for SHEIN and provide a turnkey solution for their UK operations?
ASOS (LON:ASC)
i would suspect they would want to pumell competitors into the ground rather than pay good money to buy the shares? who know though - is enterprise value of £1 bill decent value - for £3.3 bill pa sales ?
perhaps mr hunt may not get what he wants if shein do simply replace asos and ro boohoo so no net gain for uk.
It's in his fund
Seplat Energy (LON:SEPL) released its full year results today. Up a couple of percent but overall I am really pleased with todays results. A have summarised a few key highlights:
- Production up 8% to 47.8kboed
- EPS increased by 27% to US$0.14 (despite 20% fall in oil prices)
- Reserves increased by 9% to 478mmboe
- Cash flow was strong and net debt was reduced to US$306m (YE22 US$366m).
- Capital access stated that "On our current forecasts Seplat trades on a P/E for 2025 of 5.5x with EV/EBITDA under 3x".
-Production guidance for FY24 is 44-52kboed, in line with the current year.
- Special dividend announced for 3cents on top of the quarterly divi of 3cents, totalling 15cents. This is an annual yield of just over 10% on todays price.
- Guidance for start-up at ANOH (a shallow water natural gas plant) was reconfirmed as on schedule to produce first gas in Q3 this year, this should add substantial revenue add diversification.
- Seplat remains highly confident that the transformational MPNU acquisition from Exxon Mobil (NYQ:XOM) will complete this year. This is waiting signoff from the president. I must admit I was slightly disappointed to see them state "this year" as a timeframe, I was hoping for a more short term target e.g. coming months.
- No mention of the Naira depreciation impacting any aspect of the company.
Seplat Energy (LON:SEPL) is my largest holding at 12% of my portfolio, so I obviously suffer from confirmation bias and am overly bullish on the stock.
Is seplat prone to the devaluation in Nigeria?
From all the evidence I have available to me, my consensus is no. All sales of oil are in USD, as is the payment of the dividend (it has to be converted to gbp). As such there has been no impact from what I can see in the figures. The company has not mentioned it at any point.
There is some impact owing largely to the gas sales, but Seplat Energy (LON:SEPL) seem to managing the situation prudently (I hold).
See bottom paragraph of P11 into P12 at link below of full audited results for the detail the co has given re Naira impact.
https://www.rns-pdf.londonstoc...
Well noticed Snowbum, thank you for posting. I am at work had not had chance to read the full report yet. They address it with a lot of clarity and it doesn't seem to have much impact moving forward, despite hitting profits a bit this year.
To save time for others -
During the period, there was a significant adjustment in the exchange rate between the Nigerian Naira and the US Dollar, following CBN guidelines to unify multiple exchange rate windows to the Nigerian Autonomous Foreign Exchange Market (NAFEM). The closing rate for the year was NGN899.89/USD1, representing a notable difference from the rates in May
2023 of NGN461.28/USD1, before the new guidelines were implemented. The revaluation of the Group’s financial assets arising from the exchange rate difference resulted in a net (non-cash) loss of $27.7 million, compared to FX loss of $1.1 million in 2022. Overall, there is no adverse effect on the Company and summarised in the table below are the expected future impacts of Naira devaluations:
We have implemented several measures to control the impact of the Naira devaluation on financial performance including exhausting avenues to cover costs in Naira and ensuring utilisation of Naira's excess cash balances. Seplat will continue to utilise its Naira revenue (which will also increase in quantum in line with new exchange rates since gas and some oil (OML53) contract values are Dollar denominated although settled in Naira) to fund local currency transactions and constantly manage our holdings in Naira which usually doesn’t exceed 20% of total cash holding. By proactively monitoring this, the Company aims to mitigate potential risks arising from currency volatility. This strategic approach will allow the Company to safeguard its financial position, optimize its operations, and maintain resilience in the face of currency uncertainties
Note from the Capital Access - Operating profit of US$249.4m (2022 US$274.7m) was impacted by increased G&A, reflecting the cost of defending the vexatious claims during the year, adjustment for overlift and the FX impact of Naira devaluation. However, lower net interest on reduced net debt and a lower tax rate saw net income increase by 18.3% to US$123.9m (Figure 1).
So there must be some FX impact although its unclear what.
Oil traded in USD.
Edit: sorry ... did not see BenHazz's comment below.
They operate in Nigeria so obviously there is impact despite the oil still trading in USD. There are salaries , day to day operations , CAPEX etc.
Thanks
I do not hold Seplat Energy (LON:SEPL) as I to hold Afentra (LON:AET) in this sector.
However, this is what I am looking for to read in this forum. Mentioning that you are a shareholder of Seplat Energy (LON:SEPL) but you analyse with numbers the investment case scenario.
Thank you Yiannos.
http://newsfile.refinitiv.com/...
@sbds the @ is not working !! Silver bullet data services
Had a trading update this morning that read OK to me but the market has marked it down by 25%, just shows you how hard and risky it is to invest in pre profit companies. You would really need to know and understand the tech to get involved here.
It has risen a lot previously and is very volatile .
Silver Bullet Data Services (LON:SBDS) (The @ seems to be working). I sold some on the bell myself this morning then bought back about half an hour later. It appears that it may bounce back.
I added at 150p early doors. 2024 committed revenue already in excess of £5m and we're only in month 2! Hot AI space with A list clients. Silver Bullet Data Services (LON:SBDS)
Justin Waite interviews Ian James (CEO) of Silver Bullet Data Services (LON:SBDS) if anyone is interested.
Silver Bullet Data Services (LON:SBDS) is doing exactly what it said it would.
Early FY24 company confirmed it will be profitable - it had sufficient cash based on those projections at end of last year to just about get above cash breakeven but sensibly raised some money to give it a buffer so another raise shouldn’t be particularly likely/necessary in my view now.
Growth is very strong, client base is top notch and relationship with that client base seems to be strong, which is more important to me than the name itself. Plus 4D is now growing rapidly as first party data becomes prevalent and cookies are phased out.
Much lower risk now in my view operationally.
But it’s still a small market cap and therefore illiquid and will be volatile. There will have been a number of traders jumping on the bandwagon as it started rising so no surprise a few of those bailing out. But basically results and forecasts have come in exactly as I expected so no concerns from me from a personal holding perspective.
Cairn Homes and Macfarlane are more substantial holdings for us than the three I mentioned earlier, I await Paul's comments on Macfarlane's results which imo are creditable in difficult times, and hope Graham or Paul have time for Cairn too. Helvellyn has already commented on Irish v UK builders, I'm happy to second him on that.
Facilities by ADF (LON:ADF)
Somewhat terse and vague update. The effects of the actors and writers strike has perhaps unsurprisingly continued in H124. Cavendish has reduced earnings for full year 24 to adjusted PBT of £5M and adjusted EPS of 5.8p. I have little doubt the shares will get a soaking today, but will in time recover.
I have a reasonable holding, but have reduced it at the opening, on the basis that money has a time value and there are currently other more attractive investment opportunities.
Classic piece of mendacious PR from Facilities by ADF (LON:ADF) IMHO (I hold).
Gives outline figures for FY23, repeats already announced facts of record first half and Hollywood strike affected second half but talks about mitigating steps taken, giving the impression to the casual reader that these figures might be a modest outperformance. Buried in a footnote are consensus forecasts which show it's actually a miss (but at least they quote the consensus figures).
More seriously, they trumpet first half 2024 being well ahead of second half 2023, the message the news headlines pick up on. But this is to be expected following the end of the strike. The real message that they are trying to sneak out under the radar is that FY2024 will be (if Cavendish figures are right) around 30% below previous expectations.
The charitable view is we have a management team inexperienced in the ways of the stock market and poorly advised by broker and PR advisers such that they don't yet understand that the way to the market's heart is consistently to underpromise and overdeliver whilst those who do the opposite will be shunned.
The uncharitable view is that the company floated opportunistically at the tail end of a frothy market, doesn't really care what happens to the share price, fails to keep its broker and financial PR team informed and ignores their advice and will in due course go private again at a price lower than its IPO, whingeing about the City not understanding the business.
This ugly duckling could yet turn into a swan.
The contrarian in me wants to buy more at under 50p, the cynic in me wants to sell out and move on.
Which is it to be? Place your bets.
I don't hold but my main worry with this share is the glut of content from streaming companies may be coming to an end as Netflix seems to be emerging as the clear winner of the streaming wars. Paramount & Disney are discovering to their cost that streaming is not a great business model & can be near disastrous for the also rans.
Paramount Global (NSQ:PARA) actually released good streaming numbers yesterday - 67.5m subscribers, streaming rev up 69%.
I have learned (the hard way!) that if it is too hard to figure out - it is a sell! And move on to something that is not too hard!
Co promised more guidance with FY23 results but they managed to guide Cavendish already!
Spire Healthcare (LON:SPI) and PPHE Hotel (LON:PPH) good results increasing dividends good nav value nice and boring mid caps, minuium wage issues
SPI
I was expecting a much better result from this company. They should be rolling in in this market but it’s sedentary outcome to me.
It is one of my candidates for a takeover!
PPHE Hotel (LON:PPH) . I regard it more as a property company with a hotel business. It stands at discount of over 50% to its NAV of £26.72.
Spire Healthcare (LON:SPI) should be cleaning up though with the poor old Nash (NHS) on its knees. But the management have presided over sideways movement in the last three years when they should have been making hay. So I don't hold.
Facilities by ADF (LON:ADF) cheerful sounding update masks a 20% fall in forecast FY24 revenues and a 30% cut in PBT. To blame, continued ripples from the writers and actors strike. On the positive side, H2 should see a normalisation of trends. Now, where have I heard that before? Despite the cynicism of my observations, a big fall today would be a buying opportunity, I think.
The industry is incredibly quiet at the moment, and has been for months. No sign of that changing yet….
The industry is incredibly quiet at the moment, and has been for months. No sign of that changing yet….
Interested to hear if you can expand on that observation. My daughter works as a producer for Sky on outside sports broadcasts and never gets a day off! Of course, ADF is more focused on drama productions.
Hi :-)
Sports OB’s remain a very steady and predictable market. ADF generally service Film and TV drama which is a totally different market and is still exceptionally quiet…I know this for a fact as drama is my day job :-)
Sports OB’s remain a very steady and predictable market
Certainly true for scheduled sports like football and tennis which make up the bulk of OB work. My daughter however specialises in boxing - and fights on a card regularly herself - and that is anything but predictable!
There is a backlog of programs sitting waiting to be aired, consequently not much is being commissioned yet net alone being made. I work in factual but across all genres other than live, sports etc folk are not working. Commercials are probably doing alright and would be an end user of ADF but just days here and there.
Thanks TStubbs and Johnmooneywork, very useful industry knowledge.
Plus as well as the actors and writers striked, the streamers are cutting budgets, commercial TV is impacted by the advertising downturn and of course the inflation means a big real terms cut in the value of the BBC license fee.
Hence, after v many years of expansion, gloom is uniform across the majority of the sector (clearly excluding sport)!
Hunting (LON:HTG) FY results - looking good. They have a presentation with InvestorMeet at 11am today. (Edit: I hold.)
Order book increased by 19% to $565.2m.
Revenue increased by 28% to $929.1m.
Non-oil and gas revenue increased 59% from $47.6m to $75.9m.
Gross margin improved to 25% from 24%.
Some points from the Hunting (LON:HTG) investor presentation on InvestorMeet just now.
Quote from the final comments: "Buy now while it's cheap"!
Confident and positive presentation. Emphasised their expansion from oil-and-gas in North America to non-oil and gas revenue increasing 59%, and now across the globe, dwelling on the Asia-Pacific market. Also mentioned that SpaceX is a client, components for extreme conditions being their thing.
It was part of Mark Simpson's article last April on screening for Net Nets: The idea is that a company could cease trading, sell all its assets, pay all its liabilities and still return more than the current market capitalisation in cash to shareholders. However, the returns from this strategy rarely come from such liquidations. Before liquidation is necessary to extract value, a business often improves, and the market realises how cheap it has become.
My morning smallcap tweet: Buy and fold investing
Iconic Labs (LON:ICON) Kin and Carta (LON:KCT) Renalytix (LON:RENX) Supply@Me Capital (LON:SYME) BSF Enterprise (LON:BSFA) Mercia Asset Management (LON:MERC) Zytronic (LON:ZYT) Hemogenyx Pharmaceuticals (LON:HEMO) Facilities by ADF (LON:ADF) Getech (LON:GTC) Polarean Imaging (LON:POLX) Blackbird (LON:BIRD) EnSilica (LON:ENSI) Silver Bullet Data Services (LON:SBDS) ITIM (LON:ITIM)
◄Iconic Labs (ICON)► trading suspended by the FCA after c.138% rise yesterday. Co confirms it's in RTO talks. [SP=5.38 Cap=1m]
◄Kin and Carta (KCT)► notes that a 2 yr contract worth over $90m ended yesterday. KCT is providing services on a rolling basis and 'engagement with the client continues to be robust'. ?? FY outlook unchanged. [SP=128 Cap=228m]
◄Renalytix (RENX)► US adds kidneyintelX.dkd to its 10-year Government wide Acquisition Contract for early-stage kidney disease bioprognostic testing services. Also US National Government Services looking at approving KidneyIntelX and kidneyintelX.dkd testing. [SP=30.4 Cap=36m]
◄Supply@Me Capital (SYME)► guides H2-2023 rev broadly in line with H1. Expects contracts for its initial IM transaction (€10m funding) be completed by the end of March. Update on funding from The AvantGarde Group: £1.76m still outstanding. AvantGarde promises to cough up and is seeking finds to do so. Long-winded biz and funding update. [SP=0.03 Cap=19m]
◄BSF Enterprise (BSFA)► MoU with fashion company Maison Amelie Pichard to develop and sell accessories that incorporate lab-grown leather. [SP=8.39 Cap=9m]
◄Mercia Asset Management (MERC)► adds £207m to funds under management by British Business Bank. [SP=28.4 Cap=125m]
◄Zytronic (ZYT)► AGM stmt: FY rev exp unchanged. However "While disciplined cost control remains a priority during this period of reduced revenue generation for the Group, management recognises the need for increased investment in personnel, travel, marketing, and product development". [SP=73 Cap=7m]
◄Hemogenyx Pharmaceuticals (HEMO)► $4.2m placing at 2p, a 20% discount, to facilitate the development of the Company's Chimeric Antigen Receptor T-cells. [SP=2.41 Cap=28m]
◄Facilities by ADF (ADF)► slight miss in FY-Dec with rev £34.8m and adj EBITDA £7.3m vs F/C of £35m and £7.5m. Impact of 'Hollywood' strikes has carried on into H1-FY24. More guidance with FY23 results. [SP=53 Cap=43m]
◄Getech (GTC)► enters JV to pursue copper exploration in Kazakhstan. Gets nil-cost options in JV in lieu of cash for services. Sounds a desperate way to get business. [SP=8.15 Cap=5m]
◄Polarean Imaging (POLX)► strategy update inc financing - needs $10m min "with an anticipated launch in Q2". [SP=5.2 Cap=11m]. I hold.
◄Blackbird (BIRD)► £1.05m placing at 6p, a 13% discount, to grow the elevate.io product. [SP=6.99 Cap=26m]
◄EnSilica (ENSI)► cash-strapped co has received the 2023 R&D tax credit. [SP=72 Cap=59m]
◄Silver Bullet Data Services (SBDS)► guides FY-Dec rev up 42% and adj EBITDA loss down 65%+. In line? Strong start to this FY. [SP=190 Cap=33m]
◄itim (ITIM)► guides FY-Dec rev up 15% (in line) and EBITDA £0.68m, ahead of market expectations of £0.3m. Pretax loss also ahead of market expectations. "In alignment with prevailing economic conditions, itim is currently in the process of "right sizing" its business. This strategic pivot involves a shift away from 'free' implementation services towards a continual focus on increasing services revenues and EBITDA." [SP=35 Cap=11m]
Strong 17% AUM growth for FTSE-250 technology-empowered active investment management firm Man (LON:EMG). A lower year for performance fees, but this 200-yr old organisation which is now a hedge fund asset manager seems very well placed for the Ai trends, unlike many other asset managers. 5-6% dividend yield, before special dividends and buy-backs. I hold.
Schroders (LON:SDR) results out today as well that I also hold. They seem to be doing OK, but flatlining a bit at the moment and have held the dividend on lower profits. A quality asset manager as well, but having a slightly tougher time.
https://www.londonstockexchang...
Cairn Homes (LON:CRN) I think Graham usually keeps tabs on this Irish Housebuilder. It would appear that the market there is more buoyant than in England!! They are growing sales and forecasting large sales growth. Looks to be worth spending some time investigating it.
Three TU's for us today, Mercia gets a feather in it's cap and a small uplift in AUM, Zytronic comes out with another 'Place your bets' statement and Getech might just have something exciting going on by working for nothing on the promise of 5% in a copper mine -- if the exploration area has any! Comments and brickbats welcome on all three.