Small Cap Value Report (Thu 29 June 2023) - SYS, Water Cos, DLAR, TBLD, TND, PPH, MOON

Good morning from Paul & Graham!
Thank you to Roland for covering my 2 days off. I was meant to be going to Dubai for a week, but travel companions had to cancel at late notice, so I didn't go, which was actually a great relief - it's far too hot (about 40oC) there at the moment, so I'm much happier in Bournemouth than Dubai! (not something you hear people say very often, admittedly).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
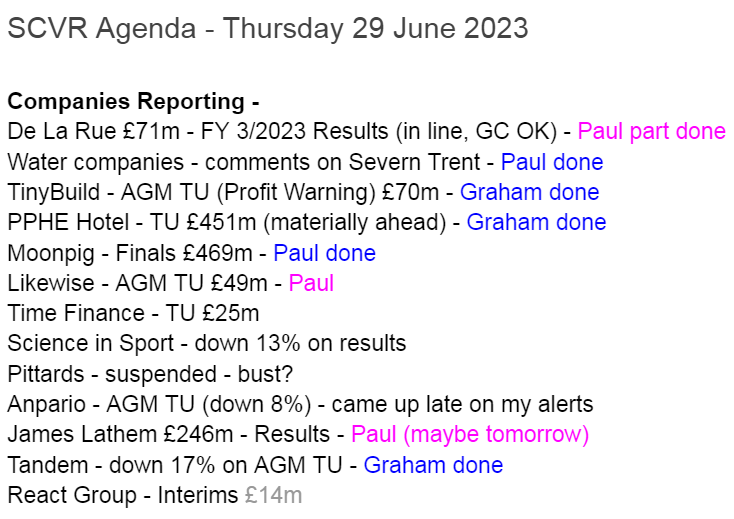
Summaries of main sections
tinyBuild (LON:TBLD) - down 72% to 9.8p (£31m) - AGM TU - Graham - AMBER
An awful RNS with the double whammy of a profit warning and CFO resignation, plus lots more. There’s little promise of short-term improvement as the company blames conditions facing indie games in general. For new investors the cash balance reduces risk at this level.
SysGroup (LON:SYS) - 31.5p (£15m) - Final Results - Paul - AMBER
A backlog item, Paul reviews its annual accounts below. Looks OK, but bank debt has increased due to acquisitions. I go off at a tangent and discuss multibaggers!
Tandem (LON:TND) - down 11% to 187p (£10m) - AGM TU - Graham - AMBER
At Tandem, the more things change, the more they stay the same. They have a new CEO and the company continues to struggle with a range of economic and industry challenges. Expectations for the year are unchanged but I change my stance from Green to Amber.
PPHE Hotel (LON:PPH) - up 5% to 1112p (£471m) - Trading update - Graham - GREEN
I’m going green on this one as it sounds like occupancy is on its way back to pre-Covid levels. The company announces a very strong REVPAR metric for H1 and it expects to beat both revenue and EBITDA forecasts this year. At a big discount to NAV, I’m interested.
Moonpig (LON:MOON) -
Paul’s Section:
De La Rue (LON:DLAR)
36.5p (pre market) (£71m) - FY 3/2023 Results - Paul - AMBER
This group prints banknotes, and has another division which makes security authentication products and software to prevent or detect counterfeit goods.
This share should be seen as a high risk, special situation.
At first glance this announcement looks reassuring, I’m writing this at 07:57, so don’t know how the share price will react, but I think it could bounce today, because -
FY 3/2023 results are in line with expectations,
Outlook/current trading also in line (although H1 weak, H2 weighting expected, which isn’t great)
Order intake sounds OK, and
Net debt far too high, but terms renegotiated with bank,
Pension fund trustees have agreed deferral of large cash injections,
Going concern “material uncertainty” seems to have been removed.
Still loads of problems to resolve, but I think we could be set up for a bounce today, might be an interesting one for any traders reading this, so I’ll pop this up at 08:00 and do more detail a bit later.
Water Companies
A topical issue that I had a look at last night. Press reports that Thames Water could be crumbling like a Victorian sewer, under its £14bn debt pile. They suggest the Govt is supposedly preparing contingency plans to take it into some special, temporary, administration type regime, if it financially fails.
We’re all no doubt disgusted by the horrible reports of water companies discharging raw sewage routinely, and frequently, into our rivers and beaches. Clearly something drastic has to be done. Is nationalising water companies the answer? Who knows, but I thought I would investigate the accounts of a sample listed water company, Severn Trent (LON:SVT) to see if it’s true that greedy management and shareholders are stripping it of cashflow, and starving it of capex.
The numbers show a rather different picture.
Consider the multi-year cashflow statements from SVT below. What this shows (the top two rows highlighted) is that substantially all of the operating cashflow is spent on capex (i.e. ploughed back into improving/renewing the water/sewerage system) -
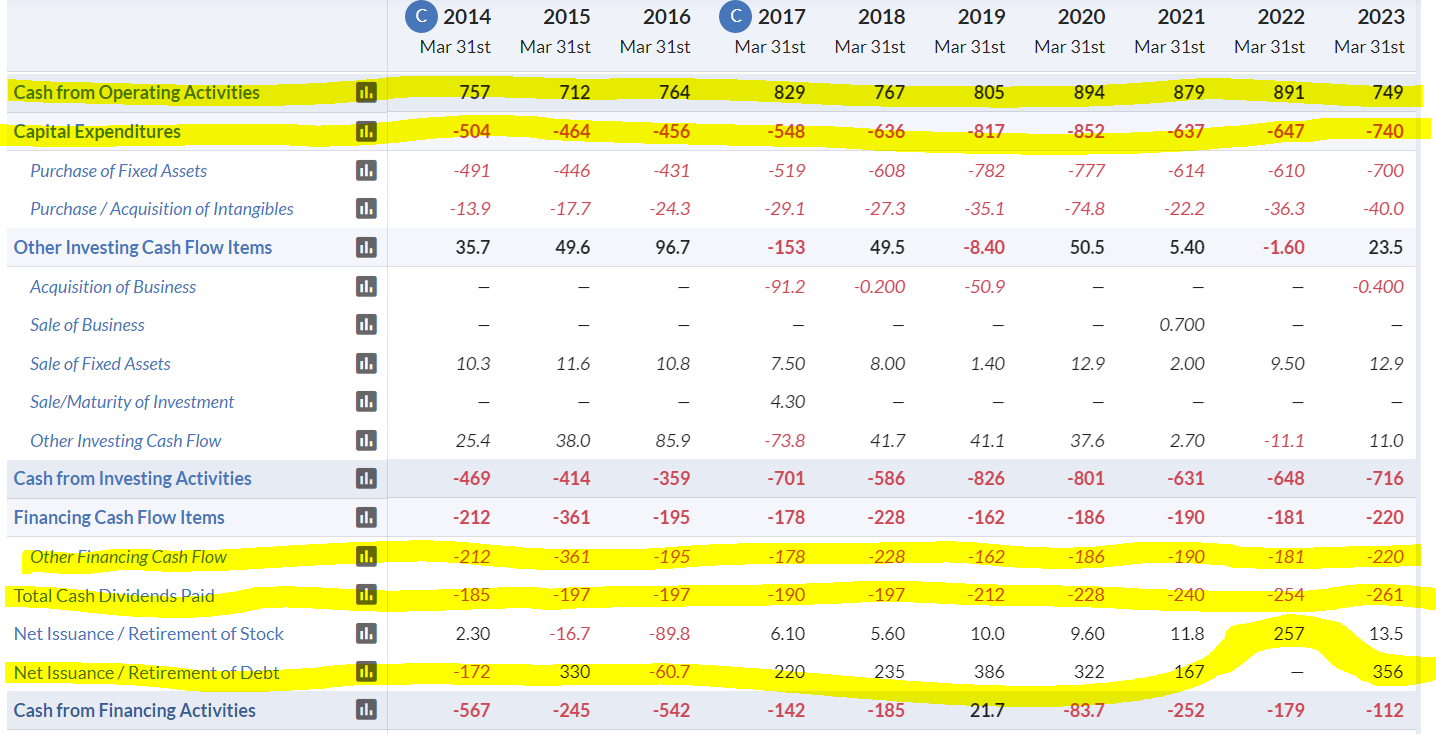
The bottom 3 highlighted rows show that dividends and debt interest are mostly funded by issuing more debt, and (in 2022) equity.
As a friend pointed out, you could just as easily argue that the increased debt was funding some of the capex, and divis are paid out of operating cashflow. A fair point. However, what I’m interested in, is whether nationalising SVT would lead to unleashing a fresh pot of money to increase capex (fixing the leaks & the sewerage discharges, over the long term), funded by stopping dividend payments to shareholders. Whilst that is a nice populist narrative, you can see from the numbers above, that it’s false. If nationalised, SVT would indeed not have to pay divis to shareholders, but that would not give it any significant extra money to spend on capex.
The divis are being funded by growing the debt pile each year.
Hence this share might be a good one to short, if you’re a risk-taker (shorting is not something I would recommend to anyone, unless you’re a professional risk-taker, and know what you’re doing), since it seems to me the divis in the sector look unsustainable, and politically it might be better for the Govt to let the companies fail, and then nationalise them.
One way or another though we, the end customers, will have to pay more for our water/sewage disposal than we are now, if we want things cleaned up. The cashflow statement clearly shows that there is not a bonanza to be had by stopping dividend payments to shareholders,as they’ve been funded from debt, not from cashflows.
Water bills have always struck me as too cheap. I only pay about £500 pa for a whole year’s supply uninterrupted of clean, drinkable water, and disposal of all my sewage. That doesn’t seem much considering what’s involved, less than £2 per day is crazily cheap I think.
It’s always worth going to the numbers, and forming your own opinion. As in this case, the result is often completely different to what I expected to see, and what all the politicians & commentators are saying!
Here’s the trend on SVT's balance sheet, of ever growing fixed assets, and debt. So the truth is they’re spending a lot on the infrastructure, but it’s clearly still not enough (although I haven’t checked whether SVT in particular is guilty of sewage discharges, and I picked this share at random from the several listed utilities) -

Anyway, I just thought this was interesting.
Personally I never invest in any regulated, formerly public sector shares. The debt amassed by the water companies looks a serious problem, hence the shares could be severely punished. I wouldn’t want to be holding any of them.
I suppose with zero interest rates, it made sense for water companies to keep racking up cheap debt. Now though, as bonds mature, it's a whole different ball game. Thames Water bonds are apparently way into junk territory now.
SysGroup (LON:SYS)
Down 3% to 33p (£16m) - Final Results - Paul - AMBER
SysGroup plc (AIM:SYS), the multi award-winning technology solutions provider, is pleased to announce its audited final results for the period ended 31 March 2023.
I only seem to look at this share once a year, at this time of annual results.
The figures look OK. My brief notes from a quick skim -
Revenues up a lot, +47% to £22m, mainly from acquisitions, plus +6% organic.
Adj PBT £2.2m, up 9%
Statutory loss £(0.1)m PBT.
Normally I would switch off at this point, but in this case most of the adjustments look OK, being mainly a £1.7m non-cash amortisation charge of customer relationships, which is goodwill by another name - related to acquisitions, not internal capitalised payroll (of which there seems to be very little).
Acquisitions - bank debt (£8m Santandar facility) has been drawn down for acquisitions, it’s making surprisingly material deals given its market cap - risky perhaps in the current climate?
Balance sheet - not good. Very top heavy with £28m intangible assets (see note 9), practically all goodwill & customer relationships (which is the same thing basically). Write off the intangibles, and the related deferred tax, and NTAV is negative £(5)m. The company says its balance sheet is “very healthy”, but it isn’t. The justification is that net debt of £1.3m (excludes deferred consideration though!) is only 0.4x EBITDA. I should meet them and give them a lesson in balance sheets! (sounds like they need it)
Outlook - current trading is in line.
Multibaggers - Megan did a recent talk on Mello, and series of articles here about finding multibaggers, which got me thinking. Acquisitive groups can occasionally produce some stunning multibaggers. Especially through combining both earnings growth, and PER multiple expansion. So buying when it's on a lowish PER is important for a multibagger, arguably.
However, it’s all about having CEOs (and others) who are brilliant dealmakers - think Ideagen, Judges Capital, and SDI - buying good businesses on the cheap, and getting the acquirer's shares highly rated as a growth company, hence each acquisition creates shareholder value. Volex (I hold) is doing exactly the same strategy right now, but has yet to be rewarded for it with a decent rating. Often the companies acquired are retirement sales of private companies.
With all 3 of those shares mentioned above, there was absolutely nothing in the figures early on to suggest they would be multibaggers. It was all about spotting & backing great management. This is often just a hunch, eg. David at Ideagen is a lovely chap, but was all over the place most of the time, yet still managed to pull off a series of shrewd deals over the years, creating a multibagger, and selling it at the top of the market.
To get multibaggers, I've noticed that not selling your shares along the way, even when the shares got over-valued, is another common trait. Easier said than done.
Trouble is, for every Judges Scientific, there are probably dozens of companies that failed to deliver shareholder value from acquisitions - eg remember Vislink?! Look how often large swathes of goodwill have to be impaired after acquisitions have gone wrong. Many management teams do acquisitions to empire build, and grow the business so they can pay themselves more, I reckon. If this is done using debt, it can be disastrous, and result in heavy dilution or insolvency if things go wrong. Management can just walk away, but shareholders suffer the losses.
So what is management at SYS like? Do they display signs of being brilliant dealmakers? I’m about to watch an IMC webinar from Sept 2022, but note today that the CEO is stepping down. So that rather means we can’t judge whether SYS might become a multibagging acquisition vehicle until a new CEO is found. Hence I wouldn't pay a premium for it right now. I don't know why the CEO is stepping down, but surely he would be llikely to stay on, if an exciting growth story was developing?
Overall though, I can’t see anything particularly wrong with SYS. It looks an OK business, with maybe a bit too much debt for my personal liking. It’s not clear to me at this stage though, where the upside potential is? Let's keep an eye on it though.
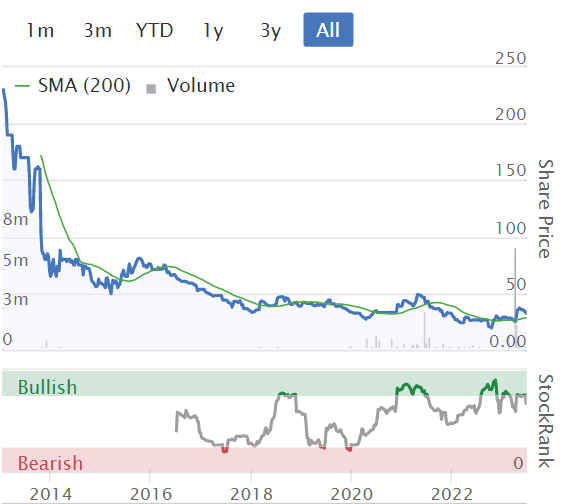
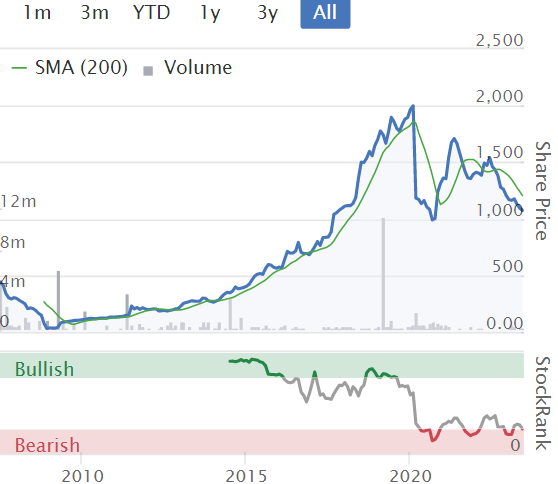
SYS has a poor share price track record since if floated in 2013, so something would need to change to convince me it's now a growth company -
Moonpig (LON:MOON)
Up 6% to 146p (£500m) - FY 4/2023 Results - Paul - AMBER/RED
This is mainly the online greetings cards/gift business Moonpig (admit it, you just sang the jingle in your head!), which is 70% of revenues, Greetz (17% revenues) - similar to Moonpig, but in the Netherlands, and newly acquired Experiences business (13% revenues) - which was acquired in July 2022, called Buyagift - acquisition details here.
I’ve previously been negative on this share, because it wrecked its balance sheet with the ill-timed acquisition of the Experiences business, and is now struggling with too much debt, and consumer demand has turned down. Plus it looked over-priced still, even after a major drop from the 350p IPO in Feb 2021, where selling shareholders somehow convinced institutions to value it at £1.2bn. Their remaining original shareholders may still be an overhang possibly? It looks like another opportunistic, and over-priced 2021 float where a pandemic boost was passed off as structural growth. Still buyer beware, nobody is forced to buy new issues, and we’re always highly sceptical of nearly all of them here at the SCVR, which has proven a sensible rule.
Anyway, here are the main points I jotted down whilst reviewing the accounts published today for FY 4/2023 -
Revenue up 5% to £320m. However this includes £41.6m from the acquisition of Experiences. Reverse this out, and organic revenue fell 8.5%
Very good profit margin (adjusted), with £48.0m adj PBT (LY: £51.5m). However, again the notes show that £11.4m PBT came from the Experiences acquisition, so organic adj PBT fell from £51.5m to £36.6m, down 29% - not good at all!
Adjustments are quite large, at £c.£13m, of which £9m relates to bonuses & share options pre-IPO.Share-based charges overall are too high, at £8m this year and last year. I think that’s taking the proverbial, given that’s almost a quarter of the profit (pre acquisition contribution). It really grates to see management rewarding themselves heavily with share options, when the share price has tanked. Yet we see that at many companies. So often at the moment, I open an RNS marked as Director transactions, hoping they're buying with their own money, but nearly always it's Directors giving themselves free options at our expense, despite presiding over a plunging share price. What planet are these people on? Talk about entitled!
EPS is 7.7p diluted (statutory), and 10.9p adjusted. So a PER of 13.4x on the adjusted earnings number might appeal to some investors.
Bank debt has to be taken into account though, and is too high at £148m net bank debt, although that has come down from £189m just 6 months earlier (Oct 2022). The commentary says debt reduction is a priority, so there are no divis.
Interest costs seem to have been hedged just before the mini-budget kerfuffle last year, a smart (and/or lucky) move!
Finance costs are very high, at £13.6m, which is taking a big chunk out of profits - although that could be seen as future upside, as it deleverages (or hopes to anyway).
Outlook - in line with expectations so far in FY 4/2024. Only expecting negligible growth in H1, but an acceleration in H2. Not really an exciting growth stock, more a value share now, that might deserve a single-digit PER, because earnings are falling.
Balance sheet - is awful.
NAV is negative at £(34)m, including £210m of intangible assets. Write that off, and NTAV is mind-bending negative £(244)m. The group has heavily negative working capital (hardly any inventories or receivables, and customers pay cash up-front). Despite this favourable setup, it also loaded up on bank debt, with £170m in long-term borrowings. Debt really does need to come down a lot. The multiple to EBITDA looks fine, but EBITDA is a nonsense number at this company - e.g. it capitalises 23% of its total staff costs onto the balance sheet (see note 7). So I think the bank debt is a bigger worry than the company thinks.
Cashflow statement - £12.9m capitalised development spend (payroll) stands out. Also £88m paid for the acquisition of Experiences.
Going concern statement is clean. Being an online business, it does benefit from variable cost, unlike bricks and mortar business with fixed costs, which find it harder to cope with a downturn in demand.
Acquisition - last time it seemed to me they had overpaid for the Experiences acquisition, but the notes say it made £11.4m in this period, and a full year pro forma would be profit of £13.4m, which is not bad at all. It’s doing a great job of masking the deterioration in performance of the original business too!
Merchant accrual liability of £56m has appeared in note 16. This relates to cash paid up-front (and I think recognised as revenue & profit) by buyers of the Experiences vouchers. Not all of them are redeemed, which makes that element pure profit (but probably also unhappy customers). But it also means that MOON should have a ring-fenced cash pile of £56m relating to experiences vouchers note yet used, which it doesn’t. That’s rather aggressive accounting, and I think there’s a strong argument for regulations to be changed to keep customer cash segregated.
Paul’s opinion - underwhelmed. Underlying performance has deteriorated a lot, obscured by the new profits from the acquisition. I don’t suppose postal strikes have helped. There are other companies in this space, and a resurgent Card Factory (LON:CARD) (I hold - a recent opening purchase) might chip away at MOON’s business, whilst it is focusing on generating cash to pay down its bank debt.
Overall then, I can’t see why anyone would want to chase MOON shares any higher, but they might, people buy for many reasons.
RED seems a bit harsh, so I’ll shift to AMBER/RED.
Graham’s Section:
tinyBuild (LON:TBLD)
Share price: 9.8p (-72%)
Market cap: £31m
There have only been two mentions of this video game company in the SCVR archives: first by myself in January (share price: 80p) and then by Paul in March (share price: 52p).
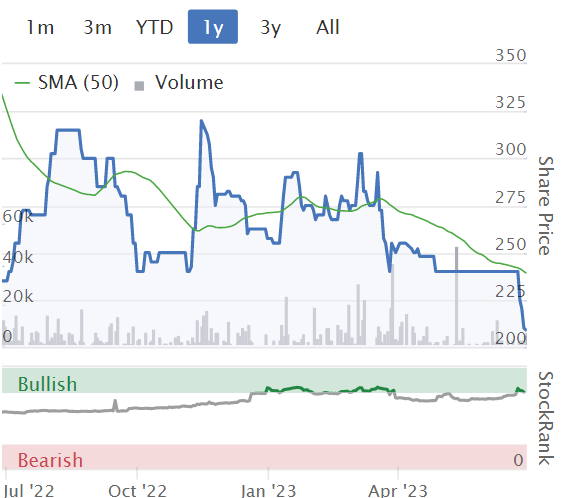
The market has been pricing in disappointment as the shares continued to slide, reaching 34.5p last night:

This morning, we have a horrible profit warning:
First-half performance below expectations due to lower contribution from platform deals and the underperformance of Red Cerberus and Versus Evil has resulted in a material reduction to FY consensus revenue and a more acute reduction in Adj. EBITDA in 2023 and 2024.
The reference to “platform deals” is elaborated upon as follows:
As witnessed across the industry, distribution platforms have been significantly downsizing the amount of investments in non-AAA games. Platform deals have been an important driver of tinyBuild's growth and profitability over the past few years, and the Board expects this downward trend to materially impact revenues.
Remember that TinyBuild is a publisher of “indie” games, i.e. games that are not mainstream and are unlikely to be at the cutting edge of software. I noted previously that I had never heard of any of the games in TinyBuild’s portfolio.
On top of that, two businesses acquired in November 2021 are underperforming. “Strategic options are under consideration”, which sounds ominous. And various other possible reorganisations are being considered for the company’s over a dozen game studios..
Cash at the end of 2023 is expected to be $10 - 20 million, versus prior expectation of over $26.5m.
That range of possibilities for the expected cash balance is very wide but I suppose it’s better to be approximately right than precisely wrong!
In more bad news, the CFO resigns for personal reasons.
He had already taken a period of leave, and so the company is ready with a chosen successor: their current Head of M&A, who is a former equity research analyst.
As Head of M&A, I wonder if he takes responsibility for the poor performance of the November 2021 acquisitions?
They also appoint a Chief Commercial Officer, another internal hire.
Portfolio/pipeline: I think there’s a typo here, as the company talks about games it published in the first half of 2022. It says that back catalogue titles continue to perform well, and it has announced “a record number of new titles for future release”.
Outlook
As reported by other companies in the gaming sector, the market backdrop has become increasingly challenging with distribution platforms reducing investment. As a result of this impact and underperformance at Versus Evil and Red Cerberus, the Board is now expecting to be materially behind revenue market expectations in 2023 and 2024. This impact becomes more acute at the Adjusted EBITDA level as a result of increased development costs, amortisation charges and a less favourable revenue mix.
FY23 is expected to be a low point in terms of financial performance and cash levels and the Board is looking forward to the contribution of new larger budget games scheduled to launch in 2024 and 2025. Early indicators of consumer traction across the Company's pipeline, including the reception of recently announced games, are encouraging and bode well for the future.
CEO comment - he is filled with confidence due to the “incredibly strong pipeline of new games under development with the potential to create multiple new long-lasting franchises”.
Graham’s view
This is a true horror show RNS. It’s got everything:
Profit warning.
Cash warning.
CFO quits.
Internal hires to fix problems caused by the existing team.
Big-picture problems (fewer platforms deals) with no signs of this ending.
Possible reorganisations/restructurings across the company.
Typos
Do the shares deserve to be clobbered by 70%? Well this is an unforgiving market for UK micro-caps and that is what happens when confidence is lost in these conditions.
My own view is that with the company having (probably) over $10 million of cash by the end of the year, I can see the shares potentially enjoying balance sheet support at some point in the not-too-distant future.
Remember that this is a 2021 IPO - the year of many of the worst IPOs in living memory. Were the profits this company enjoyed in 2020/2021 a sign of things to come, or were they a short-lived side effect of Covid? At the moment, it looks like the latter.
But the market should look forward, not back. At a £30m market cap, this becomes very cheap on metrics such as EV/sales, although admittedly I don’t know how low sales might be this year (previous estimate: $69 million).
Therefore, I won’t give this stock the thumbs down: it is already cheap relative to its turnover, and I’m not sure that it needs to get much cheaper than this. So I’m neutral. My commiserations to anyone who held it overnight (including the CEO, who owns 38%).
Tandem (LON:TND)
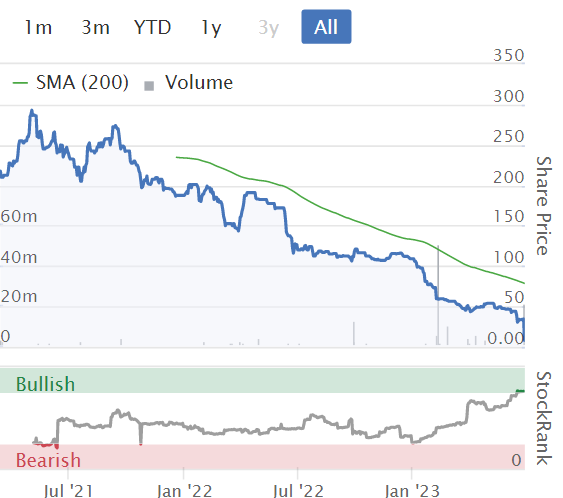
Share price: 187p (-11%)
Market cap: £10m
I gave this share the green light earlier this year (1st time, 2nd time) but hopefully I included enough warnings that things would probably not be plain sailing for shareholders! As a former holder of these shares, I know all too well how accident-prone they are.
Here is the latest bad news from Tandem: “cautious buying behaviour” continues. Trading conditions remain “persistently challenging”, further compounded by high interest rates and the cost of living crisis.
And furthermore:
We have also experienced a shift in the buying habits of national retailers who are transitioning from Free On Board (FOB) purchases to Direct Delivery (DD). This change naturally alters the pattern of our sales, aligning them more closely with the end customer's buying behaviour and therefore the timing difference in sales is to be expected to be weighted in favour of later in the year compared to prior periods.
Tandem’s goods are imported from China and under Free on Board arrangements, Tandem’s responsibilities end as soon as goods are loaded onto a ship. But without those arrangements, I think Tandem could be on the hook for a lot more responsibility when it comes to shipping - I would welcome any insights readers might have on this point.
This shift also seemingly introduces more seasonality, as sales aren’t made until later in the year, when the end-user is buying.
Other key points:
Total sales down 26% year-on-year
Toys, Sports and Leisure down 46% (partly due to overstocking and bad weather).
Bicycles down 20% although Q2 was ahead.
Home and Garden down 30%.
Emobility (including e-bikes) are up 51%.
Outlook
It’s a long outlook statement, and it finishes by saying “we therefore maintain our view of achieving market expectations of our performance for the full year”.
The expectations, as published by Cenkos, suggest revenues of £30m, adjusted PBT of £1.2m, and adjusted EPS of 17p.
This is despite “no signs of abatement” of the current, difficult market conditions.
Graham’s view
I previously gave this stock the cautious thumbs up, thinking that there was enough value on offer to justify a positive view.
It remains “cheap” today with a ValueRank of 86, which is before the latest share price weakness.

Unfortunately, there just isn’t much quality with this one and after reading today’s statement I wouldn’t be tempted to buy back in, even at lower levels than this. Today’s statement is a stark reminder that things are always going wrong with this one and conditions are always challenging - or if they aren’t now, then they will be again soon.
My positive view was also related to the appointment of a new CEO and a management shakeup, but those factors aren’t bearing fruit yet.
I am therefore changing my stance from GREEN to AMBER on this one.
PPHE Hotel (LON:PPH)
Share price: 1112p (+5%)
Market cap: £471m
We discussed this in some detail in April: the shares were trading far below stated net asset value, but occupancy rates remained short of pre-Covid levels.
Today we have a trading update for Q2. Key points:
Strong trading conditions and forward booking momentum.
REVPAR is £109 (vs. £93 in pre-Covid 2019, i.e. up by 17%).
17% growth in REVPAR is highly encouraging to me as it suggests that occupancy is getting back to where it was pre-Covid. The company does say there has been “broad occupancy recovery” in the UK and Netherlands, though Germany had a slower start to the year.
Here is how I think about the key metric REVPAR (revenue per available room):
If cumulative inflation since 2019 has been c. 25%, then in order to match the performance of 2019 in real terms, PPHE needs REVPAR to be up by 25%.
This metric depends on two factors: occupancy and pricing. I think that PPHE’s pricing has matched inflation, more or less. So then it all comes down to occupancy.
Occupancy was over 76% in 2019, but still only 67% in Q1 2023. It sounds like Q2 was better.
We also get an outlook statement:
Forward booking momentum remains encouraging, and the revenue contribution from the recently refurbished and relaunched properties, including Grand Hotel Brioni in Pula, are expected to be significant.
As previously announced, the Group's EBITDA margins have been impacted by both broader operating cost inflation and, particularly, energy cost inflation over the last six months…
Taking all of these factors into account, the Group now expects to deliver FY 2023 revenue of at least £400 million and EBITDA of at least £120 million.
Previous expectations as compiled by the company suggested revenue of £352 - £370 million and EBITDA of £106 million to £111 million. So this is an impressive beat.
Graham’s view
It’s nice to be able to cover a positive news story today!
I wrote previously that this company could be trading too cheaply if it recovered to pre-Covid levels of trading soon.
While it’s not fully there yet, I now have confidence it is on the path to achieving this. I could be wrong, but that is my current belief based on the trends.
I am therefore happy to upgrade my stance on this from AMBER to GREEN, on the basis that it trades at a significant discount to NAV and is making its way back to prior performance levels. It also has the potential to generate nice returns from managing hotels and generating returns for the planned European Hospitality Real Estate Fund.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

97 comments
Do you think now is a good entry point on this, planetx? Simon Bragg I assume was the activist investor referred to in your previous post and he bought another 50,000 at 165.25p last month. With trading stabilised and huge asset backing, I see the current share price as more or less the floor, with scope to move upwards if they outperform due to the warm weather (which I think they might). I have taken a position.
Seems to me Thames Water's current troubles are yet another mini-knot that needs to be untangled from the giga-knot of the 1973 water act. The act created regional water boards to act as both regulator and supplier, this was obviously untenable as the water boards were the major polluter... Part of this disentanglement was the 1989 water act that separated the "Game keeper" function via the creation of the National Rivers Authority and privatised the water boards to create the current suppliers whom we know and (Don't generally) love.
Whilst I'm to the left of Rishi I'm under no illusions about the days of nationalised water. In winter 1986 we had nearly two weeks of no water in north Leeds, thanks to a burst main. For the most part water was delivered in green tankers by the Territorial Army; placing LS6 and LS16 in the same category as Bosnia and Sierra Leone (Places kept alive by a humanitarian mission delivered by British armed forces), cheers Yorkshire Water Board!
Later I did my school work experience in the lab of the NRA's Yorkshire and Northumbria region, where I remember abstract discussions about whether or not their could ever be Otters returning to the Wharfe or the North Tyne. Well they did and I saw my first ever kingfisher in 1998; in Leeds city centre, flying down the Air!. Unthinkable a few years earlier. Yorkshire Water PLC built a Transpennine water main after the 1995 drought when our reservoir dried up and we were invited to walk across it and see the remains of West End village (Adjacent to the village my ancestors moved from before WWI, a very strange experience). Despite drier Yorkshire summers since, the water supply has never faltered since.
The impression I am left with is the major stumbling block for water companies is the expectation that they should be dividend machines for income investors, which diverts free cash from being reinvested.
Thanks for the Water Companies macro and contrarian views to the 'news'. If we need a catalyst for a recession then this is it, esp if reads across to other utilities. Stupid governments over 40 years, busted utilities, busted NHS, follower of events BoE, what else - oh wait, forgot our Knight in White Armour (Gandalf/Sunak) or less catchy 'NET ZERO' - nope! - property and pensions and a bit of greenery will be the last jewels to sell off.
Be careful out there.
Finishing-up on the Thames Water topic today, its been announced this afternoon that Sir Adrian Montague has been appointed the new Chairman. I've dealt with him at Anglian Water a few times in the past - he's a great top-drawer veteran chair! That has to be part of the solution to sort Thames Water out and so I suspect things may not be quite as bad as reported. I'd be surprised if they could get someone of that calibre to take the appointment if a solution wasn't likely! Maybe he's part of the solution that investors have called for before putting new investment in along with the CEO leaving.
Thanks for your input as you obviously have a lot of experience in the regulated utility sector
Would you still feel comfortable investing it utility companies in the present political environment
Would personally be very interested on your views on the implications of Labours proposals for the government getting involved in building and running green energy projects in competition with existing assets and if this would affect funding and value of the established players
Double Youch re : Tinybuild.I know it's a new issue from the heady heights of ipos.But i was considering an investment or 2 in some of the gaming sector including the fallen stars due to the ability to produce a lot of cash if they hit the right game.
However i didn't as i didn't know where to start as i've never been a gamer and have no idea about the industry or what makes a relatively simple game with an amazing ROI like Candy Crush last apart from a very well known and popular well capitalised platform such as Playstation and Xbox.Glad i avoided it for now. i'll probably be foolish enough to reconsider if the general macro and industry conditions improve for the smaller studios.
I did like the CEO's CV and deep experience as a gamer and the supposedly diversified, large number of titles in the portfolio at Tiny though.
I watched an investor presentation with the CEO once. He is very charismatic but I had an inkling he would be very domineering and company could only be as good as the decisions he can make. Investors like confident management but not a fiefdom. That was just my impression. Set against that he owns a lot of the company and is clearly passionate.
Tandem (TND)
Predictably bad results .
Industry is in a bad way so not much they can do but ride it out .
CEO is I am led to believe pretty average but even a great CEO would be hard pressed to do well in a shocking market .
Tandem is starting to get very cheap and I think valued at 0.6 times assets .
I spoke to one serious investor who was considering taking a major position and putting themselves in a position to take board seat and push for change . Certainly needs an activist investor type situation to drive out the value .
Historically tandem executives have been content to let the business trundle along whilst getting their toppy salaries and share options and no real incentive to grow the business .
If it drops to 6-7 million valuation keep an eye on the shareholder register if an activist group take a position with enough % to force change then that is the time to sit up and take note .
For now sit back and watch it drift sideways / downwards with an impotent management unable to execute yet still taking their rewards whilst shareholders go nowhere .
But one to watch as the asset value rock solid
It’s s Rockwood type situation but they will be waiting for a capitulation entry point I think .
A chain of thought may be what's in a name. Employees, investors, foreign as well as others. Not saying 'Big Build' would have cut. See things like 'Perfect Plastering' etc and tend to avoid being cynical by nature.
Shame really another small cap which just destroys confidence in anything in this market whatever it is - sad and not good.
Best Of The Best (LON:BOTB) (I hol)
Announcement just out that GIL (Sagi's investment vehicle) have purchased more shares on the open market and now own more than 30% of the company. Their voluntary takeover offer is now a compulsory one.
What I don't understand is why they have not been forced to up their bid to 600p, which is the highest price they paid for shares in the last 12 months.
They paid this price when buying their initial stake in September 2022 .
"Under Rule 9 of the Code, any person who acquires an interest in shares which...carry 30% or more of the voting rights of a company...is normally required to make an offer to all the remaining shareholders to acquire their shares...
...An offer under Rule 9 must be made in cash at the highest price paid by the person required to make the offer, or any person acting in concert with such person, for any interest in shares of the company during the 12 months prior to the announcement of the offer"
What am I missing?
In answer to your question: My guess is that what you are missing is that Sagi is a chancer who is testing whether or not he can get away with it!
He will have your trousers down as he did mine at KAPE. He's not afraid of playing hardball.
I believe it's based on the VWAP price.
Best Of The Best (LON:BOTB)
abtan - what you are missing is that the RNS states:
"The highest price paid for BOTB Shares by GIL (or persons acting in concert with it) during such period was the Offer Price of 535 per BOTB Share".
Do you have proof that they paid 600p?
Best Of The Best (LON:BOTB)
EDIT:
Well, that was silly.
"What I don't understand is why they have not been forced to up their bid to 600p"
In my haste I assumed that GIL paid 600p back in September last year.
They did in fact pay 400p, which is what I initially typed in, before thinking I'd made a typo and upping it to 600p.
A final 535p offer it is then...unless someone comes in with a higher bid of course.
A
PPHE Hotel (LON:PPH)
Hi Graham
Thanks for your thoughts here. I don't hold, but I recently purchased some Dalata Hotel (LON:DAL) so I took an interest in today's update.
One thing I was wary about with PPHE was their high net debt = c£600m.
Yes, this is fully asset-backed and yes, most of the debt repayments are fixed for the next 4 years, but given current cash generation levels (I very roughly estimated £40m pa) I am wary of the risks looking out to 2026/27 when they will need to refinance and how expansion plans will progress during this time period.
---
Another thing that was interesting from PPHE was the 17% increase in RevPAR for H1 vs H1 2019.
2 weeks ago Dalata Hotel (LON:DAL) reported that "RevPAR is expected to be 29% ahead of 2019 levels for the H1 period."
I'm sure that there's some logical explanation for the difference here - perhaps only one is reporting a LFL figure, or the geographical location of their respective hotels is impacting price increases over 4 years?
In any case these are expected increases, which presumably will do enough to offset recent inflationary pressures.
I was only interested in James Latham,(Which you mentioned in the agenda) but but after reading about all the junk, not a dicky bird?
Oh dear, sorry about that.
I've got a great book recommendation for you here - it's genuinely a brilliant book.
Wonderful retort Paul. Up there with Churchill's
"I may be drunk, Miss, but in the morning I will be sober and you will still be ugly."
Paul,
Great comments on the water sector, especially about the industry's botomless need for hefty capex. Yours was one of only two sensible observations recently in a sea of misinformation and misunderstanding.
The other comment was John Armitt head of the National Infrastructure commission. He sensibly stated that we as a country will have to decide where we want to spend our capital. I think he meant that of we want better sewers and storm overflow prevention, we are going to have to pay for it by higher capital investment.
The problems at Thames, it seems to me, is from overleverage. Maybe I am being simplistic, but shouldn't good management and regulation require that as the quantity of fixed assets grows each year then the invested equity should grow in proportion. Unless water companies grow the retained profits line of the balance sheet, the gearing will get ever higher until eventually the inevitable happens.
What a great note on De La Rue (LON:DLAR) - thank you, wish I had read it at 8am! Love your podcast (especially part 2) and updates! Even my husband who has no interest in the market really enjoys hearing your podcast - the only one I am allowed to play in the car when he is there:)
Oh that's lovely to hear, thank you! :-)
DWF (LON:DWF) What's going on at DWF? It's up 10.7% today on no news.
DWF (LON:DWF) was profiled yesterday in Master Investor:
https://masterinvestor.co.uk/l...
TheFly Thank you.
Science in Sport (LON:SIS)
Repalcement RNS:
Quite the roll forward error - I am sure it is completely innocent & not indicative of an issue with the audit report.
If I were a shareholder, I'd seriously consider exiting (easier said than done I find) - no holding
"The following sentence has been deleted from note 1 of the Notes to the Consolidated Financial Statements for the full year results announcement released on 29 June 2023 at 7.00 am with RNS number 3025E as the results are unaudited: "The auditors' report on the statutory accounts for the year ended 31 December 2022 and the year ended 31 December 2021 is unqualified, does not draw attention to any matters by way of emphasis, and does not contain any statement under section 498 of the Companies Act 2006." All other details remain unchanged."
Sylvania Platinum (LON:SLP) is a share I know many Stockopedia subscribers hold. I was hoping to get some insight. It is currently one of my larger holdings at around 7% of my portfolio. I was attracted by the large dividend and low valuation, accepting the geographical risk (SA). It is currently trading in a very narrow range between 78p and 80p, about 10% below my cost average. The share price is being propped up by the ongoing share buybacks, however no buybacks take place unless the SP falls below at 80p per share. My major concern is the price of Rhodium, which makes up a large proportion of the basket price, has fallen off a cliff, as the chart below shows:
Does anyone know of any drivers that could cause an increase in Rhodium prices in the coming couple of months? Without a perk up in Rhodium prices, or something really significant with Platinum prices I see no reason for an SP rise in the short term. When the share buyback ends on Sep 1st, I think there could be a significant decline in SP, especially as the expected ex-dividend date is not until 2 weeks later on Sep 15th.
My current thought process is to sell out now, reinvest elsewhere and then potentially buy back in after the next trading statement or when sustained rhodium growth is seen. Was interested in any contrarian views or opinions.
Ben
My gut feeling is making me hold on to my shares in Sylvania Platinum (LON:SLP) as my thinking is that the ICE will make a come-back in not so many years, the EV being a dream too far. Of course the dividend is not what it was and your divi Ben is smaller than the 5.55% on the Stock Report, same as for myself.
Sylvania Platinum (LON:SLP) sold out a while ago as wasn't comfortable being exposed to effectively one very volatile commodity, plus the SA risk. Not sure it's that cheap either based on current rhodium price, at least relative to peers. I guess the bull case is there is a sudden clamour for more rhodium as car production picks up, coupled with limited supply, although personally find it impossible to predict which way commodity prices are going to go.
Hi Ben
I am a long term holder of Sylvania Platinum (LON:SLP) it is a somewhat volatile stock that largely follows the PGM price and specifically the rhodium price as shown in your chart half the market cap is cash guessing when the price of PGM metals will turn is like other posters down to car production and also longer turn its uses in hydrogen production
They are in my opinion a well run company in one of the few places that PGMs are mined if you want exposure to PGMs with a decent divi I think they are still the best bet
A bit of info on countries it’s produced in and uses
https://ipa-news.de/assets/sus...
https://matthey.com/documents/...
tinyBuild (LON:TBLD) On 29/03/2023 the company said "All considered, the Board remains confident the Company is on track to deliver results at least in line with expectations, plus accretive acquisitions." I now cannot believe that they really felt that the statement was true when they made it. I do not think that the situation could have deteriorated so massively in the three months since. If they had not made that statement then I (and many others) would not now be suffering such a loss. I generally expect outlook statements to be a little optimistic. But this one was just absolute ********!
tinyBuild (LON:TBLD) Is it against the law to deliberately mislead in an outlook statement?
tinyBuild (LON:TBLD) ChatGPT informs me as follows:
Under the Financial Services and Markets Act 2000 companies are required to provide accurate and reliable information to shareholders and the public. Misleading statements or omissions that could distort investors' understanding of a company's financial position or prospects may be considered a breach of the law.
In addition to the FSMA, companies listed on the London Stock Exchange are subject to the Listing Rules and the Disclosure Guidance and Transparency Rules (DTRs). These regulations require companies to disclose timely, accurate, and complete information to shareholders, including any material information that may affect the company's financial position or future prospects.
If a company deliberately misleads its shareholders in the outlook statement within a Regulatory News Service (RNS) announcement, it could potentially be in violation of these regulations. Shareholders who suffer losses as a result of such misleading statements may have legal recourse, and regulatory bodies such as the Financial Conduct Authority (FCA) have the authority to investigate and take action against companies that breach these rules.
The only thing I would say is their recent game releases have been particularly poor - no one is playing Hello Neighbour 2 (released Dec 2022 but they likely forecast for increased sales when patches were released this year) and Farwrorld Pioneers - their other big title released in May - has a rating of less than 41% (i.e. is terrible.)
SteamDB is a great resource to check how titles / new releases are performing. I find publishers by googling 'SteamDB [publisher name]'. It's interesting comparing to TM17 who have many more people playing their games (on Steam at least!) https://steamdb.info/publisher...
Finally, I suspect the timing of the CFO's resignation is not just by chance. Profit warning, cash warning, restructuring, impairments (etc.) one day before the end of H1... I think it's possibly all suddenly caught up with a very inexperienced CFO who was way over their head. Perhaps the scale of the issues / misallocation of capital is only just becoming apparent.
Thank you Jacxx. You make some good points.
Jacxx I can imagine the outgoing CFO at tinyBuild (LON:TBLD) would not have too much difficulty in the court room in convincing people that he was not deliberately misleading shareholders and that it was just a matter of his incompetence! Lol! I don't know whether to laugh or cry!
Pity someone didn't take that view when "Conviviality" CEO apparently lost a "£20m" tax bill down the back of the sofa.
Time Finance (LON:TIME)
If it's not too late for requests, would appreciate a once over.
Moved from broking to own book lending & asset backed, good growth with credit risk seemingly well managed. Ballpark 10% ROE, rising earnings/loan book in a constrained financial environment (market share)
25% discount to book value. (nb on Twitter I said 75%, which is wrong & stupid)
Markets reacted OK & for technicians 30p seems a breakout level (very lazy technician (and investor) myself.
I hold - small
Time Finance (LON:TIME) continues to defy expectations - increasing order book, increasing revenues, and arrears still low. But they are increasing credit provisions, so storm clouds might be on the horizon.
At 3.5p EPS for FY May23, that's paying just 8x historic PE, with growth to come (unearned income up +24% YoY at May23).
Obviously, key factor is what happens to the credit environment for SMEs in 2023-2024.
These good results might also open the door to a reinstation of the dividend. This is one of the downsides of Time when compared to other financial services shares - you can get tasty dividends from larger players, so why Time? The key investment reasons right now is the discount to NAV, as well as the high growth rate and modest PE for that growth. But if there's dividends too, that's icing on the cake.
(I hold in the Boon Fund)
A quick look at some other suspended shares, whose accounts are delayed, suggests that the absence of a date for issuing accounts is not a red flag. Plenty of other reasons to be very cautious (avoid it?) with HEIQ.
Morgan Sindall (LON:MGNS) just over the £700m cut-off now, but worth highlighting another reassuring update, confirming they are trading ahead of expectations. Looks well placed given well diversified revenue streams and strong net cash position, while valued on a single digit PE ratio. The fitout division seems to be doing particularly well, I suspect as companies need to reconfigure their offices to meet ESG targets and to tempt staff back to the office. I hold.
£MOOON profits down, debt doubled, am i missing something for the rise this morning?!
Moonpig (LON:MOON) even!
Moonpig (LON:MOON) are generating nearly £60m of cash and has a fairly predictable business, certainly on the cards side. Inc leases, there's £170m of debt, so it's not too scary, especially as their focus is on paying it down asap. Market cap of £480 doesn't seem taxing for a business which is so cash generative, predictable and has good long term growth prospects
I know Paul doesn't like the acquisition and what it did to their balance sheet. Interesting to see if his opinion has changed based on cash generation.
And don’t forget the share overhang from Exponent PE’s residual stake, although, to be fair, it’s only c. 12% now
Hi MassimoJ,
Moonpig (LON:MOON) are generating nearly £60m of cash...
It really isn't generating real world cash of anything like that number!
Operating cashflow is £58m
To get to real world cashflow, I would deduct:
Tax paid £8.6m
23% of total payroll is capitalised as dev spend £12.9m
Bank fees £2.0m
Leases paid £3.5m
Hence my adjusted cashflow is £31m.
I haven't deducted physical capex of £9.7m either, so free cashflow on my basis is £21m.
On that basis, it would take about 8-9 years to pay down the bank debt.
So I don't think it's as cash generative as you think. Although there does seem a large adverse cashflow of £22m relating to decreased trade payables, so if that drops or even reverses next year, then cash generation could improve maybe?
Regards, Paul.
Elephant in the room is again population growth through mass migration which has impacted everything from housing schooling hospitals and water power since 1997 the population of the UK has increased by roughly 20% and urban population by more
https://www.macrotrends.net/co...
You have more than 10 million extra people living in urban centres in UK putting a lot of pressure on an already aging infrastructure
https://www.macrotrends.net/co...
All those people go the toilet that’s a lot of extra waste
SysGroup (LON:SYS) (I hold) - Thank you for covering the recent Sys Group results Paul. I agree with you, I can't make my mind up on this one. Is this what a multi-bagger looks like before it becomes clear in the track record? Or is it just another struggling managed IT services company that will go nowhere? Hence I only have a small holding.
Very reminiscent of Macfarlane (LON:MACF) a decade or so ago? Rather than a Judges Scientific (LON:JDG) ? I remember thinking at the time - am I really investing in a carboard box distributor? Success seems to come down to a variety of factors but management is a common thread? The difference between a very successful buy and build and another struggling company is indistinguishable in the numbers early in the journey? Before the track record develops?
At Sysgroup recent acquisitions have been very well handled and integrated. They seem to have spent the 'pause' enforced upon them by the pandemic improving their internal systems and ability to integrate acquisitions well. The organic growth is not high but compares well against peers in the industry eg Redcentric (LON:RCN) which has stumbled badly in the current economic environment?
The company seems to be doing ok in a difficult market and a competitive industry? But it's hard to tell if they have something special and are moving up a gear. So I was tempted to sell and look for fresh fields at recent highs. I've held off as it seems that they have found new management and I'm intrigued.
Long time CEO Adam Blinks (ok that's a freudian typo - it's Binks Blinks! ) has stepped down at the results and is followed by founder and chairman Michael Edelson. who has something of a track record with multi-baggers. So why is he stepping back? Has he given up on this company, or have they found the right successor? They are replaced by new major shareholder (14%) Heejae Chae who becomes Executive Chairman. Heejae seems to have something of a track record also, until recently having been long term CEO of Scapa, but it's not a company I followed closely having missed the bandwagon on that one? He's also put his money down on this one?
Bottom line. The figures are ok but you wouldn't pick this company on the numbers - it doesn't look to be anything special in a tough industry. So this is all about the management and the buy and build ability with advantage of being small enough to make further acquisitions relatively easy for a long time before it reaches the size that makes things much harder?
The great thing that I like about this kind of company situation - is that it's probably fairly valued on current peformance, so the downside is limited? The multi-bagger potential is pretty much in for free at the moment? The risk is opportunity cost if I hang around for too many years?
So I'm staying around to find out whether Mr Chae has the recipe for the secret sauce? And whether I can learn anything about the recipe - what it's not will be just as interesting as what it might be?
cheers
Mark
Just read up about Heejae. He also used to be CEO of Volex
James Latham (LON:LTHM) such a well run family business. Really good prelims. Outlook statement straight talking and credible. I don't own, I think I should.
And while it lasts - there is the advantage of IHT relief. There has been a significant reduction in PBT etc after a very successful previous year.
Interesting Paul on water companies. Is this another potential victim of base rate increases like the LDI fiasco? There probably will be more. It's a big story if Thames Water does actually fall over with £14bn of debt.
I used to work a lot in the water sector as an advisor. Whatever the media says, water companies are so much better run now than before privatisation, They have invested enormous amounts in capital expenditure, mostly debt funded as Paul points out.
Shareholders have done very well over the last 30 years. Unfortunately, like any regulated business, the easy wins have been taken and the regulator takes a tougher view with every price review. A number of water companies have not being paying dividends. The big issue now though is debt and the need for massive expenditure to remediate the topical issue of sewage spills. The allowed capital return return by the regulator is c5% I think until this is reset at the next price review. For companies with over 75% debt to regulatory capital value (Thames are 80%) then you can see that raising more debt is not very attractive. Raising lots of cheap debt wasn't a problem until interest rates went up 475 basis points!
There is a wider read across in my view to infrastructure assets (wind farms, solar, PFI), GP surgeries, etc. Fundraising to build such assets is no longer viable. Just look at all the infrastructure investment companies now on a discount. They cannot raise funds to build more as they could do in a low interest rate environment! Investors can get over 5% in short dated government gilts - with no risk.
Interesting commentary. Utilities were regarded as the low risk end of the equity spectrum. What is low risk now, i am not sure.
Ok. Bit of fun. Personally think crypto being lined up as the next 'gold' - oh dear.
Thanks for that very accurate representation of the current situation when it comes to future funding of infrastructure
As you say the water treatment under govemnet control was appalling I grew up fishing as a kid on the river Wey and Thames and you couldn’t see more than a few inches into the murky water the only fish that seemed to thrive was the lovable Gedgeon along with Eels
One day through boyish bravado or stupidity we decided to drink a swig of water each I have never benn so sick in my life and my friend ended up in hospital
Years later I went back and was amazed to see the water clear weed growing and lots of different species of fish
Hi topvest,
Good commentary. My only comment is for the read across to renewables infrastructure. I work in renewables (principally offshore wind and electricity interconnectors), and investors and funders seemingly cannot get enough of these projects, and more and more are being announced each week. Since the Ukraine war, European governments have increased renewable energy targets hugely, up from what were already ambitious targets. There seems to be no shortage of take up from debt or equity funders for projects, to-date.
If you're interested, as a starter, just look at the investment programmes announced across Europe by the regulated transmission system operators (including SSE (LON:SSE)), which is largely for work required just to get the electricity grids upgraded to handle all the expected future generation projects.
Cheers
Chris
Thanks Chris - interesting comments on renewables. I did a lot of work in this sector as well at one time. Not small cap, but what do you think about the renewables investment trusts? Renewables Infrastructure (LON:TRIG) Greencoat UK Wind (LON:UKW) etc. - without exception they are on a discount, and pretty much maxed out on project debt and RCFs? So, these companies spent billions, but now can't raise capital and are in recycling capital mode.
I don’t have a view on those specifically, although I’m planning to buy into a renewables IT as soon as I get round to researching them properly.
There’s a few reasons why I don’t think debt/equity funding for offshore wind, interconnectors, solar projects, battery storage etc. will not dry up any time soon.
- There’s rarely a decision to be made between funding a range of infrastructure projects, or sticking money in short term gilts / cash. That’s not how infrastructure investors work, and would do a lot of people out of their own jobs so very unlikely.
- Saying you can have 5% on cash / in gilts / low risk bonds for an unknown but shortish period of time, is not as attractive as saying you can have a 20-40 year almost guaranteed income stream at IRRs of 8%+.
- And / or you can sell all or part of your stake in a project once operation is achieved or at any other point, and recycle your capital into something else, and/or pay down your debt and start again.
Given the (effective) government support in all sorts of ways, it’s still one of the most attractive asset classes there is at the minute.
Cheers
Chris
Would agree with you but 2 things that will have an impact in future is the risk free return on gilts and cash is now around 5%
And again a different elephant in the room is the next Labour governments proposed govement owned green energy comapnay with Labour getting involved with the building and running of solar and wind plants in competition with the firms already doing it
How this will turn out for the existing firms is a guess but my best guess and history would say not well
https://labour.org.uk/press/ed...
https://labour.org.uk/press/ke...
https://www.ajbell.co.uk/artic...
For me all this reads as 'copper' and 'coal' for steel. At some point governments will nationalise their resources - except our of course.
Two from us today as React (LON:REAT) have announced HY Results.
The Group has delivered record revenues and EBITDA in H1 to March 2023. The rising proportion of recurring revenues, improving margins and strong cash generation in consolidating, specialist markets has resulted in improved visibility. As such, we have introduced estimates for FY24 and FY25, with an expectation that EBITDA margins will improve to 13%+ by FY25 (vs. 7.0% in FY22A). As the final deferred consideration will be paid during FY24, we expect net cash to rise to £3m or 34% of the NAV during FY25. Our increased fair value assumption reflects our DCF and FY1 PER and price/book peer group models and sits at 2.0p (from 1.7p), a 57% premium to the current price.
https://www.equitydevelopment....
There is also a presentation for investors at 2pm today. Thanks all. https://www.equitydevelopment....
Encouraging results from React (LON:REAT) today but still loss-making, despite what they say about adjusted profits... It is a bug bear of mine in trying to reconcile their accounts that they provide one figure for adjusted EBITDA (£927k), another for 'Adjusted profit before amortisation of acquired intangible assets and exceptional items' (£773k) on which their EPS number is calculated, yet they've made a loss for the period (£86k). Only company I know that seeks to add back all the costs that they incur through the normal course of business before presenting EPS numbers... Grrrrr!
StrollingMolby,
Regarding React (LON:REAT), an £821k charge for 'amortisation of acquired intangibles' cannot be considered "costs that they incur through the normal course of business".
It would be absurd not to add it back for valuation (EPS) purposes.
Regarding React (LON:REAT) REAT, an £821k charge for 'amortisation of acquired intangibles' cannot be considered "costs that they incur through the normal course of business".
It would be absurd not to add it back for valuation (EPS) purposes.
Effortless Cool,
Yes OK, fair point on the amortisation of intangibles – that seems to be related to acquisition of customer lists of LaddersFree and should rightly be added back. That £821k amortisation can also be seen in the reduction on the balance sheet of ‘Intangibles – Other’.
But to get from headline profit of £927k to that used for EPS purposes £773k) and then down to the overall loss (-£86k) takes more thinking than I’m used to!
The P&L doesn’t even include £773k as the number on which they are calculating EPS, you need to look at notes 4 and 5 to see what is included or not included in that number and the adjusted EBITDA figure.
If it was all transparent I would have no problem, but they seem to be deliberately obfuscating to make the figures impenetrable when there is no need to do so. They have a good story to tell and should let the numbers speak for themselves.
Also, in the 2022 Interims they reported a net loss for the period of -£92k, which this year is now -£88k. Totally de minimis I know but no acknowledgement or explanation of what has changed is provided.
I’ve only looked at 2020-21-22 so not sure if this is a one-off move or indicative of goalposts moving each reporting period – I’ll reserve judgement until I’ve seen another couple over the next year.
And I say all this as a new shareholder, as I bought in three weeks ago… In any event, Equity Development’s revised price target of 2p (+18%) is welcome, now we just need the price to follow.
SM
All the React (LON:REAT) adjustments are clearly set out in note 5, so I don't see any sign of deliberate obfuscation. Standard practice, in fact.
With regard to H1 2022, you are comparing two different figures and complaining that they are not the same! £92k was the net loss (post tax), and £88k was the pre-tax loss (think about the 'T' in EBITDA). Nothing has changed.
If ever there was a case of following the trend it's tinyBuild (LON:TBLD)
I don't watch many presentations but the finance guy, who's now gone, was one of the least impressive people I've seen. I imagine the shares will be hammered today on yet more missed targets.
Desperately poor results.
I think the worst bit about the update (and that's saying something) is appointing the previous Head of M&A as CFO, who 'reads economics' and has a masters degree in Finance. That isn't enough experience to run a listed company.
In fact, their M&A was so terrible they almost completely put a halt to it after the two disastrous acquisitions (the two companies in the update which are materially underperforming and they previously impaired by circa $11m).
This company desperately needs someone at the top who knows how to run a listed company and keep their operations under control. Internal hires won't cut it. They may release some good games over the next few months, but I fear there's still some skeletons in the financial closet which have yet to come out.
Another expensive AIM lesson!
I totally agree, even more clear now it's been run extremely poorly. They need an outside hire for the CFO at the very least. I think they have been very misleading as well, this was part of their outlook statement on 29th March, not long ago:
" All considered, the Board remains confident the Company is on track to deliver results at least in line with expectations, plus accretive acquisitions."
I doubt it could have changed so much in the past three months. Also I was wondering what was causing the sell off before today and it appears people obviously knew this was coming. Is this not insider trading?
I definitely can't trust the management there now. I commented last week suggesting I couldn't find a reason for the sell off and was considering loading the boat. Thankfully I didn't, though unfortunately do have a small position.
Down 68%. People were talking of averaging down with shares yesterday, well this is the reality if you get it wrong. To then multiply huge losses is mad I think. Personally I'm not smart enough to know which will be long term winners but I am in control of how much risk I take.
More like 80% down! tinyBuild (LON:TBLD)
It's probably into small punt territory now with market cap of £12m tho I doubt funds will care what price they sell, just want it off the books.
I didn't catch the bottom at 5p but had a small punt at 6p for a day trade. Will pay for a couple of years stocko subscription.
Same. Having a punt that it’s deserved but over done.
I joined you too, for a fun punt on Tinybuild, after reading Graham's piece. It's got enough cash for now, so solvency not an issue. Could bounce, who knows?
It's definitely a punt... CEO is an ex-gamer in his 30s and the new CFO was ranked #1 Stock Picker in 2019 (presumably by his mum as he didn't pick this one very well!)
haha very good Jacxx. Im just annoyed I didnt think to write that :)
100% correct. The chart tells the story, whatever analysis you use, and the moving average is the best and simplest of all, does not lie. Why fight a trend - put it in something that the ski slope is going the other way. I'm a holder and loser as well sold on a some story. My rose tinted glasses have faded to black for future stories for sure.
Paul, I really enjoyed your look at Severn Trent. But I think your observation that dividends are not coming out of cash flows is double-sided. No, divis are not preventing capex despite what my left-leaning FB feed is bound to assert this week, but the need to borrow to pay divis is hollowing out the balance sheet until an inevitable re-financing or collapse. That’s not good for anyone!
Morning BnB,
Glad you found my thing on water companies interesting, thanks!
... but the need to borrow to pay divis out is hollowing out the balance sheet until an inevitable re-financing or collapse. That’s not good for anyone!
Absolutely, I 100% agree! Although potentially this could end up quite well for the taxpayers, if the water cos end up going bust, then they can be nationalised at very little cost, presumably.
It would probably need a sector-relevant legal expert to tell us what would happen to the bondholders. But if they took a bath too, then I don't suppose many of us would shed any tears. Although that might then deter private sector investment in other infrastructure projects?
It's fascinating how we're seeing financial stress appearing in multiple leveraged sectors, due to the sudden, dramatic rises in interest rates everywhere (important to remember these are global problems, not UK-specific).
I'm told that commercial property could be a bloodbath, as the over-leveraged players could seriously struggle to refinance debt that matures. Combine that with the popularity of work-from-home. There was an article saying that in Germany very large numbers of office workers are now permanently working from home, so many offices won't be needed, and might have to be repurposed as residential, or knocked down if they're old.
I see HSBC is not planning on renewing its lease in Canary Wharf when that expires in 2027, preferring to relocate into central London, in a smaller premises (the old BT building apparently).
Regards, Paul.
Find it odd you wouldn’t care about people losing their entire investment as a bond holder and you are right it would cerntinally deter private investor funding for future infrastructure projects
Do agree with your point that water and sewage disposal is remarkably cheap far to cheap really if you want a better service you have to pay for it to get clean drinking water and all your sewage disposed of for the cost of a coffee every day is one of the best deals you can get
Find it odd you wouldn’t care about people losing their entire investment as a bond holder
Bond investors are large, sophisticated, almost always institutional investors. Hence they're big & ugly enough to look after themselves. That's totally different to small investors, who we champion here obviously.
No as you well know there are plenty of small investors that invest in bonds for income
Also as you well know those large institutional investors run pensions bond funds etc funds that small investors invest in so either way small investors will loose
Find your reply frankly less than I would have expected of you
I am interested in your commercial property comment, Paul. It seems to be the story, but what do you (or others) think about this from Regional REIT (LON:RGL) http://newsfile.refinitiv.com/getnewsfile/v1/story?guid=urn:newsml:reuters.com:20230609:nRSI1730Ca&default-theme=true
? I do hold, so am biased to put some credence in this from Stephen Inglis (who basically runs it and who says his family and friends own c. 12% of it).
In his own inimitable style, I seem to recall that Terry Smith called utilities Ponzi schemes. The dividends were just there to bait folks into the next capital round, whenever that might be.
I think investors are best advised never to invest in companies where net debt is greater than five times net profits, regardless of the seeming stability of revenues of the company. It's a simple rule that can save investors from much heartache. Debt is such a drag.
As far as Thames Water is concerned, it is only fair to point out that they have spent £4 billion on their ‘super sewer’ project. We all complain when rivers are dirty, but we also complain when the water companies run up large amounts of debt.
Not small cap but wondered if posters here are intending participating in the retail offering for CAB Payments. It seems to be listing at the lower end of estimates (around £850m market cap) which implies a historical p/e of around 15 but they seem to be implying a forecast p/e of around half that based on recent trading.
A separate question - I clicked the 'Sign Up' button on RetailBook website and entered my email but have heard nothing. It says on the website that it launches in H2 2023 but clearly they are already operating. Am I missing something? Are other people using RetailBook already and how does it compare to Primary Bid which I have had settlement problems with?
Thanks in advance for any responses.
NRR.L CFO bought shares.
https://www.londonstockexchang...
My morning smallcap tweet: Kicking sand in the face of failure
tinyBuild (LON:TBLD) Belluscura (LON:BELL) Cineworld (LON:CINE) Ingenta (LON:ING) DX (Group) (LON:DX.) Time Finance (LON:TIME) Falanx Cyber Security (LON:FCS) Poolbeg Pharma (LON:POLB), Light Science Technologies Holdings (LON:LST), Anpario (LON:ANP), Likewise (LON:LIKE), Tandem (LON:TND), De La Rue (LON:DLAR)
◄tinyBuild (TBLD)► warns at AGM that FY23 rev materially below exp and and a more acute reduction in adj EBITDA in FY23 and 24. Cash end Dec guided $10-20m - previously at least $26.5m. Latter blamed on "significant increase in development cost amortisation and a slightly higher percentage of revenues paid out to developers". CFO leaves for personal reasons. Companies should not be sitting on material warnings until AGM day! [SP=34 Cap=69m]
◄Belluscura (BELL)► premarket launch of its DISCOV-R portable oxygen concentrator. [SP=33 Cap=45m]
◄Cineworld (CINE)► US court confirms amended joint chapter 11 plan. Nothing for holders. [SP=0.5 Cap=7m]
◄Ingenta (ING)► wins £2m 5 yr contracts with implementation revenue due to commence in H2. [SP=93 Cap=14m]
◄DX (DX.)► agrees with administrator of Tuffnells an initial licence-to-occupy 13 former Tuffnells sites and to pay £1m for the freehold of a further site. The initial licences are a precursor to entering into direct lease agreements. Has taken on over 550 customers so far. [SP=31.5 Cap=191m]
◄Time Finance (TIME)► guides FY-May rev up 16%. In line? Own-Book lending origination up 14%. Pretax £4.1m (£1.1m). "Strong visibility of future earnings." [SP=26.7 Cap=25m]
◄Falanx Cyber Security (FCS)► guides FY-Mar rev up c.9% organic. In line? Outlook - "healthy pipeline of business and has significantly lowered its operating cost base recently and expects to improve its financial performance in the next few months". [SP=20 Cap=1m]
◄Poolbeg Pharma (POLB)► AI led programme identifies multiple influenza drug targets. [SP=8.5 Cap=43m]
In line: LST, ANP, LIKE, TND, DLAR
Bob Holt buys 1m shares Revolution Beauty (LON:REVB) - such fun!
Please my I ask my fellow investors for advice about the RNS for HEIQ. They have delayed their company accounts but the latest RNS today does not say when the accounts will be published, it’s seems (in my opinion) to provide excuses for the delays. It’s seems like a red flag that they have not provided a date. Would you see this as a red flag too? Please note I hold a position in this company.
My experience tell me to get out if I can. If a share has dropped by more that 50% it probably drops more!
Massive red flag. Usually means a restatement of accounts due to a substantial error or fraud. Unlikely that accounts cannot be produced on time, they are on computer these days! I am a Chartered Accountant.
Thank you very much both !
Hercules Site Services (LON:HERC) - initiation report *** "Driving growth through innovation"
Hercules Site Services is an innovative, entrepreneurial and high-growth business with a focus on the UK Infrastructure market. Its shares were listed on the AIM in February 2022.
The core business is labour supply, where Hercules has built a reputation as a trusted partner to an impressive blue-chip client list. Hercules has also expanded its offering in recent years into complementary construction services, namely civil projects and specialist equipment hire.
Growth to date has been highly impressive (three-year revenue CAGR 50%) and demand is underpinned by a favourable outlook for infrastructure spending, a structural undersupply of skilled labour and recent organic investment in technology and fleet expansion.
Infrastructure investment has been a key driver of the recovery of the construction industry post Covid and the medium-term outlook is well underpinned by major projects, not least HS2 with Phase One (London to Birmingham) approaching peak activity over the next 3 to 5 years.
We believe that our full year earnings forecasts are conservative and see Fair Value at 60p per share.
Severn Trent (LON:SVT) is just another share that the PI can buy and sell at will. I once held some and sold at a profit in 2019, had I kept them I would have made some more but even the anyone could see the writing on the wall:
You see, whenever a Government quango exists to protect the public interest conflict is bound to arise one way or another. With water it's dirty rivers and dirty seas today. Water is definitely too cheap, taxes IMHO too expensive.
The reason why the water supply was privatised under Thatcher was that when the EU introduced stricter water quality standards the government did not wish to provide the enormous sums of money necessary in order to upgrade the purification equipment. Opportunistically they realised that they could not only avoid paying for new equipment but also make a profit by privatising.
Almost 40 years later, it looks as though they may have to take water back into public ownership. Of course, if that does happen the debt will be the problem of the current owners, not of the government.