Small Cap Value Report (Thu 3 Aug 2023) - BLV, XAR, MAI, SCS, TTG, DEVO, MER, ADF

Good morning from Paul (yes I'm back!), and Graham.
Today's report is now finished. Thank you for all the reader comments, very interesting!
I've been enjoying a short break with the family in a holiday cottage in Blakeney, Norfolk ("drizzle tourists!"). What a lovely part of the country, which I've not explored before. Quite a surprise when a pleasant chap stopped me, asking "Are you Paul Scott from Stockopedia?!, and we had a friendly chat. So our community spreads far and wide! Mum asked him how he recognised me, and he replied, "Well he pops up on my computer every weekday!".
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Here's the plan below - as usual we'll probably end up doing 5-7 of these on a typical day.
Feel free to add your own views on anything in the comments section, which we very much welcome!
Summaries of main sections
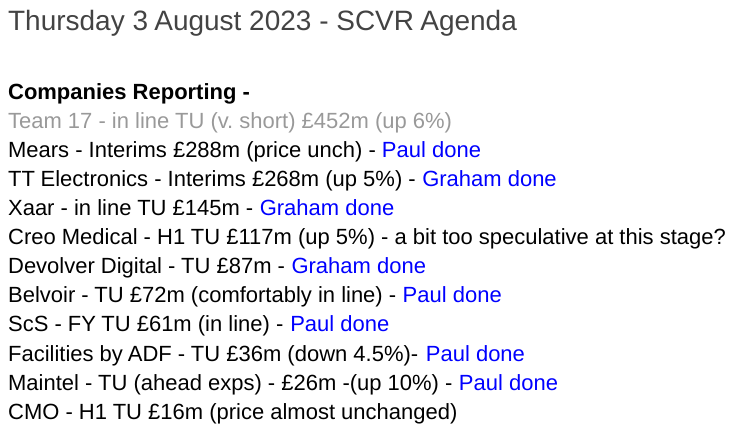
Belvoir (LON:BLV) 193p (pre market) £72m - Trading Update - Paul - GREEN
Buoyant demand for residential lettings has offset a slow property sales market, leading to H1 being strong, and confidence is expressed in FY 12/2023 forecasts. That de-risks the shares nicely I think, and on a modest 10x PER, plus 5% yield, I remain positive on Belvoir shares.
Xaar (LON:XAR) - down 3% to 180p (£139m) - Trading Update (in line) - Graham - AMBER
Analysts are hopeful of an earnings upgrade later this year, on the back of improved conditions in China, but the further reduced cash balance worries me. Inventories and raw material holdings have ballooned. Current earnings do not support the valuation here.
Maintel Holdings (LON:MAI) - Up 9% to 196p (£28m) - Trading Update - Paul - AMBER/RED
A good H1 trading update, and FY 12/2023 forecasts raised significantly by Finncap. However, I'm put off by the awful balance sheet, with heavily negative NTAV, and far too much debt. It's already doubled, so I think the upside has probably mostly already happened, so I'd be a top-slicer at this stage if I held.
SCS (LON:SCS) - Down 6% to 170p (£57m) - FY 7/2023 Trading Update - Paul - GREEN
In line with expectations update for FY 7/2023, with reassuring news on order intake, and as always pots of cash (above the market cap). I discuss below what the new normal level of earnings might be post-pandemic. Assuming there's nothing going structurally wrong, then this share seems remarkably cheap.
TT electronics (LON:TTG) - up 3% to 156.8p (£277m) - Half-year Results (in line) - Graham - GREEN
This international industrial company is confident it will deliver full-year expectations. Revenue growth has been impressive, but may plateau in 2024. More importantly, leverage has reduced through higher profitability. I continue to like this stock at a single-digit PER.
Quick Comments
Not a small cap but...
Next (LON:NXT) - Q2 ahead of plan. Increases FY 1/2024 PBT guidance by +£10m to £845m. Clearance sale has gone well. As always, the sector leader performs reassuringly well.
Other snippets...
De La Rue (LON:DLAR) - some signs of improvement in the most recent update a few weeks ago, and the biggest shareholder has switched from a seller to a buyer. So looks potentially interesting as a long-awaited possible turnaround. However, today's news that Finncap has been appointed joint broker alongside Numis makes me wonder if it's limbering up for another discounted fundraise? At least we should get some research from Finncap, as Numis are useless for our purposes. I'll continue watching from the sidelines, as risk:reward looks a little wobbly right now to me, but it's guesswork at this stage. Also, I just can't bring myself to buy into a banknotes maker, when all around us are signs of countries gradually going cashless.
Devolver Digital (LON:DEVO) - down 28% to 14p (£63m) - Trading update (profit warning) - Graham - AMBER
This November 2021 IPO by Zeus Capital is now down by over 90% from its placing price. It was originally thought to be heading for a £1 billion valuation! Currently, however, its new titles are being delayed (“in order to continue value-add production to further improve their chances of success and longevity”). On top of that, subscription revenue is down, and the company’s back catalogue is failing to contribute. The economy is blamed for the poor performance of the back catalogue, which I would say is a very poor reason to give investors: old video games are one of the best value forms of entertainment.
“Normalised Adjusted EBITDA” (!) is expected to be negative in H1, and “at least break-even” for the full year. In more bad news, the company’s cash balance reduces to $64m (£50.6m) after it spent $7m buying its own shares for the benefit of its employee option schemes (stock compensation is excluded from Normalised Adjusted EBITDA, naturally). That war chest of cash should at least provide some support to the stock at this level and so I am happy to take a neutral view.
Mears (LON:MER) - up 2% to 277p (£293m) - Interim Results - Paul - GREEN
I’m almost out of time, but had a very quick skim of these H1 results. We’ve reported on Mears favourably several times, it’s a good value share, performing well.
Today it says -
- H1 saw aPBT up 18% to £21.3m.
- FY 12/2023 guidance from Mears is now: revenues £1bn+, adj PBT £40m+
Broker updates - I can’t find any, but the StockReport broker consensus figures look consistent with, or a bit below today’s update. So we should be able to rely on the fwd PER being achievable or beaten.
Balance sheet is strong, and top marks for MER providing its average daily net cash figure, which is £57.4m, as well as the year end snapshot of £116m at 30 June 2023. We need to keep nagging all companies to start reporting average daily net cash/debt. Note very large lease entries on balance sheet.
Share buyback of £20m is “well advanced”.
Paul’s opinion - this all looks reassuring to me, although the lack of available broker research is an impediment to private investors taking an interest.
I think the strong recent rally from c.200p to c.275p looks fully justified. Maybe some traders will get bored, and bank some profits, thus giving us a better buying opportunity? Although I think it looks nice value at the current price regardless. So another GREEN from me.
Facilities by ADF (LON:ADF) - up 1% to 44.75p (£36m) - H1 Trading Update - Paul - AMBER/GREEN
This heavy equipment hire company (UK-centric) for the TV film industry cleverly softens the blow of a profit warning today. Strong H1 performance to June 2023. But no surprises that the USA strikes impacting TV/film are likely to cause a softer H2. It guides £35-40m FY 12/2023 revenues, with possible upside on that if the strikes end. Some projects being pushed into 2024 as a result, so could be a catchup effect next year from pent-up demand. Cenkos (many thanks) lowers 2023 to aPBT of £1.7m, which is 1.6p EPS. But that soars to 9.6p in 2024. The balance sheet looks OK to me, with c.£19m NTAV.
Paul's opinion - I've always quite liked this company, so the obvious time to buy would be when something temporary impacts performance, which is what's happened now. The other question is whether the strength of performance has been due to unsustainable boom in streaming companies creating loads of new content? Also there have been issues with gaps in schedules hurting short-term profits before. Overall though, I'm mildly positive here, taking a medium-term view, so we'll go AMBER/GREEN.
Paul’s Section:
Belvoir (LON:BLV)
193p (pre market) £72m - Trading Update - Paul - GREEN
Belvoir Group PLC (AIM:BLV), a leading UK property franchise and financial services Group, provides the following trading update ahead of publishing its Half Year results on 4 September 2023.
Stronger than expected H1
For background, I’ve looked back at your previous coverage this year, as follows -
1 Feb 2023 - GREEN - 183p - FY 12/2022 slightly ahead exps. Finncap reduces 2023 forecast by 13%. Buying opportunity? Yield 5%.
27 Mar 2023 - GREEN - 169p - FY 12/2022 ahead exps. Paid off debt. Graham & Paul both think it’s cheap.
18 May 2023 - GREEN - 205p - in line (lowered) 2023 exps. Short-term maybe priced about right? Long-term, good value.
Today’s update sounds reassuring, key points being -
Stronger than expected H1, with revenue up 3%
“Comfortably in line” with expectations for FY 12/2023 (strange wording! Does this mean slightly ahead? Anyway, I like it, sounds like a profit warning or further reduction in broker forecasts is now unlikely, improving risk:reward for investors)
Strong acquisition pipeline.
Net cash £0.4m.
Buoyant lettings income offsetting weak sales market.
There’s more detail in the announcement.
Paul’s opinion - Finncap has confirmed (many thanks) that forecasts are unchanged, but it sounds to me that we can have a lot more comfort in these being achieved, given today’s “comfortably in line” update.
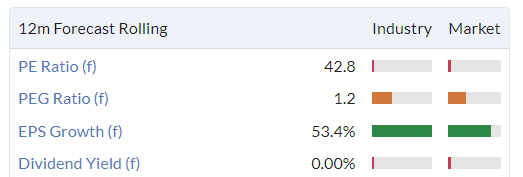
With the StockReport showing a fwd PER of 10.1x, and a 5.1% yield, and an update today reassuring us that we can rely on the forecasts, I think this makes BLV look attractive. Probably not much downside risk (as most of its revenues are linked to recurring lettings), but good upside potential in the medium term, as earnings resume growth, and the PER rating would probably rise too, in the next bull market.
Hence I’m happy to stay GREEN. Patient investors should do well here I think, and there’s a decent yield to keep you occupied along the way.
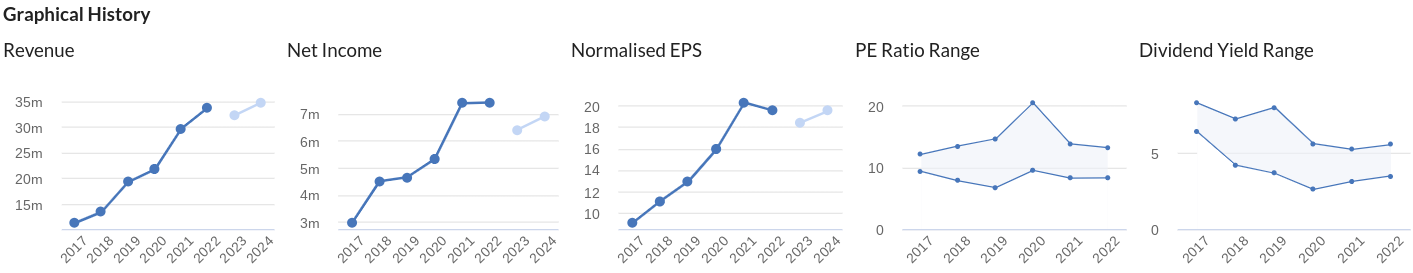
I imagine we might see the forecasts improve once the property market returns to normal, hence what looks like a flattish trend on EPS below, could resume growth - helped by more acquisitions, where BLV has a good track record. So a growth company, currently priced as ex-growth - that's attractive to me.
Maintel Holdings (LON:MAI)
Up 9% to 196p (£28m) - Trading Update - Paul - AMBER/RED
Maintel Holdings Plc, a leading provider of cloud and managed communications services, issues the following trading statement for the six months ended 30 June 2023, based on unaudited management accounts.
This very small share caught my eye today because it’s up nearly 10%, so we like to focus on big movers, in case there’s a bigger opportunity for a re-rating, or a lucrative trade.
There doesn’t seem to be anything recent in our archive, which is odd, as I can vaguely recall reviewing it at some point in the last year.
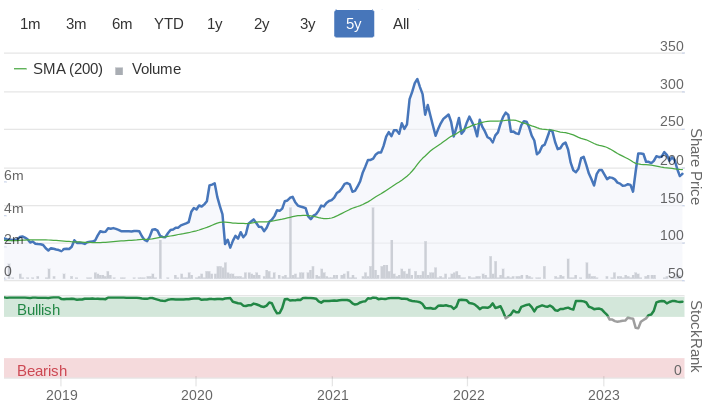
There’s been a fabulous recent rally in this share, doubling from the April-May lows of c.100p.
Today’s update key points -
“Solid H1 performance supported by business transformation”
FY 12/2023 outlook -
the Board is confident that the Company is on track to deliver results that deliver revenue in line with market expectations, and Adjusted EBITDA ahead of market expectations.
Strategy is to focus on margins & profitability.
H1 revenues £47.5m (up 2%)
Forecasts & valuation - Finncap has helpfully published an update note, which raises aPBT for FY 12/2023 from £2.8m to £3.7m, a nice upgrade. In EPS terms, this is now 22.8p (previously 16.8p).
At 196p/share that now gives us a PER of 8.6x - looks cheap? Only if you ignore the terrible balance sheet! Net debt has risen to £21.4m, and the balance sheet overall looks very stretched to me (hence risk of a dilutive placing, and little to no ability to safely pay any dividends).
At FY 12/2022, NAV was £19.4m, but this included £53.0m of worthless intangible assets. So NTAV is an awful £(33.6)m. That’s why the PER looks cheap. If we manually repair the balance sheet, just back to zero NTAV, then the share count would more than double, which means the PER would more than double, to the high teens. Therefore, I think that demonstrates the share is not actually cheap at all. Plus debt is expensive these days, in interest costs.
However, upside could come if profits continue rising. Finncap’s forecast for FY 12/2024 is a 43% rise to 32.5p. If that happens, then concerns about bank debt would recede somewhat, and all the benefit of improved performance flows to equity holders, which is why sometimes highly geared companies with awful balance sheets can be spectacular trades, for people prepared (or unaware of!) the considerable risks involved. I think McBride (LON:MCB) has been a good recent example of such a risky trade - improved performance makes the excessive bank debt less of a risk (and the bank has been very accommodating with MCB, giving it time to hopefully trade its way out of a grim financial position).
Hence it’s worth keeping an open mind with this type of recovery share (MAI as well as MCB).
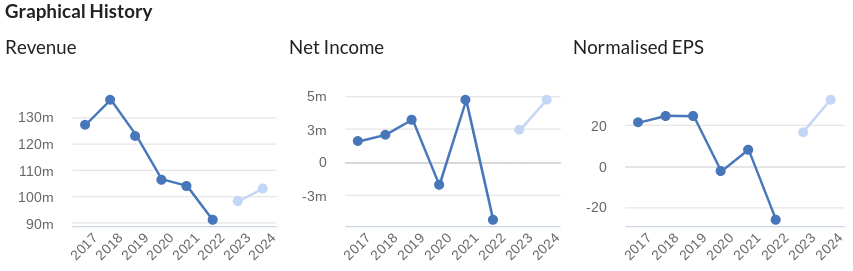
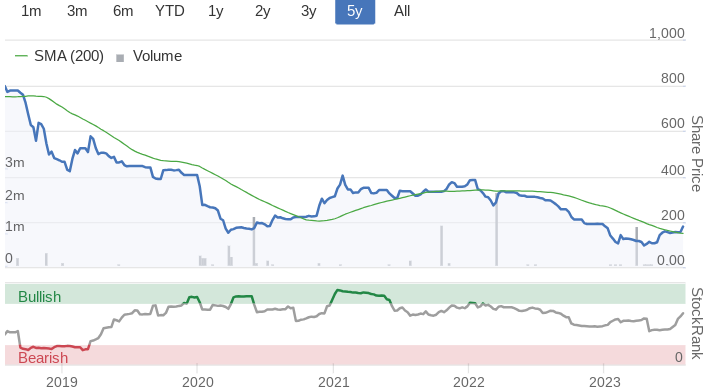
Another thing to consider is that MAI is recovering from a poor patch. It doesn’t look like a structurally growing company to me, as the graphs below demonstrate. That limits the share price upside I think, which has maybe already happened? Although someone might bid for it, and be happy to take on the debt.
Paul’s opinion - on closer scrutiny, the large share price rebound that’s already happened, combined with a very weak balance sheet, means that I’d probably be top-slicing some profits if I already held this one. Hence not of interest to me as a new purchase.
The very weak, over-geared balance sheet, means I have to warn about that with AMBER/RED. So not a disaster, but be careful with the elevated risk here - it’s up to you to decide if you think the upside outweighs the higher risk of a weak balance sheet. Sometimes it does, sometimes not.
SCS (LON:SCS)
Down 6% to 170p (£57m) - FY 7/2023 Trading Update - Paul - GREEN
ScS, one of the UK's largest retailers of upholstered furniture and floorings, today issues a trading update for the 52 weeks ended 29 July 2023.
Full year profit in line with market expectations
I’m not sure why the share price is down today (and a ridiculously wide bid-offer spread), as this sounds reassuring to me -
The Group expects to report full year profit in line with market expectations, driven by effective cost management and improved trading in the second half of the year.
The Group's financial position remains robust, with cash at 29 July 2023 of £69.5m and no debt.
Furniture retailers benefit from a favourable working capital cycle, with money received from customers before the third-party factories have to be paid for making each item to order.
Since that continuously rotates, then ScS is permanently sitting on a whopping great cash pile similar to its own market cap, and should now be earning several million each year in interest income on that.
Demand and profitability have been volatile in recent years, with the pandemic lockdowns causing stop-start trading, as for so many companies. So it’s difficult to ascertain what is normal, in terms of profitability.
Order intake - I find this reassuring -
ScS's updated brand and strategy are beginning to resonate with customers, resulting in strong like-for-like order growth of 6.0% from weeks 34 to 52 building on the 5.7% previously announced for weeks 27 to 33. As a result of this growth, following a more challenging first quarter, order intake for the full year was in line with FY22.
Continuing the trend of the past two years, the ScS business continues to gain market share, cementing its position as the UK's second largest upholstered furniture retailer.
Outlook - this doesn’t say much, but has a generally satisfactory tone I’d say -
We are cognisant of the economic conditions facing our customers including higher interest rates and low consumer confidence, which are forecast to continue throughout FY24. However, we remain confident that the Group's strategy and strong balance sheet will enable ongoing trading resilience and we continue to expect to grow our market share while selectively investing in store and other strategic growth opportunities.
Paul’s opinion - SCS looks good, and dirt-cheap, as always, taking into account the market cap is entirely covered by cash - which is not just a seasonal spike, it’s ongoing.
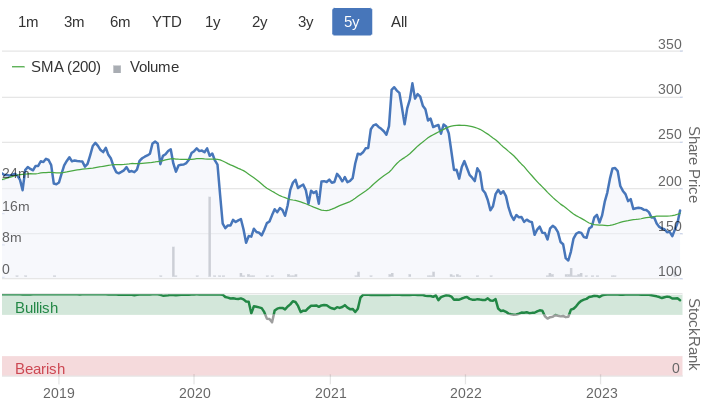
I wonder if brokers have slipped through a downgrade? No, that doesn’t seem to be the case. Shore Capital kindly lets us see its thoughts on Research Tree this morning, leaving EPS at 14.8p for FY 7/2023. That may be in line, but it’s a long way down from the 35-40p EPS achieved in the previous 2 financial years. So is the much lower profit this year the new normal, or a relatively poor performance in a year dominated by cost of living pressure on households? Should we be anticipating stronger earnings in an economic recovery? Or is ScS suffering due to some undisclosed internal problems? I don’t know, but the cash pile gives such amazing downside protection, that I can’t help but view this share positively. Freight costs should have dramatically fallen, so I'm a bit surprised that hasn't boosted this year's profits.
Maybe to some extent, people spent their lockdown enforced savings on new settees in 2021 & 2022, and now don’t need to replace them yet? SCS does generally have a value type product, suggesting its customers might be hit disproportionately hard by cost of living pressures on food and energy?
Overall then, I see SCS shares as highly attractive value, taking a medium-term view. It has to be GREEN.
Note that the share count has fallen quite a bit in recent years, due to buybacks. Surely 250p-ish might be achievable once things start to improve?
Graham’s Section:
Xaar (LON:XAR)
Share price: 180p (-3%)
Market cap: £139m
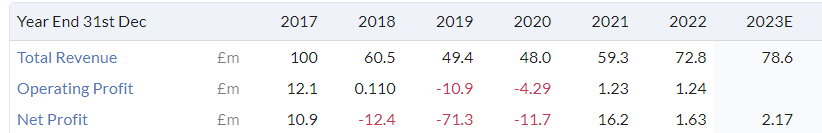
This “inkjet printing technology group” has generated hugely erratic financial results over the years. Today, it reassures investors with an in line with expectations update for H1, although I’m not very reassured by it. Here are the key points:
Revenue down 5% to £34.7m
Adjusted PBT in line with expectations, as the costs of a factory reorganisation are offset by the sale of “non-core IP assets”.
Operationally, the company seems happy with the rollout of its new Aquinox printhead. Phase one of its factory “efficiency programme” has been successfully completed.
Net cash fell from £12.6m to £7.3m, “in line with expectations”, and “reflected the previously communicated investment in inventory”.
While the company may be satisfied with this cash balance, I find it unnerving.
I got used to Xaar having cash of £20m+ (it was £40m+ for several years).
When a cash balance depletes like this, you hope that it will result in significantly improved profitability, either through acquisitions or internal investments.
It’s true that Xaar has made a couple of small acquisitions in recent years, but it also sold a valuable stake in a 3d printing business.
The really big change has been in inventories: raw material and finished product holdings have increased by almost £20m over the last two financial years, and finished 2022 at £29m. The company does have a reasonable explanation for this: while reorganising their factory, and dealing with fragile supply chains, they needed to be sure that they would be able to meet customer demand.
So my question would be: when can investors look forward to inventory reducing again, and releasing all of that cash back to the company and its shareholders? Xaar doesn’t seem to have made any promises on that front.
The Outlook statement only says that the investment in inventory “means the Group is well placed to capitalise on further commercial opportunities”.
They expect conditions to improve further in China in H2, and are looking forward to both customer product launches (which increase the demand for Xaar’s products) and new Xaar product launches.
CEO comment:
"We remain focused on the delivery of our strategy and taking advantage of the significant opportunities we have that will drive profitable growth. Our products continue to generate strong interest from customers, demonstrating our leadership in printing highly viscous fluids with all the sustainability benefits they can deliver. We have positive momentum, a growing product pipeline and look forward to continuing to accelerate our strategy and performance in H2 and into 2024."
Estimates: the forecasts from Progressive are unchanged. They are hopeful of upward revisions to forecasts, but are waiting for the picture to be more clear when the interim report is published in September.
The adjusted PBT estimate for the year is £2.5m.
Graham’s view
I don’t think I’ve ever given this stock the thumbs down, but I’m close to doing that today. It’s just that I know how volatile Xaar’s earnings can be, and I worry what will happen if they have another rough patch:
If conditions toughen for them again, they might not have the luxury of a huge cash balance to cushion the blow. This is the type of company that I think needs a large pile of cash, to help it survive the bad years.
I will remain neutral on it for now, on the grounds that the buildup in inventory and raw materials may unwind, at least partially, now that their factory reorganisation is complete.
But it’s important to note that current earnings don’t support the market cap: these shares are pricing in an earnings recovery and I have little faith in that happening in the short-term.
TT electronics (LON:TTG)
Share price: 156.8p (+3%)
Market cap: £277m
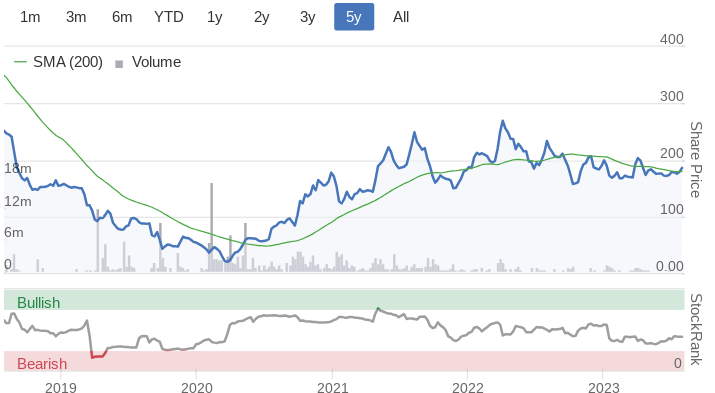
This is a main-market listed manufacturer of electronic components. I’ve been positive on it since last November, when I noticed that it was trading cheaply despite showing excellent revenue growth.
It was carrying too much debt, but laid out a clear objective to get its leverage multiples under control.
There hasn’t been any sustained improvement in the market cap since then, but it has paid a dividend:

Here are the H1 results - :
Revenue +12% at constant FX to £309m
Adjusted operating profit +34% at constant FX to £25.6m
Adjusted operating profit margin improves from 6.8% to 8.3%
Return on invested capital improves from 10.5% to 12%
It’s not all that common to see companies calculate their own ROIC - but it’s a huge green flag for me whenever I see it. Even if, as in this case, the ROIC is unspectacular, it shows that management is trying to make it as high as possible.
Achieving high ROIC is about generating high profit margins as efficiently as possible. One of TTG’s goals is to achieve a double-digit operating margin: again, even if they fail to hit this target in the short-term, it’s important that they are at least trying! They say that a 10% adjusted operating margin is “within reach”.
Adjustments: the company adjusts out nearly £5m of costs. These include nearly £3m of amortisation and £2m of miscellaneous one-off costs.
It’s an improvement on H1 last year, when £9m of costs were adjusted out. One of things I’ve been looking for from TTG is cleaner accounts, with fewer adjustments.
Net debt is little changed at c. £139m, but the leverage multiple falls below 2x thanks to increased profitability.
2x is the company’s target upper limit for leverage; at current profitability the multiple is 1.8x, and they expect it to reduce further.
It does very much sound like they intend to reduce leverage through increased profitability, not by reducing the actual amount of net debt. They are monitoring an “active pipeline” of M&A opportunities, and have been spending heavily on R&D and capital equipment.
Interim dividend keeps pace with inflation, increasing 8% to 2.15p.
Order book “provides visibility for balance of 2023 revenues with cover building for 2024”.
Book-to-bill ratio is not provided, and it sounds like it was below 100%, i.e. orders received did not fully replace orders fulfilled. In the CEO’s words: “As expected, order intake has started to normalise, but has still broadly tracked our revenue growth in the first half”
I wouldn’t be overly concerned about this, although it does imply that revenue may plateau. That would be in line with existing forecasts: Stockopedia shows that 2024 revenues are only expected to grow to £641m, from an estimated £636m in the current year.
Outlook - they have “increased confidence” in delivering full-year expectations:
…we remain focused on executing on the order book, delivering continued strong profit growth and driving a material step up in free cashflow and further reducing leverage by the year end.
Graham’s view
This is playing out more or less as I hoped it would. The leverage multiple is reducing (albeit through increased profitability, not by paying down debt). The accounts are looking cleaner than last year. Revenue has grown in line with inflation, although revenue growth may cool between now and 2024.
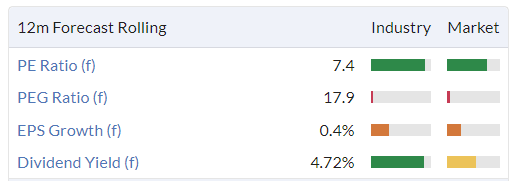
As the share price continues to drift, this company is trading at a single-digit earnings multiple. Is that fair?
TTG will have a new CEO from October, and I guess that does introduce an element of risk. However, it looks set to be an orderly transition, and the new CEO was in charge at Rotork (LON:ROR) (market cap: £2.6 billion) until 2017.
I’m going to remain positive on TTG, as I think it’s a higher-quality company than the market is giving it credit for.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
I sense a sell has begun this week, lots of stocks drifting down and losing gains they have made post good updates e.g. Oxford Metrics (LON:OMG) , Wilmington (LON:WIL)
As regards Oxford Metrics (LON:OMG) they need to do something with that cash pile! Frustrating
At this valuation SCS (LON:SCS) could buyback all but one of the outstanding shares for cash and still have enough to continue the trade - albeit with a negative NTA balance sheet. That is highly theoretical because the price would increase a lot during that process. But if it didn't you would have a business paying a £5M dividend and a market cap of £1.69 LOL
(I hold BTW)
SCS (LON:SCS)
Not sure their suppliers would give them credit on the same terms if they didnt have the cash balances they have. Note having high trade payables has put a prior incarnation of exactly the same business into liquidation previously - that came around very quickly.
Note they only have just enough cash on hand to pay all the trade payables owed (within 12 months) - i have been generoud here and excluded lease liabilities !
So net the two off andthey have £1 mill net cash !!!!!
Possibly not a coincidence that Wiko are struggling - they didnt have enough cash resources to cover supplier amounts owed out per last acounts. so if they aint making money short term peeps owed funds will be panicking. I could say ditto for hmv and game group as to how shareholders were wiped out - hmrc were from memory paying divis very shortly before shareholders were wiped out. ditto for one of the airlines too.
I am not clear (perhaps I because i haven't read the announcement in detail) for SCS is (LON:SCS) why net profit margins are forecast to be so much lower on similar or higher sales to previous years for the next few years - i.e. less than half of previous net profits on similar revenue? Gross profit margins don't seem to be that adversely affected yet operating profit is down significantly. Economic climate so providing more incentives to keep same level of revenue? Sale of "stock" at marked down prices? Is there a chance they can return to previous margins - then it would be considerably better value.
SCS (LON:SCS)
I am not up enough with events to know - i guess if you read back through the last 3-4 sets of results they will explain away somewhere. Not every business includes all direct costs in direct costs - i know one listed company who touts the fact that royalties income has 100% profit margin then goes onto say that they now have extra specific staff purely to look after these licencees (ticker code includes an S a D and a G). Normal service was probably not at play over covid when every pronoun type possible plus all cats and dogs were clambering to get a new sofa - so if more disocunting + higher cost to get sofa to customer that would make sense to me.
Neither of these comments on SCS (LON:SCS) cash position are really valid. The reality is that net cash (or own funds) is around half the market cap. The remainder are customer funds. You can’t compare apples and oranges or pick and choose which bits of the balance sheet you want to see.
So you can’t really say the market cap is covered by cash because that cash couldn’t be used to pay shareholders. It is a super useful balance to have in a 5% interest rate environment though as should add considerably to profitability.
However, equally you can’t say the cash is all required for customer deliveries because that is equally untrue. The working cap model means timing on inventories/payments makes a big diff too.
In SCS (LON:SCS) case it works out about half the funds are the companies own.
SCS (LON:SCS)
Hi David
My own take of "company cash" was closer to £13m at the interims.
Excellent points on your perspective of how we should see the cash balance though.
No position - I'm too scared by the how the company collapsed a few years ago.
Cheers
UK homewares retailer Wilko has warned that it is on the brink of collapse because of mounting cost pressures.
It would be a shame to see them go. I always thought it was a good shop, with good prices. Commiserations to their staff. Will similar retailers be facing similar cost pressures, or will this be an opportunity for them? i.e. B&M European Value Retail SA (LON:BME)
It will indeed be a shame, I've been a customer for over 40 years since I worked in Nottingham where they started. They have expanded a lot since and a lot of competition such as Dunelm, B&M for the reducing town centre footfall as well as the likes of Tesco or Amazon wanting every pound you spend.
It's got a very similar profile to that of Woolworths. In the current economic climate customers are shopping around and using stores like home bargains and Poundland. Very sad to see another name possibly disappearing from the high street.
Crazy morning for Rolls-Royce Holdings (LON:RR.) (I hold). Not a small cap but a good example of how share prices can fake one way and then swing back. Clear breakout of the flag. Heading towards 200p IMO. Probably higher in the longer term. Glad to have a UK Engineering business reporting a positive outlook. Just need the gov't to stop pontificating over nuclear power.
Filtronic (LON:FTC)
Just noticed Chris Mills' Harwood Capital have taken a sizeable stake in this company. Does anyone have any further info on this?
Been on my watchlist for a while as the company would appear to operate in potentially growing markets and have recently brought in new management.
I seem to remember subscriber Ned Kelly having a look at this sometime ago?
Richard Staveley manager of Rockwood Strategic (LON:RKW) has recently taken a position. He gives an overview of the company and his investment thesis in the latest update from Rockwood Strategic (LON:RKW) last month. It is available on investors meet company. Link below.
Investor Meeting Rockwood Final Results and Calender H1 '23 update - Investor Meet Company
I don't hold Filtronic (LON:FTC) but do hold Galliford Try Holdings (LON:GFRD) M&C Saatchi (LON:SAA) and Pressure Technologies (LON:PRES) . All of which are held by Rockwood Strategic (LON:RKW) . I have also bought a holding in Rockwood Strategic (LON:RKW) for my wife's ISA.
Ok Jonno Thanks for that, I'll take a look
Mears (LON:MER) (I hold)
Very happy with the update today. I’ve been following this company for a long time – Bull/bear case based on my personal opinion.
Bear Case:
Bull Case :
I hold, so I’m obviously very biased. Happy to hear readers comments.
Is there any significance in a Pershing Securities subsidiary buying 8.5% stake in Instem (LON:INS) over the last few days?
I think the RNS is reporting a purchase where Pershing Nominees is the custodian and BGF are the beneficial owner, the only significance seems to be a greater than 3% holding.
Instem (LON:INS)
Pershing have not bought - they are the nominee. The beneficial owner is BGF Investment Management with the holding split between BGF Investments LP and BGF Smaller Companies Impact Fund Limited.
They have not bought the whole 8.5% in the last few days. They have held between 3 and 4% for some time, increased to 6.826% on 26/7, 7.416% on 28/7, and yesterday 8.534%. That is still more than doubled in 8 days - interesting.
Morgan Sindall (LON:MGNS) released results after the market closed last night. Their price has been strong recently borne out by results. 9% increase in dividend and strong growth in orders, revenue and profit. I am a happy holder. https://uk.advfn.com/stock-mar...
Hi Paul and tic_tac_toe
We’re in North Norfolk through the weekend (nr Aylsham) for a family wedding. Look out for us if you’re in the vicinity. Typical family of four, constantly squabbling, despite kids being nearer 30 than 20 years old.
SDG Sanderson Design
Headwinds maybe but down to 98p now so broken below the pound barrier .
No buyers coming in at all so seems to be heading further .
I’ve be nibbling over the past week or so.
Should do 13p EPS and has cash and lovely license income.
Might sit back a bit, a few tough days in the market and wonder if could hit mid 80s ?
I’ve an ok position now so now rush .
Sanderson Design (LON:SDG) also on my watchlist. Don’t feel like there is any hurry as you say. Will probably start picking up a position in the 80s if it gets there. Still feel another weak trading update might be on the horizon that could drive it down further but fundamentally I like the model and it should be reasonably resilient across different macro environments.
I’m also interested in Card Factory (LON:CARD) which seems to have better business momentum. unlikely I will take positions in both so need to think about relative value. Granted they are not comparable businesses but from a pure diversification perspective stray a little too far into the middle of my Venn diagram. Tho I could take a half and half position of course.
David
The 15 million cash cushion at Sanderson would swing it for me but it’s on a medium term hold basis
Sanderson is thinly traded with big spread and can swing very quickly , I think there is a major seller in the market probably Octopus and they are around 13% now so that’s going to keep it pinned down .
I had a small fill or kill order at 97.95 executed today and it’s heading up now - I can’t see it staying sub 1 pound that is just too cheap .
Short term if you are trading in and out card factory with its tighter spread and momentum the better bet.
I've also been nibbling away, at Sanderson Design (LON:SDG) a bit cautious of how low it might go. I think this company is really well set up for when market conditions improve.
Things I like:
Things I'm not so sure about:
So, overall, a bit mixed, but I think the things I'm not sure about can be handled if management are up to the task. So far I think Lisa Montague is - despite really tough conditions they are holding up well. This should be a company that does a lot better in a more benign market.
SDG
The Portmerion profits warning based on soft US sales could read across .
Bottom line is it’s a bit of a silly price .(like a lot of AIM shares at moment )
Would I buy a company
/with 15 million in the bank ,
making 12 million a year
with a design archive of William Morris etc and
great balance sheet for 70 million .
Yes
Yes good point re: Portmerion. I think this is where the 'brand moat' might come into play. You've got to trust that SDG's brands are strong enough for people to keep returning (or at least pick them over other brands.) I'm not fully convinced, but SDG's trading update suggested USA is trading positively and I get the sense that there's a big market for them to go for, and they've got the foundations in place to go for it.
These should be the toughest conditions for SDG. Fixed and variable costs at peak (i.e. labour, energy, raw materials) consumer demand weak/weakening - yet they're still holding up alright. Gives me some confidence in the medium to long term.
Didn't SDG say last year that next year (i.e. this year) energy costs would be an extra £10 million? Maybe that has changed now with the reduction in gas and electricity prices
I have utility costs increasing £1.7m to Jan 24. Covered when discussing slide 13 of their Jan 23 results.
They fixed electricity in Oct 22 (didn't say for how long) and their gas contract is up for renewal this October.
Sanderson Design (LON:SDG)
re inventory - i think we are still somewhat in uncertain times where its better having high rather than "not enough" - they don't have cashflow issues and presumably margins on best sellers are such that its highly unlikley they couldn't get their cash back if they had to or wanted to "get rid" of later. The bigger sin is not being able to supply customer demand when they want something pronto. On sales of £121 mill £28 mill of stock doesnt sound like any kind of issue. Note they had higher stock back in 2020 when sales were at lower level. I would worry more if business didnt seem in control of finances and had a reason for pimping stock - the fact they are streamling sku's suggest they are in control of stuff like that and that having extra stock just made sense.
Re Sanderson Design (LON:SDG) and its extra inventory in best sellers, IF they are buying bigger quantities of identified best sellers, they may well also have got better prices, leading to enhanced margins and/or making be stocking up on on best sellers for a big push in a new market based . With inflation high, both are good omens for the next 12 months and made possible by cash on hand
Such agility and smart thinking would be very much in line with what the CEO has done in terms of clever management of skus (£/sku has roughly doubled in a few years with Harlequin being the last to rebalance). Fixed price gas contract up for renewal in Oct so hopefully missed the big spike there and CAPEX spent on a new digital printer and energy saving/environmental equipment - helping with both brand and bottom line.
All in all, $SDG seems to to becoming a better company. The only 2 short term risks risks I see is half of the business coming from the UK but its end user market can probably still afford new wallpaper and fashion risk. Morris for instance is very distinctive which is great on the fashion upswing but bad news if it falls out of fashion. But with a good CEO pushing all the right buttons and targetting US and Japan, I am optimistic. I've bought little new for some time but Sanderson Design (LON:SDG) is tempting me.
Team17 (LON:TM17)
I have only really paid passinng interest to this company (i did love worms version 1 back in the day) they have always come across as a nice plodder but not cheap - having a quick glance today it does seem to tick all the boxes on an initial glance for someone having no sector exposure (hmmm i do have shares in corsair gaming is that same sector (gaming consumables)?) .
I have been wary about investing in companies that i have presumsed to have benefited really well from covid on the expectations there may be some reversion to the mean as life comes back to normal. Where we are now though and looking forward i think any tailwinds they had will likely have subsided by now.
On the face value stocky numbers pe of 11 seems to suggest this share may rarely have been cheaper ?
I know nowt about its products buch mention of Barbie and Lego seems good - in some respects i get the feeling that Team17 are a more reliable company than frontier who probably needed one big release each year to hit targets and have striggled when they have struggled to deliver to plan. So somewhat behind the scenes tickover lower risk stuff is fine by me.
Balance sheet at 31/12/2022 seems fine with excess of cash and debtors over what they owe out (includes £50 mill of cash which is best sort of asset)
So that just leaves me with the a couple niggles
the ever increasing intangibles - its hard to know a buisness is making real money when all the money you have made on paper goes into intangibles (and some!)- intangibles at 1/1/2021 where £65 mill and at 31/12/2022 were £234 mill - with more acquisition this year. so rather strangely this appears to be a very capital intensive business. Profits are showing step change though in 2023 and 2024 compared to the past - for investment of £170 mill one would hope tahts returning £20 mill extra profits per year - reality is profits (2023 est) are up £20 mill based compared to 2019 but not compared to 2020 (covid boost perhaps that year?) - ok looks like they spent £83 on acquisition in early 2022 - so you aint gonna earn that money back anytime soon - so overall despite my worries here not anything to be too concerned about.
I know nowt about this sector/specifics of this company - do i need to if they are dependable plodder and on track ? - interested on thoughts of others.
Morning all,
Mears (LON:MER) interims look good, looks like a beat against stocko forecasts for full year. PBT of at least 40M, earnings look like coming in at 26/27p. Looks decent!
Don't hold but thinking about a purchase...
Any negatives please feel free to discuss?
I own. I was surprised not to see a significant leap this morning. I've read the report and cannot see why the market has stalled on this now. Clear statement from management (imo) and they seem to be improving customer satisfaction, (although I don't think 90% satisfaction sounds overly ambitious.) More long term contracts coming on board too, so I'm surprised that the price has not increased. Any ideas?
Good morning JD,
I have looked at Mears (LON:MER) recently and agree that this mornings numbers are an increase on forecasts, my view ( only because you asked for negatives) and apologies to holders, is why buy this now after a near 30% SP rise, it is a very low margin business and probably not that cheap now. There is much better value in so many UK stocks right now, the trouble is they may get even better value before they start going up.
Hello Helvellyn,
PE of 10 for this year, could do say 30p next year?
PE of 10-12 for a low margin business, share price of 330-360p. Decent upside, plus nice divi.
Thanks Helvellyn... that makes perfect sense.
MER
I think Ed Croft picked this one up for one of his portfolios.
Three companies reporting the morning, from the 30 company portfolio, 28 of which are small caps. My initial thoughts on skim reading the narratives, with the caveat that I need to get to digest the details:
TT electronics (LON:TTG) impressive interims, all metrics moving in a positive direction. Confident outlook statement. Really pleased to see leverage falling to 1.8 and cash conversion increasing significantly. There are still a number of adjustments, but statutory and adjusted metrics are starting to converge. The company's expertise is in the area of electrification is in demand and it strikes that TT electronics (LON:TTG) has reached an inflexion point with the heavy lifting of restructuring complete. Like many small caps it is cheap at present and looks great value. My several buys have been made around the current price.
Belvoir (LON:BLV) really positive update from Dorian Gonsalves who I have met om several occasions. Lettings and to a lesser extent financial services are off setting the expected and much publicised fall of in house sales. I have a lot of time for the management team of Dorian and CFO, Louise George who come across as straightforward hands on individuals who treat retail investors with fairness.
Facilities by ADF (LON:ADF) I haven't looked at the forecasts for the half year so not sure how they compare with those reported, revenue of £21.8m and EBITDA of £5.8m. It would have been naïve to think that the company would be unaffected by the writers/actors strike, which will end at some point. When it does there will be a pent-up demand as mentioned in the trading update. Facilities by ADF (LON:ADF) is the dominant player in the UK, it has sound finances and the strike is transient. I intend to sit on my hands.
Let's see how bi-polar Mr Market reacts.
All the Best
Echo your point on Belvoir's (LON:BLV) management. It's a big lesson I have coming out of this bear market - the importance of having clear-talking, honest management who proactively engages with retail investors. I've also come to really value clean, easy-to-read accounts with few adjustments.
Rosey-sounding updates combined with broker downgrades have been a recurring theme. It leaves such a sour taste in the mouth and reflects poorly on the character of the management / how they consider their retail shareholders.
These Stocko reports have been a big help in identifying the wheat from the chaff (thank you Paul, Graham, Roland!)
It was nice to bump into you Paul. We spent the remainder of the afternoon catching shore crabs on Blakeney harbour. Today we head home.
yes your mum seemed astonished and proud that her son was recognised in public! I hope you enjoy the rest of your trip.
A very succinct in-line trading update from Team17 (LON:TM17) today which feels particularly impressive given its peers Devolver Digital (LON:DEVO) and tinyBuild (LON:TBLD) have both issued profit warnings along with the wider slowdown in the videogame market.
It suggests to me that TM17 has got something right. They've got a good mix in their business - the straight-up indie game developer/publisher, the 'educational apps for children' (StoryToys) which partners with the big brands, and the more niche 'working simulator games' (e.g. Construction, Train, Bus simulator.) I think this mix makes them a bit more resilient as they're not reliant on just the indie game market.
They've also published a couple of standout games this year (Trepang2 and the more notable title Dredge - the latter being a very clever, unique finishing game where you go out in a boat to fish for all sorts of treasures amongst monsters creeping beneath the surface.) I've also got my eye on a soon-to-release and unique-looking survival game, Gord, (plus a few others in the pipeline.)
On the more negative side of things, their acquisition of Hell Let Loose (a multipayer WW2 game) got off to a terrible start. They released a couple of updates that annoyed the player base by making it easier to play and less strategic (by e.g. increasing the running speed of players.) They then released a howler of a trailer which resulted in people 'review bombing' the game on Steam and a 20% drop in the player base (at least according to SteamDB.) Naturally, TM17 have come out licking their wounds and saying they'll listen and work in tandem with players to improve the game overall and double down on what makes it unique. So they're not perfect - they tried to be a little greedy and make it appeal to a wider market. Will be interesting how it plays out from here.
Team (LON:TEAM)
It suggests to me that TM17 has got something right.
I think the secret here is to not over promise - with all the development spend and acquisitions going on thats particularly important to me as a potential shareholder.
It always seems that some companies tend to be reliable others not so much so having constant tickover of "issues beyond their control" (Frontier comes to mind) . I have been on sidelines here (barely paying attention) but inline update today bearing in current tougher conditions and low shareprice does seem like exactly the kind of news i want to hear to be potentially be comfortable investing here.
Mention of Dredge reminds me of Scuba Dive on the Spectrum backm in the day - that was a top banana game (that big octopus)
Number of ‘Isa millionaires’ surges to more than 4,000
Own up, who has got the £8.5 million?
I thought this was interesting for a few reasons. The lifetime contribution is about £340k, so this show impressive returns are possible, even to be north of 1 million, which is inspiring if one is just getting started. In a similar vein it disputes the narrative that one can’t beat the market, it can be done.
And lastly, I wonder what the future of ISAs are? It’s such a generous scheme for investors it almost seems too good to last. It is all guesswork but will the contributions just never get raised, a lifetime cap, some kind of withdrawal penalty over a certain amount? Of course as we never know I guess it doesn’t really matter.
It's August; it's the 'silly season' for news. It's a report on one extreme end of the bell curve distribution. Pretty meaningless without knowing the full distribution and contributions of all individual ISA holders.
My morning smallcap tweet: Sticking to my knitting or sewing confusion?
Streaksai (LON:STK) Devolver Digital (LON:DEVO) LifeSafe Holdings (LON:LIFS) Ediston Property Investment (LON:EPIC) Maintel Holdings (LON:MAI) Facilities by ADF (LON:ADF) CMO (LON:CMO) Polarean Imaging (LON:POLX), Creo Medical (LON:CREO), Belvoir (LON:BLV), SCS (LON:SCS), Xaar (LON:XAR)
◄Streaks AI (STK)► partnership with WeShop to "providing shoppers with enhanced and personalised customer services using AI-powered chatbots modeled after the platform's 1,300 influencers". Sounds ghastly.` [SP=2.83 Cap=11m]
◄Devolver Digital (DEVO)► warns H1-June adj EBITDA negative and FY adj EBITDA at least zero. Blames delays to new title releases, a reduction in revenue from subscription deals and a lower contribution from our back-catalogue. [SP=18.5 Cap=83m]
◄LifeSafe Holdings (LIFS)► £1.1m placing and subscription at 37p, a 9% discount, "to procure stock and general working capital purposes" ie keep the lights on. [SP=41.25 Cap=9m]
◄Ediston Property Investment Company (EPIC)► in advanced discussions on a possible sale of its property portfolio. [SP=63.2 Cap=134m]
◄Maintel (MAI)► guides FY-Dec rev in line and adj EBITDA ahead of market expectations. Cites "positive trading conditions, winning new business and the acceleration of the order book un-winding post the well-documented challenges of global supply chain shortages". [SP=180 Cap=26m]
◄Facilities by ADF (ADF)► guides H1-June rev £21.8m and adjusted EBITDA £5.8m. "As the [writers' and actors'] strikes have drawn on, several film and TV productions in the UK, on which ADF is currently engaged, have seen stoppages or delays to productions that were scheduled to start filming in autumn...Any alleviation of the prevailing strike action will provide the potential for further upside in the current financial year." Is that a warning? [SP=44.8 Cap=36m]
◄CMO (CMO)► warns FY-Dec rev only c.£80m but EBITDA in line. H1 rev LFL down 12%. Lower down it says FY will be in line! [SP=22 Cap=16m]
◄Polarean Imaging (POLX)► squeezes out another RNS. FDA approves XENOVIEW 3.0T Chest Coil for use with Philips 3.0T MRI scanners [SP=15.25 Cap=33m]. I hold.
In line: CREO, BLV, SCS, XAR
Your Blakeney 'brief encounter' raised a smile.
I met a chap while holidaying in the Caribbean who'd apparently once shared a cab with you, and found you gracious and very genial. Always nice to know
The rest of us have to wait nearly a year to meet Paul at the next Mello!
Well hopefully not a whole year as the next physical Mello will be in late November so only just over three months to go. Companies are signing up already so confidence out there is growing. We have five virtual shows in September and they are nearly all fully booked.
Do we have a date for physical Mello in November?
29th and 30th November.....All dates here https://melloevents.com/upcomi...
Were you not asked for your autograph Paul?
Let's not get too carried away!!!
Wouldn't it be a selfie nowadays