Small Cap Value Report (Thu 3 June 2021) - FOXT, MBH, NRR

Good morning, it's Paul here with the SCVR for Thursday.
Apologies for the self-promotion, but here's my latest chat with Tamzin at PIWorld, which was great fun! I've asked that the next interview be me interviewing Tamzin, to mix things up a bit!
.
Timing - should be finished by about 1pm today.
Agenda - all written by Paul today, as it's quiet for news, and Jack has other stuff to do -
Foxtons (LON:FOXT) - trading update - ahead of 2019 & 2020, but doesn't tell us if ahead of expectations or not. Holding an online Capital Markets Day (CMD) today from 14:00-16:00, not clear if private investors can attend or not, I'm trying to find out. Overall I'm neutral, as it looks expensive on current broker forecasts (but maybe those will rise in future?)
Michelmersh Brick Holdings (LON:MBH) a positive trading update, but only in line. Is it limbering up to a forecast raise later this year, perhaps? This share looks quite good - decent quality scores, and seemingly positive market conditions in its sector - rising selling prices could trigger an operationally geared rise in profits?
Newriver Reit (LON:NRR) - a quick look at this interesting value retail property REIT. Resilient performance, but maybe fairly priced now, after doubling in the last 6 months?
Foxtons (LON:FOXT)
61p (pre market open) - mkt cap £199m
Trading Update (& Capital Markets Day)
Foxtons Group plc (LSE: FOXT), London's leading estate agency, will today hold a virtual Capital Markets Day for institutional investors and analysts.
This event is from 14:00 to 16:00 today. Why aren’t private investors also invited? These events should be open to all investors, not just institutions. We often ask better questions than the institutions, I’m told, by many companies that I do speak to.
Let’s hope Foxtons at least publishes the slide deck of the CMD on its investor relations website, or better still publishes a video of the CMD. Everyone should have access to the same information, anything less is unacceptable.
I’ve emailed investor relations to confirm if PIs can, or cannot attend the online CMD today, will report back here if I get any response.
UPDATE at 08:41 - I take it all back! Just had a reply from IR at Foxtons saying;
Yes of course, all investors are welcome to join the capital markets day.
Users need to follow this link, which was also included in the RNS, in order to register and be allowed access to the presentation: https://www.foxtonsgroup.co.uk/investors/capital-markets/
So there we go - if you're interested, sign up for it! End of edit.
Current trading -
Since the Group's Trading Update on 14 April 2021, trading momentum within the business has continued to be strong. Following a 49% increase in Foxtons Q1 sales revenue versus both 2020 and 2019, the sales commission pipeline has continued to grow and is now 65% ahead of last year and 17% up on 1 January 20211.
As a result of the strong trading momentum, adjusted operating profit for the first half of the year is expected to be significantly ahead of both 2020 and 2019.
The footnote says that a large acquisition (of Douglas & Gordon estate agents) has been excluded from these figures, to make them like-for-like comparable.
My opinion - this is not satisfactory as an update. It only mentioned part of the business - residential sales. What about the important lettings business?
Also, the whole point of trading updates is to tell us how businesses are performing versus market expectations (i.e. broker consensus earnings forecasts). Foxtons doesn’t tell us that today, it just gives a fairly meaningless comparison against 2019 & 2020. It was loss-making in 2018, 2019, and 2020, and existing consensus shows a bounce back into profitability in 2021, hence the update today doesn’t tell us anything has changed in that regard - an increase in profits vs 2019 & 2020 was already expected.
I expect they’ll go into more detail at the Capital Markets Day, which you can sign up for here.
Foxtons did very well in the London property boom a few years ago, but as you can see from the Stockopedia graphs below, profitability collapsed long before covid struck. Forecasts show modest profitability this year (the lighter blue blobs below), but at a level which makes the shares look expensive (FY12/2021 forecast PER 53.1, falling to 29.8 in FY 12/2022).
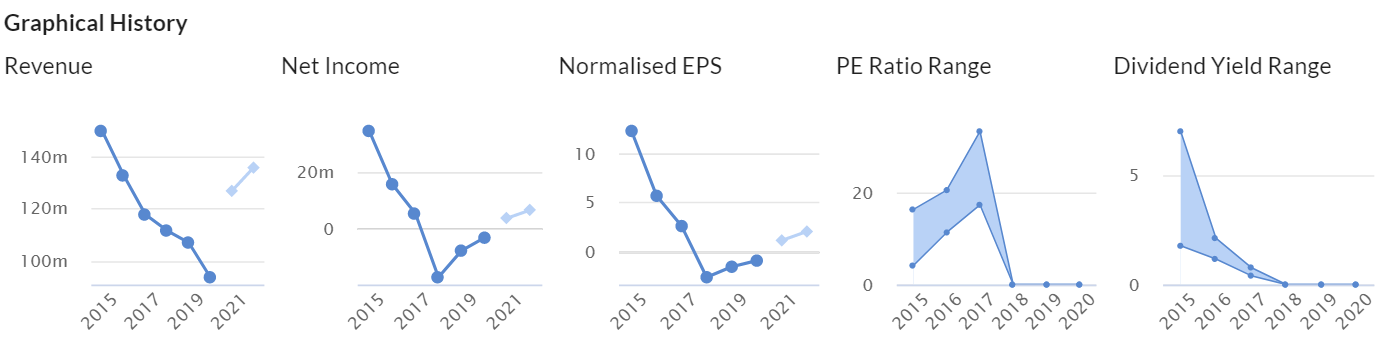
Therefore the investment case for Foxtons currently, is good if you think it’s likely to smash forecasts. Many broker forecasts are way too low at the moment, so that’s a distinct possibility. However, I’m looking for companies to be issuing “ahead of expectations”, or “substantially ahead of expectations” updates, along with big increases in broker forecasts.
We’ve not seen that from Foxtons today.
There don’t seem to be any brokers publishing FOXT research on Research Tree, so we’re in the dark.
Yes, the sales pipeline is good, partly helped by Govt schemes to boost housing transactions (e.g. Stamp Duty reductions), but what about the rest of the business, and what happens when Govt support schemes end?
I’m told by a sector expert that an influx of affluent people from Hong Kong to London is expected in the coming years, which could give a nice boost to London. Plus of course, London is already coming alive again, as many people are now returning to offices, and general activity is on the up. I would never bet against London recovering from the pandemic, it’s far too important as a business, and social/cultural/holiday hub.
As you can see below, broker forecasts have been rising, so it’s worth keeping an eye on this graph, to see if it updates again in the coming days, when brokers have attended the capital markets day, and been given more colour on how the business is performing.

.
I don’t currently hold FOXT, as I decided it looked fully valued some time ago, after a strong rise.
However, I’m perfectly receptive to the idea of buying back in at some stage, if the valuation becomes attractive again. The balance sheet is strong, it seems to have made some good acquisitions recently, and recovery in London could see forecasts continue to rise - hence it might grow into the valuation. Note that the share count did rise, as it raised cash from shareholders during the pandemic, hence be aware of dilution.
Overall then, I’m neutral, but keeping an eye on it.
.

.
Michelmersh Brick Holdings (LON:MBH)
147.5p (up 1.4% at 09:53) - mkt cap £139m
Trading Update (AGM Statement)
Michelmersh Brick Holdings PLC (AIM: MBH), the specialist brick manufacturer…
The current financial year is 12/2021.
Today’s update says -
"Since returning to full production capacity at all of our sites during the summer of 2020, the Group has experienced strong demand from its customers, with the construction market remaining very active.
During 2021 to date, the Group's performance has continued to be robust and production volumes have been ahead of expectations.
"Acknowledging this encouraging performance to date in 2021, and the Group's strong and balanced order book, the Board is confident that the Group is firmly on track to meet full year expectations.
Putting together strong demand, production ahead of expectations, and press reports of rising brick prices, I’m surprised this update today is not ahead of expectations.
Reading between the lines, it sounds as if an upgrade in expectations could be in the pipeline for later this year?
I can’t find any broker research.
Valuation - looking at the usual Stockopedia graphics below, the quality scores are good, although the valuation scores are nearly all middling, suggesting that the current share price could be about right?

.
Upside could come from forecast upgrades, which sound fairly likely.
My opinion - this looks quite good.
I suppose the key question is whether rising prices of bricks is a short term supply squeeze, or a more permanent thing? Also I don’t know to what extent MBH’s input costs are also rising, and how readily it can pass on price rises to customers? I.e. are there long-term contracts, are prices flexible, etc.?
Overall, it looks worthy of a closer look.
Brick distributor Brickability (LON:BRCK) has done very well too, and insiders at BRCK banked some profits in a recent secondary placing - suggesting that maybe the upside there is already priced-in?
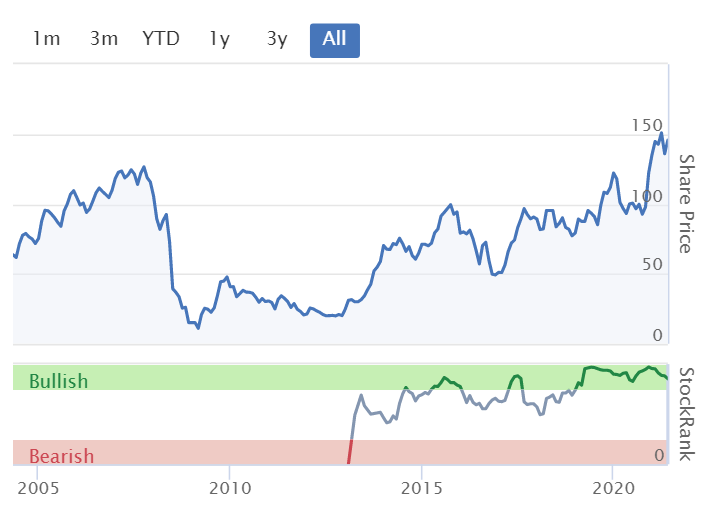
Looking at the long-term chart for MBH, shareholders had to endure a 5-year sideways move before the recent surge.
.
.
Newriver Reit (LON:NRR)
100p (down 5% at 10:48) - mkt cap £306m
We don’t normally cover property REITs here at the SCVR, because it’s a specialist area, and they take too long to analyse. However, NRR is an interesting one that we have covered for years. It specialises in sub-prime retail property, and pubs, often with development potential.
Whereas larger REITs have been under enormous pressure, eg INTU went bust - so did (different sector) ENTU actually. So if you spot companies called ANTU, ONTO, or UNTO, we should probably steer well clear!
Preliminary unaudited results for the year ended 31 March 2021
Follow this link to see the company results presentation pdf slides (the video isn’t working at the time of writing)
Resilient performance
Reinstating divis - 3p per share
Market-leading rent collection
Unsecured balance sheet
Disposing of Hawthorn pub business
Like-for-like (LFL) valuation decline -8.2% in H1, -5.6% in H2 (13.6% for FY 03/2021) - nowhere near as bad as many other retail properties - so the focus on value retailers on modest rents, has paid off
EPRA NAV per share down 24.9% to 151p - well above current share price of 100p, but that’s a steep decline in NAV, not helped by the effect of gearing. Once you factor in another possible drop in NAV in 2021, then the discount to NAV might not be that much
Bank refinancing not due until Aug 2023
Net debt £493.3m - still looks quite a lot, but I think that will come down when Hawthorn disposal goes through
My opinion - I’ve seen enough to get the gist of things. NRR has done really well during a brutal period, and crucially has not had to dilute shareholders.
Will EPRA NAV go up or down from here? I imagine in the shorter term a further decline could be on the cards. Hence that limits the likely upside on the share price to a level where I wouldn’t be interested.
The rise from 50p to 100p looks fully justified. At this stage, I’m not convinced that a rise from 100p to 150p would be easy, or come any time soon, hence I’ll pass on this one at the current price.
.

.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
hi Paul
Hope you're well and thanks for continued coverage as always.
Newriver Reit (LON:NRR) couple of things worth mentioning (I hold having bought around 65p).
1) The price falls that led to the NAV decline are mentioned in the outlook as having resumed growth since y/e, so whilst you might be correct that NAV could fall further that suggests to me it is actually going back up again or maybe flat.
2) Dividends are expected to rise to 9.8p this year and 12p year after. Thus doesn't look like a bad income share to me on 10-12% yield.
The uncertainty is the potential sale of the pub business Hawthorn. That will change the dynamics considerably. I'm still slightly bemused as to why they've changed tack on it having spent a lot of time telling investors how good a potential business it is.....hmm. I'd like more colour on that
cheers
David
I suspect they have to sell the pubs to get LTV down - currently around 50% which is too high. If they can sell the pubs at book value that will get LTV down to around 33%.
Interestingly around 20% of portfolio consists of assets earmarked for regeneration (eg converting to residential) and they think the alternative use value for these assets is around 50% higher than book value. If you add the regeneration assets to the pubs (25% of portfolio) and retail parks (16%), then around 60% of portfolio is in reasonably attractive assets. The question is how much of a discount do you apply to the c40% in traditional shopping centres?
On Michelmersh Brick Holdings (LON:MBH) it is not just the direct impacts of inflation and rising input costs and shortage.
But also if construction as a whole starts to slow down due to the shortage of other parts. Presumably to build a building you need to have all the materials (bricks, cement, mortar, timber, copper pipes, etc) all ready and delivered. Otherwise it is inefficient to stop-start a project continuously?
Building works these days are done very much in the same Toyota "just in time" production, where supplies are timed to arrived as they need. If you mess up the delivery schedule, then works slow down.
If works slow down, then brick demand is lower given a certain time period. Of course, over time those delayed orders are fulfilled - don't think projects are being cancelled. But there's a risk of missing earnings for the upcoming half year, and full year, that will be deferred to future years.
I watched this PI World video, and thank you Paul for your input. A question I would have asked just to sum up, were I Tamzin would be to ask if the companies spoken about are on a crest that makes additional investment unworthy of the PI's interest. I feel that there are many up-and-coming prospects out there that a little bit of research could find.
Silver Moon
Well I research 500-600 companies on a daily basis, so by all means share your ideas here if you think there are better ones out there. I'd love to hear about them, if I've missed them.
You asked:
A question I would have asked just to sum up, were I Tamzin would be to ask if the companies spoken about are on a crest that makes additional investment unworthy of the PI's interest.
Fairly obviously, I wouldn't have mentioned any of the stocks if I thought that was the case!
P.
eg INTU went bust - so did (different sector) ENTU actually. So if you spot companies called ANTU, ONTO, or UNTO, we should probably steer well clear!
Love it! Classic Paul comment and a major part of the reason we all come here.
In case people are interested Lord Lee has a column published today in the FT;
https://www.ft.com/content/059...
He has had some excellent returns and invests in some great companies such as Treatt (LON:TET) which I think I need to get back into at some point.
Some of the comments are extraordinary (such as pass me the sick bucket) when you consider he is one of the most successful PI’s of our time.
Hi Paul,
I have been a Stockopedia subscriber for a couple of months now and this is my first post. The various blog articles were not my main reason for subscribing at all but I have found them very useful.
In particular I am reading your report most days (too much for me sometimes when I'm at work!) and learning much. It was very interesting to see you on PI World which has reinforced my confidence in your research, it is always nice to put a face to a name.
Thank you for your continued efforts and now off to research RBG and SOS which caught my attention today!
Feels like the turnaround at Braemar Shipping Services (LON:BMS) is starting to show results. Debt coming down, order book up, dividend resumed. Finncap note this morning puts them on 24.1p adjusted EPS for current financial year and 26.7p EPS for 2023. Share trades at c.250p this morning. This is a sector I don't know much about but I bought much lower when the value opportunity looked good. If you get time Paul I'd welcome your thoughts but totally understand if it's a sector you're not very familiar with either!
Braemar Shipping Services (LON:BMS) looks like the famous 'cup and handle', well at least cup and jaggy bit. Star Bulk Carriers in US was good but whole US exposure in the dumps at present. Don't know about V shaped recoveries more realignment to sensible values.
Many thanks Paul for another great interview! What a whistle-stop tour. Always great fun talking with you and getting your update on so many companies.
Separately, I see Michelmersh Brick Holdings (LON:MBH) gave an AGM statement today. Production volumes ahead of expectations and the board are confident of meeting FY expectations. PIWORLD are hosting a management presentation on 18th June at 10am, register here for this and a number of other events including the Stockopedia/PIWORLD June StockSlam.
Just to say Tamzin I really like the PIWorld interviews - they are great and also really appreciate the stockslam recordings. I listen to the podcasts while out for a run so the option of choosing either an audio and video format is very handy.
Thank you both. very valuable . Looking forward to the role reversal interview :p
Does anyone here know when the Ekf Diagnostics Holdings (LON:EKF) restricted offer shares from the Trellus Health (LON:TRLS) IPO should appear in portfolios? Is the Stockopedia StockReport for Trellus Health (LON:TRLS) correct that TRELLUS shares cannot be held in an ISA?
They appeared in my II account yesterday together with refund as was heavily oversubscribed. Not sure re ISA. Fine in my SIPP
Hello - they showed up in my HL account yesterday I think. This is definitely within an ISA, so no restrictions that I am aware of there.
HI, I have them in my II ISA. The ones that came earlier as an in specie dividend from EKF won't be active for a while yet as they are subject to a lock-in.
My Trellus Health (LON:TRLS) are within an ISA, so Stockopedia is not correct. I have found it to be fairly unreliable for this info. but may depend which platform you are using.
Thankyou Paul. I echo Tamsins words "it is really appreciated".
Hi Paul - will you be covering Newriver Reit (LON:NRR) results this morning?
Hi josh,
Yes I'll look at Newriver Reit (LON:NRR) next.
Regards, Paul.
Thank you! :)
Good update this morning from Jubilee Metals (LON:JLP) regarding a further securing of PGM feed-source for the next 10yrs. SP has stalled recently and I notice the Stockopedia ranking dropping off, but along with Sylvania Platinum (LON:SLP) and Tharisa (LON:THS) these seem to be really strong opportunities for the continued growth in PGM's and their related SP's.
Obviously some concerns around the risks of their longevity, PGM prices in the long-term and local risks around taxation and power, but I still see plenty of room for continued SP growth over the next couple of years.
I believe Jubilee Metals (LON:JLP) has also attracted attention from some II's which should help strengthen the SP. I hold both Sylvania Platinum (LON:SLP) and Jubilee Metals (LON:JLP)
I also liked this statement in the Jubilee Metals (LON:JLP) RNS:
"The PGM Supply Agreements are all based on the LG6 chrome reef known for its high Rhodium content accounting for approximately 12 % of a produced PGM ounce compared with as low as 7 % of other chrome reefs."
Regarding KevinS1 comment that Jubilee Metals (LON:JLP) attracting II attention, I see that it is the largest holding in Gervais Williams' Premier Miton UK Smaller Comps fund.
Hi Kevin,
Interesting news from Jubilee Metals (LON:JLP) .
I reasonably convinced the high Rh price is set to stay at least for a few years. I did some comparative analysis between Jubilee Metals (LON:JLP) Sylvania Platinum (LON:SLP) and Tharisa (LON:THS) which may be of interest.
https://www.stockopedia.com/co...
As always DYOR and don't trust third parties including mine.
BSV
Thanks BSV - very interesting and worth looking at further. I have juggled between the three of them in the past and could probably do with spending a few hours going over the numbers again.
Travis Perkins recently mentioned 10 to 15% increase in construction material costs. I know from experience cement is hard to get hold of in UK. Do you think that will affect Somero at any level??
Hi Camtab,
I've been keeping an ear open for information relating to construction materials for a while now. I was listening to a podcast from USA about 6months ago where the speaker went on a bit of a tangent about how he couldnt lock down any prices for materials on a significant sized building project - the primary driver being a the shutdown of factories in China due to covid.
Lumber and steel prices are through the roof while things like glue just haven't been produced at a rate to meet the normal demand, let alone the increased demand.
Im not familiar with Somero as a business, but if its in that realm, i'd expect some sort of impact. a lot of builders are only taking contracts on work-only fee basis, and you're expected to source the materials yourself. this cover's the builder's back on the volatile prices. i suspect suppliers of construction materials will make a killing as they ramp up production.
However, i've not looked further in to this - just find it interesting so thought id share my thoughts.
FWIW
I occasionally drive past Shoreham Port , there is a yard there that accepts cargoes of Timber, I was there yesterday and have never seen it so full of the stuff. It was everywhere.
Very anecdotal I know , but. . . . .
Richard
Materials costs are rising in the building industry, particularly insulation. Lots of roof tiles I think come from France for their unusual styles (so Housebuilders can make them look more unique/bespoke) but if supply constraints due to politics (or France being er France) gets in the way of supply/demand then maybe a fillip for our homegrown like Michelmersh Brick Holdings (LON:MBH) who produce more bespoke stuff. Need to study who else out there as most materials I think are EU based. Concrete mentioned somewhere - but this is surely Portland a part of the UK? Sigmaroc (LON:SRC) gets mentioned regularly so will have a look.
Mr Thompson likes Sigmaroc (LON:SRC) - wondered where I'd heard of it. 100p resistance methinks.
Somero Enterprises Inc (LON:SOM) - the SP has 'levelled' out which means could be a long wait. Pun intended. Specialist subcontractors are expensive and not the type of thing used by housebuilders (I guess) so pumped on warehouse demand which need billiard table floors and quick build time. Expensive to get a good level floor which will last and not need downtime in remediation/repairs esp if using robots - so has a moat - maybe for the ISA/SIPP.
Paul given you encourage people to do their own research and you are not stock adviser don't apologise that you should have seen RBG coming. Maybe you should maybe not but your followers have as much liability for that error. Holder.
Thanks Camtab.
I think it's the timing of the Revolution Bars (LON:RBG) (I hold) placing that took me most by surprise. They were raving about pent-up demand one minute, then diluting shareholders the next.
If mgt had big personal holdings, I think they would have hung on, and done a smaller, less dilutive placing once business was booming in say June or July.
Regards, Paul.
Hi Camtab, I echo your opinion on RGB (I hold). It is probably best to wait it out until the bars are fully open. To sell now would involve considerable losses and unless things get worse, I can see their recovering somewhat from recent lows. However, I could be wrong. Have a nice day.
Revs has always been a student favorite . this past Saturday a group of us tried to get a walk-in spot at the bar and the bouncer said they were fully booked right through the day and night and have had no cancellations for that day. that bodes well for a recovery.
The bouncer did let me nip in to use the toilet, so i am very grateful and wish them the best of luck (i hold no position).
Results from Discoverie (LON:DSCV) this morning. Moved back to organic growth at end of period and now record order book.
(Just realised strong share price movement this year is moving it above the 'Small cap' category).
Full marks for allowing PIs in:
A virtual results briefing for analysts and investors will be held today at 9.30am (UK time) via a live webinar.
If you would like to join the webinar, please contact Buchanan at discoverIE@buchanan.uk.com
Good morning. Paul,
Sometime ago you commented on CYAN.L . Any view on this mornings rights issue,,,at a premium! please?
Morning Trevor,
Sorry, Cyanconnode Holdings (LON:CYAN) doesn't interest me, as it's had too many false dawns in the past, is always talking about huge order pipeline, etc, then every time they publish results, it's tiny revenues & big losses. That's been going on for so many years, that I'm amazed people continue to give it the benefit of the doubt.
This latest placing is only £3.15m, so getting that away at a slight premium isn't massively significant in my view.
Regards, Paul.
Paul,
Very many thanks for your views and wisdom, always much appreciated.
I was quite interested in Cyanconnode Holdings (LON:CYAN) a few years ago - seem to recall that, in addition to Paul's comments, one thing that put me off was management remuneration. It may have changed, or my memory may be playing tricks.....
My morning smallcap tweet:
Advanced Oncotherapy (LON:AVO) RA International (LON:RAI) Cyanconnode Holdings (LON:CYAN) Foxtons (LON:FOXT) SThree (LON:STEM) Michelmersh Brick Holdings (LON:MBH) Amryt Pharma Holdings (LON:AMYT) Braemar Shipping Services (LON:BMS), Zambeef Products (LON:ZAM), Pebble (LON:PEBB)
Advanced Oncotherapy (AVO) Letter of Intent for the proposed purchase of a three-treatment room LIGHT system worth up to US$107m. Parties aim for contract by March and is subject to LIGHT system getting CE mark. [SP=33.3 Cap=116m]
RA International (RAI) wins 2 year contract (with poss 2 year extention) worth c.$5m PA from US Agency for International Development. [SP=48.5 Cap=84m]
CyanConnode (CYAN) £3.15m placing at 9.5p, a 2% premium, to keep the lights on. [SP=9.45 Cap=18m]
Foxtons (FOXT) guides H1 adj op profit significantly ahead of both 2020 and 2019. In line? [SP=61.1 Cap=199m]
SThree (STEM) guides FY(Nov) pretax materially above market consensus of £39.7m. "High levels of demand in Life Sciences and Technology have been seen throughout the quarter and there have been continued strong performances from the US, German and Dutch businesses." [SP=424 Cap=566m]
Michelmersh Brick (MBH) production volumes have been ahead of expectations but still guides FY in line. [SP=146.94 Cap=138m]
Amryt Pharma (AMYT) FDA grants Priority Review for Oleogel-S10 for the treatment of Epidermolysis Bullosa. This cuts 4 months off review time. [SP=168.25 Cap=303m]
Braemar Shipping (BMS) FY(Feb) ahead of market exp with rev down 5% and pretax-cont £9.5m (£6.3m), reflecting the profit on the sale of shares held in AqualisBraemar of £2.2m. [SP=244.4 Cap=78m]
In line: Zambeef Products (LON:ZAM) Pebble (LON:PEBB)
New Capital Employed Podcast episode just published featuring Richard de Lisle discussing opportunities in American small caps with two of his favorite stocks.
Available to listen here... https://podcasts.google.com/fe...