Small Cap Value Report (Thu 3 Nov 2022) - CER, HWDN, SBRY, IGR, BT., TIFS, UPGS, KITW, GATC

Good morning from Paul & Graham! Today's report is now finished.
Podcasts - I've managed to iron out the problem with my podcasts not working on Google Podcast service. That's now fixed, and they download automatically now. I had to install an SSL certificate. Amazingly, even though I have no idea what an SSL is, I managed to somehow install one last night!
Agenda
Paul's Section:
Cerillion (LON:CER) [no section below] - another interesting CEO interview, which I recorded yesterday afternoon. The audio is here, and on podcast. I tried to get to the bottom of why the company's performance (revenues & profits) have exploded upwards in the last couple of years, with some key factors emerging. Just for Stockopedia subscribers (please don't copy it elsewhere!) I've also typed up the interview in a separate post here. I think it's fair to say that CER shares are not a bargain, on a forward PER of 32, but I think that valuation can be justified, given the outstanding profit growth, and a big market opportunity to continue growing. So it's a gone on my watchlist of things to buy on the next market downturn.
Mid caps that I happened to look at briefly this morning, so might as well comment here. Both seem to be trading well, so what about this recession that’s supposed to be starting? No sign of it so far, with either of these 2 companies. Maybe consumers are cutting back in some areas, but not others? Or is the impact of a slowdown yet to be felt? Who knows.
Howden Joinery (LON:HWDN) - trading well, and expects PBT this year to be “marginally ahead” of broker consensus.
J Sainsbury (LON:SBRY) - also says current trading is good, and leaves profit guidance for this year unchanged.
BT (LON:BT.A) Interim results - I had a very quick skim, a few key points - valuation now looking interesting, with the PER and divi yield both around 6. Lots of gross debt, so need to check interest charges (how much is fixed or variable?) Divi yield is slightly higher than the 2028 bond yield (with a running yield of 5.7%). Trend (long-term) is revenues falling. Heavy capex. Cost-cutting to maintain margins. Note pension deficit has gone up - blaming rising gilt yields (presumably that means the fall in asset values has more than offset technically reduced liabilities?) - this makes me continue to be wary of pension schemes. Selling prices are index linked mainly, so probably has good inflation protection, but does mention higher cost inflation than expected. [no section below]
UP Global Sourcing Holdings (LON:UPGS) - I review the FY 7/2022 results, which are as expected from the August trading update. The figures look clean to me, and the shares seem reasonably priced. Maybe the divis are a bit too generous, although twice covered by earnings, they're not covered by cashflow this year, because a lot has been sucked into increased working capital, and also a big increase in bank debt, although not to alarming levels. I'm doing a quick Q&A with management at 14:00 today, that's done, the audio interview is here. Overall, a thumbs up from me, this looks a decent company, performing well, with reasonably priced shares.
Kitwave (LON:KITW) [no section below] - an impressive trading update is issued today for FY 10/2022 - strong trading in H1 has continued in H2, and as a result it expects full year results to be in line with expectations. What's noteworthy is the extent to which broker consensus earnings forecasts have risen this year, and still been achieved. An acquisition in Feb 2022 has gone well. A new DC has been opened, with "considerable benefits" to efficiency. Reckons it can mitigate higher costs. Outlook "remains positive". This share looks quite interesting, could be worth a closer look. Forward PER is only 8.5, and a 5.0% dividend yield. Looks good value.
Gattaca (LON:GATC) - uninspiring results for FY 7/2022, bumping along around breakeven (after big adjustments to eradicate impairment costs). No divi. STEM staffing is a buoyant sector, as we've seen from the great performance of £STEM . So why can't GATC make any money? Is it too small, or just not good enough (probably both!) It does honestly admit that "execution has been our Achilles heel". Expects the next 6 months to be flat. The main attraction is its strong, ungeared balance sheet, with £17.8m net cash, and £28m NTAV. versus a market cap of only £24m. Hence risk:reward actually looks quite reasonable. There's not really any dilution or insolvency risk, so you get any turnaround upside in for free. I wouldn't completely dismiss this, at 74p per share.
Graham's Section:
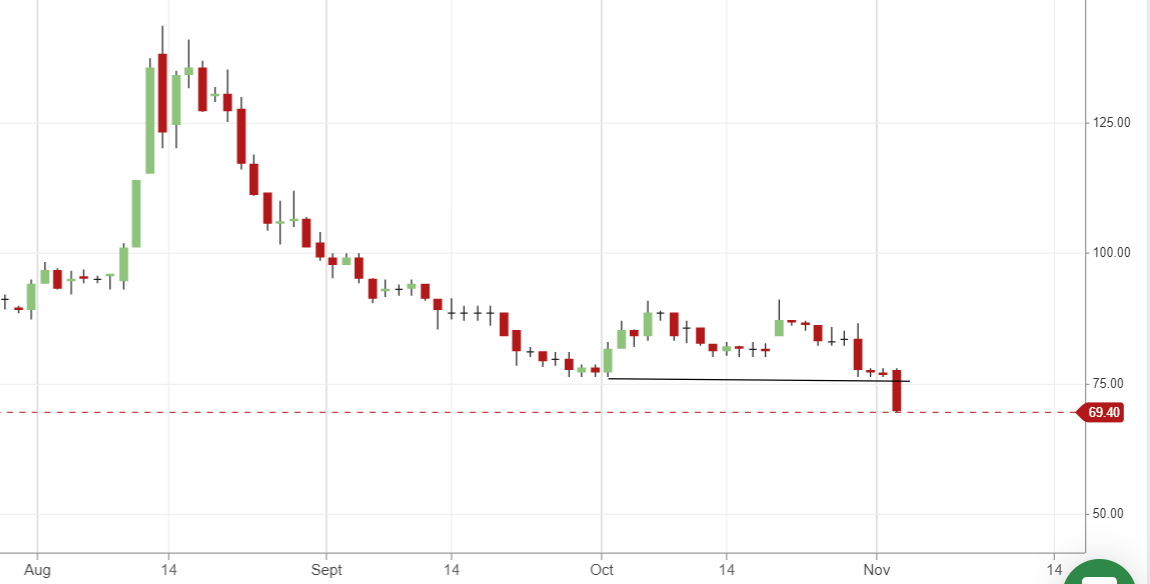
IG Design (LON:IGR) (£68m) (pre-market) [no section below] - theses share dropped 10% yesterday on no particular news: I’m guessing it may have been a combination of the company’s US exposure along with speculation over rising US interest rates, and a break lower through technical support that could have stopped some traders out. Fortunately, today brings better news as the company has finally picked its new CEO, about nine months after the previous incumbent stepped down. Paul Fineman was at IG Design for 17 years, including 14 years as CEO, and I do think it’s a negative for the stock that he didn’t stay longer to help fix the loss of margin caused by inflationary input cost increases.
Today the company announces that its recently-appointed CFO will become CEO. He has a background in the tobacco industry and also held a senior role at US-listed Tupperware Brands. He may be the right choice for the job but the instability in the CFO role is also a cause of concern for me. IG Design is now looking for its third CFO of the year while it has major financial challenges it needs to overcome. Interim results are due on 30th November.
.
TI Fluid Systems (LON:TIFS) (£670m) - this is a 2017 IPO that has previously been in much higher market cap territory. However, the slowdown in global vehicle manufacturing, combined with the inflationary loss of profit margin, have caused its financial results to flounder. Looking at this company for the first time, I note the very cheap price to sales multiple (0.27x according to Stockopedia) and the potential for margins to recover if supply chains ease up and as the company passes on price increases to its customers. Long-term, the main challenge it faces is likely to be the transition to electric vehicles.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
UP Global Sourcing Holdings (LON:UPGS)
140p (up 7% at 09:31)
Market cap £125m
Ultimate Products, the owner of a number of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872), is pleased to announce its audited results for the financial year ended 31 July 2022 ("FY22").
Probably because it was in line with expectations (hence not really newsworthy), we missed the trading update on 15 August 2022, for FY 7/2022, which indicated flash (i.e. early indication) of these numbers -
- Revenue £154.2m (up 13%, mainly from Salter acquisition, and 1% organic growth)
- Supermarkets doing well (esp in Europe), now largest sales channel.
- Underlying PBT in line with expectations at £15.8m (up 42% vs LY).
- Net debt:underlying EBITDA of 1.3x, with comfortable headroom of £17.8m in bank facilities.
- Current trading in line with expectations.
- Benefits starting from automation of warehouse.
- Confident in future prospects, proven ability to navigate & adapt (e.g. pandemic, supply chain).
Moving on to today, these are the actual numbers for FY 7/2022 -
Revenue £154.2m (exactly as expected)
Adj PBT £15.8m (also exactly as expected)
Adj EPS 14.7p (up 32% vs LY) - PER of 9.5 - seems undemanding.
Divis - policy of paying out about half earnings, with total divis of 7.12p - up an impressive 42% on LY (ot that, 2.3p already paid in July 2022), so the final divi is 4.82p. This is now an attractive (and growing) yield of 5.1%, twice covered by earnings.
All good then, all the key numbers are as expected.
Solar panels installed, expected to produce c.40% of their HQ’s requirements.
Overheads rose 16%, more than absorbed by gross profit up 27%, hence positive effect on profitability.
Clean accounts - no non-recurring items this time. No funnies, I’m happy with the accounts.
Air fryers in strong demand (buy one, they’re brilliant for small households!)
Online sales underlying down 1%, as shortages of product led to prioritising retailer customers. Recovered in H2 as supply chains improved, with +20% YoY online sales.
Acquisition of German brand, Petra, where they see a lot of potential.
Gross margin improved, to 24.9%, vs 22.2% LY - encouraging.
Share based payments charge is reasonable, at £403k this year, and £228k last year - other more greedy company Directors elsewhere, please take note!
Going concern note (note 2) says there’s headroom on bank facilities & covenants, so passes the going concern test.
Outlook - they’re only 3 months in to FY 7/2023, but sound pretty confident about things -
Current trading and outlook
The Board anticipates profit performance for FY23 will be in line with current market expectations. Whilst the current cost of living crisis represents a substantial challenge to all consumer-facing businesses, the Group is well placed to respond to this given its relentless focus on delivering value and growth.
Balance sheet - inventories have increased a lot, after supply shortages last year.
Same with receivables, also up considerably. But trade payables are unchanged. Hence the slack has been taken up by increased short term borrowings, up from £8.0m to £22.3m.
NAV is £43.5m, less intangibles of £37.0m, gives NTAV of £6.5m - not that much really, for the size of business.
Invoice discounting has been used this year, which wasn’t used last year it seems.
Total gross debt is £30.5m, net of £6.2m cash that drops down to net debt of £24.3m. That feels about the top end of what I’d be comfortable with.
Cashflow statement - adverse working capital movements absorbed about two thirds of the operational cash generation. Capex is modest at about £2m p.a.. The above means that there wasn’t really any cashflow to pay the divis of £4.8m, which has effectively been funded from increased borrowings. If that’s a one-off, it’s OK, but if expected to repeat, then there’s a good argument for say halving the overly generous divis, in my view.
My opinion - I think this looks very good. The items being sold are small household appliances, often to replace something that’s broken, so I can’t see replacement demand for say kettles or toasters disappearing.
Personally I’d be more comfortable if the company built up its balance sheet more than paying generous divis. Bank debt has increased a lot, due to a large acquisition last year, and working capital sucking in a lot of cash this year. Neither are alarming, but going into a recession, I prefer to avoid companies with gearing.
UPGS showed itself to be highly skilled at dealing with the pandemic & all the supply chain issues, so this looks a fundamentally well-managed business, reasonably priced.
I’m doing a quick Q&A with management at 14:00 today. So I’ll publish the audio around 15:00.
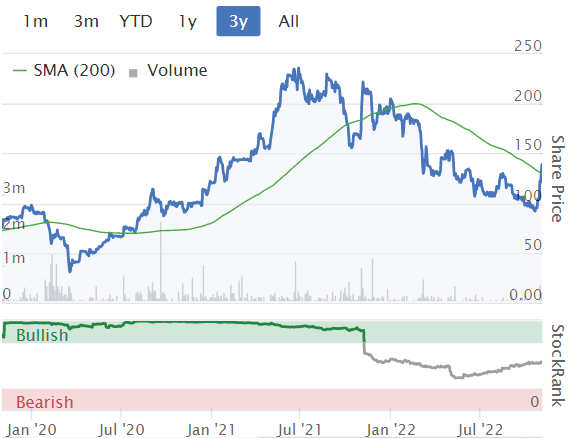
There's been a large % share price rise recently, so not sure I would want to buy after that, as many strong rebounds don't seem to be sticking at the moment, but timing your trades is up to you -
.
Graham’s Section:
TI Fluid Systems (LON:TIFS)
Share price: 128.8p (-3%)
Market cap: £670m
This is an automotive parts manufacturer that has never been discussed on Stockopedia before. Its HQ is in Oxford but its main office is in Michigan, US.
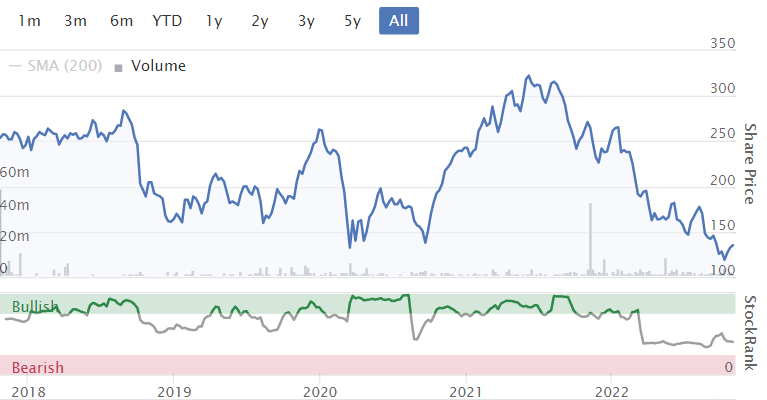
The IPO took place in 2017 at 255p, with private equity firm Bain Capital being the seller.
It has been a volatile few years. We are now 50% lower than the IPO price, and within the SCVR small-cap market cap limits:
Top-level overview:
TI Fluid Systems is a leading global manufacturer of fluid storage, carrying and delivery systems. With nearly 100 years of automotive fluid systems experience, TI Fluid Systems has manufacturing facilities in 108 locations across 28 countries serving all major global OEMs.
Let’s get into this Q3 update. Key points:
- Year-to-date (to September) revenues €2,405 million. This is +4.5% at constant exchange rates, or +10.4% at actual exchange rates ("ER").
- Q3 revenue +19.9% at constant ER, +28.8% at actual ER, thanks to increased vehicle manufacturing activity in the most recent quarter.
- “Excellent progress” in electrification. Large new bookings for BEV (battery electric vehicles) and HEV (hybrid electric vehicles), although in China progress with domestic manufacturers has been slow.
Revenue is heavily dependent on activity levels in the auto manufacturing industry (also known as GLVP - global light vehicle production), and this is obviously something that’s beyond its control.
But there’s some good news on that front, with read-across to many other companies as vehicle supply improves:
GLVP volumes in Q3 2022 continued their rebound and were 27.5% higher than in Q3 2021, driven by the recovery from the severe microchip shortages and supply chain disruptions experienced in Q3 2021, partially tempered by the ongoing impact of the Ukraine/Russia conflict on European volumes during 2022.
Outlook
Based on our current view of Q4 2022, we expect to report full year results in line with current consensus market expectations, with full year revenue growth consistent with, or slightly below, GLVP growth (on a constant currency basis), a full year adjusted EBIT margin of approximately 6.0%, and historical levels of cash flow conversion.
My view
I thought it was worth briefly mentioning this company, to give it a little bit of coverage on the site, especially since the market cap is now below our traditional upper limit.
It seems very keen to stress that it will be able to continue making money in a world without internal combustion engines, so I guess that is the main point of worry for investors.
A cursory look at its website shows its core products include things like brake lines, gasoline injection lines, high-pressure diesel lines, and fuel tank systems. How these systems will translate to a world of BEVs is beyond my pay grade but it doesn’t sound very easy.
Other concerns would be a) growth that lags its industry, and b) a failure to deliver meaningful profits in recent years. The interim results explained the lack of profits by reference to:
…persistent global macroeconomic headwinds arising from continued supply chain pressures in the form of cost inflation and dampened demand due to the continuing microchip shortages, plus the impact of the Ukraine situation on our European businesses.
Difficult decisions were made: headcount was reduced and plants were shut.
The question is whether brighter days might lie ahead and I will keep an open mind on this point: it’s possible that increased vehicle manufacturing activity, price increases negotiated with customers to reflect higher input costs, and a smaller cost footprint will enable TIFS to generate the level of profits that it did before:
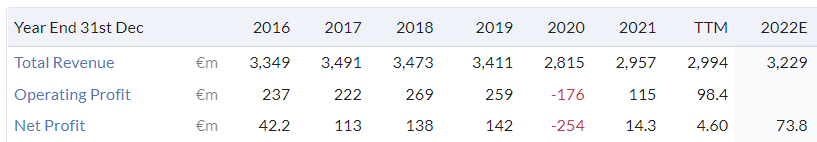
It’s remarkable when you think that this is a > €3 billion turnover business, for sale at less than €800 million. Like several other stocks we’ve covered, this is a situation where margin recovery is the most important factor.
Other factors with this stock are €660 million in net debt and the transition to electric vehicles, which does look like it will be tricky to navigate. But nevertheless it’s an interesting one for us to look at for the very first time.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Announcement by National World (LON:NWOR) late in the day for a possible offer for Reach (LON:RCH):
The Board of National World plc ("National World" or the "Company") notes the recent press speculation regarding a potential transaction involving Reach plc ("Reach"). National World confirms that it is at the early stages of exploring a possible offer for the entire issued and to be issued share capital of Reach ("Possible Offer"). National World has not yet approached the Board of Directors of Reach with regard to the Possible Offer.
RCH is 6x bigger than NWOR. How will they fund it? Will it flush out others?
Possible cash offer? Seriously? https://www.reuters.com/market...
When the deals start to get ludicrous its a harbinger of the long awaited crash.
Gattaca (LON:GATC)
Is it too small, or just not good enough (probably both!)
Certainly the latter but, far from being too small, it's almost certainly too large. To borrow a phrase, in recruitment only three things matter - focus, Focus and FOCUS. The much vaunted but cumbersome SThree (LON:STEM)'s margins are only half what the top boutiques achieve.
There's not really any dilution or insolvency risk, so you get any turnaround upside in for free.
While you watch any remaining human capital bleed out of a losing team until there is nothing left but a balance sheet rapidly draining into the hands of an incompetent legacy management and and inexperienced replacement cohort.
I've gone into more detail in the past on this so I won't rehash as users can search through past discussions. Sure, there's rebound potential but there's almost/just as much at RWA or STEM, which both look dirt cheap, as you've rightly acknowledged many times. I really would advise investors (as opposed to traders) to avoid.
Hi BnB, I've read your previous posts on recruiters with your recommending SThree and Robert Walters. Both are on attractive valuations, look good companies etc based on the figures. I get what separates SThree from the pack - a focus on STEM and hiring in for a temporary appointment which would appeal both to a lot of tech people and companies with a project to deliver - but what separates Robert Walters from the pack ? Or put another way, when the downturn almost inevitably comes, are there any factors which would allow them to outperform other recruiters?
Completely understand if you don't respond, but would be very appreciative if you did !
What separates Robert Walters from the pack ?
Or put another way, when the downturn almost inevitably comes, are there any factors which would allow them to outperform other recruiters?
When I highlight the virtues of RWA and STEM, it is only in contrast to other listed recruiters (Page, Adecco, Hays etc), but not in comparison with the quality end of the wider market. All will underperform quality boutiques, and in all market conditions, owing to weaker margins, inflexible incentives, slacker cost controls and a relative lack of focus.
Nevertheless RWA's virtues include a long trading history and excellent reputation, strong client relationships, and good sector concentration in attractive niches. It has a less attractive business mix than STEM, being 70/30 perm/contract, rather than the other way round. And that, along with the broader sector mix, has me favouring STEM. Contract is a bit like SAAS: your revenues are booked well (often years) into the future; perm has you staring into space all the time and wondering where the next deal comes from.
However, I rate RWA's management extremely highly. Roger W himself is a top man and shareholders' money is in excellent hands. More than anything I would suggest that this is RWA's strongest suit. Roger has been there and done it over 40 years: dotcom crash, GFC, pandemic - he's steered a good ship through all those storms.
I could add that RWA is more exposed to Asia, where the rate of growth of professional appointments is greater than in Europe or the USA.
Excellent analysis BnB, clearly an expert in this field, and appreciate you views!
Me too! Thanks for taking the time to respond.
Strong progress for the key brands Beldray and Salter plus significant advances in supermarkets and online coincided with increased margins across-the-board and an improvement in UP Global Sourcing Holdings (LON:UPGS) net debt/EBITDA position in FY2022. Moreover, the company anticipates that the market’s profit expectations for FY2023 will be met.
Strong sales growth in supermarkets and international sales were confirmed by today’s data which reported increases of 38% (25% excluding Salter) and 22% respectively. Online sales were a significant beneficiary of the Salter acquisition and increased by 23%.
The current share price fails to capture three salient growth drivers (namely brands, distribution and international) of the business. We believe the company’s ability to cope with external headwinds has been proven repeatedly, alongside its well-executed financial resilience. Hence, we base our 250p fair value / share assumption on an FY2023 EV/sales ratio of 1.5x and 12x EV/EBITDA.
Full note https://www.equitydevelopment....
Investor Presentation on the 9th at 11.30 https://www.equitydevelopment....
Another huge effort by Paul and Graham today - many thanks
FWIW
Personally I always read the results and especially TU's and Outlook statements from FTSE100 Co's that give an idea of how the UK consumer is behaving,
Next (LON:NXT) Unilever (LON:ULVR) Tesco (LON:TSCO) J Sainsbury (LON:SBRY) Frasers (LON:FRAS) Whitbread (LON:WTB) £ABF all usually contain worthwhile information even if you just scan thru . In the current macro enviroment i would suggest these are even more worthwhile and if Paul or Graham want to add their take on these I would welcome that.
Richard
Exactly. It's so quick for me to look at the headlines & outlook comments, that it's not either or (small caps or mid caps), it's both.
Portmeirion (LON:PMP) (I hold)
This mornings news of a design collaboration between Spode and Kit Kemp design and hotels for 2023 - also contained a short confirmation of current trading
'As we continue through our key seasonal trading period, Group sales remain
robust and further to our interim announcement on 15 September 2022 trading
for the months of September and October have been in line with management
expectations.'
So nothing to see here.
But then I don't expect anything at this stage. Management has gained a reputation for caution and in this of all years there are a lot of variables at play. The outcome will be highly dependant upon the direct sales from their UK, US and Canadian warehouses in the last few weeks still to go. And whether price increases and productivity improvements outweigh slow down in sales volume growth and input cost increases.
FWIW I am quite confident they will at least achieve their figures despite our current woes.
Currently trading on around 7x this years expected (adjusted) earnings and 6x next years. Price to book value just under 0.7x historic yield of 5.5%
I'm not an expert on luxury brands. I imagine this mornings collaboration announcement is at the luxury end of the market - and demonstrates the potential within the brands. Spode is particularly popular in the US. And a reason why I see this a potential multi-bagger from its current lowly price coming out the other end of current woes.
cheers
Mark
PS - Warning shares may go up in price as well as down. Yes really. Even mine!
/
/
/
Err - not sure how this 'undefined' message popped up. Seems to be an error onmy updating of my previous mssage.
So I'll try to use the opportunity to add my tuppence worth to the ongoing 'SCVR or not to SCVR' thread
I am completely happy with the current approach by Paul and Graham.
With their very limited resource I would much prefer to leave it to them to assess where they can best add value, Although I am entirely invested in UK small caps the SCVR doesn't often cover stocks I hold - but inevitably I learn more than I expected. Very often I value the discussion of why not to invest as much, and particularly when to get out, more than the when to invest, And not to forget the great contributions from the community on these shares.
And for that I thank you all very much.
cheers
Mark
My view of the companies that should be covered on here is that: 1) They should be outside of the FT100 because those companies have so many analysts looking at them that it is hard for us to be ahead of the crowd. 2) They should have a market cap of at least £50m otherwise they are too difficult / expensive to trade in any useful volume.
After listening to Cerillion (LON:CER) ...its obviously a great little company doing well. My concern would be a slightly nervous results day ...probably not the next 6 months but further down the road if sell cycles lengthen. Larger customers are harder to land and it wouldn't be a shock if they started to drag their feet ....esp to save some money. In the long run nothing to worry about ....as long as Cerillion (LON:CER) keep growing into their rating. As you can see from BT (LON:BT.A) ....the cost has to made back from somewhere. I know they aren't a customer of Cerillion (LON:CER) but never the less....it could be a bumpier ride. I always ask myself, would I be willing to buy more on a miss, on this one Im not so sure.
Im just listening to the BT (LON:BT.A) webinar.
The pressure from analysts is coming from the cost cutting : weak CF guidance : inline EBITDA combo....there is a suggestion that pricing weakness etc is the real concern which the company are extremely robust on. They could not be happier with their FTTP investment. They are behind on broadband due to industrial action...hopeful here that will sort itself out.
Looking fwd Enterprise and Global should stop being such a drag....they can't keep losing the same MVNO. Virgin I think. Outside this I thought numbers looked ok.
Re the pension - Gilt issues were extreme at the end of September....encouragingly they had no leverage issue. As I highlighted previously, the disclosure suggested this .... so they have just hedged liabilities themselves with the bonds. Gilts incl index linked have rallied significantly since 30 September.
re the debt.... YTM on 3.125% 2031 = 5.89%....5.75% 2028 = 5.79% suggests little stress at all. BT 3.625% 2047 = 5.3%
IMO BT would be a totally different prospect if CF supported share buybacks. It will in the future but at the moment they are investing. The analysts are worried about the competitive backdrop leading to further price weakness. The company anticipate strong ARPU reaction to investment...and keen to stress confidence here. They have moved ahead on investment at every opportunity.
BT (LON:BT.A) is a frustrating share on results day. Imperial Brands (LON:IMB) was similar until this year. Imperial Brands (LON:IMB) has been increasing the buyback. My personal view on BT is the equity return will beat the bond! When they get on top of Enterprise and Global I can see earnings getting back to mid 20s....and a dividend of 10p. This would support a shareprice north of 200. DYOR. Down here the shares make sense for private equity.
Having worked in the industry, I think £BT. is vulnerable, especially now with consumer spending power being squeezed. They are heavily reliant on their "sleeping" customer base who has been lazy to compare and switch, that they've been able to increase prices by RPI+something for years and years.
But it's one thing receiving a 3% annual bill increase and being lazy to switch, and seeing a 10%+ increase. When you're also actively trying to juggle rising costs elsewhere.
On top of that, steep MVNO competition in both mobile and broadband means they are massively undercut on price by more efficient, lower cost brands. Look at Lebara - offering 6p/month for 3GB for 6 months of sim only deals! How do you compare with that? Or broadband providers at £10-15pm when BT is closer to £30pm or higher.
They will do well eventually. Their FTTP dominance will come to the fore in a few years time. Many of these MVNOs will shut down or merge. But at this moment...
This is bang on Boon. I looked at their new full fibre offering with an intention to proceed until they declared a rise next year of rpi plus 3.9%. When asked about it they replied that is what all the companies do. It isn't and I walked over to one of their competitors. Really silly of them in my view. As I said "I have no problem with RPI everyone can see what is happening but 3.9% on top is just plain greedy."
Sorry Dicktrade FTTP.
MVNO , FTTP ??
TFF Google :-))
MVNO= mobile virtual network operator
FTTP = fibre to the premise
Are BT necessarily a loser when customers switch to an MVNO?
For Mobile - yes, BT loses out if someone leaves. Unless the MVNO is using EE (owned by BT). However, those MVNOs get bulk, regulated rates on the data and line usage. So the replacement income is not the same.
For Broadband - yes, but still get something most of the time. The vast majority of broadband currently is on Openreach, which is owned by BT. However, using (very simplified examples), a BT customer that has been with BT for many years might now be paying like £50pm for broadband (because that was the cost back then, plus all the yearly increases). If they swap to the best of market price now (Shell Energy) at £14pm, yes - some of that £14 will go to BT. But it will still be less than the margin they used to get on the £50 customer.
So really, the whole BT business model, because they are #1 in customer numbers for Broadband (and also for Mobile I think) - is to prevent their existing customer base from churning. As customers call up to leave, they retain them by putting them on better pricing. But that means that their recurring revenue is shrinking over time, even if they manage to retain every customer. And new customers they bring in, are at a much lower revenue than the existing base.
That's why the key business model driver for these Telcos over the last few years has been how much cost can they cut - they need to do it faster than the deflationary impacts of (1) data trending to £0 cost and (2) churn of their existing base.
Inflation has definitely changed the picture; but even with my former Telco experience, I'm not quite sure how this will impact BT, Vodafone, etc. Quite complicated as you look into existing back books, customer switching behaviour, debt levels, debt cost, capex requirements, competitor landscape, etc.
Thank you that is interesting although both consumer and open reach looked ok to me today. I think there are always examples where pricing of any offer can look way off or just doesn’t work for some people. When I have looked at it bundles tend to be much more competitive … and when I have considered switches myself the gains hardly seemed worth the hassle in the end. But I also agree that for others that’s not the case and they switch. As you say it’s complex but I believe the build out will put them in a stronger position and I’m happy collecting the divi in the meantime. The brokers seem to agree with you however … but in this sector they look at one no FCF and if it slips they jump up and down.
This is called "The Small Cap Value Report"
so lets change the name to 'the small cap value report and other stocks of interest'
Interesting final results from UP Global Sourcing Holdings (LON:UPGS) today which were largely in line with the recent trading update.
I think a key UPGS strength is the range of brands and suppliers they source from. This gave them the flexibility to help navigate supply constraints relatively well and grow both revenue and profits.
That said, looking deeper into today’s results I see a couple of potential issues. Firstly, UPGS sources in USD but sells in GBP and EUR. In the current FX rate environment this is obviously a headwind.
Whilst the hedges in place will help protect this year’s cash flows and profits my concern is that hedging simply delays the impact of FX movements i.e. it buys UPGS time to pass increased costs through to customers, assuming they are able to do that. This may be tricky given the impact of weakening UK and European economies on demand, so future profit margins may suffer.
Management have pointed to increased working capital investment to help ensure inventory levels are resilient and to fund growth, e.g. they recently signed a contract with a large super market in Germany. Despite operating profits of £16m, operating cash flow was only £4m.
Working capital funding has come from import loans, invoice discounting facilities and overdrafts.
Whilst it makes sense to match short term working capital needs with short term funding, short term debt has increased from £8m to £22.3m, a very high proportion of the £30m gross debt.
The Group notes facilities headroom of £17.8m but doesn’t disclose how much of these facilities are committed versus uncommitted. Typically, the overdraft, invoice discounting and import loans would not be committed facilities exposing UPGS to refinancing risk. Whilst the overdraft will be repayable on demand the other facilities will typically have a 90 to 120 day maturity.
That’s not to say the bank will withdraw the facilities but it does expose the Group to significant interest rate, spread and fee increases given the current volatility in interest rates and availability of funding.
Hopefully management will provide some colour around these key areas during Wednesday’s investormeetcompany presentation.
If you read the notes to the accounts of UP Global Sourcing Holdings (LON:UPGS) you will find that they significantly hedge both fx and interest rate risk. In addition, over 98% of trade receivables are insured (I'd guess at very modest cost as most creditors are high quality retailers). Disclosures in prelims are pretty comprehensive. The full report will contain more notes when released.
On loans, there's a 20% reduction in 'term loan' which is the structural debt part (£10m to £8m) related to Salter acquisition. Aside from this term debt other debt tends to indicate robust trading (it can mean extended import times but congestion and delays significantly down so the hint is good trading going into H1 23).
There is some risk related to inventory build primarily for own online retail (they had slowed their sales on this line fy22, particularly H1 22, so as they could make sure of make 3rd party demand in strained supply times - an excellent decision to protect and build relationships which hopefully leads to more biz over time). However this is not credit backed like goods supplied to 3rd parties (though some of the overdraft could relate to this rebuild).
UPGS continually explain these things well but the business remains reasonably misunderstood.
The key point on hedging FX is that it only delays the impact of FX rate movements on the GBP value of costs and revenues. They will be locking in very different GBP/USD rates compared to FY22.
The cost of rolling over short term working capital debt will increase with interest rate increases and market volatility.
Hopefully they explain all this next week.
Of course. They can't change the exchange rate. You will note that GBP has been on a falling trajectory for approx 6 years particularly relative to USD...and the CNY that seeks a partial peg with the USD (they are mercantilists and want CNY lower but need to be cautious on too much as raises US ire...CNY recently falling tho and must be under great pressure due to massive JPY devaluation as China competes in many market segments with Japan).
Ultimately everyone in the domestic goods market is a price taker...what counts is how you are positioned relative to others. UP Global Sourcing Holdings (LON:UPGS) have explained repeatedly their competitive positioning in this regard and proved it robust to date...
...so I'm nonplussed that you want UPGS to explain macro to you and how they will make it go away ;)
Thank you. Sounds like margins will depend on UPGS's ability to reduce Asian supplier prices given the strength of the USD.
In my podcast with UP Global Sourcing Holdings (LON:UPGS) today, their MD Andy Gossage indicated that the savings from drastically reduced freight costs, are offsetting dollar strength. So he doesn't see any need to raise selling prices in 2023. Very interesting! The audio is just published, on my website here. Well worth a listen!
Brilliant, thank you.
Anyone shorting the DOW? I know Revs was shorting the the DAX and the other US index. I saw the turn on the weekly and upper trendline resistance and shorted last Friday but got in too early by a couple of days and lost. Almost quit but had another go around 6PM last night as FED news was due. Managed to open a small short position at the highs , and now well in profit. planning to hold for 3-4 weeks for possible a 3000 point move. It's hard work trading the indexes, but the lucky trade does comes along every once in a while.
I have been trying to boost the cash balance in my Vanguard account by buying the obvious dips, not timing the bottom but buying on big down days, or several down days and selling into the bounce.
Obviously a far more simplistic method, but slowly offsetting some of the losses, and looking at the monthly report, 5:2 up since the tax year started!
Tommy
Daniel Thwaites (OFEX:THW) Solid interims,from a solid company . Big winner from interest rises due to swaps , doubling EPS. Very cautious statement from a very cautious family company. Only company I am aware of that sets out it's own NAV including their pension fund debit or credit. Reinstated interim dividend but only at a lower level.
Looks very well positioned to ride out any storm.
Just FYI, this is our plan of action for this morning:
Anyone interested in the Gattaca Prelims can read today's Equity Dev note (unchanged forecasts and FV/share of 160p) here https://www.equitydevelopment....
Hi Paul,
I really welcome more comments on Mid cap companies. I am investing more in the top 350 and less in AIMs nowadays. I understand the merits of discussing small caps here and I was going to talk to you and Ed at the MELLO in mid November about this.
Thanks Lucky dip,
I'd also like to do more mid caps commentary, as there are so many interesting valuations for excellent companies cropping up right now. Maybe we should raise our market cap limit again, and stray outside of it whenever anything looks interesting?
It's quite quick for me to look at the headlines, and the outlook statements, so I'll try to cover more companies that way with super quick comments, not any further analysis.
Regards, Paul.
I would be content for you and Graham to cover any company that you believe looks interesting regardless of market cap. If you believe Rio Tinto (LON:RIO) is about to multi bag, why should an arbitrary cap stop you informing us.
I have also moved a lot of my portfolio into higher capped companies recently.
I have also moved a lot of my portfolio into higher capped companies recently.
For me it's less about the size of the company and more about the strength of the moat. This has me in a lot of large caps but still a decent proportion of small- to mid-caps. As 55555 suggests, I do think it is worth trimming the analysis of dogs like Parsley Box and Made.com in order to accommodate higher quality mid-caps.
Probably there will be less advantage gained in the analysis, but it would spark useful debate in the community about the merits of more established companies. It would also broaden the covered universe of stocks with sufficient liquidity for those who trade in larger blocs - those lacking the information advantage of the institutions but without the nimbleness of execution enjoyed by the smaller scale PI.
Hi BnB,
I know what you mean about coverage of MADE and MEAL, but part of the purpose was to warn people away from those shares, when I could clearly see things were going badly wrong. Which is surely a useful service, as well as flagging good stuff?
Regards, Paul.
I know what you mean about coverage of MADE and MEAL, but part of the purpose was to warn people away from those shares, when I could clearly see things were going badly wrong. Which is surely a useful service, as well as flagging good stuff?
It certainly is useful Paul, and appreciated by me, so perhaps I didn’t pick the best examples. But I still feel there’s a lot of dogs taking up bandwidth here, attention space that could go to higher quality, possibly larger, names.
And I would echo MichaelFBS’s observation that, although larger names are better covered by analysts, access for PIs to that data is not always straightforward. I don’t have a UK stockbroker and quality companies like Spirax and Halma fall between the upper limits of ResearchTree and the lower thresholds of my international bank.
Would very much welcome this. Double thumbs up from me.
Paul, I’d much prefer you to cover companies that should be interesting investments whether small caps or 250 or above, than spending time doing great detailed analysis of companies we’d all best avoid.
Spot on 55555!
Maybe the 5 day coverage could be split 3 days SCVR and 2 days FTSE 250/Large Caps rather than mixing coverage across all caps every day. A specific split would allow contributors and readers more focused content.
I like the tone of the suggestion. However covering for example Rio Tinto is nothing like covering a Beeks and I can't help feeling Paul takes enough unfair abuse already. The big companies are so well covered by the large investment companies I would be very surprised if Paul can add value. The Capitals, Wellingtons, Fidelitys have analysts who cover these companies all day every day, which means you will always be trailing. That's why I invest in AIM otherwise I might as well just buy funds. I think we are all getting too into the moment where macro has created confusion and volatility. Things will in due course settle down again and Rio will become a straight play on Commodity price and point in the cycle.
I agree. While it is important to understand what is going on in large/mid-caps for the read acrosss into small caps, the chance of spotting something that is not already in the market price for large/ mid caps is remote. I focus on the small caps, because I believe I have a possibility of understanding the company “better than the market.”
"The big companies are so well covered by the large investment companies I would be very surprised if Paul can add value." Probably true Camtab but do PI's have access to this research?
And maybe not £RTZ but stuff further down the scale for example Games Workshop (LON:GAW) or (do I dare mention it) Boohoo (LON:BOO) when it was a mid-cap or, from yesterday, Aston Martin Lagonda Global Holdings (LON:AML) when it was a mid-cap.
Additionally I think historically there many exampes of large companies being really badly mispriced.
I suspect that the biggest issue for Paul adding mid/large caps to the S&MCVR is that he only has 24 hours in a day.
Regards
Michael
This gets a double thumbs up from me too Paul (and I agree with also minimising coverage of micro caps and basket cases) - perhaps £30-50m at the lower end and up to £1bn?
I agree - I am also heavily invested in FTSE250 companies and more coverage of these would be much appreciated ...
Interesting announcement from Facilities by ADF (LON:ADF) regarding the opening of a new office in Glasgow.
Film and high-end television production is on a roll in the UK. Facilities by ADF (LON:ADF) should be a major beneficiary of this tailwind, but at present my holding in the company is 'under water' along with most of my portfolio of UK small caps.
"Facilities by ADF, the leading provider of premium serviced production facilities to the UK film and high-end television (HETV) industry, today announces the opening of its new office in Glasgow, set in Pioneer Film Studios' campus, Scotland's newest and largest film studio."
On the matter of film and television production I wouldn't be surprised to see some corporate action involving ITV Studios, which was mooted in the Financial Times a few weeks ago. ITV (LON:ITV) is one of two large caps that I hold, the other being Howden Joinery (LON:HWDN) that put out a positive trading update this morning.
Regarding ITV (LON:ITV) I admit to a little self-indulgent speculation, but the Studios and back catalogue are worth more than the current market cap in my opinion. In the meantime, the shares are valued as if the company is financially distressed and administration beckons! Patience, patience and more patience, thus it goes in investing.
Regarding ITV (LON:ITV) I think the market is very suspicious of businesses which derive all or most of their income from advertising, and the collapse in price of £META is perhaps the most extreme example.
Hi Michael,
I think that you will find the revenue for ITV (LON:ITV) is roughly split 50:50 between advertising on free to air and ITV Studios and is gradually shifting towards the latter.
As for television advertising I don't see the likes of 'Meta' benefiting from the World Cup, Six Nations Rugby Union, Grand National, FA Cup or other iconic sporting events plus shows like Love Island, the Masked Singer etc.
Valuation counts so one also needs to consider the investment metrics of ITV (LON:ITV), dividend yield, PE, ROCE, earnings yield, operating margin etc together with management style. My preference is for Carolyn McCall over Mark Zuckerberg
In fairness I don't know too much about 'Meta' or Facebook as it once was called, but understand that it has de-rated significantly. I have little doubt that ITV (LON:ITV) will also suffer a decline in advertising revenue, but film and television production are going gangbusters.
Call me old fashioned or even naive, but I invest in what I believe I understand and I know which I would prefer to own.
Of course, I may be wrong. Time will tell.
All the Best
Hi Paul, I just wanted to say before my subscription runs out that I have really enjoyed your analysis and keep it up. I will be back soon when my finances improve. Also thanks to everyone else on this forum who has answered my newbie questions. #iwillbeback
Good morning Wornoutmk, thank you for your message. What a pity we're losing you, and I'll make sure the red carpet is vacuumed and ready to roll out for your return in due course! :-) Best wishes, Paul.
thanks Paul. :-D