Small Cap Value Report (Thu 31 Aug 2023) - SOM, PPHE, SND, PBEE

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
This is what we're planning on reviewing today -
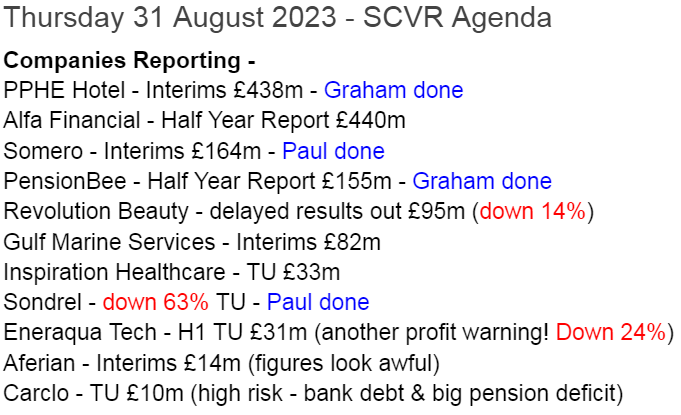
Summaries
Somero Enterprises (LON:SOM) - Down 2% to 285p (£160m) - Interim Results - Paul - AMBER/GREEN
H1 results show profit down 30% on LY, with a sharp slowdown in its main market of USA. Outlook comments reassure though, in line with (lowered) expectations for FY 12/2023. Balance sheet remains bulletproof. I stress test the numbers for a recession, and it should remain profitable. Lots to like medium-long term, but due to shorter term macro uncertainty, I've moderated my view from green to AMBER/GREEN.
PPHE Hotel (LON:PPH) - Up 3% to £11.10p (£479m) - Interims (in line) - Graham - GREEN
This hotel operator reiterates the improved 2023 guidance that it gave in the recent trading update. Additionally, there is now the prospect of capital returns (buybacks/tender offers). The low valuation of these hotel assets interests me, but occupancy must keep improving.
Sondrel (Holdings) (LON:SND) - Down 62% to 21.25p (£19m) - Trading Update - Paul - RED
A hideous update from this chip designer, which has seen expected revenues all but dry up for H2, due to project delays. I think that leaves it in a precarious financial position, as there are some nasties on the balance sheet. The company reckons it has enough cash, but I disagree - expect a distressed placing at a discount. Looks like the fund managers were sold a pup, in this Oct 2022 IPO.
Pensionbee (LON:PBEE) - up 2% to 71p (£159m) - Half Year Report (in line) - Graham - RED
Forecasts are adjusted only slightly here and this online pensions provider continues to believe that it will hit monthly profitability (on an adjusted EBITDA basis) by the end of this year. I remain sceptical and view both the cash burn and valuation as sources of concern.
Paul’s Section:
Somero Enterprises (LON:SOM)
Down 2% to 285p (£160m) - Interim Results - Paul - AMBER/GREEN
Background - we like this laser-guided concrete screeding machine group, based in the USA.
Attractions include high profit margins, great cash generation, strong balance sheet, and generous shareholder returns.
Bear points are mainly the cyclicality of its market, with less equipment being purchased by customers in recessions. Graham also flagged increasing competition in his last report on Somero, after some nifty googling. Failure to meaningfully break into international markets after years trying, might also be seen negatively.
Momentum (in both share price, and declining broker forecasts) has been poor this year.
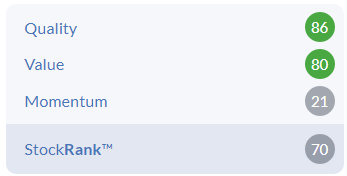
The StockRank sums it up perfectly - a quality business, at a value rating, but with poor momentum currently -
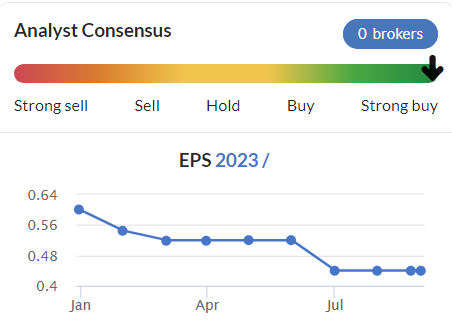
As you can see, forecasts have come down considerably, so today’s in line with expectations outlook comments are well below original expectations! That’s why the share price has fallen this year.
Key numbers for H1 -
Revenue $58.9m (down 14%)
Rest of World was fine, but USA (SOM’s main market by far) saw revenue down a hefty 24%, blamed on higher interest rates & tighter lending causing projects delays or pauses. Also an internal delay on production for one product line (since resolved).
H1 adj EBITDA down 28% to $17.3m
H1 profit before tax is down 30% to $15.6m
Outlook - expecting H2 to be slightly better than H1 -
Expected improvement in H2 2023, trading in line with expectations for 2023 revenues of approximately US$ 120.0m, EBITDA of approximately US$ 36.0m, and year-end cash of approximately US$ 32.0m..
The expected improvement in H2 2023 trading in the US compared to H1 2023, supported by the entry of the S-22EZ into full production, contributions from key international markets and positive feedback from customers, reinforces the Board's belief that 2023 results will fall in line with market expectations. With a healthy financial position, we remain committed to making sound strategic investments to deliver strong results and cash flows to our shareholders."
The StockReport also shows $120m revenues forecast for FY 12/2023, which becomes $0.44, or c.35p EPS. Giving a bargain PER of only 8.1x (at 285p per share at 08:15). Well, it’s only a bargain if you think this (reduced) level of earnings is sustainable, and won't get any worse. A deeper recession, causing a negative leveraged impact on SOM’s profits is one of a range of possible shorter-term outcomes.
It’s obvious from the P&L that the fairly high 57% gross margin that SOM achieves mean that there’s considerable operational gearing here. So a deeper drop in revenues would have a nasty impact on the bottom line. Although by my calculations, SOM would remain profitable even with a large further fall in revenues - falling to breakeven would need a c.50% drop in revenues (assuming gross margin %, and overheads remain unchanged). So there’s bags of headroom here to absorb a bad recession without any solvency or dilution worries (particularly given the strong balance sheet too). It’s always worth stress-testing accounts for all companies, to see what impact a recession would have. Some are finely balanced, but Somero is definitely not, it’s rock solid, even in a severe downside scenario.
Dividends - are generous, and a key reason to hold SOM shares. The interim dividend is held flat vs LY at $0.10. It mentions strong finances, and confidence in the H2 outlook as reasons why it has maintained the divi.
Share buybacks are just to offset dilution from share options, which the company is open about in the commentary - so these are really part of management remuneration, rather than adding shareholder value.
You have to fill in a simple form, to receive divis from US companies, which I did easily through my broker, when I held SOM shares.
Balance sheet - cash is plentiful, but well down on last year, at $25.2m.
Accounts receivable looks extremely low (which is good!) at $7.3m, indicating that SOM must be selling mainly for cash on delivery. Maybe it gets the cash quickly because hire purchase/leasing companies fund the products?
Inventories are up, at $21.4m (LY: $18.8m), which surprises me, as I’d expect lower revenues to be reflected in lower inventories too. Maybe there’s a little over-stocking here? That’s a good question to ask management on the next webinar. As long as inventories aren’t obsolete, then it shouldn’t be a problem anyway, so not that important.
Overall, the balance sheet is bulletproof, no issues here at all really.
Cashflow statement - cash generation is still good, but down on last year. Reduced profits, and a $4.8m reduction in creditors is partly to blame.
Modest capex at only $1.0m in H1.
The biggest items on the cashflow statement this year and last, are dividend payments. Somero is a big cash generator, which it mostly pays out to shareholders, making it an attractive investment I think.
Are the dividends sustainable? That depends on how trading & macro factors develop. For now, I would say yes, but in future who knows? A deep downturn would probably see divis cut, but you can say that for most companies.
Paul’s opinion - I like this company a lot. It clearly has a good niche, which is highly profitable. However, as we’ve seen before, it is susceptible to economic downturns, and we all remember how it came close to going bust after the 2008 recession. However, that was due to entering the recession with a weak balance sheet. It’s the opposite now, the company is conservatively financed, with net cash, so could comfortably ride out even a bad recession that halved revenues, by my calculations.
Today’s update reassures, with only a slight improvement on H1 needed to meet the FY 12/2023 numbers, and reasons provided as to why it thinks that is achievable. Although the comments about interest rates & reduced bank lending impacting H1 does worry me a bit, as those factors haven’t gone away - they’re getting worse. So an H2 profit warning does look a possibility here.
For that reason, I think we should trim our bullishness from green, to AMBER/GREEN, to reflect the macro uncertainty. That denotes that I like the company’s fundamentals and think it’s good long-term, but am worried about the shorter term picture, given that this type of company does tend to suffer badly in economic downturns. So holders of this share are, by implication, predicting a fairly soft landing for the US economy.
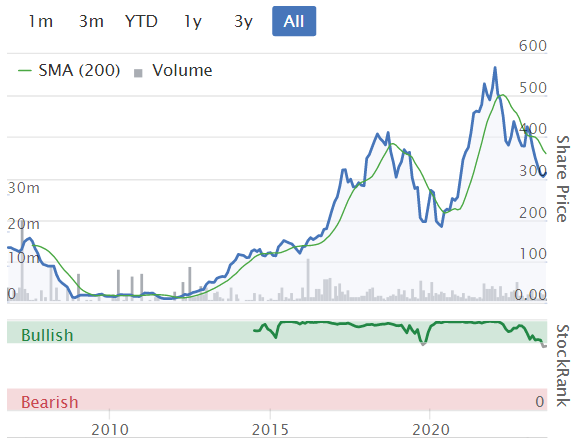
From the low, to the early 2022 peak, this share 50-bagged!
Sondrel (Holdings) (LON:SND)
Down 62% to 21.25p (£19m) - Trading Update - Paul - RED
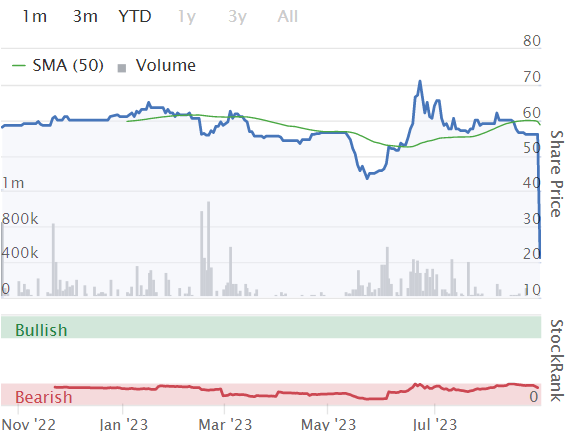
We’ve not covered this company here in the SCVRs before, but a 62% drop today compels me to review what’s gone wrong, and get something into the system here, for future reference if subscribers want to quickly check what we think about it.
It’s a small, loss-making chip design company, which floated recently, in Oct 2022.
Sondrel (AIM: SND), the fabless semiconductor business providing turnkey services in the design and delivery of 'application specific integrated circuits' ("ASICs") and 'system on chips' ("SoCs") for leading global technology brands, provides a further update on trading ahead of the publication of the Company's interim results for the six months ended 30 June 2023 ("H1 2023") on 21 September 2023.
H1 revenues expected to be £9.3m, up 17% vs H1 LY.
H1 adj EBITDA expected to be £0.4m (up from £0.1m H1 LY).
Pleased with sales pipeline in the USA - 15 potential customers, with design/prototype revenues >$100m over 2 years - potentially - not contracted yet.
Production forecasts for live European projects are up 78% to $170m., giving confidence for FY 12/2024 and beyond.
That all sounds good, so why has the share price collapsed by 62% today?
Here comes the bombshell - a profit warning for H2 2023 -
3 projects have been delayed by 6-12 months, pushing them into 2024.
FY 12/2023 revenues to be “substantially below current market expectations” at £13m+
Corresponding impact on FY 12/2023 losses (no figure provided).
Cash position - no figures again, but it says -
The Company is confident that it has sufficient access to finance for the foreseeable future following its October 2022 IPO.
CEO is promising lashings of jam tomorrow -
"Our increasing traction in the important US market, strong sales pipeline and positive ongoing relationships with our existing ASIC customers provides us with great confidence in our medium-term target to grow revenues to over £100m and we will ensure that we keep updating shareholders as we make progress towards this goal."
Broker update - thanks to Cenkos, for quantifying the extent of the damage.
It’s a massive drop in forecast revenues for FY 12/2023 - previously £28.4m, now just £13.0m. Since £9.3m is reported for H1, that means H2 has almost dried up, to only c.£3.7m revenues expected.
This translates into a loss before tax of £(6.6)m for the current year FY 12/2023.
Forecast for 2024 assumes revenues will more than triple, and a move back into profit of £2.2m. That looks rather ambitious.
The forecast balance sheet looks very weak, with NTAV forecast for Dec 2023 at negative £(11.3)m. That doesn’t look tenable to me - it’s going to need another placing I think - will there be any appetite to pour more money into this serial loss-maker?
Paul’s opinion - this looks a disaster, no wonder the share price is down 62%.
It raised £17.5m (net of costs) in the Oct 2022 IPO, priced at 55p. It’s now 21p.
The founders (Curren family) owned 45% after the IPO, so are in control, hence delisting risk looks a potential worry now, and fund managers might want a mistake removed from public view?
Looking through its Admission Document, I’m surprised they were able to float this at all. Its historic numbers are terrible, with heavy losses each year. It had run up an insolvent balance sheet too, with negative NTAV of £(16)m, so the net IPO net cash of £17.5m only just eliminated the deficit of NTAV. Add further heavy losses this year, and I reckon the balance sheet is probably in poor shape again.
I note from the admission document that payables includes £6.8m of deferred creditors for software licences, payable over 3 years. How is that going to be paid?
The balance sheet at end Dec 2022 looks very peculiar, with large & unusual receivables and creditors.
I think this is looking financially distressed, hence I’m keeping well away from it. Another placing looks very likely to me, and could be on horrible terms.
The business model is clearly flawed - with project delays now putting the survival of the company in jeopardy (even though that’s not admitted in today’s RNS, it seems pretty obvious to me, after digging into the numbers in more detail).
It’s a total avoid for me, at any price - for gamblers only now.
Graham’s Section:
PPHE Hotel (LON:PPH)
Share price: £11.10 (+3%)
Market cap: £479 million
PPHE Hotel Group, the international hospitality real estate group which develops, owns and operates hotels and resorts, announces its unaudited interim results for the six months ended 30 June 2023 (the "Period").
I turned positive on this one in June, after reading the strong Q2 update. This change in stance was based on a belief that the company was on its way to pre-Covid performance levels.
Today we have full interim results:
Revenues +59% year-on-year to £180m, up 15.9% on H1 2019.
Average room rate £159.6, up 13% year-on-year, or up 31.2% on H1 2019.
For me, the key number is the 31% growth in the average room rate since H1 2019, i.e. since the last year pre-Covid. That should be plenty to match cost inflation over that timeframe (inflation since 2019 is around 25%).
Q2 room rates were much stronger than Q1 room rates, which bodes well for the rest of the year.
The next question is whether the hotels are full enough. Occupancy was 69.1% in H1 2023, versus 76.8% in H1 2019.
So there is still some room for improvement and of course it’s uncertain when/if those pre-Covid occupancy rates might be achieved again. But I think we are on a very encouraging trend.
Note that occupancy in H1 last year was only 48%, so last year’s figures do not provide a relevant or useful measure of PPHE’s “normal” performance.
Moving on to profitability: PPHE reports H1 2023 EBITDA of £45m. This is a huge improvement on last year but is only flat compared to the figure for H1 2019.
Statutory net income in H1 is very small and in truth only around breakeven (net income to PPHE shareholders only £1 million). This underlines my view that it’s not enough for the company to match 2019’s EBITDA. It needs to significantly beat it - which it can do if occupancy keeps improving.
Net realisable value (similar to NAV, and calculated using EPRA principles) is unchanged at £25.05 per share, using property valuations as of December 2022. Fresh valuations will be carried out at the end of this year. After taxes, the estimated net disposal value of the company’s assets is £24 per share.
These numbers are obviously far bigger than the current share price, reflecting mixed views on prospects in the hotel sector!
Capital returns: the company has noticed that its shares are cheap relative to estimated asset value, and might be about to take some action in recognition of this!
Given the strength of trading and confidence in outlook, the Board believes the Company is now in a position to return to its historical capital returns policy of distributing approximately 30% of adjusted EPRA earnings (reported at £1.06 in the twelve month period to 30 June 2023), while continuing to support investment in future growth opportunities. In light of the continued significant share price discount (c60% as at 31 August 2023) relative to EPRA NRV per share, the Board intends to consult with shareholders regarding the most appropriate and effective mechanism for such distributions to take place, including dividends, share buybacks, tender offers or a combination thereof. The Board looks forward to updating the market on this capital return policy in the near future.
New hotels - art’otel London Battersea is open, and four new hotels will open between October 2023 and H1 2024 (Belgrade, Zagreb, London, Rome).
Net fund - regulatory approvals obtained for the new €250 million European Hospitality Real Estate Fund.
Current trading/outlook - “strong trading conditions have been maintained through Q2 and into Q3 across all main market segments”. They continue to focus on room rates (to cover inflation) while also rebuilding occupancy.
There is no change to upgraded forecasts of £400m revenues and £120m EBITDA this year. This implies £220m of revenues in H2 (vs. £180m in H1).
Graham’s view
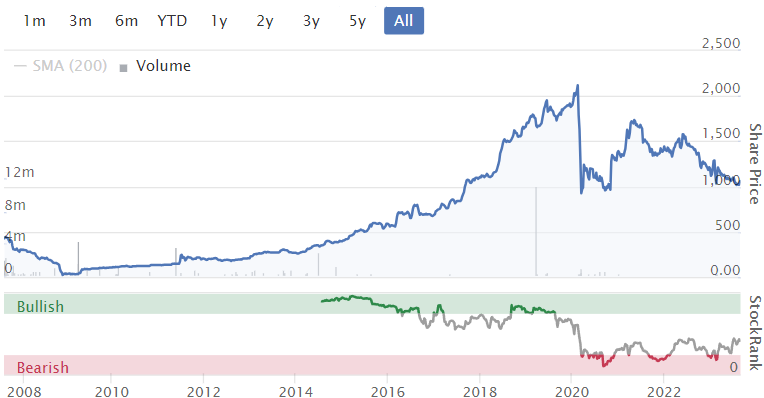
I’m remaining positive on this one for the same reasons as before: the discount to NRV and my belief that improving occupancy trends can take the company back to pre-Covid performance levels.
Additionally, today we learn that there is a possible catalyst in the form of share buybacks/tender offers, which could see the company manually helping to close the share price discount to NRV.
To provide some balance, here are some reasons for caution:
Cost of living issues may hurt affordability for the foreseeable future and prevent occupancy rates from improving to pre-Covid levels. Similarly, business travel might not reach the levels of 2019.
Statutory profits remain low here and if you look at the earnings multiple as calculated by Stocko, it’s expensive at nearly 18x.
Leverage is significant; gross bank borrowings are £850m/net bank borrowings are c. £700m, far higher than the market cap.
Perhaps I’m too optimistic but I still think that this one could prove to be a bargain, if we can get back to the assumptions of pre-2020:
Pensionbee (LON:PBEE)
Share price: 71p (+2%)
Market cap: £159m
(Disclosure: Graham is a shareholder in Hargreaves Lansdown (LON:HL.) which is a competitor to Pensionbee.)
PensionBee Group plc ('PensionBee' or the 'Company'), a leading online pension provider, today announces interim results for the six month period ended 30 June 2023 (1H 2023).
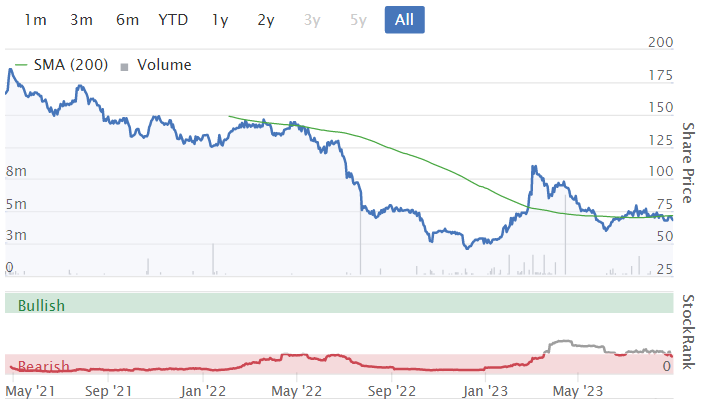
I have been negative on this stock (see here and here, with the share price around 95p-101p), and now we have interim results to mull over.
Key points:
Revenue +32% to £10.9m
Pre-tax loss £9m (H1 last year: £17m)
Invested customers +33% to 211,000
Assets under administration +38% to £3.7 billion
Cash position £14m (a year ago: £29m).
Both Liberum and Equity Development publish forecasts on this company.
Since March, there hasn’t been too much change in these forecasts: Equity Development have increased the full-year revenue estimate (£24.1m) but have also slightly increased the expected full-year EBITDA loss (£9m), due to higher costs.
It will be very impressive if the company can meet the profitability forecast: they already have an adjusted EBITDA loss of nearly £8m in H1. So adjusted EBITDA will have to improve to nearly breakeven in H2, if the full-year loss is to be only £9m.
This metric excludes substantial share-based payments of over £1m in H1 both this year and last year.
The CEO/Founder says they are “on track to deliver monthly Adjusted EBITDA profitability by the end of the year”.
Marketing spend - it’s worth honing in on this item. The company spent £6.8m on marketing in H1, much lower than H1 last year (£12.4m), which goes a long way to explaining the reduction in the financial loss this period. £50m has been spent on marketing efforts in total.
Outlook - guidance is reiterated. The £14m cash balance “leaves us well-placed to pursue a c. 2% market share target of the substantial £700bn UK transferable pensions market”. Adjusted EBITDA profitability is targeted in 2024.
Graham’s view
I can see that there is a defensible investment thesis here, based on the company reaching breakeven/profitability soon and then seeing its assets under administration grow from there with the help of both new customer recruitment and asset growth from the existing customer base.
However, I’m going to remain negative on this stock for two main reasons.
Firstly: the current £14m cash balance requires the company’s profitability to improve very quickly, or else additional shareholder support may be needed.
Remember that losses in 2021 and 2022 were greater than £20m each year. It may be turning the corner into profitability now, but it has little choice. And if the marketing budget needed to reduce further, in order to preserve cash, what repercussions would that have for growth? I just don’t think this cash balance is sufficient for shareholders to feel completely comfortable.
Secondly, on valuation. This is the company’s long-term goal:
…the Company is pursuing a market share of approximately 2% over the next 5-10 years (equivalent to about 1m Invested Customers, assuming an average pension pot size of £20,000-£25,000)
The revenue earned on those 1m invested customers is likely to be somewhere in the region of £150m (Pensionbee charges a fee of less than 1%).
Therefore, even in the best-case scenario where the company achieves its long-term goals, the revenue opportunity seems somewhat limited. If the market cap was (say) £60m I’d take a different view, but the market cap is closer to £160m!
So for me this company is both a little light on cash, given its ongoing spending needs, and its valuation is already pricing in quite a lot of success. So I’m continuing to give it the thumbs down.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
PPHE Hotel (LON:PPH)
Hi Graham
Thanks for your write-up. Some additional thoughts:
So net assets is actually closer to zero?
They've used this to highlight how relatively low their debt is.
But this seems misleading as I have looked at the balance sheet and have no idea where this £2.4b figure comes from.
I don't hold and I am wondering if I am missing a possible opportunity here given your favourable review. It's certainly one to keep an eye on as I do like the sector and there seems to be an exciting pipeline of openings on the way.
A
£PPHE
Hi abtan! Thanks for the comment. I agree that the debt will almost certainly need to be refinanced.
Regarding where the NAV comes from, it's to do with the "revaluation of owned properties in operation", which has not gone onto the balance sheet.
Look for the section in the results called "EPRA performance measures". On the basis of independent valuations (most recently carried out in December 2022), their owned properties are worth an additional c. £750m as compared with their balance sheet values. Hope that makes sense.
Cheers, G.
PPHE Hotel (LON:PPH)
Hi Graham
Thanks very much for taking the time to respond.
I didn't realise that the revaluation didn't go on the balance sheet. In fact I remember specifically looked for a revaluation reserve, couldn't see it, and then moved on.
If that £25 per share NAV figure is correct, then there is serious value on offer here.
I wonder why (my own calculation) of cash generation is so low relative to NAV?
[For reference I only accounted for maintenance Capex when I worked out free cash flow, and didn't account for the significant amounts spent on new hotels being built right now.]
It will be interested to see whether the NAV remains so high relative to the share price at the next valuation.
Thanks again
Abs
Somero Enterprises (LON:SOM) (no position)
I just read through today's report and noticed the lack of any meaningful interest income.
Where is it?
"Cash includes cash on hand, cash in banks, and temporary investments with a maturity of three months or less when purchased."
It's an odd one and makes me wary.
A
I am just amazed that people wonder why the City of London is losing credibility in the world. Sondrel are a fantastic example of the duplicity, stupidity and greed inherent. Float October 22 mentioning semi conductor (oh must be good then!) lots of prospects (brilliant) loads of opportunity (great!!). Less than a year later a profits warning on this scale. I gave up investing in IPOs years ago recognising that you only list on UK markets now if its a sh&tshow. Sorry to be so down about but it is so depressing and I don't think people do hit brokers or markets enough for devaluing one of our main income providers in this country. Still keep devaluing it on this scale and we can always fall back on our resources (oh!) well we have some fantastic multi national businesses (didn't we sell those to someone)............oh, well perhaps we could bottle fresh air then.
Turkish stock exchange has raised more money this year then the London Stock exchange.
Food for thought………….
I have been thinking of putting a message for a few days now about how much I appreciate Paul & Grahams comments here, and also I really enjoy the podcast. So today is the trigger day - thanks very much for your efforts, keep it up. So much on this SCVR is a reminder to me that dilligence and patience is the name of the game. Cheers guys (and gals) !
Thanks cheeky_minnows, much appreciated! :-)
Anyone following ASOS (LON:ASC)? Short squeeze after BestSeller upped its stake? Mike Ashley also on the books. 5.35% short last time I looked.
ASOS (LON:ASC) up over 11% today. I see Ashley has upped his stake inBoohoo (LON:BOO)
WANdisco (LON:WAND) name change to Cirata. As if that's going to make much difference!!
Almost rhymes with - disaster.
So two disasters doing some 'reputation management' today: also Omega Diagnostics.
Two all-time classics are Windscale to Sellafield and Stalingrad to Volgograd.
I see Jefferies have cut CMC Markets (LON:CMCX) to 'underperform, (hold) with a target price of 80p ....down from 190p
Shares have fallen from 250p in March to 108p today. So they wait until FTSE 250 demotion is confirmed to reduce their 'target price'
Jefferies are so far behind the curve they probably think the millennium bug is a thing.
I've never understood why brokers have a hold and a target price below the current price. Surely with a TP below the current price would be a sell and a TP above the current price would be a buy or a hold?
Well exactly, they were 'hold' in March. Their target price is now 58% lower but it's still hold. Are they allergic to the word sell.
I mean if all they do is reduce their target price on a poor update, wait for the next one and reduce again then I'll do it for £20 a company.
It could be, and I don't know if it applies in this case, that the broker is corporate broker for that company. In which case it is politically impossible to put out a Sell recommendation. A TP materially below the current one is a subtle way of saying Sell.
Yes, "hold" in broker notes actually means sell.
CMC Markets (LON:CMCX)
I see Jefferies have cut CMC Markets (LON:CMCX) to 'underperform, (hold) with a target price of 80p ....down from 190p
wow - is something up here possibly? - that seems like a semi ridiculous price target presuming company is still making profits and the price target is above the tangible book value of assets (as per last weeks comments). Wander what their beef is here with the company ?
I guess the only thing that makes sense is that if clients trade on leverage and high interest rates are in play then does that destroy their curent business model - i guess thats a posibility to some degree. Again per comments last week though it seem like they had £500 mill of clientys funds segragated - so that suggests not all stuff is highly leveraged ?. the good news about higher rates is they should be able to earn decent returns on liquid cash.
Does anyone have further details as to how and why this price target has ben arrived at.
My main worry with stuff like this would be unknown unkowns that someone knows unless we have it explained as to why this price makes sense. These concerns would probably be regulatory or problems with the numbers. I am probably going a bit ott here - if Jeffires think its worth 80p and are willing to say that fair play to them.
To be fair to Jeffries as Paul commented last week why didnt they give us more info ref exepcted bottom line numbers the lack of part of the picture on the update (that they will deffo have expectations on) was particulalry unhelpful.
Brokers forecasts after results make me laugh. Company doing well raise them. Company doing badly drop them. Accurate broker comment a few weeks before results would be better
I'm surprised no one has picked up on Inspiration Healthcare (LON:IHC) trading update and how they don't mention any profit figure in it. In fact they mention an improvement in margins. You would have to have access to their broker Cenkos' note to see a significant downgrade of 30%+ at the PBT level.
Management that do this really wind me up. Do they think retail investors are dumb?
Yes is the short answer.
Looks like Paul's gamble on Plexus Holdings (LON:POS) has paid off - up to 10p!
I did some research after Paul’s excellent weekend podcast and my take on the Plexus Holdings (LON:POS) bull case is:
The bear case is more difficult with lots of unknown knowns, not least of which are single product specialization and concentrated shareholder risk. It’s still cheap though (sub £10M Mrk Cap) and 10 years ago did have good form, so there were enough positives for me to take a small punt on this outside bet on Monday morning.
10p doesn't even begin to interest me re Plexus Holdings (LON:POS) !
I guess it's seemingly daft but why do I always think of the other 'acronym' whenever I see the Plexus Holdings (LON:POS) ticker, equally (probably) daft it makes me avoid it as I can't believe they were ever daft enough to use that as their ticker. End of rant.
I can only think of “point of sale”, is that what you mean?
I think you’ll find Paul refers to Plexus Holdings (LON:POS) ticker, on his fantastic weekend Podcast, as a piece of sh*te!!
Sondrel (SND) a fabless semiconductor company specialising in high end, complex Application Specific Integrated Circuits (ASICs) and System on Chips (SoCs). We provide a full turnkey service in the design, prototyping, testing, packaging and production of ASICs.
A fairly new IPO
Seems to be in right place at right time however they were expected to loss £0.5m now brokers have increased the losses to £6.4m after horrible update, they were expecting £28m revenue this year, not not less than £13m due to 3 contracts being pushed back to next year. The work is very lumpy, revenues are dependent on the success of the product they are being built into I understand so for each piece of work the overall revenues will vary significantly.
The order book / pipeline is increasing (currently working with a Tier1 auto co) but their trading update has left the company on the edge looking at their Balance Sheet.
At Dec22 they had current assets (incl cash of £4.5m) of £15.8m offset with current liabilities of £15.0m, but still had £11m of longer term liabilities of which the main number was software licence liabilities due in instalments (there was £4.5m in the current liabilities). They appear to be having to pay c. £5m of software licences every year - not something you can avoid if the supplier can switch these off for non-payment.
With the broker expecting them to borrow £1.5m by year end but its not clear if they currently have that facility, unless they borrow more from a shareholder loan which they also have (£700k, due 2025).
SP down alot today, if they can avoid a equity raise, cover off their borrowing requirement with the bank, have some commercial success in early H1 2024 and get some money in from new or delayed contracts this could be a substantial winner / recovery stock.
Very high risk.
Sondrel (SND) a fabless semiconductor company specialising in high end, complex Application Specific Integrated Circuits (ASICs) and System on Chips (SoCs). We provide a full turnkey service in the design, prototyping, testing, packaging and production of ASICs.
A fairly new IPO
As someone that worked in the UK electronics industry his entire working life and spent the last 25 years working specifically in Intellectual property and semiconductor design, I'm absolutely staggered that I had never heard of this company until I saw it mentioned on Stockopedia!
I have just looked at the website, assuming I might have at least come across one of the executive team, and I have not. In fact the website CV's are incredibly vague and it's obvious none of the NED's have any relevant industry experience which I find a little odd. As you can probably imagine, the UK semiconductor industry is quite a small community compared to the US and so I'm pretty bemused that I have never even talked to a company that were using their services.
Either way, it's a terribly competitive industry they are in, not only in terms of direct competition from other ASIC design service companies, but also technology wise in that the market for custom ASICs has been shrinking for many years with the increasing predominance of large scale programmable SoC devices . If you had your cynical hat on, you'd likely say the IPO has been very well timed from that perspective - drinking at the last chance saloon, if you like.
All the best, Si
interesting comments simoan and you are a good example of why these boards are so valuable.
Any views on EnSilica (LON:ENSI) which dropped in sympathy today?
Any views on EnSilica (LON:ENSI) which dropped in sympathy today?
Likely only dropped because of the delay to projects announced by Sondrel. This is par for the course in the industry and could signal less commitment by customers to start the development of new products in the current climate. Alas, the likes of Sondrel and Ensilica are just one part of the value chain for the end product, and so will not always have good visibility of the ultimate clients project decisions.
I have at least heard of EnSilica and I am familiar with some members of their leadership team. However, I had not realised they had listed relatively recently either. At least they have some kind of moat because of their specialisation in mixed signal and RF designs, which I do not see with Sondrel.
Just to be clear, it's the business model that I dislike. I see no real reason for these companies to be listed and IMHO they will not make good long term investments. As I hope I made clear, I do not know anything about Sondrel and have never looked at their financials although I am not surprised by what Paul found in his section above.
All the best, Si
I very much wish that I had your insight before I dipped a toe into Sondrel (Holdings) (LON:SND) I have a small percentage of my portfolio in riskier long shots but I did not catch the dangers here. I am intrigued how almost £70 million of sales in the last five years goes through without being noticed by industry insiders. While it is not a large amount I would have thought it is , in the context of the UK, noticeable, at least to competitors who did not get this business.
I reviewed the Directors and Officers listed in the Annual Report, and did not feel that they raised any special flags, certainly they did not seem to come under the category of having previous form on AIM. Graham Curren, the founder (and 45% holder) started the company over 20 years ago so it is not a complete flash in the pan.
I very much wish that I had your insight before I dipped a toe into Sondrel (Holdings) (LON:SND) I have a small percentage of my portfolio in riskier long shots but I did not catch the dangers here. I am intrigued how almost £70 million of sales in the last five years goes through without being noticed by industry insiders.
It may seem that £70 million revenue in 5 years is a big number, but it's really not in terms of the semiconductor market. That is proper small fry! I'm not sure what kind of customer concentration they have but it's possible the vast majority of that revenue was generated from only a handful of customers.
I reviewed the Directors and Officers listed in the Annual Report, and did not feel that they raised any special flags, certainly they did not seem to come under the category of having previous form on AIM. Graham Curren, the founder (and 45% holder) started the company over 20 years ago so it is not a complete flash in the pan.
I never said it was a flash in the pan, just that I'd never come across the company for whatever reason. I'm sorry to say that IMHO the business model is deeply flawed and will not make a good long term investment. It's funny that the company was formed when it was, because I was doing chip design around the millennium and it was incredibly difficult to find any project work at all because the whole industry dried up - projects got delayed and then they got canned. Lots of companies disappeared and many good engineers were made redundant. I imagine Sondrel emerged from that environment. Who knows... maybe that is about to happen again given that clients have started to delay project starts? If I was still working I might have some insight into the current state of things but alas I am now happily retired and have better things to do :-)
All the best, Si
I can’t say I fully understand it but it does look like 137m shares will be issues at some stage. That’s about 13% dilution so not too bad if the sp can reach the broker target of 20p.
Personally I’d rather sit on the side until I see the broker notes come out. Everything looks good apart from profit, which is the most important thing. Surely the company was expecting the drop in profit? Or were they not expecting higher interest rates. This should be answered by the broker report. I’d certainly be interested in Paul’s view here.
The sp dipped on open but soon bounced on support. Not sure where the sp will go from here so happy to wait and see.
GMtrader.
"Everything looks good apart from profit, which is the most important thing."
I would generally agree with you that post tax profit or free cash flow are the most important things. But in the case of Gulf Marine Services (LON:GMS, I don't think they are that important at present. To me the key numbers in the short-term for Gulf Marine Services (LON:GMS) are EBITDA, net debt and the fixed asset value. Also look closely at the Going Concern statement.
The reason for this is the $299m of the term loan (outstanding as at June 2023) which dwarfs the c$100m market cap. This term loan has a maturity of June 2025 (as does the currently undrawn $15m working capital facility). This needs to be refinanced. The "correct" valuation for the share will not be known until we know on what terms this term loan can be refinanced. $40m of the term loan will be need to be repaid over of the next 12 months. So rather than worry too much what the current interest payments are, the key to valuing the stock IMHO is to guesstimate what future interest payments will be. If EBITDA can be maintained around the $80m level and if we assume that upcoming amortisation will bring the term loan down to below $240m, on 3x debt/EBITDA we could assume the future refinancing will be done at reasonable terms - particularly given the strong asset backing (the Self-Elevating Support Vessels). That is why I say also look at the asset value. Given the company's need to delever, CAPEX recently has been very low. Are the assets being maintained at a reasonable quality? I don't know the answer to this but at least at present they don't seem to have a problem in obtaining contracts at good day rates on these vessels.
Thanks for your post.
Gulf Marine Services (LON:GMS) seem to be reducing debt by about $21m per 6 months and is forecast to be to be $275m end of 2023 fy and £225m 2024fy. So it looks close whether they will have debt to 3x by time refinancing is needed. I also note that net interest is forecast higher for this year ($27.3m) and to drop in 2024 to $18.5m. Do you know if interest is fully fixed? It does look like interest rates have peaked or close to peaking but a lot may depend on whether it drops or stays high for a while.
The interest payments of Gulf Marine Services (LON:GMS) will drop next year because they will no longer be paying PIK payments of 2.5% (payable when leverage was above x 4 net debt/ebitda) and interest rate margin has also dropped from 4% to 3.1% above SOFR. This is because their repayment terms improve as leverage drops. I think they'll comfortably have net debt/ebitda below x 3 by time of refinancing in June 25, mainly because I believe ebitda will carry on increasing by 15-20 % a year, driven by structural bull market in offshore O & G services therefore driving a continued increase in day rates. It's also worth noting that the consortium of six Middle Eastern banks are quite accomodating to the co imo. They could quite easily have pulled the plug a long time ago but didn't. Most of the Gulf oil companies are state owned and I think these support vessels are quite strategic for the local O & G industry, they need these vessels operating in the Gulf.
Cheers Joe.
Zeus has now released brokers notes confirming interest rate will drop now that debt is at 3.75 and below the 4%. There is a slight increase to the forecast debt for 2023 and 2024 but not material. Day rates have increased to $30.3k per day from $27.5k and they expect this to rise in H2. Overall looks ok.
Anyone got any views on Rosslyn Data Technologies (LON:RDT) recent news please?
I note that last comments here were as part of Paul Hill's portfolio update in Jan.
Hi Roger,
We've never bothered with Rosslyn Data Technologies (LON:RDT) since last commenting here in Jan 2020, where I flagged the weak finances. Shares have been a disaster for investors, as you can see here -
It's one of many tiny companies that list on AIM, promising great things, but they nearly all disappoint. This one makes losses every year, and even the growth in revenues up to a peak of about £7m has since reversed, down to only about £3m now.
News yesterday and today, that it's got a refinancing away is actually quite impressive - in the current market, not many people seem willing to inject fresh funds into effectively failed companies. So RDT must have a half-decent story. Although I note that most of the money has come from EIS/VCT investors, where the taxpayer is giving them a large subsidy to have a punt -
Rosslyn (AIM: RDT), the provider of a leading cloud-based enterprise data analytics platform, is pleased to announce that, further to the announcement made on 30 August 2023 regarding the Fundraising and the Consolidation (the "Launch Announcement"), it has raised £3.3 million (before expenses) via the placing of 517,000,000 Placing Shares (comprising 97,203,765 General Placing Shares and 419,796,235 EIS/VCT Placing Shares) and the subscription for 23,000,000 Subscription Shares, both at the Issue Price of 0.5 pence per share, as well as the issue of £600,000 of Convertible Loan Notes.
So RDT lives to fight another day, by the looks of it!
Regards, Paul.
Your feelings regarding small AIM companies gets an emphatic reinforcement from today’s announcement from Sondrel (Holdings) (LON:SND) in which I have a small (and now much smaller) holding.
Thanks Paul. Yes, EIS and VCT investors are subsidised to have a punt, but the investment managers make most of their profit from generous performance fees. They are incentivised to find and back companies that don't go bump.
Revolution Beauty (LON:REVB) results released at a rather tardy 08:30
Temporarily caused all the MM to completely pull all their quotes- a nice gift from new management to investors!
https://www.voxmarkets.co.uk/r...
I have had a quick look at Somero Enterprises (LON:SOM, for old times sake as it still retains its position as my largest ever success and also, most money left on the table... make of that what you will. (No position).
I generally check the register for anything of interest and note that on the co. website Hargreaves Lansdown, Interactive and AJ Bell all appear. Therefore this stock is very well owned in private investor circles. Ditto here I guess.
On the face of it todays statement is fine, with a confirmation of the outlook. The balance sheet is fine and the stock is cheap, with a PE sub 10, of 6.7x according to Stocko. Technically though the shares are breaking down and exhibiting relative weakness.
Having followed the stock for over 10 years the most striking thing when looking through the numbers is how little things have changed. The co is still heavily reliant on large boom sales in the US. These fell overall, and significantly in the US in H1. Some of this was a technical issue with a new product line. A "slightly" better outcome is expected in H2. This may well be cautious, and the team factoring in a slow down that doesn't take hold. Hard to say really. For me, the reliance on the US market and the large boom sales in a market that has grown way beyond my expectations 10 years ago, would temper enthusiasm.
Having said that....if they meet expectations in H2...they will have weathered a downturn in sales... and should a recession bite in H124... maybe a similar outcome..."could" result in a sales and profit outcome similar to 2020. Is this a fair downside case....maybe? The credit crisis collapse in large unit sales to zero feels an extreme we won't see again. (But shows how cyclical this revenue line can be). So maybe 33p of earnings is useful downside case. AND as the shares fall below 10x this number value would appear to be there but with a potentially difficult 2024 to come.
Feels like this one could get very interesting to buy next year... if bad news comes out.... and the outlook for 2025 feels better. Lots of ifs and buts etc but I will stay patient before buying. On the watch list though.
Somero Enterprises (LON:SOM)
Great summary RDHOWARTH - i think you have summed up the company ina nutsheet. Being honest they have had sucha purple patch in the us one should probably have expected there would have a been a bit of froth which is kinda happening albeit they seem reasonably confident (kinda makes sense that rate of new large warehouse builds and the like would have peakeed by now)
main plus points is overseas doing great - to be honest thats from such a small base that it kinda covers over teh cracks - good to see them doing well outside us.
Ref reliance on large boom sales - yes i think Somero doesnt really deserve much a premium for this reason - they have done great recently before slowdown but i ssupect thats more market related than having success is new areas. Its not that they arent trying and its not that new items are a complete disaster just no decent evidence they are the same cash cow as core offering . I am not even mentioning lfl competition they still have.
To me happy to hold solid dependable company i picked up previously when rating was low. I probably shoudl have sold at the peek (did actually sell one day for them to have a great trading update within 24 hours an dbought back at same price)
One last point ref overall update today - i guess its good news the ship has steadied at present and that things are not worsening AGAIN.
Great points from RDHOWARTH and rmillaree re. Somero Enterprises (LON:SOM) . I can't disagree. It was one of the first shares I bought when I started my stocko subscription in 2017 and I've done reasonably well with it, even managing to sell out at over £4.50 back in August last year. I dipped my toe back in prematurely in June and even at today's lowly price there may yet be better buying opportunities in the cycle.
It's true that very little has changed since 2017 - the China experiment has failed dismally, the promise of Sky Screed has been a whimper and so we're left with the large boom screed doing pretty much all of the heavy lifting in terms of revenue. It does leave Somero looking like a bit of a one trick pony with product concentration risk although the valuation does price that in somewhat.
On the plus side, overseas growth is starting to look meaningful and presumably there could be a pretty large addressable market in their target areas of Europe (US$ 7.0m +46%) and Australia (US$ 5.3m +33%).
US revenue was US$ 42.2m (-24%) but I'm cautiously optimistic that the commentary around project backlogs, production delays and the potential from government stimulus in the form of the CHIPS act may give rise to some upside surprise at the finals.
Given the carnage in Ukraine and the knock on effects across Europe, it was pretty encouraging to see European sales growing so healthily - is it unreasonable to think that sales here might eventually represent half of US revenue?
Australia appears to be growing well enough to perhaps support some meaningful geographic diversification for the company.
The 8% dividend yield makes for an easier holding and the balance sheet looks healthy enough to see them through the much anticipated recession.
How you view today's interims very much depend on one's opinion of half filled glasses but to my mind, the valuation has most of the risks priced in and perhaps the CHIPS act / onshoring narrative combined with geographic growth could provide some surprise upside from this level.
Apologies I made the school boy error ... its 33c...which makes more sense... so more like 25p ....which tallies with an arbitrary entry point around 200. We see.
Sizeable director buying at Flowtech Fluidpower (LON:FLO). In total 475,000 at 82.6p shared among 3 directors. It would have been good to see the new CEO buy few more than 60,000, still the Chairman bought 300,000 taking his holding to over 1 million. Hopefully this marks a turning point in the share price.
I hold so a little whimsical speculation.
Been keeping my eye on Flowtech Fluidpower (LON:FLO) (I don't hold) through the years, noticed the big director buys this morning , interesting but they also bought a load a couple of years ago at £1. For me it's going to take more than director buys to get me drooling and of course I may miss the boat in the meantime. But yes, interesting if they get their act together
Isn't it new directors? Didn't Christopher Mills and co. boot out the old directors recently and bring in turnaround team or do I have that wrong?
Gulf Marine Services (LON:GMS) it will be interesting to see the broker notes on this company when they come out. Revenues and EBITDA up while actual profit is down 34% due to costs of loans. Second half of year should be better still and reduced debt seems to be on target or slightly ahead. I no longer hold because of debt level and lower PAT.
I'm not convinced I understand this bit:
"As described in the 2022 Annual Report, as the Group elected not to raise US$ 50.0 million of equity by the end of 2022, it issued on 2 January 2023 87.6 million warrants giving potential rights to 137 million shares if exercised, as per the terms of its agreement with the Lenders. The strike price was determined by an external Calculation Agent to be at 5.75 pence per share."
Does that mean that at some random point in the future 137 million shares might be issued at 5.75p - if so that's quite a dampener on the SP. It would also be interesting to get some clarity on the interest rates they're paying - are they likely to go up or down from here, as with their debt pile that will make a material difference.
Fishcake
My understanding is the same as yours on Gulf Marine Services (LON:GMS) . There will be 137m additional shares if/when the warrant holders exercise - so you need to take account of this. The history behind the warrants is long. The was a big battle a few years ago as the company's management negotiated with the banks about the huge debt (net debt in 2020 was $408m vs only $50m of EBITDA). An agreement was vetoed by the shareholders - new management came in and renegotiated the terms with the banks. There has been a fair amount of dilution - but shareholders have not been wiped out.
I think the interim report gives quite a bit of detail on the interest payments. A lot will depend on what happens with floating rates (anyone's guess). But now net debt is below 4xEBITDA, there should be no more PIK payments on the loans (were running at 2.5%pa), the margin on the loans should come down from 4% to 3.1% and the interest on quantum on outstanding debt is steadily coming down too.
My morning smallcap tweet: Three warnings to choke on
Omega Diagnostics (LON:ODX) Inspiration Healthcare (LON:IHC) Crossword Cybersecurity (LON:CCS) Eneraqua Technologies (LON:ETP) Sondrel (Holdings) (LON:SND) Carclo (LON:CAR) essensys (LON:ESYS) Ovoca Bio (LON:OVB) Myanmar Investments International (LON:MIL) Infrastructure India (LON:IIP) Gulf Marine Services (LON:GMS) ImmuPharma (LON:IMM), Somero Enterprises (LON:SOM)
◄Omega Diagnostics (ODX)► proposes name change to Cambridge Nutritional Sciences. Also 61 to 1 consolidation. Why a prime number? [SP=2.2 Cap=5m]
◄Inspiration Healthcare (IHC)► guides H1-July rev flat. Blames delays to regulatory approval for certain new distributed products and de-stocking. Gross margin 48% up 400bps. "Whilst disappointed in first half revenues, we are reporting margins returning towards our expected levels and improved cash generation, which have combined to reduce net debt and put the Group in a stronger financial position. We are focussed on reshaping the business and are confident in returning to growth in the second half." [SP=48.9 Cap=33m]
◄Crossword Cybersecurity (CCS)► guides H1-June rev £1.9m up 27%. Expects FY rev in line. Guides Fy24 rev up 30% and EBITDA and cash breakeven on a monthly basis in FY24H2. Agrees £2m death spiral. At least there's a 6.5p conversion floor. [SP=6 Cap=6m]
◄Eneraqua Technologies (ETP)► guides H1 in line but warns FY EBITDA materially below market expectations of £8.8m. Blames proposed changes to net nutrient neutrality rules causing clients to to delay all or a large majority of relevant work leading to a £2m EBITDA hit. [SP=95 Cap=32m]. I hold.
◄Sondrel (SND)► guides H1 rev up 17% and adj EBITDA of £0.4m. But development and production for three major ASIC customers due to commence in H2 2023 have been delayed by 6-12 months due to increasing inflation and weakening demand in end markets. Guides FY rev only £13m+, substantially below current market expectations. [SP=54 Cap=47m]
◄Carclo (CAR)► mixed trading update with no overall guidance apart from "focus on cash conversion and margin improvement, rather than just sales growth, is beginning to reflect positively on our balance sheet". [SP=12.65 Cap=9m]
◄essensys (ESYS)► guides FY-July rev up 9% - 'resilient'. adj EBITDA loss and cash in line with market expectations. [SP=28.25 Cap=18m]
◄Ovoca Bio (OVB)► Phase II dose ranging study for Orenetide Female Sexual Function drug is a flop. Will evaluate strategy regarding the development of Orenetid . [SP=14.08 Cap=12m]
◄Myanmar Investments International (MIL)► proposed sale of MFIL to Thitikorn is off. WIll continue to explore other exit options, including with Thitikorn. "MFIL has been restructuring its own financial affairs and is close to repaying its creditors which should then leave it debt free within the next few months." SP has fallen almost non-stop for 7 years. [SP=0.05 Cap=2m]
◄Infrastructure India (IIP)► extension to the maturity dates of all its debt facilities by 2 months to Oct 31. [SP=0.22 Cap=2m]
◄Gulf Marine Services (GMS)► H1-June. Hikes FY EBITDA guidance to $77-85m up $2m. [SP=7.86 Cap=81m]. I hold.
◄ImmuPharma (IMM)► £1.35m subscription and £0.5m retail offer at 2p, a 17% discount, to keep the Bunsen burners on. [SP=2.31 Cap=8m]
In line: SOM
What are your thoughts on Eneraqua Technologies (LON:ETP) ? I'm actually tempted to buy some back at this price, but the problem is Management, I think they have pretty much lost all credibility now and can't be trusted
Hi Paul and other holders of XP Factory (LON:XPF),
I stumbled upon the Oxford Street Boom Battle Bar last night (c. 10.30pm) and popped in out of curiosity. Moderately busy, with a youngish crowd. Most of the gaming activities being used. Quite a good buzz, but would have been interesting to have seen how busy it was earlier.
I'm a significant holder.
Sounds okay for 2230 on a wednesday
Re XP Factory (LON:XPF) my son was in the area a couple of weeks back so dropped in to have a look. Around 21.30 I think on a Monday evening. Reasonably busy with circa 40 people there. I thought that was pretty good for a Monday evening in August, so bought some shares on the back of it. So did he...
Nice observation of a snap trading view
"Reasonably busy with circa 40 people"
As MrContrarian would say "Compared to forecast" ? (20? 100?)
Personally not a metric that on its own would make me push the buy button
My son went to the Ipswich one a few weeks bag and it was heaving on a week day. Not much else to do in town, spoke to staff and they mentioned when the weather is rubbish they seem to do well. going by that metric the UK is the place for them to be :)
Hi The Jayman,
Re XP Factory (LON:XPF) (I hold).
Yes, the London Oxford Street (very central, large basement site on c.£500k pa rent) is a goldmine I understand - doing very good business (multi-million revenues pa), throughout the whole week. I've visited many times, and it's always busy. Lots of corporate bookings, as offices in central London want experiential leisure for team-building purposes, to re-integrate staff who've been reluctant to come back into the office after WFH (work from home).
Experiential leisure is a booming (geddit?!) area, and must be eating the lunch and drinking the cocktails of other vanilla type bars. This realisation is what finally convinced me to cut the cord with Revolution Bars (LON:RBG) and sell out recently. If they've lost say 10% of their customers to the proliferation of experiential leisure operators, then on 75% gross margins and largely fixed costs, it's hideous for the bottom line.
Mgt at XPF are really talented I think, and pulled off a remarkable new site opening programme in late 2022, bagging superb deals from landlords for empty sites where landlords were typically giving them £500k cash to mostly fund the c.£800k per site capex. XPF couldn't have dreamed of securing sites like these, on such attractive terms, at any other time.
I think it should do really well, and is already nicely cash generative on annualised basis (not historic, as most of the sites weren't open in 2022 or previously). There's also a site in Dubai, and other overseas locations, which I think are run by franchisees.
With macro being what it is, I don't suppose the shares are likely to do much in the short term though, so more a patient investment than a trade.
Obviously as I own XPF personally, I take a positive view of the bull:bear discussion. I think bears focus on the wrong thing - historic numbers, which are not relevant due to the very rapid new site expansion more recently. I'm not buying the past, I'm buying the present, and the future.
Regards, Paul.
Paul,
Any idea why XP Factory (LON:XPF) just seems to be selling down every day? Just macro/recession risks or misunderstood or a big seller in the market?
Thanks,
Paul
there are some large holders that have stop losses in play, so when they kick in the price takes a beating
I've just booked in at the Liverpool site for a mate's stag do I'm organising in a couple of weeks, the staff member I've been dealing with has been very helpful, I'll report back in due course!
Alfa Financial Software Holdings (LON:ALFA) has decent trading update today. A good divi payer too
Financial highlights
-- Revenue up 21% versus H1 2022, 18% at constant currency -- Subscription revenues up 14%, supported by hosting up 33% -- Software revenues up 33% driven by high customer funded development in the half -- Services up 21% with increased headcount and strong chargeability -- Operating profit up 19% on H1 2022 as the business maintains investment in the future -- Continued strong cash generation at 140% -- Robust balance sheet position with GBP26.3m of cash and no bank debt -- Special dividend of 4.0 pence per share (GBP11.8m) declaredCarclo (LON:CAR) todays Trading Update may be a “harmonious blend” but without a single financial number or comment on meeting/missing/beating expectations we’re left in the dark
*I am currently away on holiday so my brain may be addled but even so it’s a poor TU
"harmonious blend of efficiency and flexibility" is a new one on me AG
Don't know why but it was giving off Spanish Inquisition vibes to me
"Our chief weapon is surprise... surprise and fear... fear and surprise... Our two weapons are fear and surprise... and ruthless efficiency.... Our three weapons are fear, and surprise, and ruthless efficiency... and an almost fanatical devotion to the Pope...
NO - body expects the Spanish inquisition!
Pensionbee (LON:PBEE) - Profitability in sight with investor interest building (new research report out now: https://www.equitydevelopment....)
Interims to 30th June 2023 show invested customers reaching 211k, with 28k added over H1-23 (+15%) and 52k y-o-y (+33%). Assets Under Administration was up £678m over H1 (+22% over 6m, +38% y-o-y), reaching £3.7bn, with £469m added from net client inflows and £210m from investment performance.
Encouragingly, increasing brand awareness and sophisticated data-driven marketing has resulted in ‘cumulative cost per invested customer’ continuing to decline (H1-22: £260; H1-23: £247). This has, in turn, resulted in strong growth continuing but with lower marketing spend (£12m spend in H1-22 v £7m in H1-23 whilst gross inflows were up 6%).
Revenue grew 32% to £10.9m (H1-22: £8.3m) with adjusted EBITDA trajectory (H1-22: -£14.9m; H1-23: -£7.9m) continuing on track to be positive in FY24, a target set at the 2021 IPO. Operational leverage continues with invested customers per staff member increasing from 919 in H1-22 to 1,026 in H1-23. Net cash remains solid at £14m with no new cash raising envisaged.
Investor interest in PBEE shares has continued to ramp up (see front page graph), and our fundamental valuation remains 150p per share.
Negative "adjusted EBITDA"?
Pensionbee (LON:PBEE)
Equity Development
Profitability in sight
Are you talking about EBITDA profitability in sight - lets get real here EBITSA profitability MUST always be flagged as such if you are not wanting to mislead others. Short shrifty should be given to anyone here arguing that EBITDA profitability is profitability - it aint - its just a measure of how a company delivers a specific number IGNORING lots of the expenses ! - so nowt to do with profits in the real world despite the fact in includes the dreaded word.
Note to be fair to your article you mention EBITDA later - but if we are only talking about EBITDA (i did check and this seems to be the case !) - then please make clear in future cheers.
Pensionbee (LON:PBEE)
It seems positive to me that this company is trenming nicely towards EBITDA profitability we all(?) know thats well short of real world profits though.
I am assuming they could potentially have a fantastic business model here - customers should generally be sticky - so even if they dont grow customer base much or at all (95% retention rate) i would expect they earn more as peeps pensions mature (we are so in early days auto enrolment i have to presume this will be the case for the next 15-20 years plus?
As a mostly automated platform too i would expect operatiuonal gearing would be super fantastic - in some respects i would expect most hassles are on the onboarding stage (stakeholder and employer questions) - so as long as accounts are conseravtively done i would hope that they could be well placed to improve cashflow reasonably easy as teh signijng up hassles are upfornt and the packback extremely long term.
I would also guess they have invested heavily to grow the brand name - on their low turnover we should expect that makes bottom line numbers look pants.
There could be executional risk i guess here if they ever mess up in regulatory sense or get beaten by lower cost competitor
Whats the company worth and should i invest ?
At £155 market cap - its priced waaay ahead of any where it should be based on sensible near term calcs - this company is obviously to me about the long term though.
I am minded to simply sit on the sidelines for now but one cant argue with that revenue growth trajectory isnt promising (hmmmm what do they have pencilled in for 2025?)
sales
6 - 12 18 -24E (2023)- 34E(2024) mill thats some very decent annualised growth
Based on those numbers hopefully cash burn can reduce dramtically as they hit critical mass. Note cash has halved from 29mill to 14 mill 12 month previously. Note h1 sales are only 11 mill - and next year we have 17 mill pencilled for half a year each (even split) in so 12 mill+ of extra revenue pa (compared to most recent 12 months) should help cashflow massively - advertising can also be dialled back in guess. Will they need to raise money with only £14 mill left now - i know not but looks like at least the extra revenue would give me confidence this may be possible.
Would be interested on some thoughts of Graeme or Paul or anyone else who has a "proper" insight of the business or business model - i havent really dived very deep into this one yet but it does seem like some decent potential here - if they continue to hit targets.
In some respects this seems a very "simple" business model to my untrained eye and they should be able to model the future pretty easily as long as they are realistic with their projections. Looks like projections have slightly improved over thr last 12 months which gives me comfort - what we need with company like this is proper realistic guidance - trying to remember the name of the fast growing phone company that always promised but all extra salss got eaten up in non discretionary costs (and more)and invariably sales never grew as fast as they promised. Hopefully none of that here albeit nowadays i try to stay away from story stocks mostly !!
Eneraqua Technologies (LON:ETP) Half year TU
“ As a result of this hiatus the Board now expects that the outturn EBITDA for FY24 will be materially below current market expectations.”
Relieved to have sold after the first PW in May!
Eneraqua Technologies (LON:ETP) As you say looks a terrible update. EPS cut 30% + 24%