Small Cap Value Report (Thu 31 Oct 2019) - CPR, FOXT, PHD

Good morning, it's Paul here.
This report is earlier & shorter than Mon-Wed reports. That's because I'm flying out to Malta at lunchtime, for a cheap, end of season break. Am taking my laptop with me, so I'll write Friday's report as usual, just from abroad.
Estimated time of completion: 10 am. Update at 09:29 - today's report is now finished. I managed to cover everything of interest, as there's not much small caps trading/results news today.
Agenda - it's a quiet day for news, thank goodness;
Carpetright (LON:CPR) - possible offer
Foxtons (LON:FOXT) - trading statement
Proactis Holdings (LON:PHD) - results
.
.
Carpetright (LON:CPR)
Share price: 9.12p (pre market open)
No. shares: 303.8m
Market cap: £27.7m
Refinancing, possible offer, and trading update
This carpet retailer did a CVA, to dispose of its problem leases, and has been propped up financially for some time by its major shareholders Meditor European Master Fund. Without Meditor's large financial support, Carpetright would have almost certainly gone bust. Note that Meditor bailed out the banks, by buying them out in Aug 2019. It's obvious now that Meditor made a bad mistake supporting Carpetright - a classic investing error of repeatedly throwing good money after bad. I know that feeling well, albeit on a rather smaller scale!
Funding requirement - today's announcement says that Carpetright needs £80m in funding;
The Board believes that approximately £80 million is needed for the Company to (i) repay the Debt Facilities; (ii) meet the Company's ongoing working capital requirements; and (iii) provide the Company with the necessary growth capital to execute its strategy as set out below.
Funding options - the company has explored other funding options, but it sounds as if Meditor is the only game in town.
Possible offer - Meditor has sounded out other institutional shareholders, to see if they would accept a 5p cash offer for the whole company. This makes sense, as Carpetright is totally reliant on Meditor's existing financial backing, that they might as well buy the whole lot. The intention is then to convert debt into equity, and presumably lick their wounds in private, rather than on the public market.
Indications of support for a 5p bid have been received from holders of 24.0% of the shares, plus Meditor's existing c.30% holding, means that they're already more than half way there. It's not a firm offer yet. I suppose that the alternative would be to withdraw lending facilities, making Carpetright insolvent, and then do a pre-pack administration, which would wipe out other shareholders. Cheaper, but more disruptive, than the 5p offer.
Strategic update - largely irrelevant to investors, as they're about to be bought out at 5p. This section of the announcement is more for the press, and to reassure other stakeholders (staff & suppliers in particular).
Trading update - again, this doesn't really matter to shareholders now, but here it is anyway;
The Board believes that Carpetright is performing well despite the challenging economic backdrop and intense sector competition. Group profitability is improving as the Company drives store efficiency and reduces the central cost base.
.
Supplier terms is a key point for people to consider at the moment, with all struggling companies. When companies do go bust, it's often because suppliers have lost confidence in getting paid, often at the behest of credit insurers removing cover. Investors tend to overlook this crucial point, and focus too much on bank debt. The trouble is we're rarely given any information about the attitude of trade credit insurers.
Whilst management of supplier terms has been challenging, the Company continues to work well with partners in its supply chain and expects this to yield an improved position moving forward.
Expanding on this point, when I spoke to management at Sosandar, they indicated that one of several reasons for their recent £7m placing, was that new suppliers are very nervous about UK retail. Many of these factories have been hit with bad debts from UK retailers going bust. Hence they are now reluctant to extend credit. This puts many, even large, UK retailers in a potentially precarious position. I reckon it's likely to be absolute carnage after Xmas, with lots of retailers going bust. Hence why it's so important to not go near anything in this sector with a weak balance sheet, that relies on credit from the bank & suppliers.
My opinion - Carpetright shareholders have no negotiating power whatsoever, against the major shareholder which is financially supporting the whole company with loans.
Therefore, the only sensible option is to accept the 5p bid with gratitude. The alternative is 0p in a pre-pack administration, so the 5p possible offer should be seen as generous. There's little chance of a competing bid, since Meditor would want its debt repaid before shareholders get anything.
If you can get more than 5p in the market, then I'd be inclined to bite the buyer's hand off!
This is a good reminder that takeover bids do not necessarily happen at a premium. Especially where a company is financially distressed.
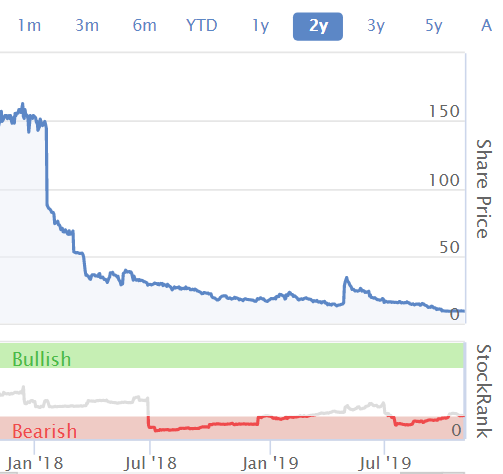
Another stunningly quick retail collapse;
.
.
.
Foxtons (LON:FOXT)
Share price: 63p (down about 5% at 08:04)
No. shares: 275.1m
Market cap: £173.3m
Foxtons plc (LSE: FOXT), London's leading estate agency, today issues its trading update for the third quarter ended 30 September 2019.
The share price has exhibited a strong recent bounce (up from 50p to 70p), which is wilting somewhat in early trades today.
This is a rather annoying update, as it fails to give the crucial information as to whether or not trading is above, in line, or below expectations. That must be explicitly stated in every trading update from every company. Dodging that issue just creates uncertainty, and increases the risk that a profit warning might be in the pipeline.
Directorspeak - this bit doesn't exactly fill me with confidence;
Overall, this was a resilient performance set against the London sales market which continues to deteriorate and the impact of the tenant fee ban on our lettings business...
.
Revenues are still dropping -
Group revenue for the third quarter was down 7% to £32.5m (Q3 2018: £35.1m). This takes Group revenue for the first nine months of the year to £83.6m, down 5% on the prior year (2018: £88.1m).
.
Stamp Duty - nothing is said on this today. Some investors are hoping that the punitive rates of Stamp Duty, stupidly introduced by George Osborne, which killed the top end property market stone dead, might be reduced soon. That would be a clear benefit to Foxtons, as it might kick-start the London market.
Letting fees ban - came into effect on 1 June 2019. Foxtons has decided to absorb this loss of income (not increasing fees to landlords), in order to grow market share by having a more competitive offering. Q3 lettings income is only down 4%, so looks like this is not a major issue.
My opinion - at some point, this share could be worth buying. I just don't know when, unfortunately. It feels to soon to anticipate a recovery in the London property market, so I'm keeping this on my watchlist, rather than diving in.
.
.
Proactis Holdings (LON:PHD)
Share price: 56.5p
No. shares: 95.5m
Market cap: £54.0m
Proactis Holdings PLC, the business spend management solution provider, today announces its audited results for the financial year ended 31 July 2019.
Rather poor results here. Adjusted EPS is down from 10.6p last year, to 6.6p this year.
I don't completely trust the accounting here, which seems a bit aggressive.
Management previously went on an acquisition spree, which has not worked out well - there's a whacking great £27m impairment of goodwill charge in today's figures.
Balance sheet is horrendous, although being a software company, it doesn't need much in the way of fixed assets. Even so, a current ratio of 0.73, and a ton of debt in long-term creditors, make this uninvestable for me.
Cashflow - operating cashflow looks good, at £14.2m this year, and £9.7m last year. However, it's capitalising £7.6m of development spend. When you take off other normal cash outflows like tax & interest cost, most of the positive cashflow is used up. Therefore in the real world, I do not see this as a particularly cash generative business.
Sale process - Proactis is up for sale, with apparently "a number" of expressions of interest. 3 months ago it announced;
...it has received a preliminary unsolicited approach from a US-based investor with regard to an offer for the Company and a number of preliminary unsolicited expressions of interest from other parties...
I think something would have happened by now, if the approaches were serious, and at a high potential premium. But you never know. Generally speaking though, the longer things drag on, the less likely a good deal is. Brexit delays might complicate things though, as I can see why bidders might want to hold back, for more certainty on that issue.
Operational problems - as previously reported, there was management change, and an exodus of customers a little while ago. I don't like that.
My opinion - I wouldn't touch this personally. I've focused on the negatives, which for me make it uninvestable. I suppose the positives should also be mentioned - mainly that it has a good client list, and lots of recurring revenues. For me, the excessive debt, and very weak balance sheet make it too risky.
.
.
I can't see anything else of interest in the small caps space today, so will leave it there.
Once I arrive in Malta later today, I'll get my laptop rigged up on the wifi, and will have a look at your comments. If there are any interesting small cap company results or trading updates, then by all means leave a comment here, and if it's quiet tomorrow (which is usually the case on Fridays) then I might be tempted to write a section on it tomorrow.
As always, when putting in a request, tell me why it's interesting. I don't want to write about boring companies just because a reader happens to have a shareholding in it! We're trying to find the little nuggets of gold that are buried out there! And to avoid all the junk that is littered throughout AIM. I do sometimes despair at the low quality rubbish that gets floated on AIM. Surely all these brokers & company promoters can find something decent out there?
There must be thousands of decent UK companies which could benefit from a stock market listing. Instead the brokers tend to float speculative dross that usually ends up disappointing investors. If brokers carry on in this vein, they'll kill the golden goose. Time for a re-think at some of these brokerages, I reckon. They should stop chasing short term personal gain, and instead think about building a more sustainable small caps market, with higher quality companies, delighting & enriching shareholders, instead of trying to fleece us.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Paul, any chance you could swing back at NXT as you mentioned yesterday?
Broker/Banks - fees being paid in company shares being floated would concentrate their minds. With a lock up of 5 years before they could dump shares. I expect we wouldn't get any takers. However, it would clean up the listings. :o)
really jealous Paul. On this day in 1983, I was having a seaside picnic at Meliha Bay for my sons 10th birthday. I worked in Valetta for 6 weeks. Fascinating country lots of history if that interests you.
Mind the traffic, they drive on the sunny side of the street and go around roundabouts whichever way is quicker. I believe the word anarchic is derived from the Maltese word for normal.
Foxtons (LON:FOXT) - impact of the tenant fee ban on our lettings business... - I find it unbelievable how a clear as day scam is such an integral part of their business plan.
By long established tradition nobody except me seems to take the slightest notice of Orchard Funding (LON:ORCH) which reported today. ( I accept that as a finance stock it is not covered by Paul and Graham’s remit)
Being a “steady eddie” type of stock with gentle growth and a 4% yield for the patient it may not attract those in need of a fizzy micro cap.
But I like it, it is in a large and growing market ( financing insurance premiums and professional fees) has a long track record of sound lending policy and a straightforward reporting style with no “EBITDA” in sight. Companies that address Profit after Tax without any ifs and buts are rarer than they should be.
They’re on again with a banking licence application and, sensibly, are not committing to a date, but it should help bring funding costs down. With a market cap of £16million, a p/e of 12 and an eps growth of 18% not much has to go right for me to be joined by other interested parties (I hope). Zero trades so far today!
Thanks for pointing Orchard Funding (LON:ORCH) out here. I had a quick look and certainly think they look interesting. However, I couldn't get passed the fact that in their last annual report the CEO earns a basic salary of £250,000 and the board costs in total over £400K. That's nearly a quarter of the total profit after tax (£1.63m). So I wonder, for who's benefit do they exist?
By contrast, Mike Creedon at Scientific Digital Imaging (LON:SDI) earns a basic salary of £146,000.
cheers
Francis
On the face of it I would agree that the Ravi and the Board take a bunch of money at Orchard Funding (LON:ORCH) but I look at it slightly differently.
Rightly or wrongly City salaries do not show that £250k is outrageously out of line for a CEO and entrepreneur of a successful enterprise. I am sure that Ravi is also entirely aware that with 54% of the company his shareholding is going to be the decider of his wealth.
Over at Scientific Digital Imaging (LON:SDI) (which I am also happy to hold) Mike Creedon is now up to £205k and in addition upping his share options from 1.385mm to 1.872mm
So I like both companies: the one that produces £1.6mm from 18 employees and the one that produces £1.9mm from 148 employees!
Orchard Funding (LON:ORCH) spread is about 12% too...
Strongly agree with the final paragraph. It strikes me that AIM not only has a global market and but also has some major advantages - the time zone, the English language, excellent communications and a first-rate legal system. Worldwide, there must be thousands of profitable and well-managed companies that would welcome a London listing. Does anyone have a list of these companies? Is there an orchestrated sales campaign (I say sales, not marketing but sales)? Does anyone physically communicate with the CEOs and FDs of these companies regularly and explain the benefits of a listing on AIM?
SImply a broad observation but London's secondary stock market needs to do more to attract successful and growing companies on a global level. At the same time, it needs to refuse entry to dubious operators. How listing a loss-making resource stock on London's AIM market benefits anyone but the promoters, managers and hangers-on is beyond me. There are resource companies that will never make any money. They simply raise money from British investors and then re-distribute this wealth to a very tiny number of already wealthy people. They pay no taxes in the UK because they make no money. Should they ever get round to digging a hole in the ground, the equipment will probably come from China and their staff on the ground will pay local taxes. If these are foreign aid projects then maybe they should be promoted as such. If they are simply reverse Robin Hood projects then, again, make investors aware.
Just how ludicrous this situation has become hit home to me recently when I asked someone what AIM stocks he would recommend. His immediate response was to tell me that the AIM market is full of junk. The person concerned was the Chairman of an AIM-listed company and this was at a presentation for his company.
Your last sentence is absolutely terrifying!!
Hi Paul, enjoy your break.
I'd be very interested in your view on small cap liquidity, specifically the point that if you can't get an electronic quote for the EMS is this a red flag in itself? If you can't get a quote to buy the EMS in a quiet time would you ever be able to get out at a bad time? Or are there other temporary reasons for not being able to get a quote?
I have previously traded a few thousand shares in K3C but today I can't even get a quote for 1500.
Of course the plus point is that if demand spikes and it's illiquid the price could ramp up quite quickly. It's a two way street that one!
I'm just killing a bit of time at Bou'mth Airport, waiting for my flight to Malta to be called. Flying from smaller airports is so relaxing - short queues, apparently no delays, and it's quiet. So I've had the obligatory full english, and a pint, before boarding.
Had to laugh, I was beckoned over by two "Counter-terrorism Police", who asked me lots of questions, and input the answers into an App on a smartphone. They looked a bit like Hale & Pace. Curious, I couldn't help asking them, "Do I look dodgy, or something?". One replied not at all, they just check people routinely. His colleague then quipped, "Speak for yourself, I thought he looked really shifty!"
Lots of sos adverts on itv lately dr Martin last night and this morning, have a good break, bou airport so quiet this time of year easy to play from drop of charge a joke!
Hi Paul
Have you noticed all the staff at Bournemouth are the same! They check you in, then change and put uniforms on to be the security team, then change again to serve you in the Duty Free shop, then they go and cook your breakfast!
Lastly, the same ones are there to take your boarding pass as you embark.
Then they all go home until tomorrow, when it will start again, for yet another flight!
I live here so know it well!
Have a great trip!!
Proactis Holdings (LON:PHD)
The solid core of the business is UK based, with a new acquisition in the Netherlands performing well in an earn-out period.
Undoubtedly the large US acquisition (reverse takeover) and oversight of that by previous US CEO Hamp has been disastrous, and de-focused the business, and now of course is dragging in lots of management time trying to sort it.
The new UK based CEO is very capable but he has a lot on his hands. The original excitement over what is now called bePayed product, which is an invoice finance function, has somewhat palled in the management promotion of the opportunities, and the lack of delivery of results. This is a great shame, because in theory it could be highly profitable, but it is a financial product, and I don't know if on the ground who sells it, and whether it is easy to sell. They haven't really built up a reference base despite what seems like three- four years of talking about it.
I would imagine for a purchaser they would currently struggle to see a clear opportunity. The Group is paying down debts slowly which is good, so that does not offer much of an opportunity for a cash rich buyer to re-finance and add much value at the bottom. So I would estimate whilst it is something of a transition mode of restructuring, an acquirer is going to struggle to see clear advantages.
I expect another couple of years of adjustment, and it is to be hoped that customer don't lose faith in the meantime,
Many thanks for the Proactis Holdings (LON:PHD) commentary Paul, I agree that the numbers look pretty awful, in particular the slight decline in ARR which suggests the customer 'bucket' is leaking faster than they can add new customers. And as you say, the FSP has been going on for three months and still no sign of a bid which I suspect, if it's forthcoming, may be at around the level of the current SP. So I sold out this morning.
Have a great time in Malta
Cheers
Francis
Paul - if you fancy lunch at the Royal Malta Yacht Club on Sunday as a regular reader I would be happy to host you -
Yes I'd love to, that would be great, many thanks! I'm actually staying 3 nights on a 42' yacht, moored directly opposite the RMYC! I thought it looked a fun, unusual place to stay, on AirBnB. So Sunday lunch with you would be awesome. Let's discuss logistics on a private message or email.
Great Paul
My email is derekwbroadley@gmail.com - drop me a line - any time for me
I find the Smartspace Software (LON:SMRT) placing today somewhat dispiriting. (I use to hold - but sold out some time ago).
At the time of the disposal of systems integration business in the summer of 2018, the company was left with £15.2m in cash (around 73p a share on the then share count of 20.8m) and a couple of interesting businesses in Connect IB and Anders and Kern, giving it an interesting foothold in the smart buildings software and hardware areas (which the market at the time was valuing around £6m - another 30p a share or so). The strategy was not to return any of the excess cash for two years and to try to buy and build a business in smart building software. If value-adding could not be found then any remaining cash would be considered to be returned to shareholders from June 2020;
Moving on 16 months and now the cash has been used up on acquisitions (mostly Swiped On) and FCF burn. And instead of any return of cash, the company is raising new cash for today's acquisition at a level per share (72p) roughly equivalent to the cash per share (alone) in the company in June 2018. The market's reaction has clearly been that the buy-and-build strategy is not yet producing value - and it is questionable how easy it is for UK management of a micro-cap to control efficiently businesses in New Zealand (Swiped On) and Australia (Space Connect).
CEO Frank Beechinor can point to the success of dotDigital (LON:DOTD) to show that he has the wherewithal to make a success out of Smartspace. I wish him (and holders) luck but I am sceptical that the best strategy is buying companies on the other side of the world.
All too often 'spare' cash in the balance sheet burns a hole in the pocket where companies store their prudence and sense
Good Morning Paul,
Please can you cover Smartspace Software (SMRT)?
Thank you
Hi Desanj,
I had a very quick skim of the results from Smartspace Software (LON:SMRT) but decided not to cover it, as it looks heavily loss-making, £4m in 6 months, on only £3m revenues.
Can you explain why it's of interest? I see there is a placing & acquisition. I don't mind looking at it tomorrow, if there's a good reason to spend time looking at it.
Regards, Paul.
Thanks Paul. Have a great holiday
Good morning Paul, would love to get your view on Proactis Holdings (LON:PHD) final results. £56m market cap, debt slightly reduced, now £36.5m, £27m impairment leading to £25.8m loss. Not pretty reading but cash generation good and possibly signs of a turnaround? The SP has recovered from 25p lows but is still a long way below where it used to be. I cant work out how much of the current SP is due to the ongoing FSP and how much the current business is actually worth alone - it'd be great if you had a view.
I'm long having taken a punt after the FSP announcement a few months ago.
cheers
Francis
My morning smallcap tweet: CyanConnode & Carpetshite grim.
Carpetright (LON:CPR), Foxtons (LON:FOXT), Cyanconnode Holdings (LON:CYAN), Smartspace Software (LON:SMRT), Oncimmune Holdings (LON:ONC), Mincon (LON:MCON), Biome Technologies (LON:BIOM), PPHE Hotel (LON:PPH)
Carpetshite (CPR) big loan repayment in Dec & July. Needs ~£80m to repay the debt, working capital requirements and necessary growth capital. White knight possible offer by Meditor of 5p (45% discount). Includes d4e swap. Board believes co is 'performing well'.
Foxtons (FOXT) Q3 rev down 7%. House sales rev down 15%, "a resilient performance given the market backdrop". H1 rev was down 3.5%. No FY guidance. I'm short.
CyanConnode (CYAN) unlikely to meet FY market expectations due to further orders delays in India. $48m orders from NIK LLC still no sign of delivery dates: unlikely "revenue will be received from those orders in the near term."
Smartspace Software (SMRT) H1, acquisition & placing. Rev-cont up 57%. Pretax-cont -£4m (-£2.7m). Outlook: "The enterprise business is less predictable due to the size of opportunities, the long sales and deployment cycle and the nature of the revenues generated. However, we have a strong pipeline of near-term opportunities mainly from existing clients, which we expect to develop into contracts over the coming months, which in turn would enable us to deliver on the market expectations for our revenue growth." Could miss expectations then. Also £3.44m placing at 72.5p (a 2% discount but 8% off SP a week ago) to fund acquisition and for working cap. I hold.
Oncimmune (ONC) FY has going concern stmt: "there is a reasonable expectation that the Group has sufficient resources to continue in operational existence for the foreseeable future."
Mincon (MCON) Q3 poor.
In line: Biome Technologies (LON:BIOM), £PPH