Small Cap Value Report (Thu 31 Oct 2024) - FTC, KNOS, PPH

Good morning from Paul & Graham!
Everyone still digesting the consequences of the Budget, I expect. I emphasise that this is a time for people to be taking professional advice from authorised financial (tax & pension, etc) advisers, for estate planning, etc, before making any changes, as it's already become clear that some of the IHT changes are complicated and have created some uncertainty.
In terms of shares, I think we should now see a wave of broker forecast cuts, because I don't believe that hefty extra wages costs (hike in minimum wage of 5%-16% in April 2025, and increased employers NICs from the rate going up and the threshold coming down) are likely to be already factored into forecasts. Hence why, for me anyway, retail & hospitality are out of my portfolio altogether for the time being until the dust has settled. Plenty of other companies are also likely to need to cut forecasts due to higher wages costs as other workers press for differentials to be maintained. Mitigation measures can soften the impact, but tend to take time to implement.
Looking for positives, I think the removal of uncertainty now allows many companies and individuals to press ahead with expansion or purchasing plans that might have been put on hold. Also the OBR says that the big increase in Govt spending will boost the economy, at least in the short-term. I'm toying with the idea of buying shares in the staffing sector, and building supplies sector, as this could be the turning point where the first signs of recovery might, just might begin to appear possibly?
Also I suspect that there's lots of investing cash on the sidelines, and with AIM losing half its IHT relief, and ISAs untouched, this could have been a lot worse. So I reckon conditions are now set up for a potential autumn rally in UK small caps - there we are, a bold prediction! This time of year is exactly when small caps began powerful rallies in several recent years.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
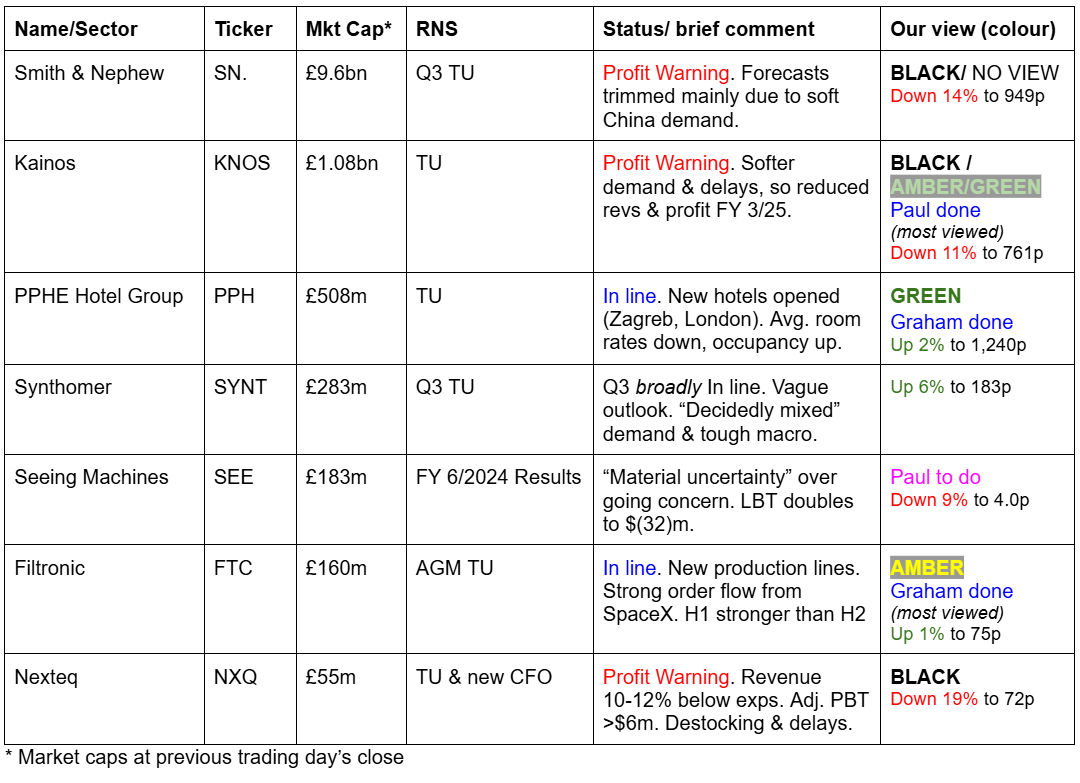
Summaries
Filtronic (LON:FTC) - up 3% to 76p (£166m) - AGM Trading Update - Graham - AMBER
These shares rose 17% yesterday in advance of an “in line” update. Advanced discussions are underway for more contracts that will hopefully feed through to earnings upgrades. As things stand, the shares trade on a PER of more than 20x.
Kainos (LON:KNOS) - down 14% to 734p (£929m) - Trading Update [profit warning] - Paul - BLACK / AMBER/GREEN
Profit warning with KNOS's usual vagueness, but Canaccord reckons we should expect at least a 10% drop in PBT for FY 3/2025 versus previous expectations. Bearish view - a former growth darling is now ex-growth, with profit actually falling. Bullish view - this is a bad year due to outside factors (public sector disrupted by election/budget) with growth likely to resume. My hunch is that there's a moderately appealing bull case tentatively appearing here. H1 results in 11 days time should reveal more.
PPHE Hotel (LON:PPH) - up 2.5% to £12.40 (£518m) - Trading update - Graham - GREEN
This hotel owner and operator is trading in line. Occupancy has improved to an impressive 81.5% although it’s not currently supported by higher room rates. New hotel openings in Rome and London will boost 2025. PPH continues to trade at a >50% discount to its standardised calculation of asset value.
Paul’s Section:
Kainos (LON:KNOS)
Down 14% to 734p (£929m) - Trading Update [profit warning] - Paul - BLACK / AMBER/GREEN
I’m no chartist, but looking at the full chart since this IT contracting group listed (main market) in 2015, my impression is that its days as a wonder, multi-bagging growth stock could be behind it maybe - we're seeing a lot of similar charts, peaking in 2021 and in a downhill trend ever since - reinforcing how over-priced UK small to mid caps got in 2021 -
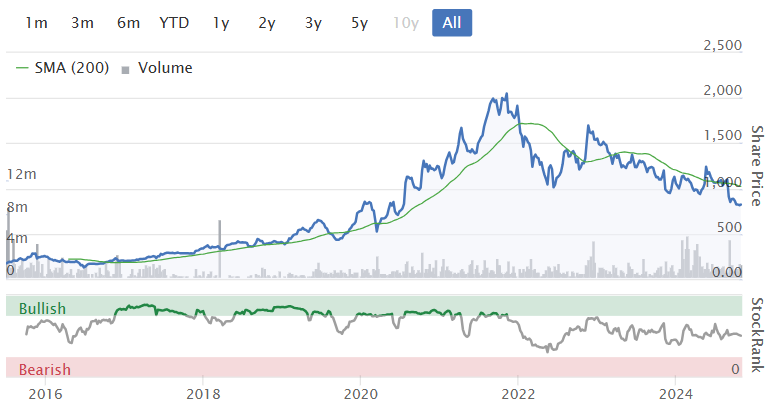
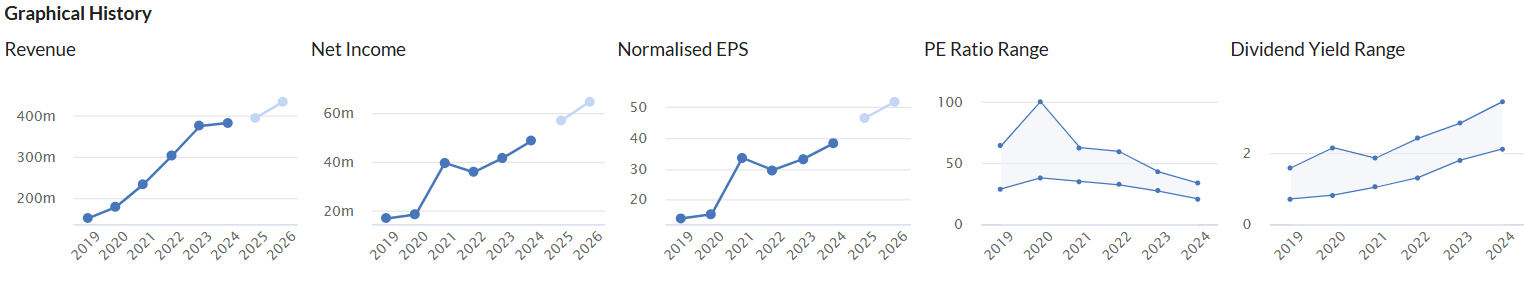
The historical graphs below tell a similar picture, bearing in mind that forecast (lighter coloured blobs) will fall after today’s profit warning, the growth trend could now turn into a more flat trend. As growth 4 shows, that’s very much already been reflected in a big de-rating onto a more normal PER range, from the heady growth days 2-5 years ago when KNOS was rated on a PER of c.50x.
This is the big problem with growth companies - eventually growth stalls, and investors suffer a double whammy of lower than expected earnings, and an often drastically lower PER multiple. Hence why we have to watch our expensive growth stocks like a hawk, and sell at the first sniff of potential trouble I would suggest. Trouble is, then we often miss out on the next big leg up, so one way or another we’re always going to get some right, and some wrong!
Checking our previous SCVR notes here -
20/5/2024 - I moderately liked KNOS, AMBER/GREEN at 1179p, based on decent FY 3/2024 results, good outlook with more growth expected, which at the time seemed to justify a PER of 25x. Healthy ungeared balance sheet.
2/9/2024 - profit warning, which the company tried to cover up, saying trading was in line, but that was revealed to be untrue with an 8% forecast drop by Canaccord. Dishonest reporting means I now don’t trust management, so am unlikely to buy this share. The market wasn’t fooled though, with a 13% fall to 964p. I dropped a notch to AMBER.
Profit warning today - as mentioned first thing on our pre-market snapshots table above (updated throughout the morning), I could identify from KNOS’s update that this was a profit warning, but it was too vague to ascertain the financial impact. That’s just bad communications from the company (and bad advice from the brokers & PRs). Profit warnings should give precise (or at least a range of) numbers, in revised profit guidance (showing old and new) - basically just see updates from Next (LON:NXT) and copy them, is my advice to all companies & advisers. Anything below that high quality level of guidance is unsatisfactory, and makes life more difficult for investors, hence we’re less likely to buy or hold your shares!
All too often though we’re given a word salad of confusing facts & figures, without it being pulled together into an overall conclusion. That’s the route KNOS has gone down today. Thankfully Canaccord has come to our rescue with an update, many thanks for that.
Anyway, let’s try to make sense of today’s update.
“Kainos Group plc (KNOS), a UK-headquartered IT provider with expertise across three divisions - Digital Services, Workday Services, and Workday Products, today issues an update on trading since 2 September 2024 and updated guidance for the year ending 31 March 2025.”
Macro environment has softened demand and caused delays to customer decision-making (some related to the budget, and public sector).
Revised guidance (of sorts) -
“Considering these factors, the Board has moderated its expectations for the second half of the year and now expects that for the year ending 31 March 2025, we will deliver revenues moderately below current market consensus with the majority of the reduction flowing through to adjusted PBT."
The trouble with that, is a moderate drop in revenue may not be moderate by the time it’s flowed through to profit, due to high operational gearing here. So it’s confusing wording. Specifically, what is “moderate”, and “majority” only means over half. Put this together, and it could encompass a fairly wide range of outcomes.
They give us a footnote of what previous market expectations were, but no new numbers, as it’s shrouded in vagueness -
“* Note: Company compiled consensus is based on known sell side analyst estimates that were updated following the Trading Update in September 2024. The ranges are: Revenue £375.5m - £392.0m and Adjusted PBT £75.0m - £79.7m. The respective consensus figures are £388.8m and £78.8m. FY2024 reported revenue was £382.4m and adjusted PBT was £77.2m.”
Good bit - one part of the business is doing well, this sounds interesting - I wonder what margin it would make on the £200m ARR target? That’s quite a big number -
“Our Workday Products division continues to deliver growth, with a very strong performance recorded in the first half of the year. The July announcement of our expanded Workday partnership has further enhanced our growth prospects, reflected in our increased ARR target of £200m by 2030.”
What’s being done about it (the profit warning)? - this all sounds sensible, and pretty obvious -
“Whilst these changes to our expectations are about delays rather than cancellations, we nonetheless continue to be focused on maintaining prudent cost control measures, reducing discretionary spending, minimising our level of contractors, while reallocating staff to our current high growth areas in Workday Products and in the Healthcare Sector of Digital Services.”
Outlook - more vagueness -
“Notwithstanding this backdrop for FY2025, the Board continues to believe that we are well positioned in our core markets, which offer substantial growth opportunities in all our divisions and that we are maintaining the appropriate balance between investment for future growth, international expansion and profitability.”
Canaccord update - strangely, Canaccord raised KNOS shares to “speculative buy” just 2 days ago, saying that visibility of a recovery was improving.
I see from the detail of the Canaccord note that KNOS has won contract(s) for digital transformation in the NHS. Given yesterday’s budget gave the NHS (and many other public sector areas) promises of more money, then KNOS might be an interesting investment idea for more contract wins in the future, after a time lag for negotiation. So I am warming to the theme of increased public sector spending finding its way potentially to KNOS, and a resumption of growth, with maybe a re-rating upwards again in its PER multiple possibly?
Canaccord acknowledges that its recent positive update was ill-timed, but that the thesis of increased public sector IT spending remains intact. Maybe the broker isn’t that close to the company? Who knows, I’m not being critical of the broker, because their published research is hugely useful to us. It delays updating the forecasts until H1 results on 11/11/2024, but warns that the next set of forecasts will show a >10% reduction at the PBT level. Ouch. That means we could be looking at FY 3/2025 profit being down c.10% on FY 3/2024 actuals (previously forecast profit was flat).
EPS of 48p last year, could be down to more like 40-44p this year I think, which breaks the upward trend, as mentioned above.
Share buyback is announced, and we will get details in about a fortnight, when it published H1 results on 11/11/2024. It has a cash-rich balance sheet, so it's a good idea buying back shares now the price is lower.
Paul’s opinion - I’ve been critical about how KNOS handles profit warnings. However I’m warming to the idea that it’s probably just suffering delays from its public sector focus. That seems a reasonable explanation, given the recent election, and all the uncertainty over the budget. What we should now see is Govt departments able to budget, and make decisions, in a more favourable spending/investment environment. Hence I’d be happy to use c.40p as a base figure EPS in a problematic year FY 3/2025, with hopefully decent upside on that number in the following years, and maybe more positive updates rather than any more profit warnings?
So is the 734p current share price a bargain, as it’s c.18.4x my estimate of 40p cyclical low EPS? Not really. That’s not cheap enough to tempt me in at the moment, but I think there’s a fairly credible bull case building up here, in that next year could rise to say 50p EPS, and maybe 60p the year after, which you could probably value at say 15-20x, so 750p - 1200p share price range might be sensible with a 2 year view. That compares fairly favourably with 734p actual price today.
I think this share could be getting close to a bottom, so I’ll push the boat out here, and up a notch to AMBER/GREEN, particularly as it has a nice balance sheet with plenty of net cash too. It’s the sort of thing where I might dip my toe in with a starter position, then wait for the interims on 11/11/2024 to decide whether to buy any more, or ditch them for a small loss if more bad news comes out.
The newsflow could improve as we move into 2025, with new contract wins possibly providing a catalyst for the shares to break out of the current downtrend. That strikes me as a fairly sensible thesis, but nobody knows for sure at this stage.
Decent sized Director buying would be a good signal. They’ve been shy about buying in the past, more keen on banking the substantial profits on share options. I note that the CFO Richard McCann has an unusually large shareholding, dwarfing the other Directors, at 4.6m shares (worth £34m!) - maybe he wants to be the bean counter because many of the beans belong to him!?
Graham’s Section:
Filtronic (LON:FTC)
Up 3% to 76p (£166m) - AGM Trading Update - Graham - AMBER
This share rose by a remarkable 17% on no news yesterday. Today we have a positive AGM trading update. Let’s get into it.
Key points:
They have confidence in delivering results in line with expectations.
There has been strong order flow from SpaceX in H1 (June to Nov) including some retrofitting work. With the retrofitting work completing, H2 will not be as strong as H1.
They are adding two new production lines.
The update also provides some detail on engineering developments.
In relation to contracts:
We are in advanced discussions for some further contracts in the space and aerospace and defence market which we hope to provide updates on soon, and have enjoyed some smaller development contract wins in recent months. Of particular note are a couple of contract wins in the space market utilising our recent investment in plastic encapsulation machinery. Encouraged to purchase by our lead defence customer for sovereign capability, we are now seeing wider interest in the technology offering throughout our core markets.
Estimates: Cavendish have reiterated their forecasts. These continue to suggest a step-change in revenues and profits from FY May 2024 to FY May 2025. FY May 2026 is then expected to produce a very similar result to the prior year.
FY May 2025: revenues £40.5m, adj. PBT £7.7m.
FY May 2026: revenues £51m, adj. PBT £8m.
Graham’s view
This is one where I missed the boat as the shares have multi-bagged while I’ve been neutral.
We covered it in June, in July and in August. In August, Paul chose to go GREEN on it.
The StockRanks still see hardly any Value here (although they do see Quality and Momentum).
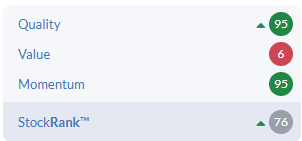
At the current level, it seems to me that the market is pricing in continued growth far above and beyond what has already been pencilled in for FY25 and FY26.
If broker forecasts are to be believed, the company will generate about 3p of adj. EPS in FY26. At a share price of 73p, we get an unusually high multiple for this industry.
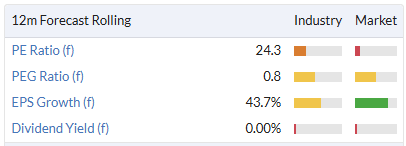
The “advanced discussions” for further contracts are key: could they move the needle and lead to new upgrades? EPS momentum is certainly positive:
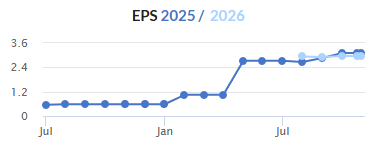
Or perhaps we won’t get another round of earnings upgrades for the next two years, but instead the blistering growth will continue again from FY27?
My difficulty is that I don’t feel able to predict the outcome here. Based on current valuation and what it is (a designer and manufacturer of telecoms components and subsystems), FTC looks overpriced. But I acknowledge that it has a prestigious partnership with SpaceX and that momentum is currently excellent.
I’m going to be stubborn and stick with a neutral stance here, embracing the uncertainty and seeing the potential for a very wide range of outcomes.
(Paul adds: I think that's a good summary, thanks Graham. FTC shares are expensive, but bulls clearly think it has upside to beat forecasts. I think the case for further orders & profit beats is pretty strong though, so for me it would probably be a more positive view, at AMBER/GREEN or GREEN. But I accept that involves some guesswork).
PPHE Hotel (LON:PPH)
Up 2.5% to £12.40 (£518m) - Trading update - Graham - GREEN
PPHE Hotel Group, the international hospitality real estate group which develops, owns and operates hotels and resorts, is pleased to announce a trading update for the three months ended 30 September 2024…
I stayed positive on this one despite a mild profit warning in August.
I also published an in-depth analysis of the company’s IMC webinar and a Q&A with the CFO - see here.
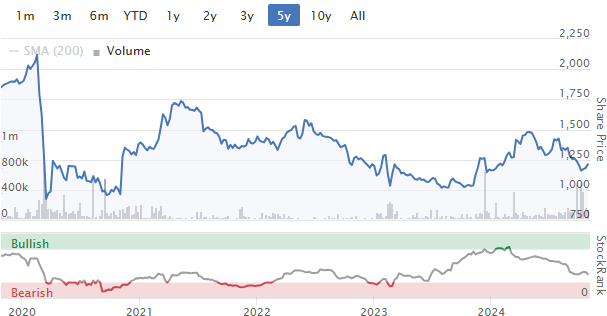
The shares have been range-bound since Covid, never getting back to their pre-Covid levels:
Here are the key takeaways from today’s Q3 update.
Like-for-like revenue growth is 1.8%. Total revenue growth is 5.1% due to new hotel openings.
Like-for-like average room rate is down 2.7% to £171.6. If new hotel openings are included, this is lower again, but I think it would be wrong to include them.
Like-for-like occupancy improved from 77.5% to 81.5%.
RevPAR (revenue per available room) gets a boost of 2.3% (like-for-like) thanks to the higher occupancy.
However, the room rate matters most when it comes to increasing profitability. There are many incremental costs to higher occupancy, but there are no incremental costs to charging a higher rate!
Therefore, I wouldn’t expect any significant gains in profitability as a result of these growth figures.
Hotels: Radisson RED Berlin is now fully operational and “is achieving excellent guest feedback”.
art’otel London Hoxton (an “art-inspired” hotel) is “nearing completion” with 90% of rooms in operation. It should fully open in Q4 2024.
art’otel Rome is now expected to soft open in early 2025.
The new London and Rome hotels suffered delays which led to the profit warning this summer. As of August, the Rome hotel was supposed to open in Q4 of this year, but it has been further delayed.
Outlook: in line with expectations.
Estimates: the researchers at h2Radnor have left their forecasts unchanged. These forecasts include adj. EPS of 118p in 2024 (about the same as 2023), rising to 128p in 2025.
Co-CEO comment excerpt:
Our commitment to delivering high quality assets and services is paramount and these latest openings are testament to our thoughtful approach to creating hospitality offerings destinations with lasting appeal.
The Group has a strong platform for continued growth, with newly opened hotels ramping up in performance, and we look forward to building on this momentum over the remainder of the financial year."
Graham’s view
I’m a fan of this one but I acknowledge that it won’t be for everyone.
It’s carrying over £700m of net debt (last seen at £765m) although this is forecast to reduce over the next two years.
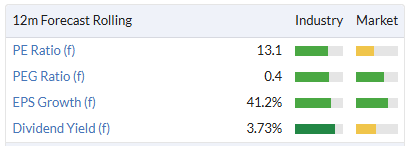
The market awards it an earnings multiple that I would view as average or below-average, given the sector. But I guess some investors may find the hotel and hospitality sector more anxiety-inducing than I do:
Valuation isn’t all that easy. The company likes to focus on EBITDA. The CFO is adamant that depreciation does not reflect the economic reality, and puts forward alternative measures.
Personally, I like to focus on PBT/EPS whenever I can.
At the same time, there are standardised calculations of asset value for real estate companies. These suggest that PPH is worth £26.24 per share. The company has bought back £4m of shares in the market at a greater than 50% discount to this.
I won’t change my positive view on this as I think that regardless of which valuation is used: PER, NAV or EBITDA, the stock appears to offer decent value. Of course it would be better if the room rate was improving but at least occupancy is very firm. I’ll keep giving this one the thumbs up at this level.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

169 comments
First October budget out of five . Government even more than last one is going to be a tax, borrow and spend one. Will need to be very selective to make gains in Uk focused stocks over the term. Fortunately took Paul Scott's advice not worth attempting to pre-empt this one.
It's great to see a professional investor give such a great accolade to Paul, Graham and Roland for the sterling work they do. They will appreciate how hard the job is. We are lucky on Stockopedia that we only get a few detractors and wingers who are never pleasant to read. Keep up the great work guys you do a wonderful job, which is appreciated by the majority.
Who are you referring to caf ?
Whoever it is, you are right thou.
After I finished being a full time FD in private equity backed businesses I used to look after a small handful of growing SMEs on a part time basis. Anymore than 3 or 4 and I would start to get confused about which business was which and the numbers all got mixed up in my head.
How on earth Paul manages to get into the detail of hundreds of businesses and keep on top of it all is just beyond me !
IFS says the NIC changes will not collect the level of tax estimated due to job reduction/salary counter measures.
This has traditionally been a 'pro tax' body, but looks like the pressure may be on RR in the next budget if this is true.
Deleted
REF - SEEDOPEDIA
Spoke to one of the guys helping us at work .
Just left uni
Cant get a job
Said “great time for you to think about starting your own business with Seed. Funding “
We can support you with infrastructure, building , office etc . If you need.
Explained how seed funding works “cant believe me and my mates know nothing about it”
Hes as liam says “mad for it”
2 more coming up next week
One down 999997 go
Steel city SeedEIS. On the move
What a lovely day
Your last rant ( or maybe it was five or six rants ago - only joking ! ) was about how there was a cliff edge coming up regarding the lack of the next generation of entrepreneurs and future business leaders .
Apparently it was all going to end with you and yours
Seems thats not the case
So many examples of upcoming youngsters who want to be their own bosses, in the daily press every single day
Great to see you are doing your bit
Secure Trust Bank (LON:STB) I don't hold but I have a substantial cash deposit with them. Shares collapsed by 30% on Monday along with other vehicle lenders. RNS here. What I need to know is how I can find the current price of its bond, here: https://www.londonstockexchang...
I have searched every bond exchange I can find and no luck so far. When a business hits trouble I always look at the bonds (if any), it's sometimes a better guide than the share price.
EDIT - my current thinking is that the Court of Appeal case does not mean immediate liquidity problems for the lenders involved. It will take time for the Supreme Court decision to emerge and meanwhile there is no sudden outflow of cash nor is there any need at the moment to write off assets (I hope). The cash outflow and write-offs will come if the Supreme Court decides that customers must be given cash compensation. Does that sound right?
So the question is what exposure does Secure Trust Bank (LON:STB) have? Have they made any provision in the accounts?
What a difference a day makes, markets buoyant yesterday, slumping today!
I assume there's a lot of data for economists to work with on the effect of payroll taxes, and the modelling really doesn't seem that disastrous for profits.
It can be claimed as a way of not raising taxes on working people , but they will in fact bear most of the burden in reduced wages.
The exception being those with a large percentage of low paid employees who are disproportionately affected, in addition to being hit by the minimum wage increase
10-yr gilts going through the roof and almost 4.5% again....market not impressed....almost a Truss moment on the way?
https://tradingeconomics.com/u...
US & EU bond yields also sharply up over the past month.
Don't think we can blame Rache for that...can we?
Yes Topvest - I noticed this earlier. Sky news showed they were starting to move yesterday as the budget notes were released. As you say - they have kept on moving today.
Stagflation has been mentioned today on this board. I would guess that the markets are considering this possible unfolding disaster.
I dont think the TV appearances by the Chancellor and PM have helped today. Our PM once again does not appear to have his PR gene functioning correctly. One would have thought he would be on safe ground visiting a hospital after awarding the NHS 23 billion.
Not so - he is reported as saying that NHS staff would have to work harder when asked if there would be more staff available to reduce the burden of work.
I dont think we have had the full fall out from this budget yet.
No, nothing like Truss!
On the budget.
“From April 2026, the 100% rates of …. Business Property Relief (BPR) will be capped at £1m, with the rate dropping to 50% thereafter. This means an effective 20% marginal IHT rate for farms or businesses worth over £1m, unless any NRB and RNRB remain available."
Does anybody have a view on:
This seems crazy & ill thought thru. It is catastrophic for small businesses and farms.
I suspect on AIM stocks £1,000,000 threshold means that few will be caught by this. Unless I and the twittersphere have misunderstood
Regards
Michael
Michael
There isn't an AIM threshold - BPR is restricted to 50% i.e. the IHT charge will be 20% on all the portfolio so it impacts all AIM investors even of modest means
"Modest means" investors who are leaving an estate in excess of £500k (or £1m married couple).
Yes modest means. . . . . . .living in a detached house in the south of England and you've been thrifty and also invested over a period and you're now of retirement age you will be well over £1m of assets
MichaelFBS,
There is a specialist department of HMRC which values unquoted shares and other hard-to-value assets. here: https://www.gov.uk/guidance/sh...
The principal page of the manuals relating to this is here: https://www.gov.uk/hmrc-intern...
They are very good at this. They know what they are doing. And historically it was one of the departments of the Inland Revenue where you could have a sensible open discussion and be treated very well if they didn't think you were trying to pull the wool over their eyes.
How are people going to pay the tax? Either by using surplus cash or assets in the estate, or by borrowing. Those who have not planned will be in terrible trouble.
Yes, the text says "The existing rate of relief will continue at 100% where it is currently
this rate. The exception is for shares designated as “not listed” on the
markets of recognised stock exchanges, such as the AIM, where the rate
of relief will be 50% and will not be affected by the new allowance", see https://www.gov.uk/government/...
The £1m relates to agricultural property relief and business property relief, here business property refers to property such as business equipment (e.g. tractors) or unquoted companies (i.e. not AIM stocks).
Irrespective of the value AIM stocks which qualify for BPR the value will be subject to BPR of 50% (i.e. with IHT at the current rate of 40% such AIM stocks will be subject to 20% IHT).
See "The rate of relief for shares designated as “not listed” on the markets of recognised stock exchanges will be 50%." Extracted from https://www.gov.uk/government/...
I has taken a year to get probate on the estate of a member of a family with a large holding in an Aim listed company I know of. I can only assume the delay was down to valuation in recent volatile times, my informant didn't say. So best to bear that in mind and plan ahead. The Grim Reaper can strike without warning and you want dependants to be taken care of without delay.
A big thank you to Paul for his excellent Budget coverage, unfortunately I was unable to read it live as I have been back helping out at my old business as the guy who bought it from me has been very poorly recently. For me that may have been a blessing in disguise as I have not been tempted or had time to tinker with my holdings in the run up to the budget. From an equity investment point of view yesterday surely was a relief, IHT on AIM holdings not as bad as expected and I know that IHT focused funds could possibly have been swamped with withdrawals but I doubt that many investors buy qualifying AIM stocks for their IHT advantages. ISA's left untouched despite the rumours but mainly I am surprised that more has not been made of the chancellor leaving SIPP contributions and lump sum withdrawals alone. I was under the impression that the 'large number' of people taking their 25% tax free sum pre budget was a major cause of weakness in the UK markets.
So now we have 5 years of a labour government and rather than complain (if that is how you feel) we should just play the hand accordingly. I have always considered myself conservative but the last government didnt exactly cover themselves in glory although with Brexit and Covid it was not an easy time to be in charge.
My chief takeaways from the budget?
Rachel Thieves:
We're all on notice there is likely to be worse to come
This is political diatribe and has no place in this forum
Well at the last count 47 subscribers disagree with you and 7 agree. I think it fair comment on her much vaunted economic stability measures. Not to mention the honesty of her campaigning.
HI pj8
IMHO opinion it's a fair and objective assessment of the big picture around the budget and how it's relevant to fellow investors.
Please, by all means counter any of the points made with your own thoughts/observations provided they rise above cat-calling anyone who disagrees with you as "far right".
Let's keep it about the public interest and how that's likely to impact the economy, specific sectors and listed small caps.
It has been a difficult period for investing in small caps and this year has brought little cheer thus far. Perhaps there may be a Santa Rally, who knows. Having digested the implications of the budget especially the increase in employers NI, reduction in the level at which it is paid and the increases living wage. I have sold my shares in Young & Co's Brewery (LON:YNGN) at a loss.
The above headwinds makes life far more challenging for employers, especially those in retail and hospitality. Young is a good company, but there are other small caps that do not face these headwinds to the same extent. The funds will be used to add to existing holdings.
I no longer hold any hospitality or retail shares, unless one counts Ramsdens Holdings (LON:RFX) , which is something of a hybrid.
Dalata Hotel (LON:DAL)(I hold) Eiendomsspar have just announced a 3% holding They are a Norwegian Group who -"Eiendomsspar AS and Sundt AS bought the Swedish listed hotel property company Pandox AB in 2003/2004 on a 50/50 basis. In 2010, the Norwegian hotel property company Norgani Hotels AS was acquired, and thus one of Europe's largest hotel owner systems was created. Pandox owns over 150 hotels in Scandinavia, Northern Europe and North America." They state share holdings are taken " Eiendomsspar/Victoria Eiendom is currently involved in several external companies within the property sector.
With a strong ownership/management commitment in these businesses, the companies share financial interests and collaborate in various business areas to achieve common goals and synergies."
At least Canaccord timing on Kainos (LON:KNOS) isn't quite as bad (yet) as UBS who went large on Card Factory (LON:CARD) the day before it collapsed.
The market eventually makes a fool of us all (usually every week for me)
Card Factory (LON:CARD) is clearly finished as a business, no?
mr market has decided and that's that!
(/s of course!)
I was pondering a sale of my holding in Card Factory (LON:CARD) which is 5% underwater.
Really not sure as the investment case is weakening and not sure about the full year numbers
selling after being 5% underwater? i would say that that is not even of remote concern really
now, a 50% drop? you may well have overpaid or made a mistake when analysing the business...(emphasis on may have)
IIRC Card Factory (LON:CARD) reiterated their guidance on their recent announcement of 0.14p EPS for the year
if you think that is a little high (i would not disagree with you if you did) then 0.10p-0.11p EPS is perhaps a more reasonable/conservative assumption. their first half EPS was 0.03p and the second half is weighted higher, for context
they were trading at £1.40 a share just over a month ago; £1.20 before that, £1.00 before that (they traded between £0.90 & £1.10 a share for the best part of a year incidentally)
you can now buy shares in the exact same business for £0.84 a share. did they get 40% worse in a month? no, obviously not!
additionally, compared to the start of the year e.g jan-feb: they are now also paying a dividend and no longer have the telios overhang
Thanks for your thoughts RJS89
Paul has an expression "when the facts change, I can change my mind".
Sometimes we also re-examine the facts which I'm currently doing and your comments are a reminder of the positives, although I think the full year was starting to look more challenging anyway and now we have the increased minimum wage and employers NI.
Just a reminder that tomorrow it is the London Investor Show and there is a Mello Zone within it this year...
Mello @ the London Investor Show on Friday 1st November 2024! Come and join us at Novotel London West, 9.30am-5pm. Lord Lee, the UK's first ISA millionaire is our main guest speaker and we will also have Paul Hill doing a talk as you can see in the programme below..
You can, hear company presentations and question top management about their views on future growth. Mello will be hosting our own zone within the London Investor Show and two of the top performing companies of 2024 will be there...Serabi Gold (LON:SRB) and Corero Network Security (LON:CNS)
Attending the London Investor Show is an excellent way to connect with over 1000 other, like-minded, investors but only 300 will have access to the Mello zone as it is a premium area offering the usual Mello sessions and engagement with companies. Ideal for those looking for long term investment opportunities in quality, growth listed companies.
For more information, click here: https://melloevents.com/mellolistickets/
For HALF PRICE tickets use code M50LIS https://www.tickettailor.com/events/melloeventslimited/1367845
More Upcoming Events:
Mello 10 Year Anniversary Event in DerbyTuesday 19th November & Wednesday 20th November 2024, 9.00am – 7.00pmDerby Conference Centre, Derbyshirehttps://melloevents.com/mello10tickets/
Interesting reading from Graham regarding Filtronic with his main problem being not necessarily if but when new contracts will be realised . My understanding is that Filtronic are at the Mello event in Derby on the 19/20th November so he will be able to ask them himself ( assuming he will be there )
The kick in the teeth to farmers is staggering. In my part of the country many farms are small and part time - my few acres will have me bumping up to the limit and maybe into it, but will not be disastrous. To make any sort of decent full time living from conventional beef/dairy/arable farming you need at least 300-400 acres, so an asset of about £4-5m. Farming is the ultimate low margin business - if you make 1-2 percent net of all costs on that invested capital, you are doing ok. No conventional investor would put up with that long term. But farming is a way of life, and farmers, despite their grumbling, do it to maintain that way of life. Your business asset and home are one unit, often indivisible, and could until now be kept together from one generation to the next, even if there's not much cash knocking about. But the maths no longer make sense. Try making a living when you have to mortgage the property to pay the IHT - it just doesn't work any more. The bill on £4m is £800k. No farm of 400 acres can pay that off and make a living.
While I have every sympathy with family farmers is it not the case that the price of farm land had been driven up to £10-£12k/ acre not because of the return you can make from farming but because it became a means of avoiding IHT.
I would challenge that assertion.
Land values are impacting by a range of factors: where you are in the country; the agricultural value of the land (grade, diary/arable, ease of use/access); the size of the parcel (large units have lower price per acre); recreational value (which might be enhanced by tax considerations); how land will benefit from subsidy payments; and good hope value for development.
Totally agree that every case is different, just as every investment case is different. But I think you would find it hard to produce a sound business plan to justify buying an average arable farm at current land prices. Ask Mr Clarkson!
How much has agricultural land gone up in value over the last ten, twenty, thirty years?
Quite a lot from 1995 to Covid.
i've been told that since the 70's if you invested in land rather than real estate you would have made more money.
Anecdotaly my brother in law is a farmer and the price increase in land has been one of the few reasons the farm business has been able to survive and still operate .
The Farm etc is in a family trust so i suspect is protected from the current tax shenanigans.
According to Savills £/acre, 1960s £200, 1994 £1800, 2004 £2000, 2014 £6000, today £10,000+.
Vinman, my first car in the mid sixties was 2 years old and cost almost the same as 2 acres. It seems nothing much has changed, governments of every colour want to pay off debt by inflation. "Invest in land, they've stopped making it." (Mark Twain, I believe said that)
Also bear in mind another factor - Forestry. Firms such as Foresight forestry buying up Welsh farms Scotland has also seen land/ forestry prices increase significantly and its all putting pressure on farming community. And add to that land being bought up for Solar Schemes. (I refuse to call them 'solar farms')
About 8% pa
Our local farming/landowner family has just sold more of his fields to Taylor Wimpey (LON:TW.) for a large development that initially was blocked, but overturned by those at the very top.Still very few affordable housing units in the proposed and now greenlit, greenbelt development though.But i agree, farming is a lifestyle for many as well as a job for a lot of farmers as it's such hard work alongside the supermarkets huge effects on margin compression and the totally unpredictable hedging markets.A lot of farmers are having to focus on rewilding schemes to boost more reliable profits now it seems too, which is good for the environment, but we get even less of the reliable uk produced food source naturally.
Perhaps that's part of the plan - forced sellers making land available for all those new houses the government wants to build.
I think the biggest worry about farming now has to be that less and less food will now be produced in this country. The farmers have already been hit too many times by regulations and standards making it near impossible for them to make profits from farming food. Then they have seen trade agreements made with the likes of New Zealand whose farmers are not regulated to our same high standards making it impossible for our farmers to compete price wise.
What then worries me, is if for some reason we had another world war, we would not have enough food in this country to feed us without importing. And for those old enough to remember the last world war, they will remember how short food was and that ships that imported food to us became a target.
it is all very well being in a world of globalisation but there is something to say for being self sufficient. And when people buy products from outside of their own country, a little bit of that money goes out of the country, which then makes us all poorer. So we may pay a bit more for products made in this country but we all benefit from it as the money stays in the country. Perpetual circle that is in our own interest to not break.
By way of balance, the respected tax lawyer Dan Niedle of Tax Policy Associates has published information today on X showing that very few farming estates should in actual fact be impacted by yesterday's budget changes. He backs this up with various evidence, stats and examples which seem plausible to me.
Not my area of expertise by a long way but its always interesting to see a detailed fact based assessment of the impact of change in order to take the heat out of the understandable initial emotional reactions
PW from Kainos (LON:KNOS) . Not entirely unexpected but not exactly welcome either.
The RNS says ....
....The Board has moderated its expectations for the second half of the year and now expects that for the year ending 31 March 2025, we will deliver revenues moderately below current market consensus with the majority of the reduction flowing through to adjusted PBT......
They lose a lot of credit for NOT being explicit and telling us how much "moderately" is. They leave it to their Broker to slip the bad news out by the back door.
As their Broker in Panmure Liberum and they don't allow us plebs to read their research that means any shareholders who are not Panmure clients are in the dark. Eminently fair given the shareholders are the ones who have effectively paid for said Broker.
Anyway, Panmure "expect a new consensus to form around £365 million for Revenue and PBT around £65 million". That's a just under 3-7*% drop in Revenue and an 13-18*% drop in adjusted PBT. The former can fairly accurately be called 'moderate' the latter most definitely can not.
I dumped my holding at the open, having grown tired of a relentlessly downward SP and lost respect for management who can't be honest about the scale of the PBT miss.
It was my worst performing share, by some distance.
*depending on whether you take the top end or bottom end of previous broker forecasts.
Euphoria to Woe
I have gone from it's not as bad as I feared (on a personal level) to the glum conclusion this is a terrible terrible budget for UK businesses.
Instead of approaching this with an attitude of, which taxes are prohibiting growth? and let's remove them, they have instead gone and done the complete opposite.
How can such commercially inexperienced people be allowed to run the biggest business of all, the State?
I can see inflation working its way back in and any growth prospects working themselves out, maybe even the dreaded stagflation...
Need to position accordingly, thinking very defensive now.
Apologies for the negativity and anti Labour rhetoric, no malice towards supporters, i'm just so so disappointed with them.
We have gone from a government of incompetent Eton pupils to an incompetent bunch of former civil servants and union officials. As a small business owner I am now seriously considering shutting up shop. My labour costs from next April have shot up.
Apparently none of the front bench have any commercial experience/ run a business/ etc.
Apparently the current Business Secretary has never worked in a business let alone run one. His whole career has been in local then national politics since leaving university ( where he studied…politics)
Correct and Chief Muppet to the Treasury the runtish Darren Jones has only ever worked in the private sector while training for a regional firm of solicitors.
He is a walking definition of the dangers of believing your own narrative - spouting nonsense about generating growth from nowhere.
Scary
No apologies necessary. As I stated yesterday, I have sold all my U.K. portfolio and indeed my investments in a restaurant and wine merchant ( both before the budget in anticipation of a disaster waiting to happen ) . Now planning to exit U.K. and live max 90 days here .
Hi Paul,
As I said before and is a counter to your anticipated swathe of forecast cuts is that I think the budget is inflationary.
Everyone is in the same boat in each industry when it comes to ERs NI. A card retailer or a pub chain or a supermarket for example have exactly the same problem in their respective sectors with the tax increases and in each sector they mainly have the same proportion of staff to revenues. So each sector constituent knows exactly how much they need to add to prices to offset the taxes but more importantly they know how much their competitors need to raise as well. Therefore I expect little resistance to increasing prices based on fears around competition and instead all of them will do it.
So cards will go up 2 or 3 pence, hospitality will keep the 1p reduction in draught and add a few pence to every drink. Supermarkets similarly will tweak pricing. All of this can be done very quickly and ahead of incurring the taxes. Given the wage increases are significantly above inflation both from a public sector and minimum wage perspective I see little consumer resistance to those price increases either at a demand level.
For me then this adds c.2% to whatever is core inflation next year and probably reduces the interest rate cuts we can see in the UK.
Best
David
The counter argument would be that businesses will also respond by being less generous in wage/benefit growth and in making new hires, which would have a deflationary impact
For sure - that will also be an effect. Firms will pull multiple levers to offset impact to profitability but I think increased prices will inevitably be one. It’s the classic model - when wage increases significantly exceed the natural inflation rate firms feel price rises are necessary to combat it. Giving people 6-7% increases will lead to at least 2-3% price increases in my view. But I agree companies will also be less generous in other wage growth and hiring.
Make no mistake this is fundamentally a stealth assault on the middle classes. For them costs go up but wages go up less. For anyone around minimum wage their spending power increases. This should be no real surprise given the party in power but is evident in the chosen tax raising measures.
As I said before and is a counter to your anticipated swathe of forecast cuts is that I think the budget is inflationary.
to me its obvious from the budget and the route taken my labour is inflationary i doint think that can be doubted - the question is whether thats against a backdrop of stable inflation otherwise. Poor workers have suffered period where prices costs gone up more than earnings - and they have basically helped keep inflation down. I see nothing wrong in the opposite happening and inflation being a bit higher than it would have been due to real world wage increases as they catch back up - if the backdrop of other stuff is low i dont see the need for wages being one segment of the whole tipping us into any area we should not be. My opinion is that real world wage increases are probably better for the economy than even growth as its likely thatthe much neded extra cash being spent in the uk that will aid business to grow - sometimes the logic of minimum wage rises always being bad seems so plainly nonsensical to me - i dont understand why the benefits are normally completely ignored. I do understand its complicated and runaway wages can cause inflation. No one ever seems to claim when higher earning people are able to get better jobs earning more and that employers cant afford these good staff - but an increased in minimum wage will destroy business. Perhaps for minority it will but overall i like the average worker having more in their pocket via their real graft.
I had my hair cut this morning and was chatting to the owner about the budget. She said that she pays her two staff slightly more than the minimum wage so the rise in minimum wage won't affect her, however she will still have to raise her prices slightly because of the NI increase.
Unless this owner has other business links that invalidate their claims its almost certain they wont be paying any employers NI previously or paying any now - i have run the calcs today for a busines with 2 low paid directors and 7 staff members paid middling pay (30-35k) pa. On a 240k wage bill the increase in employers NI is under 2k !!!! The breakeven point for them would be 5 staff members.
Note companies with 5 or less staff at that level ( more staff if employees are lowly paid) wont lose out and could be substantially better off - this is due to the increase in the employment allowance from 5k to 10.5k - soemployers start of with 5k extra pot from which to draw down teh extra costs from - soem will now pay no employers NI where they had previously paid.
Note i am kinda presuming the hair cut you get is of the more value side of the market and that the employees are unklikely to be commanding salaries of 60k plus pa each - no offence meant if you pay top dolar for a lovely quiff.
Note may business owners dont have the foggiest what they are paying when and where - this business owner probably wrongly thinks that the employees ni they deducted from salary and pay over to hmrc is a cost of theirs.
Am I missing something? The rate of employer NI has gone from 13.8% to 15% and the starting threshold has gone from £9100 to £5000. Let's say the salary is £15,000 - employer NI goes from £828 to £1350.
Yes, Employers Allowance
The employment allowance is being doubled from £5,000 to £10,500 meaning 865,000 employers will not pay any National Insurance at all next year, according to the Chancellor. That is why rmillaree says "Unless this owner has other business links that invalidate their claims its almost certain they wont be paying any employers NI previously or paying any now."
https://www.gov.uk/claim-emplo...
This is a seriously misleading stat designed to fool you into thinking the impact must be low. 865k sounds like a big number to the general population so what’s to be concerned about right? A classic politicians sleight of hand. If you are a mom and pop business employing one or two people on minimum wage then today you don’t really pay ERs NI and nor will you tomorrow…….BUT the vast majority of employees are not employed this way - they are in larger businesses who are directly impacted.
The economy will not survive on these one and two people businesses - there are 34m odd people to employ not 1m so this is a stat designed to lead us away from the impact on the 33m people by focussing on a seemingly large, but fairly irrelevant population (from an ERs NI perspective - not GDP).
Do the maths - £800 ERs average effect per FTE to generate £25bn : that means 1m people aren’t impacted but 33m are!
Employers' Allowance - If as an employer your total Employer NI calculation is £5k this year - you don't pay any. https://www.british-business-b....
That allowance is going up to £10,500
The hit is £615 per employee just on the reduction in the starting rate from £9100 to £500.
Yes i am aware of that fact - my calcs fully reflected that fact
Most of the hit in my example is the 615 per employee you mention - so 615 * 9 staff = 5535 cost
if we say the additional cost for 7 staff at 32k salary - that would be 22900 (salary above 9100) * .012 * 7 = 1923
total extra cost 7458
less 5500 extra employers allowance = 1958 extra total costs the business will pay in employers ni - albeit that extra cost is allowable deduction that will reduce corp tax
Fair play with the way this has been setup , although the bigger companies are finding an extra wad - the smaller comapnies have been given some extra relief at the lowest level. For this company with 240k pa wage bill the 2k increase is under 1% of their gross wages due despite the mention of £615 for each employee that might make some worry the damage is much more.
rmillaree my initial reaction to the drop in threshold for the Employers NI was that I would have closed my previous business before the higher levels came into force. The 1.2% rate increase was bad enough on it's own. However, you are right to point out the quantum once the extra £5,500 allowance is taken into consideration. This largely offsets the extra burden, probably, for businesses turning over £300k to £400k with 1/3 going on staff costs. Difficult to be rational when your heckles are up.
On full consideration it just seems that it is (just) yet another cut and a requirement to run even faster to standstill - and the bigger outfits in hospitality and retail in particular will suffer that much more. Glad I'm out of the trade now. IMO many small businesses in this area are pretty much lifestyle choices (though often only after the cold reality of how hard it is to make money here hits) and always on the brink economically. This may be enough to tip another tranche over the edge.
On the IHT issues I share the view someone expressed earlier that Pensions are to provide for the living in old age and not for passing on wealth with any form of tax avoidance, legal or otherwise, so not unhappy to see Pensions come into IHT calculations - pass it on quicker if you don't want the State to take a chunk. The Farm issue though needs amending as they go through the Bill. Planning, investment and husbandry there needs to be for the long term. Maybe a £5m rather than £1m threshold or a minimum 10 years working the land or some similar qualifier to exclude from IHT would be more sensible? Now if only I had a Labour MP to represent me it might be worth sending them an email. (Un)fortunately I don't.
Hi rmillaree
Yes, I make no political judgement here. My point is really that if pre budget someone wanted to raise prices they would have to consider whether the competition was also raising prices and the supply/demand elasticity equation.
However, post budget the macro picture has completely changed. Purchasers have been granted wage inflation above core inflation (so real wage growth) so the sensitivity to price rises has been reduced and Employer taxes have gone up for everyone in roughly equal proportion to their sector. So you don’t need a sophisticated model as a business to model demand/supply. You can raise prices by a few % and everyone will do so to protect margins. In most businesses the necessary price rise will be 0.3 to 0.5 of the increased wage and social security cost.
Thus the c.8-10% rise in employment costs the chancellor has forced on employers will result in an almost immediate 2 to 5% price increase depending on sector. that may be tempered marginally by rates allowances and the like but its marginal.
So you can’t necessarily assume that analysts take a red pen to forecasts as Paul suggests. It may well end up a pass through instead with the corresponding effect on inflation.
The worst position for a company is if they are in the midst of a price war or big over supply - then they’d have to absorb the extra costs and cut prices at the same time which could be disastrous. I don’t see many signs of that though in a lot of the sectors we’ve been discussing
This is the OBR's verdict on the behavioural changes that result from raising Employers NI
3.11 The indirect effects of the measure in aggregate reduce the yield by £5.5 billion in 2025-26, rising to £9.6 billion in 2029-30 (36 per cent of the static costing). This results in a post-behavioural yield of £16.1 billion in 2029-30. These comprise:
Hmmm sort of
Raising enormous sums by loading the burden onto employers' NI seems a neat solution which won't hurting the average employee, right?
But what are the consequences? Well, it's a cost burden to business and can fairly be characterised as a tax on employment, likely to inhibit job creation.
When companies are impacted by increased costs they will pass this onto their customers (if they have pricing power and are able to) or will cuts costs, and if the Genesis is employment-related it will be through wage containment or initiatives to right-size their workforce through reducing headcount or over times increased automation. Clearly a boost to some company such as MPAC (LON:MPAC) whose packing solutions replace low skill workers with machines.
If they can't do the above it impacts profitability, cash flow and the capacity to invest and remain competitive.
None of the above is helpful for “ordinary working people” . . . . . . and most people working in the private sector work for small businesses who are run by real people whose livelihoods are being squeezed.
IMO Jayman - the vast majority of these costs will get passed on : why, because all the price setting employers are in the same boat so it won’t alter demand elasticity.
The Chancellor chose ERs NI because they are gambling on that. Raise EE’s and peoples wages go down, very unpopular. Raise ERs and the general public don’t care and don’t realise it’s coming back to them anyway.
There are a number of left of centre economists who say that the argument that increases in ERs taxes lead to reductions in employment is nonsense and every time it has gone up the effect on employment is small enough to be unmeasurable. None of these people also try and argue it is not inflationary (as far as I am aware).
OBR reckons 60% passed through to consumers but I suspect in this case that’s a massaged message to appear reasonable - it will be more like 80-90% in my view.
Points taken David, but I suspect it will be a lot worse than you think, because many big employers are very low margin businesses with little pricing power. Competitors might not increase prices, or delay it, in the hope of gaining market share. The CEO of XP Factory (LON:XPF) told me that's what they had done in the last 2 years' high wages inflation - absorbed the impact, to gain market share. Mind you, the end result is that XPF doesn't actually make any real profits at all!
There's an interesting article here on Sky, saying that the reduction in the employers NIC threshold is the real killer for big employers of part-time staff, which has resulted in the impact being far worse than their pre-budget modelling. Excerpt (refers to the major supermarkets) -
"An executive at one of the quartet said their immediate calculation was that they would have to pay "between double and treble" the additional sums they had modelled following pre-Budget reports in the media that the chancellor was preparing to increase the employer NICs rate by two percentage points."
So on balance, I think my prediction of profit warnings & sharp broker downgrades is looking more likely, but only time will tell!
Regards, Paul.
Hi Paul - I guess the issue I have around this debate is the term “Pricing power” and this assumption that a macro event impacting everyone equally invokes the same effect as a specific event.
If you run a business today competing with another 3 businesses and all of your costs go up at the same time then you will all seek to raise prices at a similar level. It is possible one competitor thinks they may be able to grab some market share by absorbing the increase but here this is unlikely - the impact to profitability would be proportionately too high.
So the highest probability is that all competitors attempt to pass through the increased costs at a similar rate. As this is labour and on average 35% of revenues that equates to a 2-3% rise in prices.
So then we find ourselves in the demand equation. I’ve just raised prices 3% do my volumes go down? Well, most people have just had a 6%+ increase so it is unlikely that the demand equation changes either.
Behaving rationally then businesses increase prices.
You are of course right that the threshold is the big problem. I looked at Card Factory (LON:CARD) and guesstimate this alone impacts them by some £5m : add in the wages and another £7m so perhaps £12m in total
To recover that they need to add 2 or 3p to the cost of a card - the same employee demographic has just had a raise of £800 p/a………will that person now stop buying cards or shop elsewhere? Unlikely in my view.
But as you say only time will tell - the OBR reckon only 60% is recoverable so if you believe that then in Card Factory (LON:CARD) case it would be a £3.5m p/a post tax hit which would be a 6% EPS headwind before growth or automation.
Completely agree Paul, I know a private business (in the food processing sector) which employs 300 people. Their additional NI cost is approximately 200K for a business which doesn't make a lot more than that. Their customers are the supermarkets so they are more of a price-taker than price-maker. I can't see where they go from here, other than possibly cutting staff. There will be plenty of quoted businesses in a similar situation.
On another worrying note, I was on a budget tax course today run by a well-known tax lecturer with contacts in the Treasury. He is convinced that dividend tax rates will be aligned with normal income tax rates in the reasonably near future, unfortunately he is not often wrong.
My $employer provides services that are things like call centres for a fixed price that is increased by an index. If we can recover the lost margin (probably some not all as linked to nae), there is likely to be an average 6 month lag.
Paul, I have retired a little earlier than expected and I am eagerly learning the investing ropes. I find the SCVR invaluable and enjoy reading the chat from the Stocko community. I wanted to add my thanks and appreciation for your tireless efforts to keep us informed and entertained. A tricky balancing act at which you excel.
Well said. The SCVR is consistently excellent. Saturdays' podcast adds extra value.
So - Is there now an incentive to hold AIM shares in a SIPP to alleviate the IHT hit ?
I'm still v unclear as to whether the SIPP trumps AIM or vice versa. If AIM shares within a SIPP don't get relief, then that's a big issue.
And I don't see a lot of point in leaving non AIM money in a SIPP if one is above £500k individual/£1m per couple - left in, it will be hit with IHT, then Income tax at the recipient's marginal rate. Taken out of the SIPP and donated, just income tax at my marginal rate - if I survive 7 years. Seems to be win if I survive, don't lose if I don't.
I'd
A rather strange budget if viewed as a one off.
A large increase in taxation and borrowing to produce approximately the same growth over a four year period as previously forecast? Really?
It would seem that the increase in employers NI (26 billion) is going almost entirely to fund the NHS (22.6 billion) in one huge slug of cash 25- 26. The NHS is a hungry horse and will easily absorb this. Whether it will lead to any perceived improvements in health care remains to be seen.
I would guess that once the NHS has become accustomed to spending such a cash injection there will be pressure to follow up with further funding on a regular basis . I dont really have a problem with this as I value the concept of the NHS ,but to suggest that this will be some how contribute to growth is a bit of a stretch for me.
Also the treatment of farmers hit with IHT undervalues the importance of homegrown food in the economy. A very small amount of money will be raised in the overall context of the budget - but with huge implications on food security. The farmers I know work very hard and I think they have been treated very badly here.
I would guess that the next budget has already been drafted with further tax rises. Both the Prime Minister and the Chancellor have already started subtly briefing the message. We will see what happens...
When huge sums of new money are given at once it tends to go largely on pay rises - I would estimate between a third and a half. Obviously this won't produce much in the way of growth, which really needs to come from incentivising the private sector.
Basically Farmers now have to give their Farm to their surviving spouse on death or gift it to their children under the 7 year rule to avoid IHT. Given Farmers often will often work beyond retirement age, there are bound to be tragic cases where these new rules will penalise those who were taking a more relaxed view under the old regime.
Basically trailing high tax rates as productive is I think likely to prove a fallacy. Unfortunately you cannot disassociate productivity from the Benefits system, and an NHS system which facilitates sickness (remember the new sickness rights) by doctors being able to write off people from work for 'Mental Health' reasons is an open door to abuse, notwithstanding the smaller amount of genuine cases.
So major reform of the system would be needed. Unfortunately that will be slow if it happens at all.
I don't see the steely toughness of those involved to reform practices, as with the Union awards.
I agree, "rights" come with responsibilities, but a lot of people forget that.
But if a farmer gifts his farm early, won't he be caught by CGT??
No, as holdover (gift) relief will be claimed. This means the recipient being gifted the asset acquires it at the donor's base cost. This does, of course, mean that the recipient will have a larger gain, if they ever sell the asset, than if they had inherited it.
Thanks. When the smoke and mirrors are taken away, this is the gist of the budget. A large rise in NI levied given to the NHS with no strings attached.
Although the American system is useless, i think a move to something like the Scandinavian system is a solution for the NHS. Instead of a county with an NHS, we are now an NHS with a small economy attached.
The us system costs a lot more and delivers a lot less (unless you are in the top 1%)
Otherwise we spend slightly less than average on health as far as I can see.
The nhs suffers from being required to treat everything but some of the profitable pathways have been privatised but when they go wrong the patient is passed back to the nhs (dodgy accounting).
https://www.statista.com/stati...
When do the changes in Capital Gains and IHT tax come into effect ?
CGT was yesterday. IHT April 26 for Aim, April 27 for SIPPs I think.
Dear Paul
Thank you, Graham and Roland for all the extraordinary hard work you all do in enabling subscribers to better understand the companies in our universe. As a now retired investment manager, I can tell you that the quality of your research, and its dissection of company balance sheets, is streets ahead of anything I have read in nearly five decades in the industry.
I own shares in PPHE (PPH-LON) and, following its third quarter trading update this morning, there is a useful research note on the company by h2Radnor available on the ResearchTree website.
Kind regards
Phillip
Wow, thanks Phillip, that's made my day! :-)
Given your experience, I hope we'll hear a lot more from you here in the comments section in future now you're retired! As we always say, it's a team sport here, with the main reports being the conversation starters, but then often more detail and insights coming from readers.
Best wishes, Paul.
Hi Paul, I am also a retired fund manager and would reiterate what Phillip has just said. Many years ago I used to work with Phillip though I suspect he may not remember me.
Best wishes, Mike
If you are who I think you are, I recall auditing your business when I started my career many years ago as a trainee accountant. Enjoyed the assignment and even recall bumping into and being introduced to a certain Richard Griffiths who achieved an awful lot as an investor.
Has everyone here worked with each other? It's like a cross between the Trueman show and Nicky Campbell :)
Dear Michael
I remember you well. It would be good to speak again after many years. How do we get in touch with each other?
Regards
Phillip
mdbarnard@hotmail.co.uk
As far as PPHE Hotel (LON:PPH) goes, less than half EPRA NAV seems like the wrong price for operators with a good track record, readily marketable assets , valuations to increase with falling rates (although debt fixed in short term). Have to question why they bother paying dividends or building new hotels when they trade at such a lowly valuation, surely the best capital allocation decision would be to buy back truckloads of their own shares
Just picked up some more Billington Holdings (LON:BILN) ... although it didn't particularly feature in the downdraft, I'm surprised that it hasn't ticked up yet....
I would struggle to buy staffing companies after this budget Paul, unles perhaps they specialise in contracting work ex-IR35. There is now a strong disincentive to hire employees both because of the higher known coats: higher min. wage and higher NI; and the increased difficulty/cost in cutting staff when needed because of new unfair dismissal legislation. This is exacerbated in some sectors now given empowerment of the unions.
The large listed staffing companies have mostly non-UK earnings.
A very good point. Thank you.
Great report yesterday Paul many thanks I see J Sainsbury (LON:SBRY) selling off it argos card section 700£million with the bank gone also, could be wrip for a takeover but with NI and MW increase its could be a big avoid?! The CEO John Hourican, NewDay's CEO and interesting chap.
Budget
What an absolute disgraceful kick in the nuts for the faming community .
Just really really depressing to have Starmer and Reeves have the gall and lack of foresight to do this .
Pensions change is outrageous , “llife” planning takes place over 40 years when you save for your future based on rules in front of you - then the robbing thieves that jump to power change rules. Its just legalised robbery, absolute disgrace .
The ONLY positive by product of the budget and its more by accident is the EIS rules now becomee very attractive however rest assured
- these will now be packaged and commercialised by the corporates into sanitised “IHT products and funds”
I really hope some of us on here get involved directly with SEED EIS and EIS companies and encourage and support the next generation with our cash .
I speak to a lot of young people just out of university many struggling to get jobs, all totally unaware they could set up a business , Seed fund it , and “have a go”but of course none of them have ever heard of Seed funding (should be compulsory at universities to encourage students and show then the steps open to set up a business with rheir skills not just go the employment route)
Seed funding I explain is so generous that investors will be lining up at the door to support and help them.- im encouraging all my staff and young friends to think about setting up a business for them to own and be passionate about , always they sigh
“I dont have the capital “
I say “dont worry use seed eis we can sort that “
Maybe we should set up a SEEDOPEDIA
Thats not a bad shout, actually .
We must all know young people with talent and ideas that would benefit and are currently “lost” and know nothing of how much support they can get from high next worths who such tax advantages that a 100k imvestment that fails costs circa 14k
SEED EIS - i encourage everyone to learn about it and use educate potential beneficiaries then your wealth to help someone have a go at building a business .
- seed 250k limit now (used to be 100k
- 3 year time limit
- tax relief on entry
-CGT relief on entry
- tax relief on failure
- tax free on exit
Theres a really good Seed EIS calculator online somewhere that tells you your net costs deoemding on outcome
Only started this post to comment on farmers and say what a disgrace but feel quite positive now , think this post was good for mental health .
A lot of money flows to the advisers who intermediate SEIS/EIS fundraisings. So they always have an incentive to sell an opportunity, whether it's a decent business plan or not. Also, they have no incentive to realise the investments so your money is locked up for many years and you have no control over when it is realised which usually requires your company to be bought or significantly recapitalised. There are many zombie EIS investments out there.
My point is not to engage with advisors / intermediate .
Engage directly and encourage help and support someone our potential entrepreneurs .
Seed is remarkably easy to set up, no need for advisors or funds .
To quote jerry mcguire “show me the money”
You will get far more pleasure and engagement by doing it yourself direct .
And if it goes to shit you have lost 14% of your investment !
Im not saying put all your eggs in this basket for a % of your net worth into direct investments will give you so much more than investing in a company or fund .
I agree it is profoundly depressing for farmers. Round our way agricultural land is edging up to £12k/acre. I believe you need at least 150 acres for an economic size, so serious family farmers will be well beyond the threshold. Not forgetting their barns full of expensive kit. This Government appears to have no coherent policy for land use and food security. As Jezza Clarkson said yesterday to his fellow farmers - Don't top yourself, just survive five years and this lot will be gone. Or words to that effect.
Clarkson is not a farmer. He is an actor disguised as one. Most of the time, if not all, he talks rubbish.
Many in the 'real' farming community welcome the fact that Clarkson has eloquently and forcefully highlighted the reality of the issues they face. He does not talk rubbish. You may not like him as a personality, but many millions do.
Charlie hi, just because many millions do like Mr Clarkson, doesn't absolve him from talking rubbish.... in fact probably emboldens him. i agree he has highlighted the challenges of farming, but he is certainly NOT the representative of the community...
I have worked in the real farming community for 47 years and he does talk rubbish. I stopped watching as I couldn't watch the ridiculous things he did or said and the wanton destruction of machinery. He obviously doesn't need to make his money from farming.
Whether or not Clarkson has done a great job of bringing the realities of farming to a wider audience is open to debate.
However, the NFU is an echo chamber and we only talk among ourselves, to the supermarkets and to whoever is the agricultural minister of the day. The NFU has a very poor communications strategy for engaging the rest of the country. I have experience in this area having worked for www.SAOS.coop back in the day and been involved with putting national marketing strategies together in the meat sector.
Maybe , but I know more about farming than I ever did and he put farming on the social map. Not all bad
I reckon you need a minimum of 500 acres as an economic unit and I would stress minimum. A very specialist grower may be able to make money with 150 acres but not your run of the mill combinables/livestock farmer.
Completely depends on where you are and what you are farming.
If landowners plan ahead they can avoid inheritance tax. Another reason for farmers to complain....and I should know cos I work for one,
What do you think of Seedrs now named Republic as a seed platform?
Always really enjoy your posts, thank you.
"What an absolute disgraceful kick in the nuts for the faming community ."
Hopefully some sense may be seen somewhere down the line - hopefully farmers have their pitchforks at the ready - i think most working people would understand that passing on of farms from generation to generation at lower level should not be prevented from happening - in that regard stupid policies that have almsot nil backing will hopefully get the chop sooner or later.
Note as if the other bad news wasnt enough - they have also in the detail of the budget kicked farmers in the nuts by reversing the reversed decision of the tories not to treat double cab pickups as cars - the tories scrapped that propsed change less than 10 days after they announced it - labour have decided to go ahead.
I cant see Starmer trning up at any farmer meet and greets any time soon.
The Guardian has just quoted Steve Reed, DEFRA's minister, as saying that farmers "will just have to learn to do more with less". That is so arrogant. Reed has been a politician for London councils and constituencies all his working life. So ideally qualified to rule agriculture in Starmer's eys, it would appear.
I last made comment on WYN when they said demand was decreasing when one of the factors mentioned was the increase in solar farm applications on good farmland was impacting production. We have less than 50% food security in the UK and this IHT decision will impact further. When we then look at our energy production supply also decreasing in the UK which has been created by both parties, the combined depletion of UK energy and food production does not auger well for the future. Cutting the fuel allowance will also impact as our electricity cost is the highest in Europe. The fact that a substantial amount is going to the NHS when we have an obesity epidemic where individuals do not have to accept the cost or demonstrate any personal responsibility will not provide a healthier population. Thank you all for your constructive comment following the budget.
the thing is ref food and energy we have always got by on a near flawless basis - compare us to america where people are used to losing the entire contents of their freezer once every 3-4 months due to power cuts and i would say we have it pretty good.
If we have very few power cuts and plenty of food on the table thats job done for me - i agree we do need to up infastructure spend ref renewables etc - i am fan of renewables but i dont want to throw silly money down the drain. I am 100% happy with quality of my electric supply and food i can get from my local shops.
It seems to be constant nonsense them that ultimate about doom and gloom or that armageddon is just around the corner when we will probabaly just about manage - if we do run short at times well that would be the shock to the system that would get the job done. as a semi oldie used to frequesnt power cuts back in the day and lack of exotic food i appreciate what we have now and think its actually top notch.
I do remember the power cuts, interestingly productivity increased, we worked our 40 hrs in 4 days and had an extra day off. I went fishing to help put food on the table. Different times . In these unsettling times food and energy security is paramount
"I have altered the deal. Pray that I don't alter it any further." Labour has form for raiding pensions. It's a big juicy grub.
As I recall, Blair said that since they were offering tax perks for pension savings it was fair that they laid down terms for its use. In other words, it's not your money, it's theirs.
In my early 20's I was training as an accountant. One of our clients was a pension consultant, IIRC. There was some deal whereby he could talk to the staff to persuade them to join whatever nonsense he was trying to flog. Naively, I ended up contracted out with one of those with-profit schemes. In retrospect, I wish I hadn't.
Roll on to about 2015. It was a time when the gov't were trying to shove private pensions down everyone's throats. I was a little wiser this time, and already had contracted back in. I got some paperwork from my employer. The deal was that it would be invested in bonds/gilts. Yes, bonds. At a time when interest rates were near zero.
The logic is that bonds were "risk free". Yes, fine, but you're locking in low interest rates. If interest rates were to rise for any reason, those bonds would go down in value.
It has been my observation that insurance/pension companies always have a logic as to what they do, but that logic is always wrong. Useless.
So in the dustbin the paperwork went.
I have long come to the conclusion that pension schemes are a waste of time. I don't want other people telling me what I can and cannot with money I've contributed. So I save as much money as possible in ISAs, buy and sell when I want, draw down whatever I want whenever I want.
We go through periods where insurance companies are being investigated for mi-sselling. I have a simple heuristic: if they're selling it, then they're mis-selling it. These companies love their "schemes".
So that'll be my spleen vented for the morning.
That's a rant about pensions that matches motorist rants about cyclists. You have sensible people and you have irresponsible idiots - blaming the mode of transport for the behaviour of individual idiots doesn't get us anywhere.
Pensions as a legal structure are very useful - at their simplest they are a mechanism for earnings deferral - they allow you to smooth your earnings over your lifespan, and enable most people to pay less income tax over their lifespan.
Blair wasn't wrong. Why on earth would any government forego income tax revenues now by dishing out tax relief with no conditions attached?
What you buy inside the pension wrapper is another matter. You don't need to go anywhere near anybody selling you anything. Stick a tracker in a SIPP. You don't need to sign up with a scheme that selects your investments or jump into bed with an insurance company. As ever, there are good companies and bad companies, choose your provider like you choose your next car.
Car dealers, supermarkets, double glazing, utilities, the coffee shop down the road - they are all mis-selling if you apply FCA rules to them or suddenly decide they owe you a duty of care!
great post, socialism is hugely destructive to creating a self reliant society the benefit culture will suck us all dry in the end.
I recommend robert Murray brown who has written extensively on this over the years. He also set up a group that never gained critical mass.
I tend to agree with Michael Howell who said yesterday "Brilliant UK Budget today by Reeves for the Rest of the World. Kills UK enterprise and disincentivises employment. Masterstroke in exporting wealth creation!"
However most people with assets have done exceptionally well since the banking crisis/QE 2008. Those with no assets, at the low income end, have had a crap time. Even during Covid they were out there working while others hid at home on better pay so can understand why they wouldn't give a monkeys about IHT etc.
As far as investment goes we're in the stronger seasonal part of the year now as Paul says so hopefully we'll see a decent period. I'll be reducing UK exposure again next year tho as there's no growth in sight for the rest of the decade as far as I can see. Wouldn't mind a major selloff next year, which is a reasonable possibility I think, to rejig everything.
However most people with assets have done exceptionally well since the banking crisis/QE 2008. Those with no assets, at the low income end, have had a crap time. Even during Covid they were out there working while others hid at home on better pay so can understand why they wouldn't give a monkeys about IHT etc.
Well said its pretty simple provide jobs , have decent minimum wage keep things ticking over and build some affordable housing and keep the lights on - its a complete disgrace that whatever the promises there is not enough affordable housing in the country - labour are making the right noises in that direction but they have very hard job to deliver anything useful bearing in mind the rate of population increase we have. the moaning us us lucky ones matters not a jot what maters is that your average person who wants to do a working week can get bye and can have a reasonably price roof over their heads to have some privacy in life - they real heroes are the poeple who put in working week dont moan and get on with their life without asking for the earth of others.
The problem with affordable housing is that most people want it and can you blame them. Once in you are there for life, regardless of your financial circumstances, supported financially by people that do not live in subsidised housing. It should be meanstested and not something you have a right to live in forever, we cannot afford it.
Budget was better than feared in my view, from a personal tax perspective. Not good for the private sector with the £25bn national insurance grab though.
On inheritance tax, there's still a £1m combined limit. I take the view that, when the time comes, giving much of the excess to charitable causes in your will is the best way to avoid the government wasting your hard earned life's work!
CGT and Dividend tax were both better than feared + still get the generous pension relief in on the SIPP.
Another profit warning on Nexteq (LON:NXQ) today. Be good to get some thoughts on this one.
My morning smallcap tweet: Bouncy bounties after bumpy Budget build-up
Totally (LON:TLY) Nexteq (LON:NXQ) Synthomer (LON:SYNT) Cordel (LON:CRDL) Oncimmune Holdings (LON:ONC) Heiq (LON:HEIQ), Filtronic (LON:FTC), PPHE Hotel (LON:PPH), Seeing Machines (LON:SEE)
◄Totally (TLY)► renews Revolving Credit Facility "at a level of £3.5m to better reflect the current size of the business". [SP=8.2 Cap=16m]
◄Nexteq (NXQ)► warns FY-Dec rev 10-12% below market expectations of $95m due to de-stocking and delayed project launches. Expects adj pretax $6m+ against F/C $9.4m. FY25 order book lower in value than expected. The pipeline of new product launches and new customer projects remains encouraging. [SP=90 Cap=55m]
◄Synthomer (SYNT)► Q3 trading broadly in line with mgmt exp. Still expects to be modestly FCF positive in FY24. [SP=172.8 Cap=283m]
◄Cordel (CRDL)► contract with Australian Rail Track Corporation extended to Aug 2025.and includes network wide Light Direction and Ranging (LiDAR), Video and Clearance Assessments. [SP=6.81 Cap=15m]
◄Oncimmune (ONC)► sounds in line [SP=15.3 Cap=12m]
◄HeiQ (HEIQ)► results for 18 months to June. Outlook - Advanced Materials mkt weak. LifeSciences unit "expected to grow significantly as industrial pro-/postbiotic solutions gain market acceptance in various applications". De-lists 19 Nov. [SP=3.7 Cap=6m]
In line: FTC, PPH, SEE
Paul wanted to say some of your ideas on Tuesday of beaten down AIM stocks really took off yesterday afternoon. I had a few on my watchlist and bit the bullet yesterday morning returning myself 10-15%. Probably yet another beer I owe you.
I do not take your thoughts as tips but just ideas and do my own research but love hearing someone else’s perspective to either confirm or challenge my own
Thanks Brookeda,
Yes I also noticed that most of the shares on my recent bargain ideas watchlist earlier this week, seemed to put in a large surge yesterday afternoon, so looks like between us we found some nice opportunities. In my case it was more about holding my nerve on shares that I already held (in particular larger positions in Beeks Financial Cloud (LON:BKS) and Intercede (LON:IGP) ). It's so important to not let wider market or macro problems (esp if short-term, like a budget) scare you out of conviction holdings.
Trying to sell in advance and then rebuy right at the low often fails with small caps, because price movements can be so quick, and lack liquidity. As we saw yesterday, blink and you missed a c.15% rise in some of these things on my ideas list.
I remember a similar thing happening in March 2020 at the covid low. I was lucky enough to have a cash pile, from shorting the indices, but when I tried to deploy it in bombed out small caps, there weren't any sellers left, so I could only buy scraps, then the prices rocketed as everyone trying to time the market attempted to buy at the same time!
My view is that risk:reward was good this week -
Upside scenario - attacks on ISAs & AIM IHT not as bad as feared, result would be a rapid & strong recovery in bombed out small caps (which is what has happened).
Downside scenario - AIM IHT scrapped, ISAs capped, etc, would have led to further short-term downside, but wouldn't really matter longer-term as good companies at reasonable prices would end up with a positive outcome through either takeover bids, or moving to the full list. Also would provide fresh buying opportunities.
Well done to people who grabbed some bargains, but maybe a bigger well done to those investors here who simply ignored all this background noise and didn't do anything!
Regards, Paul.
IHT on pensions was a real blow. I note that this happens in April 2027, after consultation on the implementation process. I think that your kids inheriting your (taxable) pension benefits, but not a lump sum, would have been much better.
For me the impact is that I will want to sell shares and pass on money now, in the hope of surviving 7 years and the money becoming IHT free. AIM and EIS schemes look interesting, but have the returns been any good?
Family businesses and small farms are still low IHT. I'm too old, but they may get a boost.
ISA's still intact, which surprises me.
Back to investing......which hasn't been at all easy recently....
Indeed an absolute bugger for our next generation, we switched to SIPP's for exactly that purpose. Thankfully we did this a couple of years back when rates were uberhigh so the buy out some was a no brainer. Still glad we did it, if you pass away early a DB pension just goes up in smoke bar spouses pension if applicable.
Many of us probably sighed a little relief and can stomach extra spending but the kicker is the total lack of growth a very far cry from all the hype. OBR numbers and OFS's Paul Johnston quite damming of it all.
The world now knows that U.K. PLC is forecasted to grow at a rate of 1-2 % over the next 5 years. Which genius thought this was a great message to deliver. I am struggling to see how the flow of investment funds away from the U.K. will reverse. As an individual investor I believe I need to increase my exposure to the US where both a more business friendly environment and a AI/ technology revolution is underway.
Regarding the growth figures, I don't know why they bother publishing their estimates out to 4 years, there's far too many unknowns.
But estimates of 1.6%-1.8% are quite pathetic. No wonder the BRICS countries are overtaking the G7.
I think we are currently top of the G7 ref growth - you cant always magic it up like the glory days.
I'm 44. Everything I buy now, where possible, will be in the kid's names. I fail to understand why many people wait until death to pass things over, when the reality is on average passing an estate to your children who are in their 50's+ does little to help them. I want my kids to have everything I have whilst I'm alive so maybe they can take me to Disneyland.
As long as one's kids are hard working, motivated and moral, I totally agree... plus that they won't get divorced ... and that they are good investors / don't get scammed ...
Yes, I've told them I'll happily buy them a house. They can then pay me 'rent' which in reality will be money that I invest for them. You're right about divorces etc, whilst it is not for me to dictate, I'd like to see a pre-nup. Nothing too major apart from assets that were brought into the relationship remain. Hopefully they'll have kids and will want to pass on what was created between them onto the next generation.
If they pay you rent that is a gift with reservation of benefits and is not exempt from IHT unfortunately. They would have to live in it rent free...
Much easier to poor sometimes lol or spend it all!
But if you are on here it probably suggests that you are a prudent with your money and don't like to see it wasted...
*to be poor
Investor John, Viz wrote "rent" which in reality will be money that I invest for them, Presumably those investments will be in the names of the children. Clearly if he was actually, personally, charging them Rent then it would be a GWR and not a PET.
Regrettably I agree with Cancun. I have had to let mine go to keep my sanity......
My tax planning had been to leave it as lifetime gifts - until I met my son's chosen life partner!
you made me larf..........
Sorry Mum/Dad, we're trying to be prudent with your cash. You can have a weekend at Euro Disney!
. I fail to understand why many people wait until death to pass things over
i suspect the reailty is they dont trust the kids "enough" to not screw them over - even if you do trust them you would probably need to be barking mad not to imagine a scenario where they might do that if something were to happen in their life thats changes things - heck if not them then their 3rd partners down the line might do the dirty
Note passing on wealth has huge practical problems - eg if you give your house to your kids and stay in said house they immediately start to have capital gains problems that would not exists whilst you still owned and had owners exemption from cgt.
Last year my husband died and so I have (to my mind) the unenviable responsibility of looking after the ‘cash’ and house…So to that end yesterday I gave our 3 daughters the ‘residue cash ‘ from the bank (not an enormous amount but nice to have ) so that the 7 year countdown can begin…Now the SIPP I can’t really touch due to him dying aged 75 and 5 months…as if I do I will be clobbered by tax..So I am off to see an IFA about how to get that to the grandkids upon my demise ..Meanwhile they are not getting the house or the other money which is all ISA’d ….Why …well mainly if I need help later on I want to have the money available to choose when or where I go …(there are LPAs in the filing cabinet so if I get dementia or become unable to make decisions they can be used)…But my attitude is they were brought up and supported by us and given the best state eduction we could get them (Grammar school here ) plus supported through university to get the best degrees they could attain…Luckily all did well…My aim now is to grow the ISAs as best I can so that when I finally clap my clogs there is a pretty decent amount of money for them to inherit. Yes tax will be paid but the final amount it will be far more ££££ than if I subdivide it now and rely on their generosity for my future….I call that having an independant streak and dealing with the ISAs give me a purpose and a massive interest. So thanks Paul and team as the ISA is doing well using Stockopedia as an ideas forum
Thanks for your comments Pennyledges - its nice to see someone taking sesnible pragmatic steps to navigate the slippy slope of old age - i think your route is sensible but does highlight the many complexities and moving issues better than my normal tar with one brush could do.
Hi Penny, I am sure I speak for the majority when I say I wish my Grandparents had been even half as switched on as what you are when it came to future planning and wealth protection. Your family are lucky to have you!
Gifting:
Don't give away what you might need.
Make considered decisions.
Don't let tax and money take over.
Keep it simple.
Perhaps they can't afford to pass it on "now"? ie they need the assets and the income generated by them. That's my situation.
Regards
Michael
...EIS schemes look interesting, but have the returns been any good?
So far as far as I can tell for mine - ok (beat asx) but this is a long term illiquid investment with time horizons that are *much* longer than most are OK with.
I started this 12y ago instead of a btl. For me a moral decision. I wanted to support British small companies. Btl would have made more money.
I think EIS has had a very poor track record from my experience.
Hi Andrewdb, I completely agree re your final para and took the same decision.
As for EIS/SEIS returns, all I can say is that when they are good they can be very very good but when bad they are often bloody. My few successes have been heart warming but outweighed by the losses. Nothing that I can’t afford to lose but annoying when good businesses fail due to third parties or uncontrollable circumstances.
Really upsetting when entrepreneurs one has backed walk away with little regard for outside investors; sadly there are spivs out there who turn out to be less than honourable. Moral: look at the people as much as the business case.
Final point, planned time lines seem mostly to go wrong even with a successful start up. Periods of illiquid holding thus very disappointing.
Indeed. In my experience about
20% chancers spivs fantasists
20% it just didn't work
10% rug pulled by creditor
50% ran out of money
The tax free bit only applied if you were <75 when passing away. Given the average age is higher than this at the moment this won't be a massive income stream it was only 8 years post state retirement. I am struggling to see why they did it, it will put a cap on how much people put away I suspect going forward and result in even less income for the government... The farmers one is the big one in my view and this will receive a massive political backlash. As an aside where is the growth coming from... a budget for growth... how can you say that when there is minimal growth during your term in government!!
"For me the impact is that I will want to sell shares and pass on money now, in the hope of surviving 7 years and the money becoming IHT free."
Until they stop that!
I left the UK a while back and where I now live (and am tax resident) France, you can gift in simple terms €100,000 in your liftime and then it becomes taxable at the time of the gift.
That said, while I think the threshold is too low (it is $13,610,000 in the states) I am fairly relaxed about it. For one I'll be dead, but secondly I inherited about four times what my mother inherited from her mother and my son will cop at least 10 times what I inherited. Would I rather he did not have to pay tax yes, would I rather, if does, it didn't go to government who are hopeless at allocating capital yes, but is there is not much I can do about it? I don't qualify for Monaco, Jersey etc so no, I just have to live with it.
Regards
Michael
Hi Michael,
I see that France's Finance Committee are talking about taxing French citizens abroad if they have lived in France for three of the past 10 years and now live in a country with a tax rate at least 50% lower than France's.
Source: EU Member to Tax its Citizens Worldwide?
It wouldn’t surprise, they are all at it. That said I would like to see them enforce it. :-)
Michael