Small Cap Value Report (Thu 4 April 2024) - MOTR, CAV, CABP, FUTR, GHH

Good morning from Paul & Graham!
Almost tax year end, so we only have today & tomorrow to make full use of our ISA allowances, and similar.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Just a reminder for anyone who has forgotten. This is a list below of companies reporting, and we'll write up sections on the more interesting ones. It is not a to do list, and we usually cannot cover everything (although it's quiet today, so we probably can today!)
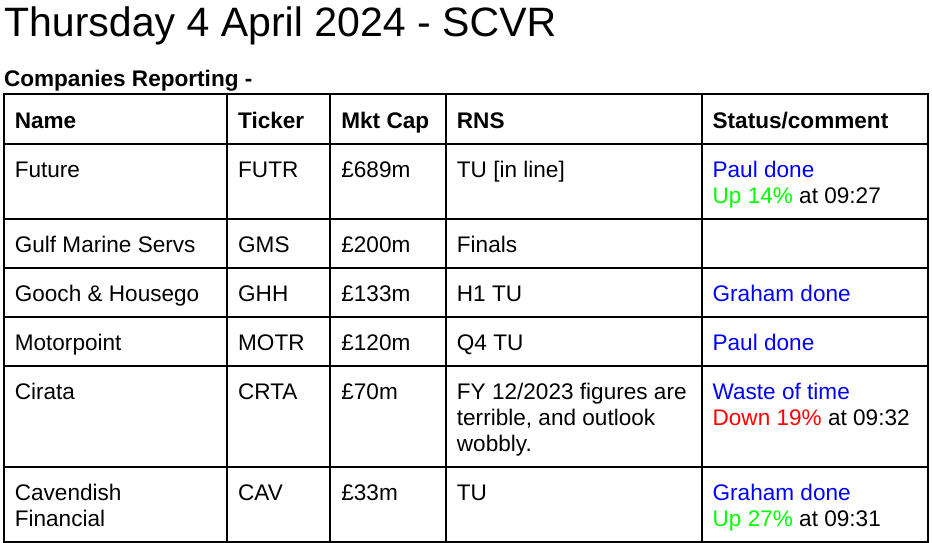
Other mid-morning movers (with news) -
Cab Payments Holdings (LON:CABP) - up 12% to 123.5p (£315m) - positive market reaction to news of it receiving a European licence -
“CAB Payments announces that its Dutch subsidiary has secured a payment service provider licence with De Nederlandsche Bank N.V. (DNB). This entity will be eligible to provide services across the European Economic Area (EEA) under the passporting regime. This is one of the operational and strategic initiatives that underpin the Group's growth aspirations for 2024 and beyond. CAB Payments is confident that being able to provide services across the EEA will bring significant opportunity for the business and for the clients and the markets it serves. “
Summaries of main sections
Motorpoint (LON:MOTR) - 134p (pre-market) £121m - Q4 Trading Update - Paul - AMBER
This car supermarket chain has seen an improvement in trading in Q4, although the guidance is still for a hefty £8m loss for FY 3/2024. The sprightly tone of today's update glosses over the negatives. Broker Shore Capital is hoping it can eke out a £3.0m profit in FY 3/2025. Vehicle stocking loans are now much more expensive, a considerable sector headwind.
Cavendish Financial (LON:CAV) - 10.46p (+21%) (£40m) - Trading Update - Graham - GREEN
A good update as H2 revenues are an impressive £34.5m, up 77% vs. H1. The cash balance bounced higher by £8m over six months to £20m. The Cavendish share price is still lower than it was at the end of 2023 and so there is no reason to change my positive stance.
Future (LON:FUTR) - up 14% to 682p (£783m) - Trading Statement - Paul - GREEN
A sprawling group of websites and magazines issues an in line H1 update. I can't understand why it's so cheap, as mentioned in previous reviews here. So well worth readers taking a closer look, I'd say on my initial quick review.
Gooch & Housego (LON:GHH) - up 3% to 529.4p (£136m) - Half Year Trading Update - Graham - AMBER
An in line with expectations update, although anything else would have been a shock after it already warned on profits in February. I still find this photonics company interesting but it hasn’t yet demonstrated the quality I think is needed to make it a compelling investment.
Paul's Section:
Motorpoint (LON:MOTR)
134p (pre-market) £121m - Q4 Trading Update - Paul - AMBER
Motorpoint Group PLC, the UK's leading independent omnichannel vehicle retailer, provides an update on its trading performance for the quarter ended 31 March 2024 ("Q4") ahead of announcing its Final Results for the year ended 31 March 2024.
MOTR operates 20 large car supermarket sites in the UK, and also sells online, offering mainly nearly new cars. Profitability has collapsed in the last year, due to various factors, including increased online competition, difficulty sourcing vehicles, reduced finance commission, and a sharp fall in used car prices last autumn.
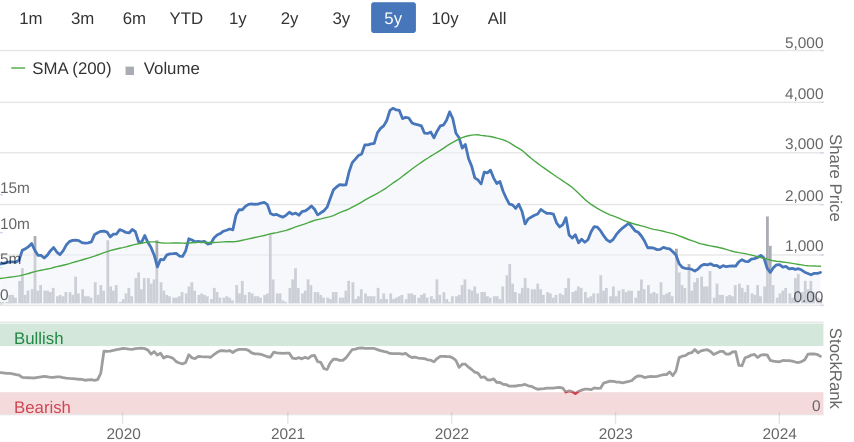
Despite that the share price has put in a decent recovery in recent months, which did surprise me, as it wasn’t driven by any good news from the company.
MOTR issued a nasty profit warning on 30/1/2024, and Zeus slashed forecast losses from £(3.2)m to £(8.7)m, due to falling used car prices, but reading today’s update it’s almost as if that never happened!
H1 results were poor, with a PBT loss of £(3.7)m, on revenues of £607m. A stand-out feature being soaring finance costs (due to higher interest rates) of £5.3m which more than wiped out a small operating profit of £1.6m. This is a big problem for the whole sector, which typically use vehicle stocking loans to finance inventories of cars, which used to be cheap, but are now a lot more expensive.
Today’s update sounds more encouraging, although somewhat vague & light on specifics -
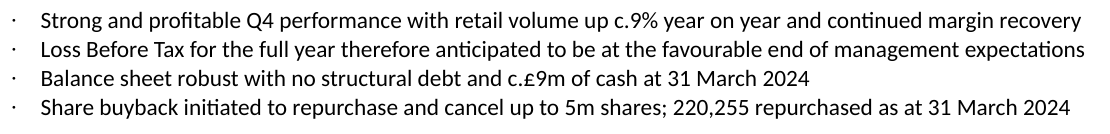
Profitability - this all sounds encouraging -
As anticipated in our Q3 Trading Update, the positive momentum experienced at the start of the calendar year continued through February and March, with Q4 retail volume increasing by c.9% year on year. As a consequence, January, February and March were all profitable months. Consumer demand has picked up, and we have benefitted from the numerous enhancements made to our digital presence during the past year which, among other things, is generating strong website traffic. Margins gradually improved through Q4 as we increased stock turn and sold through stock affected by the abrupt Q3 correction in used car values.
Balance sheet - I wouldn’t call it strong. Last reported NTAV was £32m. MOTR conspicuously lacks the big freehold property assets which are typical of traditional car dealers like Vertu Motors (LON:VTU)
Hence it’s rather odd to see the company doing share buybacks, when it’s loaded up with debt to finance its inventories.
Vehicle stocking loans were £102m at 30/9/2023, but it ignores this debt and claims to have net cash of £11.2m in the H1 results headlines, reduced to £9m at 31/3/2024.
Broker update - Shore Capital helps us out with an update note this morning, thanks for that. It says “evidence for a recovery is building”.
Shore says that the range of expectations for FY 3/2024 is a loss of between £8.0m to £8.5m, so I would say being at the “favourable end” of this range is far from a good outcome!
Shore reckons MOTR could bounce back into a modest adj PBT of £3.0m in FY 3/2025. Given the large revenues figure of over £1.1bn, it doesn’t take much of a change in margins to move profit up or down.
Outlook - sounds upbeat -
"I am delighted that the difficult conditions experienced in 2023 have eased in Q4 and, combined with our focus on driving operational excellence through a programme we call Brilliant Basics, has meant that Q4 was characterised by consistent profitability. We are achieving growth, increasing stock turn and improving margins, and this is expected to continue into FY25 as supply improves following recent new car registration growth. I am therefore optimistic for FY25 and look forward to Motorpoint making the most of the growth opportunities ahead."
Paul’s opinion - I like the concept of car supermarkets, but MOTR has a very unreliable track record of profits - we’ve now had two years of breakeven or losses.
It’s difficult to see why this company is valued at £120m, but maybe investors are hoping it can return to pre-pandemic profitability c.£20m pa. That might be a tall order, because interest rates are now so much higher, making it much more expensive to finance the stocking loans required for its inventories of vehicles.
With little asset backing to fall back on, the valuation seems to have got ahead of itself in my opinion. That said, at least current trading is improving from the poor performance in Q1 to Q3. Today’s update strikes me as over-embellished by the PR. It’s after all dressing up a lousy, loss-making result for FY 3/2024 as if it were some kind of triumph. Although it's fair to say that trading now seems to be on an improving trend.
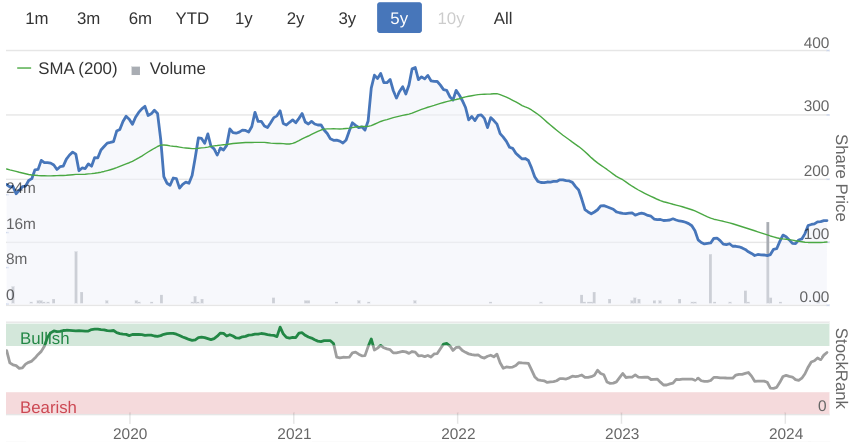
Note that the share count has actually fallen over this period, so in theory there's no reason why the share price couldn't return to previous highs, if profitability returns.
Future (LON:FUTR)
Up 14% to 682p (£783m) - Trading Statement - Paul - GREEN
My preconception of this share is positive, checking my previous notes here -
7/12/2023 - GREEN at 613p - FY 9/2023 results, shares look superb value.
7/2/2024 - GREEN at 718p - AGM TU, slightly below exps first 4 months. Why so cheap? Rapid debt reduction means I’m not worried about weak balance sheet.
Today we get an H1 update -
Future plc (LSE: FUTR; "Future" or "the Group"), the global platform for specialist media, today announces a post-close trading for the six months ended 31 March 2024.
Overall - trading is in line with expectations for FY 9/2024 -
As a result, the Group is on-track to deliver on expectations for FY 2024, subject to impact of foreign exchange translation.
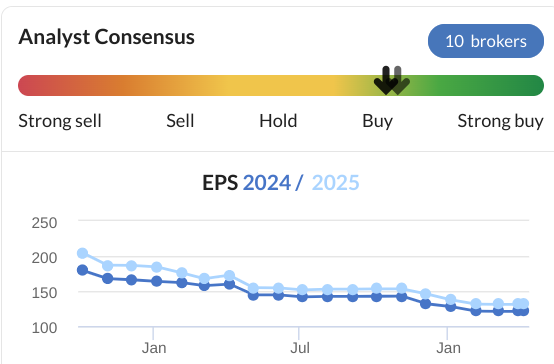
The StockReport is showing consensus of 121p adj EPS (up 9% on LY), which means at today’s increased share price of 682p the PER is only 5.6x - I don’t understand this valuation, why is it so cheap?
Note that forecasts have reduced a lot, so maybe the market was pricing in further weakness?
Returned to organic revenue growth in Q2.
Reorganisation into 3 business units will make it “more agile and less complex” apparently.
More detail - this sounds a bit mixed -
The return to growth has been driven by a strong performance in Go.Compare, alongside good growth in B2B, and a resilient performance in Magazines. This has been offset by a more challenging performance in affiliate products and digital advertising as macroeconomic pressures and low visibility continue to impact the wider sector. Website users' broad stabilisation has continued in Q2 but remains in year-on-year decline. Importantly, the implementation of the Growth Acceleration Strategy (GAS), as outlined at full-year results in December 2023, is underway, with encouraging progress from the Hero brands, which continue to outperform the wider brand portfolio. This has been combined with a stronger performance in US direct advertising, a key strategic initiative, driven by the continued focus on premiumisation of advertising inventory benefiting from the Group's scale and first-party data.
Cash - I would have preferred disclosure of what the net debt figure is, rather than general reassurance that cashflow has been good, but this will have to do -
The Group is highly cash generative and cash conversion in the half has been strong.
Paul’s opinion - as before, I’m perplexed as to why this decent, cash generative business is rated so cheaply by the market. Surely we could put it on a PER of say 10x? That would give a target share price of £12/share, giving c.76% upside from the current price.
Maybe the market might be worried that some parts of the business could be in long-term decline, I seem to recall that’s been mentioned as a concern by some readers here in the past. So that would need careful checking.
Overall at this valuation, I think FUTR looks well worth a closer investigation by readers here. Remember we’re only doing quick reviews of the numbers, we’re not digging right down into the business models, and trying to assess what the future holds - that’s your job! But on my basic review, I have to say the valuation looks highly attractive, so I’ll stay at GREEN. If you find anything wrong, let us know in the comments below!
Graham’s Section:
Cavendish Financial (LON:CAV)
10.46p (+21%) (£40m) - Trading Update - Graham - GREEN
Cavendish (LON: CAV), a leading UK mid-market investment bank, today issues a trading update for the year ended 31 March 2024.
Any signs of green shoots? Here are the key points:
H2 revenues up 77% to £34.5m vs H1 revenues of £19.5m (these are pro forma revenues; Cavendish was created by a merger that took place in September 2023).
Full-year revenues on a pro forma basis are up by 7% to £54m.
The pro forma figures are what really matter here, to avoid any distortions caused by the merger.
And then I would say it’s the full-year revenues that really matter, not a comparison of H2 vs H1. The timing of large deals can cause a bounce in a 6-month period, but I wouldn’t say that this is particularly meaningful unless there is good progress over a full year..
Cash at the end of March 2024 was £20m, covering nearly two thirds of last night’s market cap and up from £12m at the end of H1.
Outlook
Whilst the interest rate cycle appears to have peaked, conditions continue to impact demand for UK equities, making deal execution in ECM (GN note: equity capital markets) challenging across all market participants. However, private and public M&A has remained buoyant in H2 and our pipeline across both ECM and M&A remains good.
Graham’s view
While it was an excellent H2, and it does bode well for FY 2025, personally I’d still like to see another 6-12 months of better performance before getting too excited about a sustained recovery.
The positive market reaction to this update could be a reflection of the fact that the cash balance shot up to £20m; it doesn’t make a lot of sense for this company to have an enterprise value of only c. £13m, which is what it would have today if the share price hadn’t moved.
Also, the Cavendish share price has been quite weak in recent months, as if the market was pricing in very bad news into today’s update. That bad news hasn’t materialised:
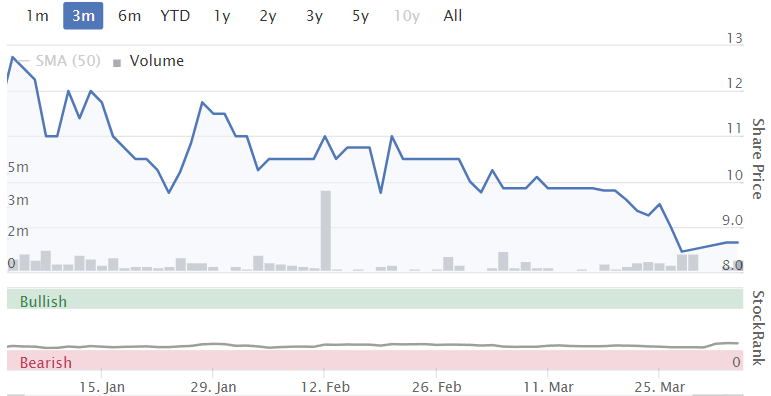
I’m remaining positive on this share as it is still cheaper than it was at the end of 2023, when I put it on my best ideas list for 2024. All of my reasons for putting it on that list are still intact: a strong balance sheet with a meaningful amount of net cash vs. the market cap, good prospects for recovery if/when the UK small-cap market rebounds, and weakened competition as Cenkos and finnCap executives work together instead of being rivals!
Gooch & Housego (LON:GHH)
Up 3% to 529.4p (£136m) - Half Year Trading Update - Graham - AMBER
This is an in line update for H1 (the full year ends in September, H1 in March)..
Gooch & Housego PLC (AIM: GHH), the specialist manufacturer of photonic components and systems, provides an update on trading for the six months ended 31 March 2024.
Note that GHH had a profit warning in February, covered by Paul here. The all-too-familiar word “destocking” was used then.
Key points from today’s update:
As previously reported, they have seen customers in some markets have “normalise their inventory holdings resulting in lower levels of demand for some of the Group’s products”.
Destocking is expected to end by the end of 2024.
H1 revenue down 5% to £67.5m and this includes the positive effect of acquisitions, i.e. the organic performance will be worse than this.
Order book is down 7% year-on-year, but GHH says it has grown “on an organic constant currency basis”, and “provides good coverage for our expected second half revenues”.
GHH sold a business last month (for £9m), and this would explain why its order book could be up on an organic basis, while actually falling.
Net debt (including leases) has grown a little in recent months, and now sits at £32m.
Strategy: manufacturing is being selectively outsourced, while the recent disposal “allows the Group to focus its resources on those parts of its A&D (GN note: aerospace and defence) portfolio where it can differentiate itself and achieve acceptable returns.”
The sold business made a loss in the most recent financial year.
CEO comment excerpts:
…we have further improved our operational performance reducing our overdue backlog and lead times.
Following the strategic addition of the GS Optics and Artemis Optical businesses in FY2023, we have already been rewarded with new customer orders as a result of the Group's enhanced portfolio.
"The divestment of our EM4 business in March this year represented an important milestone on our journey to focus our A&D business on those areas where we can secure acceptable returns, supporting the Group's path to mid-teens profitability."
Estimates: Cavendish see FY 2024 adj. PBT of £9.6m, rising to £13.3m in FY 2025. However I’d watch out for some large adjustments so that actual PBT is likely to be very different, based on the track record here (and the likely impact of the recent acquisitions/disposal).
Graham’s view
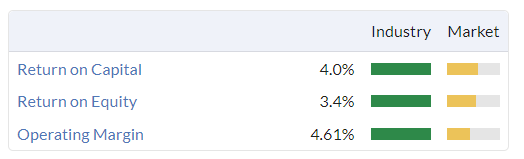
I’ve always thought this stock was worth keeping an eye on, but it has unfortunately never matched my enthusiasm with a really strong financial performance.
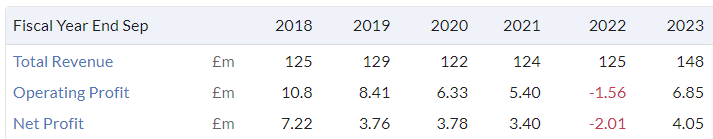
Maybe margins can improve with the outsourcing strategy? It certainly needs some kind of catalyst to improve its metrics.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

94 comments
On Future (LON:FUTR) I've never looked at it in detail, but looks like a portfolio of news/content websites? As someone in a related industry, I can think of two major headwinds:
1 - Google search results are going to fundamentally change with AI. Google's version is Search Generative Experience (SGE). Right now Future gets probably lots of free traffic from Google SEO. As their sites rank well. However, will they still rank well when the paradigm changes to SGE? Will SGE lead to less clicks/traffic from Google to publisher websites (and hence less ads shown)?
2 - Loss of third party cookies in Google Chrome. Which is the biggest browser in use, slated for later this year or in 2025. This will impact publishers massively, as the ads they show on their websites rely on third party cookies to get advertisers to pay high amounts (CPMs, CPCs) for the ad. The third party cookie is what lets advertisers target the specific customers they want, using ads shown on these publisher websites. Take away the 3P cookie, and advertising becomes less targeted; advertisers will pay less per impression/click. Publishers make less money. Especially those that are more broad content publishers (eg Marie Claire, etc) instead of being super specific in a niche.
Therefore, massive part of their revenue stream may be in jeopardy, maybe as soon as later this year. This is one that is very hard to call, even for someone like me in the industry, on what the outcome is going to be.
Future (LON:FUTR) (I hold)
Unsurprisingly excellent points from you.
As someone mentioned below I think it's also important to factor in that GoCompare probably makes up a sizeable chunk of the current value of the company, which should put a floor on the current share price.
The rest of the business is facing threats - including AI, whatever that is exactly - but I can't imagine that they are worth nothing,
As for the removal of 3rd party cookies, I'm more optimistic specifically because the brands they own are quite niche e.g. MoneyWeek, Decanter, PCGamer, etc... In a world where it will be harder to target online customers, surely these brands will have a lot of appeal for advertisers.
Hopefully anyway.
A
Ah, I hadn't spotted that Future (LON:FUTR) also owned GoCompare, that is interesting!
Yiannos, who are you to expect? SP is not an aggressive platform and I believe new contributors are to be encouraged.
Shanta Gold (LON:SHG) at today's vote the acquisition by Saturn Resources was approved. At 14.85p it seems a bit of a steal given the current gold price. The whole deal has left a bit of a bad taste due to the lack of current information and trust in the board and the acquiring company.
Was worth at least 24 pence/share, I held on after top-slicing to get on with the job of seeking better prospects and passing some of the promised dividend.
Public Policy Public Policy Holding (LON:PPHC) announcement today.Illiquid but a yield of 10% and p/e prospective of 5x
Interesting what they do.You'd imagine their services are definitely in demand nowadays., including crisis communications'..!
Gulf Marine Services (LON:GMS) GMS has been my most successful investment of the last couple of years, and has fairly recently grown enough to be my largest holding. I had held some from 2014 to 2018, which was in short disastrous on a small scale, but was buying again with confidence between Nov 21 and Jul 22 , which has worked out very nicely so far. The crash and recovery of the share price has largely been about the debt situation, which got over 10 times the market cap in 2020. Since 2021 they have been paying down debt pretty steadily, which has been gradually transformative for the company's balance sheet and valuation, and today's results give me more confidence that that pattern will continue.
Northcoders (LON:CODE) - I hold- Interesting update for me, as an open uni student too (the largest UK uni), that Northcoders is setting up a part time digital skills study programme to fit around other commitments adults and potential career swappers have similar to the OU.The OU has really been broadening out its computing programs offering too, which cybersec and data science offerings.And is naturally one of the most popular of its courses.Poor Northcoders is really flying under the radar imo.. virtually zero trades on any day.Nice little company in the right sector with the right tailwinds though imo.Perhaps the investormeet meeting post results will get a little more interest.
Loungers (LON:LGRS) Slater Investments doubled stake to 10.22% (I hold). Seem undervalued to me- been to a few . One of the founders said much the same recently. http://newsfile.refinitiv.com/...
Equals
Lord knows what’s going on .
It’s the grand old duke of my portfolio
Up to 125p now
Had fallen back to 107 10 days ago
Seems to be a bit if FOMO both ways , people pile in thinking bid is likely , then pile out when seems less likely .
It’s still a decent company with or without bid
I’d much rather bids come out of the blue rather than long drawn out put up or shut up extensions .
Hi planetx
For what it’s worth my take is that fair value for Equals (LON:EQLS) business is 175-200p. Given another suitor is now in the mix I just think investors are pricing in the probability of that event. 125p which will drop a bit if they stay as a standalone business initially versus a 50-75p upside. Looks decent risk/reward to me and I just think the market price reflects that.
The business trades in-line and still plenty of growth prospects so I don’t care either way. A decent bid and I’ll recycle the money into other undervalued shares, else I’m happy to hold as I think it can achieve well in advance of that on its own over the next 2-3 years.
I’m more concerned whether all this extended activity takes management eye off the ball.
For what it’s worth my take is that fair value for Equals (LON:EQLS) business is 175-200p. Given another suitor is now in the mix I just think investors are pricing in the probability of that event
But we are 33% off your fair value - or 50% upside. Your target would suggest that investors see no chance of a deal whatsoever. As I see it, UK stocks are being acquired for less than fair value and I think we’re positioned for a maximum of15 to 20% upside from here. And probably similar on the downside. In other words, the typical 30% premium on a bid is split in two.
Hi BnB
No - a special situations investor would look at it on the basis that a deal is say 175p and a no deal shunts the price to 100p (where it was prior). They wont be holding for the long term, it will be purely on the basis of the takeover play.
So risk is 25p here and expected reward is 50-75p (so roughly 2 or 3 to 1 ratio).
You wouldn’t take a trade on a 1 : 1 ratio : so i’d say the market is now pricing a bid around 175p mark but it could be more.
Companies are being acquired at both more than and less than fair value at the moment depending on whether there is competition. In this instance there are now two bidders competing - that increases the likelihood of fair value being achieved in my view.
But I suspect if that is not achieved the management just walk away. I don’t think they are itching for an exit and I don’t think the business needs an exit, but we’ll see.
Equals (LON:EQLS) - Well, we shall see, David. I just don’t see the level of enthusiasm in current half-interested parties’ behaviour to generate a bid that high. Though I’d be delighted to see it. I’ve sold a third on the uplift and kept two thirds - which shares some mathematical characteristics with your definition of typical arbitrage. Let’s hope I come to regret that minor trimming of the stake!
Hi BnB - yes, let's see. who knows what will happen. Really I was just making the point that I can see why they trend to around 125p as that level makes sense from a risk/reward perspective to a special situations investor. I would agree with you on interest with Maddison as they have dragged it on for a while but the new bidder is clearly keen to try and do a deal. As you say doesn't mean anything gets done.
I'm patient on this one as if the deal doesn't go through I expect the business to be even more valuable in a couple of years.
Where we diverge is on the suggestion that “the new bidder is clearly keen to try and do a deal”. I might have missed an update, but my understanding is that Embedded/Railsr/Towerbrook have made an indicative, non-binding proposal. Back in my days of corporate M&A, we used to make or require an indicative multiple of EBITDA simply in order to gain/grant access to the prospectus and what is now called the data room. The notifying of the multiple did not indicate anything other than a broad interest in performing deals at a certain multiple. A bit like the well-advertised policy at Judges of seeking deals at a max of 5-6x EBITDA. I welcome being proven too pessimistic but the glacial pace of developments warrants a degree of caution in my opinion.
Future (LON:FUTR) (I hold) - First time providing a seperate trading statement for H1, usually it is AGM statement followed by half year results. Guess the management wanted to put a floor to the falling share price. My view on some good and bad things below,
Good things :
On the financial metrics, this looks very attractive.
- EV/EBITDA 4
- EV/FCF 6
- Debt as of last FY result £327 million (Should be paid off in 2-3 years with FCF provided no M&A, or early if they get rid of B2B business)
- P/E 6
- Go.Compare generated £32 million profit last year. This was acquired on 22x multiple. Based on Moneysupermarket updates i expect Go.compare to do around £35 million this year which gives £750 million valuation. Dennis brands were acquired for £300 million for their rich first party data which could be sold at decent recurring price when google disables third party cookies. Personally i think just Go.compare and Dennis brands should cover the current EV.
- B2B business was put for sale - first move of the new CEO - in August 2023 (sky news link) and JEGI Clarity company that was hired for identifying potential buyer shared their 2024 M&A updates here .
Bad things:
- Management changes. CEO Jon Steinberg - The more i listen to him talk, the more i lose conviction. This was his last month discussion with On Marketing podcast - (link). He compares AI to a 3rd grade kid and doesnt think it will have any major impact on Future (LON:FUTR) businesses. Also reveals Future (LON:FUTR) has very minimal AI deployement to date. I've seen some of the things that AI can do and his perception is not correct (Like Nokia/Blackberry mocking Apple in early days). There is another podcast on same channel with Jeremy Kaplan who is Future's Director of content (link). This was after the CES 2024 show and he seemed fine. Penny the current CFO will leave the management team soon.
- Third party Cookies. Google is extremely slow to remove this, as it will lose a big chunk of revenue from ads. Future (LON:FUTR) says it will benefit in medium/long term from this, since it has rich first party data. But there should be some short term impacts on revenues.
- Around 3% short positions in the company.
Good luck all.
Future (LON:FUTR)
Thank you for sharing those podcast links & for your thoughts, much appreciated.
A
Hold Future (LON:FUTR as looks cheap on the low PE and cash generation. As an aside, could be a Terry Smith or Warren Buffet deterred from commenting on here by the constant sniping, who knows. Thank you to Graham Neary and Paul Scott for great analysis which here for.
CMC Markets (LON:CMCX) now a doubler since buying in the 1st week of Jan. I think it's time to top slice a few. Hat tips to Paul & Graham. Well done chaps.
cmc going into fste 250 i would not sell as pension funds have to buy with a little free float.
Hi eParo, yes I agree a big hat tip must go to Paul & Graham. I am also keen on CMC Markets (LON:CMCX) and I suspect that it could double again from it's current price today. Extraordinary positive relative strength to a still very dull bumping along the bottom Small Cap Market. It is such a joy to be holding a share that is working out well while I am waiting for the rest of my Small Cap Portfolio to wake up and come alive again. I am going to hold my nerve and keep running it because it could end up with a £1.5 billion Market Cap.
Anyone know what's happening with Warpaint London (LON:W7L) today?
Looks like there was a big seller selling large chunks at regular intervals. I bought in so will see what happens
Warpaint London (LON:W7L) - Fib extension target at 425p has been met, technical traders are selling out imo. I have an entry target around 270p , let’s see if it gets there.
Assuming you mean 370p??
No…. I meant 270p.
some US companies reporting a softer market for makeup
Ulta Beauty (NSQ:ULTA. 'Shares of cosmetics retail chain Ulta Beauty (ULTA -15.34%) sank on Wednesday following some commentary from management at J.P. Morgan's 10th Annual Retail Roundup investor conference. As of 1:20 p.m. ET, Ulta Beauty stock was down 14%.'
The duo warned investors that the company is seeing "Slower growth than anticipated in the category so far this year."
https://www.fool.com/investing...
https://www.investing.com/news...
However Warpaint London (LON:W7L) is surely only moving with average volatility today?So someone is mopping up the shares if there is a large seller.
Read across from Ulta Beauty (NSQ:ULTA) profit warning in the US yesterday - guiding Q1 estimates lower due to "category growth slowing more than expected".
Typically Ulta Beauty (NSQ:ULTA) bounced up yesterday, was up 8% at one time, whilst Warpaint London (LON:W7L) has not bounced at all. Not sure you can read across from different markets. I find US stocks often bounce straight back up. UK there no money pouring into the market. US there us an any weakness maybe considered a buying opportunity.
Does anyone have access to any research on Saga (LON:SAGA) as there doesn’t’t appear to be any on RT?
I thought earnings release was today but seems not. I keep looking at this and thinking it is well undervalued. I own some but considering a bigger position.
In a nutshell Stocko tells me eps is forecast around 30p next year. So a fwd PER of just 4 but I think the travel business should be going extremely well and having seen several motor insurance renewals recently I have to think the pricing cycle has now turned, so on a forward looking basis the broker and underwriting division should pick up anytime around now. The two together I think could drive material upgrades and I’d like to be ahead of that.
Clearly the 2024 bond is paid from cash and liquidity and ship debt is being paid down quite quickly whilst the ships themselves hold significant net tangible value. That could be released if Saga (LON:SAGA) do a sale and leaseback type model or JV. If not balance sheet is getting a lot stronger through reduction of debt.
Looking at the 2026 bonds trading around 90p suggests a required yield of circa 10% which is not particularly expensive from a cost of capital perspective. Certainly means there is no perceived bond market distress around debt so it wouldn’t surprise me if the bonds themselves could be refinanced well ahead of 2026 maturity.
Looking interesting at these levels - potential multi bag in my opinion - am waiting for results but would also like to see some research really to validate my assumptions.
Saga ( LON:SAGA) I hold
They report on Wed 17th April
I saw March cut to forecasts from Numis
FY Jan 25 PBT £40.5m from £55.7m
Insurance broking to remain a drag as they cannot pass on all of price increases from panel insurers to their customers. They have a debt reduction forecast of £45m ( previously £55m) for FY Jan 25 and have the combined travel business forecast of £52m for same period
Hope that helps
I do not have a full report or more detailed forecasts
Saga (LON:SAGA), the insurance business was up for sale some time ago, someone sniffed around but came to nothing.
The insurance cycle is indeed on a (strong) turn upwards, but note that SAGA offered three year policies -at least on household, not sure on motor and many (I don't know how many) customers will have availed themselves of that longer term certainty. So, SAGA may/will not benefit from the upturn for another 2 years or so, at least on this segment of their portfolio
Not quite Dartagnan - they do offer 3 year policies but obviously these weren’t all switched on at the same time. So they will already be starting to renew now. Average duration from here is probably more like 1 year. The obvious question is whether customers renew or switch. I’d expect Saga (LON:SAGA) to be competitive and still be able to significantly increase margins but really I want to see those green shoots to get some confidence in my hypothesis.
So fundamentally I think 2026 has a potentially big uplift in earnings to it. Ie I can see the forecast £40m PBT in 2025 move up to more like £80m+ in 2026. That would require no change in travel (which I think unlikely - they should be able to grow) but a normalised turnaround in insurance. Given historic losses I’d imagine low tax.
If I’m right I can see a 500p+ share price which is predominantly why I am mulling my timing for increasing the position but tbh I still feel a bit blind so I’m looking for key indicators to help me triangulate. It’s illiquid as well so gets tricky as I wont want to buy if it has a big jump or builds up to earnings but on the other hand I don’t want to leap early and find I’m wrong on insurance and projected earnings. Argh!!!!!!
Hi David, from a simplistic chart perspective there seems to be strong resistance at around 110p only once has it (very briefly) dropped below that level. I have held for the past 6months or so and whenever it drops to that level buyers seem to flood in. I personally believe anything around 110-115p is likely the best value you are going to get between announcements. Sentiment on the share is very low, understandable from longer term holders. Not many will be holding in profit at these prices that's for sure!
Saga (LON:SAGA). You too Davidjhill are not quite right, I think.
Let's assume these 3-year policies are evenly spread and simply take 50% then on average it'll be 18 month before they can beging the process of higher prices. That means they lag the wider insurance industry- as did DirectLine, but that was down to poor management - there the divi had to be cut, the sp sank, the CEO got sacked. It may come out ok but it's worth pointing out this IS a risk in SAGA's insurance business.
Second point you say that it'll be 'probably 1 year policies from now'. Not so, I've just checked their website and they still offer 3 year policies, both on household and motor. Again, this may not be a problem for them, particularly as the 3-year guaranteed price is based on no claims by the customer, those that do make a claim they can hit them (hard?) mid-way through the 3 years.
What we can say more categorically is that, all in all, it makes their insurance business less predictable than other general insurers who can act more swiftly (in as much as anything is predictable)
Hi David
These are the estimates I have for Saga (LON:SAGA)
2024 Revenues £661m
2025 Revenues £770m
2026 Revenues £827m
Net debt 2024 £662m
Net debt 2025 £612m
Net debt £544m
Estimated FCF about £65m pa.
Current EV about £830m with a market cap £167m is too risky.
All the best
Hi David,
Just a couple of observations. I happened to look at the Saga (LON:SAGA) bonds you refer to end sept - at that time they had a YTM of over 15% (compared to the 10% you refer to today).
Looking at the stocko chart, the share price was 124p and stockrank 44. Today the share price is lower at 118p but stockrank up at 72.
Clearly bond markets and stocko algorithms think there's been a significant improvement in prospects, but the stock market doesn't (or was too optimistic at the time)! Time will tell who's right. I've had a holding for some time and underwater, but confident things will work out in the end.
What do you do when you find an investment trust that overlaps with your stockpicks? Suggestions very welcome – I’ve asked the question in April’s Investment Trust post, so happy to see answers here or there.
The investment trust is Fidelity Special Values (LON:FSV). Regular readers of the SCVR will recognise many of the companies on its full list in the annual report, page 11.
You look at discount/premium to NAV, fees and your own investor profile. I.E. If you can buy the Inv Trust at a 10% discount to NAV gotta look good, vis versa premium. If the fees are high, the longer you hold the more damage done. Finally how good are you at stock picking because the profile of the fund will change over time, will it continue to agree with you? The only certainty I can offer you is I used to work for Fidelity and they are a very good investment house. Pedantic about the rules and they have analysts that cover a few companies more thoroughly than any of us private investors could. Likewise their fund managers (In my time anyway) come from the best analysts so they tend to know the stocks over a prolonged period. I hope that helps your conundrum.
Not sure I would agree with this
“they have analysts that cover a few companies more thoroughly than any of us private investors could. “
That's v useful input, inside knowledge of Fidelity is an unexpected bonus! Good points to think about. Thanks Camtab.
(When the stock market is going up, I'm a stock picking genius...)
Fidelity Special Values (LON:FSV) - the performance over 5 years is +8.7%, over last 2 years down 2%. Not sure this includes the dividends but yield is only 3%. Not impressive!
The aim of this IT is stated as long term capital growth, but the performance seems poor. This is the case with some other ITs too. And the discount to NAV can persist for long periods, in some cases forever. Maybe I have misunderstood something, but poor performance has put me off some other ITs too.
Happy to receive further thoughts/corrections to my perceptions.
Hi dartagnan2019, thanks for your reply. All useful!
Can I ask where you're seeing that performance data? According to the AIC website, its total share price returns have been:
9.4% over 1yr
15.1% over 3 yrs
24.9% over 5 yrs
97.9% over 10 yrs
Ongoing charges of 0.7% and a dividend yield of 3.07%, as you say.
You're welcome Indie. I got that data from the Hargreaves Lansdown website. Fidelity Special Values (LON:FSV)
Just checked their (FSV) own website and that shows individual years performance, and as TOTAL returns (ie incl divis), as follows (rounded):
2019 -7%, 2020 -25%, 2021 +75%, 2022 -14%, 2023 +5.6%.
So, if you put in £1k in 2019, then after 5 years this would have grown to £1,111 i.e a return of (just) 11% in total.
So perhaps HL are (about) right, depending when precisely the year entry points were chosen. Is AIC wrong??
dartagnan.
For Fidelity Special Values (LON:FSV) why not use the excellent aic website for facts and figures? Fidelity Special Values (LON:FSV) performance is as good as others in the sector. Also markets look forward not back. Here’s the aic link:-
https://www.theaic.co.uk/aic/f..
So as with Saga (LON:SAGA) isn’t it better to focus on figures as in yiannos1’s post AND Company updates etc and analyst comment and quality comment from the likes of Paul and Graham here? Better than you trying to reinvent the wheel?
Hi ken,
Good to see your post, I did look at the AIC website but their figures do not match FSV's own as reported in their annual report. Which is why I questioned Indie's figures.
SAGA - an old favourite of both of us and made a decent profit on in prior years. Much discussion then on the insurance side. As someone else posted previously, there are two sides to SAGA's insurance business, the underwriting side and the broking side (Acromas, based in Gibraltar from memory). It was the underwriting side they want to dispose of, but as far as i know didn't come off, in part it was felt at the time due to poor management, one Euan Sutherland, who I now see has been appointed CEO at AG Barr!! Who's his replacement at SAGA??
Paul's update on 30/1 was not hugely optimistic; here's his summary
Saga (LON:SAGA) - up 5% to 153p (£216m) - Trading Update - Paul - AMBER/GREEN
<<As usual, an unclear trading update that sends us round the houses a bit. It sounds moderately good though, with travel/cruise doing well, but insurance struggling. Outlook is more of the same. Potential restructuring intrigues me and could provide interesting upside & de-gearing maybe?>>
Share price then 153p, roll forward two months and price is down at 117p, hmmmm.....Seems the market don't like them much.
Forward looking: revenue growth expected 10-15% up, profit to double, bookings 'per diem' materially ahead, however for insurance they say ''likely changes are expected to impact insurance profitability short term''. No clarification what these 'likely changes' are.
I'm quite keen to get back into SAGA, but January at 153p would have been a big mistake. Whether today's 117p is a good entry point, who knows, it seems so, but could be quite a wait till we see concrete evidence.
My past experience says that the HL site does not provide total return. For Inv Trusts I always got to the AIC website to be sure.
FSV
I was surprised to see the LTI on a discount of 20% having followed it with the 50% premium some years ago.
It’s down 22% one year and 45% five years. Stunning underperformance.
FSV has done much better.
Incidentally I am going to buy the LTI soon.
Paul - re Vertu Motors (LON:VTU) - the CEO was on BBC Breakfast radio just before 7.00am this morning bemoaning the fact that EV sales are so low - held up only by fleet purchases which in turn led by financial incentives, which not available to the public.
Anyone interested in Battery Chemistry in the Stocko community?
I almost spat out my tea this morning when I saw Gelion (LON:GELN) in Mr Contrarian's excellent news summary - and it's news relating to it's Lithium Sulfour Battery tech. This technology was developed and patented by Oxis Energy originally, but it went bust in the pandemic and was soon bought by Johnson Matthey for a few million.
It seems that Johnson Matthey has now sold the business (not that it amounted to much of a business) and the tech+ IP to Gelion (LON:GELN), funded by a substantial and dilutive placing and retail offer.
Gelion (LON:GELN) needless to say looks like another of those pandemic jam tomorrow floats -no material revenues, then a jump to £49m in 2025!
Mentioning it because I was an Investor in Oxis Energy myself (it was originally backed by Lucius Carey's Oxford Technology VCT's and i was able to co-invest, with EIS reliefs) , suffering a total loss and a lesson learned. I was never expert enough in the science/chemistry, but a bit taken in by the whole "next generation" narrative. That said, I got to know some Oxis people (and it's then CEO) a little, and they were honest and talanted people. Towards the end I was aware that there was a number of Dyson tech people coming and going (including on the payroll), leading a few of us shareholders to speculate a little too much.
I am not a holder ofGelion (LON:GELN), nor I suspect will I be, at least in it's current state. I'm just interested because you would have thought if lithium sulfur battery chemistry had nothing going for it, it would by now have been "found out". Or perhaps this is just what is happening, with Johnson Matthey offloading it having bought it and looked at it for a couple of years, and then shipping it on to the next cashed up mug.
Anyway apologies if this is a little off-topic, but if there are any experts on battery chemistry, I'd love to hear your thoughts.
https://gelion.com/
Admission Doc: https://gelion.com/wp-content/...
Re: Lithium Battery Technolofy.
Hello Mark, very interesting. Thank you. I am not a cell chemist. Not much of an expert either, more a Jack-of-all-trades, I am a master of one, though spacraft system design is probably over-specialised but it does mean that I spent many years fiddling with the use of battery technologies in hostile environments. So I can talk with some experience of the problems of cell development.
Long story short, it always take longer and costs way more than you could imagine when you start to move the 'worlds best battery' from a perfect laboratory to commercial mass production at scale for use in a hostile environment. And you always end up with a worse performance (on average) than you expected, a trade-off of energy, power, cost, safety, temperature performance and cyle-life - where you can always improve one or more factor, but always at the some reduction of the rest. Which might be alright if the rest of the world and its gig-factories making competitor technology have stood still. But they have a nasty habit of not doing that?
I remember at Uni in 1983 having a conversation with a then Phd student at Southampton working on battery technology and his conclusion was - 'we desperately need something better than lithium batteries', 40 years later and we're still fiddling with lithium batteries.
Most of the dozens of types of Lithium cells first emerged in the 1960's and 70's with patents and technologies scattered between the US, UK, Japan, Canada and so on. In the 1990's I remember working with RAE Farnborough and UKAEA (who owned the Oxford patents at the time) on power systems to qualify the first production d-cells for spacecraft use. For some reason I seem to remember that we ended up using Sony cells rather than the UK produced ones? My memory is a little vague here. But the irony is enormous that the UK government happily received the income from these patents - whilst leaving Sony and others to do the hard work in commercialising the technology. Disappointing but not surprising. Our lack of ability to even feed back patent income into commercialisation let alone help fund the long hard slog of developing viable production at scale - goes a long way towards explaining why the UK never seems to capitalise at scale on the technologies its so good at innovating? Shameful doesn't do it justice really?
Rant over - the point of this story is to reinforce that the way we celebrate invention and 'entrepreneurship' in the UK quite possibly means we are very badly prepared for the long, hard, ruinously expensive slog, perservering despite the inevitable disappointments , of perfecting commercial high volume production at both quality and low cost.
You can probably tell where I am going with this? Unfortunately - it will most likely take much longer, be more ruinously expensive, and result in a battery that is no longer the best in the world when you get there? To fund the scale production you probably need the kind of finance involved in putting together a 'giga-factory' and to fund a giga-factory you'll need massive anchor users involved? Otherwise you'll lurch from funding crisis to funding crisis until the patents expire?
Talking of which I understand that the LFP patents expired in 2022 or there abouts. The Chinese never bothered with the patents anyhow and have spent a lot of time and funds developing the production at scale, building the giga-factories and incorporating them into Chinese internal markets and EV production. You can expect a deluge of cheap chinese EV's but with cheap low performance LFP batteries to be on our roads anytime soon? An industrial strategy in action? Not having an industrial strategy and having had enough of experts, is all very well, until you have to play against a team with an industrial strategy and plenty of experts?
Back to Li-S. Sulfur (or Sulphur) over here :-) is a poor conductor and volatile (at least in comparison with carbon) so your cathode design has intrinsic limitation from the start, in power outpit, cell life-time and degradation. It might have been possible to fix this in the lab - but extending that to mass production at the needed quality and cost - may have a long way to go yet? I really don't know the specifics, nor studied the progress with any detail - they might get lucky. But even if they do it take years to prove that the fixed technology is worth building a giga-factory for (and without the scale the battery will still be expensive) and designing into futuer products?
I'm sure that's more than enough ranting from me! As you can tell I'm fascinated by battery (and other technologies) and I'm fairly sur that I've lost money on every UK battery venture I've bought into (the only exception being the indirect investment via Mercia Asset Management (LON:MERC) into Faradion's Sodium-Ion cell - and that only made money because Reliance (India) bought it, so foiled again, too expensive to commercial with UK funding). I'd love to find one in the UK with a good chance of commercial success and the funding to achieve it.
my apologies for taking up valuable space on today's thread,
cheers
Mark (sometime, bodger, woodsman, scythesman, tinkerer with old landrovers and fettler of recalcitrant spacecraft)
don't apologise Illiswilgig, this was a most informative post - as are the others: thanks. A very useful reminder too that coming up with the right solution in the lab is a million miles away from reaping the commercial rewards.
A company to keep an eye on in this space is Lyten - they have a big investment from Stellantis. Last I heard they were building a factory in California to produce Sulphur based batteries. If nothing comes of that then perhaps it is a dead end.
However, I've lost count of the number of battery 'breakthroughs' I've read about in the last 10 years that have come to nothing. The difficulty with all these things is mass production - very often it seems there are barriers to producing them in qty, even if the science holds up.
I am not a battery expert but tend to think that the current EV situation has to be improved.
Does anyone have any thoughts on Toyota's breakthrough using solid state technology?
https://media.toyota.co.uk/toy...
Well, I'm not an expert on battery chemistry, but I follow global newsflow in the area as best I can. Lithium NMC, LFP, sulphur,sodium, semi-solid, solid.... This is because, when I could stop full-time work, I thought I would try getting involved in what I thought would be one of the most important areas of all for climate change mitigation. Anyway, I soon gave up, realising that any serious business would need many £ms. And so it turns out. The advances are coming so thick and fast, I defy anyone to list the winners over the next few years. You need scale. Good lab ideas are everywhere, but the Chinese, followed by the Americans, having that, are perhaps leading. Try this: https://www.electrive.com/2024... Good luck to Galion, but given that the Chinese don't seem to have to make money, you've got to be brave to bet on just one solution.
Oh, and that's just for vehicles. Longer-duration static storage? Lithium at all? Better vanadium, molten-salt, compressed air, pumped hydro, gravity (yup, first significant gravity battery commissioned in China. My only chip is in Invinity Energy Systems (LON:IES) , and that's proven vanadium flow. Hoping the cost reduction in the Siemens Gamesa-backed version to be launched shortly actually brings profitability. If so, multi-bagger. Like all of them! But at least it has proven systems working in the field.
Good luck all
Its not difficult to see why the UK stock market has been such an underperformer over the past 3 years.
Indeed according to Calastone, there's now been 34 consecutive months of net selling of UK equity funds.
In contrast, flows into US facing funds are going like a train.
Article in Times today which suggests that the FTSE small cap index will cease to exist in 4 years time.
Number of companies in the index has declined from 160 in 2018 to 114 last year.
Article behind a paywall but might be syndicated elsewhere.
daily mail i think it was
The Times article is reporting something said by Peel Hunt - looks like it's been picked up by a few news services if you do a google search.
An issue is that the SMXX (FTSE Small Cap excl Inv Trusts) is only for fully listed stocks so AIM stocks aren't included. My small cap portfolio is about 60% AIM 40% fully listed so I don't think there is a FTSE index that reflects that. Most small cap UK investment funds are split between the 2 indices too. AIM is a lighter regulatory regime for co's to maintain and we investors get the benefit of no stamp duty too, so perhaps SMXX co's are an endangered species.
Metals Exploration (LON:MTL) anyone have intelligence on this? Up 15% in two days. No RNS. Thanks.
Doc
I think it’s just the rising tide Gold price is starting to float all related boats – the last one being miners. See Edmund Shing’s latest Market Musings and responses. https://www.stockopedia.com/co...
MTL - In Ed's selection for his investment portfolio ,was when I took an interest, especially as SHG management were selling us very cheap , and I wanted a portfolio interest in gold.
On reading the co. plc on line ,and finding a couple of BB [ sensible] writers detail of the company working , realised this looked an attractive prospect for my Au holding.[about 3p then jan/feb ] Stoko rating was 100 very strong, when looking at stats.
Basicly they have just paid off all debt [slight disagreement with one of the debt holders over final payment but in the scheme of things they are debt free ].
They have one mine in the Philippines producing approx 800000 ozs gold at $1200 /oz acis . With the price of Au moving STRONGLY in their favour [ currently] they are on a roll. I like PAF but historically S Africa seems to be a more and more complicated country to work in.
The 'catch' - the mine has ONLY 4 yrs of life , before closure . The +tives :- CEO seems to have worked miracles in the few years he has been there ,and has plans to open a few smaller mines [ low cost] in the Au rich area. These are hopefully in production in the next 2 years. The jan 12 th RNS will explain how he expects to do push MTL to greater highs in the future .
Remembering ALL with Au miners depends on the world price , but currently ,due to the world debt levels, I think it could be in for a good run, hence my wanting a Au holding in my portfolio.
Good luck with your decision Tony
I would not be too sure about doing business in the Philippines is easier than South Africa. This outlines some of the issues: https://golocad.com/blog/expan...'s%20bureaucracy%20and%20red,of%20ease%20of%20doing%20business.
There is a lot red tape, a lot of corruption, heard it has more natural disasters than any other country. That mine is not far from Mt. Pinatubo, there was a serious earthquake as well around that time.
American style legal system, so everyone is suing each other.
There has been issues with child labour in the past in gold mining, there.
I knew someone who had a business there, he had to close, said it was not possible to make a profit.
l have not been there for 10 years, maybe it is different now?
all about debt reduction the last few years mine life not mant years left but has been extended in recent annoucement,
Cab Payments Holdings (LON:CABP) appears unloved on Stocko and on that basis looks one to avoid, especially after the disastrous float and subsequent profit warning. But an interview in the Sunday Times with the Chair lady a few months back https://www.thetimes.co.uk/art... piqued my interest. I seem to remember Paul Scott catching a good bounce when it dropped to 50p. I have bought steadily since then and today's news about a new European licence surely indicates a better future and one less dependent on some African countries that caused the profit warning in the first place. Worth a look IMO and yes, I continue to hold (where it is running a close second to CMC Markets (LON:CMCX) ).
While I understand Paul’s reluctance to spend any time on Cirata (LON:CRTA) analysis (lately Wandisco of this parish), I do strongly urge people to read the full announcement today. It could have been a mealy-mouthed smoothing over of the troubles encountered and the challenges ahead, but it is not that at all. It is a clear stating of the horrors dealt with and still being tackled. My money is not yet going into this scary situation, but this is the second straightforward announcement from the new management which encourages me to believe that they have their heads screwed on and are worth watching.
On Cirata (LON:CRTA) The rns was pretty clear which was good.
They state that they aim to finish the year on a "cashflow breakeven" basis. Not sure what that means.
My problem is that I thought their product just wasn't on track to actually make much money and did do not see any clue on actual profits in the rns
Cirata (LON:CRTA) - as a previous holder I still wonder if any action will be taken against what can only be described as earlier fraudulent activity - and there are others - I walked past a Pat Valerie shop in Colchester last week - still vacant - a reminder of just another past case.
Hi Aislabie,
I take your point that new management at Cirata (LON:CRTA) have been very open about the failings of the previous people running the company. Having met him, I've got a very clear picture of the former CEO, and came away from a meeting feeling that he was lying through his teeth, as his body language ticked every box in the excellent "Spy the Lie" book, and it was almost continuous red flags throughout the meeting. Let's hope he ends up in prison, as the story that the fraud was all down to one sophisticated but dishonest salesman orchestrating a complex fraud doesn't hold any water at all, it's nonsense I think.
Anyway, that's water under the bridge. All that matters to me now is whether CRTA shares could recover. I skim read the results today, and they're so bad, combined with a wobbly outlook, made me quickly dismiss this as an investment idea. It's likely to run out of cash again, and there's no sign of growth.
So why get involved? Irrespective of the past fraudulent misstatement of order intake, etc, it just looks a lousy business model, I don't see any signs at all of a viable business. Luckily for the company, it had some very wealthy backers who refinanced it last time, and amazingly still seem to believe in the stories about it having amazing, unique technology.
Anyway, I won't be reporting on it here unless/until there is some tangible progress, and given the history, I won't be accepting order intake or bookings as being reliable information! It needs to be progress with audited figures showing a move into profit, and cash generation. Otherwise I won't be touching it.
New management may be lovely, and completely honest, but for our purposes it simply doesn't matter, when there are no signs of this ever becoming a viable business.
Regards, Paul.
If I didn’t make it clear, I entirely agree that Cirata is currently uninvestable and I would not expect any commentary, but I wish them well and have a suspicion (and a hope) that management “grit” may just about carry them through. So I will keep an eye on them.
Golden nugget in Future (LON:FUTR) trading update:
"stronger performance in US direct advertising, a key strategic initiative, driven by the continued focus on premiumisation of advertising inventory benefiting from the Group's scale and first-party data."
First party data is going to be big in the post cookie world imo. Ridiculously priced at p/e of 5 here.
https://www.investegate.co.uk/...
Hi
Gulf Marine Services (LON:GMS) 2023 finals look quite good. I have never looked at this stock before, but others might be more knowledgeable and like to comment.
Seems expenses and leverage reducing whilst revenues and profits increasing.
At time of writing share price up +7.89%.
Portion of RNS ...
2023 Overview
2021
US$m
2022
US$m
2023
US$m
2023 versus 2022 change
Revenue
115.1
133.2
151.6
+14%
Adjusted EBITDA1
64.1
71.5
87.5
+22%
Net profit for the year
31.2
25.4
42.1
+66%
Average fleet utilization
84%
88%
94%
+7%
Underlying G&A expenses4 as percentage of revenue
9%
8%
7%
-13%
Net leverage ratio3
5.8:1
4.4:1
3.05:1
-31%
Rest of RNS here ..
https://www.investegate.co.uk/...
Regards
Howard
Gulf Marine Services (LON:GMS) I don’t hold these. First time I’ve looked at it really but nominally does appear cheap. Guidance appears to be for 5c earnings so about 4p. Net debt to ebitda forecast at 2.5* which is much more reasonable than the previous 6* not so long ago.
That looks like it puts it on a PER of about 5 but add debt in and EV/EBITDA not so cheap.
Given the cyclicality of this business I doubt it will ever trade on a high multiple but if it can continue reducing debt then the EV is operating geared towards shareholders rather than creditors. Not one for me to jump on but may merit a closer look.
I think Paul knew this one reasonably well so may be he will comment
Gulf Marine Services (LON:GMS) I do not hold
Panmure who are company’s brokers upgrade EBITDA for FY 24 to $96m from $92.4m and adj PBT to $46m from $39m
Target price moves from 23p to 28p
Gulf Marine Services (LON:GMS)
In June Graham wrote;
"Needless to say, it’s unlikely to be a sleep-sound-at-night type of stock. This is more of a multi-bag-or-bust type of deal, with multi-bag being the outcome that is winning so far. Best of luck to all holders. Of course I am staying neutral on it."
(I hold. Multi-bagger for me so far, touch wood.)
Gulf Marine Services (LON:GMS) was one of those stocks which I bought into on the premise of a recovery, but very high risk (as flagged by many experts on here). I sold out of it in early 2022 when it became clear that interest rates were rising rapidly and I sold out of anything with high levels of debt.
Looking back, how did I not keep hold and end up with a multi-bagger - but in all seriousness, how do people determine which heavily indebted shares are worth the risk vs those that aren't.
It would be great if the highly experienced investors who look at this kind of thing gave a view as to how they look at things like this.
The oddest thing about Gulf Marine Services (LON:GMS) (I hold) is that their main competitor seems to be their largest shareholder: Home - Seafox
#CAV getting siumilar vibes to #CMCX - looking forward to the comments here. Doubled cash to £20m, now c.60% of market cap (£33m). Historically PBT margin has been in the region of 15%, so with £7m annualised synergies I'd hope this improves marginally. Apply that to £50m+ historical revenue puts this at a very very low single digit PE unless I'm mistaken.....and that's before the cycle properly turns. Thoughts?
Cavendish Financial (LON:CAV) now up 30% today. I hold, topped up this morning. But can't sell any at 11p.
Been a quick rally so market makers likely want to open the spread to deter buyers and shake a few out.
I don't understand. Why would market makers want to deter buyers? Thanks.
Market makers offer a two-way price. If they sell a lot of stock they may end up short, and so they'd need to buy it back to balance their book. If they deter buyers it means they're less likely to be sellers of the stock, and by tree shaking they can get a few people to sell back to the market makers.
Even if they weren't short, widening the spread is a great way to make more profit as they can buy cheaper. They make their money on the spread.
Thanks Michael. It's a scary world out there. Doesn't sound like there is much incentive to keep spreads narrow on small caps.
I could buy but not sell. Getting this a lot recently on small caps. Price soon fell back to around 10.5p
My morning smallcap tweet: The dog with nine lies
Cirata (LON:CRTA) Cab Payments Holdings (LON:CABP) Gelion (LON:GELN) React (LON:REAT) Insig Ai (LON:INSG) Motorpoint (LON:MOTR) Plant Health Care (LON:PHC) ECO Animal Health (LON:EAH) Genflow Biosciences (LON:GENF) Cavendish Financial (LON:CAV) Gulf Marine Services (LON:GMS), Gooch & Housego (LON:GHH), Future (LON:FUTR)
◄Cirata (CRTA)► FY-Dec. Material uncertainty going concern stmt. Damning commentary on previous mgmt that led to 'rock-bottom' eg "Sadly, over the preceding 12 months, a significant portion of the engineering schedule and product roadmap was anchored in customer requirements that did not exist.". [SP=60.1 Cap=69m]
◄CAB Payments (CABP)► gets European payments licence. [SP=110.6 Cap=281m]
◄Gelion (GELN)► achieves a "high energy density milestone" on its prototype Lithium-Sulfur battery. [SP=15.93 Cap=22m]
◄React (REAT)► wins 3 contracts worth over £1.3m PA total. This underpins confidence in FY24 performance. [SP=65.1 Cap=14m]
◄Insig AI (INSG)► chmn subscribes to £250k of shares at 20p. See placing RNS 2 Apr. [SP=16.9 Cap=18m]
◄Motorpoint (MOTR)► guides FY-Mar pretax loss "at the favourable end of management expectations". Q4 retail volume up c.9% and continued margin recovery [SP=133.5 Cap=120m]
◄Plant Health Care (PHC)► Mexico approval for PHC68949 to control parasitic nematodes. [SP=3.44 Cap=12m]
◄Eco Animal Health (EAH)► sells non-core ECOmectin Horsepaste for €1.3m. €800k of this is deferred. [SP=84 Cap=57m]
◄Genflow Biosciences (GENF)► £715k placing at 1.25p, a 15% discount, to continue development and associated clinical trials. [SP=1.55 Cap=5m]
◄Cavendish Financial (CAV)► guides FY-Mar rev c.£47.5m up c.44%. H2 was up 77%. Outlook - "Whilst the interest rate cycle appears to have peaked, conditions continue to impact demand for UK equities, making deal execution in ECM challenging across all market participants. However, private and public M&A has remained buoyant in H2...". [SP=8.5 Cap=33m]
◄Gulf Marine Services (GMS)► FY-Dec. Outlook: guides FY24 adj EBITDA $92-100m. Average secured day rates of over 10% higher. Net leverage ratio below 2.5x at FY end. [SP=19.65 Cap=200m]. I hold.
In line: GHH, FUTR