Small Cap Value Report (Thu 4 August 2022) - NXT, SCS, DUKE, RNO, GYM, TTG, SDG

Good morning! It's Paul & Graham here again today.
Agenda - we've done mostly shorter sections today, to get through more companies, and more quickly -
Paul’s Section:
Next (LON:NXT) (6746p - £8.7bn pre-open) [no section below] - Q2 (May-July ‘22) trading update - always of interest for sector trends from the best in class operator that also reports so promptly.
- Trading better than expected (especially in physical stores) - due to less competition on high streets, and warm/dry weather in June/July.
- FY 1/23 EPS guidance raised 7.2% (range: 543p-588p, PER = 11.5 to 12.4 = cheap IMO!).
- Pre-pandemic trends returning in product mix (formal wear up, sports/home down)
- Online returns rate back up to 42%.
- Is online in decline? No - just returning to long-term growth trend after a boom during pandemic - this is absolutely key, and confirms my theory that bombed out online shares could now be oversold, as market has wrongly assumed they’re now ex-growth!
- H2 guidance is cautious - sales growth slowing from +12.4% in H1 to +1.0% in H2 - due to impact on consumer spending from higher inflation.
- Share buybacks continuing, reduced share count by 2.6% so far this year. Amazing long-term strategy, boosting EPS considerably over time.
My opinion - I’m highly encouraged by Next’s update, as it confirms what I always thought - that the pandemic pulled forward demand for online shopping. We then had a hangover in calendar H2 2021 & H1 2022, but things are now returning to a (more modest) long-term growth rate for online. This could trigger a potentially big re-rating of bombed out eCommerce shares - one of my main investing themes for the rest of this year & next year, as the market realises they are actually still growth stocks (the ones with decent, differentiated product anyway), but many are currently priced too cheaply as if they were ex-growth.
SCS (LON:SCS) (147p down 4% at 10:09 - mkt cap £53m) (I hold) [no section below] - FY TU 52 wks ended 30 July 2022 - profit ahead of market expectations, due to positive trading, strong margin, and cost management - I’m impressed, as I was expecting another profit warning here. Although it does warn for FY 7/2023.
Cash of £70.8m (no debt) is above market cap. £7m share buyback continuing. Also note forecast 9% divi yield, which looks sustainable to me.
Orders reduced in recent months, lower consumer confidence expected to adversely impact FY 7/2023 - this really shouldn’t come as a surprise to anyone!
My opinion - the share price has already factored in a consumer slowdown, and is now almost down to pandemic lows again. That’s despite a bulletproof balance sheet (compare it with DFS!) and a falling share count. Trading likely to be soft during this cost of living squeeze. Should be good long-term, and no insolvency risk due to favourable working capital structure. Likely to benefit from competitors going bust (e.g. Made.Com (LON:MADE) possibly?) and others - e.g. lots of independents, now rent moratorium ended. No guidance provided for FY 7/2023, but Shore Capital update is now on Research Tree (many thanks) - lowers FY 7/2023 by 17% to 16.3p - that looks sensible. Long-term, I think EPS should recover to c.30p (way above current forecasts), and share price could double. But short-term, expect weaker trading. So this is short term pain, long-term gain in my opinion. Should be able to keep paying generous divis whilst we wait, and buybacks at this price make obvious sense.
Renold (LON:RNO) (25p - £54m) [no section below] - I’ve been covering the turnaround at Renold for several years, and have been impressed with progress made. Today’s news is a sizeable acquisition, £20m [E24m] being paid out of cash/debt (no equity dilution), about 37% of RNO’s market cap. Key points -
- Meaningful synergies
- Acquired company (Spanish) had revenues of E18.6m, and EBITDA of £3.1m (FY 6/2022).
- Reasonable price at 7.6x EBITDA (falling to below 7x once cost savings implemented)
- Accretive to both EPS and operating profit margin.
- Debt: EBITDA to rise from 0.6x to 1.5x, leaving scope for further deals.
- Acquired company has no pension scheme, so enlarged group helps dilute RNO’s big pension scheme.
- Management know the target company well, and think it’s a good fit.
My opinion - expanding a group with a big pension deficit is an excellent strategy to make the problem a relatively reduced problem, and hence can trigger a re-rating of the shares. I’m hoping to interview RNO’s CEO tomorrow (no fee, no holding personally), as I like this share and think it’s an interesting company, still modestly priced.
Sanderson Design (LON:SDG) - I've had a good look through this in line with expectations H1 update. It looks fine to me. Broker forecasts are maintained for the full year, and the PER is now really low on those confirmed numbers. Great balance sheet, with pots of cash too, so this share is right up my street. There's always a risk of a deteriorating macro picture denting H2 performance though, and the company does say today it's planning for a wide range of possible scenarios. Sounds sensible to me. Long term, I see this as a winner, short term, nobody knows! (More detail below)
Graham's Section:
Duke Royalty (LON:DUKE) (£141m) - Q1 revenue comes in slightly better than expected at this provider of royalty financing. An inflationary environment should be fine for Duke, which gets paid in accordance with the revenue generated by its investees (whether it is fine for the investees is another matter). Duke probably needs to scale up even more in the years ahead and so more equity placings are to be expected. The investment process has been tried and tested since c. 2015/2016, without too many accidents along the way. (More detail below).
GYM (LON:GYM) (£323m) (+1.6%) [no section below] - an upbeat set of interim results from this operator of low-cost, 24-hour gyms. At the Q&A session, the CEO has just said that the company should be back at 2019 levels of like-for-like performance later this year. July is in line with expectations, and the company is looking forward to students returning to university and the continued normalisation of working patterns. As of June 2022, total membership numbers remain below H1 2019, but the company has 50 more gyms than it did then (215 in total). There is a small loss for the period (4.4m) and net debt finishes at £57.6m. GYM is targeting 300+ sites and £40m-£50m of PBT by FY Dec 2025, and I’m open-minded to this possibility (for context, operating profit was £21.6m in FY Dec 2019). This share offers an attractive growth story in the low-cost gym niche, with lots of upside from the current valuation if management can execute.
TT electronics (LON:TTG) (£315m) (-2.8%) [no section below] - full-year expectations are unchanged at this provider of electronics equipment. Revenue growth is 8% (organic) or 10% in total, at constant currencies. Excellent demand is seen with a book-to-bill ratio of 144% and the order book at twice pre-pandemic levels. Inflation is causing some complications but is being passed onto customers, and the dividend beats inflation too, with an 11% increase in the interim payout. Some financial risk as net debt including leases is high at £142m; the company is hoping to reduce leverage over the next six months. EPS for the period is disappointing at 2.3p and this is partly due to a much higher finance charge caused by that increased debt load, higher interest rates and the fees associated with borrowing facilities. I like the prospects for shareholders here with a PE ratio of c. 10x and a dividend yield of 4%, but it will be an easier bet after the company has paid down its loans to more comfortable levels.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
I'm doing shorter sections above to begin with, to get through more companies.
Sanderson Design (LON:SDG) (I hold)
107p (down 5% at 11:30)
Market cap £76m
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, is pleased to announce its trading update for the six months ended 31 July 2022.
H1 revenues flat vs H1 LY at constant currency, up 1% reported, at £57.9m
H1 profitability - we’re not told what it is, but that it’s in line with the Board’s expectations. That’s fine, this usually means that the company is on track to achieve full year forecasts, unless there’s something nasty in the outlook section (it’s fine, see below).
The table giving a breakdown of H1 revenue is probably more information than I need, some bits are up, some down.
Licensing revenue is the stand-out number, at +90% to £3.8m - doesn’t sound much, but remember licensing revenues are pure profit, so this is the highest quality revenue stream, and it’s up strongly, so a tick here. That might have offset softer profit elsewhere, at a guess? A new note from Progressive says the increase is due to “accelerated income from recent agreements” which sounds one-off in nature, so we probably shouldn’t be getting too excited about this - although all licensing income is a validator of the valuable brands & designs that SDG owns.
Net cash of £15.0m at 31 July 2022 is still very healthy - down a bit from £19.1m 6 months ago, partially due to “a strategic investment in inventory of our best-selling collections” - that’s fine by me, as long as it’s only best sellers, and not over-stocking of slow-moving lines, which I doubt would occur under this CEO who has systematically reduced product lines, and cleared excess inventories in the last couple of years.
Outlook -
As set out in our AGM statement on 12 July 2022, we remain vigilant in respect of the world economic environment. Current market conditions are difficult to predict and we are planning for a wide range of possible scenarios in the second half.
Despite this, full year trading currently remains in line with the Board's expectations.
The Group's strong cash position enables continued investment in the business and also provides protection in the event of any material adverse changes in trading conditions.
I think that’s fine, given current macro conditions. Maybe some investors may have interpreted the bit about a wide range of possible H2 scenarios more negatively, I don’t know?
CEO comments are interesting, and seem fairly upbeat to me -
Lisa Montague, Chief Executive Officer of Sanderson Design Group, commented: "I am pleased to be reporting good strategic progress in the first six months of the year. It is encouraging to see licensing partnerships with major retailers both in the UK and US being extended, underpinning their belief in our brands and products.
"The two-year contract extension with Williams Sonoma, a leading US retailer, signals the confidence it has in the strength of a collection that is yet to launch, and emphasises the progress we are making in the US, a core growth market for the Group.
"We retain a rather cautious outlook, mindful of the cost, supply chain and consumer confidence issues that impact the macro-environment, though we are committed to delivering further strategic progress during the remainder of the year."
Update from Progressive - this is directly commissioned research, so I always regard this as effectively coming from the company itself.
Forecasts are unchanged at £119.1m revenues, £13.0m adj PBT, and 14.7p EPS for this year, FY 1/2023.
The share price is 107p, so the current year PER, confirmed today as in line, is only 7.3 - that seems remarkably cheap to me. The market is clearly imagining that there could be an H2 profit warning, which can’t be ruled out, given how wobbly the macro position appears to be.
There again, SDG customers really won’t be worrying about food or utility bills - have you seen their prices?!
Anyway, it seems to me that the current price factors in a large margin of safety - maybe that’s sensible, given that the company itself says a wide range of possible outcomes are being planned for.
My opinion - this share is right up my street. It’s unloved, yet performing well, and has a superb balance sheet, so there should be no dilution or insolvency risk.
As with so many other shares right now, I could see this easily doubling in price, once economic conditions are more normal, however long that takes? Usually macro problems sort themselves out in a couple of years. That strikes me as a very good investment proposition, if you’re prepared to turn off your screen and ignore market sentiment in the shorter term. The same could be said for plenty of other bombed out small caps right now.
.
Graham’s Section:
Duke Royalty (LON:DUKE)
- Share price: 33.9p (+3%)
- Market cap: £141m
I was briefly a shareholder in this investment vehicle, from June 2018 until August 2019. I got out at breakeven, before counting dividends.
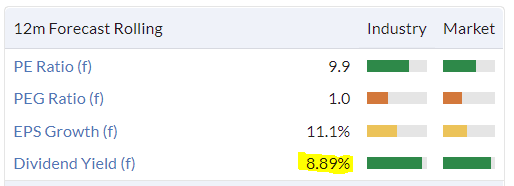
Duke’s purpose is to offer a rare form of financing that few businesses use, and which Duke thinks should be used more often: the royalty. This form of financing allows for very high yields, which in turn enables Duke to offer big payouts to its shareholders.
Here’s the forecast yield according to Stocko:
And here are the highlights for today’s Q1 update:
- “Normalised cash revenue” is £5.1m, exceeding expectations of £5.0m (this is basically how much cash the company received from investees, before counting any one-off transactions).
- Since there were no one-off transactions, the “Total Cash Revenue” is the same number, i.e. £5.1m.
- Outlook: in Q2, Duke is expecting normalised cash revenue of £5.2m.
Operational Highlights
One feature that I like is Duke’s tendency to do follow-on investments. This is consistent with the idea that the best investments are often the ones that you already own. The obvious downside with this is that it doesn’t improve Duke’s diversification.
During Q1, Duke invested over £5m in companies where it had already made substantial investments. In each case, the purpose of the funding was to pay for an acquisition (sectors: care homes and managed IT services).
During the quarter, Duke also raised £20m at 35p. It has a successful track record when it comes to fundraising for itself. In 2021, it raised £32m, also at 35p.
The dividend paid out in the quarter was 0.7p, and was “well covered by operating cash flow”.
Based on the current share count, that dividend should have cost the company £2.9m. Remember that cash revenue from investees was £5.1m - so there is a buffer to pay interest, salaries and other administrative expenses.
Outlook statement
CEO Neil Johnson mentions the “inflationary macro-environment” in the context of Duke’s revenue outlook. It’s a good point: remember that Duke’s revenues are tied to the revenues of their investees. As prices rise, even if purely as a consequence of inflation, this feeds back to Duke.
There are now 48 underlying operating companies, in “a diverse portfolio of profitable, long-established businesses in low-risk sectors”.
My view
I still find this share interesting, but have no plans to invest in it again.
What I like:
- Improved diversification as the company has scaled up (however, it would make sense for the company to scale up much more).
- The company has successfully exited some of its investments, generating attractive returns and proving that the investment process worked.
- Duke got rid of its investment in riverboats on the Rhine and Danube rivers, without making a huge loss (although most of the money from that sale hasn’t been received yet, so there’s still an element of uncertainty).
What I don’t like:
- Duke pays interest to Honeycomb Investment Trust (LON:HONY) of LIBOR plus 7.25%. Firstly, this says a lot about Duke’s risk profile, and secondly, it’s only profitable if Duke generates extremely high yields on its own investments.
- Duke has taken equity shares in its investees, as part of its deal agreements. If it gets this equity very cheaply then that’s fair enough, but it highlights that this form of financing has a lot in common with high-risk equity investing.
- The investees are frequently engaged in buy-and-build acquisition strategies, and this is likely to remain the case. Think of the complexity and the layers of management involved: we invest in Duke, who invests in Company A, who uses the money to invest in Company B. There are simpler ways to invest than this!
Having studied Duke in some detail in the past, I’m currently neutral on it. I think it’s worth keeping tabs on, as it builds its reputation and track record, and as an income play it may have some appeal.
Balance sheet net assets were £122m as of September 2021, and the company has generated plenty of income and raised £20m since then. So from that perspective, Duke’s shares may not be overly expensive, at the current market cap (though bear in mind that there are likely to be more placings along the way).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
I've looked at Duke a few times without investing. My main issue is: with all the cheap money around for the last decade why would companies use this type of finance if they have a sound business as it is inherently more expensive than other forms of funding .
Hi Paul, what other bombed out e-commerce shares do you have on the radar? I saw your post on Seraphine (LON:BUMP) recently, what about the likes o £ASC and Boohoo (LON:BOO)?
ECO Animal Health (LON:EAH) (I hold)
Earnings release tomorrow. I’m not expecting a complete reversal of fortunes but there are a few reasons to be optimistic going forward. In particular the surge in pork prices in China. EAH put their past underperformance down to poor pork prices in China so a significant reversal might reverse the performance of £EAH.
It still a high quality animal drug producer and has a good R&D pipeline.
Here is an excerpt from “The Pig Site” (there is a site for everything!).
Since March 18, 2022, China Slaughter pig prices have risen from RMB 11.98/Kg ($0.85/lb.) to a national average of RMB 16.01/Kg ($1.08) by May 20, up 27%. At the same time, culled sows prices are an indication of direction the market is heading were up from RMB 7.79/ Kg ($0.55/lb.) to RMB 10.41 ($0.70/lb.) representing 27% increase.
Perhaps what has been capturing the most attention in the headlines the last few weeks has been a huge surge upwards in the weaned pig market. Weaned pig prices have always been seen as leading indicator of the hog market to come. Recently there has been a lot of demand from small, medium and large-scale producers alike to add more piglets to their barns.
Since April 22, the National Average price of 7kg (15 lb.) weaned pigs rose from RMB 398 ($61.34) to RMB 543 ($81.28) on May 20th, a month on month increase of 32.5%. Reports are that weaned pig prices in some markets have broken RMB 650 ($100) per head. This is quite an astonishing turnaround since according to the chart below, the lowest price or piglets in 2021 was RMB 70.14 each or ($11) per head on October 12.
Since the rise in pig prices starting in April, many producers have rid themselves of their long-term losses and returned to profitability. Reported profit from finishing weaned pigs now is RMB 194 ($30) per head. There is much discussion regarding the market in the second half of the year. We expect as fewer and fewer hogs come to market as a result of the month’s long liquidation, prices will continue to increase. Price is the truth.
As a punt Eco Atlantic Oil & Gas (LON:ECO) may provide to be mega cheap now - but they have been a well established company for many years and have consistently struggled - they have many purple patches but those good streaks have always come crashing back down soon after with bad news outweighing the good news. Having said all that they made £10 mill profit ish 2017 and 2018 so a return to the glory days and the shareprice i am sure would do very well.
Anything china related and there is also the worry about being screwed over by their china partners to boot.
Do i have confidence in this company delinering ??????? - errrr passs
Nice pullback on ME International (LON:MEGP) formally Photo-me last couple of days, considering there is a special divi of 6.5p per share X11th Aug, never look a gift horse as they say, as this share must make 120's going forwards, with a further divi to come.
Risk reward seems acceptable to me, as my gut feeling is they have the pricing power to ride this phase out.
Down 10% today as I write
(I now Hold)
There again, SDG customers really won’t be worrying about food or utility bills - have you seen their prices?!
Paul,
I think you need to be careful characterising end customers of a company in this way. I’m sure they also make sales to plenty of ordinary middle income households, wanting some nice curtains and blinds, who will be effected by the increased cost of living.
You also have to take into account that they are not shipping an end product to an end customer, and most people I know do not make their own curtains, blinds etc. So once you add on the increased costs of manufacture and fitting, to the cost of the fabric it seems to me the overall final cost will be too high for all but the very rich. I think that’s a problem.
As you mention , it seems very cheap and has net cash. As an exporter, it will also have benefitted from the strength of USD year to date, so in that regard maybe this update is a little more disappointing than it first appears.
All the best, Si
A propos of nothing specifically related to today's company news, when one might well feel thoroughly depressed, I was reminded of reading recently a thoroughly uplifting RNS from Morgan Advanced Materials (LON:MGAM) for their half year results to the end of June. I intended to return to them with a view to watching them carefully and buying in at the right moment (if there is likely to be one soon!). I commend it to everyone.
Paul I just bought into Renold (LON:RNO) again so it will be very interesting to hear about your interview with the CEO tomorrow. No doubt your comments will be part of your excellent Saturday Podcast which I highly recommend to any Subscribers who may not have heard your Saturday morning musings on the weeks results and news.
Thanks for the update on Duke Royalty (LON:DUKE) I am broadly positive on this one which I think looks well placed in an inflationary environment. I agree the cost of the debt looks too high at 7.25% but I understand the company is trying to reduce its cost of debt. As they scale up they should be able to achieve both a higher equity rating and a lower cost of debt.
re: £DUKE
you're welcome! They do need to keep scaling, reducing the LIBOR margin would be very positive news indeed.
Interested to read the Property Franchise (LON:TPFG) H1 trading statement. They have a number of trading initiatives, though new instructions are proving tougher to get, due to restrictions in supply. Their acquisition is driving growth rather than organic sales, and the stronger suit seems to be their rental clients. Talk about acquiring more lettings as a positive.
Probably a similar theme developing across the likes of Belvoir (LON:BLV) and Foxtons (LON:FOXT) ?
I hold
Based on current predictions from MoneySavingExpert the energy price cap will go from the current equivalent of £1,971 per year for an average household (itself quite high) to £3,359 in October and £3,616 in January (under the new 3 month cap announced today). These are very significant price rises and that's just on energy let alone any rises on food, mortgages and other consumer goods. I am pretty negative about the 12-24 month outlook for businesses like £SCS
Volex (LON:VLX) - 200d MA crossed and comfortably above 50d MA. Chart looks good too. PEG= 0.7 and PSR <1
I thought it was a very cautious inline update from Sanderson Design (LON:SDG) which did not get hammered (down 3.5% at time of writing), which seems to have been the theme of late.
Perhaps the market is starting to come to terms with the current economic outlook.
For Sanderson Design (LON:SDG) I wonder if they can keep control of their costs as revenue flattens out, which in the current environment is not going to be easy. It would be a shame if the profit element of royalties is lost by by rising inflation and/or inefficiencies in the manufacturing arm.
Previous holder
Hi TheFloatingInvestor,
I'll take a look at Sanderson Design (LON:SDG) (I hold) next, watch this space!!!
Regards, Paul.
MrContrarian as a holder of Thinksmart (LON:TSL) you may be interested in my posts on ADVFN last December on Thinksmart posts 535,539 and 540.
In these posts I expressed the view that Private Shareholders were at the mercy of the Board of Thinksmart who control over 41% of the Shares.In the light of recent events my concerns seem sadly to be vindicated.
However a big jump in SP yesterday on the back of a rise In BLOCK Shares on the NYSE.
Morning Paul, Graham,
Interested in your thoughts on Sanderson Design (LON:SDG) and Renold (LON:RNO) updates if possible. Thanks.
Moring Tango99,
Yes, I'll be covering both Sanderson Design (LON:SDG) (I hold) and Renold (LON:RNO) (not currently holding) shortly.
Regards, Paul.
Good updates from Sanderson Design (LON:SDG) and SCS (LON:SCS) given the economic malaise, caveated by the not unexpected cautious outlook.
Also a more positive update from Facilities by ADF (LON:ADF) albeit in-line, a very much upbeat outlook narrative, with the order book for the current year very nearly full and that for 2023 continuing to grow. Acquisitions remain part of the of the company's strategy.
Finally an interesting acquisition by Renold (LON:RNO) of a Spanish manufacturer of conveyor chain. Total consideration of 24m euros. Will be earnings enhancing and accretive to margins.
I hold all of the above, except Renold (LON:RNO) that is starting to look interesting.
What to do about SCS (LON:SCS)? Hold and look through the gloom I suspect.
Thoughts and views on the above welcome.
Hi.
With regards to Facilities by ADF (LON:ADF), their Admission Document in December 2021 stated that their order book for 2022 was fully booked, however, in trading updates including todays they are now saying it’s nearly full, which may simply be a case of a poor choice of words or worse, and it leaves me somewhat uneasy in what they are saying. Particularly as their order lead times (7 months to 15 months or so) should not be resulting in a nearly full order book 6 months into the year (if that makes sense!).
What caught my eye in the Next (LON:NXT) results was the following:
"We suspect that the apparent improvement in the fortunes of our stores is, to some extent, down to the number of competing stores that have closed in the last three years."
If the surviving retailers with a large store footprint are seeing signs of stability in revenues despite the pressures on the consumer (a big if...), this could have some interesting implications for more geared plays like Hammerson £HMSO.
Morning all,
Good update from Facilities by ADF (LON:ADF) this morning, market appears not to like it?
Will you cover Paul/Graham?
Less profitable sales mix and I don't think this helps the outlook for long term demand.
https://www.ft.com/content/4dd...
Less profitable sales mix and I don't think this helps the outlook for long term demand.
https://www.ft.com/content/4dd...
I was unimpressed at how relieved they sounded to have filled the 2022 order book. There’s only a few months left in the year! And I’d have expected 2023 to be fully booked up by now, yet it is some way off.
Cuddlesticks and BnB - please tell us which company you are talking about (see explanatory notes in header).
Cuddlesticks and BnB - please tell us which company you are talking about (see explanatory notes in header).
Sorry £ADF - I do usually but, in mitigation, this was a rejoinder to a reply
I wouldn't worry, people can thread the replies. That they choose not to isn't your problem.
I wouldn't worry, people can thread the replies. That they choose not to isn't your problem.
Yes people can thread the replies, but many don't find it the best way. And yes it's partly our problem if we choose not to, but I've always assumed posters want people to read their posts., thought perhaps I'm wrong? But if they do then excluding unthreaded readers is their problem too. Stocko helpfully makes it easy to add a company reference, as BnB has already made plain he knows and usually does..
But what's the point of adding the company reference when you're replying to a thread about the company when it doesn't have the context of the original. You end up having to click on the "In reply to" link just to make sense of the conversation.
Of course, some people like to play teacher and tell others off, I find it tedious especially as the tools are there to make it unnecessary.
"But what's the point of adding the company reference when you're replying to a thread about the company when it doesn't have the context of the original. You end up having to click on the "In reply to" link just to make sense of the conversation."
Personally i find it pretty easy and useful to skim read stuff - i never use threaded and i can easily scroll down and find what i need and quite often the post speaks for itself (when you know the company) - no need for threads its easy and i only come a cropper when i dont have the ticker - so it massively helps me when ticker is present end of - not the end of the world when as you say the rely to link can take you there but i am deffo a fan of the tickers - pretty sure i am far from being alone here and the powers that be go as far as saying the following each day as a polite request.
please be civil, rational, and include the company name/ticker,
I will never moan if someone doesnt use the ticker - but it does get my goat up when peeps say the ticker doesnt serve any purpose for others when it clearly does for me and presumably others too.
Threaded replies is such a mess. If there are new posts where are they? I have to scroll down the whole report looking for them. If there are many replies then the width gets so narrow, its just long and thin. If there are several stocks then its not clear what the reply is to. with many replies its not clear who the person is replying to.
I was unimpressed at how relieved they sounded to have filled the 2022 order book. There’s only a few months left in the year! And I’d have expected 2023 to be fully booked up by now, yet it is some way off.
I have just read the RNS. I don't understand how you can imply any sense of "relief" here. I think you are trying to read too much into a simple RNS. Surely you can't simply be referring to the use of the word "pleased"?
And I don't see why they should be fully booked for FY23 when you look at how the industry works. Some companies will be engaged at an early stage of a new production but it seems to me Facilities by ADF (LON:ADF) will be one of the last services contracted in the process once everything else is committed and in place. As such, they are unlikely to ever have long term visibility stretching out 12 months into the future.
BTW I have no interest in this company and was more interested in how you could determine a sense of relief from reading a short RNS. I think sometimes we all try to read too much into these things and it's best to just concentrate on factual information, although there is so little in this update it hardly seems worth commenting on!
All the best, Si
Facilities by ADF (LON:ADF) - I think you are trying to read too much into a simple RNS
You are probably right there but I was genuinely surprised they felt the filling of the ‘22 order book was worthy of comment this late in the year. As for ‘23, productions are scheduled further in advance than you would imagine and that includes ensuring access to support services like trailers - my daughter is a producer at Sky and I understand that belts are being tightened.
SDG Sanderson Design Group
I’m loving that royalty revenue increase .
An in line update but there is a real interesting increase in licensing revenue .
“Total licensing revenue was up 90% at £3.8 million (H1 FY22: £2.0 million),
driven by £1.9 million (H1 FY22: £0.5 million) of accelerated income from
recently signed licence agreements.
The progress within licensing continues with the recently announced NEXT
contract extension, extending its partnership with Morris & Co. to 2025.
In addition, the Williams Sonoma kitchenware partnership with Morris &
Co., initially signed in August 2021, has been extended by two years to 2025,
displaying the major US retailer's confidence in the brand and products, which
are due to launch in September this year.”
This seens to be a Willy wonky golden ticket they are unlocking .
Royalty revenue is basically pure profit, to generate 3.8 million in half a year is stunning .
What I don’t understand is how this has not filtered through to increased profit ? Implying maybe rest of business is inline turnover wise but down profit wise .
The strategy should now be crystal clear
- focus on branding and marketing and develop the royalty income
- maintain distribution and manufacturing
You could even argue close manufacturing and just cash the royalty cheques every year but it’s not as simple as that .
It's a shame Sanderson Design (LON:SDG) don't do Investor Meet meetings so that they could explain those points.
Sanderson Design (LON:SDG)
I’m loving that royalty revenue increase .
Todays tailwainds are tomorrows headwinds - licence revenues can be very lumpy and can vanish overnight.
What I don’t understand is how this has not filtered through to increased profit ? Implying maybe rest of business is inline turnover wise but down profit wise .
Exactly
Royalty revenue is basically pure profit, to generate 3.8 million in half a year is stunning .
Probably not so stunning when you include the fact that £1.9 million of this is "accelerated income" - this wording suggests its actual sort of "future income" they must recognise now (presumably no clawback if future sales dont hit targets)- so on lfl basis that future periods have had that "licence income" already recognised so will have no matching revenue - note i am presuming this is the case please correct here if i have my facts wrong.
Per company today
Total licensing revenue was up 90% at GBP3.8 million (H1 FY22: GBP2.0 million), driven by GBP1.9 million (H1 FY22: GBP0.5 million) of accelerated income from recently signed licence agreements.
Note this company has history of blaming licencing fluctuations for profits warnings (24/7/18 for the elephants in the room) - so if they are using bumper accelerated licence income just to hit targets IMHO thats not great unless they clearly comunicate thats permanent step change in that income - so i suspect the news aint great. Looks like the shares have opened down so the market doesnt seem over inspired by the news today. I continue to be a happy holder at current levels overall - although with the benefit of hindsight kicking myself for not having fully sold out at the peak price last year (double where we are now) - the world is different from then though so i will not give myself a good kicking for not predicting what has happened the last 9-12 months .
Good points .
I would presume licensing revenue has to be invoiced amounts based on “sales within the period”
You say it is some sort of future royalty brought forward ?
If it’s the latter not as good as the former .
Whilst historically you say royalty has been lumpy the new CEO. Lisa Montague seems a much safer pair of hands who truly understands the brand strength and is showing how to monetise them .
Some big names like next now building and the interior market (think farrow and ball) like the SDG archive and it’s a rising tide sector so I don’t think the historic lumpiness is reflective of the current success and it is likely to grow and continue.
SDG needs to be a brand / marketing focus not a manufacturing focus and my interpretation is this is what the CEO is doing .
RE: Sanderson Design (LON:SDG)
To be honest, I found the update pretty hopeless in mentioning revenue only. In the current inflationary environment, for any update to be useful to us, companies should be giving a steer on margins. As the saying goes: "Sales are vanity, profit is sanity". It is like they are operating in a void with no details on cost pressures, product pricing etc.
It's what companies are not telling us in updates that most concerns me. Companies should always be monitoring margins, especially now more than ever, so if they don't say anything you can only read that possibly as a negative. Most of all I want to invest in companies led by up-front and honest management teams, not those that want to pull the wool over my eyes.
All the best, Si
Sanderson Design (LON:SDG)
simoan
To be honest, I found the update pretty hopeless in mentioning revenue only. In the current inflationary environment, for any update to be useful to us, companies should be giving a steer on margins. As the saying goes: "Sales are vanity, profit is sanity". It is like they are operating in a void with no details on cost pressures, product pricing etc.
It's what companies are not telling us in updates that most concerns me. Companies should always be monitoring margins, especially now more than ever, so if they don't say anything you can only read that possibly as a negative. Most of all I want to invest in companies led by up-front and honest management teams, not those that want to pull the wool over my eyes.
I think this criticism is ultra harsh and expecting too much in some respects - i would agree they could have perhaps been more upfront if accelerated licences have come to the rescue here ref meeting expectations.
Company have specifcially confirmed they are on track to meet current expectations so for trading update its job done - overall nothing is being hidden as they are on track !
Despite this, full year trading currently remains in line with the Board's expectations.
Ref getting more detail - thats exactly what the intermin results are for - they are hiding absolutely nothing we simply need to wait 2 months ish (sometime october) for those figures to come along. To me its pretty bog standard to wait for full figures before providing more detailed info - we are only 4 days past half end and we will get 6 monthly figures within 90 days of period end - probably 75. Thats certainly not tardy ref providing the necessary ectra detail and very similar to what many other companies do.
all imho of course - todays update does seem to have gone down like a sack of spuds considering that in the current environment being "on track" is actually a good outcome compared to what soem others have been delivering. (poor made.com) - so your pont about perhaps not being as transparent as they could have been seems very fair comment - if this is a sneaky back door profit warning ref the future years prospects.
You are correct , revenues explained in detail and cash balance is given.
But , that was a big miss in revenues ( at least for the 6 months ) , as market expectations are for them to grow for the current financial year. This is the reason the price has fallen , and will continue to fall , if revenues are not metro accelerate in the near future.
I think this criticism is ultra harsh and expecting too much in some respects - i would agree they could have perhaps been more upfront if accelerated licences have come to the rescue here ref meeting expectations.
Company have specifcially confirmed they are on track to meet current expectations so for trading update its job done - overall nothing is being hidden as they are on track !
Fair point maybe but they only mention cost pressures in the CEO statement at the end of the RNS. So they exist, but we are not told what they are! I just believe more information is better than less and they must have important information on costs, pricing, margins etc. that they have chosen not to disclose. As such, I personally did not find this update that helpful. I only bought in very recently and was hoping for some disclosure on costs, instead we're all left none the wiser. It seems to me there is decent likelihood of a profit warning here at the interims so I won't be buying any more for now.
All the best, Si
Sanderson Design (LON:SDG)
I would presume licensing revenue has to be invoiced amounts based on “sales within the period”You say it is some sort of future royalty brought forward ?
If it’s the latter not as good as the former .
I must admit its total guesswork on my part - but i suspect you if are giving away your crown jewels by giving others the ability to sell your stuff on tick - you would want an hefty upfront payment . I would therefore guess that if sanderson have strong hand - they would secure large upfront payment that would be based on some sort of "minumum agreed volume" - if the other party doesnt then sell what they promised or doesnt pay or rips of your products by copying at least you have had some pound of flesh upfront. I cant believe that the term accelerated could mean anything but payment now for future presumed sales. With such sales if there is no provision for refunds to be made later (ie sanderson keep the cash if targets arent met) it would make sense that these sales are fully booked now rather than applying normal rules to prepay as appropriate - all assumptions on my part i could be totally wrong.
I must admit its total guesswork on my part - but i suspect you if are giving away your crown jewels by giving others the ability to sell your stuff on tick - you would want an hefty upfront payment . I would therefore guess that if sanderson have strong hand - they would secure large upfront payment that would be based on some sort of "minumum agreed volume" - if the other party doesnt then sell what they promised or doesnt pay or rips of your products by copying at least you have had some pound of flesh upfront. I cant believe that the term accelerated could mean anything but payment now for future presumed sales. With such sales if there is no provision for refunds to be made later (ie sanderson keep the cash if targets arent met) it would make sense that these sales are fully booked now rather than applying normal rules to prepay as appropriate - all assumptions on my part i could be totally wrong.
Firstly, you seem to completely misunderstand how IP licensing works. Sanderson Design (LON:SDG) are only providing the licensee (Next or whoever) with the rights to use one or more designs, maybe even a whole catalogue of designs, for a limited time period. The licensee is not selling any of the Sanderson Design (LON:SDG) crown jewels and they still own the Intellectual Property. Think ARM Holdings. The licensee is merely buying a license to use the designs to produce their own products. So there will be an up-front license fee paid by the licensee and then maybe a stream of royalties based on volume of products shipped.
And of course, when in doubt referring to the FY22 Annual Report is always preferable to guesswork:
Licensing arrangements. These comprise a combination of both minimum guaranteed incomes and time and sales-based royalties receivable from Licensing Partners under contracts for the licensing of our products and designs.
and
Licensing contracts give rise to performance-based variable consideration. Income dependent on the performance of the third-party operations is recognised when it is highly probable that a significant reversal in the amount of income recognised will not occur. Fixed minimum guaranteed income amounts receivable under single-year or multi-year licensing agreements from Licensing partners are recognised from the point the licence and hence control has transferred to the licensee, provided there are no further performance obligations to fulfil, and the recoverability of the income is deemed highly probable. The income is recognised as revenue and accrued income reduces as the balance is settled when an invoice is issued upon delivery of the performance obligations.
Hi Paul and fellow followers of SCVR,
An interesting trading statement from £SCS . Good results but a substantial fall in the cash balance to £71m from £87.9 in January. I would have expected this to hold up until orders really fall off a cliff, should we suffer the expected recession . Does anyone have any insight into this? I don't hold. Thanks.
I have not done a full analysis of SCS (LON:SCS) (I hold) cash position movement but 4 factors spring immediately to mind which could explain the reduction:
1. Lower order levels mean lower customer deposits paid in advance
2, Seasonal factors
3. Share buybacks
4. High dividends
I am happy to wait until the results are published in October.
SCS (LON:SCS)
An interesting trading statement from SCS (LON:SCS) . Good results but a substantial fall in the cash balance to £71m from £87.9 in January. I would have expected this to hold up until orders really fall off a cliff, should we suffer the expected recession . Does anyone have any insight into this? I don't hold. Thanks.
Pure guesswork but orderbook then was £148 million and is now only £72 million - so i would expect its not unexpected that cashflow would be somewhat "lumpy" with such large variations in everything - thats ignoring the other factors like natural calendar peaks and the like. To be honest this is a simple business model they have plenty of cash in the bank but a decent % of that is match by liabilities !!
If we flip back to July 2019 they had only £57 mill net cash.
If they have made £28 mill net profit in 3 years since then
paid out £10 mill of divis
that would give us £75 mil of cash - so £71 mill seems closer to what i would have expected than £88 mill albeit thats extremley sketchy calcs !
Must admit i didn't really expect this to end up below 150p without profits falling of a cliff - if i had cash free i could very well be tempted to add here - would be nice to see if broker estimates for next year may be reduced though ?
I have warned about ScS when it was around 240p and we had a bit of a heated debate.
Their cash balance is no where near what people think ( and I mean real shareholders cash ). I do not see any upside from here and there is a big profit warning in today’s announcement that will negatively affect the share price in the future.
As I said before , I hope I am wrong and whoever holds this stock makes good money.
Thanks
In fairness re SCS (LON:SCS) it has not been difficult to isolate what cash on the balance sheet sits as true company cash so I don't think it's right to say "the cash balance is no where near what people think". Shore capital today even have a chart showing the absolute cash balance and then breaking it out between customer deposits and company cash from FY2018 through to FY2024e. It sits at over £40m of company cash for the current year, which is pretty substantial against a profitable company with a mcap of £60m.
My calculation is that the real cash balance is £33m for the current financial year , falling to £20m the next year.
Don’t forget that the last six months turnover is even worse than the 2021 equivalent turnover ( and that was impacted by Covid ). A well hidden profit warning in today’s announcement ( yet again ).
But as I said , and I will not comment further on this , I hope the price recovers to previous levels and people make money.
SCS (LON:SCS) order book is £31.8m than a year ago.
That's right, SCS (I hold) previously had an unusually bloated order book, because supply chain delays meant it couldn't fulfil orders, making lead times longer & longer.
Therefore today's news that the order book has substantially reduced, is good in that it means the company must be working through the backlogs, and lead times should be shorter (which customers prefer obviously).
The downside is that they're not refilling the order book as much, due to softer demand, likely to worsen as this year progresses, hence the profit warning today for FY 7/2023, slipped out through the Shore Capital update, and some vague wording in SCS's update. I wonder if the buyers first thing had seen the Shore note?
It's a bit underhand doing things that way, but lots of companies do the same - what seems an irrational early price move subsequently becomes obvious when more people find out that the house broker has slashed the forecasts, having obviously discussed it with the CFO. Very unsatisfactory. This is why I think all companies should publish their own guidance for profit, as larger competitor DFS Furniture (LON:DFS) does - it's much more transparent, and fairer to PIs, who suffer an information disadvantage compared with professional & institutional investors.
Regards, Paul.
I went to an SCS store with my wife last week to see if we could find a sofa we liked which we could get on the day or within a week. There were 2 sales staff and 2 customers (us). Half an hour later there were 2 sales staff and no customers. The sales guy said it was very quiet but that was usual for July/August/September. 15 weeks wait for majority of product.
Dunelm a couple of stores down had a reasonable amount of customers in it.
Instem (LON:INS) is a leading provider of IT solutions & services to the life sciences market delivering compelling solutions for Study Management Regulatory Submissions, Clinical Trial Acceleration, and Informatics-based Insight Generation.
Strong organic and inorganic growth with an over 60% increase in recurring software revenue
Combined organic and inorganic revenue for H1 2022 is expected to be in the region of £27.6m (H1 2021: £19.8m), an increase of approximately 39%. In addition, recurring software revenue grew by over 60% in the same period.
Additional Opex as sensibly increased salaries to keep software staff happy. In April to mitigate also set in place price increases of 12%.
Operates in 2 high growth areas of Life Science and Software
The Company remains optimistic about the wider market opportunity - especially given its broader reach following the integration of the Acquisitions. With a scalable platform in place and significant opportunities, the Board is confident that the enlarged group will continue to deliver growth across all key financial and operational metrics. We are therefore confident that the Group will deliver on the Board's expectations for the FY22 financial year.
Update seems decent to me and sensible action taken in this inflationary environment - look after your staff.
I hold
I would welcome your comments on Saietta (LON:SED) who IPO’d in July last year and issued their full year results at 16:40 yesterday and immediately after announced a new contract and proposed placing. This morning they announced the subscription offer was oversubscribed but they have also announced a ‘broker option’:
“In order to deal with any additional demand from shareholders and other investors who did not participate in the Placing, the Company has granted an option (the "Broker Option") to Canaccord to allow for the issue of up to an additional 1,666,667 new Ordinary Shares (the "Broker Option Shares") at the Issue Price.”
This is a very fast growing company involved in AFT (Axial Flux Technology) in the rapidly growing electric vehicle market. The company has made some canny moves (in my opinion) since IPO acquiring e-traction from Evergrande in what appeared to be a ‘distressed sale’ last November and establishing an EV motor production facility in April this year.
I hold, but bought at higher prices than current option price.
SCS (LON:SCS) Outlook:
"In recent months we have seen reduced in-store and online visitors resulting in a reduction in order levels, driven by the widely reported falling consumer confidence as a result of the cost of living pressures and economic uncertainty.
We expect the low consumer confidence will continue to adversely impact the Group in FY23. However, the Group is in a strong position as we enter the new financial year, and strategic progress over the last 12 months means we are well positioned to take market share and maximise opportunities in a difficult environment."
BOE expected to raise rates to 1.75% today, so big ticket items likely to get squeezed even more imo.