Small Cap Value Report (Thu 4 Jan 2024) - LIKE, TRU, AGL, SWG, TPT, JD.

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Live prices tracking spreadsheet for Paul & Graham's 2024 share ideas (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs) - search on any podcast provider for "Paul Scott small caps", or web link here.
Summaries
Likewise (LON:LIKE) - Up 15% to 23p (£56m) - Trading Update (in line) - Paul - AMBER
The market clearly likes today's upbeat tone, although it's only in line with expectations on profit. I can see the potential for operationally geared upside here, as it gains market share, and (maybe) demand recovers from depressed levels. On a value basis I prefer larger competitor Headlam (LON:HEAD) but LIKE is certainly a thorn in its side, and may have greater growth potential. A race to the bottom on already low margins is possible though.
Trufin (LON:TRU) - down 6% to 47p (£50m) - Trading Update (revenue miss) - Graham - RED
This group of three companies misses its revenue forecast by a wide margin after delays in commercial agreements at its video game business. The cash balance is still substantial and might withstand upcoming losses but the investment case remains far from clear to me.
Quick comments on today’s movers -
Angle (LON:AGL) up 55% to 20.5p (£53m) - “breakthrough clinical results” - Paul - RED
This jam tomorrow share ("world-leading liquid biopsy") has been around a long time (20 years on AIM!), and burned through lots of cash, funded by repeated dilutive fundraisings. Said on 9/11/2023 that “cash runway extended into Q2 2025”. Could be an interesting, higher risk punt, who knows, but price spikes on nice updates have fizzled out every time previously. [no section below]
Shearwater (LON:SWG) - up 9% to 50p (£12m) - Contract wins - Paul - AMBER
Quite an interesting update from this cyber-security services company, with a $3.2m (over 3 years) deferred contract with a global bank now signed. Plus a £0.8m deal with a UK Govt department, 3 years again. I like to see deals with major customers, as they can act as good reference sites for further contract wins. I’ve not looked at it since profit warning in Mar 2023, when I thought it might be cheap. Last balance sheet seems adequate. Could be worth a fresh look?
Topps Tiles (LON:TPT) - down 7% to 46.1p (£91m) - Q1 TU (revenues soft) - Graham - AMBER
Full-year estimates for 2024 and 2025 are unchanged, but investors might struggle to have faith given that Q1 revenues show year-on-year weakness towards the end of the quarter, and there is likely to be a large second-half weighting. Cheap but maybe priced right here.
JD Sports Fashion (LON:JD.) - Down 23% to 119p (£6.2bn) - Trading Update (profit warning) - Paul - BLACK (profit warning), but GREEN on fundamentals (it’s cheap now!)
I delve into the profit warning from this FTSE 100 sports retailer, and come to the conclusion that it's looking attractive value now. A possibly interesting entry point, I wonder?
Paul’s Section:
Likewise (LON:LIKE)
Up 15% to 23p (£56m) - Trading Update (in line) - Paul - AMBER
Likewise Group plc (AIM:LIKE), the fast growing and progressive Flooring Distributor…
This is the challenger flooring distributor, set up by a former CEO of the sector leader, Headlam (LON:HEAD) . I gave it a tentative thumbs up here on 13/1/2023, but cooled to amber on 30/5/2023 with an in line update. The business needs to scale up some more, to generate meaningful profits I think. This was confirmed when I had a call with the CEO last summer, who indicated more acquisitions, and pushing more volume through the existing facilities is the strategy to grow profits.
My main concern is that LIKE might be eroding margins at HEAD through competing for business, leaving both in a lacklustre position maybe? Although I included HEAD in my top 20 share ideas for 2024 due to its very low valuation, large freehold asset base, and scope for profit recovery as consumer demand may return to a more normal level (about 20% higher than current depressed demand, HEAD has said previously).
Both businesses are pretty basic - they buy carpets in bulk, with a very wide range, store them in large warehouses, then supply independent carpet retailers on a room-by-room basis for each customer order, charging a fairly modest mark-up. So it’s really all about scale, plus efficiency & managing the logistics & sales operation well.
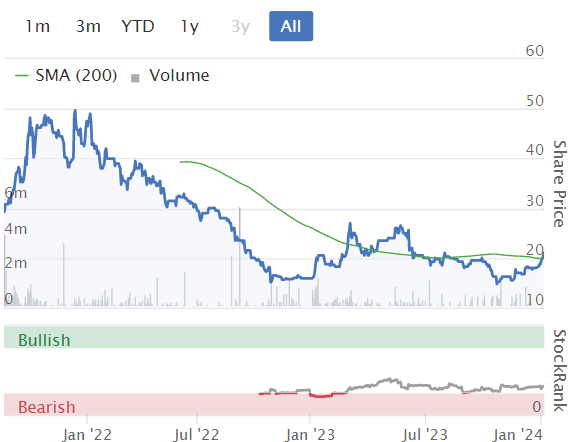
So far, LIKE has expanded rapidly, and only made modest losses during the rapid growth phase. The reason I’m following LIKE is because in a bull market, I could see the rating expand to anticipate more growth, and profit margins could rise as it achieves greater scale, so as I said on 30/5/2023 it’s possibly one to watch?
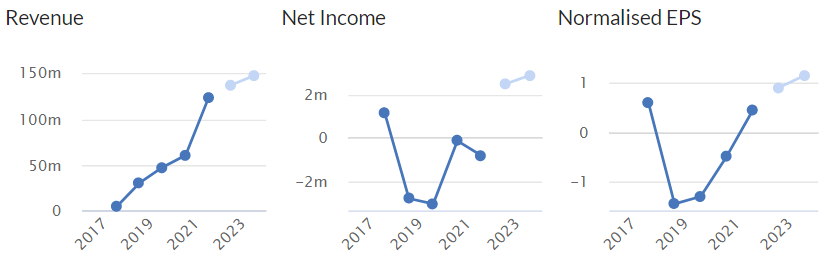
FY 12/2023 is forecast to be profitable, but only a modest profit margin -
Today’s news -
Trading update - FY 12/2023.
Revenues ahead of expectations.
Underlying profitability is in line with market expectations.
Outlook -
The Board is confident of achieving the current market expectations for FY24 as the Group continues to develop its position in the UK Flooring Market…
The Group has invested heavily in Point of Sale Displays and Sampling to significantly increase its market presence over the last three years in conjunction with establishing the Logistics Infrastructure. The final quarter of 2023 demonstrated the success of this strategy to date with the ability to generate increasing Sales Revenue whilst providing the Operational expertise to service customers effectively.
This strategy will continue into 2024 as the Group is confident in continuing to gain market share and through operational gearing, improve profitability.
Dividends - 3 small divis have been paid since it listed - 0.2p (8/7/22), 0.2p (7/7/23), and 0.1p (17/11/23) according to the data. Although the commentary today refers to a “maiden interim dividend” declared in Sept 2023. ”Committed to a progressive dividend policy in line with profitability”.
Balance sheet - I’ve checked the last one, as at 30/6/2023, and it looks OK to me. There’s some freehold property in there, and a tiny net bank debt position. Lots of working capital, but debits and credits balance up. No concerns here, although note the price to NTAV of about 1.8x (after adjusting for today’s share price rise) is much higher (ie. worse) than the exceptionally cheap 0.87x of larger competitor HEAD. In other words, buying HEAD shares provides a lot more balance sheet downside protection than LIKE shares.
Broker updates - there are 2 today, WH Ireland and Zeus, very helpful, thank you to both.
Zeus has 0.9p adj EPS for FY 12/2023, rising to 1.1p in FY 12/2024.
At 23p/share that gives PERs of 26x and 21x - not cheap, but PERs can be a clumsy measure at growing companies. Obviously the bull case rests on more growth, improving market conditions, increased market share, and hence operationally geared upside to earnings.
Paul’s opinion - this update is only in line with expectations, so the 15% share price rise is a little surprising. Although the confident-sounding outlook may draw some investors to conclude that there’s upside on existing forecasts?
I think it looks a credible growth company, although it has yet to demonstrate that it can generate meaningful profit margins.
After today’s update, I think the valuation looks about right, so I’ll stick with AMBER for now - ie some good points (growth potential), but also some less good aspects (limited profits to date, and competitive, low margin sector).
JD Sports Fashion (LON:JD.)
Down 23% to 119p (£6.2bn) - Trading Update (profit warning) - Paul - BLACK (profit warning), but GREEN on fundamentals (it looks cheap now!)
For newer subscribers not aware, at this time of year I like to cover updates from mid and large caps in the retailing sectors, to assess the general health of the consumer (more than half of GDP). This one is in the FTSE 100, and still will be, despite shedding a scary £1.85bn in value this morning.
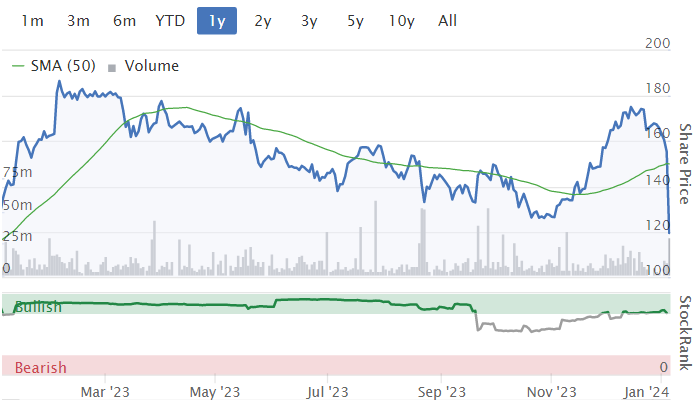
JD Sports has been a fabulous multibagger over the long-term, having grown very strongly, including international expansion. However, today its shares have given up the entire “everything rally” we saw in Nov-Dec 2023 - I thought charts were supposed to be predictive of performance, which certainly has not been the case here -
Profit warning this morning, summarising it -
Revised adj PBT guidance for FY 1/2024 (53 weeks to 3/2/2024) £915-935m.
Previous guidance on the RNS was £1.04bn (21/9/2023, within interim results), so this is an 11% shortfall in adj PBT.
Revenue growth in H2 (so far) was “slightly behind our expectations”. Reasons given - milder weather, cautious consumers, peak season “softer & more promotional” (ie having to offer discounts to shift stuff) than anticipated.
H2 (22 weeks) like-for-like revenue growth only 1.8%, well below inflation (and wages cost growth).
Gross margin lower than expected (due to discounting), but in line with last year.
Full year gross margin will be “slightly lower” than last year.
£7m profit hit from reclassifying capex into opex, and £8m lower interest income.
Inventories position is “comfortable”.
Are JD shares cheap now? This is all that matters!
Current forecast consensus is 13.3p EPS for FY 1/2024, so dropping that by 11% under-performance indicated today results in 11.8p EPS.
That’s a PER of 10.1x at today’s reduced 119p share price. This strikes me as a reasonable valuation, and it’s still earnings growth compared with the 10.6p normalised EPS shown for last year, FY 1/2023.
What’s the balance sheet like? It’s about £1.2bn NTAV at 7/2023, so not a great deal of asset backing compared with its £6.2bn market cap. The £1.3bn “Put and call option liabilities” look large & unusual - anyone got any ideas what that’s about?
It has net cash (excl leases) of £1.3bn, so cash & liquidity looks ample.
Paul’s opinion - NIKE reported softer sales recently, and its shares also gave up most of the autumn 2023 rally, but it’s valued at 26x forward earnings forecast. I know NIKE is not a retailer, but it sells trainers, like JD does. Medium term growth rates are similar. NIKE makes a higher net profit margin, but they’re not a million miles apart. So of the 2 companies, JD’s PER of 10x looks far more attractive to me.
I think this profit warning has brought JD Sports down to a fairly attractive valuation, on what looks like a fairly minor/temporary setback. Consumer demand could well accelerate in 2024 due to the now favourable macro factors in the pipeline (real wage rises in particular). So I see JD as a fairly decent GARP share. So it gets a thumbs up from me, due to the now much more attractive valuation today, for what has proven to be an excellent long-term growth share. GREEN on fundamentals, but it’s a profit warning so it has to be BLACK for my spreadsheet summary (which flags profit warnings in black).
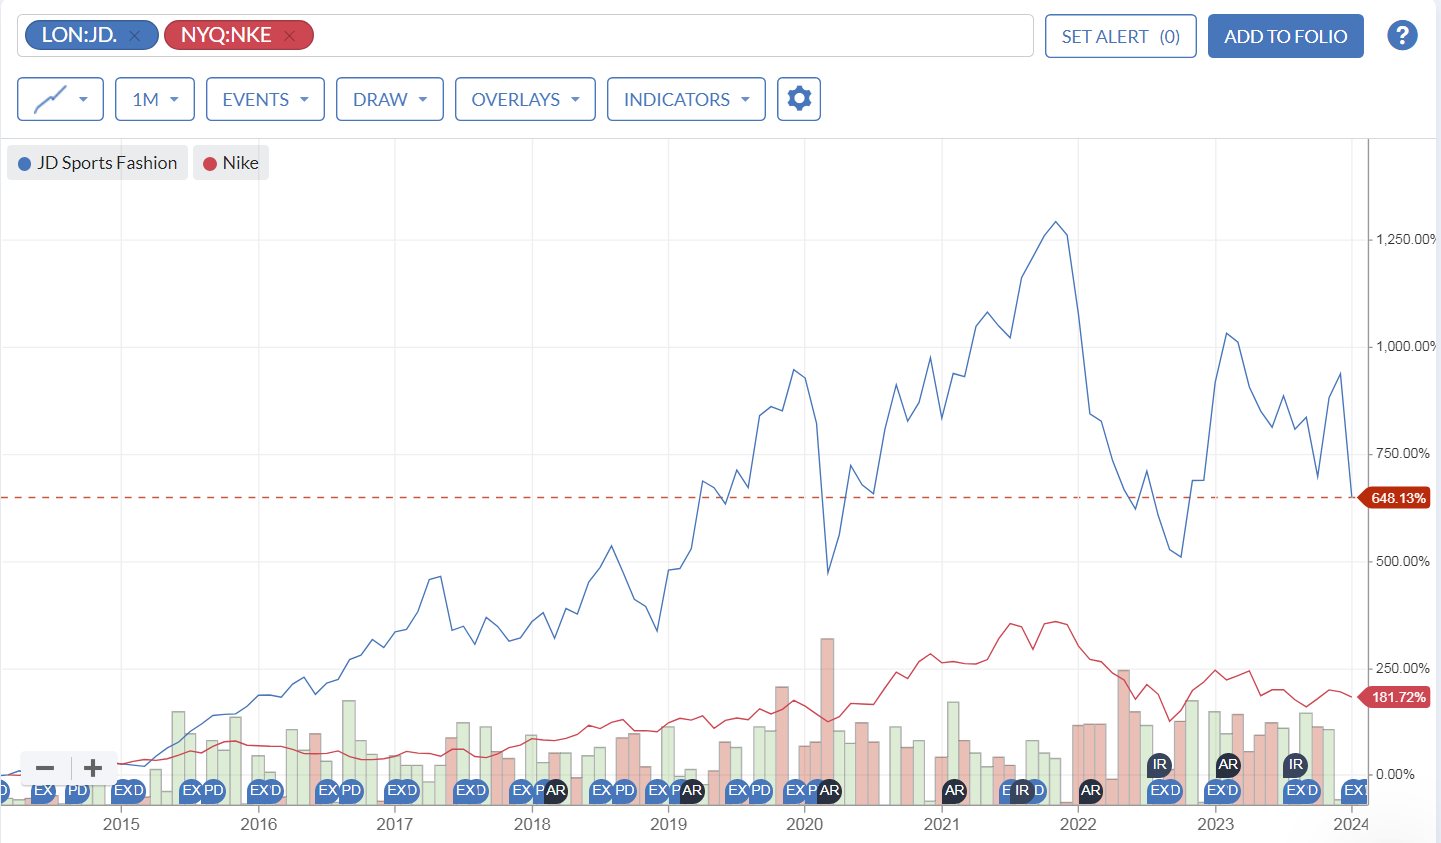
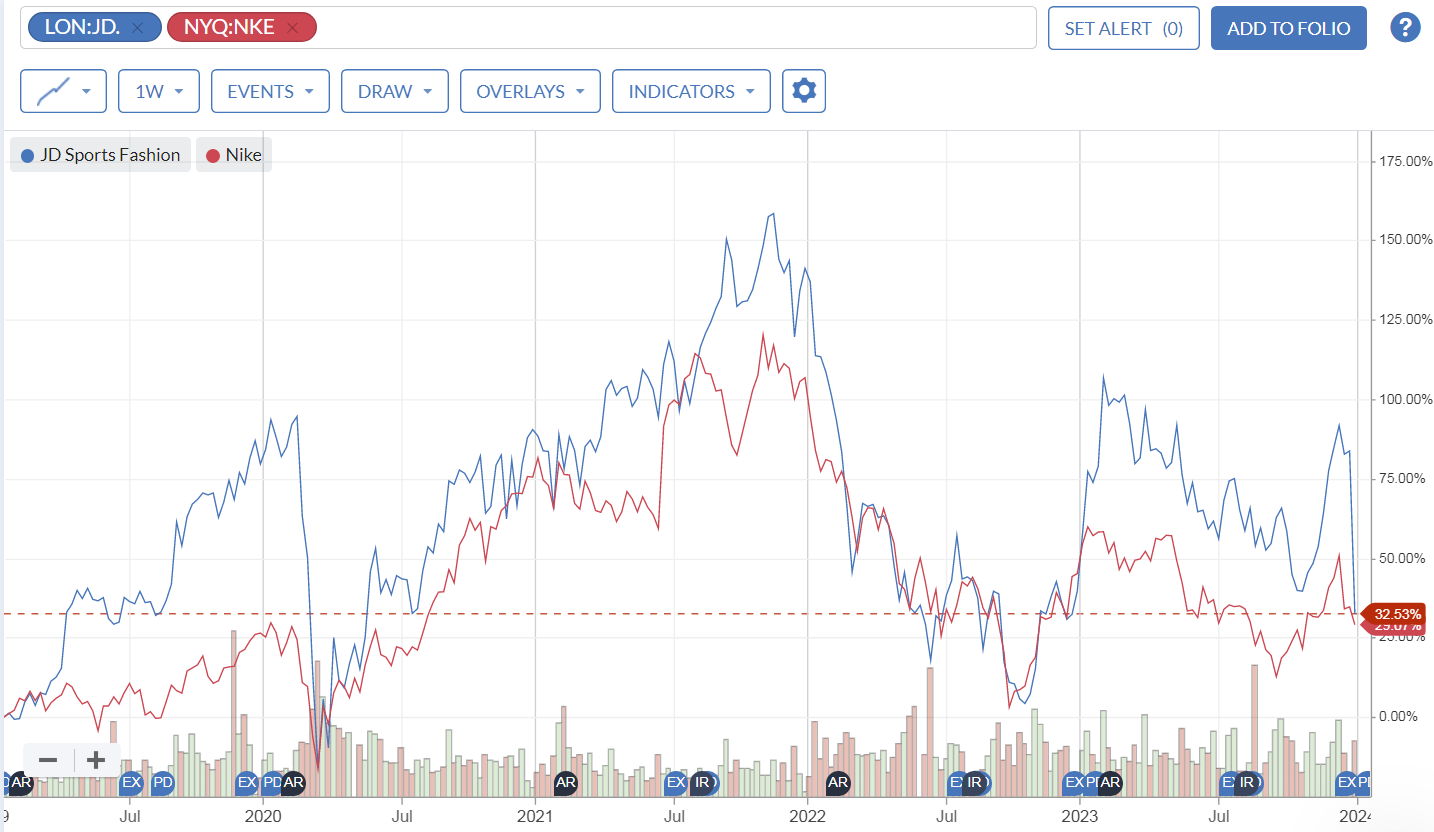
Over the last 10 years, JD shares are up +648%, versus +182% for NIKE. Although if I shorten the timescale to 5-years, then they're both only up 20-30%, and have tracked each other really closely (second chart below) -
10-year chart -
And the 5-year chart -
Graham’s Section:
Trufin (LON:TRU)
Share price: 47p (-6%)
Market cap: £50m
We tend not to cover this one, and the StockReport instantly reveals why:
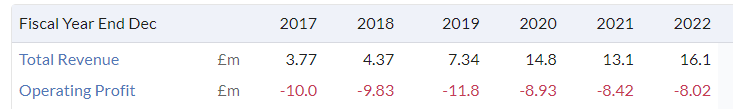
But let’s keep an open mind and see what today’s full-year update for 2023 has in store for us.
Here’s what Trufin does:
TruFin provides software and niche lending solutions to thousands of businesses across the UK via our companies Oxygen and Satago. We also have a significant interest in the mobile and console gaming company, Playstack.
Oxygen provides an early payment platform enabling businesses to get paid faster by public sector clients, and in general to “have more effective relationships with the public sector”.
In a similar vein, Satago is a platform for businesses to “avoid credit risks, improve debtor management, save time and stress on chasing payment and access invoice finance”.
So here is today’s news:
Oxygen and Satago performed in line with expectations, but Playstack missed expectations.
Revenue is therefore below expectations. Revenues are still up by at least 32% year-on-year to £20.2m.
The adjusted pre-tax loss is in line with expectations, being a loss of no more than £6.3m (last year: £8.2m loss).
The disappointment at Playstack is explained by reference to “platform deals” being slow to conclude, which I think is an issue we have seen recently from other gaming companies.
Outlook for 2024: unchanged.
Year-end cash: at least £9m, of which unrestricted cash is at least £5.5m. Trufin says it is “fully funded to profitability”.
CEO comment provides a message on each subsidiary but the overriding message is:
"Whilst a delay in finalising Playstack's platform deals and the associated financial impact is frustrating to report, the Board is confident that the Group is well placed to deliver significant value for shareholders.
Graham’s view
A pre-tax loss of £6.3m doesn’t fill me with confidence that the company is fully funded to profitability, given that current unrestricted cash is less than this amount.
Checking the broker note from Liberum, I see that the revenue miss for 2023 is enormous: £27m was pencilled in, but only £20.2m has materialised, due to the delays at Playstack.
The fact that the company missed out on nearly £7m of revenues but this made no difference to bottom line profitability is also puzzling - did Trufin not expect to book any profits on these lost revenues?
2024 estimates suggest another loss is on the cards, before the company turns the corner to profitability in 2025.
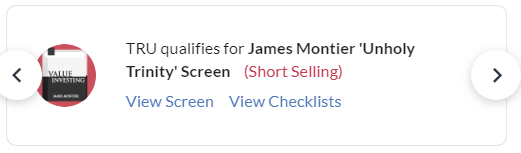
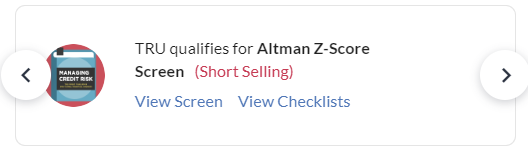
I note that this stock passes two bearish stock screens, something I don’t see very often. Although this could change when the full-year 2023 numbers are published:
While I can accept that Trufin might be fully funded to profitability, it’s still not obvious to me how we can justify a £50m market cap. If Playstack was given an aggressive video game industry multiple, then maybe we could get there?
However, while I like the video game sector as a whole, Playstack is a publisher in the “indie” space and I struggle to see how companies in this sector can be worth premium valuations. Indie games tend to strike me as quick hits, not lasting franchises with wide appeal.
I’m therefore going to have to reluctantly give this share the thumbs down. Even if the balance sheet easily survives the next year or two of losses, the £50m market cap still seems ambitious to me.
Topps Tiles (LON:TPT)
Share price: 46.1p (-7%)
Market cap: £91m
Topps Tiles Plc ("Topps Group", or the "Group"), the UK's leading tile specialist, announces a trading update for the 13-week period ended 30 December 2023.
It’s a downbeat Q1 update from this tile specialist.
Q1 trading has “reflected the ongoing challenges to discretionary consumer spending”, particularly in the property RMI (repair, maintenance, improvement) sector.
Total group sales are down 4% year-on-year (of course down more than that in real terms).
Like-for-like sales at Topps Tiles are down 7.1%. Sales to trade customers are “more resilient” than sales to homeowners.
Parkside (the commercial tiles business) is “in line with expectations” and is “profitable in the year to date”.
The update doesn’t continue much longer, key points:
Cost base well controlled, cash flow strong.
Group profits to be weighted towards the second half (this had been previously flagged).
Company expects to have gained further market share in Q1.
Estimates
Edison have left their FY September 2024 and FY September 2025 estimates unchanged, on the basis that sales were only a little softer towards the end of Q1 than they were during the first two months of the quarter. They also note that Q1 last year was strong towards the end of the quarter, making for a difficult comparative.
So there is an adjusted PBT estimate of £13.2m for the current year, rising to £14.7m for next year, on gently rising sales.
Graham’s view
This sector always makes me nervous - volatile demand and lowish margins.
Given that the share price is down 6% despite full-year forecasts being unchanged, investors must share my anxiety over any negative news relating to the revenue trend here.
The company has struggled to maintain EPS forecasts over the past 18 months:
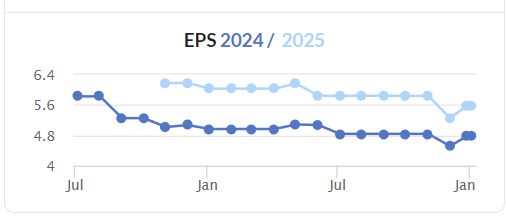
With a second half weighting flagged and a soft Q1, I’d be very cautious about another downgrade coming during the course of the year.
Of course the economy might surprise us to the upside over the spring and summer, and in any case the TPT share price might have already priced in another downgrade. But I’d have to assume that the most likely outcome here is for more bad news and for the estimates to get shaken again.
Against that, the company did report £23m of net cash (excluding leases) as of September 2023.
Value metrics are attractive, it has a StockRank of 87, and Roland has been positive on it (see here).
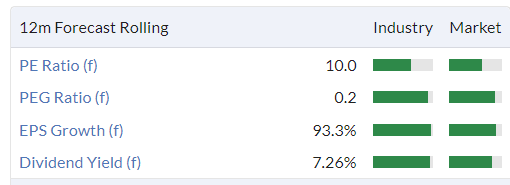
However, I can’t bring myself to give this one thumbs up, so I’m going to put a neutral colour on my stance here today. Sorry Roland!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
JD Sports Fashion (LON:JD.) Thanks for ALL your reports Paul; I know you are sceptical of charts , they are only based on known information and the Sentiment of the moment and here bottom fishers. It is though clear in the daily chart that it would not go higher until good news then on Friday ( an up day for FTSE 350) it gapped down, followed over 5 days with more falls shown by the Stochastic back to the 13th. Dec.
With a 30% gain in hand in the current market at least a top slice would be in order.
Agreed it is nowhere near foolproof BUT it can provide an idea of direction.
A Happy and Successful Rewarding 2024 for Stocko Staff and all the readers and contributors.
http://newsfile.refinitiv.com/...
Zotefoams (LON:ZTF) Schroders have added another 1% to their already large holding here, the second time in a few weeks, along with two director buys in December, one of £100,000, this is beginning to look like the Re Zorce project may have legs.
Zotefoams (LON:ZTF)
BGF appear to be new investors with 4.7% They seem to be involved with business funding. Does that have any implications?
BGF Investment Management had 3.55% (according to Stockopedia data) at April 2023.
Zotefoams (LON:ZTF) Not new, both BGF and Schroders increased they share yesterday.
Zotefoams (LON:ZTF) My mistake. As you say, they are not new. In my defence, the rns section "Position of previous notification (if applicable)" is blank so I assumed 0%
Has anyone seen this dreadful 11.20am delisting announcement from the small REIT Highcroft Investments (LON:HCFT) today? They intend listing on TISE* (which I hadn't even heard of!) - this doesn't appear very attractive for small shareholders. I've exited quickly at a reasonable profit, but at a big discount to intrinsic value (somewhere over £10).
The Kingerlee concert party doesn't appear to care about smaller shareholders and haven't highlighted any of the risks of holding TISE shares!
There is some upside as an argument could be brewing: I can't necessarily see them getting 75% as DG & MB Conn and associates who hold 23.6% don't appear to agree and have been against the board before!
A poor start to 2024 here.
*The International Stock Exchange (TISE) is a stock exchange headquartered in St. Peter Port, Guernsey. The TISE provides a listing facility for international companies to raise capital from investors worldwide. It offers a regulated marketplace, with globally recognisable clients and a growing product range, from a location within the European time zone but outside the EU.
I had heard of TISE but didnt have any detailed knowledge. I was therefore a little surprised to see this on the TISE website
"We are the second largest market for all listed UK REITs (Real Estate Investment Trusts).
This is because we fulfil the requirements of being a Recognised Stock
Exchange in order to meet UK REIT requirements, whilst also providing a
pragmatic and cost-effective admissions process."
Quite possible that Highcroft Investments (LON:HCFT) HCFT wont be the last to go down this route.
Remarkable bounce in Future (LON:FUTR) since the lows of around 600p. Liontrust > 5%, 12mth rolling p/e 6 and peg of 0.5
Thanks for looking at £JD. Certainly tempting at these levels, although I dont think correct to say adjusted EPS are expected to be still above last year - looking at the last year's report I see adjusted EPS was 13.4p (Stockopedia has a lower figure which is what you may have looked at?). Anyway it does appear that EPS likely to be down by around 10%.
JD Sports Fashion (LON:JD.) I know Singers downgraded PBT by 11%
Hi all - I've been a member of Stockopedia for nearly 2 years now which has turned around my investment results from dire to pretty good :) I previously had no coherent method for stock selection and a penchant for story stocks that didn't end well. Now my eyes are open and my largest holdings are FTSE 100 stocks with good divis. I also hold a fair chunk in FTSE 250 and some small caps (min £80M mcap). I don't pick any stock which isn't making a profit after previous experience.
I'm now 'doing my own research' running through the stock ideas suggested by Paul, Graham, Roland and Ed and have a Stock Report question - where do I find NTAV in the Stock Report? I thought it was the same as the Book Value, but is that wrong?
Thanks and all the best for 2024 everyone
hi Gung Ho
Book value is the total net asset value (NAV) which includes intangibles.
NTAV is Book Value (NTA) less intangibles.
Not sure if/where NTAV appears on the Stock Report as I use Sharepad for that as I find the presentation of financials much easier to navigate on Sharepad. Perhaps someone else can point you in the right direction.
Until then you can calculate NTAV manually by simply deducting intangibles from Book Value.
Hope that helps.
Snazzy
Thank you!
Likewise here Gung ho,
If I had joined Stockopedia 3 years ago instead of 1 year ago I'm pretty sure I wouldn't have lost 70% of my pf in 2 years ..
Oh well, we live and learn and I'm now a big fan of Warren's number 1 rule.
'Don't Lose Money'
Keep up the great work Stocko team!!
Gung Ho.
In the Valuation section on the RHS of the StockReport you will see "Price to Tang[ible] Book". That may be all you need. The ratio of the "price to book value" and "price to tangible book value" lets you calculate NTAV from Book value if you need it.
Thanks FREng - Got it!
JD Sports Fashion (LON:JD.)
Paul, you asked about the put/call liabilities on JD's balance sheet. I understand the accounting for these, but it is a little complicated.
Typically, they are granted to minority shareholders in acquired businesses and allow the incumbent owners the right to sell their minority stakes in the future. The put price is usually a multiple of the earnings of the acquired business or some other entity(s) within the JD group. Intuitively. if the relevant businesses perform better, then the put price will also increase.
It's natural to think of these derivatives as being accounted for at fair value, but they are not. The rules for MI puts demand that the maximum that can be paid should be recognised as a liability,
Hope this helps!
Frothy but improving liquidity but profit warnings coming .
Strange market at the moment with clearly improving liquidity and a bit of FOMO for cash on the sidelines . Feels a touch frothy .
A few companies are bouncing quite strongly purely on change of sentiment and inward flow of funds so some short term gains being made
However also a fair few companies can’t then back this up and are warning causing equally sharp reverses (even though probably temporary) eg JD sports .
I’m pretty much fully invested and just keep adding to current positions on drops but the recent speculative in and out trades are doing very well eg future up 30% in a month (thanks Paul )
Wynnstay and Hargreaves are the standout oversolds for me just looking for a last leg down before committing .
Re Angle (LON:AGL) I have a very small holding in basket of high risk positions that I think are overly beaten up AND have fundamental positive potential. Caution is warranted. To counter Paul's negativism a little tho...for a pre-profit biotech its dilution has been quite well managed over time (its not good or pretty tbc but they haven't been mega spaffers with a purely speculative project!). Its a true 'picks and shovels' player in a (potentially) emerging field. Its recent fall from grace is partly about sector dynamics generally (everything killed after 2021 ramp) and that they had stepped up their investment in commercial capability in last few years as well.
So, caution, as any one holding like this could be a total bust...so I have small position and basket of risks...though I'm not taking any old risk and try to find things with favourable and achievable outcomes and decent funding picture.
Very high risk. Can easily come back down as they report a bit more cash burn...or mgt can decide that a spike is good chance to bank some cash from issuance (rational tbc and why stocks like this are listed)...and that will deflate sentiment again (unless the appetite for biotech has shifted). To be invested in this area you've got to accept that tapping the market is part of the game...and that's ugly when sentiment is ugly.
This interview given this morning by Andrew Newland gives a view on the significance of both this weeks news items.
?si=X-qAOofOgC7Ff610 videoNot at my screens right now but I seem to remember that Angle (LON:AGL) rose materially on abnormal volume. Mega sniffy!
Wasn't me ;)
When tho?
Yesterday, I meant to say.
TBH Angle (LON:AGL) does seem one of those shares that the trading crowd enjoy playing with a bit
C4X Discovery Holdings (LON:C4XD) is up again substantially today too.A very decent biotech platform discovery platform, headed up by the ex government vaccine guy Clive Dix, that licences out molecules they discover to big Pharma.It has been particularly beaten down as well lately too.Perhaps some animal spirits are already back in some parts of the U.K. markets?
I hold Illumina (NSQ:ILMN, and I admit at a much better price than activist investor Carl ICahn (!!) (still working on the billionaire thing).The share price has been a bit of a mess and not just due to bathe biotech sector’s general de rating, losing a CEO and Carl chucking people off the board.The company has finally decided to divest Grail, its homegrown cancer diagnostic business, which it spun out a few years ago and reacquired later without full antitrust approval.The company does have a huge dominance in the genes sequencing machine business though which is why i bought and apparently the CAGR of the industry is supposed to be 17.12% between 2021 and 2030.according to 'Strategic Market Research'(!).
C4X Discovery Holdings (LON:C4XD) - considered but never got round to investing...no particularly negative reason but just didn't get over hurdle with it in terms of enough due diligence. Obvs like all these sort of stocks risky and to be owned with caution!
JD Sports Fashion (LON:JD.) - In the Daily Telegraph today features in their article "10 stocks top investors are backing in 2024". Note to self - NEVER follow newspaper tips - EVER!!!!
I would expand that to never follow tips, actually, just don't read them. (I did that for about 5y and my performance was erm volatile) However... if you can exclude shares that are likely to underperform and include shares that are likely to outperform and then choose from that pool, you have a better chance of doing OK (I have for the last 3y)
on JD Sports Fashion (LON:JD.) I dont see people moving on from sportswear to more formal clothes and don't see people moving from jd to other shop chains. So see this as a blip rather than an inflexion point. (Not a holder but if it fell another 15% just on sentiment maybe)
JD Sports Fashion (LON:JD.) is my largest holding, one of the few large caps I hold. Yes its down 25% today, but go and have a look at the 10 year graph and the all time graph. I have been buying and selling this share for 20 years, it was a small UK brand, now its a global brand. Off to Asia next week, then Australia, its always reassuring to see a company from little old Bury expand across the World and seeing those Yellow drawstring bags swinging from young fashionable people in far flung places. Its far from a perfect company, but its a growth company with a market cap of £8bn, generating PBT of £925m.
Newspaper tips
I do follow all tips at this time of the year for ideas to sell my shares if they are tipped to buy!
I like that! I ignore all tips...but this is the sort of monitoring I could get behind...particularly when a micro cap is tipped
Is there anywhere (site) that amalgamates the tips does anyone know?
Whilst I never buy on a tip I do like to monitor them where I can as it helps make sense of froth in certain shares and who might be plugging them during the year.
There is one called Stockomendation. But there are literally thousands of tips so I am not sure how one is suppose to use the service. Imo it seems a bit pointless unless you have a way of using the data.
Well that didn't age well, did it? And only four days in.
That's like Nick Train singing the praises of Diageo and Burberry weeks before they tanked even further.
Burberry (LON:BRBY) made the top 10 too!!!
Go on, you have tempted me in... I decided not to mention Robert Armstrong and his excellent FT Unhedged column..... but WOW... he came up with long nestle -11% long Dominos +20% Short Pulte -105% short coinbase -215% short Netflix -22% average -67%.... so for a quite sensible chap he produces all time terrible perf. and well I agree with all the comments, just ignore these stupid static stock lists that journos come up with, they dont mean anything.
Ah, JD Sports Fashion (LON:JD.), one of my "one that got away". On a PE of 10 and an EV/EBITDA of 6.6 makes it cheap. US value investor Bruce Berkowitz had the saying that he looked for companies with a Price to Free Cashflow less that 10 and he couldn't kill the company. It satisfies that criteria.
I have my own little screen which I call "Croft baggers", named after Ed of course. It is:
JD meets those criteria. I haven't looked at their latest statement nor do I have a holding in the company.
The fall in JD Sports Fashion (LON:JD.) seems to be related to its failure to meet estimates. The company does seem to be heading in the correct direction as its profits seem to be increasing.
I do hold JD Sports Fashion (LON:JD.), I did reduce my holding last month as was looking a bit frothy. Forecasts are down about 10%, shares are down 23%, maybe a buying opportunity? I find it does have quite big pullbacks, buy on a pullback and sell after a run up. Check the chart over the last 7 years.
I can't believe this drop, had high hopes for this share over the longer term, as market leader it seems way overdone. I sold out at 130p this morning thinking maybe I'd been ripped off. Putting all that money back into JD Sports Fashion (LON:JD.) again at 115p if it hits that low. I think the big boys will come to the party and start loading up over the next few days and it will recoup a chunk of the losses. Not to mention the April pay rises lining the pockets of a lot of it's core customer base (minimum wage workers... not pensioners) .
Have watched JD Sports Fashion (LON:JD.) for a little while and have decided at this value to buy a position. For me its a minor blip while the consumer is squeezed, and my personal view is that in the coming months that squeeze will ease and that consumer spending will recover. Happy to buy quality businesses on cheap ratings that hit a minor speed bump.
I just wanted to add that this reaction reminds me a little of 4imprint (LON:FOUR) , which fell out of bed in March 2000. It was otherwise a good company that was hit by the macro. I got scared out of my position, which turned out to be a bad bad idea. It subsequently recovered from ~1300p to 4445p.
Pleasantly surprised by the share price reaction to the RNS from Angle (LON:AGL) this morning (up 66% as I type). This very patient holder is hoping this company could turn a corner this year and generate a descent revenue stream and not require any further funding. As always DYOR!
hi shopping365
Angle (LON:AGL)
hoping this company could turn a corner this year and generate a descent revenue stream and not require any further funding
I think you meant to say 'decent' rather than 'descent' but perhaps your comment may be more prescient?
Snazzy
Ha ha yes I did, but you could well be right!
Just a heads up to any SCVR readers who had any interest in Angle (LON:AGL) many months ago but gave up.
Two RNS this week already, as highlighted by Mr C,the second this morning being the most interesting. Not only a breakthrough but working with Illumina and name dropping other big pharmas that could benefit. I believe AN is giving a Proactive presentation next week.
Note the company has a cash runway that will now take them into Q1 2025.
I STILL hold. DYOR.
Bigblu Broadband (LON:BBB)
I note Christopher Mills keeps buying at these depressed levels and now he and concert parties own 25%
I also note that ST in the IC reckons they are worth closer to 100p when the listing in Australia goes through.
Make of that what you will but feels like some smart cookies seeing value in the business.
Inspiration Healthcare (LON:IHC) I don't hold but it's on my watch list, describes itself thus:
"Inspiration Healthcare (AIM: IHC) designs, manufactures and markets pioneering medical technology. Based in the UK, the Company specialises in neonatal intensive care medical devices, which are addressing a critical need to help to save the lives and improve the outcomes of patients, starting with the very first breaths of life.
The Company has a broad portfolio of its own products and complementary distributed products, for use in neonatal intensive care designed to support even the most premature babies throughout their hospital stay. Its own branded products range from highly sophisticated capital equipment such as ventilators for life support through to single-use disposables.
The Company sells its products directly to hospitals and healthcare providers in the UK and Ireland, where it also distributes a range of advanced medical technologies for infusion therapy. In the rest of the world the Company has an established network of distribution partners around the world giving access to more than 75 countries."
This morning they announced an interesting acquisition of Airon, a company based in USA which is described as:
"Established in 1997, Airon Corporation proudly manufactures products in Melbourne, Florida and markets their innovative, reliable, effective, high technology pneumatic oxygen-powered life support ventilation and CPAP products and accessories throughout the world. Their products support neonates, infants, paediatrics, children and adult patients in EMS, hospital ER and trauma, MRI, OR, ICU and transport."
The rationale here is that Airon has a portfolio of complementary products which target the same customers as IHC plus it gives IHC an established sales operation in the USA where IHC are seeking FDA approval for a new neonatal ventilator.
Clearly this is early days, with the full benefits likely to take a couple of years to feed through. However, it does look to me to be a sensible acquisition that opens up a big new market for iHC and expands the sales reach of Airon's products. Currently MCAP is just £27m but heavy director buying in October suggests insiders are optimistic about the future.
Hat tip to Paul Hill for bringing this stock to my attention.
I see that Sigmaroc (LON:SRC) has quietly slipped a positive trading update into its share admission note this morning:
SigmaRoc has continued to trade well since the October Q3 update. The Company
will provide fuller commentary later in January with results expected to be at
least in line with market expectations*.
*Consensus expectations for SigmaRoc, being the average of forecasts for the
year ending 31 December 2023 provided by analysts covering the Company, are
revenue of £596.9m and underlying EBITDA of £110.2m.
Stocko currently has revenue for 2023 at £589m
Martin VT . And CRH just announced a 15.4% stake.
CRH taking that stake is part of the agreement for SRC buying CRH's lime assets. Its a positive that CRH are happy to be a shareholder in the wider SRC business but I wouldn't be viewing this as having the potential for CRH taking over SRC.
Some positive signs beginning to appear ?
HSBC now offering a 5 year fixed mortgage under 4%. This should feed through to lower savings rates thus making equities seem more competitive/attractive again.
Next (LON:NXT) this morning's TU telling us that they think the consumer environment 'looks more benign than it has for years' . UK wages set to rise faster than inflation and NEXT are 'seeing decreasing factory gate prices' enabling them to have 'zero price inflation' this year.
If the current government come up with an attempted vote winning scheme to encourage house building starts and or first time buyers , house builders and construction materials could be the place to be for 2024.
Fingers crossed!
I agree and hold Brickability (LON:BRCK) Michelmersh Brick Holdings (LON:MBH) Grafton (LON:GFTU) Eurocell (LON:ECEL) and Stelrad (LON:SRAD) - all of whom have done well with respect to share price recently, with plenty more to come I hope.
I also hold Hill & Smith (LON:HILS) Morgan Sindall (LON:MGNS) and Severfield (LON:SFR) in the hope that some larger projects may get the go ahead.
JD Sports Fashion (LON:JD.) sell darts I think, got a few shares you can buy at a great price this morning if you want...
JD. already off on the back of Nike last week. Bloomberg calling it a 'surprise profit warning'.
JD had been very strong recently so not entirely surprised by the market reaction.
JD had been very strong recently so not entirely surprised by the market reaction.
The whole training shoe sector has been very weak recently apart from a few challenger brands like ON, so the PW wasn’t a surprise to me. But I find today’s levels a very attractive entry point, and I have loaded up to a slightly more than full position. These guys know how to flog trainers and the weakness won’t persist for ever.
JD Sports Fashion (LON:JD.)
I would have slight worries that there may be headwinds in this sector. Are companies like nike actively wanting to sell more direct to consumer - i think they have indicated that they do?. Particularly in the us should we not be expecting a pivot away from in store sales to online sales?
Its clear JD are well run but i would be slightly worried that the medium term future may be tough in their segment. I wouldnt disagree with the viewpoint that good companies can still do well when times are tough so my thoughts here may be missing the bigger picture if they are able to thrive in a similar manner to Next perhaps in that the "do retail well"?
I would have slight worries that there may be headwinds in this sector. Are companies like nike actively wanting to sell more direct to consumer
I own both Nike and JD Sports as a form of belt and braces and believe that both will do well when consumer softness relents. Nike is increasing D2C sales, yes. The counter argument is that JD can sell challenger brands that are currently eating into Nike and Adidas sales. My strategy is to own the biggest brand and best retailer and hope that a more comfortable alternative to training shoes is never invented!!
Skechers USA (NYQ:SKX) only $9b market cap so a fraction of the size of Nike but expanding and extremely comfortable :-))
Skechers USA (NYQ:SKX) only $9b market cap so a fraction of the size of Nike but expanding and extremely comfortable :-))
True. But they are still trainers (albeit for OAPS like me) and if they want to expand fast they need distribution agreements with independent retailers
Skechers USA (NYQ:SKX) do supply retailers, Frasers (LON:FRAS) for example but not JD Sports Fashion (LON:JD.) which is odd. My daughter told me to buy the stock just over a year ago when it was $30 as she had just taken over their UK advertising account and they had a very aggressive plan for their new ranges. Stupidly I did not take her advice as the SP has doubled since. I think the punters perception is that they are for older wearers, maybe why JD do not stock them, but the Golf shoes are apparently first class and the new slip on range where you dont have to bend over to put them on are proving popular. I am awaiting a pullback before I buy.
Yes I got the impression Skechers USA (NYQ:SKX) were for old foggies and JD Sports Fashion (LON:JD.) is for trendy youngsters.
Love the slip-ons!
Had a quick look at Skechers USA (NYQ:SKX) look quite good but Nike (NYQ:NKE) are suing them and some hefty director sales recently, are 2 negatives I picked up. Never tried any on but have seen them in Sports Direct. I buy New Balance as can get an exact fit.
My morning smallcap tweet: Topps to bottom
Topps Tiles (LON:TPT) Trufin (LON:TRU) REGTECH OPEN PROJECT (LON:RTOP) Shearwater (LON:SWG) Tekmar (LON:TGP) Iconic Labs (LON:ICON) Destiny Pharma (LON:DEST) Likewise (LON:LIKE) Angle (LON:AGL) Microsaic Systems (LON:MSYS) Net Zero Infrastructure (LON:NZI) Aptitude Software (LON:APTD)
◄Topps Tiles (TPT)► weakness continues with Q1 LFL down 7%. Sales to trade customers more resilient than to homeowners. [SP=50.8 Cap=100m]
◄TruFin (TRU)► guides FY-Dec rev up 32%+, below exp due to significant platform deals at Playstack taking longer to negotiate and conclude. Adj pretax loss in line at £6.3m (£8.2m). [SP=48.75 Cap=52m]
◄RegTech Open Project (RTOP)► RegTech Italy (owned by Alessandro Zamboni of Zoetic/Chill infamy) still hasn't paid c.£3m of working capital loan agreement. Exploring alternative financing options should there be continued delays. [SP=14.5 Cap=9m]
◄Shearwater (SWG)► wins $3.15m 3 yr contract (includes previously deferred contractual spend from the client). Also £0.84m win from Gov't. [SP=46.8 Cap=11m]
◄Tekmar (TGP)► wins £3.5m initial contract for a cable protection system. Delivery in 2025. [SP=10.5 Cap=14m]
◄Iconic Labs (ICON)► following its exit from administration co is seeking an acquisition, will probably be an RTO. [SP=3.4 Cap=m]
◄Destiny Pharma (DEST)► biz update. Not much new I think. "Pre-clinical results are expected imminently for XF-73 Dermal and, in addition, the Company expects to make further progress across its XF drug platform and assets with target indications established for both XF-73 Dermal and XF-70, a novel anti-fungal from the XF drug platform, later in 2024." Co funded through to Q1 2025. [SP=68.87 Cap=66m]
◄Likewise (LIKE)► guides FY-Dec rev Gross sales revenue up 14%, 'Sales revenue' (must be different) ahead of market expectations andU/L profitability in line [SP=20 Cap=49m]
◄Angle (AGL)► claims 'breakthrough' clinical results: "Combined DNA Next Generation Sequencing of CTCs and ctDNA from the same blood sample highlights potential for the Parsortix system to identify key variants (DNA mutations) missed by other approaches to help guide treatment decisions". CO says it's the critical next step after the FDA clearance. [SP=13.17 Cap=34m]. i hold.
◄Microsaic Systems (MSYS)► update on the Revised Fundraising and Acquisition. Still negotiating binding conditional commitments to the placing through Turner Pope Investments. Due diligence on acquisition target continues. [SP=0.01 Cap=258m]
◄Net Zero Infrastructure (NZI)► abandons mooted acquisition of LINE Hydrogen (Australia) because co couldn't get it funded. Co considering another potential acquisition in a different sector of the market. Shares remain suspended. [SP=NA Cap=NA]
◄Aptitude Software (APTD)► wins £1.3m contract commencing in March. [SP=280.93 Cap=161m]
Artisanal Spirits (LON:ART) - The Artisanal Spirits Company (ASC) has announced an important acquisition in the US. Effective 3rd January 2024, the company has acquired 100% of the trade and assets of Single Cask Nation (SCN), which is an independent bottler and distributor of both Scotch and American whiskies. An accompanying trading update for ASC confirms recent guidance and we leave our forecasts unchanged. Our assessment of fair value remains 100p per share.
ASC states that the SCN acquisition, which includes all of its assets and global operations, will be funded out of existing borrowing facilities. Furthermore, it is expected to be EPS accretive in the first year of ownership. Consideration includes an up-front payment and the potential for up to US$0.5m (£0.4m) to be payable as an earn out, dependent on FY2024 and FY2025 financial performance. Importantly, the deal is consistent with ASC’s sustained ambitions for overall business quality, premiumisation, profitability and cash generation.
Link to note: https://www.equitydevelopment....
Some interesting stuff in the Next (LON:NXT) trading statement, although I won't steal Paul's thunder.
They are going to stop amortising the value of acquired brands through the P&L, and take the opportunity to have a sarcastic pop at EBITDA, which I thought might please a few people here.
Good morning - Do you know any companies that manufacture or promote darts ?
Most of the pros use Target I think.
(LON:LUKE)
haha very good Ox. The matches from the quarters onwards were fantastic.