Small Cap Value Report (Thu 4 July 2024) - ITIM, GLV, DFCH, PEEL, LIO Brief: SN., INHC

Good morning from Paul & Graham!
Today's report is now finished (EDIT: sorry forgot to add Liontrust Asset Management (LON:LIO) - that's now up too)
General Election in the UK today, and Independence Day in the USA. Will the excitement never end?! I'll have to dream up something witty to say to my recently-discovered American cousins, to congratulate their ancestors for jettisoning the colonial yoke. Maybe I should apologise again for us burning down the original White House in 1814, and pass it off as an accident, or error of judgement?
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
A quiet day again today.
Other mid-morning movers (with news)
Smith & Nephew (LON:SN.) - up 7% to 1,057p (£9.2bn) - an unusual move up from this large cap maker of medical equipment products. The newswire says it’s due to an activist called Cevian disclosing a 5% stake.
This actually looks quite interesting. SN. has been in a downtrend since 2019, halving from c.2000p to c.1000p. Yet some key numbers on the StockReport show some value characteristics here, and quite good quality measures - eg fwd PER 12.3x, 3.2% yield, P/TBV 9.8x.
Paul’s view - none, as I haven’t properly researched it, but some of the figures look quite attractive, and I can see why an activist might want to shake up performance. Possibly worth you taking a closer look, hence why I’m flagging it.
Summaries
ITIM (LON:ITIM) - 33p (pre-market) £10m - Contract Win - Paul - AMBER
A quick look below at a sizeable contract win for this tiny SaaS business. Looks interesting, but is already in the forecasts. I do a quick review below. One for my watchlist only at this stage.
Glenveagh Properties (LON:GLV) - up 3% to €1.32 (€753m) - H1 Trading Statement - Graham - AMBER/GREEN
We remain on track for full-year EPS of 17 cent at this home builder, giving a PER of just below 8x. The company does carry some debt but increased borrowings should unwind as sales are completed in H2. My impression of GLV remains as positive as ever; it does now trade at a premium to book.
Distribution Finance Capital Holdings (LON:DFCH) - up 26% to 34p (£61m) - H1 Trading Update [ahead exps] - Paul - AMBER
A nice spike up in share price today, but will it hold? The ahead of expectations mainly relates to writing back part of a bad debt provision, so I don't see this as being an improvement in underlying trading particularly. Discount to NTAV is probably justified, due to the inherent risks in alternative lending. But quite an interesting business, and I've enjoyed reviewing it!
Peel Hunt (LON:PEEL) - up 3% to 133p (£163m) - Trading Update (AGM) - Paul - GREEN
A slightly reassuring update, with Q1 seeing "tentative signs" of a market pickup. My view is the same as before - balance sheet supports 55% of the market cap, and there should be a cyclical recovery in earnings at some stage.
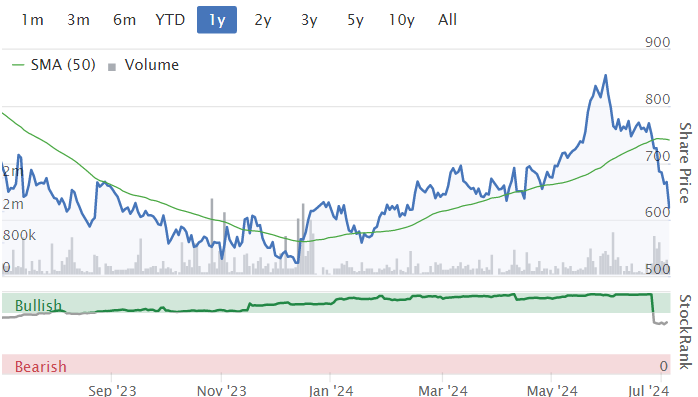
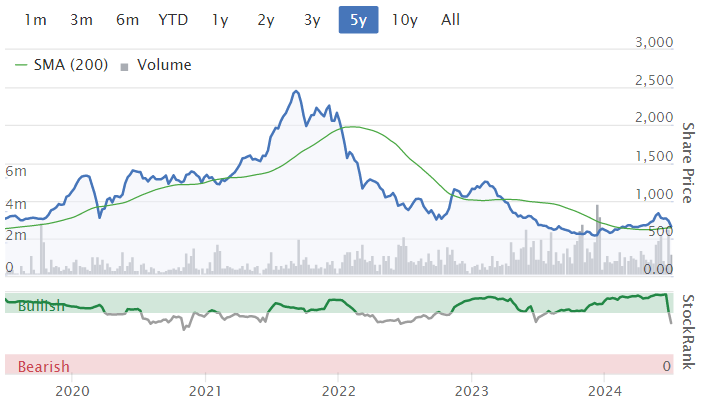
Liontrust Asset Management (LON:LIO) - 623p (£404m) - Final Results - Graham - AMBER/GREEN
Switching my stance on this one from GREEN to AMBER/GREEN as I’ve grown weary of trying to understand this fund manager’s strategy, and the latest results statement contained yet more points which seem controversial to me, including nearly £6m spent on “target operating model restructure”. No thanks!
Paul's Section:
ITIM (LON:ITIM)
33p (pre-market) £10m - Contract Win - Paul - AMBER
itim Group plc, a SaaS based technology company that enables store-based retailers to optimise their businesses to improve financial performance…
I’ve been keeping an eye on this minnow, which looks potentially interesting, if it can scale up.
Shares are illiquid, as it’s tiny, and the top 2 holders control it with 56% combined - owner/manager, and possibly the owners of River Island, the Lewis Family? Or the Lewis’s could be a “gospel and bluegrass” musical group according to Google. Clear de-listing risk there if the share price remains in the doldrums, I imagine.
Today’s contract win is another good one (earlier this year it won/renewed notable contracts with Quiz, and Majestic Wine) -
“...pleased to announce that it has signed a five-year multi-million-pound contract with Assaí Atacadista ("Assaí"), the largest Brazilian wholesaler, with more than 300 stores. Founded in 1974, Assaí distinguishes itself by offering a diverse range of products at competitive prices, serving both businesses and end consumers.”
“Under this agreement, Assaí will leverage itim's UNIFY Price & Promotions Optimisation solution powered by Profimetrics AI to refine its pricing strategies and boost competitiveness, reinforcing its commitment to quality and affordability.”
Assai shares are NYSE listed, and seem to be doing badly, making new lows recently.
ITIM seems to have an impressive presence in Brazil - how come, I wonder?
“It now is being used by 20 retailers globally and by 6 of the top 10 Brazilian retailers, underlying its capability of adding retail value.”
No change to forecasts, per WH Ireland, and confirmed in today’s news release -
“The execution of this contract is in line with the Company's financial expectations for the current financial year.” [FY 12/2024]
Paul’s opinion - it seems impressive that a tiny UK software company has signed up a large retail/wholesale business in Brazil. That suggests to me ITIM’s software must be good. Why Brazil though?
See SCVR 1/3/2024 for a review. I concluded that the balance sheet needs strengthening, so I’d expect a small placing at some stage. Ignore EBITDA as it’s nonsense, due to high (c.£2m pa) capitalisation of development spending. So the company is actually loss-making still on a real world basis of PBT.
A big recent contract win with QUIZ might be a mixed blessing, as I think QUIZ is looking very wobbly. Although with wealthy (thanks to its overpriced IPO) family backers, I imagine QUIZ is more likely to de-list than go bust, so hopefully should be able to honour its contractual terms with ITIM.
I’ll keep ITIM on my watchlist for now. Note that spikes up on contract news tend to dissipate quite quickly, so I won’t be chasing it up on any rise today. The time to buy (if at all!) would be after a long drift down. It’s another over-priced 2021 float, that has been a disaster so far, but some of these could be interesting opportunities, you never know!
Distribution Finance Capital Holdings (LON:DFCH)
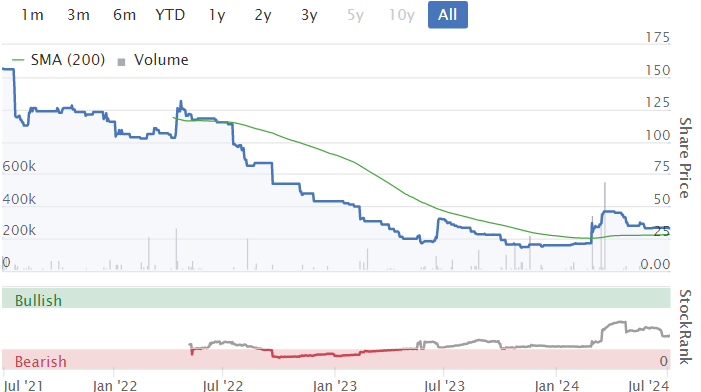
Up 26% to 34p (£61m) - H1 Trading Update [ahead exps] - Paul - AMBER
This specialist lender is normally covered by Graham and Roland, but Graham’s busy on other things today, so I’ll (Paul) give it the once over.
Previously -
29/11/2023 - down 30% to 18p on a profit warning, caused by a loss revealed on a large overdue loan. Roland went amber/red, saying it was a special situation only. This was actually the low in the share price as it turned out.
18/3/2024 - up 9% to 28p, on an ahead of expectations TU for FY 12/ 2023, moved up to amber by Graham.
Today - I can see from the StockReport that there was (as of close yesterday) a large 50% discount to NTAV, and a low forward PER of 5.8x, no divis though. So some nice value characteristics there.
Distribution Finance Capital Holdings plc, a specialist bank providing working capital solutions to dealers and manufacturers across the UK, is pleased to provide a trading update for the six months ended 30 June 2024.
An excellent headline -
“Continued momentum with full year results now expected to be significantly ahead of market expectations”
This is quite a big business for £61m market cap, eg -
New loan origination in H1 up 17% vs LY H1, at >£709m
Loan book at 30/6/2024 £600m, i[ 16% on LY, and suggesting it has rapid turnover of loans (given new loans originated is higher at £709m)
They provide vehicle stocking loans to dealers, on a short term basis (average loan 149 days).
Bad debts don’t sound a problem at all currently, which is obviously the main risk (and fraud) for this type of lender -
“In spite of the challenges of the macro-economic and higher interest rate environment, the Group's overdue accounts have continued to perform well and ahead of expectations through the period… The Group's total arrears balance represented c0.5% (H1 2023: 2.5%) of its entire loan book.”
Although bad debts can come out of the blue with this type of lending. Also I worry that bad debts could also be large, if a dealer group with multiple sites went bust. So it would be good to know the maximum exposure to say, each of the top 10 biggest borrowers.
Overall trading sounds good -
“In light of the strong performance during the six month period, the Group's underlying trading performance is expected to be ahead of market expectations for the full year, driven by stronger net interest income, lower impairments and loss provisions and stronger cost control.”
RoyalLife - this must be the large £10m impairment mentioned late last year. It says today £4.7m is in the process of being recovered, subject to asset sales mainly in 2025 - hence a write-back to profit.
Revised guidance -
“Given the Company's strong underlying operational and financial momentum and the financial recovery in relation to RoyaleLife, the Group expects to report a pre-tax profit for the six month ended 30 June 2024 of no less than £9.0m, which is significantly ahead of its expectations and more than the entire FY23 outturn of £4.6m. Accordingly, the Group expects its full year outturn for 2024 to significantly exceed market expectations.”
Entry into hire purchase funding is expected in 2025, a significantly larger addressable market, it says. Subject to regulatory approval.
FY 12/2023 Results - I’ve had a quick skim of the numbers. It makes a good lending margin, with £60m income (“interest & similar”) and only £22m in interest costs. However the resulting £38m of net interest income is largely consumed by £22m costs (mostly staff), and £12m impairments, leaving only £4.6m PBT. Since they over-provided for the RoyalLife bad debt, then we could perhaps adjust 2023 PBT up to c.£9m. Hence today’s news of profit rising from £4.6m in 2023, to £9.0m in 2024, isn’t reality in my view, it’s just been driven by being over-cautious in bad debt provisions in 2023. It’s good that the policy is cautious, but this is not really profit growth in my view, when a company is essentially making a prior year adjustment.
Balance sheet at 31/12/2024 - looks fairly strong actually, with c.£100m NTAV, well above the £61m market cap (allowing for today’s +26% share price move). It had most of its NTAV in cash, at £90m. Customer loans are by far the biggest asset, at £568m. Liabilities are overwhelmingly “Customer deposits” of £575m (see note 35).
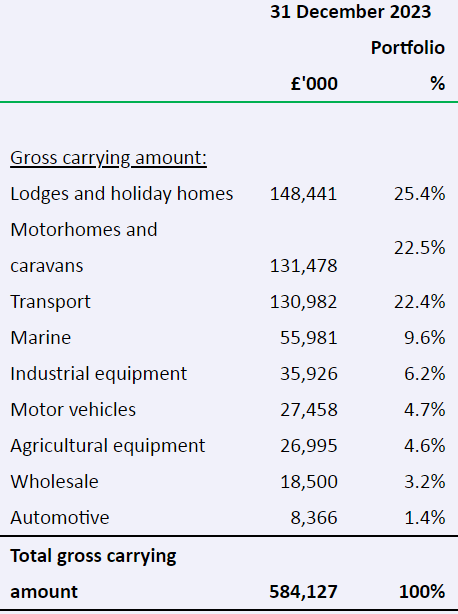
Note 39 shows who it lends to, with the largest segment (lodges & holiday homes) incurring the £5-10m impairment -
I can’t find the maturity profile of the customer deposits (ie. cash taken from retail deposits, but it’s probably buried in the notes somewhere.
Paul’s opinion - I’ve spent long enough on this, so let’s wrap it up.
I never invest in alternative lenders, as sooner or later something always seems to go wrong.
There’s a lot of potential risk, particularly from fraud. I’ve mentioned this before, but c.1991 I worked as a junior for the insolvency dept of Price Waterhouse. One job was a receivership of a Rolls Royce & Saab dealership, which I found fascinating, as I was sent out on site, to help sort out the various problems. What we discovered is that some of the vehicles on finance to a lender like DFCH didn’t actually exist. I probed the staff, and they openly told me that to keep the business going, paperwork had been falsified, and funds borrowed, for quite some time. Eventually the dealer collapsed due to ongoing trading losses during that recession.
So my point is that within DFCH’s book there could be potential bad debts that only become apparent once a customer collapses. When the lender tries to recover the assets, sometimes they don’t exist, or have already been stolen or sold. Hence why lending that you would think would be 100% safe, may not be.
What about the risk of a run on depositors? I didn’t get round to looking at that, but since the business model is short-term lending of only about 5 months on average, then a run on deposits could even be manageable? So the terms of deposits would be very important to look into - eg if it attracts deposits from retail depositors and locks the money in for say 6 months or more, then a run on deposits wouldn’t actually be a problem in theory - they could just stop lending, and the cash would quickly roll in from borrowers repaying loans, to meet withdrawals by depositors.
It seems that DFCH makes about £10m PBT on a net asset base of about £100m. Hence valuing it at a discount to NTAV seems fair to me. Maybe the discount is a bit too big at the moment, so upside on this share might be that it gets closer to NAV, last stated at 55.6p. That’s 64% above the current share price. So it could go up if investor confidence improves, and buyers are not snuffed out by selling from stale bulls. Who knows?!
Superficially cheap on a balance sheet basis, but not a particularly good business, and lots of risk from the many moving parts, so I think it should be at a discount to NTAV.
AMBER feels right to me. Today’s 26% jump in share price looks possibly overdone, as the profit growth seems more from changes to provisions, not from improved underlying trading - although that seems obscured in the commentary.
Peel Hunt (LON:PEEL)
Up 3% to 133p (£163m) - Trading Update (AGM) - Paul - GREEN
Peel Hunt is a leading UK investment bank that specialises in supporting mid-cap and growth companies. It provides integrated investment banking advice and services to UK corporates, including equity capital markets, private capital markets, M&A, debt advisory, investor relations and corporate broking.
PEEL is probably best known to most of us as a broker that writes excellent research that we can’t get access to, due to the prohibitive price after the misguided MiFiD rules were introduced.
The year end is FY 3/2025, so it gives a brief Q1 update today. Here’s the whole thing -
“As reported in our FY24 Results Announcement on 13 June 2024, we have seen some improvement in the macroeconomic backdrop since the start of FY25, with tentative signs of a pick up in equity capital markets ("ECM") activity.
During the period, we have advised clients in relation to a number of ECM transactions, including acting as global co-ordinator on two IPOs executed on the London market, and we are encouraged by an increase in activity in both our Execution Services and institutional trading businesses.
Consequently, revenues for Q1 FY25 are ahead of the equivalent prior year period and in line with market expectations.”
That sounds reasonable in the circumstances, so mildly reassuring I would say.
Looking back at previous numbers, it made a small £(0.8)m loss in H1 LY.
H2 must have been worse, with a £(3.3)m FY 3/2024 loss.
These are not alarming numbers to me. It’s a highly cyclical business, so I can tolerate smallish losses in the depths of a bear market.
Balance sheet is strong, with NTAV of £90m at 31/3/2024, supporting 55% of the market cap today. So the small losses are not even putting a small dent in the balance sheet.
Paul’s view - previously I was GREEN on 3/4/2024 at 120p.
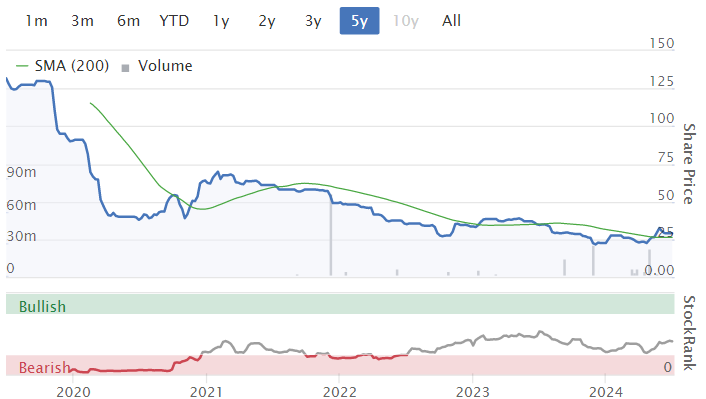
Further back, Graham was also GREEN on 5/12/2023 at 93.5p. Graham included PEEL in his top 10 ideas list for 2024, and it's up 17% YTD.
Our commentary each time here is the same - strong balance sheet, and cyclical upside in due course.
That remains my view today. You can’t value PEEL on a PER basis, as it’s modestly loss-making, but in this sector profits can explode upwards (on a reduced cost base) when proper bull markets get established.
It says in line with market expectations, without saying what they are, and we have nothing in our broker consensus figures either. Bit of a schoolboy error there! I think PEEL needs to come down occasionally from its ivory tower, and recognise that private investors do actually matter, as we create market liquidity and set the share price. Some brokers get that, and engage well with us. Suggestion - maybe PEEL could think about getting possibly just the front page of its research out to a wider audience, maybe with a week or two delay, so that the paying customers can justify the hefty cost of a subscription? If research only goes out to institutions, then there's no market liquidity - it's PIs who need to be engaged to get liquidity (and share hence prices) on the move, particularly when many institutions are still sellers (look at the two discounted secondary placings we saw last week, caused by a lack of market liquidity).
Brokers also need buyers in the market for their shares, to mop up all the employees selling their share options continuously, as is often the case in this sector. Those Ferraris don't pay for themselves!
I’ll stick with GREEN, but we don’t know what the size of the cyclical upside is likely to be, nor when it will happen, although I suspect we’re in the early stages of a bull market, despite recent softness.
Graham’s Section:
Glenveagh Properties (LON:GLV)
Up 3% to €1.32 (€753m) - H1 Trading Statement - Graham - AMBER/GREEN
It’s an H1 trading update (to the end of June) from this main market listed Irish home builder.
Before getting into the details, I should outline that the company has three divisions: Suburban (houses and low-rise apartments), Urban (apartments) and Partnerships (houses and apartments for government bodies). Suburban is by far the largest, accounting for more than three quarters of 2023 revenues, followed by Urban.
Key points:
800 units completed in H1. The full-year target is for 2,700 completions.
Order book is up 22% since 2nd May and includes 2,057 “suburban” units. “Strong visibility on deliveries and revenue in H2 2024.”
H1 revenue €150m (H1 last year: €172m), as over 500 of the completions in H1 already had most of their revenues recognised in prior periods.
Suburban margins are now over 20% thanks to “our enlarged scale, increased standardisation of product and processes, and continued integration of manufacturing” (last year: 19.3%).
Net debt increases to €250m (H1 2023: €182m), driven by work-in-progress “which will unwind as unit deliveries accelerate in H2”. So we should expect a quick reversal of this.
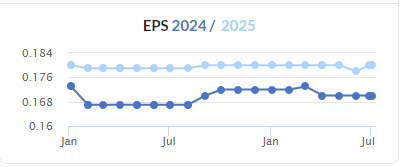
Outlook: full-year EPS guidance is reiterated at 17 cents (2023: 8 cents), ROE target 15%. Guidance has been pretty stable:
Some comments on strategy:
We continue to invest in accordance with our capital allocation priorities, notably in land where we are now seen as the partner of choice for landowners in attractive Suburban and Partnership led locations. A number of significant land transactions are now being explored in this regard.
These acquisition opportunities, should they materialise, are in highly attractive locations that are fully aligned with the ambitions of national and regional planning policy. These will also underpin long-term operational growth and optimal returns for shareholders, supported by our resolute focus on enhancing Return on Equity and our commitment to manage the size of the landbank to below €400m over the long term. Once our capital allocation priorities are satisfied, we remain committed to returning any excess cash identified to shareholders.
The CEO also provides some comments, noting that around 35,000 units are now being built in Ireland p.a. but arguing that 50,000 units p.a. should be delivered. I couldn’t agree more - in fact I think that’s on the low end of what would be a reasonable figure, given the current supply/demand imbalance. But of course it’s easier said than done - planning roadblocks, taxes (especially VAT), strict mortgage rules and high raw material costs all need to be managed and overcome to make that happen.
He finishes his comments with the following:
Glenveagh's ability to deliver great value, high-quality, sustainable homes at scale via our innovative and proven vertically integrated operation positions the business at the forefront of meeting the needs of a growing economy and rapidly expanding population, supported by motivated legislators and a strong fiscal position."
Graham’s view
I’ve only commented on this share a couple of times before. In September 2023, I gave it the green light at a share price of 97c. It originally came to my attention at 82 cents in January 2023..
Among other things, I have noted the company’s focus on ROE as a key metric, its declining share count, and low PE multiple.
Guidance for 2024 is unchanged since then in terms of EPS, and there haven’t been any more share buybacks to reduce the share count. The main change since September is that the share price is now €1.32:
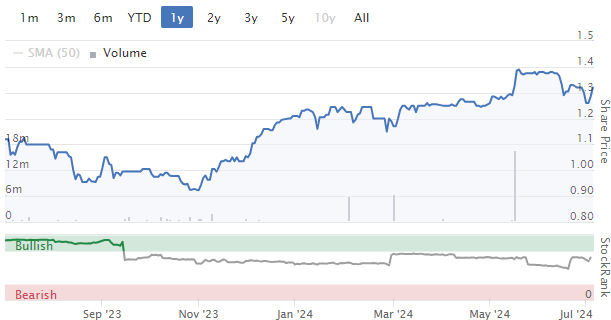
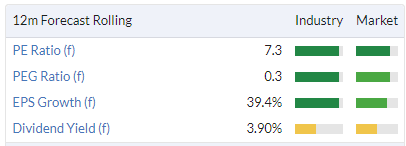
So it’s no longer trading at the bargain bucket valuation it was before, although it does still have a single-digit earnings multiple:
Against its balance sheet, it now trades at a premium to book value, instead of a discount. Net assets as of December 2023 were €678m.
Overall, my view here is unchanged: I continue to view this as a high-quality home builder that works on attractive developments in the region around Dublin.
However, I’ll try to stay disciplined: in general, when a home builder trades at a premium to book value, I take a more cautious stance. Therefore, despite the strong momentum here, I’m going to revert back to AMBER/GREEN to reflect the fact that the shares are up 36% since I looked at them last.
Liontrust Asset Management (LON:LIO)
623p (£404m) - Final Results - Graham - AMBER/GREEN
Let’s do another catch-up report on a fund manager’s results.
Liontrust published its full-year results (for March 2024) towards the end of June, while I was away.
Headlines:
Gross profits down 19% to £186m (this number is similar in meaning to revenues).
Adj. PBT down 23% to £67.4m
Statutory loss £0.6m (it’s crucial to investigate the difference between this and adj. PBT - see below).
Dividend for the year unchanged at 72p.
Assets under management fell 11.5% to £27.8 billion by the end of the financial year (March 2024), and fell a little further to £27.25 billion as of 20th June.
Net outflows for FY 2024 were £6.1 billion - a shocking figure.
CEO comment: talks about “signs of a change in investor sentiment”, and outlines strategy:
The events of the last year have not reduced our belief in active management but have reinforced the need for Liontrust to expand our investment capability across asset classes and investment styles, broaden distribution and enhance the Group's operations. As we could not accelerate these developments through an acquisition, we have been pursuing them organically, through recruitment and investment in the business. These actions are ensuring we can drive the business forward and deliver on our strategic objectives.
You may recall that Liontrust made a failed attempt to take over the Swiss fund manager GAM last year (discussed in previous reports).
UK ISA: Liontrust was “actively engaged” with the government over the idea.
Adj. vs actual Profitability
The scale of the adjustments made to the profit figure this year was staggering: £68m, a high percentage of the company’s total market capitalisation!
Here’s a table from the footnotes explaining what happened:
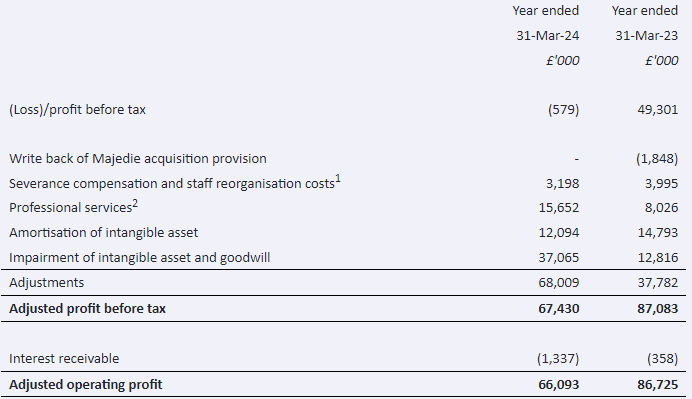
To understand the £15.6m spent on “professional services”, you have to scroll back to a footnote within another footnote in the results statement.
It turns out that most of the professional services relates to the failed GAM acquisition, but £5.6m of it is described as “Significant costs relating to target operating model restructure”. This includes new software and various other costs.
Personally, I do not allow companies to write off costs such as this as exceptional, as to do so would invite companies to pretend they are profitable when they are not! So personally I would not allow this £5.6m to be adjusted out of costs.
Similarly, I wouldn’t allow staff severance/reorganisation costs to be adjusted out. The figure for FY 2024 is not so different from the figure for FY 2023, so is it really an exceptional cost?
Amortisation and impairment - many investors are happy to let these be adjusted out, as they are non-cash, but the huge impairment figures are a poor reflection on the company’s track record in acquisitions.
Overall, I do think it’s fair for the company to argue that some costs need to be adjusted out, but I think there is a middle ground to be found between what the company presents and the unadjusted statutory loss.
Graham’s view
As is usually the case with Liontrust, I struggle to find the company’s points of differentiation vs. other fund managers. For example, the Chairman describes Liontrust as having “investment styles that have been largely out of favour during this environment of interest rates remaining higher for longer than many expected”. He goes on to describe these styles and strategies as “quality growth, small and mid caps, sustainable investing, as well as UK equity”. Perhaps they are simply running too many strategies?
The company doesn’t seem to agree - on the contrary, they are seeking more diversification of the fund range. The GAM acquisition, too, would have added complexity. It all seems very counter intuitive to me.
They do say they have been merging funds “where we can produce economies of scale for the benefit of investors”. (It’s always important to bear in mind that when fund managers describe their historical returns, they often do not include poorly-performing funds which have been merged or shut down.)
As you can probably tell from my analysis of the company’s earnings adjustments, I’m also not entirely satisfied with the company’s presentation of its results. That’s nothing new: I’ve had questions about this going back to 2022.
I am still inclined to keep my positive stance on these shares due to their cheapness:
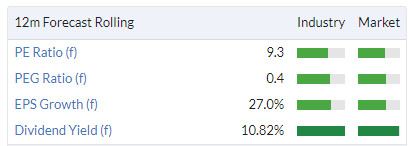
But as before, this is far from my top pick in the fund management sector. What I suspect they should do is allow themselves to merge or be taken over by a larger company. Instead they have preferred to be the acquirer, and this hasn’t worked out well for them up to this point.
On balance, I’m going to moderate my stance on this from GREEN to AMBER/GREEN. With different management, or with cleaner accounts and a simpler strategy, I could probably go GREEN again
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

69 comments
Liontrust Asset Management (LON:LIO) many thanks Graham for the excellent overview - I agree with all your points. I think you really need specialisation in fund management space, which LIO don't really have. I think Polar Capital Holdings (LON:POLR) look good in this respect, and in the large cap space I'm a big fan of £ICG
Graham, Agree re a more cautious stance on GLV- I sold my holding recently. Cairn Homes (LON:CRN) share had also drifted recently though picked up again recently. In theory with the Government measures these two should be doing well- but share prices are not moving as I would expect. If GLV trades down again to €1.10/15 I would look at buying.
Distribution Finance Capital Holdings (LON:DFCH)
Hi Paul,
I just want to check something with your comment on Distribution Finance Capital Holdings (LON:DFCH) above '... Hence today’s news of profit rising from £4.6m in 2023, to £9.0m in 2024, isn’t reality in my view'. As it gives the impression you're trying to compare the H1 2024 result with the adjusted figure for full year 2023
If you write back the over provision as you have done to the 2023 results, so £4.6m + £5.3m (over provision) to give £8.9m and then adjust out the writeback of £1.7m for H1 2024, so £9m PBT minus £1.7m (bad debt recovered to date), you get £7.3m for H1 2024. If you then assume a same again result for H2, so £2.3m + £5.3m (the full provision was made in H2), you get £7.6m for H2 2023 and so £7.3m + £7.6m = £14.9m for the full year, which would make the shares look much cheaper with the market cap of £61m
Your comments on the quality of earnings and the potential for bad debts and fraud still apply of course
Hi Daz3,
Thanks for your comment on Distribution Finance Capital Holdings (LON:DFCH) - I've not had time to check this out, it sounds like you may be right. I had to rush the section on DFCH, and something didn't feel right at the time, so I need to follow up on this.
Thanks for flagging. Apologies in advance if I cocked up the numbers - very rare here, so I'll be annoyed (and will obviously correct it) if I mucked up that section. Leave it with me - I've got a family get-together from lunchtime today and all weekend, so it might have to wait until next week.
Thanks, Paul.
Thanks Paul
I've made some mistakes in my calculation above
PBT in H2 2023 was £1.3m (£1.4m rounded up) and the write back should be £4.7m to give £6m and if added to the £7.3m adjusted H1 figure gives £13.3m
What's also clear is that H1 2024 is more than double the £3.2m achieved in H1 2023, so assuming a same again H2 is really ultra conservative with the increased loan book and lower impairments. If you assume a fairly conservative 1.5 times multiple, you get £9.1m for H2 2024, so PBT of £16.4m for the full year
Bricks!
Fail to understand the disparity in the valuations between Michelmersh Brick Holdings (LON:MBH) versus the likes of Forterra (LON:FORT) despite the former's investment metrics being so much better, e.g. cash on balance sheet, dividend yield etc. Admittedly it is smaller but beyond that it runs rings around its contemporaries on the majority of investment metrics. May be someone better informed than me can shed some light?
Brickability (LON:BRCK) Have added a few this morning. The company's diverse range of activities especially in cladding, including remediation should help offset the weakness in bricks, which will recover. Brickability (LON:BRCK) has low capex as it is not a brick manufacturer, but an importer and distributor.
Also there have been significant director purchases this year, which is a clear indication that they feel the shares are good value. The company has no issues with leverage and there is 5% yield while one waits for the brick market to improve
Brickability (LON:BRCK)
The company has no issues with leverage and there is 5% yield while one waits for the brick market to improve
I wouldnt say there is no issue with leverage they have splashed a fair wad (nearly £100 mill?) in the last 12 months or so and part of that is paid out later so not showing in debt now.
ok 1.25 * EBITDA isnt huge - but the reality is per the most recent interims bottom line profit is less than half EBITDA - they would use EBITDA wouldnt they are it sureky flatters debt metrics materially.
My slight concern is if they have paid £93 mill for 2 cladding companies right at the peak of the cycle (my presumption) - i am not saying there is not many years work to go sorting out current/past issues. But i would say then huge spike in demand will likely have created great windfall for specialist companies at teh start of the demand spike - over time though extra capacity should come onlines that i would expect would normalise profitability - looking at the acounts of the acquired companies they went from not doing much to silly money profits in no time at all - so i suspect the easy ridiculously high margins wont last forever. Thats somewhat idle speculation on my part there is no signs that these new acquisitions are currently doing anything other than performing well. I have held here but did get slightly spooked by the second £50 mill acquisition so similar to teh fisrt one - i was bottom fishing anyway so spike in price was enough for me to exit. I may buy back in at the right price but i would say new acquisitions funded most via cash with debt make it not as safe a house as it was previously perhaps for first 2 years of new acquisitions - hopefully they evidence debt can be paid down quickly and that would set my mind at rest.
Fair points rmillaree, but my take is:
13 May 2024: Brickability Group PLC, the leading construction materials distributor, announces that it has been informed that Douglas Bryce, Managing Director within the Contracting Division, has purchased 250,000 ordinary shares of 1 penny each in the Company ("Ordinary Shares") each at a price of 71 pence per Ordinary Share.
14 June 2024 Douglas Bryce, Managing Director within the Contracting Division, purchased 400,000 ordinary shares of 1 penny each in the Company ("Ordinary Shares"), at a price of 67 pence per Ordinary Share.
Brickability Group plc (AIM:BRCK), the leading construction materials distributor, announces that on 5 and 6 March 2024, John Richards, Non-Executive Chairman of the Company, purchased a total of 100,000 ordinary shares of 1 pence each in the Company ("Ordinary Shares") at a volume-weighted average price of 66.50 pence per Ordinary Share.
Brickability Group plc (AIM:BRCK), the leading construction materials distributor, announces that on 27 February 2024, Alan Simpson, Chief Executive Officer of the Company, purchased a total of 553,642 ordinary shares of 1 pence each in the Company ("Ordinary Shares") at a price of 67.75 pence per Ordinary Share.
Brickability Group plc (AIM:BRCK), the leading construction materials distributor, announces that on 29 and 30 January 2024, Alan Simpson, Chief Executive Officer of the Company, purchased a total of 850,000 Ordinary Shares of 1 pence each in the Company ("Ordinary Shares") at a volume-weighted average price of 68.99 pence per Ordinary Share.
Brickability Group plc (AIM:BRCK), the leading construction materials distributor, announces that on 25 and 26 January 2024, Alan Simpson, Chief Executive Officer of the Company, purchased a total of 150,000 Ordinary Shares of 1 pence each in the Company ("Ordinary Shares") at a volume-weighted average price of 62.33 pence per Ordinary Share.
My blended purchase price is around 60p
They have recently appointed Frank Hanna, the former joint CEO of Michelmersh Brick Holdings (LON:MBH) as CEO. He is well respected in the brick industry and has been instrumental to the success of Michelmersh Brick Holdings (LON:MBH)
Just my thoughts and I may off course have misread the tea leaves!
Brickability (LON:BRCK)
Hello jonno
I dont disagree with any of your analysis at all i pretty much agree ref the bricks side of things being at the low point of the cycle providing soem scope for rerate as you say. as you say Directors buys are pretty standout amounts i must admit. I dont doubt the volume of cladding work should remain healthy - just that the peak easy money bit might have passed if there was less competition when demand went through the roof (sellers of companies were obviously happy to cash in their chips for their 93 mill !!) . I might very well buy back in here if they keep things ticking over nicely and the price is right. ref anything i own or potentially own i like the warts and all to be out in the open.
Michelmersh Brick Holdings (LON:MBH) certainty looks a lot better on paper than likes of Forterra (LON:FORT) with earnings holding up much better, as well as a stronger balance sheet. Not sure I quite understand why MBH they have proven more resilient, but they do seem to be a bit more specialist
Forterra (LON:FORT) and Ibstock (LON:IBST) both up today perhaps on optimism that Labour will actually follow through on its planning pledges and get housebuilding moving. Certainly not related to current activity levels from the housebuilders as the Brick Stats from the ONS yesterday showed a further dip in demand in May. May down 9.3% YoY, April was down 5.8% YoY. As demand has been down consistently for more than 12 months presumably this is reflective of activity as any destocking should have worked its way through some time ago.
Or is it more about hope that Bailey will stop dithering and cut rates 1st August? Hopefully the Government won't put any more stimulus into the demand side of the equation.... prices are high enough already. Prospects of even a small cut in mortgage rates, the benefits of Rishi's tax cuts coming through and inflation remaining near target for the rest of the year should be stimulus enough.
A return to Councils being allowed to build new Council Houses (or even obligated to) and removing the Right to Buy might help rebalance the out of kilter escalation in multiples of earnings to buy a house we have been in since the GFC. Now that would get the brickmakers moving...
Marston's (LON:MARS)
Great feedback; thank you.
It is a small position for me and not a long term hold. So at 30p, if and its a big if, interest rates fall, stuttering England manage to overcome Switzerland, the election results in a working majority for whoever wins, Labour one would think and the summer weather continues to return to whatever passes as normal, there is a good possibility the shares could see close to 40p, which is a 30% uplift.
A fall in interest rates should provide an uplift to NAV and make asset sales easier. A simplistic assessment admittedly but will see how it plays out over the summer.
Card Factory (LON:CARD) Berenberg initiate a BUY rating and target SP of 154p - https://www.sharecast.com/news...
Still waiting for Teleios to Foxtrot Oscar.......
Have added a few more Card Factory (LON:CARD) this morning. Maybe someone will buy out Telios's holding, as Richard Crow, aka Cockney Rebel suggests.
Have been wondering about the impact of freight charges on the non card merchandise, soft toys etc, but think that this is baked into the current valuation.
Freight rates
Spoke to my forwarder
Sounds bad . In Chennai India. only 1 ship left last month and huge huge backlogs .(one of the major ports out of India )
Rinse and repeat looks like the situation is here to stay and as people panic more prices will get raised by the naughty ship owners who will fill their boots again just like the covid free for all .
With freight rates up and them likely to remain higher for longer (I feel like I've heard that phrase before somewhere...), are there any listed companies that will see their profits spike because of this, maybe Clarkson (LON:CKN) ? It is not an area I am at all familiar with and I'd imagine the upside is already priced in but thought I'd ask. I am sure this has probably been asked before, so apologies if that is the case.
I believe there are a couple of investment trusts which are focused on ship hire. Not looked into these in any great detail, but could be an area to explore. They always used to trade on big discounts to NAV but not checked recently.
Kenmare Resources (LON:KMR) - There is a project update posted this morning - outlining planned capex over the next few years to keep production going well into the future. Any thoughts/comments out there please on this rather niche miner
I have been a long-term holder of Kenmare Resources (LON:KMR) and it has been a bit of a rollercoaster recently. As I read it, the market was taken aback at the sheer scale of the capex needed over the next few years and worried about cost overruns. It didn’t help that this coincided with the retirement of the founder
My take is that they have done this type of project before and have a good control of costs and risk. Yes, these are large sums and the mine is in a remote area plus you have country risk. But they have been in Mozambique a long time, they put a lot of effort into working with the government and the local community.
The project update confirms my view that Kenmare Resources (LON:KMR) management know exactly what they are doing and have good visibility of costs. That leaves the fundamental point that every £ spent on capex is a £ that cannot be used for dividends or buybacks. On that basis, the shares are priced about right I think. I’m happy to continue holding long-term, based on the management track record and the significant moat that the company enjoys. I believe this is the largest resource of mineral sands in the world? Certainly one of the largest, with several decades worth of production available.
Morning….LIO seems to have fallen off the backlog list ….Have I missed something posted ??
£lio ex dividend today
Liontrust Asset Management (LON:LIO) valuation looks bonkers to me
A covered 11% yield and a PER of 8 just feel like wrong price for a quality asset manager. Any change in retail flows or just general increases in market should be operationally geared for them and none of that appears to be factored in from my perspective.
Exactly this davidjhill. Another bonkers dividend play that I'll wait until market sentiment turns which I bought heavily at around £6 together with Abrdn (LON:ABDN) and bide my time hopefully at least doubling my money including divs.
Made a comment yesterday in SCVR about Ed Croft’s 2022 NAPs selections and System1 (LON:SYS1) multibagging in only 18 months from end December 2022. Liontrust Asset Management (LON:LIO) was the 3rd worst performer in that years NAPs selection and has fallen by nearly 50% since end 2022 and Graham’s analysis offers some pretty good reasons as to why . However, many more of the poorly performing NAPs 2022 selections have continued down or flatlined at best Robert Walters (LON:RWA, Watches of Switzerland (LON:WOSG, Focusrite (LON:TUNE) and Vertu Motors (LON:VTU) to name 4 of that years losers. I guess my point is that there is an element of a lottery in any stock selection process - picking the big winner (System1 (LON:SYS1) from a fairly lengthy list of underperforming shares (14 stocks in the 2022 NAPs) in December 2022 could be seen as a matter of luck.
I do not understand why you are worried about the performance of the 2022 NAPS selections after the end of 2022. Ed always emphasises that the NAPS selections should be regularly rebalanced, so he would have assumed that they were all sold at the end of 2022.
Personally I evaluate all of the NAPS selections on a regular basis - I held on to Warpaint London (LON:W7L) after the end of 2023 because it looked to be a potential multibagger (it's now up 234% since I bought it), and I apply trailing stop losses to all of the selections, which I find increases my profits.
I do not understand why you are worried about the performance of the 2022 NAPS selections after the end of 2022
heck there is no harm looking is there - one additional piece of positive feedback would be if selections also perform well in the long run too - that kinda backs up that the picks are sensible long term selections - if one is going to hold for a year then thats not exactly quick in and out. Note by looking at later share price trends one can say - yeah we got that pick right fundamentally but the price didnt spike till the following year what was unlucky.
What do you not understand about Ed saying that the selections are not intended to be long term?
Georgia Capital / Bank of Georgia
Seems to be recovering .
Luckily I ignored [.......] and partly jumped back in at the lows .
I do wonder if the geopolitical unrest only stopped whilst Georgia had a good run at Euro 2000 and when that gets forgotten about and summers over be back on the streets .
Honestly wonder if it’s as simple as everyone watching the football and not protesting .
Bank of Georgia (LON:BGEO)
This just happens from time to time Planetx.
Political or social unrest in Georgia = lots of retail investors diving for cover. Selling stops and prices start to recover. It’s a cycle I’ve seen now over a decade, so it is what it is. The stocks are phenomenally cheap because that geopolitical landscape is unlikely to change any time soon.
I suspect regional diversification might change the rating slightly for the better at some point.
In the meantime October is next flash point as elections kick in and of course we must watch out for adverse currency moves given the GEL/GBP dynamic.
Georgia Capital (LON:CGEO) is a lot richer today as it has banked a large dividend from its Bank holding.
As I’ve always said I wouldn’t bet the family silver on Georgia but there is a place in my portfolio for it given the compound effects over time. But you have to be able to live with the volatility and be able to assess where the mood music is not just political rhetoric but becomes a genuine threat to democracy if that ever happens.
But you are correct in that there is aninvesting phenomena that large sporting events like World Cup / euros have a galvanising effect on the population and consequently share prices.
Some-one at TBC Bank I emailed with (Georgia) -which I hold-said they expected it to be quiet until elections in September. I thought of buying back into CGEO but decided against.
Georgia Capital
Luckily I just about timed it right selling s good chunk after results circa 1350 .
Sold 1/3 of my position in the way down .
Then bought back 20% right at the lows .
So this is probably exactly the same as doing absolutely nothing .
I did struggle with having it as a top holding so was very comfortable at a 2/3 holding , which before long will be back at a full holding if the price goes back to where it was.
As Sun Tsu says
“The secret to success lays in confusing the enemy but first you must confuse yourself”
Though I don’t think this is a real Sun Tzu quote
I see that Goodwin (LON:GDWN) will graduate to the FTSE 250 next Monday. That should provide support o an already buoyant share price as institutions buy in (unless already done so!). I hold.
Richard
I don’t hold Goodwin (LON:GDWN) and kicking myself for not buying down at 4500p not so long ago after a set of results. What a run - well done. I’ve just watched it rise and rise waiting for a strong pullback that never seems to come. Oh well. Clearly a great stock
David, I did try to highlight Goodwin (LON:GDWN) by setting up this dedicated thread (still holding).
Would also be interested to hear your views on Victrex (LON:VCT) which I get the impression you are keen on, although it's not a small cap. They have released a rather lacklustre Q3 Interim Management Statement, with a FY volume guidance remaining unchanged with expectations of low to mid single-digit growth. H2 PBT growth hinges on improvement in the Medical sector, which currently faces challenges from high inventory levels and industry destocking. While some end markets show momentum, Medical performance is below expectations. Cost discipline remains strong, but adverse currency rates pose additional challenges. Despite this, signs of improvement in several markets and a diversified core business offer encouraging growth prospects for FY 2025. The company maintains confidence in its medium to long-term prospects.
No idea on Victrex (LON:VCT) I’m afraid. Haven’t looked at that one in any detail. It’s on my list to review at some point but nothing to add really from me.
I have a small holding. However, I should point out that PEEK taking over the medical implant world is something they have been talking about for decades now and it has yet to get anywhere near those expectations.
Perhaps we'll have better luck with PEEK as a substitute for PFAS.
At an overly simplistic level, I think the issue is that PEEK is a very high performance material that you aim to deploy in in very in demanding environments - think medical & aerospace etc . Problem is product manufacturers in those same areas are, by necessity, very heavily regulated and very conservative. Product innovation happens slowly.
There has also always been the risk that somebody else works out how to produce the stuff in volume, reliably (there is already a Chinese manufacturer of medical grade PEEK). Solvay make something called KetaSpire which has similar applications.
Hi Turbo ... thank you for this and also for the link to the very detailed and excellent substack on Goodwin (LON:GDWN. (I hold).
Hi Graham, as it looks a fairly quiet day , would you have time to look at business financiers Duke Capital (LON:DUKE) and Time Finance (LON:TIME) , both of which reported last week but have very different profiles, both from a business and investment perspective. I hold both.
Close brothers (CBG)
Anyone is aware why the shares are up so much over the last two days? 10% yesterday and 3% today.
Marston's (LON:MARS)
The debt is frightening, but is largely asset backed by a large freehold estate. The outlook statement from the recent interims was positive in terms of like for like trading and the second half prospects. The shares are trading just off their lows and there has been director buying.
Ken Lever who is a senior independent director of Rockwood Strategic (LON:RKW) is today announced as the non executive chair of the company. Marston's (LON:MARS) is a Rockwood play if ever I saw one and I have just bought a 'springboard position' to borrow form Richard Staveley's book at a smidgeon over 30p. I may of course be completely wrong and Ken Lever's appointment may be pure coincidence, but at 30p and with current trading positive the risk reward see-saw looks stable,
"Marston's PLC is pleased to announce that, following an extensive external process, Kenneth ("Ken") Lever has today been appointed as independent non-executive Chair of the Company with effect from 8 July 2024. Ken Lever succeeds William Rucker who, as previously announced, steps down from the Board on the same date. Ken will also be appointed as Chair of the Nomination Committee.
Ken is an experienced business leader, having held a number of senior executive and non-executive positions at UK listed firms, across multiple sectors including retail, manufacturing, construction, software and business services. He is currently Non-executive Chair at Cirata PLC, Senior Independent Director at Rockwood Strategic plc, and Deputy Chair of Rainier Developments Limited. Ken has recently retired from the Board of Vertu Motors PLC and was previously the Non-Executive Chair of Biffa plc and RPS Group plc and a Non-Executive Director at Blue Prism plc."
Jonno looked at MARS a few months ago- but the debt pulled me off. Maybe I should have another look.
I've always looked at Marston's (LON:MARS) and all I can see is debt, debt and more debt and for the life of me cannot see where meaningful FCF will come from. They sold off the brewing side of the business and whilst NAV may be above the share price you really need to start selling the assets heavily to realise this - and buyers will know effectively, these are distressed assets insomuch that they need to sell to get the share price up with events. Oh and they are still making a loss IIRC.
I believe they still have the JV though. Decent brands in that
Marston's (LON:MARS)
its almost a binary gamble here with the debt - perhaps if they could pay debt down over 5 years and interest rates went low again £1 to £1.50+ could be possible. On the flip side they havent really eaten into the debt at all materially (despite positive tones) and thats despite cutting back on spending. part of the crown jewels went in covid too so they only have a share of beer profits now - if that part can make a proifit!. So any minor wobbles and holders could be diluted to oblivion like RBG - they are probably still in control with debt being long dated but with debt of £1 bill and net profit of only £50 mill pa clearly making headway from debt at current levels is not going to be easy . If they could offload material amount of poorly performing estate side of things at book value plus in theory that might boost things - i am presuming anything they could have done in that area easily they would have done - and if you shrink the estate whats left has to work that much harder to cover the plc costs.
So you pay your money and take your chance but it can be anything other than amber/red or outright red rating here for risk averse people.
Jonno
Marstons , hard you looked at -
What’s the debt
What’s the tangible assets
I’m just being lazy not argumentative
net debt exl leases 1.16 bill profits £50 mill pa and book value probably treble the shareprice (property might be worth more than book value) . They have miserably failed to make much progress ref debt reduction too. Long hard slog for them to make any progress here
I was buying in quite a lot 28-30p few months back hoping for up to 60p on any deal.
NAV is 2.5x the share price maybe more as property could be worth more but lets go with that but yeah the debt just isn't coming down much
It got back to 39p but like all small caps in my SIPP has drifted off some 25-30% in last few weeks on no news
Marston's (LON:MARS)
I hold some marstons from days of old (too lazy to sell) - i can see the upside potential for those happy to lose their shirt. Lets be honest 30p could easily be 15p in a blink if they needed to deleverage for whatever reason - so i think for anyone looking to preserve capital its a complete no go. For those happy with risks go with your conviction - its a shame if debt was 250 mill lower and interst rates lower once they start paying debt down each year interest charge comes down and debt gets paid down faster like a mortgage - reality is they are miles away from making any debt headway and their prior confidence in paying down debt has been sadly misplaced.
Jonno
Do you understand the implications of the "securitised, 95% hedged and capped and collared debt"? In particular, how would falling interest rates affect Marston's (LON:MARS?
The high amount of sport this Summer should provide good support for the second half figures, which are traditionally better than H1, but the debt and its sensitivity to interest rates rather clouds the beer for me.
Hi Paul can you let me know the web site you mention in your weekend brief for importing Japanese cars. I'm going to forward the brief as a friends daughter works at a major PR co and I know they are guilty of such practices.
#DSW Capital FY24 results presentation from earlier this week: video & podcast.
The lack of M&A has challenged but the growing number of fee earners sets them up well for the future. A drop in interest rates would be beneficial.
Secure Trust Bank #STB Capital Markets Day, yesterday. Video & podcast.
This covers the Real Estate Finance business's contribution to support the £4bn net lending ambition with ROAE 14-16%.
Supermarket Income REIT (LON:SUPR) have announced today that they have decided to scrap the script dividend alternative (shares) for this quarter due to the large discount with NAV. I don't think I have ever seen this before so sharing for interest - presumably this is to stop expanding the number of shares in issue.
"As the Company's ordinary shares are currently trading at a discount to the published EPRA Net Tangible Assets per share, the board of directors of the Company (the "Board") believes that it is not in the best interests of shareholders to offer the scrip dividend alternative, under which shareholders would have been able to elect to receive new ordinary shares in lieu of the cash dividend (the "Scrip Dividend Alternative"). The Board has therefore exercised its discretion to suspend the Scrip Dividend Alternative in respect of the Fourth Quarterly Dividend."
This has made me wonder about how dividends in the form of shares get accounted for. Are they just reflected in the number of shares in issue or does this appear anywhere else on the income statement or balance sheet? E.g. do share based payments cover this too?
It's hard to tell whether a lot of shareholders take the script dividend alternative at SUPR as the number of shares in issue has been heavily affected by equity placings to fund property development & acquisitions.
Supermarket Income REIT (LON:SUPR) - re cancelling the scrip dividend option. They've been doing it for about a year. Of course, nothing to stop one reinvesting - but with dealing costs & stamp duty. I don't know if stamp duty is charged on the shares resulting from a scrip dividend?
My morning smallcap tweet: The Importance of Seeing Earnings
Light Science Technologies Holdings (LON:LST) Distribution Finance Capital Holdings (LON:DFCH) Fusion Antibodies (LON:FAB) Image Scan Holdings (LON:IGE) ITIM (LON:ITIM) Newriver Reit (LON:NRR), Deltex Medical (LON:DEMG), Peel Hunt (LON:PEEL)
◄Light Science Technologies (LST)► guides H1-May rev up 19%, gross margin c.26.5% (20.9%) and EBITDA positive. In line? Throw me a frickin' bulb here. [SP=2.73 Cap=9m]
◄Distribution Finance Capital (DFCH)► guides FY-Dec24 significantly ahead of market expectations driven by stronger net interest income, lower impairments and loss provisions and stronger cost control. H1 pretax expected to be £9m+, significantly ahead of its expectations. [SP=26 Cap=47m]
◄Fusion Antibodies (FAB)► guides Q1-Mar rev c. £522k (£242k). Order book £0.7m. Cash will last to Q2 cal 2025. [SP=3 Cap=3m]
◄Image Scan (IGE)► wins c.£3m three yr contract for the ThreatScan portable X-ray system to be recognised in FY25 and 26. [SP=1.35 Cap=2m]
◄itim (ITIM)► five-year multi-million-pound contract with Assaí Atacadista, the largest Brazilian wholesaler, for the UNIFY Price & Promotions Optimisation solution. [SP=31 Cap=10m]
◄NewRiver REIT (NRR)► buys Ellandi Management, an asset and development management business focused on UK retail and regeneration, for £5m plus £4m earn out. For FY-Apr Ellandi's fee income was £5.7m and EBITDA was £1.1m. [SP=79 Cap=245m]
In line: DEMG, PEEL
LOL. Throw me a frickin bulb here, I'm the light.... need the lumens...... Superlative as always (im riding your coat-tails and completing the quote hahaha)
Distribution Finance Capital Holdings (LON:DFCH)
Trading update for six months ended 30 June 2024
Continued momentum with full year results now expected to be significantly ahead of market expectations
"Given the Company's strong underlying operational and financial momentum and the financial recovery in relation to RoyaleLife, the Group expects to report a pre-tax profit for the six month ended 30 June 2024 of no less than £9.0m, which is significantly ahead of its expectations and more than the entire FY23 outturn of £4.6m. Accordingly, the Group expects its full year outturn for 2024 to significantly exceed market expectations."
https://newsfile.refinitiv.com...