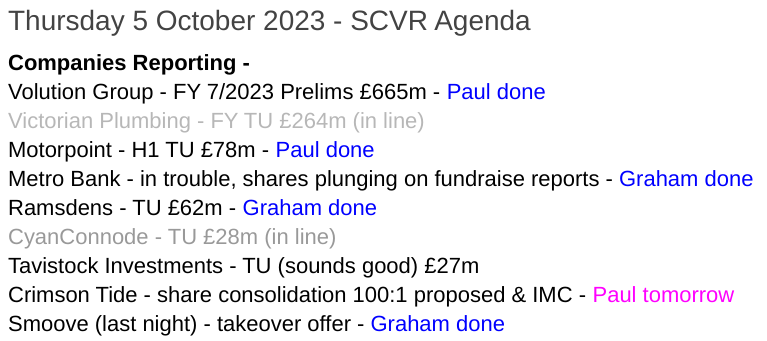
Small Cap Value Report (Thu 5 Oct 2023) - MOTR, RFX, SMV, FAN, MTRO

Good morning from Paul & Graham! Hopefully Graham's on the mend now, he's been under the weather lately.
Today's report is now finished.
Really grim market conditions too, with the AIM 100 dropping below 700 yesterday, a multi-year low. So tough times for sure, but the valuations are so attractive, and most companies reporting in line with expectations, that I remain positive about the medium-term potential being offered on a plate to us with the best UK small caps. Short term? No idea, anything could happen, as always.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Motorpoint (LON:MOTR) - 87p (pre market) £78m - H1 Trading Update - Paul - AMBER
It's half-year update shows an improving profit trend from Q1 to Q2, but it's still loss-making overall. Finance costs stand out as being much higher than operating profit, so it needs to do more work to improve basic profitability, which is only marginal at present. I do see potential here, and with the market cap down a lot, this could be a recovery share to add to our watchlists. Net cash has improved a lot, so I don't have any solvency or dilution concerns.
Ramsdens Holdings (LON:RFX) - up 6% to 201p (£64m) - Interim Results (ahead) - Graham - GREEN
Record results at Ramsdens with PBT set to come in at least slightly ahead of expectations (the RNS announcement could be a bit more helpful). The business continues to fire ahead and I don’t see any reason to change my positive stance. PER 8x and divi yield c. 5.5%.
Smoove (LON:SMV) - up 18% to 52p (£30m) - Recommended Cash Acquisition - Graham - AMBER
An excellent outcome for Smoove as they get a 54p offer from Australian group PEXA. The 54p bid is nearly 70% higher than the price at which the shares were trading before PEXA got involved. I would vote for this deal and I think that Smoove shareholders are going to.
Volution (LON:FAN) - up 10% to 370p (£734m) - FY 7/2023 Results (prelims) - Paul - GREEN & Podcast *MYSTERY SHARE*
Smashing results, and what seems a reasonable valuation, for a quality business. I like everything about it, maybe apart from a rather hollowed out balance sheet (full of acquisition-related intangibles), but that's not a deal-breaker as net bank debt is still modest compared with impressive cash generation. Looks a lovely business! I'll probably make this a podcast mystery share at the weekend. Maybe no rush to buy in current market conditions though, but certainly one for my watchlist.
Metro Bank Holdings (LON:MTRO) - down 26% to 37.2p - Response to press speculation - Graham - AMBER (Paul: RED)
This bank might need to raise equity as it ponders its balance sheet and liquidity questions. The shares are “cheap” but then so is the entire UK financial system. With so many high-quality financial stocks trading cheaply, I wouldn’t be tempted to bet on this one.
Paul’s Section:
Motorpoint (LON:MOTR)
87p (pre market) £78m - H1 Trading Update - Paul - AMBER
Motorpoint Group PLC, the UK's leading independent omnichannel vehicle retailer, provides an update on its trading performance for the six months ended 30 September 2023 ("H1 FY24").
Motorpoint operates car supermarkets - large, out of town sites, selling nearly new cars at fixed prices. Its history has been a dash for growth, but profits evaporated. I reviewed its breakeven PBT (on £1.44bn revenues!) FY 3/2022 results here on 14 June, concluding that it looks potentially interesting, if it can rebuild margins.
Next, on 26 July MOTR sensibly announced it was changing strategy to focus more on profit & cashflow, rather than revenue growth. I concluded that it might be able to beat modest forecasts, and viewed it moderately positively. That’s the background, let’s see what the latest news is today.
My notes (main points only), with my comments added -
Q1 - took action to increase margins and lower costs.
Difficult macro conditions continue - consumer uncertainty.
Affordability of used cars impacted by high prices and higher interest rates.
Broadened products from nearly new, to up to 5 years old.
Expecting used car prices to gradually return to normal as new car supply improves.
Underlying loss before tax of £(3.1)m in Q1, improving to £(0.6)m in Q2, £(3.7)m total H1. Not good, but at least the trend is improving.
This £(3.7)m u/l PBT is split: £1.6m u/l operating profit, less £5.3m interest expense - this shows how important finance costs have now become for car dealers, echoing a point I made yesterday in Vertu’s interim numbers. Clearly MOTR needs to do a lot more to improve operating profit, just to cover its own finance costs.
One-off exceptional charge of £1m for redundancies is an additional cost above the u/l figures above.
Liquidity - much improved, with net cash of £11m end Sept, up strongly from £2.2m end June. Plus a £35m facility on top. It doesn’t say this, but I presume the cash generation must have come from de-stocking.
A new site, Ipswich, was added in May 2023, taking the total to 20. Forecast revenue is £1.36bn, from just 20 sites, a remarkable £68m pa per site.
Paul’s opinion - I’m reassured mainly by the improvement in cash, which reduces risk for investors. An improving profit trend from Q1 to Q2 is good, but the figures are still much too low - not making any profit at all, after finance charges, does suggest maybe there’s something wrong with this business model, given that traditional car dealers are making good profits. It also gives an opportunity though, as only a small improvement in margin would give a much bigger profit number on £1.4bn revenues.
For now, I think the jury is out. Shares have come down a lot, as the bear market tightens its grip, particularly on unproven business models. That could change though, once the next bull market starts, and investors start looking at the figures with a more positive outlook - eg the margin opportunity on large volumes.
I’ll stick with AMBER for now, but at some point I think this share could be a potential recovery trade. Note that pre-covid it made profits of £15-20m pa. A return to that would mean a share price maybe 2-3 the current level, at a guess. So I think there’s potential here. Maybe all the online startup competitors have squeezed things but whether they survive is the big question. All MOTR has to do is survive, and market share could then drop back into its lap maybe? I think I’m almost talking myself into going AMBER/GREEN here, for the opportunity rather than the current state of affairs.
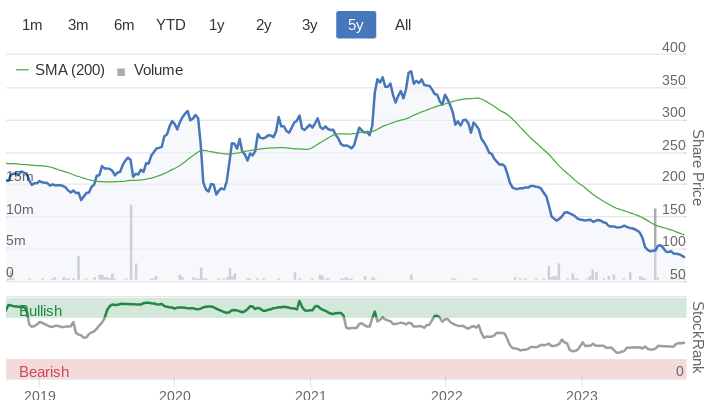
Note the despite the big share price fall below, there hasn't been any dilution from new share issuance, so in theory, were profitability to return to pre-pandemic levels, and investor sentiment improve, then this share could stage a potentially big recovery -
Volution (LON:FAN)
Up 10% to 370p - FY 7/2023 Results (prelims) - Paul - GREEN
Volution Group plc ("Volution" or "the Group" or "the Company", LSE: FAN), a leading international designer and manufacturer of energy efficient indoor air quality solutions, today announces its audited financial results for the 12 months ended 31 July 2023.
FAN share price has been steadily rising this morning, in a very tough market that’s telling me the figures & outlook must be good.
I’m not familiar with this company, but no harm in looking at something new. Graham usually covers it, summarising his previous comments (with more detail in the SCVRs of course):
14/12/2022 - GREEN - 349p - Graham sees potentially good value.
20/7/2023 - GREEN - 384p - FY trading update, at top end exps. Good 20% operating margin. Graham likes it.
FY 7/2023 Results - key points -
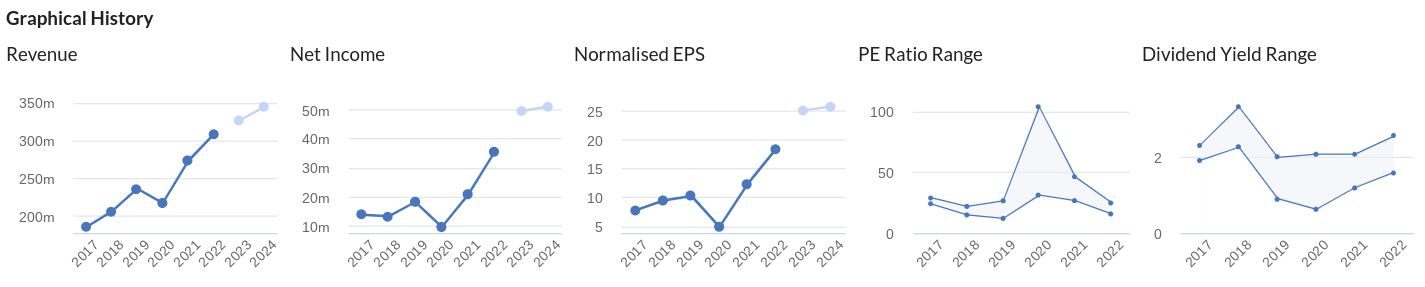
Revenue £328m (up 7%)
Adj PBT £65.1m (up 7% too, and note this is a really impressive PBT margin - so FAN clearly has pricing power, and competitive advantages, to achieve high profitability)
Statutory PBT much lower at £48.8m, so we’ll need to check the adjustments to make sure they’re reasonable.
Yes, adjustments are reasonable - a clear table is provided setting them out, and it’s nearly all acquisition-related, which is fine, customary, to adjust out, in order to arrive at proper underlying trading performance.
Adj basic EPS 25.8p (up 7.5%) - giving a PER of 14.3x (although what about dilution? I prefer fully diluted EPS as a measure). Actually, dilution only seems modest (further down it says unadjusted basic EPS is 19.0p, and diluted is 18.7p, so that’s OK)
Dividend 8.0p (up 10%) - a rather unexciting 2.2% divi yield
Acquisitions - two done in the year, costed £29.7m, and another one for £8.5m post year-end - so this explains the modest divis, it’s using cashflow mainly to grow by acquisition it seems. However, if acquisitions were to stop, then the dividend paying capacity is a good bit higher. There have also been some modest share buybacks.
Wide geographic spread, and it operates 22 different “strong local brands”. I like that it achieves high operating margins in all geographies.
Outlook - a bit vague perhaps, but the last sentence seems to indicate further growth -
Whilst we are mindful of the impact of higher interest rates on consumer confidence and new build construction, the regulatory changes in our local markets continue to drive demand for our innovative and well-positioned low carbon product technologies.
In addition, our three new acquisitions completed in the last six months; our ongoing focus on operational excellence; and the depth of experience and commitment across our local teams provides resilience and gives us confidence of making further progress in the year ahead.
Net debt - of £89.3m is only slightly up on last year. Given the high level of profitability of £65m, then this level of net debt looks fine to me. Although remember debt is costly now. I like the table it has provided reconciling opening & closing net debt, with the relevant cashflows. These numbers are all very clear in presentation, which builds my confidence in the company and its management.
Oh, I’ve just realised the £89.3m net debt includes lease liabilities. Eliminating those arrives at net bank debt is £58.1m, much better!
Balance sheet - NAV is £226m, but dominated by intangible assets of £248m, which I’ll write-off, together with £13m deferred tax, arriving at my adj NTAV of £(9)m - which is weak, but given the highly profitable & cash generative nature of the business, I don’t think it matters.
The business is essentially funded by £117m of long-term bank debt, which would only become a problem if trading fell off a cliff in a recession. Given macro uncertainty, I would urge management not to embark on any big, debt-fuelled acquisitions for the time being. You're welcome, there’s no charge ;-)
It’s been growing by acquisition, but importantly this has been done without diluting shareholders - see the progression below, and with the share count slightly down - due to buybacks.
Cashflow statement - very nice. Post-tax operating cash inflow was £68m in FY 7/2023, and £42m last year (lower due to adverse working capital movements). Nearly half (£30m) of this cashflow was spent on acquiring other businesses, £8m on capex, £8m on interest & leases, £15m on divis, and £2m on share buybacks. All very straightforward, I really am enjoying reviewing these crystal clear accounts! I often find the cashflow statement makes more sense than the P&L.
Broker update - many thanks to Liberum for making an update note available on Research Tree, tremendously helpful. It says that 25.8p actual EPS is 2% ahead of forecast (25.2p).
Forecast for FY 7/2024 is left unchanged at 26.0p, hopefully leaving some room to beat that perhaps? Or scope to absorb any macro downturn hopefully?
Paul’s opinion - as you’ve probably gathered, I really like these numbers, Volution seems a high quality business priced attractively.
My main query is whether the high profit margins are sustainable? Big profits often attract competition, which can be particularly aggressive if eg Chinese companies target a particular market, and under-cut the incumbents.
Overall though, based on the current situation, facts, figures, and forecasts (which as always will change in future), at this point in time I’m happy to view Volution as GREEN.
Graham’s Section:
Ramsdens Holdings (LON:RFX)
Share price: 201p (+6%)
Market cap: £64m
Ramsdens Holdings PLC, the diversified financial services provider and retailer, announces a pre-close trading update for the year ended 30 September 2023 ("FY23" or the "Period").
Ramsdens has “continued to trade well”, and therefore PBT will come in at “more than £10m”. I think this is a slight beat against expectations (it would be far more helpful if the announcement itself confirmed this!). Yes - a broker note from Liberum shows an existing PBT estimate of £9.98m. So this might be only the smallest of forecast beats - we won’t know for sure until the results are released in full.
Highlights:
Foreign currency revenue was up year-on-year by 8% (there is a clue regarding the importance of this revenue stream in the ticker code of the company!).
Check out the company’s newly-launched travel card - I think the main attractions of this product are to help people manage their holiday spending and to remove the risk of any unfortunate accidents affecting the traveller’s bank accounts/credit cards?
Jewellery retail revenue up 20% year-on-year “supported by particularly strong momentum online”.
Pawnbroking loan book up 20% to £10.3m (still only a fraction of the size of the H & T (LON:HAT) pawnbroking book).
Precious metal buying revenue up approximately 50% year-on-year, due to increased demand “in part as a result of the higher Sterling gold price”. The cost of living crisis is also surely a factor, as people look for ways to generate extra cash.
Eight new stores (they started the year with about 150). “Very pleased with the initial performances of these stores so far.”
CEO comment:
While the economic backdrop is challenging and Ramsdens is not immune to inflationary cost pressures, particularly energy and payroll, the Board remains confident that Ramsdens is in a good position to continue its positive momentum into the new financial year underpinned by the Group's proven and diversified business model, strong brand and clear growth strategy."
Graham’s view
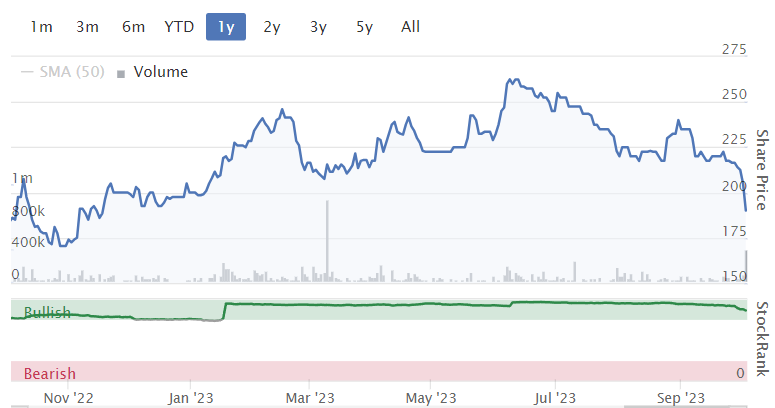
I’ve been positive on this one due to valuation, e.g. most recently at 259p in June. At its H1 results, Ramsdens announced a 33% increase in revenue and a significant increase in the interim dividend, from 2.7p to 3.3p.
The yield here should be around 5.5%, after today’s share price increase.
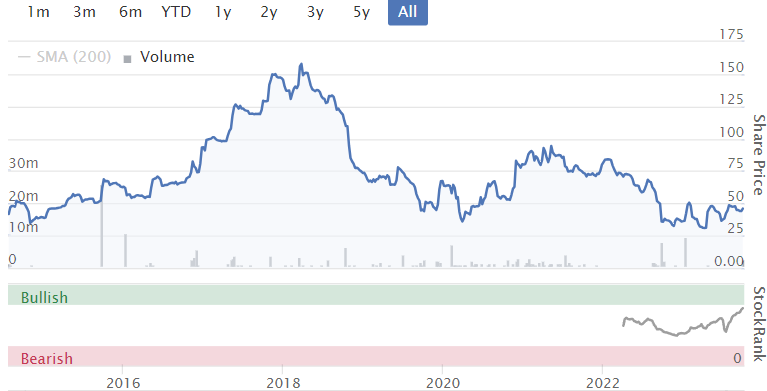
A 1-year chart shows the market allowing these shares to drift lower in recent months, despite the attractive valuation metrics:
Here’s where we are in terms of those value metrics:
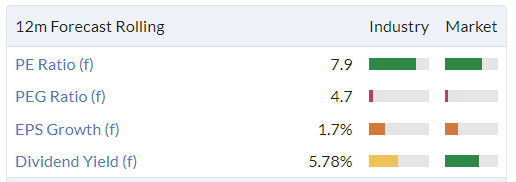
The PEG ratio shown above looks like it might be undercooked to me: it’s based on forecasts for only 1.7% EPS growth in the current financial year (FY September 2024). But given the momentum the business is currently enjoying, it seems to me like there is a wide range of potential outcomes with scope for better EPS growth than that over the next 12 months.
The broker note observes that the changing corporate tax rate (from April 2023) is a factor here. FY September 2023 is mostly at the lower tax rate, while FY September 2024 is mostly at the higher tax rate. They also think that “guidance is cautious” - I agree. But of course nobody knows for sure. It’s just a hunch!
The company has a tendency to over-deliver:
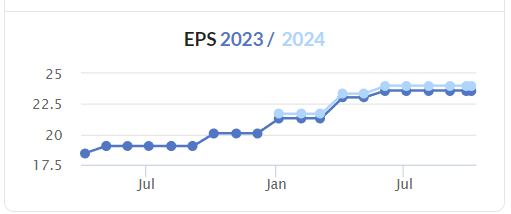
So for these reasons, I do think that the PEG number in the StockReport is a conservative estimate, and that EPS growth has a good chance of coming in better than forecast.
And if you strip out the change in the tax rate, then of course the underlying growth instantly looks more attractive.
In conclusion: I remain a fan of this business and have no reason to change my tune after another positive update today. There are plenty of cheap financial stocks in the market right now, but this is one of my favourites.
Smoove (LON:SMV)
Share price: 52p (+18%)
Market cap: £30m
This home buying services group is reaching the end of its life as an independent company, as it announces a recommended cash offer at 54p per share.
The share price yesterday was 44p, although the market knew that bid discussions were ongoing. Indeed, we’ve known since April that the Australian group PEXA were interested in buying Smoove. PEXA’s StockReport is available on Stockopedia (market cap $1 billion AUD).
As the announcement today acknowledges, the bid is actually a 69% premium to the Smoove share price prior to the date when the offer process officially began.
It’s an all-cash deal, with plans for the combined group to “build scale and depth in the UK market”
Smoove has strategic significance for PEXA: 7% of UK remortgages and 3% of UK sales and purchases are “intermediated” by Smoove.
A done deal? There are undertakings from Kestrel, Harwood Capital and Herald Investment Management to vote for it - these have 46.6% of the shares.
There is also a letter of intent from Schroders to vote for it. That’s another 9.4%.
I therefore expect the deal to go through.
Graham’s view
I wrote in July that Smoove should take any reasonable offer from PEXA. Smoove’s results for FY March 2023 were very poor, with a statutory loss of £5.8m and a remaining cash balance of £10m (after Smoove confidently made a return of capital to its own shareholders).
Losses in the current financial year were expected to moderate to £4m but the risks around Smoove continuing to operate as an independent company remained significant: how could the company be confident that it would get to breakeven quickly enough? Especially considering the difficult conditions in the housing market, with the company relying on lower-margin remortgage work, it was not a bet that I’d have been willing to make.
In the circumstances, this offer looks like an excellent outcome for Smoove shareholders and I would vote for it. Hopefully the company will have a bright future in the hands of its Australian parent. The story of this particular stock ends here.
Metro Bank Holdings (LON:MTRO)
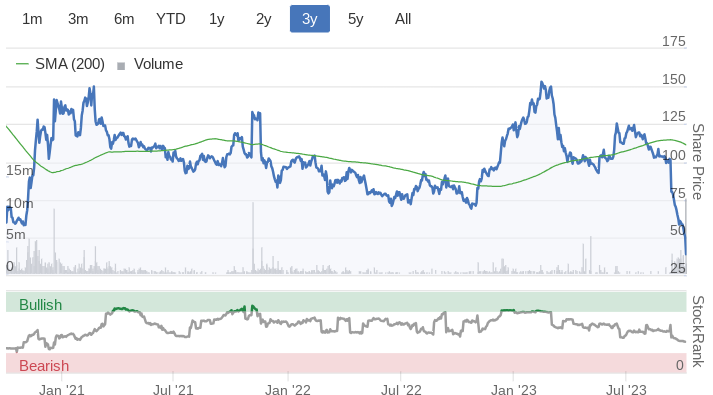
Share price: 37.2p (-26%)
Market cap: £65m
Here is an excerpt from Metro Bank’s response to press speculation (emphasis added):
…the Company continues to consider how best to enhance its capital resources, with particular regard to the £350m senior non-preferred notes due in October 2025.The Company continues to meet its minimum regulatory capital requirements and had a total capital plus MREL ratio of 18.1% and a leverage ratio of 4.4% as at 30 June 2023.
The Company is evaluating the merits of a range of options, including a combination of equity issuance, debt issuance and /or refinancing and asset sales. No decision has been made on whether to proceed with any of these options.
This follows a negative update in September: the Prudential Regulation Authority indicated that Metro would not be approved this year to use its own internal risk models to determine its capital requirements. This would likely mean a reduction in required balance sheet capital, giving the bank more flexibility and boosting its returns.
The interim balance sheet (for June 2023) showed net tangible assets of £4.42 per share. A far cry from the share price: about £1 then, and only 37p now.
With the shares trading at such a discount, the market was pricing in terrible news; in the best-case scenario, it was pricing in extremely poor capital allocation.
I note that the bank’s guidance set a target of “mid-single digit” return on tangible equity by 2024.
I don’t know about you, but the prospect of mid-single digit returns doesn't get me excited! Not in a low-interest rate environment, and certainly not in a high interest environment.
And the price paid for these returns - in terms of the risk taken - is enormous. A cursory look at Metro’s interim balance sheet shows equity of less than £1 billion supporting assets of nearly £22 billion.
That may be an overstatement of risk: the company had a CET1 Capital Ratio of 10.4% and a Total Capital Ratio of 13.2%, which are materially above the minimum requirements.
These are good measures of solvency but poor measures of liquidity. Specific mention in today’s announcement of the £350m notes due in October 2025 suggest that the bank is unsure how it will handle their maturity.
Do I think Metro is a zero? I doubt it, but you can never be sure. I specifically avoid studying bank shares because of their complexity and their poor returns.
Of course, it is possible that so many people have taken this approach that bank shares are now egregiously undervalued.
However, that still doesn’t make them a high-grade investment. Banking is one of the few industries (perhaps the only one?) where I find that smaller companies are of much higher quality than larger ones. I can easily find a host of small-cap financials earning double digit returns, but the same can’t be said of the larger institutions.
Metro’s share price might make it a small-cap, but it’s trapped in the body of a large-cap with balance sheet equity that runs ten digits long. It might make for an entertaining gamble but there are easier ways to make a few quid in the stock market, than betting on this sort of thing.
(Paul adds: the market cap is now so tiny, that my worry is the risk of massive dilution in any equity fundraise which now looks necessary. So for me it's a RED, but there again I don't invest in banks at all, and don't know much about Metro Bank. Could be a wipe-out for equity, if regulators force an emergency restructuring. Paul covers in more detail in this weekend's podcast, deciding it's bright RED, with imminent failure a very real risk, and equity holders first in line for losses of course).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
Further to the post on awful returns of the AIM All Share, Conor Mac published this article on Substack.
Why don’t you just sell all your stocks and buy ETF’s instead…..
https://open.substack.com/pub/...
which gives food to thought.
Reminds me of that programme when I was very young “Why don’t you just switch off your television and go and do something less boring instead”. That said I don’t find individual stock investing boring, even if I slightly underperform the market.
ETFs go down too. So called white gold Global X Lithium & Battery Tech ETF (PCQ:LIT) :(
Comments here about Metro Bank (LON: MTRO) from a distressed debt investor:
Very likely that this will be a zero. You should even have huge caution with the Lower Tier 2 and Senior bonds, which are trading at a significant discount to their nominal value.
Definitely a RED instead of amber I would say.
A very bright RED
Agreed - “Insiders” say nothing much to worry about, market and ratings agencies say otherwise.
Gotta remember the nature of fractional banking makes modern banking totally a confidence game - the bank has to keep up the sheen of confidence and all being well - until it fails - because otherwise they just bring forward that failure.
I suspect a "merger" (i.e. rescue) will come along shortly, arranged very nicely by the BoE.
I agree that Metro Bank Holdings (LON:MTRO) looks likely to be a zero for equity. Regulators are going to force some sort of funding, and equity never does well in these situation.
It'll survive as a bank... Probably one of the larger ones will absorb it. Maybe one of the new fintechs will buy it, to gain scale and a physical branch network.
I agree, MTRO looks an absolute bargepole for the equity. As I mentioned in a footnote to Graham's piece, and this weekend's podcast, I see MTRO equity as a total avoid, very strongly RED.
We've seen earlier this year, even with large banks, once they are perceived as distressed, and a depositor run starts, the equity can get wiped out within days, as a forced disposal is insisted on by the regulators.
Looking at MTRO's interim accounts, it has a potential write-off to equity of hundreds of millions, if it becomes forced to sell its Gilts/other bonds, because they're in the books at cost, which as it admits, is now well above mark to market if they become a seller (which is what brought down Silicon Valley Bank).
Even the bonds are only for experts, as I mention in my latest podcast.
What's the betting we get some sort of crisis resolution this evening? My suspicion is equity could easily we wiped out fully, so I wouldn't touch it. Equity is always first in line for losses, a lot of investors don't seem to understand that key point.
Regards, Paul.
Did anyone watch the Beeks Financial Cloud (LON:BKS) webinar this afternoon? What were your thoughts if so?
Yep I watched it. Thought it was good. FY24 should be the year when we see operational leverage on the Exchange investments, so profitable and cash generative. They answered my question on FY24 upside risk given the fact that the JSE revenues slipped into FY24 but the brokers have not increased their forecasts. So hopefully we will see Beeks Financial Cloud (LON:BKS) exceeding expectations which should drive the share price upwards. Here's hoping.
Yes I also watched the Beeks Financial Cloud (LON:BKS) (I hold) webinar today, and it impressed me a lot. Management apologetic about missing FY 6/2023 numbers, blamed on the Johannesburg contract slipping past the year-end. It's since signed, and sounds like it's going well. 90% of (demanding) forecast revenues for FY 6/2024 are already contracted, and mgt think there's upside on the ambitious growth forecasts.
Don't need many more staff, as they've built the systems, so incremental income from now on will generate better operational leverage.
Pipeline sounds very good, with several large contracts apparently close to signing.
Sounds to me like it's all coming together nicely, so I made that rookie error of buying more during the webinar!
One criticism is that the CEO talks in too many abbreviations, and I find it quite difficult to catch what he's saying, as he talks quite fast and sometimes mumbles over a few words, but I got the gist of most of it.
They're not entertaining M&A activity, as so much organic growth to go for. Seemed to say that they'd had inbound queries about being bought, but no details given (I might have misheard that, as it was an aside, near the end).
In a bull market this would be £100-200m mkt cap I reckon, so the £61m mkt cap looks quite attractive, if the growth does indeed happen this year. It should do as it's 90% already contracted, recurring revenues.
I was a bit disappointed with the last update, but very happy with the webinar today.
DYOR obviously, just my general impression.
Regards, Paul.
The AIM is not the only index/stock at multi year lows. There are quite a number of quality companies (though not micro-caps) across the pond at three and five + year lows. Such as 3M Co (NYQ:MMM) Pfizer (NYQ:PFE) Walt Disney Co (NYQ:DIS) American Tower (NYQ:AMT) British American Tobacco (NYQ:BTI) Estee Lauder Companies (NYQ:EL).
In fact the AIM all share is a real shocker, and going on the adage, fish where the fish are I am really not sure why I have been fishing in this pond! It is 100 points below where it was in 2004.
Yu (LON:YU.) now 20% down since IMC the other day?!
I know this share divides opinion, but now on a forward PE of around 7!
UK Small Caps are finished ha ha
surely that is just some profit taking after a good run and results on YU. Outlook is impressive too unless someone knows something else?
Yu (LON:YU.) Miton UK Microcap Trust (LON:MINI)
I might know something relevant...
YU is (was?) the largest holding in Premier Miton's UK MicroCap IT (MINI). There may be some pressure to sell this to meet redemptions.
MINI has an annual facility (at the board's discretion) to redeem shares at par. From today's RNS: The total number of Ordinary Shares in respect of which valid redemption requests were received for the 2023 Redemption Point (November) was 17,714,958 (representing 18.7% of the issued ordinary share capital).
https://corporate-premiermiton... is the last annual report (big file). Page 20 (pg 22 of the file) lists the top 30 holdings as of April. I didn't find information related to how much cash is currently held for redemptions.
Last year (June) redemptions were 13+% of the market cap.
disclosure: I hold one of the top 30 holdings...thankfully quite far down the list and unlikely to be permanently affected, if at all.
Laurie- Closed end funds do not have redemptions. They are closed end PLC's-listed on the Stock Exchange. Open ended funds/Unit trusts have redemptions. Huge difference between closed and open ended funds. I personally would not hold a Unit trust- rather buy closed end funds on a big discount. Miton UK Microcap Trust (LON:MINI) might be selling YU?, no idea, but not due to redemptions.
Card Factory (LON:CARD)
Further proof that Card Factory are further diversifying their offering. This was in my local store this morning which has just had a refurb and looked much better. Apparently this display has only been up a week and has been refilled a few times, I wonder what the margins are on this stuff??
I suspect won't be as high margin as the cards as they design and produce them in-house. Always good to have another revenue stream though and of course having all these extras may encourage people to shop there who wouldn't otherwise.
Same in Sainsbury’s so not exclusive perhaps.
Good afternoon Paul,
That really is a cracking summation of today's Volution FY23 numbers.
Volution (LON:FAN)
What I really like is the way you give a running commentary as you read through the report, flagging possible banana skins and then giving them a thumbs up ( or otherwise)as you check the numbers.
"Statutory PBT much lower at £48.8m, so we’ll need to check the adjustments to make sure they’re reasonable.
Yes, adjustments are reasonable - a clear table is provided setting them out, and it’s nearly all acquisition-related, which is fine, customary, to adjust out, in order to arrive at proper underlying trading performance.
Adj basic EPS 25.8p (up 7.5%) - giving a PER of 14.3x (although what about dilution? I prefer fully diluted EPS as a measure). Actually, dilution only seems modest (further down it says unadjusted basic EPS is 19.0p, and diluted is 18.7p, so that’s OK)"
I know that this is your style and it is very useful, giving your readers a nudge to check things like adjustments etc
Thank You.
How kind, thanks Helvellyn! :-) Everyone likes a pat on the back.
Yes I was hoping that explaining my thought process as I work through results statements might be useful to readers, so nice to have that confirmed, thank you!
Best wishes, Paul.
http://newsfile.refinitiv.com/...
Looks as though Jupiter have taken an additional 5% holding in Synthomer (LON:SYNT) ...
It's not just small and mid-caps getting crushed on a PW. Look at train manufacturer Alstom today, a company with a big moat and solid long term tailwinds. Cashflow is king. Ouch.
Metro Bank down 30% this morning!!!
Frightening.
Accrol group (LON:ACRL) full year results for year ended 30 April 2023 presented by Gareth Jenkins, CEO & Chris Welsh, CFO video & podcast. Some interesting snippets both for ACRL and for the market generally.
Top line summary provided by the RNS: A strong growth in both revenue and profit, driven by increasing market share and volumes. FY24 EBITDA now expected to be ahead of previous Board expectations, driven by accelerating margin recovery. From the presentation, the 52% revenue growth comes from 8% increase in volume and four price increases. ACRL now have a 22% market share. The market is dominated by five big players. ACRL's revenue per head has increased to £576k from £150k in 2017, which compares well with Kimberley Clark. This has been driven by automation.
ACRL have benefitted by the consumers' shift to own label. There has been a marked change in market dynamics where the consumer recognises that own label is as good as branded. Once they change they stick to own label.
Future growth will come from facial tissue and wet wipes. Cost savings including the reel change size will come through next year. More detail on the paper mill will follow in due course.
Vertu Motors (LON:VTU) interim results presentation with Robert Forrester, CEO & Karen Anderson, CFO at 1pm today. There's always an extensive Q&A. Register here. Paul covered the results in yesterday's SCVR here.
If you missed the DP Poland (LON:DPP) webinar yesterday you can watch a recording here
The new management team have been in place for 12 months and have made considerable progress in that time. Perhaps key is that for the first time in its history, DP Poland is being run by a CEO who has Dominos experience. He previously owned 23 franchisees in Australia, including 5 of the top 10 performing stores.
It started with improvements to the basics: faster delivery times and product quality are driving higher customer satisfaction. This in turn is driving higher average order count which is a key driver of profitability. There is still more to be done in improving profitability and this is key to attract new franchisees to the business but they've made a very good start.
I wonder how many more years DP Poland (LON:DPP) will keep flogging this dead horse? It just isn't working, and never has worked!
I’ll just point out, as I seem to every three months, that Volution (LON:FAN) has put out another reassuring set of numbers that has reversed an unjustified slump in the SP. I think Graham is favourable to this one.
Anyone have a list of small cap funds with decent track records that are worth looking at now? Most will have suffered outflows, but in the long run if they have good companies on their books then it's probably time to build positions as we enter Q4.
I would look at the Association Investment Companies- tools there to sort, see discounts etc.
Hi eParo. If you are willing to consider US smallcaps there is the De Lisle American Fund which claims an annualised return of over 14.4% per annum since 2010. The same fund manager, Richard de Lisle, has significantly outperformed the S&P 500 since 1995 with a fund he runs for a Cambridge University college.
Motorpoint (LON:MOTR) (I hold) Paul I believe you’re correct in thinking the cash generation (roughly £9m ytd) is from destocking. I’ve been keeping a close eye on the companies stock levels and I’ve seen a reduction of circa 10% over the past few months. But they have also put a hold on growth caped with the pausing of new store roll outs.
The difference in earning profile between Motorpoint and other listed dealers such as Vertu and pendragon is that Motorpoint makes its money on vehicles only (and some commission on finance) often called “metal margin” whereas the franchise dealers like Vertu make the majority of their money from after services and repairs, not on the cars themselves.
Motorpoint in my view is the industry leader in the nearly new used car market and has a high probability of being a highly profitable industry leader when market dynamics normalise. They are an extremely customer centric business, owner managed, with a real long term perspective. They have a defined competitive advantage as the lowest cost operator in the industry, who pass back operational savings to their customers. The franchised dealers can’t compete with them on price. They operate at low cost and turn their stock very quickly 7-8 times a year vs 3-4 for most other dealers. That’s the source of their advantage and I think their most will only strengthen as they grow.
They typically return fantastic returns in incremental capital of circa 100% and have a large runway ahead to reinvest earnings into the froth if the business (its compounding machine).
I feel they are mostly impacted by reduced volumes at the moment, tge business requires a certain amount of volume in order to generate its above average returns, but vehicle supply shortages and affordability have impacted that.
But for those conditions to persist you’d have to assume the car industry supply balance has forever changed (I don’t think it has, new car production is creeping back towards pre covid level fast and the industry is build on a tendency to oversupply due to competitive forces which are only increasing with the growth of Chinese brands), commentary from all car dealers CEO’s backed up this improving supply picture. And you’d have to assume we remain in a cost of living crisis forever, which I don’t think is true. Once those change tge business is well positioned as they say to be highly profitable and an industry leader.
tge management is top level and are in my view proving exactly how to run a business like this in difficult market conditions. I wouldn’t be surprised either if the initiate a buy back programme with the cash on hand considering the business is extremely undervalued currently
Motorpoint (LON:MOTR) have been forced to change their business model dramatically…now selling cars up to 5 years old rather than purely nearly new cars…& that means their historic low cost speedy prep advantage has been badly dented. Franchise dealers have the workshop capacity, parts availability & easier access to warranty work…as well as the experience of older stock that makes for a significant competitive advantage over the likes of Motorpoint (LON:MOTR) ….add in the fact that OEM’s are increasingly the dominant source of newer vehicles as daily rental fleets are now held longer & manufacturers favour their franchise network wherever possible and to me the odds are stacked against Motorpoint…at least for now…but potentially forever. If Motorpoint ring Vertu to book in a car for warranty work I’d suggest it is unlikely to get done ahead of Vertu’s own used cars…
Supply of nearly new cars is definitely a major issue for motorpoint as well as other car supermarkets and used car dealers in general. There is no doubt that the costs of prepping a 5 year old car would be much higher than a 1-3 year old car and that will definitely impact profitability currently.
The question of whether you feel the model for car supermarkets is broken forever is definitely the one to answer if you are considering the viability of Motorpoint going forward. I personally don't feel it is and that the supply issues currently being felt will subside and Motorpoint will shift their focus back to 1-4 year olds (With a primary focus on the 1-3 year market) as supply restraints ease.
The car industry is highly cyclical and prone towards oversupply of vehicles as companies vie for market share in a highly competitive market. The balance in the market currently won't last and conditions will normalise, especially given the competetive pressures of chinese brands.
Motorpoint only have 3.5% of a highly fragmented market, so there is a large amount of growth and supply to go for, i don't feel that the dominance of any particular OEM will stem the supply of quality used cars to the industry. The agency model is still largely untested and it remains to be seen how the agency model plays out, as well as the long term domination of the current established brands in a future EV market (especially given the rise of chinese brands) so there is as much uncertainty if not more on the established OEM and franchise model side of the business as there is for Motorpoint.
The company is also dramatically increasing its sourcing of vehicles directly from customers, and has extremely well established relationships with all the major fleet and auction companies, meaning they are often the first and best outlet for companies selling nearly new stock.
All good points …but I keep coming back to the question of why they are doing so poorly compared to peers…eg Car Giant … smaller ..fewer sites..but hugely profitable in the same period ..admittedly freehold & London based but notable difference
I believe half of the reported profit from car giant was from the sale of property so profit from the business was around £20m-£23m.
They also generate income from leasing property which is not used by the business so it’s hard to define the core car dealer numbers.
As car giant only operate from one location there would be advantages to scale and profitability / efficiency vs Motorpoint 20 locations. The companies have different models in terms of growth and footprint.
Motorpoint would also be losing money on the new stores they have opened in the past few years, typically a new store loses money in the first year and given they have just done a rapid roll out of stores that will be impacting profitability further.at maturity a store typically earns around £2m-£3m in profit and can reach up to 15% market share in its region at maturity (Motorpoint is targeting a 10% share of the national market I believe). It takes 2 car cycles before a store reaches maturity which is about 7 years (3.5 years per car cycle). That’s the sort of horizon tge managent are working towards.
I expect them to reach 30 stores at maturity nationwide, that’s managements aim, once they start rolling out new stores.
Single site agree is different indeed but the vehicle related metrics are clearly way better
re. share buy-backs, IIRC there was a note in their AGM release
the management of Motorpoint (LON:MOTR) have already proposed a share buy-back program (which passed as a resolution)
From this morning's Telegraph with an apocalyptic headline. Personally I thought we'd already slumped in a prolonged fashion, but what do I know, maybe we were just practising?
"The surge in bond yields that is sending government borrowing costs higher will only stop after a prolonged slump in stock markets, analysts at Barclays have warned. Bond markets have rebounded slightly from a rout that sent UK 30-year gilt yields to their highest level since 1998 this week.
Stocks have struggled under the weight of soaring yields in the bond market. Yields - the return paid to buyers of the bonds - rise as the prices of bonds fall as investors demand higher returns. Higher yields undercut stock prices by pulling investment away from stocks and into bonds as the returns appear more lucrative. Higher coupons also hit corporate profits and government debt by making borrowing more expensive.
Barclays analyst Ajay Rajadhyaksha indicated that the bond rout may not be over until a repricing of stocks, dubbed “risk assets”. He said: “There is no magic level of yields that, when reached, will automatically draw in enough buyers to spark a sustained bond rally. In the short term, we can think of one scenario where bonds rally materially. If risk assets fall sharply in the coming weeks.”
He added: “The magnitude of the bond sell-off has been so stunning that stocks are arguably more expensive than a month ago, from a valuation standpoint. We believe that the eventual path to bonds’ stabilising lies through a further re-pricing lower of risk assets.”
Which is one reason why I am about 75% in cash now .
Tein
John Authers in his (free) Bloomberg ‘Points of Return’ this morning is saying the same. Sharp change in the yield curve is suggesting more downward pressure on stocks.
Edit : You can sign up here : https://www.bloomberg.com/acco...
Feels like a US recession/market crash only a matter of time judging by recent movements in Treasuries. John Authers this morning talks about the recent 'bear steepening' which sounds like a bad signal. In my view, long dated treasuries probably provide the best hedge against a recession as would expect yields to fall back sharply if we do see a downturn.
John Authers this morning talks about the recent 'bear steepening' which sounds like a bad signal.
Doesn't he say something similar every day, 365 times a year? The guy is worse than a stopped clock. Anyone that pays any attention to him needs their head examining IMHO.
Don’t always agree with you Simoan but I do in this instance. Likewise is Simon Thompson. Throw a 1000 darts at a dart board each year and you will hit double top at least once.
Regards
You mean because Simon Thompson recommends "buy" on so many stocks?
You mean because Simon Thompson recommends "buy" on so many stocks?
For me it's more that he constantly recycles the same stocks, Venture Life, Inspiration Healthcare, Watkin Jones, MTI Wireless Edge, etc etc. On these, he's right half the time and horribly wrong half the time.
Yes
No he doesn’t say that every day and he is correct. Rates are climbing day by day and one of these days they will have to fall; and they will only fall if there is a 25-35% correction in the US stock markets (that usually means small caps , as they are illiquid , will definitely fall more).
Perhaps 20000-22000 on the Dow Jones will help rates to fall at levels that will make this massive government debt manageable (together with some hard austerity measures).
IMHO opinion as well and after I had my head examined.
PS. 7-8 billion are parked in money markets now with the leader being Blackrock!
That’s trillions , sorry
No he doesn’t say that every day and he is correct. Rates are climbing day by day and one of these days they will have to fall; and they will only fall if there is a 25-35% correction in the US stock markets (that usually means small caps , as they are illiquid , will definitely fall more).
The guy is unrelentingly bearish. He is a stuck record. He’s been wrong for so long, one day he will be right. You write with great certainty and conviction. No-one knows the future. Those that try to predict it, even though they have extremely poor track records, like John Authers, are fools.
"The guy is unrelentingly bearish. He is a stuck record."
Are you sure you're not confusing him with Dr John Hussman, PhD? I wouldn't call John Authers a perma-bear by any stretch of the imagination.
Are you sure you're not confusing him with Dr John Hussman, PhD? I wouldn't call John Authers a perma-bear by any stretch of the imagination.
No confusion. If you can provide a link to the last bullish article he wrote I’ll take it back. He’s a financial journalist with no track record in the stock market. Never had to earn a living from the stock market. Probably has his life savings in used ten pound notes stashed under his bed. Why would anyone listen to him?
This is what successful investing is all about-we predict the future!
I am not bearish as I never shorted stocks in my life , although I have followed and many that have and still doing it with great success. I am in fact most of the times bullish as the markets always find the way to go forward.
Unfortunately, this time is so different as the US government debt is 123% to GDP. I will not go in detail , but people with knowledge and experience in bonds understand very very well what’s going to happen (in the bond market and in the stock market).
This is what successful investing is all about-we predict the future!
Actually, being able to predict the future is not a pre-requisite for being a successful stock market investor. Someone that just dumped a few hundred quid a month into an S&P500 ETF for the past 20 years and got on with their life has probably done better than a lot of readers here without having to pick their way through the many UK small cap blow ups, or for that matter, caring what interest rates and bond yields are doing.
I think we often fool ourselves that all the time and effort we spend analysing poxy little UK companies is worthwhile. It’s not the lowest risk or easiest way to make money from stock market investing.
Doesn't he say something similar every day, 365 times a year?
Apart from the fact he’s allowed weekends off with some additional holidays, no he does not. He can only try and comment on the markets as they are and not how he or others might like them to be. You’ll also find he frequently refers to work from others, even those with differing views.
I have a second cataract op next week – I’ll ask them to check the rest of my head whilst they’re at it.
Fully agree with you on this one Jim - I'd say John Authers is pretty balanced and generally gives both the bull and bear cases. His daily email provides a very good overview of the key macro points.
This is exactly what will happen as governments cannot keep borrowing at current levels.
Tortilla Mexican Grill (LON:MEX) : Interim results earlier in the week & the CEO +FD did a presentation yesterday evening on their strategy. It's on Investor meets company https://www.investormeetcompan... looks like you need to register to view. As a holder, I was reasonably happy with what they said - it feels like the focus is on growth as opposed to short term profitability..so perhaps a slow burner
The InvestorMeetCompany presentation are usually put up on YouTube a day or two later, so you don't need to register unless you want to watch them live.
My morning smallcap tweet: Blood, sweat and jeers
Motorpoint (LON:MOTR) Crimson Tide (LON:TIDE) Eden Research (LON:EDEN) £MXCY Ramsdens Holdings (LON:RFX) Tavistock Investments (LON:TAVI) RM (LON:RM.) Trufin (LON:TRU), Victorian Plumbing (LON:VIC), Cyanconnode Holdings (LON:CYAN)
◄Motorpoint (MOTR)► guides H1-Sep U/L pretax loss £3.7m with Q2 much improved on Q1. No rev figure! Rev counter an optional extra I suppose. "We anticipate used values will gradually align to historic levels." [SP=88 Cap=79m]
◄Crimson Tide (TIDE)► 100:1 consolidation. It will "enhance the perception of the Company and its prospects". Won't look so tinpot with a SP over a quid will it? [SP=1.4 Cap=9m]
◄Eden Research (EDEN)► finally completes placing announced on 28 July. [SP=4.66 Cap=19m]
◄MaxCyte (MXCY)► guides Q3 rev down 25-27% "due to continued reduced customer activity". Warns FY-Dec rev only $34-36m. F/C on Stocko' $45.1m Still expects YE cash c. $200m. [SP=NA Cap=NA]
◄Ramsdens (RFX)► guides FY-Sep pretax over £10m (£8.4m). In line? Throw me a frickin' bone here. [SP=195 Cap=62m]. I hold.
◄Tavistock Investments (TAVI)► first 5 months gross rev up 19%. EBITDA £1.6m (-£0.14m), apparently a 13 fold rise. How daft to divide one metric by a small negative comnparator. [SP=4.62 Cap=26m]
◄RM (RM.)► sells an additional portion of Internet Protocol v4 to Hilco Streambank for $2.2m. [SP=59 Cap=49m]
◄TruFin (TRU)► has completed the announced sale of holding in Vertus Capital for £3.2m. [SP=65 Cap=69m]
In line: VIC, CYAN
Your 'Throw me a frickin' bone here' re Ramsdens made me laugh out loud MrContrarian, we hold too and for once I managed to get my timing right with a few more yesterday.
Also Motorpoint (LON:MOTR) "Rev counter an optional extra" MrC is on fire this morning!
Off-piste on the SCVR but relevent to Sunak's postion on the smoking of tobacco in the UK is todays statement by Imperial Brands (LON:IMB) on the RNS, it's optimistic. I hold.
The markets are indeed grim but for context within the latest production report from Ferrexpo (LON:FXPO) : “It is with great sadness that I must announce that 33 of our employees serving
in the Ukrainian Armed Forces have died. Each of these brave soldiers has their own story, over half of them had partners, half of them children. “
Bloody tragic ... we helped several Ukrainian refugees from Zaporizhzhia find hosts in the Cairngorms where I live and my wife and I hosted a mum and daughter for just over 12 months .... they are in Glasgow now, where the youngster has secured a place at Glasgow University after a year in the local school. Other refugees we work with have lost brothers and fathers on the front line. I think a lot of people in Western Europe do not understand this is an existential fight for Western values (and yes, I am well aware how corrupt Ukraine is). If the Ukrainians don't prevail, our sons and daughters will be fighting in the years to come.
There’s a lot of “war fatigue” creeping in and being couched in terms of Ukraine’s perceived corruption or even their chequered history re WWII and also the elections back just before Russia’s Crimea annexation, but whatever way you look at it, Finland, Norway, Sweden and all the Baltic states are shaking in their boots and making preparations for what might happen after Ukraine if Russia win. These countries know far more about their neighbour and it’s behaviour and we should sit up and pay attention. Putin must be stopped in Ukraine as sure as eggs is eggs he will go farther if left to do so.
Also worry about Taiwan. If your economy is doing poorly then nothing like a war to stop revolutions.
Ramsdens Holdings (LON:RFX) gets hammered down yesterday, and today reports record profits. Echos Paul's point about share prices going down but trading statements are still good...
Yes, like Paul said, there are some amazing opportunities on offer for the brave...
"Be fearful when others are greedy and be greedy only when others are fearful".
Is now the time to be greedy?? There's $64m riding on the answer.........
The Ramsdens Holdings (LON:RFX) statement is at least two days earlier than the corresponding date for any year of the last five years. Steadying the ship? See also Mr Contrarians note.
Re Ramsdens Holdings (LON:RFX) I read some time ago that the fortunes of the business were likely to suffer because of the dependency on sales of high value watches. As such its fortunes were likely to follow thse of Watches of Switzerland (LON:WOSG) whose shares are dawn over 50% fro the year high, and Ramsdens Holdings (LON:RFX) dawn around 30%.
Clearly Ramsdens Holdings (LON:RFX) has a much broader model than Watches of Switzerland (LON:WOSG) but the mud seems t have stuck. From a position earlier in the year of modest double digit profit, I am now in the red with Ramsdens Holdings (LON:RFX) and I'm clearly not happy about that. Given the rise in Corp Tax coming up, I dont see Ramsdens Holdings (LON:RFX) as a big buy, but I think they justify a better SP than currently.
I wouldn't read too much into the Watches of Switzerland (LON:WOSG) sell-off. Firstly, luxury watches makes up only a small part of Ramsdens Holdings (LON:RFX) business - they also do pawnbroking, travel money and other jewellery amongst other things. Secondly, a big driver of the WOSG sell-off was the news that Rolex were buying Bucherer and could potentially look to sell direct - this would clearly be very bad for WOSG, but not really affect Ramsdens who sell second hand. I think the RFX sell-off is just part of the general small cap sell-off, with no doubt a forced seller driving down the price. I've been topping up anyway