Small Cap Value Report (Thu 6 Aug 2020) - JOUL, DLAR, FUL, HMSO, D4T4, DPP, WHR

Good morning, it's Paul here with Thursday's SCVR.
Please see the header above for company announcements I'll be reviewing today.
Comments section - I don't moderate the comments, that's done at Stockopedia HQ. They're a lot more lenient than I would be. This is not an advfn or LSE free-for-all, we like to keep the comments here courteous & constructive. If someone else posts something idiotic, please just ignore it. Replying tends to start off an unwelcome chain reaction. Many thanks.
Estimated timings - I got bogged down in JOUL, so will carry on until about 3-4pm to cover everything else.
Update at about 16:40 - today's report is now finished.
.
Joules (LON:JOUL)
Share price: 98p (up 4% today, at 08:57)
No. shares: 108.1m
Market cap: £105.9m
Annual Results for the 53-week period ending 31 May 2020
Established in Britain by Tom Joule three decades ago, Joules is a premium lifestyle brand with an authentic heritage... a true multi-channel lifestyle brand; its products are available through its e-commerce websites, retail stores, at rural shows and events and wholesale channels both in the UK and internationally....
Joules carefully designs and sells clothing, footwear and accessories for women, men and children. The business also sells ever-growing collections of homeware, eyewear and lifestyle product ranges through both its licensing partnerships and 'Friends of Joules', the brand's online marketplace that brings together hundreds of creative businesses to give customers everything they could ever need for a contemporary country lifestyle.
Background - This is an interesting share to me (no current position) because it sells about half of its product online. Next (LON:NXT) showed us how this is the way to go. Next is a rare success story in retailing, because it migrated so much business online (more than half).
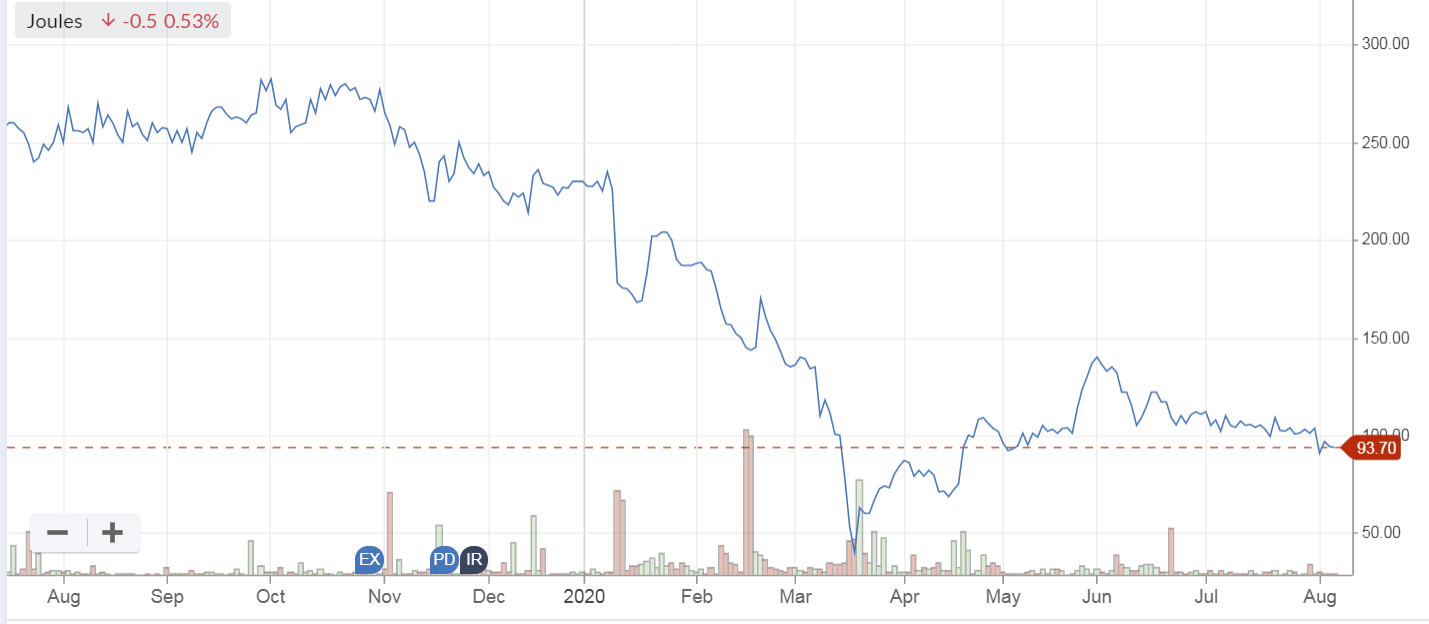
Joules messed up its website distribution, warning on profits (significantly below mkt exps) which I reported on here, on 10 Jan 2020, hitting the share price 21% down to 179p.
Then covid hit of course. It announced a £15m placing, at 80p per share, and £15m extension to bank facilities, which I covered here on 3 April 2020.
The stores had to close, but online trading was described as better than revised expectations. Regular updates have been provided throughout the crisis. All stores closed for lockdown on 23 March, as did most wholesale customers' stores.
Therefore, these results will include over 2 months impact of covid, hence I don't think there will be much use in analysing the figures beyond a brief overview.
The Group recorded a loss before tax, pre-IFRS16 - Leases and exceptional costs, of £2.0 million (FY19: £12.9m profit). The statutory loss before tax for the Period, including the impact of IFRS16 of £1.4 million and exceptional costs of £21.5 million, was a loss of £25.3 million (FY19: £12.9m profit).
Interim results showed an H1 underlying profit before tax of £9.7m (down from £10.7m H1 LY), There is an H1 seasonal bias. Assuming a further fall in H2 trading (because they messed up distribution over Xmas), then I estimate full year profit would have come in around £10-13m without covid.
The actual figure for FY 05/2020 is a loss of £2m, therefore covid seems to have hit profit in H2 by £12-15m, by my rough calculations. That seems a lot, given that the company should have received furlough money to pay staff whilst the shops were shut. Although maybe this isn't all down to covid? The company was reporting challenging UK market conditions prior to covid, plus it had the stock availability internal problems. So we mustn't allow covid to gloss over the existing problems.
Put another way, the placing of £15m has put the company's finances back to where they were, had covid not happened. Any further losses after the 31 May 2020 year end would start denting the balance sheet again.
There's a large exceptional charge of £21.5m, which relates mainly to writing down the leasehold right of use asset, and the book value of fixed assets, for stores which are trading at a loss. These stores will be closed or viable rents renegotiated when break clauses allow.
Dividends - not declaring a final divi for FY 05/2020. Also it does not intend paying dividends in the new financial year, FY 05/2021. Not a share for income seekers then, at least for now.
Outlook - given that FY 05/2020 has been a write-off, partly due to covid, how are things looking now?
... we have performed ahead of the Board's COVID-19 base case since the UK entered lockdown in terms of both trading and the Group's liquidity position.
...The Group's e-commerce channels already represented half of total retail sales prior to the impacts of COVID-19, and we anticipate that this will continue to increase in the years ahead.
This makes me wonder if it really needs the shops at all? Could it become an online only brand in future? How difficult would it be to get out of the shop leases? That could take years.
... more than a third of our portfolio has a lease event within the next 18 months, with an average lease length of less than three years. We will continue to review the appropriate shape of our store portfolio and lease agreements.
That's excellent news. So the company will be able to exit from its stores fairly easily & quickly (3 years is nothing, when trying to dismantle a retail estate). Joules will be able to give each landlord an ultimatum on lease expiry or break clause, naming the (greatly reduced) rent it is prepared to pay, or have the keys back. This is such an important point, it's worth stressing.
There are mixed messages about how the stores are performing since re-opening. In the outlook section it says;
On 15 June we were pleased to commence a phased re-opening of stores after a near three-month period of closure. Whilst it is still early in the process to fully predict to what extent store footfall and sales will recover...
Yet it says something much more positive in the headlines;
Encouraging recent trading reflects the strength of the Joules brand with continued strong e-commerce demand during the UK lockdown Business well positioned to navigate existing and potential COVID-19 challenges:
· Trading performance ahead of management's expectations1 after the first nine weeks of FY21
- E-commerce demand2 up more than 70% on the comparable period in prior year
- All stores now re-opened with overall performance ahead of expectations
- Wholesale performing in line with expectations
The footnote says that management expectations are the base case scenario used in the going concern note.
Also note that "demand" is defined as gross sales, ignoring customer returns, which is imprudent in my view.
Liquidity - this is self-explanatory. Deferred tax & rents are disclosed, which is essential information that all companies must provide, as these are materially boosting cash balances for many companies;
Net cash at the end of the Period was £4.5 million (FY19: £5.8m). Cash balances were £26.2 million (FY19: £16.0m) and Group borrowings were £21.7 million (FY19: £10.2m).
The Group's total liquidity headroom at 31 May 2020 was £52.5 million, comprising £26.2 million cash balances and £26.3 million undrawn committed financing facilities.
To preserve cash and improve the short-term liquidity position in response to COVID-19, the Group agreed the deferral of certain liabilities falling due in the final quarter of the financial year with HMRC and with landlords. At 31 May 2020 the total amount deferred under these arrangements was £6.7 million (FY19: £nil). The Directors anticipate that these amounts will be repaid over the period to May 2021.
Overall then, it looks a healthy liquidity position, providing the bank facilities remain available.
Going concern note - worth reading, as it contains interesting information.
Scenario planning;
Base plan ... It reflects phased store re-openings from mid-June 2020 through to mid-August 2020 with the re-opened stores initially trading significantly below the prior year, improving to 75-80% of the prior year's sales level by the end of FY21, with modest growth thereafter.
As I suspected, the stores are probably trading a long way below prior year at the moment, but this seems to be glossed over in the rest of the narrative.
Downside scenario - the 'Base plan' adjusted to reflect a slower recovery of the Group's stores channel with total store revenues only achieving approximately 60% of the pre-COVID-19 levels by the end of FY21, and a deterioration in the wholesale channel receipts with receivable days more than double the level of FY20.
It also outlines an even more extreme downside case, called the "Stress test scenario", where stores would be closed again due to a second wave, and no Govt support measures were given.
It passes these tests comfortably by the sounds of it;
Under the Downside scenario, the Group has more than £25 million available liquidity headroom through-out the period under consideration and has EBITDA headroom of £2.9 million against its first covenant test arising in the period with headroom increasing further for the second covenant test arising in the period.
The Group would also remain within its borrowing facilities and comply with covenants under the Stress test through this period.
That sounds fine to me. The auditors require this information, in order to sign off the accounts on a going concern basis - the fundamental test is that the Directors can demonstrate that the business can remain solvent for at least 12 months after the signing of the accounts.
Balance sheet - looks OK, but not particularly strong. NAV: £42.3m, less intangibles of £20.5m = NTAV £21.8m.
I wonder if the cumulative £13.8m spent on its new freehold HQ might be a vanity project? Also do people need to come into the office, if work from home becomes a long-term thing?
My opinion - I've spent far too long on this. It's a simple company - designing & selling clothes, but the accounts seem really complicated. After spending a couple of hours going through the figures, I still have absolutely no idea what level of profit or loss that the company might achieve in the current financial year!
Liberum to the rescue, with an update note available on Research Tree. This clarifies a number of things I was unsure about, so it's really helpful.
Forecast EPS has been raised today, from 2.9p to 3.6p - PER of 27.2 - that's high because FY 05/2021 will still have some impact from covid disruption, so I'm relaxed about that.
That rises to 6.8p the following year, pulling the PER down to 14.4 - which looks sensible.
Overall, I think the current price looks about right. Although the impairment charge is called non-cash, my view is that the company is still, in cashflow terms, carrying some heavily loss-making (in cashflow terms) shops, and will have to keep funding those losses until lease expiry/break clause. That's real cash going out of the door, whatever the accounts say. The average lease length may be 3 years, but what if the biggest loss-makers have leases 5 or more years out? Averages can conceal the most important information. Disclosures on leases are absolutely hopeless right now. IFRS16 has made accounts far more difficult to follow, without giving us the key information we actually need - i.e. when do the leases expire on the heaviest loss-making sites?
Long-term, once problem leases have expired, and Joules becomes more & more an online business, then I think it would become an increasingly attractive investment. But there's quite a bit of legwork to be done, to get to that position.
.
.
De La Rue (LON:DLAR)
Share price: 145p (up 4% today, at 11:15)
No. shares: 306.6m
Market cap: £444.6m
This group prints high security things like banknotes, security markings to verify product authenticity (e.g. cigarettes), etc.
I did some research on it earlier this year, and came to the conclusion that it seems to be undergoing a remarkably good turnaround. Last year it was looking a basket case, with poor trading, and a dangerously weak balance sheet. Things are looking very much better now, and it did an equity fundraising at 110p to fix the balance sheet earlier this year. The SFO investigation was closed, making it easier to sleep at night as a shareholder here. Annoyingly, I had to cut a few positions lately to meet a margin call, so it's not currently in my portfolio, but I want to buy back in when spare funds appear from somewhere!
This is what is says today;
The Board's expectations for 2020/21 remain unchanged from the full year results announcement issued on 17 June 2020.
The £100m equity capital raising, which completed on 7 July 2020, will strengthen the Group's balance sheet, enabling De La Rue to deliver the Turnaround Plan and create value for its employees, customers, suppliers and shareholders.
In Currency, De La Rue continues to experience strong demand and has been awarded contracts representing approximately 100% of its available full-year banknote printing capacity for Financial Year 2020/21, an increase on the 80% of capacity announced at its trading update of 1 June 2020.
The first two sections are fine, an in line update, and recap on a fundraising that we already knew about. So nothing price sensitive there.
It's the third paragraph above that I'm scratching my head over. Is this good or bad? It's good that more contracts have been won, but does that now mean customers have to be turned away if they submit new orders? Why is capacity constrained? How much would it cost to increase capacity, and on what timescale?
My opinion - overall then, I'm not sure how to interpret this. What do readers think? I suppose being maxed out from customer demand is a nice problem to have.
From my point of view, the fact that I keep selling this share when I have margin calls, probably means I don't have enough conviction in it to buy back in. I might give my pal a ring, who's researched it to death, and see what he thinks, before buying back in again. I seem to recall some of the excitement was due to other products, like cigarette security features, which apparently is a big growth area.
Sorry this is a bit vague, sometimes I find it very difficult to keep on top of so many companies, and lose the plot a bit.
.
Fulham Shore (LON:FUL)
Share price: 6.75p (up 10% today, at 11:57)
No. shares: 573.6m +36.0m new shares = 609.6m (6.3% expansion of share capital)
Market cap: £41.1m
Trading Update & Proposed Fundraise
This is a restaurant group, mainly "Franco Manca" pizza, also "The Real Greek". Both are excellent casual dining chains, in my view, with an everyday good value pricing model (no discounting or gimmicks).
By the time fundraisings are announced, they're a done deal. I got wind of this fundraising about a week ago, but because I respect the rules on inside information, I kept silent about it here, and everywhere else. It infuriates me when journalists or bloggers discover some inside information, and then broadcast it far & wide. That seems completely wrong to me. I don't like the way fundraisings are done in secret, with the shares continuing to trade, but that's the way the system works. In my view the share should be suspended the moment a fundraising starts, in order to prevent a false market developing, and insider dealing (things inevitably leak) but that's a discussion for another day.
Looking first at today's trading update, my summary of main points;
- Nearly all restaurants now open - early signs "promising"
- Sales rising week on week since re-opening began (4 July)
- Capacity reduced to 60-70% due to social distancing, partly offset by increased delivery & takeaway
- Cost reductions - rent reduction/deferral/waivers
- London sites in West End & City locations - a problem due to absence of customers, won't re-open yet - will impact current year FY 03/2021 performance
- Sharing half the VAT cut with customers. Participating in Eat Out to Help Out scheme - should boost trade
Current trading - key information here. This looks OK to me, given that footfall is well down, and should improve over time, assuming no further lockdowns;
In the four weeks since 6 July 2020, like-for-like restaurant sales at reopened sites were approximately 72 per cent. of the equivalent weeks in the previous year.
.
Fundraising - this is unusual, in that it's only a small equity fundraising, plus a much larger increase in bank facilities.
Equity - 26.14m new placing shares, 9.8m subscription shares for Directors = 35.9m new shares at 6.25p = £2.25m before fees. This looks absolutely fine to me, because the price was a 2% premium, and dilution is very small (share count increased by only 6.3%). As major shareholders, I'm guessing management want as little dilution as possible.
Debt - existing net debt at 5 Aug 2020 was £8.9m (tax/rent deferrals will have helped this figure, so underlying position will be worse). Today it announces;
New £10.75m loan under Govt-backed scheme, CLBILS (repayments due in years 2 & 3)
Existing £15m facilities with HSBC extended from Mar 2021 to Mar 2022, with waiver of certain covenants (probably Net Debt: EBITDA, is my guess, that's usually the key covenant)
These new banking arrangements, together with the Fundraise, will give the Company substantial headroom of at least £18 million over its current net debt.
That's really good in my view - that the bank is extending the existing facilities, as well as the Govt-guaranteed facility in addition, and only a small equity raise was needed to secure this, demonstrates an excellent bank relationship.
These facilities are well above what's needed for survival, so it primes the pumps for continued expansion. The deals likely to be available from landlords, could be outstanding. So paradoxically, this is an excellent time to be expanding.
My opinion - I've long been positive about this group. It's well managed, and has a genuinely good, and differentiated, value for money offering. This fundraising involves little dilution, and provides plenty of firepower to get through this crisis, and fund renewed expansion.
BUT, is this the best place for my money? I'm not sure it is. FUL is definitely going to survive, in my view. But there's also likely to be renewed competition once weaker players have left the market, and the empty sites are refreshed under new owners, operating under long rent-free periods, and low rents. As sector expert Mark Brumby of Langton Capital points out, it takes many years for capacity to actually disappear, since a closed restaurant becomes a new restaurant usually. I saw evidence of that last night when wandering around Bournemouth - one tatty old cafe was having a sleek new fascia installed, and is to become a Thai restaurant. Likely to be on a dirt-cheap rent & long rent-free.
Overall then, I like the business with FUL, but am not convinced the shares have enough upside to tempt me back in.
.
Hammerson (LON:HMSO)
Share price: 49.4p (down 12% today, at 14:30)
No. shares: 766.3m
Market cap: £378.6m
Proposed Rights Issue & Disposal
I mentioned this company on Monday, when it put out a statement saying that it was in advanced stages of a property disposal, was considering a rights issue, and approved for a £300m CCFF loan. Plus rent collection was improving, but still very poor.
Today's update confirms £274m is being raised from disposing of most of its c.50% VIA Outlets stake (at an 18.7% discount to book value) - not completing until Q4 2020, due to regulatory approvals required abroad.
Plus a bombshell announcement of a huge £552m Rights Issue - almost 1.5 times the current market cap.
That's a total cash raise of £825m.
Key points summary;
2 largest shareholders (34% combined) are supportive, taking up their full rights
More property disposals planned when markets stabilise
More flexible lease structure for tenants planned - sounds interesting
All proceeds will reduce net debt, to £2.2bn pro forma 30 June 2020
Share consolidation - 1 for 5 - so 766.3m existing shares would become 153.3m new shares, with the share price theoretically rising from 49.4p to 247p per consolidated share, and the market cap therefore unchanged
Rights Issue - a staggering 24 new consolidated shares for each existing 1 consolidated share!
Issue price - is 15p for new consolidated shares, or 3p in old money. That's a discount of nearly 95% to last night's closing price. Therefore this deal values the existing share capital at just £23m. Why hasn't the share price today collapsed completely then? The idea is that the Rights shares should be worth more than 15p - the theoretical ex-rights price is said to be 25.59p - i.e. shareholders get almost wiped out on their existing shares, but can take up or sell their Rights entitlement at a profit. In theory. It's a strategy to force everyone to take up their Rights. But over time, the 25.6p new share price could continue drifting down, nobody knows. The bottom line for me, is that this deal values existing equity at practically nothing, which is not good.
Half Year Report - no cash divis, but intends to pay divis in scrip form (new shares, not cash), in order to maintain REIT status - an interesting point, which has read-across for other REITs.
New leases - I'd like to hear more detail on this, but sounds like HMSO might be moving towards turnover rent style deals? It's good to hear that HMSO recognises the new reality, that major structural changes are needed in retailing property sector;
"The pandemic has exacerbated structural shifts in retail, exerting further pressure on both property owners and brands, and provided further evidence that the UK's historic leasing model has served its time. It is outdated, inflexible and needs to change.
We are introducing a new UK leasing approach - one that is simpler, reflects an omnichannel retail environment and rewards positive performance on both sides. It will deliver a sustainable, growing income stream and we are in initial discussions with retailers and anticipate introducing the first of the new leases later this year."
That's great, and very much needed, but there's no escaping that this is likely to hit capital values hard, hence potentially major writedowns are likely for HMSO (and all others in the sector) balance sheet property values.
The current operating stats are actually better than I expected;
Half year operational overview
Occupancy: Continued high level of Group occupancy at 94% (FY 2019: 97%); UK flagships 93%; French flagships 94%; Ireland flagships 96%; Premium outlets 93%
Rent collection: As at 31 July 2020, 72% of H1 2020 rent had been collected for the Group, with 34% of Q3 rent due collected. Average rental waiver of 1.1 months and deferral of 0.8 months during Covid-19 closures
Tenant restructuring: During the six months to the 30 June 2020, 36 of the Group's tenants have entered administration or undertaken a CVA affecting 88 units (out of 2,886 units across the Group) of which 49 continue to trade
... in recent weeks we have seen an encouraging increase in footfall as confidence begins to return amongst visitors to our flagship destinations.
My opinion - I've gone as far as I can with this. The problem is that, without a crystal ball to see into the future, it's impossible to know how much Hammerson's properties might be worth, once the dust has settled, and new lease arrangements are brought in. That will takes years, because HMSO is obviously going to continue collecting in the rent from solvent tenants, then only negotiate a new lease when the old one expires. Hence the reported figures are always likely to lag behind reality, and over-state property values on the balance sheet.
Clearly today's big fundraising will shore up the balance sheet. The major shareholders are standing their corner, but private investors don't have to. Even if covid is cured, there's still the ongoing problem of retail sales moving online. The only solution to that is for rents for physical retail space to be much, much cheaper, so that tenants can make a profit on reduced sales. Hence capital values are likely to keep falling, putting ongoing strain on HMSO's balance sheet.
It's the most shorted share on the market, with around 14% short interest. Earlier this year there was a fantastic trade on the big short squeeze. Maybe that might happen again? A covid cure could send the share a lot higher, potentially?
On balance, I can't conclude anything other than: impossible to value, hence I'm neutral.
.
D4t4 Solutions (LON:D4T4)
Share price: 232p (up c.3% today, at 15:37)
No. shares: 40.2m
Market cap: £93.3m
I keep an eye on this share, because it's in my "looks interesting, but I don't really understand what it does" tray!
D4t4 Solutions Plc (AIM: D4T4, "the Group", "D4t4"), the AIM-listed data solutions provider, provides the following update ahead of its Annual General Meeting at 9.30am today.
It sounds in line, so nothing price sensitive today;
The Group continues to trade in line with the Board's expectations, with strong levels of both existing and new client activity.
D4t4 continues to make good progress towards transitioning to a recurring revenue model, with a focus on securing new contracts and transitioning existing customers from perpetual to term licences.
Not bad, considering the macro backdrop.
I seem to recall a subscriber here made a good point last time we looked at this share, pointing out that the transition to SaaS is understating the underlying profitability. Meaning that the shares might be too cheap maybe?
My opinion - sounds reassuring. I'll keep it on my watchlist. What do subscribers think? Informed views welcomed, as always.
.
Dp Poland (LON:DPP)
Share price: 7.25p (suspended this morning)
No. shares: 254.0m
Market cap: £18.4m
Possible Transaction & Suspension
Subject to regulatory approval, they're looking at using DPP's listing to do a reverse takeover of another Polish pizza company, called Dominium S.A.. Its largest shareholder is Accession Mezzanine Capital III L.P.. Googling that, shows it's a Jersey based partnership, sounds like private equity maybe?
The Directors believe the potential Acquisition will create a superior restaurant group with greater scale and to utilise the anticipated synergies which are expected to be presented upon a combination of both businesses under the Domino's brand.
Well, it can't be much worse than DPP! I've spent years pointing out what a rubbish business DPP is - constantly loss-making, losses don't reduce as it expands, i.e. rolling out an unsuccessful format. Constant fundraisings. Constant failure to meet J-shaped forecasts. It's a terrible, badly-run business, which is not viable in its current form. But every few years, a fresh bunch of optimists come forward and put more money in.
I'll be interested to read the admission document for the enlarged business. I'd say the main risk is that Accession might be seeking to find an exit route, using DPP's listing?
Pizza is ubiquitous in Poland. I've been there often, and people tell me that Dominoes pizza is good, but too expensive. If this deal goes through, maybe the new owners can lick it into shape?
Let's wait to see what the deal looks like.
Warehouse Reit (LON:WHR)
Just a quick comment, as I've run out of time.
I've mentioned this smallish REIT before, which specialises in buying & renting out warehouses. It's a much safer proposition than trying to work out if a retailing REIT is a bargain, or bust.
Good divis are available from WHR;
Warehouse REIT, the AIM-listed company that invests in and manages e-commerce urban and last-mile industrial warehouse assets in strategic locations in the UK, today provides a business update including Q3 rent collection and progress on its investment pipeline following its successful £153 million equity raise in July. The Company also reaffirms its first quarter dividend payment of 1.55 pence, payable on 2 October 2020, reflecting an attractive annual equivalent dividend payment of 6.2 pence per share.
Rent collection - pretty good, but not quite as strong as I was expecting. This is like chalk & cheese compared with struggling retailing site owners though;
As at 30 July 2020, 94% of contracted rent due on the June 2020 quarter date had been received or is being collected monthly, with ongoing discussions continuing for the balance. The Company is taking a proactive approach towards collecting rent and has agreed to monthly in advance payments amounting to 27% of the contracted rent, of which, 60% has already been received.
Various other details are given.
I don't hold myself, but this share is on my list of good stuff. Hence worth flagging up to readers here, as something you might want to look at, doing your own research. I haven't looked at any other REITs, so cannot compare it with peers.
Time for a lie-down in the sun, methinks!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
I agree with jonthetourist comments. D4t4 Solutions (LON:D4T4) is transitioning from a classic "fixed price" model to a modern/fully integrated SaaS offering a fuller suite of service to clients (more committment + recurring revenue). Data and Digital transformation are a great combination. They work direct and via resellers (good as long as those partners reflect the same quality of service). Their latest version includes ML and NLP capabilities. Lets see if this has a positive impact on their margins (which at 22+ already reflects a niche positioning). A couple of concerns are their past reliance on 1 big, key client (still the case?) and Stocko's m-score rating (earnings manipulation). On a PE of just over 20, there's still some value to be had.
PS; I am not a holder but used to work in a similar software service industry.
Hope this helps!
Hi Paul,
Re: £D4T4
A couple of video which may be of interest. A short video (6 mins) explaining what Celebrus ( £D4T4 main product) tries to do
D4T4 - Creative Visualisation: Homeowner - December 2018
A longer (52 mins) demo of Celebrus
Celebrus v9.2 WebCast
Hi Paul
You asked for feedback on D4T4 and haven't had any, so I will have a go. All imho.
Way back at Pilot your marketing / merchandising people would have had feedback from stores (I imagine) over and above the actual sales numbers. E.g. lots of people trying item x but complaining about the fit, asking if it's available in colour A or B etc.
D4T4 's aim is to not only give this sort of feedback, but respond to it in real time in what is presented to the browsing online potential client, to maximise sales outcome. So the client gets both better market intelligence, and a higher revenue per site visit.
This software solution had been selling well on a classic sale and support contract basis. Transitioning to an annual contract substantially reduces the revenue in year one, but increases it in every subsequent year. Having chaired a software house myself, I think that counter-intuitively Saas is a better quality sale. The client spends less upfront, but is fully aware they are committing to an expensive long-term relationship. Regardless, during the period of transition revenues will be artificially depressed as a reflection of trading.
Very Janet and John overview, but hopefully helpful to some.
All the best
Jon
Slightly bizarrely, at 14:10, Jarvis Securities (LON:JIM) issued an RNS mistakenly titled "Director Declaration". In fact, its a dividend declaration, for a 3rd quarterly dividend of 14p, ex-div on 20-Aug-20.
https://www.investegate.co.uk/jarvis-securities--jim-/rns/director-declaration/202008061410294049V/
Given the completely matter of fact wording, it sounds like this may set a new benchmark for JIM's quarterly dividends. In contrast, the last dividend, which was 11p came with caveats making it sound like we should not expect the same going forward.
Extrapolating, which may not be valid, this implies an annual dividend of 56p, or over 8% at the current SP of £6.60.
I suspect something has to give here as, if this is a sustainable dividend, the SP is currently too low IMHO.
N.B. I'm definitely biased as this is my second largest holding
absolute belter this year up 45% this year without divi included
Thanks Shanks. Been expecting a divi declaration but disregarded the rns titled Director Declaration. World aint get any easier
Can anyone let me know please, if there is any way of finding out when the upcoming results of AGM's are due out? I know how to find out when trading statements/results are due out, as there are lists published, but i noticed that Paul has reported on DLAR today, which was an AGM statement and these don't seem to be included in the list.
Many of us get our company news flow from investgate.co.uk. If you look at the list on this site for DLAR you will see there was a notice of DLAR's AGM published on 13 July. This website is extremely useful and can be used to only list the news of companies you are interestred in.
Re Intelligent Ultrasound epic should have been MED
Hi PUG!
I've had a quick look at Intelligent Ultrasound (LON:MED) interims , but am not enthused to want to dig any deeper, it looks too speculative, and I don't have the expertise to guess whether its loss-making operations would eventually move into profit or not?
The StockReport shows a sea of red, with revenues rising from £1.8m to £6m over the last 5 years, but multi-million (rising) losses over that period too.
On the upside, it's now got pots of cash after a recent fundraising.
Today's update says it's aiming for profitability next year. I wish them well, but there's nothing I can add, as I know nothing about its products, hence no idea about its future prospects.
Hence I can't add anything more, looks like something for investors with the specialist knowledge to determine what its future prospects are.
Sorry about that , Paul.
Thanks Paul - Agree re cash - As current main revenue comes from selling training modules - one off capital purchase - depends very much on degree of market penetration still available - plus development of new modules for different applications - However as Ultrasound probably the most used primary scanning technique world wide thre are a lot of technicians who could find update training useful
The AI tools being developed should aid the technicians in their performing ultrasound scans and hence corporate revenue but revenue looks as a though dependent on OEM's installing the software on royalty basis. Revenue here is I suspect likely to depend on how many OEM's chose to adopt and the terms of the licence/royalty agreements - No details that I have as yet been able to uncover.
However very much under the radar subject to a short Covid related jump on news that some of the tools could be useful in interpreting scans of patients' lungs.
Intelligent Ultrasound IEH - Any thoughts on today's interim?
Sorry this is a bit vague, sometimes I find it very difficult to keep on top of so many companies, and lose the plot a bit.
I didn't know there was a plot. Could someone please give me a copy of it?
I would think De La Rue being maxed out is a good problem to have. As with all problems though it is, in my opinion how it is dealt with that will be telling.
Hi Paul, will you have time to look at the delayed McColl's (LON:MCLS) interim results? They came out this morning (delayed by 3 weeks or so). You looked at them on Feb 26th. Do you think things have improved significantly? Thanks, Simon
Hi spglet,
I probably won't get round to looking at Mccoll's Retail (LON:MCLS) - mainly because I think it's a moribund business. No reason for it to exist, and its balance sheet looks wobbly. Unless there's a major turnaround happening, then I probably won't look at it again. It's better to focus my limited time/energy on stuff that seems to have more promise.
Sorry about that.
Regards, Paul.
Thanks the reply Paul. I understand.
Hi Paul, I wonder if you could look into Gamesys, I've noticed it's on a 52 week breakout and results are due Tuesday, they have debt but are forecasted £127m and £146m net profit in 2020 and 2021? also over dinner Gym Group (GYM) came into discussion, seems to be on the move, could it be a recovery play?
I only comment on the day's results & trading updates (and sometimes fundraisings), usually within a band of market caps £10m - 400m.
Gamesys is over £1bn market cap, so well outside my scope. The idea is that I cover stuff which is usually overlooked elsewhere.
I don't know anything about Gamesys, but the Stockopedia stats look attractively cheap, and as you say, the chart is breaking out. So it could be an interesting one for readers to research.
Regards, Paul.
I see Sos have had a little run of late. Given we are all expecting a cash raise this is quite positive I would have thought. Question for the company is do you do it sooner or risk later?
Good point R-G. I hadn’t spotted that and was surprised the update hadn’t given the share a lift.
Like you I’m looking forward to Paul’s update as their last update looked so promising.
Also Dan’s updates and Mr Contrarian’s are superb, and on their own would make the comments section well worth reading. Also agree with Paul’s comments about declining quality of some of the posts here, and hope Stockopedia will be more ruthless in removing “idiot” ones, as otherwise quality posters, who add so much to the comments section, will not bother.
I wouldn't hold your breath about moderation. There are three identical threads by someone ramping a small mining share. Have reported them but they are still up...
https://www.stockopedia.com/co...
https://www.stockopedia.com/co...
https://www.stockopedia.com/co...
Its the sort of thing I left the ADVFN for and came here to avoid...
Immotion (LON:IMMO) now this looks to be an interesting play potentially ripe for recovery but with a new twist that could be lucrative.
They focus on immersive entertainment - mainly for VR. They partner with the likes of aquariums/theme parks who have high footfall where they get a cut of the revenue generated. The parks like them because it is free to them to have the installation - thus is a free source of extra revenue.
All was going well prior to covid shutting the world down of course. Just into profitability. Big flagship project at Shark Reef at Mandalay Bay in Las Vegas in process of install. Then came shutdown and no tourism etc etc.
But recent trading updates are highly encouraging. Apparently footfall is recovering and revenues are good. The Las Vegas install has gone live and terms changed that are favourable to Immotion (LON:IMMO) for revenues. Even at the reduced footfall due to distancing measures this install alone is apparently on track to generate £100k+ p/m of revenue. So at current price looks like in the absence of another shut down business is looking good again.
However, todays update intrigued me..........and I think there might be some strong value here.
Immotion (LON:IMMO) have developed a purpose built rapid UV cleaning cabinet for their headsets. They understood at the outset of the pandemic that safe cleaning of headsets was vital if you wanted customers to return to VR immersive entertainment. They also understood that this had to be super rapid else the turnaround (and queues) would be too long.
So the cabinets they have developed clean microphones, laptops, speakers, phones, headsets, even clothes etc (all stuff alcohol based cleaners shouldn't be used on) with UV........but Fast......A cleaning cycle takes between 3 to 10 minutes (dependent on the number of devices and object surface complexity) and can sanitise up to 100 phones, 50 tablets or 30 VR headsets in a single cycle and it can also charge electronic devices at the same time.
Having announced this they go on to say they've seen extraordinary demand and sold 10 of these new units in the last week alone. Chichester Uni bought 4 cabinets for student safety so this as an example shows the potential appears vast. Units cost an average of £2800 each.
So the core business is ok and looks well on its way back to breakeven. The market cap is £12m so really small.
Let's assume margin on a unit is 30% so anticipate £840 profit per unit. This could be really interesting piece of kit sold globally to all sorts of institutions. None of that potential is in the current price by the looks of things. I was long before I realised the potential of this cleaning kit - only question now is do I add more........ I'm not sure the market has picked up on this.
Looks interesting but have done a search and can see there are other UV cleaning solutions out there so wondering what makes Immotion’s one special?
I presume it is because it is specifically designed for the likes of laptops, phones, VR headsets etc where you get very rapid charging at the same time.
Not particularly bothered about competition personally. This is a sideline for Immotion (LON:IMMO) but if they are seeing extraordinary demand for it then that suggests nothing better out there right now. They don't have to own the market in UV cleaning, just take some of it to make a very meaningful contribution. It could be applied to millions of venues worldwide so plenty to go after. Think Unis, schools, theme parks, conference venues etc but also something like Bowling alleys for example.
What is interesting here is that there is nothing baked in to the share price for this. The whole thesis of investing in Immotion (LON:IMMO) is around the VR content. So this is just in there for free. Usually anything Covid solving gets the market very excited and share prices get too high too quickly, so of course the risk is investing at the top of something that may or may not work. This seems to have completely passed the market by and I do wonder if there could be a meaningful re-rating at some point.
I have a reasonable chunk but haven't bought any more yet, though I have to admit I am tempted. Risk/reward looks decent to me as this new element to the business actually hedges against a second wave shutting down some of their VR sites.
The gross margin per unit is more like 80%
£DLAR In one single sentence the management are telling the world they have no spare capacity to grow?
De La Rue says has contracts for 100% of 2020/21 currency printing capacity
Looking forward to Paul's and communities comments.
I do not hold but it is on my watchlist.
Also on my watchlist. Slightly reluctant to pay 31p over the price of the placing though.
I think currency printing capacity was cut as part of turnaround so this is 100% of a reduced amount. Was previously over 80% anyway so whilst clearly a good thing, not earth shattering from previous update. Price has gone up 10% over last few days so suspect this is already in the price especially as management do say that expectations are same as when they did the placing and gave last update.
That said I'd like to buy some just not quite at this level. will hope for a pullback.
DLAR...I hold from the placing. The year high is 235.5p and I admit I am impressed by the change in fortune. I would guess the results will be better than expected and directors are being a bit coy. So much business "in the bag" means they can build even more profitable turnover. I can see these back well above 200p this year and I struggle to see much downside myself but thats just my opinion.
Good morning Paul
In full agreement with your comments.
Moving on to this morning's RNS, Tt Electronics (LON:TTG) has released what are in my view reasonably positive interims. Although like most companies, trading has been impacted by the pandemic, it has stated its intention to reinstate the dividend at the time of the prelims. Your views on Tt Electronics (LON:TTG) would be appreciated, time permitting. The business has similarities to Volex (LON:VLX), which has continued to trade comparatively well.
All the best
Interested in your views on Joules, my wife keeps buying their stuff online and when we popped to the local store we had to queue outside due to the numbers of customers. Seems to have been less impacted by COVID-19 than many retailers, not sure on future growth prospects and if it's brand will translate so well internationally?
I posted yesterday about gold/silver and mining stocks which are booming at the moment based on sound fundamentals. It wasn't well written for which I apologised and I got a couple of negative messages. However, I got more positive than negative. Paul clearly things my post was idiotic. I don't think pointing out opportunities elsewhere is idiotic. It wasn't ramping, I don't think the global gold price is going to be influenced by a few Stockopedia subscribers! I actually think it is idiotic to not be looking at other sectors at the moment. Anyway as I said no offence was intended, a different point of view seems to be jumped on by the masses these days and seems like it's not allowed whatever the subject. Welcome to the UK in 2020!!
Morning Lee,
Hope you are well. Good way to sell It mate, would be referring to gains in Sylvania Platinum (LON:SLP) or £CAML. Both mining companies in the small cap area. They’ve done well in the last month. Anyways just an idea/compromise.
Cheers!
Can't see your comments from yesterday as Stockopedia seem to have deemed them too controversial for some reason. Too many purists on here who think they own the discussion. No harm in mentioning gold as part of macro discussion and it is good sense to be in gold now whether through small caps or not.
I deleted it as it was deemed idiotic (i.e. different !!)
Lee - it is more that this particular small cap report has always been Resource sector free. That is partly because Paul doesn't believe he has any expertise in the area nor any interest and therefore isn't going to write about it, but also because it is an area of the market that can get heavily ramped. That doesn't mean to say investors shouldn't be looking at the resource sector right now. My personal view is you'd be mad not to have any exposure to gold/silver even if you only keep it as a hedge from the world going further to sh**. However, this is not the forum for resource companies to be discussed, though perhaps there should be a separate one.
That is a shame as there are plenty of small cap UK resource companies that have great prospects.
Morning Lee - Perhaps it needs an interested champion to take on Natural resources (1 -Miners even 2 - Oil&Gas?), Pharma's is also an area Paul is honest to say he lacks experience in, there's another special interest. Seems one size (Small Cap) may not fit all!
If Championed then they ought to have a new "Focused" Thread and audience - Any takers rather than detractors Thumbs at the ready people?
Hi Lee,
Most of my recent gains have come from gold and silver, both miners and physical ETFs. I’m sure there are others here in the same position.
Maybe you should start a separate Stockopedia discussion thread on the topic as the degree of overlap with U.K. small caps is not great and Paul’s interest in analysing the sector is zero? I would be happy to join in there.
Jack recently wrote an interesting post, about gold miners with clear catalysts, that attracted some interesting comments.
Lee, I didn't even read your post! You had removed it by the time I read the comments section, so please don't put words into my mouth!
For clarity, I don't have any problem with people discussing mining shares if they want to. Just stop bickering with each other!!! It's incredibly boring.
If anyone is interested in gold mining companies John Cornford over at Master Investor does a good analysis:
https://masterinvestor.co.uk/author/john-cornford/
Lee - I think one of the problems is that this particular thread - the daily SCVR, which has not covered mining/oil & gas stocks, has become so popular that some people think it is the only place to comment on anything, for example large caps.
I very much enjoyed matylda's I Read The News Today Oh Boy! until a break was taken last November for parental duties.
That showed that not everything has to be in this thread, so there is nothing to stop you starting a daily resources thread.
Ok thanks I have started one called Gold and Silver Mining Stocks.
Fulcrum Utility Services (LON:FCRM)
Looking through their results for the Y/E 31/3/20 I came across:-
"Outlook
· Despite the impact of COVID-19, trading in the new financial year has seen continual improvement month on month and is expected to return to pre-COVID-19 levels in Q2 of FY21
· Given the ongoing market uncertainties resulting from COVID-19, the Board will not be issuing guidance for the Group's 2021 financial year at this time
· In the longer term, the Group is well placed to execute its strategy and capitalise on the UK's net-zero and smart energy revolution"
To me their second point is totally incompatible with their first point. In fact not giving guidance after saying they are expecting a return to normality in Q2 makes me wonder about the quality/competence of the BoD.
Noticed quite a few companies still using the cop-out of CV19 when,in my view, we are at the stage where this is no longer acceptable.
Contrast this with Morgan Sindall (LON:MGNS) yesterday:-
"· Improved visibility of the second half and full year outturn
o Guidance for the full year reinstated. FY 2020 profit before tax expected to be in the range of £50m-£60m
o Intention to return all payments received under the Coronavirus Job Retention Scheme during the second half"
Might have something to do with the recovery in their SP.
Phil
(No position in either company)
£FCRM. CEO, CFO and much of the Board only joined within the last year - not surprised they have no idea what's going to happen. Much play on the size of the order book, bright newcomers, and growth prospects, but no thanks to staff, and very little on work done. Quite a big holding for me ; bit disappointed, though the future still looks bright, and the cash is OK
Anyone else getting tired of placings at monumental discounts? SAE the latest culprit this morning. Not sure who I blame the most generally, lazy brokers (easy sell) or management. On SAE I mainly blame management, the CEO has been pumping the shares in recent months, if he truly believed in his company’s value he’d have tried harder on the fund raise. More specifically, I think it surely has to be time for the relaxation of the shareholder pre-emption rights up to 20% dilution to stop, companies have had enough time to do emergency Covid placings now IMO.
Having had to do a number of placings before in companies where I was a director I can assure you that the Board try to minimise the dilution, but this is not easy to achieve at the best of times. In the current environment where the future is uncertain, capital is in high demand and many companies are still trading at relatively high valuations, I am surprised how little dilution there is for some companies. The level of dilution generally reflects the quality of the company.
You’re right, I should expect discounts when a small cap does a placing in this environment. Maybe my frustration is partly a practical one, because if I wanted to join in I couldn’t, all my investment money is already in a SIPP or ISA and I can’t spend that even if the issuer is kind enough to use primary bid. When VLS did their recent placing, at least they did an open offer where I could invest from my ISA. Guess it’s just a hazard of the small cap space. I’m thinking more carefully now which company is next.
Interesting, thanks.
Fulham Shore (LON:FUL) fundraising today (I've just finished writing up a section on it) was strikingly good - only about 6% dilution, and price basically flat against the market price (2% premium is well within the bid/offer spread, so really just flat)
FUL has large management shareholdings. This is naturally going to make management averse to dilution. Also some investors such as Lord Lee, and David Stredder, both incredibly astute investors I've known for years, like investing in family-controlled companies long-term, because they tend to be far more prudent in not using excessive (if any) gearing, and avoiding dilution.
Whereas hired hand management with little to no shareholdings, often seem to go on acquisition sprees, funded by debt, in order to drive up EPS and hit their share options target, but often accidentally blow up the company in the process!
FUL fundraising today certainly supports that theory. I should probably focus more on companies where management have a lot of skin in the game, as more reliable long-term guardians of shareholder value. Mark Slater mentioned this point too, in the excellent recent podcast with Tamzin over at PIWorld. I might listen to it again actually, as there were some really good points made.
I wonder if there are any studies about whether long-term performance of shares is affected by management shareholding level?
Regards, Paul.
Thanks Paul. I hadn’t focused on management motives.I feel a bit of a muppet now, the CEO of SAE has only £10k of shares so, even if he no doubt has loads of options, he will be less sensitive to dilution. Argh!!!
"Anyone else getting tired of placings at monumental discounts? SAE the latest culprit this morning."
I'd never heard of SAE until this morning, but from a quick glance at the stockreport...
* It's made a loss in all except one of the last 6 years, and is forcast to continue to be loss making for at least the next 2.
* Operating cashflow has been negative in every one of the last 6 years.
* It has significant net debt.
* Its cash is significantly less than it's operating loss last year and the year before.
* The Stocko computers clasify it as a momentum trap.
* Edit: Forgot to include originally, the share count has increased every year for the last 6 years.
Frankly, given the sudden rise in the share price over the last couple of months and its obvious need for cash I'd have been amazed if they hadn't taken advantage in order to get a placing away!
with respect, ISAallowance, even if the points you make are valid, you could make the same comments about a lot of companies in the small cap space. The main point for my post however was that I think the time for the 20% limit on pre-emption rights being waived is past time. I could continue, from your comment this is not a company you follow, but I am respecting Paul’s request at the start of the day.
Re SIMEC Atlantis Energy (LON:SAE)
It’s a different business now to what it was a few years ago, but as you say still loss making and consuming capital.
Their tech to harness the power of tidal flows works and it is an attractive form of green energy as it is completely predictable unlike wind and solar. Problem with it is that it’s too expensive and the cost of wind and solar have dropped so far it looks even more expensive. So, the subsidies that it needs have never arrived.
The other, newer part of the business is another green energy business, in this case energy from burning waste pellets and they are converting Uskmouth Power Station to do that. However, it is also intertwined with the GFG Alliance group which seems to have a complex and difficult to understand structure.
So, very difficult to see when any of their projects will turn a profit, however, it is the sort of business where a sudden change could happen due to a change in subsidies etc. and you cannot extrapolate that from historical numbers.
So, quite an interesting green energy business (something I like) but uninvestable in my view until there is news that will create a step change in performance. (The demise of another green energy business, the Swansea tidal lagoon project, shows just how tricky these things can be).
Thanks for posting, Graham. It seems to be on the cusp of something, but today’s hammering of the share price is a bit of a reality check. Probably I should not have posted on here, it’s too much like an energy/mining stock when I think about it.
My morning smallcap tweet:
SIMEC Atlantis Energy (LON:SAE) Fulham Shore (LON:FUL) Avacta (LON:AVCT) DP Poland (LON:DPP) Naked Wines (LON:WINE) Verditek (LON:VDTK) Dekel Agri-Vision (LON:DKL) Epwin (LON:EPWN) Mobile Streams (LON:MOS) Duke Royalty (LON:DUKE) STM (LON:STM) Fulcrum Utility Services (LON:FCRM), De La Rue (LON:DLAR), £D4T4
SIMEC Atlantis Energy (SAE) £6m placing & PrimaryBid offer at 12p, a 34% discount. Needed for working capital and for investment in new fuel processing facilities via a JV. [SP=18.18 Cap=78m]
Fulham Shore (FUL) trading: last 4 weeks LFL -28% - 'encouraging'. Sites can accommodate 60 to 70% of previous dine-in capacity, somwhat offset by an increase in delivery and takeaway sales. £2.25m placing at 6.25p, a nil discount. New debt facility. [SP=6 Cap=35m]
Avacta (AVCT) selects mfr for rapid covid antigen test. "Aims to begin clinical validation of the test as soon as possible by using the first pilot batches." Well of course. [SP=128.5 Cap=320m]
DP Poland (DPP) planned RTO of Polish pizza restaurant group Dominium. Anticipated that Dominium's largest shareholder will acquire direct or indirect majority control of DPP's shares. Shares suspended. [SP=7.25 Cap=18m]
Naked Wines (WINE) AGM stmt: July sales up 73%. Last 4 months now +76%. "Our central case assumes that we see the heightened levels of new customers and repeat purchase frequency reduce over summer, entering peak trading with an increased customer base and more normalised trading patterns for each customer." Guides FY rev up 40% and new customer acquisition cost of £35-40m, at lower year on year margins. [SP=420 Cap=307m]
Verditek (VDTK) wins substantially larger follow-on order for six containerised ultra-lightweight solar Power Matts - $2.2m. [SP=13.25 Cap=39m]
Dekel Agri-vision (DKL) AGM stmt - lots of words, no insight for me [SP=2.37 Cap=10m]
Epwin (EPWN) H1(June) rev down 34% but ahead of the Board's expectations. NO FY guidance. [SP=67 Cap=96m]
Mobile Streams (MOS) FY trading with divisional sales but no overview. [SP=0.27 Cap=3m]
Duke Royalty (DUKE) Q1 cash rev over £2m, down 20%. Op cash cost down 15%. Expects Q2 cash revenue up YoY and "cautiously optimistic that it will be able to announce a positive trend of increasing quarterly cash revenues over the coming quarters." [SP=20.16 Cap=50m]
STM Group (STM) H1(June) trading - new business revenues for QROPs and SIPPs for expatriate market as expected but conversion timelines on flexible annuity and bulk transfers of work-place pensions remain slower than previously anticipated. Regulation: all actions and remediation completed to the satisfaction of the Gibraltar regulator. [SP=27.4 Cap=16m]
Fulcrum Utility Services (FCRM) FY(Mar) broadly in line with more recent expectations with rev down 6%, pretax £1.3m (£6m). No div. [SP=28.78 Cap=64m]
In line: DLAR, D4T4
Notes SP & cap are 20m delayed
Morning MrC,
Thanks so much for adding the market caps, that's a big help for me, as I have to sift through for typically £10-400m mkt caps only for these reports.
It's wonderful that we've now got 2 of you doing these early morning snapshots, different in style, but both incredibly useful/helpful, so thank you very much indeed for your tireless work on this! I know you've got clever software that does most of the work, but even so, you were clever enough to write it! :-)
Best wishes, Paul.
Yak! I just clicked on to see what this looks like on the new website and to me, the “high lighted inners” are been cut off and it all looks messy! This might be better as an email service so I can have full design over it, but that just adds to “another email” in your inbox. More thinking is required.
I wouldn’t be too hard on yourself about this.
I’ve just had a look at it on the old Stockopedia site having been trying to get used to the new site for a few days. It does look a lot cleaner on the old site (on my iPad). Partly as a result of there being more width I think. The new site still seems to lose rather too much space to the side bar on the right and the menu bar on the left (even with it collapsed). Also, the font on the old site seems to be a clearer looking font to me, but that could just be a personal preference.
Great development with the Mkt Cap, there has been a thread on Stocko about highlighting key words in RNS for a while. You might like to look at that to consider the description field content. (You are obviously quite capable of such things, thankfully for the rest of us)
One other comment - Is it just me? but I also liked your Stock Rank inclusion as another good reference for priorities
looking at your post on a mobile, the table can be scrolled sideways to reveal clipped text.
Apologies for the length of results displayed today lacking any useful inner clippings as I know this isn’t exactly useful to anyone. Today I let the code pick what gets displayed today, but it did a crappy job, so I am eager to automate this as I think it would be pretty awesome to see a summary of each companies news published on one page without opening up 20 or so tabs!
But something which has been playing on my mind is what am I trying to display in this inner clippings. Am I trying to “cut and copy” the exact sentences and display the most import ones? Or am I trying to summarise the document which may lead to the reordering of words? I want it to be useful, but at the same time, I can see how both of these approaches could be seen as distorting the news incorrectly.
I have only recently started reading the news as I am more of a chartist, so I appreciate any feedback on this type of standardisation.
Cheers
Dan
Brilliant Dan
excellent-Many thanks-my first port of call each morning as it gives me a great overview for the day.
many thanks Dan.
Current structure is superb Dan. Tqvm.
I liked it when you just put a link to the RNS on investigate. One click and we could see any we were interested in. Running an RNS through some code to try to summarize it sounds impossibly tricky to me. I also liked the idea of ordering the list by market cap.
This is great Dan, very useful!
One thing you might try that could save on the horizontal space used would be to drop the 'Link' column entirely and put the link markup around the announcement text itself.
Hollandsmith..your work is excellent but it would be very interesting to know what your charts are saying about the companies you are covering...i e your personal view via your charts...regards.tony
Fantastic! For my purposes, this makes it a lot easier for me to select which companies to report on. Many thanks! :-)
Cheers Paul! Honoured you see any type of value from it!
Brilliant stuff, just picked up a result that I would have missed...
This is great stuff. A little bit of tidying up would be nice, but a really useful contribution.
Hi Hollandsmith,
The whole list is great, some feedback from me is :
* its useful to see the large caps that have RNS's but I'm less interested in the highlights, but the link is useful so I can go there if needed.
* what you were doing last week, (similar to MR C and there is some overlap of course but id rather read something twice than miss something) and putting in the 'highlights' on the smaller cap is the most useful (and most relevant as this is about small caps). So list as today but commentary on anything below the ftse100 (or is it £500m as Pauls cut off?) is ideal for me.
Example (your update from last week) :
Argentex (LON:AGFX) - Group revenue increased 32.3%
Breedon (LON:BREE) - Completion on 31 July 2020 of its acquisition of certain assets and operations from CEMEX
Byotrol (LON:BYOT) - Product sales for the first quarter to 30 June exceeded £3.4m and orders for July and August continue to look encouraging.
Irrespective, a great contribution to this report everyday. J
Really useful!