Small Cap Value Report (Thu 6 Feb 2020) - W7L, SYS1, OTB, FTC, DSG, IGE, OTMP

Good morning, it's Paul here with Thursday's SCVR.
There's not a lot of small cap news again today, so I'll have a ramble about markets generally a bit later, and pad out company sections with other thoughts. As always, just skip any sections that you find tedious - nobody is obliged to read everything!
Estimated time of completion - I should be able to achieve the 1pm official finish time today.
Edit at 14:05 - the main report was done by 1pm, but I've added some extra bits on micro caps at the end.
Today's report is now finished.
Warpaint London (LON:W7L)
Share price: 83p (up c.4% in early trading, at 08:21)
No. shares: 76.7m
Market cap: 63.7m
Trading update
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands, is pleased to provide a trading update in respect of the financial year ended 31 December 2019, together with details of certain corporate initiatives.
Background - this share has failed to recover its previous levels, after a profit warning in Oct 2018. My impression is that, whilst nicely profitable, the company does seem rather accident-prone. Growth has stalled, but free cashflow is good, and the dividend yield of 5.7% looks attractive, if it can be maintained.
Trading update today -
Subject to audit, the Company expects to report revenue of £49.3 million and adjusted profit before tax (excluding amortisation in connection with acquisitions, share incentive scheme costs and exceptional items, which the board expects to total approximately £2.8 million) of £5.2 million for the year ended 31 December 2019, in line with the guidance provided in the Company's trading update on 20 December 2019.
That's actually a revenue miss of £0.7m, or 1.4% below the previous guidance of £50.0m. Not a huge miss, but coming right at the end of the year, it would be a proportionately larger miss if seen in isolation for December's sales.
The adjusted profit of £5.2m is towards the lower end of the previous company guidance of £5.1 to £5.5m.
I should say that achieving £5.2m adj profit on £49.3m revenues is a good profit margin of 10.5%.
I tend to find that around 10% is the cut-off where companies are starting to demonstrate good pricing power - i.e. a company must have a good product/service, if it can generate 10p profit in every £1 of sales. After all, if we look at highly competitive sectors, with little pricing power, such as supermarkets, they only make 2-3% operating profit margins typically, and require huge capital to achieve that.
Here's a link (click on picture below) to a Stockopedia comparison tool for Tesco, Sainsbury & Morrisons - quite interesting. This feature can be found on any company's StockReport under the drop-down "Tools" menu. It's very long, so I can only fit the top part of it into the screenshot below, hence I've added a clickable link to the picture.
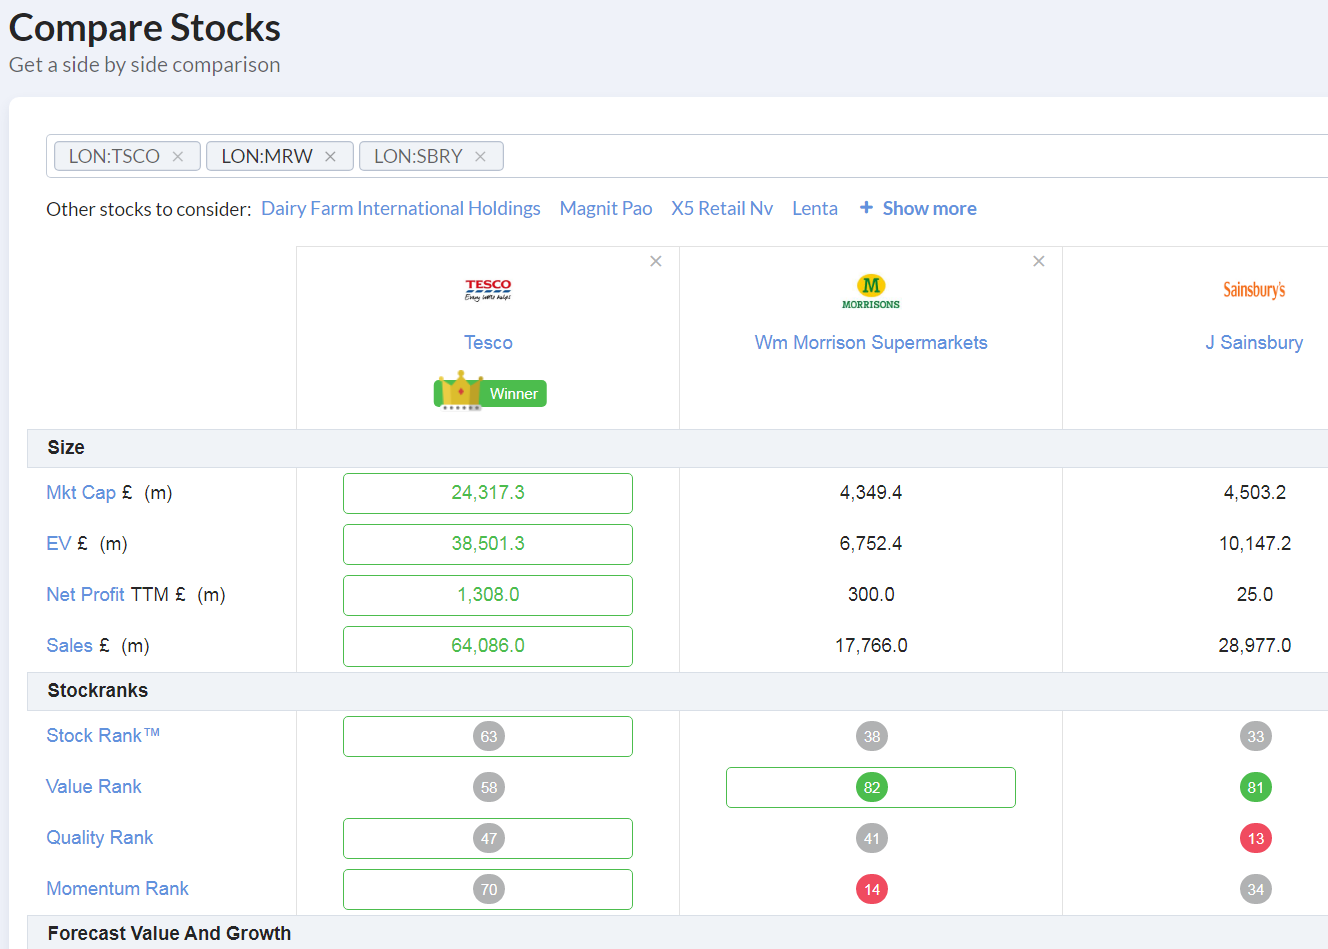
On the same theme of low profit margins, consider contracting businesses, which typically make 0-5% profit margins, only by taking on enormous risk that large contracts might go wrong & overrun on costs, which they often do (look at Carillion & numerous other contracting businesses that ended up going bust, it's a hideous sector).
Broker research & company guidance
I like it when companies issue guidance directly to the market like this, rather than via a broker. There's no reason at all why all companies cannot do this. Some brokers seem to tell their clients that they're not allowed to give guidance to the market. That is complete rubbish! Plenty of companies already do give revenue & profit guidance, and all companies should do so, because that is best practice. Shareholders and commentators greatly appreciate it when companies do give clear profit guidance. It helps us understand the business, and avoids nasty surprises which hit the share price hard. Companies & advisers need to be reminded that it's private investors who create the market liquidity & set share prices. Therefore we should be the top priority for receiving accurate & full information, not an afterthought, or worse still deliberately denied access to information.
If regulatory hurdles are the problem, then how come finncap, N+1, Liberum, and many other brokers have managed to provide us with decent information?
I suspect that the only reason some brokers try to stop their clients giving clear guidance directly to the market, is so that the broker remains the gatekeeper to information, thus enabling them to sell or give privileged access to research information to attract & retain dealing clients. When in fact their corporate clients have already paid for the research, so it should be distributed as widely as possible, not restricted! It's infuriating, and also morally wrong. If a company's broker won't let you inform the market properly, then sack them & find a broker that will.
Thankfully things are changing, with brokers such as finncap leading the way, which has its own research portal to distribute its research. Recently finncap started providing links to their research in trading updates from their clients - which is absolutely brilliant.
Quality brokers like Cenkos, N+1, Liberum, and others, make their research available on Research Tree, which is an essential tool for the serious investor in my view. It's really handy having everything in one place too, which saves me having to search multiple sites, try to get on email lists, etc., or find a back door to restricted research.
Back to Warpaint
What else does today's update say?
Supermarket - looks like a trial of 50 stores only, in bespoke free-standing display units. There's a prize of a 50p Brexit coin (haha!) for anyone who first identifies which supermarket it is, and posts a picture here in the comments section of one of these freestanding display units.
It's in discussions with other large UK retailers.
I don't see this as particularly price-sensitive, because we don't yet know whether this strategy will work. If sales are poor, then supermarkets will quickly find an alternative use for their space. Plus it's notoriously difficult to make a profit supplying supermarkets - they famously don't like suppliers making more money than they do!
Strategy consultant - a management consultant called Ward & Hagon, which is linked to Paul Hagon, an existing NED of Warpaint, has been appointed to assist Warpaint grow in the UK & USA. This concerns me. It suggests that Warpaint doesn't have the necessary knowledge & experience in-house, to develop the business. On the other hand, you could argue that the company admitting this, and bringing in the necessary talent from outside, could be a positive step.
I've never heard anyone say that they're glad they brought in management consultants. Usually people say that management consultants were expensive & clueless. Maybe it will be different here?
My view - makeup is a good sector, with high margins. Despite some mis-steps, Warpaint makes decent profits, pays good divis, and has a nice solid balance sheet. It's attractively valued on a lowish PER of 11.7 - perhaps factoring in some discount given that it has repeated forecast misses?
See the broker forecasts below, and yes I am repeatedly nagging the team at Stocko HQ to get that y-axis labels sorted! It's no use at all with just one value on the y-axis! So you can make sense of it, the darker blue line (FY 12/2019 fc EPS) goes from 16.6p on the left, down to only 6.2p on the right.
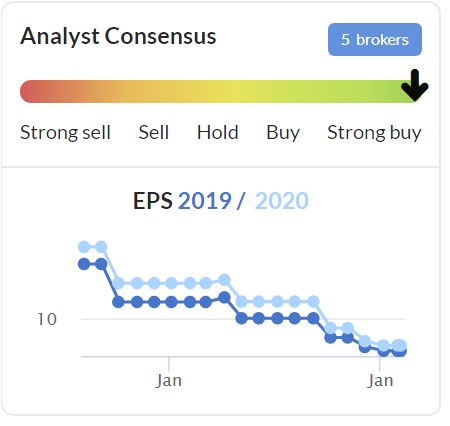
Clearly something is going wrong then. I'd need to properly understand why earnings forecasts are coming down so much, before considering a purchase of this share.
If there's any sign of earnings stabilising, and a credible plan being hatched to drive growth up, then this share might be worth a punt at some point.
I hopefully won't mis-gender or offend anybody (which seems to be punishable by death these days) if I ask for feedback from readers if you or someone you know has tried the product? What's it like? That ultimately drives long-term sales success here - the product and branding have to be good enough to attract repeat purchases from fashion-conscious customers.
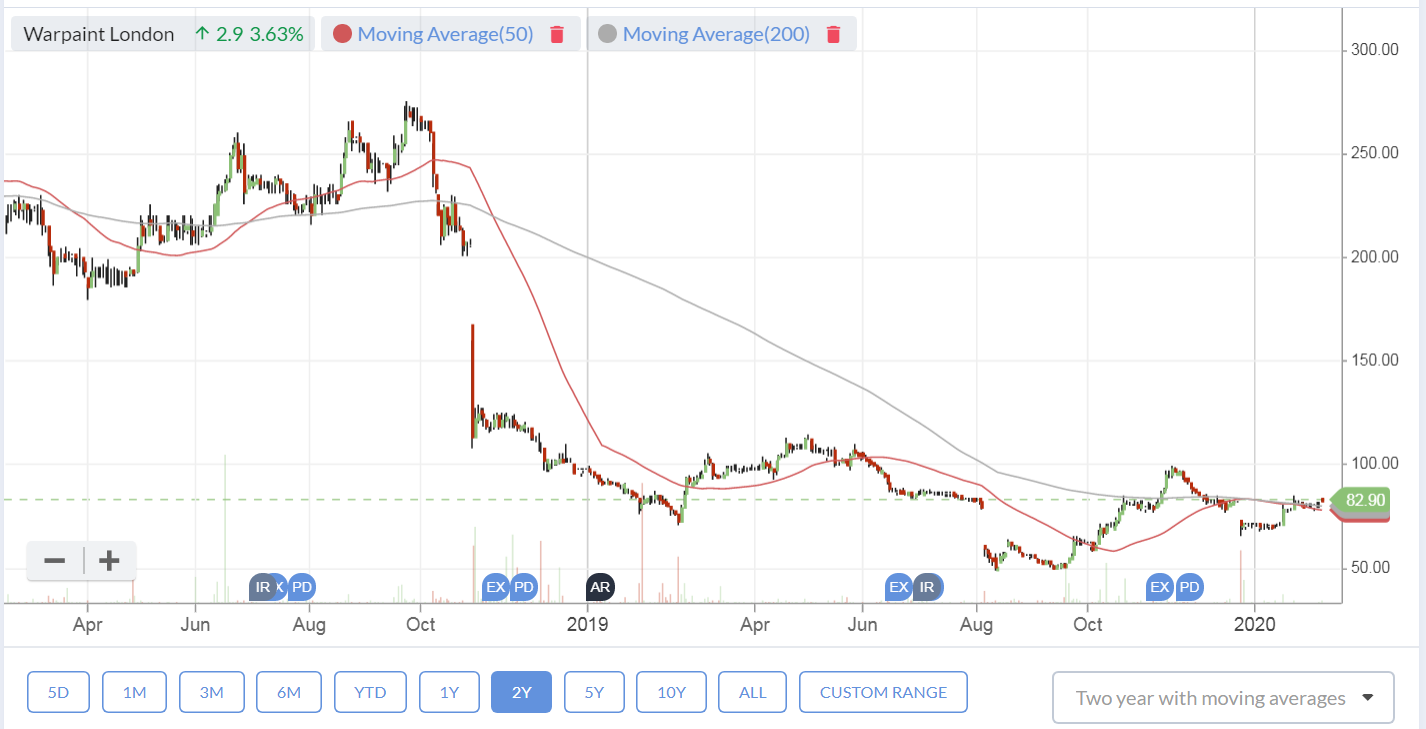
Here's the 2-year chart (I've switched to the new site charts, which are good now that the labels on the axes are a larger font!). I always remind IT developers that they are young people with great eyesight & large screens. Whereas their customers are mainly older people with smaller screens! So fonts need to be a comfortable size for us visually challenged folk to see them.
System 1 (LON: SYS1)
Share price: 225p (down 22% today, at 09:43)
No. shares: 12.6m
Market cap: £28.4m
Trading update (profit warning)
Just FYI, if a share drops sharply on a trading update, then I add the words "profit warning" next to the RNS link, so that it will come up for anyone searching for profit warnings.
System1 Group PLC (AIM: SYS1) (the international online market research agency), announces today the following trading update for its financial year to the end of March 2020.
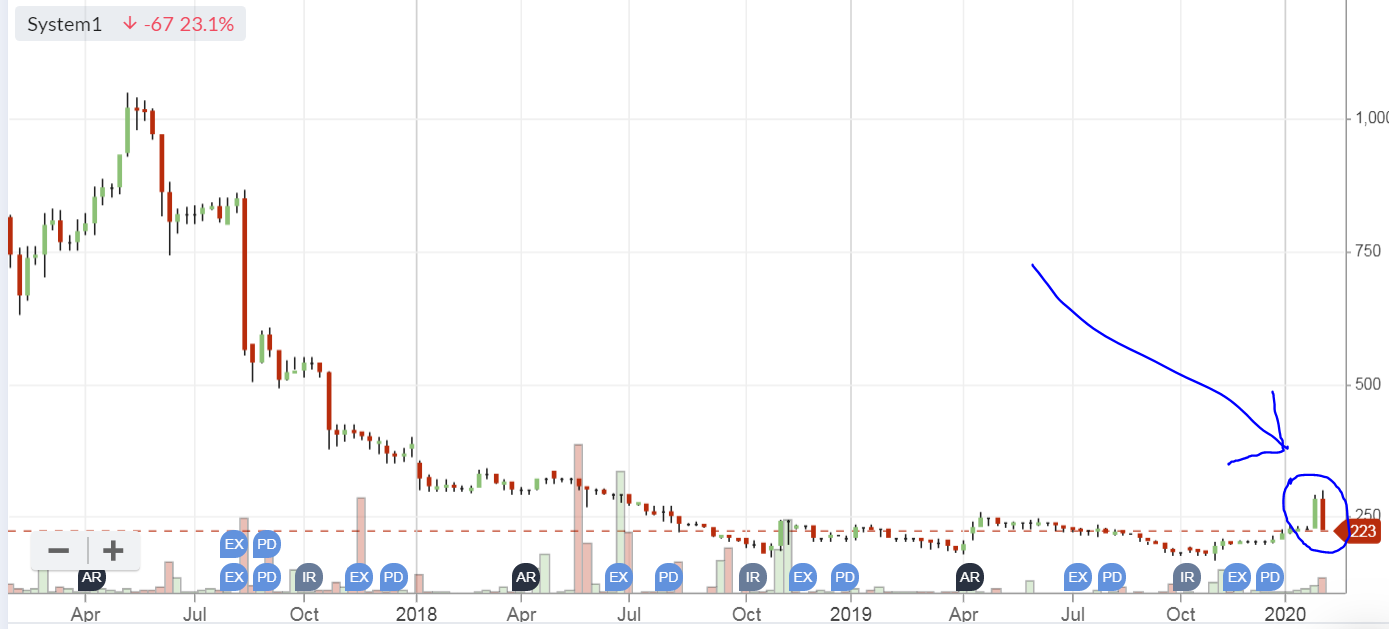
An interesting point to note here, is that today's 22% fall in share price is only reversing a recent spike up. With something as small & illiquid as this, it only takes one person to repeat buy over a few days in the market to drive the price up a lot. But such moves are often very flaky & easily reversed, as in this case.
My review here on 7 Nov 2019 of its interim results is a quick way to get up to speed, which I'm reading now (covering c.500 companies in the SCVRs, I can't possibly remember all the detail!). I did wonder in that report if the company was "putting down a marker for a possible H2 warning?" in its outlook comments.
Q4 profit warning today;
After H1 single-digit growth, followed by modest further progress in Q3, trading in Q4 to date has been disappointing, [Paul: Q4 is Jan-Mar 2020] due in the main to the ongoing transition of sales talent, and subsequent disruption and decline in adhoc revenue from smaller clients.
Given the limited visibility in some areas, it is difficult to predict the full year outturn, but the Board believes Gross Profit will be slightly down compared to the prior year.
The company has mentioned problems with lack of visibility before. With only 2 months to go to year end, it's a real concern that they don't even know how things will pan out over such a short timeframe.
The underlying reason of key sales staff leaving, is a big concern. Why are they leaving? Are there problems within the business, or are competitors offering them more money to jump ship? Whatever the reasons, it's bad. One of the advantages of a stock market listing, is to lock in key staff with generous share options. Why hasn't that been done?
Gross profit - I'm not interested in that, I want to know what the profit before tax is going to be (underlying is fine, as long as the adjustments are sensible). That's the key number, not gross profit, nor EBITDA. What is wrong with people who write RNSs, that they don't seem to understand, or are perhaps deliberately obscuring the key information that investors & commentators need? This wastes so much of my time, having to then dig out the key information, because it's missing from the trading update. Maybe it's time for more structure, and rules on trading updates? I might draft something on that, when time permits, after all I spend my life trawling through all these things, trying to make sense of them!
Broker updates - there's nothing on Research Tree unfortunately, so I'm now completely in the dark. Let's try and work things out. Last year's numbers looked like this;
Revenue £26.9m
Gross profit £22.0m
Underlying overheads £20.6m
Underlying profit before tax £1.5m (which includes losses of £2.2m for AdRatings, its loss-making startup division)
What have we been told for this year?
Gross profit slightly down on prior year. Let's guess at £21.5m
Underlying overheads up 4-6% on PY, let's guess at £21.6m
Good grief, that wipes out profit altogether! A slight loss of £0.1m, or roughly breakeven.
I think this should have been made a lot more clear than what the company actually says;
The lower than expected Gross Profit and increased costs are expected to result in a normalised 2019/20 Profit Before Tax (i.e. excluding Share Based Payments and AdRatings) materially below the current market expectation.
The company splits out the loss from AdRatings in its announcements, on the basis that it could be closed down if it fails to gain traction. I suppose that's fair enough. It's better for investors to have the breakdown of the two divisions, than not. I'd want some reassurance that the divisions are generally separate, not sharing the same overheads.
Cash position - is OK, but I'm not sure it's wise to spend a chunk of this on buybacks, when the share is already so illiquid, and it's hardly a massive amount of surplus cash anyway;
The Company has £4.2m cash, and no debt, and in line with the Company's approach to capital allocation, the Board intends to conduct a share buyback program of up to £1.5m of the Company's shares, following its normal post year-end Trading Update in April, subject to the Company's share price and cash balance at the time. This would be by way of market purchases.
That's just over 5% of the equity to be bought back.
My view - I'm irritated that I had to go round the houses, and waste time, in putting together the true picture.
Moreover, there was no information given on what market expectations were, and what they are now! Overall then, a rather poor job was done in writing this announcement. Canaccord - please try harder in future!
Despite the above grumbles, I do think this company still looks potentially interesting. You just have to look at the chart above, to see what happened when it was delivering strong growth a couple of years ago.
It remains on my watchlist, although I now have less inclination to buy, knowing that current trading is poor, and key staff have left (worryingly called "ongoing"). As the issue seems to be with staff leaving, I've had a quick look on Glassdoor here. I don't know how much reliance to put on this, but some of the comments are pretty awful, and very critical of management.
OnTheBeach (LON:OTB)
Share price: 413.5p (up c.3% today, at 11:28)
No. shares: 131.2m
Market cap: £542.5m
Trading update (AGM)
On the Beach Group plc (LSE: OTB.L), the UK's leading online retailer for beach holidays, today issues the following trading update for the four months to 31 January 2020, in advance of its Annual General Meeting to be held today.
This is for the first 4 months of FY 09/2020.
My summary of today's update, with my comments in brackets;
- Unprecedented opportunity to take market share, after Thomas Cook collapse
- Cost of flights has risen due to Thomas Cook failure, and Boeing 737 Max problems - not expected to fully normalise this year (are they able to pass on extra costs, or does this mean lower margins for OTB?)
- Focus on being price competitive (lower margins then, possibly?)
- More than doubled offline marketing spend (i.e. non-internet - it doesn't mention online spending, or give the split. Why not?)
- Strong sales growth for summer 2020, but no figures given (we're not given enough information to be able to judge the effectiveness of additional marketing spend. What are the key LTV/CAC figures like?)
- International websites doing well - evaluating entering new markets
- Classic Package Holidays - OTB's new portal for travel agents has signed up 2,300 agents. (no info on how this compares to budget. Oh hang on, the CEO says they are "delighted" with its performance)
- Interim results out on 12 May 2020
My view - this is a hopeless update, which tells us nothing of any use in how to value the shares!
It's not a financial release, it's a press release which I would expect a company to send to journalists, when they want a puff piece written. Memo to Simon Cooper (its CEO) - investors need figures, and/or a clear statement whether the company is trading below/ in line/ above market expectations (and a footnote stating what those expectations are). I know people say that if nothing is said, we can assume trading is in line. But in my experience, we later find out that is often not the case!
There's no broker update on Research Tree, so I don't have anything to work with.
Reading between the lines of this update, it sounds like the company might be seeing a squeeze on its margins, and higher marketing spend. That might put pressure on short term profitability, which the company has declined to update us about today.
It's interesting that OTB didn't say anything about coronavirus fears affecting bookings. Therefore it sounds as if, for now anyway, this is not a problem for a mainly UK-based, short haul holiday business. I see the share price is down from c.500p at end 2019, to 415p today. That could be a buying opportunity, if you're not concerned about Coronavirus spreading to Europe. Or, if you're thinking long-term and looking through the short-term risk.
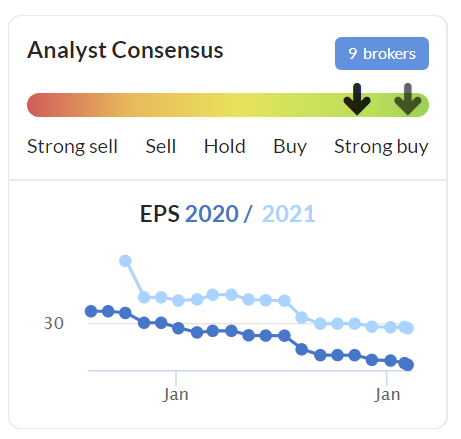
Broker forecasts have been steadily falling in the last year, before coronavirus. It sounds like the company is having to spend more on marketing to attract more business. We need to know if customer acquisition results in a one-off purchase, or how many customers come back again? That's absolutely key in determining whether marketing spend is worthwhile or not in the long-term.
Again, sorry about the y-axis labels below. The dark blue line goes from 31.4p on the left, to 25.0p on the right - quite a sizeable reduction in forecast profits. Some of that is from discretionary increased marketing spend, so it's not necessarily a problem for long-term investors.
In conclusion, I think that contrarian investors might see this as a buying opportunity - it's a reasonably-priced growth company in my view - forward PER of about 15.
More cautious investors probably wouldn't want to be buying any travel-related shares with so much uncertainty over the coronavirus.
Talking of competition, I see that Easyjet has recently entered the package holiday market, perhaps seeing how much profit that Dart (LON:DTG) is making? The profit margins in this sector do seem very high, so I could see competitive pressure eroding that over time. AirBnB is another competitive threat.
Quick sections now, for less interesting updates, and I'm nearly ready for lunch!
Filtronic (LON:FTC) - I've followed this company for years, as a result of which I would never buy shares in it - because performance has been too erratic, and it seems to rely on limited-life products. So there seems permanent restructuring going on, and large lumpy contracts being needed, with little to nothing in reliable/recurring profits. That said, there's the occasional flurry of excitement, and punters who bought at the lows can make a nice turn.
The market cap of £21m looks pricey for a micro cap with such a patchy track record. Look at the divis for example (last one paid in Nov 2010);
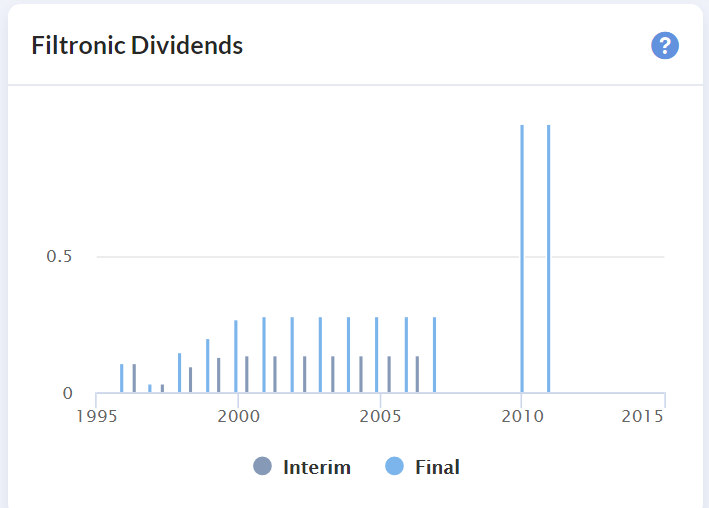
So a nice share for socialists - because it exists purely for the benefit of its staff, Directors, and paid advisers! Harsh but true.
Interim results - it eked out a tiny adjusted operating profit of £286k in H1, before a whacking great £825k exceptionals charge.
Balance sheet - not too bad. The £3.8m assets held for sale turned into cash just after the period end, according to note 10 - completion of sale of a subsidiary. That should clear debt, leaving it in a net cash position that looks fairly OK to me.
Outlook - sounds OK. Trading in line withfull year expectations for FY 06/2020.
Healthy order book of over £10m. "Strong demand profile".
My view - doesn't interest me at all. Maybe it has good things in the pipeline, but I've heard that for years, and nothing much came of it.
Oh no, I've just lost 3 new sections due to a glitch with inserting the tickers. Drat! Will try to re-write from memory, as follows;
Dillistone (LON:DSG) - great reader comments below, see Wimbledonsprinter - who points out that there's no mention of the Gated Talent product, which was meant to be the company's big new thing. Also he questions whether restructuring costs may continue, due to the wording used in today's update I think he might be right. It's now so small, and hasn't delivered on its promise, that I wonder why DSG remains listed? Probably best to go private. To be blunt, I wasn't impressed with management, and wouldn't back them.
Image Scan Holdings (LON:IGE) - makes positive noises today, in line with expectations, but that's for a small loss. Again, I can't see why it's listed, being so small. I did well on this in 2017, when management talked up the share price, but they then disappointed in 2018 & 2019. Hence I don't trust any upbeat talk from the company any more. Also, I couldn't sell as there were no buyers back in 2018, so it was very unpleasant seeing a nice profit go up in smoke & unable to do anything about it. The share price of things this small can be completely artificial (usually too high) because the MMs won't buy in any size. Sometimes the market bid price is just there for show, to keep the price propped up, but isn't real in any size.
Onthemarket (LON:OTMP) - (I am long) - more positive news about web traffic, but I feel that the growth rate isn't enough. This company has a lot of promise, if you dig into the detail, as I've done. BUT it clearly needs to raise tons more equity, to go on a marketing splurge.
That's it for today, let's hope I can publish this without half of it disappearing again, grrr!
See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Paul.
Maybe this won't work for you but when I have to write a lot of text online, I write in in a blank text document and then cut and paste it into the online document. Then, when I lose it online, I can paste it in again. I use the free LibreOffice, which handles graphics perfectly well too.
Apologies if this is teaching grandma to suck eggs.
(where did that peculiar analogy come from?)
Martyn
Thanks Martyn, yes I probably should do something like that. But because there's so much to type, adding in pictures & links, etc, it's easier to type the article direct into Stocko's user interface. Normally it works fine. I'm learning the idiosyncrasies of the new site,and the only problem occurred when I inserted the tags (ticker codes for each stock). So from now on, I'll finish the article, save it, then add the tags at the end. That should solve the problem!
Hi Paul, will you get round to giving your thoughts on £gan. Would lime to know what you think regarding the US online betting potential over the next couple of years and what a nasdaq listing could do to the share price
Hi pleaty,
I don't think I can give a sensible view on those questions that you've asked re Gan (LON:GAN)
There's a note from Liberum, dated 3 Feb 2020, available on Research Tree, that's probably your best port of call.
Regards, Paul.
I own both Warpaint London (LON:W7L) and Onthemarket (LON:OTMP) good to see you are on board with OTMP Paul but I also feel today's announcement was a bit of a 'push' to make agents sign paying contracts. Not a bad thing I guess as the traffic growth numbers are good (not outstanding) but it is only getting started.
Warpaint London (LON:W7L) was a bit of a punt but has been doing well by selling in The Range and online so good to see they are growing market presence, they need to use that presence to push sales online and improve margins. My wife used some of their products and apparently they are good, I just worry they don't push their brand on enough.
Great work as always, I currently own a property rental/renovation business which has investors which generates returns of around 10-12% PA 7-8% in cash returns in 4-5% in increase in the portfolio value conservatively speaking. All my emails/contact with my investors clearly states what im going to do with their money, how much money im going to make, how much money they will make, the financial position of the whole project and any other information I feel is necessary is given in a very clear way. Any questions investors have get answered within 24 hours. If I can do it working on my own then why cant a publicly listed company do it. The lack of respect to private investors in 99% of cases makes me just walk away, I would not invest in a company (especially a small cap) where I can not trust management and omitting key details from trading updates or hiding broker research really dents my trust in management and enthusiasm to invest.
so how can we invest in your business?
haha at the minute I am enjoying a 6 month trip round the states and latin america, I am currently in mexico city so right now im afraid you cant, in the summer I have a few ideas which already have the required investment, sorry haha. I also wouldnt take investment online like this, I prefer investors to get to know me and vice versa but maybe at some point in the future if you were serious about investing then we could discuss it further,
Paul's comments regarding the coronovirus and On The Beach (LON:OTB) triggers thoughts on possible future scenarios at a time when nobody knows how this will develop. My ISP did a quick poll - will your travel plans change as a result of the virus? resulting in a roughly 50/50 yes/no split. If OTB is mainly short haul it could benefit from people switching from (say) Thailand to Europe for holidays. However, if it develops here people will start to avoid optional activities involving being in a confined space with lots of strangers (e.g. aircraft, cinemas, restaurants (use Deliveroo instead) and bars).
I hold On The Beach (LON:OTB) and am surprised to see it up 4% on that update. I see it as disappointing and agree with what Paul says.
I (stupidly?) expected to hear that with the demise of Thomas Cook, capacity had been taken out of the market and everything was booming. Instead it sounds like they are having to work (spend) a lot harder to gain volume, with margins declining. I find that worrying. People are booking beach holidays now, maybe the type of customers that booked with Thomas Cook are simply not natural customers for OTB.
OTOH for OTB, the long term story is intact and the valuation leaves room for upside in my view.
Warpaint London (LON:W7L) bought Warpaint yesterday to go in my new blame Stockopedia if it goes wrong/I'm a genius if goes right portfolio. Think the downside is limited and the Stockopedia scores & research say there's quite a bit that could go right.
Warpaint London (LON:W7L) Anyone know why Warpaint has popped by 20% today? I cant see any news. Was wondering if there was any relationship with Creightons (LON:CRL) who are in a similar market. Bought both a few weeks ago and they've both popped by 20% .
Yes enjoyed the Tesla chat yesterday, and I understand how it can irritate some, but I think its such a big story and will have many trickle down effects, its worth thinking about and discussing. Also only seems to come up every few months..
I agree. The TSLA chat yesterday brought out some fantastic reader comments here, including the post about current (geddit?!) tax breaks for electric cars. Another reader comment flagged up that Govt will lose so much fuel duty that it will have to radically increase taxes on electric cars once they are ubiquitous! Great points that I was very pleased to see posted here, so many thanks to the contributors concerned.
re W7L and consultants, on the face of it Mr Hagon, as an NED, has views on how the company should expand further, possibly a bit different from the current ideas of the executive, and has persuaded the board to appoint Ward and Hagon to develop these views into a more detailed strategy. Whether this is good or bad for the company probably depends mostly on how right Mr Hagon is.
Many thanks for the W7L article which was very intuitive and much appreciated. I bought in at 70p on the basis the share price didn't really factor in much growth and I like the sector very much and with a good div its worth a bit of risk. The big issue here is management mis-steps, if that can be controlled then £1 should be achievable in the short medium term
I really like the EPS forecast graphs. But Paul is dead right that the Y axis needs to show more than one number. I would say that a number at the top, a number at the bottom, and about three numbers in between would be a lot better than it is now.
Strix (LON:KETL) has appointed a joint broker. That seems often to precede some corporate action such as a placement or a sale. What other reasons are there?
The new broker is Stifel Nicolaus Europe Limited, whose website says "we provide a bulge bracket range of services to middle-market clients". What on earth does that mean?
It means they claim to provide a swanky service with bells on to people who can't afford such a swanky service. To be fair to them, the people who they are targetting with that message will understand what it means.
re Strix (LON:KETL), I suspect the management of having acquisition ambitions, now that it has paid down a chunk of the PE inherited debt pile.
Acquisition ambitions and planning to raise cash to fund them?
Maybe they want a European based broker as a precaution for new rules that may be introduced due to Brexit
'bulge bracket' is a term generally used in the 'City' to describe the largest investment banks, JP Morgan, Goldman, Morgan Stanley etc who provide the whole range of investment banking services to their clients, advice, research, distribution
"I've never heard anyone say that they're glad they brought in management consultants."
Because to do so would be to admit their own limitations. Better to take the credit when it goes well and blame the consultants when it doesn't.
I like to see management bring in outside knowledge and skills when it's appropriate. There's a balance to be struck. In some companies you can sense a "not invented here" syndrome develop, usually alongside a level of arrogance. Far better to be open to other opinions and approaches. In a fast changing world, the idea that any management team knows everything, and has all the skills it ever needs, is frankly for the birds.
Re: Broker research
I mentioned last week that Sosandar (LON:SOS) are one such company who's broker, Shore Capital, do not/will not make their research available anywhere. Perhaps you could have a word with them as I suspect the volatility in their share price is in part due to PI's 'flying blind' without this access.
cheers
Francis
PS: if you do have a copy of their latest broker note, I'd love to see it! fwyburd@virginmedia.com
I'd second that. If they provided to Research Tree that would be much better. It seems idiotic to me that a broker issues research in a primarily retail held stock but doesn't make that research available to the target demographic of the company shareholder base! I understand that Shore Cap might want to protect that research for the benefit of their own clients but what that means is the house broker is conflicted. I find this very odd. It's one of the few research notes I can't get my hands on. Someone copied the forecasts somewhere which gave me at least some info to work with.
Paul - maybe something to raise with the two founders, given you have access to them?
I raise this issue every time I speak to mgt. To be fair, they got it sorted, and Shore started publishing notes on RT, but then stopped shortly afterwards (see my comments above).
It was me who published the revised forecasts here, because I didn't want any of you left in the dark.
Hi Francis,
I can't pass round broker research I'm afraid.
The problem with Shore Capital, is that they signed up to Research Tree, but apparently some new compliance officer decided they shouldn't be (probably trying to make their mark), and Shore dropped off RT.
It's a pity that mgt at Shore didn't assert themselves on this issue, and ask why it's fine for other brokers to use RT but not them. Therefore the compliance officer story could just be a smokescreen, who knows?
Rest assured, I raise this issue every time I speak to SOS management.
The other issue is that Shore & Sosandar both left outdated forecasts in the market for too long, which led to the plunge in share price recently, when revised (heavily increased) losses were slipped out via a broker note that most people can't access, and buried at the end of a positive-sounding update.
When I reported on Sosandar's last trading update, I flagged up the greatly increased forecast loss to readers here, on the day, so I do try to get accurate information out to you.
They should have managed market expectations better. I've already made that point to mgt.
Regards, Paul.
Thanks Paul, I appreciate your reply.
But what exactly are the 'rules'?
I find this very confusing - is there a site someone can direct me to that lays the rules out clearly?
cheers
Francis
Thanks Paul - yes, your information is always good within the bounds of what you can publish. There is no regulatory reason why Shore cannot publish via Research Tree, so it is either a smokescreen or someone needs to do a better job! I will ask Rob over at RT for more on this.
You are right that expectations needed to be far better managed. I have no problem with investing to grow sales if there is empirical data that the lifetime value of the customer significantly exceeds the cost of acquisition. In fact I would actively encourage it provided there is ample cash headroom to avoid any distressed fund raises later. But far better to make this clear and simple. Sing about it rather than bury it in a throat clearing "ahem" !! And always always always raise from a position of strength.
I think Sosandar (LON:SOS) has superb potential and am long but I am disappointed in the management of the story and I don't know if this is coming from inexperience within the company or from its advisors/PR/brokers and it needs to be addressed if this firm is to reach its potential.
Management talk about not worrying about share price or market fluctuations and anecdotally this is valid, in that we don't want them to lose focus on operations, but they need to pay more attention to managing the story and accessing capital to grow the business in minimally dilutive ways. The mistake lots of management teams make is assuming this means raising only small amounts of capital, but actually far better to think big and raise lots of capital but at much higher prices. That involves a strategy that currently appears lacking.
Sosandar (LON:SOS) - you can bet your life that they'll be making all the numbers and rationale public when the begging bowl comes around again. The problem, from their point of view, will be that their lack of communication to date will mean they'll be asking from a position of weaknes rather than one of strength.
Sosandar (LON:SOS) Interesting to see that they've resumed TV advertising.
I've noticed the same thing but I only watch streaming TV theses days (on demand - Not live)
Targeting based on your viewing habits ? - If so and correctly focused - cheap spend?
I have also been targeted with Viagra adverts the last couple of days, not sure how well that is targeted!
Paul,
I declare an interest here as my business provides a software platform used by brokers to produce their research product (Blue Curve). I'm not promoting it here - our customers are corporates who produce financial research, not the general public. I'm simply passing on some experience in this area that may help others understand the way the financial research market works.
The research market is made up of several types of firm, each of whom gets paid in a slightly different way for producing research. Broadly speaking, firms either get paid by the subject companies, or they get paid by their investor customers (either directly or indirectly). (There are also firms who only produce research for their own internal use, mainly fund managers, but not relevant here.)
Much of the research we see today in the small cap market will be described as a "marketing communication" or "sponsored research. This is a term used by regulators to describe research that may be conflicted and is normally paid for by the subject company. There is a lower level of disclosure required for this type of report. Edison is one of the largest providers of this type of research in the UK.
Other research may be described as "independent research". This requires a much higher level of regulatory disclosure, and compliance is generally more active in this area. This type of report is generally not paid for by the subject company, so the producer has to "sell" this type of report to it's investor customers.
Many brokers produce a mixture of "sponsored" and "independent" research.
In the distant past, research was a bundled service (along with Sales & Trading) and was paid for by trading commission income. No-one really paid attention to understanding who was paying for it. When research compliance rules started tightening in the early 2000's (remember Eliot Spitzer?), firms had to start differentiating between sponsored and independent research. Then, when MiFIID II came in, a few years ago, firms were forced to account separately for their research services, and that forced them to discuss explicit pricing with their customers.
As a result, firms are now much more protective of their research product generally, especially the "independent research". They need to be able to charge as high a price as possible to their investor customers, and that limits their desire or ability to give it away at a lower cost (or for free).
When MiFIID II came in there were many services like Research Tree that started up (ResearchXchange, Research Pool, One Access etc). Brokers who release their content to services like this are trying to get some additional revenue from smaller investor markets that are not core to them. Unfortunately, many brokers do not see enough revenue from these services to make it worth their while. I suspect the lack of revenue is why firms come off these services, not the regulatory compliances issues.
Many firms do offer access to their research portals to "Sophisticated Investors" or "High Net Worth Individuals". You can normally register directly on their portals - I know that finnCap offer that. We run the research portal for Arden Partners who also cover many of the smaller caps, and you can sign up here https://research.arden-partners.com/ - click the Register button. You will be vetted by the compliance department, so access is not guaranteed. You will also be limited to seeing their "sponsored research", unless you'd like to pay them directly for access to everything they produce.
Research is a business like any other, and now more of a standalone business since MiFIID II. Paul has discussed previously the potential impact of MiFIID II in relation to lack of coverage for small caps. Because of the need for the producers to get paid a good price for their work, it also means that "independent research" is much less freely available than it once was.
Hope that is useful. Cheers, Mark.
Hi Mark,
Smashing summary of the various types of research notes, thanks for posting!
In my view brokers should at the very least make their research available on Research Tree, for stocks where they are the house broker. For a lot of small caps, that will in any case be the only broker coverage there is!
The smallest companies baulk at paying £20-30k to Edison or Equity Development to do sponsored notes, which I can understand. Although if they're cash burning & need to do repeated fund raises, then you could argue that it would be money well-spent. Although how many people actually read sponsored research? Probably very few.
Regards, Paul.
It seems to me the lack of research is a self-limiting exercise, and I think for the costs that a quoted public Company pays for their annual broker/AIM advisor should incorporate research that it can release, if if it wishes.
I think disruption of the investment market is well overdue for capital markets. Most of the compliance issues etc for AIM do not prevent dodgy outfits getting through, or mealy mouthed RNS's being issued by management, and regulators require an industry of compliance officers who add little or nothing to productivity, or an investors overview of a business.
The fact is that human nature being what it is, the lattitude afforded by accounting techniques allows
managers, allied with the natural reluctance to deliver bad news or news of under performance, to fudge their answers, because no one wants to take a beating from the market.
Generally companies do not welcome investors, and it is wrong to think they do, unless the company is able to release a constant stream of good news, in which case Happy Days!
Arguably positive rewards should be given for honesty, but as this is not the case, expect more RNS which do not tell the whole truth or which use elusive language to veil what is happening under the bonnet.
My morning smallcap tweet: Dillstone ditches millstone
£W7L SysGroup (LON:SYS)1 On The Beach (LON:OTB) Onthemarket (LON:OTMP) Dillistone (LON:DSG) Polar Capital Global Financials Trust (LON:PCFT) Access Intelligence (LON:ACC), Image Scan Holdings (LON:IGE), Stock Spirits (LON:STCK), Filtronic (LON:FTC)
Warpaint London (W7L) to sell in a leading UK supermarket in over 50 stores. Sees FY in line.
System1 Group (SYS1) weak Q4, sees FY gross profit down, pretax materially below market expectation.. Blames "ongoing transition of sales talent" = we lost sales people.
On the Beach Group (OTB) recent trading sounds in line. Has increased non-web ad spend more than 2x. Management expects that a 'proportion' of this will payback in H2.
OnTheMarket (OTMP) trills 'record' site traffic. Well of course - it's a rapidly growing portal. It will fail unless it grabs mkt share.
Dillistone Group (DSG) guides FY loss £0.3m (profit £0.02m), broadly in line with market expectations. After a review "one of the Group's six core products, Evolve, was withdrawn from the market. Product development investment has refocussed with a view to prioritising development which will lead to significant long term growth, rather than short term product enhancements." Guides FY20 rev miss but with faster growth than expected from 2021 onwards.
Polar Capital Global (PCFT) will continue as inv. trust after end of current 7 yr term ending May.
Access Intelligence (ACC) Cello Health will pay Access Intelligence compensation of £1.6m for a shortfall in NAV for its Pulsar acquisition. This follows an accounting review of Pulsar.
In line: Image Scan Holdings (LON:IGE) Stock Spirits (LON:STCK) Filtronic (LON:FTC)
I had two thoughts on the Dillistone (LON:DSG) trading statement:
1). There was no mention of Gated Talent, which is about the only product the company has been talking about the last 12 months. Given its apparent importance going forward (it reportedly became broadly EBITDA break-even back in Sept 2019) I find the lack of an update in today’s statement disconcerting.
2). I had presumed that the c£600k reorganisation cost would all be booked in 2019. I would think it likely that any costs in closing down Evolve (the new news announced today) would also get provisioned in the 2019 results. Therefore I found the 2020 guidance being on PTP pre-exceptionals (positive in H1 and H2) a bit worrying. Will there be more re-organisation ahead?
I used to hold this stock - but sold out over a year ago. I still follow it to see if there is an opportunity to buy back in, in the event of the turnaround working. Market cap too small and illiquid to be of interest to many on this board, I would think.