Small Cap Value Report (Thu 6 Jan 2022) - DBOX, SOS, MADE, SAA, TEG

Good morning, it's Paul & Jack here with the SCVR for Thursday. Today's report is now finished.
I typed up my mystery shop of TGI Fridays, in the coffee shop of a garden centre, yesterday afternoon, waiting for my Daimler Double Six to be MoT'd (Edit: I only drive it under 1k miles p.a. by the way, and average 18 mpg, before Greta Thunberg rolls her eyes at me, and hisses some insult). The good news is that the Daimler passed with flying colours, with the MoT tester telling me the car is in "mint condition" underneath, despite being 30 years old. The bad news is that my TGI's review is really boring, but I'll post it later, once I've thought of something a bit more interesting to liven it up.
Fed tapering - the US indices (esp. tech & small caps) took a knock yesterday, due to minutes from the last Fed meeting, which indicate the Fed is set to start reducing QE more aggressively than some previously thought. Stimulus from central banks has certainly been a big boost for equity and bond markets, by artificially suppressing interest rates. So if that stops, then it's likely to be bearish, especially for highly valued, more speculative shares. Bond yields (on Govt debt) look ludicrously low to me, but it's a rigged market, so why anyone would voluntarily hold bonds that yield far below inflation, is a mystery to me. That said, all of this is already known, so nothing new. Bitcoin also took another sharp fall, so it looks as if speculative assets could be coming under pressure. Maybe punters might rotate into value? Who knows. Anyway, we're heading for a down day, with FTSE 100 futures set to open c.100 points down.
Agenda -
Paul's section:
Sosandar (LON:SOS) (I hold) a reassuring, in line with expectations update for the peak Q3 period (Oct-Dec 2021). Not cheap for a business that's still (slightly) loss-making, but it's the stellar organic growth (at high gross margins) that makes this share interesting.
M&c Saatchi (LON:SAA) - announces it's now in takeover talks with Vin Murria (a recent major shareholder & Director).
Ten Entertainment (LON:TEG) - FY 12/2021 has ended at the top end of market expectations (not specified). Thankfully the vagueness of the trading update is made up for by Liberum's update note. Looks good value to me, assuming no further lockdowns.
Jack's section:
Digitalbox (LON:DBOX) - small micro cap (only around £11m even after this morning's c20% jump) so will not appeal to a lot of investors, but it's a 'significantly ahead' update for the owner of The Daily Mash and The Tab today. There has been change here over the past year or two and it looks like a new strategy is allowing the company to more effectively monetise its digital assets. Worth looking into for those that do dabble in micro caps (which always have to come with a health warning!)
Made.com (LON:MADE) - online homeware retailer looks like it should be able to recover from recent supply chain issues. It's down c25% on the IPO price and stands to take share from the likes of John Lewis in what is a big market. But growth forecasts are fairly aggressive and the company remains loss-making for now. More detail will be provided in the preliminary results on 8th March so I'm waiting for that and keeping it on the watchlist in the meantime.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Sosandar (LON:SOS) - I hold
31.5p (pre market open) - mkt cap £70m
Sosandar, the online women's fashion brand, is pleased to provide the following trading update covering the three-month period ended 31 December 2021.
Sosandar’s current financial year is FY 03/2022. Q3 is the busiest trading period, with mgt having previously told us that Oct & Nov are the peak trading months.
Company summary says -
Record trading with revenue up +122% year on year, first EBITDA positive quarter and trading in line with the recently upgraded market expectations *
Highlights - some decent stats in here, especially the excellent gross margin, and cash pile remaining static (no cash burn), plus positive trading with the 3 key third parties -

.
Other key points -
All 3 months (Oct, Nov, and Dec) were EBITDA positive.
(On this point, I’ve already emailed the Directors, to say that many investors are suspicious of EBITDA, including Charlie Munger & Warren Buffett with these brilliant comments (do click on this video link, it’s superb) on EBITDA. In Sosandar’s case, there’s hardly any difference between EBITDA and Profit Before Tax, since the depreciation & amortisation charges are minimal. Therefore I think it’s an own goal in this case to use EBITDA as a key profit measure. I’ve suggested they quote both EBITDA and Profit Before Tax, to satisfy everyone, in future trading updates).
Returns rate - now lower than pre-pandemic, due to broader product range, an important, positive point.
Supply chain - no material impact.
Current trading - reassuring -
Trading throughout the period, including post-Christmas and into early January, has been strong. Demand has followed trends of expected seasonality…
Overall trading - in line, and thank you for the really helpful footnote (below) - all companies should be clearly stating what market expectations are, in this way. There’s no reason not to, and it’s extremely helpful to investors. Apparently some brokers try to resist this approach, in which case they should be replaced with a more sensible, investor-friendly broker!
As a result, the Board confirms that the Company continues to trade in line with recently upgraded market expectations* for the current financial year.
*Sosandar believes that market expectations for the year ending 31 March 2022 are currently revenue of £27.1 million and an EBITDA loss of £0.9 million.
Conference call - if you read this in time, it’s at 09:30 today, and is open to anyone. Another sign of an investor-friendly company, allowing in private investors. Register here. I’ll be on the call, and will report back if there’s anything interesting to add to the above.
EDIT: I missed the middle section of the half hour webinar, due to my internet going down, but did pick up on a couple of useful points from the Q&A -
- Update note from Singers is available on Research Tree - I’ve just had a read of this, and the analyst Matthew McEachran sees potential for SOS to achieve £75-100m revenues and >10% EBITDA margin, by FY 03/2025. If so, then I think that would justify a share price of maybe 3x the current level, possibly?
- Clean inventories position - pretty much sold out of Xmas stock, so didn’t need to do a January clearance sale - similar to Next - sounds good.
- Overseas growth? Still in “research mode”, which they’ve said before, but see a “massive opportunity” to expand overseas via third parties.
- Shein (Chinese clothing app) - not a threat, because it’s targeting 18-30, undercutting on price. Whereas SOS is older customer, not price-driven, strong emotional engagement with customers, and unique designs/imagery/communications, etc.
- CFO - there’s a substantial opportunity to grow more. Quality of customers acquired is key, not looking for one-off transactions.
- Next update in April, for FY 3/2022 year end.
End of edit.
My opinion - I like this update, but given that it’s in line with expectations, then it’s reassuring, rather than fuel for another big move up in share price.
As mentioned before, I feel the market cap at Sosandar is reasonable - it’s a punchy price for a company that’s still hovering near breakeven, but it’s the extremely rapid organic growth (over 100% Y-on-Y) that is so exciting. Obviously that growth rate has to moderate in time, as the numbers get bigger.
In terms of the business model, I feel Sosandar is now proven beyond doubt. Being a mainly eCommerce business, costs are highly flexible in a downturn, as we saw during 2020, a big advantage over bricks & mortar retailers. SOS could switch off (or reduce) marketing (a major cost) any time, and operate at cashflow positive. Although that would obviously erode sales growth over time.
The wholesaling to the 3 big name third party websites is lovely business with more-or-less guaranteed profitability. Plus it enhances the Sosandar brand & drives organic growth.
Overall, I remain a happy long-term holder.
I do like Sosandar’s distinctive product, and USP of targeting fashionable, over 30s women, with targeted product and fit. The high gross margin demonstrates that this is real, rather than having to discount generic products in a race to the bottom with lots of other similar companies.
As with all high growth businesses, it’s not cheap, but you have to pay up for rapid growth. If something goes wrong, and growth stops, that’s the main risk here. No sign of that being a problem so far though. I don't think there are likely to be any more placings, due to a decent cash pile, and cash burn having been eliminated now.
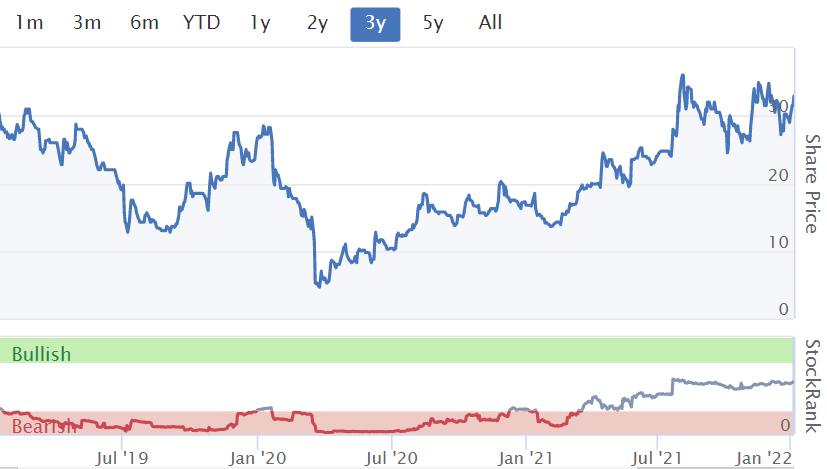
Note the StockRank has clawed its way out of the red too, reflecting improving fundamentals.
.
.
M&c Saatchi (LON:SAA)
209p (up 10%, at 10:25) - mkt cap £255m
Checking back through previous SCVRs, we began to turn positive on this PR group from June 2021 onwards, reacting to legacy issues being resolved, and a series of positive trading updates throughout H2 of 2021.
An eagle-eyed subscriber here, called slopsjon, posted a comment on Tuesday’s SCVR here, pointing out that big trades (about 15% of the company apparently) in SAA had just been printed after hours, priced at 200p, well above the prevailing share price of 167p. That was a great spot, well done slopsjon, as big trades at a premium usually means someone is building a stake, and might be about to bid for the company. I’ve seen that happen before at other companies in the past.
SAA shares gapped up to 200p the next day (Weds 5 Jan 2022), drifting down to 190p later on Weds. All has become clear today -
Statement regarding possible offer
The Board of M&C Saatchi notes the recent press speculation and confirms that it has received a preliminary approach from AdvancedAdvT Limited, a vehicle connected with Vin Murria, a director of the Company, which may or may not result in an offer for the Company.
No proposal has been received but the Board has been told to expect one in the near term…
This sounds more like a summary of previous trading updates, than a new one -
The Board confirms that the new strategy announced in Q1 2021 is already delivering, with the Company's performance consistently exceeding expectations, demonstrated by a succession of positive trading upgrades.
Takeover Panel rules have now kicked in, with all the usual disclosures now being required.
My opinion - unfortunately I sold my shares recently, thinking it looked fully valued (which it does, based on broker forecasts, even if you allow for further out-performance). There’s no point in crying over spilt milk, when you sell just before a takeover bid, these things happen. In a way it’s a positive, to have recognised the turnaround, and to have bought the share in the first place. Selling is always the toughest decision for all of us, and frequently turns out to be wrong, with hindsight.
However, the bidder clearly sees value in SAA, and is happy to pay up (200p+), and being a Director of the company, Vin Murria obviously has an informational advantage over other investors, and is very highly regarded as an investor, so I’m sure she’s right.
SAA is now priced at a premium, at c.209p, which looks logical, given that the bidder has to pay at least 200p if a takeover bid goes ahead. Also, even if the bid is rejected, this share should be fairly well underpinned at 200p, if the (now largest) shareholder was happy to pay that.
It will be very interesting to see how this pans out.
We need to keep an eye on Vin Murria’s activities, and consider buying shares in anything else where she pops up with a disclosable stake maybe?!
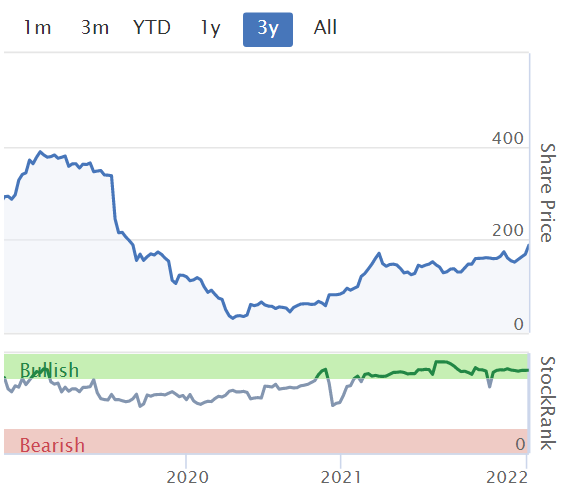
The share price has 6-bagged since the March 2020 pandemic lows, but that's because the fundamentals, performance, macro backdrop, and outlook of the company have improved so much in that time.
.
.
Ten Entertainment (LON:TEG)
257p (up 5% at 11:12) - mkt cap £176m
Trading Update (Full Year)
Ten Entertainment Group plc ("TEG" or "the Group"), a leading UK operator of 46 bowling and family entertainment centres, today announces a trading update for the 52 weeks to 26 December 2021.
The company’s summary says -
A compelling recovery with sector-leading sales growth.
Profits to be at the top end of expectations.
Where’s the footnote to specify what expectations are?? There isn’t one.
Thankfully we have Anna Barnfather at Liberum, who comes to our rescue, with a helpful update note today, available on Research Tree.
FY 12/2021 forecast PBT is raised 25%, but it’s only a small number, so the percentage isn’t as exciting as it sounds. Given that sites were shut for most of H1, then 2021 numbers are not really very important, with only £3.1m PBT (Profit Before Tax) forecast.
Strong LFL (like-for-like) sales growth of +29% (vs pre-pandemic 2019 sales) from May 2021 re-opening until year end, is really impressive - demonstrating strong, and sustained pent-up demand. Although bear in mind this will have benefited from many households abandoning summer holidays in 2021, hence having more money & time to spend on UK leisure activities.
Forecasts for FY 12/2022 and beyond are more interesting, as they (hopefully) won’t have enforced closures, and should see a more normal levelling out of demand throughout the year. So 2021’s strong performance from May, will be 2022’s tough comparatives.
EPS is forecast at 17.0p in FY 12/2022, and 20.0p in FY 12/2023.
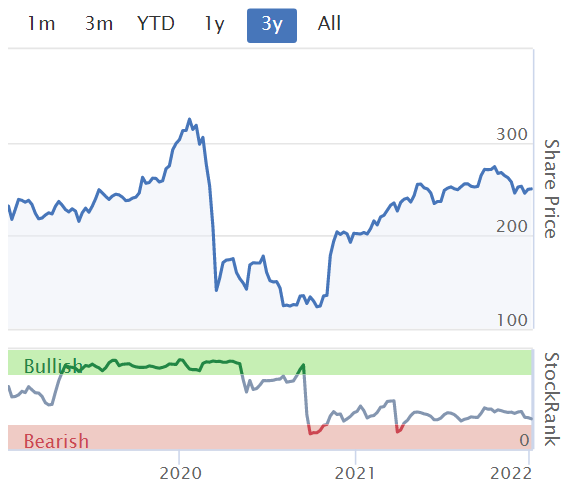
At 257p, the PERs are 15.1, and 12.9 - pretty good value, and there’s always the hope that forecasts now might turn out to be too cautious in reality? That often happens in a recovery.
Current trading - a blip down in December, due to omicron, as lots of companies are saying, but it sounds short-lived -
Trading during December remained good, albeit understandably there was some softening of demand from large groups and parties driven by government messaging and the impact of the implementation of constraints in Wales and Scotland.
For the first week of FY22, immediately following Christmas, we returned to the previous trend, delivering the Group's highest ever sales for the Christmas and New Year period.
My opinion - there’s more detail in the update, which reads positively.
I think there could be further upside on this share, assuming no new lockdowns.
.
.
Jack’s section
Digitalbox (LON:DBOX)
Share price: 11.25p (+20%)
Shares in issue: 116,332,457
Market cap: £13.1m
A very small company, but one trading significantly ahead.
Digitalbox is in some ways like a mini-Reach in that it owns a couple of content websites that it is now looking to more concertedly monetise through digital advertising. Unlike Reach, there are only three sites though: Entertainment Daily, The Daily Mash, and The Tab (which itself has around 33 local university websites).
I was first introduced to it by Judith Mackenzie of Downing LLP, which now owns more than 20% of the group (see Major Shareholders).
Following the publication of its trading update on 2 December 2021 the Board of Digitalbox is pleased to report trading across Digitalbox's three brands was stronger than anticipated in December 2021, which is traditionally the Company's most important trading period. As a result, the Company expects revenue and EBITDA* for the year ended 31 December 2021 to be significantly ahead of the recently upgraded market consensus of EBITDA* of £850,000, with revenue now expected to be not less than £3.6 million.
The strong trading resulted from the continued positive trend towards mobile advertising inventory, and better-than-expected traffic from increased editorial investment over the period.
That looks to be around a 10% beat in terms of revenue. Assuming previous estimates were £3.3m of revenue and £850k of EBITDA, and assuming a static EBITDA margin (there could be some gearing here), then there might be closer to £930,000 in FY21 EBITDA.
After adjusting for net cash, I make that an EV/EBITDA multiple of around 12.6x, which looks better value than Reach (LON:RCH) or National World (LON:NWOR) .
Conclusion
Digitalbox is a particularly small micro cap so will not be appropriate for some, but it is an interesting one and it’s likely that the lack of liquidity means the share price jumps today. In fact you can see investors have been anticipating good news.

Edit - shares have opened up c20%.
Interestingly, at these levels, the group still qualifies for Stockopedia’s ‘New Lows’ screen (which looks at the share price over three years). That might change after today.
The balance sheet is dominated by intangibles - something to check, but could be justified given the online nature of the business. Presumably very little in the way of physical assets is required here.
This has been on my radar for a while due to the changing strategy, which revolves around replicating what other, larger companies have already proven, but it’s been lower down the watchlist due to its small size and liquidity.
Digitalbox is probably still off most investors’ radars so the ship hasn’t sailed quite yet. But relatively small volumes can produce big swings in the share price so volatility can be expected. There are more buyers than sellers presently, so should that reverse then share price gains could rapidly unwind.

Still, there’s been enough in recent updates to suggest the revamped digital strategy is bearing fruit and so it’s worth visiting for those who do engage with particularly small micro caps.
Made.com (LON:MADE)
Share price: 142p (+1.28%)
Shares in issue: 390,139,698
Market cap: £554m
Made is a recently-floated online retailer that has been hit by the widespread supply chain issues affecting everyone at the minute. Shares remain around 25% below the IPO levels.

It warned the market in the Autumn on gross margins which would persist into H2, with trouble in its Vietnam logistics, before warning again later in the year on deferred orders (to the tune of £35m). Not a great start to listed life, but the Made brand itself has a good reputation for products and it is taking share from the likes of John Lewis in the UK, with expansion underway in France and Germany.
Assuming this is a temporary blip in an underlying growth story, then now could be quite a good time to take a closer look. Made is a quality name and story, with a strong management team that has online pedigree and understands digital marketing in a way you might imagine John Lewis and some others might not.
There could be an opportunity for a dedicated online retailer to really offer a superior service here, with more nimble stocking and quickly refreshed collections:
Operating at the intersection of design and technology, proprietary algorithms take consumers on a journey: from outreach that makes designs discoverable to a frictionless digital shopping experience. Combined with an innovative 'just-in-time' order model, MADE provides a fresh and ever-changing range, with nine new collections launched every week and more than 8,000 active SKUs in the catalogue as at 31 December 2021.
Strong customer demand driving +38% year-on-year gross sales growth
- Both UK and Continental achieved +38% year-on-year growth (+40% at constant currencies).
- H2 gross sales of £220m represent one and two-year growth of +25% and +69%.
- +26% growth in active customers; repeat order mix +260bps to 44% and average order value up 8% year-on-year, partly driven by range expansion into higher price point products being adopted well by customers.
- Unaudited net cash at 31 December 2021 was £107m.
The group expects to achieve the target 3-4 weeks average lead time during H1 2022 and has worked hard on its warehousing and logistics. Additionally, supply of goods from Vietnam has now returned to close to normal levels, so all key suppliers are now operational.
The ‘marketplace’ could be promising and Made is moving to the next stage of development here. There are more than 100 designer makers, artisans and small brands onboarded and the group has completed the first phase of its marketplace technology infrastructure implementation.
Philippe Chainieux, CEO of MADE commented:
I am delighted with how well the business is performing, with strong customer growth in all markets and the self-help measures implemented in H2 2021 now mitigating the impact of industry wide supply chain issues. Indeed, by the end of H1, we expect average lead times to be significantly below pre-lockdown levels and, with the acceleration of the homeware product range, the company is well positioned to deliver its strategic initiatives in 2022.
Conclusion
The StockRanks classify Made as a Sucker Stock, but it is quite a substantial one that is growing quickly and is taking share in large markets (£94bn in size, according to Liberum). Revenue is forecast to grow by some £148m in FY22E. I think the scale of anticipated top line growth alone warrants further investigation.
But the implied rate of growth also makes me slightly nervous as the base case still assumes quite a good performance. Made remains loss-making and there is that old refrain ‘sales are vanity, profit is sanity’.
The group has net cash, so it has the firepower and if it can continue its historic rate of revenue growth and customer acquisition then it’s not hard to see profit materialising and then growing quickly. I’m also of the opinion that recent slip ups are probably temporary and due to conditions beyond management’s control.
But say revenue grows to even around £1bn by FY25, implying a c30% CAGR, and Made generates a 5% profit margin (above the likes of Asos and Boohoo). Value it on a PER of 20x implying ongoing growth and that’s a market cap of £1bn, so maybe shares can double if everything plays out well.
I might be understating the growth potential or ultimate level of profitability - revenue growth and eventual EBITDA margin assumptions are key to valuing this and I don’t have a firm view on them. The forecasts are punchy and I’m erring on the side of caution for now.
On balance, I’d want a lower share price and more information below the gross sales level. Preliminary results will be published on the 8th of March. They’ll contain a lot more detail.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
Hi all,
Volex (LON:VLX), the fall continues. Now rated on 15 x forward earnings...
Volex (LON:VLX) Time to top up???
StockRank has fallen from 90+ to just over 50 over 12 months.
I think you would enjoy a recent rebuild of a Jaguar Coupe, (same car) on Harry's Garage YouTube . Yes I know off topic but very enjoyable watching someone spending £67000 on a service.
Thanks for the observation Ken
Having watched Paul's annual portfolio review and his comments on spending - As soon as I find out he has been tempted to spend the same amount on a car
I am selling ALL my holdings! (His Splash the cash warning comment)
If you want a Mk1 Jag, this one has a cracking history (not that I play the uke): https://www.the-saleroom.com/e...
Can anyone figure out what’s happening at Rockwood Realisations (RKW) which was Gresham House Strategic .
There was of course a humdinger of a fallout between Gresham who were managing and got the boot to be replaced by Christopher Mills company .
This ended up with an agreement to a controlled realisation of investments over the next 2 years and return of cash to shareholders .
What is intriguing is Christopher Mills appears to be buying shares himself and building a chunky stake There’s an RNS out seemingly every other day with his new shareholding .
They seem to be about 12% below NAV so maybe he just thinks it’s good value ? Or maybe other plans .
Note also they own I think circa 5 million. GBP of Saatchi shares so that’s an uplift on NAV of circa 1 million on the past week .
Anyway , wonder if Christopher Mills is just building his stake for the value ? He also seems to be buying a bit below the market price that !!
I hold (as of today) , looks pretty solid and safe to me .
On 8th December (Interims), Rockwood Realisation (LON:RKW) reported "Augean plc has been sold, as has the holding in RPS Group plc. There has also been a bid for Universe Group plc which when the proceeds are received, will increase the cash balance to approximately £30m."
Given AuM of around £60m, then the NAV discount (ex-cash) is approx 30%. So fairly sizeable.
NB Harwood/Mills were already 3% shareholders in the Trust. So recent purchases have been marginal
Mills buying again another RNS , up to 4.17% . It is quite a hard share to buy and they are clearly happy to top up day by day .
Northbridge in the portfolio too which is a solid share and one of my biggest holdings .
I guess even if the plan is to liquidate the portfolio over 2 years and a 30% discount to NAV it seems to offer a decent enough return compared to keeping your cash in the bank .
Epsilon
Are you sure this is right ?
"Given AuM of around £60m, then the NAV discount (ex-cash) is approx 30%."
NAV last week stated as 1644p , which gives a discount of around 12-13% , which is about right as GHS varied from 7-15% max over the past years .
Share price dropped £3 per share few weeks ago when that was dispersed .
Sanderson Design Group (SDG) well down today bouncing around the 160p mark .
They have quite a nice license deal with Next who have reported strong sales so that should be a big positive , royalty / license income is a pretty strong business model if ever I saw one especially with the likes of Next .
Think this is a bit of a shakeout / bear trap before a leg upwards especially if the Next deal starts dropping profits into the coffers which will be a shot in the arm of profits .
(I hold)
Hi planetx,
Yes, I'm hoping the trading update due imminently will be good news.
I have emailed the company on this matter, but no reply as yet...
Paul.. I really enjoyed your end-of-year review posted earlier this week but can you send us all some cheer by showing us all a picture of your wonderful Daimler car, please ?.
Hi Tony,
I can do better than that, am planning doing a video of my classic Daimler when time/weather permits!
Regards, Paul.
I am looking forward to this after selling off all of my classics last year.
I wonder if S4 Capital (LON:SFOR) run by Martin Sorrell could take a look at M&c Saatchi (LON:SAA)
S4 Capital (LON:SFOR) are on a PE of circa 33x
I don't know of course but I doubt Sir Martin would change his strategy at £SFOR - he is focused on taking market share from such 'dinosaurs' as he sees them post £WPP.
"The StockRanks classify Made as a Sucker Stock"
Jack, I notice that the top Sucker Stocks are the best performing style over the last year and 2 years.
Over 2 years they are up over 95%, next is Neutral +50%, next Momentum Traps +46% then Superstocks +42%.
Clearly the suckers are in control.
Maybe losing control, in the last 6 months, they are not performing so well. A lot of Stockopedia rankings were turned on their heads in 2020 and early 2021.
it amazes me how strongly the markets can react to news which is surely already known or expected?
Everyone knows inflation is present and rising, globally.
Everyone knows interest rates are going up.
Everyone knows the fed is tapering.
Yet when there’s an announcement to confirm it, there’s a big sell-off.
I get that they’re basically saying the situation is worse than they thought... but is this really news to anyone?
The Fed minutes imply a far more hawkish outlook than expected, hence the reaction…. The Nasdaq has been propped up by its largest constituents for most of the previous year, even a small contraction in the multiples of these mega caps will therefore produce a significant reaction. (I’m short).
In times like this, i try to remind myself ( although hard sometimes! ) that the world isn't going to end, and that there may be one or two real bargains to be had out there
For any Made.com (LON:MADE) holders or anyone looking into it, InPractise.com did a good interview with Christoph Haberbauer who was the former MD at made.com comparing it to their competitors Westwing & Wayfair.
Some snippets are here but you'd need to subscribe for full interview:
https://inpractise.com/article...
I don't hold
@mginvestor
Redde Northgate (LON:REDD) (no position)
For any holders here, you may be interested in ALD's acquisition of LeasePlan this morning for 4b EUR.
They are currently the #4 and #5 biggest players in this sector.
https://www.aldautomotive.com/...
https://www.aldautomotive.com/...
Cheers
A
Paul: "why anyone would voluntarily hold bonds that yield far below inflation, is a mystery to me."
There are life assurers who need the security and portfolio managers who want a hedge, but the major swing buyers are commercial banks. When we deposit our hard earned cash at the bank, they have to do something with it if they want to make any profits. Usually they will want to make loans to individuals and businesses. They will make nice fat margins on that business. But what if there are no takers? What if personal and business customers don't want to splash the cash and so have no demand for loans? Then the banks will have to find somewhere else to put the money - and the major alternative is government bonds. A nominal yield below inflation may not be very attractive, but it is better than nothing.
This is part of the picture that tells us inflation is being driven by supply constraints, not excessive aggregate demand. In a world of excessive demand, banks would have no shortage of takers for loans and the swing buyers of government bonds would fade from the market.
cmpeckham, you make a very interesting and insightful comment re: why anyone would voluntarily hold bonds that yield far below inflation.
cmpeckham, you make a very interesting and insightful comment re: why anyone would voluntarily hold bonds that yield far below inflation.
Bond markets are roughly three times bigger than equity markets so if you're a bank or a pension fund you have limited options. Plus government regulations force certain parties such as pension funds to hold government bonds.
It's a classic government debt reduction strategy to hold bond yields below inflation rates and legislate to force financial institutions to fund the deficit and allow inflation to erode the value of the debt.
timarr
It's a classic government debt reduction strategy to hold bond yields below inflation rates and legislate to force financial institutions to fund the deficit and allow inflation to erode the value of the debt.
Cheers timarr - intresting fact that is
It's a classic government debt reduction strategy to hold bond yields below inflation rates and legislate to force financial institutions to fund the deficit and allow inflation to erode the value of the debt.
Not to mention the introduction of legislation, over the last few years, to force investment in such pension funds, which effectively drives more investment in these value decretive bonds will be bought. And yes, my current NEST pension, running since 2017, is currently worth slightly less than the total amount invested. And that is the result in GBP taking no account of inflation.
Did you realise that the only way to hold 100% equities in NEST is to opt for sharia investment? I'm not convinced that it's the best name for a pure equity fund but there we go.
The lack of understanding of prudent financial management shown by some here puzzles me, especially when people even mention managing money on behalf of others.
The absolute key is to invest to meet your liabilities. Take a grossly over-simplified example; suppose you’re responsible for a large highly mature pension fund with £100m pa outgo declining linearly over 20 years when your last pensioner is projected to draw their last breath. So £1bn cash outgo ignoring any discounting and indexation. You put it all into equities as ‘equities have always outperformed in the long-term’. Sadly, this is autumn-2007. UK equities fall pretty rapidly to a low of barely half by early 2009 before staging a slower recovery, finally recovering their capital value in 2013. You breathe a sigh of relief, congratulating yourself on holding your equity nerve. Problem is, over the first 3 years 27% of your entire pension cashflow has been paid out. Over the first 5 years it’s 44%. To meet this outgo you’ve had to sell your equities at materially depressed prices, have become technically insolvent, have egg all over your face, and would need a mega return in subsequent years to meet your remaining contractual outgo. (It would be lovely if you could say to your pensioners ‘’Our investments have taken a knock so we can pay only 80% of your pension this year. Trust us! - we’ll make it up later when things improve. '’ But that’s not how the world works.)
So pension fund trustees and insurers take as their starting point the minimum risk investment strategy, ie a portfolio of index-linked and conventional gilts constructed so that interest and redemption proceeds year by year ‘match’ as closely as possible the annual pension outgo, regardless of future changes in interest and inflation rates etc. This is the modern evolution of Redington’s immunisation theory from the 1950s, developed over the years most notably by the pioneering work of Exley, Mehta and Smith – see https://johnralfe.wordpress.com/2020/06/19/the-pensions-prophets-10-years-on-by-barry-riley-ft-april-23rd-2007-exley-mehta-smith/ and https://www.cambridge.org/core/journals/british-actuarial-journal/article/abs/financial-theory-of-defined-benefit-pension-schemes/9655AB6962D8516723BFD29BB485163D
In practice the world is a lot more complex and not so cut and dried. You’ll need inflation swaps and other derivatives to fine tune your portfolio to match your cashflow (not least because there’s not nearly enough index-linked gilts around to meet UK pensioners’ needs). You’ll venture up the risk spectrum into corporate bonds and overseas bonds as the higher yield should more than cover the credit risk. You might add property and infrastructure-type assets with reasonably secure and predictable income streams. You might even add some equities back in. But the further you diverge from the minimum risk position the bigger the cushion of surplus you need to be sufficiently confident of weathering the type of drawdown outlined above. (That’s where the asset-liability stochastic models beloved of the pension industry come in. And if your models are anticipating only say a 4% pa higher return from equities than bonds, but with considerably higher volatility, you might conclude it’s hardly worth the candle.) If you can’t afford that cushion then you’ll need a cast-iron ‘employer covenant’ to convince the regulators of your prudence, perhaps even a quasi-government guarantee.
So the simple answer is yes, pension funds and insurers will still invest in bonds of appropriate duration even if they show a negative real (maybe even nominal!) yield. Holding your fund entirely in cash (perhaps ‘waiting for yields to recover’) is not the answer either – you have no way of knowing with confidence what investment conditions will be in 1, 2, 3 years’ time when your deposits roll over.
For general insurers (notably property and motor) the issue is perhaps even starker – you take in premiums at the start of the year to pay out claims typically just 12-24 months ahead.
Sorry for the long, dry lecture! I expect there’s plenty of free trustee training resources on the web for anyone wishing to better understand basic institutional investment.
Hi Paul / all,
Do you have a view why Sosandar (LON:SOS) has such low EBITDA margins forecast? I would have expected the relatively high price point of their clothes & online model would have helped them deliver healthy margins, but even on the forecasted £52.5m FY 24 revenue the forecast is for only £2.62m EBITDA (5%). The growth is exciting, but do you expect margins to improves, as otherwise it will take a lot of growth to start producing significant earnings in relation to the current MC.
Compared to In Style (LON:ITS) (6-8% expected), £ASOS (c. 8%), Boohoo (LON:BOO) (6-10%) - and is more at the level of Quiz (LON:QUIZ) which I'd have expected them to beat really (due to business model, and price point of clothes).
Do you have a view why Sosandar (LON:SOS) has such low EBITDA margins forecast?
There are at least two answers to this.
Firstly, even with £52m of revenue in y/e Mar 2024, the business will still be sub-scale, meaning that 'fixed' costs remain a high percentage of Sales.
Secondly, the largest cost line below gross profit is Marketing. As the graph below reveals, the company has the discretion to alter this spend as they please. Hence the Mar-2024 EBITDA forecast by Singer is assuming a continued high Marketing/Sales ratio.
The marketing is the key. It is the right strategy for Sosandar (LON:SOS) now to invest heavily, as their CLVs to CACs are probably profitable, inferring from their stats. However, because the marketing cost is opex and realised now, its depressing current profits. One could argue they should capitalise the marketing costs to match the CLV benefits over a lifetime, but that gets into tricky accounting grounds....
Of course, estimating CLV accurately is not easy. Akin, to say, calculating the value of highly rated, unprofitable tech companies based on their future earnings 10, 20 years out...
(I hold)
I don't know if anyone else was interested in Concurrent Technologies on which Paul has written this week following good results. It is a company I have been following for a year and trying to understand. There was a question regarding their client base which was raised and I wanted to follow up on. The Company responded well (which is important to me) and the outcome is their largest 10 clients 7 are defence, 2 are technology and 1 is scientific. 50% of their revenue was derived from 8 clients in 2021. In 2020 12 customers accounted for 50% of revenue. The largest customer in Qtr 1 was not the largest customer in 2021. Their customers are tied in to contracts/projects, so as one falls away another picks up hence the changes. Projects tend to last a few years. Overall during 2021 they had 250 clients across all sectors of defence, scientific and tech. The top 20 clients make up around 78% of rev. I hope this is helpful and would like to thank Jonathan Martin CFO for the co, for his input here.
Thanks very much Camtab for the detailed info
Hi Camtab,
Great stuff, well done! Certainly deserving of a hat tip, for you taking the trouble to contact Concurrent Technologies (LON:CNC) and ask for this info, and brief us here.
Best wishes, Paul.
Just as an aside, and because of some comments here prior to Xmas, I notice that Simon Thompson of IC issued a new article yesterday for the first time since 24th November. Good to see him back.
I can't find it. Where is it?
I don't have Alpha but am a general subscriber. I tried a search but can't get anyhting recent. I had also noticed his lack of recent stuff..
Click on ideas.
(Search engine is rubbish)
Ten Entertainment (LON:TEG) ( I hold)
Trading update today at the top end of expectations. Looks cheap versus the growth opportunity. Peel Hunt have £14m pbt in for 2022, they made that alone in the last 6 months! They were trading well pre pandemic and are trading even better now and with a growth opportunity in excellent market conditions. Generally I have been looking for and adding to these types of names, where expansion of their business model is being aided by market conditions. Relatively immune to supply chain and wage inflation issues. Debt levels down again, solid balance sheet.
Happy New Year to Paul and everyone here and thanks for all the amazing work and comments that goes into making this such a great community.
Mike
Ten Entertainment (LON:TEG)
I certainly have a price as 300-350p as being fair value at minimum based on infor they are trotting out and the fcat they seem to be in a reasonably decent "niche" where its not really in the interests of the main operators to be price gauging each other. If there is easy money being msde though then perhaps we should worry that new competition may enter the market? - hey ho at present at tickedy boo here. Hopefully some updgrade to 2022 £14 mill numbers may be on the way at some stage (today???) - not sure if new sites slightly mask the real level of profitability short term? (i have no idea if they syphon the early start up costs for new sites off as some companies do).
Lot to like in Ten Entertainment (LON:TEG) trading. Was being pegged back prior to update as people were concerned that Xmas trading may have been impacted by the omicron plan B measures, but it appears minimal impact and very short lived. I think Hollywood Bowl and Ten Entertainment (LON:TEG) more or less have the bowling market sewn up nationally - there will always be room for a few independents but they will struggle to make the economics work given Ten Entertainment (LON:TEG) will be a big beneficiary of scale. It might be "easy money" at scale but it isn't if you only own 2 or 3 sites.
I'd be surprised if there aren't some big upgrades to the £14m PBT over the course of the year. If by YE23 they are trading at FCF of 9.8% on current share price I'd also expect the stock to re-rate to a minimum of 350p.
With divis now pencilled in at 2.5% Im comfortable to hold for next 2 years looking for a compound 20%+ growth.
Ten Entertainment (LON:TEG) (no position)
Hi MH1 and rmillaree
I sold out of Ten Entertainment (LON:TEG) recently, primarily over Omicron fears, but I may buy back in the short term as I think current 2022 revenue forecasts (which I believe to be £95.6m) will actually be beaten.
I do, however, have some concern for 2023 revenues based on the following assumptions:
My annualised revenue in 2023, even with 8 extra sites (46--->54), then drops to £101m from £106m in 2022.
It will be interesting to see whether updated forecasts tie in with my very basic assumptions.
I still think the company's financial metrics are excellent, with individual sites being highly cash generative, even after maintenance capex is accounted for.
Cheers
A
Forecasts are for £96m in FY22 and £107m FY23 but see earnings risk to the upside as revenues cautious based on omicron
I think your customers per site are too low. They should be ahead of 2019
Ten Entertainment (LON:TEG)
Hi David
Thanks for those FY23 forecasts.
I'm one of those who believes that the entertainment sector will have a "catch-up" period before things revert to their pre-covid levels.
Indeed, we saw Revolution Bars (LON:RBG) like-for-likes drop to 0% vs 2019 just before Christmas and I heard as much anecdotally from a friend who owns a bar.
My thinking is that the number of customers per bowling venue will therefore also return to 2019 levels sometime during 2022, and definitely by 2023, and will not stay at the current elevated levels.
Based on this, I will leave my assumptions as they are and adjust as updates are provided.
Cheers again for providing those forecasts.
A
Next (LON:NXT) Trading statement today
"Next has said it will raise its prices this year to offset increased wages as well as higher shipping and manufacturing costs.
It said prices for its spring and summer ranges would rise by 3.7% from a year earlier, while it expects a 6% increase for autumn and winter goods.
Its forecast came as it said sales for the three months to 25 December were up 20% compared with pre-pandemic 2019.
Next also upped its profit forecast for the year.
It now expects to make an extra £22m, taking annual profits to £822m, which would be nearly 10% higher than in 2019.
The retailer said sales in the final quarter of 2021 had been boosted by strong revival in "formal and occasion wear".
Next's online business saw sales soar by 45% from two years ago, whereas sales at its High Street stores were down 5.4%."
Next (LON:NXT) trading updates are always worth reading simply because of the clarity of everything in their statements. Though trading has been excellent and a special dividend of 160p (ex div next Thursday) as a result, the flip side is the possible hurdles and headwinds ahead that will apply not just to them but to so many other Companies too.
e.g as explained in this extract from their comment today:-
“ECONOMIC UNCERTAINTIES FOR 2022
Pent-up demand. To what extent has the buoyancy of the last nine
& savings months been the result of pent-up demand combined
with the spending of savings accumulated over the
pandemic? How much of this will reverse out as
we move through next year?
Travel and To what extent will the return to spending on overseas
leisure holidays and other social activities depress demand
for discretionary goods?
To what extent will inflation in essential goods,
goods inflation and services (fuel, electricity, food, etc) reduce
discretionary spending on clothing and homeware?
To what extent will the inflation in our own selling
inflation prices, estimated at around 6% in the second half
(see below), serve to depress the demand for our
products?
Tax and To what extent will the 1.25% increase in National
interest Insurance and possible increases in mortgage rates
rates affect discretionary spending?
Clear answers to these questions are impossible at this stage but they all point to a tougher environment as we move through next year.”
Next (LON:NXT) RE: Price rises. Too right I bought a TV stand from their website for £350. When it arrived (promptly I must say) the box was affixed with a large sticker that said £260. That's a 35% price hike on obviously pre-existing stock, no wonder they're increasing profitability.
Clothing price rises are very much in the pipeline for this year Associated British Foods (LON:ABF) guided as much in their September results (which I studied yesterday) albeit not as concisely as next. Interestingly Associated British Foods (LON:ABF) have indicated that they are going to ramp up their number of primark stores by 25% over the next 5 years which is quite staggering given the state of the high street/ shopping centres, perhaps they are at a point of critical mass in the US.
Beyond clothing we all know the consumer is going to be badly hit this year. It will interesting to see if wage inflation keeps up with all of these increases.
I think £NEXT has fired the starting gun in terms of the key driver of inflation over the next 12 months; manufactured/processed goods. We've already seen inflation in raw materials, goods (energy, oil, food, direct labour) feed through to the current high inflation.
However, many companies had held prices of their goods, as due to long supply chains they were still benefiting from factory/cost prices in the first half of 2021.
However, like Next, the goods sold in 2022 will be produced in H2 2021, and therefore would have higher factory gate prices.
I expect to see, in H1 2022, many companies warn on profits, as they face the music of higher input prices and their inability to pass on in terms of price rises to their customers. These will be the weak companies without pricing power; for illustration look at Mcbride (LON:MCB) who has already suffered this (due to their high turnover rate from raw materials->production->sales) but other similarly weak companies will now be starting to suffer.
Digitalbox (LON:DBOX)
Cheers Jack worth buying some just to be a part owner of the daily mash - todays headlines include the following ! (who needs the daily mail when you get this level of entertainment each morning from "The Mash".
Wedgies, and other school experiences far more traumatic than wearing a mask
Prince Andrew's next six brilliant visionary legal moves to get himself off the hook
Man disappointed to find his job still there
Did you spot the Cookies permission has "whatever" rather than "agree". Glad to see I have my money well invested
Joules (LON:JOUL) posted a Christmas trading update last year on the 7th of January.
Can we expect to see one tomorrow?
Duplicate removed
As an aside on supply chain issues, I am now being quoted a lead time for a new garden room of 3 months, a month ago we were being told 5-6 months.
That sounds promising although hopefully somewhat to be expected - you won't be in business for long if you have nothing avaialble to sell in the next 6 months !
I didn't include the company specific details for made but they are confident of getting back to lead times of 3-4 weeks - presumably the lead time to them is everything as i suspect bods are less likely to hang around waiting for orders when ordering online. Would be nice to get back to a more normalised situation ref supply chain issues and freight rates !
Specific comment from made
"Average of 3-4 weeks lead time expected to be achieved in H1 2022"
Ref ongoing supply chain issues.
Slightly more upbeat news today from Made.com (LON:MADE) ref supply chain issues - perhaps the worst of these issues may be coming to an end "soonish" for some or most buisnesses (i guess things like semi condiuctors and the like may take longer to get back to normal?)
Note comments from today should be taken in context of their profit warning last month so the bad news tone was laid last month just in time for some slightly more positive news in the new year.
These disruptions led to up to 20% of key high performing furniture ranges to be unavailable during peak trading this Autumn. All key factories are now open, dispatching product and shipping disruptions have been easing.
The group has built stockpositions to deliver significantly better lead times to consumers for 2022 andbeyond. Additionally, supply of goods from Vietnam has now returned to close to normal levels, so all our key suppliers around the world are now operational.
Indeed, by the end
of H1, we expect average lead times to be significantly below pre-lockdown
levels and,
Surprised Made.com (LON:MADE) hasn't held on to its gains this morning. Up 10% first thing and now down 2p. Remember the profit warning was actually just a 4 week delay in revenue recognition that happened to cross YE reporting periods due to the elongated supply chain. The Sales were in-line with original guidance and the new year now has the benefit of the extra revenue recognition. As long as growth rates remain in-line (and so far they are) Made.com (LON:MADE) should be nicely profitable this year and are now looking pretty cheap to me. Getting the lead times to sub 4 weeks should be an excellent driver of revenue growth too.
Sosandar (LON:SOS) trading update - don't forget Q3 last year was only +6% so the comparative period was a bit weaker, but these are still good results nonetheless especially the improvement in gross margin. I think the business has reached an inflexion point.
I personally like to value high growth, earlier stage businesses on sales as a personal guide to whether I should top up or top slice. This is trading below 2x sales for next year which seems like reasonable "value" to me - it wasn't that long ago Boohoo (LON:BOO) was on 2-3x sales (although note the radical de-rating to 0.8). There are lots of racy shares on much higher sales valuations. Moonpig (LON:MOON) which I also like, but I think is too expensive to own right now, is on 4x sales for example and the sales growth looks much lower there going forwards albeit it is the market leader.
Sosandar (LON:SOS)
Nice of sosandar to include the following brief line that makes things so much easier to digest - long may this continue with regard to their updates and other companies please take note that this one added line in "every" in year update makes all the difference to us small shareholders trying to workout wherewearewhereami.
*Sosandar believes that market expectations for the year ending 31 March 2022
are currently revenue of £27.1 million and an EBITDA loss of £0.9 million.
You can't do a blanket "2x revenues" valuation on tech shares, and also lump Sosandar (LON:SOS) in, and compare to £MOON. For one, the latter has much higher margins and operational gearing to growth.
Maybe a better comparison would be revenue multiple compared to BOO (1.3x) or JOUL (1.5x), but accepting a higher rev multiple since it is smaller and thus have more "growth" available in the tank?
(I hold SOS)
I wasn't necessarily thinking about tech but early stage companies generally. Granted many of these have higher margins you're right, but I did make the Boohoo (LON:BOO) comparison as it was on around 3x sales not that long ago. Moonpig (LON:MOON) does have better margins at the moment but I don't think it has that much more pricing power for cards - but it probably still justifies a stronger rating for being the dominant company in its sector.
Anyone have the latest Sosandar (LON:SOS) research note from Singer this morning? I can only access the excerpt - it is still a Buy from them - but any updates to EPS guidance for FY23?
(I hold)
Its on Research Tree (which is well worth subscribing to in my opinion if you don't)
FY23 looking for £38.5m revenue with £1..4m PBT and 0.6p eps moving to 1p in FY24
I am a long term Sosandar (LON:SOS) holder. It feels to me as if they can sell more or less all they make at high margin full price. The partnership with M&S, Next and JLP are all clearly doing well and require no marketing costs. Important to note that a) there are many other similar partner opportunities eg Zalando, Asos, Debenhams etc and b) these are only online partnerships currently as SOS cannot meet demand for in store. Sales via M&S would probably double if SOS was rolled out to stores and there would be corresponding benefits for the direct to consumer side as new M&S customers discover the full range available online. It's difficult to see much downside with high potential upside.
M&c Saatchi (SAA) so what's a fair price to take out this once iconic company ? Plainly Vin (effectively approx 22% holding) is uber keen on it but just what will she pay ?
I remember hearing her speak at a recent Mello or similar about M&c Saatchi (LON:SAA) and noting how enthusiastic and excited about the changes that were occurring in the company.
Also will the offer be cash, or include shares in Advancedadvt (LON:ADVT)?
Looking back 2.5 years I see that M&c Saatchi (LON:SAA) was expected to make around 10% net profit, whereas current estimates are between 4-5%. If Vin can see (which presumably as Vice Chair of M&c Saatchi (LON:SAA) she can) an efficient route to achieve those sort of returns, any offer between 200 - 250p would still make an excellent proposition for Advancedadvt (LON:ADVT) (M&c Saatchi (LON:SAA) had highs close to 400p in 2019).
Her modus operandi previously when buying private companies was to pay no more than 7x earnings ( a strategy that is now difficult to implement due to Private Equity interventions), so paying for a public company currently on a PE of circa 19x is a new stretch.
My suspicion is that there was a push for Advancedadvt (LON:ADVT) to do something as it hadn't done anything for nearly 2-3 years, and there is risk of being delisted unless you get permission from the relevant authorities to extend their time threshold for not trading.
I am not expecting a high price, but she could find some other bidder might be interested if too low.
Morning all,
Not the start to the year I was hoping for most of my small caps! Looks like the rally at the end of December has petered out fairly quickly...
Not just small caps - Market seems to have turned against the ESG favourites - Croda International (LON:CRDA) Halma (LON:HLMA) and £SPX and don't even mention £SMT.....
Are we seeing the beginning of the end of the "Quality" share bubble???
Phil
Made.com (LON:MADE) (no position)
An interesting set of results from Made.com this morning.
I must admit to being quite impressed.
Some positives:
By my estimate this should be c11% in H2
https://www.made.com/monteross...
There is a new furniture warehouse going live, but my understanding was that this was around April 2022, so perhaps those lead times will come down towards the end of the period?
And for balance some negatives:
I was not expecting this and I'm not sure what has driven such a drop.
There is the new warehouse being set up, but this is not due to go live for a few more months.
Repeat Order Growth is slowing down in the UK too, though it's hard to read too much into this given the last 2 years.
Conversely Europe repeat orders seem to be growing - now +41% in H2 FY21, up from +33% in Q2 FY21.
No position for now, but still high on the watchlist.
A
Avon Protection announce new CFO, Rich Cashin
You couldn't make it up!
Quiet Paul? greggs, b&m,sos,next with trading statement plus teg high street trading had a good xmas buy the looks of it?
Only one of your list is a small cap though! So I've got to focus on those first. Might comment tomorrow on the larger caps, as an aside, rather than full sections.
P.
Srt Marine Systems (LON:SRT) announces a major contract win - at last!
https://www.investegate.co.uk/...
The first of three or so that have been "imminent" for what seems to be a very long time.
£40m over two years from this one, plus significant expectations from subsequent phases of work. That compares with £8.3m revenue in the year to end-March 2021, so even this single contract is very material to the business, never mind if and when they deliver the others.
I'm wishing I'd selected SRT as my "#1 share pick for 2022" now.
I’m pleased for SRT and Simon Tucker who I have met a couple of times. Because of his incredible enthusiasm and work effort I bought and held the shares for several years before selling out at a loss. I judged that SRT was likely to remain a ‘jam tomorrow’ company and never be rewarded for its research and development of an excellent product. Pleased that the company and its long-suffering shareholders will finally get their reward.
I've also been waiting for this for ages. Have wondered if it is a "story stock". I can't judge the product but I like the idea. History is littered with good ideas where the company can't execute. LON:BIRD in your portfolio?
Anyway I've been waiting for another real customer to commit. Judging by the price move this AM it looks like there will be a chance of hoovering up a few near yesterday's price. Will be interested in SCVR comment on this company.
Srt Marine Systems (LON:SRT) had a market cap of about £70m, so the share price had already priced in some level of success with new contract wins. Finally delivering a contract brings two main benefits, in my opinion:
Until the contract is cancelled as per a government contract some time ago! Too long ago to remember..... Was it the Philipinnes?
Srt Marine Systems (LON:SRT) tipped again today by ST in the IC. He includes this additional information that has all, presumably, been gleaned direct from his discussions the company:
The other three contracts (worth £31m in total) are all expected to close before the 31 March financial year-end. SRT’s chairman, Kevin Finn, also notes that three other contracts worth £54m (two in the Middle East and one in Asia) have “unexpectedly progressed and could materialise during the current financial year”.
This really does look promising, potentially transformative.
I'm short USA technology stocks. Also, ironically I'm long gold miners which are very much unloved many of which pay good dividends – I can’t see how they’ll be able to control inflation by just increasing interest rates a few measly notches? They’ll more likely to crash the market at which point they’ll panic and revert course? And they can’t really raise rates too much because the USA deficit is huge? Any thoughts?
Ten Entertainment (LON:TEG)
Top banana trading update from ten entertainment the only surprise with the amount of superlatives they have included is that they are only at the top end of expectations. I am not getting excited about the amazing lfl’s currently being generated as repeating anything above inflation next year may be tough going - can’t ever complain about bumper trading when it happens though and more sites on the way is good news. Just waiting for management to award themselves a bumper set of freebie options at the exact time all the superlatives have been laid out on the table. Well done to hardworking staff and management here it must be nice to get back to something like business as usual. I remain happy holder at current price level.
I have been short ARK Innovation; long Uranium and O&G and long gold equities (mostly through the royalty companies) for 12 months. Ark has been my most profitable trade; Uranium equities are volatile as hell, albeit up for the year; O&G doubled and gold has gone precisely nowhere. My European/UK small caps are slightly better than break-even. 2021 was a strange year and I suspect 2022 is about to get even stranger. It sounds like our views are similar and I see no reason to change mine.