Small Cap Value Report (Thu 6 June 2024) - MTO, RFX, SUS. Briefs: FEVR, SPEC, GRC, WG.

Good morning, it's Paul & Graham here!
Webinar tonight at 18:00 - on how to use the StockRanks to pick the best value stocks in a recovering market. These occasional webinars are always fascinating and well attended, so I've set an alarm for 18:00 myself.
Roland has written an interesting article here which runs through his process for selecting high quality shares, well worth a read.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
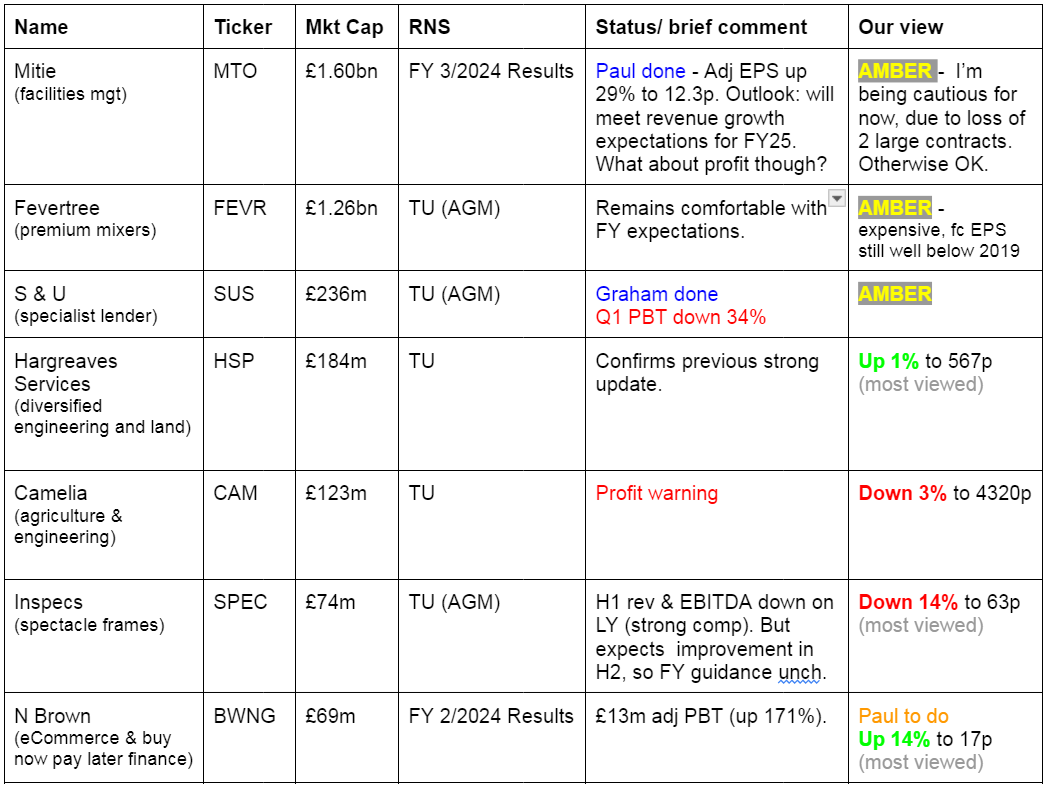
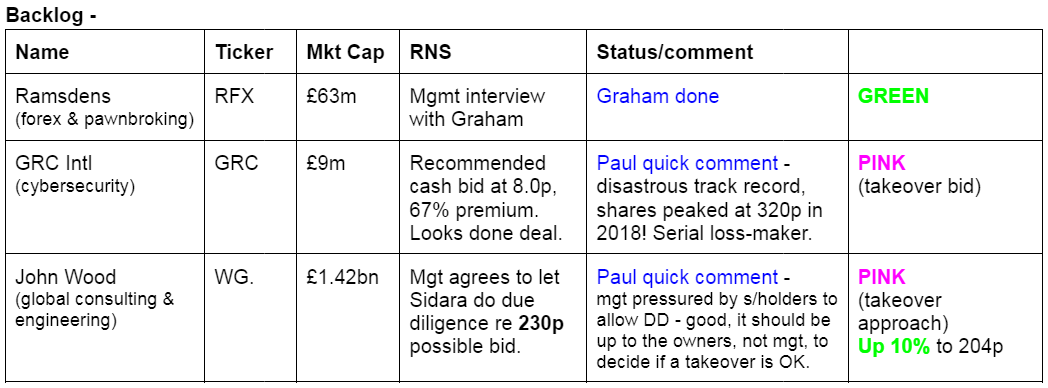
Companies Reporting
Summaries
MITIE (LON:MTO) - up 2% to 122p (£1.63bn) - FY 3/2024 Results - Paul - AMBER
Excellent growth in profit, but a slightly wobbly outlook due to loss of 2 large contracts. I have a proper rummage into the numbers below, and am generally happy that everything looks OK. Maybe I could have been a bit more generous than amber, but I want to see how FY 3/2025 progresses, given the lost contracts.
Ramsdens Holdings (LON:RFX) - 199p (£63m) - Graham - GREEN
I provide my typed up notes after getting a Q&A session with the management at Ramsdens. Nearly all questions were provided by readers and we covered everything from regulatory risk to competition to the company’s new travel card product. A great way to understand not just the company but also how management thinks about the challenges they face.
S&U (LON:SUS) - down 4% to £18.75p (£228m) - AGM Statement and Trading Update - Graham - AMBER
This update reveals a sharp fall in Q1 PBT as motor finance repayments have fallen further. Discussions with the FCA/Skilled Person are ongoing and S&U feel that they must be cautious in relation to how they approach repayments in these circumstances. I am similarly cautious on the stock until we have clarity.
Paul’s Section:
MITIE (LON:MTO)
Up 2% to 122p (£1.63bn) - FY 3/2024 Results - Paul - AMBER
I’ll start with Mitie shares (facilities management group) today, as the figures look good, and the valuation reasonable. I moderated my view to amber last time on 15/4/2024 because shares had risen strongly to 120p and I wondered if they were up with events?
A strong headline for the FY 3/2024 Results -
A record year of delivery
Revenue +11%; Operating profit +30%; EPS +29%
Here are some key numbers vs guidance, FY 3/2024 -
Revenue is massive at £4,511m (guidance: at least £4.5bn, tick!)
Adj operating profit £210m (guidance: at least £200m, double tick!)
Adj PBT £201m
That’s all good, but note that adjustments are considerable at £44.5m, making statutory PBT of £156m, 22% lower than adjusted PBT.
Closing net debt £80.8m (guidance: £85m, another tick) - NB this includes leases, it's actually net cash excluding them.
Contract renewals rate fell from >90% in FY3/23, to 79% in FY3/24 due to “the loss of two notable contracts”.
Adj EPS up strongly, 29% to 12.3p - giving a PER of 9.9x (looks decent value). This seems to be ahead of broker consensus of 11.1p - so I think it might be an earnings beat, but there are no broker notes available, so I can’t be certain (because figures are often worked out differently, adjusted in different ways, etc, diluted or not, so we may not be comparing apples with apples).
Total divis up 38% to 4.0p, yield of 3.3%, plus buybacks are ongoing too.
Huge order book of £11.4bn (up from £9.7bn a year earlier), and even bigger pipeline.
“Our divisions are all performing well”
“we have met or significantly exceeded all of the financial targets set out in the previous Three-Year Plan (FY22 - FY24), and this has been reflected in Mitie's Total Shareholder Return over the period (80% TSR; #10 in FTSE 250).”
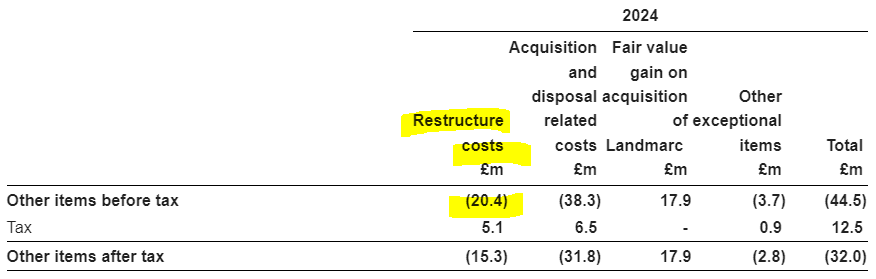
Adjustments to profit - are they reasonable? See note 4 below. I accept acquisition-related adjustments (usually goodwill) which is customary to adjust out, and is just a book entry and nothing to do with actual trading.
However Mitie seems rather too regularly to adjust out restructuring costs. £20m this year, and £17m last year. I’d argue that for a sprawling group like this (with 68k staff) there are always going to be parts of the group that need to be reorganised in the normal course of business. This is about 10% of profit, so I personally would adjust EPS down by about 10% to better reflect reality that these costs are real, and do seem to repeat in some form each year.
Outlook - this strikes me as sounding a little wobbly in the short term -
"We have secured a number of new contracts and projects in the fourth quarter of FY24 and first quarter of FY25, which give us good business momentum and we expect to offset, in the medium-term, the contracts lost and ending in FY24. Margin enhancement initiatives are also expected to deliver further benefits in the current year, and we will continue to generate strong cash flows and enhanced shareholder returns.
"FY25 will be another year of delivery towards our medium-term targets and meeting our high single digit revenue growth expectations for the year."
The key thing I look for in all outlook comments is simple confirmation that trading is in line with expectations. Mitie dodges saying that today, which together with the contract losses and comments above about medium term recouping the losses, suggests that there might be a question mark over performance in the new year, FY 3/2025.
Balance sheet - is not good. NAV of £474m includes £645m of intangible assets (mostly goodwill, but also includes £50m of capitalised software and development spend). NTAV is negative, at £(171)m.
Mitie had £245m in cash on 31/3/2024. It had £150m of gross borrowings (US private placement notes - unsecured, but with typical covenants it says have been complied with) which are mostly very cheap, at a fixed coupon of 2.94%, a canny move, with an average maturity of 10 years from 2022. Secure, cheap borrowings, good to see.
There also seems to be an unused £250m RCF to Oct 2027.
Overall then the liquidity position looks comfortable, hence I’m not overly concerned about the negative overall NTAV.
Average daily net debt is the key additional disclosure we need from all companies, and MTO gets a gold star from me with this disclosure -
The Group uses an average net debt measure as this reflects its financing requirements throughout the period. The Group calculates its average net debt based on the daily closing figures, including its foreign currency bank loans translated at the closing exchange rate for the previous month end. This measure showed average daily net debt of £160.7m for the year ended 31 March 2024, compared with £84.3m for the year ended 31 March 2023.
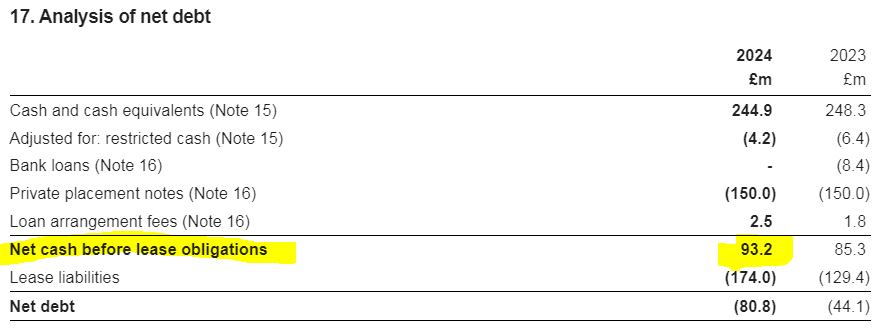
Note the Mitie seems to include lease liabilities in its figures, whereas I want to see the net debt excluding leases, which better reflects reality in my view. Leases are future operating costs, not debt (since they can’t be withdrawn, don’t have covenants, etc, so completely different to other forms of debt).
Here we are, note 17 shows that Mitie is actually holding net cash excluding leases, so I wonder why they haven’t given proper prominence to this favourable point? A presentational own goal here - which makes the group look higher risk than it actually is -
Overall this looks fine I think.
Note that there is almost nothing in inventories, which means Mitie can operate OK with a leaner balance sheet than say a manufacturing company which would have to fund substantial inventories.
Large and public sector clients can often be good payers too (with little to no bad debt risk), if favourable payment terms are negotiated into the contracts, which it looks like MTO already does.
Pensions - the cashflow statement shows £13.2m in “defined benefit pension contributions” going out, so it looks as if there are still deficit recovery cash outflows.
Note 19 indicates that £18.1m + £22.1m was paid into defined contribution, and auto-enrolment schemes, but these are fine because they go through the P&L statement as a payroll cost. No problem there. It’s the defined benefit pension schemes that are a menace if they’re in actuarial deficit, because deficit recovery cash payments do not go through the P&L, so they’re an additional cash outflow with money that could otherwise have been paid out in divis. Hence why shares with big deficits on their pension schemes are usually priced on low PERs to adjust for this. Although higher interest rates are causing some big improvements in some pension schemes, so an interesting area with potential opportunities.
It seems that the deficit at Mitie has indeed improved dramatically, and hence I think we can tick off pensions from my list of potential concerns, as not being significant -
The most recent triennial valuation was carried out as at 31 March 2023, which indicated an actuarial deficit of £19.4m, an improvement of £72.7m since the last valuation. During the year, Mitie paid £10.6m of deficit repair contributions and the Group has agreed to pay total deficit repair contributions of £22.5m over the next four years.
Cashflow statement - share based payments of £20.3m (LY: £17.3m) is almost 10% of operating profit, so management have got their hands deep in the till.
Post-tax cash generation is much better this year at £198m (LY: £83m) but that’s mainly due to a large negative move in receivables last year reversing this year. I would deduct £41m in lease payments too, which appear further down.
The main use of the cash generated is £34m acquisitions, and shareholder returns of £78m buybacks, and £42m divis paid.
So it’s a genuinely cash generative business that is mostly using that cash for shareholder returns, pretty good.
Paul’s opinion - hopefully I picked up all the main points there. Annual accounts are a good opportunity to have a good rummage and find the things that companies don’t want to tell you in their trading updates!
I can’t find anything serious here, it mostly looks pretty good.
My main concern though is the outlook section, where two lost contracts is clearly having some impact on FY 3/2025. I’m worried that this could cause brokers to slip through some moderation of the forecasts perhaps? Maybe not, and the valuation is quite modest really at about 11x existing consensus for FY 3/2025. Although if I make my adjustment for reversing the restructuring charge, then I get to a higher PER of about 12x. That’s not expensive, for what is a pretty impressive, large and cash generative business.
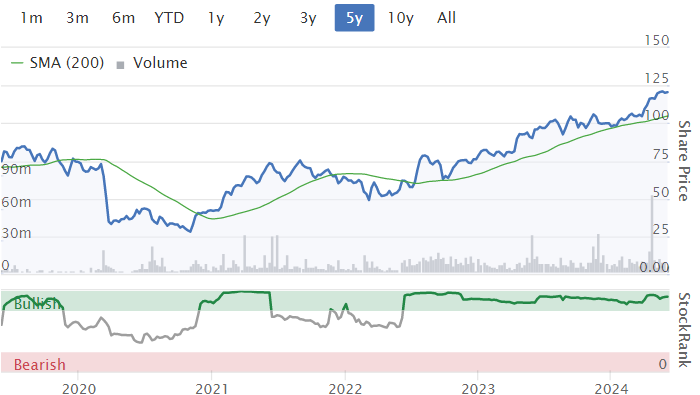
Let’s go with AMBER for now, as I’d like to see how the lost contracts affect the new year’s numbers before becoming more bullish, and the shares have had a lovely run from the 2020 lows, quadrupling. It’s in a nice up-trend, which might attract momentum buyers.
Very good StockRank of 92.
Graham’s Section:
Ramsdens Holdings (LON:RFX)
199p (£63m) - Graham - GREEN
Many thanks to readers for submitting your questions for my Q&A with Ramsdens Holdings (LON:RFX). I asked almost all of them.
Here are the written notes from my conversation with CEO Peter Kenyon and CFO Martin Clyburn.
Q1. Regulation.
I asked if the company was currently worried about the possibility of changes in lending regulations, especially with if there was a change in government.
A: They would be exceptionally surprised if the FCA changed the way they act towards pawnbrokers. There is a high bar in the UK on regulation, and some pawnbrokers do find this frustrating and exit the market. But pawnbroking is centuries old. The FCA knows that their previous actions have already had a huge impact on payday loans and doorstep lending.
Q2. Staff costs.
I asked about the company’s experience of wage inflation over the past 12 months and how they see it developing over the next year?
A: The real living wage has increased 10% in each of the last two years. Ramsdens has not responded by increasing the interest rate charged to pawnbroking customers, but there have been adjustments in the FX margin and the retail margin. They do not think a 10% increase every year is likely or sustainable, and they do not think there will be a 10% increase next year. Of course a Labour government may want to see a faster increase in wages.
The point was also made that Ramsdens is diversified and provides a range of goods and services. Wages aren’t the only cost and the company can efficiently spread out the impact of higher wages across its operations (vs. competitors where wages may be a higher percentage of their costs).
Q3. Competition.
I asked how they are finding competition during their expansion and generally, not just against their main pawnbroking competitor but also against smaller/independent operators.
A: They gave an example of Warrington where Albemarle Bond used to be active, but where Ramsdens and H&T are now both successful. In general, they can succeed in a town with a population as low as 9-10,000. But there are c. 350 towns across the UK with a population of 30,000 or more. So there are plenty of opportunities.
Another benefit of being diversified is that they can provide jewellery, pawnbroking, or whichever other services are most in demand in a particular area. They have also found that the high street in some ways offers weaker competition than it did before as travel agents have moved off the high street and jewellery chains have been shrinking their estates. Independent pawnbrokers often struggle to get the banking facilities which might enable them to expand to their 2nd or 3rd stores.
Q4. High value customers.
I asked about the “past due” number rising by £500k in yesterday’s results, due to one high value customer. Can they reveal how many high value customers they have and give information about the security on these loans, as we found it quite surprising that Ramsdens had this sort of exposure?
A: They helpfully revealed that they only have two customers with borrowings of more than £100k. One of them has borrowed on a watch, and the other has borrowed on gold jewellery. The interest rates on these loans are lower than Ramsdens normally charges, as they are high-value loans. However the loan-to-value is within the 75% limit that applies to all Ramsdens loans.
Q5. Travel cards.
I asked how Ramsdens can compete with a prepaid travel card product seeing as travellers have many similar products to choose from.
A: Ramsdens has had over 1 million customers. They have 168 stores that customers can walk into and touch. And they think their prepaid currency card is a better product than the card offered by the Post Office.
When it comes to the likes of Revolut and similar online offerings, they think those products are less straightforward for customers than the Ramsdens travel card, and they query whether these products make any money and if the companies behind them will be around for the long-term.
Q6. Travel cards part 2.
I asked if the company shared customer concerns that prepaid travel cards might end up with large amounts of money left on them, that people might find it difficult to get their money back out of them, and that customers might suffer high fees for refunds.
A: They do think about this issue and answered this question in a number of ways. Firstly, they pointed out that it’s normal for travel cards to start charging utilisation fees on unused balances after 12 months. Their own card does not charge these fees for 18 months.
Secondly, they said that in partnership with Mastercard, they do speak to customers to urge them to make sure that they use their card! They want this product to succeed because customers are using their balances on holiday, not through fees on dormant balances.
They also pointed out that the prepaid card can be topped up in real-time, while on holiday (at a competitive price). So people don’t need to add more than they intend to use. And if they wish, they can always convert back to Sterling and use their remaining balance when they get home.
Graham’s view: this was a very helpful interview for me and I hope you have found it useful, too. I feel more knowledgeable about this company than ever before! And I’m happy to maintain a positive stance on it.
Huge thanks to Tommy H, davisj99, cheeky_minnows and ridavies for all the questions, even if I didn’t get around to every single one of them.
S&U (LON:SUS)
Down 4% to £18.75p (£228m) - AGM Statement and Trading Update - Graham - AMBER
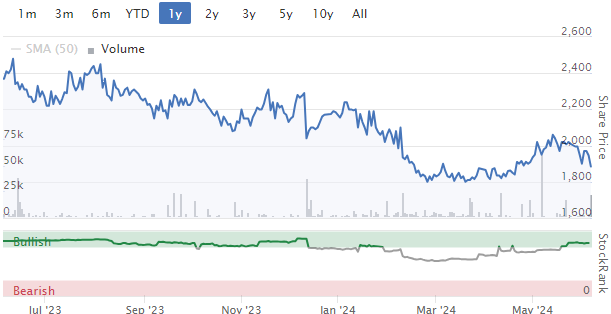
I was previously a huge fan of this stock, and in many ways I still am. However, I have felt obliged to take a neutral stance due to some regulatory question marks hanging over it (for the avoidance of doubt, I am confident that S&U have done absolutely nothing wrong. But I do not know if the FCA will agree.)
The share price over the past year has reflected these concerns:
Today’s update continues the theme.
In relation to the motor finance division (“Advantage Finance”), we have the following news:
At Advantage, our cautious approach to repayments in the light of continuing discussions with the FCA and Skilled Person on interpreting and adapting to the new Consumer Duty regime and the sector wide review of Borrowers in Financial Difficulty, have had a significant impact on repayments and profitability. We anticipate that these discussions will be concluded during the second half of the year, when we will welcome the new regulatory clarity which will provide a strong platform for the continuing growth of the business.
I’m sure that investors will also welcome clarity, and I’ll be glad to take a “GREEN” stance on S&U again, when it’s clear what we are dealing with in terms of regulatory action.
The result of these circumstances is that Q1 PBT is only £6.9m (Q1 last year: £10.5m).
They say: “Increased impairment provisioning arising from the lower repayments at Advantage accounted for £3.6m of this reduction [in PBT]”,
If my maths is correct, this means that a normal repayment experience would have resulted in a flat PBT performance.
Forecasts published by Edison in April this year suggested that the full-year adj. PBT result would be £37.3m. S&U tend not to use many adjustments in their results so I’m inclined to treat this as a forecast for clean PBT.
That being the case, Q1 PBT of only £6.9m leaves a lot of work to do over the rest of the year, if the forecast is to be met.
Advantage Finance
Some more detail that is worth emphasising:
Advantage's discussions with the regulators mainly revolve around affordability and forbearance, arising from the FCA's industry-wide focus on borrowers in financial difficulty. These come as industrywide used car advances are 7% down on 2023, accompanied by a 6% fall in transaction numbers. However, demand for Advantage's products remains strong…
Due to S&U’s caution in this period of regulatory uncertainty, live monthly collections have reduced from 92.1% at the end of January to 87.7% in Q1. But there is hope:
Belated recognition by regulators that for some customers repossession may be the best outcome, is gradually seeing a return to normality. Hence Advantage's empathetic and flexible customer relations are also expected to resume in the second half of the year.
Live collections had previously been as high as 94% - see my report in Dec 2023 when I first switched to a neutral stance on this stock, noting that collections had started to drop off.
Aspen Bridging
This property finance company continues to grow with advances in Q1 more than doubling year-on-year. PBT in Q1 was £1.45m, and ROCE reached 11%.
Comment on the outlook for Aspen:
More promising still are signs in the UK residential market of an increase in sales instructions and prices. Nationwide recently reported the latter up 1.3% on last year, despite a delay by the Bank of England in reducing interest rates. Aspen expects both favourable trends to continue and possibly accelerate.
S&U’s borrowings: £237m vs. facilities of £280m.
Chairman comment:
Although fully cognisant of the challenges currently being negotiated at Advantage, an improving economic outlook both for consumers and businesses, a strong labour market and greater political stability will all benefit S&U over the coming year. We wrestle on with confidence."
I’ve remarked in previous articles on how downbeat he has been. This is the most positive collection of words I’ve heard from him in a while!
Graham’s view
The situation at Advantage is fluid with a range of possible outcomes over the next 6-12 months. Will the regulators do nothing (unlikely), make cosmetic changes (quite possible) or could they seriously hamper S&U’s ability to trade? Could they find instances of wrongdoing by S&U?
The problem for investors is that it’s often very difficult to predict what view a regulator might take. But based on what I know about Advantage Finance, it seems to me that it’s a responsible and reasonable lender. So I don’t expect that it should face any worse outcome than any other lender in the industry.
But with the regulatory review ongoing, I still don’t think I can raise my neutral stance.
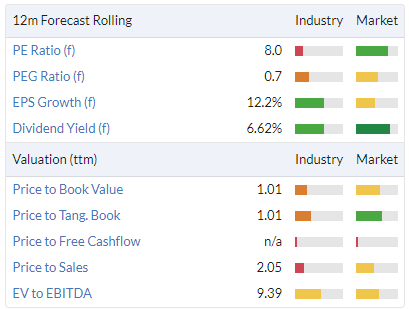
For those with even more confidence than I have in S&U, the shares can now be purchased at a very reasonable valuation offering plenty of upside when the dust settles. But personally I’d prefer to wait until I know for sure what the FCA is thinking.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
Will anyone have chance to catch up on the ones missed so far today, mainly BWNG for me?
Much appreciated....
Hi Paul. Thank you for the write up on Ramsdens Holdings (LON:RFX) interview. These are always very interesting. Could you post your view on your impression of these two directors. I’ve met Peter Kenyon a few times myself and have always been quite impressed with him.
keep doing these interviews. They make a nice addition.
My apologies, I meant Graham.
Reach (LON:RCH) Currently 91.2p
Referring to Grahams write up on 2 May 2024:
RCH qualifies for John Templeton Bargain Screen (Value Investing). Lombard Odier and Welcome Trust have been adding to their holding in RCH in recent months.
I bought some a few days ago, thinking.of topping up. Happy to hear your thoughts.
Bought as well three weeks ago (for trading purposes though).
Where do you see the growth coming from that will re rate the current PE and dividend yield status?
Reach (LON:RCH) is a company with declining revenues that has gone into debt as well recently.
Though technically looks that it can climb to 120p and probably it will with the current market conditions.
All the best
To be honest, I have to confess I have not done much in-depth research, so am unable to answer your question. My decision has been based on recent bullish chart signals and also potential to perhaps edge towards broker generated fair value estimate of 147p. Depending on how things pan out, this could be a short term trade or a longer hold. Graham is of the view that "management is running a tight ship, with a clear focus on profits and cash flow."
Fevertree Drinks (LON:FEVR)(I hold) I am more bullish than an "Amber"- in2018 it was on a PE of 60. New range of mixers and overseas growth look positives to me. The brand name is strong and I would not be surprised to see a bid from one of the majors in the industry. I bought in recently.
You tempted me to read Fevertree Drinks (LON:FEVR) 's AGM statement. A masterpiece in taking three paragraphs to say convey no useful information whatsover.
Does anyone else find this highly frustrating? I mean what's the point? Especially for a company like Fevertree which probably has a good forward story to tell.
I only glanced through it- there have been a few articles in the press over the last few months- Times being one- which suggests the new ranges are doing well. They are apparently now the No 1 ginger beer brand in the "UK and US and in Europe, as well as Canada." Non-tonic lines are 40% of global sales. That it was interested me back in March this year
Fevertree Drinks (LON:FEVR)
use the force luke comes to faith with fevertree - you just have to have the faith. Perhaps reading the narative of the trading updates over the last 3 years would get you up to speed - they are normally reasonably telling us how it is in this updates and most of the woes speak for themselves (ref profits).
Main issues are that their costy increases have been very high - eg the price of glass.
USA - thats a big country and its going to be alot harder work to get super efficient there so that all the stuff is done and shipped at minimal cost - particularly as they move into new areas and scale up.
One should expect as they are in decent growth phase at present in the Us and other parts of the world they are probably more likley to accept lower margins / change less till they become more mature .
so whilst their bottom line profit increases most definately have shown woeful progres over the last 5-6 years - ref sales and new marketplaces they had done pretty well builidng out the worldwide brand - albeit i have been dissapointed with progress in most of their non core stuff - that would have been cherry on top though - its not that they are making no progress.#
There has to be doubts as to whether margins will ever ghet back to teh good old days - there is probably more copmpetition now so i suspect they are now more competitive on price - and those extra few pennies on each sale are all profit when you fdont keep margins fixed
In summary i think this is a much better company thank it probably looks - i dont think they are going backwardss or even standing still - and the 2025 numbers (presuming they hit targets) to be expected do evidence that they seem to have turned the corner ref obvious headwinds previously
This used to me my number 1 holding but i sold out completely a couple of years ago as imho with the struggles they had at the time 2500 plus seemed like really godo exit point. I would fully expect this share to get back to 2500p - but its not the same profit making machine that i was attracted to in the first place and its never quite been top of my list when choosing where to invest funds since i sold out completely - with 50p eps and shareprice around 20 times earnings though i may buy back in sometime soon - i fear though if they maintain progres into 2026 ref increasing profits then price may not stay where it is for long.
slightly surprised they havent had to fend of hostile bids if i am being honest - seems like perfect type of company for anyone to snap up if its reasonably clear that profits wil bounce back.
Have been enjoying the recent calm and measured discussion on these boards, would be great if we could please try to keep it that way. Just for clarity, this is a general comment which should not be seen as being directed at any individual poster. :)
Different opinions in a forum so I can’t see where is the problem. After all there must be a buyer and a seller that obviously have a totally different opinion for a transaction to take place!
The prime minister and his wife are tax dodging and there is a problem with all these conglomerates that employ so many people and have injected in their operations so many billions! Imagine ONLY ONE Amazon factory until it becomes fully operated how much money has gone into the UK economy (builders , joiners , plumbers etc etc etc etc).
All the best
Think balanced views and opinions are good, but guess some live in a sugar coated world...
Not sure why Palace Capital (LON:PCA) has gone down today- a tender offer has been announced. Appreciate the board have written down NAV but seems an odd reaction. Details of tender will be announced later this month. Shore Capital have just rated as a buy.
Jersey Oil and Gas (LON:JOG) Simon Thompson small cap oiler favourite that farmed out to NEO Energy and Serica Energy (LON:SQZ) dropped 20% yesterday as the main partners want to wait to see what the new government's policy will be for oilies before further progressing.I think they're mostly concerned about the possibility of investment tax relief being scrapped, which could make it a no go for them perhaps.I was considering a buy as Jersey Oil and Gas (LON:JOG) seems to jog up and down a lot in price but not so sure as it's going to be a labour government barring.....?!Alot of other oilies are naturally already moving exploration/production away from the north sea including Harbour Energy (LON:HBR) and Kistos Holdings (LON:KIST), whose ceo is a punter's favourite after his previous oilie success in the north sea at Rockrose Energy (LON:RRE^I20).
Hi Graham,
Many thanks for putting questions to Ramsdens Holdings (LON:RFX) , very much appreciated.
hi Graham
Ramsdens Holdings (LON:RFX) - I hold.
Many thanks for your notes on your meeting with Management. I found this very useful additional information.
Management must be frustrated with the lack of credit the market is giving them for consistently strong results post-Covid. I fear this will continue for some time with two active large sellers (both holding around 10%) in the background (Close Brothers and Downing) who are creating a large overhang in the shares.
It may take some time for a re-rating to occur although patient investors are being rewarded with a 5.5% dividend yield while they wait.
Perceptions remain that Ramsdens is a pure cyclical pawnbroker but, unlike H & T (LON:HAT), they have a much more diverse business mix with 4 roughly equal divisions (pawnbroking, forex, retail jewellery and gold) which makes, imho, more appeal to private investors.
Snazzy
Ramsdens Holdings (LON:RFX) Always looks cheap and has always been cheap. the market doesn't want to give this a rating above a PE of 9ish. can see this moving sideways as most better stocks, re-ratings and turnarounds race higher.
Latest PMI shows a further strong rise in UK construction activity - should be good for the building material and construction firms.
Decided to put in a small order with my broker for Raspberry Pi IPO - should generate some excitement and possibly some profit!
Raspberry Pi Foundation, the principal shareholder will be selling $35mn of shares to semiconductor and software designer Arm and up to $20mn of shares to investment manager Lansdowne Partners, both existing shareholders, in the IPO.
Do you have the ISIN for Raspberry Pi? Can't see it in the published docs
Hopefully this link will help.
.
Raspberry Pi prepares for London listing
Low-cost computer maker, which sold 7.4mn units last year, seeks valuation of $630mn
I found the video quite interesting.
https://archive.ph/qQTzc#selec...
A couple of small but interesting orders for Concurrent announced this morning.
Live on Vox Markets at 9.30am tomorrow, I will be interviewing successful investor Richard Crow (alias Cockney Rebel).
Here we're planning to cover lots of stock ideas including favourites CMC Markets (LON:CMCX) , Zotefoams (LON:ZTF) and, Warpaint London (LON:W7L), alongside #FCH, #GNC, #IGR, #LIO, #LUCE, #MPAC and #SYNT.
Plus we'll be trying to answer any questions you might have. So please feel free join us here on Youtube. Everyone is welcome. Lots to discuss.
N Brown (LON:BWNG)
13.3m Adj EBITDA and £5.3m PBT are above market expectations.
Cash and cash equivalents £65.2m. Net debt £236.3m.
Gradual improvement in trading expected FY25
Would be good to get Paul/Graham's take on the results. tia
From the price action in Mobico (LON:MCG), looks to me as if it had fallen so far out of the FTSE250 boundary, most of the selling had already happened before the index reshuffle announcement.
Mobico (LON:MCG) is cheap as chips and is a consumer staple so is low risk. But is there a catalyst for a re-rating?
To me it seems a little odd that investors keep taking their money out of UK equity funds - especially as the major indices have performed relatively well so far this year?
"£1.11bn of redemptions in May, of which £792m was from actively managed UK funds".
The Mag 7 attract a lot of press, so the public will follow these type of funds, not the boring old FTSE250.
ASML Holding NV (NSQ:ASML )news that they're delivering their new EUV lithography machine to Taiwan Semiconductor Manufacturing Co (NYQ:TSM) later this year caused another huge semiconductor rally yesterday.When will it stop?Although a new machine means even more advanced semi production and thus more AI y type future developments posssibilities sooner.
Palace Capital (LON:PCA)
To return £22m to shareholders through a tender offer, details of which will be announced shortly following consultation with major shareholders the largest being Peter Gyllenhamer with slightly over 13%. Christopher Mills in various guises has an interest in over 17% , e.g. Harwood Capital and J O Hambro Capital Management.
There is a lot of detail in the prelims that I am still working through, but property companies in a net cash position are a rarity. I hold. A second tender offer is also referred to
"An additional tender offer is likely to take place later in the year as further property sales are completed."
I hold.
Hargreaves Services (LON:HSP) Slightly better-than-expected profits for year-end May 2024. Services unit grew profits. Land unit had strong second half with notable deals, record profits. German joint venture improved in second half after tough start. Year-end cash £22.7m, leasing debt reduced to £28.6m. Expects to report Profit before Tax (PBT) "marginally ahead of market expectations "
Fund managers give cool reception to prospect of Shein London IPO
UK fund managers have warned that investors will “struggle to support” fashion company Shein’s potential blockbuster flotation in London over concerns about its alleged treatment of workers.
“Given the corporate governance . . . issues, a Shein IPO could clearly have negative reputational impact on the UK market.
James Alexander, chief executive of the UK Sustainable Investment and Finance Association trade body, said: “The notion that certain companies with particularly poor human rights practices and sustainability credentials could choose London as a listings destination will not help to make us more competitive in the long run.”
https://archive.ph/R2TCK
Tax dodgers, and poor conditions for workers...
Asos and boohoo didn't get away with it, Shein is next for a clean up which will mean they have to increase selling prices...
The tax avoidance makes my bull boil, unfair playing field for UK business in their home country. You would not see that in China. It needs sorting (the small packets loop hole).
I’m not sure the labour issue will be sorted, we seem to be quite happy as a society, with low prices, but only if the bad conditions happen abroad.
It’s a real issue for UK growth.
Not sure what the solution is, more red tape and import checks at the border is not what the UK needs.
Let’s be fair and equitable here.
Shein are Chinese and attract our criticism .
But compared the billions laundered from our economy by Jeff bozo at shamazon , Googke , Facebook with their tax dodging transfer invoicing and horrible in our faces manipulation this is small change.
So hopefully Labour have the balls to take on the real modern day robber barons not only a Chinese mail order clothing company .
But Labour can’t win because those guys will spend trillions on the best tax avoidance defence and yet everyone keeps buying from Bozo .
And investors keep buying the shares of the tax dodgers because they make huge profits at the cost to our national economy yet when can make a few quid everyone thinks it’s not so bad .
First serious rant of the day. Enjoyed it! Keep 'em coming.
This drives me crazy too! Companies like Amazon, Google, Shopify, etc., have become so dominant that you have no choice but to use them, especially, like me, if you own an e-com business. Not being on Amazon or eBay means missing out on 50% of the market. It really frustrates me when I receive invoices from Amazon, eBay, and Google without any VAT applied. I get taxed when I buy essentials like toilet paper and toothbrushes, but these massive corps seem to avoid it. I always laugh at the £109 Regulatory Digital Services Tax on my Google bill.
They employ thousands of people in the UK that pay taxes , VAT and at the same time have a roof over their head and food on their table.
All the best
I employ people, pay tax, pay VAT, pay UK corp tax and keep roofs over heads and food on tables too. But i still pay VAT and UK corp tax and don't off-shore it to Ireland.
But you don’t necessarily employ thousands and contribute billions to the UK economy.
That’s the difference!
He also doesn’t invoice all his sales via Ireland and avoid paying corporation tax on profits or vat on sales .
It’s a national disgrace don’t see how anyone can credibly argue a counter point .
There is a reverse charge here and before you comment you have to understand the accounting issues involved and the arrangements between the companies and the governments before operations begin.
Yes it is a national disgrace when someone does not want to understand how much these giants offer to the UK economy and its people.
How is it fair if you have Costa Coffee when it was owned by Whitbread (LON:WTB) paying UK taxes and Starbucks selling the same product but with a tax advantage. You could say the same about Amazon Food and Ocado.
agreed
we all know the place to source coffee from is swizerland - they would never be buying from subsiduary there to minimise uk taxes - hmmmm . ok lunch time now off for my double Irish with a Dutch sandwich - i have heard that always does the job.
That’s how tax issues and domiciles work.
The advantages of these companies operating here and the contribution to the UK economy are much more important.
Have a look also where British conglomerates (also doing business in foreign countries) pay their taxes!
All the best
The point is i would employ more people, feed more families, give more to charity etc if my taxes were lower like Google, shopify, starbucks, amazon, etc
Also, if Google, amazon, starbucks etc left the UK, other firms who pay the correct taxes and who employ 1000s of people would take their place.
All the best
Google and Amazon to leave the UK??
And other some kind of fantasy UK firms take their place??
You do realise these two companies combined market cap is bigger than the GDP of the UK.
I do understand your arguments though but i have to say that it is the same tactics employed by UK firms as well operating in foreign countries.
Intel (NSQ:INTC) has recently announced a further investment in its Kildare factory ; AI investments that will probably change our lives in the next 10 years or so (billions of further investment along with Apollo that will benefit the Irish economy) and we are talking here about Amazon and Google to exit the UK!
On another note a very knowledgeable friend (still works in the City) has alerted me recently on the next Conservatives leadership favourites: Kami , Penny , Suella , Cleverly, and Priti Pattel.
One of these will probably be the next opposition leader (no further comment needed),
Time to slowly cut down some positions.
All the best
Also worth remembering that our UK critical defence and intelligence network is hosted on - Amazon Web Services.
Not easily replicated by your average mom and pop business.
aws is just remote servers. But it just shows how enthralled the uk is to these huge businesses
Hi intuitive6191,
Correct but sadly surprised that some people think that Amazon sells just some cheap toasters!
No need to comment further as people ignore the VAT reverse charge (something that the UK companies adopt as well!) just to support an argument that it is not there.
Recently a new warehouse has opened North of the country and I happened to be briefed in detail on how this has benefited the local community in general by creating thousands of jobs in a series of chain events.
All the best
My point stands, why should some companies pay VAT and some get away with it? i'm sure we can get our cheap crap from other online retailers, use other cloud computing companies, use other search engines and maps etc. The UK gov doesnt have the balls to take these cos on.
Why should some companies pay VAT and some get away with it
Companies don’t pay VAT - they collect it on their sales and net off the VAT on their purchases, remitting the balance. It’s the consumer that pays the tax! I’m not arguing that tax avoidance doesn’t change the perpetrators’ competitive advantage - see Shein vs BooHoo - but you’re framing the argument inaccurately.
Personally, I don’t care much about multinational tax avoidance - ‘twas ever thus. It’s the hopeless lack of industrial policy that has left us flailing in the wake.
BnB,
Nicety said as always and thanks for explaining the VAT reverse charge and the failing of the UK’s industrial and business policies for the last 20 years or so.
All the best
I notice you have chosen to ignore the fact we lose out on taxes when these companies bill non vat registered customers in that regard HMRC lose out on 1/6 of the cost paid that’s billions per year in lost taxes. For no logical reasons other than the authorities being stupid
Ditto where small items can be sold from outside uk with no vat accounted for
Companies don’t pay VAT - they collect it on their sales and net off the VAT on their purchases, remitting the balance. It’s the consumer that pays the tax!
Practically speaking though sometimes they do on like for like basis and that’s the point here
if we take company a based in uk and they bill non vat registered business for advertising services they remitt 1/6 of the funds received to HMRC
If it’s Google or Facebook they can charge the same all in price to the small uk business and they remit nothing to hmrc
Facts are they get to keep 1/6 of price charged where same uk company does not - how is uk based company meant to compete against that and how can anyone not see that this is sucking huge amount of cash that should be going to uk government into the pockets of companies based overseas
These companies make huge margins they will pay up like everyone else if we make them but we are that stupid that we don’t !!! It’s crazy
BnB
Companies don’t pay VAT - they collect it on their sales and net off the VAT on their purchases, remitting the balance. It’s the consumer that pays the tax! I’m not arguing that tax avoidance doesn’t change the perpetrators’ competitive advantage - see Shein vs BooHoo - but you’re framing the argument inaccurately.
That is not correct, if I employ a non VAT registered decorator (Amazon) to paper my hall stairs and landing and he charges me £2000 the HMRC gets no VAT, if i use a VAT registered decorator and he charges me the same £2000 the UK gets £333 VAT , therein lies the problem.
Third party sellers are exempt sometimes and this is declared prior to your purchase.
They are exempt following the regulations here in the UK!
They are exempt following the regulations here in the UK!
we know these companies may be following the rules - that doesnt alter the obvious loss of revenue that could very easily be rectified
i have clients who do odd jobs aborad and may need to register for vat in that country - i have clients who have sold modest amounts to other countries and need to register due to distance sales rules - i have clients selling modest amounts where i have to account for vat at approrpiate rate in every country they sell too and submit that info each monthn pronto.
and yet google and facebook can sell into the uk probably in the billions each year and not be vat registered - the fix to level the playing field is so simple - simply make them acount for uk vat like everyone based here.
Bigger issue for me BnB is its estimated 20% of the working age population 16-66 don't pay any tax so you have nearly a fifth of the population taking out but not paying in, a lot of these will be students who hopefully will go on to decent jobs, I don't know what the answer is but can only see it getting worse as the 55 plus working generation who pay lots in start to retire and then start drawing out also via state pensions , medical costs etc.
There is a reverse charge here and before you comment you have to understand the accounting issues involved and the arrangements between the companies and the governments before operations begin.
the reverse charge is as about as useful as a leaky sieve at minimising vat loss and vat fraud - as per my earlier post if small business non vat registered uk person pays google/facebook for adverts hmrc do not get the 20% they would get from that buisness paying similar uk based advertising agency - they probably will also miss out on corp tax to in all likelyhood and employment taxes.
wouldnt surprise me if indeed based in ireland become the biggest uk jobs - anyone who cant see cash being syphoned out of uk without fair taxes being paid has to be pretty blind imho.
Heck uber didnt pay vat for yeare trying to argue they didnt provide tgransport - eventially when clobbered they are now a tour operator when you hire a ataxi !
if nothing else the gov should be going out of their way to provide "fair playing field" as starting point for all uk companies trying to compete with overseas compitors.
facts are these giants can still make amazing profits whilst paying their fair share of taxes - i would agree its up to the powers that be to implement fair rules - we cant expect these companies not to minimise taxes they pay -so its no real criticism of them - but lets not pretend 30%+ of uk spend in certain areas going mostly overseas with very little paid to uk plc is good for your average person !
its 100% up to the powers that be to sort this current powers that be have completely failed - its not exactly hard to identify these firms and set apporpriate new "tax" that equalises things - particularly now we dont have the excuse that we are part of the EU. any company selling more than £5 mill of stuff into the uk should be monitorted assessed and levied as appropriate if needs be. Bloody disgrace that if your local, non vat registered plumber pays to advertise with uk firm - the gov keeps 20% vat - wheras when they advertise with indeed/google/facebook the gov gets nowt - facebook and google probably have 50% of all small business advertising now based on stuff i see - and the fact uk plc vat authorities lose 20% there (where small trader is not vat reg) - is a scandal. We dont need any overseas company doing business in te uk - and every large company structured to avoid uk taxes should be squeezed suitably as part of teh deal that they can extract how hard earned cash out of the uk - thats another problem in that when it goes to these overseas companies the cash isnt recycled and spent in the uk often (i accpet that situation where fair taxes are being paid)
Not sure how the torries can have got this so wrong as its not exactly a vote loser slapping extra traxes on multinationals - oh let me think who do the friends family and partners of alot of mp's work for - hmmmmmm
I would doubt that any Government, Labour or otherwise would make this a priority.
Restricting cheap goods and'or making the man in the street pay more for everyday items that they have become accustomed to sourcing cheaply online isn't an obvious vote winner.
indeed its crazy how James Alexander cant take the factual positives here that listing in london is likely to do more to ensure better ESG concerns/conditions for people doing business and working for Shein that if they dont list her. He coluld also have taken a positive approach and said - clearly red flag company but we would lok forwward to engaging with the board to enusire positive change is enacted. IMHO oeople like this who deman deveryone should do exatly as they see their ideal world being when there iz pretty much zero obligation for that to be doine are living in cloud cookoo land. Not sure if he has ben misquoted or he poorly worded his statement but imho this sounds like exactly the wrong kind of person to be in charge of improving standards - it must involve work form both sides in positive fashion. Hey ho i am sure he is well paid for taking his nice moral stance.
International (legal) tax avoidance can only be dealt with by an international agreement including US EU etc. But some moderate changes could be made if there were political will.
Part of the problem is political parties are obliged by "convention wisdom" to listen to big business..... but the big businesses self interests have outgrown every country on the planet.
Selling through a tax loophole is always a risky business.
Will be interesting to see how a new Labour government will position itself: closing the tax loophole and expressing concerns about labour issues in their supply chain; or alternatively wanting to be seen as welcoming an important new listing, supporting the attractiveness of London as a market.
I suspect reading between the lines them disclosing talks had taken place with Shein, the balance might rest with the latter
What has happened with Ali Express is that they now charge VAT on orders to the UK. I don’t know why or the circumstances behind it. Should be possible for all businesses if they can do it
That was an EU initiative that the UK adopted just before Brexit.
The site is now charging VAT but sending fakes into the UK, and still advertising on Google. I was looking at a new bike frame for £5.5k the other day in the UK, Ali Ex are selling a fake one for £600.