Small Cap Value Report (Thu 7 Dec 2023) - PMI, SMS, POLX, TEG, BMY, SDI, VTU, FUTR

Good morning, Paul & Graham here. Catch-up day today.
We'll leave it there for today.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Premier Miton (LON:PMI) - up 2% 61.7p (£90m) - Full Year Results - Graham - AMBER
This has been one of the hardest-hit fund managers, being UK-centric and exposed to the outflows from UK shares and the weakness of small-cap and mid-cap valuations. I do think it will recover along with its peers, but I would like to see it develop some unique selling points.
Smart Metering Systems (LON:SMS) - 680p pre-market (£906m) - Agreed cash takeover bid - Paul - PINK (takeover)
Another takeover bid! This is agreed by management, at a 40% premium, 955p all cash bid. The buyer is American global investment firm KKR, which will put SMS within a $17bn fund focused on infrastructure investments. With the offer price being close to the all-time high, I don’t think anyone can complain that they’re being short-changed.
We’ve not covered this share in the SCVRs before, so don’t have a view on it. Well done to any holders here! [no section below]
Polarean Imaging (LON:POLX) - 5p (pre market) £11m - Company Update - Paul - RED
A long overdue update from this disastrous share, a cash-burning blue sky project that needs more funding. Today's update gives us some positive-sounding operational snippets, but nothing firm about how it's going to raise more cash (runway is getting short now, at Q3-2024). So purely for gamblers at this stage.
Ten Entertainment (LON:TEG) - up 32% to 409p y’day (£280m) - Recommended cash acquisition - Paul - PINK
US private equity has found yet another UK company to buy - at a 33% premium, all cash bid 412.5p. Yet again Harwood Capital is a major shareholder, with a history of taking this bowling operator private before. Well done to holders, with hindsight the value was obvious, sorry we didn't focus on this one enough.
Bloomsbury Publishing (LON:BMY) - up 10% to 465p (£378m) - Trading Update (materially ahead) - Paul - GREEN
Smashing news here, from one of our favourite value/GARP shares, book publishers Bloomsbury. It's materially ahead - profit for FY 2/2024, boosted in particular from strong sales of fantasy fiction. Valuation is still reasonable, strong balance sheet with plenty of net cash, high StockRank, it ticks all my boxes, so a continuing thumbs up.
SDI (LON:SDI) - down 18% to 90.65p (£94m) - Interim Results - Graham - AMBER
Material cuts to the revenue and PBT outlook here due to customer destocking and weak demand in China and Germany. Some of the factors are temporary but I’m moving my estimate of value territory for SDI down to sub-80p (previously sub-£1).
Vertu Motors (LON:VTU) - down 22% to 66p (£225m) - Trading Update (profit warning) - Paul - AMBER
A sudden, and sharp fall in used car prices has forced Vertu into a profit warning. I still like the strong balance sheet, and potential for a takeover offer. However, the deterioration in trading means we have to slip down from green to amber - reflecting that there are positives & negatives to this share.
Future (LON:FUTR) - down 18% to 613p (£716m) - Full Year Results FY 9/2023 - Paul - GREEN
In line FY 9/2023 results today, combined with a sharp fall in share price, make this look pretty superb value to me. Large and rapid debt reduction makes me relaxed about the weak balance sheet. Could this be a second bite of the cake for a former major multibagger? I think it could be, with the 85% fall from the peak looking way overdone. Mind I said that back in Sept 2023 too, and it's fallen since then, so maybe I've missed something? Well worth a closer look by you anyway. Let me know what you think!
Paul’s Section:
Bloomsbury Publishing (LON:BMY)
Up 10% to 465p (£378m) - Trading Update (materially ahead) - Paul - GREEN
This book publisher is one of our favourites here at the SCVR (and amongst readers too). We reviewed it positively here on 1 June, 18 July, and 26 Oct 2023, viewing it GREEN on all 3 occasions, which I’m happy to reiterate after today’s good news.
Today’s update relates to FY 2/2024 -
Revenue comfortably ahead and profit materially ahead of expectations…
* The Board considers that the consensus market expectation for the year ending 29 February 2024 is currently revenue of £274.2 million and profit before taxation and highlighted items of £32.9 million.
This follows exceptionally strong trading in the Consumer division for a number of titles and particularly Sarah J. Maas' 15 titles… "I am delighted to report a strong period of trading which is principally driven by the continued phenomenal demand for fantasy fiction…
Broker updates - nothing available. Crunching the figures myself, I get to FY 2/2024 EPS perhaps c.33-35p EPS. So on this morning’s 465p increased share price, we get a PER of 13.7x - still a very reasonable price, I’d say, for a group with a very impressive growth track record -
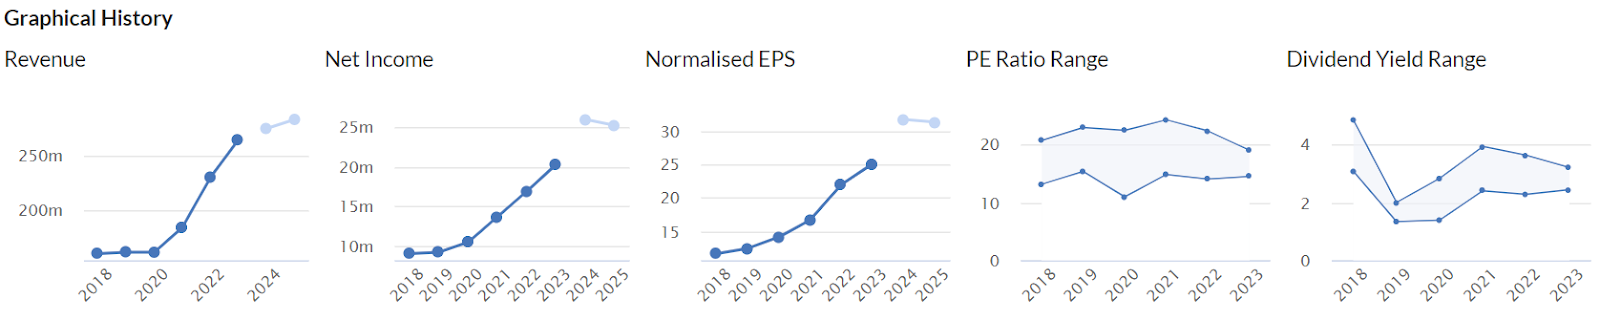
With its fragmented institutional shareholder base, I wonder if the Yanks might come along and bid for BMY next? After all, owning the publisher of what they call “Hairy Padder” might be a strong attraction?! So you’ve got a potential cherry on top of the value/GARP pie, in the form of a possible takeover bid.
Paul’s opinion - an excellent share we think. Today’s news is really encouraging, and the valuation still looks perfectly reasonable to me. So I remain keen, with another thumbs up, so GREEN it is again. Well done to holders, this has been a nice safe haven in a horrible small caps bear market. Also a 4-bagger in the last 10 years, and a 2-bagger since the covid lows in 2020. With divis on top too, as well as self-funded growth. You also have the comfort (and ability to make acquisitions) from a strong balance sheet last reported at £100m NTAV, with plenty of net cash. Very high StockRank too. So it ticks pretty much all my boxes!
Polarean Imaging (LON:POLX)
5p (pre market) £11m - Company Update - Paul - RED
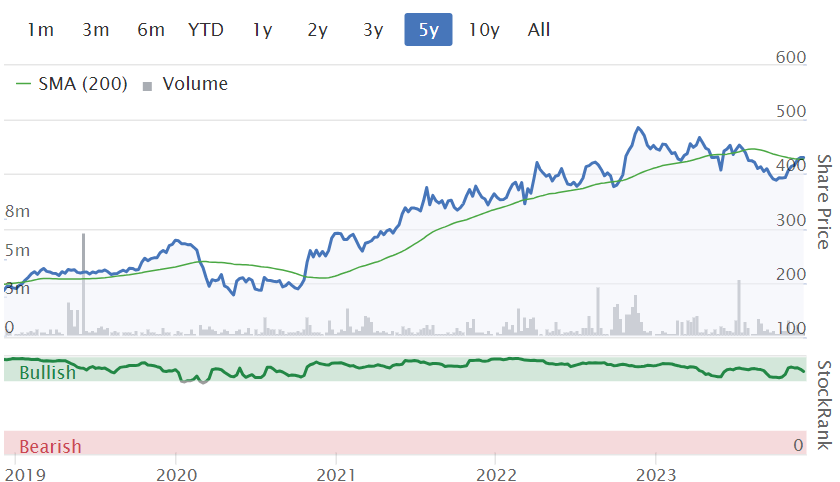
This has been an alarming situation, where management seem to have been frozen in the headlights, and allowed the share price to collapse to almost nothing (down c.95% from the peak), whilst uncertainties remain over its funding situation. So yet another promising-sounding UK innovator, that is under-funded, and withering away. The stock market really is not the right place for this type of company, let’s hope that is reflected in the next wave of IPOs - we need proper, established, profitable companies listing in the UK, not more blue sky projects - hardly any of which actually work out successfully.
Today’s update says some positive-sounding operational things, but all I’m interested in at this stage is funding. It says -
The Company’s current cash runway is expected to last into Q3-2024. Management is continuing to evaluate all options for further financing… Whilst we are assessing various financing options, I am confident that we will be able to finance the Company for the medium term, and would like to extend my thanks to our strategic investors for their continued strong support”.
Paul’s view - the shares are just a gambling chip at this stage. All the power lies in the hands of whoever puts in fresh money, so existing small shareholders are powerless, and you could be all but wiped out in the next fundraising. Or it could be a multibagger, there’s no way of knowing at this stage.
My policy is to wait until the finances are sorted out, and only buy a cash-burning share like this if there’s at least 2 years cash in the bank, and even then just treat it as a punt. There’s nothing today to reassure that it’s any closer to a funding solution. I see management as having been negligent here, allowing the existing equity to wither away to almost nothing.
Ten Entertainment (LON:TEG)
Up 32% to 409p y’day (£280m) - Recommended cash acquisition - Paul - PINK
Announced yesterday, an agreed cash bid at 412.5p, a 33% premium.
The buyer, as usual, is a US private equity fund called Trive Capital Partners. Googling the name, it seems to only have $4bn of assets, which would make this deal large for the buyer. Although often these type of investment firms have various offshoots, so that $4bn figure may not be the whole picture maybe?
Note that Harwood Capital (Christopher Mills firm) is a 16% holder, and often agitates for buyouts. In fact, it bought TEG itself years ago, when it was called Essenden, then refloated it a few years later for multiples of the price paid.
Paul’s view - we took our eye off the ball here, and haven’t reported on TEG for a while, sorry about that. However, I can vaguely recall it being discussed by readers a while ago, with people saying they didn’t think the discount to Hollywood Bowl (LON:BOWL) in PER terms was justified - a very good call! Looking at the StockReport, it seems to have looked obvious good value at a forward PER of 8x, which has now gone up to 12x with the bid premium in it - not exactly a knockout valuation, but it looks to be a new all-time high for this share, so nobody can really complain, given the lamentable state of UK small caps markets.
Well done to holders! It gives you a fresh pot of cash to deploy in something else really cheap, so no complaining I’d say. This deal looks likely to go through, looking at the shareholder list, which is dominated by institutions who will no doubt relish the liquidity event, and the boost to their performance stats. It already has c.40% support, so likely to go through.
Vertu Motors (LON:VTU)
Down 22% to 66p (£225m) - Trading Update (profit warning) - Paul - AMBER
Vertu Motors, the UK automotive retailer with a network of 195 sales and aftersales outlets across the UK provides the following trading update for the three months ended 30 November 2023 ("the Period")...
a number of negative external market factors resulting in profitability for FY24 now expected to be lower than current market expectations.
This is Q3 of FY 2/2024.
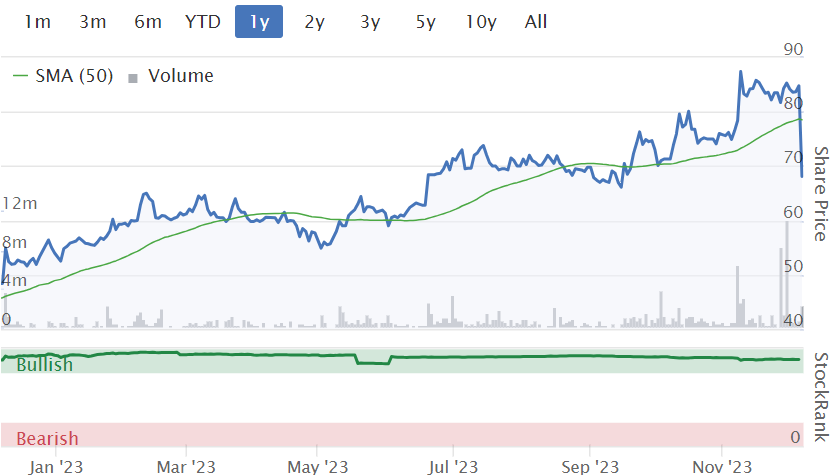
Clearly a setback, as shares have this morning given up the gains of the last 3 months - still up nicely year-to-date though -
Used car values are falling - this echoes what Motorpoint (LON:MOTR) told us recently -
The Period has witnessed a material change in the used vehicle market with UK wholesale values experiencing a significant reduction in October and November.
This happened due to lower consumer demand, combined with increasing supply.
This rate of decline in used car values sounds considerable, and fast -
CAP1 have reported that values have fallen on average 4.2% in both October and November, representing record levels of monthly decline….
… the largest drops of 7% -11% per month arose in the premium brand segment.
So there you are, if you’re in the market for a jazzy nearly new car, it just got a lot cheaper!
Everyone knew that inflated used car prices would eventually correct, as supply normalises, but it seems to be happening a lot faster than expected.
Outlook for used car values -
The Board consider that UK used vehicle values are likely to continue to weaken above historic norms in the near term. Once the current pricing correction has eased, used car prices in the UK will be more affordable to the consumer and margins should stabilise. Reducing interest rates in the medium-term would also aid affordability and provide a further stimulus to a market benefitting from increased supply.
New cars - more detail is given, saying supply has increased back to normal, although this bit worries me -
Overall, new vehicle supply has started to exceed natural demand levels, leading to an increased pipeline of new vehicle inventory, which when combined with higher interest rates, has increased manufacturer stocking interest charges significantly above expected levels.
Aftersales - trading improved on last year, but is being held back by some supply chain problems for vehicle parts. I imagine this should sort itself out in due course.
Costs - well controlled. Mentions 9.8% increase in Living Wage as a cost headwind in FY 2/2025 - “low single digit £millions” above budget.
Outlook overall - volatile market conditions, so they’re cautious.
Broker updates - this is the most important part - guided by management of course, how much have the brokers downgraded forecast earnings?
Zeus helpfully publishes its thoughts with an update this morning. Given that we’re not far from the end of FY 2/2024, a downgrade of 17% in adj PBT is quite hefty, and £8.0m drop to £39.3m.
Zeus has only reduced FY 2/2025 by 6% to £48.6m, which immediately strikes me as not being enough. Can we assume that FY 2/2025 will be above FY 2/2024 at all now? I’d feel safer assuming that it might be the same or lower than FY 2/2024. Although there is a boost to earnings from the big acquisition made during this year, so a full year's contribution next year.
I prefer to work on adj EPS, which was forecast at 9.8p for FY 2/2024, but is now reduced to 8.2p.
FY 2/2025 is reduced from 10.7p to 10.0p. With volatile market conditions in demand and supply, it’s very difficult to make forecasts at all.
Paul’s opinion - I summarised the bull & bear points for Vertu here on 1 Nov 2023, which is worth revisiting. With hindsight, maybe I should have moderated my view to amber back then? Clearly the (expected) fall in used car values has happened much faster than Vertu and brokers imagined. I’ve also noted before that finance charges are shooting up on vehicle stocking loans, plus VTU has increased other net debt to make a series of acquisitions. Note on Zeus’s latest forecast, finance charges have doubled from last year, and now consume about a third of operating profit. So VTU will need to concentrate on reducing inventories I think.
There were some warning signs, both at VTU and others (eg Motorpoint (LON:MOTR) ) but even so, this downturn in trading has clearly taken everyone (including me) by surprise with its rapidity.
Also I think a lot of people will have probably decided to hold tight for potential bid interest, with VTU being one of the remaining UK listed dealers that had not yet been bid for. A drop in share price could actually make a bid more likely now. Competitors have been adding to their disclosable stakes too.
So as always, it’s your call really - stay in it for the bid potential, and the strong freehold property asset backing? Or ditch them as positive trading conditions have sharply & suddenly deteriorated?
I’m trying to be disciplined with my traffic lights, so given the deterioration in current trading & forecast falls, it has to be a move from green to AMBER, to reflect the mixed attractions of this share - some positives (which I still like), and some not so good now that trading has deteriorated recently.
Future (LON:FUTR)
Down 18% to 613p (£716m) - Full Year Results FY 9/2023 - Paul - GREEN
Long-serving CFO announces today she is stepping down, technically next year (due to 12-month notice period). Who knows what the real circumstances are, we can only speculate. Of course it raises eyebrows, coming on (poorly received) results day.
Background - as you can see from the 10-year chart below, Future shares were an astonishing major multibagger (c.40x!) - between 2017 and 2021. Graham and I did cover Future quite a few times when it was starting to take off, in 2018 & 2019, with our reviews typically saying that we haven’t researched it in detail, but it keeps issuing out-perform updates, some balance sheet concerns, and that the price usually looked up with events! Just shows doesn’t it, sometimes we need to discard our value hats, and look at growth companies in a more flexible way!
After Ed’s brilliant multibaggers webinar (the next part is coming up on Wed 13 Dec at 11am - you should have received an invitation message/email today), I’m looking back at previous multibaggers to see how they looked at the time, when the big move upwards was starting, as we’ve got an SCVR archive going back 11 years now, and it’s all in there. Here’s our archive for Future, when it was beginning its 40-bagger rocketship phase!
And remember that the next few years’ major multibaggers will be somewhere buried in recent SCVRs probably, but we just can’t tell you at this stage which companies they will be!
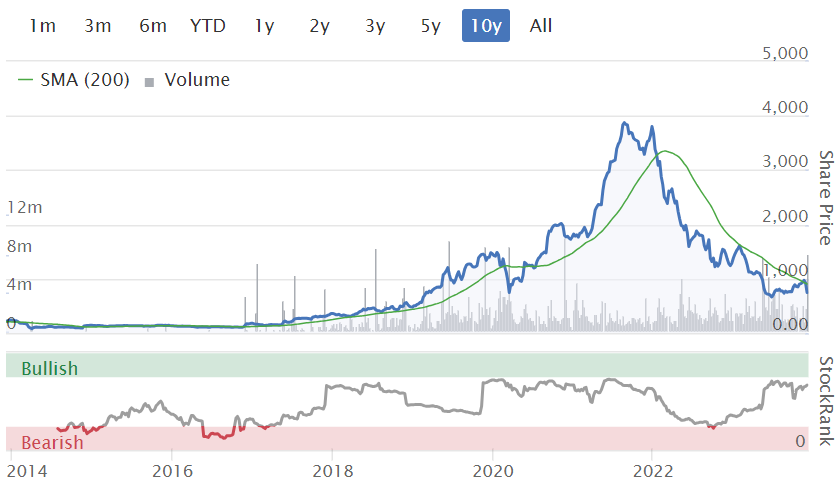
Moving on from the glory period, after peaking at almost 4000p per share, FUTR is now down to only 613p, having given up well over 80% of its previous stellar gains. So the share price has wound down 5-years, to prices last seen in early 2019.
This is either a bargain, for us to grab a second bite of a multibagger cake, or something serious has gone wrong and it’s best avoided. Or somewhere in between!
This year - having soared almost into space, FUTR crashed back through our artificial ceiling (£1bn market cap) here at the SCVR in May 2023.
I reviewed it here on 29 Sept 2023, when the shares put on a nice 16% daily spurt on an in line trading update, and also looked back at the H1 results. Overall, I quite liked it at 827p, looking cheap, but (as usual!) I moaned about the heavily indebted balance sheet. Concluding AMBER/GREEN due to what seemed an attractive valuation.
Moving on to today, the price is down heavily, and at 613p is now a good bit cheaper than last time we looked. Let’s check it out, as always with fresh eyes.
Future plc (LSE: FUTR, "Future", "the Group"), the global platform for specialist media, today publishes its results for the year ended 30 September 2023.
It owns Go.Compare and lots of online magazines.
I’ve quickly reviewed the results, and this looks good to me, given tough macro (when I would expect subscriptions and advertising revenues to have dropped somewhat, which they have, but not anywhere near enough to cause concern).
Some key numbers -
Revenue down 4% to £789m (but -10% organic)
Adj PBT down 13% to £221m - still a very impressive PBT margin of 28%
Statutory PBT is lower at £138m - I think the adjustments are mostly reasonable (being goodwill amortisation, so I’m happy to rely on the adjusted numbers [Graham probably wouldn’t be!]
Adj diluted EPS of 140.9p is down 14% (in line with market expectations), the PER is now just 4.4x - I had to double check that figure, but yes it’s correct!
Is it financially distressed then? I’d say no - net bank debt is considerable, but falling fast, at £327m (last year £424m, so 23% paid off this year from cashflows). Covenant leverage is 1.25x (LY: 1.48x) which looks quite comfortable I’d say, in the context of big & genuine cash generation. I’m usually the first person to sound the alarm & warn people to evacuate the building, but in this case I don’t see a problem with this level of debt, given how fast it’s coming down.
Share buybacks are underway, £13m done by 9/2023 year end, from a £45m programme. I like buybacks when shares are on a low valuation, and it’s another sign that the company is not financially distressed.
Going concern statement is clean.
Balance sheet - a bit scary for me, with a gaping hole due the huge intangibles from previous acquisitions. But actually there is value in the intangibles, and it could sell off titles and get some money back. Even so, NAV of £1,115m contains goodwill & similar of £1,054m + £586m, less deferred tax liability of £116m, reduces my version of NTAV to £(409)m - not a disaster given how cash generative FUTR is. So despite the weak balance sheet, it has to be seen in the context of fabulous cash generation.
Cashflow statement - looks very healthy, with £183m cash generation after bank interest & tax paid. Does it capitalise huge development spending? No, only £9.3m, which is fine. Tiny dividends, with more spent on buybacks. Cashflow has mostly paid down debt & funded more acquisitions.
Forecasts - nothing available, but the company says it expects to return to growth in H2 2024, and seems to be increasing spending to drive growth, rather than retrenching.
Paul’s opinion - if there’s anything wrong with these accounts, I’ve not found it. Well, other than a weak balance sheet with a lot of debt, but given the scale of the cash generation (despite tough macro), I don’t see a problem with this bank debt, and it’s rapidly reducing too.
Not everyone will agree with me here, but based on the valuation here of just 4.4x, and acceptable debt, I think this share looks really attractive.
Results seem to be in line with the broker consensus on the StockReport, so I have no idea why it plunged first thing today.
I’m not an expert on the company at all, but I'm tempted to buy at this very modest valuation, for a previous wonder-stock. So I’ll be a bit daring here, and shift up from amber/green to GREEN.
Graham's Section:
Premier Miton (LON:PMI)
Share price: 61.7p (+2%)
Market cap: £90m
Premier Miton Group plc ('Premier Miton', 'Company' or 'Group'), the AIM quoted fund management group, today announces its final results for the year ended 30 September 2023.
These results were published Tuesday. Key points:
AuM falls from £10.6 billion to £9.8 billion
Net outflows of £1.15 billion (previous year: £1.08 billion).
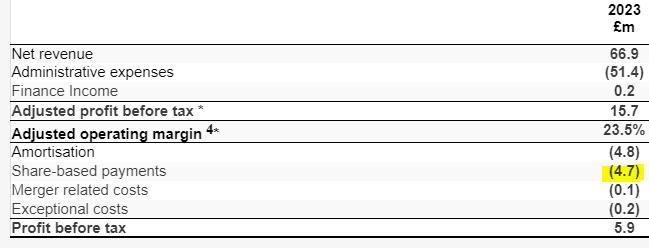
Adjusted PBT £15.7m (last year: £24.3m)
Actual PBT £5.9m (last year: £14.9m)
Nearly £5m of share-based payments are excluded from the adjusted numbers:
The full-year dividend reduces from 10p to 6p, but this is still an attractive c. 10% yield on the current share price.
Adjusted EPS is 8.8p so in this sense the reduced dividend payout is covered by earnings. However, actual earnings per share are only 2.5p.
Acquisition: in November (i.e. in H2 of the financial year), Premier Miton bought Tellworth Investments, bringing in another £559m of AuM.
CEO comment: the general backdrop remains challenging, but the CEO seems happy with fund performance (73% of funds in the first or second quartile since inception with their current managers). He reminds us that they are ready to manage more assets, whenever flows return. They are also increasingly looking at acquisition opportunities:
Our business has the operational infrastructure to manage a multiple of the assets it currently looks after and we have built the necessary distribution and marketing platform to capitalise on this opportunity. We will continue to assess opportunities that can add talented investment teams, or which allow us to access new markets or product capabilities."
Comments on market conditions/policy support - this fund manager, being UK-centric, is particularly affected by the very cheap valuations and the outflows from UK equities. They are endeavouring “to influence public policy decisions to address these structural issues in a positive way”.
Graham’s view
These shares are extraordinarily cheap by historic standards, reflecting the extraordinary current circumstances.
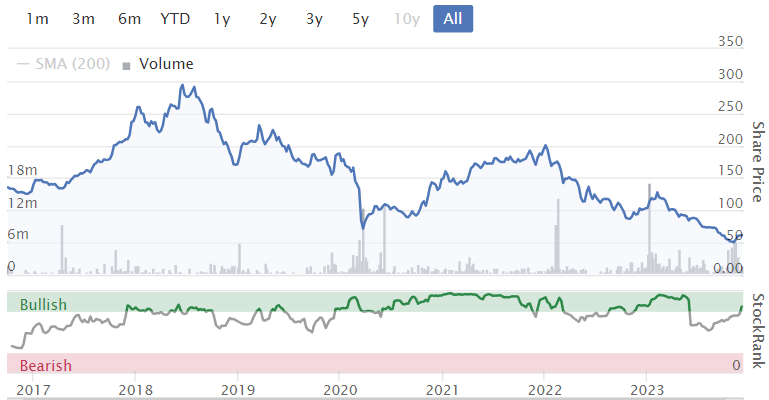
Based on the end-of-year numbers, £1 invested in these shares obtained about £109 of AuM. This is about the same as Jupiter Fund Management (LON:JUP).
Maybe the key challenge for these companies is differentiation, not demonstrating good historical performance of their funds relative to peers.
Good historic relative performance from existing funds is a basic requirement: I think fund managers need to go further and give investors a “why”. This could be a particular theme, or it could be ESG. For some fund managers, it will be providing access to hard-to-reach investments.
Historic relative performance against UK peers probably won’t be the answer in an environment where a random selection of US mega-tech stocks has outperformed almost everything.
I’m not sure what the answer is for Premier Miton. And there are several good options for those interested in investing in fund managers right now, not just this one. But I do see this recovering along with the rest if or when positive momentum returns.

SDI (LON:SDI)
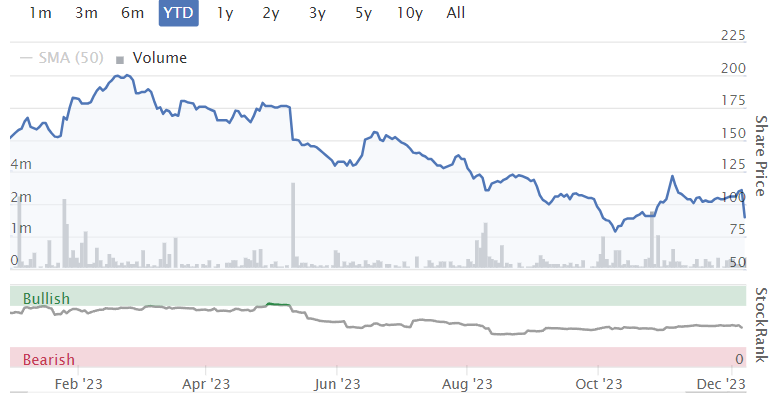
Share price: 90.65p (-18%)
Market cap: £94m
This is a profit warning, at the end of a tough year for SDI shareholders.
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing and control applications, is pleased to announce its results for the six months to 31 October 2023.
Here are the key bullet points:
Revenue +1.6% to £32m, including acquisitions.
Organic revenue growth 2.2% excluding Covid-related sales (i.e. organic growth would be negative if you included the impact of falling Covid-related sales).
Adjusted operating profit £4.4m (H1 LY: £6.9m)
Reported operating profit £3.4m (H1 LY: £6.5m)
The organic revenue decline including Covid-related sales is 18.4%.
Net debt is £13m with c. £15m additional headroom. The leverage multiple is 1.1x, which would be considered moderate.
Chairman’s comment:
Profits have been affected by some destocking, some of which is likely to be temporary, alongside a slowdown in China and Germany. We now expect to report FY24 adjusted profit before tax of between £7.9m and £8.4m.
At the AGM trading update in September, SDI said that market expectations were for FY adjusted PBT of £9.8m.
The new guidance therefore represents a cut in the adjusted PBT forecast of between 14% and 19%.
Covid comments - “the changes in customer behaviour the pandemic caused have continued into this financial year”, with OEM’s initially over-ordering and now apparently still destocking. We have seen the destocking explanation given by plenty of companies over the past year.
Tax rate is now 24.9% (H1 last year: 20%).
Outlook:
Alongside the reduced profit guidance, we get a reminder of SDI’s good long-term track record:
For over ten years SDI has consistently grown value by focusing on a clear and straightforward strategy. We acquire private companies at a significant discount to those on the quoted markets. These subsidiaries are then encouraged to grow for the benefit of all stakeholders. I am pleased to report that we have a number of new acquisition opportunities under review. So, despite the recent headwinds we look forward to the future with great confidence.
Estimates
I’m curious to see what the analysts are doing with their top-line forecasts. At Cavendish, the new revenue forecast for FY April 2024 is £65m (down from £72m) and the new FY April 2025 forecast is £70.4m (down from £77.1m).
These are significant cuts to the revenue outlook, particularly when you consider that H1 FY 2024 revenue (reported today) was already £32m. There is now almost zero growth pencilled in for H2 vs H1.
Graham’s view
Checking my notes in August, I was neutral on SDI but starting to get interested in the valuation (at 122p). One of my main concerns here, which I have mentioned probably on multiple occasions, is the lack of organic growth.
That concern remains valid today, as SDI’s organic growth remains below inflation and seems destined to remain so in the near-term (and that’s even if we exclude the collapse in Covid-related orders).
I previously said that below £1, I would consider SDI to be good value although that implicitly assumed that trading didn’t deteriorate further.
With a reduction in forecast adj. PBT of up to 19%, today’s fall in the share price by about the same amount does make sense.
Therefore I’m going to stay neutral, and move my estimate of value territory down to sub-80p.
Here are the value metrics as of last night:
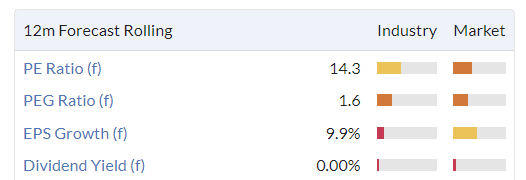
The new adj. EPS forecast for the current year is 7p, so the new adjusted P/E multiple remains in the region of 13x.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

124 comments
Vertu Motors (LON:VTU) I hold. On reflection the positive is that as an acquisitive company they may be able to buy dealerships cheaper. I bought more on the fall-averaging cost price upwards as I think the market has over re-acted, The CEO gave a clear explanation today. Upside after that was Chapel Down (OFEX:CDGP) gave us shareholders a 40% discount on the flagship Kit's Coty range of sparkling wines. I buy the wines they produce and most people I give them to are really impressed.
Future (LON:FUTR)
Thanks to Paul and others for their comments here.
As a holder I'm slightly bemused by the drop in valuation over the last week.
Despite a "weak" year, underlying cash generation was pretty similar to last year at c.£180m (my calc) vs a current EV of £1b, with minimal capex spend required to run the business.
---
On first viewing of today's results I was only disappointed by net debt "only" reducing by £100m when cash generation was higher than this. However, it was reassuring to see that excess funds were spent on:
I'm a big fan of the latter, and Penny mentioned as much in the webcast today, highlighting that this was a good allocation of capital whilst the share price was so low.
I agree.
---
Some commentators have noted that Penny leaving is a negative. I actually worked with her many years ago (and the old Future CEO) and I'm surprised that she didn't leave when Zillah (the old CEO) did - they've now moved together across 3 businesses as far as I'm aware. Maybe Zillah is looking to start working again in a year when Penny's notice period finishes?
---
The material upside might be a couple of years away given the evident negative sentiment today, but there certainly does seem to be a lot of value here and I don't see any balance sheet risk.
I'm therefore happy to hold whilst the cash generation is so strong relative to the EV.
A
Regarding Ten Entertainment (LON:TEG) I see the closing prices as stated by stocko is 418p. Does this mean that the market expects a counter offer given the offer price was 412.50p or is this just something to do with the spread.
I hold
Any thoughts?
Looks like a 412-419 spread at close for Ten Entertainment (LON:TEG)
Looks like mr market thinks there’s a second or improved bid in the wings.
Just read planetX post regarding cutting and pruning.
I am fairly patient and generally like to sit still and use dividends to add to existing holdings, however sometimes I don't sit still long enough. I sold Ten Entertainment (LON:TEG) a few weeks ago around 305p for a reasonable return on the basis that I had come across a more attractive proposition, PayPoint (LON:PAY) .
Needless to say my execution was less than perfect with Ten Entertainment (LON:TEG) now subject to an all cash offer of 412p and PayPoint (LON:PAY) having declined by 12% or thereabouts. In the medium term my reasoning may be correct, if PayPoint (LON:PAY) turns out to the be the bargain it appears , but as said being right too early, assuming I am, is tantamount being wrong.
On a more positive note I added a few more Bloomsbury Publishing (LON:BMY) yesterday, so draw solace from today's update.
Spectra Systems (LON:SPSY) Anyone got any insight on the circa 10% rise today? So far as I could tell the takeover a week or so ago was fairly neutral but I certainly could be underplaying it?
Simon Thompson article
I get Graham's point about Premier Miton (LON:PMI) needing unique selling points. Given the pressure on Investment Trusts to merge and reach a £250 to £400m size, and competition from ETF's etc. There must be a limit on the number of mainstream (non boutique) UK Investor Houses that we need? Thinking ABDN Pheonix Lloyds(Scottish Widows) etc.
So strategically I am thinking Premier Miton (LON:PMI) and Jupiter Fund Management (LON:JUP) might make a good fit , but I suspect too many ego's will prevent it happening
Thats not to say either/both may or may not be good value.
Premier Miton (LON:PMI) Liontrust Asset Management (LON:LIO) and Jupiter Fund Management (LON:JUP) could all merge - then merge all the duplicate funds and cut some of the staff to bring costs down.
the consolidation of UK fund managers and UK actively managed funds (& UK pension providers more generally but that is another topic) is well overdue
too many fund/asset managers, too many funds etc.
Quite right - last time I looked on Trustnet, there were about 350 UK equity funds, most of them very similar. Desperately need some consolidation.
Regarding Polarean Imaging (LON:POLX) Paul, I wonder if you have asked your "shrewd friends" if they are still keen?
(May 22 "We don’t normally cover blue sky companies, but some shrewd friends pointed me towards this one")
Regarding Polarean Imaging (LON:POLX) Paul, I wonder if you have asked your "shrewd friends" if they are still keen?
I didn't like to ask, as it would be like rubbing salt into their wounds. But everyone has gone completely quiet about POLX, that's for sure. Just goes to show, plenty of rich & successful investors make howling mistakes too. Especially in a roaring bull market like 2021.
It would indeed! I noticed that Gervais Williams (who I think is shrewd) was talking positively about it in a Paul Hill vid in June, although Premier Miton don't seem to have a notifiable holding.
Cutting, Pruning, Building big chop n change day.
Listened to Pauls vox interview last night (in the bath not that that's relevant but was quite relaxing) struck me he made a smart move chopping back some positions earlier this year to free up some cash to spread into a few new positions especially with a view could be coming to an upswing .
Im sat in a few shares that have been good "bedrocks" in the past 18 months downturn that have limited downside but hard to see them taking off too much as no real catalysts so on the guess that there is a bounce likely in the next period probably a good plan to get a few more surfboardsin the sea to catch a wave .
Was looking at 4-5 that I think have a big chance of rerating so did a bit of a pivot -
Spent a good day yesterday digging into following and moved out of the steady hard to see moving old guard into a few that might move on an upward tide if the various catalysts kick in
TRANSENSE - really like it, they have a royalty revenue until 2030 that should cover the market cap alone, they have cash, and are in a good sector and look pretty solid . Took a decent position today with the cash freed up (from Colefax) . Like this a lot .
REACT - has sold off recently, looks at bottom of its curve and looks good bet.
CARRS - Like the turnaround possibility, similar space to Wynnstay so have chopped Wynnstsy and replaced same value with Carrs . Might have further to fall though ,
PENNANT - Smart money going in here, hard to buy, good sector , illiquid so capping this quite low ,
COMPTOIR- Tiny position just for fun
RESTORE - already moving so might have missed this
Cut back 5-10% on the following but still decent holdings , just freed up some liquidity to start on the above
Wynnstay, Vertu (luckily sold some last week also but cut more today,) , Equals (still biggest holding) , Avingtans (only a few % still 2nd biggest holding ) , Colefax
Sold out of BP
Sold out of Pressure Tech couldn't get a stake
Quite an intense time making so many trades quickly especially in illiquid small caps, need to go for a lie down and leave alone for a few weeks now to let the dust settle .
Carrs is a completely different business to Wynnstay.... (speaking as a diligent farmer)
I bought a small position in Vertu Motors (LON:VTU) in May and sold in August for a 15% gain. I sold too early but I did so as I thought the imbalance between supply and demand would be short lived.
Robert Forrester the CEOof Vertu is a very impressive guy and I thought it was reassuring that in his statement today he exprssed the view that the current imbalance would be over in `4 to 5 months`.
I am sure I am not alone in watching the SP like a hawk in the next few days for a suitable re-entry point.
Vertu Motors (LON:VTU) I know many of us on here tend to be investors rather than traders, however, I can't help but think this could be a really solid buy just before the close. At a 25% drop, if a few decent sized buys pop up in the morning or an RNS stating that one of the institutions has topped up further, it could see a bounce back 5-10%. I sold out at 72p this morning and hope to buy back in just before the close at around 64p. Knowing my luck it will bounce in the next hour or so back up to 70p!
Vertu Motors (LON:VTU)
With zero evidence that the drop in residual values has fully flowed throughand bottomed out and the worst may be over - i would be presuming there could very well be worse to come before things get better
Chapel Down (OFEX:CDGP) this morning's RNS advising of Chapel Down's switch of index from Aquis to AIM also had the following quote from CEO Andrew Carter ;
"We are pleased to announce Chapel Down's admission to trading on AIM, a move which reflects the maturity of the business and the ambitious growth plan we are committed to delivering in the years ahead. Chapel Down has greatly benefitted from its AQSE listing over the past 20 years as it has grown from a start-up in an embryonic industry into England's leading and largest winemaker with a consistent track record of profitable growth.
"We believe that a move to AIM will attract a wider pool of investors to participate in Chapel Down's growth as the leading producer in the world's newest global wine region and as we continue to pursue our well progressed and fully funded plan to double the size of the business in the five years to 2026. In November we confirmed a record 2023 harvest, with tonnage 86% higher than 2022 and 75% higher than the previous record posted in 2018, which is creating great excitement within our business, and will underpin our strategic ambition to double the size of the business by 2026 as we continue to build Chapel Down's position as England's number one and most celebrated winemaker."
I was expecting (and prepared for) them to need a raise to fund this growth plan, especially the new Vinery in Canterbury, if indeed the plan is already fully funded this would make the investment case even more exciting than before.
A different take on AJ Bell (LON:AJB) , with ramifications for all the platforms, especially Hargreaves Lansdown (LON:HL.) and also Jarvis Securities (LON:JIM) .
I remain quite concerned over how much revenue the retail investor platforms are making from skimming their client's interest on cash balances. To what degree this is sustainable under the new Consumer Duty obligation is the million pound question, and the FCA wrote to platforms in July seeking disclosure on how much of the interest they receive is passed on.
Going through the AJ Bell statement I think we can conclude that it has been very carefully worded indeed.
Recurring ad valorem revenue grew by 58% to £161.2
million (FY22: £102.2 million). The key driver of this growth was the
higher levels of interest generated on cash balances held on the
platform following increases to market rates of interest in the year,
combined with elevated average cash balances in the first half of the
year. Our economies of scale enable us to benefit from these interest
rate rises whilst also sharing them with our customers by paying a
market-competitive rate on their cash balances.
Transaction related revenues (dealing commissions etc) were actually down 17%:
Revenue from transactional fees decreased by 17% to
£26.4 million (FY22: £31.9 million). This decrease was due to lower
dealing activity levels in the current year, impacted by the
macroeconomic environment.
They clearly know they need to hand more of the interest over to customers, and say they will do so soon:
Following the increases in the UK base rate throughout
the year, we raised the rates we pay to customers on cash held on the
platform. Early in 2024, we will be introducing a higher interest rate
on cash held in SIPP drawdown, reflecting the fact that these customers
often hold more of their portfolio in cash to fund their short-to-medium
term retirement plans, as well as higher rates for SIPP and ISA
customers with large cash balances.
Problem with this is why early 2024? They are effectively admitting that the rates they pay are not directly linked to base or bank rates - in terms of outcomes they take what they like, and not what they are entitled to keep having declared their charges to customers transparently & up front. If the BofE cuts rates before early 2024 (for argument's sake, not what I expect) then will AJ Bell still increase their rates, or renege on the "we will" bit?
For those wishing to explore further, this interview is interesting (more aimed at advisor platforms but still relevant):
unveiling-transacts-view-on-cash-with-glen-sweet
For those saying "it is a competitive market, like bank current accounts, and platforms should be free to do what they like" - I disagree. Given the cash sits alongside your securities and may be within a SIPP/ISA wrapper, it is not realistic to expect a customer to change provider to access better rates on cash - it would involve very slow & cumbersome ISA/SIPP transfers.
I am an AJ Bell customer for some of my accounts. They are usually competent, but they are not angels.
We find later on in Note 25 just what AJ Bell skims:
The spread of rate retained by the Group is variable
dependent on rates received by banks (disclosed to customers at between
1.15% below and 0.15% above the prevailing base rate) and amounts paid
away to customers.
How that squares with Treating Customers Fairly is a can of worms. If you think this is an area that doesn't matter.....how would you feel if your platform started helping itself to a variable proportion of your dividend income?
This is not going to go away.
AJ Bell (LON:AJB)
thanks for that assessment Monty Carlo
Ref note 25 - does that give us any indication what interest rate margin they are scooping off? - if banks are happy to scoop off 1% - should be not be expectiing they sholuld be doing similar - or could it be the case they are making double or treble that ?
AJ Bell are charging you a custody fee, and then they are also dipping into your interest as they see fit...which is potentially double-charging that the banks don't do.
I think platforms are going to have to declare the amount they skim for managing cash on an instant access basis and stick to it (so I exclude AJ Bell's cash hub fixed term products here). Aviva are stirring here by retaining nothing and being loud about it.
The sensitivity analysis in Note 25 shows AJ Bell changed what they do between 2022 and 2023. In 2023 they are passing on all base rate hikes & cuts, whereas in 2022 they snaffled it:
In FY23, movements in the UK base interest rate would not have impacted the retained interest income earned by the Group, as any increases or decreases to the UK base interest rate when it is at higher levels would be passed to customers in the form of higher or lower pay away rates respectively.
Conversely, in FY22 a 50bps increase would result in an additional £11.8m retained interest income, as the majority of the increased gross interest income earned would be retained by the Group to rebuild revenue margins when UK base is at low levels.
As to exactly how much AJ Bell (LON:AJB) made from skimming customer interest? Surprise, surprise they don't tell us - but you can make a guesstimate from the sensitivity analysis.
AJ Bell, HL, ii and other platforms
Excellent analysis by Monty Carlo. For the time being they are like the goldmine! earning big interest from the customer cash. Nothing will change anytime soon and by the time the regulator gets their acts together, the interest rates beginning to come down and the issue is resolved!
Incidentally, I think all the platforms share are good value and I own all of them!
You are clearly comfortable that the current P/Es price in the risk of Hargreaves Lansdown (LON:HL.) and AJ Bell (LON:AJB) receiving a "Dear CEO" letter from the FCA that halves their earnings overnight (I exaggerate for effect...they may get to keep something).
A major platform called Transact (used by IFAs, not us retail plebs) have gone on record as stating that they view skimming any interest whatsoever as contrary to their interpretation of the Consumer Duty rules.
In FY 2023, £268.7m of HL's £735m annual revenues was derived from net interest margin on client accounts (they skimmed 192bps). That's 37% of revenues.
That's £268.7m of revenues that probably flowed through to the £403m of PBT at verging on zero marginal cost.....
Hargreaves Lansdown (LON:HL.)
Great post Monty Carlo - sobering stats indeed. If we look at the way the regulators destroyed all the scammy money lenders into oblivion (woop woop) - we shouldnt be surprised if they take action. I think they have recently taken specific action against St James wealth too - so thats without geoing into the detail of whether these firms might have other somewhat hidden ways of making a quick buck that arent transparent. We cant say we havent been warned.
I am not a AJB customer but do use HL, so answering from that perspective.
I generally run fully invested so cash interest is of little concern to me, but HL do offer their "Active Savings" for me to deposit cash into and earn more "competitive" rates of interest. However, generally I don't bother. It would take time to get the money back and I could miss an opportunity to trade in the meantime.
So it's almost like the cost of doing business. I want the instant access, I accept they pay less interest there, not dissimilar to a bank account. Instant access bank accounts pay less than if you lock it up.
I find the whole Consumer Duty angle in this respect a bit ridiculous. There is no secret as to what they pay on interest, they give you ample opportunity to put your money away and earn better rates if you want to. They can manage their liquidity profile better given their size, so I sort of don't see the problem.
Basically, I think there is a bit of personal responsibility to be had here. You've taken the decision to put your money on an investment platform, so it's not like a bank account where having one is a requirement of life, you can therefore also put a bit of effort in to maximising your cash return if you don't want to invest it.
The difference is that you are stuck practicably speaking if its for example a sipp - its not practicable to swap sipp suppliers continually to get a better rate foir the cash you have so added protection makes sense. As you say though if decent rates are on offer easily and peeps chose not to use them then thats not really teh fault of the provider - specifically ref AJ though i dont know if they make it easy to earn a decent crust on balances - if they dont then the fcat you cant easily extract elsewhere seems like they are somewhat taking advantage of a captive market.
I suspect one of the reasons Royal London Short Term Money is so popular is precisely because its a secure option for spare cash held in a SIPP or ISA though of course you still have to pay the platform fee
Or short dated gilts eg TN25. There was a useful disussion on this the other day. If you just sit this out you have a fairly secure 5%. Also hold Royal London Short term money - along with just about everyone else.
If you hold in an ISA without platform fee eg IWEB then the return is free of broker fee erosion.
There are times when everyone's circumstances mean that they may wish to hold cash in an ISA or a SIPP. The brokers have been making a steady and growing cut here and its no surprise that the FCA has woken up.
Actually there is hardly any difference on instant and fixed rate terms now. On HL the too instant rate is 5.06%, 1 year fixed is 5.32%.. Longer term rates are lower.
General comment here addressing several points above, not a specific response to Rusty2.....
It is all a bit more complicated than our discussion so far has covered.
The issue that arises is whether the skimming of interest cross-subsidises the platform/custody fee and distorts competition in the sector.
The AJ Bell accounts stray perilously close to admitting it:
"We have been mindful of the need to share the benefits of higher revenue margins across all our stakeholders. For customers we have kept our prices low, paid a competitive interest rate on their cash balances and invested in our propositions; for our people we have improved our pay and benefits package in response to the rising cost of living; and for our shareholders our investments in brand and propositions position us to continue to increase our market share, whilst once again increasing our ordinary dividend."
If so, then it makes a mockery of price transparency in the sector - when you sign up for a platform you know what the monthly custody fee and per trade commission will be, but you have no idea what they will skim from your interest. You are unable to do a true price comparison if there are cross-subsidies going on.
There is a precedent of the FCA intervening in these matters. It used to be that fund managers could generate a nice little revenue stream by lending out client assets via stock-lending programs. Most don't bother any more because the FCA said they would have to start passing on the benefit to clients, retaining only a small portion to cover their expenses in running the lending program - at which point the fund managers decided it was no longer worth the candle.
I therefore suspect the solution will be for platforms to declare up front on their rates sheet what margin they will skim off client cash, and then stick to it. Customers will then be aware before signing up to a platform.
I think you have replied to the wrong person. I was talking about interest rates on savings not in the share account.
But some platforms pay interest and others don't. I see your point but what matters to most people, is how much interest you are being paid, on your cash on the share platform. IG group (LON:IGG) pay nothing, Hargreaves Lansdown (LON:HL.) pay various rates depending on the amount, Interactive Brokers (NSQ:IBKR) pay around 5%, I think. I have moved some of my Share ISA cash from HL, into a cash ISA that pays 5.8%.
deleted - amended earlier post instead
The problem with this analysis is that you are applying commonsense. That is not how the FCA work. They will view our laziness as predatory behaviour by the platform and legislate accordingly. Personally, I thnk it is too much of a risk to invest; but, of course , each to their own.
Really great post .... I think the days of raping customers on returns on their cash balances - for this is surely what it is - will come to a fairly abrupt end in the not too distant future. The interest works out at just under 75% of total revenues. There is a bigger political risk in the likes of A J Bell and H L than we think.
There is one little niggling issue though ... these platforms need to pay for the service they provide us one way or another. I do wonder to what extent low dealing and platform charges are cross-subsidised by this. We end of paying one way or the other ..... it is just an issue of semantics. What would we like to call it?
An excellent analysis Monty Carlo, made for a great read through this morning, thanks. It's certainly something to think about and keep an eye on. For those wondering AJ Bell currently pay 3.7% in a SIPP & 2.45% in an ISA, for cash above £10k. Slightly less for below £10k. Hargreaves pay more of a sliding scale capping out at 3.7% in an ISA, over £100k, and 4.2% in a SIPP with over £100k.
I totally agree this could be seen as a scammy way of treating customers and more interest probably should be passed on. However if these providers are forced to pass on more interest, isn't it extremely likely they'll simply put dealing & custody fees up to compensate? So the customer in the end won't be any better off.
Vertu Motors (LON:VTU) CEO interview this morning , published on Research Tree https://www.research-tree.com/...
I have taken the opportunity to increase my holding and it is now over 10 % of my total portfolio . Will buy more on further weakness as I see this as an excellent long term hold and obviously a short term takeover target .
I have done the same although not that large a % of portfolio.
Future (LON:FUTR) After the massive decline this a.m. this is now qualifies as under £1bn, so here are some notes as it is not being analysed by the team today:
Revenue and Profits
Outlook Statements
Going Concern
Funding Needs
In summary, while financial results declined modestly year-over-year, the outlook statements were positive about returning to growth. I believe the share buy-back is still in place too. The only other negative was the loss of a director who had been with the company for 8 years. My stop loss kicked in so I am no longer a holder!
£FUTR I'd point a few other negatives (although arguably these are all more than priced in after the vicious sell-off over past few days):
- Margins guided down to 28-30% (from 32%) - that's roughly a 10% drop, so quite hefty.
- 10% fall in organic revenue was pretty poor given we've had inflation of 5-10% - so you're probably talking a 15% fall in real terms. And recession not even started yet so could be a lot worse to come.
- They mention they expect organic growth to return in H2 24 - that's quite a way out, so strongly hints that current trading is not great and they're hoping it will improve some time next year.
Overall, not one for me as while very cheap, it is clearly not trading well and from my experience share prices only really recover when trading improves, and this doesn't look like this will be anytime soon.
What I don't understand with today's results at Future (LON:FUTR) is the difference between the relatively cheery full year trading update (29/09/2023) and today's more gloomy results. What can have happenned between now and then? What am I missing?
That said I am still a holder this morning, though with a disciplined stop-loss approach it would indicate a sell.
Situation reminds me slightly of Moneysupermarket.Com (LON:MONY) which is also highly cash generative, but whose earnings are viewed as low quality by the market.
The valuation of Future (LON:FUTR) with this morning's 15% share price drop seems attractive on a PER and cashflow basis (Sub 10x). With their loss of a long standing director and mismatch between two recent financial statements, that leaves a niggling doubt.
If nothing else, I wish the company would reign in the share buybacks until debt was under 1x expected free cashflow.
Future (LON:FUTR)
is it a coincidence that the Chief Financial and Strategy Officer has just handed in her notice - perhaps now succession planning is firmly in place she may not want to paint any rosy pictures when she wont be about to deliver?
dont know the exact details but imho its never great news when any compoany says "we need to invest now for a rosy future at some unkown point in the future " - sometimes its true but is that not just an excuse for being caught with their pants down ? ie why didnt they previously invest so that rosy future is right now ?
Future (LON:FUTR)
I would assume it is not a coincidence. I watched the first results webinar with the new CEO some months ago and remember thinking how stark the contrast was between the new CEO and current CFO. The CFO seemed quite reserved and calculated - the CEO was far more entrepreneurial, high energy and looking to put his stamp on the company. I remember thinking there isn't a hope in hell they'll gel and make a good partnership - despite their skills probably being what you'd like in a CEO and CFO. This is obviously purely anecdotal and I may have misread the situation.
A further cheeky comment is I think they've paid pretty 'toppy' prices for the brands (/ websites) they've acquired - which is what's helped rack up the current debt pile. I think some greater prudence wouldn't have gone amiss, but perhaps that doesn't go hand in hand with big time growth/valuations which can (and have) come plunging down to earth in a bit of a downturn.
Its great to have the 955p agreed cash offer for Smart Metering Systems (LON:SMS) but in contrast to Pauls comment above I think shareholders are being short changed! The Cavendish DCF valuation for SMS is 1494p. I think this looks like another opportunistic PE bid
Interesting dynamic going on with Kin and Carta (LON:KCT) that leaves me scratching my head a bit.
There was previously a cash bid of 110p and the market seemed to be pricing that in to fail as traded around 100p.
Today BidCo have upped the offer to 120p in cash and yet the shares are still trading at almost a 10% discount to that cash bid.
It’s a final offer unless someone else bids more. It is clear that BidCo wants the company and it seems clear enough that if they are seeing value in upping to 120p you’d expect the board are agitating other possible bidding candidates behind the scenes. (Or at least they should be if they have their eye on the ball which is often actually not the case tbh).
So feels to me like it’s highly likely the improved bid gets accepted with a much smaller probability of a further improvement. It’s all in cash so no merger/share discount.
Market is still pricing as though it is only 50/50 it goes through. I value it at greater than 150p so it isn’t a particularly fantastic offer anyway but in this market unsurprising so maybe other major shareholders are not minded to take a low ball offer?
Future (LON:FUTR) after this morning's drop this is now firmly in small cap positive territory - not one they usually cover but would be very interested to hear Paul or Graham's view as this is now on a PE of around 4-5.
'Hairy Padder' had me chuckling Paul. Bloomsbury Publishing (LON:BMY) a fantastic buy and hold share IMO.
There is a sea of red in my portfolios today, was it something I said?
Nice one!
Mine too.
Vertu Motors (LON:VTU) At this rate I could turn to drink!! Not all small cap but so far in last couple of weeks seen repeated hits to portfolio: Xaar (LON:XAR) , Diageo (LON:DGED, British American Tobacco (LON:BATS. On more serious note re Vertu Motors (LON:VTU). should I ‘stay or go’. Always sell on a profit warning but then there might be an acquirer waiting in the wings. Interested to hear the view of the SCVR team.
I was dithering about this for a while and have taken the halfway route of selling half of my current holiday at a gain of about 100% on the original price so I have my money back. The bear and bull on this is equally strong. Its gone from being my 2nd highest holding to mid holding now and I'll sit for a while now and see what happens
Sounds like a sensible strategy. Sadly I bought Vertu Motors (LON:VTU) later and am currently sitting on 5% loss so not an option. Currently a bit ‘rabbit in the headlights’ not sure which way to jump. Have got it wrong so many times in last couple of years. Even sold Bloomsbury Publishing (LON:BMY) too early as banked the profit at the time! Only share in my speculative small caps pot that is in the money is H & T (LON:HAT) and that seems to be in a bear (declining watch/jewellery sales) and bull (rising gold price) stand off. Hopefully not the next domino to fall!
Yes same for all of us, you sell and it goes up or gets taken over or you keep and it continues to go down :-)
H & T (LON:HAT) is actually my largest holding although I've held it for 7 years now so have managed to do ok over that time. Its loan book is very strong at the moment so hope for very good results on that next year.
Good luck whatever you decide
By accident I've ended up doing the same with Vertu Motors (LON:VTU) - forgot that my holding was split between two ISAs - sold one at the bell for a 17% drop (but about 10% up overall), but still holding the other. The drop is done now hopefully, so will wait to see if there is a bounce.
Does mean I've got some cash to put elsewhere though.
Dave
Vertu Motors (LON:VTU) - statement from the CEO in the link below. FWIW I've decided to hold - I got in a couple of years ago in the mid 40's. It'll be a bumpy 6 months or so if the CEO's timescale for the macro issues are correct, but I like how he states a clear plan to deal with this situation, and that they have implemented similar previously. There's also the potential buy out in the background and it's a very solid company anyway. Time will tell if that's the right decision.
https://www.brrmedia.co.uk/bro...
I joined the party late (at 80 pence) in the spirit of things and have belatedly applied DYOR today; Simply said it all yesterday.
I managed a spectacular fail by selling my stake for a 20% profit (second hand car prices falling) followed not long after by placing a long CFD trade (bidder imminent, surely). Wiped out my gains.
Coats (LON:COA) Rushing around this morning so haven’t got a lot of time for detail but Coats have reached a deal with trustees of UK pension scheme. Significant increase to FCF of £2m a month! Surely more significant than a +5% share price? I don’t hold.
Coats (LON:COA) - share price up 11.9% now - the market seems to like the pension scheme announcement! Thanks for mentioning, Feta.
Quiz (LON:QUIZ) Paul is this still on your backlog list from Tuesday? I know you speak with the company so any insight welcomed...
I unfortunately hold, got sucked in last year with their post pandemic boom in sales, the super low ev/sales ratio and the large founder/management skin in the game. Bought it as a trade and now a big ugly blob of red on my portfolio.
For what it's worth it looks like the poor trading may have accelerated the exploration of some form of corporate action, we will know what this looks like next quarter. Their going concern statement was positive and they still have net cash.
Not a fan of consumer discretionary stocks (obvious exceptions Shoe, Next, Frasers maybe even Card) but everybody makes mistakes, however this was ill disciplined given the well telegraphed macro outlook.
Hi Burnt Onions - my philosophy is that as a small retail investor the odds are always against us - so always hold back and DYOR before buying. On retail I look around - e.g. Greggs outlets always busy so too Next. What baffles me J D Wetherspoon (LON:JDW) - I went into one of their pubs early Saturday morning - amazed to find it heaving. No wonder the prices are almost giveaway - Unlimited coffee £1.50 and the cheapest pint just £1.77. I came away thinking I'd love to invest but what profits will they bring me. Back to Quiz - I occassionally pass through Westfield shopping centre. The Quiz shop there is always empty
Finally - can Paul or someone please explain what is meant by the phrase 'share based payments - see Premier Miton above.
J D Wetherspoon (LON:JDW)
wethspoons has always made decent profits (covid excepted) - so you dont have to worry about their business model it has stood the test of time and does work and generates healthy profits year in year out(back in 2018 they made as much profit as greggs) . Albeit covid/energy prices/wage increase/other inflationary increases and some peeps having less disposable income - mean they have had headwinds from covid times on that may take time to reverse long term no reason to believe their buisnes model is broke - its not far away from doing excatky what greggs does. Note spoons do accom now too so there is scope for them to pimp our their real estate - or get good real estate cheap if prices are depressed in twon centres medium term. Only real issue is on current earnings it aint cheap - then again greggs aint generally cheap either. JDW have played the long game here too investing in frehold property which should boost earnings in the long term even though it reduces profits now by bumpijng up debt and finance fees and hassle of purchase.
Free or reduced price shares for staff
The Lord give the and he taketh away .
Bloomsbury ahead and up
Vertu behind and down
1-1 score draw .
Vertu Motors (LON:VTU) and Bloomsbury Publishing (LON:BMY)
Same here planetx although I'd probably score it more like a loss on away goals with Vertu down 21% and Bloomsbury up 8%.
Snazzy
A cracking set of full year results from AJ Bell (LON:AJB) today. Pushing the small cap bracket, but I figure probably a fair few holders here.
I hold the stock and am also a customer, holding all my ISA's and SIPP with them. I have never used another broker platform to compare, though I have to say I like the platform and have no plans on switching. Easy to use and a wide range of investing options.
It's a fairly meaty set of results, so far more information than I can condense down here, though generally very strong I think.
AJ Bell (LON:AJB)
Cheers Phil P - love the layouts of your postings - kinda draws one in with the prettiness of the formatting.
Never looked at this stock before - quick look at stocky numbers suggests this is a nice garp type stock and it looks like current price is well off the peak. I like the look of the margins they are making - for what they do big really probbaly is best? , so seems like their business model should be nice and simple particulalry if clients portfolios are still generally in investment rather than drawdown phase (i would presume generally that is the case) - add a few new services along the way and bobs your uncle - with decent divi to boot. Price aint exactly "cheap" compared to the market but quality normally costs a bit more doesnt it ! . While my look is superficial the screens it pases seems like top banana ones too Buffetolgy-esque and T Rowe. I probably have some funds coming my way soon from ten entertainment sale so perhaps this will provide competition for cmc markets and others as to where my cash is redeployed - this company seems less spivvy than cmc -cmc is of interest more due to the NTAV value and history of decent profits rather than the companies future prospects looking good - they are in a real bad spell.
Are there any chartists out there who can commnt on AJ Bell (LON:AJB) - is the shareprice firmly in a downtrend ? downtrends are there to be broken so perhaps good news (or lack of bad news) could be catalyst for that to end ?
Hi rmillaree, I'm glad you like the posts. Yes I like this stock and believe it has a fairly long runway of growth ahead of it. Certainly not 'cheap' compared to some others in the financials sector, but does have a different, more defensive model to a lot of the trading companies out there. Even though the share price has still taken a hit, I think it's less exposed to large drops in revenue, due to the fact that their products focus more on investing, rather than trading. They don't really have any suitable products for real traders. Think of all the people with ISA's, SIPP's etc. Every account has holding fees & dealing charges and people don't often pull money out of these accounts, unless retiring, so they have a consistent revenue stream.
They also offer their own funds which they also make revenue on. These are proving successful and rapidly growing AUM. The question then as I see it, is simply are they taking market share? Which they have been & I think will continue to do so. Their main competitor I believe would be Hargreaves Lansdown (LON:HL.) .
AJ Bell (LON:AJB) AJB
Interesting comparison to Hargreaves Lansdown (LON:HL.) who are their main competitors
* both have excellent quality metrics though HL looks even more impressive
* HL's market share is bigger than AJB
* AJB is growing fast vs. HL which seems to have stalled at least for now
* HL has a few specific problems to face - new initiatives that may not work out, claims relating to including Woodford in its recommended fund list, reliance on profits from investing customers cash at higher interest rates, ...
* both are expensive on transaction charges and holding charges. IG e.g. is significantly cheaper than both
* share prices of both are at significant discounts to previous levels
* both are benefiting from the interest earned on customer cash but AJB are also growing AUM fast and so should cope better if this source of revenue reduces
In summary:
* Hargreaves Lansdown (LON:HL.) looks very cheap for a market leader but faces quite a few challenges
* AJ Bell (LON:AJB) looks cheap (not very cheap) but is motorin
I own HL and have just bought into AJB
AJ Bell and HL,ii
The platforms are making good money at the moment. The churn is low because it takes so long to move your assets . I recently moved my SIPP from AJ BELL/Barclays smart investor to ii. It took three months for the shares and five months for my cash to be transferred. This is a long time to be out of the market and therefore many holders stick to their current platform even if they are not happy.
one way to benefit from this unsatisfactory arrangment is to be a customer and owner of the platform at the same time. I own ii (abrdn), HL and am thinking of owning AJBell .
Hi Phil do you have a template of your sheet that you might be willing to share? Nice sheets!
Hi Dave, it's simply text in boxes on an excel sheet. It would probably take more time for me to figure out how to share it than to simply re-create it.
Interested to hear Andrew Carter from Chapel Down (OFEX:CDGP) on the BBC radio 4 Today programme talking about moving today from AQSE to AIM, citing wanting access for institutional investors. They produced 1.4million bottles of wine in 2022 and hope to double this by 2026, their ten year plan is for 5 million bottles giving £100m revenue. (I have no position).
I hold, in profit and get 33% of the excellent wines they make
That's a lot of wine!
Re Chapel Down (OFEX:CDGP) I think they have b***red up, or AIM has, their transition to AIM today as they seem undealable at the moment, and there is no trade data.
Bloomsbury Publishing (LON:BMY)
Some good news for my portfolio in what has been a difficult year for UK small and mid cap shares
I am not often right, but pleased to to say my view that the company was being overly conservative with its outlook at the interims proved correct. Will be interesting to see the market reaction.
Trading ahead of expectations.
"Revenue is now expected to be comfortably ahead and profit before taxation and highlighted items materially ahead of current market expectations* for the year ending 29 February 2024. This follows exceptionally strong trading in the Consumer division for a number of titles and particularly Sarah J. Maas' 15 titles. Bloomsbury has published all of Sarah J. Maas' books throughout the world and has seen excellent growth in the backlist. The Non-Consumer division continues to trade in line with current expectations."
I must say I'm really shocked at the lack of activity around this. Up only 7% with, only 40 trades gone through in the first half hour, mostly sells and nothing for over £15k on the buy side. Seems strange for a £375mil company that has just put out a materially ahead statement... any ideas?
The market is moribund. Hence all the takeovers . It's like taking candy from babies.
Games Workshop (LON:GAW) down 10% on what seems to be an inline update?
Great expectations?!
When you are on a “growth” p/e of 23 like Games Workshop (LON:GAW) you have to do better than flat/in-line especially if your most profitable piece (licensing) is flat to declining. A downward re rating in this stock could be quite painful.
Games Workshop (LON:GAW) looks like it is ticking along to me. Licensing is the big untapped market. With Frontier Developments (LON:FDEV) apparently making a horlivka of their game adaptation and no news on the Henry Cavill backed Amazon Warhammer production things could drift there. But in the end, they have world class IP that they are simply not exploiting. Having sat through most of the Marvel and Star Wars output with my son, I'd be surprised if GAW didn't end up being swallowed by Walt Disney Co (NYQ:DIS) or someone similar. The IP is so stupidly good that the licensing should be generating hundreds of millions a year.
Ah, but their high rating is also a reflection of the exceptional quality metrics - ROCE, cash generation beyond amazing
re. Games Workshop (LON:GAW), I topped up this morning on the pull back because this company just keeps on churning out remarkable results. Although today's update is only inline, the numbers are still quite astonishing. I expect people may get bored, the share price may drift and then, quietly, without fanfare I wouldn't be surprised to see a news release about the Amazon deal when nobody is paying much attention.
I just ask myself what this business might look like in ten years time and quite honestly, if Hotel Chocolat can be currently worth half a billion, then what price would an American acquirer put on this gem?
Games Workshop (LON:GAW) Thanks, just thought I was missing something, surprised it went down so much, Stocko had it down 15% but when I checked, it had already recovered somewhat. I think in the past, they tend to beat the forecasts, so inline is disappointing. I share your view on a takeover.
Worth looking at Future (LON:FUTR) today as it was a poster child for AIM and is still a pretty big company. Was in a nice uptrend for a few months, buying back its own shares every day, then down 20% last week and another 20% this week on poorly received results.
I have no position, but it raises so many questions. There are lots of companies buying back their own shares, but it makes no sense if your results are disappointing. And why the dump last week? It is just symptomatic of the "smell" around the UK market imo.
Two brokers downgraded Future (LON:FUTR) which caused the big drop recently. More misery today on results.
Its the Bioventix (LON:BVXP) (I hold) AGM today at 2pm. I was half thinking of going. Has anyone been in prior years? Does anything happen or just the legal requirements in 15 minutes?
Re Bioventix (LON:BVXP) I have never been, but when I have met Peter Harrison in the past he is one of the most open (and nicest) CEOs around. Best part of AGMs (or indeed any shareholder meeting) is the opportunity to chat informally afterwards and (hopefully) have any doubts assuaged.
Thanks grumpy, my dilemma is whether my questions are going to be intelligent enough in a company where I don't understand the technology to be worth a 2.5 hour round trip.
PH knows that most of the rest of the world don't understand his science as well as him, and would gladly lead you through it. But 2.5 hours? Not sure I would fancy that much driving in the SE.
Martinck1 - Bioventix (LON:BVXP) . If you hold your shares via a platform such as Interactive Investor, you won't personally be on the share register, so not automatically entitled to attend..... You'd need to get a letter of representation from II - not enough time today.
If you turn up clutching a print of your account, you will probably be allowed in as an observer. But you'd be unlikely to be able to ask questions in the meeting, or vote.
As others have said, it's v well worth going to some AGMs
Thanks garbetklb appreciate that, but I have some in my own name
Hi Martinck1. I've not been but I know that respected PI, Maynard Patton does attend and podcasted about his experiences at the last AGM which included a surprising amount of dissent against Peter Harrison, CEO. From what I recall it was an interesting AGM and he picked up some nuggets (including the revelation that the environmental testing development was proving to be challenging). The podcast (which he did with Roland Head of this parish) can be found here: https://podcasts.apple.com/gb/...
Thanks to both johnsmith68 and grumpy5, your thoughts are much appreciated. I’m a happy holder, but I’ll listen to the podcast later and decide.
Bioventix (LON:BVXP) AGM: Well thanks again grumpy5 and johnsmith68, I did go and listened to the podcast on the drive over there. As you said, Peter Harrison is a very open and interesting CEO and it was helpful that they were some other knowledgeable holders there who created some interesting discussion. Impressive new non-exec. My understanding of some of the votes against some of the resolutions were that they were box-ticking formulaic voting, which we need not pay much attention to. IMO, no dissent in the room.
Latest brick sales/stats, nothing shocking but interesting info for those holding housebuilders, brick manufacturers or distributors
https://www.linkedin.com/posts...
'Brick deliveries in October 2023 were 1.5% higher than in September and were 27.6% lower than a year earlier according to latest data from the Department for Business and Trade). This is in line with the views of house builders, who stated Summer was poor, September did not have the usual pick up and October only had a marginal improvement.'
Thanks, TB_Investor, a very interesting read - especially that house builders are completing builds but not starting new ones, and recovery not anticipated until end 2024 or 2025.
Two nasty profit warnings this morning Vertu Motors (LON:VTU) and FUTR my policy is to get out first thing when things start going pear shaped. Took a couple of big losses this morning but does show benefit of having a diversified portfolio with max 3% in any position - as a result my overall portfolio is somehow little changed from yesterday
Vertu Motors (LON:VTU) was a little unusual because the price had increased on large volumes leading up to the update, so the profit warning maybe wasn’t expected. I got out early as well just in case the news isn’t fully priced in.
B.P. Marsh & Partners (LON:BPM)
Chomping sale for bpm this morning
11.3 mill uplift from July valuation so that’s some excellent profit being books with potential for another 17 mill plus based on future events
Company was already trading at a decent discount with decent excess cash
They also have about 60% of the market cap in cash once this goes through. Understand they have a lot of deals in the pipeline but surely there needs to be a special dividend from this one. Happy holder here
B.P. Marsh & Partners (LON:BPM)
but surely there needs to be a special dividend from this one. Happy holder here
Yes and no - timing is like london buses my memory says that bpm had fully loaded up to march 2022 (to a certain degree funds at bank were pretty modest after that date up to recent chunky disposal ) - whilst having many opportunies coming through the door . This company lives to invest in others and imho that almost kinda works best from cash just sat there - certainly in the somewhat higher interets rate era its not all bad if they have cash sat there earning 4% plus as long as they have aplan to invest over the next 1-3 years. I am not against special divi personallyif they feel thats right and it could very well make sense but if they feel its right to do nothing now with cash to reinvest later if there is the appetite there i will go with the flow - management seem sensible here.
Its been a decent wait to get some realisations with the cherry on top - i guess the good thing even without any recent cherries is that they seem to be have been eeking out decent increases in NTAV anyway. Do they still have stake in that company that was going to be floated but didnt ?
I guess the one thing with 2 of the big investments being sold on is that the increases in near term NTAV are likley to be limited if more of the company is held in cash. Hey ho nice to have a little plodder doing ok in these turbulent times.
Chariot (LON:CHAR) Deal signed!
· Energean to acquire 45% and 37.5% interests in the Lixus and Rissana licences respectively, and take operatorship of both licences
· Chariot will retain a 30% and 37.5% interest in Lixus and Rissana respectively, with ONHYM maintaining a 25% stake in each licence
· Chariot will receive:
o US$10 million payable on completion of the transaction
o US$15 million payable on Final Investment Decision ("FID")
o US$85 million gross carry including:
§ All Lixus costs up to FID, including the additional Anchois well with a gas flow test
§ Planned Rissana seismic acquisition costs separately capped at US$7 million
· Following completion of the Anchois well, Energean will have the right to acquire a further 10% of Chariot's equity in the Lixus licence for:
o US$850 million gross development carry to first gas (including the US$85m gross carry)
o US$50 million 5-year zero coupon convertible loan note with a strike price of £20 adjusted down for dividends or issuance of three million Energean shares, at Chariot's option on FID
o 7% royalty payment on Energean's gas production revenues in excess of a base hurdle on the realised gas price (post transportation costs)
· Energean's carry of Chariot's costs is non-recourse, and has a coupon of 7% over the one year Secured Overnight Financing Rate (SOFR), with the carry including interest repayable from 50% of Chariot's future net sales revenues from the Lixus licence
· Completion of the transaction is subject to standard Moroccan regulatory approvals
Chariot (LON:CHAR) market has gone “meh” to this. I think investors expected more upfront and higher carry.
There is a call at 10am so see what mgmt say then.
I don’t understand the 7% royalty payment. It say on Energean gas production revenues in excess of a base hurdle gas price. Does this mean ALL of Energeans gas production or just the licences in question? The former might be very significant but I assume the latter despite the wording suggesting otherwise.
Be interesting to see what the analysts move risked NAV to. Was around 50p so anything materially lower implies a poor deal
Congratulations to Paul and Graham for delivering so much content so early today.
#SMS
Many congrats to anyone who's benefitted from today's 955p/share all cash acquisition (40% premium) of Smart Metering Systems by KKR.
Judging by the guy who came to our place 2 weeks ago Smart Metering Systems (LON:SMS) employ some right numpties, and I'm being polite there!
Probably the only redeeming factor in my otherwise dismal SIPP
Vertu
Be interesting today
Great chance for any potential buyer to mop up a decent chunk of shares .
Bid premium arguable does not change and arguably increases .
Any potential buyer who has been building is unlikely to be put off by a profit warning as they are surejy already on the inside of market short term movements .
On the positive (digging a bit too deep for ray of sunshine ) a bit of a sell off now could sell flush out a serious buyer to swoop and make a move .
I’m sure last week holders would have been looking for 1.20 a share to approve , As of today probably holders will agree 1.00 a share
So that’s a “20% off” ticket so a buyer has just saved themselves circa 57 million quid ??
Hi Planet X - I agree. I had ummed and arghhd last week wether to sell out and take my small profit on Vertu Motors (LON:VTU) due to the cyclical nature of the stock and having watched it climb up to the mid 80's.
However, I was too tempted by a potential bid so decided to hang on. With this PW I am having to again rethink my strategy, and TBH with potential bidders in the wind I will take the 20% SP drop (complete guess) today in the hope that one of them materialises.
I had recently told myself to follow the rationale "sell on a PW whatever" having not done so too many times, but I see the first time this is tested I have fallen......oh well.
Good luck to all holders this morning. I hope none of us regret our decisions whatever they are.
Vertu
Profit warning or not
Still a good company with no debt loads of cash and making profits and below NAV
Sill cheap and still a good company
Remember Mr Market is a manic depressive fixated on emotion and short termism .
Bid premium remains .
Nothing much to worry about with vertu .
Been holding #VTU from around 30p and not planning on selling on this as the fundamentals are still there for a sellout. I considered at some point top slicing but with this mornings fall thats off the table.
I doubt we'll see any action this week as everyone will wait to see where the SP settles but who knows
Latest figures show £175M debt
Brain fog
, I was going off clearly declining memory, pre Helston ? purchase they were net cash .
Vertu Motors (LON:VTU) new Zeus note out. Still forecasting eps of 8.2 for 2024, 10p for 2025.
I sold this morning to consolidate my profits. Like you, I ummed and arghhd (never knew how to spell those so thanks for that!) about selling over the last fortnight.
I'm still going to keep an eye on it though - it's even more of a takeover target now I think.
Any thoughts on SDI (LON:SDI)
Bloomsbury Publishing (LON:BMY) materially ahead....
And looking at the Vertu Motors (LON:VTU) warning this morning I think we all owe contributor JASVFS a vote of thanks (or in some cases an apology) for his post on Oct 24 where he commented on what he was observing from friends in the motor trade.
To save everyone going back and looking:
ASVFS Joined 2015 249 posts Oct 24, 2023
Off topic today but I feel beholden to mention this, we have sold our top holding Vertu this morning after increasing warnings from knowledgeable friends on car sales across several large dealer groups. Margins are under severe pressure and sales falling quite badly, used car values are also being hit hard. We will happily buy back in if Vertu doesn't hit forecasts. I also assume any likely bidders for Vertu will also be aware of the trading environment and might wait. If they don't it will add to my collection of big mistakes. For what it's worth our top holding is now Ramsdens which we topped up on recently.
Imagine we start uploading when and who said what!
On the day he posted that I have disagreed and I still disagree.
Firstly , the price on the 23rd of OCT was 72p-74p therefore nothing much really has changed.
Secondly , on the 23rd of OCT Vertu Motors (LON:VTU) has bought over 300K shares at 74p!
Thirdly , after the 24th OCT a giant involved in the industry was buying share up to 85p.
Then another major dealer had bought 3% of the company at 85p.
Lastly , I have seen Zeus NEW research note in the morning and I have used my Santa ten pin bowling gift to add to my current holding.