Small Cap Value Report (Thu 7 Oct 2021) - POLX, RWA, RBG, SUR, SOS, PDG

Good morning, it's Paul & Jack here with the SCVR for Thursday.
Market comment (from Paul)
We've had a brutal correction in small caps especially in the last few weeks. Looking at the futures (FTSE 100 predicted to rise 81 points [as at 07:01]) then this could be a good day for putting some fresh cash to work, grabbing some bargains. The early bird catches the worm. Unfortunately, my longs have taken such a battering in the last week especially, that I don't have any spare cash to deploy, having recycled all my French Connection (LON:FCCN) (I no longer hold) gains promptly into Scs (LON:SCS) (I hold), where I see excellent risk:reward (long term - I've no idea about short-term price).
I feel there have been some unreasonable price drops in good quality small caps, and can certainly see bargains around, for the first time in ages. Although plenty of other over-priced shares have rightly come down in price (and many still look overvalued to me).
I can understand why companies with supply chain risk would fall back a bit, but not to the extent that some have fallen (30%, even 40% can be seen in some cases). After all, supply chain disruption is a temporary factor, and probably isn't going to affect earnings much, if at all, from 2023 onwards.
Although this does have the look of a panic sell-off, because I've noticed plenty of companies with little, or no supply chain exposure (e.g. services companies) also sell-off. Some people, especially relatively new investors, tend to panic sell when things fall, then try to buy back, thinking they can catch the bottom. I've found that doesn't work well for me in the long run.
I'm not going to provide a list of bargain shares - this site is all about doing your own research (DYOR) remember, we're not tipsters, and you already know which shares we rate highly (from a value/GARP standpoint), from our daily commentary.
EDIT: it also occurs to me that companies which put out positive trading updates now, which have seen indiscriminate share price declines, could be a good place to start, in terms of deploying cash, because there's no uncertainty about current performance - which improves risk:reward (the most important investing concept). Whereas buying other companies, which have not yet provided a recent trading update, involves more guesswork about current trading. End of edit.
By all means post comments explaining what you're buying & why, if you want to discuss particular shares. Or if you're not buying yet, also we'd be interested in hearing why.
Agenda -
Paul's Section:
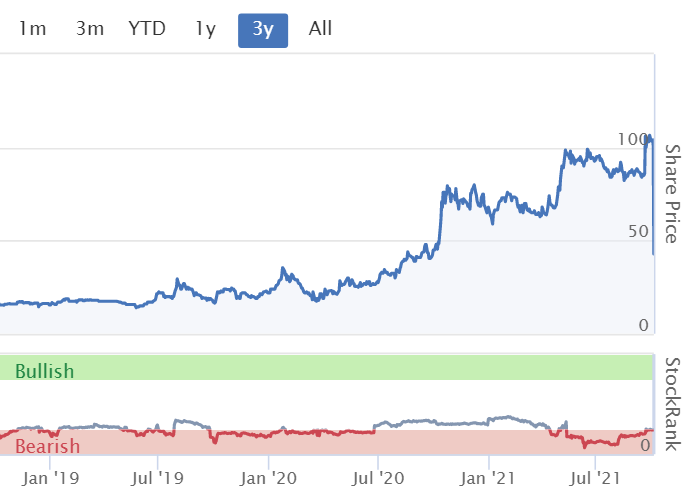
Polarean Imaging (LON:POLX) (I hold) - a shattering disappointment last night for holders, with FDA approval denied. Price dropped c.60%. The company says it has enough cash to tide it over, and is addressing the issues & hoping to resubmit. Long delay likely. Terrible news, bad luck to fellow holders.
Revolution Bars (LON:RBG) - a superb trading update - LFL sales +17% since restrictions lifted on 19 July. With the high operational gearing, this has fed through to stunning free cash generation of £8.7m in just 3 months! The market seems to be asleep as to how good this is, and I think we have a lovely buying opportunity right now. Covid remains a risk though maybe. Now holding net cash, and with all problem sites disposed of, this business is now comprehensively fixed, but the market cap has yet to reflect that, in my opinion.
Sosandar (LON:SOS) - very strong revenue growth in H1, and on track to meet market expectations for the full year. I think a beat looks more likely. Still (modestly) loss-making, but profits now clearly on the cards for future years, assuming nothing serious goes wrong. Lots to like here, but how to value it? Under £100m strikes me as reasonable, given sector comparisons.
Pendragon (LON:PDG) - another car dealer reporting very strong profits, and an upgrade. Doesn't seem quite as positive as yesterday's updates from LOOK and MMH though. They're all cheap, but riding an unsustainable profits boom. PDG confirms what we heard yesterday, that golden market conditions for profits (driven by supply shortages) are set to continue for the rest of 2021.
Jack's section:
Robert Walters (LON:RWA) - continued strong trading from this recruiter, with Asia Pacific in particular doing well. The shares are approaching all time highs and recruiters are cyclical, but it's hard to argue with the current momentum and it seems as though further EPS upgrades must follow.
Sureserve (LON:SUR) - positive update, with the order book up 30% year-on-year and a recent £140m contract extension suggesting buoyant conditions. The momentum on display suggests the share price could go higher, but the inherent business model risks must also be considered.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Polarean Imaging (LON:POLX) (I hold)
43p (down 59% yesterday) - mkt cap £89m
Complete Response Letter received from FDA
Polarean Imaging plc (AIM: POLX), the medical‑imaging technology company, with an investigational drug‑device combination product using hyperpolarised xenon-129 gas to enhance magnetic resonance imaging (MRI) in pulmonary medicine…
Bad luck to fellow holders of this speculative share. The nightmare scenario unfolded yesterday afternoon - the widely expected approval by the USA’s Food & Drug Administration actually resulted in a rejection. The story with Polarean was that it was supposedly quite straightforward, using existing chemicals (something like that!), so FDA approval would be straightforward. that's turned out to be wrong.
The FDA has -
… provided a list of issues to be addressed by the Company. These issues are mostly technical or manufacturing-related in nature and centre around the Xenon hyperpolariser system.
Polarean will work to address the issues identified by the FDA with a view to resubmitting the NDA and securing FDA approval as quickly as possible. Following resubmission of the NDA, it is expected that the FDA review period will take 2-6 months…
...the Company believes that the issues to address in the CRL are attainable...The Company will seek additional discussions with the FDA as a matter of urgency and further update the market when material information is received.
Liquidity - crucially, the company says it has enough cash to get through -
Polarean's net cash balance of $38.2m as of 30 June 2021 allows the Company to fund operations comfortably through the anticipated Company response and FDA review periods.
My opinion - this type of share is completely out of my comfort zone and expertise, so I hardly ever invest in speculative, jam tomorrow situations.
In this case, I followed several friends in, so it was just a smallish punt (under 1% of my portfolio), which so far hasn’t worked. I take full responsibility for my research & buying decision, so it's my fault that I made a loss, not my friends'.
Given that the company has cash to continue, and that it’s now a tiny position (under 0.5%!) I’ll just run with it, and see what happens. In terms of timescales, it sounds like we could be looking at a wait of maybe a year, at a guess? I'm not interested in averaging down on a losing position where the fundamentals have gone badly wrong.
All in all then, a big disappointment, which often happens with speculative shares. I’ll stick to my knitting in future I think, with profitable value/GARP shares instead! Lesson learned.
.
Revolution Bars (LON:RBG) (I hold)
22.5p (pre market open) - mkt cap £52m
Revolution Bars Group plc ("the Group" or "the Company"), a leading operator of 67 premium bars, trading mainly under the Revolution and Revolucion de Cuba brands, is pleased to announce a Q1 update.
RBG has a FY 06/2022 year end.
We last heard from the company in a year-end trading update, which I reported on here (1 July 2021). Here’s my summary from 1 July 2021, to save time -
Revolution Bars (LON:RBG) (I hold) - a strong trading update. Since re-opening indoors, 86% of 2019 revenues achieved, on only 28% capacity. Guidance raised, and net debt largely eliminated by recent 20p placing. Good upside here in my view, providing covid restrictions don't return. [SCVR, 1 July 2021]
Today’s update is the first since covid restrictions were removed, and the company previously told us that they expected to see strong pent-up demand, which is very much the case.
Here’s my summary of today’s update -
Restrictions removed in England from 19 July, 2 weeks into new financial year
Like-for-like (LFL) revenues up a barn-storming +17% against pre-covid 2019 comparatives (this figure is from 19 July, not including the first 2 weeks of still-restricted trading, until last week 2 Oct) - this proves that there is indeed strong pent-up demand - probably helped by a reduction in overseas holidays, and staycations?
Unrestricted English sites (56 out of 67 total) did even better, +21% LFL vs 2019
Refurbishment programme has recommenced - this is key because, with hindsight, it was the gradual deterioration in condition of sites which caused the previous problems (they had a 7-year refurb cycle, when it should have been 5-year. Previous management focused on opening new sites, instead of properly maintaining the existing ones)
Profitability -
This strong trading performance was well ahead of the Company's expectations for this period, and costs have continued to be well controlled resulting in good profit generation from these sales.
Outlook - just a standard statement here - fair enough, if we’ve learned anything from the pandemic, it is surely that nobody knows what the future holds -
Whilst confident in the outlook for the business in the current trading environment, the Board remains cautious of the potential impact of an escalation of Covid-19 and any associated restrictions on the business in the upcoming key trading months, including Corporate Christmas parties…
… We are therefore confident in the Group's outlook assuming that there are no further restrictions on our ability to trade.
Liquidity - this is very impressive -
The Group's balance sheet remains strong, with net cash of £3.7m and £36.5m facility headroom as at 6 October 2021.
It doesn’t specifically say so, but the net debt figure quoted does not include lease liabilities (rightly so). Sorry, net cash. Yes, net cash! Last time the company reported, as of 30 June 2021, RBG had net debt of c.£5m.
Therefore, today’s number of net cash of £3.7m means that it has generated £8.7m of free cashflow in just 3 months! That’s an astonishing figure. It probably won’t include much working capital benefit either, because the bars were already trading (hence stocked up) at the start of the period. There could be other one-offs in that number, but I can’t think of any unusual receipts that were due. If anything, there would probably have been outflows, to catch up with any stretched creditors. Although the company had previously said that there were no rent arrears.
It's fair to say that LFLs are likely to gradually settle at a reduced rate, +17% is probably not sustainable, but the prior year comps remain soft for about another year, so I'm anticipating very strong peak season trading at Xmas/NYE (assuming no lockdowns).
Diary date - 16 Nov 2021, for (now largely irrelevant) results for FY 06/2021.
My opinion - I think the market is asleep, and doesn’t seem to have realised what a fabulous update this is. I haven’t looked at all competitors, but off the top of my head cannot remember other bars groups achieving such strong LFL growth. I did look at J D Wetherspoon (LON:JDW) results over the weekend, a fascinating read actually, as Tim Martin gives a superb critique of corporate governance rules, and how they damage good businesses. He also writes convincingly about other issues, such as supermarkets undercutting on price, and the social damage this causes. JDW’s recent trading was not at all impressive, with LFL sales down -8.7% on 2019. RBG is up 17%, a huge outperformance against arguably market leading pubs group JDW. There again, RBG is not a pubs group, it focuses on late night bars, a hybrid of a bar/nightclub really, targeting mainly younger people.
Moving into net cash at this stage, shows the business is now generating shedloads of cash. This removes any lingering worries about solvency, and means the company can press on with refurbs, new site acquisitions (there must be plenty of good sites available on reasonable rents), even divis/buybacks.
The situation is completely transformed, and the market often takes a while to digest that, so I think we have a very good opportunity here, to buy at an extremely attractive multiple of likely cashflows. That’s assuming of course that covd restrictions don’t once again cause chaos - your individual view on that is the key factor here.
VAT is not mentioned in today’s update, but the reduced rate of VAT will have helped boost profits & cashflow. Although food & soft drinks are a small part of RBG’s business, and alcoholic drinks did not attract lower VAT. Therefore, the benefit is probably not material.
Based on today’s information, I see potentially 50-100% upside on this share price, based on a reasonable multiple of cashflows. That’s taking into account the awful dilution we’ve seen, with 2 emergency fundraises, both at a lamentable 20p. However, that doesn’t matter, if you filled your boots at 20p or less, as we make back the previous losses by holding many more shares now.
Hospitality generally is attracting a lot of interest at the moment, with Various Eateries (LON:VARE) managing to float at (to me) an inflated valuation in Sept 2020. Also, Nightcap (LON:NGHT) managed to float (again at an inflated price, in my view) in Jan 2021. Both have drifted down since, as the newness premium begins to wear off.
I much prefer the old/staleness discount for RBG, because I’m getting a radically improved business that is now generating massive cashflows, and has ditched all the problem sites with a CVA or consensual negotiations with landlords, raised 2 lots of cash so it’s now eliminated that bank debt completely, and is now in expansion mode again just at the right time.
This is a really good opportunity in my view, if you can focus on the future, not the past. I’m staggered that we can still buy at 23.5p at the time of writing. That seems the wrong price to me. 30-40p looks justified on the greatly improved fundamentals, in my opinion. I could be wrong of course, and have been before.
I'm completely ignoring broker forecasts, which seem way too pessimistic, given the stunning cash generation announced today.
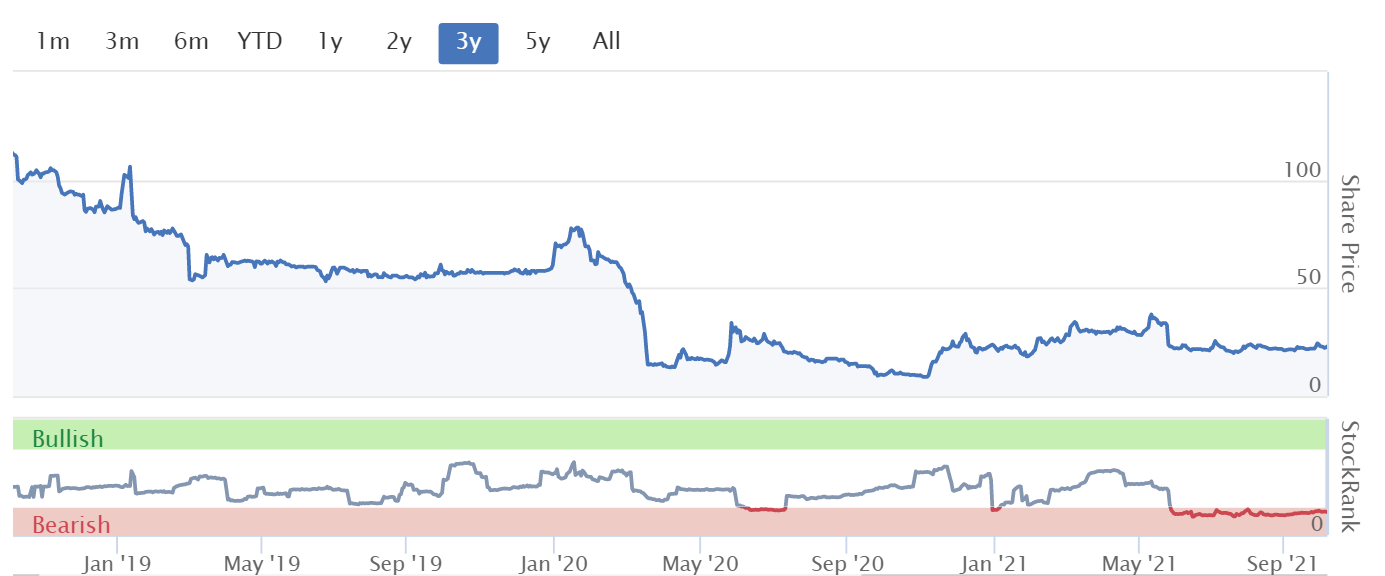
NB. When viewing the 3 year chart below, remember that the share count has risen from 50m to 230m in two placings at 20p. Therefore previous highs are unattainable now. so it's meaningless to draw lines on the chart, unless you do it from when the share count was most recently enlarged (June 2021).
.
Sosandar (LON:SOS)
30.25p (up 20%, at 10:58) - mkt cap £67m
(For accuracy, I always recalculate the market cap manually, so the £67m above includes today’s 20% rise).
Several friends messaged me early, to say it’s a good update, confirmed by a 20% share price rise.
Readers have already covered the main points in the comments section below.
Looking back through our archive, Sosandar last reported on 20 July, which I reported on here, concluding that stellar Q1 (Apr-Jun) revenue growth of +256% looked like a game-changer, with Sosandar probably heading for breakeven or a small profit in FY 03/2022.
Sosandar, the online women's fashion brand, is delighted to provide the following trading update covering the six-month period ended 30 September 2021.
A very strong first half with revenue up 184% year on year, continued improvement in EBITDA and a record start to autumn trading
Very strong revenue growth - bear in mind that growth had almost stalled a while back, so this is a dramatic turnaround -
Revenue of £12.2 million, a 184% increase against the same period in the prior year, and more than was generated in the entirety of FY21
Still loss-making though (no figures given, but it’s only 7 days after the H1 period end) -
Continued improvement in EBITDA loss
Gross margin - is up decently to 56.5% (H1 LY: 52.3%). That’s a very good margin for the modest size of the business. In my view this shows that SOS has pricing power from designing its own products & targeting an under-served market. The improvement is also because H1 LY saw margin pressure due to discounting when covid began, reducing the gross margin at the time.
Net cash - looks ample at £7.3m, benefiting from the fundraise in May 2021. Operational cash burn should now be a thing of the past.
Inventories are rising, as planned, which sucks in cash, to achieve higher sales particularly at third party websites, the key ones being M&S, J.Lewis, and Next - “very strong” trading with them.
Current trading -
… in line with market expectations…
… Early autumn sales have been very strong as demand for 'going out' and work wear has increased.
(no footnote provided)
Customer returns rate - this is the bane of online fashion retail, with returns rates of 40-50% being the norm. During the pandemic, returns rates dropped across the sector, helping profitability - partly due to more loose-fitting casualwear sales replacing complex fit party/work dresses, and partly due to possible reluctance/difficulty of customers getting to post offices, etc.
Today Sosandar says this, which I think is positive -
Now that returns rates have normalised in line with buying behaviour, the diversified category mix has also proved to have a positive effect on returns rates which are at a lower level than pre-pandemic.
Supply chain - a smart move to bring in autumn/winter (A/W) stock early -
The Company took the decision to bring in stock early for autumn, anticipating early demand for partywear, coats, boots and knitwear. Sequins, Christmas jumpers and fur coats are already best sellers…
With all the widely publicised supply chain problems, I’m perplexed as to how Sosandar has sailed through without any disruption. I’ll have to ask them!
Sosandar has not experienced any material impact from supply chain disruption, maintaining a constant flow of stock to meet customer demand.The Company is well stocked for the autumn season across both its own site and third parties and has good visibility of incoming goods.
As the Company scales and increases its order quantities it has seen margin growth, which has offset the small degree of upwards pressure experienced on supply chain costs.
Sosandar remains mindful of the wider market disruption, is constantly reviewing the situation and will take mitigating actions as appropriate.
Diary date - early December, for H1 figures to 30 Sept.
Broker update - many thanks to Singers for an update note today, which leaves forecasts unchanged, which is: Revenues £24.4m (double H1, which seems unduly pessimistic given H2 is seasonally stronger), Adj loss before tax of £(1.5)m.
More modest growth is then forecast for the next 2 years, with a move into profit.
I think it’s too early to think about next year’s growth, as growth companies are so difficult to predict. I prefer to focus on what’s driving the growth, and is that likely to continue?
The biggest third party websites are key, and that area is clearly expanding rapidly, with more lines & deeper quantities of each, in the pipeline. Hence continuing growth looks a reasonable assumption, not wishful thinking.
My opinion - as mentioned here a few months ago, it’s now clear that Sosandar has passed the inflection point from being a cash-burning, jam tomorrow share, to becoming a viable business.
The major acceleration in growth rate this year is superb, and in contrast with the sector, which tended to have a very good 2020 (helped by lockdown), but suffering this year from much slower growth, and supply chain problems (cost & delays).
Sosandar seems to be doing the opposite - accelerated growth, and no material issues from supply chain. That is really impressive, in such a tough market.
The big problem - how to value it? I honestly don’t know. Comparing Sosandar (LON:SOS) (I hold) with In Style (LON:ITS) which has a similar market cap, I think SOS is a much better, more differentiated brand. ITS has also just warned on profits, and cited supply chain problems. Whereas SOS has just announced stellar growth, in line with expectations (small) loss, and no supply chain problems.
Another issue is the competitive threat from aggressive Chinese app Shein, and many other smaller me-too fashion eCommerce businesses. This is a direct threat to Boohoo (LON:BOO) (I hold) and all the other young, fast fashion chains (including ITS), but I really don’t see it being an issue for SOS, due to the older, more affluent demographic it serves, with differentiated product styles & fit.
SOS also does not have the heavy expense of paying (often huge sums) to “influencers” (think Love Island, reflective white teeth, plastered in makeup, botoxed lips, pouting a lot & flicking their hair around constantly) , which the fast fashion companies compete over. Whereas SOS’s influencers get the product free, but are not paid any fees at all (Lorraine Kelly is much more down to earth!). They wear SOS because they like the product. That’s a big bull point for the shares, in my view - free marketing.
Consequently, I remain an enthusiastic long-term holder of SOS shares, but don’t ask me to value it, as I haven’t got a clue. Oh go on then! Anything under £100m is reasonable in my view, so at £67m I see it as sensibly priced. If growth continues (which looks likely) then it’s the type of share I’d probably run to an over-valuation (i.e. continue holding, even if it looks expensive). It would be such a pity to sell up now that the business model has just been proven, and then watch from the sidelines as it goes parabolic (Sod’s Law!).
Something Julie Lavington (joint CEO) said in a Q&A on recent webinar stuck in my mind. She said that when they created Sosandar, the plan was to create something big. They’re not in this to build a small, niche business. Their ambition is to build something that could be as big as Asos (I hold) or Boohoo (I hold) long-term. That’s quite interesting I think. You also couldn’t wish to have more determined, and hard-working, passionate management. When I asked Julie about the risk of burn-out, she laughed and said, “We don’t see it as work, we love what we do”. That’s more than a slogan, it comes across very much in the webinars. So a big tick in the box for entrepreneurial, passionate management who have proven all the doubters wrong so far!
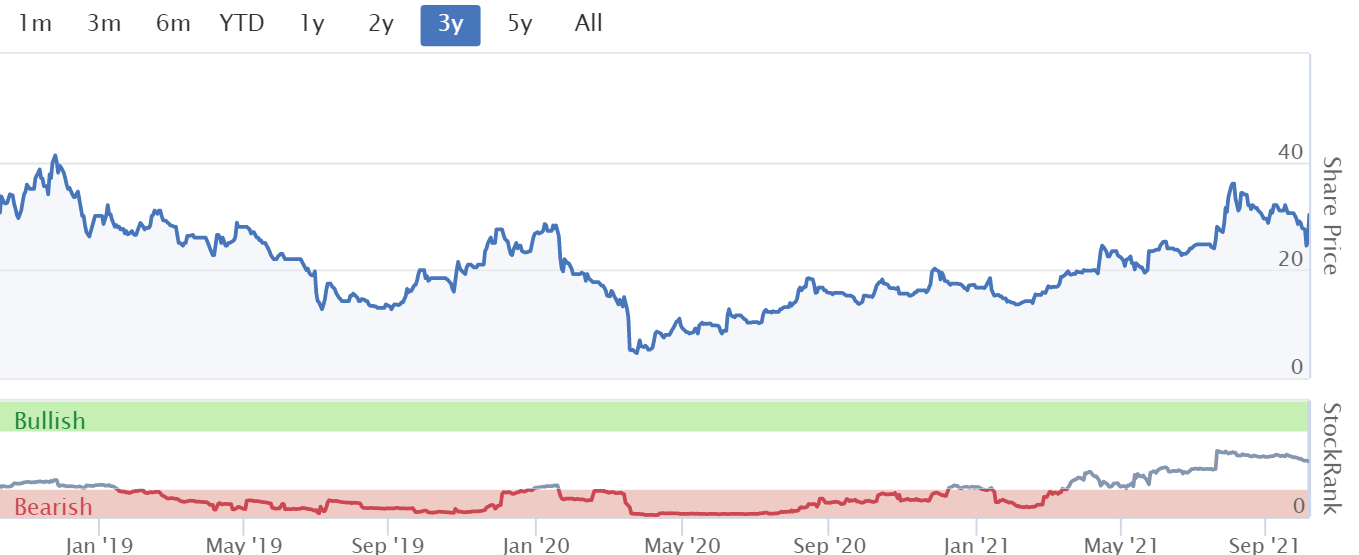
When I first got involved in SOS shares, it was a total punt. Now it's a proper business at/around breakeven, growing very strongly. Hence risk:reward is dramatically better than it was a while ago. It's interesting to note that not all jam tomorrow shares go disastrously wrong - SOS shares are double the IPO price now, despite them having to double the number of shares in issue. So 4 times the market cap at IPO.
Note how even the grumpy StockRank system (which hates jam tomorrow shares, rightly so!) has reflected SOS's better prospects, with a now middle-ranking rating.
.
Pendragon (LON:PDG)
18.5p (up 6%, at 12:44) - mkt cap £259m
I’m almost out of time, and have two company meetings online scheduled for this afternoon to prepare for & attend, so need to keep this brief.
Also, we already know from yesterday’s updates from Marshall Motor Holdings (LON:MMH) and Lookers (LON:LOOK) that car dealers are continuing to have a bonanza of profits at the moment, due to unprecedented increases in gross margins, more than offsetting lower volumes due to vehicle shortages. So I’m sure Pendragon will say something similar.
Pendragon PLC (the "Group") today provides a trading update and increases underlying profit before tax guidance for the full year to 31 December 2021 from approximately £55.0m - £60.0m to approximately £70.0m.
Crystal clear guidance there, very helpful.
Same story as we heard yesterday from the competition -
Performance has remained strong during the third quarter, with the shortfalls in new vehicle supply mitigated by strong gross profit per units in both new and used cars, as well as cost and efficiency savings delivered under the Group's strategy implementation.
Q3 order intake up on last year, but deliveries down
Key point of difference - some volume brands which PDG represents saw volumes down more than the 34.4% sector drop (SMMT figures also mentioned yesterday)
New car margins have mitigated (note - not offset, or more than offset) the volume shortfall.
Used car gross profit ahead of expectations “during September” (what about the rest of Q3?)
Used car prices (which have gone through the roof as we know) - it says this -
Whilst we also continue to expect a realignment of used vehicle margins over time, we expect these to remain strong for the remainder of this financial year, providing us with some mitigation to lower new vehicle volumes in particular.
Outlook/guidance -
Our strong year to date financial performance, together with these factors, means that we now expect Group underlying profit before tax for FY21 to be approximately £70.0m. The Board continues to believe the Group's strategy positions it well to respond to the ongoing market uncertainty and to capitalise on any resultant opportunities.
My opinion - this is obviously a good update, but it doesn’t seem as strong as the updates yesterday from MMH and LOOK, both of which pointed to out-performance against SMMT new car sales, whereas PDG says it’s behind.
I’ve heard that the car manufacturers are prioritising higher value cars, given shortages of chips. Therefore seems to be a better time to be supplying premium brands, not mainstream ones maybe?
All the car dealers seem to be trading their socks off, so I think the shares look much of a muchness.
.
Jack’s section
Robert Walters (LON:RWA)
Share price: 758.92p (+3.68%)
Shares in issue: 76,556,670
Market cap: £581m
The Robert Walters Group is a specialist professional recruitment group with over 3,300 staff spanning 31 countries. It was established in 1985 and now recruits across a broad range of fields including finance, banking, IT, legal, and engineering fields.
The client base ranges from the world's leading blue-chip corporates and financial services organisations through to SMEs and start-ups.
Business is good in recruitment right now due to widely reported labour shortages and a busier jobs market in general. Now the RWA share price is comfortably ahead of pre-Covid levels, a situation that may well be justified.

The forecast rolling PE ratio is 18.1x but the PEG is just 0.6x, suggesting further growth. We can see the broker upgrades began in April of this year, increasing steadily from 22p to 33p.

Highlights:
- Group net fee income +32% to £91.8m
- Asia Pacific +54% to £44.4m,
- Europe +22% to £22.7m,
- UK +17% to £18.7m,
- Other International -6% to £6m
Trading was strong across all major regions and profit for the full year is now expected to be comfortably ahead of guidance. I can’t actually find any concrete guidance in the half year report, but RWA has already increased guidance a couple of times. According to Stockopedia, it’s somewhere around £26m of profit before tax. That figure should now be comfortably beaten.
The Asia Pacific region performance was strong considering ongoing lockdown disruption, with Japan, Australia, and mainland China getting namechecked as particularly strong markets.
RWA continues to invest in headcount across all markets and disciplines (up 5% in the period to 3,376) and purchased 46,308 shares at an average price of £7.27 for £0.3m through the Group's Employee Benefit Trust.
Balance sheet - this is just a Q3 update so no balance sheet is reported but RWA says it had net cash of £126.0m as at 30 September 2021 (30 September 2020: £138.9m), along with a £60.0m committed loan facility until 2024. Looking back at the most recent figures suggests there’s nothing to get too concerned about here.
Robert Walters, the CEO and founder, commented:
With candidate and client confidence accelerating across all recruitment disciplines and candidate shortages becoming ever more acute, the competition for talent is fierce. Significant wage inflation has emerged particularly for the most sought after skill-sets. In short, the jobs market is hot. I am pleased to report that the Group has once again benefited from operational gearing and that profit for the full year is expected to be comfortably ahead of current market expectations.
The group will publish a trading update for the fourth quarter ending 31 December 2021 on 11 January 2022.
Conclusion
The near term outlook continues to look promising for good recruiters, with labour shortages and increasing demand for workers potentially paving the way for higher wages, which should mean higher fees for the likes of RWA.
As with a few dynamics right now though, it’s important to consider for how long strong conditions might persist, and what might happen to the share price on a 2-3Y view if the same companies benefiting from strong tailwinds right now see a bit of a cooldown.
That’s something I continue to wonder about, given my exposure to Marshall Motor Holdings (LON:MMH) and Scs (LON:SCS) , both of which report strong demand and low earnings multiples, but which feel hard to value at present due to the complex macro situation. You can add the brokers and investment banks to that list as well, which have been reporting stellar results due to an increase in corporate activity. Which trends will prove transient, and which will persist?
But back to RWA, the StockRanks are very favourable here so that points to a number of positive financial data.

And the group’s exposure to Asia Pacific markets is clearly working in its favour at present as this is both the largest and fastest growing reported segment.
If you take a long term view, the shares are as high as they’ve ever been. These are cyclical companies, so it is worth bearing in mind that risk.

Ultimately though it’s hard to argue with the current momentum. Half year basic EPS was 20.9p compared to the FY consensus of 33p, so that looks very beatable and you’d have to think there are further upgrades in the pipeline. The current share price level is justified in my opinion.
Sureserve (LON:SUR)
Share price: 79.7p (+13.97%)
Shares in issue: 161,213,788
Market cap: £128.5m
A new company to me. In these instances. I often open up the StockReport and head over to the Discuss tab to see everything the community has said about it.

On this occasion, it’s led to a bit of a detour into this excellent Market correction watchlist post from gringo made on the 5th of October, a great idea and I imagine the comments are well worth reading later on in the day.
Sureserve originally floated in 2015 as Lakehouse but it quickly ran into trouble and has more recently been in turnaround mode. The share price chart certainly suggests progress has been made. That recovery did occur in a generally rising market, however.

This is a compliance and energy services group that performs critical functions in homes, public and commercial buildings, with a focus on clients in the UK public sector and regulated markets. Services are delivered through two divisions: Compliance and Energy Services.
This type of contracting company is accident prone, and margins tend to be low, so it’s a risky part of the market. It is possible to grow though, and there are some good institutional investors on the shareholder register including Slater and Chelverton, so they’ve found something to like.
Coincidentally, the group is one of only three qualifying for the Jim Slater ZULU Principle Screen.
Strong performance with full year expectations in line with management's expectations
Sureserve reports ‘strong growth in revenue, earnings and cash flow’ in the year to 30 September 2021 and expects results to be in line with expectations. Net cash stands at £16m and the order book is up more than 30% year-on-year (2020: £356m)
The group’s services are non-discretionary, driven by mandatory inspections and accreditation requirements, so that gives some security of business, while other services here ‘form a critical part of the Government's growing Green Agenda.’ This sounds similar to Kinovo (LON:KINO) .
Sureserve will publish its full year results on Tuesday 25 January 2022.
Chairman Nick Winks comments:
The Board is focussed on our medium- term strategic options and is progressing with its search for a Chief Executive Officer as a matter of priority. Our growth strategy remains, as previously announced, focused on expansion through a mix of organic growth and prudent, earnings enhancing acquisitions.
Conclusion
It’s a short update, but a positive one given the increasing order book. Sureserve also recently won a £140m contract extension for The Guinness Partnership. The long term nature of such agreements is attractive, and the fact that this is an extension with a known and reputable client could perhaps help Sureserve’s reputation in winning new business.
Its forecast PEG is just 0.6x so more growth is forecast to come. But it’s also a competitive sector where margins tend to be low and cash flows can be lumpy. These aren’t perfect businesses, but they can grow and money can be made. It just pays to be cognisant of the risks, too.
The balance sheet looks ok but not strong. There’s about £44m of goodwill and intangibles in its £113m of assets, with £43m of receivables and £9.7m of cash. Set against that is £44.3m of payables, which looks high. I think the current ratio could be stronger, to protect against shocks. Even with a market cap of £128.5m, it looks like it’s difficult to trade in size with a 286bps spread and an EMS of 3k suggesting less than £3k can be reliably bought or sold at quoted prices. So if there is a rush for the exit at some point, it could get nasty.
The valuation does appear compelling though, with the forecast PER of 9.1x. It looks like Sureserve is doing a good job in what can be a tricky sector, and the share price could do very well if it continues to win new business and extend contracts in a recovering market, but it’s not without risk.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

96 comments
I agreed with Paul's comments that the trading update from Revolution Bars (LON:RBG) was very impressive and can be easily verified by the busy clubs/pubs.
Young people are desperate for social interaction and are willing to pay the high drinks prices for a good night out. Christmas bookings are already filling up/full so it looks like it could be a bumper season for good bars and restaurants.
As of today there is another buying opportunity for Revolution Bars (LON:RBG) as it has returned to its pre-trading update price (7th Oct) of circa 22p. Presumably investors are taking profits or hedging loses because it makes no sense unless you believe further social restrictions are coming back (which I find hard to believe).
I spoke to a hospital doctor who said the hospital numbers are manageable and most people in hospital are there with Covid not necessarily because of it (this is despite such a high number of cases out in the community). Their biggest problem is the old story of bed blocking because there are no spaces in care homes for the elderly patients.
I believe Revolution Bars (LON:RBG) are set to have a very good trading period and are cheap at 23p.
POLX
It might be worth glancing at this company and the presentation materials it has for an upcoming NAm microcap conference. This briefly lists others in the medical imaging market - I am sure they are all unique either in their technology or targets...
Perimeter Medical Imaging (PINK.V)
Congrats to all NUFC shareholders agreed cash offer of £300 mill
hmmmmm sorry bit of a typo there lets try again
take your £300 million MA and . ... (plenty of fff's)
rmillaree ... the others will not understand. So be it.
I am cursed to have been an NUFC supporter pretty much all my born days. I'm not a pure-bred Geordie but Newcastle is my home town and I stood and swayed (at great risk to my life it sometimes felt) with my mates on the Popular Side every other Saturday more-or-less from the age of 11 to 19 years old. (that was a very long time ago btw ... think Wynne Davies, Alan Suddick).
I had written off the Saudi take-over and resigned myself to permanent misery under Mike Ashley's (totally focused lack of ambition) regime. Finally ... we can break free and enjoy football again ... trying to win instead of trying to break-even.
Apologies for writing so off-topic. But there are passions that shape our lives far more importantly than our investment portfolios .. and Newcastle United (whether you or I like it or not) is a very important one of mine.
Regarding Robert Walters (LON:RWA) (I hold) - When his eponymous company was only weeks old and consisted just of himself and another ex-Page colleague, Robert Walters came close to persuading me, as a recent graduate, to join his nascent business. Although I eventually took a different offer I was very impressed with RW and it has been no surprise to see his success. Over the years my businesses have collaborated with his and, when I transitioned from entrepreneur to investor, I looked for the opportunity to take a stake in his company. I rate it highly among the listed recruiters. Just as Sthree (LON:STEM) (I hold) is best located by sector, RWA is exposed to the most interesting geographical distribution.
Recruitment is cyclical - but is also undergoing secular growth and I see plenty of potential for RWA beyond current expectations. Staff shortages don’t just accelerate wages (=larger commissions) but they increase the use of professional recruiters relative to in-house HR (=bigger TAM) and create opportunities to extend margins (=higher fee %ges). Analyst expectations for RWA’s FY23 revenue, EBIT and EPS only envisage matching the 2018 peak. Those strike me as inherently conservative and I am happy to hold what has become a relatively large position without trimming for now.
Revolution Bars (LON:RBG) (I hold)
Quick addition to the cash generation highlight today.
Daily cash generation has jumped from £70.6k to £89.7k since re-opening commenced on 10th May 2021.
If this stays the same for the remainder of the year (adverse cold weather offset by peak xmas season) = £20.1m reopening cash generation.
If correct that's not bad for 64% of the financial year and a current market cap of £52m.
Fingers and toes crossed.
Very difficult to Salsa with your fingers and toes crossed …..
One piece of news that i have not seen regurgitated anywhere this morning is regarding the number of expected redundancies at the end of the furlough scheme , apparently early data is suggesting that the number is nowhere near what was expected ( by whom i dont know !) .
This must be bullish, mind you it was from the BBC so probably not true !!
Richard
haha - yes. I'm not that surprised tbh. From what I've seen of the furlough scheme is that in a number of industries it has been used flexibly. Let's say a company has got 10 staff on furlough. Often it is not the same 10 staff across an 18 month period but rather a flexible pool of staff. Now the likelihood is therefore that once the furlough ends those 10 roles don't disappear from the company they get absorbed. Perhaps 2 or 3 get lost. It always struck me that media were paying too much attention to headline numbers (or should I say headline grabbers) without much economics theory going into the extrapolation of likely job losses post furlough end.
Also there are plenty of job vacancies, so even if made redundant, many should be able to get a new job. However some of those jobs may not appeal.
The hospitality sector is struggling to recruit staff.
Hi Ray,
The hospitality sector is struggling to recruit staff.
I didn't see anything in Revolution Bars (LON:RBG) update today about price rises, or staffing problems, which is interesting. There again, I think working at a Revs would be more fun, and appealing to young people, than pulling pints in some grotty old boozer full of miserable, leering old men! ;-)
Also, Boohoo (LON:BOO) (I hold) and many others talk about supply chain problems & costs, whereas Sosandar (LON:SOS) (I hold) today tells us that it's not had any material problems.
Which does make me wonder (as a reader cleverly pointed out the other day), if supply chain & staffing problems are falling on companies which are maybe not so well organised, but shrugged off by better managed companies?
Or it could be showing up companies with no slack in their forecasts, and CFOs who haven't squirrelled away enough into their bottom drawer account (to absorb cost shocks) maybe?
Another key question is whether companies have long-term contracts for shipping at fixed prices (ideal, obviously), or whether they're unplanned, and just having to pay spot rates (nightmare at the moment)?
It's very difficult for investors to anticipate these things, as we don't have enough information. Hence why trading updates at the moment are revealing both good and bad surprises.
Regards, Paul.
Paul,
I had read somewhere very recently that the cost of a 40' Container China to Felixstowe had halved in the last couple of weeks , although still 5 x 2019 cost.
I can't substantiate that, although the Baltic Dry Index ( which measures the cost of Raw Material Shipping) does not bear that out.
Baltic Exchange Dry Index | 2021 Data | 2022 Forecast | 1985-2020 Historical | Price (tradingeconomics.com)
Does anyone have a link for 20 and 40' container costs?
Richard
A 30 second search using a well known search engine (no, not that one) returned this
Container Shipping Cost Calculator | Freightos
States that Shanghai to Felixstowe is $18k
Thanks, I did find that but it doesn't give historical rates :-))
This gives historical rates for different sizes of container ships (but I am not sure what is the route or distance covered). From these charts no sign of a downturn yet.
https://ycharts.com/indicators...
I owned an import business up until recently , historic container rates would be circa 2k for a 20 foot , 3k for a 40 foot . Prices from China
I’m hearing freight rates are still in the 20k region for a 40 foot and haven’t dropped yet .
th
And here's another one - I found it informative for current rates and a graph.
https://www.drewry.co.uk/suppl...
I am seeing the $10-11k figure on the indexes (Edit: just read the site properly and it's an overall composite rate - other rates are available) - but much higher figures quoted separately. I can't explain the difference but I guess if you are in a screaming hurry for a single container - you will be paying through the nose right now?
The peak shipping season for bookings is almost over, rates will likely continue to fall into the new year as demand eases and supply increases. Many companies have been planning their shipping for months and will likely have booked early - or have a deal based upon their level of shipping - but no doubt there will be some that have left it too late - or that specialise in fast or just in time shipping. As usual there will be winners and losers - at the moment the assumption seems to be everyone is a loser - it's going to be interesting to see who is who?
cheers
Mark
In response to Mark, peak season for shipping out of China is the 2 weeks before Chinese New Year as factories typically shut down for a month so output is typically doubled upto the run up (that’s assuming the state doesn’t force factories to work normal hours due to electricity shortages)
Graham,
' peak season for shipping out of China is the 2 weeks before Chinese New Year as factories'
Quite right. Thank you. I learn all the time. I had not taken into consideration that there are two peaks - I was referring to peak Import season - which is typically August to October- and with a hard import deadline for Christmas retail - and the peak export season which does not have a similar import deadline?
My unstated assumption is that the current import peak is caused by limited freight capacity on most routes and that limited export volume from China will actually help rates fall as falling import demand, increasing freight capacity and falling exports combine. But I am not an expert - so probably wrong,
cheers
Mark
I hold Braemar Shipping Services (LON:BMS) which seems to be in the shallows despite a tailwind and $SBLK which is about to up-sail (maybe). So where should I put my money UK/US.
Be wary of the 'news' is something Mr Croft expounds and becoming of the same mind. The SP tells the story at some point - think about all the brain power in these investment houses - and they invest in Polarean Imaging (LON:POLX) (or maybe not).
Thanks, Paul, I was wondering about Revolution Bars (LON:RBG), maybe it depends on the location. In my area of east Suffolk I know companies are trying to recruit staff and not even getting any applicants. There maybe shortages from some workers going back to Europe. I know some local pubs are closing by 9 and they do seem to few staff. Some have gone into other industries because of Covid.
I agree the picture is not clear but there are clear shortages in some areas such as HGV drivers and butchers which is/will cause some real problems.
The other issue is energy costs, I know some companies that use gas, have closed down production, because they are losing money.
Paul: "supply chain disruption is a temporary factor"
The global issues are, but what's been underlined recently is that we have some UK specific issues that may be longer lasting. In the words of the Adam Smith Institute:
“Shortages and rising prices simply cannot be blustered away with rhetoric about migrants. It’s reprehensible and wrong to claim that migrants make us poorer. There is no evidence that immigration lowers living standards for native workers. This dogwhistle shows that this Government doesn’t care about pursuing evidence-based policies. We can both control migration and allow migrants to fill skill gaps. "
Looking at the numbers on the HGV driver issue suggests that approx 50% of the issue is global and 50% down to UK specifics. In some areas, such as food production, the UK component will be bigger. All these issues can be resolved in time, but the UK issues are likely to be less temporary than the global ones.
A new economic structure in this country is certainly possible, but it cannot appear overnight as the government seems to believe. They say that businesses have had since 2016 to plan for this but that seems harsh. Moving from a low productivity model to high will take many years to achieve, if it ever really happens. In hospitality for example, we will see some digital innovations coming through but I find it hard to see a fundamental change to the ways of working.
In the meantime this will be inflationary and a headwind for UK GDP and sterling, creating an advantage for shares with international earnings. Maybe these are the right policies for the country from a social perspective, but economically the road ahead is likely to be more bumpy than it would otherwise be and this will dent sentiment and valuations.
I read somewhere that Polarean Imaging (LON:POLX) imaging technique depends on having >80% purity Xenon gas which can only be produced on gas centrifuges - expensive, technical and hard to access (also used for enriching nuclear fuels). Polarean Imaging (LON:POLX) is not able to produce this itself. It seems the FDA is not satisfied with the provenance of the Xenon gas ( procurement, quality control, certification who knows?) . The tech may work but the business model may be dead in the water.
Do you have a source? Not doubting just this does change things. One of the bull cases for me was the continuing sales of polarised Xe by Polarean to adopters of their tech. If they can't make the Xe and therefore sell it to customers I might eject (after only a couple of hours- my fastest trade ever!)
Poster on ADVFN quoted the POLX admission document:
from the Admission doc: https://www.polarean-ir.com/docs/librariesprovider37/archive/admission-doc.pdf.
Old but interesting.
Full para:
7.4 Manufacturing development risk
Management has devised a manufacturing process for the company’s
product. The company has arranged for GMP manufacturing from an outside
supplier. The manufactured products from the external supplier will be
assembled at Polarean’s facility, which was previously ISO 9001/13485
certified when it was run by General Electric. Polarean is currently
working on recertifying the facility.
There are no critical parts suppliers as most of the products can be
sourced from alternative providers. 129Xenon is a naturally occurring
and abundant isotope of xenon, making up 26 per cent. of the naturally
occurring gas. Polarean requires 80 per cent. or more isotopic purity
for their technology to work. The only way to purify xenon is to carry
out gas centrifugation, which is a complex process only performed at a
few facilities around the world, most of which are in the former Soviet
Union. It is costly (around $150-200/litre) and there are few
specialised suppliers who work with the gas centrifuge companies.
Polarean has an agreement with one of these suppliers, Nukem. If
Polarean were required to seek analternative supplier, the Company has
identified alternative providers.
There are risks associated with development work, not least how well the
final manufacturing process will be scaled up to industrial level cGMP.
Polarean have taken appropriate steps to mitigate such risk by
appointing a highly experienced drug/device manufacturing specialist to oversee the process.
Nukem is a German supplier, if the company is forced to turn to a Russian source of purified Xenon isotope it's not hard to guess what the FDA verdict will be.
Polarean Imaging (LON:POLX)
removed--irrelevant
Polarean Imaging Polarean Imaging (LON:POLX) Just thought I would tell my POLX story. I bought a small quantity in May at 90.9p and made a note to buy more on a 15% profit. I bought more on Monday 4.10 at 111.6p and then they collapsed by 60%. This morning I bought more at 51p. I am convinced they will come good once the issues raised by the FDA are ironed out. The FDA are notoriously difficult to satisfy but I am sure they will succeed in the end. You have to be an optimist in this game!!!
GUS 1065
Just a shame the Americans won’t let them sell it.
Polarean Imaging (LON:POLX) is listed here but their address is 2500 Meridian Pkwy Ste 175, DURHAM, 27713-4214, United States. I only mention this in relation to the drop in the share price of Angle (LON:AGL) yesterday in reaction to the POLX FDA refusal. Angle (LON:AGL) have been working closely with the FDA and their submission is in a different league IMHO. There have been views expressed elsewhere that the FDA are ‘against non-US companies and favour their own’ but yesterday’s news should debunk this. I’d love to see Angle (LON:AGL) jump 60% on approval !
I've been thinking how the new car and more importantly in this instance new Van shortages (41.8% decline in September against pre-pandemic avg) would read across for Redde Northgate (LON:REDD) Will the shortages mean more people have to hire them?
Redde Northgate (LON:REDD) possibly but do they have more capacity? I imagine these vans are booked up most of the time? Or with people returning to work will online deliveries diminish? Will supply shortages have a knock on effect? Will energy/food prices rises dent demand?
I hold, thinking of topping up but not sure.
One thing I'd say on Redde Northgate (LON:REDD) is that the 2nd hand prices they can achieve have certainly gone up so their NAV should be considerably higher given the stock levels.
Redde Northgate (LON:REDD) yes that is true but how long will that last? Prices may start to fall next year.
maybe - but they divest a good %age number each year so NAV will benefit
Redde Northgate (LON:REDD) is one of my largest holdings. When i was in business i did use these people and although lapsed i do still have an account with them. I imagine they will be very busy, the shortage of truck drivers will be a positive in that firms wanting to move one or two pallets can do so in a 3.5 tonne van which has no driver restrictions rather than wait for a space on an artic lorry. The worry would be continuity of supply of new vans, if this was a problem i imagine they would just keep their existing fleet longer. On their website they are offering to buy second hand vans ( i don't know if this is new or they have always done this) . They do offer vehicles from a range of manufacturers so not all their eggs are in one basket.
I just tried to hire a vehicle on my old account and they do have availability.
Hope this helps.
Richard
Holders of Redde Northgate (LON:REDD) should not overlook the companies purchase of ChargedEV back in July, with the impending fuel 'shortage' this could not have been better timed.
Richard
Paul,
Thanks for your interesting comments and views on Revolution Bars (LON:RBG) ( i do not hold) . I do not think i have ever been to one of their venues but I was fortunate enough to have lunch in London's West End two weeks ago, the whole area was heaving, I have never seen it so busy, even without tourists, we tried to find a bar or pub or anywhere to have a drink after a late lunch and could not find a seat anywhere. Also I have just returned from a week's walking in the Lake District, with which I am very familiar, I stayed in three different places and again every one said they have never been so busy at this time of year. So there may be some shortages of goods but certainly no shortage of demand for hospitality services. I was not aware that the reduction in VAT for hospitality did not apply to alcohol. Which apart from PC reasons i would see as counter productive. I also find it initially odd that J D Wetherspoon (LON:JDW) have not been trading well but on second thoughts their demographic has probably got used to paying 50p a can and drinking at home so this may take some time to revert.
Richard
Revolution Bars (LON:RBG) I am really surprised this hasn't taken off! I think investors may be missing the fact that in the last 3 months the business has generated cashflow of £8.7m *moving from a net debt position of £5m to cash of £3.7m) with the company stating they are profitable and 17% ahead of 2019 due to improved offering.
That's huge cashflow generation in a single quarter for a market cap of £50m with their busiest period coming up. Not sure the market has grasped that yet.
DO they capture the VAT holiday in this LFL? when does this roll off?
VAT holiday is marginal. Doesn't apply to alcohol and obviously cocktails are the big part of Revolution Bars (LON:RBG) offering
Key point is this - if the business is able to do £8.7m of cash in a single quarter not even in its busiest season, then for a full year it is capable of what? maybe £8.7m * 4 = £35m (ie assume Xmas strength and Q1 weakness offset each other)? Let's be conservative and whip another £10m off that and say £25m of positive free cashflow. Business is worth £50m at present so trading on 2* free cashflow?
Granted some of that free cash will be utilised in refurbishments, new stores etc but demonstrates the value on offer.
Thanks for clarifying re VAT. I agree the shares are cheap but not your cashflow analysis ... maybe have a look at history... when they were bid for they only did £10m cash flow.... I guess we are shooting for £10-12m EBITDA but I may be wrong. This is consistent with Pauls up side to 40p.... clearly a lot going on in the cash-flow that will even out.... at the moment if they return to pre COVID revenue on a slimmer estate then margins may be in line ( costs rising) ... which I think is consistent with above but may be wrong.
you can't look backwards as the business is a different beast today - revenues are already 17% ahead of 2019 and operational gearing is high. Costs are also a lot lower than then too.
Cashflow will be used for refurbs/expansion etc so I don't expect £25m of free cashflow to persist but £12-15m appears achievable but will only ever command maybe a 7 or 8* multiple so I agree with the 40-50p all things being equal.
The point of the £25m cashflow (ex investment) is that it shows that if you ran off this business (ie stopped refurbs/expansion) and milked it that you could probably quite easily generate £125-150m net cash before you shut down. In my view that's broadly where I'd value a business using a discounted cash model. Nonetheless it also happens to coincide with around the 50p mark.
David,
Revolution Bars (LON:RBG) It's like for like revenues that are up - but only "86% of 2019 revenues achieved"
"same site sales growth of 17% when compared to the same period 2 years ago"
which is 2019.
The 86% of 2019 revenues relates to the period 17th May to 21st July so this +17% since then is a marked acceleration.
Motorpoint (LON:MOTR) update:
* MOTORPOINT GROUP PLC - HALF YEAR TRADING UPDATE AND
NOTICE OF
RESULTS
* MOTORPOINT GROUP PLC - TRADING CONTINUES TO BE IN LINE
WITH
BOARD'S EXPECTATIONS FOR FULL YEAR
* MOTORPOINT GROUP PLC - GROUP REVENUES GREW BY C.57%
AGAINST H1
FY21
Sosandar (LON:SOS) super results. H1revenues of £12m was more than entire revenue of last year, so the anticipated growth at scale is starting to come through. Hard to see that £24m for full year won't be beaten and though we are expecting a £1m ebitda loss feels like they should be around breakeven if the Christmas period goes well.
Cash down a little but this is due to increasing stock for the upcoming period also suggesting it's hitting a cashflow b/e point with plenty of buffer cash, which is always helpful.
No supply chain issues or cost inflation to speak of. (Probably an important wider point to note that not every business is impacted in the same way despite investors tendency to make assumptions, always worth trying to look through to what's going on in a business.)
EDIT : from the Analyst call this morning it reinforces my view of just how good the results really were. They acknowledged that they are basically now trading cashflow flat (so the small drop in cash is related to inventory increases as their stock is selling through so quickly).
Also confirmed that they are being prudent/cautious leaving forecasts unchanged so I do now personally expect some quite heavy upgrades at their next update. In fact I'd be surprised if they weren't moving into profitability by then or very close (though that's just my take on how trading appears to be going)
Scale is being achieved giving increased purchasing power alleviating any cost pressures or supply issues.
3rd party marketplace is now at 20% of revenues but still only a fraction of their range in those marketplaces so lots of growth coming there.
TV ads are shot very cheaply (as part of their Stills photography) and each campaign leads to a big spike in new customer engagement, so they are now on TV most months but only on specific targeted programmes.
There is a lot to like in this update and reinforces my long term view.
Yes and surely Q3 and Q4 is going to be quite strong because people will be buying more occasion wear and work wear vs this time last year when we had another lockdown (providing current fall in covid hospitalisations continues). I bought an opening position in Sosandar (LON:SOS) at the bell this morning at 26.9p as I think this is now looking very positive with much reduced risk of further dilution and near-term profitability fast approaching.
Yes - and I'm going to stick my neck out and say Sosandar (LON:SOS) will be breakeven (or very close - sub £300k ebitda loss) by y/e despite current forecasts being unchanged. You lot can chop it off when I'm wrong later in the year :D (but hopefully not).
"Also confirmed that they are being prudent/cautious leaving forecasts unchanged".
I also took that away from the Q&A. If it were not for current uncertainties (supply chain in particular) then coming into the busiest part of the year I think they would be guiding higher.
I’ve also taken a bit of a caning on a small position on Polarean Imaging (LON:POLX) although having purchased in March much of yesterday’s loss was wiping out a previous paper gain from a 60p entry price. I bought in on the back of research including very positive commentary from Paul Jourdan at Amati (12.5% holders in Polarean Imaging (LON:POLX) ) who I rate as a specialist manager. Essentially, he thinks they have invented a better mousetrap. (Just a shame the Americans won’t let them sell it.) I’ll be looking out for any comment from him/ reaction of Amati to yesterday’s news. If they’re still supportive and buying more at a possible fire sale price, I would consider this a very bullish signal.
Gus.
Hi Gus,
Polarean Imaging (LON:POLX) I have been following this for a very long time but never bought. I was slightly put off by their own brokers' report which I thought showed a fairly modest sales trajectory following final approval. I always wondered though if they were being a bit pessimistic with the forecast. When the news came I decided to have a sub-1% of my funds punt @38.9p. My belief is the chances of this getting back to 90-100p after re-submission are much higher than a drop to 20p or so. I think the risk reward is very good from where we are. I think the extraneous positives are that Paul Jourdan and Bracco Imaging are backers, and that gives me some confidence.
Morning all. Its certainly been a bit frantic recently. Its seem to be a global wobble. USA to suspend debt ceiling possibly. Payroll news tomorrow. Evergrande real estate possibly to be taken private. New Metropolis to be built in Hong Kong announced 5 minutes ago. Nikkei recovered well after Olympics , then sold off again. Energy crisis. Shell announce taking a big hit after gas hike. Putin comes to our rescue. Afghanistan debacle. Supply chain. Quite a concoction!
I bought more (LON:IGP) yesterday. It looks to me as though they already have around £4 million of new contracts in the bag this year as well as multiple upgrades from existing customers. So surprised at the sell off there. News possibly tomorrow on trading. Talking of speculative Medical Equipment companies Paul, (LON:ONT) came off the blocks well on their IPO last week, but I bought into a couple of investment trust that have large positions in that company prior to the launch. So still seems to be plenty of money around. Good Luck everyone!
Regarding active trading of my portfolio, I’ve been uncharacteristically busy. I tend to buy and then hold through all the market’s gyrations. But I sold 10% of my growthiest/highest valued names (mostly US) when bond yields hit their early September lows and then bought the same shares back last week. I recycled the profits and a maturing bond-like product mostly into UK-based GARP industrials in the last five days.
Did I time the sale right? Yes, amazingly, to the very day on which assets peaked. But that’s where the self-congratulation ends. I should have had more courage in my conviction and sold 25% or more. Then I could have better managed my re-purchase discipline to profit from falls that exceeded my target - I automatically re-purchased at a 10% discount, when I might have targeted to re-purchase tranches at 10%, 15%, 20%. Also, having focused on the riskier growth names, I failed to react ahead of the wider correction caused by supply chains etc. Portfolio is still down 10% in a month - only slightly worse than the market - the benefit of a highly diversified portfolio (300+ names) despite high sector concentration (Tech, Healthcare, Industrials).
Have I timed my purchases right? Almost certainly no. More skilled re-purchases would have yielded more profit and the new portfolio additions are all showing a small loss averaging around 5% - which is a day’s trading at this week’s volatility levels. But, as a long term investor, I’m happy with the entry levels and its now down to time, compounding and the skills of management to work their stuff. Or not.
So POLX did turn out to be BOLX then (did make me laugh when you posted that originally Paul) However I don't think it is totally dead... It passed stage 3 trials (which means the science is all good and safe) and is already in use in certain places. I don't know what's gone on here but I suspect people should still keep an eye on this over the next year... I'm not invested but was right on the cuff and if it comes up again and gets approval I will jump straight in.
I have been keen on Polarean Imaging (LON:POLX) but never invested as I came too late in terms of a price (80p+)
I went in this morning with a very small punting stake. From what I've read of the technology it is just flat-out better than regular MRI, particularly for lung imaging, and could even bring about screening for lung cancer. Regardless of the next decision from FDA, I suspect the price will rise as decision day approaches.
I agree POLX will do well in the long term. Today is a great buying opportunity.
Thanks Paul for your thoughts on the market drift. My instinct (often wrong!) is that sentiment will remain negative for a while yet - there are just too many tanks on the lawn, the biggest being the significant threat of inflation, which won't go away until the reopening trade is complete & we'll know for sure whether it's a blip - that's going to be at least 6 months out. Sure, there will be some bargains, but not yet IMO. I've cleared out all but my highest conviction holdings and top sliced the remainder. Yes, I may miss out on the bottom, but I'm keen to safeguard the results of an easy bull market for the last few years - the best way to make a decent return is not to have too many clangers IMO!
Would be really interested to learn what others think.
I agree with you
It's easy to forget that the first objective for investors must be"Preservation of Capital"; in other words be cautious. There seems to me to be exceptional instability on many fronts, political, financial and practical. I feel I can forego the current opportunities to preserve my 2019/20/21 gains. My current strategy seems like yours and I sleep well at night knowing even if there is a very significant crash (have we seen the end of this very long 12/20 year bull market) the results will feel unfortunate but not worrying.
Headlam (LON:HEAD) CEO steps down immediately after 5 years, and 30+with the company. Strange, though may be health related (not mentioned). Similar changes at £IPO and not so precipitate generated a significant SP fall yesterday. The 2 companies are as different as chalk from cheese, I grant you, but.........
Seemingly very good updates from Sosandar (LON:SOS) (couldn’t really imagine a better update if we’d tried although some profits might be nice) and Revolution Bars (LON:RBG) this morning which will probably attract most discussion here. Slightly more under the radar, steady progress from non-conforming lender Morses Club (LON:MCL) reported in their Interim Results. Appears to be seeing growth across the board and picking up business from its sector peers that have been having well publicised problems of late.
https://www.investegate.co.uk/...
Some of the figures seem a bit obscured by the impact of IFRS9, not least the “impairment as % of revenue” up from 23.5% to 31.5% which at face value appears to be a concern. Need to brush up on my accounting to see if this is an issue (I guess the share price will tell us).
Gus.
My wife has been buying clothes from Sosandar (LON:SOS) in recent months and has been very happy with them so far (not achieved lightly :)).
Re Morses Club (LON:MCL) (I hold) - I listed to the company webcast this morning and came away very reassured for the medium term and impressed again by the MD - I trust him to be cautious but prescient - a good combo.
Home Credit is made up of ever higher quality (144K, down and Agents (now only 1163, skilled/motivated ones, 1% vacancy) on a digital-led , reduced cost base (90 offices shut) with market leader Provident gone (along with 150 smaller companies!). Demand likely to boom in next 6 months from i) reopening of holidays and usual Christmas surge. Impairments at 16% incredibly low albeit not sustainable there. Only onerous regulation a risk but no sign of this - and until it occurs, lots of regulation is a big moat!
Digital is what (I believe) drove today's price down. Breakeven pushed by a few months to Q1 next fiscal. However, long term looks good. Volume has trebled, loans moved to mostly longer term (>66% lons 6m+) with huge market to go after. Waiting on legal restructuring in Q4 to access more funds to expand into 18-48M (ie where Non-standard Finance (LON:NSF) was doing so well before it blew up). IFRS requires impairment on a growing book to be recognised early, flattering mid term profits (and making no difference to cashflow). I really like the relatively slow steady progress and system put together at low cost/low risk from opportunistic acquisitions. Platform there to now really accelerate.
U money relaunch delayed(again, allegedly) to focus capital/mgt but this offers a distinctive 3rd leg in time via revolving credit and a digital banking system designed for the needs of the low/variable income non-standard market - not the fancy competitive youngster market most FinnTech targets. No one else is offering this as well.
Conservatively run and financed. Paid a divi of 3p last year (4.4% at today's 67p ) and on track for more this year and much more in 2-3 years.
Dull, a bit non-PC but great prospects (albeit always with sudden regulatory risk). Has managed the digital transition/Covid superbly well and left itself in a great position. Will be a lot higher in another 2 years IMHO having paid out good divis.
The results from Eenergy (LON:EAAS) look good to me. I hold these. I think this is a business at the right time in the right place. They have a really good management team with experience in creating value and in M&A. The acquisitions look good and the organic growth is strong.
Rising energy prices will only magnify the benefit they offer clients.
This is an opportunity to get in early in my opinion. This could be an excellent growth opportunity with recurring revenue. There is a presentation about the business and it's most recent acquisitio9n here: https://eenergyplc.com/2021/09...
I would welcome thoughts from Paul.
Highlights:
Financial
· Revenue up 200% to £13.6 million (2020: £4.5 million)
· Organic revenue growth of 75% in the core eLight business, generating revenues of £7.9 million
· Generated maiden Group profit
· Adjusted EBITDA1 of £0.8 million (FY20: loss of £1.5 million)
· Profit before tax and exceptional items1 of £0.1 million (2020: loss of £1.9 million)
· Cash at bank £3.3 million (30 June 2020: £1.5 million)
· Net cash (including £0.7 million of IFRS 16 lease liabilities) of £0.8 million (30 June 2020: net debt of £0.5 million, including £0.6 million of lease liabilities)
Operational
· Number of eLight projects increased by 69% (FY21: 211, FY20: 125) and average revenue per project increased by 52%
· Renewable Solutions Lighting ('RSL'), acquired in July 2020, fully integrated and strengthened Group's leading Lighting--as--a--Service ('LaaS') position in Multi-Academy Trusts and State schools
· Beond, the Top 20 energy management business, acquired in December 2020, integrated into eEnergy with advanced discussions with a number of Beond's clients for Group's eLight LaaS solution
· Launched MY ZeERO, the smart metering and intelligent data analytics platform
· Group delivered first combined LaaS and smart metering & analytics project in June 2021
Since the year end
· In September 2021, the Group completed its largest acquisition, UtilityTeam, and raised £12 million (gross) through a placing to both existing and new institutional investors to fund the initial cash consideration
· On a pro forma basis, following the acquisition of UtilityTeam, we derive approximately 55% of Group revenue from our Energy Efficiency division and 45% from our Energy Management division2
Sosandar (LON:SOS) is one that has been hammered quite a bit recently from the wider market rout, no doubt on fears of supply chain. But just reported this morning no impacts so far, an astounding H1 performance, and reiterating FY expectations.
(I hold)
I’m not so sure that the H1 results from Sosandar (LON:SOS) are astounding.
It all sounds very upbeat - revenues up dramatically, operating margin up, no supply chain issues.
But then we get the kicker. Even on much higher revenues and higher margins they are still loss making, and to cap that they say that the full year outlook is inline with previous expectations.
Will they ever make a profit? Other thing here is that they are totally dependent on Clipper for their logistics (repacking the returned stuff etc) as far as I am aware, but they are very much small fry for them. That makes me nervous.
No position
Well... +184% revenue growth for a ecommerce company, where the comparison period (Apr-Sep20) was in Covid already... I would call it astounding.
But it has already been assumed by brokers, given they're only just on course to meet FY expectations.
However, I can't see how broker expectations won't be raised? £24.4m rev FY is the broker forecast consensus but having already done £12.2m revenues in HY and H2 hearing up to be seasonally higher, and also more growth (expanding lines, more stock, marketplaces continued growth) surely the broker forecasts will rise?
Maybe, but they have a three month window to, effectively, double H1 as Jan-Mar revenues are very low. So the £24m figure is sensible until we get the update in December that lets us know how autumn trading went. Hopefully they’ll move into profitability then too, not holding my breath on that though.
No, Sosandar (LON:SOS) FY starts 1st Apr 2021, so the YoY comparison is against a time period full affected by COVID. Arguably, they've had tough comparisons in Q1, as competitors with retail stores have re-opened.
So when they say Half Year Trading Update, it is from 1st Apr 2021 to 30th Sep 2021. Compared to 1st April 2020 to 30th Sep 2020.
Yes, sure, thanks for explaining their financial year to me, but that doesn't change anything I said.
if you watched the analyst webcast you would realise that they have their busiest period by far coming up. So H1 (weakest) = £12m and H2 (strongest) is still forecast at £12m!
The likelihood of zero sequential growth in H2 (given customers are up 40% with increasing repeat buying) and in the busiest season of the year feels very low. They are well stocked so shouldn't be any mishaps there.
They are already cashflow profitable (excluding increases in inventory). I would say the odds of some serious upgrades towards year end are high and that would get them at b/e.
The guidance is deliberately uber cautious. I have no problem with that but it is thinly disguised.
Yes, my point is though, and I must've communicated this badly, is that this busy period is only half as long as the summer period, so they have to do the same sales in half the time. Jan - Mar sees a sales slump until we get back into the spring / summer collections.
Hence why I think keeping the 12m number there is sensible and then give an update in December once they've seen how things shook out. Of course, there's nothing to stop them raising expectations earlier if trading goes well this month / next, but it's imperative they manage expectations having lost credibility in the past with over optimistic forecasts.
I hold and have done for years :)
Yes, though it typically is much better. Also, September was a record month and very strong, October started in the same manner.
Nonetheless I don't disagree with leaving the forecasts unchanged, but I would be disappointed if that's all they come up with at year end as it would suggest sequential growth just stops in its tracks. The business is quite heavily 2nd half weighted. I therefore think that the odds favour an earnings beat.
I'm long - I don't trade the stock as I don't believe I can time it well enough so have them tucked away but the last 2 updates have really encouraged me for the long term.
Sosandar (LON:SOS)
GrahamF
It all sounds very upbeat - revenues up dramatically, operating margin up, no supply chain issues.
Will they ever make a profit? Other thing here is that they are totally dependent on Clipper for their logistics (repacking the returned stuff etc) as far as I am aware, but they are very much small fry for them. That makes me nervous.
I have been sometimes unimpressed with Sosandar's ability to forecast the future (and some of their updates have been over waffly avoiding core points) - so i have witheld investing on the basis i wanted some firm evidence that the profitability will likleu show up soon.
I though todays update was one of their best - simple main stats with no silly numbers thrown in to pimp up the story.
With regard to your concerns about profitability GrahamF are you losing confidence at the exact moment they have actually started making profits ?? as far as i can see they are profitable right now !!!!! (woop woop). Ok this may be jumping the gun somewhat but stocky numbers show expected profit of £0.75 mill ye 31/3/2022 - they made loss h1 and confirmed they are on track for forecasts as of today as far as i can see they expect profits for full year and probably decent profits for H2 (based on H1 probable loss) - whats not to like about that.So my opinion has swung in the exact opposite direction from previously worrying "when" to now thinking as long as they execute H2 its job done.
Another bonus is that being on track will probably as of now at least leave ye 31/3/2023 forecasts as they were are they are expecting £3.65 mill profit the closer we getinto that year and further into that year without downgrades then i can see the real end in sight here with regard to the "forced" cashburn to get to scale. Note even if they don't hit £3.65 mill halfd that figure would still be close toia couple of mill.
Obvioulsy they havent exactly been over reliable previously ref forecasts so i see where any doubting thomases are coming from - before i looked at todays update i would have said jump from £24 mill revenue this year to £38 mill next year seemed a huge ask - the fact they hit £12.2 mill H1 here suggests they are bang on track in that they dont require a huge H2 number to hit their "high expectations" as they have previously had - still a big ask next year but trend seems good. Hopefully for holders they don't need to pimp the numbers now as they don't need to raise any more funds - simply execute as per plan.
Ok no certainties here they may have had temporary post covid bounce that will tail of and they dont know that yet - they may hit supply chain issues and the prior predicting ability has been poor but for once i have been impressed how the numbers stack up "compared to what they have promising the market".
The new finance guy seems to be the catalyst, might be coincidence and they were going to get there anyway, but I'm not a big believer in coincidences :)
I'd say the new finance guy is pretty good. I've heard him talk a few times and he is well on top of the numbers. That's what you need though - allow the creatives to go and do their magic and let the finance guy manage the numbers
I share your concerns. Experience tells me that investing in 'jam tomorrow' businesses can be very bad for your wealth.
I want to see real profits and a healthy balance sheet before getting involved to prevent sleepless nights.
Following on from your pre-amble, any thoughts on Sureserve (LON:SUR) . A Naked Trader current favourite, A long time member of the Jim Slater screen, and TU today in line with management expectations.
Order book up 30% from previous year
Won a 10 year contract in August for £140 M over 10 years
But down around > 20 per cent over the last 2 or 3 weeks. Is this one of those potential bargains you mention?
I'm invested in Sureserve. According to SimplyWallStreet, it's undervalued, debt free and insiders are buying shares, about £150K in the last six months. My shares were up about 8% a month or so ago. I still believe that it is a sound company but I'm not expert. I'm tempted to buy more.
Revolution Bars (LON:RBG) a nice update to the market re current trading being ahead and strong.
Am I missing something in respect of Revolution Bars? My read of them is they make no profit, pay no dividends have debt, dilute shares, and not much cash.
My question is a genuine one as I am only into my first year of investing for myself.
Am I missing something in respect of Revolution Bars? My read of them is they make no profit, pay no dividends have debt, dilute shares, and not much cash.
Your read of their historic results, or your estimates for future results?
Hi unbelievablejeff,
With Revolution Bars (LON:RBG) (I hold), we need to look forwards. As you point out, the historic numbers are unimpressive, even before covid.
However, shares are valued on the future, not the past. As explained in the article above, RBG has now been comprehensively fixed, and is generating huge cashflows (free cashflow of £8.7m in Q1), and has paid off all its bank debt (placings & cash generation recently).
The prospects are therefore looking enticing, when combined with a low market cap. It's up to each of us to decide how much weight we put on all these factors. In my view, there's often a very good opportunity with turnarounds like this, where other investors are slow to recognise the turnaround, and remain jaundiced by previous losses & disappointments with this share (understandably emotionally, but making money on shares usually involves ignoring your emotions)
Hope that helps!
Regards, Paul.
Hi Paul,
Thanks for your reply and further info, I will keep this in my mind. One big constant learning curve for me!
Cheers
Jeff.
I think your view is correct.
Holders want to add more lipstick on this dog as explained in the below link.
https://www.stockopedia.com/co...
Since then Revolution Bars (LON:RBG) generation new cash by.
The company indicates a Q1 trading update for 2022 but cant report the year-end of 2021. the dilution over the past 2 years suggests a valuation above 20p is unlikely even if the business is going great guns.
Stockopedia information is clearly out of date. In my opinion, this business is best put to sleep in the long run.
Always DYOR, and don't rely on comment boards' vested interests.
BSV
Bluesky,
£RBG "Stockopedia information is clearly out of date". The only information you refer to is the share count. The up-to-date shares in issue figure on Stocko is 230 million, which to me clearly reflects the numbers you highlight. The "Average Shares" figure is just that; an average.
Glad we agree the information is out of date. As the share count has gone from 50M to 230 but not reflected in the numbers. This will affect another valuation number such as EPS, P/E etc.
I guess I was just saying you really need to look at the numbers by DYOR and deciding if it's worth owning the company.
BSV
Hi Jeff,
Part of the research needs to also include the question "do I trust management to manage the business with the best interests of the shareholders at heart?"
Or are they taking advantage of the shareholders and lining their own pockets. What are their salaries, how easy/hard are any LTIP's to achieve, is there a reasonable II holding (or reason why there isn't). Do they keep retail investors up to date - are they given the same updates and access as the II's. When there is a fund-raising can retail investors partake at the same T&C's?
There are many brilliant companies that are in it for the right reasons and tick all of the above boxes. If you have any doubts I wouldn't invest and would go elsewhere.
I am not saying Revolution Bars (LON:RBG) do not do all of the above, I am just saying DYOR and don't be swayed by others - some don't care about the above (traders for example), others think that the short-term doesn't matter if they are only going to hold it for a few months etc.
Best of luck. K