Small Cap Value Report (Thu 8 Aug 2024) - JIM, TIFS, CLBS, MER. Brief: SVS, HSW, FIH, NAH

Good morning from Paul & Graham!
Today's report is now finished. Apologies for it taking longer than usual.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
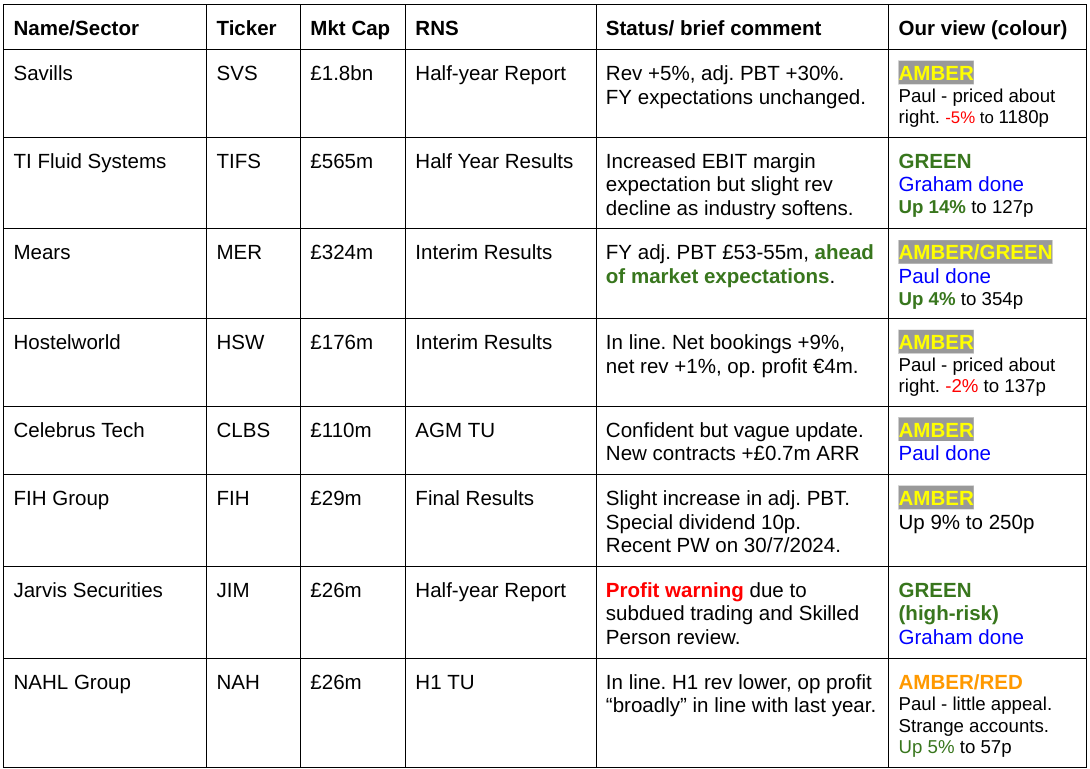
Summaries
Jarvis Securities (LON:JIM) - down 20% to 47p (£21m) - Half-Year Report - Graham - GREEN (high-risk)
It’s a profit warning to add insult to already-injured JIM investors. Costs associated with the Skilled Person Review have increased, restrictions on the company’s ability to trade remain in force, and trading volumes remain subdued. The company’s broker has now withdrawn estimates and its valuation of the stock. Clearly this is a high-risk situation with a wide range of possible outcomes, but I don’t wish to change my GREEN stance on the stock as we are on the cusp of finding out the conclusions of the regulatory review.
TI Fluid Systems (LON:TIFS) - up 10% to 123.2p (£619m / €719m) - Half-Year Results - Graham - GREEN
Some pleasant news here with respect to profit margins and ROCE as the company battles through a period of soft demand from its customers. I am leaving my long-term GREEN stance unchanged as I think the share price may be artificially low due to concerns about private equity selling down their old stake in this business, rather than more substantial problems.
Celebrus Technologies (LON:CLBS) - unch 280p (£110m) - AGM Trading Update & Contract Win - Paul - AMBER
This AGM update doesn't tell us anything about trading, other than that management say they're confident. Contract wins announced are only £0.7m ARR. So it's looking a bit flat to me. I like the company, and its cash-rich balance sheet, but think it needs something more exciting to propel shares even higher. So I'm shifting down a notch from amber/green to AMBER, to reflect the strong share price rises already, and a rather vague update today.
Mears (LON:MER) - up 4% to 354p (£340m) - Interim Results - Paul - AMBER/GREEN
Impressive H1 results, and broker upgrades to forecasts. There are some one-off contracts for housing asylum seekers, which are expected to normalise in 2025, so I think it makes sense to use the 2025 forecasts for valuation purposes. This gets me towards the upper end of what looks reasonable. However, the really impressive cashflow, funding big share buybacks (a remarkable 12% reduction in share count!) and decent divis on top, swings me towards keeping a favourable opinion at AMBER/GREEN.
Paul’s Section:
Mears (LON:MER)
Up 4% to 354p (£340m) - Interim Results - Paul - AMBER/GREEN
Mears Group PLC, the leading provider of services to the Affordable Housing sector in the UK, announces its interim financial results for the six months ended 30 June 2024 ("H1 2024").
Excellent first half performance and positive outlook
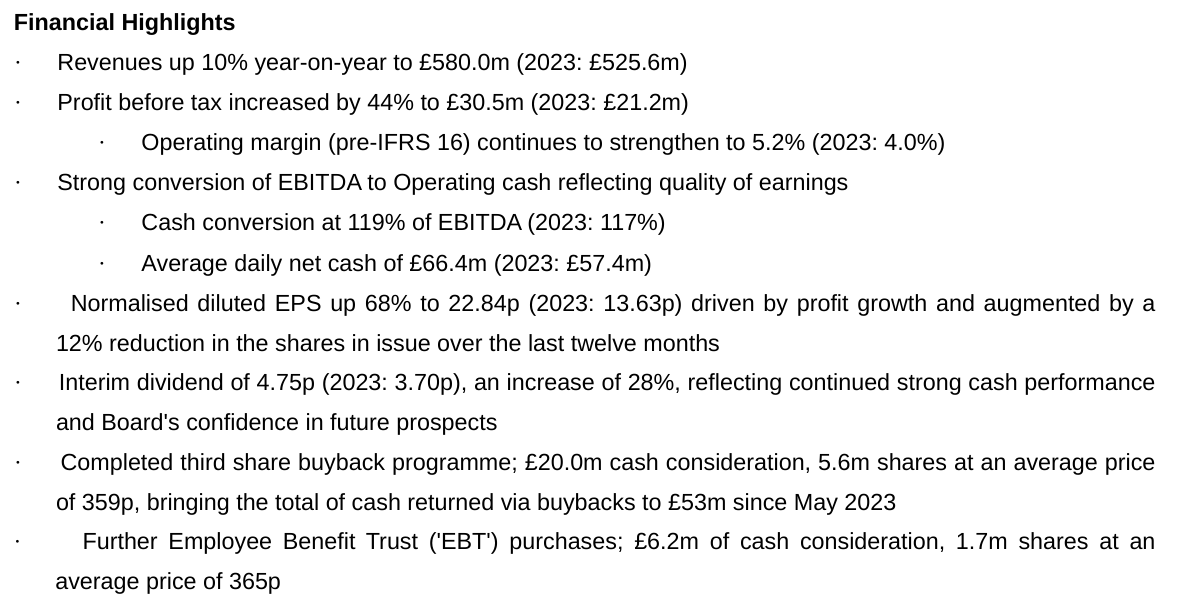
Impressive highlights here - note in particular the gold standard of reporting average daily net cash - all companies should do this, as it shows the reality of a company’s cash position, not a year end one day snapshot (that can be so easily window-dressed).
Also note the huge 12% reduction in share count through large buybacks -
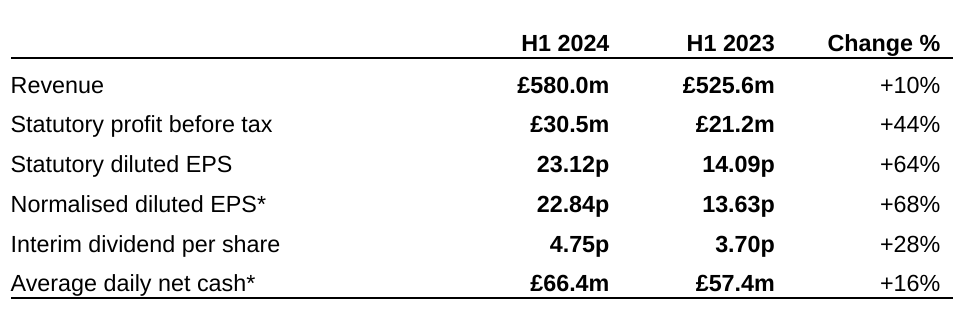
The obvious questions are: what is driving the improved profitability, and is it sustainable?
Whatever they’re doing it’s clearly working well -
Outlook for FY 12/2024 is ahead of expectations, although it sounds as if there might be some one-off boost to profit this year from asylum related housing contracts, which are expected to normalise in future. It has bought some properties for this contract, and says it will be doing sale and leasebacks to recycle the capital. So we need to be a bit cautious about valuing this share on a PER basis in what might possibly be a peak earnings year.

Broker updates - many thanks to Panmure Liberum, whose note today raises FY 12/2024 estimated adj PBT by +10% from £50m to £55m.
In EPS for FY 12/2024, this is old: 37.0p, new: 42.1p.
PL’s note also gives a full explanation of the expected impact of normalising the asylum contract, baked into its 2025 forecasts, which get a boost today mainly due to the share buybacks reducing the share count substantially.
FY 12/2025 forecasts are amended today, old: 28.9p, new: 31.4p.
Historically, Mears shares tend to trade in a PER range from about 7x to 13x, which based on 2025 forecast gives me a share price range of 220p to 408p.
Today’s price is 354p, which is towards the upper middle end of my valuation range.
Some investors might strip out the cash, to give a higher rating, although I’d be a bit careful about that, as the balance sheet is not especially strong. NAV of £187m includes £128m of intangible assets, so NTAV of only £59m.
Paul’s opinion - it’s a nice business, performing well.
Cashflow has been very good, funding dramatic share buybacks, and paying decent divis too, not something you see very often on this scale.
Hence even though I think the shares look priced about right, the cashflow & big shareholder returns swing it positively for me to remain at AMBER/GREEN. There could also be potential upside, if the asylum housing contracts get rolled over in some way - that problem doesn’t seem to be anywhere near resolved, based on general media reports, so maybe Mears might continue to benefit from it?
Shareholders have done remarkably well, so maybe it needs to consolidate for a bit before making another attack on 400p? Who knows!
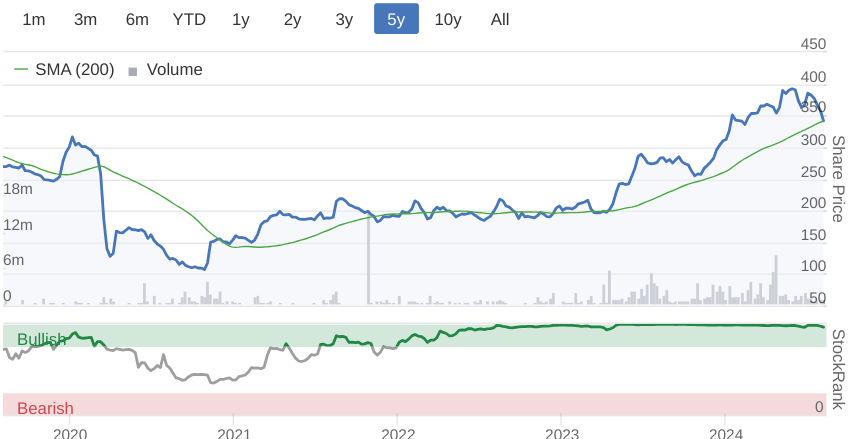
Note the StockRank is jammed on maximum!
Celebrus Technologies (LON:CLBS)
Unch 280p (£110m) - AGM Trading Update & Contract Win - Paul - AMBER
Celebrus Technologies plc (AIM: CLBS, "the Group", "Celebrus"), the data solutions provider…
Surely they could have come up with a better description than the above!
There’s a more detailed company description further down, but this is not very well written either. It seems to be mainly about data analysis to prevent fraud, and for marketing, and customer loyalty purposes -
“As a disruptive data technology platform, Celebrus is focused on improving the relationships between brands and consumers via better data. Celebrus redefines what digital identity verification means to power both next-level marketing and fraud prevention use cases. Deployed across 30+ countries throughout the financial services, healthcare, retail, travel, and telecommunications sectors, Celebrus automatically captures, contextualizes, and activates consumer behavioral data in live-time across all digital channels. Through the addition of behavioral biometrics and AI, Celebrus empowers brands to detect and prevent fraud before it occurs. To ensure that brands can begin to improve those relationships quickly, Celebrus Cloud activates the Celebrus platform efficiently for brands in a single-tenant, private cloud implementation.
The Group has offices in the UK, USA, and India with key talent in all markets to drive the growth of the business…”
Today’s trading update doesn’t really say much about trading, and keeps it all vague, without specifically stating if it’s trading in line with expectations or not.
“Recent contract progress adding to confidence in FY25 and beyond”
This year is FY 3/2025.
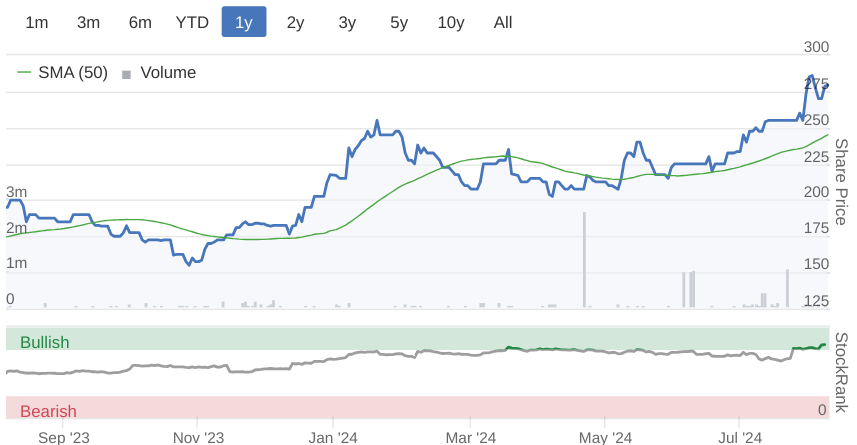
An attractive looking one-year chart - which looks on its way to doubling from the Oct 2023 lows -
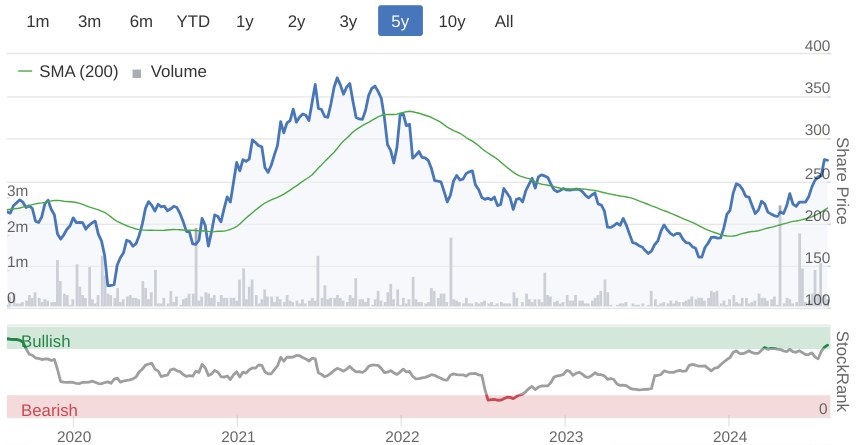
Zooming out to five years, we’re about mid-way in the range, now in a nice up-trend. There has been about 15p in total divis paid over the last 5 years on top -
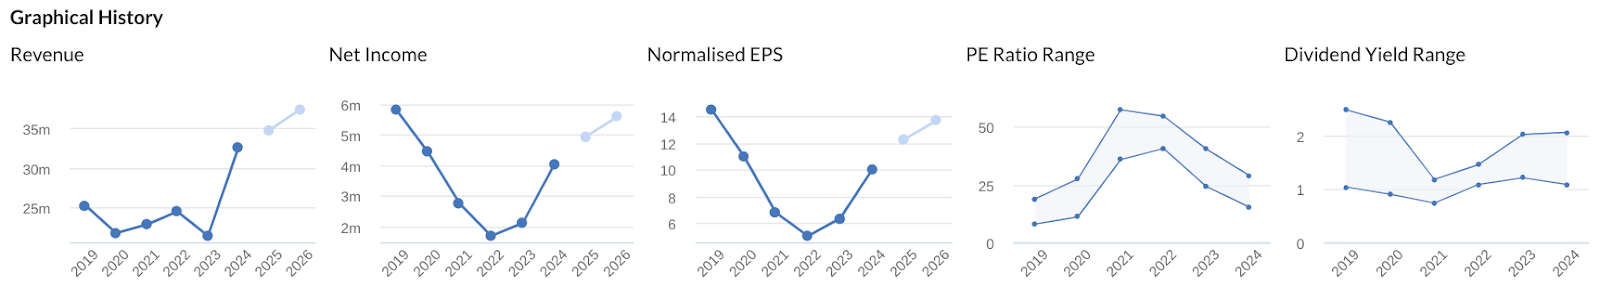
Graphical history below shows CLBS has been profitable throughout, but disappointed for several years with falling profits, but this is now recovering -
Going into the detail, see what I mean about this being vague -
“growing pipeline across a range of end markets and is highly confident in the Group's strategy to deliver growth and create significant shareholder value in the coming years…”
Contract wins only total £0.7m ARR, so not material to a group with c.£35m pa revenues.
Selling strategy is now focusing on particular industry verticals.
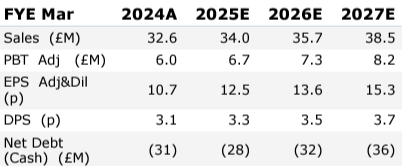
Broker update - given that CLBS itself tells us very little today, more information can be found in a note published today by Canaccord (many thanks to them). I hope they don’t mind me including this small excerpt below giving the key forecast numbers. It says in the commentary that these forecasts might be conservative -
[courtesy of Canaccord]
Valuation - at 280p/share I make this a PER of 22.4x - not exactly a bargain, especially given that the next two years are only forecast to have modest earnings growth.
Remember though that CLBS sits on a healthy cash pile, so there’s an argument for subtracting this (worth about a quarter of the market cap) for valuation purposes. Although if doing this, you would also need to reduce your earnings figure, to subtract the interest income on the cash pile.
Paul’s opinion - I’m listening to the webinar on InvestorMeetCompany at the same time of typing this. It doesn’t scintillate.
I admire CLBS, and have a generally positive view of the company - profitable, cash generative, and with a healthy balance sheet.
What concerns me, is that the business never quite seems to achieve its potential. Growth seems fairly pedestrian, and there must be any number of specialist data analytics companies out there competing.
That said, AI and data analysis are hot investment areas at present, so it looks as if CLBS is re-rating as the sector becomes more fashionable.
Is CLBS going to be a big, multibagging winner? I can’t currently see any evidence of that. So owning this share is more about hoping that contract wins might accelerate in future, beyond the small wins announced today, which barely move the dial.
Previously I’ve been amber/green, but given the share price has gone up a lot, and that there’s nothing particularly exciting in today’s update, I feel easing down to AMBER makes sense. If we get some better future newsflow, then I would shift back up to a more positive stance.
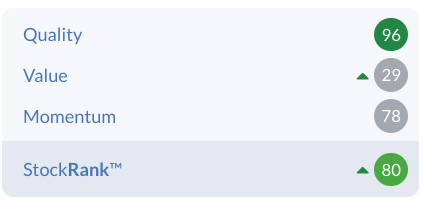
Quality & Momentum scores are high, but Value is low -
Jarvis Securities (LON:JIM)
Down 20% to 47p (£21m) - Interim Results - Graham - GREEN (high-risk)
This one has unfortunately been a horror show for investors over the past few years:
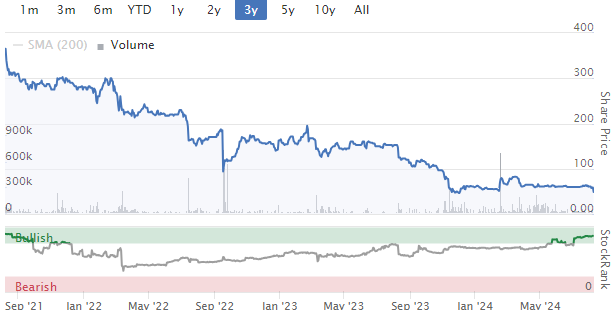
Today’s results are yet more bad news, with a fresh profit warning.
The financial headlines are as follows:
Revenue down 12% to £6.5m
PBT down 29% to £2.7m
Cash under administration (key source of interest income) down 15.5% year-on-year.
A regulatory intervention has been responsible for most of the doom and gloom here, with a Skilled Person Review ordered by the FCA.
The “Skilled Person” is now in Phase 2, which means they are reviewing the remediation work carried out by Jarvis in response to previous findings. This is expected to be completed “by Q4 2024”, and will include a final recommendation from the Skilled Person. So it is starting to sound as if Jarvis could be approaching the end of this saga.
Profit warning:
Due to subdued trading volumes; the increasing costs of the Skilled Person review; the costs of the associated remediation work and the ongoing impact of the VREQ [GN note: voluntary restrictions] on the Company's Model B clients, the directors anticipate that the trading for the full year ending 31 December 2024 will be significantly below market expectations.
Financial statements: everything is moving in the wrong direction on the income statement, as you’d expect, but the PBT margin is still a remarkable 42%. Many companies can only dream of earning a profit margin like this but for JIM, it’s not a great result.
The balance sheet remains small and efficient with tangible equity of about £5m.
Cash flow is always pretty good and again most PBT has been converted into free cash flow.
The company’s cash balance increased by £400k despite paying £1.5m of dividends to shareholders (admittedly they had paid out twice as much in dividends the previous year)..
Dividends: in a separate RNS, Jarvis declares a 1p quarterly dividend. The corresponding dividend last year was 3p.
Estimates: the company’s broker Jarvis has withdrawn its estimates and valuation for JIM, “pending the outcome of the remediation work expected in Q4”. So there is no official guidance. Previous estimates from WH Ireland for 2024 suggested there would be adj. PBT of £6.3m.
Graham’s view
Perhaps it is foolhardy to express an opinion when the company’s own broker no longer wishes to do so.
However, I continue to stubbornly think that JIM can pull through this, even if the profit result for the current year turns out to be very poor.
H1 PBT (with no adjustments) is already £2.7m. In H2, I would suggest that trading volumes are unlikely to be much more subdued than they already were. The interest rate cut from the BOE is only 0.25% thus far. And the Skilled Person Review and its associated costs have been with the company for a long time already. Admittedly these costs are increasing, but they won’t last forever.
Putting it all together, I would still humbly and cautiously suggest that we should still end up with a PBT result for the full year that is significant in the context of a £21m market cap.
The wildcard risk is the final recommendation of the Skilled Person, and then the final decisions by the FCA. Will JIM’s “Model B” business be permanently restricted? Will the company suffer fines? Will the company’s reputation among retail investors be damaged?
These are impossible questions to answer and so there is probably no point in making estimates for 2025.
I am willing to make one prediction: I think the FCA is likely to have a strong opinion on JIM’s interest income on client cash (see here). How ironic that it may start clamping down on this just as interest rates start to fall.
Checking my previous comments on JIM, I must acknowledge that this is one I’ve got wrong - I’ve been positive on it, and the share price has disappointed.
Feb 2024 - I was positive at 68p.
Nov 2023 - I was positive at 56p.
August 2023 - I was positive at 125p
March 2023 - I was positive at 139.5p
Sep 2022 - I was positive at 94p.
What have I got wrong? Several things, but mainly:
Not realising how long the Skilled Person Review would take
Not realising how expensive the Skilled Person Review would be for JIM.
However, the FCA still hasn’t revealed its cards. The final outcome remains unknown.
For this reason, I don’t think I can change my positive stance. JIM might yet walk away from this controversy with a few bruises but with its business more or less intact and with a £21m market cap that doesn’t make any sense. We simply don’t know.
Perhaps we need Paul to pipe in with a more sensible view, but I’m staying GREEN on this one - while admitting that it’s high risk with a wide range of possible outcomes.
The experience of following this saga has taught me one thing - when I hear the words “Skilled Person Review”, I am now far more cautious about the company that is getting one. If I could go back in time, I would have turned AMBER when this news was announced for JIM way back in Sep 2022. But nearly two years later, with the process presumably reaching a conclusion, and with a much cheaper valuation, it doesn’t make sense to me to change my stance now.
TI Fluid Systems (LON:TIFS)
Up 10% to 123.2p (£619m / €719m) - Half-Year Results - Graham - GREEN
TI Fluid Systems plc (TIFS), a global industry leader in highly engineered automotive fluid storage, carrying and delivery systems and thermal management products and systems, announces its results for the six months ended 30 June 2024 (the 'period').
Let’s review progress here. It’s been a while - see Nov 2023.when the company was trying to recover back to the financial performance levels of previous years.
Highlights from these H1 results:
Revenue down 1.4% to €1,719m
Adj. EBIT +4.8% to €135.5m
Actual EBIT up by less than 1% to €95.8m.
A small acquisition in Sep 2023 has boosted revenues and so I believe the organic growth rate is a little worse than what is shown above. It would have been helpful if the company had adjusted out the additional revenues from this acquired business.
The acquired business (“Cascade”) was expected to generate €35m of revenues in 2023, so that’s about 1% of full-year revenues at TIFS.
ROCE: TIFS helpfully calculates its own adj. ROCE, and comes up with 25.4%. That’s a great score and better than H1 last year (21.7%).
Stockopedia calculates ROCE for last year as only 10%, however, so there’s a big gap between adjusted and unadjusted numbers.
Debt and leverage: net debt is significant at €682m (almost as high as the market cap), with little change year-on-year.
As I’ve noted before, TIFS management seem to be comfortable with this level of debt. They calculate a leverage multiple at 1.7x (excluding leases). Including leases, the leverage multiple is 2.1x. In my book these are high levels but are probably manageable.
The company certainly thinks they are manageable with €69m of capex spend in H1 described as “modest”, a €23m dividend payment during H1, and €22.5m spent on share buybacks (out of a planned €40m). The company is clearly happy to splash the cash around for shareholders, and they describe their balance sheet as “strong”.
Total gross debt is over €1 billion, mostly in the form of a fixed rate bond maturing in 2029. Other bonds are floating rate and mature in 2026. The bonds apparently do not have any significant covenants.
Free cash flow was negative in H1 but this includes seasonal outflows of working capital that should reverse in H2.
Outlook sounds positive, here are some snippets:
Our first half performance demonstrates TI's fundamental strengths. Our propulsion agnostic portfolio and geographic and customer diversification underpin our resilience. Our ability to deliver further margin expansion despite volume and labour inflation headwinds reaffirms our confidence in returning to a double-digit Adjusted EBIT margin in the mid-term…
As a result, we are increasing our full year Adjusted EBIT margin expectation to above 7.6% notwithstanding a slight decline in revenue at constant currency due to the recent softening of the 2024 industry outlook…
Graham’s view
This is another tricky situation to assess.
Just look at the valuation multiple the market has assigned to this company:
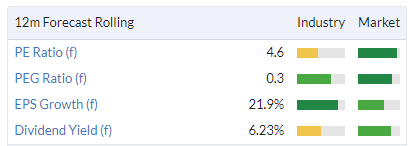
A clue as to why the valuation is so low might be found in the shareholder register:
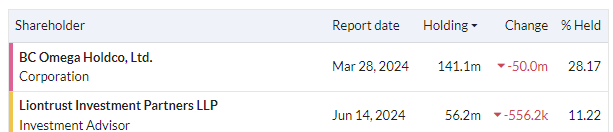
That’s nearly 40% of the company held by funds that don’t seem particularly able or willing to continue holding it.
As noted by Paul in March, BC Omega is a Bain Capital fund. Bain brought TIFS to IPO in 2017, and I imagine they are frustrated that they still hold so much of it. The share price has not cooperated with their exit plans:
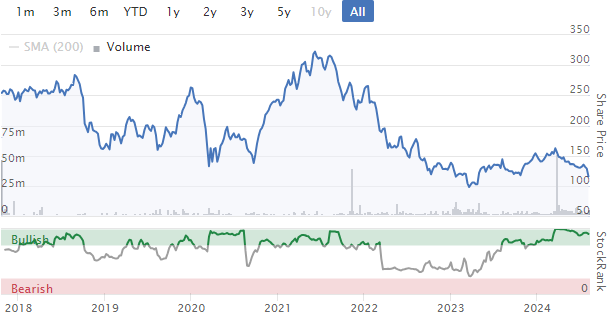
The second name on the register, Liontrust Asset Management (LON:LIO) is a name we discuss regularly here. Suffering a low series of outflows from their funds, they should also be viewed as shaky hands, although they are less dramatic sellers than Bain.
As the problem of weak holders has nothing much to do with the business, I don’t think it should affect my stance here.
The company’s approach to debt and leverage does leave me a little concerned, even if management aren’t worried. But for investors who are willing to accept the financial risk associated with the debt load, there is a lot of business for sale here at a £620m market, or a £1.2 billion enterprise value. I’ll leave my GREEN stance unchanged, betting that the share price reflects the overhang of sellers rather than more fundamental problems with the company.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
According to Morgan Stanley, the top 4 mistakes investors make in volatile markets are:
1) Panic-selling at the bottom.
2) Going totally to cash and staying there.
3) 'Buying stocks poorly on the dip' based on fiction, rather than fact.
4) Trying to make up for losses by doubling down on poor quality companies.
I'd add a 5th:
5) Paying any attention whatsoever to what the Morgan Stanley strategist or CIO thinks about market direction and timing.
Mike Wilson was predicting the S&P would fall to 3900 by the end of 2023:
https://fortune.com/2023/10/17/morgan-stanley-mike-wilson-sp-500-rally/
In fact make that the strategist from any of the banks (I can remember Goldman's Abby Joseph Cohen going from goddess to laughing stock). As the old saying goes, "strategists are like neckties - every trading floor has one, but nobody knows what they are for".
Other than to prompt clients to trade, of course. They don't care if you buy or sell, as long as it is through their traders. Best execution permitting , of course.
Paul- and it ended with this "Our study of nearly 120,000 investors with a Morgan Stanley financial plan during the COVID crash found that more than three-quarters of those who were considered “on track” to achieve their goals at the market’s peak remained on track even at the market’s bottom—before equities began their subsequent recovery.1 In addition, despite a portfolio decline of 16% for the typical investor in this group, their likelihood of achieving their financial goals was down just 2% at the market’s trough."
Resonable advice and easy for a broker to give. But I'd take everything they say with a grain of salt. Morgan Stanley, like all other IBs make money from commission rather than performance... if they had all the answers they'd have a bunch of funds that consistently outperformed the index, but alas they don't...
If anyone is wondering why the market has turned up since lunchtime, my take is that the latest US jobless claim figures came in slightly below expectations, easing fears of a recession triggered by a breaching of the Sahm Rule on Friday.
TT electronics (LON:TTG)
interims don't look inspiring, on initial reading
Like any business this could goto the wall. But the falling debt and positive book to bill ratios suggest the turnaround is taking hold. And the problems are not idiosyncratic - inventories remain higher than desired across the board - see XP Power (LON:XPP), RS (LON:RS1) etc. I just think patience is required. I’ve only held for 7 months and I’m flat to slightly down, hardly a disaster. If I'm correct, there are decent gains to be had when demand returns and the company will be in a leaner shape to enjoy better operating leverage.
Good to see that the Carclo (LON:CAR) yo-yo remains fully operational. -12%, +12%, repeat daily.
One issue I have with Jarvis Securities (LON:JIM) is that I can't see what would cause a new customer to sign up with them. iWeb were already slightly cheaper, and now a well known name AJB is also more competitive. Is there anything that they offer that the other larger better known platforms don't? And as far as I can see their accounts (looking at the x-o website, maybe they offer other brands?) can only be used to buy UK securities - who doesn't buy any foreign shares in this day and age?
Jarvis Securities (LON:JIM)
As well as xo they have a ShareDeal Active a/c where:
https://www.sharedealactive.co...
I have a Jarvis account and had become concerned re the security of the situation. I then noticed the following additional insurance policy taken out by Jarvis to protect against additional loss above FCA provision https://www.jarvisim.co.uk/#!/... I’m not aware of other brokers providing this.
As a secondary account I find it cheap and easy to use and has allowed trading in some stocks not covered on my main account
Jarvis Securities (LON:JIM) Before getting too reassured by their Professional Indemnity policy, I'd want to know things like its limit and exactly what types of claim it would respond to - and how.
At a guess, might be £10m in the aggregate per year? So that means £10m (or whatever the limit is) spread between all the claimants.
It's extremely unlikely to be on a per client basis - otherwise the insurer can't control their exposure .
And I'd imagine all the providers would be carrying similar PI insurance.
I have had no problem with US stocks in my ISA at Jarvis Securities (LON:JIM), but they did want a minimum investment of £10k for an Australian stock. I have not tried Canada or Japan as I generally keep the ISA for likely UK IHT effective stocks. I have found their staff to be helpful and quickly responsive.
There are not that many companies which offer share trading accounts. If you have a sizeable amount, you don't want all your eggs in one basket just in case the worst happens. Ideally you don't want more than £85K with one financial institution.
I have many accounts, including one with Jarvis. The big positive is there is no annual fee (I am one of the ex-Yorkshire bank customers). It's not the best share trading account I hold, but it's not the worst either. I also hold Jarvis Securities (LON:JIM).
Good to see some readers speaking up for Jarvis. Imho a great little company and when it comes to service small can be beautiful,. Remember "too big to fail" banks? All shares are held by a nominee company with clear indication of beneficial ownership as described on the following web page along with ring-fenced client cash and many other questions. https://www.jarvisim.co.uk/#!/...
Just to be clear, I have nothing against Jarvis Securities (LON:JIM) , and indeed I hold a small starter position, having thought (incorrectly lol!) that 60p would be the bottom.
I still can't see any clear differentiated proposition that either x-o or ShareDeal Active offer that would make a new customer sign up vs. the competition though. If any non-investing friends ask me for a first broker suggestion, my default answer is AJB. If I google "10 best execution brokers UK" AJB and HL have the top two sponsored links, and I can't see either of JIMs brands in the next batch of links.
Over the past few years the FCA has, I believe, established a very poor record for nailing several very doubtful characters, for taking a long time rather than acting decisively ( see the SEC in the US) and being bureaucratic rather than effective.
The website, FCA.org.uk has a large amount of information but, if you believe that it houses a small crack team of experts I would warn that the site is not for those of a nervous disposition, starting with the finding that it has 4000 employees (up by 1200 since 2022) and a budget of £755million for 24/25, up by 10%. They have massive staff turnover with more than 1000 leaving in the last two years. The hiring effort alone is a massive undertaking, averaging more than 3 people per working day for two years. They are unable or unwilling to say how many of their staff have financial training.
Their number one objective is to “reduce the growth” in financial crime ( notably, not just ”reduce”), but it will probably all be OK because their CEO is paid £455,000 (!)
Re Jarvis Securities (LON:JIM) . I Know little of the company but something of FCA regulation. The timing of the skilled person review is unfortunate as it co-incides with introduction of Consumer Duty. The CD rules are perhaps less prescriptive but include a lot of "cross cutting rules". At this point it's an educated guess that having skilled person review in progress would steer the company towards less profitable decisions.
On the other hand IF they have come out of the review and met consDuty rules they are perhaps looking better as far as FCA are concerned.
A well timed purchase in Capita (LON:CPI) Paul. CFO designate bought 1.2m on 7th!!
City of London Investment Group (City of London Investment (LON:CLIG) has seemingly bucked the trend and managed to increase FUM over the year;
"Funds under Management (FuM) were $10.2 billion at 30 June 2024, an increase of 8.7% as compared to $9.4 billion at 30 June 2023."
There seems to be continuing outflows, but these have been offset by positive investment returns.
This is another unloved asset manager paying huge dividends.
I invested thinking that the EM sector may improve as an investment destination, which might produce some share price growth in addition to the chunky dividend.
Jim
Is an increase in FUM of 8.7% in a year that good a performance? FUM is often presented as implying that more investors are using the investment companies services, but it also includes the investment returns of the funds. I suspect many on here would hope their portfolios would perform better than 8.7% a year.
I suspect many on here would hope their portfolios would perform better than 8.7% a year.
i am happy with 8.7% per year (average)
City of London Investment (LON:CLIG) is clearly an equity fund but if you think of it as an income generator, rather than a growth share, the capital return over 5 and 10 yers is far better than UK Gilts or UK Corporate Bonds and has thrown out more than twice the level of income. As part of a portfolio for an income seeking investor, it’s not actually done too bad. Recent changes to move away from just EM only improve its prospects in my view. Each to his own I guess.
Eenergy (LON:EAAS) - *** Save the Date - Investor Presentation on Monday 12th August - sign up at the link below ***
eEnergy (AIM: EAAS), the net zero energy services provider, is pleased to conduct an online Investor Presentation on Monday 12th August at 4.00pm (BST).
Harvey Sinclair (Chief Executive Officer) and Crispin Goldsmith (Chief Financial Officer) will provide an update to investors following the company's recent H1 Trading Update, and answer questions submitted by viewers.
The webinar is open to all existing and potential shareholders, and registration is free. You can sign up to register here: https://www.equitydevelopment.co.uk/news-and-events/eenergy-investor-presentation-12august2024
RE: Jarvis Securities (LON:JIM)
What have I got wrong? Several things, but mainly:
Not realising how long the Skilled Person Review would take
Not realising how expensive the Skilled Person Review would be for JIM.
I wouldn’t be so hard on yourself, Graham. At the end of the day you trusted the view of the company who pronounced the review would take 3-6 months in the initial statement in September 2022. And here we are nearly two years later. It’s the credibility of the management rather than your own judgment you should be questioning.
Jarvis Securities (LON:JIM)
At the end of the day you trusted the view of the company who pronounced the review would take 3-6 months in the initial statement in September 2022
ahhhh but if these companies have somewhat gamed the system or taken risks in the first place (to make a buck for shareholders) - should we trust those very same people with their inititial assessment/excuses that are presented to shareholders when the problem first turns up. I supect they will always be minded to take the best possible intital stance with regard to how this might be settled - imho saying anything else will be pointing further blame at themselves (unless the broom is new and is holding a kitchen sink)
Would be interested to see a set of initital resonses and how things have panned out compared to what was said - i would be very surprised if many are settled very quickly or as per initial hopes.
In summary i fully expect the initital assessments from most companies will be more talking from the lower regions rear end than the higher regions fron end practicably speaking. That is probably being harsh on the unlucky ones who really havent done much wrong and will get back on track asap - obviously there will be some stuff that aint nearly as bad as other stuff.
Thank you simoan! A very kind interpretation of events. However it's always a bit of a sad excuse when an analyst blames management after a stock call goes bad. Part of the job of an analyst is to assess whether management are credible and whether management's statements can be trusted and believed. So I will take responsibility for getting this wrong. Cheers. G
Part of the job of an analyst is to assess whether management are credible and whether management's statements can be trusted and believed. So I will take responsibility for getting this wrong
Respect to you, Graham, for owning the mistake - one that I’m sure most of us would also have made.
The original company announcement in sept 2022 is here followed a month later by a NED share purchases of a total 20000 shares at 135p.
Expectations were set very wrongly by the consultants and we all fell for it. Not surprising that share ownership and hence prices are in decline and companies are being bought out left right and centre by foreign organisations.
Interesting new refillable product launch vs Zotefoams (LON:ZTF) ReZorce's cartons.
"Ocado is testing offering everyday products such as pasta, rice and washing liquid in refillable packaging in a first by an online supermarket.
The scheme will trial a reusable vessel that can take food or laundry products with no extra costs for customers.
The first phase of the trial, starting this month, will include 2kg packs of basmati rice and 1kg of penne pasta, both under the Ocado Reuse brand. Phase 2 coming later this year, will add 3 litre containers of Ocado Reuse non-bio liquid detergent and Skies fabric conditioner.
Under the scheme the reusable containers are pre-filled with product and delivered to customers with the rest of their shop. Empty containers are returned to drivers when they deliver the next order and then washed and refilled by suppliers.
reminds me of milk bottles in the 60's and 70'S
Let's not forget paraffin, gas and Alpine lemonade
I still get milk bottles delivered by a milkman in South London . They are collected , washed and reused. We have a choice of companies doing this.
Yes, it's good to see Ocado promoting reuse of plastic contaainers. Whilst reuse is obviously better than recycling, I doubt that Ocado's trial of refillable containers will be a big threat to Zotefoams (LON:ZTF) market for ReZorce cartons.
This is why I come here. A wonderfully balanced assessment of Jarvis Securities (LON:JIM) from Graham and great input from Kirkie. I used to hold but can now claim to be a smart arse having sold at the first sight of a smoking gun…
I'm grateful for your comments on Jarvis Graham, thank you. As the SCVR warns everyday -- DYOR. Your own analysis and Roland's and Paul's is always good, it's up to subscribers what they choose to hold buy or dump. I should also have known skilled person means very expensive person, we have some in our family! We're holding while I'm adopting the brace position for the final report. It can't be fun for Jarvis employees either.
Morgan Sindall (LON:MGNS) and Hill & Smith (LON:HILS) not making the cut Paul?
I think it is because they have a market cap above £1 billion. I am a holder of Morgan Sindall (LON:MGNS) myself, very pleased so far with the investment :)
Savills (LON:SVS) at £1.8bn….
SPI
I am waiting for the market cap to drop a little under 1bn so that Paul or Graham may kindly review the next set of results.
SPI is in the right sector, the largest independent healthcare provider.
It is lamentable the company has not been able to benefit from the current high demand for its services.
From memory, Christopher Mills, Ed Croft and The Naked Trader like the share . Each have their own reasons!
Spire Healthcare (LON:SPI) you are right Yadi. If you can't make hay as a private healthcare provider at this time in the UK you must be pretty hopeless at managing a business. Spire have flatlined for 4 years while trading conditions have been completely in their favour. DD
Morning Paul, if you get a chance over the next couple of days be interested in your views on results from Keller which look great with a positive outlook
A little outside the world of small caps, two of my Lloyds Insurers have reported interims this morning - Beazley (LON:BEZ) appear at a first 1 minute glance to have reported great results, with a decreasing (ie good) combined ratio and strong top line growth, continuing the trend of the last couple of years. Lancashire Holdings (LON:LRE) have also reported what appears to be good results with low CORs: initial share price movements differ, though, with Beazley up around 10% and Lancashire merely holding steady.
Interested on thoughts on these: I hold (and will likely continue to do so once I've digested the results in more detail) - the obvious attraction is a strong underwriting franchise in each, with the negatives being the potential huge hits that can arise from events affecting the Lloyds market. With this hurricane season expected to be worse than normal, that is perhaps a cloud on the horizon (although Beazley isn't active in this space).
Beazley (LON:BEZ) Kirkie - are you sure about Beazley not being US hurricane exposed? A quick look at their website suggests that they don't write (?much) US Cat treaty reinsurance, but do write direct insurance / Fac reinsurance.
Just a quick look but, if I was considering and was concerned about cat exposure, I'd want to dig a fair bit deeper.
But presume they have adequate Excess of Loss reinsurance to cover any major losses? It is the reinsurers that have the most exposure, those being the ones that write Excess of Loss reinsurance.
Hi Rusty2 - sorry for the delay in replying. Beazley (LON:BEZ) - yes, I'm sure they buy cat xol for their property book.
But they are also a cat writer themselves : "We specialise in writing worldwide property catastrophe, per risk and aggregate excess of loss and casualty clash." How much etc, I don't know.
I'm 16 years out of the market, so completely out of touch. However, my impression is that Beazley are a well run operation. If I was looking to invest in an international insurer/reinsurer, I'd start by looking at Hiscox & Beazley.
Thanks, garbetklb - my morning coffee will be spent researching this in a bit more detail! I'll admit my research on this area is probably 18 month only in terms of the lines they wrote / underwrote - but I seem to remember a few comments from results that they tended to avoid (certainly first order) exposures in this area.
TT electronics (LON:TTG)
interims don't look inspiring, on initial reading!
bit slow going- but I can see this company getting taken over , as it looks very cheap
I read it and thought it all depends on how much you believe the turnaround story. I think they are making progress and continue to hold
Jarvis Securities (LON:JIM)
A profit warning that surely can't surprise anyone who has followed them forthe last 2 years as the FCA carry out their witch hunt alongside very slow markets. The boys in the City are being well rewarded in fees for digging through the likes of Jarvis, HL etc examining all the dirty laundry for evidence of who knows what.
Stocko show the Y-o-y price down 64% compared with a 29% decrease in PBT so one might say the bad news is in the price. 1p dividend declared.
Jarvis Securities (LON:JIM) - one to be very careful on .... what does the word "currently" imply?
"Although the regulatory review is ongoing, as a firm we are currently committed to working through it and emerging in a more robust state and ready to focus on the future of the firm and its plans for growth."
Fee and commission income is dropping like a stone. Bailed-out by interest on cash balances. Massive dividend cut. Used to hold this at one time. No price would tempt me back in as I'm not sure who their customers are and share platforms of this size cannot compete without cutting corners. They are better off selling the business and customer base to another party, if they can't resolve their regulatory problems soon. Indeed, a transfer of their legitimate customers may be the only way forward.
Oh dear topvest, you infer something very sinister from the word currently and go on to imply that they're doomed. I am a customer and have been for twenty years since leaving Charles Stanley. The difference being, one you start with a large sum and you pay a lot in fees to protect it and the other you trade on line doing most of the work yourself and grow a small sum into a larger one paying minimal fees. A cynic might say the bigger outfits are trying to squeeze companies like Jarvis out of business, the "Skilled Person" has taken two years to find nothing but a small number of their model B clients are a bit lacking in ensuring that money launderers can't do business with them and shock horror they don't pay interest on cash balances but instead use interest income to subsidise fees. I only pay for trading at £5.95, nothing else, and am relaxed about leaving cash available to re-invest when required. Their service has always been very satisfactory and most importantly the CEO doesn't make himself invisible and uncontactable. An email will quickly resolve any problem on the very rare occasion one has arisen.
EDIT I should have said, if it's not obvious, I hold Jarvis Securities (LON:JIM, most of which being the result of divdend re-investment.
Jarvis Securities (LON:JIM) - Samsgrandad - apologies, I should have clarified - it's who their model B customers are. The CEO is very good. It was a great share to be in for many years - a multi-bagger and fantastic dividends with aligned rewards. I am just saying that the world has moved on and small brokers cannot compete with the likes of Interactive Investor, HL and AJ Bell. Their days are numbered and it will likely go the same way as Share. Personally, I wouldn't have all my funds on one platform and would avoid the smaller ones. Why take the risk?
Jarvis Securities (LON:JIM)
is the summary here that the skilled person tasked to performed the skilled person review doesnt have the necessary skills to do their task in timely fashion?
i have zero tolerance for these companies that seems to reluctantly be tlerating this issues. Should they not be enusring all their propcesses are such that it would be super easy for siled person to come in and set - ahh thats great - bish bosh bash. I dont know the technicalities of how these people work - i suspect they are high paid jobsworths who dont care about the realities of what the business needs out of their review - if they are akin to auditors surely the way to go is have processes in place so that ideally there are no delays and everything they want is laid to them on a plate. Can you ever imagine next blaming third parties with regard to what and when they report to the market - i doubt it. So too me any mention of company business being affected by skilled people review is a red flag - albeit when it is announced one turns up , that is when we see how competent managment are to make sure this review does not descend into chaos.
All i do know is that its hard looking from the outside to work out what the end result will be with regard to whetehr company carries on as before or not - and i do know that those on the ground will have much more of inkling as to whether it wil all be fine and dandy or not - would i want to hold shares in company where there may be material news that i am last to know about ? - not on your nelly.
At present i am giving most of these fca regulated entities a wide berth - ok old hand like aviva/l&g and the like are probably ok. Having said that i did own CMC Markets (LON:CMCX) for a while recently so so its so easy to lower one standards when one say i wont do this.
I would like to add an example of where a skilled person review went quite smoothly, and the company managed to tick the boxes and move on successfully.
H & T (LON:HAT) is an example - they had a skilled person review back in 2021. It did take quite some time (6-12 months if I remember correctly?) and there was a delay to the original timelines. But they emerged from it with an all-clear, some small changes to be implemented I believe, and that was that. Business as usual again going forwards.
Jarvis Securities (LON:JIM) Just to note up front, this isn't an investment I'm familiar with, nor do I know what the exact issues that have called for a skilled person's review.
However, I've done these before first-hand for the FCA/PRA on regulated firms. If you get a s166 called on you, it's because the regulator KNOWS that you have serious issues and wants an in-depth assessment of everything to do with it - end to end - so that it can be adequately remediated. If the regulator isn't satisifed with the remediation, they'll take regulatory enforcement action.
It's not quite a "blank cheque" for the firm that is appointed to do the review - but it's a tripartite engagement between the regulator, the firm being investigated, and the skilled person. If the regulator isn't happy with the scope, they'll demand the firm changes it.
In summary - no good news EVER emerges from one of these things from the point of view of a firm being investigated - only degrees of bad. And it's exceptionaly likely. that a s166 results not only in (a) an expanded scope, so more cost (what's happened here?), (b) remedial action requiring more resource cost to fix, and (c) future work to gain assurance that the problems have been fixed and can be evidenced.
And the overhead from the point of view of management time required to deal with it is HUGE.
IMO, It's not necessarily a red flag from an investment point of view - but it's a helluva large amber duvet cover being waved, normally...
Jarvis Securities (LON:JIM) Easy in retrospect to say that companies should have been more focussed on internal processes but anyone who has bought a house in the last few years knows how suddenly the goal posts were shifted to ensure that money laundering can be prevented. I suspect that some political impetus added to the urgency recently to make sure that the City lost its reputation as the goto for Russian Oligarchs. As markets were quiet, a nice little earner for some under-employed in the City and no need to rush, a blank cheque at the end. JIM's model B white-lable business was a weakness with some of its clients who didn't know their customers well enough and I understand these were given the chop very early by JIM's management. I believe they will survive and get stronger afterwards.
Consumer Duty is a form of communism that has been applied to financial services!
thats your viewpoint - other look at it as protecting consumers from scammers who will happily lie by omission
Apology accepted topvest and thanks for the more measured comments. Two model B clients that I'm aware of from their website are Yorkshire Building Society and a Goldman-Sachs staff fund. Being a late comer to investing I guess it's a matter of trust and sticking with what you know. Risk is the game isn't it and we all try to mitigate it how we can.
I´m also a Jarvis (x-o) customer and have quite a large portfolio with them, though currently a very low cash balance. If this "skilled person" rules unfavourably against Jarvis is my portfolio at risk in any way? Can´t see anything about it on the website, though may have overlooked the revelent info. Thanks
PJY5 the JIM website has the answer to lots of queries here , worth having a good nose around. You have to be nosey to root out stuff for yourself, rather than asking on-line, some will tell you wrong answers, sometimes deliberately.
It could be more prominent instead of on the bottom line of the page. NB the Jarvis Securities website is more concerned with the holding company, dividends, results etc
Many thanks Sgd, most helpful.
Jarvis Securities (LON:JIM) - some guidance here https://www.investorschronicle...
Not saying any of this is likely to happen, but always best to be informed.
I am a customer of Charles Stanley Direct but have Interactive Investor at about the same size now. This is because I wanted to diversify from 1 platform to 2, rather than having all my eggs in one basket. Both are financially strong, so probably a tad over cautious.
On Jarvis Securities (LON:JIM) (on my watch list now)
would currently bet against them going bust - a material breach of CASS regs (keeping client money separate from co money and knowing what client the money belongs to etc) would have not been left to stew for so long.
also now understand why we were recently told to keep the regulatory training up to date in the $job :). As long as they haven't tried to hide anything, there may be a fine (but optimistically no restriction on business and not a big fine). Any shenanigans like deleting emails or losing your phone (news international and politicians) would not end well (the consumer duty / individual conduct rules are pretty scary).
Biggest risk probably a delay in trading depending on what fca say or do. Unlikely but not impossible.
Morning
The main takeaway from NAHL (LON:NAH) ’s update this morning is that the sale of Bush is progressing well. As a reminder to readers, that business generates over £5m of non cyclical ebit that converts fully to cash, and is growing 10%+ pa. Could easily fetch £45-50m vs a market cap of £25m…
#ENT shares looks like optimisation and Euros has supported a beat here. Ignorning the complex RNS for one minute and comparing to gambling peers + new CEO + propsect of regional sales + US story is all quite positive...let's see what the reaction is today (+10% maybe?!)
Early morning in N.E. Lincolnshire. Gear on for short lively run before 7.00 am (at 81 - should know better), decide to check RNS first, note Jarvis and reach for sick bag. Mr Contrarian has covered it this morning and Graham did on the 15/2/24. It reminds me of Ken Mitchell's observations late yesterday! Endorphins have kicked in now, there were no riots yesterday, no war yet in the Middle East, onward and upward friends there's plenty of good news on shares about too.
81? I am impressed, onwards and upwards.
Morning All,
Excellent interims from Mears (LON:MER) this morning. I know they caution on possible normalisation of revenues/profit going forward, but still looks way too cheap...
Very disappointing reaction thus far, what am I missing?
My morning smallcap tweet: JIM in a jam
Jarvis Securities (LON:JIM) Celebrus Technologies (LON:CLBS) Concurrent Technologies (LON:CNC) Seeing Machines (LON:SEE) Mears (LON:MER) FIH (LON:FIH) Earnz (LON:EARN) Hermes Pacific Investments (LON:HPAC), NAHL (LON:NAH), Oxford BioMedica (LON:OXB), Impact Healthcare REIT (LON:IHR), TT electronics (LON:TTG), Hostelworld (LON:HSW)
◄Jarvis Securities (JIM)► H1-June rev down 12%, pretax down 29%. Warns FY significantly below market expectations due to "subdued trading volumes; the increasing costs of the Skilled Person review; the costs of the associated remediation work and the ongoing impact of the VREQ on the Company's Model B clients". [SP=57.13 Cap=26m]
◄Celebrus Technologies (CLBS)► wins three-year Celebrus Platform contract with a leading global airline. No £££. [SP=278.5 Cap=110m]
◄Concurrent Technologies (CNC)► $1.5m contract extension with major US Defence and Aerospace contractor. [SP=118.12 Cap=101m]
◄Seeing Machines (SEE)► Q4 KPIs. Production of new vehicles using Seeing Machines' DMS technology up 80%. [SP=4.68 Cap=194m]
◄Mears (MER)► H1-June rev up 10%, pretax up 44%. Guides FY rev £1.1bn, with adjusted profit before tax in a range of £53m-£55m, ahead of market expectations. [SP=340 Cap=327m]
◄FIH (FIH)► FY-Mar. Div 6.75p (6.5p) plus 10p special div (0p). [SP=245 Cap=31m]
◄Earnz (EARN)► the cash shell plans £4m placing at 7.5p, a 9% discount, to fund RTO. [SP=8.3 Cap=5m]
◄Hermes Pacific Investments (HPAC)► proposes delisting. Blames costs, large discount to NAV. [SP=59.7 Cap=1m]
In line: NAH, OXB, IHR, TTG, HSW
Deutsche downgrades Polar Capital
Deutsche Bank has slashed its rating for Polar Capital Holdings (LON:POLR) as it estimates the major technology investor’s assets under management have been hit by the recent selloff in the sector.
Analyst David McCann cut his recommendation from ‘buy’ to ‘hold’ and lowered the target price from 635p to 510p for the Citywire Elite Companies + rated firm to reflect his estimation that Polar Capital’s assets under management (AUM) have fallen 9% since the last official figure of £21.9bn in June.
‘We estimate Polar delivered £0.1bn net inflows in July and has remained in small net inflow early in August,’ McCann said. ‘However, we also estimate that current AUM has declined approximately 9% since the Jun-24 reported figure, principally driven by Polar’s high weighting towards technology assets and the associated sell-off, as well as recent negative market movements more generally.’
He noted that the decline and the business’ operational gearing, or borrowing, knocked Deutsche’s earnings estimates by 19% and had a similar impact on their valuation.
The shares rose 1.4% to 520p on Wednesday, putting them up 12.4% year to date.
Genuinely baffles me why anyone would hold Polar Capital Holdings (LON:POLR. A geared play on US tech stocks - just hold those stocks instead! Or buy their main technology fund which has delivered far superior returns to polars share price
circa 10% dividend plus exposure to tech funds which is easier for many who dont understand the tech space
Polar Capital Holdings (LON:POLR) Not quite the same thing - yes they are heavy in tech but also have a lot of other good strategies (healthcare, emerging markets, global insurance). Importantly they seem to be a genuinely good active manager in specialist niches , so would expect them to grow AUM over time.
Still doesn't make any sense to hold Polar Capital Holdings (LON:POLR) shares over the funds. Lets do a quick comparison of performance over 5 years:
Polar Capital Holdings (LON:POLR) - down 6.85%
Polar capital technology fund - positive 95%
Polar capital Biotechnology - positive 89%
polar capital artificial technology - positive 86%
You're comapring 2 different things - an asset manager on the one hand, with various investment funds on the other. Asset managers have obviously had headwinds from outflows in recent years.
You've conveniently ignored, as Bouden54 says, the fact you are comparing apples with oranges, and the ~40% that you would have received in divis owning Polar Capital Holdings (LON:POLR) as well.
ok fair challenge, so with dividends you have a c.40% gain. Still awful compared to the three funds I mentioned.
I disagree its comparing apples and oranges. Polar capital, like all asset managers, makes its money by charging fees on AUM. In Polar's case their AUM is highly concentrated in those top funds. So why hold the asset manager when you can hold the fund(s) which have far superior returns? This is a unique set up, i wouldn't say this of any other asset manager as they generally have much better diversification than Polar. Polar is uniquely concentrated in US tech which adds considerable risk.
Yes the funds have performed better than asset manager in recent years, but that doesn't mean they will going forward - if we see a return to net inflows across the sector then I would expect the fund manager to outperform. Either way, quite separate dynamics so too simplistic to say the funds have performed better recently so will therefore also perform better in the future.
no your failing to see that the funds performance is intrinsically linked to Polar's performance. If those funds start to under perform, clients will divest and Polar's AUM and profits will subsequently fall. Unless Polar massively diversifies its book i guarantee your better off in the funds
Firstly, I would politely suggest that there are no guarantees in financial Markets.... but also, if the funds flatline then the underlying asset manager will still be earning fees and paying dividends... I would guess that in a negative market environment the asset manager would potentially sell off, but to a lesser extent... they are definitely correlated, but would suggest that Polar Capital Holdings (LON:POLR) will be less geared...
@cwatson you’re not accounting for the bumper Polar Capital Holdings (LON:POLR) dividends, not sure what the adjusted % gains would be taking them into account ?
And pay a sizeable dividend too