Small Cap Value Report (Thu 8 Feb 2024) - REVB, SDG, WOSG, AFM, FSJ

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
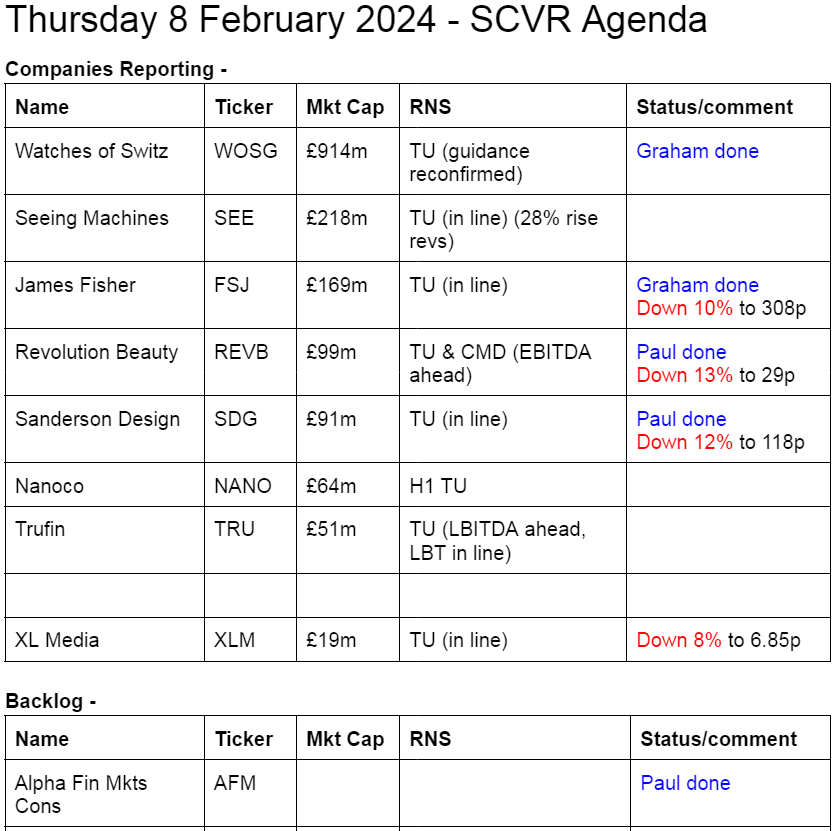
Other mid-morning movers (with news) -
Sondrel (Holdings) (LON:SND) - bonkers mover of the day! Up 140% to 14.25p for this almost-bust chip designer. Company issues statement noting press speculation (Daily Mail article pumping it here), saying it doesn’t comment on customer links. It does say continues to trade in line, and has demand remains strong. It needs to get emergency fundraising done, this looks like a pump to help get placing done maybe?
British American Tobacco (LON:BATS) - large cap up an unusual 7.4%, on beating full year forecasts. PER 6x, yielding >10%, selling cigarettes.
Hardide (LON:HDD) - down 23% to 7.5p - FY 9/2023 results show reduced loss of £(1.2)m. Slow start to FY 9/2024. Seeking cash & debt from investors to meet short term cash constraints. Sounds serious - discounted placing now seems a high risk.
DS Smith (LON:SMDS) - up 12% to 314p - mid-cap with generous divi yield notes media speculation, and confirms it has received a "highly preliminary expression of interest" from larger rival Mondi (LON:MNDI) about a possible offer. Takeover Panel rules now kick in.
Summaries
Revolution Beauty (LON:REVB) - down 8% to 29.5p (£94m) - Trading Update & CMD - Paul - AMBER/RED
Not a bad update today, with adj EBITDA guidance raised, although it's not much above breakeven when translated into real world profit. Bank renews for 12 months. A very ambitious growth strategy is outlined, with a CMD coming. I see high risk of an equity fundraise being needed here, so be aware of that risk. Could be an interesting turnaround though, so worth keeping an eye on.
Sanderson Design (LON:SDG) (Paul holds) - down 17% to 105p (£70m) - Full Year Trading Update [in line] - Paul - AMBER/GREEN
In line with expectations year end update for FY 1/2024 - a year where strong licensing income offset a weaker performance in the core business, as we already knew from previous updates. Expectations for the new year are trimmed about 7%. Superb balance sheet protects downside. I like it a lot still, but am moderating my view slightly to reflect lower profit guidance today.
Watches of Switzerland (LON:WOSG) - up 3% to 391.8p (£939m) - Q3 FY24 Trading Update (in line) - Graham - AMBER
Market seems relieved there is no further bad news from this luxury retailer. USA trading well but UK/Europe suffering from weak demand in part due to absence of VAT free shopping. Valuation is starting to look tempting in my view; hoping to see decent full-year results.
Alpha Financial Markets Consulting (LON:AFM) - down 10% y’day to 335p (£384m) - Trading Update - Paul - AMBER/GREEN
Our first ever look at this specialised staffing group, and I reckon it looks pretty good. Dropped 10% yesterday on a mildly negative trading update, but forecasts have only been slightly reduced, so I don't think it really qualifies as a profit warning, more an adjustment. Ambitious growth plans, and it's paying a 4.2% dividend yield. Looks worthy of you taking a closer look, just based on my quick initial review.
James Fisher And Sons (LON:FSJ) - down 13% to 292p (£147m) - Full Year Trading Update (in line) - Graham - RED
It might be a little harsh but I’m giving this marine services business the thumbs down as they seem to be having some trouble paying down their debts, while at the same time simplifying operations and getting back to profitability. High-risk, high-reward if they succeed.
Paul’s Section:
Revolution Beauty (LON:REVB)
Down 8% to 29.5p (£94m) - Trading Update & CMD - Paul - AMBER/RED
CMS is Capital Markets Day for anyone unfamiliar. These are events designed to drum up interest in the company with institutional investors and analysts, and can sometimes be a warm-up act for an equity fundraise. Or management trying to get the city on side for its strategy.
Revolution Beauty (AIM: REVB), the multi-channel mass beauty innovator, will today hold a Capital Markets Event for institutional investors and sell-side analysts. The Group is also providing a brief trading update for the 2024 financial year.
So far REVB has been a disastrous 2021 float, with all sorts of problems emerging. It survived a near-death experience when accounting irregularities were found, shares were suspended, then a battle for control in 2023 (with Boohoo taking a stake and forcing changes).
I would say currently the jury is out as to whether the turnaround is working or not.
I’m pleased to say we spotted the accounting problems here in the SCVRs, and warned people away from it in 2022, well before things went seriously wrong.
However we like turnarounds, so I’m happy to look at it with fresh eyes each time it reports.
The headline is aspirational rather than factual -
New leadership team outlines strategy to accelerate profitable growth and ambition to deliver retail brand sales of £1 billion by 2030
Ah, that ambiguous phrase “profitable growth” that is so fashionable at the moment. What does it actually mean? Very little! It’s designed to sound like profits are growing, without actually directly saying so. It could mean a wide range of things, including growing revenues, whilst profits falling to almost zero. That would still be profitable growth. Such a silly phrase - do the PRs actually think this fools us?!
Existing revenues are c.£200m, so growing that to £1bn over the next 6 years is certainly an ambitious target. Note the CFO is Neil Catto, formerly long-serving CFO of Boohoo in the glory days, who certainly knows a thing or two about rapid growth in eCommerce.
Maybe they should ask for some tips from Warpaint London (LON:W7L) who are showing the way to achieving strong global growth in affordable cosmetics.
The strategy outlined today by REVB just sounds like sensible basic stuff to me - eg cost-cutting of £10m over 3 years, reducing number of product lines to focus on key products, developing the brand name, maximising retail/distribution partnerships, especially in the USA.
Trading update for FY 2/2024 -
Sounds like slower revenue growth, but higher margins, hence higher overall EBITDA -
At the time of its half year results announcement in November 2023, Revolution Beauty expected to deliver adjusted EBITDA of not less than double-digits and high single digit revenue growth for the 2024 financial year.
As noted above, the Group has accelerated the rationalisation of lower margin SKUs, successfully driving margin improvement. As a result of this greater focus, FY24 adjusted EBITDA is now expected to be between £11 million and £12 million, and revenue growth is expected to be in the low single digits.
Any broker updates today? No, nothing available unfortunately. The company needs to speak to some brokers about getting information out to private investors, who are the main market for its shares whilst institutions are mostly hiding in the basement, and dealing with redemptions!
Looking at its last interims, to 31 Aug 2023, it did £90.4m revenue (up 20%), £6.4m adj EBITDA, and PBT of only £0.4m. Net debt was £(23.8)m.
The last balance sheet was weak, with negative £(15)m NTAV. A £16m deferred consideration creditor worries me, as it doesn’t have the cash to pay this. Or could it be paid in shares maybe? That needs looking into. Inventories & receivables also looked too high. So it clearly still has balance sheet issues, and I would say an equity fundraise looks a considerable risk for existing shareholders, who might not have access to a discounted placing.
So investors have to decide whether to wait for a fundraising to sort out the balance sheet, avoiding dilution risk. Or whether to just gamble on the turnaround working, and hope for the best re dilution.
My caution is reinforced by a “material uncertainty” going concern note with the last interims.
Also see note 3 in the interims, “Correction of prior period errors”, includes a £4.9m provision for allegedly breaching music copyright in social media posts. Although it reckons £3.6m can be reclaimed from its insurers, so it doesn’t look too bad overall, but reinforces what a minefield social media can be, if staff accidentally use copyrighted images & music.
Here’s a useful table which shows how £6.4m adj EBITDA in H1 turned into a £(528)k operating loss. Some of these items (eg exceptional legal costs) would be OK to adjust out I think, as non-recurring.
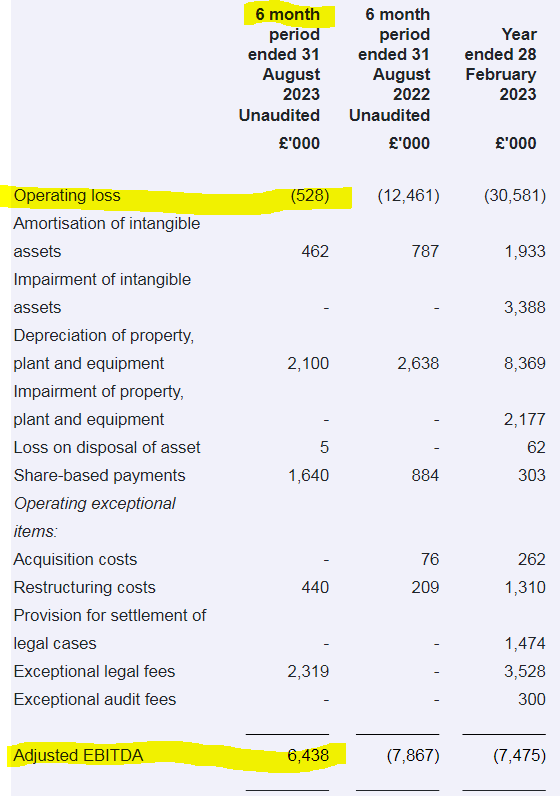
Overall then, the new guidance today of £11-12m adj EBITDA for FY 2/2024 is pointing towards H2 being slightly less profitable than H1, which is a bit disappointing to me given that H2 includes the buoyant Christmas period.
It seems that real profits (at the PBT level) would be small overall, hence I can’t get excited by the £11-12m EBITDA forecast.
The company needs to get some proper numbers out via brokers, instead of forcing us to try to work out the numbers manually.
Bank borrowings - this sounds good news, as the company is completely dependent on its bank borrowings at the moment -
The Group has also signed a 12-month extension to its £32 million Revolving Credit Facility (RCF). The RCF will now run until October 2025 on unchanged terms.
Although 12 months isn’t a major commitment from the bank, and is maybe another sign that a placing is likely later in 2024 to repair the weak balance sheet?
Paul’s opinion - quite an interesting share, but £102m market cap is already pricing in a considerable improvement in profits, which are currently only low if we include all costs.
I’d say dilution risk from a placing looks high, and in current nervous small caps markets, who knows what terms a fundraising would be on? The risk is that small shareholders get heavily diluted by institutions who name their terms. Boohoo are notoriously tough negotiators, and owning 27% of REVB, they would be in the driving seat for any fundraise I imagine.
Overall, I’m happy to watch from the sidelines, and will go with AMBER/RED for now, to flag the risk of dilution from its weak finances. Whilst also recognising that trading is a bit ahead of previous guidance, although only really a bit above breakeven in real world profit terms.
As a trading share, this could get interesting, if more investors start to buy into the turnaround potential, who knows?
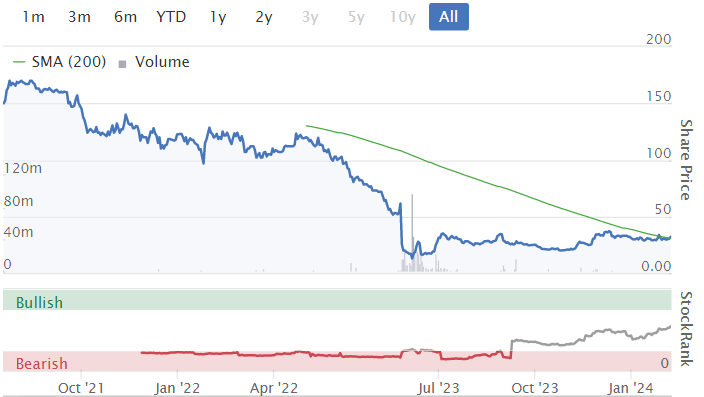
Sanderson Design (LON:SDG) (Paul holds)
Down 17% to 105p (£70m) - Full Year Trading Update [in line] - Paul - AMBER/GREEN
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, is pleased to announce its trading update for the financial year ended 31 January 2024.
Results in line with expectations with profitability driven by Licensing
Revenues down 3% at £108.5m
Underlying profits c.£12m (LY: £12.6m)
Net cash £16.2m at end Jan 2024, slightly up on 6m ago.
A table provides more detail, with the quick version being that revenues were down in UK & Europe, partially offset by growth in USA.
More importantly, high margin licensing revenue has really bailed out the rest of the business, up 68% to £10.9m. Without that success, profit would have been much lower.
Outlook comments strike me as sensible, and hopefully there might be upside as consumer spending & housing markets begin to recover in 2024? -
Licensing has become a significant strategic pillar for the Group whilst, geographically, North America continues to be a key growth market. We intend to focus on these two growth drivers and also take advantage of any other international growth opportunities.
Whilst trading conditions are expected to remain challenging in the UK and Europe, at this early stage of the current financial year ending 31 January 2025 the Board's full year revenue outlook remains unchanged.
Certain cost pressures are expected, including the increase in the Real Living Wage and property-related costs, such that profitability in the current financial year is expected to be similar to that of the year ended 31 January 2024…
The Group has a strong pipeline of product initiatives in the year ahead, including the strategic focus on the Sanderson brand. Giles Deacon's capsule collection of Sanderson designs has just been launched, and last year's successful launch of the Disney Home x Sanderson collection brings further potential in the current year.
Broker updates - both Progressive and Singers update today, very helpful.
Singers has 12.8p adj EPS for FY 1/2024, and 12.5p for FY 1/2025.
Progressive uses the same adj PBT forecast of £12.0m, but arrives at higher adj EPS figures of 13.4p and 13.3p, not sure why - maybe it’s assuming a lower tax charge?
Note that Progressive has lowered FY 1/2025 forecast by 7% at the EPS level, so I suppose we should see this as a minor profit warning, ie lowering forecasts a little. Hence today’s 7% dip in share price does make sense.
Paul’s opinion - I think SDG has weathered the tough consumer macro environment very well in FY 1/2024. That’s down to a highly successful year with licensing - some of the deals do repeat, but others are one-offs, so it’s not necessarily quite as high quality revenue as in other licensing businesses which have longer-term income streams.
Looking at the H1 results, if we assume licensing revenue is almost pure profit, then it means the rest of the business was really only operating around breakeven, with all the £6.8m H1 adj PBT coming from the £6.9m licensing revenues. Which does raise the question, why bother with manufacturing and branded products at all? Isn’t it just an overhead? Why not concentrate on just licensing, and become a pure IP company?
Maybe the licensing only happens because the designs are so visible from selling fabrics and wallpapers? Those would be good questions to ask management.
Overall, it’s proven resilient in a tough environment, and seems to be capable of producing around 12-13p EPS again, with possible upside if a consumer/housing recovery gains traction in calendar 2024, as seems likely.
There again, there needs to be a recovery from the core business, in order to replace potentially weaker licensing revenues, if FY 1/2024 turns out to have been a lucky one-off for big licensing deals? Who knows how it will pan out?
Is the valuation reasonable? Yes, I think so. Using c.12.5p EPS, the 118p share price is only a PER of 9.4x - leaving plenty of scope for shares to rise, if earnings meet or beat forecasts.
There’s also risk, if FY 1/2025 cannot match the prior year’s licensing receipts, and the core business continues to struggle. It could go either way.
Valuation is also strongly underpinned by a terrific balance sheet, with c.£60m NTAV, including £16m cash - that’s surplus cash too, as net current assets is a very strong £42m when last reported (and no long-term liabilities of any significance).
So even in a downside scenario, there’s no threat to solvency or risk of dilution.
On balance I see it positively, but I’ll soften slightly from green to AMBER/GREEN, to reflect the 7% lowering of profit forecasts for FY 1/2025. It’s worth noting there is a risk of a profit warning at some stage, hence why this share is cheap (it’s tempting to keep some powder dry, to nip in and buy on any future profit warning, but that risks missing out on a recovery).
For full disclosure, I’m only holding a tiny position in it at this stage, to keep my foot in the door.
Stockopedia really likes it, with a StockRank of 98.
Alpha Financial Markets Consulting (LON:AFM)
Down 10% y’day to 335p (£384m) - Trading Update - Paul - AMBER/GREEN
This company floated in Oct 2017, and I’m struggling to understand why we’ve never looked at it here in the SCVRs before?! It must have just slipped throught the net.
The track record looks fairly decent - and note the consistent divis throughout the pandemic -
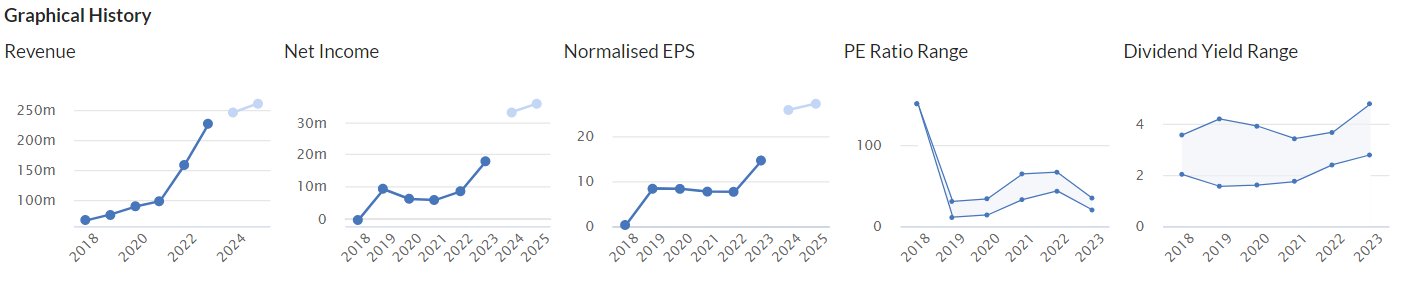
The lighter blobs above (forecasts for 2023 and 2024) show quite a large increase in forecast earnings, so is there some risk to those forecasts not being met, I wonder?
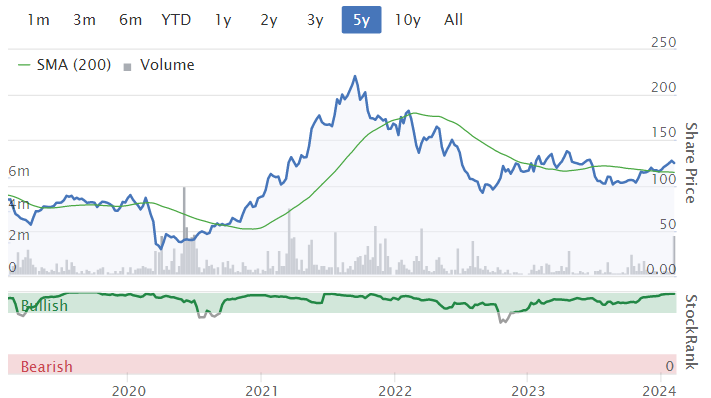
Here’s the full share price graph since it listed -
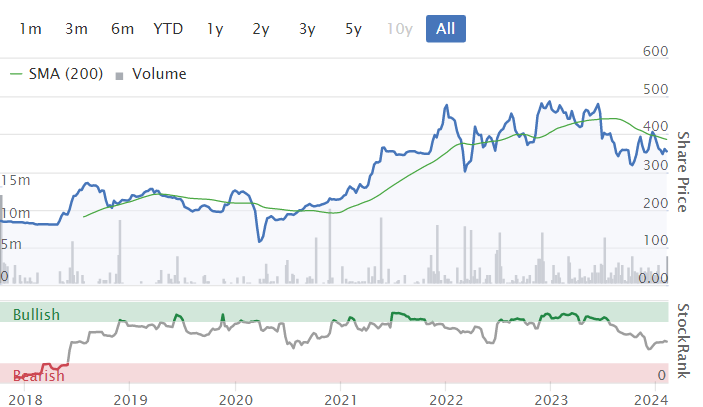
It seems to be an acquisitive management consulting group, hiring out just over 1,000 consultants, and reporting NFI (net fee income) as revenue - so a specialised staffing company by the looks of it.
Balance sheet is almost all intangible assets (goodwill & similar), there was only £9m of NTAV at Sep 2023, so no asset backing to speak of.
Cashflow statements show it’s generating cash, and using it to pay for acquisitions and growing divis (now yielding a fairly healthy 4.0% pa, covered about 1.8x).
So far so good, this looks quite decent on my first look at AFM shares.
The forward PER is 13.6x, which also looks reasonable.
Trading Update (published yesterday morning)
Alpha FMC (AIM: AFM), a leading global consultancy to the financial services industry, provides a trading update for the year ending 31 March 2024 ("FY 24").
Q4 slower than expected. Mentions competitive environment, and longer sales cycles, so some client projects delayed.
Revised guidance (it’s so annoying when companies don’t disclose what the previous guidance was, wasting our time trying to find it) -
Consequently, the Board now expects the Group to deliver FY 24 results showing net fee income growth of up to 5% against the prior year and adjusted EBITDA of approximately £42m - £43m at a slightly improved margin on the first half.
In the current market environment the Group has maintained consistent day rates, a selective approach to hiring into key growth areas, and continues to manage actively its cost base. The Group also maintains a strong net cash position.
There’s no broker research available to us.
I’ll try to piece it together from the H1 figures, which showed: revenue 115.6m (up 7.5%), adj EBITDA £20.1m (down 10.5%), and adj PBT £18.4m (down 13.6%), adj EPS of 11.8p (down 16.2%).
The FY 3/2024 guidance of £42-43m adj EBITDA implies H2 is slightly higher than H1, at £21.9-22.9m.
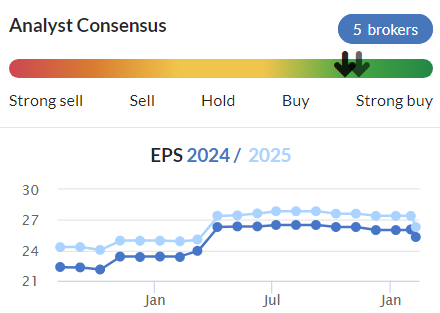
Adj EPS looks to be heading for about 25p for FY 3/2024. Looks like I’m almost bang on there, as Stockopedia has overnight updated consensus broker forecast from 26.0p to 25.3p.
Hence this looks like only a minor trim to broker forecasts, so small that it hardly justifies being labelled as a profit warning.
FY 3/2025 forecasts have also been slightly trimmed, from 27.4p to 26.3p. Again, no great shakes, so I’ve decided not to label this as a profit warning, more a minor adjustment.
This graph puts things into perspective - not a cause for alarm -
Outlook comments sound OK to me -
The Group continues to see robust client demand and has seen higher sales wins in recent months, while maintaining a strong pipeline of new business opportunities. These factors, together with the strong long-term structural growth drivers that underpin demand for Alpha's services and the Group's compelling proposition to clients, gives us confidence that the Group remains well positioned for continued growth, in line with our ambition to double the business again by 2028.
Luc Baqué, Chief Executive Officer, commented:
"The challenging market environment previously reported remains prevalent. While trading is improving in the second half it has not recovered at the pace we envisaged when reporting our interim results, as the market continues to rebalance supply and demand. However, we continue to see improving market conditions and with the Group's ongoing strong pipeline, leading expertise, strong propositions and multiple growth opportunities, we remain well positioned for future growth."
Paul’s opinion - is purely based on my first ever initial review of AFM, not deep research, which I have to say is quite positive. It looks like a specialist staffing company, which has grown impressively (albeit with some dilution - no. shares 90m in 2018, 114.5m now), whilst making acquisitions and paying a decent dividend yield.
It sounds like there’s scope for trading to improve in a recovering economy, and it’s remained pretty robust during the pandemic and more recently. It’s making nice margins, and generating cash. All for a PER of 13.1x, hardly demanding.
So AFM gets an initial view of AMBER/GREEN from me, as I quite like the look of this.
Graham’s Section:
Watches of Switzerland (LON:WOSG)
Share price: 391.8p (+3%)
Market cap: £939m
We have an “in line” update from Watches of Switzerland this morning, on the back of a dramatic profit warning seen last month:
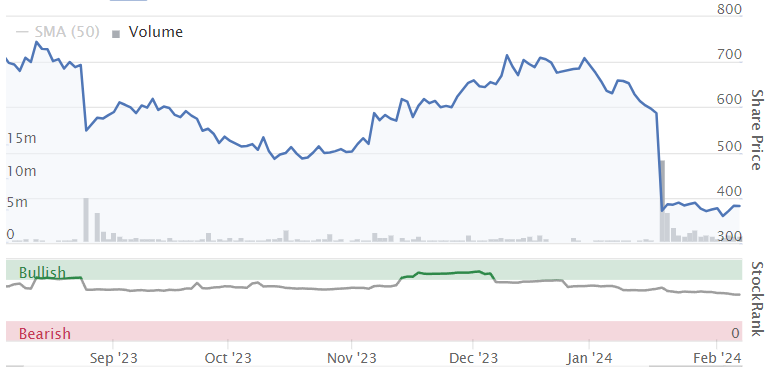
This stock had exceeded our small-cap limits for some time, but is now firmly below the £1 billion mark again.
Here are the Q3 highlights (Nov to Jan, as the year-end is in April).
Q3 revenue down 1% at constant FX, down 3% at actual FX.
Year-to-date revenue up 1% at constant FX, down 1% at actual FX.
E-commerce revenue down 15%.
As disclosed in the January profit warning, UK demand for luxury discretionary purchases was worse than expected in the run-up to and beyond Christmas.
Drilling into performance by geography, there are much stronger numbers from the US as compared with UK/Europe. US year-to-date revenue is up 10% to £502m, with WOSG “gaining market share in the fragmented US luxury watch market”.
In the UK and Europe, by contrast, year-to-date revenues are down 5% to £656m.
There was particular weakness in non-branded jewellery “where we saw unusually high levels of promotional activity” and generally consumers were “allocating discretionary spend to other categories such as fashion, beauty, hospitality and travel”.
In a sign of a shrinking market, WOSG maintains that it increased market share despite falling revenues.
The UK has seen “minimal return of tourist spending due to the lack of VAT free shopping”.
However, perhaps there is light at the end of the tunnel with recent reports that VAT-free shopping could possibly make a comeback. Since 2020, the UK is one of the few countries that doesn’t offer the incentive to tourists.
Indeed, WOSG says today: “We are encouraged by the UK Office for Budget Responsibility's review of VAT free shopping for tourists; we have not included its reintroduction into our guidance.”
Outlook for the financial year is unchanged, i.e. revenues £1.53 -1.55 billion (about the same as the previous year) with an EBIT margin of 8.7%-8.9% (down from 10.7% the previous year). No change in trading conditions is expected.
Graham’s view
I’ve always found this share quite interesting as a way for investors to participate in the luxury space. The downside, of course, is that it’s just the retail end of the space. There is no brand ownership, only long-standing (and hopefully very secure) relationships with brands.
Rolex, for example, would be worth billions if its shares were listed. But instead it is owned entirely by a private Swiss foundation. And unfortunately for us, it is the brand owner who gets to keep the enormous luxury gross margins, not the poor retailer who takes all of the risk of flogging them to customers.
These shares do offer much better value than they did before:
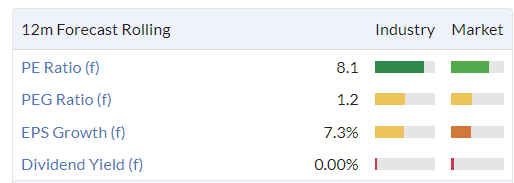
The PER has fluctuated but is sharply down from where it was in recent years:
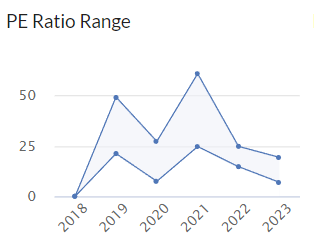
For me, this is in territory where you could argue that it’s a respectable value share, if you’re willing to make some compromises on quality.
Excluding leases, the company last reported net cash of £16m (for October 2023). Lease liabilities were substantial at £460m. For a retailer, the balance sheet didn’t stand out to me as being particularly strong or weak.
Overall I’m leaning towards taking a positive stance on this one, due to the cheap valuation. But this sector (retail) does make me nervous and I’ve learned from experience that we need to be extremely selective. Maybe if we see a nice clean set of full-year results I’ll be able to take a positive view on WOSG.
James Fisher And Sons (LON:FSJ)
Share price: 292p (-13%)
Market cap: £147m
I don’t normally look at this marine services group but thought that the 13% share price drop was worth commenting on.
The last few years have been tough for shareholders here:
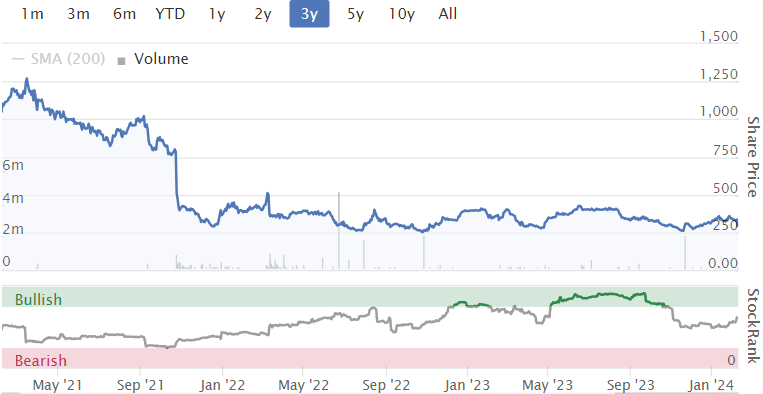
Roland commented on it in September 2022. Profitability had collapsed, the company was showing a high degree of leverage (net debt £172m, or nearly 3x EBITDA), and it had suspended its dividend for the first time in 20 years.
Onto today’s update:
Overall underlying trading in the second half was resilient and in line with market expectations. The Group has continued to make further early progress with its transformation during the period, focusing on operational improvements and simplification.
It’s strange to see a share price fall 13% on an in line update, but the wording of the announcement doesn’t inspire confidence. Why not simply say that trading was in line, instead of “overall underlying trading”?
The next paragraph discloses some good and bad news. Excerpts:
“...North Sea IRM (inspection, repair and maintenance) and decommissioning conditions continued to be challenging.”
“While revenue from larger project orders within Defence was lower than anticipated in the year, as procurement timelines were extended by customers, the division retains a solid pipeline and is still expected to deliver an improved year-on-year performance in 2023…”
If revenue from larger projects was lower than anticipated, then surely this is a miss against forecasts? Even if the revenue will appear in 2024.
Net debt has increased during calendar year 2023, from £133m to £140m. This “reflects the additional financing and restructuring costs incurred in the year”. At least it is lower than the level it reached when Roland was looking at during 2022.
CEO comment:
…I am encouraged by the progress across the three divisions. We are building the foundations for recovery and are seeing the benefits of the operational improvements being implemented. We remain fully committed to our ongoing portfolio simplification, which should further strengthen our balance sheet, as well as the investment in capability that will provide a platform for sustainable growth.
Graham’s view
The company has an impressive heritage dating back to 1847 and is 22% owned by a charitable foundation. But when I look at the directors, I see that most of them have been hired in the last few years (one NED has been there since 2014, another NED since 2018, and the other six are more recent than that). So I’m not sure if the long heritage and the stewardship of a charitable foundation will help very much in 2024.
Overall, I’m not seeing very much to like here. It appears that the company’s ROCE performance wasn’t too bad, prior to 2020, but the company has been loss-making since then. Net debt isn’t coming down very quickly - it actually went up in 2023. On balance, I’m going to have to give this stock the thumbs down
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

172 comments
Jeepers...........what a SCVR today.
Spent most of the day working and then traveling all evening so only took a look at 10pm which is very usual as I spend most of the day normally dipping in & out.
Not sure I learnt a lot today apart from there are a lot of feisty people who probably need to take a breathe and count to 10 before posting.........it's like a school playground fight today. Lost of "he-said, she said etc etc"
Surely we can all relax, chill out and get back to the usual very high standards of this board tomorrow - brilliant insights, great commentary and some seriously great investors sharing their thoughts.
I look forward to tomorrow getting back to normal. Good night all.
Thanks for this post of Simon Thompson's bargain shares. Not sure last year's lot did any good??
Card Factory (LON:CARD) holdings RNS out showing Telios has further reduced by c. 0.7% .
is this what is holding the price back?
Be careful what you wish for...
SCVR is author's space...kind of for them to say what they like and collate the space as they see fit. We don't need to look in...
I find throwing round the term 'bullying' for an area of discussion that is always fraught (see discussions below!) a bit distasteful...and a type of emotional coercion escalation that is an attempt at a winner takes all move in a discussion. We all get triggered at times...and most of the time that is our problem
Todays volume leaders
Just checking in here to let everyone know I’ve bought nothing today & sold nothing either
Very disciplined Rhom.
No stop losses?!
I’ve never indulged in stop losses…they seem illogical if I’ve correctly selected the underlying investment with the intention of holding it forever…other folks do things differently & with considerable success though
Luceco (LON:LUCE) - another good sized PDMR buy.
I am infuriated about Arm Holdings (NSQ:ARM) because I sold my Shares about 2 weeks before the takeover in June 2016 for £10.16 per share because as a Private Investor I did not know they were in Takeover discussions with the Japanese outfit Soft Bank..
I wrote to the Takeover Panel in Feb 2021 and received the usual non reply which I still have.
Imagine you'd sold out of MicroCloud Hologram (NAQ:HOLO) earlier this week. You really would be kicking yourself.
Arm being 90% owned by Softbank is kind of acting like a hedgefund version one of those microcap, low float, often chinese manipulated US listed companies that pop up often.Crazy move and option call sellers got absolutely crushed.Some further OTM calls were up over 2,000%.
If only we could know the future portugall :)
I find it hard to believe Labour’s £28bn green prosperity plan u turn justifies the 12%+ share price fall in Good Energy (LON:GOOD) today.
To my knowledge Labour aren’t reversing the heat pump subsidies currently in place for example, though I believe Good Energy (LON:GOOD) has much more to it than being just a Government green subsidy play.
Nevertheless Good Energy (LON:GOOD) is now back to a £43m market cap with £18m net cash, so EV of £25m. 31 December 2023 forecast PAT of £3.25m is forecast to grow to £4.4m this year.
Forward PE of 15 (ignores cash assets) but PEG of 0.3.
Forecast 31 Dec2023 net assets of £24m (after deducting cash assets) gives a ROCE above 10%.
I think today’s share price fall is an opportunity brought on by traders taking profits, opening shorts and a series of resulting stop losses being hit.
I hold.
I'm still in Eneraqua Technologies (LON:ETP) now there is a perfect example of where i should have used a stop loss. Very dishonest management I feel.
Still hopefully a lot of end of life heating systems in large public buildings will be converted to heat pumps when Labour do get in and I can get my money back.
The problem being, the killer rns looked ok, you only got the real story in the subsequent brokers note....
I agree. But for me the alarm bell at Eneraqua Technologies (LON:ETP) was their reliance on a small number of local council contracts and the fact that the other private sector initiatives (e.g, hotels, local housing, India) never seemed to develop between trading updates. They also used quite a dodgy 'weighted average' order book which, when you looked at the definition, was really just management's guesstimate.
That said, to say they were backward about coming forward when orders dried up would be an understatement
Aren't they only involved like you say with large, public buildings (Council contracts) and the recent news about the end of the fines is for domestic installs?I must admit i bought a few down here but was lucky to buy after the last profit warning unlike with a few others, as i reckoned if they can get things sorted and back on track the previous profits were large compared with current mcap expectations.And the ceo, even if perhaps 'misguided' does own a substantial amount of the shares (around 20% with his wife i'm guessing, Anila Dhanak?). So i can't see him not wanting it to recover.Whether it will in the end.. who knows.He did look exhausted in the last video presentation though.
Hopefully he will be able to turn it round, he did manage to sell £1.7 million at the end of 2022 at £2.90 now that was good timing....... Eneraqua Technologies (LON:ETP)
Sarah Breedon , deputy gov. of the Bank of England lecturing everyone again about pay rises. Meanwhile shes had a £100k pay rise herself when promoted last year.
"For services inflation to fall to levels consistent with target, some combination of a further moderation in labour cost growth and firms’ margins will be needed. ........ Here, monitoring wage growth and how firms pass these onto prices over the next few months will be vital."
Sanderson Design (LON:SDG)
Further to my earlier post I have added to my holding. Had to pay 108p, but a few pence here or there will be inconsequential in a year or two, whichever way the cookie crumbles. To paraphrase Peter Lynch, one shouldn't 'nickel and dime' a stock if one believes you are being offered good value.
Premature or prescient, time will tell.
Anyone watching the US open and seen the reaction to Arm Holdings (NSQ:ARM)'s latest earnings report?Up over 50% and over $100 billion market cap and on some rather silly current p/s ratio too.
Shame the government let the company go and double shame the lse and government never persuaded them to even dual list in London and NYC.I'm sure none of us would say no to a bit more of that kind of liquidity over this side of the pond.
If it was listed on the UK market it would probably be down 10% post earnings ;)
I agree. If you listen to the Investor Chronicle weekly podcast when they covered last year's ARM listing their ignorance and negativity is appalling.
Alpha Financial Markets Consulting (LON:AFM) do a lot of work implementing systems/upgrades for City finance firms/fund managers.
As such I would be a bit wary of projects being put on hold due to the drop in revenues/profits at a lot of these firms at the moment, as discussed here in various SCVR updates. IT costs at these firms have ballooned in the last couple of years, as most software contracts have inflation rate rises built in. So there's a lot of pressure to keep costs down. One way of doing that is to defer any system changes/upgrades and the army of consultants they often require.
James Fisher And Sons (LON:FSJ)
Graham, thank you for covering the update. I agree, lots not to like in this statement.
Certainly high risk. They may declare an 'underlying' profit in line with forecasts but debt has risen YoY which was not the intention? And makes me think that the statutory profit won't be in-line if cash is going out of the door? At the same time the potential level of reward seems to be reduced with each update?
Looks to me that the 'underlying' trading in line sleight of hand is created by 'ceasing operations at Subtech Europe'? £40m of turnover and associated losses become discontinued - and makes room for the once again 'unexpectedly' low contribution from the defence division? Plus the increased costs of finance and restructuring.
Does the sharp fall in share price today indicate that the brokers will be reducing FY24 figures on the back of this update? It seems to be how its done these days?
Disclosure: 'I' still have a very small position I'd forgotten to sell in a 'family' portfolio. I guess I was hoping that things would get better? For the company if not for me. That will get me some grief!
Some here might remember me as a perma-bull of the company? Very much so. I held James Fisher And Sons (LON:FSJ) for 20 years during which the price rose 28 fold from 70p to 2000p. Unfortunately I gave most of that back by not acting on the red flags of growing debt, gross capital misallocation bordering on negligence, but I'll be kind and go with unlucky, falling ROCE and poor management of operations. Big learning lesson. I have a much more focused and selective approach to the management of companies now.
Of course it was all wrapped up in a perfect storm of cyber attack, lock-downs, logistics constraints, oil and gas projects postponed and wars, followed by inflation and rising interest rates. All very clear in hindsight.
But still the good times don't roll? I finally broke and ran in early 2023 when management sold the nuclear businesses to a VC for £3 - plus a ?£3m? loan but did not get a waiver from their finance consortium. Which goes part way to explain the 'increased costs' of the refinancing? At the same time they retained certain parent company guarantees against customer contracts! Three months later the VC closed the doors. I imagine those PCG's are now being negotiated? I'm still shocked at this behaviour. Not at all the way the heritage of the company is implied?
At the same time I discovered that key management for the submarine rescue team at Defence - once the crown jewel - had left and joined ( by management buy in) a competitor. It's no surprise that major projects at defence are still being delayed? I regard the devision as gutted. Which builds on key teams leaving other businesses. Something of an exodus?
I have an aversion to this style of management - so selling even at such a low value relative to the peak was a no-brainer, if painful. And a real learning lesson for me. Sadly its not the company it was and the potential of the turnaround now looks substantially lower to me than it did a couple of years ago?
The fall in debt over the last couple of years is entirely due to the disposal of assets and a couple of non-core businesses. The gradually reducing number of continuing operations have not been able to pay down debt, and with debt still rising the company will struggle to provide sufficient growth capital to the business it still retains with good prospects? Further constraining the turnaround?
Clearly I'm biased. So take my pessimism with a pinch of salt by all means - the key point is that the business has been transformed, but not in a good way, and in my view there is very limited potential to return to the kind of margins and profits the company enjoyed a few years ago? I hope the company prospers, but its uninvestable for me at the moment.
cheers
Mark
FSJ BUZZ-UK: "James Fisher and Sons falls on revenue weakness in defence division"
How can their defence division be weak? BA has been minting it the last 2 years. Oh well.
Its avg ROCE over 5 years was 4.5% and has an interest cover of 1.5. I'm using the analyst 2023 estimates of net profit of 1£0m. Trailing net debt was £204m. Way too much debt and weak profitability. It's not the sort of company I'd be interested in as a long-term buy and hold.
Worrying signs for the housing market:
Latest UK Finance figs. Number of people in arrears on their mortgage increased by 5,750 in the final three months of 2023. Total now 93,680 – up 25% over the past year. Buy-to-let mortgage arrears up by 124% year on year. Except these numbers to keep rising say AJ Bell. @MerrynSW on X
EParo sorry to disagree but....
These numbers on mortgage arrears look very encouraging to me. Hard on those poor souls impacted by the massive cost increase in their mortgages but the percentage is irrelevant and just gives our mathematically incompetent media and commentators click bait.
If we have less than 100,000 mortgage payers in arrears out of 8 million or so mortgage payers (from memory) that seems quite a benign level to me.
No sympathy for BTL sector. Just sell your property if you can't make it pay. Let's have houses for living in first and foremost.
Housing market unlikely to be concerned by these levels of arrears imo. With the first cut in interest rates I'd expect to see 10-20% jump in housebuilders and supporting industries within the week.
Timing? Well that's another matter. Would expect US to cut in June at the latest. We might see first move in March but I think those hoping for this are being too optimistic.
Each to their own. You may be right but there are bigger things to worry about on the war fronts at the moment.
Kitwave (LON:KITW) emerging from the doldrums - wonder if there will be a trading update soon (edit: ah just noticed FY23 earnings are scheduled for 26/02)
Kitwave (LON:KITW)
Hi Plinkut, another share, where I have a smallish position with my interest piqued by comments from Stephen English in his interview with Paul Hill. Very much a buy and build strategy using existing cash flow as opposed to raising equity, which I like. Much the same as Bloomsbury Publishing (LON:BMY) and Belvoir (LON:BLV) (shortly to be merged with Property Franchise (LON:TPFG) ., all of which I also hold
Kitwave (LON:KITW) is a business that is easy to understand and is founder lead, albeit Paul Young is to retire shortly, but currently retains a substantial shareholding, 15% from memory. The CEO in waiting is the present Chief Operating Officer, Ben Maxted who has been with the company for sometime. The shares are inexpensive as with many good quality UK small caps and also pay a good dividend of around 4%. Lots to like in my view.
Kitwave (LON:KITW) also took a small position on the weakness last year, Agree with the above, this is a nice buy-and-build strategy, where they can pick up smaller peers cheaply and then drive synergies through economies of scale. Very fragmented industry so lots of opportunities. Works well where you know a niche industry inside-out, which Kitwave clearly do. Not been a trading update for a while and mindful we've had a few profit warnings recently in the retail sector, but I think Kitwave should be fairly insulated from any consumer slowdown.
Hi Bouden54
Kitwave (LON:KITW)
There are many non-specific unknowns, but have been wandering how the company has coped with the vagaries of the weather, which in general has been fairly grim of late. No doubt we shall soon find out.
Kitwave (LON:KITW) Cheers both, I’ve held since last year for the same good reasons you list. Let's see how it goes.
Sanderson Design (LON:SDG)
17% fall looks like bordering on overdone to me despite all the caveats regarding future trading and licensing income. Current PE 8.5ish, priced at 0.9 times NAV, with £16.2m cash on the balance sheet which equates to around 18% of market cap.
At some point sales from the brands and fabric/wall paper will improve. The William Morris and Arthur Sanderson archives held by the company are irreplaceable. Sanderson Design (LON:SDG looks like a prime bid target at these levels in my opinion
I have a small holding and am tempted to add but will continue to monitor the share price and wait to see if a better entry point appears.
JONNO
SDG -
I think there is a lot of nonsense being talked about lumpy license income.
Historically yes but commercially it just doesn't work like that any more .
A good friend of mine manages the IP for Conan Doyle estate and in recent years the change has been marked in that licensees now understand the value and this is an expanding market for any company owning a strong historic brand .
The William Morris archive in particular is a very valuable asset.
I did ask Lisa Montague directly about the comments about lumpiness in license revenue and she was extremely confident that this was a growing and super strong income stream with no chance of taking a backward step .
With a focus on the license and a break even on the manufacturing I think thats where they will end up . But you do need the manufacturing side to add value to the license side .
The key here is to run the winners which is
- focus expand and develop relationships on the license side
- run a tight lean ship on production that adds value to the above .
I topped up a few today at 107, probably should have gone harder but it could go sideways for a while.
Sanderson Design (LON:SDG)
I dont think licence income has to be too lumpy to be potentially lumpy if i am being honest - licences will start and end and there may be accelrated income or not in a particualr year. So although it may be reasonably consistent and the trend may be clear and reaosnably long term i wouldnt expect progression each year not to be somewhat lumpy - so if we have a large jump forward as we had year just finished - i would be somehwat surprised if we beat that number easily ( or at all) this year - even if the overall trend is clearly in the right direction. I do take it a positive if Lisa is positive as she certainly knows more than my uneducated twaddle.
Sanderson Design (LON:SDG)
personally i have taken comfort from the comments made by Paul - reading the update i was expecting a higher downward revision from the brokers ref the new year. so broadly similar or the same as year just finished at pre tax level is fine starting point from me. again lack of direct clarity from the company probably causes the crash in price , if not everyone has instant acces to broker notes - if they expect to match year just finished numbers this year and have given that nod to the broker then ensure its crytsal clear you dont expect profits to be moving backwards in release today - so i suspect the tone has done the damage. Note the market reaction might be right anyway - if its a toss up between saying we will meey expectations and we may fall short and they have gone with glass full - perhaps the market has realised this may be a stretch - i see it as a stretch from where we are and i see the excuse has already been written for later in the year - being "overall results were satisfactory but licences income did not match last years exceptional results" we are confident about long term licence propsects.
Had these on my watchlist for a while and had been waiting to add, however, the below concerned me
"certain cost pressures are expected, including the increase in the Real Living Wage and
property-related costs, such that profitability in the current financial year
is expected to be similar to that of the year ended 31 January 2024."
Certainly could be a case of management sandbagging a touch, but to me reads almost like there are a lot of headwinds and the year will barely/just about mirror that of previous.
Interesting article about funds flows - helps explain why the UK markets continue to underperform - https://www.reuters.com/world/...
Nobody cares if your stops are being hit, or whether people are buying this or that share! It adds nothing of any value to the discussion, and wastes the time of thousands of readers, who have to scroll through clutter. Please can we avoid posting, unless it's adding something useful to the discussion about particular companies. Thanks, Paul.
With respect Paul, I very much do care who is buying this or that. It doesnt mean that i have to or are going to copy them, in fact usually very much the opposite, however a couple of my best investments in the last few years have come from stocks that I was not immediately aware of but have picked up from these pages and done a bit of digging and taken a position. IMHO there are some very astute investors in this community and if they are willing to share with me what they are buying or researching I am more than grateful.
I am going to chuck my two pennyworth in here.
I find Paul's bullying - this is the fourth instance I can recall - totally unacceptable and distasteful. Unlike the poster above, I do not find bullying worthy of any respect at all. You occupy a unique position on this Board Paul, but let us be clear, we are all paying subscribers and I guess you do not do the job from the goodness of your heart. Personally I expect a less confrontational approach and more carefully chosen words from someone in a position of responsibility in Stockopedia and presumably someone who is paid by Stockopedia.
TBH it’s a fairly good opinion , although I didn’t see it as bullying. Paul’s entitled to his opinion too.
Of course he is, but his comment directly abused a fellow subscriber. In my world, we call that bullying and the organisations I have worked for would deal with that robustly in this day and age. I have fired senior managers for bullying. It is simply not acceptable and is even worse when coming from an individual in a position of responsibility. Period.
Hi James. For avoidance of doubt I red flagged you. I gave misinformation as the reason as this discussion place has got nothing to do with your work and your penchant for firing people you don't like
I don't see why you should dictate your personal preferences to all of us. And you are not the manager of this space...definitely not the author.
sorry but the due care staff need to provide to other employees is not the same due care peeps need to show when posting random crapola on random internet boards.
Of course no one thinks bullying should be tolerated. But I think it is going much too far to describe Paul's words as bullying or abuse. I agree with Paul that what we want to hear about is WHY people think a particular share should be bought or sold, rather than just the fact that they have bought or sold it.
Has a point but nothing wrong with manners and point could have been better said to a subcriber, all human and everyone snaps now and again. Bought a small amount of Card Factory (LON:CARD) , PE just looks cheap.
Yes I see where you are coming from. It would probably have been better for Paul not to address the post to any particular subscriber. And then Paul could have avoided the ridiculous accusation of bullying.
Personally i fail to see how Paul's comments today can be described as bullying - hey ho thats the wanders of "posts" on the internet stuff can get blown out of all proportion to the issue at hand or perhaps even turned into something they arent by others - no offence meant with your post jamesalastair - you obviously are fully entitled to your viewpoint here - that is the wander of these forums we all have a voice when we need to unless .......
Thank you to Ken Mitchell
Ken, appreciate that I do not always have time to post, but your input around higher yielding and income trusts with good yields has been much appreciated.
Whilst I look after various parts of the family's money, from the ages of 8 years old to 83 years young, the 83 years young income portfolio is certainly starting to look better now that I know about the AIC site and also just starting to be more confident around understanding values against book and potential incomes coming from more out of favour sectors.
I appreciate that to others growth is a better long term outcome, and that might be true and there are parts of Mum's portfolio designed to do that, things like Twentyfour Select Monthly Income Fund (LON:SMIF) to give a steady monthly income to top up the state pension are a lifesaver, and slowly trying to find new homes for things that have now gone from the market like EPIC.
Cheers
Tommy
Interesting that others hold Twentyfour Select Monthly Income Fund (LON:SMIF) SMIF. It is a long term holding of mine and as discussed has produced a decent income.
I think that I have a small capital loss of about 3% but this has to be judged against the income yield over the years.
For anyone new to investing reading this thread - Twentyfour Select Monthly Income Fund (LON:SMIF) SMIF is not an entirely straightforward investment with guaranteed liquidity. The Key Investor Document rates it a 4 and does warn that "You are about to purchase a product that is not simple and may be difficult to understand."
Nobody cares if your stops are being hit , or whether people are buying this or that………….
Ok shall we speak about the weather then?
Yes, there is sleet outside the window :) and my daughter is at a day long football competition in York and of course refused to take her coat or dry-robe this morning, still in the back of the car not that I can see that through the window! No doubt I will be in the wrong with MrsH later on, and my daughter if the team did pants or she froze or she cannot go to the County swimming at Leeds on Sunday morning.
Actually the snow is not settling, both the girls will be grumpy!
I have bought some things today with some of the cash that was sitting earning pittance in the account high income plays, small stakes and slightly skewing the portfolio concentration within some sectors. I have sold nothing, and need to update the spreadsheet tonight to figure out mum's projected income for this year, and what she can afford to give away to the grand-kids unless she wants a big holiday.
Enjoy Yiannos1
Tommy
Perhaps a little terse. However if there is a post it would be nice if all of
1. What the share is
2. What facts concern you
3. Why you think those facts are worthy of comment
Was in the post. On that standard both this post and the parent deserve some disapproval.
To disagree I understand , but to dictate what can be written it’s too much.
Personally I have enjoyed planetx post this morning about what he is buying/selling/holding.
Thanks
But you learn nothing from a post that simply states 'sold on a stop loss'. What % stop loss? Was it a trailing SL? Was it sold on a profit or a loss? What was purchase price? Have the fundementals changed? Why did you have a SL? Etc etc. I'm with Paul - add more meat to the post or it is a pointless post and unnecessary clutter.
Fair enough and that’s your opinion- but I found out that there were some stop losses on Good Energy (LON:GOOD) today and after making some further inquiries/phone calls I have a clear view on what happened today to the SP.
Believe me the stop losses were massive and they were not the losses of the person of the original post!
And this is because of a post that you think is pointless.
Nothing is pointless here-disagree with a post and disagree strong enough , but please do not dictate what should be written.
Well thats even more mysterious! whose stop loss got triggered and why? come on Yiannos spill the beans, share the wealth and tell us the full picture on Good Energy (LON:GOOD) . I'm a holder and would appreciate the insight! Is this a top up opportunity?
I hold as well Good Energy (LON:GOOD) with an average price of 350p!
Obviously I do not know whose stop loss was triggered-seems that many investors invested on margin.
I am afraid you have to do your own research and decide what to do with your own money.
All the best
Hi Yiannos, would you be willing to share your clear view on what has happened to the SP? As a holder who is down nearly 15% on what appears to be no news, I would be interested to hear, any additional info in valuable to help inform next steps. Cheers. Ben
yiannos1 The posts informing of sales on a SL were on the board by 10.47, the SP had by then dropped by just under 10% from 299 to c. 270 - I would suggest a drop of that magnitude will always trigger numerous SLs. Would you not have investigated further whether or not the relevant posts appeared on this board? If not, why not?
Would you be so kind as to help improve my (and others) investment skills and shed a little more light on your findings - I for one would be most interested to find out which large sales were SL sales and just how it is possible to ascertain that they are SL sales rather than normal market trading.
A big drop (or a big rise) accompanied by continuously changing prices in a stock means that stop losses are triggered( can easily be observed in small caps).
When Good Energy (LON:GOOD) hit the 270-260p mark then their was a change in the bid/ask price literally 2/3 times in a second. That’s when margins/stop losses are hit and market makers and their systems are not sure where the bid/ask should be. Good Energy (LON:GOOD) SP does not change like that in a day!
yiannos
Your a hard man to please sometimes so ill take that as a compliment
I ended up selling everything listed but bought a bit of SDG and Pennant .
Was meant to sell a few Pennant but at 29.4 buy price lost my senses and bought instead of selling got a bit carried away and more cash tied up in an illiquid micro cap. May regret it later if get stuck in another value trap mess like Holders turned out to be
Think Pennant is interesting as the sector is hot , need to really get to know what is going on there as haven't quite got into the weeds yet ,
Selling everything listed is not a bad idea!
Taking a break from the market for a couple of months and just keep researching is the best investment you can make.
I wonder sometimes when the US corrects what’s going to happen here-cause it will correct at some point (maybe after the elections-who knows).
Pennant International (LON:PEN) is very illiquid for me. Sanderson Design (LON:SDG) I have never invested in it and I do not think I will ever do (no particular reason).
My current UK holdings are Nanoco (LON:NANO) (17.5p) Good Energy (LON:GOOD)(350p!!) Trustpilot (LON:TRST) (120p) Kier(127p) (LON:KIE) Cornerstone FS (19p) (LON:CSFS) and Afentra (LON:AET) (33p) Revolution Beauty (LON:REVB) (31p).
I hold some other stocks but they are positions that are just profit ;the likes of McBride (LON:MCB) and Bank of Cyprus Holdings (LON:BOCH) .
All the best
Good Energy (LON:GOOD) down to 280p now in as many days
tempted to open a position
So, what do I know! But ignorance never stops me...
It feels a bit febrile in here recently. People desperate to chase some winners. A bear gloom subsided in Q4 2023 and some things bounced hard...and everyone wants a piece.
If you are a trader and work on short time frames then chase well my friends....the ones that do it well won't follow the news and views of others but have their own process, triggers and psychological conditioning. If you ain't doing this then don't play in this game as your main function in the ecosystem is to feed the returns of those that do it well.
If you are longer horizon and 'fundamental' still don't be a follower of tips and hot speak. There's a lot of it. Lots of great stories with sharp price moves to 'prove it'...new stock picking gurus to follow looking for some of their luck. Do your own work...find your own vibe (lots that are viable)...understand why you hold the stock...think about how you handle negative price action (it can happen to what turn out to be good companies). I'm not a fan of stop loss if you are 'fundamental' as imo that means you've not done work on understanding well enough (and getting your entry perfect is hard...if you are fundy not trader). If you ain't doing the work and detailed imagining on a stock then again your role in the ecosystem is to feed people that have and are ramping their own stuff...or even darker, feeding the people that will short the spike (I'd guess that some of the highest profile stock tippers on social media put a bit of short on once they know the momentum has broken...maybe with their nudge...think dark when money is involved)
If market and economy move from funk to boom over coming months...well then all approaches will work and all boats will float. But if its more variable or halting than that then the ebb and flow of prices can get vicious. TBC I'm not bearish (and I wasn't last year...nor negative on US economy etc in 2022) and I think we will likely move into a fairly long-ish recovery phase post what has been a rather long depressive phase...but not everything goes up (and this may be particularly true in a world where there is a higher cost to capital with interest rates higher)
Obvs I'm a killjoy ;) Ignore the pesky contrarian...it'll be alright...honest...
Happy hunting
Best wishes, your mojo x
It was always the case that followed commentators would impact on price movements but the lack of liquidity seems to be exacerbating the problem at the moment. Both Good Energy (LON:GOOD) and Avon Protection (LON:AVON) appear to be examples that had a lot of hot money heading into them. It was why I was very reluctant to chase either. Sell the news is prevalent too. It used to only be penny shares that had such volatility but we’ve got to a point where even 350 stocks are finding the same problem. Ie most of the trading is retail so relatively small size is moving markets out of proportion.
I think the thing worth noting in todays conditions is that if stocks are being talked about persistently then the likelihood is that spike will fade. So whilst these companies may have good futures I find it beneficial to curb my fomo, bite my lip and bide my time.
The other thing I find helpful is to understand where commentators are long. For example CR has been extolling the virtues of Avon Protection (LON:AVON) on X and sub stack for some time, even above 1000p the positivity kept coming. But remember he is long at around 600p so has a vast buffer : he might believe the stock is going to 2000p but his risk/reward is very different to yours buying at 1000p. So try and read these things in context.
You are absolutely correct David and it seems that many still use high leverage!
I shall add it to the list of wisdom found on these boards:
I'm not interested in price or performance reporting by anyone unless its an audited return. There is only screwed up emotions in following that sort of stuff imo...I'm going to be better and worse than everyone in here at some point in time, when its not my time there's no point me trying to transition into being David Hill etc...my long term return is decent but it makes no sense to compare to others running a different sort of race from me. Why would I take a decision anchored off what other people (honest guv) say they did?
I'm only interested in what they have to say (...or don't say) about a company. What's the angle and info? Some commentators do that really well (see Paul and Graham...I don't agree with them all the time and they are very different from me) but I think most with profile with PIs (inc newspaper tipsters) are punting varying shades of FOMO to be consumed by the gullible and fomo side we all have and little actual substance. If you are talking bowls etc or trying to fade Simon Thompson's next tip...then I think you are probably gambling. By all means tell yourself you are clever enough fade the players and markets....
Liquidity and market conditions...plus ça change plus c'est la même chose ...there's generally not a story nor excuse in this stuff
Not entirely sure what you are inferring Mojo re comment about not transitioning into me. I’d prefer you didn’t.
My point was exactly that - when someone talks about a stock their comments and expectations are almost always coloured by where they bought said stock. So you have to assume that their risk/reward is not the same as your own - thus it is very important as an investor, at least in my view, to try and shut out the FOMO and do your own research that isn’t anchored against someone else’s risk/reward that you have no real idea about. Given the illiquid market conditions volatility on relatively low volume extends far up the market cap range in the UK. That means popular commentators have an outsized effect on prices unfortunately and in my experience people can get sucked into that rally without necessarily realising that said commentator is already sitting on sizeable profits.
All I mean is I can't be you...and there's no point me worrying about it.
Personally I try very hard not to think about how much I have or don't have in the bank with a stock. I'm not a trader and tend to be a long term and high risk investor compared to most. Plus a bit contrarian...though I try to suppress that from being too strong.
More generally and not directed to you tbc and just a general zeitgeist perspective: I'm bemused/befuddled by the idea we shouldn't invest in small caps that are volatile and may fall in price due to blah blah blah factor...that sounds like opportunity to me. Just scale and judge appropriately. Now if you gonna trade and chase short term pops and plunges then that might be different
Obvs the US has been fabulous and everything looks rubbish by comparison. Same Japan in 1989. and Brazil 2010 looked like a miracle outside of world's woes...
IMO the massive stack of historical evidence says don't chase the narrative too hard
Ah Ok - understood and completely agree Mojo.
I think the not chasing narrative applies at both a macro and stock specific level, particularly if you are an investor. As you say a trader may trade the trends they identify but that’s a very different discipline and requires strong risk management, particularly if using leverage. The 70% loss ratio on spread betting accounts suggests that’s a skill too many traders don’t really have either.
Completely agree David. No need to be chasing small caps in particular, unless its something with knockout growth potential. Sentiment changes so quickly, 2 years of grinding bear market has understandably made people jittery so moves are exaggerated.
Can afford to wait for a pullback and then take a position. All it would take is a 3-5% selloff in the US markets and some of these smallcaps will give back 20% or so.
Avon Protection (LON:AVON)
RNS - Capital Markets Day today (announced some time back), starting 14:00, recording will be available. Targets:
'No new information on trading will be shared at the event.'
I had been expecting another trading update to put a boost under the CMD. I don't find those targets very enticing. But it may still be a takeover target despite rising nearly 50% since last October (down 16% in the last 5 trading days). I sold into the recent spike, now watching and wondering what would be a good price to buy again. I'm very cautious.
EDIT: Is 5% Revenue CAGR growth enough to sustain these metrics? I think not.
For me that is a bit simplistic. A mid teen op margin is probably more important. It takes them back to margins pre covid where profit was significantly higher.
Margin on its own is not enough. If they want to stay listed in the UK there has to be growth to sustain a P/E much above 10. Last trade at 831, HL quoting 806-828 as I type. I think the market agrees with me.
Michael apologies I bruised your ego there and I didn't intend to. I think what I meant was that to draw a conclusion from CAGR of 5% is not enough. Neither is an operating margin. But the two together with a number of other factors don't lead me to the same conclusion as you. Hey its a market. I think we both know that recent movement probably doesn't reflect either of our views, that is the market. Sometimes with these posts I can be a bit bang rather than oo er so again my apologies.
Avon Protection (LON:AVON) I spent the afternoon on the capital markets webcast and was quite impressed. I think when they get margins up and ROIC to 17% this could be a very high quality business with significant recurring revenues.
I was very impressed by the moat, the leadership (experienced, intelligent fanatics with big shareholding’s), the product development paths that are open (some R&D will be customer funded!) and the fact that since Jos Slater and Rich Cashin arrived they have replaced 40% of the top 150 leaders in the business to drive significant culture change and a winning approach. Previous management must have been completely asleep at the wheel on how to run productive factories with continuous improvement.
However, having blurted all that out, I can’t determine whether it is cheap enough to buy at the moment or whether it might take off now…
On reflection, they are a year or so into a 2-3 year plan so there is time to watch for progress. I would say that Jos and Rich are not the kind to take prisoners if the ball gets dropped, operationally speaking of course, performance will be improved -end of!!
@ Paul, the rise in British American Tobacco (LON:BATS) is partly due to their announcement that they are looking to "monise" (ie, 'sell') some of their shareholding in India's ITC.
ITC are an Indian consumer goods giant that makes a large portion of its revenue from cigarettes but also operates hotels, a paper business and more. BATS hold approximately 30% of ITC and it's worth c£15 billion.
D S Smith are we going to get a offer? I hold
All packaging companies up this morning so don't think anything specific to DS Smith or likelihood of any offers.
Mondi potentially readying an offer
Or more specifically an “all share combination”. Presumably the messaging will be that given DS Smith shareholders get to share in the synergy upside of the combined group there is no need for a stonking control premium. This, the lack of a cash element, and the fact that there is no formal offer yet explains the rather muted jump in the shares
DS Smith (LON:SMDS) or by announcing they might be trying to flush out other possible interest that want a slice of the pie given that Smurfit Kappa (LON:SKG) merger with WestRock is going to happen?
Nexteq (LON:NXQ) (I hold) up around 9% this morning on no news. Could this be because of rise in Chinese markets?
There's a couple of broker notes out this morning on Nexteq (LON:NXQ) that's probably the cause
hi Revs8
Nexteq (LON:NXQ)
Likely cause is two broker notes released today on Research Tree (Cavendish and Canaccord Genuity) following ICE trade show this week.
Snazzy
Thanks. Good info.
Hs anyone got any thoughts on the rise and fall this morning of Sondrel (Holdings) (LON:SND) which I hold. There was a mention of it being connected with Musk and AI in yeserday's Mailonline. Wish I'd bought more.
see mid-morning movers section above, just below main agenda, I've commented on Sondrel (Holdings) (LON:SND)
Home affairs correspondent pumping Sondrel (Holdings) (LON:SND)
Just when you think youve think you've seen it all!
"Im sorry Mr Tingle, I dont give a monkeys about your reputation. Get this written up or youll spend the rest of your career making coffee for They/Them at the Huffington Post" ;-)
Good old rumour mill still working a treat.Better liquidity for the company now though.
China inflation figures worse than forecast. Interestingly food prices declining at a record pace (-5.9% vs -3.7% in December)
Could China end up with deflation, resulting in lower prices for their exports and helping to reduce inflation in the West?
Conversely increased price pressure on competing products manufactured in the West?
Good Energy (LON:GOOD) still tumbling, anyone wuthering a valid reason why?
With sorry typo
Hi JohnDoe2378 & everyone,
You can edit any post within an hour, by clicking on the fat pencil icon.
So there's no need for additional posts to correct anything, just edit it instead! Helps avoid clutter.
Thanks, Paul.
Editing: The pencil is there for an hour when you're on a computer, but not if you're on a phone (mine, anyway). If anyone knows a way to edit a post when you're on a phone, I'd be glad to hear.
Indie - change view (in browser) to desktop view and it appears - well it does on my pretty standard Android phone. Hope that helps.
Thanks for taking the time for that advice, Lincs. Sadly, didn't work with my (Apple) phone, but I'm sure you've helped many.
I accidentally found the fix yesterday Indie... I'm using an iPhone and found that if you turn your phone horizontally the edit button appears once the screen has adjusted for the move.
Thanks, but I've tried that before and it doesn't work either for me. Might try the green button to see if there's a minimum spec, or if there's anything I can do to unlock these wonders!
In case anyone's wondering about why the Edit pencil appears with some phones in landscape but not all, I had the following reply from the green button:
Having investigated this, the edit icon will appear at resolutions greater than 768 pixels wide. This works for a large number of mobiles (in Landscape) however unfortunately your iPhone SE has maximum dimensions of 667 pixels, so it doesn't appear.
the edit icon will appear at resolutions greater than 768 pixels wide
your iPhone SE has maximum dimensions of 667 pixels,
ouchies - sounds like some iphone hater has selected a limit to deliberately wind up iphone users !!!!
Please tell me there is a logical innocent explanation here ref cutoff point.
I happen to have an iPhone, but it’s a size limitation that would apply to all phones
I missed out on Yu (LON:YU.) and the recent rally for Good Energy (LON:GOOD. Bought into OPG Power Ventures (LON:OPG) hoping for a repeat of Yu. Its got a good spread for a small cap, and with a bit of luck profit takers from the other two may rotate in to this one, which to me, looks very similar- same sector at least.
Good Energy (LON:GOOD) :Stop loss triggered. Sold on sentiment.
Yep, my stop also hit!
Nobody cares if your stops are being hit, or whether people are buying this or that share! It adds nothing of any value to the discussion, and wastes the time of thousands of readers, who have to scroll through clutter. Please can we avoid posting, unless it's adding something useful to the discussion about particular companies. Thanks, Paul.
Nobody cares if your stops are being hit, or whether people are buying this or that share! It adds nothing of any value to the discussion, and wastes the time of thousands of readers, who have to scroll through clutter. Please can we avoid posting, unless it's adding something useful to the discussion about particular companies. Thanks, Paul.
Amen. I should also add that I find it disrespectful to the efforts of Pau & Graham, but they are unlikely to say that. If you want the world to know the minutiae of your every act, there are a myriad of social media channels, or you can start your own blog instead of boring everyone here.
There have been a number of recent articles on the subject of momentum. Since the sp of Good Energy (LON:GOOD) has reversed and is now close to its 120 day MA I would have thought this was noteworthy.
Hi SC120
Yes it was noteworthy and thanks for that.
Lots of empty spaces at EV charging points?
Labour are supposed to be moving away today from their £28 billion a year pledge for green energy projects and there seems generally to be a move away from 'good' energy back towards 'bad energy, in the short term at least.
Headlines can be misleading I think, they are still moving forward to the green transition with aplum. They just realised they don't need to spend £28 billion to do it.
You are also misleading NewInvestor1972r. I think rogerh was nearer the mark.
Listening to R4 today and from a Labour spokesman, Labour are NOT moving forward on their green agenda (certainly not with a plum < aplomb>) nor is it correct to say that they 'realised they don't need to spend £28bn'.
They DO need to spend that amount and probably more but simply don't have the money to do it, or, if they do then would need to cut welfare and all sort of budgets which would not be politically expedient (in the light of the forthcoming elections). To decarbonise homes alone would exceed that sort of figure.
So it has become much lower key in their manifesto, although they may well be pursuing parts of this agenda but in conjunction with private finance - but, as was also stated, private finance has been woefully inadequate; they don't say how they would change that situation. I got seduced in investing in Good Energy 'green' energy, but already regretting it. Could be some years before this sector becomes investable (for PIs, or at least for me)
Good to see you posting here dartagnan, but a shame it includes your disappointment at the big fall in the Good Energy (LON:GOOD) share price today on top of big falls from that £4.20 peak before today. I hold too and have now lost nearly all my paper profits despite top slicing and a couple of successes with a trading stake. The falls today have possibly been made worse because of Labour’s cancellation of the £28 billion for green investing.
Hope it wasn’t any of my posts that helped tempt you to buy GOOD. It’s not helped by GOOD having been tipped too much, including here, Naked Trader (£5 target) and Small Company Sharewatch. Has that tempted in too many fickle small investors and hence as they trade in and out, those big share price swings.
It might need a reassuring update to reverse the recent big share price fall. There’s also the risk that it might not be just fickle small investors, but bad news leaking. Hope that’s not the reason!
Finally I’ve pasted below a post I did on a GOOD thread last November as a reminder of why Good Energy (LON:GOOD) looked so tempting. IF those profit forecasts are still realistic then the share price could go up as fast as it has gone down. Hope it’s not too much longer before GOOD update.
Here’s that paste. The “it’s partly” bit at the start is the ten fast rising share price:-
“It’s partly because of Good Energy (LON:GOOD) being highlighted in the October edition of Small Company Sharewatch who pointed out that Investec are forecasting their profits to double every year for the next 3 years.
I.e £2.3 million this year, to £4.2 million, £7.4 million and then £15 million and eps going from 18.3p end 2024 to 69.2p by end 2026. And recently Good Energy (LON:GOOD) issued a better than expected update which has put a further booster under the share price.
So no wonder the share price has rocketed to over £4. It looks overbought short term but if those targets are realistic there’s a lot further to go, so fingers crossed on that as I hold too.”
kenmitch -Not wishing to clutter up the Board here, hope people dont mind but just wanted to acknowledge ken's post; good to meet again ken, I've seen your various posts here, brilliant as ever in particular Investment Trusts. I think people here are enjoying your posts, and valuing them - I would wholeheartedly echo that.
On Good Energy like yiannos who holds from 350p average, I'm not far off that with a 25% loss currently. Hopefully the share has found its nadir and will recover somewhat, but in view of my earlier comments on future public/private investment in green energy it's too volatile a market for me at the moment, I'll likely ditch GOOD if a sensible level is reached (or if it goes down further!)
Best wishes
Thanks dartagnan but I’m sorry to read of your Good Energy (LON:GOOD) loss. A new lesson leaned for me is to realise that when a small share like GOOD gets tipped and hyped sometimes multiple times, the result is likely to be too many fickle small investors having far too big an influence on the share price as they buy in droves then and sell in droves.
What to do now?
I prefer selling for investment reasons when the investment case changes for the worse. E.g as soon as there is a poor update or profits warning. So I’ll probably hold until GOOD next update. Also once we’ve luckily reached the stage of having a portfolio that has long been profitable we can afford the occasional disaster. I don’t think that will happen with GOOD. Their most recent update was an above expectations one.
The additional big share price fall yesterday was probably because of Labour’s cancellation of their £28 billion green policy. And anticipation of that before yesterday could explain daily falls recently. With luck a lot of the “hot”money is out for good now if a lot have lost heavily.
Until GOOD update I’ll just remind myself why I invested. E.g those doubled profits every year forecasts.And what they do. It sounds convincing enough to me. Green energy might be slowed but it isn’t going away surely?
Below are two reminders. What they are AND the text of the November trading update, The sooner we get the nxt one the better!
Good Energy (LON:GOOD)
I know nowt about tis company but did have some initial questioons after my very lazy 2 minute research effort , i posted on another thread but got no reponse - would be grateful if anyone can advise if this company does have decent moat and is not over reliant on peeps wanting to pay over the odds fro clean energy ?
my random thoughts/questions
Ref Good energy would I be correct in presuming that they rely on the largesse of customers to pay above cap prices (voluntarily) so they can be seen to be getting top banana green credentials? If this is the case I would massively worry that if we were to get glut of cheap energy deals could that not put them in a position where they couldn’t cope if the price differential was too much? At present it all seems like a closed ship cartel with limited supply at too whack prices - at some stage though I would expect more options for customers and better deals to come to market ? When that would be I know not. Another worry would be that now green is big and established enough any positive subsidies would start to be removed as the main job over getting green to be the majority player in town is done.
Are holders happy this company can compete on open fair and free of subsidies and box ticking world?
I think they're moving away from just supplying energy to be more of a green energy services company i.e. installing and maintaining solar panel and ground/air source heat pumps. They're aiming for the 'whole house' solution market where these also connect up to the customers EV and perhaps sell excess back to the grid. It's a long term growth market but how quickly it will all happen is the name of the game.
Sanderson Design (LON:SDG) fall on solid results looks a good opportunity to me (I hold) and a play on an improving housing market (house transactions currently c30% down). On the assumption that a lot of their business is driven by consumers redecorating after a house purchase then the market will improve going forward. Throw in increasing recurring profits from royalties and US expansion and this looks all lined up to be taken out. Just got to be patient!
Sanderson Design (LON:SDG)
I think you're right about being patient. I need to do more research - so keen for others views here - but I understand that licensing was not a huge feature of their business model pre-pandemic, rather it's something Lisa Montague has identified as being a real area for growth given the opportunity in that space + margins. They were profitable pre-pandemic (circa 5% net margin) so could you assume that, should demand/spend return to the established UK business, you'll have a decently profitable business with the licensing income providing a healthy boost (and significant) boost to profitability?
I take the point that licensing is potentially more one-off in nature so keeping up momentum and being on top of the sales pipeline is key.
ME International (LON:MEGP) has shot up over 5% today on no news
ME International (LON:MEGP) chart showing very clear bottom and probable end to wave 4. I’ve been building a position (and saying a bottom is forming) for a few weeks. Breakout above 130p has immediate price target of 145p based on chart. However, I don’t buy simply based on charts, brokers saying ME International (LON:MEGP) very cheap so (if this is the end of this wave of selling) then I’m expecting price to go to 200p in longer term.
In haste but note that Riverstone Energy (LON:RSE) (I hold but didn’t include in the post yesterday) has today announced a tender offer at £10.50 for about 36% of the shares. Share price is up £1.08p to £9.10 (still well below tender offer price). NAV at end Dec 2023 was £12.53. So previous mvery wide discount has narrowed to around 25% today.
Details and portfolio details and valuations here:-
https://www.stockopedia.com/sh...
I am also a fan of Riverstone Energy (LON:RSE) having invested a couple of years ago. They've managed some of their investments well and have bought back an awful lot of shares with spare capital. The fact that they can now tender for around 1/3 of the outstanding share count is remarkable.
The question now is whether to stick or twist!
Well done Paul & Graham for highlighting CMC Markets (LON:CMCX) in your 2024 picks.
RBC raises target price to 190p from 150p.
Peel Hunt 200p tp.
Metrics look good post recent update.
shhhhhh - quite enjoying the stealth mode here.
Hercules Site Services (LON:HERC) is one of a number of small caps enjoying sharp share price recoveries in recent weeks. Learn more from their management when they host a webinar ar 10.45am TODAY. All are welcome, simply sign up here: https://us06web.zoom.us/webina...
Going crazy at Sondrel (Holdings) (LON:SND) this morning after some kind of link with Elon Musk and an RNS from the company. Hopefully good news for Paul Hill who holds from a higher level I believe (I don't hold) Good luck Paul H, I hope it sticks for you.
Big move higher today for Sondrel (Holdings) (LON:SND)
Apparently this UK nano-metre ASIC chip designer played a key role in assisting Elon Musk's California-based Neuralink project to implant a chip inside a patient's brain for the 1st time on Sunday.
https://www.dailymail.co.uk/ne...
Hi Paul, I was posting at the same time as you. All the best with this Paul. I hope it comes good for you.
Nice one Paul! Goes to show it's worth having a couple of minnows with potential in your PF, just in case
Thanks guys. Albeit, despite being a 'helluva' case study showcasing Sondrel (Holdings) (LON:SND) 's technological expertise, the company still has plenty on its hands wrt funding and contracts.
Certainly not for widows or orphans.
Yes Sondrel (Holdings) (LON:SND) is almost bust, and having to do an emergency fundraise, so the sceptic in me is a bit suspicious of a ramping article suddenly appearing in the Daily Mail!
Agreed Paul.
On reflection I suspect you may right wrt the timing of the Daily Mail's article. Perhaps a little too coincidental?
It's a great opportunity to exit for those that held on after the recent warnings (I sucked up some losses). No numbers on the Musk project and the multi year sales timeline mean this remains very high risk, even post fund raise.
Agreed Cuddlesticks
I followed your lead & decided to cut my very heavy losses. Time to move on for me
Did you sell before posting this morning Paul?
I hope so as I like your interviews. Dont like to see people posting positively as they're selling tho. Its just not cricket.
Sold late morning
Carbon copy of ramptastic article that appeared for EDEN in the DM which created a price spike - followed tout de suite by a fund raise. You are right to be suspicious
In Out Shake it all About
Couple months ago took around 16 starter / fitst positions after ditching big positions Colefax and Holders .and thinking there was a little bounce due so wanted cash in the market .
Sort of got that right now time to cut it back , so 7 get the chop and 9 make it through to the semi finals .
In an X factor style who makes the cut going to ditch the ones that don’t get me excited or not comfortable with and hold / build / watch on the others .
Tax bill and other cash drains mean need some liquidit
Out
TEAM17 - sold last week for a nice 30% swing
EKF - up 5% but I find I’m just not interested in healthcare .
CARD FACTORY - need the cash out to pay my tax bill and no IHT cover plus no conviction , down 10%
ANIMALCARE - up 10% but doesn’t really interest me
JAMES FISHER - up 10% sell as couldn’t get a decent stake so lost interest
GOICH Co - up 10% , as above and 10% in 8 weeks ok
REACT - down 5% , maybe sell down doesn’t get me excited cleaning windows
Hold / add to long term holdings list and stick with it
CARRS - up 20% let it run plus easy to understand , got a decent holding , seems to be things happening
CENTAUR - hold / build, it looks too cheap at 36p level might add
SAATCHI - let it run , up 20% as bought on the lows but looks goood
MSI - Hold , sector and company good
PENNANT - hold , maybe trim a little over exposed as illiquid and position a bit high .
RESTORE - good position now , with momentum
TRANSENSE - very keen on this . In a full position now ,
SPEEDY HIRE - going to watch this , think it’s going to get hammered further but it’s 11% divi and cyclical so may be interesting , stay in to keep interested plus easy to understand
PENDRAGON - hold just to see what happens (small position )
I am a big fan of Richard Staveley and Rockwood /Harwood so support your views on Centaur Media (LON:CAU) .
Centaur Media (LON:CAU) Maybe I'm being a bit thick here, but what's a company with "Media" in it's name doing still having an "Investment Case" page on it's website using 2022 numbers?
Investment Case | Centaur Media PLC
interesting thoughts and I also feel like I need some surgery, Ive had a broker dg (Capita (LON:CPI), ok results that haven't moved the dial BT (LON:BT.A) , not so good results Serica Energy (LON:SQZ) Hostmore (LON:MORE) , and a turnaround story that went down like a lead balloon Navient (NSQ:NAVI) ..... not a great recipe and performance being propped up by U3O8 ! Geiger Counter (LON:GCL) Yellow Cake (LON:YCA) hmmmmm But, On Feb 13 we get the monthly update re US CPI data....Im inclined to wait to see how this goes down and whether it turns the current market. A good no, ie weak, "could" weaken the $ and restore the rates down story that had driven better small cap and value stock performance in Q4 last year.... We do lose a rather chunky 0.8% from last January so there is a chance.
Hope you are all fairing better.
This is so helpful - thank you for this. I have done a similar "shake out". After a year of small cap investing with a mixed bag of results, I have sold out of almost all positions. I have come to realise that the profit warning surprises and lack of momentum and liquidity is not for me. I'm here for Paul's insights and podcasts which I find educational, entertaining and interesting even though I will not likely invest in any new positions .
I am now only investing in companies with a wide moat which I measure by ROIC - WACC (among other data) which leaves me with Games Workshop (LON:GAW) (chart does not look great atm but strong conviction here) and Warpaint London (LON:W7L) (am a bit concerned about ELF In the US being a too-strong competitor so am watching this one closely).
Stockorocko
These were very much a smattering of starting positions .
I’m still very much committed to holding my top holdings
From these starters I’ll end up with one or two I’m happy with, I even increased on pennant this morning .
The IHT benefits of AIM is a big plus to keep me invested .
Technically if I dropped dead on my core positions I’m 40% up once I’ve held 2 years .
But does require a resilient mind set and it’s not an easy market if you firstly haven’t got time on your hands and secondly can handle the swings.
I have a very concentrated portfolio which is really not suitable for many investors but I find the wider it gets the more uncomfortable I get .
But if I’m 40% up with the IHT benefit my kids will be happy .
Ps - just ditched all my Carrs holding out of trading account as non IHT cover., holding the ones in pension .
I have found January quite frustrating so far, 2-3% down YTD but certainly have that feeling that I need to think really clearly about who might be buying certain shares I own. I have had a number of in line or better trading statements that have actually hammered my portfolio - Card Factory (LON:CARD) , Saga (LON:SAGA) and today Sanderson Design (LON:SDG) . This is in addition to a shocker from JD Sports Fashion (LON:JD.). I think on reflection all of these are quite high profile and quite popular amongst PIs, they might also be attracting "traders" or those looking for quick wins, therefore the in line updates are turning into 10-20% losses quite quickly. Might be time to take a look at some shares that are utterly unloved.
Can't remember a market this cheap. I have a wide portfolio of good quality safe shares all priced with a PER below 10.
Chomping at the bit for April when I can deploy extra funds!
Would be grateful if you could list a few ?
I'm looking JD Sports Fashion (LON:JD.) and trying to figure what's what here, especially given their stake in Applied Nutrition and how a potential IPO will value this. On face value and extra £300 million is not that much given the Market Cap, but perhaps too simplistic?
I have seen a figure of GBP1bn mentioned as the potential float price of AN. The continuing fall in the SP was probably nothing to do with the AN news but rather because of the short just disclosed, Voleon, amounting to 1.8% of the shares in issue.
Saga (LON:SAGA)
Saga forecasts for the current year have been downgraed over 10% in the last 14 days - so presumably the update was treated as mini start of the year profit morning by brokers (unless they updated forecasts before trading update which would be odd) - note the company told us didly squat about new year compared to prior expectations.
It doesnt refelect well on management when holders dont realise (ie they arent told it straight) current year outlook is worsening.
The market will always look fowards rather than backwards so even if it was a slight beat on last year thats the past - peeps are more interested in how they are doing in thne now/future for pretty obvious reasons.
Note i havent had time look at Sanderson Design (LON:SDG) yet but i also presume hatchet job will be taken to current year prospects.
Card Factory (LON:CARD) - is the anomoly here albeit after 300% rise pullback should have been expected at some stage from peak.
Crapola like this happens all the time to me - not much one can do other than reasess if outlook for company has turned from positive to negative ref profits trend mid term - that clearly seems to be the case with Sanderson Design (LON:SDG) - albeit as its just the start of the year how accurate any forecasts will be is up for debate.
Final note ref Saga (LON:SAGA) - to be fair to the company they are expecting profits to increase this year compared to last year materially - so its not all bad news teh outlook is still trending forwards compared to prior year - fact is increase is now expected to be less than it was previously so we cant dress that up as anything other than bad news - they have consistent recent history of starting the year high and ending up with much less unfortunately - albeit for year just finished they did claw backa bit of ground i think right at the end.
If i am investing in companies for next 3 months - i want them to be positive plus (or at least on the ball ref forecasts) unless they are dirt cheap - hopefully in tougher times the better trading companies are easier to spot. For my sins i do hold Sanderson Design (LON:SDG) and havent sold today.
Thanks got your detailed response rmillaree. All of these are long term holds for me with the exception of Saga (LON:SAGA) which I could ditch if things don't pick up. I actually bought back into JD Sports Fashion (LON:JD.) this morning after some time away (at the bottom for once, 104p) , I just think with a change in sentiment at any point in the next year or two its going to move up past 125p at the very least. That's your 10% per annum and it seems a sensible risk with that time frame. Cheers
Saga (LON:SAGA)
This in imho is probably the hardest share to value on the market it could be 300p or 60p in the next 12 months all I would say is that if you hold you pay your money and you take your chance
My morning smallcap tweet: Fountain of spoof
Hardide (LON:HDD) Digital 9 Infrastructure (LON:DGI9) Revolution Beauty (LON:REVB) Woodbois (LON:WBI) Light Science Technologies Holdings (LON:LST) Trufin (LON:TRU) Ten Lifestyle (LON:TENG), Sanderson Design (LON:SDG), Seeing Machines (LON:SEE), Nanoco (LON:NANO), James Fisher And Sons (LON:FSJ), XLMedia (LON:XLM)
◄Hardide (HDD)► FY-Sept. Outlook - slower than expected start to the year with a number of OEM customers de-stocking. Guides FY24 rev broadly flat; EBITDA positive from -£0.1m. £1m of additional funding is required before early March. [SP=9.8 Cap=6m]
◄Digital 9 Infrastructure (DGI9)► more bad news as sale of Verne Global held up by "Phase II investigation" by Iceland competition authority. Takes up to 90 days or even 135 days. [SP=23.2 Cap=201m]. I hold.
◄Revolution Beauty (REVB)► guides FY24 rev up low single digits but adj EBITDA £11-12m driven by cutting lower margin items. Prev guidance was for rev up single digits and adj EBITDA not less than double-digits £. Has ambition for retail brand sales of £1bn by 2030, FY23 rev was £188m so that's 23% PA. Good luck with that. [SP=32 Cap=102m]
◄Woodbois (WBI)► signs term sheet for a $5m facility. Planning improvements in Gabon. "Confident that 2024 will mark a positive and decisive turning point for Woodbois, turning the Company into a reliable, cash generative and profitable business." [SP=0.7 Cap=26m]
◄Light Science Technologies (LST)► £130k order from a new client in a new segment, the sports market. Other orders of totalling c.£1.4m. Guides H1 rev in line. [SP=2.58 Cap=9m]
◄TruFin (TRU)► guides FY-Dec rev up 32%+. Adj EBITDA loss ahead of prior expectations at £3m. Adj pretax in line. Co fully funded to profitability. Playstack weak in Q4. [SP=48.75 Cap=52m]
◄Ten Lifestyle (TENG)► partnership with the world's largest collection of international luxury travel agencies, Global Travel Collection. Has 1300 travel advisors. [SP=79 Cap=68m]
In line: SDG, SEE, NANO, FSJ, XLM
Digital 9 Infrastructure (LON:DGI9) I too hold and very much wish I didn’t!! Share price down 20% this morning. Not entirely sure why there should be any competition issues with the sale of a data centre to a third party. Seems unlikely (?) that they would block the transaction and a delay of 90 to 135 days in the overall wind down which is forecast to take until 2027 at the earliest is hardly significant. However, I guess if the sale proceeds from Verne were needed to pay off debt maturing in the next few months it could force Digital 9 Infrastructure (LON:DGI9) into insolvency. What a mess!!
Some further comment on Digital 9 Infrastructure (LON:DGI9) . Ardian the buyer of Verne Global is a large private equity outfit https://www.ardian.com/house with investments in over 300 businesses globally (including exits). Having reviewed the portfolio https://www.ardian.com/experti...and press releases the only businesses they own in Iceland appear to be Mila - the national telecommunications network https://www.ardian.com/news-in... and a carbon monitoring activity at the national airport. The first of these was cleared by the Competition authorities so it seems unlikely that Verne Global would be blocked - but what do I know! . Perhaps the issue is as I said in my previous comment is down to timing of monies to pay down debt. Otherwise it would seem little more than a technicality and an over reaction to see a further 20% fall in the already bombed out share price.
It's 7.12 a.m. and no RNS showing on my feed (as in folio news). Is that the same for everyone?
Same here
No . Have normal feed showing
Updates now trickling through.