Small Cap Value Report (Thu 9 Feb 2023) - SUS, ARB

Good morning from Paul & Graham.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda - to follow.
Graham’s Section:
S&U (LON:SUS)
Share price: £20.90 (pre-market)
Market cap: £254m
This specialist lender issues a full-year trading statement for the year ending 31st January.
We covered the last update, issued in early December, here.
Thankfully, trading in both of S&U’s operating businesses remains “excellent” and the full-year results will “meet expectations and exceed budget”.
The company notes that “UK business confidence is reported by the ICAEW to be a thirteen year low whilst a potential recession and rising interest rates continue to pose challenges” - and I agree that this adds to the impressiveness of S&U’s performance.
Their loan books continue to grow strongly even at the same time as lending criteria are tightened:
Despite the period seeing prudent adjustments to underwriting and the scorecard, and some rate increases to protect net interest margins as both operational and financial costs grow, group net receivables have now reached c£420m against £370m at the half year. That ultimate measure of quality - collections - remains good in both businesses.
Motor finance division (Advantage Finance)
This loan book is now £306m (up from £296m two months ago).
S&U argues that these customers are “nearer” to prime than they were bevore, after lending criteria were tightened up. They also “marginally” reduced interest rates in this division, “to attract a higher quality customer profile”.
Average loan size has increased 9% to £7,800, loan terms have lengthened (they can afford to do this for more creditworthy customers), and importantly transaction volumes increased 21% versus the prior financial year, as the car market recovers from its many Covid-related problems.
This loan book is now £114m (up from £108m two months ago).
I’m relieved to think that this division might be slowing down. As a new venture, in a property market that has some issues, do they need to go hell for leather? I don’t think so.
House prices have now been reported to have fallen for five consecutive months, whilst mortgage approvals and transaction activity have been restricted by rising interest rates and cost of living pressures.
These trends are expected to continue during 2023. Prudence has therefore dictated further rises in Aspen's own interest rate and tightening of its already conservative loan-to-value requirements.
Even at a slower pace of growth, profits at Aspen have still exceeded budget, thanks to the lack of customer defaults.
Funding - I’ve noted previously that S&U’s borrowing facilities don’t seem to be big enough. They will need to increase them again soon, to accommodate current growth. However, debt funding as a percentage of their total balance sheet is likely to remain conservative, in my view (I’ll check this again when full-year results are published).
Second dividend - 38p, up from 36p last year (S&U pays three dividends each year).
Chairman comment:
Whilst the uncertainties of forecasting and fly casting have much in common, 2023 is likely to see constrained levels of consumer confidence and spending in the UK. Nevertheless, historically this has and, I believe, will continue to present good, responsible, lending opportunities for S&U.
My view
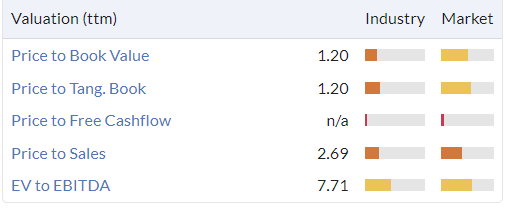
No reason at all for me to change my view on this one. A modest premium to book value for a family business that historically and currently earns terrific ROE, seemingly without excessive risk, strikes me as more than fair:
Argo Blockchain (LON:ARB)
Share price: 17p (-6%)
Market cap: £81m
This bitcoin miner has enjoyed a renaissance in its share price ever since the December announcement of a major refinancing agreement (which we covered here).
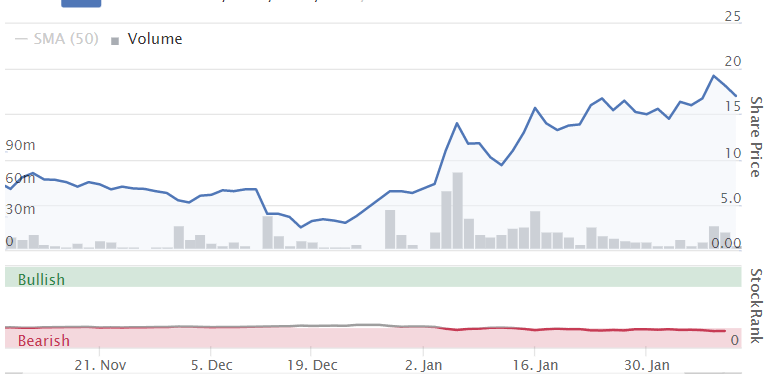
The deal meant selling the ownership of its Texas facility to a specialist lender, “Galaxy Digital Holdings”. This helped to deleverage the balance sheet, but it also means that Argo is on the hook for both interest and rental payments to Galaxy from now on.
However, that’s not what today’s news is about. Today we learn that the Argo CEO (who lives in Canada) is stepping down, “to pursue other opportunities”.
He says:
It has been a great privilege to have led Argo Blockchain over the past three years. It has been quite a journey, and we have come a long way. I am pleased to have recently led the successful Galaxy deal, and I thank all my colleagues at Argo for their dedication, support, and enthusiasm in driving Argo forward. Onwards and upwards!"
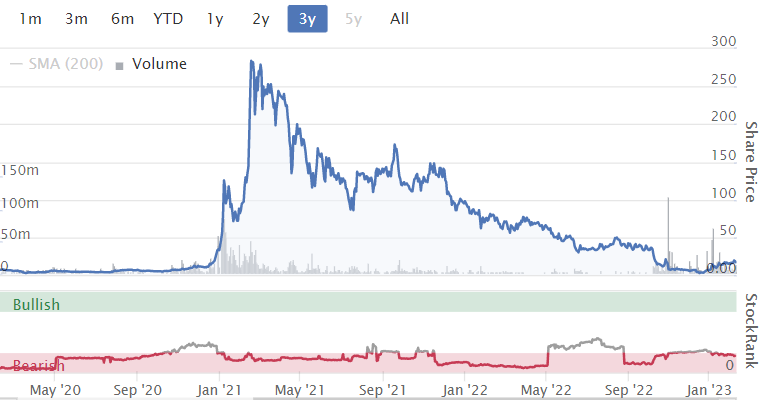
Here’s the Argo share price over the past three years. Quite a journey indeed!
Last year, I checked out Mr. Wall’s career history, to see how he came to lead a crypto mining business.
A background in computing, perhaps in hardware or cryptography, is what I expected to find. But instead I found that he was a filmmaker.
This is no secret - his LinkedIn clearly shows that he has many years of experience in videojournalism, and he has also been involved in events management, building a co-working space, and corporate communications.
Ten years ago, he gave an excellent TedX talk in which he described the benefits of making fun films with his kids on their holidays.
Now maybe you’ll think it’s unfair to question the credentials of a CEO after he is gone. Perhaps it is. But I think we really need to look for CEOs who have a passion and a strong professional background in the specific industry in which their company operates. I don’t think it’s too much to ask.
Based on the presentations I’ve viewed, Mr. Wall is extremely likeable. A great communicator and very funny. Probably a great leader to work for. It’s easy to understand how he inspired thousands of private investors to believe in his project.
However, many of these investors have been led off a financial cliff as the Argo share price has soared and then crashed over the past few years. The risks the company took with its balance sheet were reckless - I discussed them here, when the market cap was still nearly £200m.
Lawsuit - I note in passing that Argo and various of its Directors are being sued in New York in connection with their 2021 US IPO. The lawsuit alleges that:
…the Offering Documents and Defendants made false and/or misleading statements and/or failed to disclose that: (i) Argo was highly susceptible to and/or suffered from significant capital constraints, electricity and other costs, and network difficulties; (ii) the foregoing issues hampered, inter alia, Argo’s ability to mine BTC, execute its business strategy, meet its obligations, and operate its Helios facility; (iii) as a result, Argo’s business was less sustainable than Defendants had led investors to believe; (iv) accordingly, Argo’s business and financial prospects were overstated; and (v) as a result, the Offering Documents and Defendants’ public statements throughout the Class Period were materially false and/or misleading and failed to state information required to be stated therein.
The complaint can be read for free here. The case should make for an interesting comparison of how listed companies are treated in the UK vs. the US.
My view is that Argo should hire a CEO with a strong professional background in computing. It should also pursue a sustainable financial strategy. This strategy might be less exciting to the crowd, but it could last.
As for the merits of these shares currently, I would say they are uninvestable. The company has not published useful financial information for some time, it will bleed cash to Galaxy Digital for the foreseeable future, and it has lost its CEO. I would continue to enthusiastically avoid these shares.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
Hi Paul, I thought I would share something I saw which I think could make your life easier. I think this column is great and you go through a ton of data each day. Just watched something on how you can use chat GBP, or more specifically co pilot in bing where it helps you analysis financial reports. You can compare them to other companies with very simple commands. I reckon if you used this it would save to a ton of time. I hope you don’t mind me suggesting this and if you want me to share more details happy to do so.
Paul might shoot me down for this Colin Craig 1, I'm sure your suggestion makes sense but there's a camaraderie on Stockopedia much of which rests with the personalities of Paul Graham and Roland plus many subscribers, I'd be very sad to see AI take over.
Yes me too. I 100% agree that the personalities of Paul, Graham, Roland and Co is what makes the SCVR. I was meaning more that I saw a video where the bing chat basically showed someone looking at a 15 page financial report and the chat allowed the user to summarise the report in seconds and then you couple compare the summary with a competitor again in seconds. I just thought it was the next generation of search engines and I’m sure it will help a lot of investors analysis data very quickly.
However, as a say, I totally agree that personalities and human experience are priceless.
Then someone will invent a high frequency algo to trade based on AI summarised results and announcements.
So therefore, as a PI, using that same AI (which is likely inferior to specialist HFT fund AI) will mean you're trading after everyone has gone in.
Better to depend on your brain, which currently is unrivalled and unmatched by any AI, to outsmart the AI and trade on better analysis, rather than faster :)
tinyBuild (LON:TBLD) 31m shares out of 200m traded today. Price recovered a bit from a low this morning
What on earth is going on with TinyBuild
Kitwave (LON:KITW)
A 2021 IPO that's seemingly on an upward tear on no news. Up 5.5% today and 20% this month, full year results due end of this month. What's going on?
(I hold)
Snazzy
Zytronic (LON:ZYT) AGM Trading Update. (I hold) - FWIW here are the notes I made this morning.
A slightly disappointing though not at all surprising trading update from Zytronic. Order intake for the first 4 months (to January) have continued in line with the end of the previous H2 and hence H1 revenue expected to be in line with previous H2. Value of the net cash pile has increased 0.4m to 6.8m in the first 4 months so the flat revenue does not appear to be a disaster at this stage.
FY revenue now expected to be H2 weighted as the rising level of prospects start to turn into order intake. Zytronic has limited visibility of order intake – typical lead-time of 4-6wks – so caution on the outlook is sensible as order intake can swiftly increase. But also swiftly decrease. Nevertheless the increasing value of the prospects pipeline seems to be viewed optimistically by management.
International supply chain disruption still impacting Zytronics OEM customers and Zytronic. It should be borne in mind that the delay cycle from start of prospect to order intake is typically 12-18 months and that Zytonics customers are OEM’s and traction in their sales is needed for Zytronic orders to follow suit. Probably this is still some months away?
I share the concerns expressed over the shortage of ‘certain electronic component items’ which I believe is referring to the ASIC used in the ZXY500 controllers – a recently launched product which simplifies customer use of, and adds value to, the bespoke large format rugged touchscreens which are Zytronics primary product.
I don't know how many touchscreen orders are currently being shipped with controllers. Older/pre-existing customers won’t be using them and not all customers will choose to use them. It’s probably not a majority of orders?
Zytronic refers to 2 options regarding the components:
to purchase certain items either on the grey market (at higher pricing) or to cannibalise existing finished stock,
Ooops. It’s not clear to me what this is trying to say. It’s possible to take this to mean any number of things, could be a big problem, or relatively minor? So I’ll spend some time on my thoughts what this might mean.
It is not stated what proportion – if any – of finished stock are re-worked (I prefer the usual industry term). I am very sure that Zytronic would only consider re-working finished stock is the cost and availability of buying on the grey market exceeded the cost and resource of re-working.
Zytronic generally maintains low levels of finished stock as its products tend to be bespoke and lead-times are short. Finished items with controllers will only be a proportion, probably a small proportion, of this low stock level.
It’s also unclear what level of re-work is required afterwards to re-finish the stock. If the asic is socketed, then the level of re-testing will be relatively routine. If it’s not socketed, then frankly I’d expect them to switch out the whole controller unit rather than the component - and again re-work and re-testing may be relatively routine. But of course still more than nothing.
It’s a shame that the TU did not provide clear wording of the extent of the re-work or any impact upon financial results through the cost of re-work. My view is that the statement was intended to provide more understanding of the lengths to which the operation is going to maintain product deliveries, likely for the most important customers. And that financial impact will be limited.
Current global constraints caused by the spike in demand for automotive/industrial devices and the limited fab capacity to produce these devices (after they were idling for best part of a year) means its likely this will continue for at least another few months. I am speculating that this may now be exacerbated by increasing demand for asics and mcu’s in navigation/controllers for drones and other similar uses. None of this is the fault of Zytronic – and I take this statement to show that they are choosing the best approach to fulfilling orders that they can under the circumstances.
Conclusion:- Actually I’m perhaps a little reassured and remain disappointed but not at all surprised. This kind of management caution at H1 has been a feature in previous years and the company has delivered. The short term is constrained by internal labour and material cost pressure and external material price and availability for some months. As cost pressures ease in the medium term order intake will likely begin to rise in response to increasing opportunities.
My view of the medium and long term outcome is unaffected by this trading update. Cashflow remains positive. It’s not going to be a ‘steady-eddie’ journey so patience will be required?
cheers
Mark
PS - if the share price remains weak in the coming days I will likely buy some more, assuming that I can find some cash down the back of the sofa, but no great hurry I think?
Re Zytronic. Thank you for that thorough look into the statement illiswilgig, if only their TU has been as good. We will also be looking down the back of the sofa, as you say patience needed with this one.
Hi Graham - the thing about these class action suits in the US is that they seem to be thrown around like candy. Equivalent of financial ambulance chasing. I've noticed over the years lots of these crop up and lawyers even advertising to drum up business. It strikes me that most of them seem to go nowhere or get an out of court settlement. I find this a bit abhorrent really as it doesn't treat all investors fairly and merely encourages more ambulance chasing. I'm all for bringing companies to account if they mislead investors but I'm not sure this current approach is good for financial markets holistically.
With regards to Argo Blockchain (LON:ARB) I see the whole of the cryptocurrency and NFT scene as one big ponzi scheme and one to be avoided. I imagine post Sam Bankman-Fried/FTX debacle there'll be a few more of these class action suits.
I agree but there are incredible returns to be made if you can go against the consensus bias and catch these companies when BTC goes on a bull run.
I made life changing sums of money and luckily sold most of my holdings in these garbage companies in late 2021.
I agree though, most of crypto scene generally doesn't hold any great value and most of the projects, NFT's, Coins etc will inevitably go to zero. Blockchain technology is pretty fascinating though so I think there could be something in that long term applied to the right areas. What they are I have no idea
I agree you can make money off anything if you time it right. However, for everyone like you who has made life changing money there will be 10x (if not more) the amount of people who've lost their life savings. DYOR etc etc, good luck to all those who run the gauntlet but it's not for me.
That's how markets work though isn't it. For every winner there has to be a loser on the other side of the trade. That's what makes a market.
People lose their life savings because they have no plan or risk management. They get attached to their bias and can't admit it when they are wrong therefore hold on to losing positions hoping it will one day come back rather than cutting the loss at an acceptable level and moving on.
A good description of the perils of investing for the unwary.
Many lose their money in jam tommorow firms.
No, it’s a good description of trading, not investing.
Sorry but I disagree with this. Much of the market is a zero sum game (like trading currencies / commodities etc). But equities imo are not the same situation. A good profitable business (especially those that are growing) can create value for the shareholders without someone else losing on the other side of the trade. Think of a painter who just buys a canvas and paint - then creates something worth more than the sum of its parts. Most businesses generate revenue and profits from the economy - if they make more money then people are willing to pay more for the stock. Those new investors have paid more but they are getting higher earnings and hopefully will also get a good return on their entry price based on the business carrying on its success. So I wouldn't confuse equities with things like Bitcoin for example.
Also in terms of whether one should hold on to a losing position - this is a strategy point that will be different for all investors. As I am often a contrarian, I expect to have to hold my ground against what I might consider to be an irrational market. If I cut my losses based on the paper loss, I would have missed out on many great investments. I prefer to look at the business fundamentals along with some forward analysis as to how they may perform as a company and how the sector may perform (say over the next 3 - 5 years). So I would never sell a stock based on the actual price or anchoring to my starting price. imo it is better to just always re-evaluate. If it was cheap before and has become cheaper (with no fundamental changes) then why would you sell. As Warren Buffet says - the stock market is the only place that can have a sale - and all the customers run out the store.
Solicitors are less trustworthy than estate agents in my view / experience ... Ambulance chasing is spot on, that's exactly what they are doing a large majority of the time.
Journeo (LON:JNEO)
Nice trading update out on this today confirming in-line and acquisition of Infotech going well.
Looks absurdly cheap to me now - Looking at broker forecasts with first full year of enlarged group we are looking at eps of 18p. Include cash and a PER of just over 4 !!! and I suspect those numbers are light - looking at orders I'm expecting a beat next year.
order intake jumped 50% to £27m and revenues jumped 35% to £21.2m so clearly good momentum in the business. Now have a bigger international presence too given the Infotech acquisition gives them an $18m contract for New York subway.
Net Cash position of around £5m+ with no debt so balance sheet is good.
Historically I understood why it was cheap - transitioning market to software, relatively low revenues and market cap kept it off most peoples radars but the landscape has significantly changed and I don't think investors have switched on yet.
Anyone found any negatives I should bring into my thinking? always helpful
David, I agree Journeo (LON:JNEO) looks interesting, but where do you see that it has a net cash position of £5m+?
When it bought Infotech that acquisition came with £4.5m of net cash and when they did the raise that added about another £500k of capital on top of acquisition costs.
Now cash generative so that number should be going up too
Journeo (LON:JNEO) My thoughts... I think it looks really interesting, but the market they operate in tends to suffer from protracted capital investment cycles. Orders are often pushed back to fit with budget cycles, which are obviously stressed these days. Quite a few of their customers (the decision makers who sign off the contracts) will be public sector organisations. I used to work in the industry 5 years ago, so I'll be a little out of date. It's really cheap. I wonder if it's orientated towards bus and coach operations than rail. It looks UK focused, but must be good opportunities in Europe.
With the acquisition they are in the UK, US and moving into Europe with some there already.
Order book underpins revenues now at £27m so not really suffering from any protracted investment cycles particularly as they have been focussing more and more on software.
davidjhill... Journeo (LON:JNEO) As I say interesting and cheap co, but I'm not sure I understand what you mean by "not really suffering from any protracted investment cycles particularly as they have been focussing more and more on software." Their solutions are a combination of hardware and software. It doesn't matter if this is SaaS or some other kind of subscription model because the issue is around what drives the business. Their sales process will involved responding to a public tender. There will be a competitive submissions from various suppliers, which will eventually lead to an order for someone. A big part of this business will be technical alliances with bus, coach and train manufacturers who will provide interfaces to the whole system, and there will be other sub-system manufacturers that will have to be "partnered" with. It's a game of lots of moving parts set against the backdrop of public sector finances. So I stand by my point about protracted capital investment cycles, which as investors won't necessarily be highlighted to us by the company. The reason for this is obviously because it makes revenue forecasting difficult.
davidjhill, also meant to add, love following your various posts on SCVR. Very informative. Thank you.
Thanks spglet - appreciated
what I meant was that with a £27m confirmed order book and forecast revenues of £31m next year they appear to have very strong revenue visibility. A protracted investment cycle by end user clients doesn't really matter to a service provider once they are over a certain hump and have a pipeline sufficiently large and diversified. Ie this is factored in to sales forecasts. Whilst it might take time for a brand new sale to work its way through the pipeline there are other more mature sales further along in the hopper ready to come out.
Historically I was always a bit concerned they were sub scale and thus orders could be lumpy. The numbers they are showing now in terms of revenues, confirmed pipeline and potential orders suggests they have reached scale and growth. Potentially a nice sweet spot if I am correct.
Journeo (LON:JNEO) Thanks davidjhill. I understand where you are coming from. A £27m confirmed order book is very good. The sales cycle itself - gathering leads -> qualifying to prospects -> submitting proposals may be quite long (something like a year I'd imagine) but as you say the latency doesn't really matter at this stage of the company's growth (over the hump). Next year's forecast will be based on something like a 20% conversion ratio of the leads (pipeline) they have. I think you are right they seem to have reached scale and growth. That means the addressable market is something around £155m (5 x £31m). Which doesn't seem very big for what we're talking about - I'd imagine the market for transport systems of the type they produce is at least ten times that in the UK. That means there is quite a lot of growth for them, the constraint might be deployment not sales. Anyway, just conjecture...
yes - interesting, and thank you for the extra industry insight, that is very useful.
I know not one that SCVR would cover as it's resources but, may be of interest to commenters: Diversified Energy (LON:DEC) did a (very) rapid book build for a placing yesterday. As a holder I received a notification from my broker just after 5pm and had to respond within hours if I wanted to participate. The placing was successful at a price of 105p and, at that price, it's yielding circa 13%
why did it need this I have sold out do not trust
It was an immediate opportunity to acquire productive wells in adjacent territory. supposedly immediately earnings enhancing so looks like a good deal. But, yes, confusing that a co that was doing buybacks does a 180 and performs placing.
It's also paying out large dividends - doesn't really make sense to be doing this while raising new equity at the same time. I like Diversified Energy (LON:DEC) and have held in the past, but find all their hedging activities adds just an extra layer of complexity that I can't quite get my head around.
Well, to be fair, they did stop the buyback at the end of October as far as I can see, so three months ago. They will have accumulated some cash since. I'm still mulling this over. It takes them into some drilling, which I thought they didn't want to do, but the purchase price looks compelling. Their hedging has worked so far (you may have wanted to sell at spot last summer, but you wouldn't want to now: Diversified Energy (LON:DEC) are providing reliable cashflow, key to institutional investors). I'm tempted to add for 13% yield (less 15% US withholding tax) remember), but have my theoretical max position already... Not an easy one. Do remember that Rusty Hutson owns £23m in shares (and two other directors roughly £2.5m each). Directors have skin in the game.
I am a holder of DEC and was expecting better performance during the last year of energy crisis. High dividend is a compensation for poor performance for now.
Good morning all, can anyone recommend a good Level 2 service? What do people use here? I've tried ADVFN previously, but wasn't a huge fan - are there any others people recommend?
Thanks!
Hello,
I am happy with ADVFN, does the job for me! Not sure what others are, LSE maybe?
Hi. i use the level 2 with my provider Interactive Investor. pretty happy with it and easy to navigate between my portfolios and the order book.
I use IG Level 2 - good value and DMA works well
I know it is well above the SCVR market cap limit but Watches of Switzerland (LON:WOSG) was a 2022 NAPs selection so be interested to hear views on why share price down 15% this morning. I have read this mornings trading update and it exudes positivity and the numbers look pretty reasonable. What have I missed?
My thoughts as well, Watches of Switzerland (LON:WOSG) shares down 9% now. Not had a chance to look more closely yet.
One theory. WOSG has obviously benefitted from a major tailwind by all the recent madness in the luxury watch space. By madness I mean the strong imbalance in supply and demand, particularly for Rolex. Reason being that at peak insanity those same watches could be flipped for 2x or 3x their retail value on the grey market the moment they left the showroom. Lots of recent anecdotal evidence (just search Google / YouTube) that this bubble is now rapidly deflating / has popped, in tandem with the withdrawal of QE / bursting of crypto. If that is the case, then WOSG are potentially in for a much more pedestrian rate of growth over coming years. Again just a theory because in general current demand seems to be resilient and luxury in general is holding up surprisingly well. But perhaps the market is starting to look ahead. Further off topic I would just add that I would be doubly cautious with WOSG because at the end of the day they don't own their IP. They are the just the route to market. In my mind that's a far less secure place to be than a Hermes, Burberry or, speaking of watches, Rolex itself, which can all tweak supply by volume, price, region and distribution channel. WOSG has no such ability. I don't see it as a quality play on luxury for that reason. Dare I say it but perhaps a flash in the pan, right place / right time type of stock??
Yes in a nutshell, luxury watches may have been yet another Covid era bubble - this led to very strong growth at Watches of Switzerland (LON:WOSG) which led people to assume it was a high growth company (with a high growth rating). This is now unwinding - at least that's my rake.
serving the rich has been a good business to be in over the last 15 years. WOSG is the latest arrival but I think the bigger one are better placed here. LVMH has it all and has performed well. L'Oreal is another one.
Vanity and old age does not going out of fashion anytime soon. Luxury product serves both groups (the old have become generally richer over the last 15 years).
Yes LVMH is a far better business as it owns all the brands, unlike WOSG which is just a distributor. Unfortunately it's LVMH is always very expensive, a bit like its products I suppose.
Unfortunately LVMH is always very expensive
It’s on a FY23 EV/EBITDA of 15x for one of the most consistently profitable and recession-robust businesses on the planet. How is that expensive?
Or to put it another way. Is one of the world’s richest men selling his LVMH shares in order to buy an ex-growth carpet distributor on a half the multiple?
I'm not sure they are only selling to the rich - there aren't that many people that can afford to put a car on their wrist or shoulder.
LVMH juggernaut is a function of being able to borrow at negative interest rates to acquire & cut costs while selling items on 0% finance/BNPL etc etc, with share price appreciation a function of a limited free float.
WOSG also relied quite heavily on 0% finance for jewelry that goes (went) up in value - a win win win for everyone except savers. Interestingly they don't offer 0% finance on stainless steel sports watches where demand exceeds supply.
I am not sure how long this will continue. Merill Lynch made a great business bringing wall street to main street until they didn't & I can see a world where luxury follows a similar path
Thank you Paul, I have followed S&U (LON:SUS) for a long time now. You may be interested in some details of them at https://lewissrobinson.com/, Lewis has written about them a couple of times.
Thanks whirlybird, Lewis is brilliant when it comes to S&U analysis (and many other shares).
Zytronic (LON:ZYT) The sentence in the AGM statement which I really do not like is this: ' As the shortage of certain electronic component items persists the Group continues, by necessity, to purchase certain items either on the grey market (at higher pricing) or to cannibalise existing finished stock, due to the lack of availability and levels of allocations from original manufacturers.'
Cannibalisation is a pretty awful admission because if they are to account honestly they must reduce the value of their stock holdings. A cannibalised product is worth very little until the missing components are replaced and any damage made good. I don't know how bad the problem is but a properly finished product which is cannibalised to extract components will need not only to have those components replaced but will also need to go through all the QC procedures again and be re-packaged. That's a huge cost and means taking staff away from new production. Awful.
Zytronic (LON:ZYT) I think it shows pragmatism in getting orders out of the door when faced with severe supply chain issues. They won’t be doing this long term, and while surprising, I don’t think it’s that big a deal in the bigger multi-year picture.
The price is almost fully backed by cash, freeholds, long leaseholds and land. The current value of inventory is neither here nor there really.
We also hold Zytronic GavSmith01, I've always found their statements to be 'tell it as it is' . I take Michael C's point but with orders going in the right direction sometimes needs must. We won't be selling. Note the biggest individual shareholder about to join the board for a limited period, let's hope his experience helps them.
Thanks for your reply. Accounts YE 30/09/22
Work in progress 344
Finished goods 293
Total £0.637m compared to PBT £0.705m
It all depends how long it takes to replace the cannibalised components, run the products through QC again, rectify any faults or damage, and re-package.
I keep being told that the value of companies is backed up by freehold properties. The changes in energy performance requirements are going to have quite a severe effect on many commercial properties and I am not convinced this is being fully reflected in valuations yet. We did see a big reduction in the value of freehold investment properties in the Direct Line Insurance (LON:DLG) announcement, I foresee others going the same way.
Zytronic (LON:ZYT)
It might be awful but fair play to management for being open and transparent here. At the end of the day if you have components you need you cant buy and exist in products you have lying around surely minimising sales disruption here is a lesser evil than potentially losing customers who may be forced to use a rival - just so you avoid a slight stock wriedown. Their business should be sticky so to me doing whatever needs to be done to keep most customers happy here seems like sensible action being taken - once a customer buys units elsewhere they may never come back. Perhaps not so sensible is being in this position at all in the first place- we all know though carmakers couldnt get cars finished due to same issues so they are not alone being in that boat.
My morning smallcap tweet: Financial fillies and also-rans
Argo Blockchain (LON:ARB) Graft Polymer (UK) (LON:GPL) Zytronic (LON:ZYT) Malvern International (LON:MLVN) Avon Protection (LON:AVON) Journeo (LON:JNEO) Fusion Antibodies (LON:FAB) Shield Therapeutics (LON:STX) Genedrive (LON:GDR), Oxford Metrics (LON:OMG), S&U (LON:SUS)
◄Argo Blockchain (ARB)► CEO scarpers. He is thanked. NED also leaves. [SP=18.2 Cap=89m]
◄Graft Polymer (GPL)► nearly completed installation of the new production lines to double production. Also an order from a cosmetic company, a first for Graft Polymer. [SP=12.1 Cap=13m]
◄Zytronic (ZYT)► AGM stmt - H2 weighting will be greater than previous FY due to continuing supply chain issues and the increasingly robust opportunities pipeline. Warns that pay rises for staff and other inflation may exceed budget. [SP=155 Cap=16m]
◄Malvern (MLVN)► guides FY-Dec rev up 170% and pretax loss c.£1.1m (£1.6m adjusted for Singapore disposal). Jan uptake for University Pathways significantly ahead of mgmt expectations. English Learning Training - confident. [SP=14.5 Cap=4m]
◄Avon Protection (AVON)► further $6.7m order from US Defense Logistics Agency under the second-generation Advanced Combat Helmet contract. [SP=980 Cap=295m]
◄Journeo (JNEO)► guides FY-Dec rev up 35%. Profit in line with market expectations. Order intake up 50%. [SP=127.8 Cap=21m]
◄Fusion Antibodies (FAB)► new service, Mammalian Display, for high volume mammalian cell surface expression and screening of antibodies. [SP=40 Cap=10m]
◄Shield Therapeutics (STX)► guides FY-Dec rev £8.5m (£1.5m) inc £4.4m in licence payments. [SP=6.14 Cap=36m]
◄genedrive (GDR)► Antibiotic Induced Hearing Loss test receives preliminary recommendation by NICE. Final guidance will follow a public consultation [SP=25 Cap=23m]
In line: OMG, SUS