Small Cap Value Report (Thu 9 May 2024) - CCT, RBN, WOSG, ITV, FDEV, AAF, LST

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
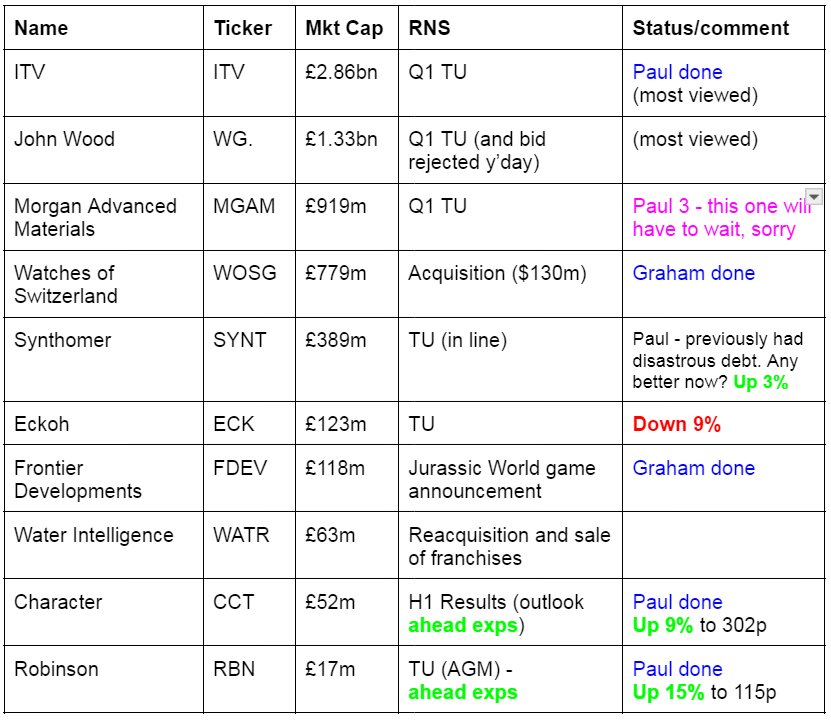
Other mid-morning movers (with news)
Airtel Africa (LON:AAF) - down 9% to 105.3p (£3.95bn) - Final Results FY 3/2024 - Paul - no view.
Telecoms & mobile money group, in 14 African countries. Commendably fast reporting of FY 3/2024 numbers. Moved into a loss, mainly due to adverse forex, esp Nigerian naira devaluation (which we’ve also seen hit other companies, eg CABP and PZC).
Not my cup of tea, with negative $(1)bn NTAV.
Light Science Technologies Holdings (LON:LST) - up 13% to 3.05p (£10m) - Distributor Agreement - Paul - AMBER/RED
I very quickly reviewed its FY 11/2023 results here yesterday. Still loss-making (albeit reduced loss) and a weakish balance sheet, so almost certainly another placing will be needed I reckon.
Today it announces signing of a distributor agreement in S.Africa, with no financial details disclosed. It relates to LST’s vertical farming products. Why does a £10m market cap group have 3 divisions? It seems a scattergun approach, from a series of small acquisitions, with inadequate financial strength to properly develop them, I suspect.
I’ve only just spotted that yesterday’s results contained a “material uncertainty” warning. Nearly all the revenue comes from its contract manufacturing business, with the other 2 divisions being blue sky.
I’m sticking with AMBER/RED, due to the risk of a discounted placing. So expect a flurry of rampy RNSs in the lead-up to the next fundraise! That’s the usual pattern with this type of company. Although note that Directors are big shareholders, a positive thing.
Summaries of main sections
Character (LON:CCT) - 276p (pre-market) £52m - H1 Results - Paul - GREEN
Ahead of expectations update for FY 8/2024. H1 results are much improved on last year's near-breakeven result. Notably strong balance sheet with plenty of cash and no interest-bearing debt. Good dividends, plus buybacks. Looks a decent value share to me, I like it. Although bear in mind historical performance can be erratic, but it always seems to recover from occasional profit warnings.
Robinson (LON:RBN) - up 23% to 123p (£21m) - AGM Trading Statement - Paul - AMBER
Ahead of expectations update, and Cavendish raises operating profit forecast by 20% to £3.0m. Although this is a misleading profit measure, as finance costs of £0.8m are ignored. The forecast PER is now 13.2x, which I feel is high enough for a low margin, capital-intensive business in a highly competitive sector.
Watches of Switzerland (LON:WOSG) - up 1% to 328p (£785m) - Acquisition of Roberto Coin Inc - Graham - AMBER/GREEN
A surprising acquisition in some ways as WOSG buys the US-based distributor of a jewellery brand. Looking into the details, I come away with a positive impression based on the price of the deal, WOSG’s ability to afford it, and the strategic reasons. WOSG shares are increasingly interesting to me.
ITV (LON:ITV) - up 2% to 75.6p (£3.02bn) - Q1 Trading Update - Paul - GREEN
A confusing and badly worded update, that doesn't tell us if they're trading in line with expectations or not. However, I'm delighted with the news that the pension scheme is now fully funded, which will free up a lot of cash for improving the already good shareholder returns.
Frontier Developments (LON:FDEV) - up 1% to 303p (£120m) - Jurassic World game announcement - Graham - AMBER
This video game developer and publisher has provided welcome clarity on its plans: a new game (name unknown) will be released in the upcoming financial year FY May 2025, then a Jurassic World game in FY26, and then another new game in FY27. The odds of success for shareholders seem finely balanced.
Paul’s Section:
Character (LON:CCT)
276p (pre-market) £52m - H1 Results - Paul - GREEN
Designers, developers and international distributor of toys, games and giftware
I’ve followed this toys company for many years, and my preconception is that shares usually look cheap or very cheap, but it has a rather erratic track record, and disappoints with profit warnings every now and then. It’s been a generous dividend payer in the past, and is doing buybacks too. There might have been question marks over management remuneration too, I vaguely recall.
H1 results are much improved on last year -
Revenue flat at £57.6m
Adj PBT (profit before tax) up 320% to £2.1m (from a low base last year)
Adjs are only small, and actually reduce profit this H1 by £154k.
Adj diluted EPS up huge % from almost nothing last year, to 8.7p this H1.
H1 dividend held at 8.0p, almost all of earnings, and uncovered by earnings LY.
Outlook - positive news here -
"The Group has a strong portfolio of products, underpinned by a strong balance sheet, and has a net cash position with substantial unutilised working capital facilities in place. On the back of our first half-year's performance and these signs of the Group's robust health, we anticipate profit before tax and highlighted items in respect of the full year to 31 August 2024 will exceed current market expectations. The Board is comfortable that the Group is on course to meet its targets."
Balance sheet - looks healthy to me. Inventories have reduced by £6m to £11.7m, with the benefit flowing half through to increased cash of £13.4m, and reduced trade creditors. Working capital looks very comfortable, with £25m net current assets. Put another way, the cash pile of £13.4m almost completely covers what they owe suppliers (£13.8m). There are no significant longer-term liabilities. So my verdict is that CCT is in rude financial health, meaning that there’s no solvency or dilution risk, and it has ample dividend-paying capacity, as it demonstrated last year with divis still paid despite not being covered by earnings. It’s not fashionable at the moment (where everyone seems to chase high ROCE), but I like the safety that a strong balance sheet provides investors with.
Cashflow statement - all looks fine to me, no issues. Note that share options charge is very low at £55k in H1, and £204k in FY 8/2023, certainly not excessive.
Broker update - thanks to Allenby for crunching the numbers this morning. It increases FY 8/2024 PBT by 10% to £6.6m. In EPS terms that is: OLD: 23.3p, NEW: 26.1p.
CCH shares historically have tended to only attract a high single digit PER. Is that fair though? I think a PER of about 12x seems fair here, so that gives me a share price target of 313p. That’s a bit above the current price, so there’s likely to be some upside here. A 10% rise in forecast earnings usually flows straight through to a 10% rise in share price on the day, so I imagine (I haven’t looked yet, as it’s funt o guess!!) we might end today c.300p, which would certainly not be a stretched valuation, especially when you take into account the very strong balance sheet, and generous divis, plus it has authority to do substantial buybacks - which I approve of where a share is cheap on fundamentals, and is not a diversion to cover up excessive management share options (as we saw recently at Trainline for example).
Paul’s opinion - I like it. GREEN.
Robinson (LON:RBN)
Up 23% to 123p (£21m) - AGM Trading Statement - Paul - AMBER
Robinson plc ("Robinson", the "Company" or the "Group"; stock code: RBN), the custom manufacturer of plastic and paperboard packaging…
New CEO - “in advanced discussions” to appoint someone.
Key points -
Jan-Apr 2024 revenues up 8% (volumes up 12%, prices down)
Improved gross margins and lower operating costs.
Profit ahead of 2023, but doesn’t say how much.
Surplus properties valued independently at £7.4m (about a third of the market cap) - further sales likely in the next year, some subject to planning approvals.
Net debt has risen by £0.7m since Dec 2023 year end, due to £1.1m of capex.
Outlook & profit guidance -
After strong performance in the first four months, the Company expects revenue for the 2024 financial year to be ahead of 2023 and current market expectations. With this additional revenue, full year operating profit (before amortisation of intangible assets and any exceptional items) is expected to be in the region of £3.0m (2023: £2.2m), this being ahead of current market expectations. We remain committed in the medium-term to delivering above-market profitable growth and our target of 6-8% adjusted operating margin.
I wish companies would stop reporting operating profit, because it ignores (often substantial) finance costs, which also these days post IFRS 16 can include significant property lease costs. We need to be told real profit, including all costs, so adj PBT is the number I want to see, not the misleading operating profit number.
In this case, RBN had £805k of finance costs in FY 12/2023, which is 27% of the guided operating profit of £3.0m above. So ignoring these real world costs is not good enough. It’s PRs probably trying to pull the wool over our eyes as usual, and trying to make the numbers sound better than they really are. Still, untangling their complicated webs of deceit does at least keep me busy!
Broker update - Cavendish issues a helpful update. Sure enough, this confirms that adj EBIT (operating profit) of £3.0m turns into £2.2m of adj PBT, which turns into adj EPS of 9.3p - up 24% on 2023, but flat vs 2022. So it’s not clear whether this is structural, sustainable growth, or just oscillating around the flat line?
This gives us a PER of 13.2x, which I think is fully up with events.
Paul’s opinion - I wouldn't get carried away with today’s news, the price looks high enough I think. The surplus property is good, but we’ve known about that for many years, these things take a long time to actually pay out. It covers net debt, so I doubt there would be much (if any) return to shareholders from property sales. Hence in valuing the shares, personally I net off the surplus property against elevated net debt, with a result that it’s neutral overall.
This is a low returns, capital-intensive business in my view. Performance is improving, but that’s after spending £4.0m in capex in 2023, and £2.6m in 2022. The products are low margin, and up against a multitude of competitors. Put those factors together, and I see little appeal in this share. There’s nothing actually bad about it, just a lowish quality business in a highly competitive sector, where I don’t see any competitive advantages or growth potential for its products. Surely there must be better places for our money? Overall then, I can’t muster any enthusiasm for this, but there’s nothing actually wrong with it, so AMBER seems about right. Also bear in mind RBN shares can be extremely illiquid. I remember getting stuck with a small position here a few years ago, and it was tricky to exit from. Hence I imagine there are likely to be plenty of stale bulls happy to use a big price move up as a selling opportunity.
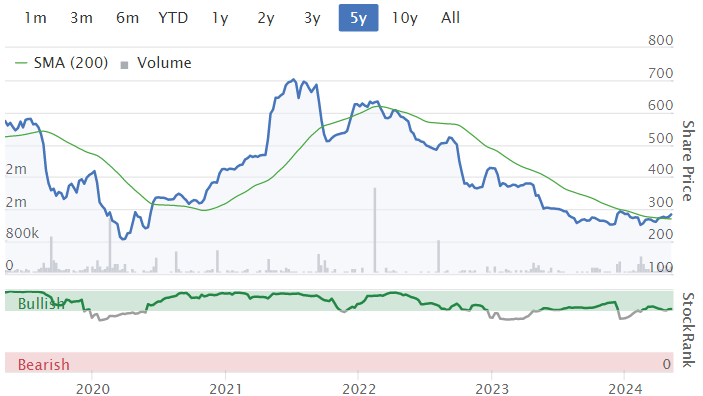
Nice-looking chart though, and a good StockRank, so maybe traders might see more upside here, who knows?! -
ITV (LON:ITV)
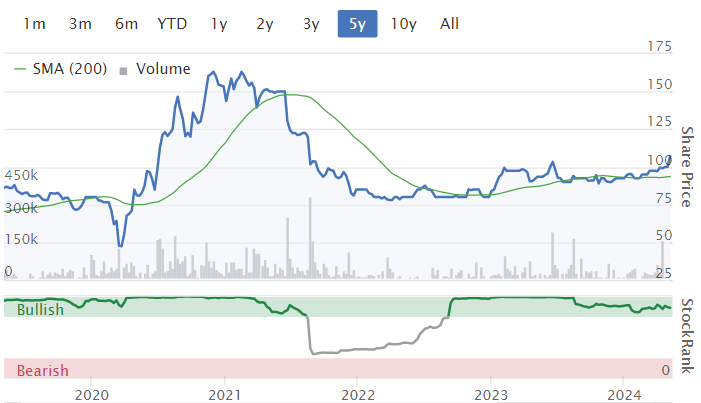
Up 2% to 75.6p (£3.02bn) - Q1 Trading Update - Paul - GREEN
We stray into mid-caps where we see potential value. I reviewed ITV twice in Mar 2024 -
1/3/2024 - 64p - sells Britbox JV to BBC, to fund a big share buyback (9% of co). Low PER & high dividend yield. But cash hungry pension deficit.
11/3/2024 - 71p - Amber/Green - I was intrigued by FY 12/2023 results, and concluded it’s worth a closer look.
On to today’s news, Q1 (Jan-Mar 2024) -
This is by far the most significant news I think, on the pension deficit (previously a large drag on cashflow) is now in actuarial surplus, a big turnaround -
ITV Pension scheme in surplus following latest triennial valuation; removes a significant historic drag on free cash…Following the agreement of the latest triennial valuation we expect no future deficit contributions while the Scheme is in surplus, other than a small payment relating to a legacy asset-backed scheme. This removes a significant historic drag on free cash (refer to Note 6 for further details)...
The triennial valuation of the ITV Pension Scheme (the Scheme) as at 31 December 2022 has been completed. At the valuation date, the Scheme had a surplus of £83 million. This is compared to a deficit of £252 million at the previous valuation date of 31 December 2019.
As the Scheme is in surplus, there are no deficit contributions payable. The Group will continue contributing an annual payment of c. £3 million under the London Television Centre Pension Funding Partnership. The Group's pension deficit contributions for the year to 31 December 2023 were £40 million, and for the year to 31 December 2022 were £137 million.
Liquidity & net debt - looks much improved -
ITV continues to have good access to liquidity. At 31 March 2024, net debt was £272 million (31 December 2023: £553 million). ITV had total liquidity of £1,514 million, comprising total cash of £614 million and committed undrawn facilities of £900 million.
Outlook - doesn’t tell us what we need to know, ie how is trading this year vs market expectations? It mentions an H2-weighting, so maybe it’s trying to cover up a softer H1? -
With the continued strong strategic progress we are making, we remain on track to deliver our 2026 KPI targets.
As previously guided we expect to deliver a total of £40 million of cost savings in 2024 - made up of £10 million from our 2019 to 2025 cost savings programme and £30 million of additional in-year savings as part of our strategic restructuring and efficiency programme which we announced as part of the 2023 full-year results and are already executing upon.
Paul’s opinion - a very badly written trading update that gives a lot of fragmented detail, but doesn’t pull it all together with a conclusion - which is what we need, just saying whether or not they’re trading in line with expectations. When companies deliberately avoid stating this, it just makes me suspicious.
Broker consensus forecasts for both FY 12/2024 and 2025 have been drifting downwards for quite a while, which combined with the key gaps in today’s update, and talk of an H2 weighting, increases my unease that H1 results could disappoint maybe?
That said, the pension scheme deficit payments stopping, and greatly reduced net debt too, are highly positive. ITV now looks a really good income share, with forecast yield of about 6.8%, with scope for that to go higher I think, since not having to fund the pension scheme any more will free up plenty more for dividends perhaps.
I’ve not gone into all the details properly, so this is just a quick overview, and on that basis I think ITV shares look well worth investigating further, doing your own proper in-depth research.
I think the removal of pension cash outflows and moderate net debt, is enough to make me up my view from AMBER/GREEN to GREEN. Although I should stress that this is not based on deep research, just an overview.
Graham’s Section:
Watches of Switzerland (LON:WOSG)
Up 1% to 328p (£785m) - Acquisition of Roberto Coin Inc - Graham - AMBER/GREEN
It’s a large ($130m) acquisition announcement from Watches of Switzerland this morning.
Information on the acquired company, Roberto Coin Inc:
According to research by WOSG itself, Roberto Coin is “the sixth largest jewellery brand in the US by sales at retail value”.
Roberto Coin Inc “has exclusive perpetual rights to import and distribute Roberto Coin jewellery throughout the US, Canada, Caribbean and Central America”.
Roberto Coin is “delicately handcrafted jewellery with a unique ruby signature”. It’s currently available in 16 WOSG showrooms in the US.
For a moment, when I started reading this announcement, I was astonished that WOSG was buying a jewellery brand - but then I quickly saw that it was buying the right to import and distribute a jewellery brand, i.e. an expansion of its existing jewellery distribution rights.
The strategic rationale? The deal “builds on the group’s proven capabilities in showcasing luxury brands across both watches and jewellery”, particularly in the US.
Some of the specific reasons given:
Grow the wholesale business under the leadership of the existing President of Roberto Coin Inc, expanding the network of independent retailers and exporting outside the US.
Sell directly to the consumer using WOSG’s existing showrooms and websites. WOSG will benefit by buying directly from the Roberto Coin parent company in Italy, instead of having to lose margin by buying through Roberto Coin Inc.
Financials
Key facts:
$10m (out of the $130m total payment) is deferred for one year and contingent on profitability.
In 2023, according to unaudited figures, Roberto Coin Inc made PBT of $30.2m on revenues of $138.7m.
In 2022: PBT of $30.1m on revenues of $146.2m.
The US jewellery market shrank in 2023, so it’s not a surprise that revenues might have fallen. It is surprising (to me at least) that this had no impact on Roberto Coin Inc’s profitability.
If the unaudited figures are valid, it means that WOSG is only paying 5x PBT: surely there is a catch?
Funding: WOSG are borrowing to get this deal done. The leverage multiple (net debt/adj. EBITDA) increases to 0.8x, a level that would normally still be considered very safe.
As of the most recent interim results (to October 2023), WOSG reported having a net cash position.
WOSG CEO comment excerpt:
We have partnered with Roberto Coin for over a decade in the US, retailing its elegant jewellery in a number of our Mayors' showrooms. It is a hugely popular, growing brand, occupying a strong position in the market, underpinned by product quality, design creativity and imagination.
"We believe there is significant opportunity to leverage our proven retail expertise in luxury branded jewellery…
Graham’s view
Checking the archives, I last covered WOSG in February (share price at the time: 392p), when I said “the valuation is starting to look tempting”.
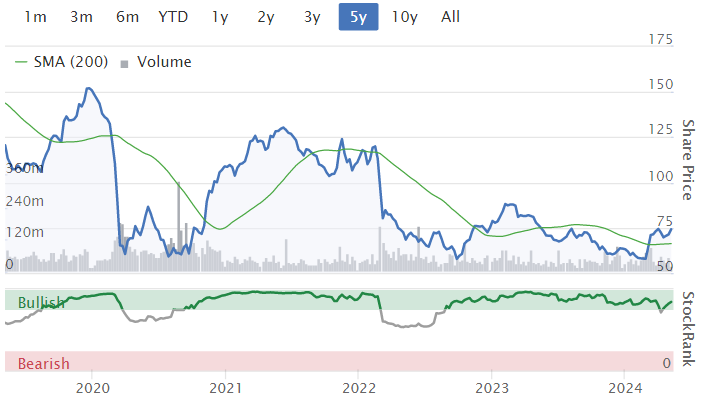
The WOSG share price has been decimated during the Rolex bust:
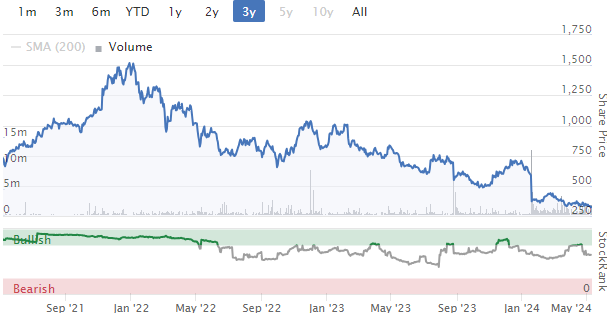
There has been no increase in the share count during this time, and indeed the company’s balance sheet has been reasonably strong, with lease liabilities being the only major risk factor.
Today’s deal does inevitably increase the risk associated with this share. However, I can’t argue that the company shouldn’t do it. It had an (admittedly small) net cash position, and after the deal it has a modest leverage multiple. So can it afford to do the deal? Based on current figures, yes.
Of course if trading were to continue deteriorating, this would change both EBITDA and the leverage multiple for the worse. But as things stand I would say that yes, WOSG can afford this deal.
Another (more controversial) way of looking at it is the percentage of WOSG’s market cap involved: $120m paid upfront is only about 12% of the current market cap. So WOSG shareholders could have funded the deal with additional equity, without suffering much dilution.
As for the valuation: I consider myself appropriately sceptical when it comes to unaudited figures, but I have no reason to doubt that Roberto Coin did generate $30m+ of PBT last year. On that basis, the $130m price tag appears to represent good value for WOSG (even if we acknowledge that Roberto Coin Inc is merely an importer and distributor).
And the strategic rationale? From an outsider perspective, that makes sense to me too. Luxury jewellery only represents about 6% of WOSG’s revenues (vs. 88% in watches), and I don’t see any harm in growing the jewellery side of the business.
Overall, therefore, this deal gets the thumbs up from me.
I’m going to very tentatively adjust my stance on WOSG from AMBER to AMBER/GREEN.
My reasons are:
I already thought WOSG might be approaching value territory earlier this year, and the shares are cheaper again now.
WOSG is deploying its balance sheet strength to achieve some non-organic growth and also diversifying the business in a reasonable way.
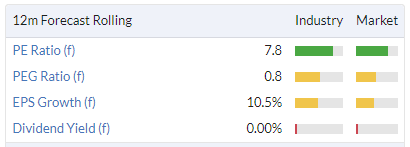
Risk levels here are more elevated than they were before, but the potential rewards for success are getting bigger too:
Frontier Developments (LON:FDEV)
Up 1% to 303p (£120m) - Jurassic World game announcement - Graham - AMBER
We had a trading update from FDEV on Tuesday, covered here.
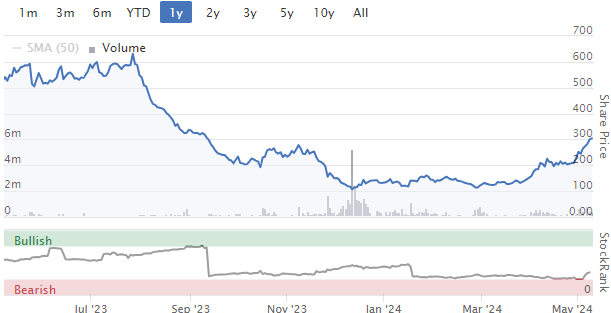
In Tuesday’s report, I observed that this video game company didn’t seem to have many exciting title launches coming up soon, and that they were in desperate need of a big hit.
They have answered the call today with the announcement of a third Jurassic World game.
This news was badly needed. The first two Jurassic World titles were two of FDEV’s most successful ever games. With two and a half years having passed since the most recent version was launched, it seems that now is a good time to start working on the next one.
In the company’s words:
Following the major success of Jurassic World Evolution and Jurassic World Evolution 2, which released in June 2018 and November 2021 respectively, Frontier and Universal Products & Experiences have signed a licence for a third Jurassic World game which is scheduled for release in Frontier's financial year 2026 ('FY26'), between 1 June 2025 and 31 May 2026. In February 2024, Universal Pictures and Amblin Entertainment announced an all-new Jurassic World event film currently scheduled for release on 2 July 2025.
A nice example of the “film plus video game” formula.
And here is FDEV’s new plan for future title launches, explicitly laid out in an RNS for the first time I think:
Over the next three consecutive financial years, Frontier plans to release one new CMS game per year; the development of the unannounced own-IP CMS game for FY25 is on track and Frontier expects to announce the title in the coming months; the third Jurassic World game confirmed today is scheduled for FY26; and a third unannounced CMS game is planned for FY27.
As noted above, the company’s financial year finishes at the end of May. Therefore FY25 is FY May 2025; a new game (whose identity is yet to be revealed) will be released at some point during this period - I would presume that this will be at least several months before Christmas 2024?
Then we will have Jurassic World in the following financial year, and then another game the year after that.
Graham’s view
This RNS puts to rest many of my concerns around future title launches. I was concerned that FDEV didn’t have much in the works, but we now have confirmation of a new game in the upcoming financial year, with Jurassic World to follow.
This means that I don’t need to hop into the AMBER/RED or the RED category just yet. FDEV might yet pull some rabbits out of hats, in the form of some successful game launches, and we now have some welcome clarity on their plans in this regard.
There’s still a lot to play for: video game development isn’t cheap and I’ll be keeping a close eye on FDEV’s shrinking cash balance. But at least we now have a much better idea of what FDEV will be working on.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

107 comments
Just looking at Argentex (LON:AGFX) latest RNS in regard to the placing. It got off £3.25m worth - so well short of the £5m target. The RNS doesn't mention the price paid (which I think was 45p) or the original target - presumably as that would be embarrassing for them - and also those backers are all sitting on pretty hefty losses (about 25%) - total shambles really.
In regard to the RNS - I don't remember ever seeing so much legal rambling on an RNS before - it goes on and on. Is this normal? Not that anyone should worry as there was a 'massive' purchase (RNS this morning) for 50,000 shares at 36p by the compliance and risk officer, so all must be fine.
Stockopedia | Argentex Group PLC - Result of Placing and Retail Offer | Argentex News (AGFX)
nb, just to add. The legal stuff that I didn't understand is -
Why is this information restricted if it has just been released as an RNS?
Why is it unlawful to share this information with anyone in the regions mentioned?
Further down -
Why is the content restricted and not for publication - why can it not be shared in certain jurisdictions?
Why does the company website not form part of the announcement?
Might all just be fairly standard stuff - but it looks a bit over the top to me - and I don't understand some of the above?
Also the RNS states the announcement contains inside information - so how was the compliance and risk officer able to buy shares 2 days before its release? I thought that wouldn't be allowed if you have a sensitive information RNS release pending.
All the legal regional specific jargon is typical placing legal template jargon.No idea of the intricacies of the uk or foreign law regarding this but i've seen it before.And perhaps the insider purchase was a scheduled purchase, possibly to do with employee benefits scheme or something?Otherwise no idea.I know US companies use schelduled share sales for management.Sorry i can't be more helpful.Hopefully someone else more knowledgable can help.
I agree the purchase wasn't a huge amount like On Beach group (LON:OTB) 's CEO or even substantial like with a NED's wife i think at Frontier Developments (LON:FDEV) buying £100 k around the lows.At least the company at Argentex (LON:AGFX) seem to have some record and experience in the game though.Bottom drawering for now.
From the BBC:
Troubled online used car retailer Cazoo is close to entering administration, putting about 1,000 jobs at risk.
The move marks a fall from grace for a company that became one of the darlings of the pandemic, when car buyers were forced to make their purchases online.
Total opposite to almost relatively recently bust Carvana Co (NYQ:CVNA).That, combined with the large short interest perhaps and their lenders Apollo's lenience, has been a multibagger (if you dared buy near the near bankruptcy lows or afterwards).There was an FT article i think i heard mentioned on LBC radio this morning about how over a $1 trillion in market cap has been lost from the pandemic darlings average peaks.
Interesting Guardian article about Cazoo today 'The London Stock Exchange has inspected the public numbers (as it would)and found that, of the 20 UK companies that have raised over $100m in the US over the last decade, eight have already delisted, only three are trading above their IPO price, and the rest are trading down by an
average of 71%.'.
Really don’t understand how stockranks are calculated on here
Card Factory (LON:CARD) has a ranking of approx 95 a few weeks ago
recently announced good results and reinstated dividends yet now down to 86?
Hi James, my understanding is the ranking is relative so quite simply it was overtaken by others despite the news, I agree it would be nice to have the exact calculation spelt out with the actual numbers rather than the high level help text
You can compare the current Card Factory (LON:CARD) StockReport with the May 2, print. I note the F score is down slightly, the EPS is less than forecast. Growth is very low. Quality and Momentum are both down.
Dividend is not showing on Stockopedia yet, so won't be included in the rankings.
Angling Direct (LON:ANG)
I thought might have been dragged down by the poor weather, but the weather has been good this week and they still haven't bounced
The screen of top stock ranks is up 15% YTD, 24% over 1 year and approx 30% off the October low.
Makes a very strong case for simply following stock ranks and not trying to over think stock picking.
It has done well recently, since October, 2023, but prior to that not so well, over the last 3 years, only +10.5%.
These are based on the top 25 stocks, in each category, not sure if rebalanced quarterly or not.
3i (LON:III) - excellent results today from this and their connected 3i Infrastructure (LON:3IN) the other day. Not only is it a 12.5 bagger since 2011, the dividend is now 28% of cost versus the 3% dividend yield. The power of compounding, when it works. This winner was just a case of investing in a competent cheap and slightly distressed investment trust in the aftermath of the GFC. The Action transformation was good fortune really. It just demonstrates to me that you can never really tell where the big winners come from!
Impressively 3i have not been tempted to sell any Action shares - they actually added a few more in the year to take their holding to 55%. Action, the discount chain, is worth an eye watering Euro 26bn. Most PE Houses would have cut and run a long time ago! 3i have committed to being long term holders. Will Action come to the UK I wonder?
This is the interesting point for me, why haven't 3i (LON:III) sold Action yet or when they do what valuation would it be. I hold
Action continues to expand at a rate of knots across Europe. There is plenty of growth left in Action and the retailer is well positioned for our austere times. I hold 3i and I only hold 3i because it is the only way to gain exposure to privately held Action, a company I used to supply back in the day. They have the slickest supply chain management in the business, and I have supplied M&S Food, Tesco, Sainsburys, Morrisons, Delhaize, Casino, Monoprix, Auchan, Metro, Manor in Switzerland, Gruppo GS and Euromercato in Italy. Action is simply the most professional out of all of them.
For me, I will sell 3i when they float Action as the rest of their PE portfolio is a bit meh.
Volex (LON:VLX)
As far as I can tell brokers have increased the earnings for this year and next. Volex (LON:VLX) reports in dollars and its recent strength is likely to be a contributory factor.
Anyway my recollection is that a few months ago, or so, earnings were 29 and 35 cents for this year and next. Stockopedia are now showing 32.2 and 36.1 cents respectively. Sharepad shows 32.2, 36.3 and 39.5 cents for this year and the following two, respectively.
Much to cheap in my view, hopefully I am proved right.
Definitely on board with your Volex (LON:VLX) view Jonno, but have a full position there already... top sliced Future (LON:FUTR) this morning which has had an outsized bounce these past few weeks .... looking to recycle into something that has not felt the love of the recent small bounce.... apologies for asking for help, but does anyone have any favourites that perhaps have been overlooked these past few weeks please? The only bad thing about sentiment turning is that it's harder to find the really deep value...
Good read across for Future (LON:FUTR) from ITV update where advertising revenue up 3% in Q1 and strong momentum into Q2.
Their growth acceleration strategy is progressing well. Shares look cheap on a very low p/e. Go Compare should be doing well. Could FUTR be a takeover target?
Gulf Keystone Petroleum (LON:GKP)
There is a lot of value here.
The pipeline will have to open some time this year as all parties involved are losing serious money.
Always diversify. Personally I never hold more than 5-7% in any position.
All the best
Many thanks indeed Yiannos1... I'm only carrying 81 positions at the moment, so a very long way to catch up to BnB's 200 haha... just as an aside... for me the number is that high so that I can learn from my mistakes more cheaply and in a more concentrated time period... very much appreciate your reply
A rarity yiannos. I agree with you about a lot of value in Gulf Keystone Petroleum (LON:GKP) . They have adjusted well to just local sales, and eventually the pipeline should reopen. Note that Gulf Keystone Petroleum (LON:GKP) paid 88p in dividends in 2002 until all payouts were cancelled because of the pipeline closure. The reopening of the pipeline is not priced in, and the share price has the potential to soar, but not until confirmation of the pipeline reopening or news that agreement is close. I hold and added recently.
Ken….. strange things happen in this amazing world of stock picking.
I am a bit worried now though about Gulf Keystone Petroleum (LON:GKP) :)
All the best
does anyone have any favourites that perhaps have been overlooked these past few weeks please? The only bad thing about sentiment turning is that it's harder to find the really deep value...
The following may fit - Saga (LON:SAGA) Somero Enterprises (LON:SOM) Sanderson Design (LON:SDG) Intercede (LON:IGP) Plexus Holdings (LON:POS)
Many thanks indeed Neville... I own 4 of the 5 , but can't quite get convinced to buy the other one regret
Hi Cancum, it does sound like you have plenty of UK Smallcap deep value already. If you are short of ideas on where to put your Future (LON:FUTR) top slicing cash and you want to play UK Smallcap value/recovery, why not buy some Rockwood Strategic (LON:RKW)
Not many of us are going to beat Richard Staveley's performance. So I have 15% of my portfolio in Rockwood Strategic (LON:RKW) as one of my plays on the long awaited UK Smallcap recovery.
Regards Neville
Volex (LON:VLX) Much to cheap in my view, hopefully I am proved right.
I'm of the same view and scratch my head to think why. In the end, I'm guessing it comes down to a combination of low gross margin - real quality industrials have GMs in the 40s and 50s, some even higher - and a listing in the neglected UK.
But it can stay on this multiple for all I care as long as it continues its run of double digit eps growth well into the future.
Hi BnB
It is the operating margin and revenue growth that one needs to look at in my view. Both are increasing. Operating margins should be close to 10% post the acquisition of Murat Ticaret, up from 9% to 9.5%.
All the best
James Cropper (LON:CRPR) Unabashed, base speculation.Background buyer of the shares the last few days post last TU.Could be a smallcap fund (if any are still active in the market currently!) trying to get in?£14 k worked purchase come through at around midprice (looking at the free 15 minute delayed data). where the only other trade at the time was at the bid, circa 10p higher.Not much volume moving the needle north currently though.Spread is still wide though.
Clarkson (LON:CKN) have put out a TU this morning ahead of their AGM - looks a bit wishy-washy to me. Thoughts Paul or others please ? (Yes, I hold)
Hi Paul, Re ITV (LON:ITV) and revenue forecast clarity. Huge UK Hit with Mr Bates v the Post office for ITV, their biggest success in a decade. Critical acclaim, kickstarting investigations into what went on @ the Post Office and bound to win TV awards, BUT it apparently lost £1M as It wasn't a storyline that they could sell abroad.
"We're hoping this may be because it caused such a furore here that maybe sales will pick up, but there's no evidence of it yet," he continued.
"If you're in Lithuania, four hours on the British Post Office? Not really, thank you very much. So you can see the challenges here."
https://uk.news.yahoo.com/mr-b...
Thought I saw somewhere that it was selling in places like Australia and of course there's the streaming revenue but suspect thats now very small.
Anyone know anything about the Foxtons (LON:FOXT) bid rumour?
https://www.stockopedia.com/sh...
The ITV (LON:ITV) actuarial pension swing is a good example of what I think we can expect to see across a number of other large pensions. I think Reach (LON:RCH) were one flagging the likelihood of this in their last results statement, which I mentioned at the time and we should find out reasonably soon.
People have dismissed the non actuarial Accountancy calculations of pensions schemes on here as being irrelevant because all that counts is the triennial, but that is missing the point. What the accounting values show should be a good indicator of the forward looking triennial review, so it’s worth looking at both in combination.
Reach (LON:RCH) I seem to recall that the 2023 results announcement in March stated that the 2022 triennial actuarial valuations had been completed, and that contributions were scheduled to continue at c. £60m p.a. until a sharp drop in 2028. If that is right, anyone hoping for improved cash flow from reductions in pension contributions is in for a long wait.
Re Angle (LON:AGL) in recent times, and over the years. Hello everyone. I haven't been around for some time on Angle (LON:AGL), and currently am not a shareholder.
I have been one for the bulk of the time between 2011 and now.
I held on at the time of FDA approval when I should have sold at +75% vs my holding cost at the time. Fell for that one. Should have sold the lot, and reinvested for the same amount of shares, or more at a fraction of the price.
Averaged down on the 80p fund raise. Second big mistake.
I sold out at roughly the current price which then subsequently fell to around 10p.
All of this, only myself to blame.
I am not a scientist. I regard myself primarily as a competent marketing man however. I will focus on the marketing opportunities with a realistic approach. I will add in the science as I see it.
My key point is that in the last couple of years I have been following developments at some distance. I now feel that I am now removed sufficiently from the detail and ready to do a summary of what I feel about the share going forward, and the legacy elements I can draw on which are important to my assessment.
I would like to put this out there for all of you followers to have a go at, to add to, to criticise - constructively of course as I would expect from such a band of Angle (LON:AGL) warriors.
Selfishly, I am looking for a way forward - to join in once again or to pack my bags for good and take my money elsewhere. It would be like leaving an old friend, but I have been sentimental about Angle (LON:AGL) for too long and need help to reinvigorate me.....or go the other way.
I don't know how to post something new on the Discussion Board in the form of a relatively lengthy assessment which I hope will be worth your involvement, so this comes as a reply to a previous posting. Please advise me you long standing warriors/sufferers on how I should go about taking it forward in the next few days.
I have put it on the initial FDA Approval Discussion board, and presumably I should do the same with my next stage.
Thanks for listening, if you got this far!
Angle
I don’t know much about the company but seeing 2 red scores on Stocko is strong No for me.
Sentimental investment is a common issue for most of us and I am a holder of Disney with a big loss for that reason.
Cancelled
### Not small cap - please scroll on if not interested ###
Given the inability to search through posts in the Discuss section I thought I would re-post one of my efforts from a few years back regarding the "stock count" discussion in comments below.
On diversification in general there seem to be four approaches:
1. Put your eggs in one basket - watch it very carefully (Warren Buffet)
2. Hold the maximum number of shares you have the time to monitor
3. Hold a concentrated portfolio to maximise divergence from a performance benchmark (i.e. maximise return on stock selection)
4. Take the mathematical approach of seeking to diversify away a large chunk of the stock specific risk.
I would argue Option 1 is for the full time pros who know their companies AND can afford to take a big hit without changing their lifestyle, or for the gambler who enjoys the ride.
Option 2 is for the keen amateur investor with a day job holding positions in a SIPP alongside a company pension, the enthusiastic private investor using an ISA etc alonside other savings.
Option 3 is for fund managers who need to market their fund and demonstrate they are not index huggers. By all means hold these funds (e.g. Fundsmith) but don't put all your money into just one of them! Hold a basket of them and mind the overlaps.
Option 4 is for those private investors who are "all-in" and rely on their portfolios to fund their livelihoods. It is not always possible to spot fraud, the unexpected happens, and the professional fund managers frequently get things embarrassingly wrong too. Diversify to protect yourself because you realise just how ignorant everyone is, and nobody can predict the future. The maths says you can diversify with as few as
20-25 holdings, but in practice you are looking at 50-70 stocks once youtake into account sector concentrations and factor correlations. If you include liquidity risk because you hold small & mid-caps then it can be sensible to hold well over 100 positions. I will take some flak for saying this as it isn't fashionable, but in investment being fashionable doesn't work for long.
Of course you can cut corners with ETFs, investment trusts etc, at the expense of paying someone else to diversify for you. They make a lot of sense for overseas markets... just try dealing in Japanese equities or reclaiming withholding tax from some other markets.
In fixed income you have an asymmetry of return (upside is the coupon, downside is 100% wipeout if no recovery post default). Corporate bond portfolios should be 125+ holdings or even higher (HY/junk being slightly different).
It costs very little to diversify, and over-diversification never killed anyone.
Excellent discussion. For me the main points are:
1. Diversification is an almost free way of reducing risk.
2. But, everyone needs to run their portfolio in a way that matches their situation and personality.
At some point, the extra gains from diversification become very small. Personally i like a 30 share portfolio, it has a lot of diversification but it is small enough to understand each company.
Never before seen ~50 to 70 stocks recommended, and even 100+ to include liquidity risk. Makes my nearly 90 holdings seem rather more respectable. Certainly I can’t monitor every one closely; and of course changes mean it is never truly ‘balanced’. But I don’t want it to be balanced: no tobacco, gambling or shady directors. I take hits all the time but they so far are outweighed by the successes, especially since I learned to ‘let profits run’ (at least some of them). As a newbie here I look forward to gaining more (some?) insight.
Frontier Developments (LON:FDEV) has rebounded sharply over the last few weeks although down massively from its high.
A third Jurassic World game announced today:
https://www.investegate.co.uk/...
Liberum up TP to 500p:
FDEV today announces the signing of a new license with Universal Pictures for a third Jurassic World game. This is being unveiled as the second of three new CMS launches slated for release over the next three financial years (to FY27). JWE and JWE2 (released 2018 and 2021 respectively) are FDEV’s top and second games by revenue generated in their first two years, with estimated revenues of c.£70m and c.£50m in year of launch respectively. This clearly puts substantial upside risk on the ~£20m we forecast for the 2nd CMS franchise for FY26E.
We remain cautious on the congested industry release schedule, and only add c.£15m to FY26E revenues for this CMS release, although this is partially offset by a c.£5m reduction in forecast JWE2 revenues. Our FY26E revenue forecast rises +12% to £104m, although gross margin moderates 3pp to 64% for FY26E (increase in licensed-IP share). EBITDA and FCF forecasts rise >100% to £7.4m and £7.6m. We raise our TP to 500p/share, with our TP underpinned by a 4.5% FY26E FCF yield and rising upside risk to numbers. BUY
Quarterly TU from Morgan Advanced Materials (LON:MGAM) tells us that revenue growth is good, but nothing more. Seems to be fully recovered now from the Russia origin cyber attack. There has been a long-drawn out repositioning of this company to more strongly growing markets which the current share rating ignores - a re-rating could be quite dramatic. On the other hand capex is heavy, and the dividend is not covered by free cash flow. Revenue growth is needed. I hold.
Mr. Peter Gyllenhammar
Seems a very smart investor
Keeps popping up with deep value investments I am checking out
Clearly smarter than me as invariable he’s in there 6 months before I look .
Must have a good chunk of cash to splash .
worth keeping an eye on his movements .
He had a large holding in two of my worst investments, one of which went bust, and the other is on the way. I think you might see him as a different kind of indicator !
Re: Gyllenhammar, I completely agree, a very astute UK small cap investor, I particularly enjoyed his chapter in 'Free Capital' by Guy Thomas.
Now I know of his stakes in Palace Capital (LON:PCA) and Pressure Technologies (LON:PRES) but what else have you come across?
Just bought over 3% in Robinson few weeks ago
He's been in LPA (LON:LPA) since Jun21. Now with a 26%+ stake.
However, I don't think the share price has done much in that time.
It is a deep value small cap.
As Burnt Onions mentioned Peter Gyllenhammer holds a significant position in Palace Capital (LON:PCA) , from memory 13% or thereabouts. I have a reasonable position and am looking forward to the indicated return of capital and hopefully well priced tender offer.
You can see his investments/activities here: https://pg-ab.se/en/
It might be slightly out of date. For example his website lists DCI Advisors (LON:DCI) as a current holding but whilst he used to appear on the Stocko major shareholders for DCI Advisors (LON:DCI) . he seems to have dropped off at some point. And as Burno Onions says, he has appeared on the Pressure Technologies (LON:PRES) register, but this isn't on his website (yet).
Shame to hear the BBC bash UK PLC again this morning with a poor and unbalanced article on delisting of E-Therapeutics. CEO bleat was pathetic imo. Visited this outfit several years ago under a different CEO. Seemed a hopeless cause then. Never commercial and has yet to reach £0.5m turnover. Richard Griffiths taking it private with a 30% holding seems a good and sensible end to their public life.
I've heard about and seen Griffiths investing substantially in terms of percentage ownership in a fair whack of more bluesky/puntier aim companies going back a few years.I wonder what his overall strategy is here financially.I've been diluted and lost a lot with some of these ilk of companies like many, but always been a minnow and never been a major shareholder.
Hi, can you provide link to this article please? Thanks
Hi Dulpesh
It was on Radio 4 Business News this morning.
Hardly bashing the UK. Merely stating a fact. Yes, E-therapeutics is a minnow, but de-listing from London is a real concern - caused mostly by Brexit and pension providers being obliged to invest in bonds rather than shares. When companies list in London, the BBC (R4 business news) covers those too.
Character (LON:CCT) prompted by a discussion on Twitter I had a look at directors salaries
2023 was clearly a tough year for management as they didn’t get bonuses but 2022 saw J Driver earn a total of £1.01m, K Shah £790k & J Kissane £615k
Shades of Tclarke (LON:CTO) ?
Well spotted
I remember that I looked at character and it was exactly this that put me off .
Far too high salaries in relation to turnover , profit and performance .
Run for the hills when you find this .
To your discussion point, Paul. By contrast, I run a 200 position fund in order to achieve geographical and multi-currency diversification across my specialist sectors of Technology, Industrials and Healthcare. This does not just mean holding assets in a range of different currencies, but also having exposure to competing businesses across USD and at least one of GBP, EUR, CHF, SEK and JPY, which tends to flatten out the distorting effect of currency movements on performance. However, since the start of 2023, I run two dummy portfolios of 30 and 50 stocks taking the “best” ideas from the fund. This is in an effort to test the theory that smaller portfolios perform better. Over the 16 month period to date, all three portfolios have performed almost identically. My take is that either diversification is not diworsifaction in my case, or, more likely, I’m just not a good stock picker!
Well everyone has to be comfortable with their own level of risk and diversification, BnB. However, there is virtually no way in which you will substantially outperform the market with that many stocks. At an average position size of 0.5% they simply won't move the dial. There are also many issues such as;
1. High dealing costs
2. Difficulty keeping track of how each investment is performing
Have you considered getting your diversification and reduced risk by perhaps switching, say, 150 stocks into 20-25 Investment Trust holdings that are well spread by geography and sector then trying a 50 stock fund of your own? You might find that approach more successful and, importantly, more fun! I am only guessing, but it might be that once you are putting all your energy into just 50 stocks rather than monitoring 200 you achieve a better performance? But its your choice at the end of the day.
I previously had a 160 stock portfolio and had a buy-and-hold philosophy, but gradually I became irritated by the number of saggy stocks (that I originally intended to ignore on the basis that there would be a few multibaggers in the mix) and have whittled down to a more actively manageable 60, which I would like to trim to 30. I was certainly aware that having such a large number of stocks pretty much assured me an "average" return.
However, there is virtually no way in which you will substantially outperform the market with that many stocks.
What makes you think this is my objective? I simply want to be aligned with secular growth drivers.
1. High dealing costs
2. Difficulty keeping track of how each investment is performing
As for dealing costs, it’s a buy and hold portfolio. It’s not like I’m swapping 200 stocks each year. Although I’m not averse to opening new positions , many of my holdings haven’t been touched in years. In cash terms, I doubt the turnover rate is any higher than for a 20 position portfolio.
Difficulty tracking so many positions? Seriously? These aren’t obscure small caps and special situations. The market does a lot of the work for me - when Microsoft updates do I really need to study their annual report to find something everyone has missed? And I have analysis available on every company from my bank, Morningstar, and other sources. It takes time, admittedly. But I have plenty of that and it’s a fascinating intellectual exercise.
BnB
I guess it’s horses for courses and whilst 200 stocks sounds nuts to me if it’s what is right for you that’s good
I think balanced portfolio actually should apply to a persons overall wealth
For example I only have 8 core holdings and 8. 1/2 positions .
That’s probably nuts to most investors on here
However that’s only 30% of my overall investments and I’m 30% in forestry (actual forest not fund) and so it’s not as extreme as it seems
The best advice I ever had was from KPMG who advised me when I sold my business
- treat your overall wealth as a series of pots
- put a certain % in each pot and stick to that
- decide risk factor on each pot
Sit back and look at all your pots and see if you are happy with the risk / reward / overall feel ,
So if stock market tanks or one of 8 stocks goes totally bad (like holders got hammered ) I’m At a max loss of 1/8 of 30% .
What I tend to actually find in many asset classes actually rise and fall together , eg stock market down 20% forestry down 20% etc
So many different things appeal to different people
Having said all that personally I found anything over 30 shares held I just ended up with a headache and inability to stay focussed , jumping around too much
With a low number forces you to learn about a company and sit and hold even when the market is not agreeing with you and driving the price down .
From memory something like 15-20 stock positions can give you the relevant diversity but what I would say is that often investors think that diversification means just buying different stocks and it doesn’t.
The smaller number of stocks you own the greater degree of separation you should look for. People tend to gravitate - like children round a football. So if you own a small number of stocks think about all the venn diagram cross overs and decide how correlated they are. For example if shipping routes are heavily disrupted how many of your stocks will be impacted or if semi-conductor supply gets cut off. If interest rates change does everything go the same way etc.
Then look at your pots and consider how those asset classes correlate based on history but ALSO current market conditions. For example if you asked me 5 years ago about investing any of my pots into bonds I would have laughed at you. They were so clearly in bubble territory it was completely obvious that if the macro changed the impact on stocks and bonds would be similar. That’s different to historic trends so you have to think about both.
Interesting discussion on diversification. I agree with your approach ... put your wealth in pots: farming; forestry; bullion; property and stocks and shares. The pots may or may or may not be correlated, but holding the bulk of one's wealth in illiquid assets like farming and forestry stops knee jerk reactions, especially if those assets have been held for multiple generations.
My stock market holdings amount to 33 shares which I often think is about 13 too many as I struggle to follow anything over 30 holdings. The research shows that the diversification benefits fall dramatically after 15 holdings. The term Diworsification was first used by Peter Lynch and referenced a company moving beyond its core competency by acquiring non-core businesses; it does not reference the number of holdings in an investor's portfolio.
One last point is that I try and stick to my circle of competence: defence; agriculture and food, retail, energy and mining. I generally avoid tech, biotech and pharma.
Anyway, each to their own. I belong to a small investment group with members in Germany, Israel, Ecuador, NZ, the USA and the UK. We talk every week. It is clear to all of us that we all have very different approaches, but we all make money ... just not always at the same time. I don't think there is one right way; only one way that makes sense to you.
Spot on James I think it was you that did a post a few weeks back about a portfolio that had pretty much been left alone and had returned 12-14% per annum. I'm moving towards 20 core trust/etf holdings as although I love this game I don't do much better than the market/good fund managers for a lot of effort time I put in.
I intend to hold some gold, an oils trust and BlackRock World Mining Trust (LON:BRWM) , the rest of the exposure will be 50% global growth trusts and 40% in defensives bonds and possibly 3i Infrastructure (LON:3IN) .
A crucial point I have learned to my expense is if you hold a good range of relatively vanilla trusts in different asset classes tinker at the bare minimum theres so much stuff I have jumped out of thinking the sector was out of favour and then watch it steam back up 6-12 months later.
I intend to start drawing a bit of my pension in Dec so will put two years worth of intended income into two seperate money market funds and then split the rest of the money over 18 other trusts,funds and etfs in equal shares with monthly rebalancing.
I'm reasonably confident with quality trusts/funds longer term I will average out around 8-12% per annum and I can then check in a couple of times a week for max of 1-2 hours and find a new hobby that hopefully I can be better at.
Fair play to BnB with all those holdings which sounds a lot of work but I get the impression he loves doing it and I also get the impression he's probably in the top 10% of investors returns wise as comes across as someone who knows his onions.
Regards Andy
Thanks Andy and yes that is another good point ... one's age. There comes a time when it is time to go fishing and enjoy the grandchildren!
Agreed James I'm 55 in Dec this year, happy to continue working part time but planning on having thurs & fri's off and take 8 weeks off per annum, thankfully I'm in good health but equally aware I might only have twenty or so years left on this planet even though still feel 18 in my head.
I'm fortunate I love what I do and work for myself and can pick and choose my clients with a view to steering clear of the 1% of the UK population who are serial complainers.
Have a good weekend the weather is finally looking great.
Regards
Andy
Well in that case you have answered your own initial question. It looks as though you are only looking to gain exposure to sectors where you think the secular growth profile looks right and you are more concerned with the macro picture than the minutiae of individual stocks. That's fine, but I don't believe that its active fund management.
Well in that case you have answered your own initial question.
I don't recall asking a question!
you are more concerned with the macro picture than the minutiae of individual stocks
Yes, I might make small adjustments if the macro dictates a shift in emphasis. For example, I've mildly increased my weighting to cyclicals recently. But why do I hold AMD and not Intel, Schneider Electric and not ABB, Microsoft and not Apple, AstraZeneca and not Roche, Stryker and not Medtronic? I could go on with 195 further comparisons. First I pick the growth opportunity, then I find the highest quality businesses and buy them - I'm pretty price agnostic. If a company proves a poor choice, I let it go and replace with my best new idea. It’s just possible you'd be surprised by what I can tell you about each of my choices, the rationale for them and their latest updates. But you're happier making assumptions.
I suspect BnB knows exactly what he is doing.
Provided you don't trade too frequently it is much cheaper to have your own portfolio of directly held stocks than to pay a fund manager or pay the board of an investment trust to be clueless about what the investment manager is up to. You also have much more freedom to manage your CGT situation.
In practical terms the biggest constraint is on managing your cash levels - making sure you don't build up excessive cash balances across a multi-currency portfolio can be demanding. Parking money in ETFs while you plan single stock purchases can help.
I do use investment trusts for some overseas markets, but they come with their own problems. Just talk to any Hipgnosis or Home REIT holder (I'm picking the letter H as an example...if you go back a letter you can choose from a selection of Gresham or Gore St efforts....)
Provided you don't trade too frequently it is much cheaper to have your own portfolio of directly held stocks than to pay a fund manager or pay the board of an investment trust to be clueless about what the investment manager is up to. You also have much more freedom to manage your CGT situation.
This. It’s a global fund over which I have complete control and free of charges.
There is CGT if you are a UK resident.
Anthony Bolton used to hold lots of stocks in his Special Situations Fund at Fidelity, yet he and that fund were one of the most successful combinations in investment history. I take issue with "outperform the market" comment (in a discussional way and hopefully with the kindness that we both might learn something). It depends how you define the market? Anthony did well because he held stocks that were not in his market. Market in this case being the benchmark. I think used FTSE All share (but please correct me if I am wrong). The point is if I want to match the market I just balance stock choice and weight of individual stock to the index. If I want to out perform (and underperform) the market I can pick the same stocks but weight them differently, or pick stocks that aren't in the universe or do both. Replicating the market was the "low" risk choice back then because you got the index performance (which was an interesting conversation with Trustees around in particular 2000 and 2008!! "Didn't we do well we outperformed!" "Yes I understand that you are down 40% but we are only down 38% so we outperformed the benchmark by 2% as your mandate requires?") Why did Neil Woodford earn his name, well partly because he ignored IT stocks in the run up to 2000 as did Anthony Bolton. Was that risky? Therein lies another discussion.
Good point. Essentially a bar bell approach, say half in a massively diversified fund like a world tracker, and then half in say 50 shares where there is no diversification consideration just high return.
Your suggestion is close to what I have been doing for the last 15y
40% passive global equity all the time
60% uk about 20 to 30 small to med cap stocks. In the early days picked myself, had some success, then when I thought I was clever it all went wrong. Now (last 5y) the possible universe to pick from is high SR or 'approved of' here and this reduces my chances of loss.
Works for me.
Agreed - I'm currently running 179 positions (admittedly across 8 or so portfolios).
People obsess over whether they can outperform an equity index, when they would be better off spending time ensuring they get their asset allocation right.
Outperforming an equity index is pretty meaningless if you have the wrong % of your assets invested in equities to start with.
Totally agree Monty. The problem is though Asset Allocation (aa) risks are always far higher than stock selection risks. For aa I probably take 3 or 4 decisions and getting one wrong has a huge impact on performance whereas a diversified stock portfolio reduces individual choice risk. E.G. So far this year I made a blooper by buying James Cropper at £8. They have halved but my portfolio is up over 15%. That for me is risk control. But I suspect if you ask those back when COVID broke heavily invested in UK small cap what decision hurt them? I would be interested to know how many of them have made their money back given £1 to 50p is 50% downside but 50p to £1 is 100%.
' I made a blooper by buying James Cropper at £8. They have halved'
If you still hold James Cropper, then an effective risk control measure would have been to sell it when it reached a predetermined stop loss price.
If you still hold James Cropper, then an effective risk control measure would have been to sell it when it reached a predetermined stop loss price
A quick look at the chart for 17/1/24 will show you that a stop loss would have done nothing to prevent a holding being cut in half
wow! £12 for a round trip into and out of a stock is £2,400 just in dealing costs. I have 12 in my ISA and 15 in a SIPP. That's plenty.
£12 for a round trip into and out of a stock is £2,400 just in dealing costs
I don’t follow. Please can you elaborate?
£6 to buy and £6 to sell. £12 x your total holdings of 200.
How do you know it is £6? Many platforms have lower dealing fees now. Maybe he uses Interactive Brokers (NSQ:IBKR) ?
I just assumed mate!
£6 to buy and £6 to sell. £12 x your total holdings of 200.
Thanks for clarifying. I would suggest that what matters is that your charges are proportionate to the size of your portfolio and your activity levels. Although I have an account with Hargreaves, where the transaction fees are at the high end, for my very small representation in UK small caps, the low spreads and higher than average liquidity are ample compensation. But the huge majority of my portfolio sits on my bank’s e-trading platform where there are negligible transaction fees and almost no stamp duty (being an international fund). Of course, there’s no such thing as a free lunch. The bank charges a meaty holding fee to cover the value of its custody, its research and the cost of my advisor. But even this is amply defrayed by the access this gives me to their options desk, where I actively trade puts and calls for income generation - my holdings typically being low or zero dividend payers.
"To your discussion point, Paul", could someone point me to this discussion point please as I'm struggling to find it. It sounds interesting. Thanks
could someone point me to this discussion point please
First post of the day
of course, I thought it was refererring to Paul Scott not Paul Hill, doh !
As John Authers reminds us this morning Markowitz said that diversification is the only free lunch investment offers us.
Wow! I have 11 companies that I have ownership in and it takes up a lot of my spare time, and I cannot remember all of the CEO names, but I think I understand all of their individual characters. I think I could do 40 if I didn't have to work. Anyway, I am up to my limit for how I like to act - but each to their own. Good hunting.
How many stocks to hold
I retired a few years ago and became my own fund manager!
I invested, traded, shorted and whatever else was doable. I held around 100 stocks including the magnificent seven.
I also put 20% of my money in Vanguard all cap all world for security and comparison.
The Vanguard has beaten me squarely on most of the time frames and in total return.
I enjoyed the intellectual challenge and entertainment. But financially I would have been better off with the vanguard, Fundsmith or JGGI.
You would have been better off doing a tracker than Fundsmith "Fundsmith Equity, managed by Terry Smith, has underperformed its benchmark for three calendar years in a row. In 2023, his global equity fund returned 12.4%, which was below the 16.8% return for the MSCI World index,"
I do hold Fundsmith but it has not performed very well, especially considering it is around 70% US stocks.
I do wonder if it gets harder for these popular funds to outperform as tidal waves of money flows in there must be a point where you have so much cash to deploy you have to steer towards mega caps for liquidity reasons if you want to sell and you end up morphing into some form of tracker.
Yes there be problems for large funds but Fundsmith is mainly invested in US large caps, so should not be a problem. IMO, he made some serious misjudgments with PayPal Holdings (NSQ:PYPL, selling far too late and Adobe (NSQ:ADBE) and Intuit (NSQ:INTU), selling too early, both have gone up considerably since he sold. He also missed out on some big tech risers such as NVIDIA (NSQ:NVDA) etc.
Interesting to see Fundsmith start a position in Texas Instruments (NSQ:TXN. Not prone to huge drawdowns like most semiconductor stocks, and a big beast - but still a cyclical, with relatively commodity-like products.
Yes l saw that, had a look at Texas Instruments (NSQ:TXN) but the growth forecasts are not very good. Think there are better alternatives.
Yes l saw that, had a look at Texas Instruments (NSQ:TXN) but the growth forecasts are not very good. Think there are better alternatives.
Indeed. I considered a wide range of options for my choice of analogue chipmakers. In the end I plumped for Analog Devices (NSQ:ADI) and Infineon Technologies AG (ETR:IFX. The latter was very good value a week ago!
I wouldn’t view the performance over 1 year…his long term performance is pretty good!
That is over the last 3 years, he has underperformed the index, 3 years running. Yes it was good until about 3 years ago.
200 stocks worldwide portfolio? I Would instead buy an MSCI World ETF, surely cheaper, and pick up another hobby on the side with the time I will spare. Unless I can beat the index by selecting 200 stocks.
I Would instead buy an MSCI World ETF, surely cheaper, and pick up another hobby on the side with the time I will spare
But that wouldn't contain the companies I like in the proportion I want them. And perhaps I don't view it as a hobby :-)
Fair point.
My morning smallcap tweet: Dullish beats bullish, often as not
Robinson (LON:RBN) Avon Protection (LON:AVON) Eckoh (LON:ECK) Arecor Therapeutics (LON:AREC) Triple Point Social Housing REIT (LON:SOHO) DG Innovate (LON:DGI) Graft Polymer (UK) (LON:GPL) Character (LON:CCT) Light Science Technologies Holdings (LON:LST), Synthomer (LON:SYNT)
◄Robinson (RBN)► AGM stmt - guides FY24 rev up YoY and op profit c. £3m up 36%, both ahead of market expectations . [SP=105 Cap=17m]
◄Avon Protection (AVON)► wins £38m (max) MoD order for a General Service Respirator. FOur yr contract with five further 12-month option periods. [SP=1234 Cap=375m]
◄Eckoh (ECK)► guides FY-Mar rev c.£37.2m, missing F/C of £38.9m but adj op profit c.£8.3m, £0.1m ahead of F/C due to "higher proportion of cloud-based SaaS revenues and ongoing cost efficiency". [SP=42.78 Cap=124m]
◄Arecor Therapeutics (AREC)► Medtronic to fund Arecor's development of Arestat insulin for use in combination with a next-generation implantable pump. [SP=137 Cap=42m]
◄Triple Point Social Housing REIT (SOHO)► reviewing the terms of the investment management arrangements to further align them with the interests of shareholders. [SP=60.8 Cap=239m]
◄DG Innovate (DGI)► £786k placing at 0.1p, an 11% discount, for "short term funding to support the establishment of the joint venture with EVage Automotive" and strengthen the BS. [SP=0.11 Cap=11m]
◄Graft Polymer (GPL)► update on recent developments which oddly has nothing new. [SP=0.16 Cap=m]
◄Character Group (CCT)► H1-Feb. Guides FY pretax above market expectations. [SP=275 Cap=52m]
◄Light Science Technologies (LST)► exclusive distribution agreement with agricultural automation provider AgriLogiq Technical Systems in South Africa. [SP=2.8 Cap=9m]
In line: SYNT
DG Innovate (LON:DGI)
Placing at 0.1p-Obviously the Mrs. did not know anything when selling at 0.17p and not declaring it.
She just did not know the rules!
Macro vs Micro
Many successful investors claim they are 100% bottom up stock pickers, and ignore the macro.
Companies though don't operate in isolation & are instead impacted by the external environment.
Hence to me, one needs to also have a view of what's going on 'Big Picture'. But similarly recognise the economy is immensely difficult to predict accurately.
Indeed, just look at how the best minds in Wall Street have struggled forecasting the number of US interest rate cuts (see below) in 2024. Predicting in Dec'23 1.75% of #Fed easing this year, but only 0.25% now.
So what's the answer?
Here I try to align both 'bottoms up' & 'top down' scenarios. Yet equally accept there is a high degree of uncertainty (62% hit rate) wrt my analyses - especially over a 12-24 month view.
Plus when it comes to asset allocation, I try to avoid 'betting the farm' on just one perceived 'home run' (however great).
Instead running a more diversified (but still concentrated) portfolio (eg 15 stocks) to help smooth out the inevitable & frequent losing positions.
Buffett alluded to this in the last Berkshire meeting. Asked if he thought 2024 was similar to 2000 prior to the tech bust he said he didn't know. But he was finding it hard to find companies that offer a high return on capital, hence the massive cash holding.
Buffet holding a massive cash holding shows very clearly where he thinks we are in the US cycle, in my view. He will deploy capital when the time is right. Actions speak louder than words here as Warren Buffett is very careful in ever criticising the US economy although he did make some political comments this time around on the deficit which was making the Feds job very difficult.
I think he was referring to large caps. There are plenty of cheap small caps with high ROIC in the US and in the UK.
Totally agree Paul. Everyone takes a different view and in an environment of relative certainty for growth which I think fairly summarises the world since the end of the second world war, it is a fair bet that global GDP growth will occur and a long term bet on equities seems a fair bet. However where that certainty breaks down the long term equity bet breaks down. So you have to take more interest in macro events. My own view is that never ending GDP growth is a pipe dream laid down by politicians trying to get power. In the end all wealth comes from nature and as it breaks down uncertainty increases. My favourite was a piece written on one of the majors quote "the oil industry believes people have to make a choice between the economy or the environment" believe me that is no choice at all driven by an industry which has lost sight of reality.
‘If anyone believes you can have exponential growth on a finite planet they’re either mad or an economist’
Kenneth Boulding