Small Cap Value Report (Thu 9 Nov 2023) - SFOR, ACT, VID, ADF, ZOO, AGFX, WRKS, PCIP

Good morning, it's Paul & Graham here!
Right, we're all done for today. I'm off to 'spoons for some fish & chips, as I enjoyed it so much on yesterday's mystery shop.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
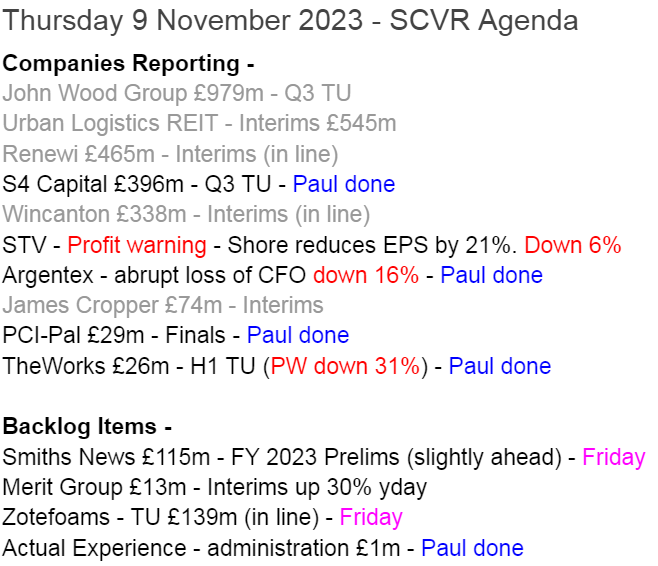
There's a fair bit of news today, so we obviously won't be able to cover everything, here's the list - I've greyed out some "in line" updates that don't look very interesting -
Summaries
S4 Capital (LON:SFOR) - Down 13% to 58p (£341m) - Q3 Trading Update (profit warning) - Paul - BLACK/RED
Another profit warning from Sir Martin Sorrell's mainly US-based digital advertising group. It's expanded too fast, run up too much debt, and profits & cashflow look suspect, coming from many & large adjustments. I remain highly sceptical.
Actual Experience (LON:ACT) - jam tomorrow company goes into administration. Closing our notes on it below, with some brief observations.
Argentex (LON:AGFX) - down 18% to 65p (£73m) - CFO Resignation - Paul - RED
What on earth is going on here? Shares in this FX company tumbled 22% to 75p on 26 Oct 2023 (we covered it here) on news that the CEO (12% shareholder) had abruptly resigned, with no explanation as to why. I speculated that, based on a wobbly outlook comment in the last interim numbers, there could be a profit warning brewing possibly?
Today, just 20 days after the CEO walked (or was kicked?) out, the CFO has also resigned!
Paul’s opinion - shareholders need to be told what’s going on. I think the Chairman should now feel obliged to be open and honest about why the company has lost both its CEO and its CFO in rapid succession. Obviously shareholders are going to be worried, and it’s not right to leave the owners of the company in limbo like this.
The last balance sheet looks OK to me, so solvency doesn’t seem to be an issue, unless there’s been some calamitous breakdown of internal controls/IT? That would be my main worry for risk, in a company that has large flows of money in & out.
We need answers, pronto!
Hollywood Actors Strike - the BBC reports that a “tentative deal” has been reached to end this strike, which has contributed to poor performance from several UK shares exposed to TV/film.
This seems to be the reason for the following price movements today - together with our last comments here on each company -
Videndum (LON:VID) - up 14% (SCVR 26/9/2023 - uninvestable for me, until it has refinanced)
Facilities by ADF (LON:ADF) - up 13% (SCVR 3/8/2023 - I concluded it might be worth a dabble, after PW)
Zoo Digital (LON:ZOO) - up 10% (SCVR 28/9/2023 - PW. Might be a turnaround once Hollywood strike ends?)
Nice trades there, well done to holders. It’s an unforgiving market though, and sellers often use the liquidity from good news to ditch more of their shares. Time to bank profits on the good news? What do holders think?
Works co uk (LON:WRKS) - down 31% to 27.6p (£17m) - H1 Trading Update - Paul - BLACK (profit warning) - AMBER/RED (on fundamentals)
Trading has deteriorated recently, as consumers rein in spending, and hence are forcing WRKS to discount more. Forecasts lowered to only £1.0m PBT for FY 4/2024. Looks a marginal business to me, worth very little I think.
PCI- PAL (LON:PCIP) - Down 7% to 41p (£31m) - FY 6/2023 Results - Paul - AMBER/GREEN
I weigh up the bull & bear points below, coming out moderately positive overall.
Paul’s Section:
S4 Capital (LON:SFOR)
Down 13% to 58p (£341m) - Q3 Trading Update (profit warning) - Paul - BLACK/RED
This is Sir Martin Sorrell’s digital advertising group, which we are most definitely not fans of here at the SCVR. We’ve reviewed its announcements 4 times this year (11 May, 9 June, 24 July, and 18 Sept), concluding RED every time, with the recurring theme being its weak, over-geared balance sheet (from too many acquisitions on an inadequate capital base), and complicated accounts full of adjustments required to conjur up adjusted profits. I see little evidence of what I would call genuine profit or cashflow.
To add to that list, we have another profit warning today, on top of continuously falling forecasts, which it now says it won’t meet.
Today’s update is, what I would call gibberish. This is supposed to be a communications company. Here are its headlines - can you make any sense of this, as I can’t! -
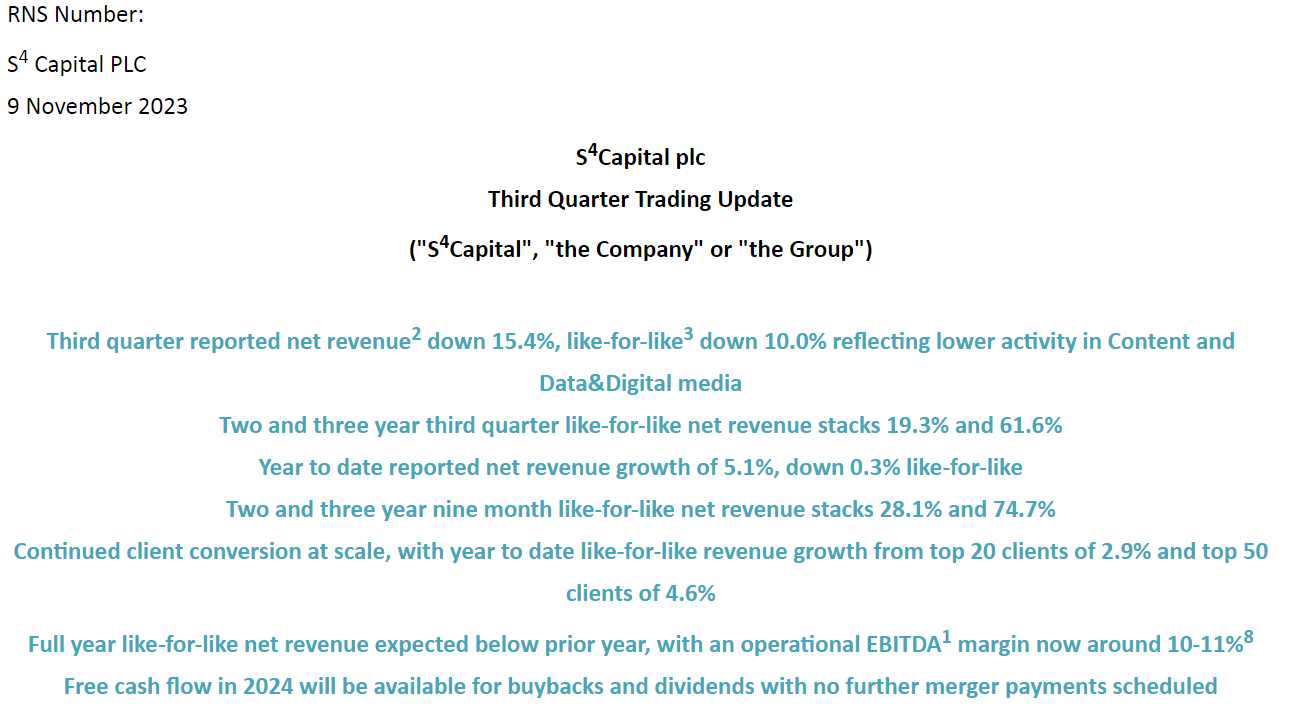
Thankfully, Dowgate Capital (via Research Tree) come to our aid in clearing the fog, many thanks to both.
Key points are -
Yes, it’s a profit warning. EBITDA guidance was 12-13.5% range (for FY 12/2023), it has today been lowered to 10-11%.
Heavy Q4 seasonal weighting, as in previous years (which introduces further risk I’d say)
Deteriorating revenue trend within 2023.
Dowgate forecasts 4.7p EPS for FY 12/2023 (previous forecast 6.7p), a PER of 12.3x
SFOR says larger clients are still showing growth, but smaller clients cutting back.
Note that most (79%) revenues come from the Americas.
Net debt £185m at end Q3. Expected to be c.£220m at Dec year end, due to the last deferred consideration payments being made.
Debt covenant seems loose at 4.5x, and Sir Martin doesn’t seem concerned about debt.
Hoping to see EBITDA margin return to “historic levels of 20%+”
Paul’s opinion - I very much dislike the numbers from SFOR - explained in detail here on 18 Sept 2023, when I dissected its interim results.
It strikes me as bizarre that SFOR is today talking about dividends and share buybacks in 2024, when surely debt reduction should be its priority?
What about a cyclical recovery then? The US tends to have short & shallow recessions (if it has one at all), so SFOR shares might come surging back if it starts reporting growth again. The trouble is, I don’t see any track record of proper profitability at SFOR, even when economic conditions were better. For that reason, I’m not at all convinced there’s a good company here, as there’s no evidence of it as yet.
So it’s another thumbs down I’m afraid. There could be a trading bounce in this share at some point, but on fundamentals it looks very poor I’m afraid. It’s not cheap either, with an enterprise value of c.£560m, even after its collapse in share price, losing c.93% from the bonkers Aug 2021 peak.
Generally speaking, I’m not a fan of startups where some star manager tries to recreate former glories. It’s surprising how often they’re not able to do it, especially when macro conditions are tough. Yet investors are asked to pay up-front with a lofty valuation before anything has been achieved. Risk:reward has turned out to be very poor on SFOR. So far anyway.
Actual Experience (LON:ACT)
Shares suspended - gone into administration - Paul
Another one bites the dust. I remember when ACT floated in 2014, as an excited fund manager rang me and told me what an amazing company it is, and to buy some shares almost at any price. The story was that it analysed the user experience of websites, thus making them better.
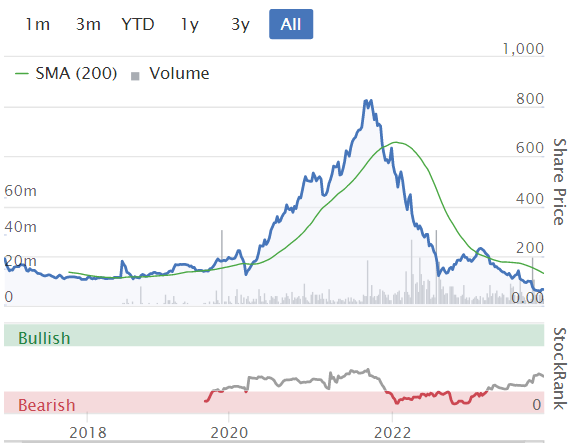
As you can see below, its financial performance was hopeless, with revenues not getting above £2m pa, and losses typically of £5-7m pa. It burned through a decent cash pile, then had to start doing more placings.
Investors have obviously now declined to pour more money in, and the company has gone into administration.
Yet another AIM story stock that promised the world, and failed to deliver.
Keeping away from loss-making story stocks (where there’s no proper business) has got to be one of the key investment lessons that some of us need to re-learn every few years! I have to constantly remind myself of this, with my latest lesson re-learned being the WANdisco fraud last year.
Works co uk (LON:WRKS)
Down 31% to 27.6p (£17m) - H1 Trading Update - Paul - AMBER/RED
The Works, the multi-channel value retailer of arts, crafts, toys, books and stationery, announces an update on trading for the 26 weeks ended 29 October 2023…
Not good, this update. It says “consumer demand has softened further” in the last 9 weeks.
“High degree of uncertainty” over forecasting for the key Christmas season.
Revised guidance - good clarity of reporting here -
Taking into account the level of uncertainty with regard to sales, and our expectation that it will be necessary to continue to maintain a higher than planned level of discounting to remain competitive, we have revised our estimate of the likely full year result for FY24, and now expect that the pre IFRS 16 Adjusted EBITDA will be approximately £6.0m.(2)
(2) | The Company compiled estimate of the market's expectation for the FY24 pre IFRS 16 Adjusted EBITDA result prior to this announcement was approximately £10.0m. |
Looking back at the FY 4/2023 results, it made £9.0m adj EBITDA, but £10.1m adj PBT, which looks wrong, as PBT would normally be lower than EBITDA. A footnote said -
The FY23 Adjusted PBT is greater than the pre IFRS 16 Adjusted EBITDA because of the effect of IFRS 16. We would normally expect the Adjusted PBT to be less than the pre IFRS 16 Adjusted EBITDA. Please refer to page 14 of this report and note 3 of the condensed financial statements for further information. |
I can’t follow this, so have no idea what is the significance of EBITDA being higher than PBT.
It’s not worth spending time on trying to figure it out, as I’ve no intention of investing in this share anyway.
There was a very long going concern note in the FY 4/2023 accounts, which included a “material uncertainty” - I normally try to avoid investing in anything that has such a warning, as it indicates high risk of dilution or insolvency in a downturn.
Liquidity - this sounds OK, I don’t expect WRKS to go bust any time soon - unless it has a really dire Xmas season -
The Group had net bank borrowings of £2.5m at the Period end, reflecting the build of stock prior to the peak trading season, and the corresponding low point in cash levels. There was £17.5m of headroom within our £20.0m bank facility.
The last balance sheet had negligible NTAV, and the lease entries show a large deficit, so there must be lots of loss-making shops.
Paul’s opinion - this is a marginal business, that is worth very little, in my opinion.
It’s done well to survive the pandemic, thanks to generous taxpayer support of course. But it looked a marginal business pre-covid too, remember the shares were a dismal float in 2018, and lost about ¾ of their IPO value before the pandemic even began.
I wouldn’t rely on the dividends, as I think this business has little dividend paying capacity.
The bull case is that management seem to have done some good things, and kept the business going, but it’s barely trading above breakeven now - Singers kindly crunch the numbers, and now forecast only £1.0m adj PBT (down from £10.1m LY) for FY 4/2024.
It should manage to get back into a net cash position by year end next year, due to seasonal cash flows.
Where’s the upside going to come from? Maybe if energy costs reduce considerably, and wage growth moderates, and consumers start spending more, that might help get it above breakeven in future?
Overall it just looks a low quality business that’s probably going to mainly be focused on survival, rather than creating any shareholder value.
So for me, it’s going to have to be AMBER/RED, after this latest profit warning, and less than sturdy finances. There are plenty of other more profitable retailers, on reasonable valuations, so why scrape the barrel with this?
PCI- PAL (LON:PCIP)
Down 7% to 41p (£31m) - FY 6/2023 Results - Paul - AMBER/GREEN
PCI-PAL PLC (AIM: PCIP), the global provider of secure payment solutions for business communications, is pleased to announce full year results for the year ended 30 June 2023
Headline -
Strong Growth with Record New Business
I’ve had a quick review of these figures (and commentary), this is how I see it -
Bull points
Strong organic revenue growth +25% to £15.0m
Forecast revenue growth (28-30%) for FY 6/2024, and maiden profit.
High gross margin of 88%, and high quality recurring revenues (86% of total)
Clean going concern note.
Liquidity just about enough, if £3m (undrawn) RCF remains available, plus £1.2m cash.
Bear points
Adj PBT is stubbornly still loss-making, at £(2.3)m, only slightly down from £(2.9)m LY
Heavy costs of patent legal dispute are excluded from that, so total LBT is £(4.9)m
Patent case won in the UK, but still ongoing in USA, expected summer/autumn 2024.
Balance sheet is weak, I think it would benefit from a £3-5m placing.
Paul’s opinion - it’s quite rare to find a strong organic growth software company, with high margins and recurring revenues, at only £31m market cap.
They’re running it a bit tight for cash, and the costs & distraction of the US patent action are still ongoing. If that works out favourably though (and the UK patent case win is a nice plus), then I could see this share re-rating in a future bull market.
It could become a bid target possibly? We know that bidders in the software area like recurring revenues, and are often prepared to pay up with racy valuations.
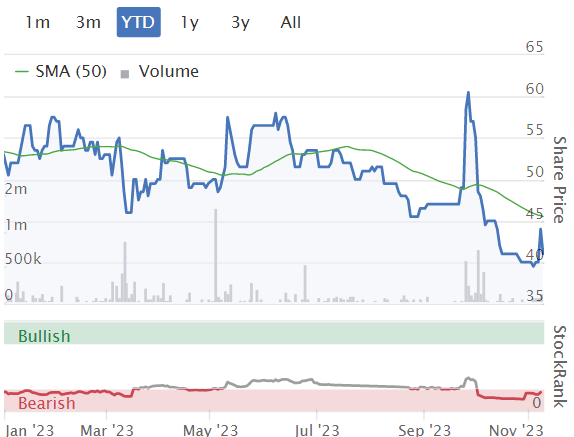
Quite a volatile share price this year -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

129 comments
Are we hoping for an interesting start to Vertu with a share rise in the last 30 mins of trading with Cinch interested?
Why has NWF (LON:NWF) (hold) gone up 15% in the last two days on no news? Anyone know?
Yes, I like Secure Trust Bank (LON:STB) and Arbuthnot Banking (LON:ARBB) - purchased STB at a much higher price, but have it on my watch list as a rare average down prospect. I am waiting for the 50 dma to cross over the 200 dma first which would be a clear indicator that the horrendous downtrend is broken.
Secure Trust Bank Capital Markets Day given 8th November 2023 video & podcast.
A Pathway to delivery of the Medium Term Targets of a £4bn loan book to allow the group to deliver a cost income ratio of 44-46%, and a future 14-16% return on average equity.
The day focussed on V12 Retail Finance, referred to as ‘An emerging powerhouse’. V12 is delivering significant growth, structural improvement in its cost of risk and significant operational leverage and scalability through digitalisation of customer service.
Then, Rachel Lawrence, CFO, went on to provide an update on the Group’s medium term targets. The event was opened by Lord Forsyth, Chairman, with David McCreadie, CEO providing an introduction and closing summary, followed by analyst and investor questions.
I was there yesterday and like them a lot. David McCreadie is a safe pair of hands. It's a Lord Lee holding, with a low PE of just 3 and fantastic dividend yield of 8.55%.
For retail finance, there was a helpful chart on risk by sector, least risky is Furniture, then Jewellery followed by Leisure (often bikes) highest risk are Electricals. They focus on the less risky sectors with interest free finance, they say the cost of risk has now reduced from 3% of the loan book in 2019 to 1.6% at H123.
Yesterday they also gave a Trading Update showing that Q3 closed with ongoing momentum. Net lending up 14.2%. V12 Retail Finance represents 79% of the growth! Their retail finance market share has also increased to 13.2% from 7.5%. A competitor has disappeared and that has been beneficial to STB.
Did they say what their current cost of capital is? I sold Secure Trust Bank (LON:STB) when I saw how they were having to price new bond issuance.
Secure Trust Bank (LON:STB) Most of their funding comes from deposits. Their costs of funding doesn't look too bad with their net interest margin broadly stable over last couple of years. The bond you're probably referring to was a subordinated issue - these are a regulatory requirement and designed to take first losses if their capital ratios fall - as a result they are always issued at a high interest rate, but this is not reflective of their overall cost of capital.
Hi Scotty
I appreciate this might be another one of my 'bonkers ideas'. But would it ever be possible to perhaps measure the success/hit rate of SCVR's Green/Red calls (say over the next 6-12 months)?
It would certainly be fascinating to see the stats, especially wrt continuously improving the already top notch service that yourself, Graham & Roland provide.
Hi Paul,
We've already got something similar - my 32 favourite GREEN stocks for 2023 (published early Jan 2023). The results are on this spreadsheet - the top 20 has out-performed AIM by 20% YTD, the 12 runners up are ahead by 28%.
Regards, Paul.
Thanks Paul
The idea related to possibly somehow automatically tracking all the Red & Green stocks - ie not just those highlighted at the start of each year (which is obviously very helpful anyway)
Hi Paul,
The idea related to possibly somehow automatically tracking all the Red & Green stocks - ie not just those highlighted at the start of each year (which is obviously very helpful anyway)
The trouble is that would then turn our reports into share tipping, which is not what they're intended to do.
All we're saying with our SCVR traffic lights, is: based on the facts, figures, and forecasts as of today, this is our opinion.
We're not trying to predict what happens next over x months or years, as we have no way of knowing how the facts, figures & forecasts will change, nobody has!
Our traffic lights are not intended to be predictive. It's more about flagging potential risk, and potential opportunity, so people need to be particularly careful if we flag something as RED, then make up their own decision. It could turn out to be multibagger, as risky investments sometimes are. But there are plenty more that fall by the wayside which we've flagged as RED, loads of them this year.
Regards, Paul.
Hi Paul,
A very visual indication of your favourite picks for 2023 is shown with a stocko portfolio. I did a temporary portfolio of your top 20, it looks pretty impressive. I thought about suggesting this as a Stockopedia saved portfolio under 'Discuss' - but it would create too many issues. People would tend to blame you more for any problems with any performance below a benchmark, rather than making their own decisions. Still - it does merit a hat tip to your skill and experience.
Zoo Digital (LON:ZOO) Facilities by ADF (LON:ADF) Videndum (LON:VID) Well done to any holders who have held through the volatility, especially for Zoo Digital (LON:ZOO) shareholders, of the actors' and writers' strikes.Hopefully the tentative deal will be approved by the SAG-AFTRA national board this Friday.The small cap uk market seems to be betting on it so far.Here's hoping things can only get better.
'"It gives SAG-AFTRA the biggest contract-on-contract gains in the
history of the union, including the largest increase in minimum wages in
the last 40 years; a brand new residual for streaming programmes;
extensive consent and compensation protections in the use of artificial
intelligence; and sizeable contract increases on items across the
board."'
https://news.sky.com/story/us-...
Re: Zoo Digital (LON:ZOO) Not great news for Judith at Downing this morning.I remember seeing an interview with Paul from Vox on her.I wonder if a larger shareholder was pushing for the wind down and capital distribution?She seemed pretty resilient.
However, the market can definitely digest new information still pretty quickly to the upside.Fingers doubly crossed the overall UK market will have a few of those days soon!And that upcoming Zoo Digital (LON:ZOO) 's upcoming interims don't hold anymore nasties and i'm not getting too over optomistic and end up slipping on a banana skin in retrospect!
A reasonably pathetic update from WRKS. A discount value retailer having to discount to stimulate volumes feels oxymoronic.
PCIP - I think any cash requirement would be subject the successful claim of legal expenses from Sycurio. We will know more in December. This has to be a bid target at a reasonable multiple of sales
We have an absolutely fabulous line up of keynote speakers at Mello London at the end of this month and we would love to see as many of you as possible. If you have never been to a physical Mello conference before then now is the time to join us. I will be delighted to give five Mello virgins a free ticket for one of the days so that you can try before you buy...just send me an email via David at melloevents.com (putting @ instead of at) and I will send you a code for a free ticket by return
Many of the 40 companies that are presenting are on crazy low ratings and this could be exactly the right time to talk to the management teams and build your confidence in their leadership and the fundamentals of the company.
We have Katie Potts joining our line up of speakers at the two day event. So along with Christopher Mills, Lord John Lee, Andy Brough, Richard Crow, Stockopedia founder Ed Croft and Paul Hill we have a cracking line up and of course SCVR stars Paul and Graham will be there to do live reports and meet Stockopedia subscribers.
Here is a link to the full details and our event webpage is updated regularly with a full programme released shortly https://www.stockopedia.com/co...
We have three BASH (Buy, Avoid, Sell or Hold?) panel sessions live at the show so you have lots to enjoy. See you there
David
Is buying small caps stocks a mugs game? They go up and down but the long term trend is down like a casino. I would like to see a study of how small UK caps have performed over the last two years. I have the suspicion that 70% of them would be at least 25% down?
First we have the greedy directors who try to extract as much juice as possible from listed companies by issuing tons of share options to themselves and lofty salaries. And if a company is lucky enough to ride the recession and make profits in a tough environment it gets slapped by 25% (?) in corporate profits. If you make great profits you risk being penalised further like oil companies operating in the North Sea. It doesn't seem like a winning proposition to me for us shareholders? No wonder many people in the UK don't touch equities!
I also trust the people who do the editorials here get paid for analysing companies?
Argentex (LON:AGFX) Yes it is if events at Argentex are anything to go by, the fundamentals looked great, cheap on per with a solid balance sheet, but as events are turning out another disaster, I am losing faith and not being able to place my trust in anything these days. Share prices are carrying dramatic falls on any sniff of negative news , with very slow dribbles upwards on anything positive. With interest rates now being high , whilst this persists for me investing in most small caps is a dead and risky venture (in my opinion).
Ben, on AIM since Nov 2021
Majority of IPO since not included so will be worse as most are down.
FTSE all share
You can still make money in bear markets but you need to be very picky with what you buy. Ive tried to stick to companies with growing eps and the possibility of beating forecasts eg YU, MEGP, MSI etc. (+selling any with falling forecasts) these have all doubled or more in 2 years. Theres lots now which look good recovery prospects. I'd use the knowledge of the last 2 years as an intense training exercise, you'll know what to do next time and when a bull market does arrive it'll seem easy.
thanks wolf - those stats look even more terrible than i suspected - where did you get the stats from if i may ask? Many of these listed companies have been listed for many years - but a lot has unravelled in the last two years. Yes, proffittpar and then there's riskless bonds competing with the equity market which makes things even worse. Look at WRKS today - a profit warning and boob - 25% of the market cap (i.e. your capital if invested!) gets slashed! Its a negative sums game like a casino but with possibly even worse odds.
In a bear market it can feel like a negative sum game.
If I make an assumption that you started investing when you joined here (2022), I can only advise to stick with it. The last two years or so have been tough and it can feel the deck is stacked against you, but in a bull market it can feel the opposite. Sometimes it all feels so easy. you can't quite believe it. Of course, until the next bull knocks you back down, but hopefully still higher than you were.
I am not sure I would've persevered if the last two years or so were my introduction to investing.
No i have over 20 years experience trading/investing - lived thru 2008 and all but now I have greater capital at risk. I know that stocks have been listed for years but the last two years have been devastating for many. I usually try to swing trade in and out but with all my skill I'm still down around 45k on an original 270k pot. And that's just one of my accounts. The result of my 'trading' is that i have crystallized substantial profits over this year but my running losses are big.
Tiddlers haven't been easy to trade Ben that's for sure. Dopey fund managers who were so easily conned into buying overpriced IPOs have had their finger on the sell button for some time.
Last few months I've moved more to mid caps, tighter spreads and easier to get out if need be. Things like YouGov (LON:YOU) Computacenter (LON:CCC) GB (LON:GBG) Moneysupermarket.Com (LON:MONY) as well as the odd short and bet on indexes,gold,oil.
Interesting and I feel your pain, but a 20% jump and you are back to square one and that's assuming you didn't earn any dividends in the period in question. Could be a lot worse.
Large-cap vs. Small-cap Stocks - 44 Year Chart | Longtermtrends This is US based but it shows what you would expect, there is a time for large cap and a time for small cap. I can tell you without any great study that over the last 2 years small caps have been horrible but over the last 10 years they have given me a fairly good living. I don't know if any of that helps ben.
Hello Ben,
I have only been investing a few years, i'm sure you know you should stick with it!
This is my first taste of a bear market, i and probably many others are feeling very frustrated at the moment. Hopefully this means the turn is not too far away!!
The simple answer Ben is that it depends on what you buy and how much you pay. After all, big caps were once small caps. The execution of course isn't so simple and requires much research and often a great deal of patience and a little luck.
The SCVR and analysis of company reports/announcements by Paul, Graham, Roland and other Stockopedia contributors such as Mark and Edmund form part of the research
Not quite true anymore.
With more new companies going down the VC and PE route for longer, they're coming onto the public markets much later than in previous decades. So the small cap space is missing out on some of those potentially big companies.
On the other hand, we also gratefully miss out on Wework (NYQ:WE) .....
Apologies Ben, I have just read the other replies to your post. I would add that I am not a trader nor do I use stop losses. I have neither the skill or aptitude to swing trade.
If a company's share price falls but in my view it continues to trade well or there are specific events events of a temporary nature that impact performance I will hold or add to my position. Examples being Jet2 (LON:JET2) where I have added and Facilities by ADF (LON:ADF) where I have continued to hold.
However I will sell if:
The above list is not exhaustive
This approach to investing suits my personality although I appreciate that it is not for everyone. I would also add that like all investors I have made several mistakes some painful, but hopefully have learned from them.
Decent small caps will turnaround and I suspect significantly. The obvious trigger being any suggestion no matter how nuanced from the Bank of England that interest rates are to be reduced.
Good luck
Well, there's a reason why small cap space is sometimes nicknamed the "Wild West". There are plenty of traps, dangers, predators, and unsavoury characters lurking in the space.
Yet - it is possible to get outsized returns.
This is my ISA performance chart, since Jan 2021. My Boon Fund consists of my ISA and SIPP. Into my ISA goes small and mid companies, typically lower than £200m market cap. You can see all my prior holdings, through my Boon Fund articles back to Jan 2021.
Many of my most profitable holdings in that period were market caps in the £5m-£50m range. The fact is that they are shunned by institutional, 80-hour professional investors with armies of people and data to analyse. They also suffer from liquidity, which causes outsized drift of share prices away from fair value. Exploit those two, and you can make good returns in the small caps. There's a reason why I completely shun buying anything that is getting lots of media attention (or Stocko attention, I never buy when the community rating is 30%+).
I'm up 60%+ compared to the FTSE All-Share benchmark that I use. (arguably, the wrong benchmark, since it is heavily weighted to the FTSE100).
Impressive. My chart looks a bit similar but the other way around.
May be of interest to any holders or potential holders of Chapel Down (OFEX:CDGP)
https://www.thisismoney.co.uk/...
Natwest (LON:NWG)
I can't help but occasionally make stupid impulsive decisions, with the barest smattering of analysis, and have bought some NatWest shares.
Pray for me.
Balls of steel!
I have just sold mine ;).
Caper4 - Ibought Kitwave (LON:KITW) the other day only to see a post by another member saying they had just sold. Possibly I bought his/her shares. Maybe we could set up a scheme to just buy and sell shares from and to each other and save the spreads!
A good plan . Alas I bought with the proceeds Secure Trust Bank (LON:STB) so probably going from the frying pan to the fire !!
Bought some NWG 2 weeks ago….they are doing OK so far….no need for prayers
NWG and other Bank shares
I think there is more chance of not losing money with buying bank shares now than in small caps which is discussed in these pages.
UK bank shares are down for several reasons: fear of recession, house market crash, government investigation into not paying enough interest to cash holders and so on...
But they are all massively cash generators, paying good dividend and have remained unpopular with international investors and national investors (Terry Smith does not invest in Banks).
These all makes the sector a good investing, surely we are not at the peak of banking bonanza share prices.
I own all bank shares.
Plus500 (LON:PLUS) paid me the dividend today and I have cycled it into Secure Trust Bank (LON:STB) as a starter position, it seems so cheap. Now I hold both.
Lancashire Holdings (LON:LRE)
Special Dividend.
Lancashire Holdings Limited (“Lancashire” or “the Group”) today
announces its trading statement for the nine months ended 30 September 2023.
Trading statement highlights
* Gross premiums written increased by 23.2% year-on-year to $1.6 billion.
* IFRS 17 insurance revenue increased by 22.1% year-on-year to $1.1 billion.
* Group Renewal Price Index (RPI) of 117%.
* Total net investment return, including unrealised gains and losses, of 2.8%.
* Capital return of up to $169 million ($119 million in special dividend and
up to $50 million in buy-backs of Lancashire’s Common Shares) following
strong operating performance year-to-date.
Would appreciate you looking at LRE sometime, I hold Beazley (LON:BEZ) and am considering LRE and would be interested in your thoughts.
Conduit Holdings (LON:CRE) also looking interesting and trading below book value.
Hi davidjhill I was very interested in your post yesterday re Entain (LON:ENT) which I have been in and out of for 7 years previously GVC. £15k profits banked to date.
I was my biggest position last January when I sold out at 1365p which proved fortuitous given the SP recently fell below £9. 00. My big mistake was not selling in Sept 2021 at £23.
However I am back in with a smaller position which is 35% down! However I think like you that the prospects in USA are immense as the yanks are big gamblers and the market is huge. The key is the JV with MGM which breaks even this quarter. The SP weakness is largely down to Regulation in my opinion.
I intend to add at these levels and over a 5 year period that you suggest I think the prospects are huge barring the mother of all recessions which hopefully will be avoided.
Vertu Motors (VTU)
Share up nicely today. Know it is a share liked by many on this blog. Decent volume as well but can't see any news.
Looks like Cinch increased their holding, so probably has an effect to feed buyout speculation.
Ah, thanks Raven, I see that now.
Have you read todays RNS?
TDR Capital are building a decent stake-did the same in Lookers.
I just wished every stock I hold performs like Vertu Motors (LON:VTU) .
I managed to buy it a few years ago at almost the bottom (31p a share) and its not unsurprisingly my 2nd largest holding. Still holding on my hands but the temptation to top slice is clearly growing.
I noticed Norman Broadbent (LON:NBB) down 20% today despite a positive update. Are there any holders here who understand why?
I am not a holder, but is this within what might be considered a normal volatility ? It has a very small market cap & spreads are very large.
I noticed Norman Broadbent (LON:NBB) down 20% today despite a positive update. Are there any holders here who understand why?
I do not own and I don’t see the share price move on Sharepad, so I’m not sure there’s anything to explain. My further comment on the name is that I have some insight having been approached for a board position there a few years ago. I found a business that could not make a profit because its fixed costs, mostly salaries, were too high, yet impossible to moderate in London’s highly competitive employment landscape - good consultants earn big bucks, bad consultants lose you money. It was also trying to redefine itself strategically, though I note that the CEO of the time has moved on. The latest results are the best I’ve seen in a while from them. However I would not personally invest in the name - certainly only on grounds of liquidity, but also on account of a fragile business model.
Buy recruiters as you exit a recession, and sell them as the cycle peaks - if only I could master that discipline! I’ve owned SThree (LON:STEM) through the cycle and bought into Robert Walters (LON:RWA) too soon these recent months, with the recession/no recession being constantly moved forward in time. It was supposed to occur last spring!
Buy recruiters as you exit a recession, and sell them as the cycle peaks - if only I could master that discipline! I’ve owned SThree (LON:STEM) through the cycle and bought into Robert Walters (LON:RWA) too soon these recent months, with the recession/no recession being constantly moved forward in time. It was supposed to occur last spring!
Talking of recruiters... FDM (Holdings) (LON:FDM) appeared on one of my screens recently. It's a company I've held in the past but sold in 2021. It has good quality metrics, so I assume the much reduced share price is down to a drop off in business with reverse gearing in operation. Alas, I can't remember why I sold it and I had stopped following the story. Do you have any current thoughts on it?
All the best, Si
Talking of recruiters... FDM (Holdings) (LON:FDM) appeared on one of my screens recently. Do you have any current thoughts on it?
FDM is not quite a recruiter. It’s more of a train and place operation, taking ex-military personnel and career switchers and teaching them to code. A small distinction you could argue but there’s an important difference when you consider the potential impact of AI reducing demand for coding skills and increasing those for business and data analysis up the experience scale. Where a traditional recruiter can almost instantly change its emphasis with the whims of the market, a training operation will operate at a substantial lag and cannot bridge up to higher experience levels. For that reason I sold and put half each in SThree (LON:STEM) and Robert Walters (LON:RWA, which are both, for me, big positions now.
Paul has lost faith in Robert Walters (LON:RWA) and he could be correct. But my inference is that the poor recent performance, some of which is down to excessive internal hiring at the top of the cycle, which can be unwound, also reflects the unhealthy perm/contract split. In an up cycle, this ought to mean-revert.
FDM is not quite a recruiter. It’s more of a train and place operation, taking ex-military personnel and career switchers and teaching them to code. A small distinction you could argue but there’s an important difference when you consider the potential impact of AI reducing demand for coding skills and increasing those for business and data analysis up the experience scale. Where a traditional recruiter can almost instantly change its emphasis with the whims of the market, a training operation will operate at a substantial lag and cannot bridge up to higher experience levels. For that reason I sold and put half each in SThree (LON:STEM) and Robert Walters (LON:RWA, which are both, for me, big positions now.
Thanks BnB. Having previously held I understood the "Mountie" business model but your comments about the possible effect of AI and the inherent lack of flexibility in the business model compared to more traditional recruitment are worth noting. As I mentioned, I was only kicking the tyres because FDM still looks good on quality metrics but has de-rated significantly since I held.
All
FDM (Holdings) (LON:FDM) used to be a good company with a good purpose. Unfortunately it has been taken over by a self-serving and not very pleasant leadership team who despite being self-serving don't actually seem to know what is good for them or the company. I speak from several recent contacts.
There are other companies doing what FDM used to do well but much better.
FDM (Holdings) (LON:FDM) used to be a good company with a good purpose. Unfortunately it has been taken over by a self-serving and not very pleasant leadership team who despite being self-serving don't actually seem to know what is good for them or the company. I speak from several recent contacts.
Yes, I remember shortly after I sold in September 2021 there were some massive director sales. No sign of any significant director buying since, strange that... Thanks for your input. I was just curious what the situation was, because everything else aside, the share price is about a third of when I sold, the company has net cash and the quality metrics still look appealing. It also qualifies for 3 Stocko long screens FWIW.
Might be due to the announcement by Downing Strategic Micro-Cap Investment Trust (LON:DSM) of its intention to wind up and they are a holder?
For pity's sake - a statement that Norman Broadbent (LON:NBB) is down 20% and four replies about why but nobody has pointed out that it is NOT DOWN. It is 6.25 - bid 5.5 offer 7 as it has been for the last week and if you don't believe me here is the London Stock Exchange:
You have been taken in by the unhelpful way that Stocko shows prices as the last trade. Someone sold 105,263 shares this morning and this being way beyond the EMS of 7,500 the price obtained was outside the spread.
I never use Stocko to look at prices.
You should be aware that NBB is highly illiquid - these are the only recent trades:
Yes Stocko prices are very misleading, I have mentioned this many times in the past.
Today they had Henry Boot (LON:BOOT) up 9%, when it has not moved at all.
Stupid system of using the last trade price.
Think you can change it in settings to
Does not make difference, what settings you have, even in your folios.
For pity's sake - a statement that Norman Broadbent (LON:NBB) is down 20% and four replies about why but nobody has pointed out that it is NOT DOWN
Are you sure?
BnB at 10:06 - “I don’t see the share price move on Sharepad, so I’m not sure there’s anything to explain”
Apologies - missed that bit.
You have to remember it goes on the last trade, I had that yesterday something popped up as a manual stop loss warning, I looked and it was a trade of 4 shares at 20% below market, and the following trade 15 minutes later was back at market...
B&M European Value Retail SA (LON:BME)
http://newsfile.refinitiv.com/...
I don't hold and know its not a small cap but had a very quick read of this mornings FY24 interims and apart from the Outlook statement saying LFL for the first 6 weeks of Q3 being only +1.6% I could not find much I didn't like but SP is off 4.5% ! Any holders on here to tell me what I missed please.
Small bolt on acquisition by Galliford Try Holdings (LON:GFRD) for £7M.
"For the year ended 30 September 2022, AVRS generated revenue of £7.9m and profit before tax of £1.3m. The gross assets of AVRS as at the same date were £3.8m."
Looks like a reasonable deal.
John Wood (LON:WG.) (No Holding) are weak today on fairly decent numbers I thought. The sector isn't travelling that well just now as big oil are missing numbers and US stocks like Caterpillar (NYQ:CAT) and Transocean (NYQ:RIG) are giving back previous gains. Longer term I quite like the idea of John Wood (LON:WG.) and think there maybe scope for an improved interest charge so the rating might be lower than current stocko numbers. Positive free cash flow would clearly help after a number of years of exceptional costs. On the radar.
Conduit Holdings (LON:CRE) Just wondering if CRE is on anybody's radar. It falls within the market cap range for the SCVR I believe but doesn't appear to have been covered. Positive update yesterday and very interesting Investor Meet Company with Neil Eckert. Also discussed in Paul Hill's interview with Chris Mills from June. (I Hold)
I did own...as a cheap way into a strong cycle ... and a clean book. The sector is one for specialists and I believe longer term this team would need to earn their reputation underwriting wise. Hiscox (LON:HSX) has been quite weak and much less likely to let you down.
Conduit Holdings (LON:CRE) - I have held for a while. It's taken a few years to get going, but is delivering the goods now. I purchased too early on, but good potential. The management team are well regarded. Lancashire Holdings (LON:LRE) and Beazley (LON:BEZ) also held and look good. Insurance cycle strong.
Time Finance breaking out of a base today. I hold a small position. Not a company I know and it's also terribly illiquid.
You hold a position so must know the company? Time Finance (LON:TIME)
I'm a trader, and this is a swing trade. I'm sure I'll know more if Paul writes about it!
Trading update says ahead of market expectations. Performance since CEO Ed Rimmer took over has been really impressive, in a market you'd think on the face of it would be depressed.
A series of profit upgrades, this is the latest one at Time Finance (LON:TIME)
Market cap barely trading at their NTAV, and with EPS upgrade momentum.
Strategy started two or three years ago is working. It was to shift away from originating loans for third parties, and instead keep the loans on its own books. Thereby capturing all the lifetime value of interest payments, rather than a one-time origination fee.
The key question now is where will they get more capital to keep building their own loan book? They don't take deposits and is not a bank, so they depend on wholesale market funding.
Nevertheless, even with current capital constraints, IMO this should be valued at the 40-50p share price range rather than 30p.
(I hold in the Boon Fund)
Quite a downbeat statement by Works co uk (LON:WRKS)
https://www.investegate.co.uk/...
Read across to others? E.g Card Factory (LON:CARD)
I have a moderate holding in Card Factory (LON:CARD, where the investment metrics are much better than Works co uk (LON:WRKS)
From Stockopedia:
Card Factory (LON:CARD) ROCE 17%, operating margin 15.32%
Works co uk (LON:WRKS) ROCE 12.1%, operating margin 3.37%
From Sharepad:
Card Factory (LON:CARD) ROCE 14.1%, operating margin 13.8%
Works co uk (LON:WRKS) ROCE 9%, operating margin 5.2%
Card Factory has several expansion/improvement initiatives in execution, e.g. with Matalan and in the middle east, the recent South African acquisition and the ongoing low capex store make overs.
Card Factory (LON:CARD) is vertically integrated and subject to a trading update, expected sometime soon, I remain happy to be invested.
Hoping for signs of some recovery in my holdings in Zoo Digital(LON:ZOO) , Facilities by ADF (LON:ADF) and Keywords Studios(LON:KWS) today on the news of the likely ending of the actors strike in the US.
I was surprised to be able to buy back into Videndum (LON:VID) at only a 5% premium to last night’s close at today’s open. Puzzled why it hasn’t jumped 20-25%. Debt is still a problem but the story they’ve been telling the bank now has a likely date for the, hopefully, happy ending.
Keywords similarly unmoved, but that’s an AI story as well.
UPDATE: a bit more momentum now though not the level I had anticipated. I wouldn’t normally make trades like this, but it’s a former quality share holding that became a deep value share that I cut when the material risk statement arose in September. Anyone can see that I’m chasing my loss but the picture has hopefully changed for the better. Has anyone else been foolish/brave enough to dive in?
Morning BnB
I continue to hold Facilities by ADF (LON:ADF) and have a reasonable position. I exited Videndum (LON:VID) much too late as it happens on reading the recent interims. I still like the business, but the debt situation looked and still looks troublesome. I have not seen any RNS regarding refinancing and I suspect that you are better informed than me. Are you able to provide a brief overview on how you see the current situation?
Many thanks
Videndum (LON:VID) Are you able to provide a brief overview on how you see the current situation?
I can’t really add much to my earlier comment. The continued funding shortfall means they need an equity raise or additional waivers from the bank. In the former case, we saw yesterday how XPP’s dilution actually increased the price per share - because the additional funds improved the balance sheet. That could happen here and I think that investors would be supportive given the potential ending of the strike. In the latter case, the bank is likely to be more sympathetic now that an end to the hiatus is potentially near. Of course the time to go cap in hand is when the deal is hopefully confirmed.
Management has been slow to initiate a raise so I assume that the bank is where efforts have been concentrated. But perhaps they have been waiting for better news out of Hollywood. And could the new chair bring a change in corporate finance strategy?
Frankly my stake had got so small it did not materially dent my cash balance heavily to put it back on - at a price 20% below my exit. My reckoning is that I’m either going to lose the lot or make a decent return. It would be a surprise to me to see shares still in the low 300s come next year. Which direction they move is still uncertain.
A good summary, which is similar to how I see the company. Have bought a few more at 333 as believe the upside from here is greater than the downside.
Cheers BnB
I see the news that the actors strike has been resolved, which is good all round.
For the time being I shall keep what little powder I have dry and stick with Facilities by ADF (LON:ADF) which to my mind is much easier to understand from an operational perspective and doesn't have the financial worries that burden Videndum (LON:VID)
I thought about purchasing some Videndum more as a punt as strictly, going by my new rules after years of bad trading decisions in the past, i should totally avoid it with the going concern lender issue.However, after the XP Power news like you, and it previously having been a quality share i am tempted and i think Lord Lee owns/owned it.
The deeply discounted Synthomer rights issue did really put me off, but who knows.I was half thinking, when having nothing better to do pretty much, about how a 'diversified basket of distressed equity' portfolio (just full of highly indebted companies) might perform over the next few years.Some surely will outperform and will have higher upside as they scrape by dilution risk relatively unscathed.Obviously some won't.Anyway i think i'll leave that idea for the more skilled investor.
Videndum had the actor's/writer's strike to worry about too, so maybe i will jump in with a small amount if volume increases in the right direction in the next few days similarly to with XP Power : the trading was almost totally green days with little selling post profit warning.I'm also wondering if some market participants knew that was XP's plan as usually after a profit warning in this market environment that was unusal trading in my opinion with the inherent debt covenant risk.Caveat : I'm not suggesting anyone did know anything.But i'm sure i saw some data a while back (i'll have to have a look for it again) which surprised me at the amount of insider trading that does occur and not just in junior markets in the uk.
Hoping for signs of some recovery in my holdings in Zoo Digital (LON:ZOO) , Facilities by ADF (LON:ADF) and Keywords Studios (LON:KWS) today on the news of the likely ending of the actors strike in the US.
Interesting notification by Vertu this morning. Seems Constellation Motors (Cinch, We Buy any Car, Marshalls Motor Group, Elmo,BCA) have an interest of around 17%. It would probably make sense......
Good luck to holders. The move is driven by TDR Capital. It's a bitter pill for us as I thought I could buy back cheaper before a bid when poorer trading becomes evident, really bad timing!
I don’t think is 17%
You have added everything up from the RNS but it does not work like that.
Vertu Motors (LON:VTU)
The TDR Capital holdings have increased from 3.1% to 4.15%.
Snazzy
I have said that about 3 hours ago!
hi Yiannos
Vertu Motors (LON:VTU)
To clarify.
What you actually said was:
I don’t think is 17%
You have added everything up from the RNS but it does not work like that.
That was of course correct. However I was merely confirming the actual new level of holdings, primarily for Camtab's benefit.
Snazzy
Thankyou Snazzytime and Yiannos. Did I get that wrong I will have to go back and look at the RNS. My bad!!
Ooops you are quite right. I hope my error isn't responsible for the 10% jump today. I will be getting a call from the FSA.
A quote from Judith MacKenzie, Head of Downing Fund Managers and Partner of Downing LLP, today as their small company investment trust Downing Renewables & Infrastructure Trust (LON:DORE) gets put into wind-down:
"The decline and demise of the smaller companies’ markets in the UK are now part of the daily narrative of the ecosystem. The facts are stark:
► The number of UK-listed companies has halved since 1997. New issues have fallen by 33%. 2022 was the worst year for new issues since 1980.
► The UK equity market has shrunk relative to GDP over the last 20 years. From 104% of GDP to 94%. Meanwhile, the US has increased from 101% to 156%.
► The reasons why this de-equitisation continues are multiple and complex, however, they point to one thing. There are more investors (institutional and private) selling small companies than buying them. This needs to change before sentiment towards small companies improves.
► The UK market is dominated by traditional sectors, with just 16% coming from companies that would be described as growth (vs 42% in the US).
► UK growth companies rely on non-UK investors for 60% of their funding (and more than 70% for deals larger than $100m).
► Pension fund allocation to UK companies is at the lowest level in history."
I know the UK economy in the 50s and 60s was completely different but this still looks some decline.
Pension reform / Private Equity and ZIRP I guess ... "IF" we do see trouble in PE with higher for longer rates....maybe it's the equity market that refis the good businesses as way out and kick starts a renewed growth cycle. Would be nice.
Judith MacKenzie / Downing selling at the bottom?
On the contrary. A stagnant economy through 2024, inflation well above BoE target, lots of profit warnings, cost of servicing debt very high. What's going to drive progress for small companies?
Read the recent Begbies report.
Aren't the stock market and the economy two different things eParo?
I agree with you that the prospects for the UK economy look grim but would argue that the AIM has over shot to the downside considerably..
Love your optimism eParo. Probably a useful cold bucket of water to my own eternal look on the bright side!
I hope the drop in inflation to below 5% which we are due to see shortly will act as a catalyst in a number of ways. Firms still waiting to finalise pay deals for next year will have a more favourable base to negotiate from for a start. They will also be able to base plans on a more stable economic outlook than at any point over the last 2 or 3 years, albeit not one that is growing much. The volatility of Covid and recovery I would suggest has broadly worked through and supply chains are closer to balance than they have been of 3 years now.
Canada, Germany and others already in recession will hopefully turn the corner soon. Whilst the professionals believe US and EU (+ us) are heading into recession I suspect most will avoid it, narrowly. Perhaps I'm just too optimistic but always more Tigger than Eyeore. Not expecting interest rates to go up any further, though there might be on more nudge to come. If that doesn't happen this side of Christmas I'd expect first rate cuts early Q3 '24. Not before. But as markets look forward could we see the bounce come in ahead of that?
Too optimistic? Current drop in Oil prices would certainly support your gloomier view.
Retail outflows continue from UK equities. Mortgage re-fixes coming up next year at 3x or 4x old rates. I watch the FTSE AIM All Share Index (FTSE:AXX) which is still 8% below the 120d SMA. Winter fuel bills are going to be higher this winter as no govt. support now. Tightening budgets are going to squeeze spending so I don't expect fireworks anytime soon in the UK stock market. Flight to Fixed Income continues. Sorry to be downbeat. ATB
Downbeat is fine if that is what your tea leaves are telling you. I believe some 2 million mortgages have either refixed at higher levels already or were already on SVR. I think many will stay on SVR for now hoping the pain will reverse and better rates be available within the next 2 years. And yes there will be another 1m plus before rates start heading down even in the best case scenarios. (I understand something like 800,000 fixed rate mortgages are due for renewal each year)
Given the price of gas is 20% of what it was a year ago I don't see energy costs being much higher for households regardless of previous government subsidy, at least not tangibly. And how much support did industry get? Not aware of any (though out of the loop) so should this not be a significant saving year on year?
And good luck to those locking in long-term savings rates. Would expect those to start falling from June/July next year if not coming off slightly in advance. Then some of the high divis might appeal and start the recovery in share prices. Could still be worth sitting out for another 12 months in Fixed Income. The recovery, when it comes, won't all come in one go. Though the early up days could be spectacular.... he says hopefully!
Please do keep posting the downside.
Isn't it the Downing micro cap trust that will wound down, rather than the renewables trust?
Yes. It’s Downing Strategic Micro-Cap Investment Trust (LON:DSM) They will be selling off stakes in the following, some of which are widely held by fellow investors here
and for those interested there is an excellent summary of each investment above, here
http://newsfile.refinitiv.com/...
Thanks Neil's. What an 'interesting' collection of shares. I'm getting a cold sweat just looking at the list.
Quite so Wolf! Judith does enjoy (I think) going in and aggravating for change!
A somewhat sanguine and damning Chairman's report on UK economic governance over the past decades. Well worth a read. Good analysis of Volex and a few others as well.
As you say Chelsea a good read and pretty much on the money in my view. I tend to steer clear of politics but am surprised that the country does as well as it does, despite the best efforts of politicians, most of whom in my books are inept and self seeking.
At least you can sell your shares in a company if it turns out that your judgement in purchasing was misplaced, not so with MPs, where excepting a by election one has to wait 4 years to effect change.
I thought Downing Strategic were also bullish holders of Venture Life and Duke Royalty. Anyone know when they exited? I don't hold, but just interested, as Judith MacKenzie often talked about them as long term positions.
Thank you Topinvest. Very interesting.
There is an interesting article in The Atlantic in this vein:
The Secretive Industry Devouring the U.S. Economy
https://www.theatlantic.com/id...
But the U.S. economy has done so much better over the last 50 years, whether it be judged by inflation, increase in the Stockmarket, GDP per head etc (though some might take issue with the share of all this enjoyed by “labor”. I am not going to go into my theories as to why, we all have our own strongly held views on this but there seems to be a dynamism in the US just to not present in the old world.
Sorry if this is a bit of topic,
Regards
Michael
As well as the UK small cap market going through a tough time I think it's important to note that Downing made some very poor investment decisions (e.g. real good food group). In a small focussed fund this was always going to put them in trouble.
Chapel Down (OFEX:CDGP) Announces move to AIM and a record harvest. I hold.
“Favourable growing conditions at key periods of vine growth throughout 2023, combined with the skill of our world class viticulture and winemaking teams, have enabled the delivery of a harvest of exceptional grape quality and yield. Across its 750 fully productive acres under vine, the Company has delivered a record 3,811 tonnes of grapes. This tonnage is 86% higher than 2022, and 75% higher than Chapel Down's previous record posted in 2018.
The majority of grapes (c.80%) harvested were of varieties used for traditional method sparkling wine, in line with the Company's strategy to focus on its higher margin award-winning sparkling wines, which benefit from the cool maritime climate and chalk soils of the North Downs of Kent.”
Up ~12% today so far..
I've noticed a lot of pubs & bars in the SE (and possibly elsewhere) are now selling Chapel Down's still & sparkling wines by the glass & are stocking their other products. They seem v popular & quite reasonably priced.
And 33% discount for Shareholders who hold 2000 shares plus.
The manager and manageress of my local M&S Food and Majestic regularly tell me how Chapel Down is make inroads into their sales of French Champagne with their English Sparkling wine and at around a 30% discount in price for a very similar taste it is no surprise .
Wow, and last year saw some good tonnage and quality, so for this year to beat is pretty amazing.
Chapel Down (OFEX:CDGP) really on a roll. The downside, of course, is that it is still a very fragmented market with multiple other sparkling wine brands, getting heavy private and public investments for growth too.
Wouod not be surprised if next year there starts to be a bit of a price war. There's only so much space on supermarket and bar/restaurant shelves... And Chapel Down have had the benefit of early mover advantage in the last few years. But the others are catching up in marketing and sales firepower...
https://www.ft.com/content/39b...
FT article about DraftKings examined bid for 888 Holdings (LON:888) during the summer
My morning smallcap tweet: Waiter, what's in the soup? "You are."
Home Reit (LON:HOME) £STV Fusion Antibodies (LON:FAB) Time Finance (LON:TIME) Works co uk (LON:WRKS) Regional REIT (LON:RGL) DSW Capital (LON:DSW) Angle (LON:AGL) Libertine Holdings (LON:LIB) Myanmar Investments International (LON:MIL) Concurrent Technologies (LON:CNC), Wincanton (LON:WIN), Renewi (LON:RWI)
◄Home REIT (HOME)► sells 153 properties (6.5% of the portfolio by number) for a total of £24m. Properties were in poor condition, largely vacant and requiring significant capital expenditure. [SP=38.05 Cap=301m]
◄STV (STV)► guides FY op profit c.£20m "impacted by weak national TV advertising in Q4 and the related effect on the rate of commissioning in Studios". Q1-3 rev up 30%. Q4 ad rev soft. [SP=NA Cap=NA]
◄Fusion Antibodies (FAB)► guides H1-Sep rev behind current market expectations, at £541k+. Several projects were subject to certain technical challenges. Weak rev offset by stringent cost controls to preserve cash. Outlook - positive spin: "prospects for growth remain positive". [SP=5.25 Cap=3m]
◄Time Finance (TIME)► guides FY24 pretax £5.4m+ cf F/C £5m. [SP=28.72 Cap=27m]
◄TheWorks (WRKS)► warns FY-Mar pre IFRS 16 adj EBITDA only c.£6m. Blames weak demand and a need to maintain a higher level of discounting than envisaged. [SP=40.46 Cap=25m]
◄Regional REIT (RGL)► sells office for £6.25m, 26% above book. [SP=27.45 Cap=142m]
◄DSW Capital (DSW)► guides FY-Mar adj pretax £1.1-1.4m. An upgrade? The higher end remains achievable but is subject to certain M&A deals. Licensees have seen a more normalised level of M&A activity in Aug-Oct. [SP=47 Cap=10m]
◄Angle (AGL)► warns FY23 rev only c.£2.2m cf F/C £3m. Cash in line. Cash runway extended to Q2 2025. [SP=13 Cap=34m]. I hold.
◄Libertine (LIB)► AGM stmt. update on H1-Sep trading and operations that has no trading data I can see. Cash at hand £0.9m which should last to May. "We are on track with the implementation of further performance and durability enhancements to our intelliGEN™ and HEXAGEN™ platforms. These enhancements are intended to satisfy entry requirements for multiple OEM new product development programmes expected to commence in 2024." [SP=2.5 Cap=4m]
◄Myanmar Investments (MIL)► proposes delisting after flagged consultations. "Realisation of the remaining investments could be some time away and that urgent steps are needed to conserve the Company's cash reserves." [SP=0.05 Cap=2m]
◄Concurrent Technologies (CNC)► launches its highest performance Plug In Card "with enhanced operational performance unlocked using an emerging cooling technology". [SP=69 Cap=59m]
In line: WIN, RWI
Cinch Holdco increasing their stake in Vertu Motors plc.
Good morning. If you have time could you go over jet2 and see how that looks in your eyes? Thanks.
Morning Tomas,
Jet2 (LON:JET2) is a bit big for us now, at £2.4bn mkt cap - see the explanatory notes above for what we cover (£10m to £1bn market caps).
Also, I don't see any news from it today - it's each days news that drives our agenda.
Looking at the StockReport, I see JET2 has a strikingly low forward PER of 6.6. I've been very impressed with the company over the long run.
Regards, Paul.
http://newsfile.refinitiv.com/...
Hi Tomas,
these Wizz Air results are a pretty good read across for Jet2
Wizz Air Holdings (LON:WIZZ)
Jet2 (LON:JET2)
And whereas Wizz Air Holdings (LON:WIZZ) has a terrible reputation (the worst for cancellations and delays) Jet2 (LON:JET2) has among the highest customer satisfaction ratings. Why is the P/E ratio so low? General worries about aviation (fuel cost risks, pandemic risks, cost of upgrading the fleet)? Should relate over time unless something really bad happens. I hold
Wiz air deserve there poor reputation, ok when things go right but when things go wrong they are worse than useless.
Morning Tomas
I hold Jet2 (LON:JET2) for various reasons already posted on Stockopedia. In my view it is a very well managed company, which is strikingly cheap despite the positive updates from its peer group.
Notwithstanding its cyclicality and the current economic malaise I would be happy to add to my existing holding at the present price, but that is just my view, others are welcome to disagree.
http://newsfile.refinitiv.com/...
Chapel Down (OFEX:CDGP) Huge increase in quality and quantity of 2023 Harvest reported this morning.
And proposes moving it's listing to AIM
http://newsfile.refinitiv.com/...
Bull market thought of the day.
It appears (see below) there's a 'mountain ($5.9 trillion) of dollars' currently parked in US money market funds - hopefully primed at some point to come back into stocks.
During this rise in money market deposits the US market has experienced bullish conditions most/much of the time. So that's a bad correlation at the simplest level of this 'insight'.
A significant and perhaps most of the rise in money market funds in US can be explained by moves in rates and yields. Causes: 1) deposits move from interest rate lagging bank accounts into money market funds that reflect Fed rate rises promptly (see Feb/March deposit panics) and 2) the significant inversion in yield curve means that some money has moved to short end for extra yield rather than traditionally parking at long end (and some of that probably flows into money market funds)
Quote from a recent FT article dated November 6 on the deluge on inflows into money market funds over the last year.Could be statiscally irrevelant as just one data point but the US markets, ex- the Magnificient Seven for obvious reasons, have had a big reversal the last week.Even the XBI ETF, pre-revenue biotech had a big 5% bounce one day and a few other non GAAP profitable, billion dollar valuation us companies have been rewarded significantly on earnings reports recently, notably ROKU (one of Cathie Wood's stable).Perhaps some of it is already making its way back into equities?Could we dare dream?!
'But, despite overall inflows in the year to date, October marked a partial reversal of the tide, with $36bn leaving US money market funds on a net basis. That marked the biggest monthly decline since April 2022.'
'In the seven days to October 18 alone, more than $100bn was pulled out of US money market funds — the biggest weekly outflow on record, based on EPFR data going back to 2007.'
'Still, early signs of an outward trickle have sparked questions over the competitiveness of cash-based vehicles as higher interest rates start to drag up the yields on longer-dated assets. It has also fuelled debate over the risk of a small leak from money market funds turning into a torrent.'
https://www.ft.com/content/935...
Is there a sterling ETF or other sterling grouping investment covering he Magnificent 7 in the US. I guess there are a range and any recommendations, other information would be gratefully received form contributors ere, not just Strawberry Dreams, no matter how tasty he sounds!