Small Cap Value Report (Thu24 Sept 2020) - PMP, DISH, CCT

Good morning, it's Paul here with the SCVR for Thursday. Apologies for the placeholder being a little late (07:24), this is because my phone was accidentally turned off, and so my alarm didn't go off as usual at 06:50.
Timings - TBC.
Agenda -
Portmeirion (LON:PMP) (I hold) - Interim results
Bigdish (LON:DISH) (I hold) - funding update
Character (LON:CCT) - trading update
.
Bigdish (LON:DISH)
Share price: 2.0p
No. shares: 275.7m
Market cap: £5.5m
(I hold)
This is a tiny, pre-revenue share, so I'll keep it brief. It's one of my larger personal holdings, because I see interesting highly speculative upside. The concept was originally a discount dining app, that used yield management principles to allow restaurants to offer discounts for specific half hour slots, in order to get bums on seats at times they would otherwise be empty. It worked superbly, and I used it at least twice per week, pre lockdown.
The business model was recently broadened, to expand into takeaways, link into EPoS systems, and become a package (initially free, to rapidly gain market share) intended to disrupt existing booking apps, and in particular to start eating JustEat's lunch (who price gouge takeaways by charging 14%).
The market potential for an ordering & discounting app is clearly much larger now, as restaurants need to manage the flow of customers more closely, in order to maximise revenues, given that capacity constraints and 10pm closure are being imposed to help battle covid.
Quite an ambitious plan, and it needed funding of $5m, with the remaining cash close to running out. The Chairman told me he didn't want to dilute existing equity, so was looking at alternatives. Since DISH has a full listing, not AIM, a conventional equity fundraising would be too expensive, needing a prospectus to be produced. He's proven adept at raising money before, getting c.£2m from a US investor last year, at 7p per share (price now c.2p per share). Technology investors will pay mind-boggling money for startups these days, especially in America.
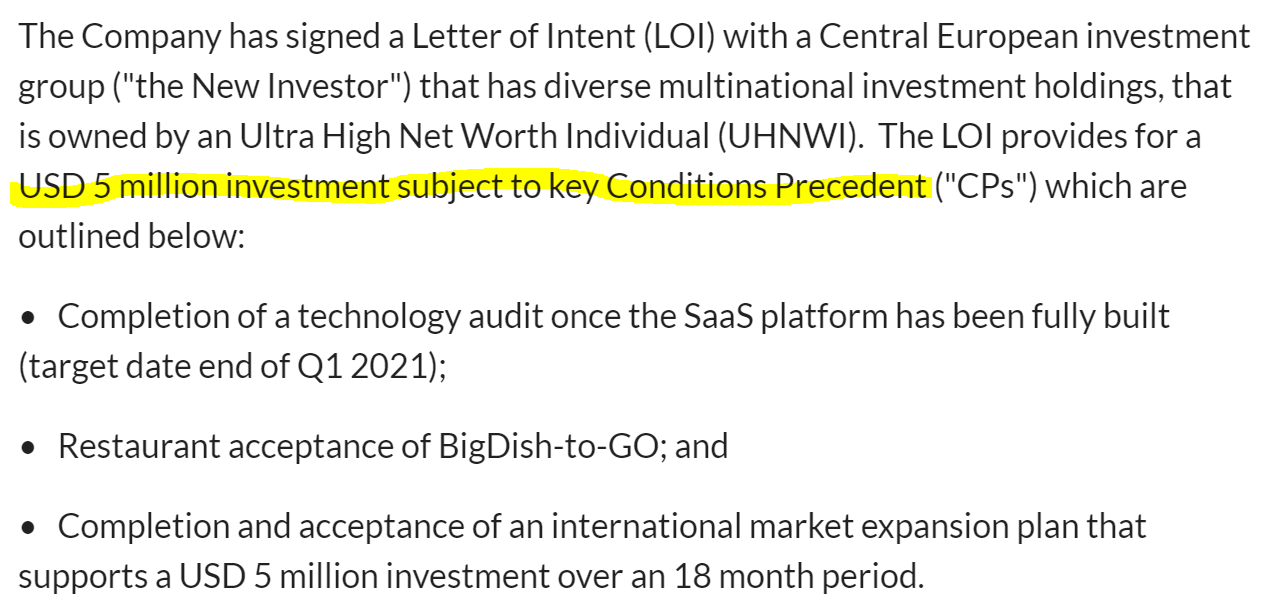
Today we're told of a deal that's been done, but it's subject to quite stringent conditions.
Short term funding of £540k has been secured as a loan, which extends the cash runway until June 2021 - good news. Although I don't suppose the loan would be cheap, but we're not told the terms. It avoids dilution at a low share price, so as a shareholder, I'm very pleased about that.
Potential $5m funding - heavily conditional, so obviously there's no guarantee this will complete next year;
.
.
My opinion - I'm happy with this. My main worry was that cash is close to running out, so I wanted to avoid being diluted in a further fundraising. As I've emphasised numerous times before, this is highly speculative share, which will either go bust, or be taken private for peanuts, or multi-bag. If it works, it could be a major multibagger - that's obviously why I'm having a punt on this, in the hope the shares could go bananas next year. But I'm fully aware of the risks, and have sized the position so that it won't kill me if things fail.
Given that the existing app is excellent (I used it a lot pre-lockdown) then I understood the potential for this, if everything goes well in the future. Plus the company already has an excellent telesales operation, which pre-covid had a proven track record of recruiting restaurants rapidly.
The stock market is obviously sceptical at this stage, which is why the market cap is so small. That's fine, it will take 6-9 months for this project to develop, so we'll see what happens in due course. Definitely not for widows & orphans!
.
My mouse just clipped the "BROWSE" button on the left, by accident, and I lost the entire section I'd almost finished writing on Portmeirion. An hour's work destroyed, arrgghhh! So I'll have to start all over again. It's so maddening when that happens. I think I've managed to successfully suppress my rage & urge to destroy something!! And breathe. Right, here goes...
Portmeirion (LON:PMP)
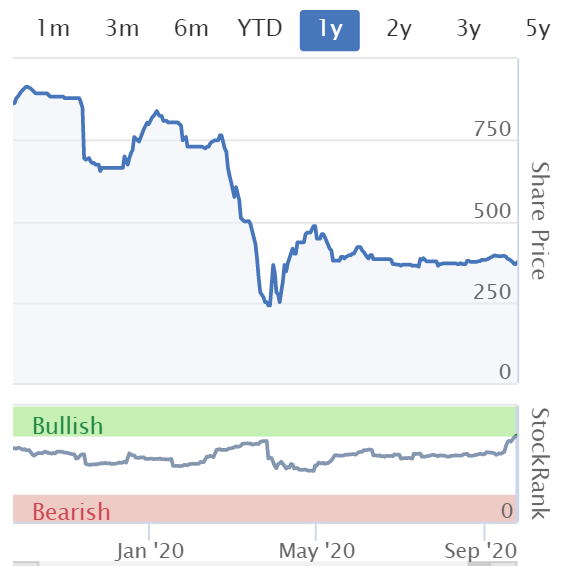
Share price: 375p (up 2%, at 09:43)
No. shares: 13.97m
Market cap: £52.4m
(I hold)
Portmeirion Group PLC, the designer, manufacturer and worldwide distributor of high quality homewares under the Portmeirion, Spode, Royal Worcester, Pimpernel, Wax Lyrical and Nambé brands, is pleased to announce its results for the six months ended 30 June 2020.
It's worth having a recap of my report on 15 July 2020 here, which summarised the H1 trading update. Today's figures are consistent with that, so no surprises.
H1 revenue down 8.3% to £32.0m (helped by acquisition of Nambe, organic growth was minus 20.4%) - obviously caused by covid resulting in customers shutting down their retail sites
Headline loss of £(2.7)m - not bad in my view. H1 is seasonally slow anyway, with only a £0.5m profit LY
Continuing improvement in sales within H2, and UK factories now close to pre-covid capacity
Online growth very strong at +90% in UK & USA. This is a very important element of the new growth strategy, with digital marketing & eCommerce specialists having been recruited to drive sales through this (higher margin) channel. The company is expecting continued strong growth in H2
Net cash of £1.1m, plus plenty of headroom on bank facilities - helped greatly by £11.2m (net) placing at 380p
Dividends expected to resume in 2021. Historically PMP paid generous divis, so I think buying now could lock in a decent long-term income stream - although remember to adjust for the increased number of shares in issue since the placing.
Balance sheet - is strong. NAV: £56.5m, less intangibles of £16.5m, gives £40.0m NTAV - which is plenty for a group this size, and not much less than the market cap.
Inventories look high at £30.6m - possible over-stocking, I wonder? Or it could just be due to the last acquisition coming into the numbers for the first time?
Note the pension deficit, of £2.0m. Not much, but it consumed cash of £1.2m last year, and that fell to £0.4m in H1 TY. With interest rates now permanently zero (probably), then pension deficits are an ongoing problem.
Cashflow statement - looks fine.
Outlook - very vague comments, sticking to the previous formula of saying that H2 should be profitable - which sets the bar very low, because H2 is usually strongly profitable, making almost all the year's profit.
Webinar & interview - there's a InvestorMeetCompany results presentation, with Q&A at 2pm on 28 Sept.
Plus, I will be interviewing the CEO (audio) late on 2 Oct. So if you have a brief and coherent question (not some rambling essay, as people often post!) that you'd like me to ask the CEO, then please leave a comment below. It's great to have some crowd-sourced questions.
My opinion - the growth strategy appeals to me, especially online growth. I've ordered twice, and am delighted with the Botanic Garden range of items received - terrific product quality, and not expensive for what it is. There's a clear opportunity to engage directly with customers, which bags both the wholesale and retail margins for PMP, and talking directly to the end customer means they're more likely to repeat buy, as the products are nice things to collect, and replace when they get broken. Email marketing to an existing customer is free. Although I am finding the frequency of emails rather annoying. How many plates do they think I'm destroying? Well after today's episode of losing my work, to be fair, it could have been several! Maybe I have some Greek blood?!
I was watching coverage of Nike results on CNBC last night, and they're now selling about a third direct to end customers. I think this is the way forward for brands. It's a huge threat to Jd Sports Fashion (LON:JD.) and Frasers (LON:FRAS) I reckon, as more brands are likely to go down this route, of cutting out the middleman and instead building a relationship direct with end customers. It could also ultimately prove a threat even to £AMZN as brands take back their customers from the original disruptor, possibly?
Some of my best investments in recent years, have been companies which crack the online market. A great example is Best Of The Best (LON:BOTB) (I still hold, but have reduced my position size more recently). I doubt whether PMP is likely to shoot the lights out like BOTB has done, but it could do well if it successfully migrates more sales online. In the meantime we should start receiving divis again next year, and sleep soundly knowing that the business is strongly financed, and has demonstrated the ability to cope well with covid problems.
Not the most exciting investment idea, but it looks solid, and good value to me, taking a long term view.
I almost forgot to mention, the historic problem of grey imports into South Korea (PMP's 3rd largest market) seems to have been fixed. This is where retailers would order product at lower cost via another country, thus reducing PMP's margins.
I think the challenge for the new CEO is to get trading back on track post-covid, but then to establish a renewed upward trend in profitability. In the last few years, profits seemed to stall, despite acquisitions - meaning that the original business was going backwards. That's why the share price has fallen a lot. Maybe a buying opportunity, maybe a stagnant struggling business? Time will tell.
.
.
Character (LON:CCT)
Share price: 316p (down 2% today, at 11:08)
No. shares: 21.38m
Market cap: £67.6m
Designers, developers, and international distributor of toys, games, and giftware
The Board of The Character Group plc (AIM: CCT) (the "Board") provides the following update to shareholders on the Group's trading ahead of the publication of the Company's results for the year ended 31 August 2020.
This is a rather quaintly-worded update, but it seems to read well. Key points;
UK lockdown had considerable impact
Trading has been satisfactory
H2 should be at least as profitable as H1. I've looked up H1 figures, and it was PBT of £2.5m, and diluted EPS of nearly 10p. Therefore it sounds as if the full year FY 08/2020 should be 20p+ EPS - rather poor since the prior year was c.43p EPS - but not a disaster, considering all the problems this year re covid
Demand resilient
Expecting "steady progress" for Xmas 2020 & into 2021
Early feedback on 2021 Xmas products "extremely gratifying"
Strong balance sheet, and "sizeable" cash, plus unutilised facilities
Prospects good
My opinion - I've checked back to the last published balance sheet, and it's excellent, with over £32m in NTAV, and pots of cash, nearly £20m, less a little debt. This is therefore an unusually strongly asset-backed small cap. That greatly reduces risk for shareholders, and means you're getting a load of surplus assets in for free, the way I look at things. Plus you're not likely to be diluted, as it won't need to do any fundraisings. And/or the cash could be used to make earnings-enhancing acquisitions, or a special dividend? Lots of opportunity when a company is sitting on a lot of surplus cash.
I also like what is said in today's update about strengthening relationships with customers during this troubled period. That's important, because business is essentially all about relationships, and trust. Therefore, companies which understand this, will have used the covid period to strengthen those relationships (e.g. giving customers more time to pay, or reduce order sizes, etc). It sounds as if CCT has done that.
Broker forecasts look too high, given what is implied today about H2 being similar to H1 earnings.
This share always looks cheap, and it's been an excellent dividend payer for years, so the total shareholder return is a lot better than the share price suggests. Looks quite good to me, as a value share.
.
I'm taking a break for lunch now. Will look at a couple more things later.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
Hi Paul - you had TEG on yesterday's list but, what with dog grooming etc....you must have run out of time to give everyone your latest view. Despite the general trend south this week, TEG is holding up well so I assume their limited reopening is going quite well, but would be great to hear your take on it please?
Paul did get round to commenting on it on yesterdays review - https://www.stockopedia.com/co...
Does anyone know the reason behind the goco fall today?
Goco (LON:GOCO)
I hold.
Maybe it's to do with the launch this week of an energy switching service by rivals Moneysupermarket.com (LON:MONY) ?
Or it could just be down like everything else in my portfolio today, which looks more like a Tarantino movie than a happy share portfolio.
A
Thanks abtan I'm a bit out of touch since I met them a couple of years ago, but they seem to have good momentum with their own switching service and imagine there is room for 2 or 3 players including compare the market. I wouldn't have thought people were assuming they would completely dominate the space.
Tremor International (LON:TRMR) H1 20 results presentation by Ofer Drucker, CEO, who outlines Tremor's vision, H1 highlights, market trends, KPIs and the outlook.
Video or Podcast.
finnCap say, H1 is ahead of forecasts & with a strong Q3 update, they have upgraded FY20 forecasts, have a target price of 500p.
Tomorrow, we will publish the piworld interview with Cockney Rebel, from the live webinar today. It was superb. I'll post a link here on the SCVR, and you'll also find on piworld, as a video or podcast.
We should also be publishing results presentations from Litigation Capital Management (LON:LIT) & Judges Scientific (LON:JDG). Just awaiting permission to publish!
Paul's comments about manufacturers going Direct To Consumer instead of selling to retailers are echoed and amplified by the latest blog from Richard Hyman who is rarely wrong about retail, see the post here: http://www.richardtalksretail....
Hyman points out that the shift is made up partly of brands selling direct (eg: Apple, Nike) and partly of retailers developing their own labels (eg: BooHoo, M&S food). But whichever way you cut it, the losers are brands who find it hard to sell direct (eg: Unilever,) and retailers who cannot produce their own outstanding product (department stores).
For what little it is worth I completely agree. When a large long-established business sector is in decline it is easy to mistake the occasional blips upwards as marking the end of the decline, but I think the widespread investor sentiment that conventional bricks-and-mortar retailing is dying (ie: going, eventually, to be dead) is absolutely right, and the response to the virus has taken about 10 years off the remaining lifespan.
Where I think most people are behind the curve is in the effect on retail property. Every time I come face to face with a real life example I am forced to the conclusion that there is hardly a retail property in the country that hasn't declined in value by 30-50% in the last 6 months. I know of some real-life examples where the decline is 75% (eg: the sale of a vacant shop at auction for £120k, bought for £500k two years ago). Any shop where the rental value has fallen by 50% will probably have seen its multiplier also fall by 50%, so a shop with a rental value of £50k and a capital value of £1m (5% yield) now has a rental value of £25k and a CV of £250,000 (10% yield).
Where I think absolutely everyone is behind the curve is the effect of this on pension funds who hold UK retail property as assets. They are losing both income (tenants refusing to pay rents because the government is preventing foreclosure) and capital value, both at the same time.
But... take a look at £CAPC. Owns Covent Garden and 26% of Shaftesbury. Both on 50% of book. Looks cheap so I bought.
Great choice. I don't hold yet. Used to walk past covent garden each week for weekly dim sum with the family. After C19, some places, particularly Grade A prime props like these will go back to doing what they do best. Thanks for pointer
It’s similar to divi stocks - cut the dividend and share price follows - those who hold lose both income and capital value
I visited Covent Garden during a 3 day walking tour of central London 25 - 27 August. Covent Garden was dire, absolutely dead in the water. My contacts in London say things did start to pick up the following week but this week's madness will have sent the place back to square one. I will be interested to see how much of the rent Capital & Counties Properties (LON:CAPC) were able to collect today (September quarter day). But perhaps the CG leases are monthly base + turnover - I don't know.
FWIW I took some video inside Harrods and Peter Jones during my visit. I know a dead department store when I see one, and I was looking at two of them then. They are demised. They have ceased to be. They have expired and gone to meet their makers. They have shuffled off this mortal coil. They haven't actually run down the curtain yet. I'm guessing that will be January, around the time IAG do the same to British Airways.
which stocks could benefit from the new government scheme just announced? I wonder..
https://www.cityam.com/governm...
Hi luckystrike, The uptake will be interesting as it looks like HMG are "taking a stake" in funding your employee, so that if I read it correctly and to simplify - once the individual is funded you are UNABLE to make them redundant and the company will have its capital distribution controlled too.
There were quite a few companies that took funding originally and then repaid it - it will be interesting to see this schemes take up.
I'm not implying that only the Zombies will fill their boots but the ones who publicly say thanks but no thanks would interest me more as an investment
I'm not sure it is actually aimed at typical recipients of the help so far. My back of envelope calculations for pubs:
Ex- VAT Turnover £100
Typical Wage Cost % = 30% of turnover (varies greatly - food focused or smaller pubs higher, larger drink focused lower)
So typical wage cost is £30 per £100 taken
If you were to take full advantage of scheme - i.e. use to the max benefit by keeping all employees at 1/3 of current time, the split would be:
33.3% wages as normal for actual hours worked
22.2% wages as top up paid by employer
22.2% wages as top up paid by government
So the wage bill for employers per hour would climb by 66% in that scenario to 50%ish of total turnover. This would be instant massive losses for every pub and restaurant in the country.
I guess you could stomach it to keep good staff for a short time in an emergency or try and use it at the margin to retain a few staff but....
It must be aimed at companies that have extremely highly trained staff - pilots maybe who have to fly so many hours a month to keep current maybe? People like that I guess.
US system is much cleaner. You sign on as temporarily unemployed. They then give all unemployed a supplementary benefit..As jobs return they come off unemployment.
Paul,
I want to plug Investor Meet Company as a resource for private investors as I have already sent questions to it for £PMP. You book for their online results presentation with a simple drop down box to ask a question. No doubt they aggregate and select but even so, fantastic! I asked:
Q1. What absolute £ and % of sales are are now made i) online through company controlled websites (known) and ii) online through 3rd party (internal estimate). (As E-commerce increased 96% is pretty meaningless - vs a base of $3 or $3,000,000)
Q2: In its results staements, why does the company not publish simple tables (This half, this half last year, full year) of its performance on its key strategies like internal management get vs wordy, difficult to interpret statements (Always mention this, maybe eventually it will change)
Q3: Is the Board confident a >£1Mn in Hand Sanitiser line will deliver long term sustainable returns. MANY MANY companies have launched hand sanitisers and built CAPEX for it. COVID is likely to be controlled within 1-2 years max based on history so surge in demand is likely to be temporary and permanent uplift small. Is Wax Lyrical a good brand for a germ killer AND a romantically scented candle
I also note the Sales & Marketing Director is exiting the company. I have liked the pivot towards digital that began 2 years ago and was long overdue for a company that sells individually small moving skus in retail stores and which can build into collections. There should be huge upside here at much much higher margins - no data here but shifting crockery to a store, displaying it and waiting for it to sell must be hugely expensive vs selling it direct off a digital picture..
I hope the new CCO will also address the desperate looking permanent 50% off list price pricing strategy and the presentation of products on the website which is completely out of kilter with a quality story that includes 250 years of history (Spode) and 'each piece passes through 22 hands' before reaching you the customer. More brand story to build value (what at the end is a nicely patterned dish).
Finally, like most here, I am nervous about an aquisition strategy but these are special, blood on the street times. In the next couple of years there should be loads of small, good brands turning over a few milion that are going under; done right these could be added to the 6 key brands already held and provide scale for a nice upmarket homeware company.
I am very optimistic that on a 2-3 year basis this share can get back to the >1000p level a steady dividend as it now focusing on correct issues (online, US/Uk centric plus ltd ROW) and has some tailwinds like WfH and limited eating out which I think will stimulate interest in the kitchen. Resumption of dividends is (nearly) promised for 2021 although I think the company will rightly reset to a lower start point so it can progressively increase again and keep balance sheet strong for opportunistic bolt ons.
"I hope the new CCO will also address the desperate looking permanent 50% off list price pricing strategy" re. Portmeirion (LON:PMP)
Couldn't agree more, Zipmanpeter. It reminded me of Paul's comment the other day about discounting by Superdry. If you disrespect and devalue your own brand, what signal does that send to your customers?
err you can always "groupon" them instead !!!!! On the otherhand, probably not good idea either!
Echoing your thoughts on Character (LON:CCT) Paul - it always looks cheap. I was previously a holder a few years ago and it reached over 500p but Toys'R'Us going bankrupt, then a big Scandinavian retailer collapsing followed by Hasbro's takeover of Entertainment One (who own the Peppa Pig brand) has meant the share price has pretty much gone nowhere for the past year.
Although the 95p/shr cash gives a decent buffer, I think there's still concerns over whether they'll eventually lose the Peppa Pig licence (I think it expires either in 2021 or 2022), Xmas spending being curbed by the recession and a pretty mediocre P/E range over the last 5 years (highs of 13.5x).
Private investors - Great chance this afternoon to listen to a Fund Manager discuss the highs and lows of his job - and crucially how to pick and avoid stocks. He may even confess his mistakes! Simon Young of AXA Framlington at 4pm today. Register here:
https://us02web.zoom.us/webinar/register/3915996385255/WN_PgOaolxuQ4qIwDHGqD9F0Q
N+1 Singer coverage of £PMP today. Target price of £6.50.
Around break even this year.
2021 EPS 36.7p
2022EPS 56.4
Dividend resuming next year at 4%. 2022 6%
If these number are accurate its on a 2022 PE of 6.5x with a 6% forecast divi
Great, thanks Ringo - very helpful as I hadn't spotted those forecasts.
I was going to say, the forecasts on Stockopedia look to be old ones. TR doesn't seem to remove old forecasts, even when guidance is withdrawn. This means care is needed not to automatically rely on forward-looking metrics like PER & divi yield.
We own Venture Life (LON:VLG) in the Staff Investment Club - which I've written up here. I'm long too.
This is a great article, Ed. The BuySell rules are an interesting stimulus to develop one's own. Congratulations on your outperformance. Will you publish your club portfolio whenever it changes?
This press headline caught my eye today.... "Europe risks languishing in slump as America's economy powers ahead". I look around for the European major tech companies; they don't really exist. Our major index is full of banks and oil companies. The UK banks seem almost desperate to withdraw credit; yet the number of people saving for the first time has apparently gone through the roof according to Nat West and others. Confused about where we are? I certainly am.
Have we actually got a world class company in the UK? years ago there was Royal Dutch Shell (LON:RDSB) but not now. Maybe they are private like Ineos and Dyson or ARM but I can’t think of a FTSE 100 that merits that label.
How about Diageo (LON:DGE), GlaxoSmithKline (LON:GSK), Unilever (LON:ULVR) ?
Maybe Diageo but hardly £GSK. USA has J&J, Pfizer and many others. Maybe £RB but not sure.
Not long ago LON:RR would have been one for sure. Sadly ....
I contend that UK is full of banks & oil is a lazy media narrative that persists today, not supported by data
Looking at £VUKE in top 10, HSBC, Rio, BP, Shell are cyclical (15% of index). Remaining 6 is consumer defensive & healthcare: AZN & GSK, ULVR, DGE, RB. and BATS (25% of index).
Collectively, oil/banks are 17% of the index (25% when adding metals & 33% including diversified financials).
No tech, but quite defensive & very international. In effect, it is the much vaunted barbell strategy that was all the rage in Q2.
Am tempted to add here. I am still very bearish on UK plc (have certainly been diversifying my £ cash) but FTSE100 has very little to do with UK. I dare say FTSE100 is a decent option whether you expect a cyclical recovery or want to hide in defensives.
£BP shares must be on thirty year low and so too £RDSB. Perfect value traps. Our banks don’t compare with JPM or Goldman Sachs and have virtually given up investment banking . They are zombies. If you want a tracker MSCI World or S&P must be better.
Boohoo (LON:BOO) still failing to close above 325 although it went as high as around 236 yesterday but slumped back again. This is the 5th time it can't hold on to above 325p.
I am not a chart follower but what would the chart suggest if Boo can close above 325p?
It’s already on a PER of nearly 50.
Not having a go at £Boo, everyone’s favourite!. Just pointing out fundamentals are what to look at.
It's on a PER of 50 is that statement.
Is that forward PER or historic? If historic, if they grow at 40% this year, that becomes a PER of 30, another (let's not overplay this) 20% growth the year after then puts it on a PER of 24.
Historic PER is meaningless in that context. Fundamentals indeed.
weak sellers will eventually give way to the buyers then hopefully.
see what happened to Integumen (LON:SKIN) as an example when it finally broke free on the 5th August after 3 months of consolidation never managing to breach a resistance line
I don't see how fixating on the chart is very relevant with Boohoo (LON:BOO) at the moment.
The key issues will come next week - it's meant to be publishing the supply chain review by a QC, at the same time as Q2 trading.
If the supply chain review is bad, and suggests that BOO management knew of malpractice in its Leicester suppliers, then it could trigger yet another spike down in price. These have been lovely buying opportunities in the past, but they do get tiresome after a while.
The Q1 trading update was superb, so I imagine Q2 is likely to be strong also. Will it be strong enough to offset any panic over the supply chain review? Who knows?
The market might look through the supply chain review, and as long as BOO promises to fix the issues, then it's like to soon be forgotten.
Given that I didn't want to go into another spike down with a humungous leveraged position on spread bet, I've reduced it down to a size where a (say) 25% spike down wouldn't hurt too much, and would still leave me with cash available to buy the dip heavily.
Long-term, BOO is probably the one share I'm most confident about. Buying up failing brands, and putting them through the same winning formula, makes them unstoppable in my view. The supply chain stuff is a problem, but soon gets forgotten, and moving production overseas will bring down the cost of production, thus boosting profits.
I think 28th Sept (Monday) is the date for both trading update and supply chain publication. So likely to be a bumpy ride is my best guess.
Regards, Paul.
On Bigdish (LON:DISH), I don't like fact that Jonathan Morley-Kirk, Non-Executive Chairman, sold 349,045 shares at 2.3 pence per share on 28 July 2020. Why are mgt selling if this has decent prospects?????? Again, the price has dropped so above person called the direction of travel of share price right. Plus Tom Sumner CEO only came on board late last year....(experience????)
Slightly sceptical comment on Bigdish (LON:DISH) on Richard Holway's TechMarketView daily email:
"BigDish, the main market-listed food technology firm that we track, has lined up a $5m investment over an 18-month period from an Ultra High Net Worth Individual that could secure the long-term future of the business. However, the funding comes with some pretty hefty caveats and tasks that need to be completed, that means that BigDish has everything to do in a short space of time.
Firstly, the firm has to successfully pivot to SaaS by the end of Q1 2021. No easy feat and to fund this a short-term loan from an investment company of £540k has been agreed.
Secondly, BigDish needs to secure market acceptance of BigDish-to-GO – we assume some targets have been set that must be reached to release the funding. Whilst the market is definitely moving in this direction post-pandemic with takeaway and delivery performing better, it’s a competitive and pretty crowded market and their tool is still in beta.
And finally, BigDish must deliver “Completion and acceptance of an international market expansion plan that supports a USD 5 million investment over an 18-month period.” – something that sounds both difficult and expensive. It’s also not obvious which markets they are targeting and rolling out across the UK looked hard enough.
It all sounds very “Brewster’s Millions” (for those of you who remember the Richard Prior movie from the 80s) with lots of money and effort to be spent against the clock in order to win the grand prize. If Big Dish completes these tasks it then gets its money by the end of the second quarter of 2021 or as the company puts it…..“Whilst the Company is optimistic of a successful outcome……..there can be no guarantee of such.”Sounds like there is a movie script in this one or at least a reality TV show."
I’ve always learnt that sells by management should be treated with caution as a signal unless they are enormous or give away control by a founder or something of that nature. 349,000 shares sounds like a lot but in value it’s less than £8k - maybe his roof had a serious leak or he needed a new car or a holiday. It might mean something, granted but it might not.
Buys by management are a different matter. I always liked the quote from Phil Town (which I’m sure he stole from someone else) “I know of a hundred reasons why someone might sell stock but I only know one why they might buy some”.
Byotrol (LON:BYOT) results look better than I had expected though clearly some weaker holders getting out this morning with quite a big drop. I suspect it is investors who went in on the recent newspaper tip being disappointed it hasn't multi-bagged in 5 minutes :)
Anyway results were already known so no surprises there. More interestingly the outlook which is apparently ahead of recent trading update expectations, which in themselves were ahead of expectations at least twice before I think so clearly we are now seeing a strong upward trajectory in profitability.
There is some research on Research Tree which puts a target of 11p on it - similar valuation metrics to peer Tristel (who are also licensing the Byotrol (LON:BYOT) hospital product). That says revenue at £11.5m for the year. eps of 0.3p which feels a bit light to me. On the basis that the last trading update saw £3.4m sales for the quarter and expectations are ahead that feels like an H1 of around £7m+ so £4.5m in 2nd half would be a big slow down and it's not like sanitisers/disinfectants etc are out of fashion!
Can see analyst expectations on revenues and profits needing to be upgraded over the year on that basis so expecting maybe £13-14m in revenues and 0.5-0.6p eps personally. With £1.9m net cash balance sheet is ok, so think fall today is overdone.
£byot are now showing as +1% on stocko and -13% on Hargreaves L - stocko prices seem a bit out recently, anyone else noticed?
For what it's worth, I use Google for live prices (I think they're still live!) both Stocko and HL are out by a least 15 mins. Also Stocko shows the mid-price, whereas (in your portfolio at least) HL will show you the Sell Price.
Google LON:TICKER (e.g. LON:BYOT)
I also like that dragging your cursor from one point on the curve to another point on the curve gives you appreciation(or depreciation) in Google's charts.
I thought Stocko. showed the last trade price, so prices go up and down like anything if the spread is wide. Byotrol (LON:BYOT) is down about 12%, don't know why Stocko was showing +1%. Stocko prices are delayed by at least 20 minutes.
As herbie47 has pointed out Stocko price is the (delayed) last trade and this I avoid - if a small cap with a 6% spread is unchanged all day it will be shown varying between +3% and -3%.
However, google is no better, except that it is live - I have just tried it for Venture Life (LON:VLG) and it shows 101.05 (trade at 10.50.09) whereas it is 102 (101/103) at the moment.
Might be watchful on the time stated on the google prices / charts. For the less liquid stocks, they can be out by 15 minutes still. If I really need to know the exact price at a certain time, as a freebie, I use IG and see instant share price movements there. In that way, I know what I am seeing is in real time.
Hi Paul,
Would you mind having a look at £btoy Byotrol
Unusually this has fallen 9% on an exceed statement:
‘’The Directors were pleased with developments in the year, with good progress in financial performance and in all strategic initiatives.
The Directors are similarly pleased with performance to date and expect results for the year to 31 March 2021 to exceed current market expectations.
Financial highlights
Our results to the year were marginally above expectations across all key financial measures. Headlines are:
• Revenue at £6.07m (FY19: £5.66m)
• IP sales included in revenue £0.78m (FY19: £1.93m)
• Gross profit at £2.89m (FY19: £3.61m, including IP profit of £1.93m)
• Adjusted EBITDA at £0.26m (FY19: £1.08m)
• Pro forma cash £2.01m (FY19: £2.80m), net cash £1.42m (FY19: £2.55m)
• Cash resources supporting organic growth plans
BUT buried in the financial section it states they are to make a £43000 loss?
This looks odd reporting, disingenuous ? & the market seems to agree, appreciate your forensic scalpel.
Thank you
John
Yes john652, the way it was reported, it looks as though Byotrol did not want to make the £43,000 loss too prominent! Notwithstanding the earn-out payment to Medimark, I am amazed that any company focussed on antimicrobial products including antiviral hand cleansers could have made a loss over the past year. One wonders where the company would have been without the pandemic.
Eleco (LON:ELCO)
Good Morning Paul, my first attempt at a post here.
Interims this morning from Eleco (LON:ELCO) a 75m mcap - software for the project management, construction, architectural and associated services company - with sales down 4% to 12.2m whilst operating profit is up 19% to 2m, profit before tax up 23% to 1.93m and cash generation of +4.5m turning a 200k debt into +4.3m net cash. If I've read that right!
Not cheap - but seems a very positive result supplying software and maintenance to an industry which was much affected by the lock down?
(I hold)
cheers
Mark
I think your net cash figures on Eleco (LON:ELCO) are wrong. Looks to me like it went from approx -£1.2m to £2.2m net cash. But I agree with you that this looks like a very positive result in the circumstances, so I bought more this morning given that the price fell. You say it's not cheap but I guess that depends on your criteria. To me it looks good value. Some might not like the negative NTAV but that's only because their core asset - the software - is in intangibles.
Paul may not have time to look at it but well worth a look for readers.
Thanks Mark, nice first attempt!
I like Eleco (LON:ELCO) also, and have written positively about it in the past.
Not sure I'll get time to revisit it today, but it's on the reserve bench.
Best wishes, Paul.
Paul, would it be possible to ask for your thoughts on Integumen (LON:SKIN) please?
Today's update whilst not a trading statement looks to be a whopper (they released interims last Friday) and it would be great to get your take on their prospects.
I wouldn't know where to start with something like Integumen (LON:SKIN) - it looks like a near-zero revenues, loss-making, blue sky type of thing, historically. The share price seems to have multibagged based on covid-related products.
What I do here is run through results statements for conventional companies, not speculate on blue sky stuff in sectors where I've got no expertise, e.g pharmaceuticals, etc.
that's fair, thanks Paul.
Yes I would agree with Paul's initial comments on Integumen. The CEO, Gerard Brandon, was founder of AIM listed Alltracel Pharmaceuticals so check out his track record and that of Alltracel. My initial impression is that Integumen is a bit of a hotch potch of ideas and assets so having management with a track record of success in exploiting technologies is, I would suggest, important.
Half year report from Venture Life (LON:VLG) is about as positive a set of results as you'll ever see, with operational gearing kicking in, and taking full advantage of the increased need for hand sanitiser etc, including:
• Gross profit increased 97% to £6.9 million (H1 2019: £3.5 million)
• Adjusted EBITDA1 increased 368% to £3.5 million (H1 2019: £0.7 million) implying an EBITDA margin of 21%
• Profit before tax, amortisation and exceptional items increased nine-fold to £2.7 million (H1 2019: £0.3 million)
• Adjusted profit per share2 of 2.85p (H1 2019: 0.15p)
Thanks fishcake, interesting!
I remember being very impressed when I last looked at Venture Life (LON:VLG) - looks a terrific little company, going from strength to strength. I'll add it to my list to hopefully look at later.
Thanks Paul would also be interested in your take on this.
Thanks Paul for adding Venture Life (LON:VLG) to your list (I hold).
Today, I have noticed that Ten Entertainment (LON:TEG) (I bought last week) StockRank has fallen from 82 yesterday is down to 17 today even through the shares were up 4p yesterday and 0.4p today. I welcome comments from either yourself or Ed, etc as to why the StockRank has drastically fallen so much in 24 hours??
Logical David - regarding Ten Entertainment (LON:TEG) it looks as if yesterday's results have been put into the stock report - note the TTM column. This will affect the figures that go into the SR. I suggest you open the current report and then the one from 14th Sept. http://reports.stockopedia.co.uk/257376986/Ten_Entertainment_LSE_257376986_20200912.pdf in another tab and flick between the two. You will see figures used for the SR such as Piotrosky, Altman, return on capital and return on equity have collapsed.
Thank you shawr and Glorenfeld for your helpful feedback. As you say, when you flick between the two reports you can clearly see that many of the figures have changed. I notice in particular that the Net Gearing has fallen off a cliff from 21% to 438%. I believe Ten Entertainment (LON:TEG) will survive due to the fact that it is profitable with only 50% capacity in use.
I think that this year is particularly interesting from a StockRanks perspective. As the StockRanks are a ranking, and some companies were forced to shut down completely (like Ten Entertainment (LON:TEG) - I hold) while others could continue trading, the impact of companies' most recent results on their respective rankings is going to be profound.
For those companies that can survive, however, this should be a short term blip and their ranking should normalise after a future results feed into the system. All of which is to say that I wouldn't personally put too much emphasis on a sudden drop in StockRank from companies such as TEG, but would use it as a flag to research whether it is likely to survive.
That said, perhaps Ed and team would say that the updated StockRank does fairly encode the chances of a basket of companies sharing those ranks outperforming, even given the uneven impact of the external shock across the universe of companies being ranked?
Seems to be a lot of PI's in VLG, and for good reason.
Venture Life (LON:VLG) have done a great job I concur and I'm annoyed at myself for not buying any all the way up from 40p. In fact I'm more annoyed as I saw them present a couple of years back when down much lower at 25p and thought they had an interesting strategy then. congrats to anyone that did buy.
Results as you say are excellent. I looked earlier to see if I'd want to buy and got a bit put off by current valuation. Broker notes forecast 5.3p eps this year but only a 10% increase next year. If that is correct then it means they are on 17* 1Y fwd earnings and moving to much lower growth profile. That in itself isn't massively expensive but it is toppy for this type of business.
It isn't expensive though if the growth forecasts are just too conservative (something I see in the Byotrol (LON:BYOT) case) and something the broker note alludes to, which is the bit leaving me in a conundrum. My other worry is the reliance on large forward orders from a Chinese distributor. I'm sure lots of these get done with no issues all the time and we only hear about the horror stories but it is a risk that should be discounted in some way.
Anyway I am leaning towards there still being some room in the valuation for new investors but if anyone has any thoughts on why growth should indeed by much greater than 10% next year I'd like to hear that so I can factor it in to my thinking.
Just a couple of points on VLG (I hold)
Assets are now >2/3 of market capitalisation
Cash this year has been impacted by the very rapid growth (receivables up and inventories up) - this should work through as invoices paid and inventory level becomes the new normal for the company reports so cash should recover next period
Profit margin is up and the recent acquisition has been revenue and earnings virtually from day 1 of the take over which is very unusual.
A great longer term hold IMHO but it does not yet pay a dividend (perhaps when cash flow increases but no comment in these results)
Been seeking to buy VLG on its dips. However, it hardly ever dips!!! It's now over 100p!
My morning smallcap tweet:
Open Orphan (LON:ORPH) BigDish (LON:DISH) U and I (LON:UAI) Character (LON:CCT) Nuformix (LON:NFX) Smartspace Software (LON:SMRT) Escape Hunt (LON:ESC) KKV Secured Loan Fund (LON:KKVL) Immedia (LON:IME) Byotrol (LON:BYOT) Petards (LON:PEG) Safestay (LON:SSTY) Hansard Global (LON:HSD) AA (LON:AA.), NWF (LON:NWF), Biome Technologies (LON:BIOM)
Open Orphan (ORPH) in advanced negotiation for a covid challenge study in the UK which would be worth over £7m. Also remains in discussions with potential vaccine developers over covid challenge studies. SP jumped yesterday on speculation. [SP=18.5 Cap=123m]
BigDish (DISH) possible £5m funding (into an SPV) from wealthy person, subject to three hurdles. Hopes for agreement end Q2 2021. Also has short term loan from an investment company of £540k to fund SaaS dev. [SP=2.03 Cap=8m]
U and I (UAI) planning permission progress at £200m Tunbridge Wells project. Remaing are resolution of Highways Mitigation measures and completion of the standard procedural and judicial review process. [SP=57 Cap=71m]
Character Group (CCT) guides H2(Aug) profit at least equal to H1, better than expected. [SP=328 Cap=70m]
Nuformix (NFX) has signed an exclusive option agreement with Oxilio for a licence for the development and exploitation of NXP001 in oncology. If option taken co gets "significant upfront payment and additional development milestones and a royalty on net sales, capped at £2m PA." [SP=3.53 Cap=17m]
Smartspace Software (SMRT) signs distribution agreement with a major AV integrator in the Far East, to resell its Space Connect workspace management solution. [SP=82 Cap=23m]. I hold.
Escape Hunt (ESC) AGM stmt: encouraged by last 6 weeks rev down 28%. Cautious re growing rate of covid infections and the likelihood of further restrictions being imposed. [SP=7.67 Cap=6m]
KKV Secured Loan Fund (KKVL) proposals for a managed wind-down of ords of the co despite holders voting to continue. CItes feedback from several major shareholders. [SP=17.65 Cap=122m]
Immedia (IME) absurdly late FY(Dec), Pretax -£990k (+£100k). Guides this FY EBITDA negative but substantially improved. [SP=25.5 Cap=7m]
Byotrol (BYOT) FY(Mar). Outlook better than recent guidance. [SP=8.4 Cap=37m]
Petards (PEG) H1(June) rev down 20%, post-tax -£469k (+£65k). "Other than the impact of the pandemic and delays on its eyeTrain business, the Group's operations returned a good performance in H1...closing order book of over £12m continues to provide a solid base to build upon, although given the uncertain business environment the provision of forward guidance remains extremely challenging." [SP=7.3 Cap=4m]
Safestay (SSTY) H1(June) rev down 58%. July & Aug at higher end of Board's forecast scenarios. [SP=13.93 Cap=9m]
Hansard Global (HSD) FY(June) new business sales up 2.5%, U/L profit £6.2m (£6.1m). Div flat. Q1 new business levels slightly down. AuM 'remains strong' at similar levels to the year-end. [SP=33 Cap=45m]
AA (AA.) TowerBrook and Warburg Pincus to explore the possibility of a consortium offer. Co continues to engage with a number of other parties to assess a range of alternative potential refinancing options, including the possibility of raising new equity. [SP=28.2 Cap=175m]. I hold.
In line: NWF (LON:NWF) Biome Technologies (LON:BIOM)
We're all allowed a small lie in every now and again.
Small-Cap Dog of the day Bigdish (LON:DISH)
https://www.stockopedia.com/co...
BSV
Bluesky Ventura seems to attract down ticks because he has alighted (deliberately or otherwise) on a couple of shares Paul holds but which Paul has warned readers are highly speculative and not for everyone. Having said that his comments on Bigdish (LON:DISH) are not that crazy. I could add something myself about the huge expense incurred so far in earning almost absolutely nothing. In the first instance had this been a great idea they could have approached someone like Y Combinator who have helped companies like AirBnb and Dropbox get started before finding them substantial investors. It just amazes me that companies like this manage to get a listing.
I can confess it is deliberate, but out of the desire for civic duty.
If people still invest at least they are aware of the pleather of warnings signs highlighted to them.
As always DYOR and don't trust the vloggers and bloggers
BSV
Hi, todays beta is displaying it on a full page.
Find me in the discuss tab under The Early Morning News
View on old site
View on new site
Covered today
Avacta (LON:AVCT) -Dr Alastair Smith, Chief Executive of Avacta Group commented: "I am very pleased to learn of the promising evaluation of the Affimer reagents in Integumen's sensor systems. Once detailed validation of the sensors has been carried out using SARS-COV-2 virus samples at the University of Aberdeen, and we have reviewed those data, Avacta will provide a further update to the market."
Open Orphan (LON:ORPH) - The Company confirms that it is in advanced negotiation with the UK Government and other partners for a Coronavirus challenge study in the UK. While negotiations continue, it is expected that in the event that a contract is agreed revenue will be in excess of £7 million, being the approximate anticipated revenue for a Coronavirus challenge study as indicated by the Company on 22 May 2020. However, there can be no certainty that these discussions will lead to a new contract until final negotiations are concluded. The Company will update the market in due course as appropriate.
Venture Life (LON:VLG) - Revenues increased 80% to £16.9 million (H1 2019: £9.4 million) - Gross profit increased 97% to £6.9 million (H1 2019: £3.5 million) - Adjusted EBITDA increased 368% to £3.5 million (H1 2019: £0.7 million) implying an EBITDA margin of 21% - Profit before tax, amortisation and exceptional items increased nine-fold to £2.7 million (H1 2019: £0.3 million)
Cheers!
Good Morning Paul, better late than never! I look forward to your take on Portmeirion (LON:PMP)
Silver
Interesting to see Funding Circle Holdings (LON:FCH) report an operating loss of £113.5m for the 6 months to 30 June 2020. There are some non cash items which have impacted and they claim at an EBITDA level to be near to break even for the 2nd half of the year.
They also claim that the medium to long term looks good. I guess we need to define medium term. In my opinion things don’t look great for FCH. They have been providing the CBILS loans and have done well. A lot of this has been used to refinance their existing loans. This gets rid of noisy retail investors and shifts risk of default to the government. The fees on these loans will have a positive impact. However, has this cannibalised future demand? I think it will have. How many SME’s will be left that haven’t taken up CBILS loans at low rates. This removes the need going forward. The business generates most of its income from platform fees for the setting up of the loans. They do not lend their own money (except for a very small amount) and as such need to keep pedalling to generate income.
The business is valued as a tech business. At best it is a Finance company but without it’s own loan book it is just a fee generative platform. No new loans. No fees.
I am surprised it hasn’t dropped further. I am assuming the break even at EBITDA level for H2 will be just for H2 rather than the full year.
Funding Circle Holdings (LON:FCH)
Hi Camraid
Thanks for your input on this company.
EARLY HOPES
I held earlier this year on the hopes that they would be in prime position to take advantage of the PPP loans in the US, and CBILS and BBL in the UK.
They put out lots of little clues over how well they were doing on LinkedIn and Twitter at the height of the crisis and I thought they would be quids in.
After all, a large chunk of the PPP loans were 100% backed by the US Treasury. All Funding Circle Holdings (LON:FCH) had to do was be in a position to find borrowers and take their 5% fee.
Imagine issuing $1b of PPP loans (out of c$300b issued in total) and taking a 5% cut - that's revenue of $50m right there in 1 country in just a few months.
(FYI the company generated £167m in FY19 in total)
It was one of those golden opportunities.
HOPES SHATTERED
Sadly, the company has clearly been massaging their announcements and it was soon obvious that they were performing nowhere near as well as they had been insinuating. Today's update has not changed this point of view.
As an example, they said this:
"Since being accredited, Funding Circle has become the 5th largest CBILS lender in the UK with a market share of c.20% of loans approved. We have approved c.£1.2bn and originated c.£815m of CBILS loans"
There's a footnote saying these figures are correct as of September 20th.
We know from the UK governments' website published that same day (link here) that £15.45b worth of loans have been approved.
By simple maths, that makes a market share BY VALUE of 5.3%.
So the 20% highlighted above is correct, but it's clear they have purposefully avoided the more important value, the value I would be more interested in knowing.
It's little things like this that made me sell my holding.
REPORTED LOSS
I sort of lost interest half through reading the results this morning, but from what I could see the loss came down to a revaluation of the Asset Backed Securities (ABS) on the balance sheet - business loans they funded and packaged up with the intention to sell to institutional investors in the US who aren't able to directly give money through Funding Circle's platform.
Which would have been fine, until a once in a century pandemic came along. I think I read that the company state they only have $110m exposure to the ABS, but from memory I thought they had $300m of cash invested in it - one to explore in more depth for anyone interested.
If it was $300m and they are able to receive that money back, I think the EV would actually be close to zero (or at least it was when I was looking into it earlier this year), which would significantly de-risk the shares.
CONCLUSION
There could be hidden value here, but I've been put off by the simultaneous bullish commentary and poor revenue generation to spend more time looking.
A