Small Cap Value Report (Thur 11 July 2024) - POLR, JET2, TRST, GLE, PPH, HAS

Good morning from Paul and Graham! We are wrapping up now (1pm). Have a good day!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
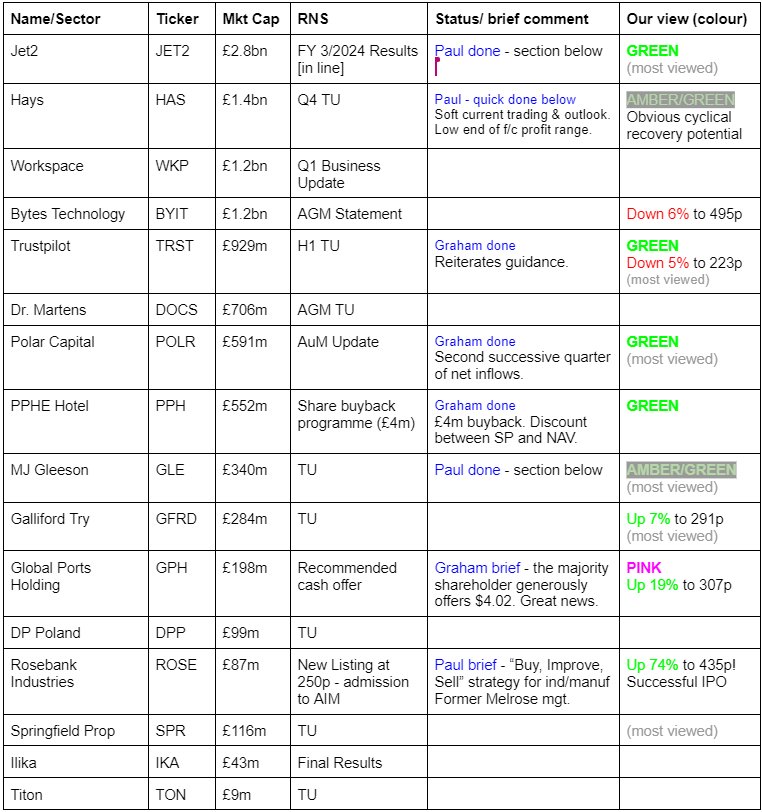
Summaries
Jet2 (LON:JET2) - up 2% to 1311p (£2.81bn) - FY 3/2024 Results - Paul - GREEN
In line FY 3/2024 results, and it also says YTD trading for FY 3/2025 is in line. Although it notes people are booking holidays later, so it declines to give detailed guidance. Smashing balance sheet with loads of cash now earning interest that accounts for 31% of profit. I cannot fathom why this quality company is so lowly rated, shares look a bargain to me.
MJ GLEESON (LON:GLE) - down 2% to 576p (£336m) - Trading Update - Paul - AMBER/GREEN
A small profit miss, caused by a big land sale slipping into the new financial year. FY 6/2024 has had its challenges, but GLE remains a superbly well-financed business, with good growth drivers in hand. I also like its niche of compact, cleverly designed affordable houses. My main worry is if the new Govt hikes property developers tax. GLE shares possibly a little toppy in the short-term, but still good value longer term.
Quickish Comments
Polar Capital Holdings (LON:POLR) - up 3% to 597p (£606m) - AuM Update - Graham - GREEN
I covered Polar’s full-year results recently. Relative to its AuM, it’s about twice as expensive as other fund manager shares. However, I think the reasons for this are convincing. Today, we are reminded of these reasons as the company posts a 7% increase in AuM in a single quarter.
The company benefited from net inflows of £0.6bn in Q1, and also from positive market movements of nearly £1.0bn. AuM increases from £21.9bn to £23.5bn.
The full-year results gave us an early snapshot into Q1, with the news that net inflows from 1st April to 14th June were £197m. Given that Q1 finished up with net flows of £0.6bn, the last few weeks of the quarter must have been very successful indeed.
CEO comment says there has been “continued demand for a broad range of our funds”, though most of the net inflows were driven by Emerging Markets and Asian Stars - this team has recently won an award for Emerging Markets Manager of the Year, and their US mutual fund has been upgraded by Morningstar.
Against this positivity, the CEO notes that “many investors are still grappling with multiple geopolitical and market risks, and therefore the potential for further redemptions remains”.
Graham’s view: I was already very positive on this stock, so I’m pleased to see that it is now putting together a series of net inflows. Long may this continue!
Analyst Paul Bryant at Equity Development has left his forecasts for Polar unchanged as it is still so early in the year, and there is that ongoing risk of net redemptions. However, the company has already, as of the end of Q1, hit his target AuM for the financial year-end (March 2025).
POLR is more expensive than some others in the sector but I believe it still offers value at this level, given its outperformance. I’m happy to be GREEN and happy for its continued participation in my best ideas list this year.
Trustpilot (LON:TRST) - down 5% to 224p (£935m) - 19% constant currency bookings growth - Graham - GREEN
This is an H1 trading update and it confirms that H1 revenue growth is expected in line with expectations at 17% (at constant currency exchange rates).
Bookings (the lead indicator of future revenues) are also strong, with 19% growth (at constant currencies). Momentum is particularly strong in North America (+23%).
Net cash is $76m, down by $16m but this is after a $20m share buyback. More share buybacks have been enabled by a restructuring of the balance sheet figures.
CEO comment: pleased with strong and strategic/operational progress. New product features released in April. Reiterates guidance of “mid-teens constant currency revenue growth and margin improvement for the full year”.
Graham’s view - the share price may be lower today but just look at how far we’ve come year-to-date:
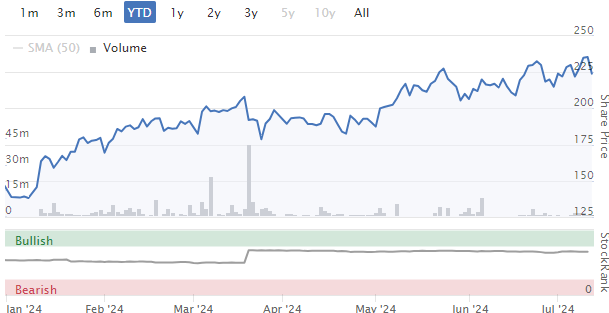
I continue to believe that this company has a genuine moat, in that no other review service has anything like the brand recognition or the “trust” that this one does, when it comes to reviewing larger businesses.
There are bearish arguments against the stock, and I tried to outline some of them in March. Today’s update doesn’t provide any insights into customer numbers, and there is a continued risk that existing customers may at some point soon be unable to prop up revenue growth any further (the number of customers only grew at 4% last year).
As for valuation, it’s still too soon to value this on earnings. Price to sales is 7x, about. It’s no longer the bargain it was before. But I’d sleep much easier owning this one than I would owning NVIDIA at a price to sales ratio of over 40x! I’ll keep my positive outlook on Trustpilot for now. If price to sales was over 10x for example, or if revenue growth slowed down, I would be forced to adjust my stance.
PPHE Hotel (LON:PPH) - down 1.5% to £13.10p (£552m) - Share buyback programme - Graham - GREEN
I appreciate that buybacks are a controversial topic, but this strikes me as a decent little announcement from PPHE Hotel Group. As I mentioned last year, the company’s official valuations of its assets come up with much bigger numbers than the share price suggests. Paul also reviewed the stock in Jan 2024, taking an AMBER/GREEN stance.
The most recent full-year results (to December 2023) suggest a disposal value of the company’s assets of £26.72 per share (I believe this is a pre-tax number), up from £25.17. Despite higher interest rates, the company’s strong trading and outlook resulted in higher valuations of its properties.
Some might argue that these valuations are fictitious and not relevant to the investment case here. After all, unless the properties are sold at these valuations, how do they benefit shareholders? That is fair enough, but one way that the company can respond to the situation is by buying back its own shares at their discounted level. Today, PPHE says (emphasis added):
As set out in the Group's full year results to 31 December 2023, the Group's EPRA NRV per Ordinary Share stands at £26.72 which is a substantial premium to the current share price. In light of the current share price discount relative to the EPRA NRV per Ordinary Share, the Board believes it would be in the best interests of shareholders to return a portion of capital to shareholders by means of the Share Buyback Programme.
Unfortunately, it is only a £4m buyback announced today, less than 1% of the company’s market cap. PPHE is carrying significant borrowings (gross debts £893m as of December 2023) and therefore it doesn’t have the flexibility to spend huge sums on buybacks. Even so, I think this is an interesting development. In March, the company already spent nearly £4m on another small buyback.
Perhaps the company is going to carry on in this manner, mopping up small parcels of stock as the funds become available to do it? A few million here and a few million there - it could add up to a substantial number by the end of the year!
Graham’s view - I’m happy to keep my positive stance here as the company continues to enjoy improving operational KPIs, and I appreciate its efforts to address the discount between its share price and its fair value NAV per share. The most recent trading update in April left expectations for the full year unchanged and showed continued improvements in both occupancy (from 66.9% to 71.3%) and in revenue per available room, although average room rates did drop back or as the company says “normalised”, as expected.
Hays (LON:HAS) - up 2% to 91.3p (£1,445m) - Q4 Trading Update - Paul - AMBER/GREEN
Net fees sharply down in all regions in Q4 (Apr-Jun), mirroring the profit warning from similar sized recruiter Pagegroup (LON:PAGE) on Tuesday this week. “Challenging” market conditions, “low confidence” and delayed decision-making by clients. Driving productivity and controlling costs. Near-term expecting conditions to remain challenging.
“I know we can deliver substantial profit growth once our end markets recover…”
“Despite a more difficult quarter, our cost actions mean we expect FY24 pre-exceptional operating profit of c.£105 million, around the bottom of the market consensus range*
*Bloomberg consensus operating profit range for FY24 is £106.0m to £113.0m”
Net cash £55m is strongly up from net debt £20m 3 months earlier. Of course recruiters generate cash when business slows down, because receivables shrink. Bad debts remain at historical lows.
Paul’s view - it’s an obvious cyclical recovery sector and share, so I see it as simply choosing which recruitment share to buy, or even buy a selection of the better ones that offer attractive value. I could see HAYS rising c.50% once recovery is underway, and its finances look OK (£363m NTAV at Dec 2023). Quite attractive, so I’ll go with AMBER/GREEN.
Paul's Section
Jet2 (LON:JET2)
Uup 2% to 1311p (£2.81bn) - FY 3/2024 Results - Paul - GREEN
One of my favourite value/GARP mid-caps. Checking our previous notes here -
23/11/2023 - GREEN - 1084p - very bullish review from me, flagging value, H1 results.
15/2/2024 - GREEN - 1377p - positive TU, forecasts raised.
24/4/2024 - GREEN - 1404p - TU - FY 3/2024 in line, profit 33% up on LY. Pricing in Apr & May more competitive. Too early to give FY 3/2025 guidance.
Today’s results - impressive figures here, and a 33% rise in profit looks in line with the last update -
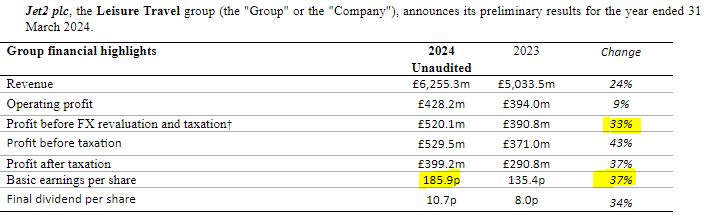
Canaccord’s note today (many thanks!) is using an adj diluted EPS of 170.4p, so I’ll use that. This is a PER of only 7.7x! That’s remarkably cheap in my view, assuming that level of earnings is sustainable, let alone capable of growth.
Forecast changes are very minor, so not significant (FY 3/2025 EPS raised 0.2%).
Current trading - looks OK -
“Year to date the business is trading in line with management's expectations.”
It repeats the line that it’s premature to give guidance for FY 3/2025, due to peak summer season not being complete. Many customers are booking holidays close to departure date. Pricing is “showing a modest increase”, but only partly offsetting cost increases. Despite tough macro, it says holidays are a high priority for customers.
Balance sheet - very strong. NAV is £1,409m, with only £27m intangible assets to come off, so NTAV £1,382m, or 49% of the market cap. No issues here, this is a very well funded business - good because sector risk is obvious - another pandemic, or planes grounded due to other factors. So I want to see a big cash buffer, which is the case here. Note also that finance income is massive, as JET2 sits on substantial customer cash, plus its own, earning interest on that now - finance income was £160m in FY 3/2024, that’s 31% of profit. So it’s quite an interest rate sensitive share.
Paul’s opinion - it’s a wonderful share! A terrific, differentiated business (low cost, flying from secondary cheap airports, offering full package holidays and flight-only options, great brand name & loved by customers, with a brilliant long-term track record - shares have multibagged).
Yet you can buy it for a PER of only 7.7x - how does that make sense? Only if you expect earnings to fall in future, but why would they? Forecasts show continuing revenue growth, but flat profits, so maybe it has reached peak margins, and might see margins squeezed in future?
So it would be worth doing deeper research to look at what the downside risks might be, and the competitive landscape, with Ryanair being the obvious threat. Based on these highly attractive numbers, I remain keen on this value share, and think it looks significantly under-priced. So it’s another GREEN from me.
MJ GLEESON (LON:GLE)
Down 2% to 576p (£336m) - Trading Update - Paul - AMBER/GREEN
MJ Gleeson plc, the leading low-cost housebuilder and land promoter, issues a trading update for the year ended 30 June 2024 (the "Period").
Results expected to be broadly in line with expectations following Gleeson Homes' robust performance and Gleeson Land planning delays
Gleeson Partnerships signs first agreement
Slightly below expectations is a bit disappointing. Singers (many thanks) says the shortfall is about £1m, with actual profit now c.£24m.
There had been previous forecast cuts too (unlike the largest housebuilders, which have seen this graph below flatlining). And of course the sector standout performers are the Irish housebuilders, Cairn Homes (LON:CRN) and Glenveagh Properties (LON:GLV) which are trading their socks off (esp Cairn), mentioned here recently.
Here’s Gleeson -
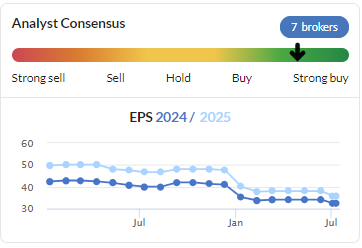
The actual profit being slightly below already reduced forecasts, is not a good look.
However, digging into the detail, the core Gleeson Homes division did alright, with completions up 3% to 1,772 new homes. Operating profit of c.£30m is ahead of expectations.
The problem is at Gleeson Land, where a “significant disposal” has been deferred into the current year FY 6/2025. This has caused profit to be way below expectations at £2m (Singers forecast was £7.5m). I can forgive that, it’s not a big deal being a timing issue, providing there are no undisclosed problems.
Cash - net cash at 6/2024 year end was £12.9m, which is good. I have no balance sheet worries, as GLE has a bulletproof balance sheet. Last reported NTAV was £287m, supporting 85% of the market cap. Or put another way, price to book value is 1.17x, which I think is still attractive, although we did have the opportunity to buy housebuilders at good discounts to NAV at the low points in the last two years, where they were absolute no-brainers (I put GLE on my top 20 share ideas for 2023 at c.344p, now up 67%). It’s funny isn’t it, at market lows, the bargains are staring you in the face, but many of us are too terrified to buy them!
Partnerships - this is very interesting. GLE is aiming to roughly double the size of the business, and do more partnership type deals (taking a leaf out of Vistry (LON:VTY) ‘s book). That’s a great, and pretty obvious idea, that could nicely drive profit growth. The first deal has been signed, with more in negotiation.
Outlook - sounds positive, with other housebuilders saying similar things about an improving outlook -
Gleeson Homes' sales rate over the last six months was steady but less vigorous than expected as a consequence of deferred expectations around interest and mortgage rate reductions. Looking ahead, the Board expects that, as rates start to fall, demand for new homes will strengthen through FY2025.
The Board remains confident of its medium-term objective as growth accelerates into FY2026 from the multiple outlet openings scheduled in FY2025.
With a good number of prospects, and in a more stable operating environment, Gleeson Land is confident of a strong performance in FY2025.
It makes positive comments (unsurprisingly!) about the new Govt’s stated aims for increased housebuilding.
Paul’s opinion - it’s been a wobbly year for GLE, with a profit warning in Jan 2024, reduced forecasts, and now the slippage of a land sale into the new year. However, I think the positive outlook outweighs these issues, and the valuation remains attractive to me, even after a strong recent run.
My main reservation is a political unknown, on how the new Govt will approach taxation for the housebuilders. They must be an obvious target for windfall taxes, or maybe even a new property developers tax, or increase in the 4% existing RDPT surcharge. My guess is that this 4% rate could see a significant increase (10% or more maybe? Possibly in stages?), as the new Govt is boxed on election pledges, yet desperate for more money to spend on (necessary) improvements in public services. And let’s be honest here, the huge profits made in the housebuilding sector, and the big shareholder returns, are crazy. Especially given that the quality of many new houses is lamentable. Huge profits for shoddy houses, is an obvious target for higher taxes. I’m turning socialist here!
So personally I won’t be chasing up the GLE share price for now, and expect it might slip back a bit as euphoria over the drive to build more houses could easily be derailed by higher taxes, but that’s unknown at this stage. Personally I’d want a share price of 500p or less to motivate me to get involved here. We’re not traders though, so on fundamentals I’m happy to remain at AMBER/GREEN, even though I think the price is maybe a little ahead of itself in the short-term.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

122 comments
Honourable mention to Archie Roberts. New member, first post, somehow posts a GIF and gets red flagged.
Royal Flush. Well played Sir.
Nice write up guys - we all need a break from the routine now and again, and I think it shows.
Didn't MJ GLEESON (LON:GLE) move out of housebuilding to its core infrastructure projects. Fixing 'broken Britain' is clearly a sector to study - but still low margin and high risk with fixed price contracts, and ESG requirements a 'core' checklist for tenders, esp with the new mob.
No, Harry Hindsight, MJGleeson (GLE) moved in the opposite direction. Years ago they didn't have any involvement in housing but were mainly a heavy civils contractor, eg. on one large dam building project we beat them by a whisker when at the time they had a substantial muckshift fleet ready to start work.
The short haul airlines benefit from externalising their impact on the climate. Is there any significant risk that this could soon attract tax?
The government has been taxing the short haul lines for a very long time:
Rates for Air Passenger Duty - GOV.UK (www.gov.uk)
Meanwhile, the UK government is fine to subsidise rail travel, causing unnecessary journeys and pollution. On the busses, my local bus route, I am the only person who pays when I board, the driver always commenting that he/she has to do some work when I get on, everybody else has a free bus pass. I wonder quite how much Gordon Brown free bus pass scheme for senior citizens has caused in extra unnecessary pollution?
Decided to have a look at market performance here and elsewhere since the start of this Century. Interesting!
UK Underperformance is notable especially so since Gordon Brown’s infamous Pension Tax raid which has resulted in pension Funds going from big investors in the UK to very small now.
Since the end of 1999:-
FTSE 100 . Only up 20% from 6900 to 8200.
FTSE 250 much better …and tripled from 6200 to 21000.
FTSE AIM ALL SHARE. Disaster area! DOWN 60% since the turn of the century from 2000 to just 776 now. AIM 2000 tech bubble peak was a brief soar to 2900. It’s down over 70% from that peak.
Since AIM is popular with small investors, those who have invested mostly in AIM shares need only look at these figures to see how hard it’s been to do so successfully.
OTHER INDEXES FOR COMPARISON.
CAC 6000 to 7600. The only major one almost as bad as the FTSE100.
DAX 7300 to 18400 UP around 2.5 times.
SENSEX 4000 to 8000 UP 20 fold……and now on 22 PE.
VIETNAM 140 to 1300 UP 9 fold to 1300.
NIKKEI 14000 to 42000 and up 3 fold.
US INDEXES.
DOW 11000 to 39000 UP 3.5 fold.
NASDAQ 3000 to 18600 UP 6 fold. And up 14 times from the post 2000 tech crash bubble low of 1300. The tech bubble peak was 5000.
S&P 1400 to 5630 UP 4 fold.
Conclusions.
1. Best not to have all our eggs in the UK and especially not UK AIM shares…….but after such dire performance for so long is the future much brighter now for small Companies?
2. Best to diversify and have a wide range of Countries and Sectors in our portfolios to maximise gains from Regions doing much better than the local market? An obvious way is via Investment Trusts with so many quality Trusts on unusually big discounts to NAV.
3. Having nothing or very little invested in the US (guilty) has been a big mistake. Will it continue to be a mistake?
Sorry Ken,
But all comparisons are completely wrong. The UK has indeed underperformed but not that badly. Distinguish firstly between indices that count for dividends and other adjustments such fundraising and splits.
All the best
It needs to be the Total Return series (e.g. FTSE 100 TR is currently c. 8900).
Which Stockopedia doesn't make available for commercial reasons. Which then in turn makes loading up your dividends into the the Stocko Folios a rather futile exercise.
How I long to spend 10mins with many of the subscribers on this forum (and indeed all of the Stocko employees) and run through a series of TRA screens ("Total Return Analysis" which incorprates all cashflows & corporate actions, then compounds up properly) on a Bloomberg terminal (I no longer have access).
It would change how many view the world. It would also highlight that there can be many different answers, depending on how you set the reinvestment criteria.
Over longer timeframes dividends will be the majority of many investors' returns. Over multiple decades the number for me is something like 57.5% of my returns....(skewed by holding dividend paying equities instead of bonds when rates were close to zero).
Over 25 years my returns are 25% from dividends , 75% capital. Not the majority in dividends. Though I'll take you up on the offer of the hour on a terminal.
Yiannos.
I just used the standard indexes that I look at frequently and have done for multiple years. I.e just simple straightforward comparisons between one index and another. So I (and possibly others) am keen to know what I have got “completely wrong.”.
This post is not to provoke, but because I’m bemused and would like to know as I’m always keen to learn from mistakes especially when new knowledge can help our investment performance.
Ken
A simple answer would be that you are ignoring dividends.
The "standard indices" you've used are capital return indices and completely disregard the compounding of dividends, special dividends and certain other corporate actions.
They are OK for short periods and "is the stock market up this week?", but over multi-year periods they can diverge enormously from total return indices as the compounding kicks in.
The UK has a much higher income return than most other regions, so by using "standard" indices you inevitably exaggerate the UK underperfomance considerably.
Chart below makes it very clear - FTSE TR vs "standard" FTSE.
MC
Thanks MC. I’ve assumed that all the indexes exclude dividends. . Is that right?
As a great fan of big dividend paying investments and with a portfolio full of them (as there are so many quality shares and Investment Trusts available that look absurdly cheap)it’s ironic that it looks as though I’m ignoring their attractions!
I’m aware of the big difference in FTSE100 performance if dividends are included. The other indexes would also get an uplift with dividends included, but not as much as the big yielding FTSE100 which includes a lot of International shares.
This article from 2020 explains more with FTSE100 up 122% in the 20 years from 2000 if including dividends, but flat if not.
https://www.schroders.com/en-g...
It’s still the case though that the AIM index in particular has woefully underperformed.
Most of the indices you list exclude dividends.
And therefore should not really be used for performance comparison over any period longer than a month or two, let alone back to 1999.
In the UK companies tend to pay dividends, whereas in the US there is often a preference for share buybacks.
Share buybacks will manifest as capital appreciation and be captured in a capital return "standard" index, whereas dividends won't.
So even a comparison between two "capital" return indices in different regions is fraught with difficulties.
The "standard" indices tend to be capital return because it is really, really difficult to publish a live total return index. You can't get all the info you need for calculation purposes quickly enough. Some corporate actions can't be calculated without reference to end of day pricing. This is one reason why running a passive "index tracker" fund requires more skill than people generally appreciate & still requires decisions to be made.
Hi Ken,
Others have already answered and Monty Carlo has covered this in detail. Some indices include dividends but not all , others do not make adjustments on fundraising issues , splits etc.
I had this discussion before with someone here as he/she was claiming that the DAX has underperformed the FTSE and I have provided accurate numbers that the DAX had performed better over the years (about 20%) if you add all dividends involved. DAX is one of these TR indices.
The numbers you provided have not been correct but I do agree with you that the UK market has underperformed for over 25 years (not to the extent you provided) and I believe the same will happen in the future.
I totally agree with you that diversification in different markets makes sense and it’s something I have been doing for many years now. However I do not hold many stocks ; I tend to always hold 20 stocks maximum.
All the best
Thanks yiannos. That’s a really helpful reply. I didn’t know until today and the posts from you and Monty Carlo that some of the indices adjusted for fund raisings and splits etc and not others.
What I DO know is that my biggest investment mistake has been largely to ignore the US (except from time to time Technology Investment Trusts) throughout this Century and even before, because wrongly believing the many commentators claiming the overvalued US stock market was about to crash!
My opinion is that we are at/near the highs for the US market (for this cycle).
During the last 2 months the behaviour of the iShares Russell 2000 ETF (PCQ:IWM) the SP500 and the Yield Curve DO NOT MAKE any sense at all. It is obvious that the leverage used will one of these days catch up with all these risk takers.
I only hold 7 stocks now. Made Tech (LON:MTEC) Cavendish Financial (LON:CAV) Gulf Keystone Petroleum (LON:GKP) and a small position on SysGroup (LON:SYS) that will probably add more after these month results.
US holdings are Oscar Health (NYQ:OSCR) DraftKings (NSQ:DKNG) and Golar LNG (NSQ:GLNG)
Friendly advice Ken-Stick to what you know and understand better-the US markets and their accounting complex reporting will take years to digest!
All the best
yiannos.
Thanks for the friendly advice. I nearly included in my post that having missed out on those huge US share price gains for so many years, no way was I going to buy now in case I timed it when at last their markets crashed.
I also hold Cavendish Financial (LON:CAV) which seems very cheap and Gulf Keystone Petroleum (LON:GKP) where, as you’ve posted, the share price should go up a lot when, and surely it is when, at last the pipeline is reopened.
Another with that sort of upside is Ferrexpo (LON:FXPO) which I held until the Russian invasion. I’ve no wish to try and profit from their misery while the war lasts (a lot of their employees have been killed on the front line) but like Gulf Keystone Petroleum (LON:GKP) while the pipeline is shut, Ferrexpo is coping remarkably well and upside looks big IF somehow both sides can come to a compromise to end the slaughter and when Ferrexpo (LON:FXPO) can get back to full production again.
I hold Kier (LON:KIE) as well sorry missed that.
Ferrexpo (LON:FXPO) I must have studied it so many times but never convinced me to press the button , but I do understand the investment case when/if things get back to normal.
All the best
Ferrexpo have the Ukrainian billionaire major holder issue hanging over them too., which caused another discount.And i don't believe anyone can quanitify that in the market and it is defintely too complicated for me.However, i believe that it will be sorted out without wiping out international investors,But maybe i'm missing some company complicity somewhere, and putting all the blame on the billionaire, or majorly misjudging the situation.Upside could potentially be huge over years.Worst side downside naturally a zero.
I thought you also had Afentra (LON:AET) ?
Sold Afentra (LON:AET)
Still good value. Good experienced management that will deliver long term.
Not comfortable to hold many stocks before and after the US elections with the two candidates involved!
All the best
Well I can certainly understand that. Dement v Despot.
A trader and very disciplined - hats off.
I'm still holding Boohoo (LON:BOO) Heiq (LON:HEIQ) THG (LON:THG) etc from my start out days and dazzled by IPO's post apocalypse covid. One day "my prince/princess will make good", but by then inflation probably eats my lunch.
Harry
I am definitely not a trader!
All the best
For the DAX, have you used the performance index ? If I remember correctly the DAX is offered in two versions, one is rather more flattering as it includes the dividends. I suppose it might be compared to iShares Core FTSE 100 UCITS ETF GBP (Acc) (LON:CUKX). I am a novice investor so your final question a key one for me - a simple Nasdaq or S&P index fund has had very good yields over the last few years. Probably necessitating a separate discussion post - but I am very curious about the influence of passive index funds on US market strength.
edit: yiannos got there before me ! still, I didnt know anything about the splits
On Jet2 (LON:JET2) , for those who do not know, the apparent value on offer and balance sheet strength may not be quite as it seems, due to very large new aircraft orders that the company has committed to.
These are disclosed in the ‘Aircraft Order’ RNS announcements dated 18 Oct 2022, 5 Oct 2021 & 31 Aug 2021 (see here).
A hat tip here to another subscriber who mentioned this briefly several months ago.
Jet2’s Market cap is currently £2.75bn, with net cash of £1.7bn according to today’s interim report.
They currently have c.127 aircraft in their fleet, according to today’s going concern note.
But the October 2022 RNS said the company has committed to purchasing a minimum of 98 new aircraft from Airbus, with the option to take this up to 146 aircraft. Deliveries have now started and they extend to 2031.
By my calculations, using info from the three RNS announcements, the indicative list price is around $120m-$130m per plane. The 98 committed purchases are worth up to $12bn. And if they take up the option for 146 planes it would be $18bn worth of planes.
The true cost is hard to guess, as the company notes that “significant discounts” were obtained from list prices. Several billions less, no doubt. There are articles out there that suggests Airbus offers discounts of 50% to airlines for bulk buying, which I presume will be around right in practice. So let's say $6bn - $9bn total cost.
I used to hold Jet2 a few months ago, but based on this massive ramp up in the fleet and the inevitable move to a significant net debt position, it is basically too difficult for me to forecast the firm’s future prospects, so I sold out at around current levels, for roughly the same price I bought at. In terms of financing the deals, Jet2’s order announcements simply say “through a combination of internal resources and debt.”
One question I have for the accountants out there: at what point should the company be required to disclose these massive future liabilities on its balance sheet?
Hi Chris Brown,
Very interesting detail on Jet2 (LON:JET2) thanks!
I take your point that risk increases if they move from net cash to net debt. But they wouldn't be buying all those new planes unless they were going to be put to productive use. Plus new planes are more fuel efficient, so presumably more profitable to operate?
So to me this seems more glass half full - signalling big expansion, which should increase profits. Although maybe glass half empty if you're very conservative with your balance sheet preferences.
Regards, Paul.
Quick sense check
1 - Are all the aircraft being purchased an increase to the fleet number, or are they buying new and selling some second hand?
2 - I have just flow on holiday with TUI who used a "white unbranded" plane chartered in for the summer season from an Eastern European charter airline - I know, because they pointed it out in the small print of my booking = OFF Balance sheet
Hi ezlifeme. Yes of course: Jet2 say it is to accommodate both an expansion in the fleet and to replace older planes, which presumably have resale value. I'm not sure if they have disclosed the detail exactly. My point is simply that the balance sheet will transform quite radically in future, the net cash will convert to a fair bit of net debt, like many other airlines have, and it's all just a bit too complex for a PI like me to untangle. All the best to holders - my main concern was to make sure people were aware of this as a factor. There has to be some execution risk, if say expansion plans (and the gearing) were to coincide with a downturn in demand.
Chris - you miss the point that they may spend $6-$9bn over the next 10 years, but they are also generating cash every year - at $500m profit, that all but covers the low end of the estimate. Further, they are generating that cash from current assets already aquired- if they have $1.7bn of net cash (presumably net of any current debt for their current planes), then the cash profits are higher than $500m each year to pay for the planes as they arrive. So, you are way off simply suggesting they will go from net cash to significant net debt.
Good point Edward, thanks. I was making an assumption based on the large sums involved and management stating that funding would involve debt. We'll see how it pans out!
I haven’t looked in detail, but to me the biggest surprise is they currently are net cash with significant fixed assets (i.e planes) needed to generate the current profits. It would not be unreasonable to assume such businesses have borrowings to fund those assets from which they can generate profits (and thus pay back the debts, hopefully with some left over for shareholder returns!) the fact they don’t at present suggest they are very well capitalised/have strong net assets.
As others have said, the spending on the new planes will come from cash flow and ultimately help generate higher profit in future years, so don't really see this as an issue. The company has obviously decided to prioritise capex over dividends/buybacks, and given their high returns on capital I'm prepared to back their judgement. Also, in terms of running an efficient balance sheet I would say it's probably good for them to hold some debt, as long as not excessive. I haven't looked in detail at how much debt they may need to take on, but again I'm happy to back management here who always seem fairly prudent.
Reminded me to look at Amedeo Air Four Plus (LON:AA4)
Monthly chart - oh well "another one missed the ... airplane".
Hi Chris,
In my notes from this morning I wrote:
Expected gross capital expenditure of nearly £5.0 billion over the next six years.
But as Paul says, this is where growth will come from, and given the prices of new aircraft ready to go vs list price, they could sell the old planes (and possibly new ones) at a decent profit - which is one of the reasons I'm holding Avation (LON:AVAP) too as I don't think the market is aware of the potential profits that could be realised.
Polar Capital Holdings (LON:POLR) ( I hold). A lot of the negativity of sentiment towards the fund management sector has been concerns about the move to passive funds/ETF by investors. Arguably if there is an increased move of funds to trackers this will provide more opportunities for active management based on thorough research. Imagine if 50% of investment funds were in passive/index funds. The opportunities for an active manager would be to seek out the undervalued would be large. I also hold Impax Asset Management (LON:IPX) and Ninety One (LON:N91) .
Portfolio management - I am not sure how others track their investment portfolio, I know many just do this through their broker website. For those not aware I wanted to share that if you have your portfolio updated in Google Finance it will give a really nice graphic that shows what proportion of your portfolio is allocated to each stock, with the colour coding and percentages showing the daily moves. I find this great way to track my portfolio at a glance throughout the day, as a opposed to the more detailed holding information found on my brokers site or on Yahoo.
Anytime I see other people's portfolio's I get real pangs of portfolio envy, "I wish I had that one...and that one.... and that one ;)'
Well done BenHazz, that's very tidy and a good tip re google finance, I never used to use it but will do now, thank you.
I enjoy seeing other peoples portfolio's, it is a real insight. I am exactly the same when it comes to share envy, especially when I see people holding stocks that I used to hold but sold waaaaay too early - NVIDIA (NSQ:NVDA),CMC Markets (LON:CMCX) and Marks and Spencer (LON:MKS) are my big 3 for that in the past couple of years. Oh and not to mention those watchlist shares that I've just watched go up and up without opening a position like Warpaint London (LON:W7L).
When you first input all of the stocks it will show them in a traditional listed format, so you need to click the "visualise" button shown below:
Just don't invest too much time into anything Google that is free (or even not free in some cases). They have a really horrible habit of discontinuing things after you've invested hours into it or just bought their gadgets (I have many bitter experiences...and lots of their shares as I appreciate their ruthlessness).
Check out:
https://killedbygoogle.com/
https://gcemetery.co/
I second that Monty Carlo, I used to have my portfolio listed on Google and then they stopped it, surprised they have brought one back. Used to download Paul's weekend podcast on Google, now that's gone. Don't trust them at all.
For those with an interest in US stocks, news just out Quantumscape (NYQ:QS) has signed a deal with Volkswagen to ramp up solid-state battery production in QuantumScape.
SP moving up sharply, currently up around 20%
Regarding Jet2 (LON:JET2) and the threat of Ryanair mentioned by Paul, O' Leary was spouting off about Jet2s weak business model in 2008, Meeson fired back that it was robust, and to me has played cracking shots all the way down the course to his retirement. Having worked in low cost and regional aviation, I can say both O' Leary and Meeson are my most admired leaders, both run superb airlines and have for aviation, very good business models, and both have a place in the market.
Friends who live in the North complain about Jet2 fares always being significantly higher than easyJet and Ryanair, but to me as a shareholder I like that they can charge higher fares, which I believe is due to brand loyalty. Most airlines are selling a very similar product these days, but Jet2 has a sensible schedule and pricing policy, and has a premium for its products.
My only concern, which I have held for a few years, is where Jet2 (LON:JET2) future expansion is going to come from? The company has grown from its Northern base to throughout UK (even Bournemouth), but the UK market is limited. I would like to see the company expanding to EU, this will be difficult and costly in short term, and far from assured the model will succeed (I remember Greggs setting up and failing in Belgium, yet a similar home brand value bakery 'Panos' has thrived), and for me that is why I believe the Jet2 (LON:JET2) share rating is low.
Corero Network Security (LON:CNS) share price currently having a good run. (By far my biggest holding)
If anyone wondering what they actually do this new presentation might be of interest.
I am moving a modest six figure SIPP into drawdown at Hargreaves Lansdowne to crystallise the 25% tax free lump sum ("the 25%").
Usually they quote 5- 10 working days (heaven knows why it takes so long). Today was working day #5 and I chased. The reply: 'It can typically take 10 working days to process your application. However, this is not guaranteed and we have had a large increase in volume of applications recently.'
Perhaps I am not the only one seeking to crystallise the 25% in advance of the Labour budget!
I had to wait 2 months last year for HL to put part of the SIPP into drawdown. Expect a longer delay!
Currently transferring a very modest 3 figure sum pension from a major UK pubic provider to ii to simplify my affairs... and we're now on week ten since I made the initial request.... The major provider continues to 'review' my request.
Sounds a dream. I started a transfer of ISA investments from HSBC to Fidelity on 29th March. Guess what. Still in progress as my Wealth Manager 'reaches out' to the transfer team to jolly them along. Heading for the 4 months anniversary. However, I do get thanked a lot for my patience and understanding......
Roy Edwards, there was a time when I put most of my clients on the Fidelity Platform, and then the service fell off a cliff and I regretted ever using them! Good luck with your transfer (and afterwards).
Michael C, I recently retired from a career in Financial Services. Since 1982 I don't remember a time when someone hasn't been worrying about the removal of tax free cash from pensions. People have to be encouraged to save in pensions - and without the carrot of a tax free lump sum, for the majority of people there wouldn't be much point in doing so.
now changing the way tax relief applies to contributions, or the Inheritance Tax on pension pots, these seem like more obvious targets to me.
Perhaps I am not the only one seeking to crystallise the 25% in advance of the Labour budget!
labour confirmed they are not gone to touch the 25% unless i am very much mistaken - if they want to be back out of office quickly that would be the easiest way to get voted out. This being the case i see close to nil chance that anyone will be affected - i am happy to look at any credible sugestion that i am wrong here though if you have anyone credible saying otherwise.
One question with 25% crystalisation - can that be a very bad idea if you dopnt need the funds? specifically does that mean that money cant now grow tax free as would have been the case previously ? not sure how it works if its neutral/good or bad going down that route if you dont need the money?
Agree - best option unless you actually need the cash is the hybrid where you can make one off withdrawals which include 25% of the cash tax free over any number of years rather than taking it all in one go and then having it sitting in an account paying tax.....Its worth taking time out to read up the rules and regs for those not familiar with them.
Thanks bohenie
how does that work if i took my full 25% - if then i add say another 10k back in - can i get 25% of that later add ins or have i lost any ability to get 25% once its been fullyucrystalised - even if i inject new funds.?
As you say i think i waqs planning if i get to go early and have unused allowances to draw that with 25% on top at teh time - that would hopefully presumbaly be best middle ground for me if i have no need for the lumper - i guess for many needs must.
Note nore sure practicably how much you would expect to lose out on anwway - if you have the cash that can also be invested for growth possibly even tax free if you have isa allowances.
It's 25% of whatever you move into drawdown, otherwise known as a crystallization event.
If you moved 100k of a 500k pot into drawdown, then you can take 25k of the 100k tax free, the remaining 75k is potentially taxable when you withdraw it (assuming you take more than the tax free allowance each year). The remaining 400k can be left to grow, before you move another chunk into drawdown and take another 25% of that tax free.
If you move £16,700 or thereabouts into drawdown each year you can avoid paying income tax - the 25% tax free amount takes the remaining amount down to the (current) personal allowance.
But of course if you're over 66 you will just about be hitting income tax levels with your state pension?
I took my entire 25% tax free, which gave me money to live on for the next few years. In addition, I moved £20,000 of the tax free money into my ISA each year until my spare cash was used up, giving me additional investment funds on which I will never pay tax.
I also did this and as I'm married we have been able to put £40000/yr into ISA's. I retired at 55 and have no earned income so each year since I have also been able to withdraw up to my personal tax-free allowance from the remaining 75% of my pension without paying any tax. Once I get state pension this option will end, but during the intervening 12 years and based on the current personal allowance I will be able to withdraw a further £150000 tax free. In addition as my earned income is still just below £12570 I can use my dividend allowance (£1000),personal savings allowance (£1000) and starting rate for savings (£5000) to receive up to a further £7000 of dividends and saving interest tax free which covers the income from the 25% lump withdrawal that has not been transferred to ISA's so far.
Interactive Investor have a few articles on this, and FT weekend finance also covered it.
Sorry, no links
I posted this in the discussion forum earlier . . . . . .
"Taking a tax-free lump sum when "crystallising" a SIPP and transferring it into draw-down: Hargreaves Lansdown and some other popular SIPP providers insist that the 25% tax-free lump sum is taken immediately upon moving a SIPP into draw down or the right to receive it is first permanently waived. This is disadvantageous as the tax-free lump sum then leaves a tax-free wrapper and becomes taxable, while if not taken it might grow for sometime. This is not a legal/regulatory requirements and seems a policy adopted by some SIPP providers. Is anyone aware of a SIPP provider which allows more flexibility re the timing of the taking of the tax-free lump sum?"
I agree there is no point in taking the 25% immediately upfront but many SIPP providers don't allow a more flexible approach other than take the 25% immediately or waive the right to ever receiver it.
Is anyone aware of a SIPP provider which provides more flexbility re timing?
Much thanks
Try BestInvest
Jayman, you miss the point slightly. 25% tax free cash must be taken when you crystallise, but there is no requirement to crystallise all your pension pot at one point. e.g. if you need £x Tax free cash today , crystallise £4x. Whether you take the rest of that crystallised amount might depend on your requirements and or tax allowance.
The other thing to consider is that anything taken as Tax free cash and not actually spent, is potentially thereafter to be liable to income tax on divs/interest and CGT on gains, if not invested within an ISA. The money will also be part of your estate on death for IHT whereas money in a pension should be outside the estate for IHT,
As a general point, once passed age 75 it is more likely to be best to ensure that Tax free cash is taken before you actually die! There's an awful lot of permutations so most important thing is proceed with caution and maybe pay an expert for advice.
RMillaree, your comment regarding reinvesting tax free cash in pension to then get another bite at the cherry - in theory yes, but beware of rules and limits that restrict recycling Tax free cash. They were brought in after Hargreaves Lansdowne made a big noise about the tax advantages of such recycling, which was annoying to those of us who were quietly recommending people do it!
I think we might be conflating two related but separate potential concerns - whether the new government might:
(i) re-introduce the LTA, with a material charge on large pension pots exceeding it (initially in response to the LTA abolition Rachel Reeves said Labour would restore it but more recently she confirmed to the Financial Times that she had no immediate plan to do so, possibly acknowledging that a detailed bill and then SIs would be needed to being it back and that would take at least a year; and/or
(ii) reduce the 25% tax free lump sum which in any case is now capped at £268,275, the real value of which and is now being gradually eroded by inflation.
Arguably "crystallising" a pension and putting it into draw down will provide some immediate protection against (i) above, but under the old LTA system pots would be re-tested against the LTA at 75 to discourage people allowing them to accumulate and not paying tax on their draw down payments. So you might still be exposed to a charge on that second testing, if restored.
Taking the 25% lump sum now would secure it but at the cost of the funds leaving a tax-free wrapper where it would otherwise compound and grow. Onother comment correctly stated that unless you need to funds for a specific purpose such as repaying a mortgage it would be better to defer taking it.
My issue (see my post here >>>>> https://www.stockopedia.com/co...) is that many SIPP providers insist that you take the 25% tax-free lump sum immediately upon crystallisation, even though it is legally possible for it to be taken later. There maybe SIPP providers which allow a more flexible approach but Hargreaves Landsdown and AJ Bell aren't among them. Can anyone shine a light on this?
It works for us on the numbers in this SIPP. The 25% is just under the ISA limit so I will put £20k in an ISA and my wife will do the same with the balance.
I have read every page of the Labour manifesto and quite a lot of the comments made by Reeves and Starmer- to the best of my knowledge they have not given any assurance that the 25% is safe.
I have read every page of the Labour manifesto and quite a lot of the comments made by Reeves and Starmer- to the best of my knowledge they have not given any assurance that the 25% is safe.
They have, albeit perhaps by accident, after Starmer seemed to suggest in an interview that it would be abolished.
Labour quickly tried to defuse the issue. “The ability to withdraw 25 per cent of your pension as a tax-free lump sum is a permanent feature of the tax system and Labour are not planning to change this,” a spokesman said.
Asked whether Labour was making a solid promise not to change the current system — as opposed to simply having “no plans” — a spokesman said: “It’s a firm commitment.”
https://www.ft.com/content/a3a...
timarr
That was the bit i had seen too - to be honest its nearly unbelievable that Starmer could have got that so wrong (preume its given they wont target the 25% tax free pot) he really must have been poorly prepped or had a memory failure or lost the plot. It shouldnt be lost on everyone that he has ptentially massively benefited from having legislation introduced (specifically for him) so that his specific pension had its own tax free perks - i think he didnt say he didnt want to benefit from that situation (well he would do wouldnt he!)
Hi Michael C. I would be interested to hear more of your experience moving to drawdown with HL once completed. I am considering this too. How is the 25% actually worked out? do you need to sell individual holdings in advance of initiating the process to have 25% of your portfolio in cash or does this happen after making the request?
See the comment by af20001 for how the 25% is worked out.
In my case I was able to make my application online. As their website explains, that isn't always the case. I had to say how much I wanted to place into drawdown, what to keep in the SIPP, and how much tax free cash to withdraw. And in my case I had the 25% in cash because I had sold some holdings. I expected I would be able to save a copy of the electronic form I filled in but never saw that opportunity and I can't find a copy on the Hl website, mind you I am probably the world's worst at navigating websites, I think I may have a form of dyslexia when it comes to website navigation. So I suggest that it might be worth taking screenshots at every stage of the process so you know what you have actually requested!
Sadly I can't answer the crucial question about what happens if there isn't enough money to pay the 25%. Suppose you have a £100k SIPP, apply to put the whole lot into drawdown, and take £25k tax free cash. Then, while the drawdown application is being processed, the value of your holdings falls so the SIPP isn't worth £100k at the time the drawdown actually takes effect. HL don't offer any guidance about that so far as I can see.
Hi
Seems like quite good news ...... a posting on Twitter (link to City AM article at the bottom)
https://www.cityam.com/uk-swee...
Two charts from the article referenced
Regards
Howard
Ecora Resources (LON:ECOR) - the natural resources royalty company now focused upon ‘transition’ materials, mainly copper, nickel, cobalt, vanadium and uranium warns Q2 Kestrel royalty (remaining coking coal in run off) materially above expectations.
I saw ‘warns’ revenue materially above expectations – as the company remains deeply unpopular with investors. I don’t expect today’s news or the purchase of an early stage royalty with Rainbow Rare Earths last week to change investor sentiment.
Probably because the UK market still strongly associates it with its historic high yielding coal royalties which are now ending. Currently rated at around 9x forecast revenues with a dividend yield of around 5% - which seems fair for a set of royalties currently in production?
But that largely misses the asset value of the company and in particular any value to be ascribed to future royalties not yet in production?
The assets of the company are now entirely focused upon Copper, Nickel, Cobalt with some Uranium, Vanadium and other minerals mainly from mines increasing production, in construction or in early stage development (when a royalty deal is mutually beneficial to both parties).
On its assets Ecora Resources (LON:ECOR) is currently rated around 0.44x Book Value.
Early stage assets are classified as intangible assets (on a licence or development/construction plan) which values the company at 1x Tangible Book Value – which slightly misses the point by valuing all prospective assets at zero? But admittely they are hard to value accurately without foreknowledge of demand and supply in the future? But zero seems to be harsh, given that once a mine starts production there tends to be a re-rating to 100%?
As a reference - the only other London listed natural resources royalty company Trident Royalties (LON:TRR) recently accepted a cash takeover bid of 49p at around 1.7x Book Value – with zero Tangible Book Value - as all of its portfolio are in development or early stage.
Which makes Ecora Resources (LON:ECOR) a potentially highly rewarding investment with downside limited by current production and dividend. With upside currently around 3x based upon the Trident Royalties (LON:TRR) offer?
If there is no bid (I’m not hoping for one) then I see greater upside as royalties move closer to production – particularly West Musgrave(Oz), Nifty(Oz), Santa Domingo(Chile) and Piaui (Nickel – Brazil) to name a few – assuming that copper demand continues to rise while supply (lack of new mines currently as old mines are exhausted) remains constrained?
I bought too early on this one. I’d be buying - except I’m fully invested right now in my UK listed small cap portfolio of 13 companies - and looking for any spare cash down the back of the sofa – so bear in mind that [1] I’m not a mining expert (but this is about royalties not mine economics [2] I’m biased and [3] so far I’ve been very wrong about when this will happen, as copper prices have risen the share price has fallen substantially. So far.
One to keep an eye on?
Cheers
Mark
Nice summary of Ecora Resources (LON:ECOR) , thanks Mark. It is one I held back when it was Anglo Pacific a few year ago. Your post has prompted me to take a second look. Cheers.
'Ecora Resources (LON:ECOR)
thank Ben,
But Whoops!
My timing is awful as usual!
Turns out that this morning - BHP announced the suspension of their nickel operations in Oz -which includes the West Musgrave mine construction - shortly after I wrote my note.
I predict that the delay in mine construction will weigh on the share price more than the material increase in current revenue.
Long term - frustrating though it is I suspect that it makes little difference to Ecora Resources (LON:ECOR) long term prospects. Short term I can see the share price going lower,
cheers
Mark
Bloomsbury Publishing (LON:BMY)
The shares are on a roll. I top sliced pre the acquisition of Roman and Littlefield, but managed to add back a few at under 600p on news of the acquisition. As previously posted I think the company will beat current market forecasts due to the Roman and Littlefield purchase and the continuing success of Sarah J Mass, whose books continue to sell very well according to the large Waterstones that I regularly visit.
I also think that the market is behind the curve with regard to Property Franchise (LON:TPFG) that I also think will come in ahead of expectations, notwithstanding the likelihood that house purchase momentum may have paused pending the outcome of the election. The caveat being that Andrew Bailey does the sensible thing and starts to reduce interest rates in the near future.
My reasoning is based on the extensive financial advisor network that the company acquired when it merged with Belvoir, the recent acquisition of The Guild of Property Professionals and Fine & Country and the recent AGM statement, extract below.
For what it is worth I also think that Louise George, former CFO of Belvoir and now company secretary will be appointed as the CFO of Property Franchise (LON:TPFG) on the departure of David Raggett, the current CEO who has stated his intention to step down at the end of FY 2025
"The first five months of FY24 have been transformational for the Group, with the completion of two significant transactions: the merger with Belvoir Group plc completed in March and the acquisition of The Guild of Property Professionals and Fine & Country completed last week.
As reported at the results in April, FY24 started with good momentum and that has continued to build. Our longstanding businesses have traded in line with our growth objectives. Notably, their lettings' revenues have continued to grow at similar rates to last year and the sales-agreed pipeline at 30 April 2024 was 20% up on the same period in FY23, signalling a much stronger sales market so far in FY24."
Just my views and I am biased as I hold both companies.
Hi Jonno
Property Franchise (LON:TPFG)
It's anecdotal, but talking to a couple of mortgage advisors a few days ago they were saying they have been unable to keep up with demand over the last 6 weeks, 'market has gone crazy'.
TPFG & LSL Services are perfectly exposed to a rebounding housing market, I think you will continue to do very well with your position here, I am definitely a buyer on any retracement...
Cheers Burnt Onions,
Fingers crossed I have not misread the tea leaves!
BMY They seem to give cautious guidance, and treated the excellent news earlier this year as a one-off. You'll notice that analysts are gradually ratcheting up their forecasts, though.
I heard a fund manager say some interesting things about the company. Their digital offering is something that BMY is keen on, offers high returns on capital, and seems to be going at least as well as they are expecting.
So one of BMY's growth driver is being overshadowed by the great showing that its more traditional business line is.
What's interesting to note is the company's ROCE over the last 6 years. It was around 8.5% say in 2019-2021, but is more like 13% in 2022-2024. The ROCE was particularly high in 2024, at 19%, although I assume this will moderate in 2025.
I hold BMY, so I'm obviously a bit biased. The forward PE is 18.2, which isn't cheap, but its trailing P/FCF is 17.2, implying a FCFY (Free Cashflow Yield) of 5.8%. I reckon a yield of 4% or above is a sensible enough valuation to pay for a company that one thinking is growing and of good quality.
So that's my 2c.
Bonus content: I found an interesting article on "Coffee Can Investing": https://newsletter.rationalwal... There are some really good writers over on Substack.
Rosebank Industries IPO today. The stock has shot up from 250p to 440p. Some thoughts on it here:
https://www.fool.co.uk/2024/07...
Do we know if any retail investors have the opportunity to participate in the Rosebank IPO? I assume not as didn't see anything. It will now be trading at c70% premium to NAV (i.e the cash raised) so don't think I'll bother with this one now, although wouldn't be surprised for it to do well given the team's track record.
It wasn't available to retail investors unfortunately.
Despite the historic track record of Messrs Peckham and Miller it appears somewhat bonkers to me to buy an IPO at a substantial premium to the money raised on listing.
If one wants to invest in a company with a buy, improve and sell strategy with adept management Avingtrans (LON:AVG) is in my opinion much the preferred option.
Its earnings are currently depressed by investment in its nascent medical division comprising Adaptix (portable 3D X-ray) and Magnetica, (portable MRI) if either of these are successfully commercialised one will have to pay closer to £7 or more, for the shares, rather than the £3.70 or thereabouts that it currently trades on.
In the meantime it has a very successful engineering division serving regulated industries, including nuclear, which is likely worth more than the current market cap.
Needless to say I hold Avingtrans (LON:AVG)
This appears to me just a shell company looking to buy a company to improve and sell. When they find one I suspect there will be further fundraising and dilution. It trades on the reputation of Melrose MRO which acquired GKN, de-merged all the auto business as Dowlais and what was left is GKN Aerospace as MRO's trading subsidiary. MRO year end '23 tells the story here. The deal makers have moved on and are planning on doing it again as ROSE when they find a company to buy. I used to have shares in Melrose but they liked to return capital to investors in a complicated way I couldn't get my head around so I took advantage of a rise in price to sell. An investment now in Rose will be a long haul I suspect.
Planet X
Harking back to a cycling discussion some days ago - I've ordered a Fairlight Strael (in their tall geometry). Turned out they are based half a mile from my house, so popped in to see them.
Very impressed with their service so far - all is not lost for the UK bike scene!
I bought a Fairlight as my retirement present, from me to myself. Good service, great bike, fat lump on top of it!
I'm around 100kg.
They just laughed when I mentioned how many carbon seatposts I've been through - they just removed their one from the bill and told me I would be better off with my own alloy post.
Fairlight
Good designer with good connections .
There’s a hole in the market for sure so these new companies without historic debt and without huge orders in place have opportunity right now to get a solid footprint.
Very niche though and whether they can, or even want to , scale up is their challenge .
Easy to build 500-1000 bikes a year
Above that headaches appear .
They spent over an hour being very helpful - laser measured my old bike to check fit etc.
I wouldn't describe it as scalable, but it was admirable. Nor did I get the impression that capitalism was high on the priority list.
But then this is North London - where we all bow to Karl Marx having a nap in Highgate Cemetery as we do laps up Swain's Lane!
Planet X is a great firm... competitively priced equipment and clothing.
I sold it 4 years ago
Not my train set any more .
(After I sold it the train did crash !)
But it was a great train set in its glory days. I know of many happy customers.
Sadly you were always too sensible to push into the lower volume corners and never made anything big enough for me!
There were times when it almost seemed sensible to buy one of your bikes and transfer all the parts across to a larger frame (if you did it yourself). Sadly it was never quite as simple as it might first appear...bottom brackets, cable length, rim clearance etc.
Titon
That’s an interesting update.
Sales tough and behind but thats not unsurprising
Another of the founding Anderson family gets the boot (or scarpers)
Not managed to dump the Korean subsidiary
However the restructuring is clearly underway and titon have a good product now with a fiduciary requirement for use in a building market that has just been given a big green light by labour .
And 2m cash and freehold etc still backing
Classic long slow turnaround .
Not for the impatient and maybe another 12 months of going sideways before we see if they can start to get this sorted
Probably better opportunities but quite interesting to watch this unfold, a classic Rockwood long term play .
Not easy to buy and sell and spread is pretty big too , plus maybe the exiting family members are going to sell their shares in the next period .
It's not on the list of stocks for review today but Trustpilot (LON:TRST) had a Trading Update this morning. So far it has not been well received by the market. I wonder if Graham might have time to have a quick look, as it's on his list of 2024 stock ideas.
A good morning for the portfolio, at least that is my view, as for the market who knows?
Jet2 (LON:JET2)
Unless I am mistaken, the prelims are very impressive with basic EPS of 185.9 some way ahead of consensus. The only down figure I can see in the headline commentary is the average load factor of 73.4% versus 75.2% (2023), but this is on seating capacity 12.3% higher versus 2023.
One never knows how the market which is caprice in the extreme and has been dismissive of UK shares, especially those AIM listed will react, but this is a quality company and deserves a higher rating.
Galliford Try Holdings (LON:GFRD)
Excellent update. CEO, Bill Hocking has done an excellent job in turning the company around and with demand for infrastructure, especially in the water industry expected to remain buoyant, the future looks very positive.
"· Strong progress in the year against our strategic targets, with increased revenue and profit before tax.
· Full year revenue and pre-exceptional profit before tax expected to be above the upper end of current analyst forecasts1.
· Continued balance sheet strength, with circa £227m of cash at 30 June 2024 (2023: £220m) and average month-end cash during the financial year of circa £155m (2023: £135m).
· Confident outlook driven by a high-quality order book of £3.8bn (2023: £3.7bn) with 92% of revenue for the new financial year secured (2023: 92%).
· Capital Markets Event, held on 23 May 2024, set out the Group's growth strategy to 2030, building further on the strong operational and financial performance delivered since 2021.
· Kris Hampson will join the Group as Chief Financial Officer on 2 September 2024."
Polar Capital Holdings (LON:POLR)
Two consecutive quarters of positive AUM flow. Admittedly one of the more expensive asset managers, but is has a discernible investment approach and outperformed its peer group. Happy to remain invested
"Polar Capital reports that as at 30 June 2024 its AuM was £23.5bn compared to £21.9bn at the end of March 2024, an increase of 7% over the quarter. In the quarter, AuM increased by net inflows of £0.6bn and a £1.0bn increase related to market movement and fund performance."
Some great numbers it would appear by Jet2 (LON:JET2)
Strong demand and successful market penetration
Profit before FX revaluation and taxation increased by 33% to £520.1 million, operating profit up 9% £428million.
EPS up 37% 185.9
Final dividend per share increased by 34% to 10.7p
Higher margin package holiday customers rose by 15%
Negative: Average load factor for Summer 2024 is currently 73.4%, down from 75.2% in 2023.
I've held waiting for the TU and have a modest loss, hoping that fortunes will turn today, the outlook does look good, although they will need to keep committing large amounts of capital to keep growing.
Holiday and flight prices are up a lot. A cyclical business, they are making out like bandits now that Thomas Cook are dead.
Jet2 (LON:JET2) are not "making out like bandits" - that implies some overcharging. You can see that operating margins are under some pressure. Some cost lines are going up because of their long-term intent to build the business, some because of inflationary pressures (e.g Eurocontrol charges).
What I love about this management team (& it is Philip Meeson's legacy) is that they are unafraid to build for the long-term. Note that they have converted some of their Airbus options from A320's to A321's (i.e with greater capacity). (Don't think that is in the RNS). They also continue to show a lot of regard for their workforce, unlike competitors such as BA. Another mark of a great company. I hold.
Jet2 (LON:JET2)
Epitychia
Holiday and flight prices are up a lot. A cyclical business, they are making out like bandits now that Thomas Cook are dead.
Have you looked at the numbers here or are you just providing unsubstantiated tittle tattle?
this year 6.3% of turnover has ended up as profits - looking at 2018 and 2019 combined 2 years pre covid 6.3% of turnover ended up as profit. Last year 6.5% of turnover ended up as profit. So where is the bumper bandit income you allege they have - thats right it doesnt exist
Yes their buisness is obviously cyclical and they and they will no doubt have years where they post little to nil profits or perhaps even losses - but covid excepted this company looks like it has a great track of not gouging the eyes out of customers and delivering reasonable consistent pricing and decent customer service. With holidays its pretty simple that no one is forced to buy the product so the company has zero ability to really do any gouging imho. Its pretty obvious to me why holidays cost more than they used to - that reason i dont think needs explaining.
Jet2 (LON:JET2) Profits are up from £371m last year to £530m this year.
A 43% increase.
Jet2 (LON:JET2)
Jet2 (LON:JET2) Profits are up from £371m last year to £530m this year.
I agree that is factually correct - i was using post tax profits totals on my calcs as thats whats left for shareholders - thats only up 37%
Note sales were up 24% - so jump in profits of has to be taken into cotext that all other things being equal we should perhaps have expected 37% increase on lfl basis ignore any benefits of growing sales.
So as % is the same as 2018 and 2019 combined at 6.3% - i have double checked 2023 and that figure was 5.7% not figure i quoted (apologies for any confusion) . To me difference of under 1% point is neither here no there and certainly doesnt suggests they have been making unreasonable profits compared to prior years. Surely you must agree the main reason for the profits hike is clearly due to the sales increase?
I had the misfortune of being the analyst who was allocated the Thomson Travel IPO back in 1998....
I've never forgotten the off-the-cuff quip from a colleague who sat near me:
"Holiday companies have an earnings quality somewhere between cabbages and steel"
Dismissive? Yes, but there is a grain of truth to it.
Problem is, despite being fully aware of what nearly always happens to cyclicals, we still get suckered in occasionally. Like the scorpion and the frog crossing the river....
Just talk to Warren Buffet about his airlines.
I honestly have no idea why Jet2 (LON:JET2) is trading at a p/e of 7 based on last year's figures. Can someone explain what I am missing?! It should be 12-13 surely based on how well run the business is and the growth rate?
I'm shocked it is pretty flat today.
An excellent set of results. Quality metrics - ROCE, cash conversion etc. all suggest a high quality business which is also growing well. So why the low p/e ratio? My best guess is that investors (private and institutional) are avoiding the sector because they fear another major lockdown whether caused by another pandemic or war or political / geopolitical unrest. Sadly this means that well run businesses like Jet2 (LON:JET2) are not afforded the premium they deserve over their less well run competitors.
My hope is that the next two years' forecasts are overly cautious. Another year or two of excellent numbers should help the shares to re-rate.
A medium sized holding - would be larger if the share price reflected the performance of the business
Hi Tortoise investor. I have just added a separate comment about their new aircraft orders, which I hope helps.
I agree Viz, some great results from Jet2 (LON:JET2) & a well run business in my opinion. Though I think the expectations of little growth in the bottom line for the next couple of years may be holding the share price back. An updated analyst note this morning expects Adj&Dil EPS of 167.2p for 2025, 173.3p for 2026 & then a return to growth in 2027 with 200p. Obviously just one analyst, but I'm assuming in the right ball park.
I think you may be right Phil (flat share price) - although with more load capacity, Bournemouth flights and more package holidays, I'm hoping there's growth right there. I'll be honest, I'm expecting a rerate, at what point, who knows - appears to be traders are on holiday!
Jet2 (LON:JET2)
I am a reasonably new holder here and have been happy to scoop up some shares at around the current prices - we obviously know the dangers of the airline/travel sector (or should do) but i like the consistency of the numbers from this company - simply do a bit more sales each year keep margin around 5-7% at bottom line for us shareholders and its a nice job done.
Hoepfully they keep a super sensible sound balance sheet to cover future nasties. Ok they are probably in a sweet spot right now that might not fully last ref closer to 7% profit than 5% bottom line (% of sales) but looking back covid excepted this company seems to have remarkably consistent profit generation. from what i have seen ref customer feedback and independent reviews Jet2 seems to always be near the top of the pile too ref customer service - just what we want to here as company owners.
at p/e of 7.5 seems great value to me - albeit i dont blame anyone who rules it out due to the sector its in - when things temporarily get bad in this sector listed companies can take a proper beating at that time.
At present it looks like new year has continued growth but lower projected % of saesl flowing troughn to teh bottom line - hopefuly thats sensible grounded forecasts that have room to be beaten If they continue to have favourable conditions - looking at the last 12 months it looks like estimates have been upped rather than lowered so hopefully that may be repeated. If not no biggie as it likely wont be anythihng they have done wrong.
In guess scale here matters - is anyone really going to want to start from scratch and spend the capital to undercut Jet2 on pricing for less than 5% return on sales ? - so hopefully status quo remains where everyone knows that pricing needs to be sensible and include reaosnable element for profits to be made.
As a Jet2 (LON:JET2) holder I can only reiterate what I posted a while ago. If my brother-in-law (aka Shylock) rates them as a good company they must be doing something right. Maybe Paul can do a first-hand assessment early next year from Bournemouth !
Jet2 (LON:JET2) no position. hope some may find this useful
In a recent Which Mag survey of short haul airlines (Feb 24) Jet2 came top on customer feedback with a score of 81% . Next was Iceland on 74% and for context EasyJet 50%, Ryanair 47 % and Wizz bottom on 44%
For everyone that is "shocked" by Jet2 (LON:JET2) share price movement today despite the seemingly good numbers...
For me the red flags are the weak outlook commentary.
Usually, management don't have the balls to say the bad news as it really is. They have to mention it, of course, but do so via indirect statements and figures. Looks like the case in Jet2 statement today...
£Jet2
Usually, management don't have the balls to say the bad news as it really is. They have to mention it, of course, but do so via indirect statements and figures. Looks like the case in Jet2 statement today...
Should that not all be in the current forecasts though potentially ??- this year sales are at present expected to rise £891 mill but profits only £10 mill. so to me it seems that current forecasts as they are already factor in much weaker overall numbers at the bottom line. I dont like outright sketchyness but as long as forecasts are being updated regularly as brokers will surely do here - to me its not the end of the world here if the actual updates contain a bit of waffle - what we want to avoid is huge changes to expectations without an explanation - in that regard i dont expect anything to huge to change based on what was said today. Hopefully someone has broker updates that complete the picture and will confirm the real updated position?
Hi Boon,
Re Jet2 (LON:JET2) I'd argue that on a PE of 7 the bad news that you highlight is more than in the price after the recent 15% fall from highs in April.
Any bad news is always relative to the share price; 1500 - 1550 (PE 8.5) looks more reasonable to me but only time will tell..
Hi Boon, Your red flag in relation to Jet2 (LON:JET2) "summer bookings trailing capacity" has also been raised by Investor Director of AJ Bell - Russ Mould, who remarks "The company's revenue, profit and dividend are all up on year and the airline flew a record number of passengers. While that is positive for the company, less positive is how consumers remain reluctant to book too far ahead. Last-minute bookings typically mean airlines have to fight on price to fill their planes or holiday packages," I hold shares in Easyjet (LON:EZJ)and I thought their last results were positive but they also made a comment in relation to "winter bookings being light" and the share price dropped 16% , they have only just started to turn round from early July. Investors still appear to be very cautious in relation to the airline industry.
I think you're probably reading too much into some short term and quite volatile data points, but even if true that this does point to some short term pressure on margins, I would focus on the longer term picture - Jet2 (LON:JET2) has delivered very good growth over many years and would expect this to continue.
Delayed reaction, but good to see the share price is now up by 4.5%.
Springfield Properties (LON:SPR) - "Strong delivery against cash generation targets"
Springfield’s year-end trading update confirms a positive conclusion to FY24 with profit and cash generation both ahead of forecast despite the challenging market backdrop. The key focus for the year was debt reduction and Springfield has once again proven its ability to reduce debt rapidly in response to changing market conditions. Bank debt reduced by over £20m during the year to c.£40m, well below management’s original £55m target. Current trading is steady, and Springfield is well positioned to capitalise on any improvement in market conditions.
Full year revenue is expected to be c.£266m, a 20% reduction year on year, reflecting challenging market conditions as well as Springfield’s decision to pause new affordable-only contracts during FY23. Revenue is therefore c.7% lower than forecast, but the impact has been more than fully offset by profitable land sales completed during the period.
We make no notable changes to our FY25 forecasts, which were already conservatively positioned and assume only modest revenue growth year-on-year.
We note that Springfield continues to trade at a marked discount to sector peers, notably a c.33% discount on a P/Book basis. We reiterate our Fair Value / share estimate of 140p, which equates to FY’25 P/E rating of 17.5x and P/Book of 1.0x. Link to research note: https://www.equitydevelopment....
Polar Capital Holdings (LON:POLR) - "Strong start to FY25 with AUM up 7% in Q1"
AUM was up £1.6bn (+7%) over Q1 of FY25, from £21.9bn on 31 Mar 24 to £23.5bn on 30 Jun. Investment returns were strong over the quarter, contributing +£978m (+4.5%). Pleasingly, net flows continued to gain momentum, contributing +£644m, the second successive quarter of positive net flows (Q4 24: £+56m) - a marked turnaround from the net outflows which characterised calendar 2022 and 2023, when many investors rotated out of equities.
Our fundamental valuation remains 650p, with potential to tick up if AUM remains at or increases from current levels over the next quarter. Given its superior growth rate, niche strategic positioning, strong profit margins and strong balance sheet, we think Polar should trade at a substantial premium PER to most peers, but it does not and so we see potential for a re-rating (page 2).
Link to research: https://www.equitydevelopment....
Lovely update from Polar Capital Holdings (LON:POLR) which is a reminder of how fund managers go up like a rocket during bull markets once client funds start pouring in.
Equity Development I think you're maybe being slightly too cautious in your forecasts. I completely get why you want to be conservative this early on in the financial year but your year end AuM expectation of £23.5bn has already been met and surely the balance of probability is towards average AuM and year end AuM succeeding your current expectations.
My morning smallcap tweet: I'm Forever Blowing Money
Ilika (LON:IKA) Titon Holdings (LON:TON) Videndum (LON:VID) MJ GLEESON (LON:GLE) Global Ports Holding (LON:GPH) Graft Polymer (UK) (LON:GPL) Totally (LON:TLY) Cambridge Cognition Holdings (LON:COG) Norman Broadbent (LON:NBB) Galliford Try Holdings (LON:GFRD) Onward Opportunities (LON:ONWD)
◄Ilika (IKA)► FY-Apr pretax loss £5.8m (£8.9m) on £21.m rev. Outlook "Cirtec contract represents most immediate commercialisation opportunity". [SP=26 Cap=43m]
Let's sing Ilika's theme tune:
I'm forever blowing money,
Pretty money in the air,
It flies so high, nearly to the sky,
Then like my dreams it fades and dies.
Fortune's always hiding,
I've looked everywhere,
I'm forever blowing money,
Pretty money in the air.
◄Titon (TON)► warns FY-Sep below mgmt expectations due to some hoped-for ventilation orders yet to convert into sales. Also continuing slow sales in Window and Door Hardware. Sales & Marketing Director scarpers, supposedly to cuts costs. [SP=79.6 Cap=9m]
◄Videndum (VID)► warns H1-June weak as the cine and scripted TV market recovery is taking longer than expected. Broadcast TV segment OK. [SP=273.5 Cap=258m]
◄MJ Gleeson (GLE)► confusing FY-June trading stmt. Homes op profit c.£30 million, ahead of market expectations but in outlook says "Gleeson Homes' sales rate over the last six months was steady but less vigorous than expected as a consequence of deferred expectations around interest and mortgage rate reductions." Land op profit c.2m, below market expectations. [SP=575 Cap=336m]
◄Global Ports Holding (GPH)► proposes to delist. Cash offer of $4.02 (312p) by Global Yatırım, a a 29% premium. [SP=258 Cap=198m]
◄Graft Polymer (GPL)► two new provisional utility patent applications in US for treatment of substance use disorders and mental health disorders using depot drug delivery systems. [SP=0.15 Cap=m]
◄Totally (TLY)► wins c.£11mm contracts to be recognised this FY. [SP=7 Cap=14m]
◄Cambridge Cognition (COG)► gets Innovate UK grant for Bio-Hermes 2 project. No £££. [SP=39.12 Cap=16m]
◄Norman Broadbent (NBB)► guides H1-June net fee income £4.5m, down 14% and U/L EBITDA £0.1m to £0.15m (£0.27m). "We are navigating extremely challenging market conditions. However, this doesn't impact the confidence we have in our prospects." [SP=6.15 Cap=4m]
◄Galliford Try (GFRD)► guides FY-June rev and adj pretax above the upper end of forecasts of £1.435bn to £1.643bn and £26.7m to £29.2m resp. Order book of £3.8bn. [SP=272 Cap=283m]. I hold.
◄Onward Opportunities (ONWD)► NAV 116.32p/sh up 9.2% since Dec and 20.6% YoY. [SP=123.4 Cap=25m]
Illika's tune could apply to most of AIM!
Come on England!
Sweet Jesus they could do it