Small Cap Value Report (Thur 28 May 2020) - BOO, Market comment, TND, FLTA, KETL, CCT, CTO

Good morning!
Graham here.
its going to reach 24 degrees today, so I'll to have to get this report done early, before the heat kicks in. One of the few benefits of corporate offices, that I do miss in the summer, is the powerful air conditioning!
Building a list for today:
- Tandem (LON:TND)
- Filta Group (LON:FLTA)
- Strix (LON:KETL)
- Character (LON:CCT)
- Tclarke (LON:CTO)
All done at 5pm.
Boohoo (LON:BOO)
In mid-caps, I see that Boohoo (LON:BOO) has attacked the bear argument head-on and bought out the rest of PrettyLittleThing for £320 million. The certainty this provides and the lower-than-feared valuation should be received positively, I think.
Market open - Boohoo is up 11% and is threatening to break out to an all-time high.
Shadowfall's research note speculated that the cost of buying out PrettyLittleThing could have been almost £1 billion, if Boohoo waited until 2022 and if it paid a very high EV/EBIT multiple (in line with stock market multiples for Boohoo, Asos and German peer Zalando)
The much, much lower price paid is terrific news for Boohoo shareholders and takes away the fear around this impending deal. I think it makes sense that the Boohoo market cap has increased by over £400 million - that accounts for most of the difference between the worst-case PLT scenario, and the reality which has transpired.
Boohoo argues that it is using its existing cash to fund the £162 million cash portion of the deal, not the £200 million it recently raised from investors.
Since all money is the same, regardless of where it came from, this is stretching things! The facts are that it recently raised £200 million, and it is spending £162 million in cash (plus more in shares) to buy out the Chairman's son.
And it could have bought the PLT stake several years ago, at a much lower level, but chose not to.
Conclusions - this short attack looks to have failed within 48 hours, in my opinion.
I do want to make it clear that I think Matt Earl is a brilliant analyst. He has scalped companies before and will do it again.
In this particular instance, it looks like the weight of the bear argument wasn't strong enough, and it has been counter-acted by decisive management action.
Generally, shorting is difficult for companies which are:
- profitable
- cash-rich (Boohoo has cash, no debt)
- not frauds
If a company ticks these boxes, then it might not matter how overvalued it is. It might not matter if there are some related-party transactions or if there is some confusion about how results are being presented (which is the main thrust of the argument by Shadowfall against Boohoo). You need a meatier argument than this.
Otherwise, if there is no obvious catalyst for the share price to collapse, there is always the possibility that it won't collapse, and your short trade won't lead anywhere.
Shorting can still make sense as part of a long-short portfolio where risks in one part of the portfolio are being hedged by trades in another part.
But if you make a large bet on one particular short, then I do think you need to be more careful - personally, I don't short anything, any more, unless there is a near-term catalyst.
Market comment
I find it very interesting that the FTSE is back around 6200.
Another 250 points higher by September, and I'll be in profit for the spread bet which I placed just before the crisis kicked off. That would be quite a result!
I've been sitting on this trade through the entire disaster, even watching the FTSE slide all the way to 4900 and continuing to hold. I stubbornly stuck to my guns.
The optimism is justified, I think. So many European countries have opened up, with no real evidence of a "second wave" (I've got strong opinions on this topic, which I'll reserve for my Twitter account!).
It's true that UK/Ireland are way behind Continental Europe in lifting lockdown, but even so, there is great cause for optimism with all UK retailers opening back up very soon. The economic pain will still be with us, but the worst of the catastrophe will be over.
In the US, I understand that several states have re-opened and they also haven't seen any "second wave" (Georgia, Florida, Texas).
I can't wait to get back to normal conditions when every article and every RNS doesn't have to be put in the context of the recent disaster.
The movement of the FTSE over the last two months is consistent with the view that those conditions are not so very far away.
Tandem (LON:TND)
- Share price: 237.5p (-6%)
- No. of shares: 5 million
- Market cap: £12 million
Please note that I have a long position in TND.
This is a share I have some history with.
I owned it from 2015 to 2017, a period in which the company went from one accident to another, and I sold out for a painful loss after deciding that I had got it wrong. My experience with it was one of the reasons I abandoned "value" investing for my larger positions.
Last year, I noticed that the company was doing rather well, so I bought in again, but this time for a much smaller stake (2% of portfolio).
This purchase was really an emotional hedge, designed to prevent me from experiencing disgust if it went on to succeed after I had researched it heavily and then moved on.
Background
It's a bike and toy distributor based in Birmingham. It also sells mobility scooters, gazebos, party tents, etc. It owns a range of long-established bike brands and has licenses for Disney, Batman and Peppa Pig.
The problem is that the value in the business hasn't accrued for shareholders - management are very well remunerated, and in contrast the dividends to shareholders have historically been very small.
For 2017-2019, for example, total EPS was 106.5p. Dividends for these three years add up to 15p. The dividends for 2019 were increased by over 50%, from a very low base, after shareholder pressure.
Dividends shouldn't matter, of course, if retained earnings are being used wisely. One of the reasons I originally sold out of Tandem was my concern that acquisitions had failed to deliver much by way of increased profits, and my fear that future retained earnings would be wasted on more poor-quality acquisitions.
The good news is that acquisition activity has calmed down, and the company has instead been paying off the mortgage on its £3 million property in Castle Bromwich.
The most recent balance sheet showed net assets of £14.3 million, or TNAV (tangible net assets) of nearly £9 million. This should support the market cap, I think.
It still needs to work on reducing its pension deficit but there are signs that, if it wanted to, it could start paying very large dividends (compared to the market cap) within a short few years. This is highly uncertain, of course!
Latest update
I never expect RNS announcements from Tandem to be positive, and today's announcement is unfortunately another disappointment.
The UK government told people to basically "get on their bike" instead of using public transport, and it has been boom-time for bicycle demand.
Has Tandem capitalised on this? Yes, but there are problems.
Key points from today's AGM update:
- bicycle sales +77% year-to-date
Doing very well here but there are supply problems due to global lockdown, the company is "working hard to replenish stocks as quickly as possible".
- online sales "strong", including outdoor products which have sold "well"
Tandem says the supply chain from China is now "broadly back to normal with regular supplies being received".
My own quick investigation suggests there are still supply problems in this division. Hedstrom outdoor products, for example, has very limited supply at Argos.
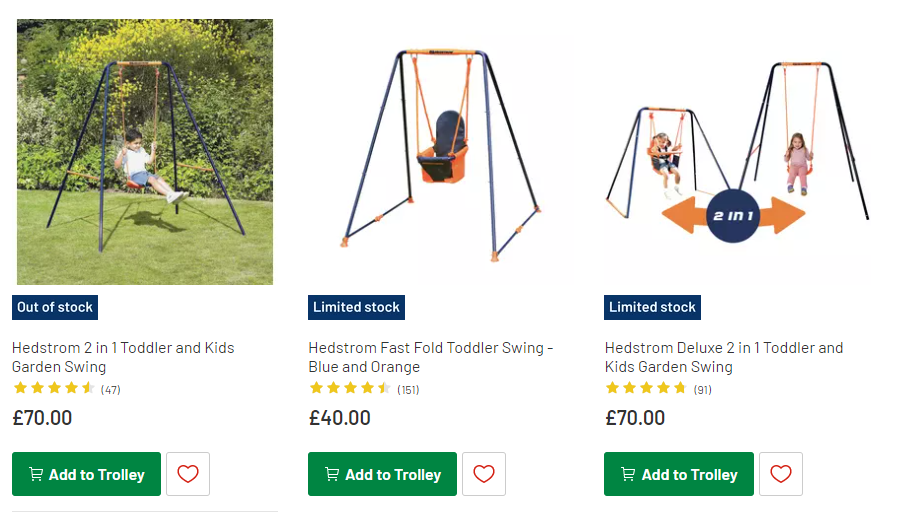
- national retailer business - problems here as most toy shops are closed. Orders delayed and new orders slow to arrive Order book down 21%.
Conclusion:
Year to date Group revenue is slightly ahead of the prior year, although the overall Group order book is approximately 3% behind last year. We therefore expect Group revenue to fall behind the prior year during the Summer period as a result of the lack of national retailer FOB orders and a limited supply of bicycles.
AGM - cannot be attended in person.
My view
I'm planning to stick around here, for the foreseeable future.
The company earned an operating profit of £3 million last year, and the average annual operating profit over the last six years is £1.9 million.
Over this time period, the worst annual result was £1.2 million.
I have no idea if it can solve its supply problems in the short-term, but I think it should be able to, since the world is opening up. It is of course a terrible missed opportunity, that it is failing to fully capitalise on the demand this summer.
My expectations here are genuinely very low, but I'm happy to stick around at a £12 million market cap. Stubbornness has a habit of paying off.
Filta Group (LON:FLTA)
- Share price: 108p (+1.4%)
- No. of shares: 29 million
- Market cap: £31 million
This company offers a range of services - it owns FiltaFry (fryer management/cooking oil filtration) and FiltaSeal (refrigeration seal replacement). Does it get more boring and unpleasant than that?
As an investment, it's not so boring. Organic revenues were up 16% for FY December 2019, and were boosted by acquisition revenue, so that total revenue was up 75%.
Adjusted EBITDA is +20%, adjusted PBT is +7%.
However, I am disappointed to see no mention at all, in the headline numbers, of the fact that reported operating profit is down 32% and reported PBT is down 46%.
Why the huge discrepancy?
Two main reasons.
Firstly, finance costs related to loans shot up:
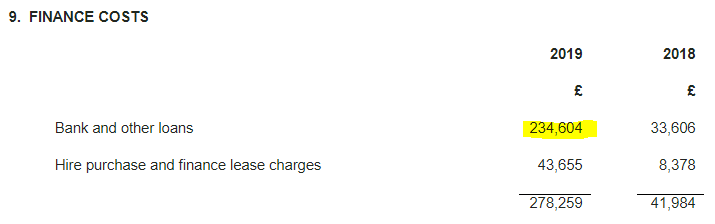
Secondly, depreciation and amortisation charges increased by £1 million. These charges increased in each of the group's operating segments.
Digging into it a little, I see that amortization of customer relationships and customer contracts jumped massively.
If I was a shareholder here, I'd be asking the company what is happening with these intangibles. The higher charges are probably to do with the most recent acquisition.
Worth noting that Filta's balance sheet is laden with various intangibles. Strip away intangible assets, goodwill and "contract acquisition costs", and you are left with tangible equity of c. zero (at least it's not negative!)
Covid-19
Lockdowns have been a major problem - "a significant part of the Group's activities are focussed on the entertainment and leisure industries and our business has been affected by these events".
In response, the company launched a new service, "FiltaShield", to protect customers from COVID-19. This is in its early stages.
There is very little hard info given in terms of current trading and outlook, we can only presume that the situation is currently very poor. The company is optimistic for a return to normality:
With the strong pipeline of potential franchisees prior to the lockdown and based on the continuous and positive discussions that we have had with franchisees and key customers during the last 2 months, your Board is confident that when social distancing restrictions are lifted and more normal trading conditions are resumed, revenues and margins will return to the levels being experienced in the first quarter of the year.
My view
This one doesn't tick enough boxes for me personally, and the StockRanks don't see much value in it.
However, I like it a lot more at the current level than I did at 250p+. If everything goes to plan, this could be a very reasonable entry point.
Strix (LON:KETL)
- Share price: 189.4p (+3%)
- No. of shares: 199 million
- Market cap: £377 million
AGM Statement and New Banking Facilities
This company designs, manufactures and sells safety controls for kettles (for which it owns global patents).
In recent years it has moved into coffee, water filtration, and other related areas.
AGM statement - the company has made "a solid start to 2020", and implemented measures "to limit the impact on the full year forecast".
Banking facility - increased from £49 million to £60 million. RSB is still involved, and HSBC is replaced by Bank of China.
My view - the core business at Strix should be ok in the near-term, I would have thought. The demand for kettles is hardly going to fall off a cliff!
Character (LON:CCT)
- Share price: 230p (-6%)
- No. of shares: 21.4 million
- Market cap: £49 million
This bears some similarities with Tandem - it designs and distributes toys and games and has some valuable licenses.
H1 to the end of February (pre-pandemic) was poor. Revenue down 12% and profit more than halved.
These numbers are before the impact of CCT's FX hedging. If you include those effects, the numbers are a bit worse:
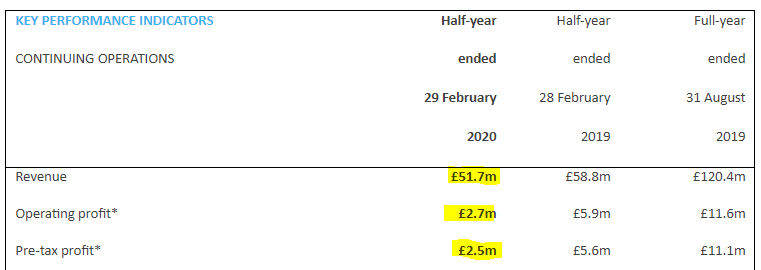
H1 is said to have been affected by many issues:
- a large toy store going bust
- declining consumer spending on toys
- weak Sterling (since CCT is an importer)
- Brexit uncertainty.
H2 won't have been any easier. Sales have been "deeply impacted".
CEO comment:
"There is no disguising the fact that the severity and duration of the COVID-19 pandemic has considerably affected the toy sector globally and will affect our second half results for this financial year... we intend to be fully open for business and to re-establish our prior trading trajectory as soon as we are safely able to."
Balance sheet: net cash of £16.8 million.
Product portfolio - continued development in H1. Peppa Pig and Pokemon are still here, and lots of new brands have been added.
All of these toy brands have very silly names so I'll spare you the details. If you're interested, click here.
Dividend - 2p, down from 13p last year. Covered nearly 5 times by underlying earnings.
I consider it a green flag if a company continues to pay any dividends during this crisis. It suggests that A) it's still thinking about its shareholders, and B) it has probably not been devastated by lockdowns.
Outlook
This section includes some useul info:
..with the quality of our brand portfolio, the strength of our customer relationships and the resilience of our cash-generative business model, the Board expects to achieve a profit in the second half and, accordingly, for the current financial year as a whole.
With a sizeable cash balance and substantial unutilised bank and finance facilities of at least £50.0m, the Group has a strong balance sheet...
My view
I'd much prefer to own a company like this one, instead of the toy retailers it sells into (remember Toys R Us?).
Character needs to manage its inventories and its customer relationships, but it doesn't need to worry about vast fields of retail space and an army of employees (it has headcount of just 212, according to Stocko).
It will be a very difficult period, but I don't see why Character shouldn't emerge from this in reasonable shape.
The StockRanks tend to like it, because it's often quite cheap and it earns high ROCE/ROE. That is still the case today.
Tclarke (LON:CTO)
- Share price: 101p (+12%)
- No. of shares: 43 million
- Market cap: £43 million
This building services company announces that its June AGM will be for Directors only. This is evidently a trend.
Dividend - the Board recommends the proposed full dividend of 3.65p, up from last year's final dividends.
Q1 update - profitability remains "strong" and underlying operating margin of 3% was maintained (building services tends to be very much a low-margin business).
The good news is that Q2 is expected to be around breakeven on an underlying level, so the underlying H1 result will be an operating profit of £2 million (last year, the underlying H1 result was £5 million).
So there is no real damage expected, save for a quarter of missing profits.
Restructuring - one-off costs of £3 million have been incurred (which will be treated as exceptional), to generate annualised cost savings of £4 million. Sounds reasonable and appears to be part of a broader strategy, not just in response to Covid-19.
Order book - is up slightly compared to the start of the year. Described as "robust".
Balance sheet - CTO had net cash of £12.4 million at year-end, no debt. It reports today that it has maintained positive net cash through April and May, and has £25 million in RCF and overdraft faciltiies.
The balance sheet is quite big, so there could be big variations in cash flow. I'm thinking in particular of £85 million in payables at year-end. CTO says it "remains committed to the supply chain and is maintaining regular payments to our suppliers to ensure that their cash flow is supported".
Outlook
A number of possible scenarios have been modelled, each of which results in an underlying operating profit for full year. The current uncertainty and resulting range of possible outcomes means that it is not possible to give accurate market guidance for the full year at this time.
My view
Kudos to management for hitting their operating margin target, and staying focused on it this year. It appears to be maintaining its discipline when tendering for projects.
Visibility is of course extremely poor. Its net cash position and tendering discipline are likely to help it trade through this period, in my opinion.
That will do it for today. Cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
Hi hayashi22
I’ll reply in more detail later, but Investment Trusts can be bought and sold on our stock market exactly the same as shares. That and the chance to buy at a discount (including many right now) is one of the big plus points.
Each Trust also has charges that are taken out of the share price, so investors don’t really notice them Charges for many Trusts are low, and under 1% sometimes. Trustnet and theaic sites both show the charges for each Trust.
If you could give a brief indication of your knowledge/experience with them that will help with the next reply.
2Shedsham
I too would go for, and hold, Vinacapital Opportunity Investment Trust VOF.
Latest Net Asset Value is 390p yet it can be bought for a 20% discount to that price at 315p.
I marginally prefer VOF to Vietnam Holdings Investment Trust, also on a big 17% NAV discount. I like their user friendly updates too. e.g their monthly factsheets.
Note how Vietnam has dealt with Coronavirus superbly and Vietnam is seen by some ad the next China. So this Trust could prove a superb long term holding.
For excellent info on Investment Trusts I used to use www.trustnet.com
but I now use the easier to navigate aic site itself.
Here’s the link taking you straight to the VOF page. Just scroll down below the “Company Announcements” heading on the right to find their latest fact sheet.
Hope that helps
Ken
https://www.theaic.co.uk/companydata/0P0000FTTI
Thanks for that Ken. I;m tempted by investment trusts for direct exposure to a country. Out of interest what are the annual charges you pay each year in order to hold the fund. That for me has been one of the issues. With shares you pay your £10 whatever to buy and sell and that's it. I have one pension fund with various pots and they pay 1.65%...that's quite alot of dosh on an average £50k pot.
Final words for today timarr, and it’s good of you to reply again.
I’ve given you a false impression. I do dabble in the odd speculative share like Revolution Bars, but my methods are usually much more like John Lee. i.e quality dividend paying shares (dividends blown away for now though!) and Investment Trusts to invest all round the World, including promising Countries like Vietnam. And my focus is always on sectors that look good value after falls. Spoilt for choice recently.
Hope your last sentence is proved right!
Hi Ken, would be interested in your choice of Trust for Vietnam. Recently went for the Vinacapital Opportunity fund but no real conviction in choice, just wanted a bit of exposure to the country.
Hi again timarr
I respect your views and I’m sure the vast majority here will agree with you, the more so as every day the media bombard us with genuine horror stories from the front line.
What doesn’t get stressed enough is that the vast majority of severe cases are obese people (and Boris freely admits that applied to him at 6 stone overweight) and those unfortunate enough to have other medical conditions like diabetes, along with some ethnic minorities. The fact that for fit under 45s the death rates and severe cases are very low, at only around 500 of the 40000 fatalities gets little if any coverage,
Aldo the media do not every day dramatise the equally terrible deaths from cancer, heart attacks and strokes and many others, nor that those have increased significantly since lockdowns. Why the extreme focus on coronavirus? There has been hardly anything else on the news for weeks. Yet 99.99% in the UK, one of the worst affected Countries, have NOT died from it.
I’m not guessing about the millions who may well have had it. That too has been covered but gets ignored by much of the media. I really do believe that many have been brainwashed.
And I guess here on Stockopedia, many of the contributors are retired and in the age group more likely to be affected, and it’s so noticeable that posts bearish on the virus get well recommended, and those giving the opposite view don’t. The crowded beaches are a guide as to how often younger folk are reacting.
As for investment angle, the markets have gone with my view, but also with the incredible “money” being thrown at it. And I have gone with the market. I was down 25% but buying since mid March along with a couple of lucky buys mean I have now recouped all my losses this year. And some of those profits have been taken.
This site and the Small Company reports and comments have also considerably helped my performance. Ditto Paul’s sensationally good market/virus comment.
E.g I bought Revolution Bars back after comment from Paul Scott here just 2 days ago, and it has already doubled....in just 2 days. I can now look to sell half and run the rest for free. And several other recent buys are up more than 50%. Some shares are doubling or more in a day!
And it’s a shame that many seem to be waiting for a safer time to buy, failing to notice that markets, at least for now, are far more bullish about virus outcome than many posters here and elsewhere. By the time some change their minds and buy it might be just before the next big dip IFIF the virus returns with a vengeance. THE best time to buy is so often when news is dire, but priced in, and any better news isn’t. That was the case in mid March. It isn’t the case now markets have soared.
And time will tell on how the virus was handled worldwide. Again though investors here seem to be ignoring the fact that many Countries dealt with it far better than the UK. Stock markets are reflecting that too.
Why the extreme focus on coronavirus? There has been hardly anything else on the news for weeks. Yet 99.99% in the UK, one of the worst affected Countries, have NOT died from it.
Actually its only 99.999% of people in the UK that have died from it. Which is 'only' 60,000 people. Which, remember, was suppressed by lockdown.
As for investing - as I said, there are lots of opportunities. How you go about it depends on the type of investor you are. For me the likes of Revolution Bars (LON:RBG) is pure beauty parade investing - with no earnings visibility it's a bet that other people will bid up the stock as they turn positive on it surviving. Which is absolutely fine, just not my thing.
There are plenty of great opportunities around with no capital risk, it's a good time to be any sort of investor on the long side but I want stuff I can buy and hold, I don't want stocks I have to monitor constantly in case in turns out they're about to go bust or shut down as a Covid-19 superspreader location.
Each to their own. Personally, I'm enjoying the investing opportunity, I reckon this will lead to years of portfolio outperformance with minimal supervision.
timarr
boo stinks-do you think they would be buying now if it was not for the short attack plus lots of deals which are done include an additional payment if targets are reached- surely that would have been the way to go with the original 66% purchase
I timarr
The only thing worth challenging in your post is the number of people here (and elsewhere) who have had it and often without realising it.
There are so many cases where people having it were not tested. I think in Paul Scott’s household only the one very sad fatal case was recorded. The other three all got it, but won’t show on official figures. And with so many seeming to get it without knowing it, this sort of thing must apply in other Countries too. So I suspect that millions more here have had the virus than is being recognised.
So I suspect that millions more here have had the virus than is being recognised.
Hi Ken
Surely we have to go with the best data rather than our own guesswork? That's not just about investing but about personal safety - although most people are hardly touched by the virus for those who do get it badly, it's a terrible experience:
https://www.bbc.co.uk/news/527...
The New York studies, the ones in Sweden and the ones in the UK mainly show a range of 8% to 12%. There are a variety of methods being used but this isn't guesswork, it's combination of sampling and testing with some modelling thrown in. While that won't be perfect I'd rather work on the basis it's roughly right than trust my personal instincts.
If you really believe that the rates are significantly higher than that then you should invest accordingly - all in on travel and leisure - and stop worrying about social distancing and all of the other measures. To me that sounds quite a high risk approach
Personally I suspect those figures are roughly correct and I would rather get it later than sooner. The later you get it the better the treatments and the better your survival chance if you are unlucky enough to be badly affected.
EDIT: The ONS figures today say that 7% of people in the UK have had it, just to add to the evidence pointing in that direction:
https://www.bbc.co.uk/news/hea...
timarr
Has anyone been following the Stelios v Easyjet saga? I've only seen bits and pieces, but today's latest shot across the bows from Stelios is fun. He's offered £5m to any recently sacked EasyJet employee who will whistle blow on connections between the board (aka scoundrels) and a "dodgy" Swiss lawyer. Can't wait for the film...
https://easy.com/sir-stelios-easyjet-staff-are-getting-to-carry-the-can-not-airbus/
BTW does the person in the photo not remind you of the late, great Dave Allen!?
"Goodnight, thank you, and may your God go with you." Si
"My view - the core business at Strix should be ok in the near-term, I would have thought. The demand for kettles is hardly going to fall off a cliff!"
You missed an opportunity to say demand is unlikely to come of the boil or even run out of steam :)
Whoops :)
And itHi timarr
Agree that we need to be very careful and also with your comments about percentages.
What so many seem unable to grasp, including the media, is such clear evidence that it was already well established in the UK long before the first official cases were reported. A golfer at our club who I and many others mixed with almost certainly got it last December. He had all the now well known symptoms and genuinely feared for his like as he struggled to breathe.
Many of us were in close contact with him, and some must surely have had it without knowing. I think I could well have had it in very mild form, as had intermittent temperature, and each time that happened a rasping dry cough and lack of energy, Then it went and then came back again. Luckily mild each time. I know others who put it down to flu, but said it was different this time and they too now think they could have had it. It’s now well known that a Harrogate choir had several members with classic symptoms also last December and it transpired that one of them had direct contact with someone from Wuhan! They could well have caused it to spread.
Premier League footballers have been surprised they’ve tested positive as they’ve had no symptoms at all. It could well be that millions have had it without knowing, so IF that provides protection against getting it again, the worst might soon be over. Markets are behaving as if that is he case.
I'm another who thinks they had "it" at the start of February but never needed to be tested. I think the early cases here were likely the Wuhan strain brought here mostly by returning students in January, which wasn't as severe for us as the strain that came back from the Italian and Austrian ski resorts after half term.
Hi Ken
There are various estimates around but the average seem to suggest that between 10% and 12% of the UK population have had the disease - which is a long way short of the two thirds that need it to get herd immunity. In Stockholm the latest tests surprised everyone by showing that less than 8% of people had antibodies - and Sweden has had four times the number of deaths of neighbouring Denmark, which did lockdown, so the price has been high.
Personally I think that looking to this kind of thing for guidance on where markets will go is a bit of a red herring. We will have to learn to live with the disease which means more social distancing, better sanitation control, gradually improving track and testing and gradually finding better treatments (blood thinners and interferon already appear to be helping). A vaccine may arrive eventually but if this mutates like the common cold we'll need a new one every couple of years.
That would suggest that we've already seen the worst for markets in terms of fear and uncertainty. The major unknown is peoples' behaviour - the only similar event I can compare this to was 9/11, and it took about 3 years for behaviour to fully revert to normal. That impacted transport, hotels, leisure - although you'd think the 18-25 group will mainly not care and go for it anyway, and good luck to them (as long as they stay away from me!).
However, we are guaranteed a steep downturn and weaker businesses will fail so we're into normal pre-recession planning. There will be a lot of job losses although unemployment would probably plateau quite quickly, but that will impact house purchases, new car registrations and big ticket home items (sofas, etc).
Some trends like e-commerce and homeworking have been accelerated by this, they're unlikely to ever fully unwind. I assume governments will invest more in healthcare and perhaps a bit less in defence going forward. Commercial property will have to change, although it's hard to know how.
Most of the big share price movements are in stuff that's already been heavily beaten down. There's been a trend towards companies moving off-market because of the boom in PE / VC money - but right now, the public markets are the place to be as companies raise cash with relative ease. Anything funding itself through to safety is going to bounce because unlisted competition that came into this without funding is in big, big trouble.
But looking at vaccines and infection rates isn't really a guide to the future, IMO.
timarr
My view - the core business at Strix should be ok in the near-term, I would have thought. The demand for kettles is hardly going to fall off a cliff!
Surely you mean go off the boil ??
As we have strayed into the realms of climate change, just a little aside. In 1965 my Geography Master (David Hughes) said 'the world will heat up before the next ice age' we all said, 'how can that be sir?' He said 'latent heat of vaporisation', we said 'Uuuuuugggghh, whats that? He said ' as the world heats there is more evaporation, evaporation causes cooling and the ice caps will extend causing the next ice age. And he added it will happen relatively quickly. The question is was David Hughes a genius or an idiot? I may not discover the answer in my life time but it makes one think. Just thought you might all be interested. :-)
I’m afraid that he should have asked the science teachers before holding forth on things that weren’t his subject area.
Yes, vaporising the water uses energy.
For the same reason, when you come out of the water after a swim you feel cold as water evaporates off your skin using heat from your body.
What he should have known is that that moisture in the air condenses from vapour back to liquid at altitude (forming clouds) reversing the process and releasing that heat again as it changes state.
So, this is immaterial in terms of climate change as overall it causes neither warming nor cooling.
What he would not have known back in 1965 was that our greenhouse gas emissions are causing a greenhouse effect that increases temperatures overall. This may cause more extreme weather but not an ice age.
hi Paul, Thanks for your various reports on Revolution Bars (LON:RBG), I read with interest and brought in a few months back, great to see shares up 50% today.
Just noticed all my best buys since the start of April have been retail: N Brown (LON:BWNG) I bought at 11p and again some at 18p, Ted Baker (LON:TED) at 145p and Warpaint London (LON:W7L) at 45p. All were down 80-90% from before the crisis.
All are bouncing back from the doom and gloom of 6 weeks ago nicely. High beta and high risk but personally I saw our handling of the crisis as only able to get better from the start of April as we hit the peak. and testing increased significantly.
My personal view is even a second wave will be tackled in a much better way from here on, we have the testing, the social distancing in all stores, people are more aware of what to do and slightly better treatment. A vaccine would put a close to the whole topic but let's wait on that.
Financially, I see consumers holding up fine but the burden moving to gov debt; even though I see this more as a prolonged low rate issue rather than a credit shock or insolvency issue - and more taxes are almost certain to come.
Yes and CARD soaring today. Was looking at other retailers today to see if any bargains. Quiz? FCCN?
I enjoy the reports Graham but I'm wary of how expressing your opinion on lockdown being an excessive measure might be necessary or accurate? What are your thoughts on South Korea today reporting a large spike in cases since they eased their own lockdown? I mention this as it clearly has market and economic implications in the UK, especially as South Korea is seen as a country which has managed the Pandemic effectively.
Large increase is only 40 new cases to them. Perfectly manageable.
Personally I think it is a good thing to see a British company fight off a short-sell attack, kudos to Boohoo (LON:BOO) , people keep doubting and they keep powering on.
People will have their own opinions on its valuation but it is good to see businesses doing well, that's the whole point of investing, rather than just trading.
I held Boohoo (LON:BOO) but sold a while ago above 300 just because I saw other opportunities (Just Eat Takeaway.com Nv (LON:JET) being one of the main ones which I think is an exceptional growth story and the potential is huge) and not because I think it is a bad company or that it won't keep compounding 20-30% returns Y-on-Y.
Hello Thornabian
Just want to applaud you for your amazing insights and the superlative investment and timing you have let us know about on here re Boo, Just Eat, Amazon, etc
Bravo! No doubt such acumen has been very richly rewarded.
I am being won over by your sage opinions and timeless wisdom...and so have elevated your personal opinion re Boo and short sellers to a very dizzy mental altitude.
Ciao
Hmm
Since we seem to be mentioning "second waves" of the virus today it's worth noting that the evidence for waves in pandemics is murky - it seems to originate in the Spanish 'flu outbreak, but due to military censorship it's not certain there was a second wave - it may just have been one long uncontrolled outbreak. However, coronaviruses are typically seasonal - they tend to die down in warm weather and then reoccur as colder, wetter weather sets in: i.e. they're always with us, but it looks like it comes in waves.
The trouble with that is that we won't know until after the (second) event. But if it is seasonal you'd expect the current fine weather to be helping suppress the infection rate. I think we have to expect the government to be relatively cautious about relaxing social distancing measures until after next year's 'flu season but in the meantime presumably they'll try and get as much open as possible as soon as possible. It's pretty obvious that most people want to try and resume some kind of normal life.
You'd also hope that if there is a second wave we'll be better prepared for it.
timarr
It's also suspected that it's not just that the viruses are seasonal, it could also be that our susceptibility to them varies with the seasons, perhaps as a function of our Vitamin D levels so this weather is perfect to get outside and top up our levels naturally.
I listened to this podcast which is a good summary on my daily walk yesterday.
https://www.theguardian.com/science/audio/2020/may/27/covid-19-the-role-of-vitamin-d-podcast
You'd also hope that if there is a second wave we'll be better prepared for it.
That would be big dose of hope, based on the way the first wave was dealt with, especially given that there was ample 'notice' by observing what was happening in other nations before it finally hit the UK.
Graham,
Thanks as always for your views on macro and micro alike. You are a great asset to this site.
I find myself agreeing with so much of what you say, but there’s something that has been bugging me for a few months. It’s your spread bet on the FTSE, set to break even at 6400. Can you explain what your thinking was for this?
You’ve been very clear about your long term bullish view on the FTSE and also your approach to holding on to quality companies through any corrections. In this case, as you didn’t want to sell anything to raise cash, wasn’t the obvious strategy to go short the FTSE as a hedge against your equity holdings rather than doubling down on them. You could then have raised more cash by closing to add to your quality holdings. I know this all sounds simple in hindsight but many people did just that. I’d be interested to get your thinking on this. Thanks.
The response to the last serious crash ( GFC ) was met with ineptitude by central bankers and governments around the world with the US probably the only exception judging by how well their markets performed post that particular stimulus ( TARP et al ).
This crisis has seen less dithering by governments and a determined effort to underpin economies and markets and a desire to go 'all in' with financial stimulus. A better effort all round.
My personal feeling is with infection rates largely on the wain, we will see further upside and then the wall of money sitting in cash on the sidelines will come and add more froth. Where else is the yield investors crave?
I hope I am right but I might be wrong. Either way I am buying stocks of all sizes with solid balance sheets that can weather this storm and be in a dominant position post crisis when some other competing firms have withered and died
Graham, there is a gap from 8th March to fill on the FTSE around 6388. Hopefully, will fill soon
PS I'm not trying to talk up any bullishness. Crazy situation. Take care and DYOR.....my best advice at the moment...anything you own assume it can go down 30% from here for not much reason (and if the bug is the armageddon we've been told by some then double that and add a bit more too)
Suns out and market up so all rosy. Second Q results may dampen the party so may save the powder till July when will know who stays and who goes.
My long on Bae Systems (LON:BA.) has just warmed up from a channel. Maybe Trump selling missiles to Taiwan and sabre rattling over Hong Kong - so the US election will add to the volatility, ho hum. Bought Ultra as North Korea building a big missile sub. I would not want to get in (the sub that is) but buy the rumour as they say.
Looked at Ergomed but 20p spread a killer. I need to look at other marketeers.
I think we are a long, long way from normality. I think there will be short term wave of euphoria followed by a material chance of the following;
Realisation that (a) there will be a lot of job losses as earnings don't recover to the prior levels (b) a material number of businesses fail (c) housing activity to stall and prices to fall (d) repeat until stock market has fallen below prior lows (e) house prices to fall c.50%
I just can't see how so many businesses can survive on even 20% less sales which I feel is optimistic. Yes there will be big winners in the next 5 years, online retailing (maybe online anything) being an obvious one but with continued uncertainty (even if a second wave is avoided) it could mean a very difficult time for many businesses.
Even people that are not afraid of the virus may not go out as much as I don't think it will be much fun having dinner in a restaurant with perspex screens, waiters wearing masks and whatever else. We've seen images of people sitting outside eating abroad but of course that has never been a reality in the UK for very much of the year.
Sectors I think face material uncertainty for the foreseeable future;
Restaurants
Bars
Hotels
Any form of travel, airlines, buses, trains
Bricks and mortar retailers
Anything involving big purchases (housing related, cars)
Clothing retailers of any kind if we go out less (even if they are online to a degree)
Luxury retailers of any kind if we change our lifestyles even a little bit
Any sport that relies on a live audience (almost all)
Don't forget in normal times if any business had a sales drop of 10% it would be considered cataclysmic. Now we are shrugging off 100% sales drops! And thinking 40% down is not too bad!
Since the 2008 credit crunch what pains me is that both business and individuals remain indebted up to the hilt and unable to deal with any bad news, even short term. We don't seem to have learnt the lessons in my view. I hope I am wrong and things recover quickly in some ways but in others I also wonder if a painful 3-5 year recession will leave both businesses and individuals in a better place.
It's not always just about the money!!
You could be right but I hope you are wrong...................if they find the vaccine soon then the game changes
I hope I'm wrong but the damage may already have been done or be done by the time a vaccine is found (if one is found at all)
https://www.newscientist.com/article/mg24632804-000-why-itll-still-be-a-long-time-before-we-get-a-coronavirus-vaccine/
Markets are perplexing.
Market calamity can be an opportunity for reset of expectations. In 2008 emerging markets and commodities were junk. By 2010 they were a rocket to the moon.
In 2020, large swathes of the market were junk even before covid. The FT100 is lower than 20 years ago. Same goes for every major market in Europe and Japan. Maybe its end times (I can make a case based on demographic, geographic and consumption factors for UK, Europe and Japan)...but thro modern industrial history we regularly face end times.
I think it will be entirely mundane and possible that FT100 ends 2020 higher than 2019. A bit rotation and change in sentiment and there are a number of businesses that can attract higher attention. In fact, that everyone (and we all do, including me) feels this is impossible and sort of emotionally wrong makes it more likely. I think the odds of FT100 at 7000 by end of year are pretty high.
As one last point re perplexing....we have depression like data. Run any 'rational' spreadsheet and the conclusion has got to be we're fckd...unless you're drinking the US mega tech koolaid! But the on the ground reality is far from depression in that incomes have not been so significantly hit (yet maybe....bottom 50% in US are better off at the moment and I have a number of low wage friends and family who also report to their surprise feeling comfortable) and capital has been generally preserved (note that depressions are so destructive as its not just malinvestment that is torn apart...its everything)....its possible that the capital cleansing + capital preservation + massive govt support/stimulus = boom time once we feel we can peer beyond bug.
Don't want to get political...but I think Cummings-gate perhaps is an illustration that people are ready and wanting to go back to normal and are fed up with their contained living...and that is part of the reason he's getting so much heat (personally, I think the only bit of his story that is stretching it is the trip to test his eyesight...the rest is okay unless someone proves he acted recklessly)
Anyway, the potential for us to surprise ourselves with how good things are is quite high. Then there's the bug itself...nasty...but not nearly as bad as narrative/model made us feel it would be. We probably feel we can cope going forward (and UK was one of worst hit). And there's a decent chance it peters out without a massive spike 2nd wave. There's a lot of data out there that suggests we've overestimated how bad it is for us...
Wow. The reflexivity in this is huge....news could go either way....but the price action is probably balanced up as we know that if things turn down the monetary and fiscal support will be stepped up again...holding the fort for a brighter day.
I don't feel bullish...but I do think there is much more to be positive about and that gloom emotions could be a trap. This market keeps going up as big money is FOMOing....and they might have a lot more of it to do
I feel also that the huge imponderable is what governments do. If they print money to spend their way out of recession, as we saw in the banking crisis, that money tends to inflate assets - eg housing or share prices.
Yup...and I remember reading lots of strategists in 2009 and meeting hundreds of fund managers (I analysed and interviewed them for a living at the time) and >90% were of the view the rally was fragile, the world was screwed, FOMO it for a bit as the Fed was providing help...but in 6-12 mths start taking the risk off as things were not going to be okay. This view rolled on until we hit eurocrisis time in 2011/12 and a new fear took centre stage.
I don't know what's going to happen....my hunch is that we had our version of the great depression 2008-2020....covid is like the post 1937 depression time when FDR realised that his prior actions had been ineffective as they crippled business plus the build up to war started to create demand. I'm not saying its the same but I think we are more 1940 than 1929. Note that if you read social history of 1930s it feels quite like our times in many ways particularly the populist politics, the extreme good vs evil positioning of all debates and the progressive vs conservative perpetual antagonism.
My biggest fear...we waste the opportunity that covid gives us to move forward and step back to the craziness of austerity and perpetual progressive vs conservative posturing
"I think the only bit of his story that is stretching it is the trip to test his eyesight"
I noticed he'd said this, thought it peculiar, but then realised I'd done it myself.
Had a few eye problems, recovered but vision felt subjectively different. Had long trip coming up. Tested by checking out number plate reading distance which was well legal. Still not entirely happy, so took a local drive for long enough to be confident.
I've no idea about Cummings but in my mind a peculiar explanation that I personally know might be real gives him more credibility, not less.
I still regularly check my number plate reading distances for fear I might miss deterioration. Did that even when optician said I'm fine.
All very fair points and I think you are right that these could be very difficult times. I would put a contrarian view though that the Government has taken a lot of the short term pain away by its measures. The one year business rates exemption has helped a lot as has the furlough scheme. The self employed scheme and the bounce back loan.....up to £50,000 at a very low interest rate....has really assisted millions of people. My work has not been affected as its online but overall financially as individuals my family is much better off at the moment. That sounds wrong somehow but its true. The markets are suggesting a recovery and indeed there is a growing belief by some scientists that Covid will be gone (at least for now) by August. There remains the debate about whether lockdown achieved anything. One for the politicians and historians in hindsight I guess.
More easement will apparently be announced today.
My view remains that these have been amazing times to buy shares at crazy low prices. For instance, a lot of debate about RBG on here recently. Bulls and bears have had their say. No argument about the price though. It has and is soaring since that debate. The market is always right is a favourite saying of mine and the bulls have it. For the moment anyway.
Exactly re the weirdness and how odd it feels.
Hi barnetpeter
Just to say I agreed strongly with everything in your last paragraph. And apart from early 2009 I can’t recall so many bombed out shares recovering so fast. So it’s been a great time for those of us who prefer to react to what markets are doing ahead of doing nothing while pondering what they might do further ahead!
Also the easiest gains are often the first ones. Some are doubling and more in a day. . My recent buys (e.g RBG, Trinity Oil, Saga, Carnival and others) have nearly all, shot up. And if markets do turn turtle again these paper gains provide protection against renewed falls, and often still to get out at a profit.
Though the jury is out on whether the virus will return, what is getting far too little attention is the vast numbers who seem to have had the virus with no symptoms at all.
e.g A friend alerted me to an article hidden away in The Mail today where a cruise ship study found that 80% of sufferers had no symptoms. All crew and passengers on a cruise from Argentina to Antarctica were tested after the first case after 8 days. 217 were tested. 128 tested positive. Only 24 had symptoms and 108 didn’t!
Yet experts and even posters here persist in using the word WILL when debating things like whether or not the virus will return, and if it does, in worse form than this time. Ditto their opinions on shares like Revolution Bars. Opinions are just that, and not certainties.
All crew and passengers on a cruise from Argentina to Antarctica were tested after the first case after 8 days. 217 were tested. 128 tested positive. Only 24 had symptoms and 108 didn’t!
This is what the data coming out of the large scale testing in New York is showing - only about 10% of people who catch it end up with symptoms and 1.4% of people die.
However, I think there's a tendency for people to use percentages to mimimise the impacts, both potential and actual. It's more relevant to put it in terms of actual numbers of effected people.
If everyone in the UK over 19 got it that would mean 5.5 million people would have symptoms, 2.5 million would end up in hospital and 750,000 people will die. You could probably add another few million deaths due to the NHS being overwhelmed.
Until we have treatments that can reduce the recovery times and death rates we need to be careful, otherwise the last ten weeks would have been wasted.
timarrOn COVID-19: I'm puzzled by the science and by the policies worldwide (always "led by the science" - which is too rarely published in the form that went to policymakers).
We are told that
If that's true, then the crowds we see photigraphed on beaches and the lifting of restrictions would seem to lead to an inevitatable second wave of infections.
Cummings' antics seem to have increased the already growing frustration with the lockdown.
The "test-track-trace" seems to rely on people's willingness to go into voluntary self-isolation for 14 days on the basis that someone who thinks thay might have COVID symptoms says they were near enough to you in the past week to have infected you, if they really do have COVID. I'd really like to see the science on which that policy is based, and what proportion of people they assume will comply.
The range of possible outcomes over the next 5 years seems to me to be wider than I have experienced in 40 years of trading - and though I have no way to assess the probabilities, the downside risk from here feels greater than the upside opportunity.
I think you are too pessimistic. The effects of the virus are receding worldwide irrespective of strategy used to control it; lockdown , no lockdown, social distancing... This suggests that the virus is in natural decline. Also there is little sign of a second wave anywhere. The optimistic view is that the virus may disappear of its own accord like SARS and a vaccine will be unnecessary. It is already difficult to test a vaccine because there are not enough people infected with Covid to test it. Agreed there will be short term pain and redundancies but by the end of the year or sooner I am expecting things to be relatively back to normal.
Boohoo (LON:BOO)
No one will care what's happened last few weeks if they double revenue over next couple of years and have credible claim that they will keep up a pace like that (that's what the valuation says...got to believe in duration of such high growth to be 66x trailing earnings pre PLT acquisition)
Going forward will PLT and boohoo brands be autonomous? Or will they use the same factories, warehouse, distribution, marketing engine, etc. Are they the same product or are they uniquely different. And did the sons use dad's knowhow, contacts, ongoing support/advice, etc? Do you think they made it all on their own and it just happened to look a bit like boohoo?
The searingly obvious lesson is that boo don't employ shareholder capital well, but they do employ it well for founding family. They are paying +/-£300m to acquire 100% ownership of a brand they built, that is narrow split apart from the foundational brand, that they have already made significant investments in to help it grow from near zero sales (add significant £m to price tag). PLT has been nothing but a wealth transfer from shareholders to the family....I hope dad sells some more shares now just to emphasise the wealth transfer.
If you view this as a good outcome then you are a cynic or a mug. Better the former obvs as you can manage and price that. So, be honest with yourself which camp you're in. If you are in a different camp I'd be interested in what camp that is and why I shouldn't allocate you to the mug one.
The share price was at all time high in middle of pandemic. Kudos. Its been a great success story and founder deserves great credit (and coin) for it. The market has put a high price on the biz and the family have exploited that to the max....=> forecast => ...The family will exit the business in next 3 years and will set up a new venture lead by sons.
Feel the hubris....
The family will exit the business in next 3 years and will set up a new venture lead by sons.
They already have - its called I Saw It First - what's the betting growth in that now accelerates & PLT thing decelerates!?
Yes, I would struggle to conclude that BOO is being run entirely for the benefit of the outside shareholders as opposed to the founding family. Not that shareholders have done badly of course - I held until the expose in the FT of the conditions in their Leicester based suppliers. I'm sure things have moved on since but I go with the Munger/Buffet "There's never just the one cockroach in the kitchen" maxim.
In this particular instance, it looks like the weight of the bear argument wasn't strong enough, and it has been counter-acted by decisive management action.
Generally, shorting is difficult for companies which are:
If a company ticks these boxes, then it might not matter how overvalued it is. It might not matter if there are some related-party transactions or if there is some confusion about how results are being presented (which is the main thrust of the argument by Shadowfall against Boohoo). You need a meatier argument than this.
Basically, we should all learn a lesson that the future is unknowable and so it's nice to see those that think it is come a cropper every once in a while to remind us. To be out by a factor of 3x on PLT valuation is rubbish, isn't it? Worse than a chimpanzee pushing buttons. Apart from anything, the whole premise relied on the independent directors of a £4 billion company being weak and not acting at "arms length" and in the best interest of all shareholders. I have never seen the slightest evidence for this.
And it could have bought the PLT stake several years ago, at a much lower level, but chose not to.
Yes, and I could have bought a lot more Boohoo (LON:BOO) at 25p and not have sold a third of my holding at 250p a month ago. Still waiting for 20/20 Perfect Hindsight Inc. to release their first product :)
BTW if you haven't already gathered I dislike people that issue these dossiers. I feel sorry for anyone that dumped their Boohoo (LON:BOO) shares yesterday as a result. You really shouldn't pay any attention to these people. If you've done your research properly you need to stick to your guns.
All the best, Si
Boohoo had an exclusive option to buy PLT in its entirety for 5million if memory serves me and yet choose not to for absolutely no reason they decided to buy only 66%. How an earth is that the same as you buying more BooHoo shares at 25p.
Boohoo had an exclusive option to buy PLT in its entirety for 5million if memory serves me and yet choose not to for absolutely no reason they decided to buy only 66%. How an earth is that the same as you buying more BooHoo shares at 25p.
It's not, and I didn't mean to infer it was. However, both would require some form of hindsight. We don't know why they didn't exercise the option sooner, but that's history. All that matters is that they have made an earnings enhancing acquisition this morning.
Surprisingly often, as a shareholder you have to hold your nose - many companies I hold would have some kind of remuneration or bonus scheme that I consider overly generous. The honest truth is that we'd hold very few companies if we let that override otherwise sound business fundamentals when making our investments. Have you seen how much Terry Smith pays himself? Any idea why he lives in Mauritius? I'm prepared to cut a bit of slack to management who have performed well and overseen the kind of growth that Boohoo has. I guess others don't, and that's fine, but don't cut off your nose to spite your face would be my message.
All the best, Si
I only found out about this today, as I don't have a position in Boohoo (LON:BOO) but it is on my watchlist. So there was an option to buy PLT for £5m, but they chose instead to buy 2/3rds of it for £3.3m and let the other 1/3 ride, to motivate the individuals involved. 3 years later, they are buying the rest for what looks like £300m.
This is not a question of hindsight. If it had been an arms length transaction you would say it was a catastrophic decision of the board to pay £300m more than they needed to for an acquisition. Even if the management of PLT needed incentivising, surely £10m would have done it?
But when you hear the acquisition was from the son of a founder of boo, you have to wonder about the corporate governance. It just doesn't look good.
And I see the Kamanis have set up Medusa17, to help distribute Avacta (LON:AVCT) covid test strips. The market likes this, saying that its great because they will be able to use the boo network. And you can't help suspecting whether that is true, and if so, how much boo will charge Medusa17 for using their network, how much Medusa17 will grow in value as a result of being able to leverage off boo, and whether that will be used to justify boo buying Medusa17 for an inflated sum in future?
Finally, boo is an online retailer with a huge infrastructure. Can it not develop its own brands for a fraction of £300m, or is it really more cost effective for members of the Kamani family to develop brands which boo then acquire?
Easy to take the cynical view. As a holder I thought about it at the time. But I then reflected that I wouldn't want to risk losing the management that was driving that growth.
Yes it may always have been linked with the parental company, but it clearly had different managers and a different marketing strategy - and some of that difference was generational. I thought the son was doing well out of it, but that putting his nose out of joint could have been catastrophic, and seeing his parents with a huge pile while he only had a small one would certainly have detracted from his motivation.
Been obvious for a few years that the Kamanis are shifting focus. Bringing in experienced mainstream management, and most shareholders seem to like that. I'd expect momentum to reduce but the train staying on the tracks for quite a while.
Not sure about the rating, but I haven't sold yet and it's looked stretched for much of that time.
Morning Graham, could you take a look at Character (LON:CCT) half year report please?
CCT is on the menu, yes! G
Another cracking placing offer by Primary Bid last night. A placing on behalf of IWG. This is a FTSE 250 company, owner of Regus and it raised £320 million. The CEO personally bought £91 million worth in new stock. How is that for confidence! A fighting fund to buy up the inevitable distressed assets. The City likes the sound of that it seems. The new shares will be issued at 239p and the market price is already above 300p at the time of writing. The shares were above 450p in March. I know nothing about the company myself but I certainly liked the update issued last night after the close.
Primary Bid are only allowed to issue a max of about £7 million to retail investors. Some form of EU directive it seems. They often don't last long so you have to be quick with this type of offer if you want to get involved. I suspect a long list of companies.....small caps mainly...are waiting their turn to use PB.
I guess this may be the way forward. When the largest companies place at a discount they often get lots of complaints from disgruntled small investors who feel excluded. By using Primary Bid the company can now argue everyone was included.
Morning Graham any chance of a ramble of Paypoint (LON:PAY) been a lot of consolidation in this sector, salary reviews and management bonus suspended, profits up slightly but not sure if this is covering the months since covid an issue.
GM Paypoint is failing to it's peer PayZone... so I wouldn't prefer Paypoint
Morning Graham any chance of a ramble of Paypoint (LON:PAY) been a lot of consolidation in this sector
It's a good company but they're main business is physical point of sale in convenience stores to allow people without access to online services to do things like pay bills, etc. The rise in card payment volume is because there are more people visiting those stores who use cards rather than cash while the fall in everything else is because their less connected customers are either being driven online - so utility companies moving people over to subscription or prepaid services - or are simply not using the services.
They're adaptable so they'll pivot somehow, but at the moment payment growth is all online (Visa / Mastercard online payments outside travel and entertainment up 25%, everything else negative in March). I vaguely recall they sold off their e-commerce division to focus on physical point-of-sale so they're probably just in the wrong place at the wrong time.
No question they'll survive, the question is how you put a value on them.
timarr
Thank Timarr always appreciate your input.
Pleasantly surprised that Tclarke (LON:CTO) 's final dividend was only postponed (now paid in July) and not cancelled.
This and :-
"Forecasts for the full year are dependent upon timing of sites restarting and the productivity achieved. A number of possible scenarios have been modelled, each of which results in an underlying operating profit for full year."
suggest confidence going forward.
To survive is one thing, but companies making profits in difficult sectors in the current enviroment are worth searching out.
Phil
Trading Update and AGM from Tclarke (LON:CTO) if you could add to your list please Graham.
Ok, I'm adding CTO to the list! Cheers.
Charles Stanley (LON:CAY) released FY results today. Here's a video overview by the CEO and CFO.
Revenue +11.5%; Profit margin up to 11.7%; Underlying EPS +47.1%
Separately, don't forget, later today is the piworld Thursday webinar, 1pm. Paul Scott is our guest, talking about current markets, and what he's been buying or selling. Register via this link.
Further we have two company webinars coming up:
1. Panoply Holdings (LON:TPX) next Tuesday 2nd June, 2pm. CEO & CFO will give more detail on their contract win and trading update, earlier this week, (which moved the sp by 40%! Seems to be a bit under the radar). TPX is a tech services company, fulfilling their clients' digital transformation. Clients both public and private sector.
2. Tr Property Investment Trust (LON:TRY): Tuesday 9th June, 5pm. TRY was mentioned by Reg Hoare in his excellent overview of Investment Trusts (webinar) last week. Discount to NAV 12%. Pays a 4% dividend. Property IT (in less exposed sectors) . Looks like Directors have been buying. 5 star rating on Morning Star.
To attend either webinar register via this link.
I imagine we'll see a fair amount of chat around Boohoo (LON:BOO) today, small cap or not ... :-)
Positive results and an improved dividend from Charles Stanley (LON:CAY) but a fairly gloomy outlook. Volatility driving trading volumes but interest rate cuts and share price drops impacting future income.
Interesting results at Paypoint (LON:PAY) whose business is mainly payment terminals in convenience shops allowing additional services like bill payments. They're seeing massive drops in bill and ATM payments but a big rise in card payments - there are structural pointers in there as ultiity companies switch consumers to prepay and people use local shops more than in the past. You'd imagine the former will stick, the latter may fade.
And also interesting to see the Easyjet (LON:EZJ) update - they expect Q4 (June-Aug) to be flying only 30% of the capacity flown same period last year. On the other hand they report winter bookings well ahead of last year, partly driven by people rebooking cancelled flights. They don't expect to see 2019 market demand levels recover until 2022.
timarr
Johan Lundgren of Easyjet (LON:EZJ) also saying that they aim to cut up to 30% of workforce. If those aren't recession numbers I don't know what are.
Hi Graham
Please could you look at the FY trading update from Draper Esprit (LON:GROW) ? I am particularly interested in whether you agree with their following claim:
Lower growth forecasts for 2020 and 2021 have been assumed for companies impacted by COVID-19. The Group consistently applies multiples lower than those prevailing for comparable quoted companies to mitigate stock market volatility
Please can you make sense of the following?
Relative to our pre-COVID-19 expectations which were in line with our 20% portfolio growth target we have made provisions of circa £99m across the portfolio, which is equivalent to a 21% adjustment across 53% (by value post-amendment) of our portfolio.
It looks as if they have more faith in their 18 core holdings:
Only around one third of these adjustments related to our 18 core portfolio assets, reflecting the strong performance and positions of these businesses even when viewed through a more stringent valuation lens. The long-term potential of the portfolio remains positive and we expect the value of the portfolio to grow post COVID-19 particularly in light of the accelerated transition to digital
You had a generally positive outlook when you last reviewed it in May 2018 but there has been some criticism elsewhere of overly-generous valuations. Is this provision evidence of this?
And by no means a smallcap: Boohoo (LON:BOO) agrees to buy out the 34% of PLT for £324m max. Initial £270m of which £162m is cash. The £54m contingent payable if SP averages 491p over a 6 month period between completion and 14 March 2024. Seems Matt Earl's Shadowfall note has had the positive effect of giving certainty on the PLT quantum, though his prediction that the £200m placing cash would probably be used to buy PLT has come true very quickly!
And by no means a smallcap: Boohoo (LON:BOO) agrees to buy out the 34% of PLT for £324m max. Initial £270m of which £162m is cash. The £54m contingent payable if SP averages 491p over a 6 month period between completion and 14 March 2024. Seems Matt Earl's Shadowfall note has had the positive effect of giving certainty on the PLT quantum, though his prediction that the £200m placing cash would probably be used to buy PLT has come true very quickly!
So that values PLT at less than £1 billion (even with the contingent payment) against a current market cap for Boohoo (LON:BOO) of around £4 billion. I'd say that's a fair price and possibly very good value.
It must be horrible to be right but wrong on the direction of the share price. Happens to me frequently, so it makes me smile a lot when some self important professional investor does it so publicly! Hope he wasn't short :)
All the best, Si
A tip for keeping cool Graham, open windows in the early morning to cool down and then close all doors and windows and blinds as the sun rises. I manage to stay 10 degrees cooler than outside which is welcome when I've been gardening. Harder to achieve when family coming and going I admit.
A tip we use from a friend of mine who grew up in India is to hang wet towels (not dripping wet but definitely more than “damp”) inside the windows of a few rooms with the windows open. As the air comes in, the heat is taken to evaporate the water and it cools the air. I was skeptical until I tried it.
Not necessarily practical in all rooms but in a couple (maybe bedroom and lounge) it works a treat.
24C is my idea of the perfect temperature. Just wear shorts.
Failing that, I see domestic aircon units are not that expensive.
Yes but they will probably be Chinese.
Had partial aircon installed at home last year. Best decision ever. Amazingly cheap to run (sensibly). And as an inverter, on a chilly Spring evening, it was also good at raising temperature in a selected room without running the whole heating system.
Modest installation cost. And it was made in Thailand!
Cool?
PS Back on topic - buying aircon was more sensible than shorting BOO (which, as a holder, on reflection, more than paid for the installation when I top-sliced.)
At the risk of going way off topic, the issue I have with AC is that it's a potential climate disaster, unless it can be driven by renewables. As the world heats up more and more AC will get installed, and more and more energy will be used to drive it, potentially making the problem worse.
I'm not saying no one should ever use AC, it has real value, and it's not going away, but the more we can use passive cooling methods, as described earlier in the thread the better, and maybe the less we'll end up needing the AC.
Shorts have been deployed!
I was confused at first. I thought you were saying that you were shorting a stock.
Some people consider shorts to be morally wrong - apparently.
Some people consider shorts to be morally wrong - apparently.
Only at our local golf club, apparently :-)
All the best, Si
Definitely with long socks and sandals
Thanks for the tips!
My morning smallcap tweet:
DX (Group) (LON:DX.) EQTEC (LON:EQT) Nanoco (LON:NANO) Tclarke (LON:CTO)
Group (DX.) Trading in both DX Freight and DX Express has been better than anticipated since mid Apr, although revenue is still ~10-15% below expected seasonal levels. Guides FY rev and adj EBITDA ahead of market forecasts of £309.1m and £1.6m (IAS 17 basis) and £22.2m (IFRS 16 basis).
EQTEC (EQT) detailed project updates. Co "experiencing an increase in the number of large operators that are engaging in conversations with us regarding collaboration opportunities. We believe the coronavirus pandemic may influence the pace and nature of climate action positively."
Nanoco (NANO) framework agreement with STMicroelectronics extends extends the collaboration that was in place while both cos were working for a US Customer. Orders for development work on material for a new application and small scale volumes of an existing material received. Any further purchase orders will extend cash runway from Q2 2021. I'm short.
T Clarke (CTO) AGM stmt: many project sites have been closed, April rev £10m. "In spite of the fall in turnover, underlying operating profit (EBIT) is forecast to break even for Q2. Underlying operating profit for the first 6 months of 2020 is therefore expected to be circa £2m."